
Zhongji Innolight Deep Update: Behind Nomura’s RMB 1,325 Target, How 2.4T/3.2T, NPO, and CPO Push the Profit Anchor Beyond 2028
目录
TL;DR
I. First, Dissect RMB 1,325: Not the Most Aggressive Target Price, but a More Disciplined Formula
II. The Real Change Is in 2027/2028: Revenue and Profit Are Both Well Above Consensus
III. Where Consensus Differs: Nomura Has Greater Confidence That Volume, Price, and Share Can All Extend
IV. Shipment Assumptions Have Changed: 1.6T Is the Main Axis, While 2.4T and 3.2T Are Long-Dated Options
V. Supply Bottlenecks Are a Double-Edged Sword: They Protect Pricing but May Also Limit Delivery
VI. The Significance of NPO/CPO: Not a Concept, but a Valuation Window for Module Vendors
VII. Comparison with Eoptolink and TFC: Buy Certainty in Innolight, Not Maximum Optionality
VIII. Investment Framework: RMB 1,325 Is Neither a Ceiling Nor a Safety Cushion
IX. What to Watch Over the Next Four Quarters
X. Conclusion: The Research Question on Eoptolink Has Shifted From “Is There a Cycle?” to “How Far Can the Cycle Extend?”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Nomura’s incremental point on Zhongji Innolight is not simply a higher target price, but an upward reset of 2027-2028 shipments, revenue, and profit. 2.4T, 3.2T, NPO, and CPO are being placed on the same curve, forcing the market to reassess whether the company can extend its position as a core AI optical-interconnect holding beyond 2028.
TL;DR
Nomura’s focus is long-dated profit. Nomura maintains a Buy rating and raises its target price to RMB 1,325, but that is not the most important part of the report. The real increment is that it incorporates the post-1.6T product roadmap into the earnings anchor, indicating that the research question around Zhongji Innolight has shifted from whether near-term orders are strong to whether the profit step-up can continue beyond 2027.
The target price is more restrained, and the formula is more disciplined. The market has already seen more aggressive target-price frameworks for Zhongji Innolight. Nomura instead prices the stock using 20x P/E and RMB 66.06 EPS. The value of this formula is that it puts the pressure back on earnings delivery rather than continued PE expansion; as long as EPS holds, valuation pressure can be absorbed by profit.
The consensus gap is mainly long-dated. Nomura’s revenue and net-profit forecasts for Zhongji Innolight are significantly above Wind consensus, with the gap widening toward 2028. This shows that the debate has moved from whether 2026 orders are strong to whether 1.6T, 2.4T, 3.2T, and NPO/CPO can extend the profit step-up.
Supply bottlenecks both protect profit and constrain delivery. In Nomura’s shipment assumptions, 800G remains the scale foundation, 1.6T becomes the main axis, and 2.4T/3.2T begin entering the model. Bottlenecks in InP wafers, MOCVD, and 200G EML will keep near-term delivery tight, but may also slow price declines for high-end products versus traditional cycles. The follow-up question is whether the company can turn bottlenecks into profit protection or whether bottlenecks will limit revenue delivery.
NPO and CPO determine the valuation window. 800G is already a delivery item, 1.6T is the 2026-2027 main axis, and 2.4T/3.2T plus NPO/CPO determine whether the profit anchor can still be discussed beyond 2028. If NPO scales before CPO, Zhongji Innolight’s pluggable and near-package window will be extended; if CPO is more quickly dominated by system vendors and switch-chip vendors, the long-term multiple for module makers will be compressed back into a manufacturing-stock framework.
The next validation depends on five numbers. The most important items ahead are not the target price itself, but quarterly revenue step-ups, gross margin, high-end module share, real customer deployment of NPO/CPO, and operating cash flow. If these five numbers continue to close the loop, Zhongji Innolight remains a core holding; if any one breaks, valuation will be folded back into the manufacturing cycle.
I. First, Dissect RMB 1,325: Not the Most Aggressive Target Price, but a More Disciplined Formula
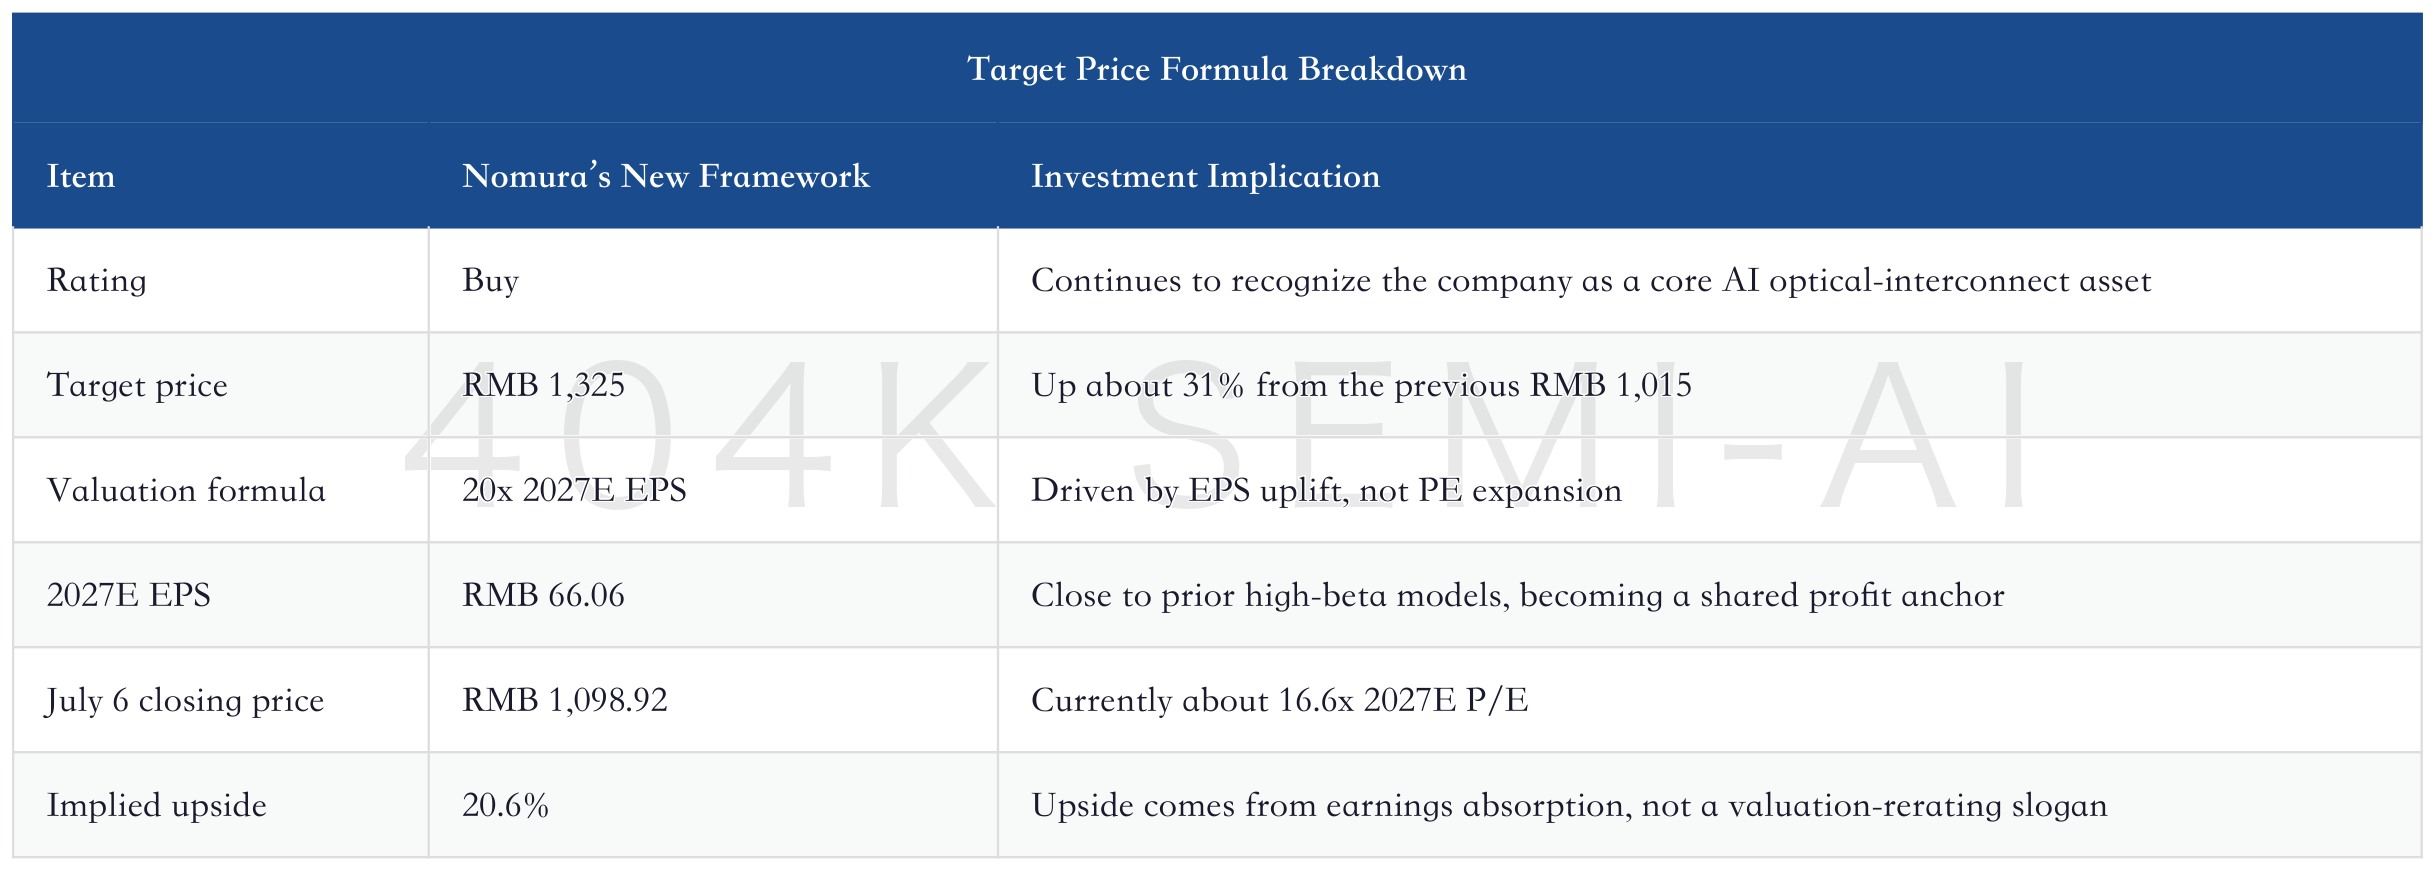
Nomura raised Zhongji Innolight’s target price to RMB 1,325. On the surface, this looks like a routine target-price increase, but the formula is what really matters. It does not assign a higher PE; instead, it prices the stock at 20x 2027 EPS of RMB 66.06. Based on the July 6 closing price of RMB 1,098.92, the report implies upside of roughly 20.6%.
The meaning of this formula is clear: the next leg for Zhongji Innolight should not rely on further PE-driven imagination, but on delivery of 2027 EPS. 20x is not an exaggerated multiple; it is even more restrained than some previous sell-side valuation assumptions for optical-module leaders. But if 2027 EPS can indeed reach RMB 66.06, the current share price implies only about 16.6x 2027E P/E.
This is the most useful part of Nomura’s report. It compresses the trading question from “what target price is assigned” back to “whether the earnings anchor holds.”
This logic is not exactly the same as BofA’s previous RMB 1,650 target price. Earlier, the market focused more on whether 2027 EPS could be raised materially after 1.6T and NPO entered the model. Nomura is more restrained this time: it does not lift the multiple, but instead raises 2027/2028 revenue, profit, shipments, and share.
Zhongji Innolight Re-Rating: BofA Raises Target Price to RMB 1,650; 1.6T Ramp and NPO Inclusion Open the 2027 Profit Anchor
Therefore, this report should not be read as “less aggressive than the previous target price.” A better reading is: when a more restrained valuation multiple can still produce RMB 1,325, the market debate is no longer about the concept, but whether 2027-2028 profits can keep holding up.
II. The Real Change Is in 2027/2028: Revenue and Profit Are Both Well Above Consensus
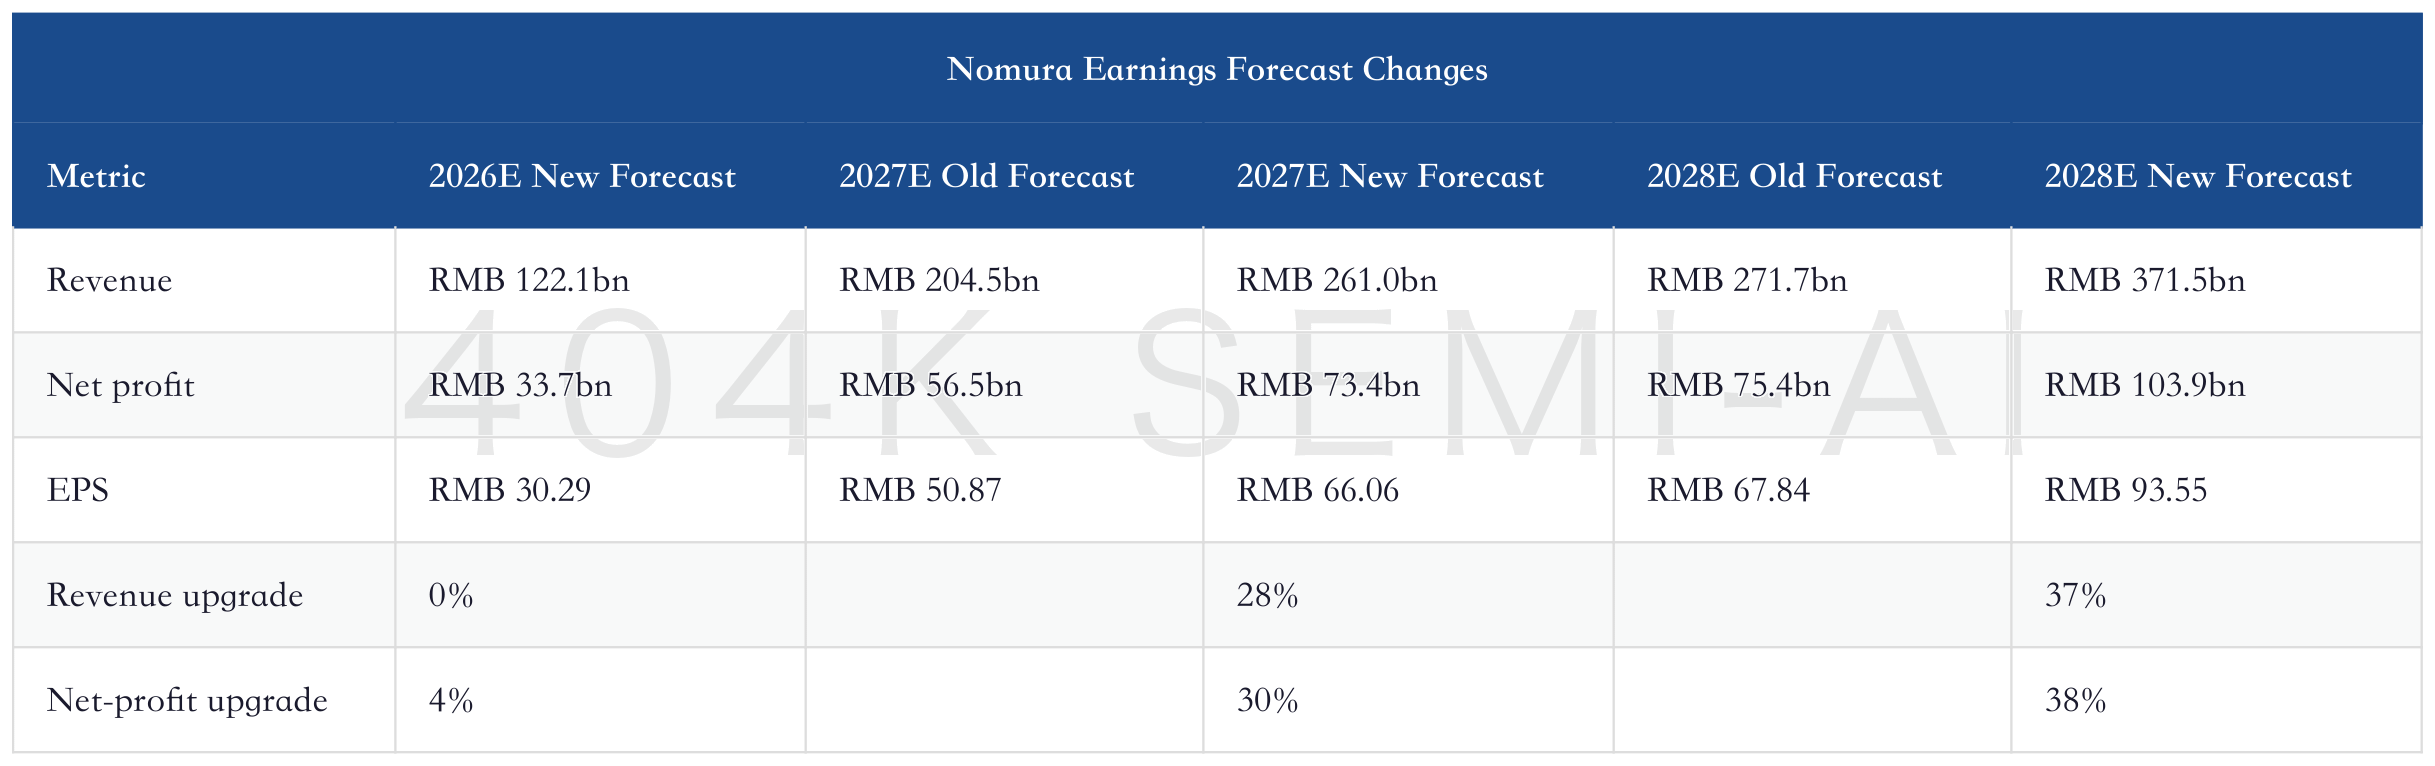
Nomura did not raise its 2026 revenue forecast, keeping it at RMB 122.1 billion. But it raised 2027 revenue from RMB 204.5 billion to RMB 261.0 billion, and 2028 revenue from RMB 271.7 billion to RMB 371.5 billion. Net profit was also raised from RMB 56.5 billion to RMB 73.4 billion in 2027, and from RMB 75.4 billion to RMB 103.9 billion in 2028.
This slope shows that Nomura is not revising for one strong quarter, nor simply pulling 2026 demand forward. It is reassessing the durability of high-end optical-module demand after 2027, as well as Zhongji Innolight’s share stability across multiple generations of speed migration.
This table has two implications.
First, 2026 is no longer the main point of disagreement. Zhongji Innolight’s high growth in 2026 will likely be fully tracked by the market. What really affects the target-price center is whether high growth can continue in 2027. Nomura’s 28% revenue upgrade and 30% net-profit upgrade for 2027 show that it believes 1.6T and higher-speed products are not a temporary peak, but the second curve after 800G.
Second, 2028 is the more important option value. Nomura raises 2028 revenue by 37% and net profit by 38%, and assigns EPS of RMB 93.55. The meaning of this number is not that investors should immediately assign full valuation to 2028, but that if 2.4T, 3.2T, and NPO/CPO begin generating real revenue, the profit anchor after 2027 may continue to move.
This is also a natural extension of the previous “2027 profit anchor” framework. The May deep dive on Zhongji Innolight focused on the transition from 800G delivery to 1.6T succession; BofA’s June update focused on 1.6T and NPO lifting 2027 EPS to around RMB 66; this Nomura report pushes the discussion further out, with the key question becoming whether there will be next-generation speed and architecture revenue beyond 2028.
Zhongji Innolight Deep Dive: From 800G Delivery to 1.6T Succession, How the Core AI Optical-Interconnect Holding Gets Re-Rated
III. Where Consensus Differs: Nomura Has Greater Confidence That Volume, Price, and Share Can All Extend
Nomura’s forecasts are materially above Wind consensus. Its 2027 revenue forecast is 60% above consensus and net profit is 31% higher; for 2028, revenue is 67% higher and net profit is 38% higher. The gap is not as large for 2026 alone; the further out the forecast horizon, the more optimistic Nomura becomes.
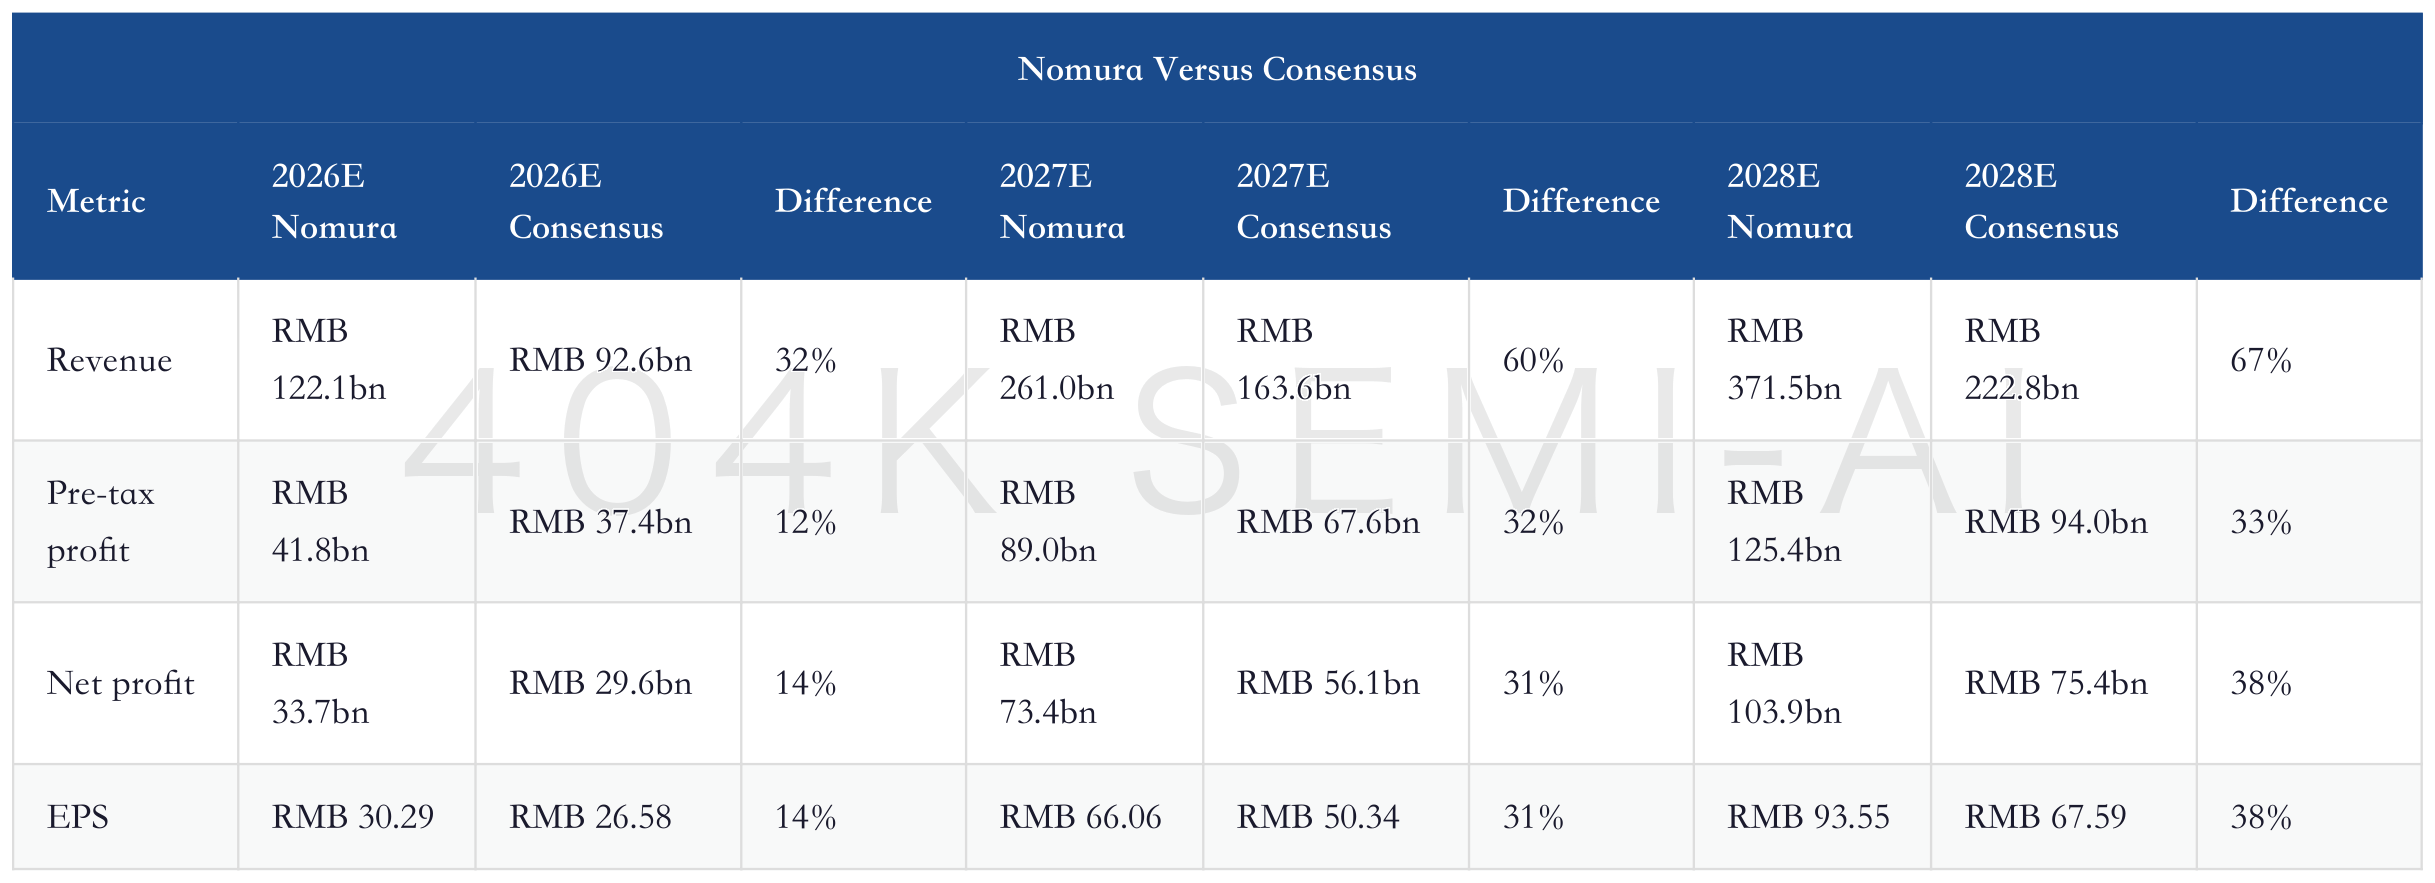
This gap is not a rounding issue. It reflects a difference in worldview.
Consensus is closer to buying the continuation of the 800G and 1.6T upcycle. Nomura is closer to buying a world in which, after 1.6T, 2.4T, 3.2T, and NPO/CPO take over. The former supports valuing Zhongji Innolight as a leading high-cycle manufacturer; the latter is what keeps the company within the framework of AI networking bottleneck assets.
Nomura’s three core optimistic assumptions are straightforward.
First, high-end AIDC optical modules remain a bottleneck. Customers are not buying modules for ordinary network expansion, but to prevent GPU, ASIC, and large-scale AI cluster compute from sitting idle. The more expensive the compute cluster, the less acceptable it is for networking to become the bottleneck. This should allow high-end modules to retain priority within total capex.
Second, Zhongji Innolight can maintain a 30%-35% share. If the company were merely growing with the industry, the profit upgrades would not be this large. Nomura is effectively assuming Zhongji Innolight can continue to rely on R&D;, customer qualification, and supply-chain management to maintain its core global share in high-end AIDC optical modules.
Third, product upgrades can drive gross-margin expansion. Nomura raises its 2026-2028 gross-margin forecasts by 2.2-3.9 percentage points. Under the new assumptions, 2026/2027/2028 gross margins are 45.7%/46.1%/46.2%. This is not an extreme jump, but a moderate improvement as the product mix shifts from 800G toward 1.6T, 2.4T, 3.2T, silicon photonics, and NPO.
The real variable to track in the consensus gap is not which institution is more optimistic, but which set of assumptions is validated faster by quarterly data. If revenue continues to step up in 2H26, gross margin stays above 45%, and customers continue to provide 2027 production visibility, the market will gradually move closer to Nomura’s model. If revenue or gross margin turns down earlier, consensus will regain the upper hand.
IV. Shipment Assumptions Have Changed: 1.6T Is the Main Axis, While 2.4T and 3.2T Are Long-Dated Options
Nomura’s upward revision to shipment forecasts is the report’s hardest industry assumption. It raises its 2027/2028 global 800G shipment forecasts to 55mn/78mn units and its 1.6T forecasts to 71.5mn/126mn units. It also incorporates 2.4T shipments of 2mn/5mn units in 2027/2028 and 3.2T shipments of 2mn units in 2028.
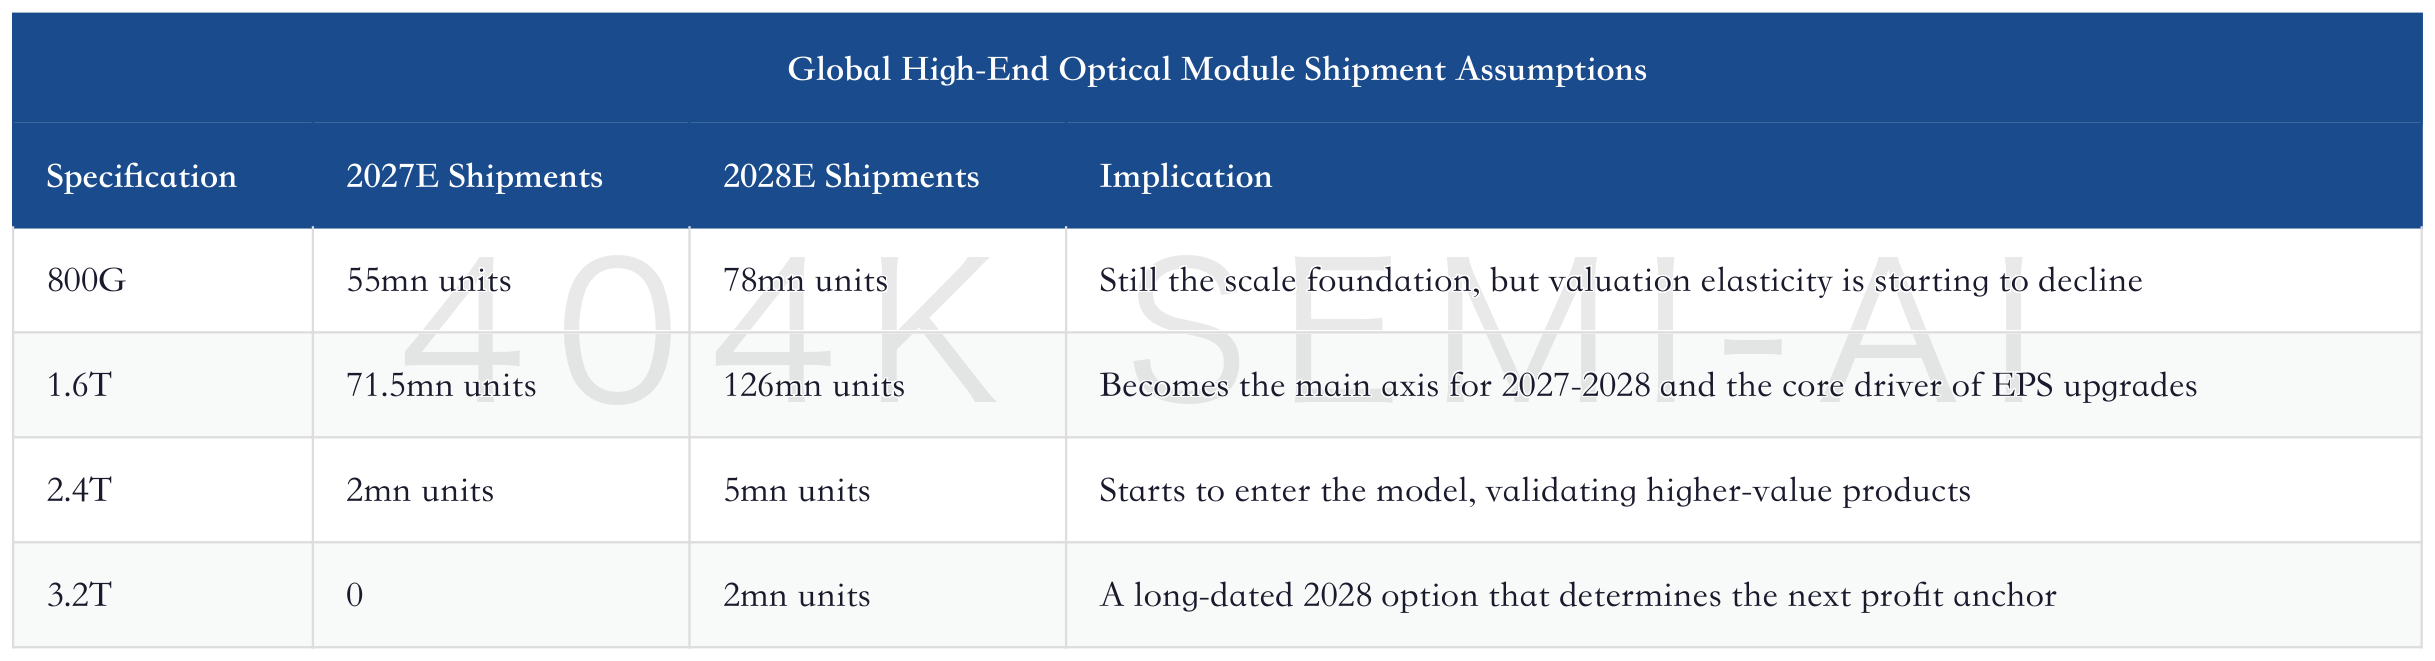
The most important point here is not any single shipment number, but the sequence of speed migration. 800G has already proven that AI data centers are willing to pay for bandwidth. 1.6T proves this demand did not end with one product generation. 2.4T and 3.2T show that customers are still pushing toward higher bandwidth, lower power consumption, and higher density.
Zhongji Innolight’s investment logic is therefore divided into three layers.
The first layer is the 800G base. It determines whether 2025-2026 revenue and profit can remain at a high level, and whether the company has enough cash flow, capacity, and customer trust to take on the next product generation.
The second layer is the 1.6T main axis. It determines whether 2027 EPS can approach RMB 66. What the market is really buying now is not the 800G upcycle, but whether 1.6T can support the next profit step.
The third layer is the 2.4T/3.2T and NPO/CPO option. It determines whether 2028 EPS can still move above RMB 90, and whether Zhongji Innolight can remain a core AI networking holding rather than reverting to a high-cycle manufacturing stock.
This also shows that the focus is no longer on repeating the basic logic of “upward revisions to AI optical module demand.” The AI optical interconnect series from 404K SEMI-AI has already shown many times that demand is not ordinary server expansion. Rather, the larger GPU/ASIC clusters become, the more easily the network becomes a bottleneck to compute utilization. The new question now is whether Zhongji Innolight can maintain its position as a core supplier through each generation of speed migration.
V. Supply Bottlenecks Are a Double-Edged Sword: They Protect Pricing but May Also Limit Delivery
Nomura explicitly notes that the high-end optical module supply chain still faces near-term bottlenecks, including InP wafers, MOCVD equipment, and 200G EMLs. This view is consistent with optical interconnect supply-chain tracking over the past several months: customer demand is very strong, but upstream links capable of stable high-end mass production do not have unlimited elasticity.
Supply bottlenecks are neither purely positive nor purely negative for Zhongji Innolight. They are a double-edged sword.
The positive side is protection for pricing and margins. In traditional optical module cycles, ASPs gradually decline after new specifications ramp, and margins fall as competition intensifies. But if key upstream components, materials, and equipment are all tight, leading customers care more about securing supply than squeezing suppliers to the lowest price. As a core supplier, Zhongji Innolight is better positioned to lock in resources and convert a high-end product mix into margin resilience.
The negative side is the delivery ceiling. However strong the orders, if InP, EML, MOCVD, or testing capacity becomes a hard constraint, revenue recognition may lag demand. The difficulty in high-end optical modules is not producing samples, but delivering high-volume products in line with customer schedules, yield requirements, and reliability standards. If supply bottlenecks are not handled well, they can shift from margin protection to revenue constraint.
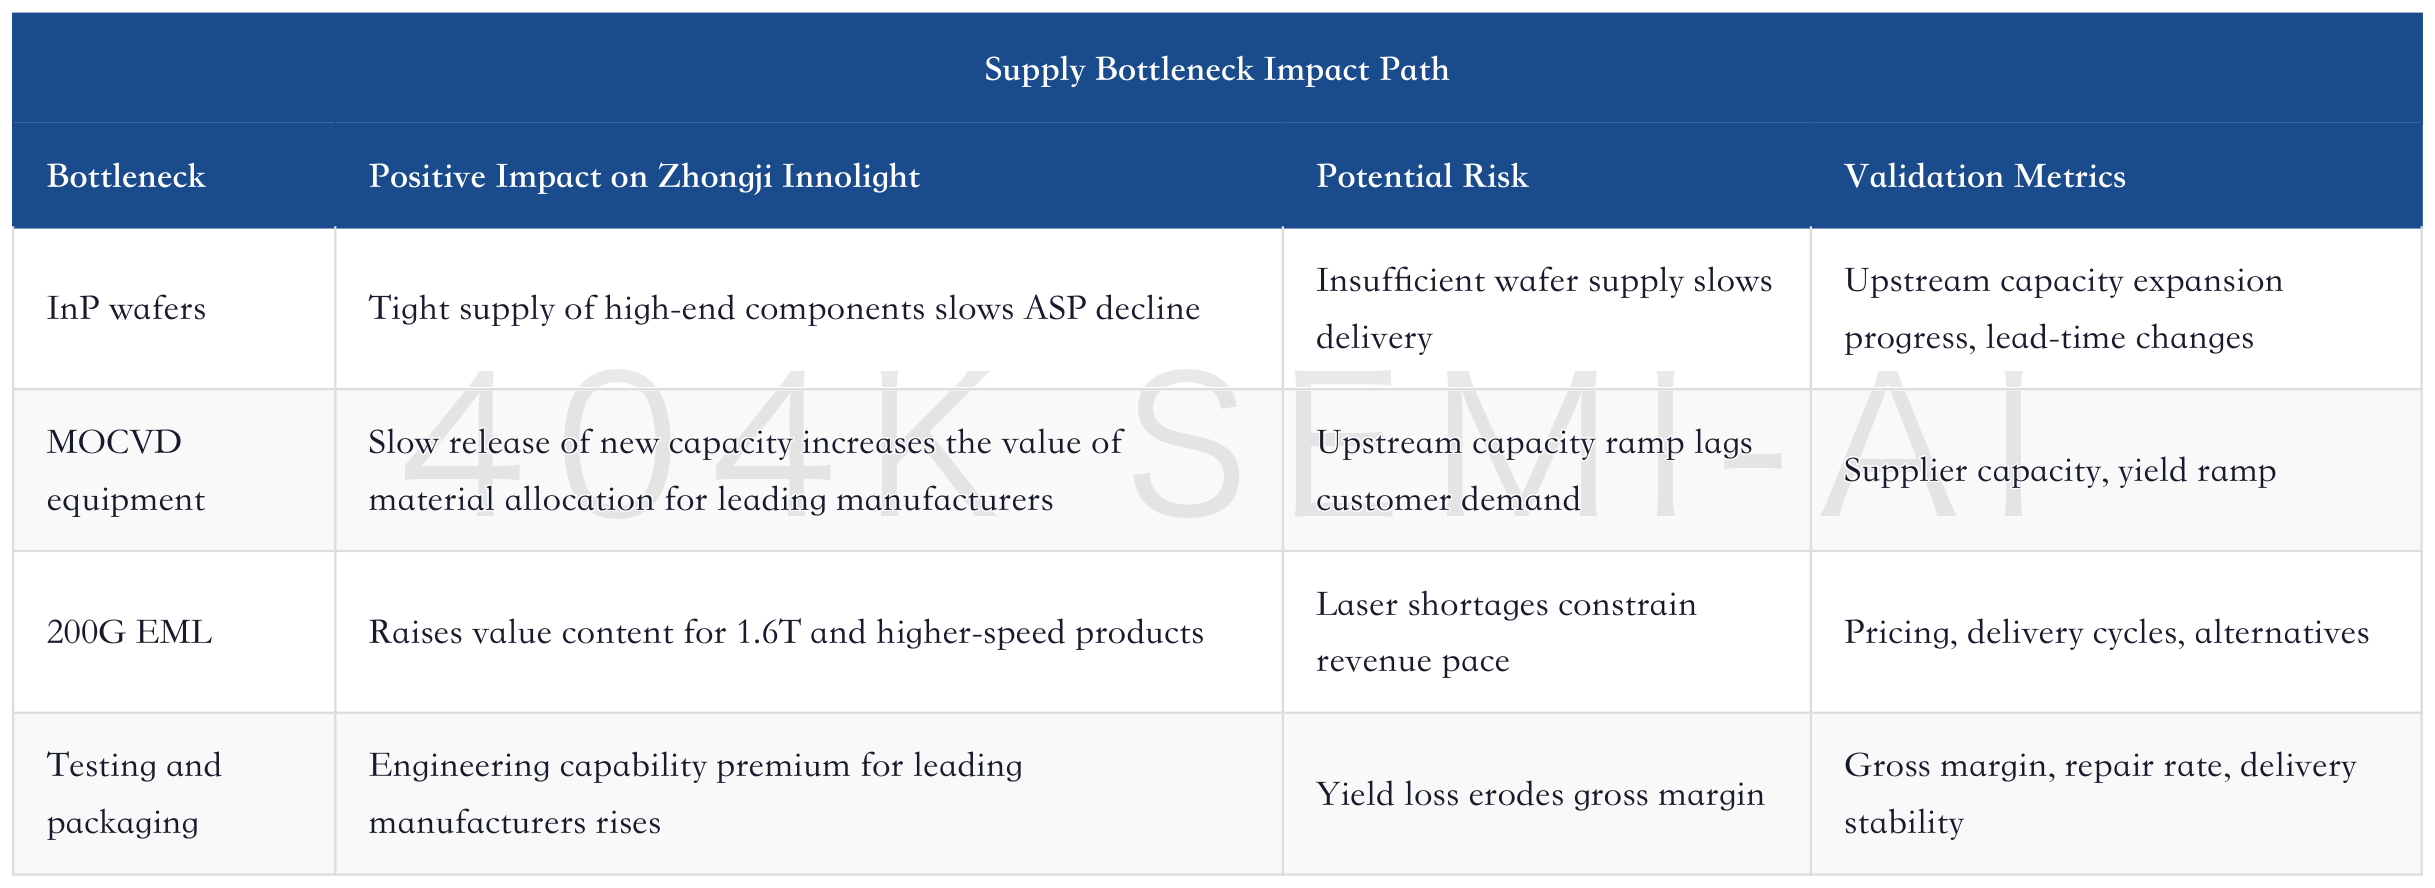
Nomura believes long-term supply shortages will ease, most likely after 2028. This judgment is important. Near-term bottlenecks make 2026-2027 margins look better, but the easing of longer-term bottlenecks may bring price competition back. What Zhongji Innolight really needs to prove is whether, after bottlenecks ease, it can still preserve margins through customer qualification, scaled delivery, and participation rights in new architectures.
Therefore, over the next few quarters, investors should not look only at revenue growth. A better tracking approach is to look at revenue, gross margin, inventory, and cash flow together. If revenue rises, gross margin remains stable, inventory does not build abnormally, and operating cash flow keeps pace with profit, it would show the company has converted supply tightness into margin protection. If revenue stalls, gross margin declines, and inventory and receivables pressure rises, investors should watch for bottlenecks shifting from a moat into a constraint.
