
目录
Executive Summary
I. What RMB1500 Implies: Earnings Forecasts Are Not the Highest; the Multiple Matters More
II. Why the Market Could Expand 6–10x: Each GPU Is Requiring More Optical Connectivity
III. The 2026–2028 Earnings Base: 1.6T Matters More Than NPO
IV. Why NPO and CPO May Coexist: The Value Lies in Proximity to the Chip, Not the Label
V. Financial Forecasts: Earnings Are Substantial, but Cash Flow Deserves Closer Attention
VI. FCC Risk: Overseas Capacity Can Cushion, but Not Eliminate, the Worst-Case Scenario
VII. The Five Most Important Signals to Validate Next
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
After a roughly 35% pullback from its June high, UBS has resumed coverage with a RMB1500 price target. The real debate is no longer about 800G, but about the ramp-up of 1.6T, the commercialization of 3.2T NPO, and whether overseas capacity can absorb policy-related risks.
Executive Summary
The RMB1500 target is based on a clear formula. UBS applies 25x earnings to its 2027 EPS estimate of RMB60.69, yielding approximately RMB1517 before rounding the target to RMB1500. This represents 62.9% upside from the RMB921 share price on the report date.
Network architecture is reopening the industry’s growth ceiling. UBS expects the data-communications optical-module market to expand from approximately USD19bn in 2025 to USD120bn–185bn in 2028–2030. The key drivers are growth in GPU/ASIC volumes, a higher ratio of network interface cards to GPUs, and network expansion from single-tier to dual-tier and eventually cross-data-center architectures.
Pluggable 800G and 1.6T products will remain the primary medium-term earnings drivers. UBS expects annual shipments of both generations to remain in the tens of millions in 2027–2028, far exceeding NPO volumes over the same period. These products underpin earnings delivery through 2026–2028.
3.2T NPO represents the second leg of the longer-term valuation case. UBS expects 3.2T NPO shipments to increase approximately 50x in 2028 versus 2027, contributing around 10% of revenue in 2028 and potentially around 30% by 2030. Higher integration and greater value per system explain why its early revenue contribution should substantially exceed its shipment share.
UBS’s model is more restrained than Citi’s and Nomura’s. Its 2028 net-profit forecast of RMB100.245bn is below Nomura’s RMB114.172bn and Citi’s RMB166.774bn. UBS also projects gross margin declining gradually from 45.4% in 2026 to 42.9% in 2028. The RMB1500 target is driven primarily by applying 25x to 2027 earnings, without assuming continued gross-margin expansion.
A hard FCC restriction is the largest tail risk, while cash conversion is the most immediate operating risk. UBS believes moderate restrictions could be largely mitigated by the company’s approximately 85% overseas capacity, but comprehensive restrictions could reduce revenue by approximately 50% and profit by more than 50%. Working-capital requirements and capital expenditure will also absorb substantial cash in 2026–2027, making operating cash-flow delivery a key metric to monitor.
I. What RMB1500 Implies: Earnings Forecasts Are Not the Highest; the Multiple Matters More
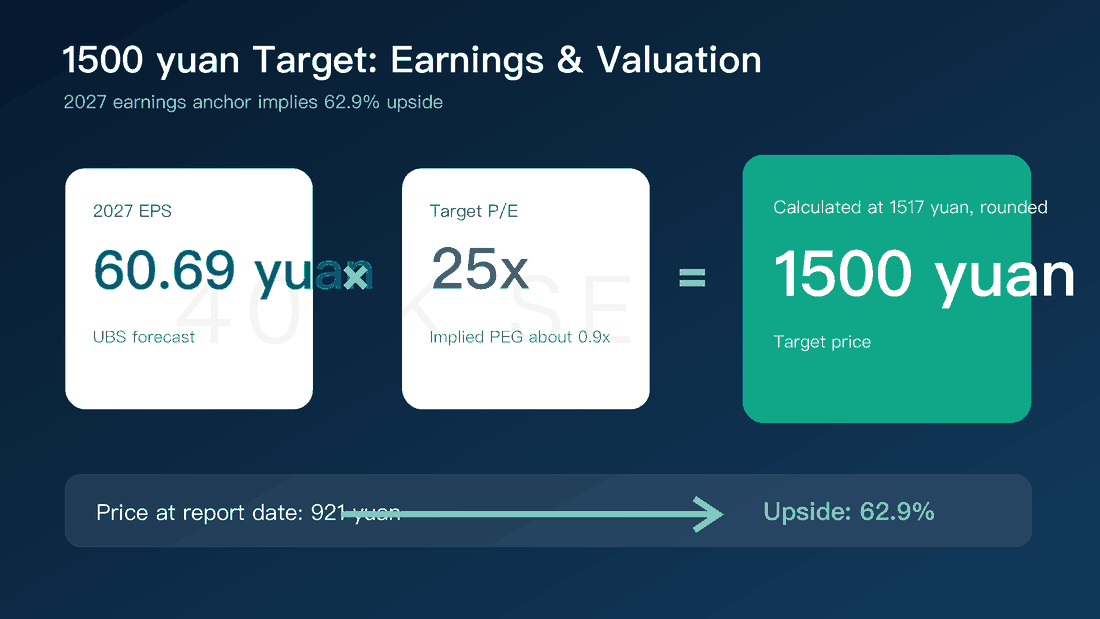
UBS has resumed coverage of Zhongji Innolight (300308.SZ) with a positive view and a RMB1500 price target. Its valuation uses 2027 EPS of RMB60.69 and a 25x earnings multiple. Multiplying the two gives RMB1517.25, which UBS rounds to RMB1500. This implies 62.9% upside from the RMB921 closing price on the report date; including an expected dividend yield of 0.5%, the total return is 63.3%.
The valuation has two components: earnings and the multiple. UBS forecasts EPS of RMB29.69, RMB60.69, and RMB84.96 for 2026–2028, respectively, implying a compound growth rate of approximately 69% over 2026–2028. The rate then moderates to 27% over 2027–2029. The 25x multiple equates to approximately 0.9x the 2027–2029 earnings compound growth rate. In other words, UBS expects the market to continue valuing Zhongji Innolight at an earnings multiple broadly aligned with its growth rate even as rapid expansion enters a later phase, rather than treating it as a conventional cyclical manufacturer.
A simple sensitivity framework illustrates the vulnerabilities in the RMB1500 target. If 2027 EPS reaches only RMB50, applying the same 25x earnings multiple would imply a value of just RMB1250. If EPS reaches RMB60.69 but the multiple falls to 20x, the implied value is approximately RMB1214. The RMB1500 target therefore requires both earnings delivery and sustained market acceptance of a 25x growth multiple. Conversely, EPS of RMB70 at an unchanged 25x multiple would imply RMB1750. UBS’s target thus reflects a moderately optimistic scenario in which earnings are broadly delivered and the valuation premium is maintained—not a conservative stress-case value.
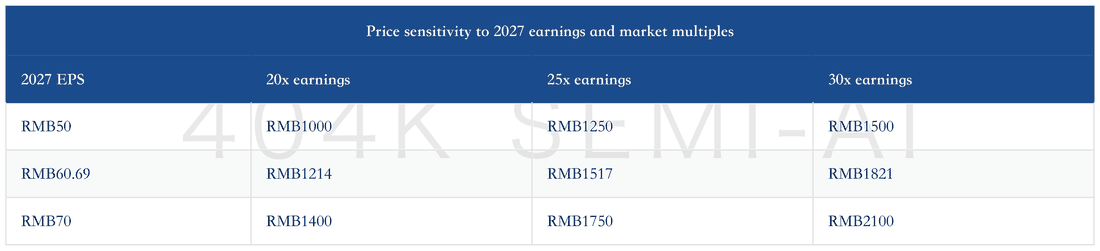
At RMB921 per share, the stock trades at 31.0x, 15.2x, and 10.8x projected earnings for 2026, 2027, and 2028, respectively. The market is effectively betting that 2027 net profit of RMB71.606bn will establish a sustainable earnings plateau, rather than represent a one-off order surge in 2026. If the 2027 forecast is delivered, the current valuation is not demanding. If mass production of higher-speed products is delayed by one generation, however, both the 25x valuation anchor and the RMB60.69 EPS estimate would come under pressure.
This is why RMB1500 should be understood as the outcome of two conditions—earnings delivery and a sustained market multiple—rather than a simple extrapolation of industry enthusiasm. As discussed in our Nomura RMB1375 price-target update, Nomura applied 21x to 2027 earnings. UBS arrives at a higher target despite using a lower 2027 earnings forecast because it applies a 25x market multiple. The central disagreement between the two institutions is how long rapid growth in high-speed optical interconnects can persist.
II. Why the Market Could Expand 6–10x: Each GPU Is Requiring More Optical Connectivity
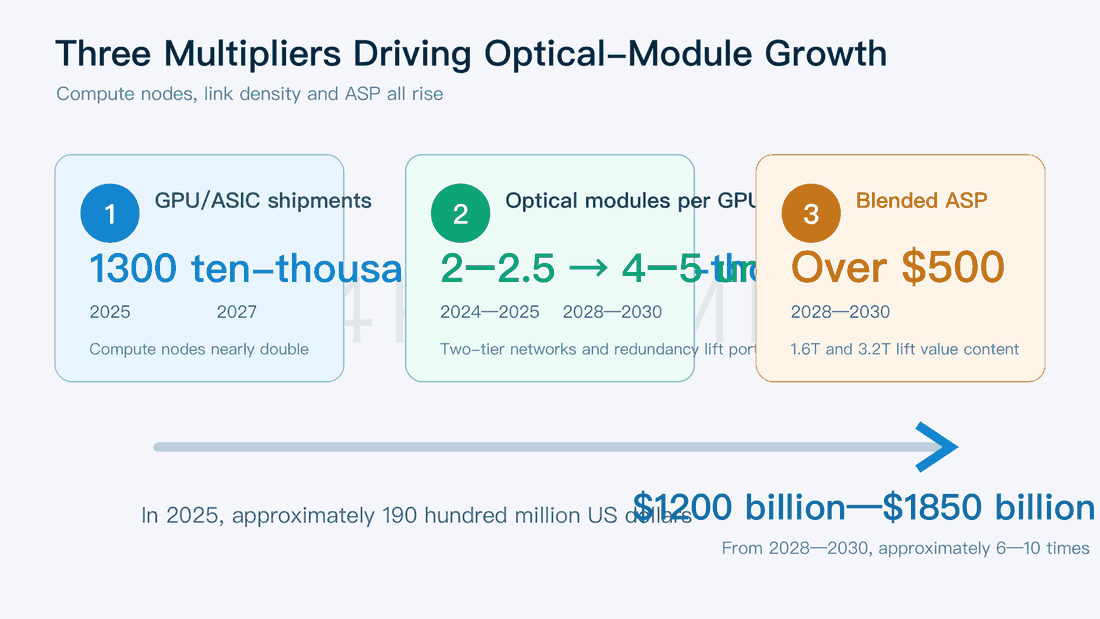
UBS expects the global data-communications optical-module market to expand from approximately USD19bn in 2025 to USD120bn–185bn in 2028–2030, equivalent to 6–10x growth. This projection depends on three multipliers changing simultaneously; growth in AI capital expenditure is only one of them.
First, global GPU and ASIC shipments are expected to increase from approximately 13mn units in 2025 to approximately 28mn units in 2027, nearly doubling the number of compute nodes. Second, the ratio of network interface cards to GPUs should rise from approximately 1:8 historically toward 1:4 and potentially 1:1, as larger clusters require more high-speed interconnect ports. Third, as network topology moves from single-tier switching to a two-tier fat-tree architecture, the number of optical modules required per network interface card increases from approximately 2–2.5 to 4–5, while inter-data-center connectivity further extends optical-link distances.
Consequently, the number of optical modules per GPU could rise from 2–2.5 in 2024–2025 to 4–5 in 2028–2030, while migration to higher data rates pushes the blended average selling price above USD500. Unit growth, greater connection density, and higher pricing are occurring simultaneously, allowing the optical-module market to grow significantly faster than GPU shipments.
It is also important to distinguish between growth in capital expenditure and growth in optical-connectivity intensity. The former determines total data-center investment, while the latter determines how much of each RMB1 invested in computing capacity is allocated to networking. As large-model training scales from individual racks to tens of thousands of compute nodes or more, cluster efficiency increasingly depends on inter-node communication. If accelerators are left waiting for data, expensive computing capacity sits idle. Networking is therefore no longer merely an auxiliary component of computing infrastructure; it is a bottleneck that determines effective compute utilization. Even if overall capital-expenditure growth slows, optical-module demand could remain robust as long as networking continues to capture a larger share of system budgets.
