
Zhongji Innolight Deep-Dive Update: 96.4 Million Optical Modules, a 50.4% Gross Margin, and an RMB166.8 Billion Earnings Anchor
目录
TL;DR
Citi’s Most Important Incremental Insight: No Price Target, but a Steeper Long-Term Earnings Curve
Two Models Published on the Same Day: Citi Is More Conservative Near Term but More Aggressive Long Term
Demand Extends Beyond Scale-Out: In-Rack and Cross-Cluster Connectivity Drive the Valuation Tail
800G Ramps Down, 1.6T Takes Over, and 3.2T Begins Scaling: Speed Migration Is Not a Smooth Curve
Volume and Price Growth: The Model’s Greatest Strength—and Its Greatest Vulnerability
Start with Three Arithmetic Cross-Checks: The Model Reconciles, but the Assumptions Still Need to Be Proven
Between Doubling Capacity and Expanding Margins Lies an Arithmetic Question That Must Be Proven
Silicon Photonics Determines Margins; CPO Determines How Much Pluggable Modules Will Still Be Worth
A Declining R&D Expense Ratio Does Not Mean Lower R&D Investment
The Three Financial Statements Are More Candid Than the Income Statement: Growth Consumes Cash Before Releasing It
Valuation Sensitivity: 12× Was Close to the Prevailing Market Capitalization; 25× Is Not the Default Answer
Four Methodological Guardrails: Do Not Let Attractive Numbers Obscure Comparability Issues
Six Falsification Triggers: Whichever Weakens First Is Where the Model Breaks
Investment View: Treat RMB166.8bn as a Stress Test, Not the Default Destination
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Citi did not provide a single price target, yet projected 2028 net profit at RMB166.774 billion. The real debate is not about the valuation multiple, but whether shipments, pricing, and cash flow can all deliver simultaneously.
TL;DR
Citi has substantially increased Zhongji Innolight’s (300308.SZ) long-term earnings potential under a high-growth model. It forecasts revenue of RMB104.216 billion, RMB277.352 billion, and RMB456.338 billion for 2026–2028, with net profit of RMB35.091 billion, RMB97.464 billion, and RMB166.774 billion. Revenue and net profit CAGRs for 2025–2028 reach 129% and 149%, respectively.
The differences between Citi’s model and Goldman Sachs’ model published the same day are instructive. Citi’s 2026 revenue and net profit forecasts are 16% and 9% below Goldman’s, but its 2028 forecasts are 37% and 52% higher, respectively. Their 2028 gross-margin assumptions differ by only 0.3 percentage points. The real gap comes from long-term shipments, product mix, and blended ASP—not margin assumptions.
Shipments totaled 21.1 million units in 2025 and are forecast at 30.1 million, 60.2 million, and 96.4 million units for 2026–2028. Blended ASP is projected at US$490, US$656, and US$675 per unit. Simultaneous volume and price growth is the model’s strongest assumption. With 2026 shipments rising 43% but revenue growing 173%, the primary variables to validate are the share and pricing of 800G-and-above products.
Silicon photonics will determine margins, while new network architectures will determine how long earnings can remain sustainable. Citi expects global silicon-photonics penetration to rise from 38% in 2025 to 73% in 2030. Approximately 70% of Zhongji Innolight’s high-speed product revenue already came from silicon-photonics products in 1Q26. However, co-packaged optics could reduce the content value of conventional pluggable modules if digital signal processors and optical engines are moved into the switch-chip package.
Cash flow is less straightforward than the income statement suggests. Citi forecasts RMB35.091 billion of net profit in 2026, but only RMB21.058 billion of operating cash flow. After RMB7.816 billion of capital expenditure, free cash flow would be approximately RMB13.242 billion. Free cash flow is projected at roughly RMB44.11 billion in 2027, still well below net profit of RMB97.464 billion. Capacity expansion, inventories, and receivables will absorb cash first, with a meaningful release not expected until after 2028.
Citi did not provide a single price target. Its valuation page only presents a sensitivity analysis based on 10–30x 2027 P/E. The report cites a market capitalization of approximately US$161.365 billion at the time, almost exactly equal to the US$161.5 billion implied by 12x Citi’s 2027 net-profit forecast. The market is effectively betting on whether RMB97.464 billion of earnings can be delivered; if the earnings forecast is wrong, debating 20x versus 25x is meaningless.
Investors should treat Citi’s model as a high-execution scenario rather than the base case. The six most important evidence sets to monitor are: the shipment mix of high-speed products; blended ASP; capacity utilization and yields; gross and net margins; the operating-cash-flow-to-net-profit ratio; and customer adoption of 1.6T, 3.2T, near-packaged optics, and co-packaged optics. If two or three of these metrics consistently undershoot the model, long-term earnings estimates should be cut first.
Citi’s Most Important Incremental Insight: No Price Target, but a Steeper Long-Term Earnings Curve
The easiest mistake when reading Citi’s research is to treat the P/E sensitivity table on page 19 as a price-target table. The report’s front page uses a research-view format, while the valuation section does not select a specific multiple. It merely applies a 10–30x P/E range to forecast 2027 net profit and shows the corresponding equity values. The ratings history on page 25 also indicates that the company was already not covered. The report therefore presents an industry and financial scenario, not the conventional conclusion that “Citi assigned a price target of RMB X.”
This makes the analytical priority clearer: assess the earnings model first, then discuss valuation. Citi expects Zhongji Innolight’s revenue to rise from RMB38.24 billion in 2025 to RMB456.338 billion in 2028, while net profit increases from RMB10.797 billion to RMB166.774 billion. Over three years, revenue expands nearly twelvefold and net profit more than fifteenfold, with gross margin rising from 41.5% to 50.4% and net margin from 28.2% to 36.5%. This trajectory simultaneously assumes sustained AI capital expenditure, rising optical-interconnect penetration, speed upgrades, market-share gains, mass production of silicon photonics, product premiums, capacity ramp-up, and operating leverage.
Improvement in any single variable would not be enough to support RMB166.774 billion of net profit. Zhongji Innolight can achieve this trajectory only if demand, market share, pricing, yields, and expense ratios all remain favorable simultaneously. The analytical value of Citi’s model lies precisely in specifying these conditions in sufficient detail: shipments, ASP, product mix, gross margin, R&D; expenditure, capital expenditure, cash flow, and valuation sensitivity can all be tested individually.
In other words, the report does not provide a convenient headline price target. It offers something more useful: a long-term earnings model that can be continuously validated or disproved by quarterly results.
Two Models Published on the Same Day: Citi Is More Conservative Near Term but More Aggressive Long Term
On July 17, 2026, Goldman Sachs and Citi published two Zhongji Innolight models pointing in the same direction but with different growth trajectories. Both recognize the migration from 800G to 1.6T and 3.2T, rising silicon-photonics penetration, and incremental optical-interconnect value from scale-up connectivity within racks. Their main disagreement is not about the industry’s direction, but about how much volume the company can capture, at what price, and how long the growth can continue.
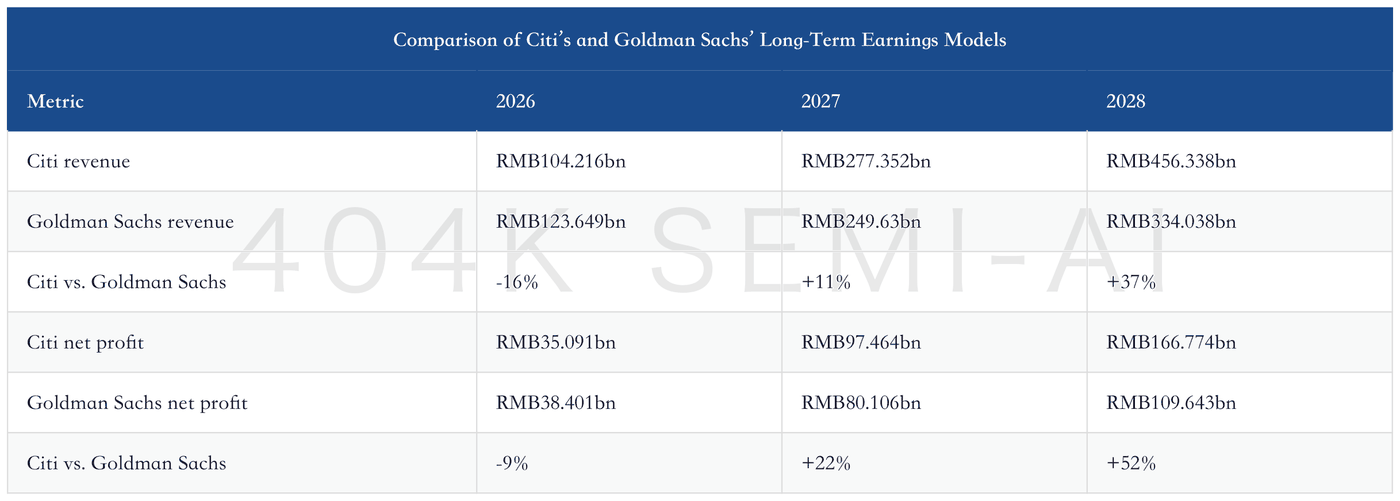
This comparison dispels a common misconception: Citi is not more aggressive than the market’s most bullish institutions starting in 2026. On the contrary, its 2026 revenue and net-profit forecasts are below Goldman’s. This means Citi allows for a near-term ramp in capacity expansion, customer qualification, and product transitions rather than assigning all orders to 2026 at once.
The real steepening occurs in 2027–2028. Citi’s net-profit forecast is 22% above Goldman’s in 2027, with the gap widening to 52% in 2028. Yet their 2028 gross-margin forecasts are 50.4% and 50.1%, respectively—a difference of only 0.3 percentage points. The long-term earnings gap mainly reflects Citi’s much higher revenue assumptions, not gross margin.
This shifts the investment debate from whether Zhongji Innolight can achieve a 50% gross margin to more fundamental questions: can it ship 60.2 million units in 2027 and 96.4 million units in 2028, while sustaining blended ASPs of US$656 and US$675 per unit? If either volume or pricing fails to deliver, the revenue gap will emerge before any margin gap does.
Zhongji Innolight Deep-Dive Update: Goldman Sachs Raises Its Price Target to RMB2,581—How Silicon Photonics, 3.2T, and Intra-Rack Connectivity Support a New Earnings Anchor
Goldman’s model resembles a bullish scenario in which silicon photonics, 3.2T, and intra-rack interconnects enter the revenue base with relatively high certainty. Citi goes further by assuming that these technologies generate greater total shipments and higher blended ASPs in 2027–2028. Neither forecast is conservative, but Citi concentrates more long-term demand and market share in Zhongji Innolight, making its model better suited to identifying falsification points than serving directly as consensus expectations.
Demand Extends Beyond Scale-Out: In-Rack and Cross-Cluster Connectivity Drive the Valuation Tail
Citi estimates that global AI capital expenditure totaled approximately US$900 billion over 2021–2025 and will rise to US$6.1 trillion over 2026–2030. Higher capital expenditure does not translate proportionally into optical transceiver revenue. The real determinant of optical-interconnect value is network architecture: as accelerator counts, cluster sizes, and per-rack bandwidth increase, data must move more frequently among chips, servers, switches, racks, and data centers, making the network more likely to constrain compute utilization.
Citi divides data-communications networks into four use cases. Scale-out networks connect more servers and switches, providing the most certain demand base for 800G and 1.6T. In-rack scale-up networks provide high-bandwidth, low-latency communication among accelerators within the same rack or compute domain. Cross-cluster interconnects combine multiple compute clusters or data centers into a larger resource pool. Front-end networks carry conventional application and management traffic.
In 2025, scale-out accounted for approximately 77% of optical-interconnect demand in data communications, front-end networks and other applications approximately 22%, and cross-cluster interconnects approximately 1%. Industry forecasts cited by Citi project 2026–2030 CAGRs of 19.4% for scale-out and 21.6% for front-end networks. Cross-cluster interconnects are expected to reach 7% of the market by 2030, representing a 117.4% CAGR. In-rack scale-up starts from an even smaller base, but optical substitution for copper could deliver a 297.7% CAGR. High growth does not mean revenue is already substantial in the near term, but it suggests the long-term product mix could look entirely different.
For Zhongji Innolight, scale-out determines near-term cash flow, while in-rack scale-up and cross-cluster interconnects determine the valuation tail. The former relies on high-volume deliveries of pluggable optical transceivers, a business model that has already been validated. The latter two could introduce higher-density pluggable optics, near-packaged optics, co-packaged optics, external laser sources, optical engines, and optical circuit switches, but positions within the value chain have yet to become fully established.
Zhongji Innolight Deep Dive: Revaluing a Core AI Optical-Interconnect Holding as 800G Delivers and 1.6T Takes Over
This is also why Zhongji Innolight should not be viewed simply as “selling more optical transceivers.” Customers procure high-speed optical interconnects to reduce the idle time of expensive compute chips caused by network congestion, power consumption, and failures. The closer a product is to addressing a system bottleneck, the more customers value reliability, yield, delivery cadence, and joint development across multiple product generations. However, as products move closer to switch chips and inside the rack, system vendors and chipmakers also gain greater control over the architecture. Industry expansion does not automatically guarantee that transceiver vendors capture all of the value.
800G Ramps Down, 1.6T Takes Over, and 3.2T Begins Scaling: Speed Migration Is Not a Smooth Curve
Mainstream optical-transceiver standards typically transition every three to four years rather than adding bandwidth at a steady annual pace. Citi’s industry timeline indicates that 100G and 28G SerDes were commercialized around 2016, 400G and 56G SerDes entered commercial deployment around 2019, 800G and 112G SerDes began development in 2020 and scaled around 2023, while 1.6T entered commercialization alongside the next generation of AI servers in 2025.
In 2025, 1.6T represented approximately 4% of the global data-communications optical-interconnect market and is expected to reach 45% by 2030. 3.2T is expected to begin contributing in 2027 and account for approximately 32% by 2030. 800G accounts for approximately 51% and 48% of the market in 2025 and 2026, respectively, before declining to 16% by 2030 as 1.6T and 3.2T scale. Accordingly, 800G will continue growing in absolute terms while surrendering mix share; it will not disappear immediately.
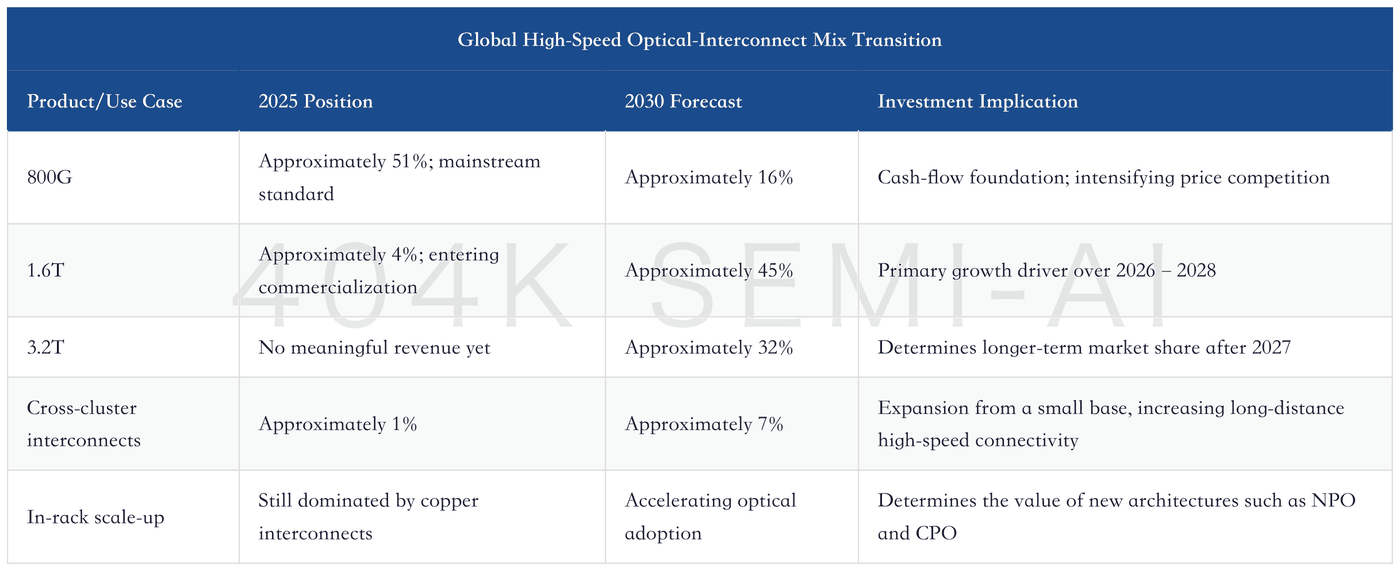
The revenue impact of speed migration is not limited to selling the same number of modules at higher prices. New standards typically begin mass production with high unit prices, low yields, and tight supply chains, followed by price declines as they mature. Older standards experience faster price erosion as competition intensifies and capacity expands. To sustain its blended average selling price, the company must increase shipments of premium new products faster than prices decline for legacy products.
Citi expects Zhongji Innolight’s high-speed optical-transceiver shipments to reach 26 million, 57 million, and 94 million units in 2026, 2027, and 2028, respectively, accounting for 86%, 95%, and 98% of total shipments. Mid- and low-speed product shipments are expected to decline from 6.5 million units in 2025 to approximately 2.4 million in 2028 as resources increasingly shift toward high-speed products. A six-month delay in the adoption of 1.6T and 3.2T, or customers extending the 800G deployment cycle, would affect both blended ASP and the revenue-growth trajectory.
Volume and Price Growth: The Model’s Greatest Strength—and Its Greatest Vulnerability
The three most important lines in Citi’s model are total shipments, the share of high-speed products, and blended ASP; net profit is simply the outcome of these variables. In 2025, Zhongji Innolight shipped 14.6 million high-speed products and 6.5 million mid- and low-speed products, totaling 21.1 million units, with a blended ASP of US$253 per unit. In 2026, total shipments are expected to rise 43% to 30.1 million units, while blended ASP increases 94% to US$490 per unit. This drives revenue growth of 173%, far outpacing shipment growth.
In 2027, total shipments are expected to double to 60.2 million units, while blended ASP rises another 34% to US$656 per unit. In 2028, shipments are expected to increase 60% to 96.4 million units, with ASP edging up to US$675 per unit. Citi also cautions that pricing for mature 800G and 1.6T products could peak around 2026, followed by intensifying competition. The model therefore requires 3.2T, higher-density pluggable products, and new networking use cases to continuously upgrade the mix and offset price declines in mature standards.
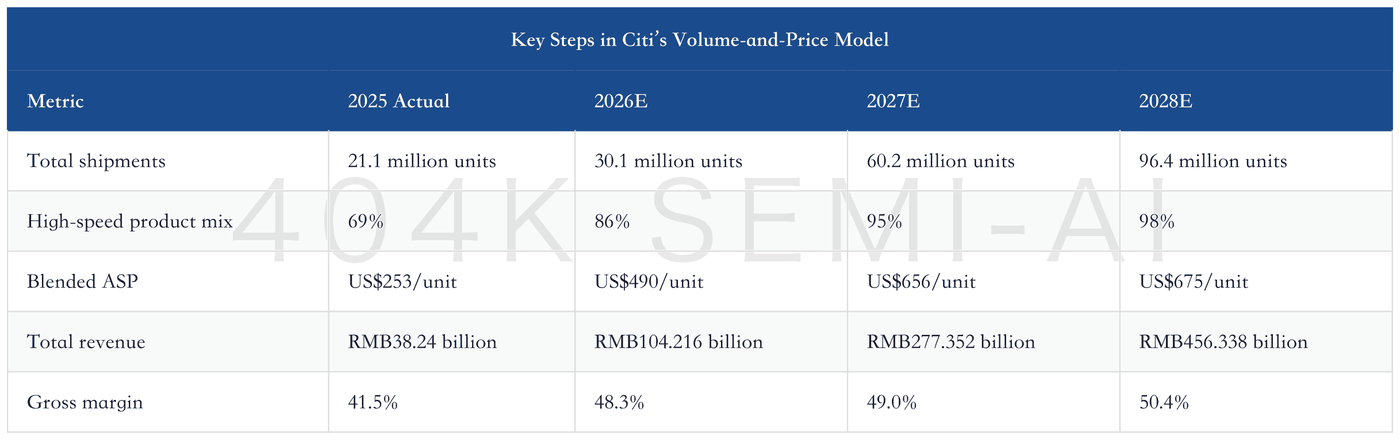
This volume-and-price model requires at least four conditions. First, 1.6T must generate a sufficiently large share of revenue in 2026 rather than remaining limited to samples and small-batch shipments. Second, 3.2T must enter commercialization on schedule in 2027, with Zhongji Innolight maintaining a core market share. Third, the pricing-and-yield combination for new high-speed products must be superior to that of legacy products, rather than merely carrying a higher nominal price. Fourth, the capacity, R&D;, and supply-chain resources released as mid- and low-speed products are phased out must be effectively redeployed to premium products instead of becoming idle or duplicative investment.
The greatest risk is equating a higher blended ASP with broad-based industry price increases. Citi has already stated that prices for mature high-speed products will peak amid large-scale capacity expansion and intensifying competition. ASPs of US$490, US$656, and US$675 reflect the mix effect of selling more premium products, not continuous price increases for every unit within the same product generation. Investors should track 800G, 1.6T, and 3.2T shipments and pricing separately rather than looking only at total revenue.
Start with Three Arithmetic Cross-Checks: The Model Reconciles, but the Assumptions Still Need to Be Proven
Citi’s product-level model can be arithmetically cross-checked. Multiplying 2025 total shipments of 21.1 million units by US$253 per unit yields approximately US$5.338 billion, close to the reported revenue of US$5.46 billion; the difference reflects other businesses, product classifications, and ASP rounding. This shows that the blended ASP can be reconciled to total revenue rather than being an arbitrary point estimate.
For 2026, total shipments of 30.1 million units multiplied by US$490 per unit yield approximately US$14.749 billion. In Citi’s segment forecasts, high-speed product revenue is approximately US$14.2 billion, mid- and low-speed product revenue approximately US$554 million, and other businesses approximately US$141 million, totaling approximately US$14.895 billion, broadly reconciling the model. For 2027, 60.2 million units multiplied by US$656 per unit yield approximately US$39.491 billion, versus aggregate segment revenue of approximately US$39.604 billion. For 2028, 96.4 million units multiplied by US$675 per unit yield approximately US$65.07 billion, versus aggregate segment revenue of approximately US$65.163 billion.
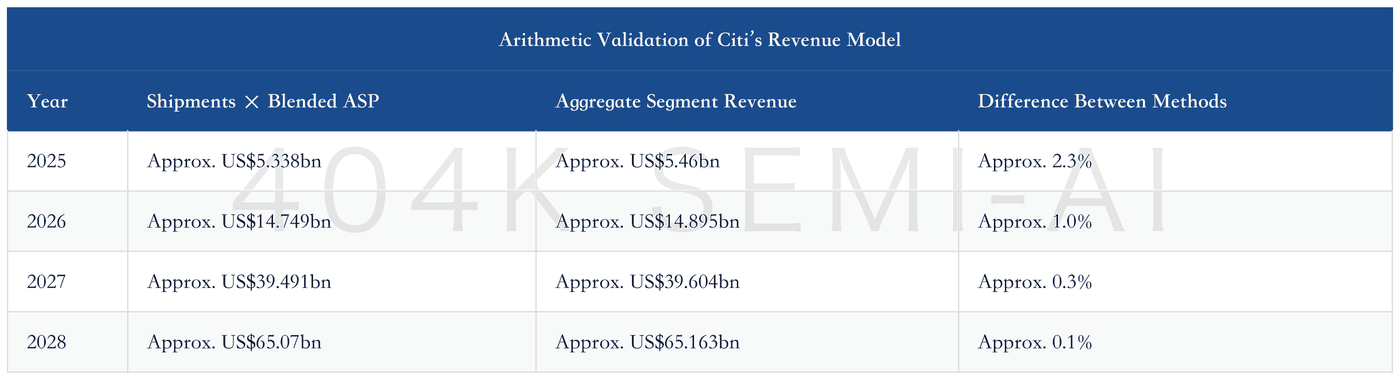
Arithmetic reconciliation only demonstrates that the model has no obvious internal omissions; it does not prove that the inputs will materialize. The outcome remains driven by shipments and pricing for each product generation. Particularly in 2027–2028, the close alignment between aggregate segment revenue and “shipments × blended ASP” indicates that revenue has virtually no buffer against these two inputs: if shipments or blended ASP are 10% lower and the other variable does not compensate, total revenue would be revised down by a similar proportion.
FX also warrants attention. Citi presents product revenue and ASPs in US dollars before translating them into the RMB income statement. RMB appreciation reduces translated revenue, while RMB depreciation increases nominal revenue; however, key components also carry US-dollar costs, so the earnings impact is not unidirectional. Quarterly validation should consider US-dollar revenue, RMB revenue, and gross margin together to avoid mistaking FX movements for changes in product mix.
Between Doubling Capacity and Expanding Margins Lies an Arithmetic Question That Must Be Proven
Zhongji Innolight’s annualized capacity was approximately 28.1 million units in 2025, 1.9 times higher than in 2023; shipments that year were approximately 21.1 million units, implying a simple capacity utilization rate of about 75%. Citi expects the company to expand capacity by approximately 100% in 2026 and by more than 100% again in 2027 to meet global customer demand. Meanwhile, gross margin is forecast to rise from 41.5% to 48.3% and 49.0%.
This creates a tension that requires continued validation. Mechanically doubling 2025 annualized capacity would produce approximately 56.2 million units of capacity in 2026, against forecast shipments of 30.1 million units, implying rough utilization of about 54%. If capacity doubles again in 2027, it would exceed 112 million units, versus forecast shipments of 60.2 million units, again implying rough utilization of about 54%. Because capacity may be commissioned in phases and year-end capacity differs from full-year average capacity, this calculation cannot determine actual utilization directly. It nevertheless highlights that margin improvement cannot rely primarily on fixed-cost absorption and must instead be driven more by product mix, silicon photonics yields, automation, and procurement leverage.
Citi attributes the company’s mass-production advantages to differentiated new-product introduction processes, adaptable equipment, automation and AI-assisted manufacturing, and a multi-site manufacturing network spanning Suzhou, Chengdu, Tongling, Taiwan, and Thailand. Overseas capacity accounted for approximately 71% in 2025, while Citi’s risk section describes Thailand as contributing about half of production. Globalized capacity can mitigate tariff and single-region delivery risks, but it also increases the complexity of cross-regional management, equipment replication, workforce training, and yield ramp-up.
Gross margin depends on whether new plants can rapidly replicate mature production lines; the number of factories alone does not generate profits. High-speed optical modules require coordination across optics, electronics, thermal management, packaging, testing, and firmware. Overly rapid expansion may initially bring depreciation, low yields, and rework before delivering scale benefits. If capacity expands materially faster than shipments in 2026 while gross margin still reaches 48.3%, this would indicate sufficiently strong contributions from silicon photonics and product mix. If gross margin remains near 45%, the US$490 blended ASP, yields, and cost absorption should be reassessed.
Silicon Photonics Determines Margins; CPO Determines How Much Pluggable Modules Will Still Be Worth
Citi views silicon photonics as one of Zhongji Innolight’s most important technology barriers. The company began investing in silicon-photonics optical-module R&D; in 2017 and has achieved commercial scale. According to the report, more than 50% of high-speed products use silicon photonics, and approximately 70% of high-speed product revenue in 1Q26 came from silicon photonics. At the industry level, silicon photonics penetration in the global datacom optical-interconnect market is projected to rise from 38% in 2025 to 73% in 2030.
The investment implications of silicon photonics extend well beyond merely “switching chips.” It integrates more optical functionality into chips and standardized packaging, potentially reducing the number of discrete components, lowering assembly complexity, improving consistency, and broadening supply sources. Early-stage mass production still faces challenges in coupling, packaging, thermal management, testing, and yields, but once scale stabilizes, manufacturing leaders are better positioned to capture declining unit costs.
Zhongji Innolight’s disclosed product roadmap already extends beyond conventional pluggable modules: 800G LR2 coherent compact optical modules, 12.8T 8×DR8 ultra-high-density pluggable optical modules, 400G and 800G linear-drive pluggable optics, as well as near-packaged optics and co-packaged optics R&D.; Ultra-high-density pluggable optics retain the maintenance advantages of modularity; near-packaged optics place the optical engine close to the switch chip, shortening the signal path; co-packaged optics integrate the optical engine more deeply with the switch chip to reduce high-speed electrical signal transmission distances and power consumption.
The closer the technology architecture moves toward the switch chip, the better the power efficiency and density, but the more uncertain the optical-module vendor’s value boundary becomes. Citi explicitly identifies co-packaged optics as a risk: digital signal processors and optical engines may move into the switch-chip package, materially reducing the content value of conventional pluggable modules and changing the competitive landscape. Zhongji Innolight can participate in new architectures through its silicon photonics and optical-engine capabilities, but participation does not mean preserving the legacy revenue-recognition model or margin profile.
Silicon photonics and co-packaged optics therefore should not simply be combined into a single bullish theme. Silicon photonics improves the cost structure and integration capabilities of existing high-speed modules, making it a near-term margin variable; co-packaged optics changes the system-level division of labor, making it a longer-term business-model variable. In the best-case scenario, the company extends its silicon-photonics capabilities from pluggable modules into optical engines, external laser sources, and near-/co-packaged solutions, maintaining its position in the customer value chain. In a weaker scenario, system vendors or switch-chip manufacturers control integration, leaving module vendors with only part of the manufacturing value.
A Declining R&D; Expense Ratio Does Not Mean Lower R&D; Investment
Citi forecasts Zhongji Innolight’s R&D; spending to rise from RMB1.615 billion in 2025 to RMB3.461 billion in 2026, RMB8.277 billion in 2027, and RMB13.534 billion in 2028, representing growth of 114%, 139%, and 64%, respectively. At the same time, the R&D; expense ratio falls from 4.2% to 3.3%, 3%, and 3%. Although the expense ratio declines, revenue is expanding much faster than R&D; investment, while absolute R&D; spending still increases more than eightfold.
Whether this operating leverage is achievable depends on whether R&D; has expanded from individual modules into a platform. The 800G, 1.6T, and 3.2T generations require different optoelectronic chips, packaging, testing, and thermal designs, while near-packaged and co-packaged optics require joint development with the switch-chip, system, optical-engine, and external-laser-source ecosystems. If R&D; is primarily directed toward reusable silicon-photonics platforms, automated testing, and cross-generation packaging, the expense ratio is more likely to decline as revenue scales. If each product generation requires extensive customized engineering, a long-term R&D; expense ratio of 3% may underestimate the required ongoing investment.
