
Zhongji Innolight Deep-Dive Update: Target Price Raised to RMB2,581—How Silicon Photonics, 3.2T and Intra-Rack Interconnects Support a New Earnings Anchor
目录
TL;DR
The Target Price Doubled Because the Underlying Earnings Forecast Doubled
Silicon Photonics Expands Revenue While the Product Mix Lifts Margins
The Model’s Greatest Strength Is Also Its Primary Source of Risk
What the New Report Changes—and What Remains Unchanged
Investment View: RMB2,581 Is a High-Execution Scenario, Not a Foregone Conclusion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman Sachs raised its 12-month target price for Zhongji Innolight from RMB1,187 to RMB2,581, primarily because its 2027 earnings forecast nearly doubled, while the valuation multiple increased only modestly.
TL;DR
This is not a minor model revision. Goldman Sachs raised its 2026–2028 revenue forecasts for Zhongji Innolight by 57%, 100% and 118%, and its net-profit forecasts by 65%, 108% and 119%. Its 2027 EPS estimate increased from RMB34.72 to RMB72.10. Approximately 92% of the increase in the RMB2,581 target price is attributable to earnings upgrades, while the P/E multiple increase from 34.2x to 35.8x accounts for only about 8%.
Silicon-photonics pluggable modules are the primary engine of the new model. Goldman Sachs expects the business to generate revenue of RMB100.22bn, RMB211.588bn and RMB290.189bn in 2026–2028, representing 81%, 85% and 87% of total revenue. Meanwhile, the revenue contribution from conventional electro-absorption-modulated laser modules is projected to decline from 15% to 1%, lifting the blended gross margin from 42% in 2025 to 50.1% in 2028.
The second engine is intra-rack scale-up. Near-package optics, co-packaged-optics engines, fiber-array units, external laser sources and optical circuit switches are now explicitly included in the model. Their combined revenue contribution is expected to rise from 3% in 2026 to 12% in 2028, with an assumed gross margin of approximately 57%. This suggests that Zhongji Innolight is no longer monetizing only inter-rack connectivity; it is also beginning to capture the intra-rack high-speed interconnect profit pool.
RMB2,581 is not a low-risk target. The model assumes that after capacity doubles from 60 million to 120 million units, utilization still rises from 71% to 80%. Zhongji Innolight’s silicon-photonics 3.2T shipments are projected to reach approximately 19.6 million units in 2028, equivalent to about 70% of Goldman Sachs’ global 3.2T shipment forecast. Demand, market share, yield and supply-chain execution must all deliver for the long-term earnings assumptions to hold.
The four most important operating indicators to monitor are whether fourth-quarter 2026 revenue can reach RMB48.341bn, whether gross margin can continue approaching 50%, whether free cash flow can jump from RMB8.5bn in 2026 to RMB62.307bn in 2027, and whether 1.6T, 3.2T and near-package optics can enter volume delivery on customers’ timelines.
The Target Price Doubled Because the Underlying Earnings Forecast Doubled
The headline figure in Zhongji Innolight’s (300308.SZ) new report is RMB2,581, but the change in target price can be decomposed clearly. Goldman Sachs continues to value the company on 2027E P/E: the previous target price was approximately RMB34.72 in EPS multiplied by 34.2x, while the new target price is approximately RMB72.10 multiplied by 35.8x. Replacing only the EPS estimate with RMB72.10 while retaining the 34.2x multiple already yields approximately RMB2,466; increasing the multiple to 35.8x produces the RMB2,581 target.
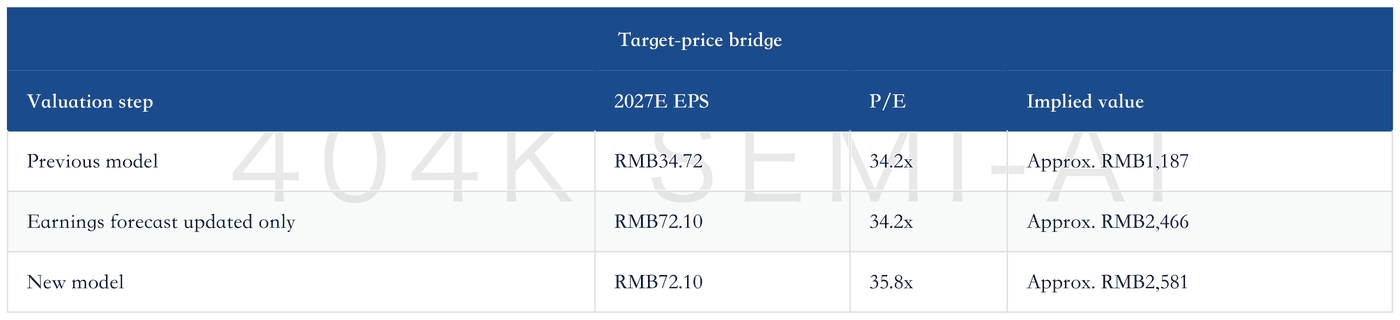
The key question in assessing whether the report is aggressive is therefore whether 2027 net profit can rise from the previous forecast of RMB38.578bn to RMB80.106bn. Goldman Sachs raised its 2026–2028 revenue forecasts to RMB123.649bn, RMB249.63bn and RMB334.038bn, and its net-profit forecasts to RMB38.401bn, RMB80.106bn and RMB109.643bn. Both 2027 revenue and earnings are approximately twice the previous estimates, naturally requiring the target price to be reset.
Zhongji Innolight Deep Dive: Re-Rating a Core AI Optical-Interconnect Holding as 1.6T Takes Over from 800G
Silicon Photonics Expands Revenue While the Product Mix Lifts Margins
Goldman Sachs’ first core thesis is the continued upgrade from 800G to 1.6T and 3.2T. Its global model forecasts approximately 34 million 800G shipments and 26 million 1.6T shipments in 2026. These rise to 45 million and 46 million units in 2027, respectively, while 3.2T begins contributing approximately 13 million units. The demand foundation is the expansion of AI racks and migration to higher network specifications, rather than a simple assumption of price increases within the same product generation.
At the company level, Goldman Sachs positions silicon-photonics pluggable modules as the dominant business. Their revenue contribution is expected to rise from 81% in 2026 to 87% in 2028, with shipments increasing from 25.498 million to 59.191 million units. Silicon photonics increases component integration, reduces assembly complexity and provides greater sourcing flexibility. Once mass-production yields stabilize, cost reductions can be retained in the company’s gross margin. In contrast, the revenue contribution from conventional electro-absorption-modulated laser modules is projected to fall from 15% to 1%, preventing legacy products from weighing on the earnings mix.
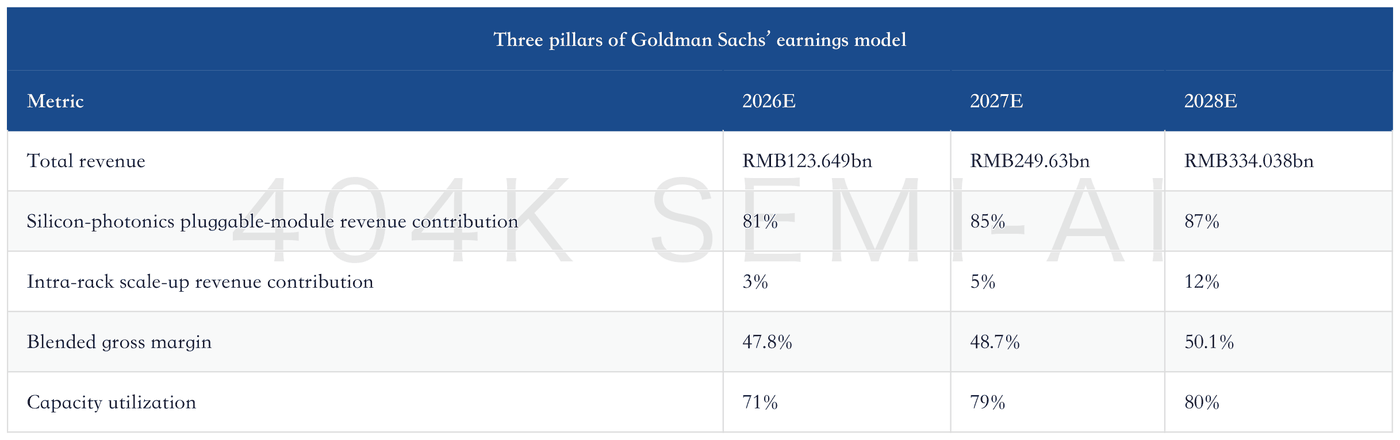
The second thesis is an expansion of the company’s addressable market from inter-rack scale-out into intra-rack scale-up and inter-cluster connectivity. Goldman Sachs expects intra-rack scale-up revenue to increase from RMB4.157bn in 2026 to RMB39.633bn in 2028, with optical-engine shipments rising from 3.6 million to 21.266 million units. The model also includes fiber-array units, external laser sources and optical circuit switches. The assumed gross margin of approximately 57% is materially higher than for the traditional business, providing another driver for the blended gross margin to reach 50.1% in 2028.
The Model’s Greatest Strength Is Also Its Primary Source of Risk
The model derives its strength from multiple variables improving simultaneously, which is also where its risks lie. First, capacity expands from 60 million units in 2026 to 120 million units in 2028, yet utilization does not decline; instead, it rises from 71% to 80%. This requires customer demand to grow faster than capacity and the company to maintain yields while rapidly hiring staff, commissioning equipment and introducing new products.
Second, Goldman Sachs expects Zhongji Innolight’s silicon-photonics 3.2T shipments to reach approximately 19.599 million units in 2028, versus its global 3.2T shipment forecast of approximately 28.162 million units. This implies a market share of nearly 70%. The assumption is that the company will retain an unequivocally central position even after the technology transition. Revenue and earnings would be highly sensitive to faster qualification of new suppliers, greater procurement diversification by customers or a later-than-expected 3.2T ramp.
