
Zhipu Deep-Dive Update: Kimi K3 Resets Valuation; Price Target Cut to HK$1,600, but ARR Growth Thesis Remains Intact
目录
TL;DR
Valuation Reset First; Revenue Thesis Remains Intact
Why Kimi K3 Is Sufficient to Change the Long-Term Valuation
Why a Correction of More Than 50% Did Not Directly Break ARR
The Quality of US$1bn in ARR Must Be Assessed Across Four Layers
Why Zhipu Remains in the Frontier Cohort
The Financial Requirements Behind the HK$1,600 Price Target
From Model Launch to Valuation, the Transmission Chain Is Far from Short
Four Falsification Conditions Matter More Than Daily Rankings
Conclusion: Zhipu Shifts from “Long-Term Winner” to “Persistent Frontier Participant”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Kimi K3 has undermined the notion that Zhipu can maintain a long-term monopoly at the model frontier, but it has not disrupted the company’s annual recurring revenue growth trajectory. The valuation has been reset downward; commercialization still needs to be validated by the next model release and operating data.
TL;DR
JPMorgan’s downgrade primarily targets the valuation multiple, not Zhipu’s earnings assumptions. Its December 2026 price target was cut from HK$2,400 to HK$1,600, mainly because the projected 2030 P/E multiple was reduced from 30x to 20x. The 2030 forecasts of RMB17.5864 billion in revenue, RMB5.038 billion in adjusted net profit, and RMB106 in adjusted EPS were not materially reduced, while the rating remains “Overweight.”
Kimi K3 has changed what the market should pay a premium for. China’s strongest model has changed roughly every one to two months over the past year, making it increasingly difficult for any single company to remain No. 1 over the long term. High valuations should no longer reward a single model generation for topping the rankings. They should reward companies that remain in the frontier cohort across multiple generations, convert their models into stable API revenue, and demonstrate manageable inference costs.
A decline of more than 50% in Zhipu’s share price does not imply a corresponding decline in ARR. JPMorgan cites Zhipu’s ARR of approximately US$1 billion as of July 2026, versus roughly US$2.1 billion for China’s four leading independent model vendors combined and approximately US$69 billion for Anthropic. Although these figures are not entirely comparable, the difference in scale suggests that commercialization of Chinese models remains at an early stage. The current constraint appears to be insufficient compute supply rather than several companies competing for a fixed demand pool.
Zhipu remains in the frontier cohort, which is the key distinction between it and MiniMax. JPMorgan still ranks GLM-5.2 among China’s top two or three models. GLM-5.3 is expected to launch between late July and August 2026, while a flagship model with more than 2 trillion parameters is expected in September or October. Zhipu does not need to lead every benchmark, but it must demonstrate that it can repeatedly return to the frontier across successive model cycles.
Investors should track four sets of operating metrics, not just model scores. First, ARR and enterprise API usage growth; second, customer retention for high-value coding and agentic tasks; third, inference utilization, service costs, and gross margin; and fourth, whether adjusted net profit turns positive in 2028 as projected. If any of these metrics materially underperform, the 20x forward P/E multiple could compress further.
Valuation Reset First; Revenue Thesis Remains Intact
The most important takeaway from this report is the distinction between a lower price target and reduced fundamental forecasts. On July 12, JPMorgan raised its Zhipu price target from HK$2,000 to HK$2,400, arguing that approximately US$4 billion in financing would ease inference-service capacity constraints and improve visibility into ARR over the next 12 months. Nine days later, it cut the target to HK$1,600. This may look like an abrupt reversal in the investment thesis, but the change occurred mainly on the valuation side.
Zhipu Deep-Dive Update: US$4 Billion Financing Eases Inference-Capacity Bottleneck; JPMorgan Raises Price Target Again to HK$2,400
The previous report addressed whether capital could be converted into revenue; the new report addresses what multiple that revenue deserves. The financing thesis remains intact: additional capital can expand training and inference resources, converting existing API and enterprise demand into recognized revenue. The new issue introduced by Kimi K3 is that even if Zhipu continues to grow revenue, it can no longer command a 30x forward P/E multiple on the assumption that it will maintain a long-term monopoly at China’s model frontier. Model leadership is more likely to rotate, requiring investors to discount uncertainty around Zhipu’s technological position.
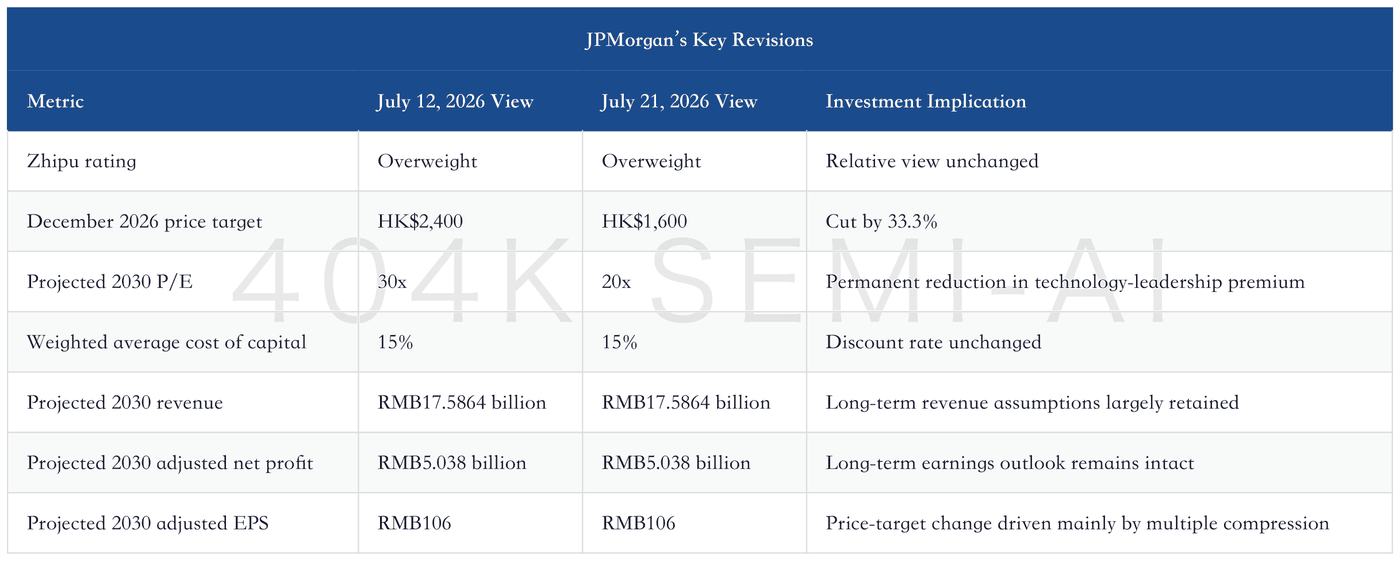
The reduction in the price target from HK$2,400 to HK$1,600 closely matches the reduction in the valuation multiple from 30x to 20x. Both revisions were made by the same institution, for the same H-shares and in the same currency, while the new report explicitly states the previous target, so no additional conversion for security units or corporate actions is required. This relationship indicates that JPMorgan does not interpret K3 as evidence of a collapse in Zhipu’s revenue. Instead, it views K3 as increasing the risk premium attached to model assets.
This is also the key to understanding the latest share-price volatility. Changes in model rankings typically affect the forward multiple investors are willing to pay before they affect financial forecasts through customer usage, contract renewals, and pricing. The former can occur within days; the latter requires at least several months of operating data. The market’s removal of the “perennial champion” premium does not mean it has direct evidence that Zhipu’s revenue is weakening. Likewise, the remaining upside to the price target cannot substitute for subsequent operating validation.
The weighted average cost of capital remains at 15%, further narrowing the source of the revision. Had JPMorgan also raised the discount rate, the lower price target could have reflected a broad-based increase in financing, policy, or cash-flow risk. With the discount rate unchanged and long-term earnings assumptions largely intact, the main revision is concentrated in the terminal valuation multiple. This indicates that K3 has changed the assessment of the competitive structure: model companies can still build large businesses, but individual companies are less likely to command pricing associated with a near-platform monopoly.
Why Kimi K3 Is Sufficient to Change the Long-Term Valuation
What K3 has truly disrupted is the assumption of a single long-term winner. Foundation-model capabilities do not follow a stable ranking that extends only in one direction. Changes in architecture, training data, reinforcement learning, infrastructure, or inference optimization can reshuffle the leaderboard after a single version release. JPMorgan observes that China’s strongest model has changed roughly every one to two months over the past year and expects this rotation to continue after models with more than 2 trillion parameters launch in rapid succession between August and October 2026.
This makes it highly risky to extrapolate five years of revenue and profit directly from a single model generation’s No. 1 ranking. Zhipu’s GLM-5.2 may lead today, Kimi K3 may change the market narrative the following week, and subsequent releases from Alibaba, DeepSeek, MiniMax, or Zhipu may once again alter their relative positions. Model companies should no longer be valued on a winner-takes-all basis. They increasingly resemble a group of frontier laboratories that must continually requalify.
Kimi K3 Deep Dive: 2.8 Trillion Parameters, Coding Agents, and the Inflection Point in Chinese Models’ Pricing Power
