
Zhipu AI Deep-Dive Update: US$4bn Financing Eases Inference Capacity Bottleneck; JPMorgan Raises Target Price Again to HK$2,400
目录
TL;DR
I. What Has Changed in This Upgrade
II. How Much Growth Capacity Does US$4bn Buy?
III. How Is the HK$2,400 Target Price Derived?
IV. Four Metrics to Monitor
V. Financing Reduces Funding Risk but Raises the Valuation Hurdle
VI. Conclusion: The Upgrade Thesis Is Becoming More Verifiable
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
JPMorgan has raised its target price for Zhipu AI from HK$2,000 to HK$2,400 within five days, maintaining its Overweight rating. The revision reflects approximately US$4bn in financing that should ease inference-service capacity constraints and convert existing enterprise and API demand into recognizable annual recurring revenue over the next 12 months. The valuation methodology is unchanged; the earnings model has improved.
TL;DR
The upgrade is driven by earnings revisions. JPMorgan retains its existing P/E multiple and discount-rate assumptions while raising its target price to HK$2,400; its 2030 adjusted EPS forecast increases to CNY106. The valuation framework has not been expanded. The higher target price mainly reflects upward revisions to revenue and profit forecasts.
The financing first addresses inference-service supply. Zhipu AI plans to place 19.78mn new H shares, raising estimated net proceeds of HK$31.375bn, or approximately US$4bn. JPMorgan believes existing API and enterprise demand is approaching Zhipu AI’s service-capacity ceiling. Additional compute capacity should enable the company to convert existing demand into annualized revenue more quickly over the next 12 months.
Revenue upgrades are concentrated from 2027 onward. JPMorgan raises its revenue forecasts for the next five years by 7%–13% and increases its 2028 adjusted net profit forecast to CNY4.12bn. The market now needs to assess utilization, API call volumes, and gross margin after the new capacity comes online—not merely the size of the financing.
The July 7 and July 12 upgrades reflect two distinct layers of the thesis. The earlier upgrade focused on the optionality created by distributing open-weight models through external clouds and inference platforms. The latest upgrade adds a nearer-term monetization path: using fresh capital to expand inference supply and convert existing customer demand into annual recurring revenue. The latter is easier to validate through operating data.
Ample funding does not eliminate product risk. The company still needs to demonstrate that subsequent models such as GLM-5.5 can remain competitive and that revenue from coding agents, enterprise APIs, and cloud services can cover rising compute costs. The placement will dilute post-placement share capital by approximately 4.25%, while the placement price represents a 12.99% discount to the pre-announcement closing price. The elevated valuation remains sensitive to execution shortfalls.
I. What Has Changed in This Upgrade
JPMorgan has reframed Zhipu AI’s near-term constraint from “whether demand exists” to “whether it can provide sufficient service capacity.” Its July 7 report raised the target price from HK$1,800 to HK$2,000, mainly based on the commercialization optionality of open-weight models. These models can expand their reach through external clouds, inference-service providers, and enterprise infrastructure, while Zhipu AI monetizes official APIs, supported enterprise endpoints, licensing, and coding workflows. That thesis offered greater distribution upside but remained primarily a medium-term opportunity.
Zhipu AI Deep Dive: A Chinese Test Case for Pricing Power at the Model Layer—Can the Coding-Agent and API Flywheel Outrun Compute Costs?
The new information on July 12 is more directly linked to financial delivery. JPMorgan believes demand from Zhipu AI’s existing enterprise customers and APIs is already straining its inference-service capacity. Approximately US$4bn in fresh capital can fund the purchase or leasing of cloud compute, improve compute-resource scheduling, and support subsequent model training. Inference resources directly determine whether customers can access the service and whether usage can grow, making their revenue impact more immediate over the next 12 months. Training investment determines the competitiveness of next-generation models and has a longer payback period.
This gives the latest target-price increase a clearer validation chain: proceeds received, inference resources expanded, API call volumes increased, annual recurring revenue raised, fixed compute costs better absorbed, and profit forecasts upgraded. Each link can be monitored through subsequent operating data.
II. How Much Growth Capacity Does US$4bn Buy?
The company announcement confirms the financing size, while the conversion into inference capacity reflects JPMorgan’s operating assumptions. Zhipu AI plans to place 19.78mn new H shares at HK$1,588 per share, with estimated net proceeds of HK$31.375bn. The new shares represent approximately 4.44% of pre-placement share capital and 4.25% of post-placement share capital. Disclosed uses include R&D; and compute resources, commercial expansion, strategic investments and M&A;, and working-capital replenishment. The company plans to deploy the proceeds by the end of 2027 but has not disclosed the allocation across categories.
The financing’s value depends on deployment speed and output per unit of compute. Zhipu AI raised approximately HK$4.896bn in net proceeds from its listing and had used approximately HK$4.588bn by the end of June, representing a utilization rate of more than 93%. The rapid deployment of existing funds confirms that model development and commercial expansion require sustained capital. The new financing is approximately 6.4 times the net proceeds from the IPO, sufficient to expand resources materially but also increasing management’s capital-allocation responsibility.
The first test after inference supply expands is whether real customers use the additional compute. The second is whether higher usage translates into relatively stable annual recurring revenue. The third is whether cloud-service and API gross margins improve as utilization rises. If compute comes online before paid usage grows commensurately, depreciation, leasing, and bandwidth costs will weigh on profits first.
III. How Is the HK$2,400 Target Price Derived?
The valuation multiple and discount rate are unchanged, while earnings forecasts have moved higher across the board. JPMorgan continues to base its valuation on 2030 adjusted EPS, applying a 30x P/E multiple and discounting the result at 15%.
Its 2030 adjusted EPS forecast increases from CNY91 to CNY106, with the additional shares from the placement already incorporated into the model.
The target price rises by 20%, from HK$2,000 to HK$2,400.
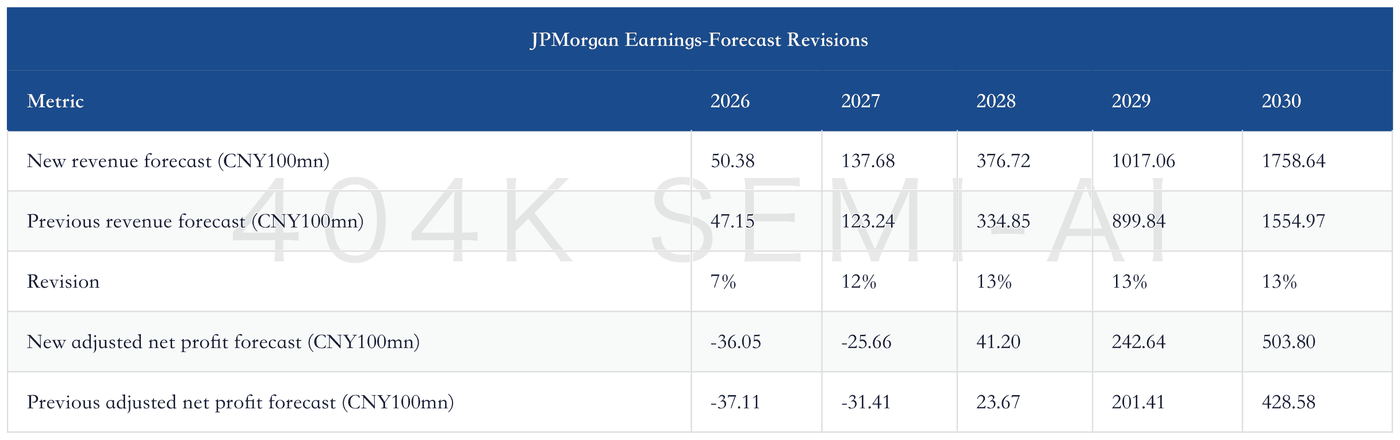
Profit improvement outpacing revenue growth is the most important source of operating leverage in the revised model. The 2027 loss forecast narrows by CNY575mn, while the 2028 adjusted net profit forecast increases by CNY1.753bn. This indicates that JPMorgan is assuming both greater revenue scale and improved unit economics. The assumptions require higher inference utilization, relatively stable API pricing, and a customer mix shifting toward high-frequency enterprise usage.
