
目录
I. Behind RMB954 Million in Revenue, Zhipu AI Has Become a Different Business
II. Cloud Gross Margin Turns Positive, but the Revenue Mix Weighs on Consolidated Margin
III. No Inflection in the Income Statement Yet, but Loss Margins Have Narrowed Sharply
IV. US$1.6 Billion of ARR Is Impressive—but Demands the Strictest Definition
V. Unit Token Costs Fell 80%, but Total Compute Spending Is Still Rising
VI. The HK$31.375 Billion Placement Shifts the Constraint from “Does It Have the Money?” to “Can the Money Generate Gross Profit?”
VII. Coding Is the Proven Entry Point, but Co-worker Determines the Long-Term Revenue Ceiling
VIII. Valuation Will Shift from the Model Narrative to Three Forms of Financial Evidence
IX. Eight Metrics to Watch in the Next Earnings Report
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Zhipu AI has moved beyond proving that demand exists, but has yet to demonstrate that revenue can cover R&D; and compute costs. API revenue surged 27-fold and cloud gross margin turned positive. US$1.6 billion in ARR suggests growth is still accelerating, but this remains a management-defined annualized run-rate figure.
I. Behind RMB954 Million in Revenue, Zhipu AI Has Become a Different Business
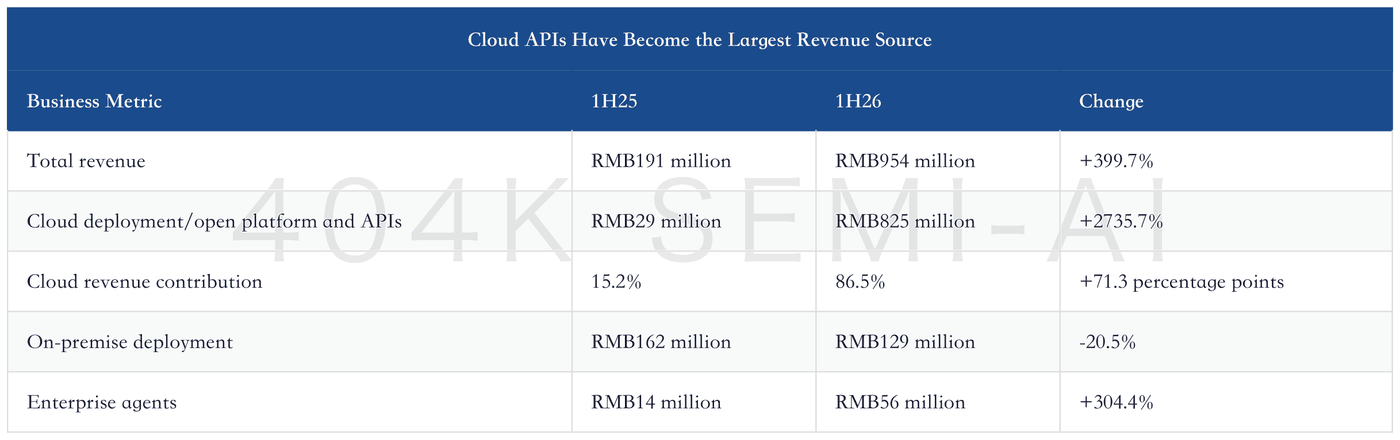
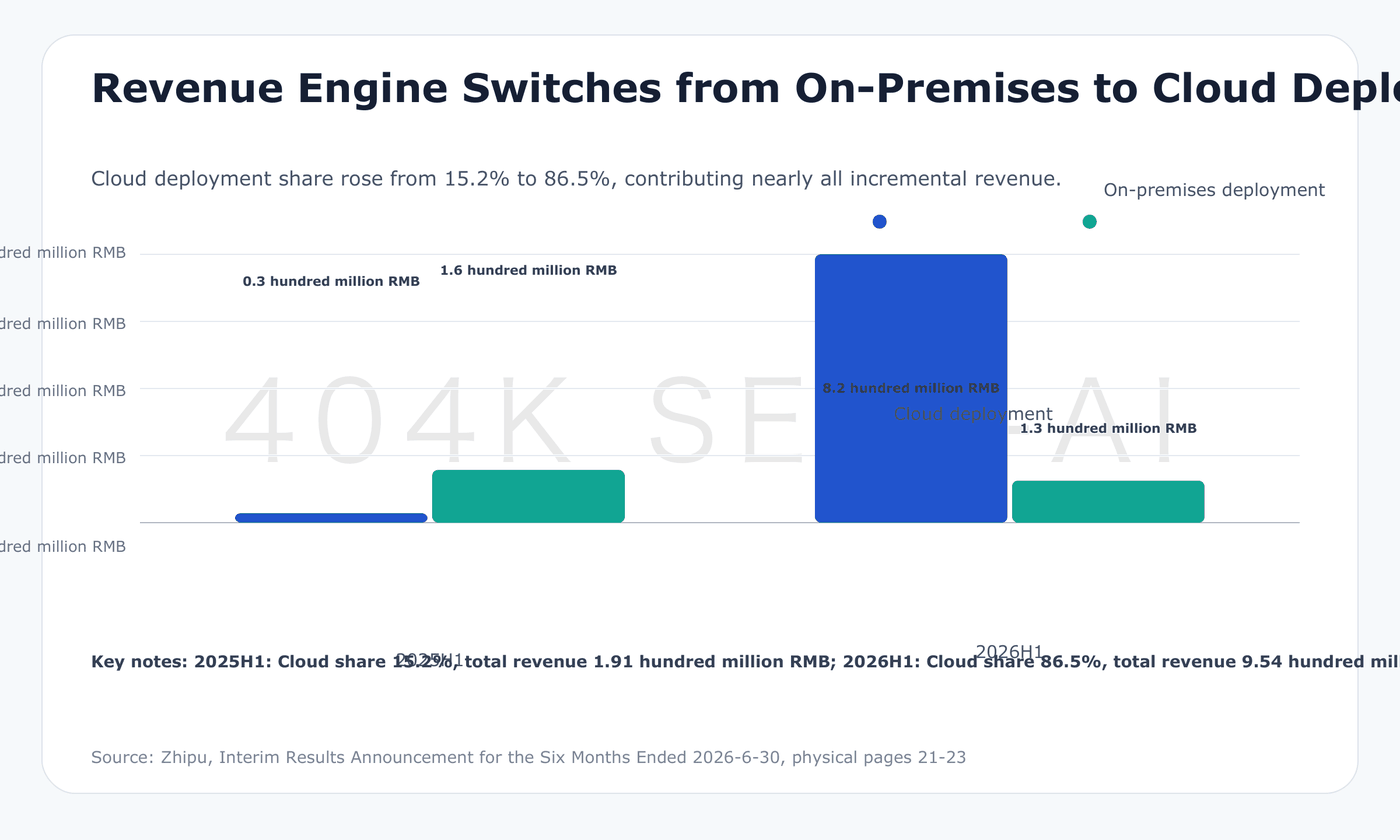
The biggest change in the first half of 2026 was Zhipu AI’s shift from on-premise projects to cloud usage. Revenue reached RMB954 million, up 399.7% year over year. Open-platform and API revenue rose 2735.7% to RMB825 million, accounting for 86.5% of total revenue, versus just 15.2% a year earlier.
These figures show that Zhipu AI is no longer primarily dependent on one-off large-model project deliveries. Customers are increasingly paying for usage, subscriptions, and recurring workloads. Cloud revenue is no longer merely a proxy for developer activity; it is now the company’s primary reported revenue stream.
The company’s official segment reporting confirms the shift. Cloud-deployment revenue was RMB825 million, while on-premise deployment revenue was RMB129 million. The latter fell 20.5% year over year, with its revenue contribution dropping from 84.8% to 13.5%. Cloud growth more than offset the contraction in on-premise business and lifted total revenue to nearly five times the prior-year level.
By product line, enterprise-agent revenue increased 304.4% to RMB55.56 million; enterprise general-purpose large-model revenue declined 54.6% to RMB67.04 million; and technical services and other revenue totaled RMB6.12 million. Open-platform and API revenue exactly matched cloud-deployment revenue, while the other three product lines comprised on-premise revenue.
The growth in enterprise agents and contraction in general-purpose large models also point to a change in purchasing behavior. Traditional on-premise projects were closer to “delivering a model to the customer,” making revenue highly dependent on individual project acceptance. Agents embed models into enterprise workflows, so customers are paying for task execution, system integration, and continuous optimization.
This transition remains at an early stage. Enterprise-agent revenue was only RMB55.56 million, or 5.8% of the total—too small to support a second growth engine on its own. Its significance lies in showing that enterprise customers are moving beyond model-capability testing toward workflow deployment. If agent revenue sustains rapid growth, the on-premise business could evolve from general-model delivery toward systems more closely tied to business outcomes.
The 54.6% decline in enterprise general-purpose large-model revenue may also reflect deliberate reprioritization. As the company shifted resources toward cloud APIs, Coding, and Agent offerings, on-premise general models became less important. If customers merely migrated existing on-premise deployments to the cloud, this would represent a change in revenue format. Only a reduction in existing projects without migration to the platform would indicate genuine demand loss. The announcement did not disclose customer migration data, so the two cannot yet be distinguished.
This mix shift is critical to the investment case. On-premise projects typically carry larger contract values, longer delivery cycles, and heavier customization requirements. API and subscription revenue can generate recurring usage, but places greater demands on inference costs, platform reliability, and customer retention. Whether Zhipu AI’s revenue quality improves will depend on whether usage persists—and how much gross profit the company retains from each yuan of usage revenue.
II. Cloud Gross Margin Turns Positive, but the Revenue Mix Weighs on Consolidated Margin
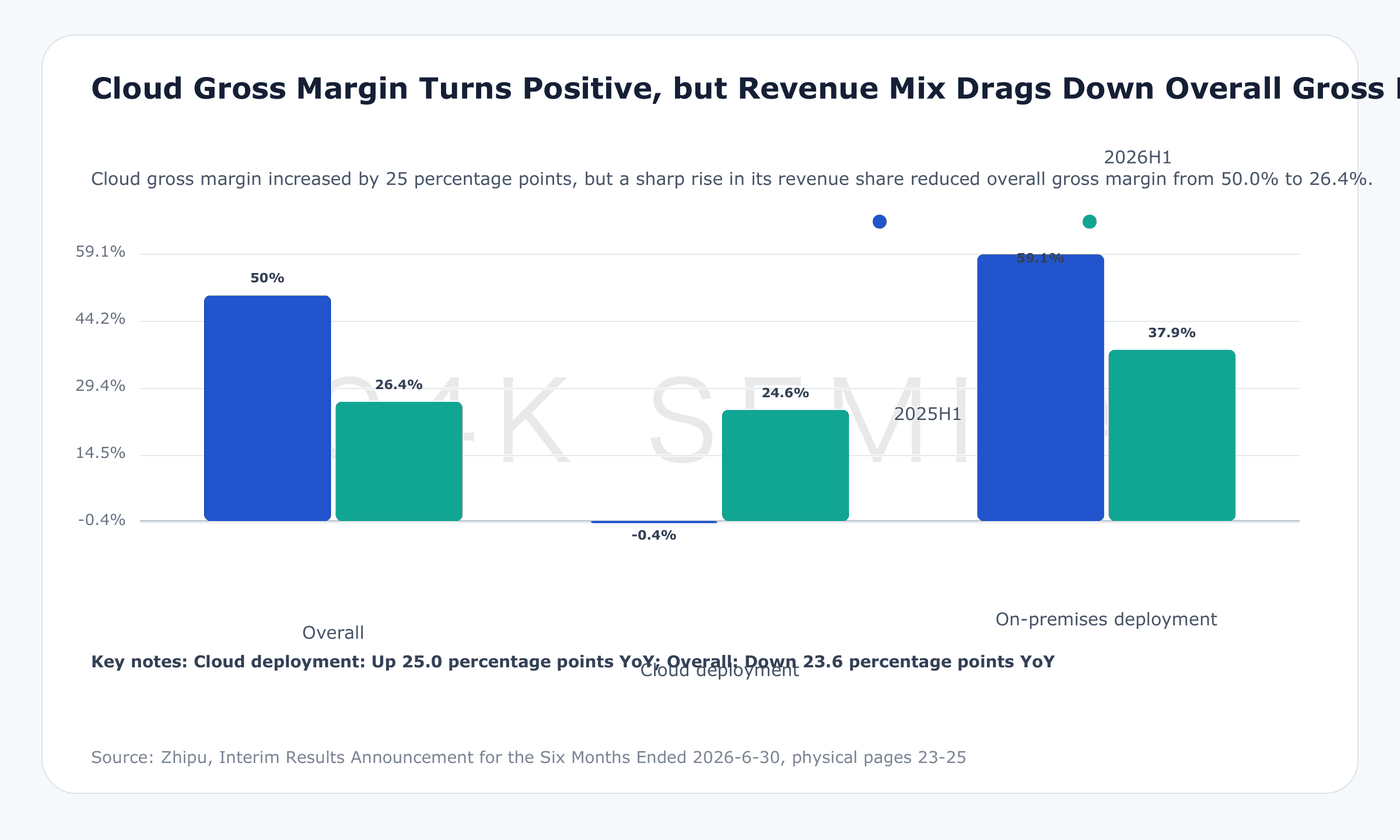
Cloud unit economics have clearly improved. In the first half of 2026, cloud-deployment gross margin reached 24.6%, versus -0.4% a year earlier. Cloud gross profit rose to RMB203 million, accounting for the vast majority of companywide gross profit. The fact that rapid scaling no longer produces negative gross profit is the most important positive signal in these results.
However, consolidated gross margin fell from 50.0% to 26.4% because of the revenue mix. On-premise deployment accounted for 84.8% of revenue a year earlier and carried a 59.1% gross margin. Its revenue contribution fell to 13.5% in the current period, while its gross margin declined to 37.9%. The contraction of the higher-margin on-premise business and rapid expansion of the lower-margin cloud business naturally diluted the consolidated margin.
This does not diminish the significance of cloud margin turning positive, but the two issues should be assessed separately. The first is whether the API business can generate profit; a 24.6% gross margin provides a provisional affirmative answer. The second is whether the company itself can become profitable; current gross profit remains far too small to cover R&D;, sales, administrative, and financing costs.
Product-line margins show a similar divergence. Open-platform and API gross margin matched cloud deployment at 24.6%; enterprise agents generated a gross margin of approximately 35.6%; enterprise general-purpose large models, 42.3%; and technical services and other, just 9.4%. Gross margins for all three latter categories declined year over year.
Cloud gross margin still needs to rise further. Greater inference scale can spread platform and engineering costs, while model optimization can reduce the compute required for a given task. Conversely, price competition, discounted traffic, and long-context usage for complex tasks could push margins down again. The 24.6% margin shows that the business model is gaining a foothold, but does not yet demonstrate that it can consistently reach mature software-company profitability.
III. No Inflection in the Income Statement Yet, but Loss Margins Have Narrowed Sharply
Zhipu AI generated only RMB252 million in gross profit in the first half, against RMB2.131 billion in R&D; expenses. R&D; spending was approximately 8.5 times gross profit, meaning gross profit covered only about 11.8% of R&D; investment. These two figures alone explain why the company continues to report substantial losses.
R&D; expenses rose 33.6% year over year—well below revenue growth—but increased by RMB537 million in absolute terms. Cost of sales surged 635.4% to RMB702 million, outpacing revenue growth. Operating loss widened from RMB1.899 billion to RMB2.147 billion, indicating that higher gross profit has yet to offset the expansion in R&D; and other costs.
The rise in R&D; spending was not simply the result of headcount growth. Full-time employees totaled 981 at period-end, versus 883 a year earlier—an increase of approximately 11.1%, well below the 33.6% growth in R&D; expenses. Investment intensity is increasing across training compute, data environments, infrastructure engineering, and senior talent.
General and administrative expenses fell 44.2% year over year, while share-based compensation declined from RMB159 million to RMB85.76 million, suggesting that listing-related and organizational overhead is receding. R&D; and compute remain the main sources of operating leverage, while back-office costs are showing some discipline. Rising financing costs and financial-asset impairments offset part of these efficiency gains.
Lower share-based compensation also makes the reported loss appear to improve more quickly. Adjusted net loss adds back share-based compensation and is therefore more useful for assessing the underlying operating trend. Even so, it remains sensitive to the timing of R&D;, compute procurement, and revenue seasonality, and should not be treated as a stable forward loss level.
