
Yuanjie Technology Update: 1.6T, 3.2T and CPO Push Domestic CW Light Sources Toward a Global Optical-Chip Entry Ticket
目录
Too Long; Didn’t Read
I. What Changed in This Update: Yuanjie Moves From Order Elasticity to a Global-Share Narrative
II. Nomura’s Core Model: Revenue Rises From RMB1.803 Billion to RMB7.863 Billion in 2026-2028
III. 1.6T Remains the Profit Anchor for the Next Two Years; 2.4T and 3.2T Push Demand Further Out
IV. CW Light Sources Are Yuanjie’s Revenue Mainline: 70/100mW Delivery, Followed by >100mW
V. NPO/CPO Turns 300mW from an R&D Project into a Long-Term Ticket
6. How Global Share Changes: From No. 1 in China to About 32% CW Share in 2028
7. Why IDM Matters More: Epitaxy, Testing, and Yield All Become Share
8. What the Neutral Rating Means: Growth Has Not Deteriorated, but Valuation Has Already Moved Ahead to 2028
IX. Risks and Disconfirmation: Customers, Gross Margin, CPO Timing, Competitive Capacity Expansion
X. Follow-Up Tracking Checklist: What to Watch Over the Next Four Quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Nomura’s initiation shifts the research focus on Yuanjie Technology from 70mW/100mW orders to the entry ticket for 1.6T, 3.2T and CPO light sources. The debate is straightforward: three years of high earnings growth are visible, but the share price has already priced in expectations of becoming a global optical-chip leader by 2028. The key question is whether high-power light sources can deliver global share and margins.
Too Long; Didn’t Read
Nomura assigns a Neutral rating. Its target price is RMB1,655, slightly below the report’s reference closing price; valuation is based on 2028 earnings and a 65x P/E. The growth logic remains very strong, but triple-digit revenue and net-profit CAGR has already been substantially reflected in the share price.
1.6T remains the main driver over the next two years. Nomura estimates global 1.6T optical-module shipments will rise to 126 million units by 2028, while 800G continues to grow and 2.4T and 3.2T begin to take over. Rate upgrades push demand for high-power CW light sources further out and extend Yuanjie’s validation cycle from a single order to multiple product generations.
CW light sources are Yuanjie’s revenue axis. Nomura expects Yuanjie’s CW laser-chip revenue to rise from RMB393 million in 2025 to RMB7.337 billion in 2028, with the revenue share increasing from 65% to 93%. Within this, 70/100mW products drive 2026-2027 delivery, products above 100mW post an estimated 2026-2028 revenue CAGR of about 90%, and products above 300mW begin to capture NPO/CPO demand from 2028.
Rising global share is the incremental variable. By Nomura’s definition, Yuanjie ranked sixth in global external laser-chip sales revenue in 2025, with 3.1% share; in high-speed interconnect chips such as EML above 100G and CW above 50mW, its share was 4.3%, ranking first among mainland Chinese suppliers. In the model, Yuanjie’s global optical-chip share rises from 4.3% in 2026 to 10.5% in 2030, while its CW laser-chip share reaches 31.8% in 2028.
Valuation risk is already on the table. Whether high gross margins can hold depends on yields for products above 100mW, customer price negotiations, and competitors’ capacity-expansion pace. The largest customer still accounts for a high share, while capacity expansion and Hong Kong listing financing will also weigh on free cash flow. Valuation upside requires sustained delivery from new products.
Track four sets of numbers from here. First, whether data-center revenue and gross margin continue in 2Q and 3Q. Second, shipments, ASP and customer certification for 100mW products. Third, whether 300mW, external laser source and NPO/CPO projects enter sample, validation or small-batch stages. Fourth, customer concentration, overseas capacity and cash flow, to confirm whether Yuanjie can move from order-driven elasticity to a global optical-chip platform.
I. What Changed in This Update: Yuanjie Moves From Order Elasticity to a Global-Share Narrative
The value of Nomura’s initiation lies in moving the research framework for Yuanjie Technology from “near-term earnings elasticity brought by AI optical-module orders” to the medium- and long-term question of “global optical-chip share migration.” The market had already seen volume ramp in Yuanjie’s 70mW CW light sources, rapid data-center revenue growth and progress in 100mW product validation. Nomura’s report breaks these clues into three clearer timelines: 2026-2027 depends on continued 1.6T volume ramp, post-2028 depends on 2.4T, 3.2T and NPO/CPO, and through 2030 depends on whether light sources above 100mW and above 300mW can become Yuanjie’s new revenue axis.
Under the old framework, Yuanjie looked more like a scarce domestic CW light-source supplier upstream of AI optical modules. Under the new framework, Yuanjie has to answer a more demanding question: can it move from 3.1% external sales share in the global laser-chip market in 2025 to roughly 10% share of the overall optical-chip market by 2030; can it push its share of the CW laser-chip segment to 31.8% in 2028; and can it turn EML, CW above 300mW and external laser sources into a second growth curve.
Nomura’s target price lays out this debate plainly. It assigns a Neutral rating and a target price of RMB1,655, based on 2028 EPS of RMB25.47 and a 65x P/E. Based on the July 7 closing price of RMB1,715.04, the implied upside under the report’s methodology is -3.5%. This shows the sell-side model already embeds very strong profit growth, but the share price has also discounted a large portion of 2028 earnings.
So this update does not repeat the old logic that “AI optical modules drive volume growth for domestic light sources.” What is more worth unpacking are three new questions: first, why Nomura is willing to push Yuanjie’s 2028 revenue to RMB7.863 billion; second, which product cycles correspond to light sources above 100mW and above 300mW; third, with the share price already priced off 2028, which numbers should be used over the next four quarters to verify or falsify the thesis.
II. Nomura’s Core Model: Revenue Rises From RMB1.803 Billion to RMB7.863 Billion in 2026-2028
Nomura’s model is aggressive, with 2028 revenue and net-profit forecasts pushed to RMB7.863 billion and RMB3.171 billion, respectively. The table below puts revenue, profit, EPS and margins together. The key point is the rapid increase in the data-center business mix.
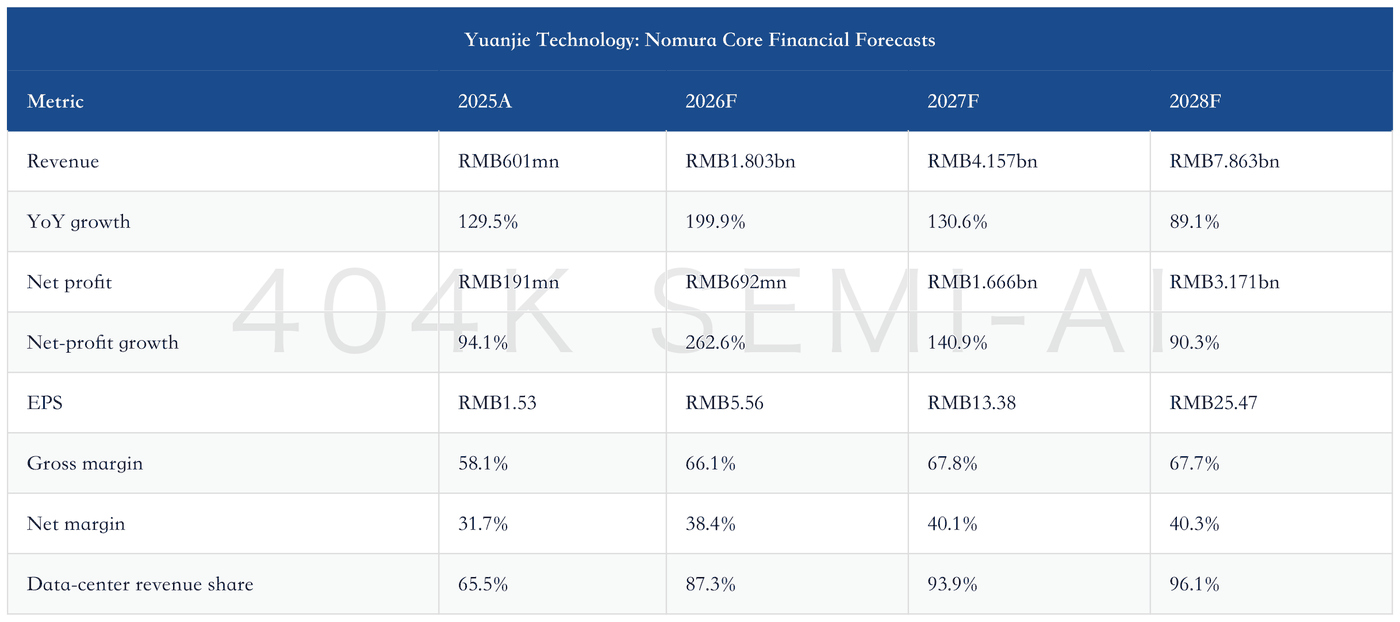
The most important part of this forecast set is that margins and revenue mix change at the same time. The data-center business becomes the main axis. The telecom business still retains the process and cash-flow foundation, but has already moved to the second layer of the model.
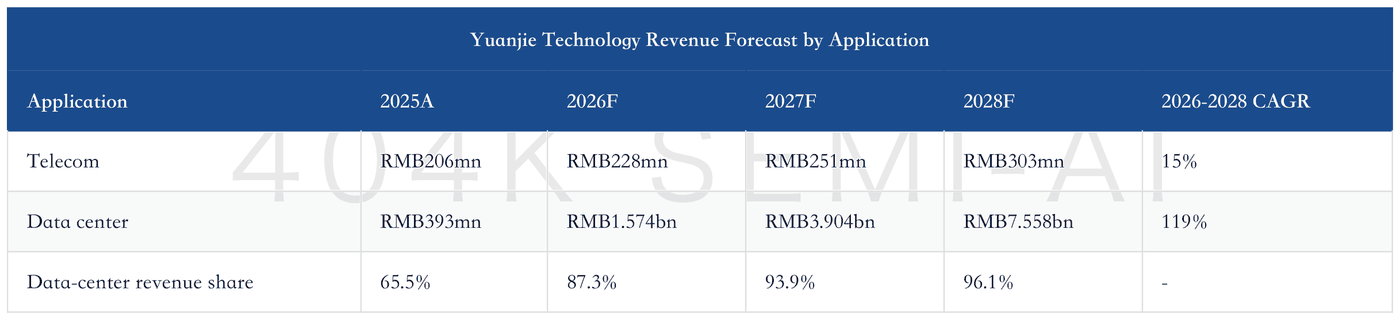
This means Yuanjie’s valuation is now largely determined by data-center light sources. The telecom business still provides a foundation in process, customers and cash flow, but what investors are really pricing is 70mW, 100mW and CW above 100mW, followed by light sources above 300mW and EML. If data-center revenue ramps smoothly, Yuanjie will move from a domestic telecom optical-chip company to a global AI interconnect optical-chip company. If data-center volume growth or gross margin falls short of expectations, valuation will quickly revert to a discount for “single major customer and single product cycle.”
Nomura’s model also implies a higher requirement: Yuanjie’s margins must remain in a very high range. Gross margin was 58.1% in 2025, is forecast at 66.1% in 2026, and remains at about 68% in 2027-2028; net margin rises from 31.7% to around 40%. This type of margin can only be supported by high-power CW, high yield, in-house epitaxy and customer shortages. Once competitors expand capacity, customers add second suppliers, or yield ramp for high-power products is slow, the margin assumptions will be more sensitive than the revenue assumptions.
III. 1.6T Remains the Profit Anchor for the Next Two Years; 2.4T and 3.2T Push Demand Further Out
The performance anchor for Yuanjie over the next two years remains the transition from 800G to 1.6T. Nomura expects the global data-center optical module market to sustain high growth in 2026-2028, with 1.6T as the most important source of incremental demand, while 800G will not exit immediately.
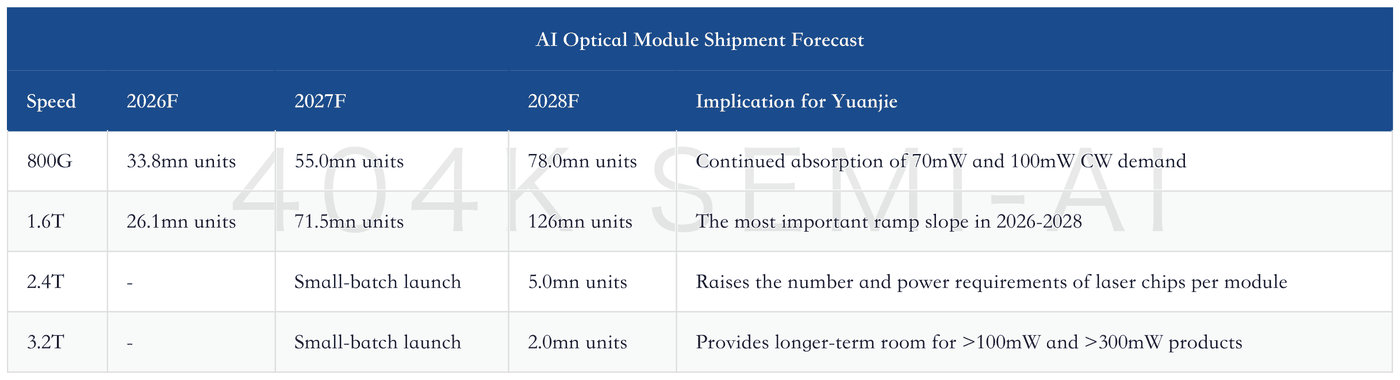
The key significance of 1.6T is that it concentrates each optical module’s demand for high-power continuous-wave light sources. Silicon photonics solutions typically require an external or integrated CW light source as the optical carrier, with the backend using modulators to load signals. As speeds rise, channel count, per-channel power, thermal management, and coupling loss all become harder to manage. Laser chips move from “able to supply” toward “high power, stability, low noise, low drift, and high yield.”
The value of 2.4T and 3.2T lies in extending the cycle. Optical module companies, switch-chip companies, and cloud providers cannot stop at 1.6T. Subsequent speed upgrades will continue to raise requirements for higher-power CW light sources, EMLs, and external laser sources. Nomura places the launch of 2.4T and 3.2T in 2027-2028, with combined shipments of 7.0mn units in 2028. The near-term absolute volume is not large, but these products will influence customer qualification, R&D; investment, and the longer-term valuation narrative after 2027.
This is especially important for Yuanjie. In 2025, the company’s data-center revenue had already reached RMB393mn, up 719.1% YoY, with a gross margin of 72.2%. In 1Q26, revenue was RMB355mn and net profit was RMB179mn, with a single quarter already close to full-year 2025 net profit. Part of the short-term earnings elasticity has already been realized. For valuation to continue moving higher, the company needs to prove that 1.6T orders can extend into a continuous product ladder across 2.4T, 3.2T, NPO, and CPO.
IV. CW Light Sources Are Yuanjie’s Revenue Mainline: 70/100mW Delivery, Followed by >100mW
In Nomura’s model, CW laser chips are Yuanjie’s main revenue source over the next three years. The table below shows that the CW revenue contribution rises rapidly and almost determines Yuanjie’s 2026-2028 revenue curve.
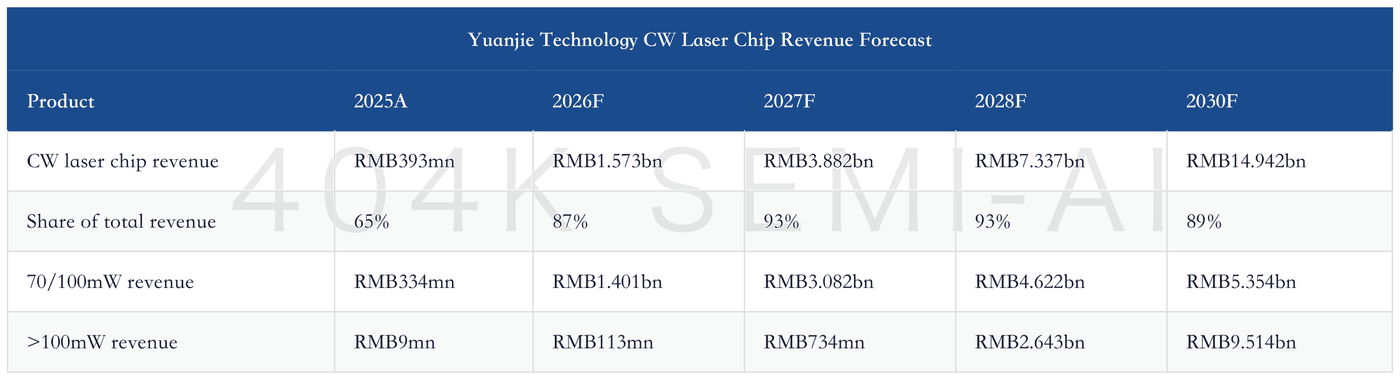
70/100mW is Yuanjie’s most realistic delivery point in 2026-2027. Volume expansion and ASP uplift correspond to the 1.6T ramp, higher silicon photonics module penetration, and customers’ continued restocking of stable high-power light sources.
Products above 100mW are the key to valuation extension. Revenue, shipments, and ASP in this tier all rise together, indicating that Nomura views higher-power products as Yuanjie’s main channel for continued share gains after 2027.
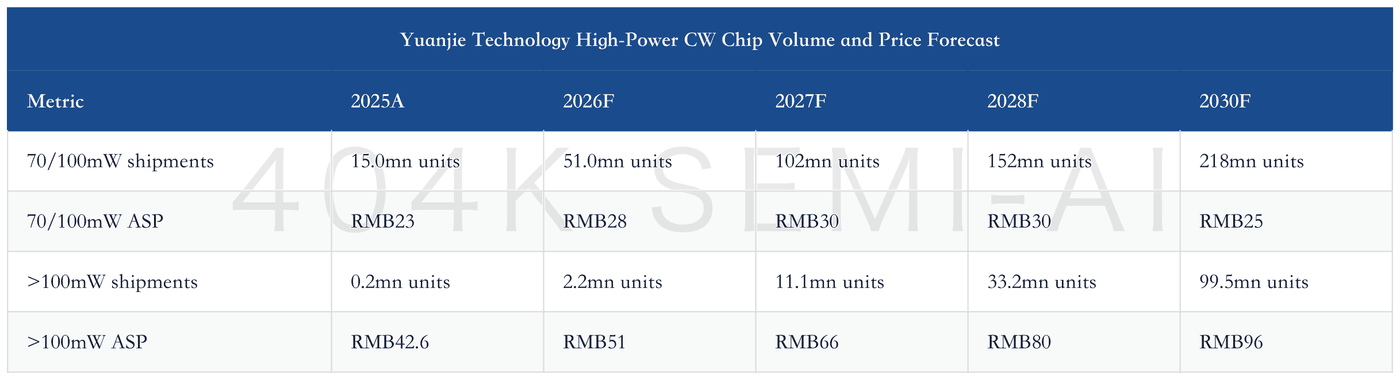
This table shows that Yuanjie’s future performance is not driven simply by “selling more 70mW.” If only 70/100mW products continue to ramp, revenue growth would be strong, but ASP and share would ultimately face competitive constraints. The value of higher-power products lies in increasing value per chip and raising customer switching difficulty. Products above 100mW require better epitaxy, facet processing, thermal stability, and testing capability. Yield ramp is slow, customer qualification cycles are long, shortages are more likely in the short term, and high gross margins are easier to sustain.
Yuanjie’s current progress is broadly aligned with this model. The company’s 70mW products have entered mass production, 100mW products have completed customer qualification and are expected to enter mass production in 2026, while higher-power products such as 150mW and 300mW are in R&D; and qualification. Nomura expects products above 100mW to start ramping from 2026 and products above 300mW from 2028, corresponding to NPO and CPO requirements for external laser-source power.
V. NPO/CPO Turns 300mW from an R&D; Project into a Long-Term Ticket
CPO and NPO push Yuanjie’s long-term story from “supplying CW light sources to silicon photonics modules” further toward “supplying external laser sources to switching systems.” In a CPO architecture, the optical engine sits close to the switch chip, and CW lasers typically provide continuous light through an external laser source module, which is then delivered into the optical engine via fiber or couplers. This structure raises all requirements for laser-chip output power, thermal stability, narrow linewidth, low noise, and reliability.
Nomura’s teardown reference for NVIDIA’s Quantum-X800 CPO switch is representative. The system contains 18 ELS external laser source modules, with a total of 36 CW lasers. Based on its BOM estimate, the value of CW lasers is about US$2,160.
ELS modules and optical engines have higher value shares, accounting for roughly 22% and 43% of total system BOM, respectively. Laser chips are not the largest share, but they are what constrain stable light supply and system reliability.
This is also why Nomura places >300mW CW after 2028. For ordinary silicon photonics modules, 70mW and 100mW can already cover a considerable share of current demand. For NPO/CPO, external laser sources need to deliver stable long-term output under high temperatures and more complex system environments, making >300mW products closer to a long-term ticket. If Yuanjie can enter CPO/NPO customer qualification, its valuation would shift from a “1.6T order company” to an “AI switching-system light-source company.”
But CPO/NPO also should not be counted as certain revenue ahead of time. The pace at which large cloud providers and switch-chip platforms adopt new architectures depends on cost, power consumption, serviceability, supply-chain maturity, and system-level reliability. If NPO/CPO begins delivery in 2027-2028, it will only bring meaningful revenue for >300mW CW after 2028. In the near term, Yuanjie still needs to rely on 70mW, 100mW, and >100mW products to support earnings, while CPO/NPO is more about the valuation ceiling and validation of the product roadmap.
6. How Global Share Changes: From No. 1 in China to About 32% CW Share in 2028
Another important clue Nomura provides on Yuanjie is global share. Based on 2025 global external sales revenue for laser chips, Yuanjie already ranks No. 6 globally. This ranking shows Yuanjie has entered the global optical-chip competitive landscape; the market can no longer value it only as a domestic-substitution company.
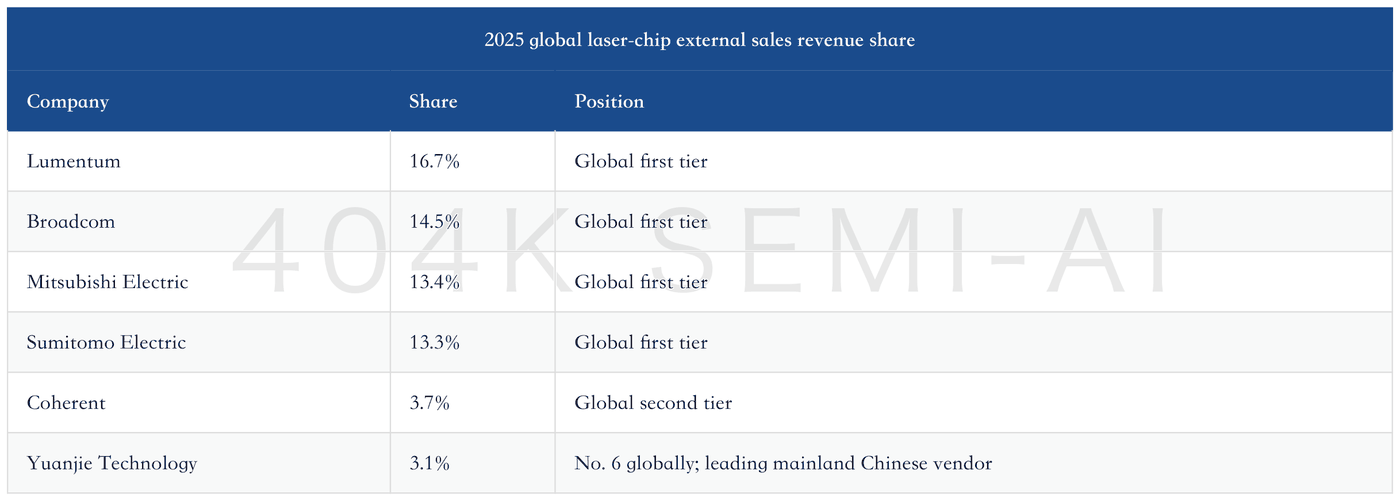
In high-speed optical interconnect chips, Yuanjie’s position is clearer. Nomura includes EML above 100G and CW above 50mW in its high-speed interconnect statistics. Yuanjie’s 2025 global share is 4.3%, ranking No. 6 globally and No. 1 among mainland Chinese vendors. This scope better reflects AI data-center value than the overall optical-chip market, because it excludes a large volume of traditional low-speed telecom chips.
Nomura forecasts Yuanjie’s global optical-chip share will continue to rise, with its CW laser-chip share reaching a stage peak in 2028. EML share remains very small. It is more like a long-term option, while near- to medium-term revenue and profit are mainly contributed by CW.
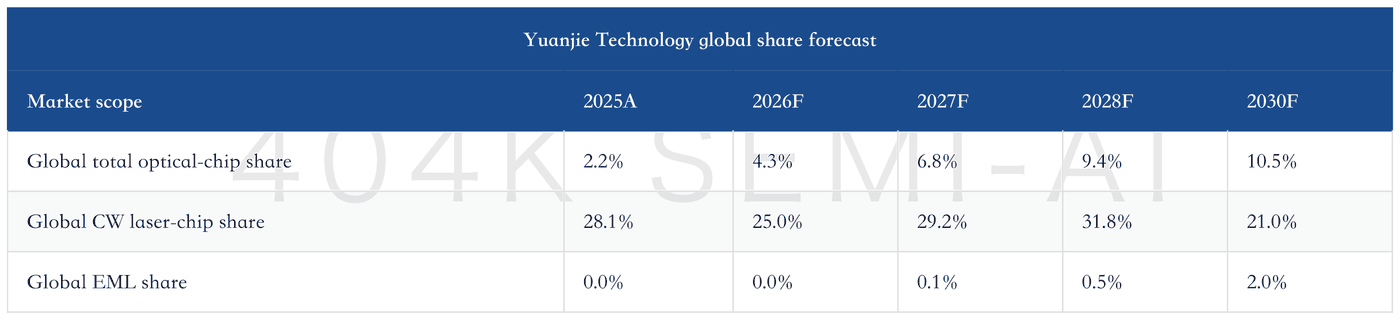
The conclusion from this share forecast is clear: Yuanjie’s core driver in 2026-2028 is not EML, but CW light sources. EML provides technology reserves and long-term optionality, while the real revenue and profit contribution still comes from high-power CW. If Yuanjie can maintain around 30% share in CW while pushing its total optical-chip share close to 10%, its valuation anchor will shift from domestic scarcity to global share. If CW share declines and EML does not ramp in time, valuation will return to concerns over a single-product peak.
7. Why IDM Matters More: Epitaxy, Testing, and Yield All Become Share
In optical-chip investing, it is easy to focus on terminal speeds, but what really determines whether Yuanjie can expand share is IDM capability. Yuanjie covers epitaxial growth, wafer manufacturing, chip processing, packaging and testing, and reliability validation. Its core equipment includes epitaxy equipment such as MOCVD. For high-power CW and EML, epitaxial wafer quality, gratings, facets, thermal resistance, coupling efficiency, and consistency all affect yield, and yield directly determines whether stable supply is possible.
Nomura’s description of the industry supply chain also shows the importance of IDM. Global InP substrates, epitaxial wafers, and key equipment segments remain controlled by a small number of overseas companies, and optical-chip leaders have long controlled the pace of high-end products through in-house epitaxy and wafer processes. Yuanjie’s IDM model allows it to adjust processes more quickly when customer demand changes, and to prioritize epitaxy and testing resources toward high-gross-margin products when supply is tight.
Capacity is the other side of IDM. Yuanjie currently has two production bases in Shanxi, with total gross floor area of more than 28,000 square meters. Phase I of the production base has total investment of about RMB950 million and was launched in 2022. Phase II was announced in February 2026, with planned total investment of about RMB1.25 billion, focused on high-speed optical chips. Total investment for the 50G optical-chip industrialization project was adjusted to RMB757 million, with completion expected by end-2026; it is compatible with DFB, EML, and CW products.
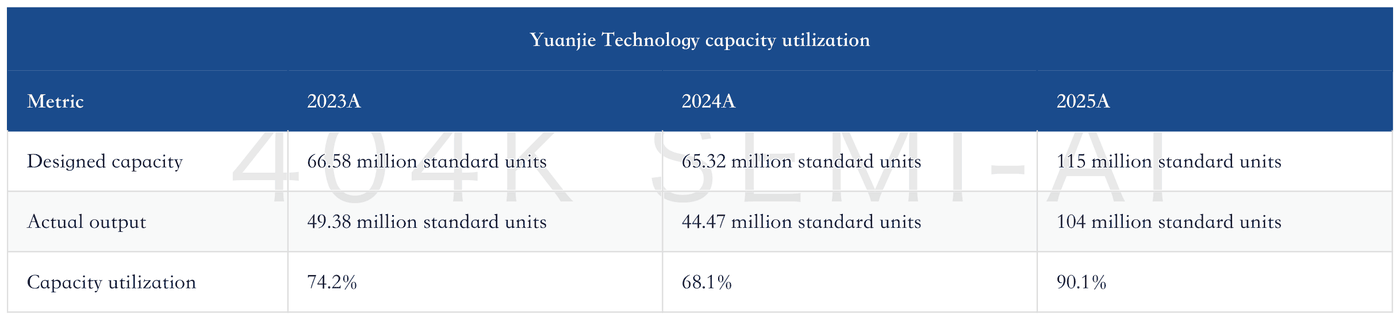
Capacity utilization rose significantly in 2025, indicating that data-center demand has already absorbed existing capacity. Capacity expansion raises the revenue ceiling, but also brings cash-flow and depreciation pressure. Nomura expects free cash flow to turn meaningfully positive only in 2028.
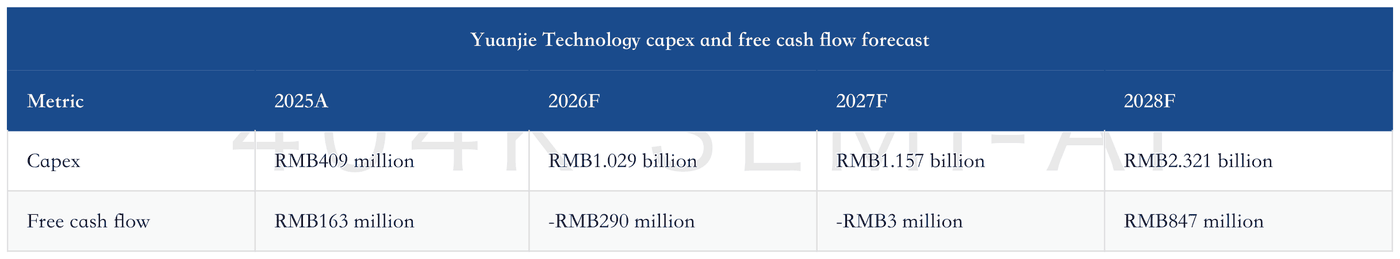
Yuanjie is also planning a production base in Vancouver, Washington, in the United States, with a disclosed investment cap of US$50 million and plant area of about 150,000 square feet. The lease was completed in May 2025, but production has not yet started. The significance of the overseas base is not only capacity, but also customer service, supply-chain resilience, and a buffer against geopolitical risk. However, overseas capacity construction has a long cycle, complex certification, and a higher cost structure. It should not be counted as a near-term profit contributor; it is better viewed as an entry ticket into major customers’ global supply chains.
8. What the Neutral Rating Means: Growth Has Not Deteriorated, but Valuation Has Already Moved Ahead to 2028
Nomura’s Neutral rating is not mainly about conservative earnings forecasts, but about the current share price already pricing in the story in advance. The RMB1,655 target price corresponds to 2028 EPS of RMB25.47 and a 65x P/E, roughly aligned with the median 2028 P/E for China A-share optical-laser names. Based on the July 7 closing price of RMB1,715.04, Yuanjie is already trading at about 67x 2028 EPS under the report’s framework.
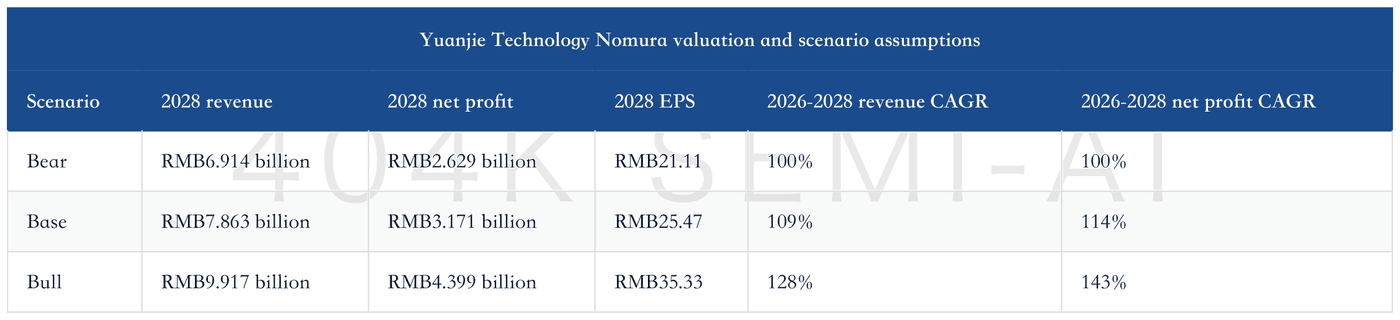
The key point in this scenario table is that the base case itself is already very strong. For a company with 2025 revenue of RMB601 million, 2028 revenue of RMB7.863 billion, net profit of RMB3.171 billion, and a 40.3% net margin require three consecutive years in which high growth, high gross margin, strong delivery, and high share all hold at the same time. For valuation to be revised up further, the market needs to see a clearer customer mass-production cadence for products above 100mW and above 300mW.
From 2025 to 1Q26, Yuanjie has already delivered strong validation. The table below explains why the share price has been strong, and also why valuation is unlikely to keep rising solely on the basis of being “directionally right.”
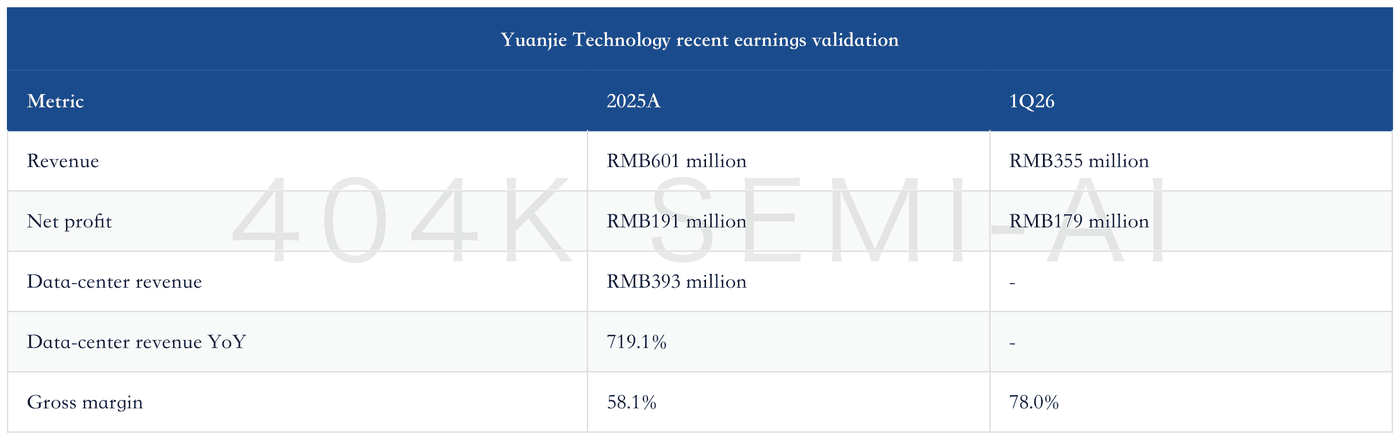
The next stage of share-price upside will become more selective. If revenue grows rapidly but gross margin declines, the market will worry about competitive capacity expansion. If CW remains strong but customer concentration does not fall, the market will worry about bargaining power. If CPO/NPO remain at the sample and roadmap stage, the market will treat products above 300mW as a long-dated story. The Neutral rating is effectively reminding investors that the growth logic has not ended, but the verification standard has been upgraded from “having orders” to “share, power, gross margin, and cash flow all being delivered together.”
IX. Risks and Disconfirmation: Customers, Gross Margin, CPO Timing, Competitive Capacity Expansion
Yuanjie Technology’s biggest risk remains customer concentration. Nomura disclosed that in 2025, the company’s largest customer accounted for about 53% of revenue. For the high-speed optical module supply chain, large customers bring volume, but also uncertainty around pricing, delivery schedules, second sourcing, and product roadmaps. If the largest customer increases its second-source ratio, or allocates more high-power light-source orders to overseas suppliers, Yuanjie’s revenue growth and gross margin would both be affected.
Gross margin is the second risk. Yuanjie’s gross margin was 58.1% in 2025 and reached 78% in 1Q26, an extremely high level for a manufacturing company. High margins come from product shortages, customer mix, process barriers, and a higher share of high-power products, but all of these factors can change. Competitor capacity expansion, customer renegotiation, and below-expectation yields for products above 100mW could all push gross margin back toward a more normal range. At the current valuation, even a small change in gross margin would materially affect 2028 earnings.
The third risk is the pace of NPO/CPO adoption. NPO/CPO imposes higher requirements on CW products above 300mW and external laser sources, but there is still uncertainty in moving system architecture from validation to large-scale deployment. Cloud customers will weigh cost, power consumption, thermal management, maintainability, and supply-chain maturity. If NPO/CPO delivery is delayed, the revenue curve for Yuanjie’s products above 300mW would also shift back.
The fourth risk is global competitive capacity expansion. Lumentum, Broadcom, Mitsubishi Electric, Sumitomo Electric, Coherent, and others still have long-term accumulation in high-end laser chips, with strong customer relationships, reliability track records, and global capacity. Yuanjie’s ability to gain share in CW does not mean all competitors will concede a high-margin market. If overseas leaders expand capacity faster than expected, Yuanjie’s path to share gains will become more uneven.
The fifth risk comes from supply chain and corporate governance. High-end optical chips depend on InP substrates, epitaxy equipment, lithography, testing, and packaging resources, and the global supply chain still faces geopolitical and equipment-delivery uncertainty. The criminal detention matter involving a former company executive also needs continued monitoring. Although it does not directly change product competitiveness, it will affect the market’s risk discount for governance stability.
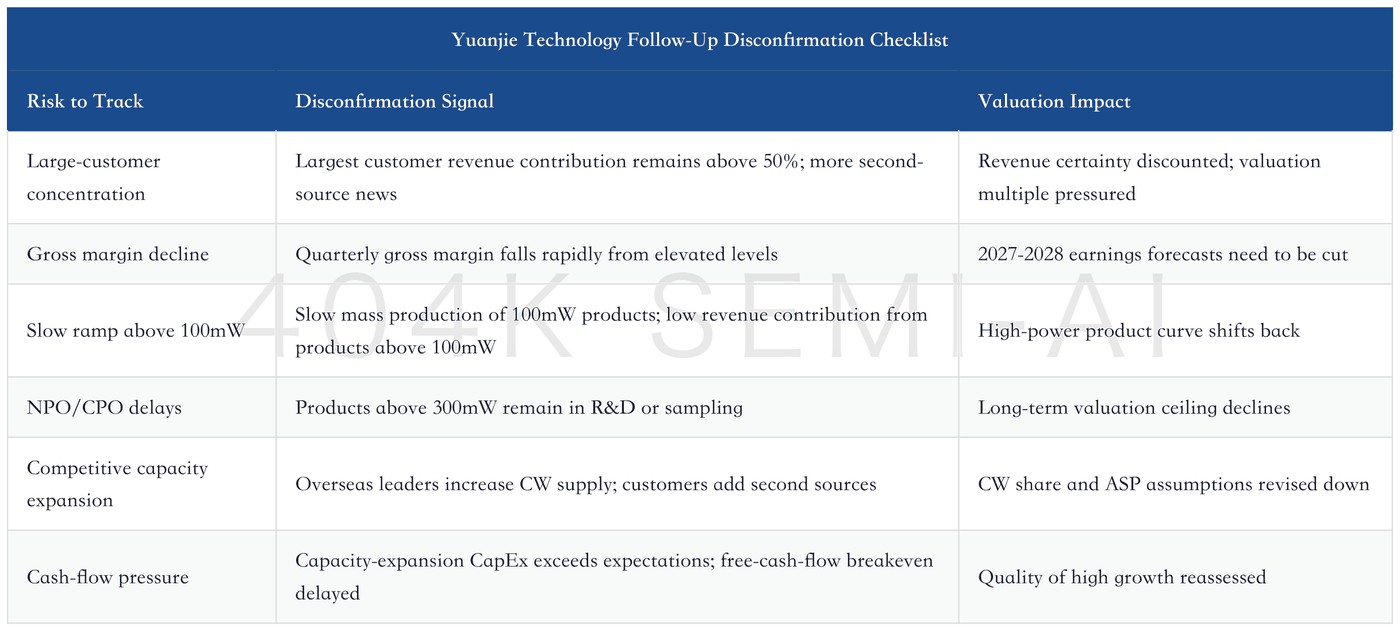
X. Follow-Up Tracking Checklist: What to Watch Over the Next Four Quarters
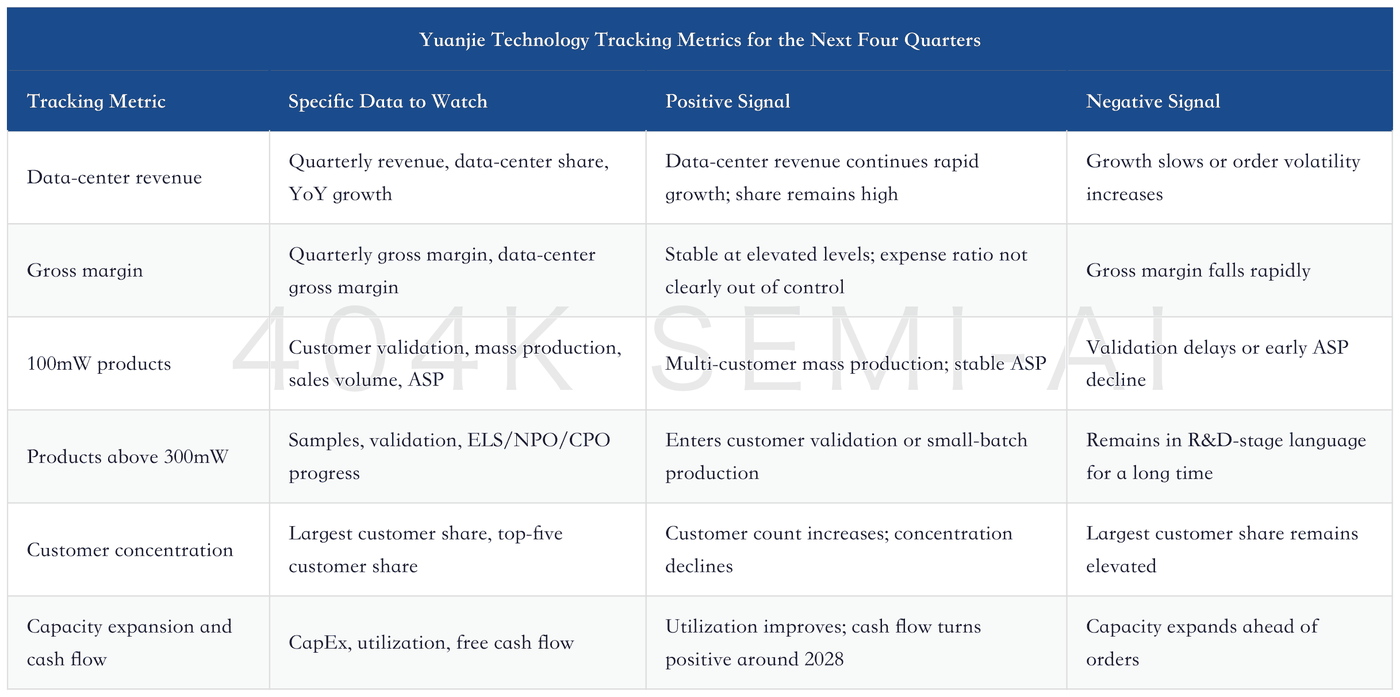
Yuanjie has now moved past the “directional judgment” stage; the next phase requires quarterly data to verify each item. The first set of numbers is data-center revenue and gross margin. If data-center revenue continues to grow rapidly in 2Q26 and 3Q26, and gross margin remains elevated, it would show that 70mW and 100mW orders and customer mix remain strong. If revenue grows quickly but gross margin falls meaningfully, the market will begin to reassess pricing and competition.
The second set of numbers is 100mW products. Yuanjie’s 70mW products are already in mass production, and 100mW products have completed customer validation. The next items to watch are mass-production pace, shipments, ASP, and number of customers. In Nomura’s model, revenue from products above 100mW rises from RMB113 million in 2026 to RMB2.643 billion in 2028. If this line materializes ahead of schedule, the valuation narrative will shift from “70/100mW volume ramp” to “high-power upgrade.”
The third set of numbers is 300mW, ELS, NPO, and CPO. The market does not need Yuanjie to confirm large-scale revenue immediately, but it does need to see real progress in samples, validation, customer cooperation, and product roadmap. If products above 300mW can show clearer customer validation in 2027, the post-2028 revenue curve will become more credible.
The fourth set of numbers is customer concentration and cash flow. For Yuanjie to move from single-product optionality to a global platform, its customer structure must broaden, and cash flow cannot be consumed by capacity expansion for too long. Free-cash-flow pressure in 2026-2027 is understandable, but if utilization, yield, and customer orders fail to keep pace after expansion, the market will revisit the capital efficiency of its IDM expansion.
The conclusion from this Yuanjie update can be compressed into one sentence: the company has moved from a domestic optical-chip optionality asset into the validation phase of a global AI interconnect light-source platform. Nomura’s model lays out a strong 2026-2028 growth curve, while also warning that the current valuation is already relatively full. For the share price to keep moving higher, the market needs to see mass production of products above 100mW, validation of products above 300mW, sustained global CW share, and resilient gross margin. If any one of these links falls behind, the market will reclassify the company as a high-beta manufacturer in a single cycle.Yuanjie Technology Update: 1.6T, 3.2T and CPO Push Domestic CW Light Sources Toward a Global Optical-Chip Entry Ticket
目录
Too Long; Didn’t Read
I. What Changed in This Update: Yuanjie Moves From Order Elasticity to a Global-Share Narrative
II. Nomura’s Core Model: Revenue Rises From RMB1.803 Billion to RMB7.863 Billion in 2026-2028
III. 1.6T Remains the Profit Anchor for the Next Two Years; 2.4T and 3.2T Push Demand Further Out
IV. CW Light Sources Are Yuanjie’s Revenue Mainline: 70/100mW Delivery, Followed by >100mW
V. NPO/CPO Turns 300mW from an R&D Project into a Long-Term Ticket
6. How Global Share Changes: From No. 1 in China to About 32% CW Share in 2028
7. Why IDM Matters More: Epitaxy, Testing, and Yield All Become Share
8. What the Neutral Rating Means: Growth Has Not Deteriorated, but Valuation Has Already Moved Ahead to 2028
IX. Risks and Disconfirmation: Customers, Gross Margin, CPO Timing, Competitive Capacity Expansion
X. Follow-Up Tracking Checklist: What to Watch Over the Next Four Quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Nomura’s initiation shifts the research focus on Yuanjie Technology from 70mW/100mW orders to the entry ticket for 1.6T, 3.2T and CPO light sources. The debate is straightforward: three years of high earnings growth are visible, but the share price has already priced in expectations of becoming a global optical-chip leader by 2028. The key question is whether high-power light sources can deliver global share and margins.
Too Long; Didn’t Read
Nomura assigns a Neutral rating. Its target price is RMB1,655, slightly below the report’s reference closing price; valuation is based on 2028 earnings and a 65x P/E. The growth logic remains very strong, but triple-digit revenue and net-profit CAGR has already been substantially reflected in the share price.
1.6T remains the main driver over the next two years. Nomura estimates global 1.6T optical-module shipments will rise to 126 million units by 2028, while 800G continues to grow and 2.4T and 3.2T begin to take over. Rate upgrades push demand for high-power CW light sources further out and extend Yuanjie’s validation cycle from a single order to multiple product generations.
CW light sources are Yuanjie’s revenue axis. Nomura expects Yuanjie’s CW laser-chip revenue to rise from RMB393 million in 2025 to RMB7.337 billion in 2028, with the revenue share increasing from 65% to 93%. Within this, 70/100mW products drive 2026-2027 delivery, products above 100mW post an estimated 2026-2028 revenue CAGR of about 90%, and products above 300mW begin to capture NPO/CPO demand from 2028.
Rising global share is the incremental variable. By Nomura’s definition, Yuanjie ranked sixth in global external laser-chip sales revenue in 2025, with 3.1% share; in high-speed interconnect chips such as EML above 100G and CW above 50mW, its share was 4.3%, ranking first among mainland Chinese suppliers. In the model, Yuanjie’s global optical-chip share rises from 4.3% in 2026 to 10.5% in 2030, while its CW laser-chip share reaches 31.8% in 2028.
Valuation risk is already on the table. Whether high gross margins can hold depends on yields for products above 100mW, customer price negotiations, and competitors’ capacity-expansion pace. The largest customer still accounts for a high share, while capacity expansion and Hong Kong listing financing will also weigh on free cash flow. Valuation upside requires sustained delivery from new products.
Track four sets of numbers from here. First, whether data-center revenue and gross margin continue in 2Q and 3Q. Second, shipments, ASP and customer certification for 100mW products. Third, whether 300mW, external laser source and NPO/CPO projects enter sample, validation or small-batch stages. Fourth, customer concentration, overseas capacity and cash flow, to confirm whether Yuanjie can move from order-driven elasticity to a global optical-chip platform.
I. What Changed in This Update: Yuanjie Moves From Order Elasticity to a Global-Share Narrative
The value of Nomura’s initiation lies in moving the research framework for Yuanjie Technology from “near-term earnings elasticity brought by AI optical-module orders” to the medium- and long-term question of “global optical-chip share migration.” The market had already seen volume ramp in Yuanjie’s 70mW CW light sources, rapid data-center revenue growth and progress in 100mW product validation. Nomura’s report breaks these clues into three clearer timelines: 2026-2027 depends on continued 1.6T volume ramp, post-2028 depends on 2.4T, 3.2T and NPO/CPO, and through 2030 depends on whether light sources above 100mW and above 300mW can become Yuanjie’s new revenue axis.
Under the old framework, Yuanjie looked more like a scarce domestic CW light-source supplier upstream of AI optical modules. Under the new framework, Yuanjie has to answer a more demanding question: can it move from 3.1% external sales share in the global laser-chip market in 2025 to roughly 10% share of the overall optical-chip market by 2030; can it push its share of the CW laser-chip segment to 31.8% in 2028; and can it turn EML, CW above 300mW and external laser sources into a second growth curve.
Nomura’s target price lays out this debate plainly. It assigns a Neutral rating and a target price of RMB1,655, based on 2028 EPS of RMB25.47 and a 65x P/E. Based on the July 7 closing price of RMB1,715.04, the implied upside under the report’s methodology is -3.5%. This shows the sell-side model already embeds very strong profit growth, but the share price has also discounted a large portion of 2028 earnings.
So this update does not repeat the old logic that “AI optical modules drive volume growth for domestic light sources.” What is more worth unpacking are three new questions: first, why Nomura is willing to push Yuanjie’s 2028 revenue to RMB7.863 billion; second, which product cycles correspond to light sources above 100mW and above 300mW; third, with the share price already priced off 2028, which numbers should be used over the next four quarters to verify or falsify the thesis.
II. Nomura’s Core Model: Revenue Rises From RMB1.803 Billion to RMB7.863 Billion in 2026-2028
Nomura’s model is aggressive, with 2028 revenue and net-profit forecasts pushed to RMB7.863 billion and RMB3.171 billion, respectively. The table below puts revenue, profit, EPS and margins together. The key point is the rapid increase in the data-center business mix.
The most important part of this forecast set is that margins and revenue mix change at the same time. The data-center business becomes the main axis. The telecom business still retains the process and cash-flow foundation, but has already moved to the second layer of the model.
This means Yuanjie’s valuation is now largely determined by data-center light sources. The telecom business still provides a foundation in process, customers and cash flow, but what investors are really pricing is 70mW, 100mW and CW above 100mW, followed by light sources above 300mW and EML. If data-center revenue ramps smoothly, Yuanjie will move from a domestic telecom optical-chip company to a global AI interconnect optical-chip company. If data-center volume growth or gross margin falls short of expectations, valuation will quickly revert to a discount for “single major customer and single product cycle.”
Nomura’s model also implies a higher requirement: Yuanjie’s margins must remain in a very high range. Gross margin was 58.1% in 2025, is forecast at 66.1% in 2026, and remains at about 68% in 2027-2028; net margin rises from 31.7% to around 40%. This type of margin can only be supported by high-power CW, high yield, in-house epitaxy and customer shortages. Once competitors expand capacity, customers add second suppliers, or yield ramp for high-power products is slow, the margin assumptions will be more sensitive than the revenue assumptions.
III. 1.6T Remains the Profit Anchor for the Next Two Years; 2.4T and 3.2T Push Demand Further Out
The performance anchor for Yuanjie over the next two years remains the transition from 800G to 1.6T. Nomura expects the global data-center optical module market to sustain high growth in 2026-2028, with 1.6T as the most important source of incremental demand, while 800G will not exit immediately.
The key significance of 1.6T is that it concentrates each optical module’s demand for high-power continuous-wave light sources. Silicon photonics solutions typically require an external or integrated CW light source as the optical carrier, with the backend using modulators to load signals. As speeds rise, channel count, per-channel power, thermal management, and coupling loss all become harder to manage. Laser chips move from “able to supply” toward “high power, stability, low noise, low drift, and high yield.”
The value of 2.4T and 3.2T lies in extending the cycle. Optical module companies, switch-chip companies, and cloud providers cannot stop at 1.6T. Subsequent speed upgrades will continue to raise requirements for higher-power CW light sources, EMLs, and external laser sources. Nomura places the launch of 2.4T and 3.2T in 2027-2028, with combined shipments of 7.0mn units in 2028. The near-term absolute volume is not large, but these products will influence customer qualification, R&D; investment, and the longer-term valuation narrative after 2027.
This is especially important for Yuanjie. In 2025, the company’s data-center revenue had already reached RMB393mn, up 719.1% YoY, with a gross margin of 72.2%. In 1Q26, revenue was RMB355mn and net profit was RMB179mn, with a single quarter already close to full-year 2025 net profit. Part of the short-term earnings elasticity has already been realized. For valuation to continue moving higher, the company needs to prove that 1.6T orders can extend into a continuous product ladder across 2.4T, 3.2T, NPO, and CPO.
IV. CW Light Sources Are Yuanjie’s Revenue Mainline: 70/100mW Delivery, Followed by >100mW
In Nomura’s model, CW laser chips are Yuanjie’s main revenue source over the next three years. The table below shows that the CW revenue contribution rises rapidly and almost determines Yuanjie’s 2026-2028 revenue curve.
70/100mW is Yuanjie’s most realistic delivery point in 2026-2027. Volume expansion and ASP uplift correspond to the 1.6T ramp, higher silicon photonics module penetration, and customers’ continued restocking of stable high-power light sources.
Products above 100mW are the key to valuation extension. Revenue, shipments, and ASP in this tier all rise together, indicating that Nomura views higher-power products as Yuanjie’s main channel for continued share gains after 2027.
This table shows that Yuanjie’s future performance is not driven simply by “selling more 70mW.” If only 70/100mW products continue to ramp, revenue growth would be strong, but ASP and share would ultimately face competitive constraints. The value of higher-power products lies in increasing value per chip and raising customer switching difficulty. Products above 100mW require better epitaxy, facet processing, thermal stability, and testing capability. Yield ramp is slow, customer qualification cycles are long, shortages are more likely in the short term, and high gross margins are easier to sustain.
Yuanjie’s current progress is broadly aligned with this model. The company’s 70mW products have entered mass production, 100mW products have completed customer qualification and are expected to enter mass production in 2026, while higher-power products such as 150mW and 300mW are in R&D; and qualification. Nomura expects products above 100mW to start ramping from 2026 and products above 300mW from 2028, corresponding to NPO and CPO requirements for external laser-source power.
V. NPO/CPO Turns 300mW from an R&D; Project into a Long-Term Ticket
CPO and NPO push Yuanjie’s long-term story from “supplying CW light sources to silicon photonics modules” further toward “supplying external laser sources to switching systems.” In a CPO architecture, the optical engine sits close to the switch chip, and CW lasers typically provide continuous light through an external laser source module, which is then delivered into the optical engine via fiber or couplers. This structure raises all requirements for laser-chip output power, thermal stability, narrow linewidth, low noise, and reliability.
Nomura’s teardown reference for NVIDIA’s Quantum-X800 CPO switch is representative. The system contains 18 ELS external laser source modules, with a total of 36 CW lasers. Based on its BOM estimate, the value of CW lasers is about US$2,160.
ELS modules and optical engines have higher value shares, accounting for roughly 22% and 43% of total system BOM, respectively. Laser chips are not the largest share, but they are what constrain stable light supply and system reliability.
This is also why Nomura places >300mW CW after 2028. For ordinary silicon photonics modules, 70mW and 100mW can already cover a considerable share of current demand. For NPO/CPO, external laser sources need to deliver stable long-term output under high temperatures and more complex system environments, making >300mW products closer to a long-term ticket. If Yuanjie can enter CPO/NPO customer qualification, its valuation would shift from a “1.6T order company” to an “AI switching-system light-source company.”
But CPO/NPO also should not be counted as certain revenue ahead of time. The pace at which large cloud providers and switch-chip platforms adopt new architectures depends on cost, power consumption, serviceability, supply-chain maturity, and system-level reliability. If NPO/CPO begins delivery in 2027-2028, it will only bring meaningful revenue for >300mW CW after 2028. In the near term, Yuanjie still needs to rely on 70mW, 100mW, and >100mW products to support earnings, while CPO/NPO is more about the valuation ceiling and validation of the product roadmap.
6. How Global Share Changes: From No. 1 in China to About 32% CW Share in 2028
Another important clue Nomura provides on Yuanjie is global share. Based on 2025 global external sales revenue for laser chips, Yuanjie already ranks No. 6 globally. This ranking shows Yuanjie has entered the global optical-chip competitive landscape; the market can no longer value it only as a domestic-substitution company.
In high-speed optical interconnect chips, Yuanjie’s position is clearer. Nomura includes EML above 100G and CW above 50mW in its high-speed interconnect statistics. Yuanjie’s 2025 global share is 4.3%, ranking No. 6 globally and No. 1 among mainland Chinese vendors. This scope better reflects AI data-center value than the overall optical-chip market, because it excludes a large volume of traditional low-speed telecom chips.
Nomura forecasts Yuanjie’s global optical-chip share will continue to rise, with its CW laser-chip share reaching a stage peak in 2028. EML share remains very small. It is more like a long-term option, while near- to medium-term revenue and profit are mainly contributed by CW.
The conclusion from this share forecast is clear: Yuanjie’s core driver in 2026-2028 is not EML, but CW light sources. EML provides technology reserves and long-term optionality, while the real revenue and profit contribution still comes from high-power CW. If Yuanjie can maintain around 30% share in CW while pushing its total optical-chip share close to 10%, its valuation anchor will shift from domestic scarcity to global share. If CW share declines and EML does not ramp in time, valuation will return to concerns over a single-product peak.
7. Why IDM Matters More: Epitaxy, Testing, and Yield All Become Share
In optical-chip investing, it is easy to focus on terminal speeds, but what really determines whether Yuanjie can expand share is IDM capability. Yuanjie covers epitaxial growth, wafer manufacturing, chip processing, packaging and testing, and reliability validation. Its core equipment includes epitaxy equipment such as MOCVD. For high-power CW and EML, epitaxial wafer quality, gratings, facets, thermal resistance, coupling efficiency, and consistency all affect yield, and yield directly determines whether stable supply is possible.
Nomura’s description of the industry supply chain also shows the importance of IDM. Global InP substrates, epitaxial wafers, and key equipment segments remain controlled by a small number of overseas companies, and optical-chip leaders have long controlled the pace of high-end products through in-house epitaxy and wafer processes. Yuanjie’s IDM model allows it to adjust processes more quickly when customer demand changes, and to prioritize epitaxy and testing resources toward high-gross-margin products when supply is tight.
Capacity is the other side of IDM. Yuanjie currently has two production bases in Shanxi, with total gross floor area of more than 28,000 square meters. Phase I of the production base has total investment of about RMB950 million and was launched in 2022. Phase II was announced in February 2026, with planned total investment of about RMB1.25 billion, focused on high-speed optical chips. Total investment for the 50G optical-chip industrialization project was adjusted to RMB757 million, with completion expected by end-2026; it is compatible with DFB, EML, and CW products.
Capacity utilization rose significantly in 2025, indicating that data-center demand has already absorbed existing capacity. Capacity expansion raises the revenue ceiling, but also brings cash-flow and depreciation pressure. Nomura expects free cash flow to turn meaningfully positive only in 2028.
Yuanjie is also planning a production base in Vancouver, Washington, in the United States, with a disclosed investment cap of US$50 million and plant area of about 150,000 square feet. The lease was completed in May 2025, but production has not yet started. The significance of the overseas base is not only capacity, but also customer service, supply-chain resilience, and a buffer against geopolitical risk. However, overseas capacity construction has a long cycle, complex certification, and a higher cost structure. It should not be counted as a near-term profit contributor; it is better viewed as an entry ticket into major customers’ global supply chains.
8. What the Neutral Rating Means: Growth Has Not Deteriorated, but Valuation Has Already Moved Ahead to 2028
Nomura’s Neutral rating is not mainly about conservative earnings forecasts, but about the current share price already pricing in the story in advance. The RMB1,655 target price corresponds to 2028 EPS of RMB25.47 and a 65x P/E, roughly aligned with the median 2028 P/E for China A-share optical-laser names. Based on the July 7 closing price of RMB1,715.04, Yuanjie is already trading at about 67x 2028 EPS under the report’s framework.
The key point in this scenario table is that the base case itself is already very strong. For a company with 2025 revenue of RMB601 million, 2028 revenue of RMB7.863 billion, net profit of RMB3.171 billion, and a 40.3% net margin require three consecutive years in which high growth, high gross margin, strong delivery, and high share all hold at the same time. For valuation to be revised up further, the market needs to see a clearer customer mass-production cadence for products above 100mW and above 300mW.
From 2025 to 1Q26, Yuanjie has already delivered strong validation. The table below explains why the share price has been strong, and also why valuation is unlikely to keep rising solely on the basis of being “directionally right.”
The next stage of share-price upside will become more selective. If revenue grows rapidly but gross margin declines, the market will worry about competitive capacity expansion. If CW remains strong but customer concentration does not fall, the market will worry about bargaining power. If CPO/NPO remain at the sample and roadmap stage, the market will treat products above 300mW as a long-dated story. The Neutral rating is effectively reminding investors that the growth logic has not ended, but the verification standard has been upgraded from “having orders” to “share, power, gross margin, and cash flow all being delivered together.”
IX. Risks and Disconfirmation: Customers, Gross Margin, CPO Timing, Competitive Capacity Expansion
Yuanjie Technology’s biggest risk remains customer concentration. Nomura disclosed that in 2025, the company’s largest customer accounted for about 53% of revenue. For the high-speed optical module supply chain, large customers bring volume, but also uncertainty around pricing, delivery schedules, second sourcing, and product roadmaps. If the largest customer increases its second-source ratio, or allocates more high-power light-source orders to overseas suppliers, Yuanjie’s revenue growth and gross margin would both be affected.
Gross margin is the second risk. Yuanjie’s gross margin was 58.1% in 2025 and reached 78% in 1Q26, an extremely high level for a manufacturing company. High margins come from product shortages, customer mix, process barriers, and a higher share of high-power products, but all of these factors can change. Competitor capacity expansion, customer renegotiation, and below-expectation yields for products above 100mW could all push gross margin back toward a more normal range. At the current valuation, even a small change in gross margin would materially affect 2028 earnings.
The third risk is the pace of NPO/CPO adoption. NPO/CPO imposes higher requirements on CW products above 300mW and external laser sources, but there is still uncertainty in moving system architecture from validation to large-scale deployment. Cloud customers will weigh cost, power consumption, thermal management, maintainability, and supply-chain maturity. If NPO/CPO delivery is delayed, the revenue curve for Yuanjie’s products above 300mW would also shift back.
The fourth risk is global competitive capacity expansion. Lumentum, Broadcom, Mitsubishi Electric, Sumitomo Electric, Coherent, and others still have long-term accumulation in high-end laser chips, with strong customer relationships, reliability track records, and global capacity. Yuanjie’s ability to gain share in CW does not mean all competitors will concede a high-margin market. If overseas leaders expand capacity faster than expected, Yuanjie’s path to share gains will become more uneven.
The fifth risk comes from supply chain and corporate governance. High-end optical chips depend on InP substrates, epitaxy equipment, lithography, testing, and packaging resources, and the global supply chain still faces geopolitical and equipment-delivery uncertainty. The criminal detention matter involving a former company executive also needs continued monitoring. Although it does not directly change product competitiveness, it will affect the market’s risk discount for governance stability.
X. Follow-Up Tracking Checklist: What to Watch Over the Next Four Quarters
Yuanjie has now moved past the “directional judgment” stage; the next phase requires quarterly data to verify each item. The first set of numbers is data-center revenue and gross margin. If data-center revenue continues to grow rapidly in 2Q26 and 3Q26, and gross margin remains elevated, it would show that 70mW and 100mW orders and customer mix remain strong. If revenue grows quickly but gross margin falls meaningfully, the market will begin to reassess pricing and competition.
The second set of numbers is 100mW products. Yuanjie’s 70mW products are already in mass production, and 100mW products have completed customer validation. The next items to watch are mass-production pace, shipments, ASP, and number of customers. In Nomura’s model, revenue from products above 100mW rises from RMB113 million in 2026 to RMB2.643 billion in 2028. If this line materializes ahead of schedule, the valuation narrative will shift from “70/100mW volume ramp” to “high-power upgrade.”
The third set of numbers is 300mW, ELS, NPO, and CPO. The market does not need Yuanjie to confirm large-scale revenue immediately, but it does need to see real progress in samples, validation, customer cooperation, and product roadmap. If products above 300mW can show clearer customer validation in 2027, the post-2028 revenue curve will become more credible.
The fourth set of numbers is customer concentration and cash flow. For Yuanjie to move from single-product optionality to a global platform, its customer structure must broaden, and cash flow cannot be consumed by capacity expansion for too long. Free-cash-flow pressure in 2026-2027 is understandable, but if utilization, yield, and customer orders fail to keep pace after expansion, the market will revisit the capital efficiency of its IDM expansion.
The conclusion from this Yuanjie update can be compressed into one sentence: the company has moved from a domestic optical-chip optionality asset into the validation phase of a global AI interconnect light-source platform. Nomura’s model lays out a strong 2026-2028 growth curve, while also warning that the current valuation is already relatively full. For the share price to keep moving higher, the market needs to see mass production of products above 100mW, validation of products above 300mW, sustained global CW share, and resilient gross margin. If any one of these links falls behind, the market will reclassify the company as a high-beta manufacturer in a single cycle.