
WUS Printed Circuit Deep Dive Update: Citi's Rmb189 Target Price, 1.6T Switches, 3.2T R&D;, and AI PCB Pricing Discipline
目录
Too Long; Didn't Read
1. What the Suzhou Field Trip Added: From Industry Story to Operating Validation
2. 1.6T Switches: WUS Printed Circuit Moves From Certification to Primary-Supply Validation
III. 3.2T and CoWoP: The Next-Generation Ticket Is Still in R&D Validation
IV. Pricing Discipline: AI Customers Do Not Force Price Cuts; the Real Pressure Comes from Peer Competition
V. Capacity Layout: Power Stability Has Become a Variable in High-End Manufacturing
VI. Financial Baseline: Old Earnings Have Been Delivered; the New Debate Is After 2027
VII. From Goldman Sachs’ RMB142 to Citi’s RMB189: The Debate Lies in Earnings Slope and Material Locking
VIII. Earnings Bridge: The RMB189 Target Price Requires Three Variables to Deliver Together
IX. Peer Ranking: WUS Printed Circuit Answers the Network-Side Primary-Supplier Question
X. Materials Locking and Domestic Substitution: Gross-Margin Protection Does Not Come Only from Customer Pricing
XI. Falsification Checklist: The RMB 189 Target Price Requires Six Conditions to Keep Holding
12. What to Watch Over the Next Four Quarters
13. Three Scenarios: WUS Printed Circuit Is Not a One-Way Bull Case
14. Conclusion: WUS Printed Circuit’s Re-rating Has Entered Its Second Stage
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Citi's Suzhou field trip moves WUS Printed Circuit's AI PCB story from industry TAM to operating validation: primary supply for 1.6T switches, 3.2T R&D;, pricing discipline, and capacity expansion in mainland China. Subsequent revenue, data-communications gross margin, operating cash flow, materials lock-in, and customer share will need to keep proving whether the Rmb189 target price can hold.
Too Long; Didn't Read
Citi's field trip increased the density of validation. The core incremental point is not "continued bullishness on AI PCB," but testing WUS Printed Circuit across five operating details: 1.6T switches, 3.2T R&D;, catching up in CoWoP, pricing strategy, and capacity geography. If these details continue to materialize, WUS Printed Circuit's valuation logic will shift from an industry-cycle upgrade to a repricing of customer share, pricing discipline, and high-end manufacturing capability.
1.6T is the main axis of this update. Citi's field-trip read-through indicates that WUS Printed Circuit is already a major supplier of 1.6T switches for several customers, which is closer to revenue conversion than "completion of customer certification." The most important indicators going forward are not whether the industry has 1.6T, but whether WUS Printed Circuit's share, delivery stability, and gross margin within core customer platforms can scale accordingly.
Pricing power matters more than price hikes. Management's signal is that AI-related customers do not force price cuts, and pricing pressure mainly comes from competition among suppliers; the company also will not simply raise prices because capacity is tight. This suggests WUS Printed Circuit is pursuing long-term customer relationships and product-mix gross margin rather than short-term price-hike trades. Data-communications gross margin and materials-cost pass-through should be monitored.
Capacity choices create a new debate. Citi's field trip emphasized that Thailand's power-grid reliability is insufficient, so WUS Printed Circuit's large-scale expansion will remain in mainland China, while Thailand data-communications Phase II began ramping in July 2026. This arrangement turns the capacity question from "how many plants" into "where power, yield, customer certification, and materials supply are most reliable."
The Rmb189 target price is based on 2027 earnings valuation. Citi derives the Rmb189 target price using 30x 2027 P/E, with an 86% earnings CAGR for 2026-2028 as the core support. Goldman Sachs issued a Rmb142 target price in May, while Citi maintained Rmb189 in June and July. The divergence mainly lies in the 2027 profit slope, materials lock-in capability, and share in high-end networking boards.
Share and cash flow are the key risks. WUS Printed Circuit's 2025 data-communications revenue was Rmb14.656bn, and 1Q26 revenue and net profit attributable to shareholders continued to grow rapidly, but 1Q26 operating cash flow declined year on year. If progress on 1.6T, ASIC, and 3.2T is delayed, or if post-expansion price competition compresses gross margin, the profit assumptions behind the Rmb189 target price will need to be revised down.
1. What the Suzhou Field Trip Added: From Industry Story to Operating Validation
The old framework for WUS Printed Circuit was already clear: the company is not an ordinary PCB cyclical, but a high-end multilayer-board asset on the networking and server side of AI data centers. The 2025 annual report and 1Q26 report have already shown that high-speed network switches, AI servers, and high-end data-communications PCBs are flowing into revenue, profit, and gross margin. The value of Citi's Suzhou field trip is that it pushes this framework one layer further.
The old framework answered "why WUS Printed Circuit benefits from AI PCB." This field trip answers "which operating actions those benefits actually land on." 1.6T switches are no longer just a technology direction, but major supply across several customers; 3.2T is not an immediate revenue ramp, but a next-generation ticket after standards become clear in 2028; CoWoP is not a current strength, but the company is catching up; pricing strategy is not a price-hike narrative, but customers not forcing price cuts while competition determines pricing; capacity is not casually replicated overseas, but jointly determined by power stability, materials ecosystem, and customer certification.
These five points matter more than a target price. Target prices can change with market sentiment and valuation multiples, but operating facts determine whether the profit slope can truly support the valuation. What WUS Printed Circuit now most needs to prove is not that "the AI PCB TAM is large," but whether the company can simultaneously defend its share in high-end networking boards, pricing discipline, and capacity delivery.
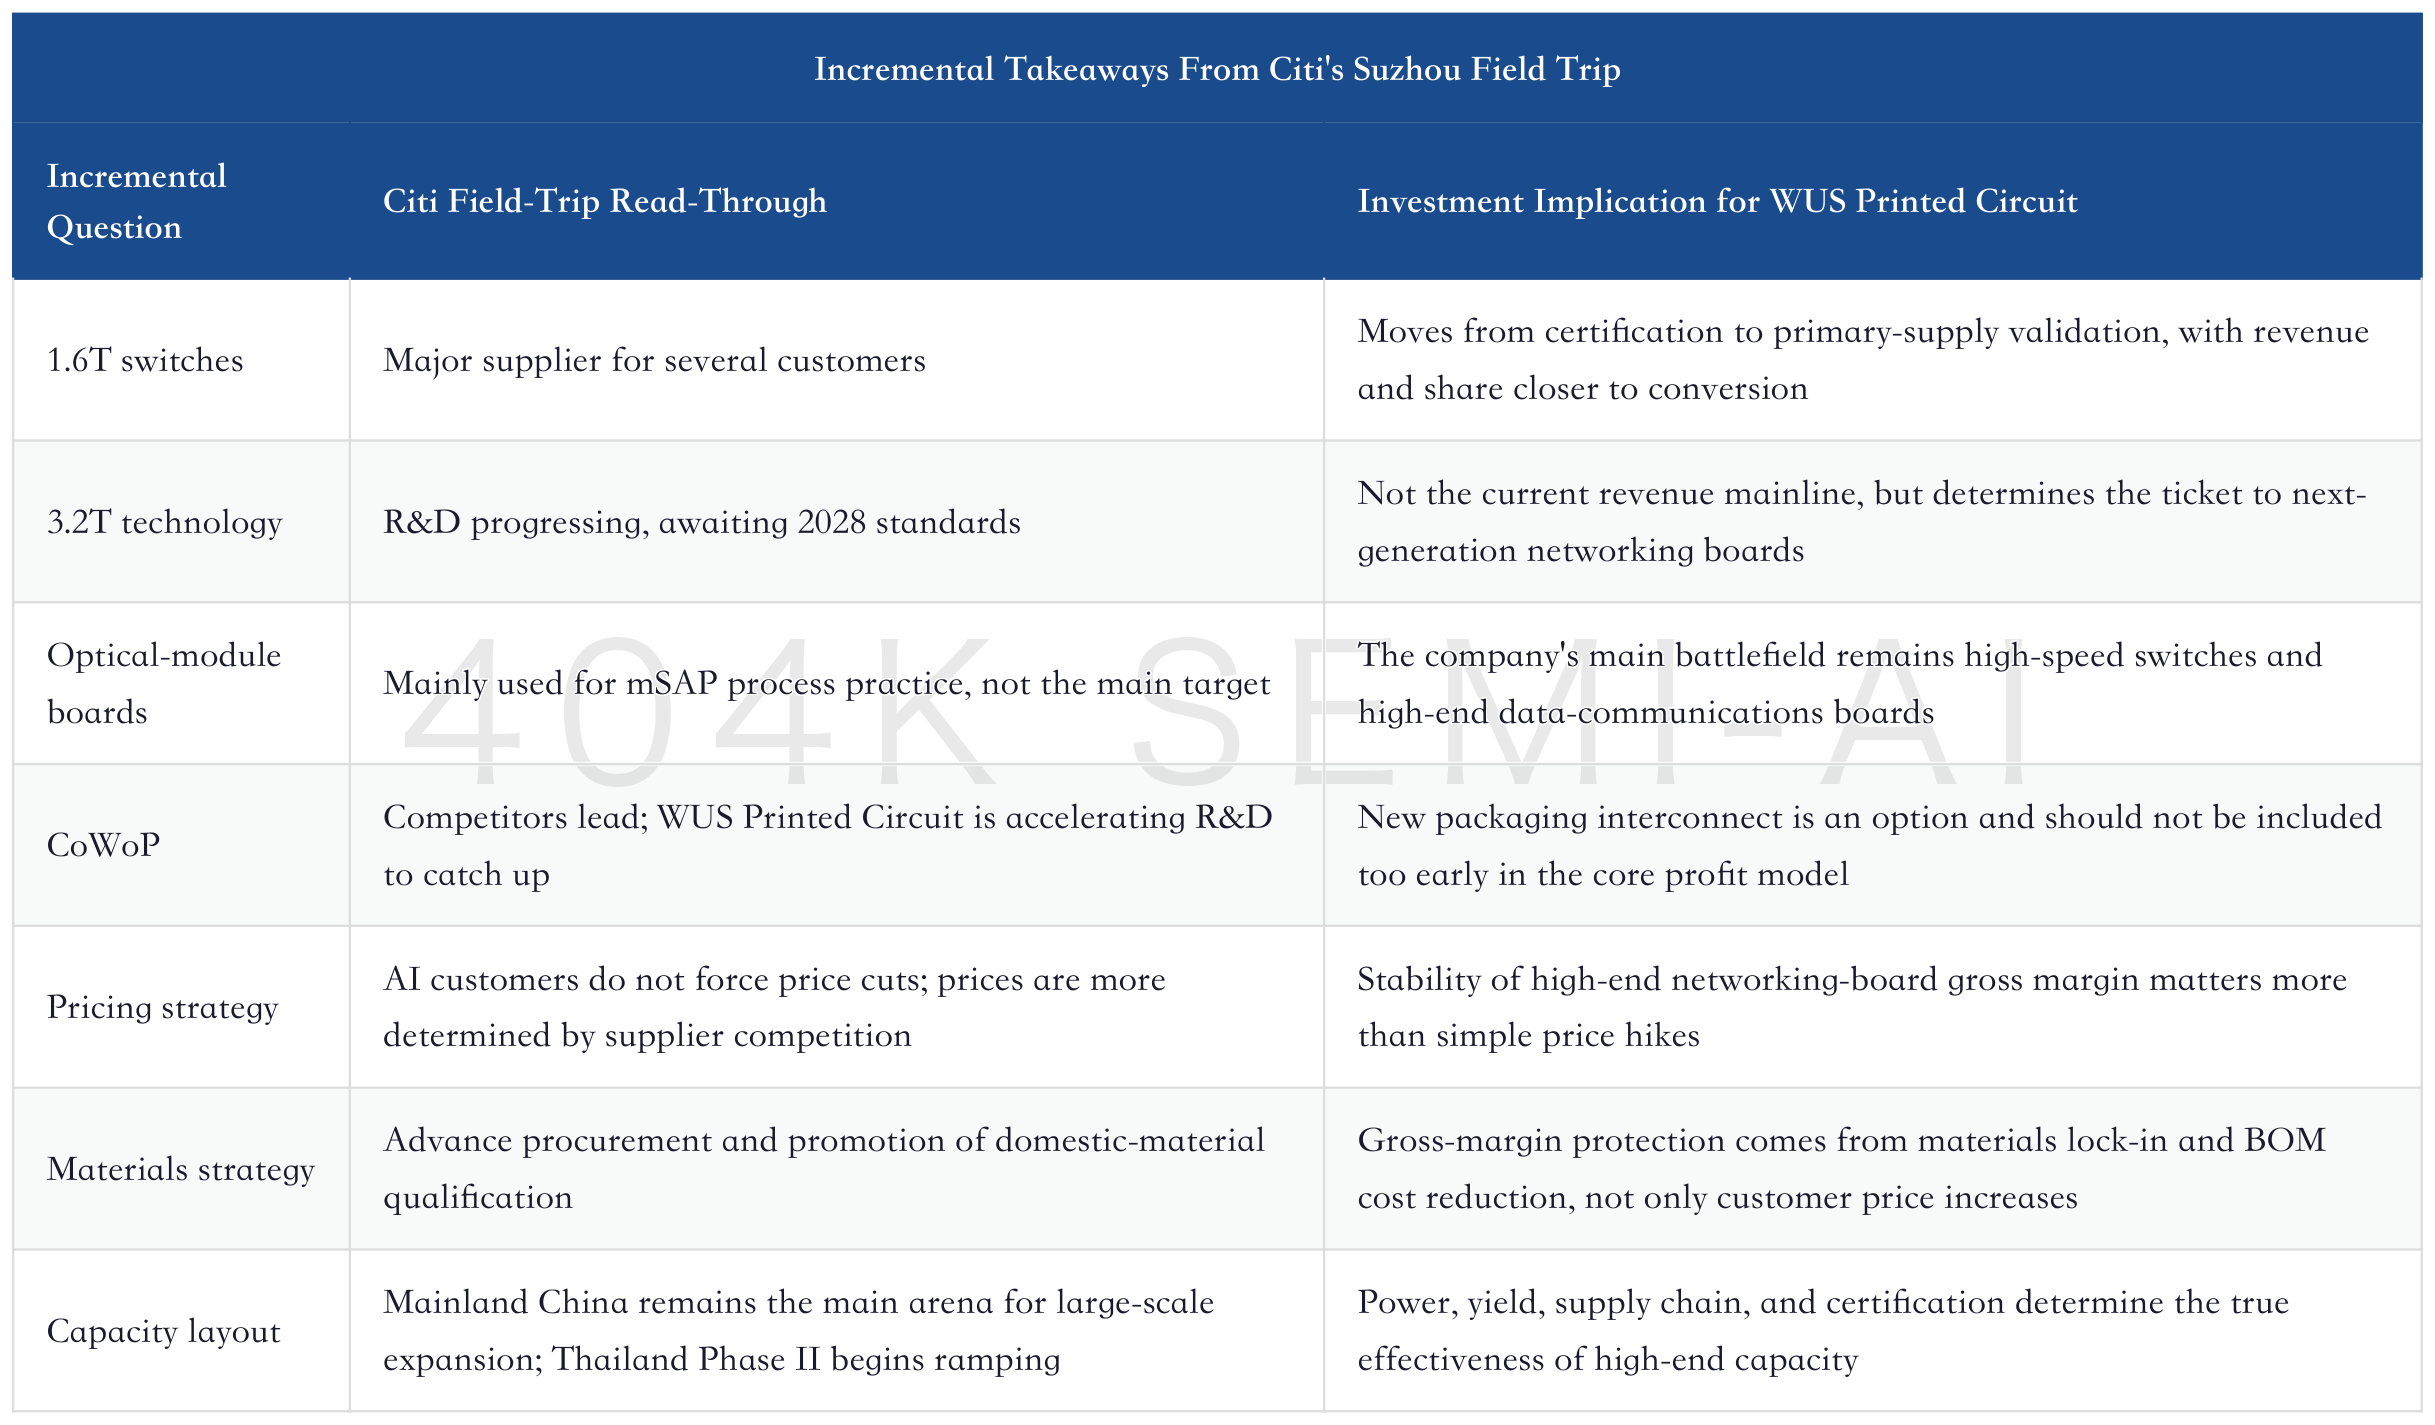
This is also why this update cannot simply be written as "Citi raises its target price." Citi already raised WUS Printed Circuit's target price to Rmb189 in its June AI PCB TAM update; the July Suzhou field trip is more like a review of operating assumptions. It confirmed micro-level details in 1.6T switches, materials strategy, pricing discipline, and capacity choices, and also pushed the Rmb189 target price back from the model spreadsheet to real factories and customer projects.
2. 1.6T Switches: WUS Printed Circuit Moves From Certification to Primary-Supply Validation
WUS Printed Circuit's most valuable incremental opportunity remains on the networking side. The market easily reduces AI PCB to server boards, but the larger training clusters become, the more important switches, line cards, backplanes, and high-speed interconnect become. The significance of 1.6T switch ramp is not only a doubling of speed; it also raises PCB requirements for layer count, materials, signal integrity, backdrilling, thermal reliability, and yield.
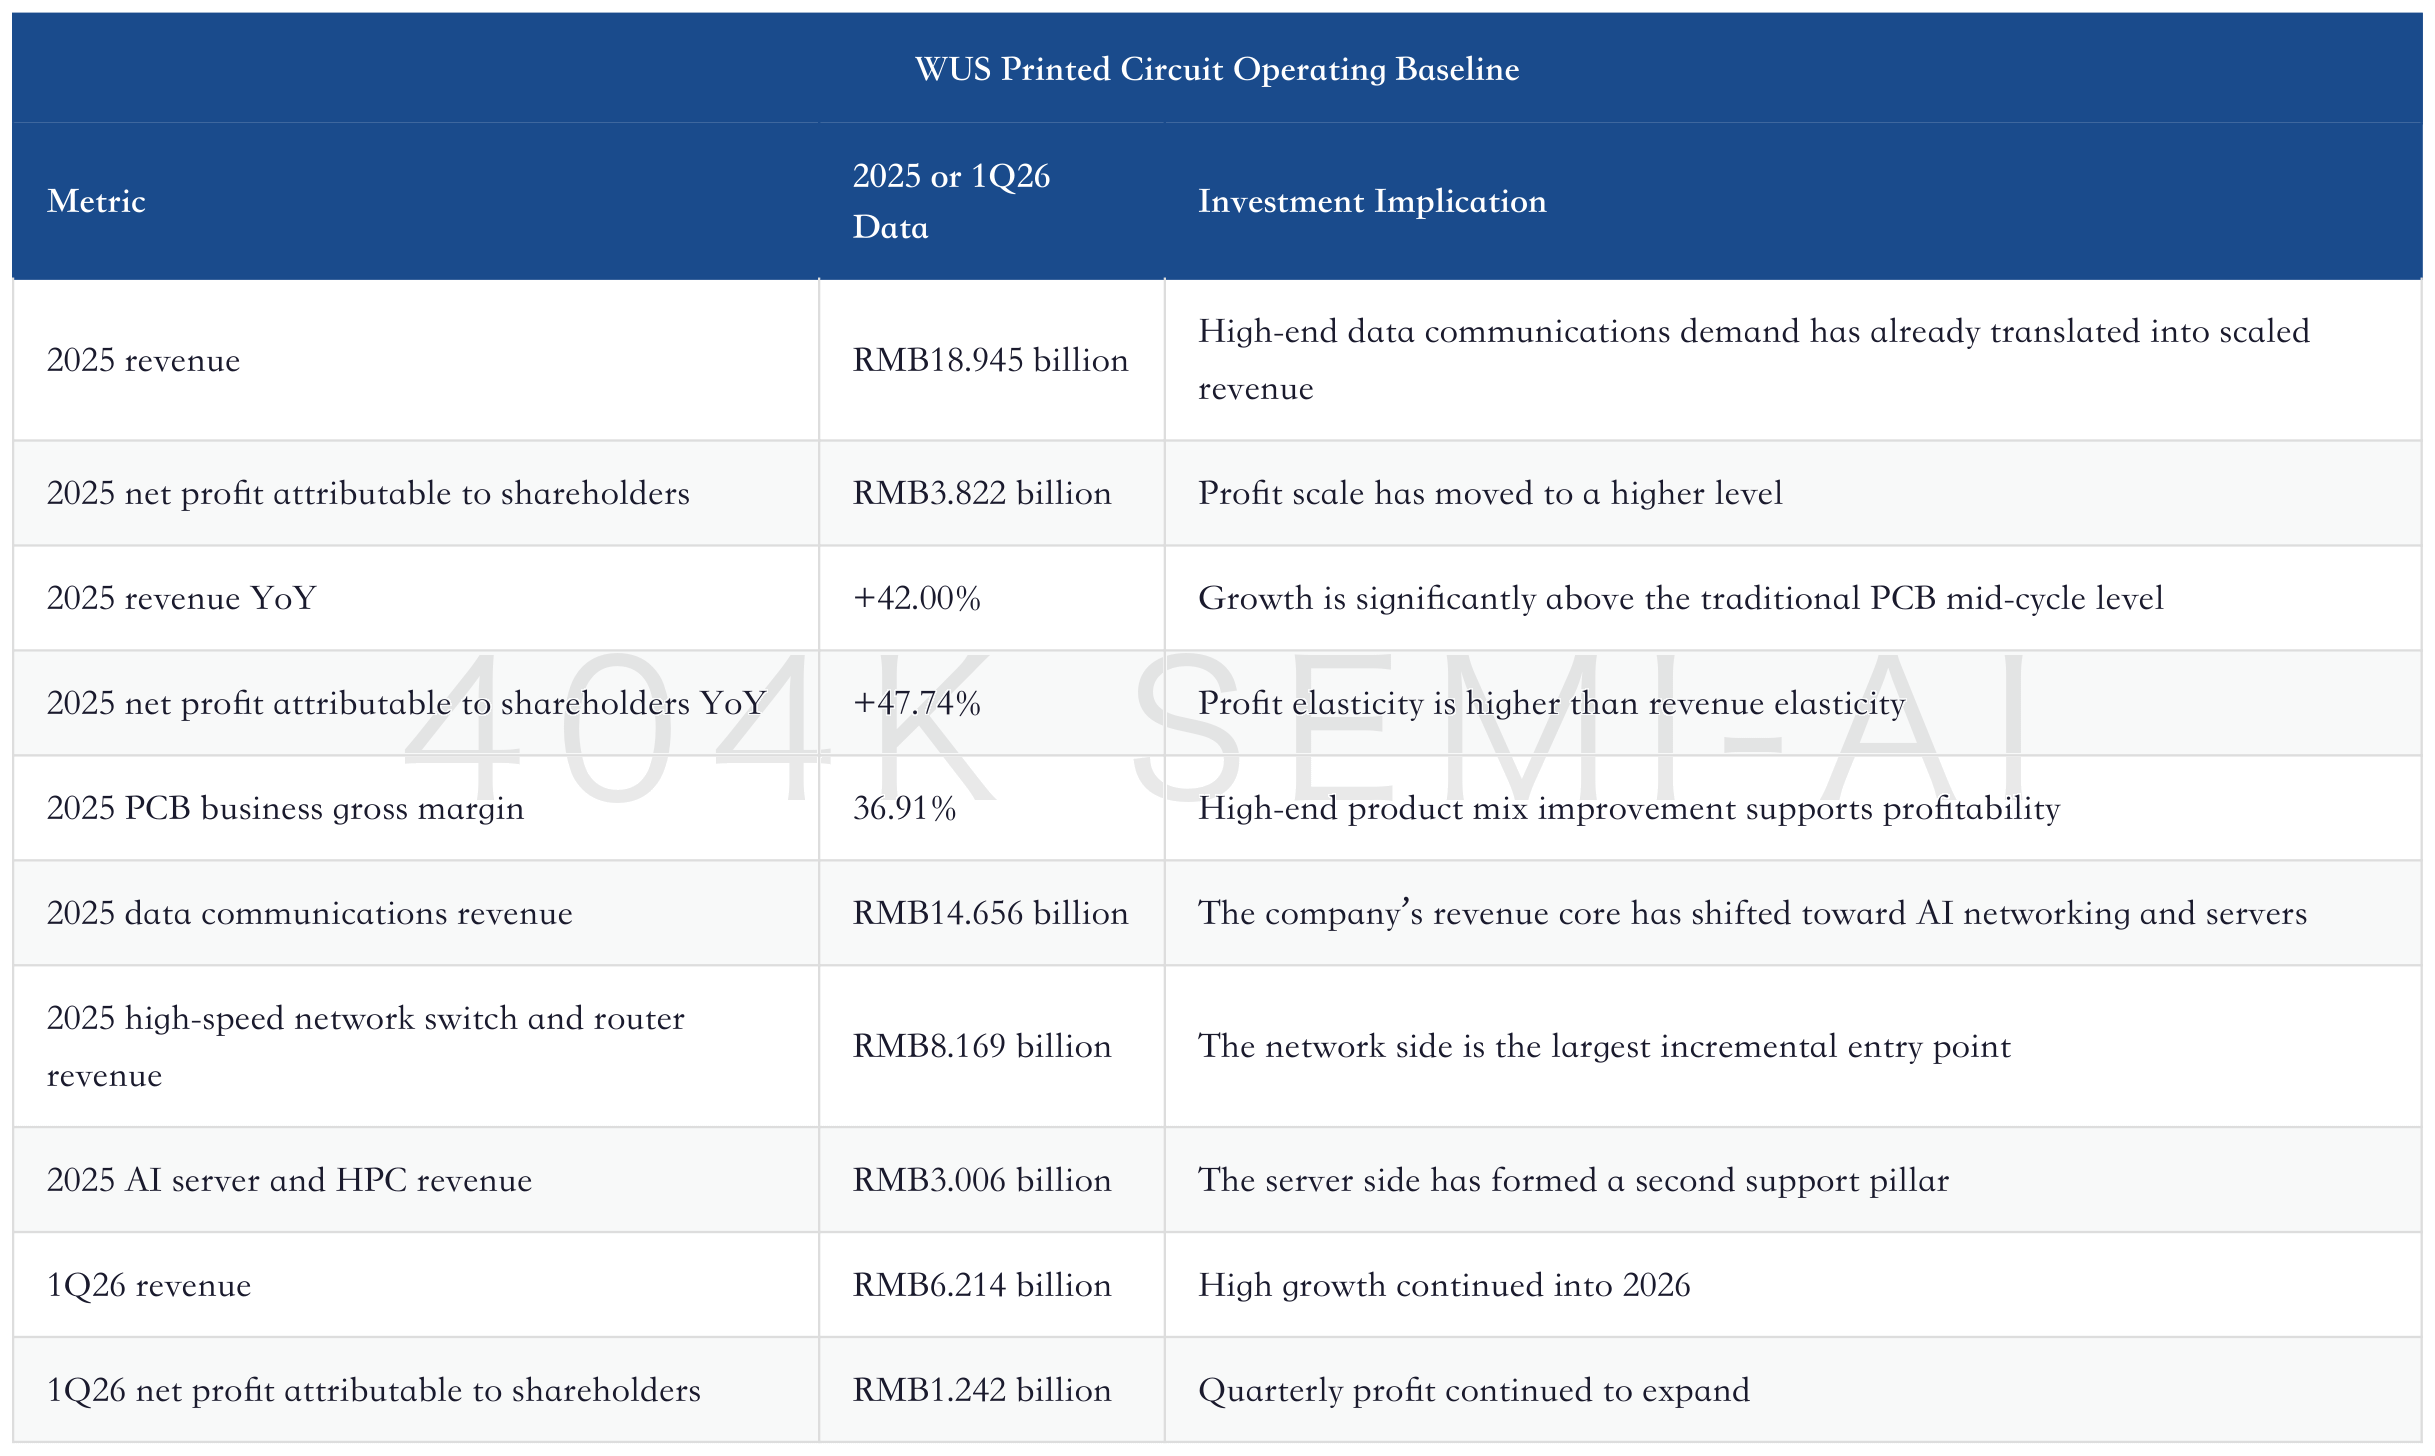
The 2025 annual report already provided the first layer of evidence. PCB revenue from data-communications applications was about Rmb14.656bn, up sharply year on year; within this, revenue from high-speed network switches and supporting routing applications was about Rmb8.169bn, while AI server and HPC revenue was about Rmb3.006bn. Data communications has already become the company's largest source of revenue and profit, and high-speed network switches are the fastest-growing direction within it.
The company has disclosed that products related to 1.6T high-speed network switches completed customer certification and began small-batch delivery. Citi further wrote this time that WUS Printed Circuit is already a major supplier of 1.6T switches for several customers. Certification, small batch, and primary supply mean different things: certification means the company can make it; small batch means it can deliver; primary supply means share and customer trust are starting to be validated.
“1.6T switch”
These three English words are short, but they correspond to a much longer profit chain. 1.6T switches require higher-grade materials, more complex lamination, narrower process windows, and more stable mass-production yield. Customers will not easily switch suppliers for short-term pricing on a few boards, because if high-speed signals, thermal stability, or reliability go wrong, the entire platform delivery is affected. If WUS Printed Circuit becomes a primary supplier across multiple customers, its value is no longer merely "being able to make high-end boards," but "being able to assume core supply within customer platform cycles."
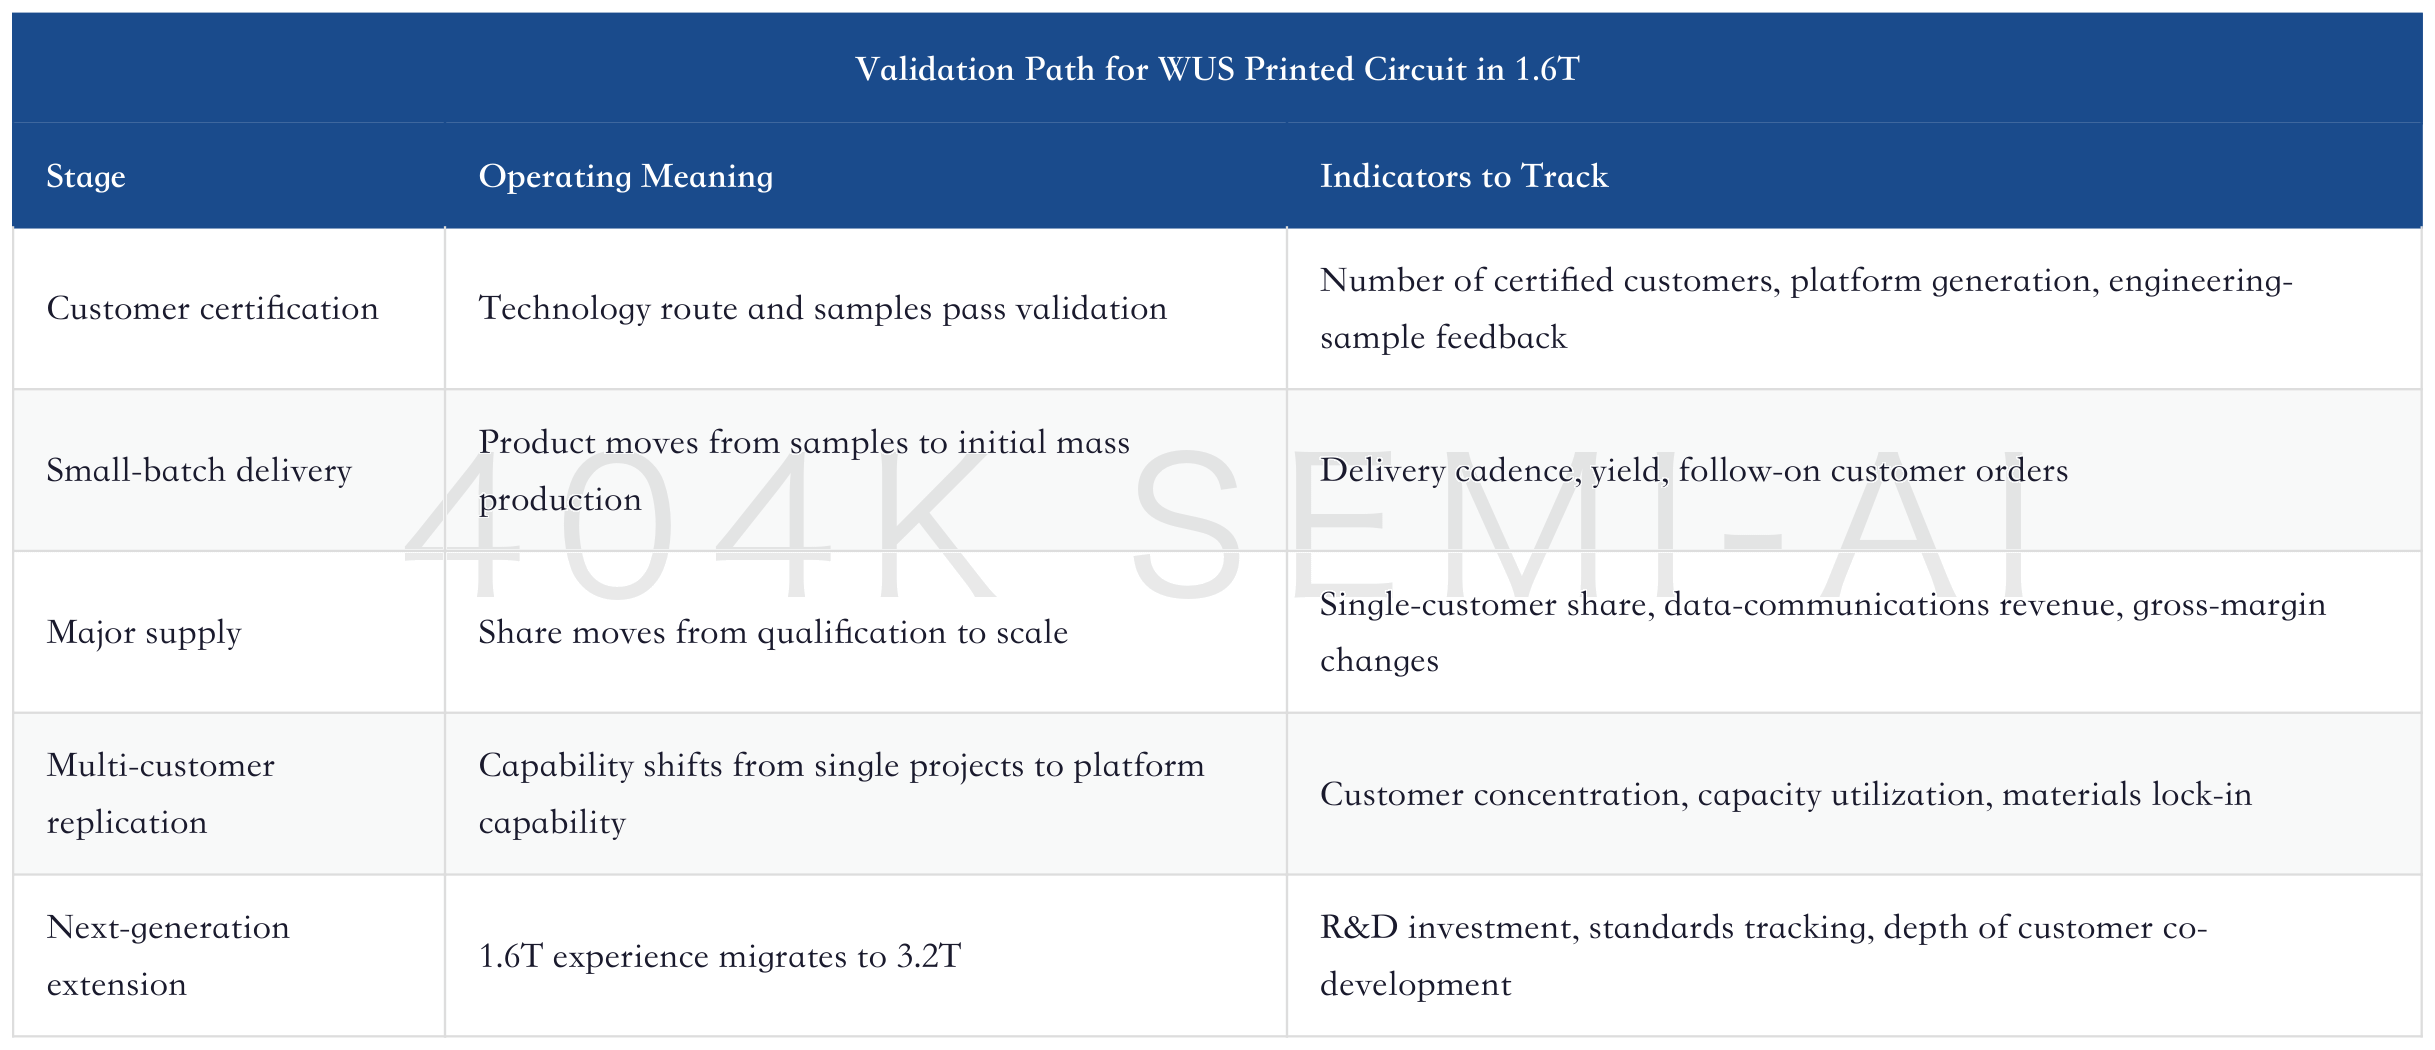
The profit significance of 1.6T comes from the combination of three variables. The first is volume, as AI clusters and high-speed network upgrades continue to drive switch shipments. The second is value content, as higher layer counts, high-frequency/high-speed performance, and low-loss materials lift board ASP. The third is share, as major suppliers have greater stickiness within customer platforms. If WUS Printed Circuit only captures volume growth, profit elasticity will be limited; only if volume, value content, and share all rise together will profit growth exceed revenue growth.
This is also one of the underlying logics behind Citi's Rmb189 target price. Citi is not only looking at industry size; it believes GenAI-related PCB demand, product mix, and delivery capability can support high earnings CAGR in 2026-2028. The 1.6T primary-supplier read-through makes this assumption more concrete, because it maps "high industry growth" onto WUS Printed Circuit's customer share.
III. 3.2T and CoWoP: The Next-Generation Ticket Is Still in R&D; Validation
3.2T is the ticket to next-generation network boards, not a major contributor to current revenue. Citi’s research indicates that the company’s 3.2T-related R&D; is progressing, but it is still awaiting the 2028 standard. This wording should be interpreted cautiously: it shows that WUS Printed Circuit is already tracking the next-generation technology roadmap, but it also shows that 3.2T should not yet be treated as a near-term earnings realization item.
“3.2T tech is ongoing”
The emphasis in this sentence is on “ongoing.” What high-end PCB manufacturers fear most is missing the early definition stage with customers. Before standards are fully finalized, suppliers need to prepare material combinations, process windows, signal testing, and reliability capabilities in advance. Once customer platforms enter formal qualification, suppliers that participated in early development have a better chance of securing share. What WUS Printed Circuit needs to do now is migrate its 1.6T customer relationships, process experience, and delivery capabilities to 3.2T.
CoWoP is another, earlier-stage option. Citi’s research acknowledges that competitors have a first-mover advantage, while also noting that WUS Printed Circuit is actively catching up in R&D.; This judgment is important because it avoids two extremes: immediately writing CoWoP into WUS Printed Circuit’s earnings as a certainty, or ignoring the value of the company’s continued catch-up simply because it is temporarily behind. A more reasonable treatment is to include it as a technology option and tracking indicator, rather than in the current core earnings model.
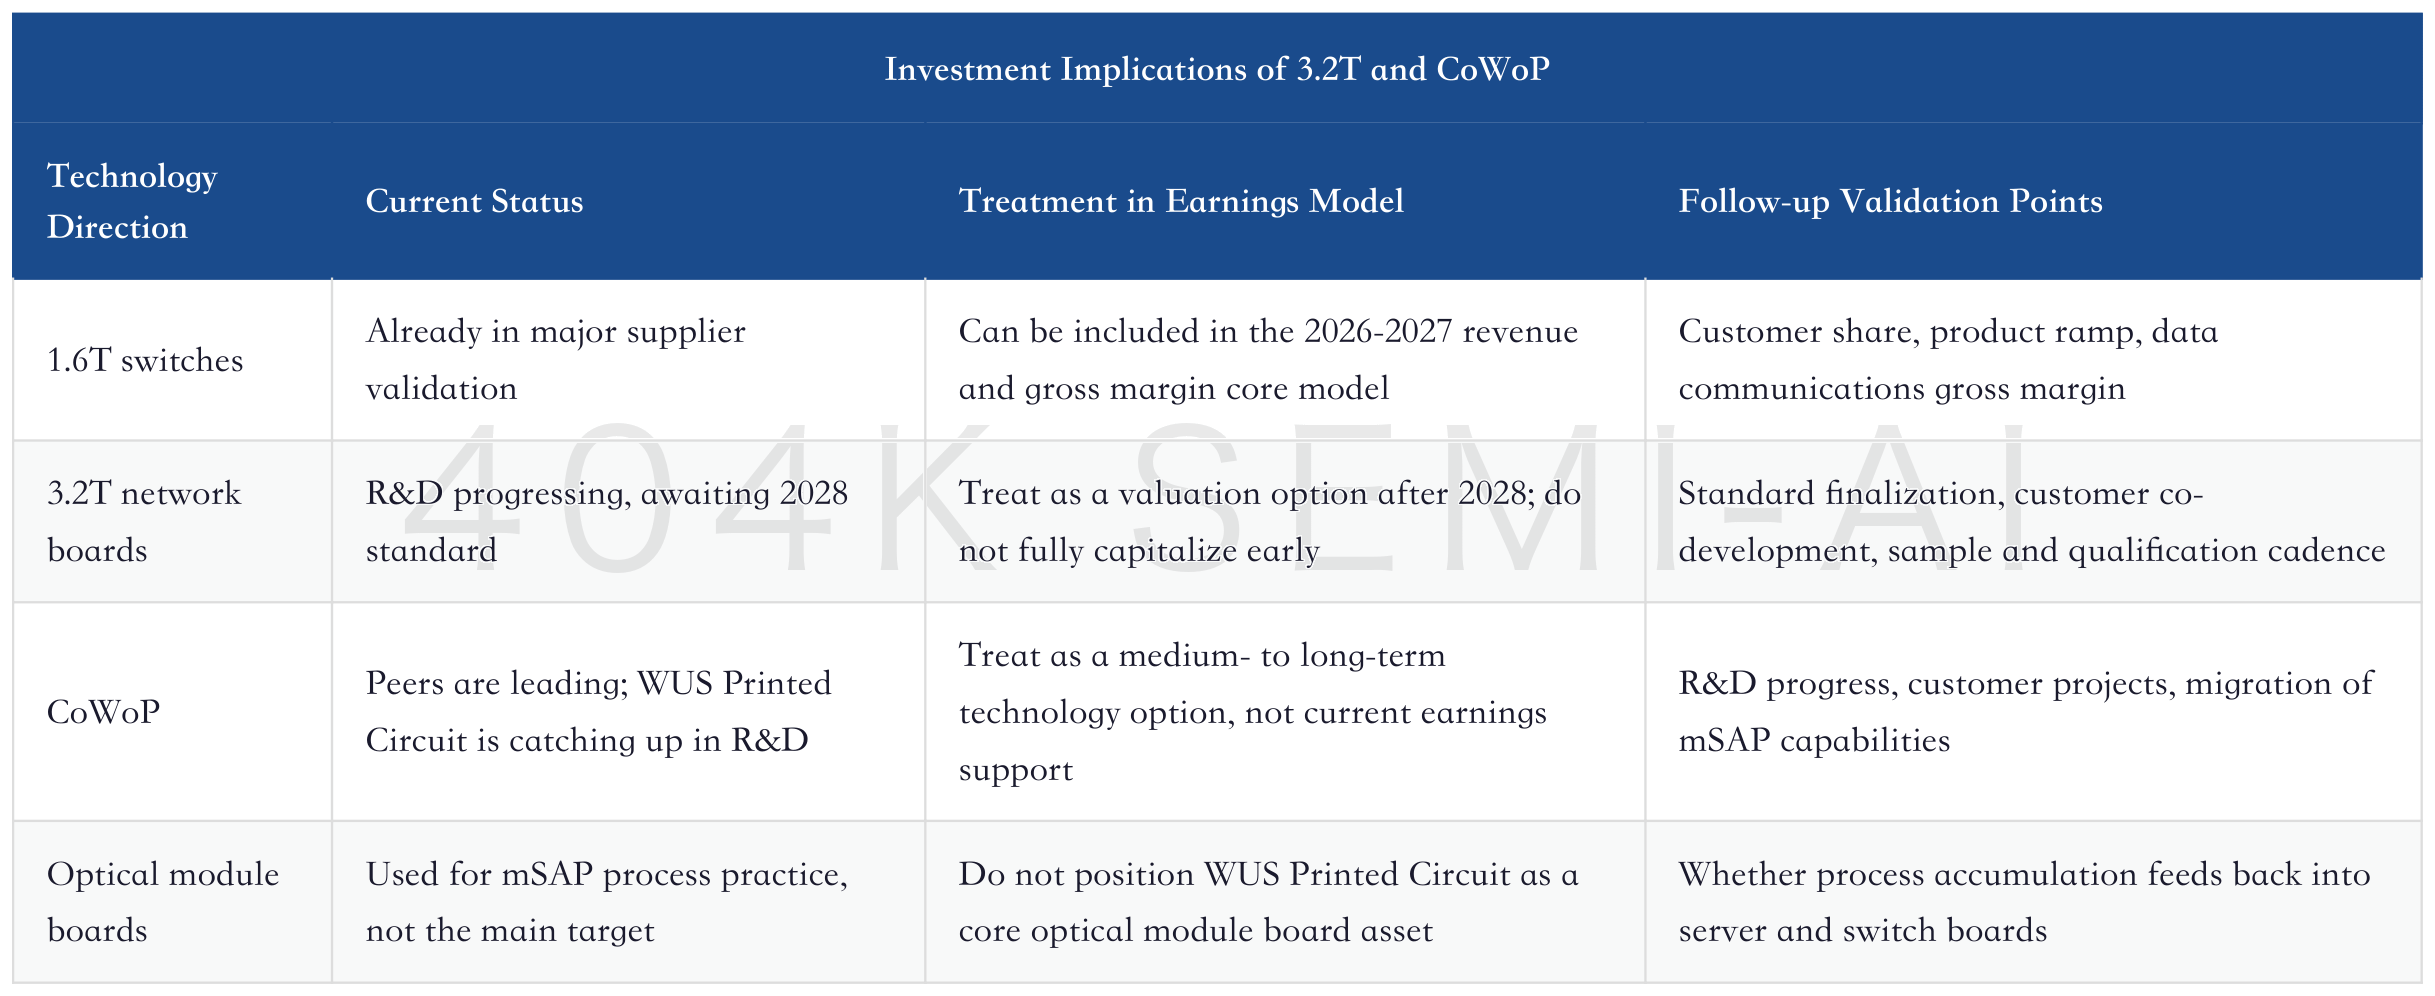
The most common mistake here is to pile all new technologies into a single “AI PCB upgrade” concept. WUS Printed Circuit’s most certain areas today are high-speed network switches and high-end data communications boards. 3.2T is a next-generation extension, CoWoP is an earlier-stage packaging interconnect option, and optical module boards are more about mSAP process practice. Different stages warrant different valuation weights and different ways to disprove the thesis.
AI Network Interconnect Hardware, Part I: Value Migration Behind 1.6T/3.2T, and Who Benefits Most Across Switching, Copper Interconnects, Optical Interconnects, and the Physical Layer
From an industry-chain perspective, WUS Printed Circuit’s advantage is not a single technology label, but the ability to organize high-speed network boards, server boards, material supply, customer qualification, and high-end capacity together. If the 3.2T standard becomes clear around 2028, customers will screen suppliers again. Manufacturers that have already proven delivery capability on 1.6T platforms will naturally be ahead of new entrants.
IV. Pricing Discipline: AI Customers Do Not Force Price Cuts; the Real Pressure Comes from Peer Competition
The most valuable line in Citi’s research is that AI-related customers do not force price cuts, and pricing is determined more by supplier competition. For a PCB company, this matters more than simple price increases. Mandatory annual price cuts would turn high-end products into a cost pass-through game. If customers do not force price cuts, suppliers have the opportunity to defend gross margins through technical difficulty, delivery stability, and product mix.
“clients do not force price cuts”
This sentence should not be interpreted as WUS Printed Circuit having unconstrained pricing power. Management also emphasized that the company will not simply raise prices because capacity is tight, as long-term customer relationships are more important. The real meaning of the pricing strategy is that pricing pressure for high-end AI boards mainly comes from competition among qualified suppliers, rather than fixed-formula customer price reductions. WUS Printed Circuit needs to preserve gross margin through product mix, yield, material locking, and supply-chain coordination, rather than short-term price hikes.
This is very different from ordinary PCB cyclical stocks. Once ordinary boards and low- to mid-end capacity expand, prices fall quickly and customers have strong bargaining power. Competition in high-end AI data communications PCBs is more about “who can deliver stably.” Customers are willing to pay for certainty, yield, and platform schedules, but not for concepts. If a supplier’s delivery is unstable, even a low price makes it difficult to enter core platforms. If a supplier delivers stably, it still cannot raise prices without limit, because customers will still cultivate second suppliers.
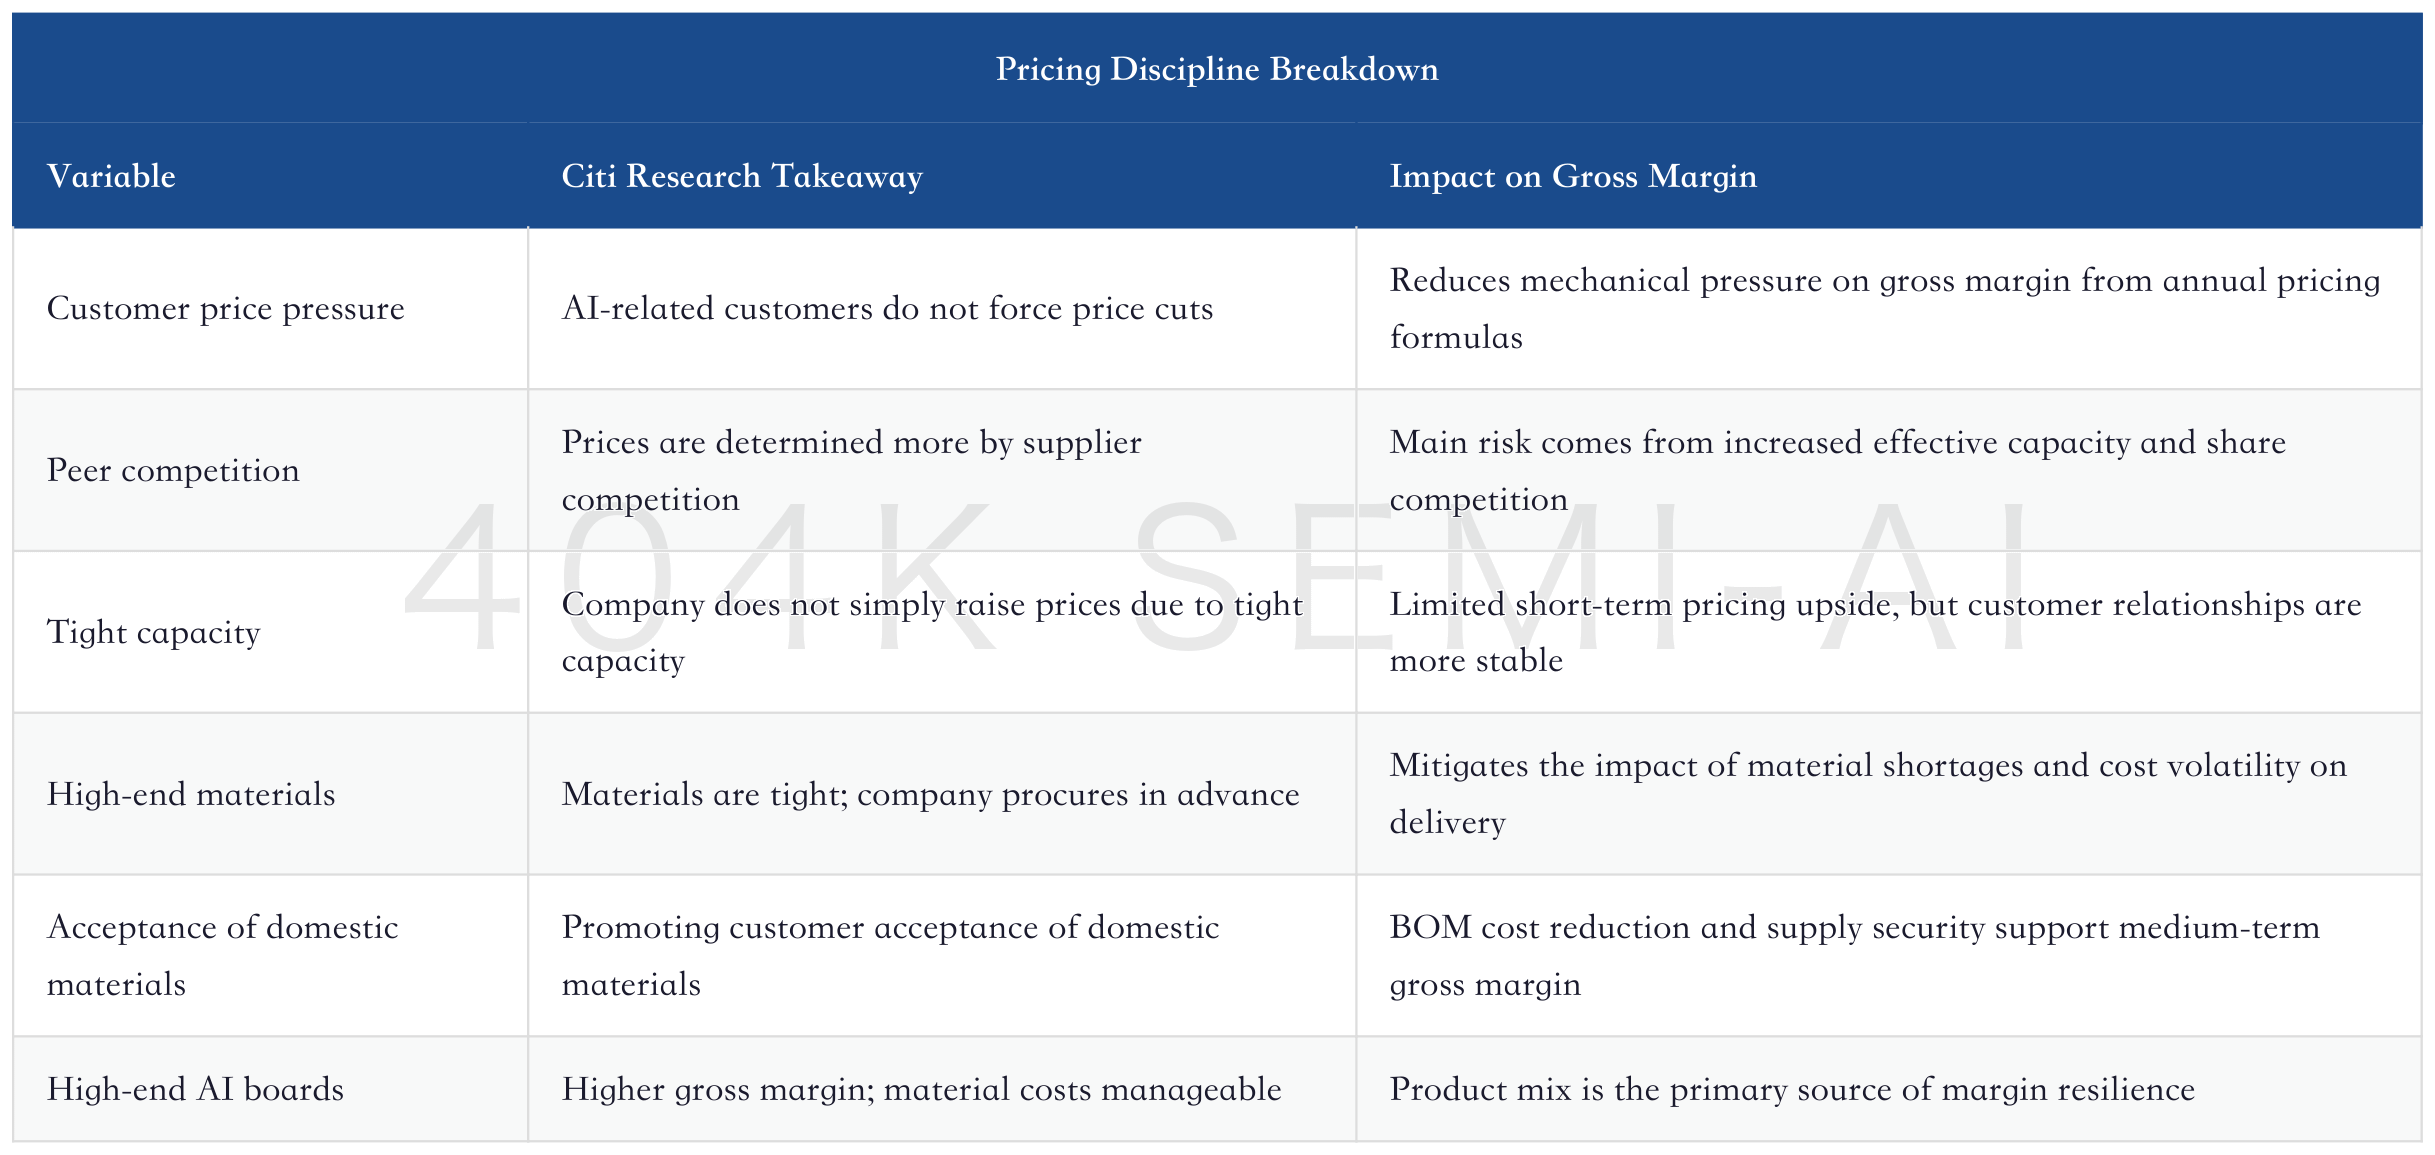
WUS Printed Circuit’s PCB business gross margin in 2025 was around 36.91%, while the data communications business had a higher gross margin of around 39.68%. These figures show that the company’s high growth is not low-margin revenue expansion, but an improvement in high-end product mix. Citi’s research further explains why gross margin may be resilient: customers do not force price cuts, high-end boards have higher gross margins, materials are locked in advance, and customer acceptance of domestic materials is progressing.
But this logic also carries clear risks. If large amounts of high-end PCB capacity come online after 2026, peer competition will become more intense. If customers resume price pressure to control system costs, high-end AI boards will also come under pressure. If material prices rise faster than customer acceptance improves, BOM cost reduction will not be enough to offset cost pressure. Pricing discipline does not mean “prices only rise and never fall”; it means whether gross margin can preserve the earnings quality of high-end products amid competition.
V. Capacity Layout: Power Stability Has Become a Variable in High-End Manufacturing
Citi’s research describes the capacity issue in concrete terms. WUS Printed Circuit’s headquarters has two 110kV substations with total capacity exceeding 120,000kVA, and a dual-circuit structure that ensures continuous and stable power supply. Management also stated that Thailand’s power grid has insufficient reliability and frequent outages. Therefore, for the foreseeable future, major capacity expansion will remain strictly within China, while Phase II of Thailand data communications capacity will begin ramping in July 2026.
This information shifts the capacity judgment from “where labor is cheap” back to “where high-end boards can be manufactured stably.” High-end PCB production is not simply about moving equipment. Continuous processes, lamination, drilling, electroplating, inspection, and yield ramp all depend on stable power, environmental infrastructure, material supply, equipment engineers, and customer qualification. Power interruptions are a problem for ordinary manufacturing; for high-end PCBs, they are more likely to directly affect yield and delivery.
The key to capacity layout is not a binary choice between overseas and domestic capacity, but assigning different tasks to different capacity. Domestic Chinese factories handle high-end complex products, large-scale expansion, and delivery to core customers. The Thailand factory handles part of overseas supply-chain configuration and customers’ multi-region needs. If Thailand’s capacity ramp proceeds smoothly, it can add supply-chain flexibility. If power and supporting infrastructure constraints are significant, it is not suitable for taking on the main capacity for the most complex and continuous high-end network boards.
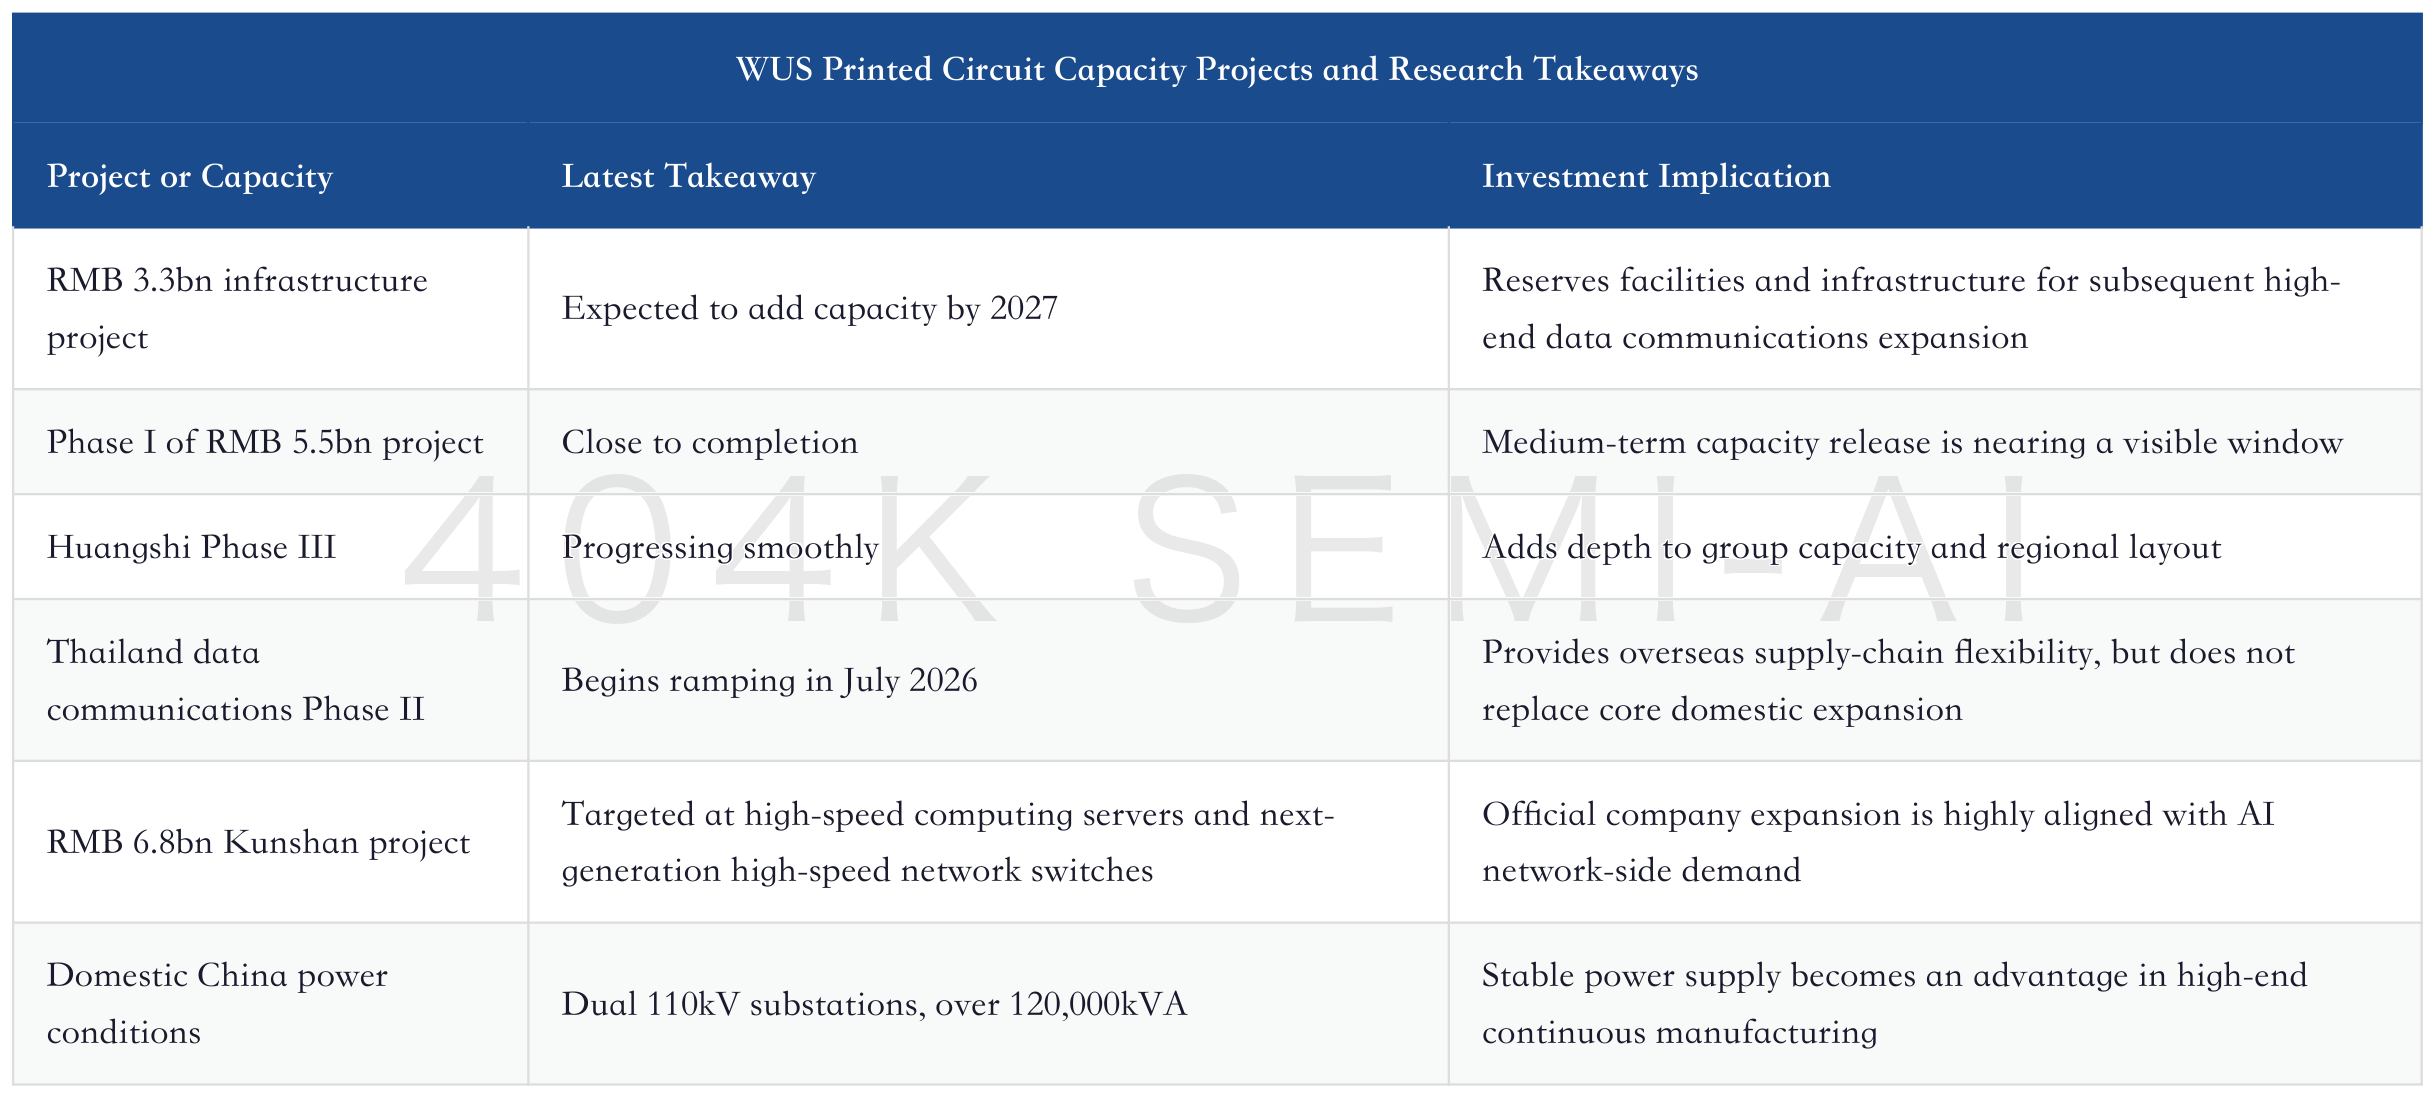
The official capacity expansion announcement also supports this direction. In April 2026, the company announced a planned investment of around RMB 6.8bn to build a printed circuit board production project and supporting facilities. The project targets demand for high-performance, high-reliability PCBs used in high-speed computing servers, next-generation high-speed network switches, and related applications. This is not generalized expansion into ordinary PCBs, but continued expansion around the company’s fastest-growing direction.
Capacity will also bring pressure. Building plants early and purchasing equipment flexibly is a prudent strategy that can avoid excessive one-off equipment investment, but ultimately it still depends on customer demand, qualification progress, and yield ramp. If market demand continues to exceed expectations, plants built in advance will become a delivery advantage. If customer platforms are delayed, depreciation and labor costs will enter the income statement first. Citi’s research explicitly states the strategy of “build plants first, procure equipment flexibly according to demand,” indicating that management is also controlling the pace of expansion.
VI. Financial Baseline: Old Earnings Have Been Delivered; the New Debate Is After 2027
WUS Printed Circuit’s financial baseline for 2025 and 1Q26 is already strong enough. In 2025, the company generated revenue of approximately RMB18.945 billion, up 42.00% YoY; net profit attributable to shareholders of approximately RMB3.822 billion, up 47.74% YoY; and a PCB business gross margin of approximately 36.91%. In 1Q26, revenue was approximately RMB6.214 billion, up 53.91% YoY; net profit attributable to shareholders was approximately RMB1.242 billion, up 62.90% YoY.
This set of data shows two things. First, high-end PCB for AI data communications has already entered the financial statements; it is no longer limited to orders and concepts. Second, profit growth is outpacing revenue growth, indicating that product mix, scale effects, and operating efficiency are working. The key to Citi’s RMB189 target price is not the earnings already delivered in 2025, but whether earnings can continue to compound rapidly in 2026-2028.
Cash flow is the counter-evidence that needs to be tracked separately. In 2025, net operating cash flow was approximately RMB3.872 billion, with very good quality. In 1Q26, net operating cash flow was approximately RMB511 million, down 64.04% YoY, mainly due to increased cash paid for goods purchased and services received. It is not unusual for high-growth companies to see cash-flow volatility during inventory build, capacity expansion, and material locking phases. But if cash flow remains weaker than earnings for several consecutive quarters, growth quality will need to be reassessed.
This is also the dividing line for WUS Printed Circuit’s valuation. If revenue growth, gross margin, and cash flow improve together, the market will be willing to discount 2027 and 2028 earnings in advance. If revenue growth is built on inventory and receivables while gross margin is pressured by materials and competition, the high target price will lose support. The follow-up results that Citi’s research should track are not only orders, but also cash flow, inventory, material procurement, and capacity utilization.
VII. From Goldman Sachs’ RMB142 to Citi’s RMB189: The Debate Lies in Earnings Slope and Material Locking
In May, Goldman Sachs raised its target price for WUS Printed Circuit to RMB142, mainly because AI infrastructure server and switch specification upgrades are driving growth in high-speed connectivity PCBs. It expects high-speed network PCB and AI server PCB revenue to maintain high growth in 2026-2028 and become a larger share of revenue by 2028. In June, Citi raised its target price for WUS Printed Circuit to RMB189, and its July Suzhou research visit continued to validate operating details around that target price.
Both institutions are bullish, but their valuation assumptions differ. Goldman Sachs derives its RMB142 target price from 23x 2027 P/E, emphasizing high-speed connectivity, AI servers, and operating efficiency. Citi derives its RMB189 target price from 30x 2027 P/E, emphasizing GenAI PCB demand in 2026-2028, ASP and gross-margin improvement, and strong execution and delivery capability. Behind the multiple gap is a different judgment on earnings visibility and material-locking capability.
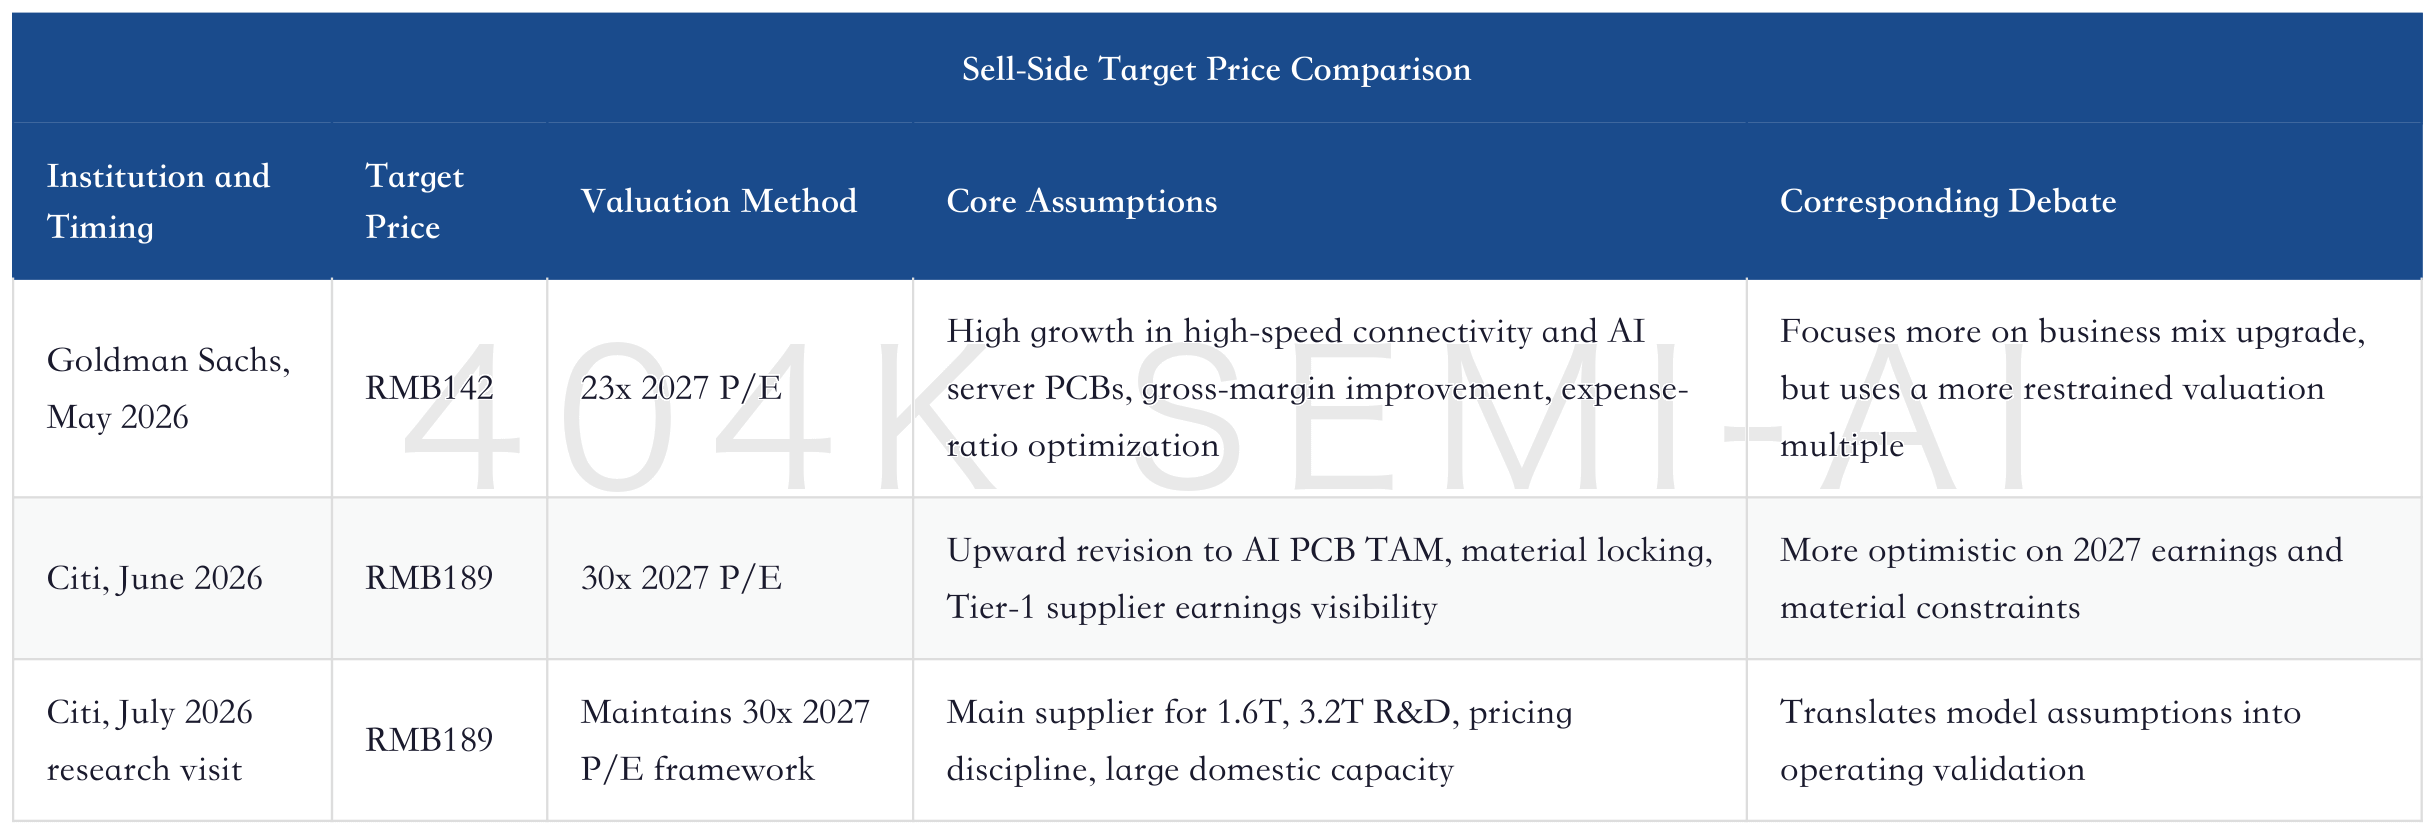
Why is Citi willing to assign a higher multiple? First, WUS Printed Circuit’s high-end data communications business has already delivered, with strong 2025 data communications revenue and gross margin. Second, becoming a main supplier for 1.6T switches improves share visibility. Third, materials and CCL may become industry bottlenecks, making Tier-1 PCB manufacturers’ material-locking capability more valuable. Fourth, the company has a stable track record in high-end manufacturing and customer delivery, supporting higher earnings visibility.
But the target price is not the conclusion itself. The RMB189 target price implies high growth, strong gross margin, controllable materials, stable customer share, and smooth capacity expansion. If any one variable changes, the valuation must be recalculated. Especially after A-share high-end PCB names have already undergone a meaningful rerating, the market will not continue to revise upward simply because Citi’s target price is high. Real quarterly data will be needed from here.
VIII. Earnings Bridge: The RMB189 Target Price Requires Three Variables to Deliver Together
The RMB189 target price can be broken down into a very simple earnings bridge. The first pillar is revenue, coming from high-speed network switches, AI servers, ASIC-related boards, and subsequent penetration of the 3.2T platform. The second pillar is gross margin, coming from high-end product mix, material locking, yield, and customer pricing discipline. The third pillar is expense ratio and depreciation absorption, coming from scale expansion, project ramp-up, and equipment procurement cadence.
No single pillar is enough on its own. If revenue is fast but gross margin declines, the market will treat it as low-quality capacity expansion. If gross margin is stable but revenue does not scale, the RMB189 target price lacks earnings elasticity. If both revenue and gross margin are strong but cash flow continues to deteriorate, the market will worry that inventory and receivables are consuming growth. Citi’s high multiple essentially reflects its judgment that these three variables can move in a favorable direction at the same time.
