
目录
Executive Summary
What Is Genuinely New in This Report
Why a Strong AI Cycle Can Coexist With a Late-Cycle Memory Market
Prices Are Still Rising—Why Are Earnings Losing Upgrade Momentum?
LTAs Can Raise the Floor, but Contract Strength Determines Valuation
Buybacks Are Not Just Rhetoric—the Source of Free Cash Flow Matters
Samsung Electronics and SK Hynix: Both Undervalued, but with Different Rerating Paths
Price Targets Are High—Why Is the Options Market Still Unconvinced?
Which Variables Should Investors Monitor Now for 2028 Supply Risk?
Conclusion: The Next Leg Will Be Evidence-Driven
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Morgan Stanley believes July’s sharp selloff has passed its most dangerous phase, although DRAM price increases have fallen short of expectations. The next leg for memory stocks will depend not only on pricing, but also on whether long-term contracts, free cash flow, and buybacks can extend today’s high-profit environment.
Executive Summary
This is not a bearish turn on memory fundamentals, but a reprioritization of the drivers. Morgan Stanley believes July’s most severe valuation correction is over, with an approximately 3x next-12-month P/E offering scope for a tactical rebound. By the fourth quarter of 2026, however, the industry will enter a late-cycle phase marked by slower price increases, rising inventories, and additional supply.
AI demand remains very strong. The report raised its forecast for 2027 capital-expenditure growth at four US hyperscalers from 14% to 29%, while all four remain constrained by data-center capacity. Strong AI-driven demand for HBM and server DRAM can coexist with a late-cycle environment in PCs, smartphones, and consumer NAND.
Prices are still rising, but the slope has flattened. Tracked third-quarter DRAM contract prices are up 15%, below the previous 20% expectation, while NAND remains at 20%. PC DRAM price growth has slowed from 45%–50% in the second quarter to 15%–20% in the third quarter. Higher prices can still lift near-term earnings, but are unlikely to drive upgrades of the same magnitude.
Long-term agreements (LTAs) can raise the earnings floor, but will not automatically eliminate cyclicality. Samsung Electronics aims to place 60%–70% of capacity under LTAs, while SK Hynix has completed negotiations with approximately 10 customers. Contract durability will ultimately depend on deposits, minimum volumes, price floors, cancellation costs, and enforcement during a downturn.
High price targets do not reflect another major round of earnings upgrades. SK Hynix’s 2026 EPS was raised 13%, mainly because of a one-off asset-disposal gain, while 2027 EPS was cut 2%. Samsung Electronics’ EPS was cut 10% for 2026 and 2% for 2027. Neither company’s price target was raised, meaning upside increasingly depends on the duration of earnings and valuation recovery.
The key issue is not whether prices rise again next quarter, but whether locked-in demand can absorb 2028 supply. The cycle’s valuation midpoint may genuinely move higher only if LTA execution, free cash flow, and buybacks strengthen as the pace of price increases slows.
What Is Genuinely New in This Report
The previous report, “Why Memory Stocks Fall as Profits Rise: Why Did Earnings Upside Stop Working, and Has the ‘Cyclical-to-Growth’ Thesis Failed?”, established a central point: memory stocks are priced not on the absolute level of current earnings, but on how long those earnings can last. The new report advances the discussion from “why did the stocks fall?” to “under what conditions can investors buy again?”
The answer is not simply that AI remains strong. Morgan Stanley proposes a new valuation sequence. First, July’s selloff cleared out some crowded momentum positioning and excessive expectations. Second, an approximately 3x next-12-month P/E is sufficiently low for an industry that continues to generate substantial free cash flow. Further upside, however, can no longer rely on analysts raising current-year EPS. It must come from LTAs improving revenue visibility, capacity discipline protecting margins, and buybacks returning cash to shareholders.
This marks a shift from trading memory prices to investing in earnings duration and cash returns. That shift may support a re-rating, but it requires more rigorous evidence than the previous phase.
Why a Strong AI Cycle Can Coexist With a Late-Cycle Memory Market
A common market mistake is to treat strong AI demand and a peaking memory cycle as mutually exclusive. In reality, they describe different market segments and different time horizons.
On the AI side, the report raised its forecast for 2027 capital-expenditure growth at four hyperscalers from 14% to 29%, an increase of 15 percentage points. All four also remain constrained by insufficient data-center capacity. This implies that computing infrastructure is still expanding rapidly, making a sudden collapse in demand for HBM, server DRAM, and enterprise SSDs unlikely. Suppliers are still targeting a 50%–100% year-over-year increase in 2027 HBM prices, with the goal of aligning HBM margins with conventional DRAM.
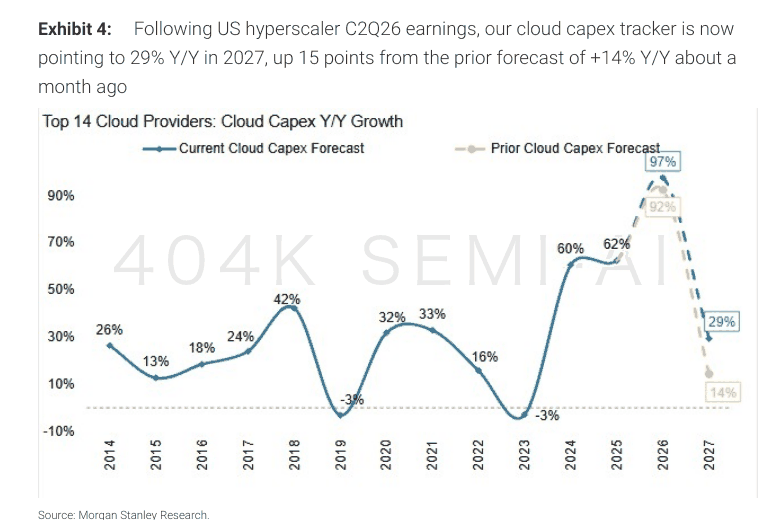
Figure 1: Morgan Stanley raised its forecast for 2027 capital-expenditure growth at major global cloud providers from 14% to 29%. Source: Morgan Stanley research, August 6, 2026.
On the consumer side, however, buyers are approaching the limits of their cost tolerance. Third-quarter PC DRAM contract prices may still rise 15%–20%, versus 45%–50% in the second quarter. Slower price increases in certain consumer and specialty DRAM products do not reflect a sudden easing in supply; customers are simply no longer willing to accept increases of the same magnitude. NAND is also diverging, with strong enterprise SSD demand but weaker consumer customers.
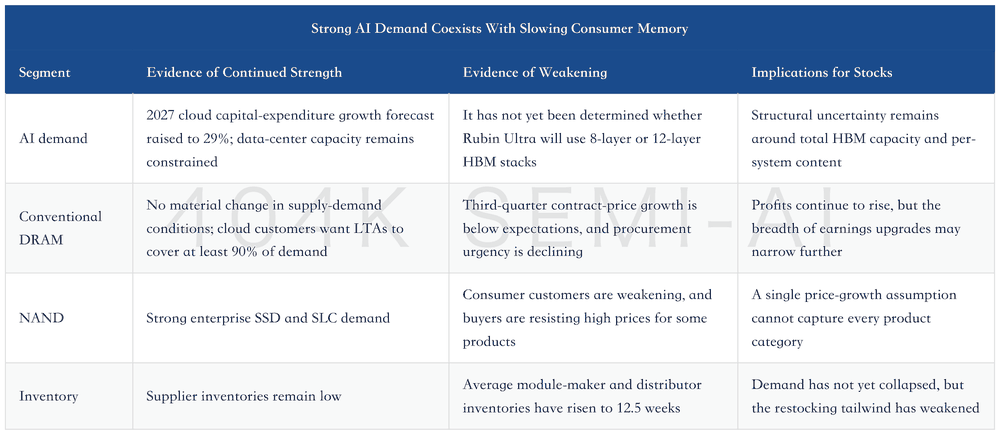
A strong AI cycle and a late-cycle memory market are therefore not contradictory; they reflect product-level divergence. The next phase will not lift all memory companies uniformly. Winners will be those whose capacity is most concentrated in bottleneck products, that can lock strong demand into long-term contracts, and that retain more cash after expanding capacity.
