
目录
Executive Summary
1. Read the Quarter in Three Layers: Operating Results, Physical Shipments, and Accounting Noise
2. Evidence of Both Volume and Value Growth: 231 EB Is Not the Whole Story; the 18% Increase in Revenue/EB Is Key
3. Why Gross Margin Rose from 41.3% to 54.4%: Pricing and Mix Improved First, Then Expense Leverage Amplified Profit
4. Strip Out the $2.05 Billion Sandisk Equity Gain: The HDD Business Was Excellent, but Not as Extraordinary as $8.21 Suggests
5. Why 55.5% Is the New Anchor: Q1 Guidance Calls for Further Expansion from a High Base
6. Free Cash Flow and Deleveraging: Earnings Have Become Capital-Allocation Capacity
7. 40 TB ePMR Shipments Have Begun: Validate the Technology Through Economics, Not the Headline
8. The Next Two Quarters: What Would Prove That 55.5% Is Not a Cyclical Peak?
9. Conclusion: A 55.5% Gross Margin and 34% Free Cash Flow Margin Are the New Anchors
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Western Digital's Q4 results showed simultaneous gains in nearline HDD capacity, the revenue-per-capacity proxy, gross margin, and free cash flow. Once the Sandisk equity gain is stripped out, next quarter's 55.5% gross margin guidance becomes the key gauge of the company's new earnings base.
Executive Summary
Core operating performance was stronger than the headline revenue growth alone suggests. Western Digital generated $3.747 billion of revenue in FY2026 Q4, up 44% year over year. Non-GAAP gross margin was 54.4% and operating margin was 44.2%, up 13.1 and 16.1 percentage points, respectively, while non-GAAP EPS rose 109% to $3.56.
Volume growth was only the first layer; the improvement in the revenue-per-capacity proxy mattered more. Total shipments increased from 190 EB to 231 EB, up about 22%, including an increase in nearline HDD shipments from 170 EB to 209 EB. Revenue grew materially faster than capacity, lifting the revenue/EB proxy from $13.71/TB to $16.22/TB, an increase of about 18%. This points to better pricing and product mix, although it is not the same as the company's reported average HDD selling price.
GAAP EPS of $8.21 cannot simply be annualized. Q4 GAAP net income of $3.195 billion included a $2.05 billion mark-to-market gain on Western Digital's retained interest in Sandisk. More representative measures of the HDD business's recurring earnings were $1.655 billion of non-GAAP operating income, $1.382 billion of non-GAAP net income, and $1.281 billion of free cash flow.
The 55.5% gross margin outlook indicates that earnings are still expanding from an already high base. The midpoint of FY2027 Q1 guidance calls for $4.1 billion of revenue, a 55.5% non-GAAP gross margin, and EPS of $4.00. Using the midpoint assumptions for revenue, gross margin, and expenses implies non-GAAP operating income of about $1.881 billion and an operating margin of about 45.9%.
Cash flow has already converted cyclical profits into balance-sheet improvement. Q4 free cash flow margin was about 34.2%, and full-year free cash flow reached $3.511 billion. Interest-bearing debt declined from $4.711 billion to $1.052 billion, while period-end cash was $1.579 billion, shifting the company from net debt of about $2.597 billion to net cash of about $527 million.
Whether elevated margins can withstand customer concentration and a technology ramp is now the biggest question. Cloud has represented 89%–90% of revenue for five consecutive quarters. That concentration provides scale and visibility, but also magnifies the effect of purchasing decisions by a small number of customers. Western Digital has begun shipping ePMR drives with capacities up to 40 TB, but the materials do not disclose customer qualifications, shipment volume, or yields. EB shipments, revenue/EB, gross margin, and cash flow must therefore validate the ramp together.
1. Read the Quarter in Three Layers: Operating Results, Physical Shipments, and Accounting Noise
For the FY2026 fourth quarter ended July 3, 2026, Western Digital reported revenue of $3.747 billion, up 44% year over year and 12% sequentially. Gross margin under U.S. generally accepted accounting principles (GAAP) was 54.1%, and GAAP operating income was $1.563 billion. Excluding stock-based compensation, restructuring, transaction, and other items, non-GAAP gross margin was 54.4% and operating income was $1.655 billion. Operating income under the two measures was relatively close, confirming that the HDD business itself delivered a genuine earnings step-up.
The year-over-year comparison is also reasonably consistent. Sandisk was spun off on February 21, 2025, and its post-spin results are no longer consolidated into Western Digital. The materials classify Sandisk's historical results before the separation as discontinued operations, while the historical Western Digital figures in the tables are presented on a continuing-operations basis. The comparison between Q4FY25 revenue of $2.605 billion and Q4FY26 revenue of $3.747 billion therefore largely reflects the same HDD business perimeter; the growth was not manufactured by excluding flash revenue. What must be separated instead is the post-spin market-value movement in the retained Sandisk interest and the related transaction costs.
Net income is the figure most likely to be misread. GAAP net income of $3.195 billion and EPS of $8.21 were substantially above non-GAAP net income of $1.382 billion and EPS of $3.56. The difference mainly reflected the fair-value movement in the retained Sandisk interest after the separation, not an additional $2.05 billion of HDD sales during the quarter. The results should therefore be read in three layers: revenue and operating income first, EB shipments and product mix second, and non-operating gains stripped out of net income last.
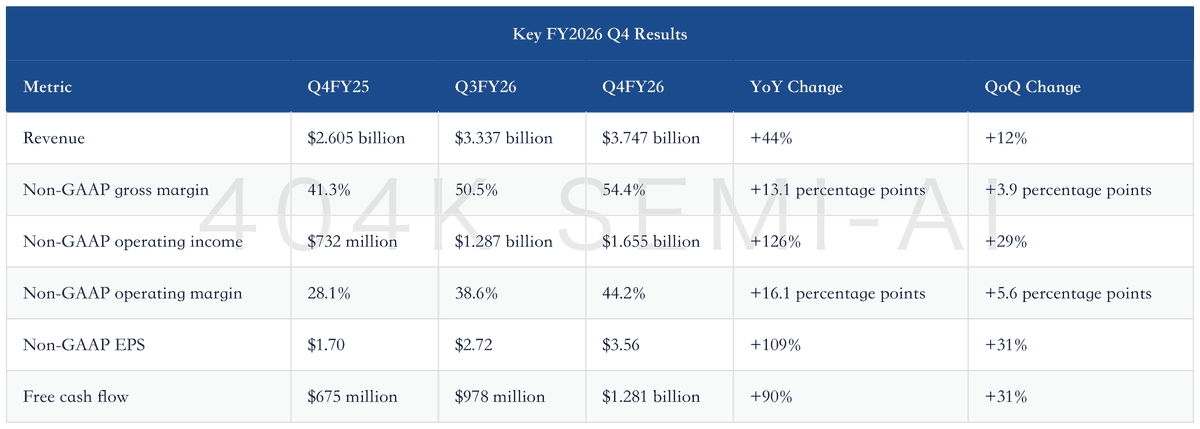
The strength of this set of figures is that revenue, margins, and cash flow moved in the same direction rather than relying on one adjustment item. Revenue increased by $1.142 billion year over year, while non-GAAP operating income rose by $923 million, meaning profit expanded far faster than revenue. Free cash flow also approached non-GAAP net income. Even if GAAP net income is ignored entirely, the core business still delivered results well beyond a conventional capacity upcycle.
2. Evidence of Both Volume and Value Growth: 231 EB Is Not the Whole Story; the 18% Increase in Revenue/EB Is Key
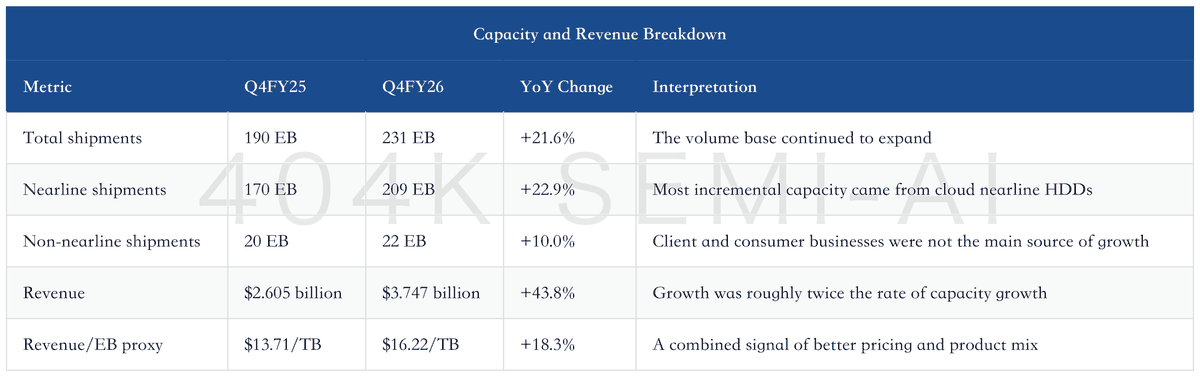
Total Q4 shipments were 231 EB (exabytes), up about 22% from 190 EB a year earlier. Nearline HDD shipments rose about 23%, from 170 EB to 209 EB, while non-nearline shipments increased 10%, from 20 EB to 22 EB. Nearline products accounted for 39 EB of the total 41 EB increase, showing that cloud-oriented, high-capacity storage drove virtually all of the expansion.
Capacity, however, explains only about half of the revenue growth. Revenue increased 44%, from $2.605 billion to $3.747 billion, materially faster than EB shipments. Dividing total revenue by total EB produces a revenue-per-capacity proxy of about $13.71/TB a year ago and $16.22/TB this quarter, an increase of about 18.3%. The proxy reflects capacity per drive, HDD pricing, customer mix, contract terms, and product mix. It is not the company's disclosed average selling price, but it is sufficient to demonstrate that revenue growth did not come solely from shipping more capacity.
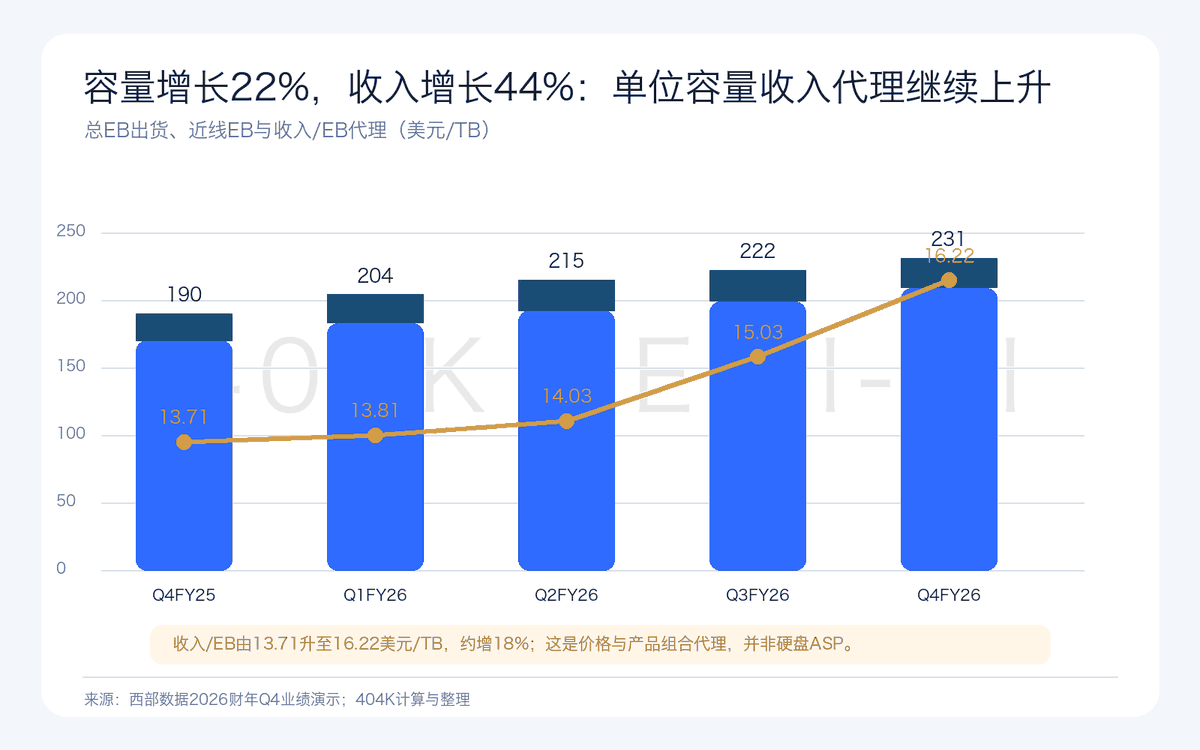
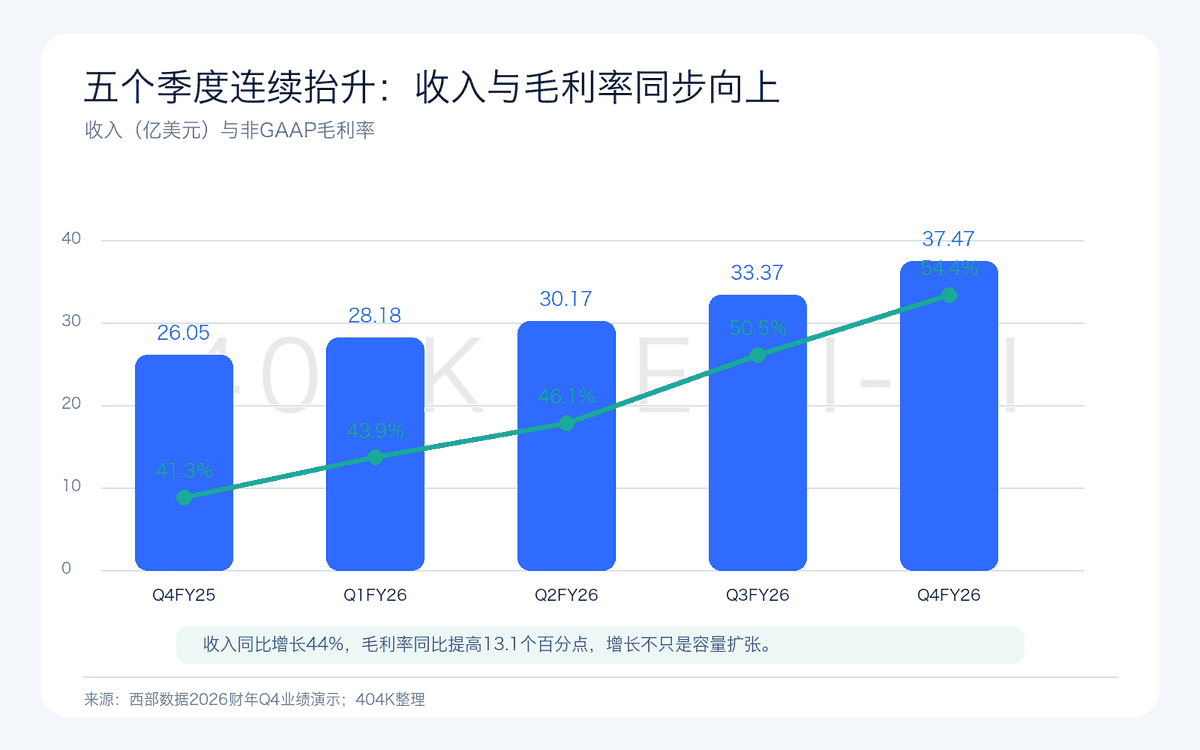
The improvement in capacity economics was sequential rather than a one-quarter Q4 jump. Using the same method, the revenue/EB proxy over the past five quarters was approximately $13.71, $13.81, $14.03, $15.03, and $16.22 per TB. Changes were modest in the first two quarters, then accelerated in Q3 and Q4. Over the same period, non-GAAP gross margin rose sequentially from 41.3% to 54.4%. Both series moved upward together, indicating that a meaningful share of the improvement in revenue per unit of capacity reached gross profit rather than being fully absorbed by manufacturing costs, warranty expenses, or new-product introduction costs.
This proxy also defines the limits of any pricing conclusion. Looking only at 44% revenue growth could lead to attributing the entire increase to price; looking only at 22% EB growth could understate the contribution of mix. A more reasonable decomposition is that roughly 22% capacity growth provided the volume base, while about 18% improvement in the revenue-per-capacity proxy supplied the pricing and mix base. Multiplying the two brings the result close to the 44% revenue increase. Because Western Digital does not disclose HDD unit shipments or average capacity per drive, the 18% cannot be split precisely among per-drive pricing, areal density, and customer mix, and this report does not extrapolate beyond the materials.
Cloud has represented 89%–90% of revenue for five consecutive quarters and accounted for 89% in Q4; client represented 6%, and consumer represented 5%. This confirms that Western Digital has shifted from a diversified storage company spanning flash, personal devices, and HDDs to an HDD infrastructure company highly focused on cloud and data-intensive workloads. The materials do not separately disclose "AI revenue." AI flows into the financials when cloud customers retain more training, inference, and business data, ultimately appearing in nearline EB shipments, product capacity, and capacity economics.
At the same time, the 89% cloud revenue mix creates concentration risk. Qualification schedules, purchasing cadence, inventory strategies, or long-term agreement changes at a few large customers will flow through to revenue and utilization more quickly than in the past. The high percentage is neither inherently bullish nor bearish: it improves scale efficiency when demand is strong and supply discipline holds, but it can also pressure both EB shipments and pricing when customers postpone deployments.
3. Why Gross Margin Rose from 41.3% to 54.4%: Pricing and Mix Improved First, Then Expense Leverage Amplified Profit
Western Digital's non-GAAP gross margin over the past five quarters was 41.3%, 43.9%, 46.1%, 50.5%, and 54.4%, with no interruption in the progression. The 13.1-percentage-point year-over-year increase in a single quarter shows that the company did not trade price for volume. Capacity growth, a higher nearline mix, a rising revenue-per-capacity proxy, and operating execution lifted gross profit together.
An approximate decomposition of the year-over-year change in Q4 gross profit makes the point clearer. Based on disclosed revenue and margins, non-GAAP gross profit increased by about $962 million, from approximately $1.076 billion a year ago to roughly $2.038 billion. If revenue alone had grown while gross margin stayed at 41.3%, the additional revenue would have contributed about $472 million of gross profit. The remaining roughly $490 million came from applying a higher gross margin to this quarter's revenue. The two components were approximately equal, showing that both capacity growth and a repricing of unit economics drove the earnings surge; any explanation focused on only one side is incomplete.
The expense base amplified the improvement. Q4 non-GAAP operating expenses increased just 11% year over year to $382 million, versus 44% revenue growth and even faster gross profit growth. Operating income consequently rose from $732 million to $1.655 billion, while operating margin increased from 28.1% to 44.2%. Fixed R&D;, sales, and administrative costs did not rise in proportion to revenue, allowing more gross profit to flow directly into operating income.
This incremental margin should not be extrapolated mechanically. The current result reflects supply-demand conditions, product mix, and expense discipline at the same time. Once gross margin exceeds 50%, each additional percentage point depends more heavily on pricing discipline, yields for high-capacity products, and customer mix. If pricing stops rising or ramp costs for new products increase, operating income may still grow, but it will not indefinitely outpace revenue.
Gross margin does not need to set a new record every quarter to prove that the earnings base has moved higher. A 13.1-percentage-point move from 41.3% to 54.4% cannot recur every year. As long as capacity and pricing do not reverse and expense discipline holds, a gross margin plateau near 55% can still allow operating income and free cash flow to grow with revenue. A simultaneous decline in the revenue/EB proxy, gross margin, and EB shipments would be the signal that supply-demand conditions and product mix have reversed together.
The full-year figures show the same operating leverage. FY2026 revenue increased 36% to $12.919 billion; non-GAAP gross margin rose 9.7 percentage points to 49.1%; and operating expenses grew only 8%. Non-GAAP operating income therefore increased 107% to $4.817 billion, lifting operating margin from 24.4% to 37.3%. Full-year non-GAAP EPS rose 104%, from $5.02 to $10.22. Q4 was therefore not an isolated year-end push, but the culmination of a year-long progression in volume, value, and expense discipline.
4. Strip Out the $2.05 Billion Sandisk Equity Gain: The HDD Business Was Excellent, but Not as Extraordinary as $8.21 Suggests
Western Digital completed the separation of its flash business on February 21, 2025, after which Sandisk was no longer consolidated into continuing operations. Western Digital's retained interest in Sandisk was marked to market, producing a $2.05 billion fair-value gain in Q4, while debt and equity transaction costs totaled $362 million. These and other adjustments caused GAAP interest and other income, net, to reach $1.684 billion—more than GAAP operating income of $1.563 billion.
GAAP net income of $3.195 billion was therefore not a simple representation of one quarter of HDD operating profit. The difference between non-GAAP operating income of $1.655 billion and GAAP operating income of $1.563 billion was relatively modest, supporting the quality of core profit generated by revenue, gross margin, and expenses. Non-GAAP net income of $1.382 billion excludes the Sandisk equity gain and related transaction items and is therefore a better measure of recurring earnings.
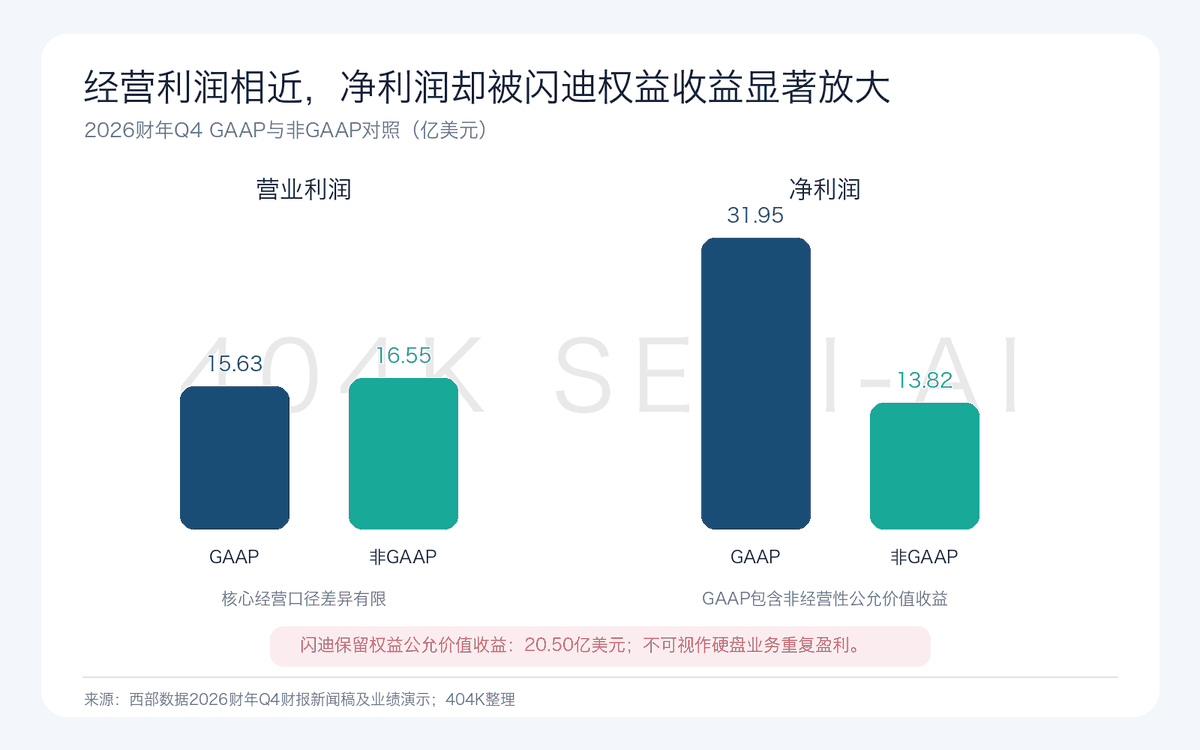
The full-year divergence was even larger. FY2026 GAAP net income was $9.298 billion and EPS was $24.28, compared with non-GAAP net income of $3.883 billion and EPS of $10.22. The full-year fair-value gain on the retained Sandisk interest was $6.498 billion, while debt and equity transaction costs were $907 million. Any valuation of the HDD business that simply annualizes the $24.28 figure would mistake capital-market price movements for sustainable operating earnings.
The retained Sandisk interest on the balance sheet declined from $354 million at the previous fiscal year-end to zero at the current year-end. Without a new related asset or transaction, this fair-value gain should not be treated as a recurring source of earnings in subsequent quarters. Conversely, that will also make FY2027 results easier to interpret: GAAP net income could decline year over year because the gain is absent, even if operating income, non-GAAP net income, and free cash flow continue to grow.
5. Why 55.5% Is the New Anchor: Q1 Guidance Calls for Further Expansion from a High Base
Western Digital's non-GAAP guidance for FY2027 Q1 calls for revenue of $4.0 billion–$4.2 billion, gross margin of 55%–56%, operating expenses of $390 million–$400 million, interest and other expense of about $15 million, a tax rate of approximately 17%, diluted shares of roughly 388 million, and EPS of $3.85–$4.15. The midpoints are $4.1 billion of revenue, a 55.5% gross margin, and EPS of $4.00.
At the midpoint, gross profit would be about $2.276 billion. After subtracting $395 million of operating expenses, implied non-GAAP operating income would be approximately $1.881 billion, for an operating margin of about 45.9%. Subtracting roughly $15 million of interest and other expense and applying a 17% tax rate yields net income of about $1.548 billion. Dividing that amount by 388 million shares produces EPS of about $3.99, consistent with the $4.00 midpoint.
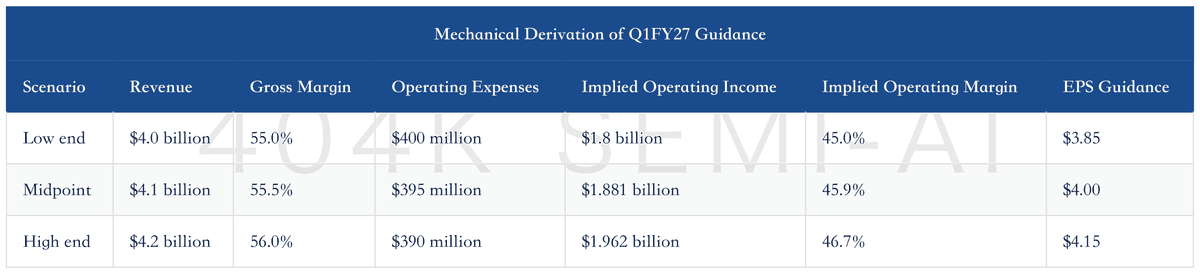
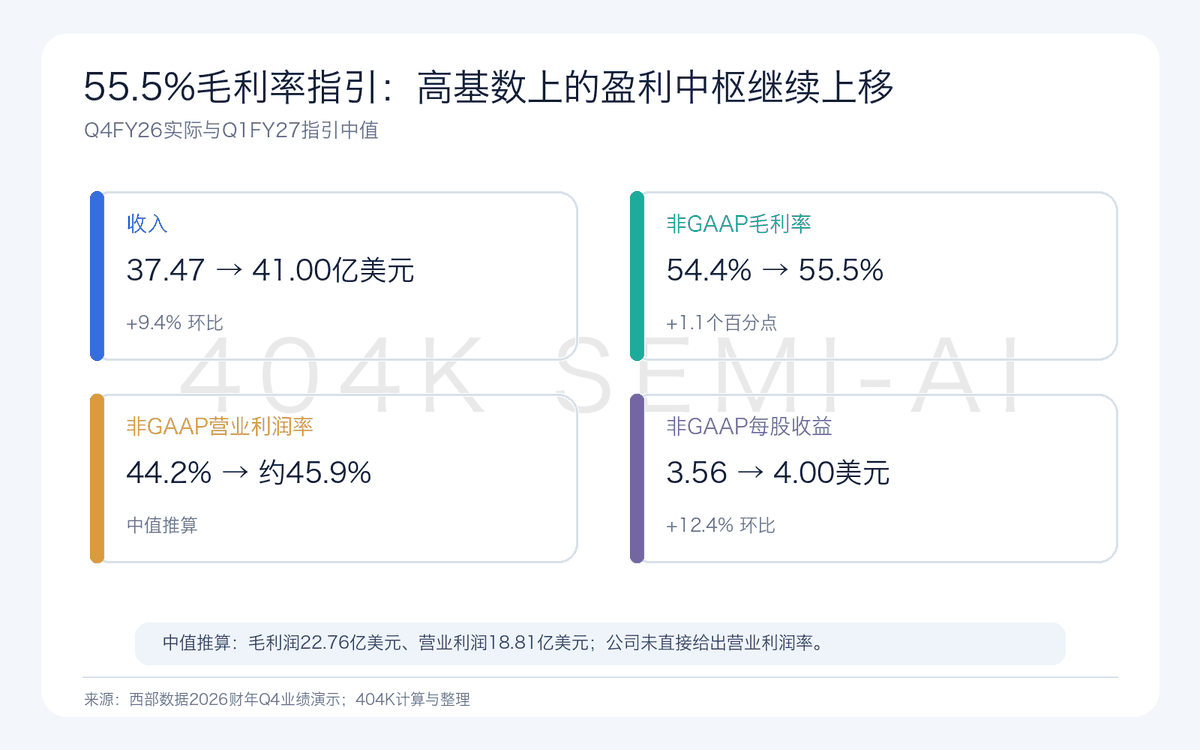
The endpoints combine the mechanical boundaries of each input and do not imply that Western Digital has promised all variables will occur simultaneously. What matters is the direction of the midpoint: revenue would rise 9.4% sequentially from Q4, gross margin would expand another 1.1 percentage points, operating margin would increase about 1.7 percentage points, and EPS would grow 12.4%. Even after an already strong Q4, management still expects at least one of volume, pricing, or mix to improve further.
From Q4 to the Q1 midpoint, revenue would increase by about $353 million and implied operating income by roughly $226 million, corresponding to an incremental operating margin of about 64%. That is not the product's long-term margin; it is a period of operating leverage in which fixed expenses grow more slowly while gross margin continues to expand. If Q1 reaches the revenue midpoint but misses the 55.5% gross margin midpoint, the market's assessment of a new earnings base should be lowered. Conversely, if gross margin approaches 56% while EB shipments continue to grow, further earnings upgrades would remain plausible.
The midpoint assumptions also allow for a simple sensitivity analysis. At constant revenue of $4.1 billion, each 1-percentage-point deviation in gross margin would change gross profit by about $41 million; using a 17% tax rate and 388 million shares, the EPS effect would be about $0.09. Each $10 million change in operating expenses would affect after-tax EPS by about $0.02. Each $100 million change in revenue, assuming an incremental gross margin near 55.5% and no expense change, would affect after-tax EPS by about $0.12. EPS of $4.00 is therefore sensitive to revenue, but the ability to hold gross margin above 55% matters more because it determines both current-quarter profit and the market's view of medium-term pricing discipline.
6. Free Cash Flow and Deleveraging: Earnings Have Become Capital-Allocation Capacity
Q4 operating cash flow was $1.389 billion, net capital expenditures were $108 million, and free cash flow was $1.281 billion, for a free cash flow margin of about 34.2%. Full-year operating cash flow was $3.929 billion, capital expenditures were $418 million, and free cash flow was $3.511 billion, for a free cash flow margin of about 27.2%. Capital expenditures were modest relative to revenue, allowing most of the margin improvement to convert into cash.
Cash conversion was also strong. Q4 free cash flow was approximately 92.7% of non-GAAP net income, and full-year free cash flow was about 90.4% of non-GAAP net income. Both ratios were close to 90%, showing that, after excluding the Sandisk equity gain, core earnings did not remain trapped in accruals. These percentages will not be stable every quarter because receivables, inventory, payables, and taxes create volatility, but they provide more direct evidence of current earnings quality than GAAP net income.
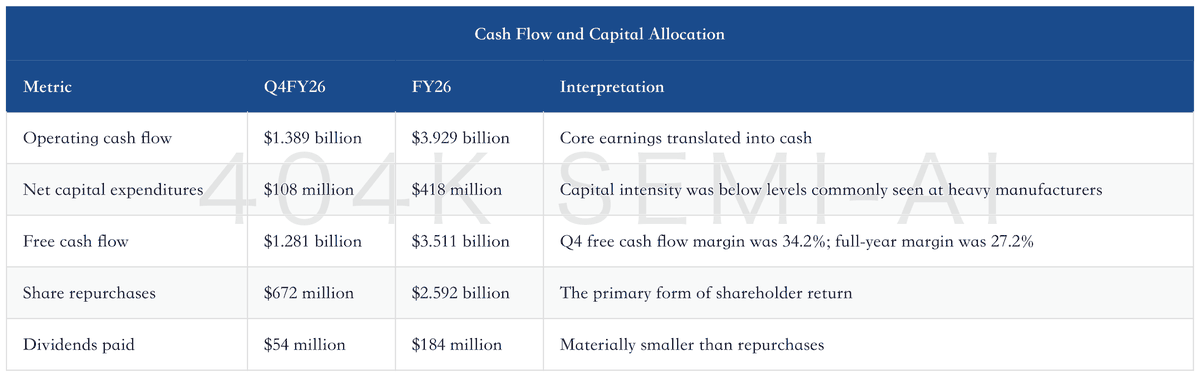
Full-year repurchases and dividends totaled $2.776 billion, or about 79% of free cash flow. The company also paid $1.22 billion in Q4 to settle convertible notes, resulting in full-year net financing cash outflow of $4.032 billion. The decline in cash from $2.114 billion to $1.579 billion did not signal weaker cash generation; it reflected the use of free cash flow for buybacks, dividends, and deleveraging.
The balance-sheet change was more direct. Current debt declined from $2.226 billion to $1.052 billion, long-term debt fell from $2.485 billion to zero, and total interest-bearing debt decreased by $3.659 billion. The company moved from net debt of about $2.597 billion at the prior year-end to net cash of approximately $527 million at the current year-end, an improvement of roughly $3.124 billion in its net financial position. Deleveraging reduced the interest burden and preserved capacity for future repurchases, dividends, or technology investment.
Working capital still warrants attention. Accounts receivable increased 36%, from $1.486 billion to $2.026 billion; inventory rose 17%, from $1.291 billion to $1.511 billion; and accounts payable increased from $1.266 billion to $1.774 billion. Receivables growth was broadly in line with full-year revenue growth, and inventory grew more slowly, so the overall working-capital pattern has not yet shown any obvious sign of losing control. Yet with revenue expanding quickly and customer concentration elevated, the timing of collections and the cash-flow benefit from higher payables should not be overlooked.
The board declared a cash dividend of $0.15 per share, with a record date of September 8, 2026, and a payment date of September 17. At the current level of cash flow, the dividend is not the primary constraint on capital allocation; repurchases and debt actions are the larger uses of cash. Investors should watch whether Western Digital maintains a high repurchase rate now that it has moved into a net cash position, and whether the prices paid create value per share.
7. 40 TB ePMR Shipments Have Begun: Validate the Technology Through Economics, Not the Headline
Western Digital disclosed that it has begun shipping its next-generation ePMR products with capacities of up to 40 TB per drive. The significance of the milestone is that more capacity per drive allows customers to store the same data on fewer HDDs, potentially improving rack-space, power, and operating efficiency. For the supplier, it could also increase the mix and per-drive value of high-capacity nearline products.
The two materials, however, do not disclose 40 TB shipment volumes, the scope of customer qualifications, yields, per-drive pricing, or margins, so "started shipping" cannot be equated with a volume ramp. Higher capacity also changes how performance should be observed: EB shipments can rise even if HDD unit volumes do not, and revenue/EB could decline if capacity per drive grows faster than pricing. The economics of the new product must therefore be judged through nearline EB, the revenue/EB proxy, gross margin, and free cash flow together—not capacity specifications alone.
The positive evidence so far is that initial 40 TB shipments coincided with a 54.4% gross margin and 209 EB of nearline shipments, providing no sign that the product introduction weighed on overall profitability. The next real test is whether Q1 revenue reaches roughly $4.1 billion, gross margin reaches 55%–56%, and EB shipments continue to grow. If the ramp proceeds smoothly, capacity growth and product mix should continue to support profit; if qualification or yields are delayed, one of EB growth, revenue/EB, or gross margin will typically be the first indicator to fall behind.
8. The Next Two Quarters: What Would Prove That 55.5% Is Not a Cyclical Peak?
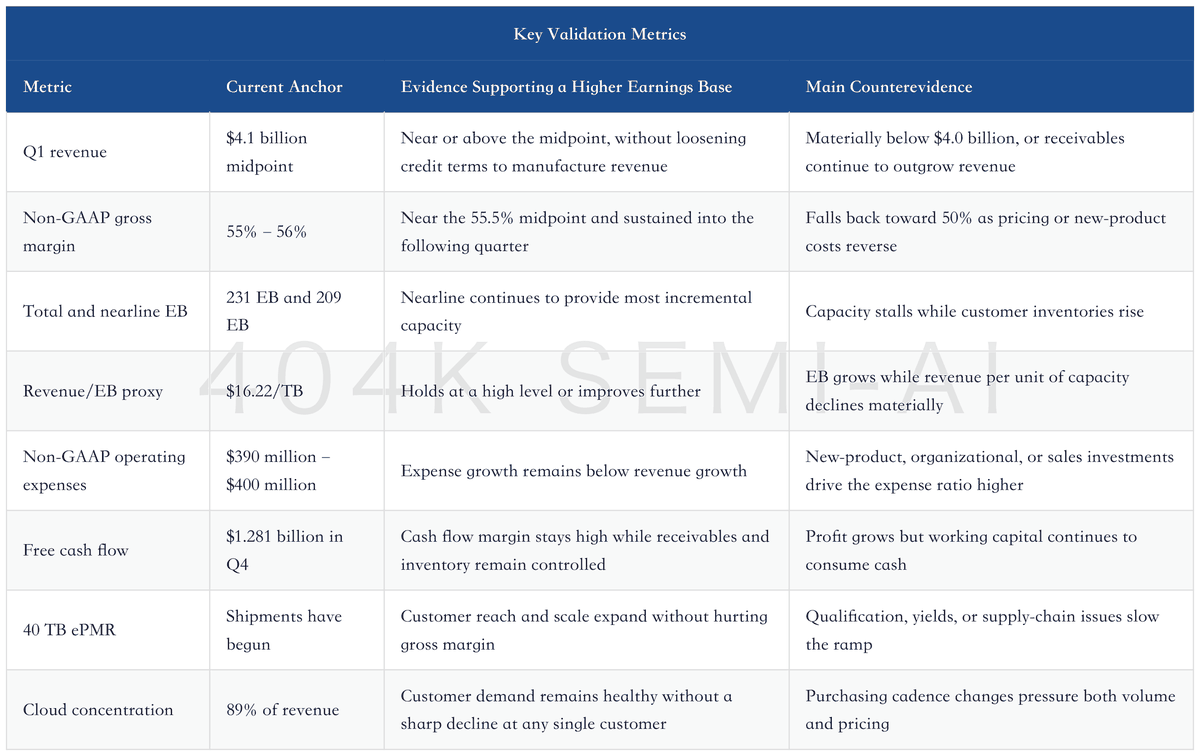
In the base case, Q1 revenue and gross margin broadly reach their midpoints, the 40 TB product ramps gradually, and free cash flow continues to cover repurchases and dividends, while gross margin enters a plateau near 55%. In the upside case, nearline EB, revenue/EB, and gross margin continue to rise together and operating margin moves above 46%, confirming that supply-demand conditions and product mix have jointly established a higher earnings base. In the downside case, cloud customers slow purchases, the revenue-per-capacity proxy declines, new-product costs rise, and gross margin turns down before revenue does.
The two official documents do not provide a share price, price target, or long-term EPS forecast. They are therefore sufficient to assess earnings quality, but not to determine whether valuation is attractive on their own. A disciplined valuation should begin with non-GAAP earnings and free cash flow from continuing operations, then incorporate separately verified share-price, net-cash, and medium- to long-term capacity assumptions. Quarterly GAAP EPS of $8.21 cannot simply be annualized.
9. Conclusion: A 55.5% Gross Margin and 34% Free Cash Flow Margin Are the New Anchors
Western Digital's Q4 results provide a complete operating evidence chain: total EB rose about 22% year over year, nearline EB grew about 23%, revenue increased 44%, the revenue/EB proxy improved about 18%, non-GAAP gross margin expanded 13.1 percentage points, operating income grew 126%, and free cash flow rose 90%. Volume, capacity economics, expense leverage, and cash conversion improved together, demonstrating that the profit increase was not the product of an accounting adjustment alone.
GAAP net income was nevertheless inflated materially by the Sandisk equity gain. The $2.05 billion fair-value gain lifted GAAP EPS to $8.21, versus $3.56 on the core operating measure. Even after stripping out the gain, the quarter remained very strong; the reason simply changes from "net income surged" to "cloud nearline HDDs delivered both volume and value growth, margins stepped higher, and cash conversion was robust."
Western Digital has therefore entered the validation phase for a higher earnings base. Q1 revenue of $4.1 billion, gross margin of 55.5%, and EPS of $4.00 are the outcome anchors. If nearline EB, revenue/EB, gross margin, and free cash flow continue to move together, a gross margin above 55% can become the new plateau. If pricing, yields, or cash flow fall behind, Q4 will look more like the top of the cycle.
Related Reading
Microsoft FY2026 Q4 Deep Dive: Azure Growth Rises to 43%, Cloud Gross Margin Falls to 65%
Kioxia Deep-Dive Update: 75% Margin, ¥800 Billion Buyback, and ¥155,000 Valuation Anchor
Arm FY2027 Q1 Deep Dive: Data Center Royalties More Than Double, AGI CPU Demand Exceeds $2 Billion