
Victory Giant Technology Deep-Dive Update: How Rubin High-Layer Board Delays, New TPU Orders, and CNY20bn Capex Validate Effective AI PCB Capacity
目录
Too Long; Didn’t Read
1. What BofA Really Changed This Time: Near-Term Cut, No Retreat on the Long Term
2. Why Rubin High-Layer Boards Matter: Rising Content and Unfinalized Specifications at the Same Time
3. Why New Customers Matter: Victory Giant Cannot Fill RMB20bn of Capex on a Single Platform Alone
4. How to Read the Financial Model: 2026 Is Slower; 2027 Is the Real Test
5. How to Break Down Valuation: RMB455 Is Not a Dream, Nor Is It a Floor
VI. What to Watch Over the Next Four Quarters: Six Variables Matter More Than Saying “AI Cycle”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core of this Victory Giant Technology update is not whether AI PCB demand exists. It is whether, after a slow 2Q ramp, Rubin high-layer boards, new TPU orders, new ASIC/optical-module customers, and CNY20bn of capex can together prove one point: the new capacity is not ordinary expansion, but effective capacity locked in by platform orders.
Too Long; Didn’t Read
The debate on Victory Giant shifts to 3Q. BofA cut 2026E EPS from CNY9.08 to CNY8.65, mainly reflecting a slower-than-expected 2Q26 ramp for the Vera Rubin platform, while maintaining its CNY455 target price and 30x 2027E PE. The real issue is not the near-term downgrade itself, but whether VR200, TPU high-layer board orders, and new customers can reaccelerate revenue and profit from 3Q.
Rubin high-layer boards are the biggest variable. BofA estimates VR200 PCB content at around 3x GB200/GB300. The Rubin Ultra backplane may use 78-layer or 100-layer-plus HLC, with materials still being tested from M9+Q Glass to M10+HVLP5. Victory Giant has prepared capacity in high-multilayer, HDI, HLC, and mSAP, but backplane specifications have not been finalized, meaning order upside and delay risk coexist.
New customers determine whether risk can be diversified. BofA notes that U.S. ASIC customers, domestic customers, and optical-module customers should help Victory Giant hedge uncertainty around the Rubin Ultra backplane. For Victory Giant, the best case is not a single bet on Nvidia platforms, but GPU, TPU, ASIC, UBB, switch, and optical-module PCBs all filling capacity, allowing CNY20bn-level capex to map to multiple customers and platforms.
2026 is a cash-flow stress test. BofA forecasts Victory Giant’s 2026E revenue at CNY33.425bn, net profit at CNY8.267bn, capex at CNY20bn, and free cash flow at -CNY10.225bn. In 2027E, net profit rises to CNY14.844bn and free cash flow turns positive to CNY6.253bn. What Victory Giant needs to prove is not whether it can grow, but whether heavy investment in 2026 can become cash flow in 2027.
Gross margin matters more than revenue. BofA’s 2026-2028E gross-margin forecasts are 35.2%, 37.4%, and 39.2%, clearly below consensus but still rising. This conservative framing gives a clean validation line: if a rising mix of high-end AI boards cannot offset pressure from FR-4, CCL, depreciation, and yield, Victory Giant will be treated as a cyclical PCB manufacturer; if gross margin recovers with platform upgrades, valuation still has room to move higher.
The conclusion here is conditionally bullish. Victory Giant is no longer a generic PCB expansion story; it is an effective-capacity asset for AI server interconnects. But the CNY455 target price is not an unconditional end-state. Over the next four quarters, investors need to track 3Q sequential acceleration, TPU/ASIC new-customer orders, Rubin Ultra backplane specifications, gross margin, operating cash flow, and the pace of capex transfer into fixed assets. If any two variables fall behind, Victory Giant’s valuation identity needs to be revised down.
1. What BofA Really Changed This Time: Near-Term Cut, No Retreat on the Long Term
The most valuable new information in this Victory Giant Technology update is that the bull-bear debate has finally moved from “is AI PCB in a strong upcycle?” to “how does that upcycle pass through a slow 2Q ramp and capacity-expansion pressure?” BofA did not reject Victory Giant’s long-term logic, but it cut 2026 earnings by 6%, mainly because the Vera Rubin platform ramp is slower than previously assumed.
This is different from the Victory Giant narrative of the past several months. Previously, the market preferred to discuss “AI PCB,” “H-share discount,” “target-price upgrades,” and “scarce effective capacity.” None of that is wrong, but those points answer the direction question. This BofA report addresses the timing question. The direction is continued upside in AI PCB content. The timing is a potentially slow 2Q26, followed by reacceleration from 3Q26.
Victory Giant Technology Deep Dive: AI PCB Enters the Effective-Capacity Era, and How Victory Giant Becomes a Server Delivery Asset Rather Than Just a Board Maker
The three actions in the report should be read separately. First, BofA cut 2026E EPS from CNY9.08 to CNY8.65, reflecting the slow 2Q ramp. Second, 2027E EPS was essentially maintained at CNY15.10, implying the long-term profit curve has not been impaired. Third, the target price was kept at CNY455, with the valuation anchor still at 30x 2027E PE.
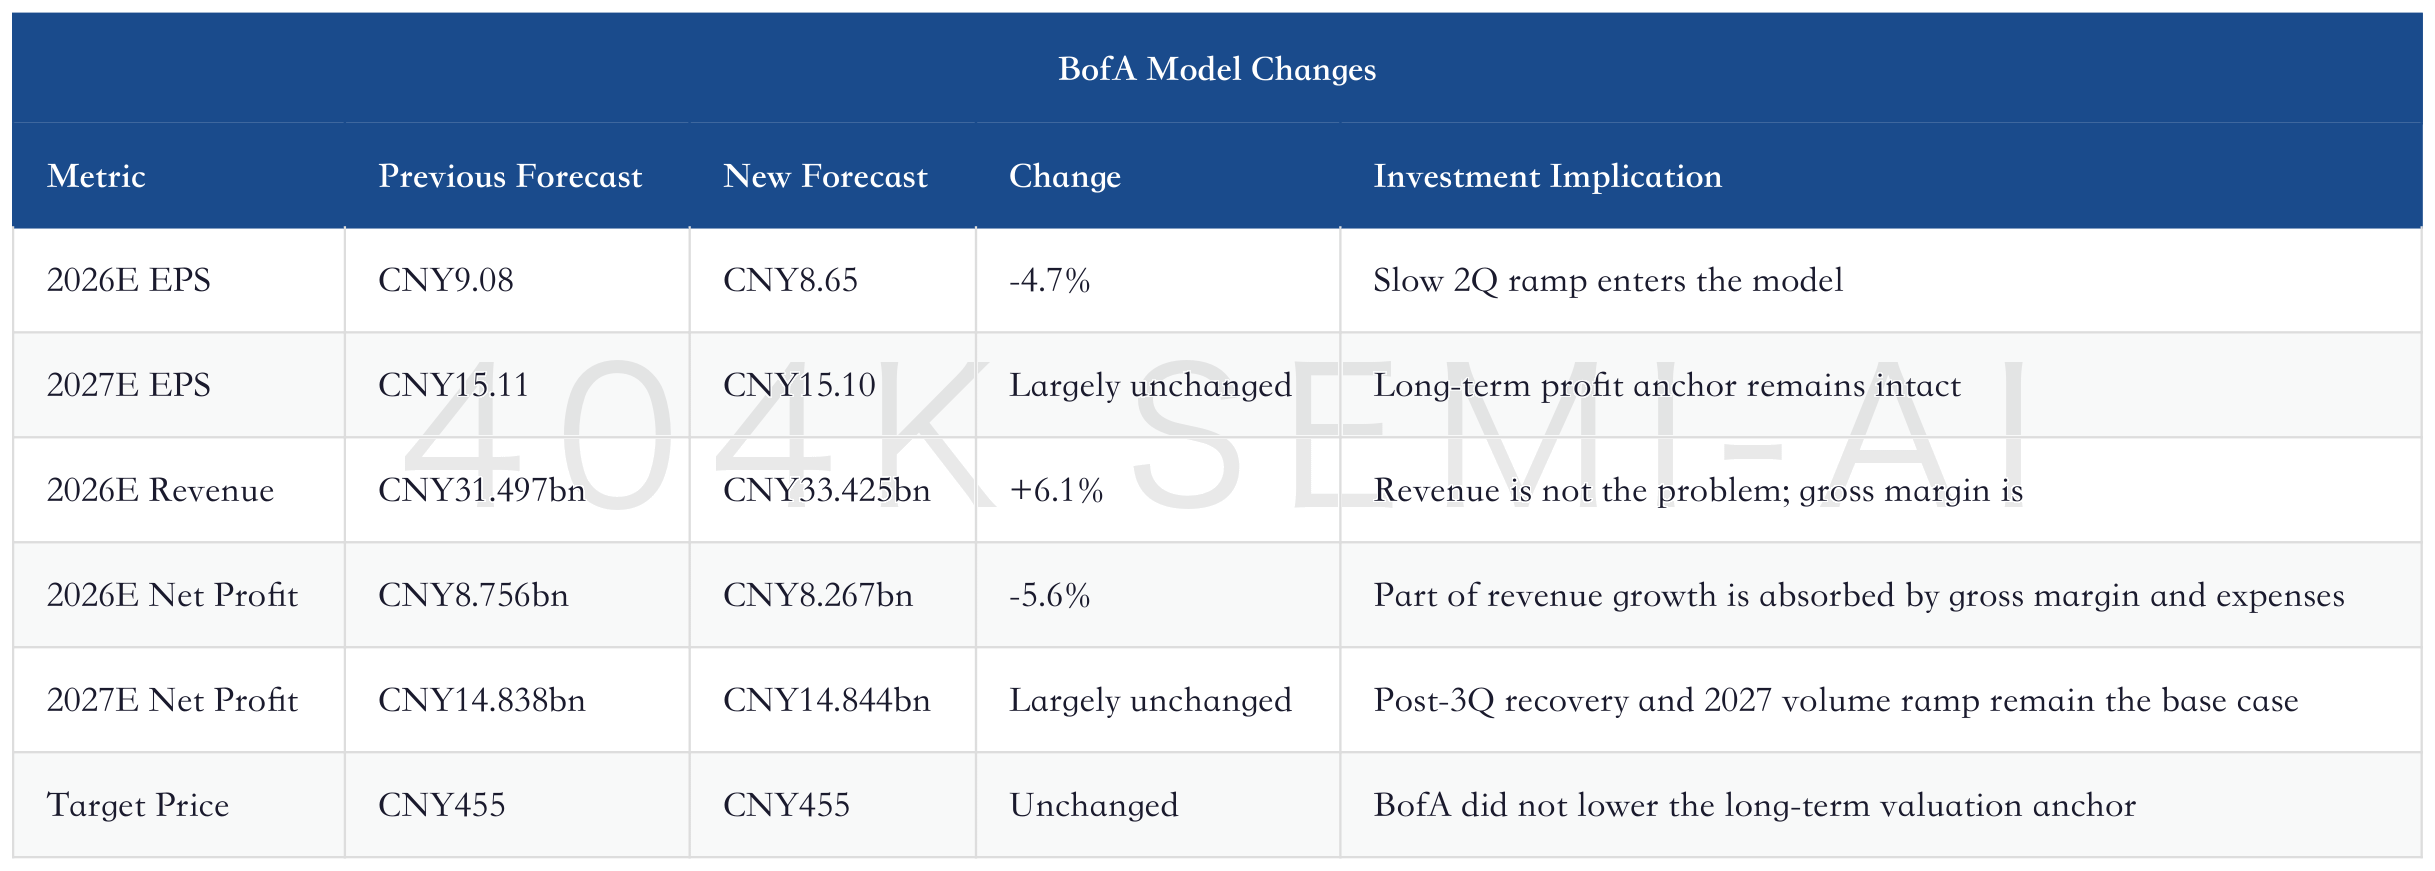
This table shows that Victory Giant is not in a “broken thesis” situation. It has entered a harder validation phase. In the first phase, the market only looked at incremental AI PCB demand. In the second phase, it looked at capacity expansion and customer qualification. In the current third phase, the question is whether expanded capacity can be converted, quarter by quarter, into revenue, gross margin, and cash flow.
Victory Giant Technology Deep-Dive Update: H-Share Discount, HKD600 Target Price, and Repricing of Effective AI PCB Capacity
The core view on Victory Giant can be compressed into one sentence: a slow 2Q is not fatal; failure to accelerate in 3Q would be. BofA has already built the slow 2Q ramp into its model, so the market will now focus directly on 3Q. As long as 3Q revenue, net profit, and gross margin all recover sequentially, 2Q looks more like platform-transition noise. If 3Q is still slow, Victory Giant’s valuation will retreat from “platform supplier” back to “high-cycle manufacturing stock.”
2. Why Rubin High-Layer Boards Matter: Rising Content and Unfinalized Specifications at the Same Time
Rubin is the most important word in this Victory Giant deep-dive update. BofA breaks down PCB content across different Nvidia platforms: around USD2,500 for H100, rising to USD20,000-30,000 for GB200/GB300, further to USD60,000-80,000 for VR200, and potentially above USD100,000 for Rubin Ultra.
What these numbers really show is content migration, not simple price increases. After AI racks upgrade, PCB upside no longer comes only from a single OAM or UBB board, but from simultaneous upgrades across the compute tray, switch tray, midplane, backplane, CPU board, and other locations. Layer count, materials, line width and spacing, back drilling, lamination, thermal reliability, and signal integrity all become more difficult.
Revaluing Rubin Racks: GPU Share Falls to 51%, AI Hardware Value Migrates Toward Memory, PCB, Power, and Liquid Cooling; Who Captures the New AI Hardware Spend
BofA’s description of the Rubin Ultra backplane is critical: it may be 78 layers, or it may exceed 100 layers; materials may be M9+Q Glass, or may move further to M10+HVLP5. There is no need to debate the final specification here, because the investment implication is already clear: the next-generation platform pushes PCB from “high-end board” into the key bottleneck of system interconnect.
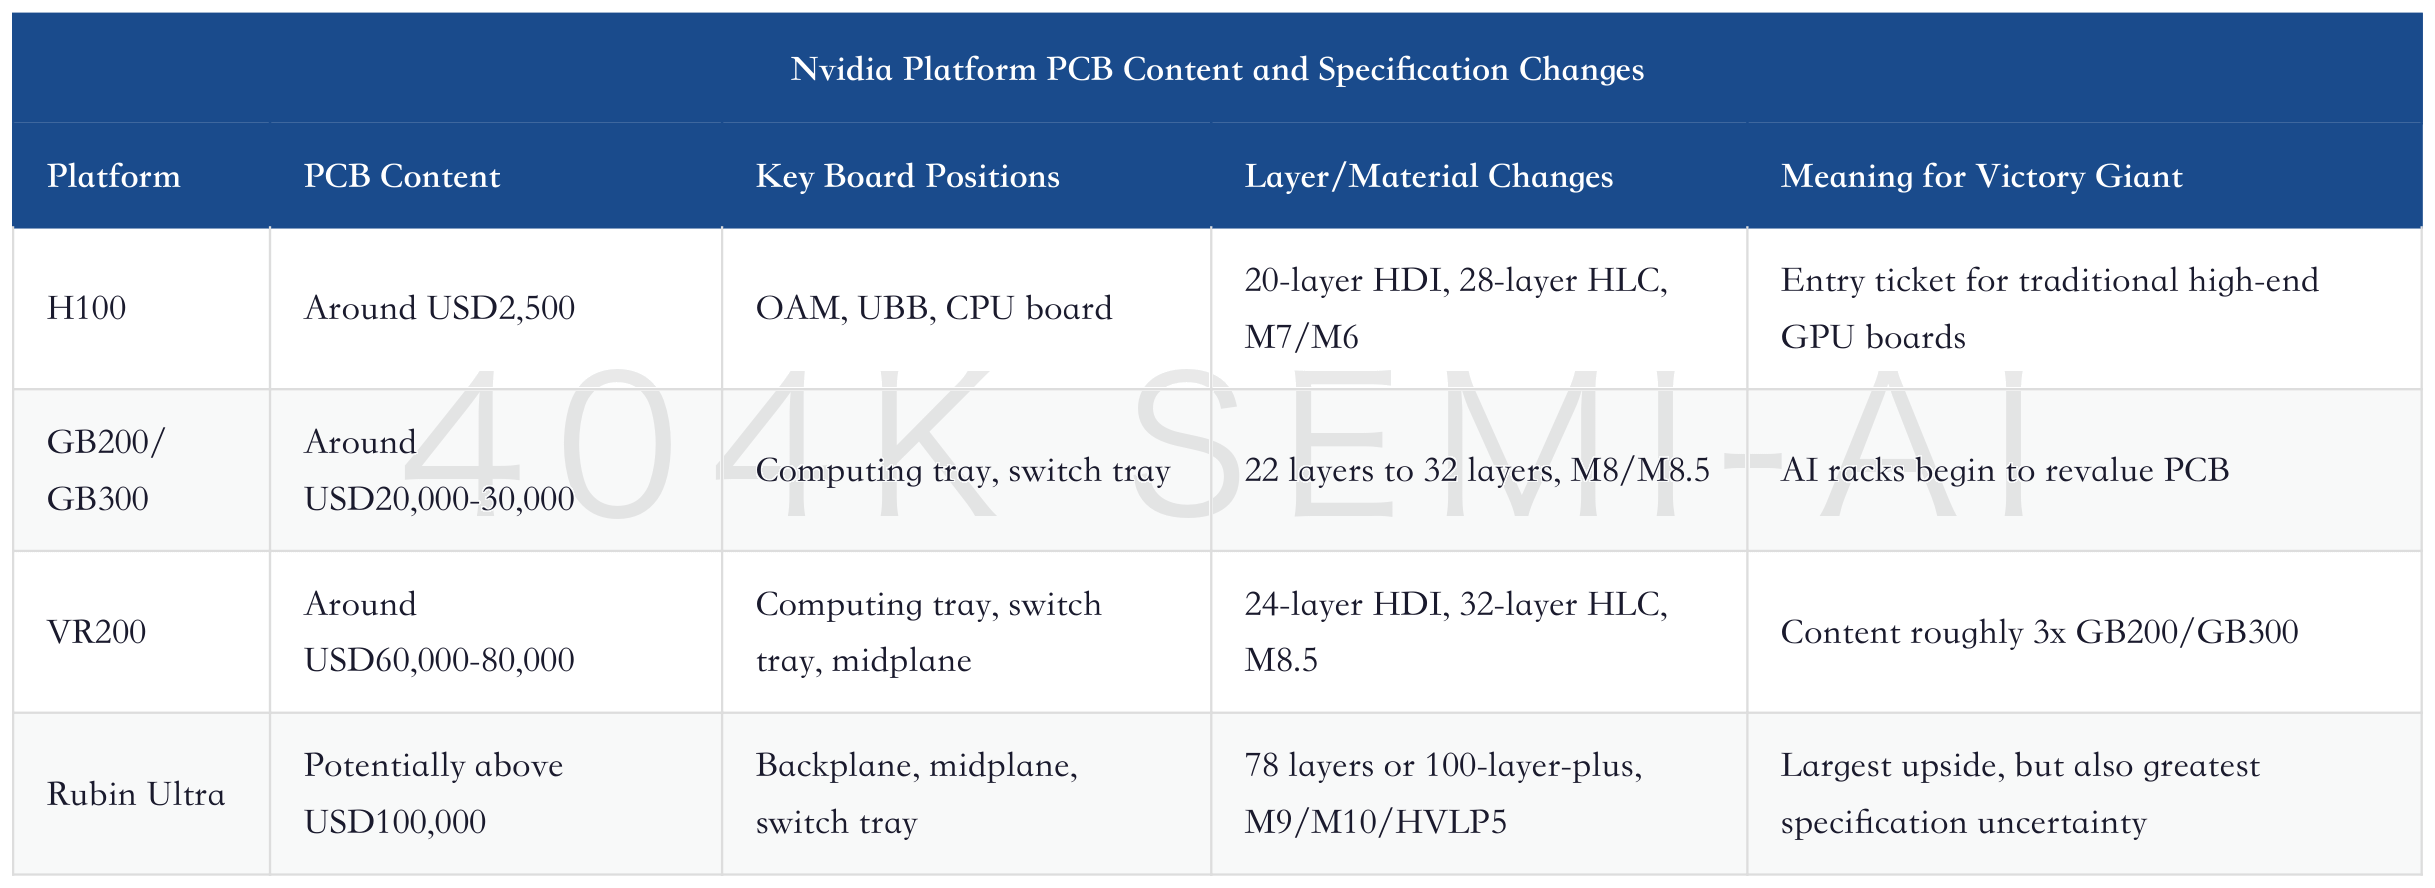
Victory Giant’s opportunity lies here. The company’s 2025 annual report has already disclosed technical capabilities in 100-layer-plus high-multilayer PCBs, 10-step 30-layer HDI, and 16-layer any-layer interconnect HDI, while advancing R&D; certification for 14-step 36-layer HDI. It is also among the first companies globally to achieve mass production of 6-step 24-layer HDI. These technical qualifications align with BofA’s description of Rubin high-layer boards.
But the risk is here as well. The higher the specifications, the longer customer testing takes, and the more likely platform mass production is to encounter timing gaps. BofA explicitly attributes the slow 2Q ramp to a delayed Vera Rubin platform ramp-up: compute boards had only small-batch trial production in April, with formal ramp beginning only in June. For Victory Giant, more difficult specifications make barriers easier to build; but before those barriers are established, they also create delays.
So Rubin is not a one-way positive for Victory Giant. It is a simultaneous increase in content and uncertainty. If VR200 compute boards and higher-layer-count TPU boards ramp smoothly from 3Q, the market will be willing to tolerate a slow 2Q. If Rubin Ultra backplane testing keeps stretching out, the market will re-discount Victory Giant’s 2027 profit anchor.
3. Why New Customers Matter: Victory Giant Cannot Fill RMB20bn of Capex on a Single Platform Alone
The second incremental point in BofA’s report is that it makes customer diversification more explicit. The report notes that Victory Giant can manage potential Rubin Ultra backplane delay risk through US ASIC customers, domestic customers, and optical module customers. This is more specific than simply saying “customer diversification.”
Victory Giant’s biggest structural advantage today is its high-end board capability, while its biggest structural risk is heavy capex. BofA expects the company’s 2026E capex to reach RMB20bn, with RMB10bn each in 2027E and 2028E. This level of investment means Victory Giant cannot rely on one platform, one customer, or one board position to fill capacity.
AI PCB Phase 6: Expansion Announcements Do Not Equal Effective Capacity — Full Read-through of 2026 Equipment Orders for Han’s CNC, Victory Giant Technology, and Shennan Circuits
The truly healthy path is for multiple demand pools to absorb new high-end capacity together. GPU platforms provide the highest-spec validation; TPU and ASIC bring customer diversification from cloud vendors’ in-house chips; optical module PCBs and switch boards provide spillover from the networking side; UBBs and midplanes add rack-level interconnect demand. Only if these demand sources fill capacity in parallel does Victory Giant’s RMB20bn capex avoid becoming a single-platform bet.
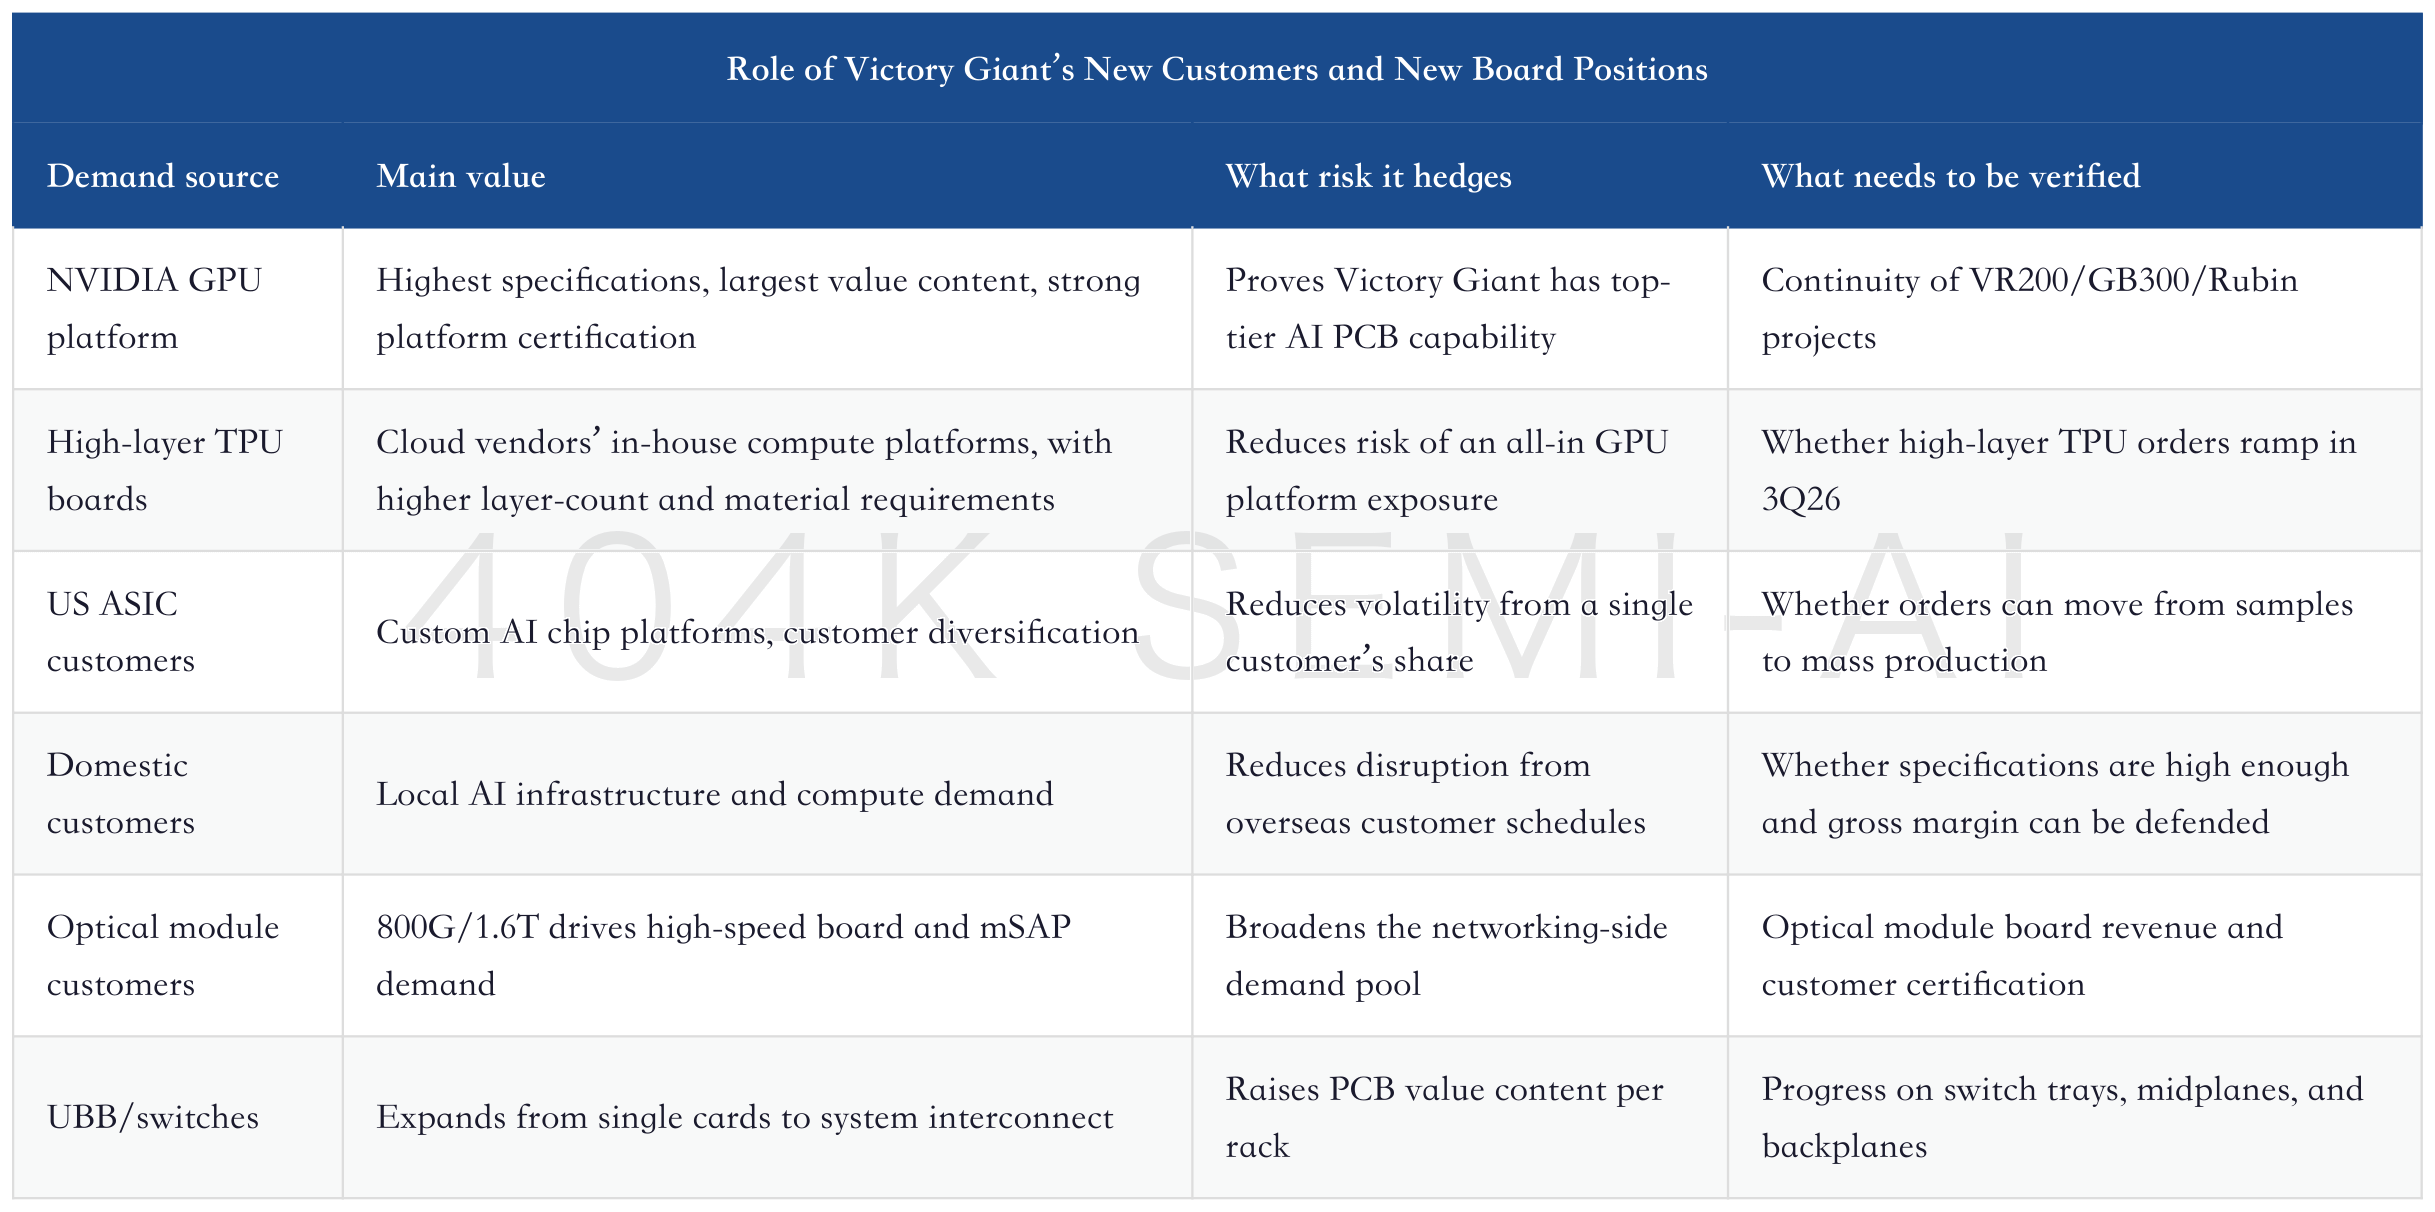
This is also why research on Victory Giant cannot stop at calling it an “AI PCB leader.” Being a leader does not mean there is no risk. What high-end manufacturers fear most is not a lack of orders, but a mismatch between order cadence and capacity cadence. Equipment, plants, personnel, materials, and yield are all invested ahead of time. If a customer project is delayed by one to two quarters, the income statement and cash flow will immediately come under pressure.
AI PCB Phase 8: Customer Lock-in Is the Real Moat — Full Read-through of 2026 Platform Certification for Victory Giant, Shennan Circuits, WUS Printed Circuit, and Guanghe Technology
Therefore, the significance of new customers for Victory Giant is not that they make the story sound better, but that they make RMB20bn of capex more explainable. If new capacity can be filled jointly by GPU, TPU, ASIC, optical modules, and switches, Victory Giant moves closer to being an “AI interconnect delivery asset” rather than merely a “high-beta board maker.” If new customers are slow to enter mass production, capex will first show up as depreciation, inventory, and cash-flow pressure.
4. How to Read the Financial Model: 2026 Is Slower; 2027 Is the Real Test
BofA’s model provides a very clear cadence. It forecasts 2026E revenue of RMB33.425bn and net profit of RMB8.267bn, 2027E revenue of RMB55.001bn and net profit of RMB14.844bn, and 2028E revenue of RMB77.990bn and net profit of RMB22.718bn. In other words, BofA is still betting that Victory Giant’s net profit will sustain a high compound growth rate from 2026 to 2028.
But the difference between this model and market consensus is also important. BofA’s 2026-2028E net profit forecasts are 9.9%, 7.2%, and 3.5% below consensus, while its gross margin forecasts are 4.8, 4.0, and 3.2 percentage points below consensus. This is not pessimism; it is a more conservative recognition of pressure from materials, depreciation, yield, and traditional business costs.
