
目录
Table of Contents
The 2Q Report Card: Growth Intact, with the Expectation Gap in Revenue and Gross Margin
Why Profit Looks Better Than Gross Margin: Separating Non-Operating Income from Operating Quality
How Next-Gen GPU and ASIC Raise PCB Dollar Content
Inventory and capacity have been front-loaded—what gates remain before revenue is realized
Cash flow and capacity expansion: the other side of growth preparation is capital lock-up
What the RMB 550 target price depends on, and which numbers to watch over the next two quarters
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Second-quarter revenue and gross margin came in below expectations. Next-generation GPU and ASIC orders, raw-material and work-in-process inventory build, and the ramp of new domestic capacity still provide verifiable support for a second-half acceleration.
Table of Contents
The 2Q Report Card: Growth Intact, with the Expectation Gap in Revenue and Gross Margin
Why Profit Looks Better Than Gross Margin: Separating Non-Operating Income from Operating Quality
How Next-Gen GPU and ASIC Raise PCB Dollar Content
Inventory and Capacity Have Been Front-Loaded; What Gates Remain Before Revenue Is Recognized
Cash Flow and Expansion: The Other Side of Growth Preparation Is Capital Lock-Up
What the RMB 550 Target Price Depends On, and Which Numbers to Watch Over the Next Two Quarters
The 2Q Report Card: Growth Intact, with the Expectation Gap in Revenue and Gross Margin
Victory Giant Technology continued to grow in the second quarter; the market's disappointment stemmed from growth pace and unit profitability coming in below what had been priced in. Goldman Sachs' August 28 report shows 2Q26 revenue of RMB 6.11 billion, up 29% year over year and 11% quarter over quarter. That figure was 16% below Goldman's estimate and 6% below consensus. Gross margin was 32.1%, down 2.4 percentage points from 1Q26 and down 6.7 percentage points from the prior-year period, also below Goldman's 35.6% forecast and the 36.8% consensus.
Net profit held up better. 2Q26 net profit was RMB 1.568 billion, up 28% year over year and 22% quarter over quarter, 4% above consensus but still 11% below Goldman's estimate. Weak revenue, weak gross margin, and near-consensus net profit together indicate that the expense ratio and non-operating income cushioned pressure at the production level. They can support current-period profit, but they cannot substitute for order conversion, yield improvement, and utilization ramp.
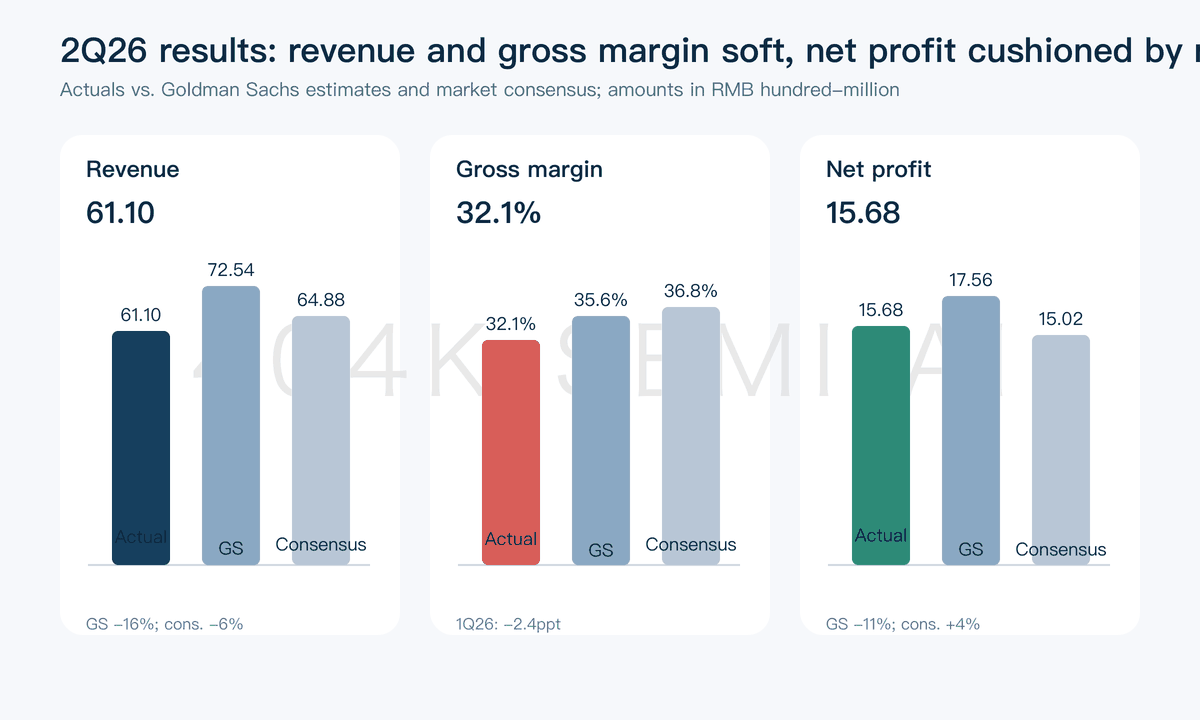
This report card updates the prior thesis to "revenue direction confirmed, gross-margin recovery slower than expected." Earlier coverage of Victory Giant Technology framed 2Q26 as a shallow-ramp period for the new platform, with a re-acceleration expected in 3Q26 and key watch items being revenue slope, gross margin, new customers, inventory, and cash flow. Revenue did grow 11% quarter over quarter, indicating demand has not stalled; the continued decline in gross margin to 32.1% indicates that headcount, depreciation, and process ramp have already entered the cost base before new capacity has entered the revenue line.
Goldman attributes the revenue shortfall mainly to the manufacturing difficulty of AI-server PCBs. Higher layer counts, higher-order HDI, and stricter signal-integrity and material requirements mean new equipment takes longer to reach stable yields. The company's explanation on the August 27 earnings call was more granular: the second-quarter gross-margin decline was driven mainly by headcount and depreciation, with raw materials having a smaller impact. First-half headcount rose about 30% year over year, with training and staffing running ahead of orders; after new plants were capitalized, depreciation also entered costs first. The two explanations differ in emphasis. Goldman stresses materials and ramp; the company stresses headcount and depreciation. The operating fact they both point to is that capacity costs have already been incurred while revenue is still ramping.
The real test of the second quarter therefore falls on 3Q and 4Q. If headcount, depreciation, and inventory build represent front-loaded volume preparation, subsequent revenue growth will dilute fixed costs and gross margin should recover as utilization rises. If order delivery is delayed further, the front-loaded costs will remain on the income statement, and inventory and depreciation pressure will increase. The second quarter alone cannot resolve this judgment; revenue, gross margin, and inventory turnover must all improve simultaneously over the next two quarters.
Why Profit Looks Better Than Gross Margin: Separating Non-Operating Income from Operating Quality
The interim report shows Victory Giant Technology's core business still growing, while the income statement also contains a sizable non-recurring cushion. The company's unaudited 2026 interim report discloses H1 revenue of RMB 11.629 billion, up 28.77% year over year; net profit attributable to shareholders of RMB 2.857 billion, up 33.30%; and non-GAAP net profit attributable to shareholders of RMB 2.418 billion, up 12.50%. The 20.8-percentage-point gap between attributable and non-GAAP growth is already enough to affect judgments about earnings quality.
Cost-side pressure is clearer. H1 operating costs rose 34.83% year over year, faster than revenue, implying a consolidated gross margin of 33.22%, down 3.00 percentage points from 36.22% in the prior-year period. Main-business gross margin fell from 33.05% to 28.58%, a decline of 4.47 percentage points; parent-company gross margin also fell by about 3.23 percentage points. The simultaneous decline across all three measures indicates broad-based pressure on the core manufacturing business that consolidation-scope effects cannot explain away.
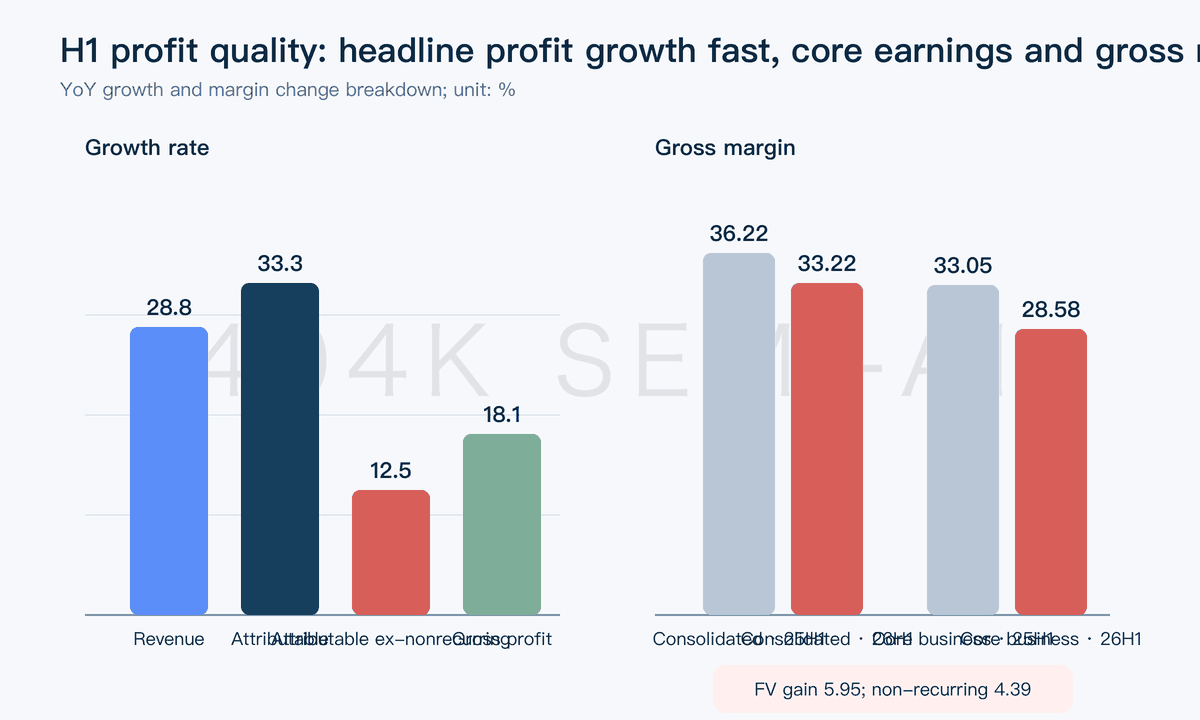
Reported net profit was boosted by financial-asset gains and dragged by FX losses. H1 fair-value gains were RMB 595 million, mainly from trading financial assets; total non-recurring items were RMB 439 million, about 15.4% of attributable net profit. Finance costs in the same period were RMB 297 million, up nearly 7x year over year, including FX losses of about RMB 222 million. Victory Giant Technology has high export revenue while material purchases are settled more in RMB, which tends to create large foreign-currency receivables and cash exposures. The company uses forward FX contracts and foreign-currency borrowings for partial hedging but does not apply hedge accounting, so quarterly profit can still swing.
R&D; spending also needs to be viewed within the expansion cadence. H1 R&D; expense was RMB 359 million, up 1.81% year over year, with the R&D; expense ratio falling from about 3.91% to 3.09%. The company is simultaneously advancing processes such as 100+ layer high-multilayer boards, 30-layer 10-order and 36-layer 14-order HDI, vertical power-delivery embedded capacitance, and COWOP. The decline in the R&D; ratio may reflect revenue growing faster than expense input, or it may reflect resources shifting more toward equipment, manufacturing engineering, and volume ramp. This should be assessed in conjunction with high-end product revenue, yields, and R&D; headcount changes; the expense ratio alone is insufficient to infer weakening technology investment.
Evaluating profit quality requires looking at three sets of numbers simultaneously. The first set is gross margin and non-GAAP net margin, which represent core operating efficiency; the second is fair-value gains, FX, and finance costs, which determine quarterly net-profit volatility; the third is operating cash flow and working capital, which test whether profit converts into cash. The resilience of 2Q26 net profit deserves recognition, but the current financials do not yet prove that unit profitability has bottomed.
