
Vertiv Q2 Deep Dive: Revenue Timing Mismatch Does Not Derail Earnings Upgrades; Second-Half Delivery Is the Real Test
目录
Key Takeaways
I. Revenue Did Not Beat Across the Board, but Earnings Delivered a Stronger Result
II. Margin Expansion Is Genuine, but the EPS Surprise Was Helped by the Tax Rate
III. Free Cash Flow of $925.3 Million Was Strong, but Its Sources Were More Complex Than the Headline Figure Suggests
IV. Regional Divergence Persists: Americas and Asia-Pacific Deliver, While EMEA Has Yet to Truly Recover
V. The Full-Year Upgrade Is Aggressive and Shifts the Burden of Proof to the Second Half
VI. 800VDC and Liquid Cooling Increase Value per Megawatt, but Commercialization Evidence Remains at an Early Stage
VII. Acquisitions Expand the Capability Perimeter, While Net Cash Provides Room for Further Investment
VIII. Six Verifiable Signals to Watch Over the Next Two Quarters
Conclusion
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Vertiv’s Q2 2026 revenue was slightly below its original guidance, but margins, adjusted operating profit, and full-year guidance were all raised. The central issue has shifted from demand strength to delivery execution: in the second half, particularly Q4, the company must simultaneously deliver higher revenue, higher margins, and acceptance of more complex projects.
Key Takeaways
Q2 revenue was $3.2743 billion, up 24.1% year over year but 2.3% below the midpoint of original guidance; adjusted operating profit was $738.4 million, up 50.9% year over year and 4.0% above the midpoint of original guidance, indicating that earnings quality was materially stronger than revenue execution.
Adjusted operating margin reached 22.6%, up 4.1 percentage points year over year. Operating execution, productivity, and favorable price-cost dynamics made genuine contributions; however, the adjusted effective tax rate was 20%, below the 23% originally guided, and the tax benefit also amplified the EPS surprise.
Adjusted free cash flow was $925.3 million, with conversion exceeding 150%, but deferred revenue increased by $1.1715 billion during the quarter. Customer prepayments were an important component of the cash-flow surge. The full-year conversion target is approximately 95%, so the Q2 level should not be annualized directly.
Organic revenue in the Americas and Asia-Pacific grew 21.1% and 25.7%, respectively, making them the principal growth engines; organic revenue in Europe, the Middle East, and Africa still declined 2.4%. To achieve low-single-digit organic growth in the region for the full year, the company must accelerate materially in the second half.
The midpoint of full-year revenue guidance was raised to $14.0 billion, the midpoint of adjusted operating profit guidance to $3.325 billion, and the midpoint of adjusted EPS guidance to $6.70. This implies Q4 revenue of $4.325 billion and an adjusted operating margin of 25.8%, making delivery, project acceptance, and the easing of supply-chain congestion the central tests.
800VDC, closed-loop liquid cooling, and recent acquisitions have completed the company’s capabilities from chip-side cold plates to outdoor heat rejection. However, current disclosures relate to technology validation and project case studies, not quantifiable order or revenue contributions. The company also did not disclose quarterly orders or ending backlog.
I. Revenue Did Not Beat Across the Board, but Earnings Delivered a Stronger Result
This article was completed at approximately 18:30 Beijing time on July 29, 2026, after the official earnings release and presentation materials were published but before the earnings call began. The U.S. Securities and Exchange Commission has received the related 8-K, with EX991 serving as the earnings release; the quarter’s 10-Q has not yet been filed. The analysis below therefore covers only publicly available written materials and does not treat earnings-call Q&A; that has yet to occur or financial-statement footnotes that have yet to be disclosed as evidence.
Vertiv reported Q2 revenue of $3.2743 billion, up 24.1% year over year. Organic growth was 17.8%, acquisitions contributed approximately 5 percentage points, and foreign exchange contributed approximately 1 percentage point. Growth remained rapid, but revenue was $75.70 million below the original guidance midpoint of $3.35 billion. The company attributed the shortfall to temporary supply-chain congestion, execution of multi-stage projects, and slight shifts in recognition timing associated with large, complex deployments.
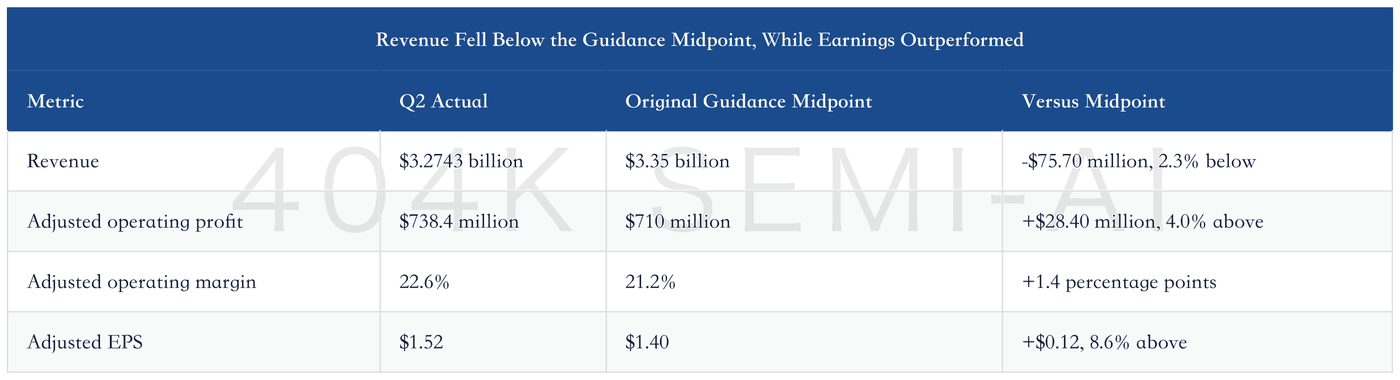
Determining whether the revenue shortfall was “delayed” or “lost” requires more than management’s explanation; investors should assess whether subsequent guidance contains verifiable commitments. Vertiv not only raised the midpoint of full-year revenue guidance from $13.75 billion to $14.0 billion but also provided Q3 and Q4 midpoints of $3.75 billion and $4.325 billion, respectively. This means the company did not use the Q2 timing issue to reduce its full-year demand outlook, instead incorporating the delayed deliveries into higher second-half targets.
This evidence supports the revenue-timing explanation but does not yet prove that the issue has been resolved. The larger the data-center infrastructure project, the more complex the coordination among power, cooling, racks, and services, making customer-site readiness, equipment arrival, staged acceptance, and revenue recognition more likely to create quarterly volatility. The Q2 shortfall of $75.70 million was not large. The real questions are whether Q3 can recover to the company’s guided 35% organic growth and whether Q4 can absorb a higher concentration of projects. If supply-chain congestion has not yet eased in Q3, the “timing difference” will shift from one quarter’s noise to an execution bottleneck.
II. Margin Expansion Is Genuine, but the EPS Surprise Was Helped by the Tax Rate
Q2 GAAP operating profit was $637.9 million, up 44.2% year over year; GAAP operating margin was 19.5%, up 2.7 percentage points year over year. Adjusted operating profit was $738.4 million, up 50.9% year over year; adjusted operating margin was 22.6%, up 4.1 percentage points year over year. Both measures improved, indicating that the increase in profitability did not depend entirely on non-GAAP adjustments.
The company attributed the margin expansion to operating execution, continued productivity improvements, and favorable price-cost dynamics, including tariff impacts and mitigation measures. This explanation is corroborated by regional performance: adjusted operating margin in the Americas reached 27.6%, up 3.6 percentage points year over year; Asia-Pacific reached 13.3%, up 2.7 percentage points; and Europe, the Middle East, and Africa reached 25.7%, up 3.8 percentage points. Even in the weaker-revenue European region, margins improved significantly, indicating that pricing, product mix, and execution efficiency are working together.
However, the $1.52 in adjusted EPS cannot be attributed entirely to operating profit. The company disclosed a Q2 adjusted effective tax rate of 20%, below the 23% originally guided, primarily due to tax benefits related to equity compensation. Adjusted operating profit exceeded the guidance midpoint by $28.40 million and even surpassed the upper end of guidance by $8.40 million, so operating performance clearly beat expectations. Nevertheless, the tax benefit also contributed materially to the EPS outperformance. A more prudent assessment is that “operating profit and margins exceeded expectations, while the tax rate further amplified EPS,” rather than treating the entire $0.12 difference as a sustainable operating improvement.
