
U.S. Semiconductor 2Q26 Preview: DRAM Price Hikes, Analog Price Hikes, and the Validation Window for $250 Billion WFE
目录
Too Long; Didn’t Read
I. 2Q26 Is Not a Broad Rally Window, but an EPS Realization Window
II. AI Compute Is Not Oversupplied; the Bottleneck Has Expanded From GPUs to DRAM and CPUs
3. Memory Is the First Tollbooth; Micron’s Leverage Comes from Non-LTA Pricing
4. Analog Chips Enter a Price-Hike Recovery Phase; Texas Instruments Depends on Gross Margin and Nvidia Power
5. The Equipment Cycle Points to 2028; $250bn WFE Is the Long Anchor for This Round
VI. Handset Supply Chain Is the Weak Spot in Earnings Season; Qualcomm Put on Downside Watch
VII. Pre-Earnings Stock Ranking: AMD, Texas Instruments, and Applied Materials First
VIII. Trading View: Semiconductor Pullback Is Healthy, but Positioning Must Shift from Beta to Validation
IX. The Earnings Models for Five Asset Classes Have Already Diverged
X. What to Ask on Earnings Calls: Don’t Ask About AI, Ask About Pricing and Supply
XI. Scenario Framework: A Strong Market Has More Than One Path
XII. Valuation Is Not the Biggest Issue; Earnings Revisions Are
XIII. Falsification Checklist: Signals That Would Show the Main Thesis Is Weakening
XIV. How This Citi Report Relates to the Recent Semiconductor Chain
XV. Deep Dive on Memory: Pricing Leverage Matters More Than Shipment Leverage
XVI. Compute Deep Dive: AMD Is Trading Share, Not Industry Direction
XVII. Analog Deep Dive: Texas Instruments’ Real Variable Is Margin
XVIII. Equipment Deep Dive: Order Quality Matters More Than Order Quantity
XIX. Handset Chain Deep Dive: Low Valuation Is Not a Left-Side Opportunity
20. Portfolio Implementation: Split Semiconductor Exposure into Three Layers
21. Post-Earnings Monitoring Cadence: Prices First, Orders Second, Valuation Last
22. Conclusion: Watch Four Numbers in 2Q26: Pricing, Gross Margin, Orders, and Handset Order Cuts
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
U.S. semiconductor 2Q26 earnings need to test how AI demand flows through to EPS upgrades: whether DRAM price hikes can continue, whether the analog chain can raise prices and expand gross margins, whether equipment orders can support $250 billion of WFE in 2028, and whether downward revisions in the smartphone chain will weigh on sector risk appetite. These are the trading fault lines for this earnings season.
Too Long; Didn’t Read
The earnings validation points have narrowed. After the sector’s sharp rally, the market will no longer pay indiscriminately for the AI label. Earnings need to validate whether profit upgrades can spread from core compute to memory, analog, power, and equipment. If a company can only discuss long-term TAM but cannot translate it into pricing, gross margin, orders, and customer share, earnings may instead become a realization window.
Compute is still not an oversupply trade. Cloud capex continues to be revised upward, and cloud compute pricing is also rising, indicating AI compute supply remains tight. But the bottleneck has shifted from individual accelerators to memory, processors, networking, power, and equipment. This shift benefits Micron, AMD, Texas Instruments, and Applied Materials, while lowering the relative positioning of pure smartphone-chain names and companies with weak AI exposure.
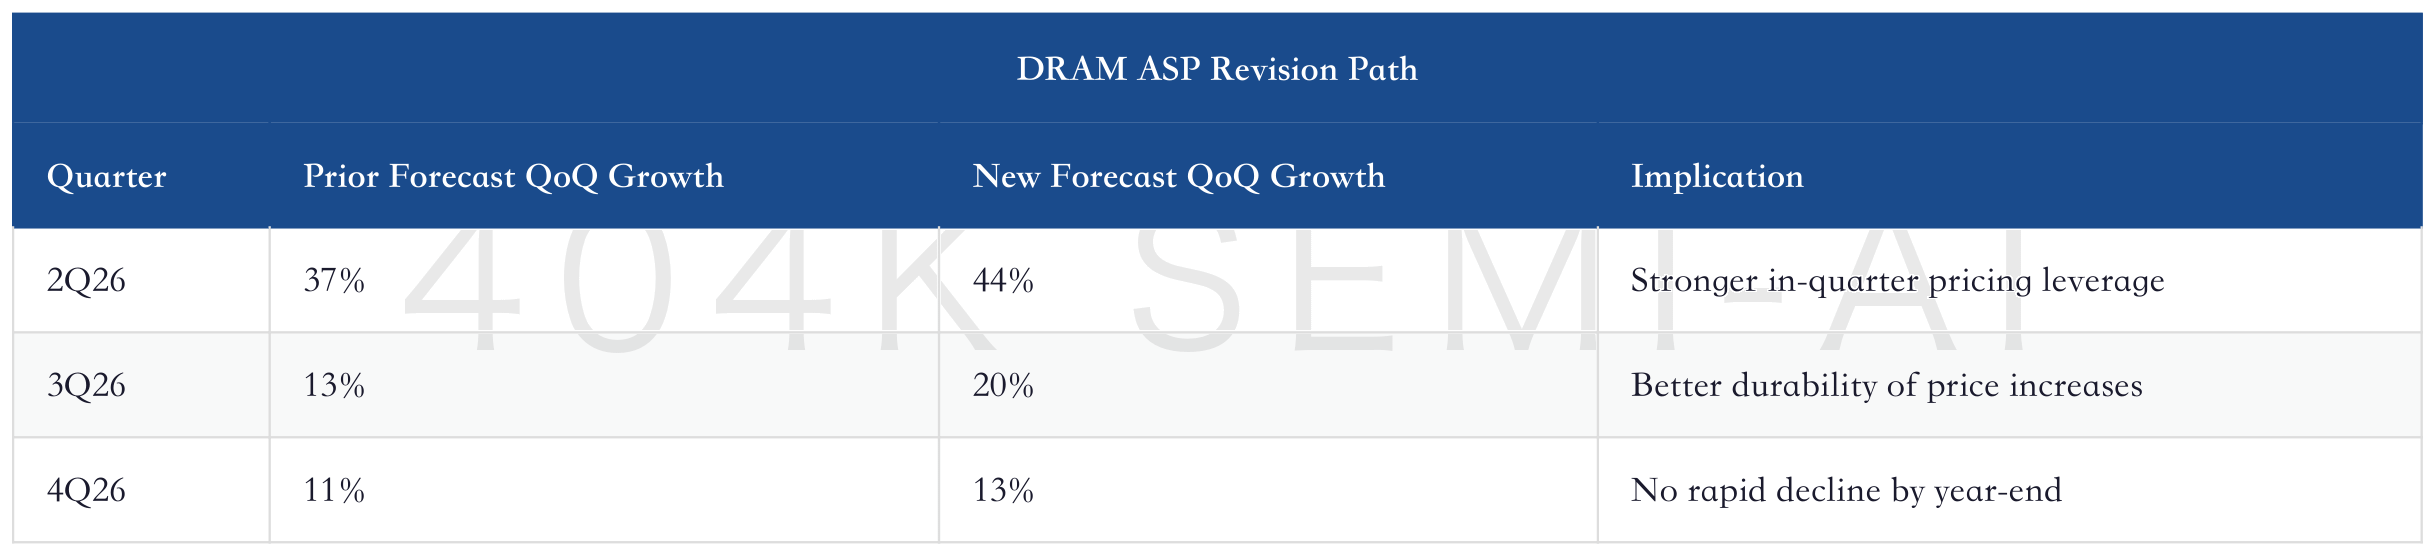
Memory is the first toll booth. Citi raised its 2Q/3Q/4Q26 DRAM ASP QoQ growth forecasts to 44%/20%/13%, and placed Micron on a 90-day positive Catalyst Watch, because AI CPU and inference demand continue to absorb DRAM supply. The key for Micron is not only HBM, but also the roughly 60% of non-LTA sales where pricing elasticity can flow quickly into EPS.
Analog chips are entering a price-hike recovery phase. The global manufacturing PMI rose to 52.6 in May, industrial demand is recovering broadly, and analog and MCU pricing is also rising. Texas Instruments’ opportunity comes from industrial recovery, share in Nvidia’s power supply chain, and a rebound in internal capacity utilization. If both gross margin and orders improve in 2Q26, analog-chain valuations can remain elevated.
The equipment cycle is about 2028, not current-quarter orders. Citi’s WFE path is roughly $145 billion/$200 billion/$250 billion for 2026/2027/2028, driven by simultaneous starts in DRAM, advanced logic, advanced packaging, and fab expansion. Applied Materials is one of the preferred names ahead of earnings; the key validation points are whether its DRAM equipment mix improves and its valuation discount narrows.
The biggest weakness is the smartphone chain. Citi placed Qualcomm on a 30-day negative Catalyst Watch, citing an expected 14% decline in handset revenue in FY26. Shipment target cuts by Xiaomi, Oppo, and Vivo will continue to pressure the non-Apple chain. If 2Q26 handset customer order cuts do not improve, Qualcomm, Qorvo, Skyworks, and Universal Display will be relative weak spots in this semiconductor earnings season.
I. 2Q26 Is Not a Broad Rally Window, but an EPS Realization Window
U.S. semiconductors have reached an awkward but valuable point: is the index very expensive? Not extremely. Is the trade crowded? Already crowded. Citi’s numbers are direct: the SOX is up 78% year to date, versus a 9% gain for the S&P; 500 over the same period. The leadership order has been memory, semiconductor equipment, compute, analog, and the smartphone chain. The market has already traded one round of AI diffusion. The question for 2Q26 earnings season is whether these gains are actually supported by EPS.
Valuation has not fully blocked the bull case. The SOX trades at roughly 19x FY2, broadly in line with the S&P; 500 and below its average relative premium of about 17% over the past five years. In other words, this semiconductor trade is not simply a high-valuation bubble. The market has already priced in AI capex, memory price increases, analog recovery, and equipment orders. Earnings season needs to prove whether these assumptions can continue to be revised upward.
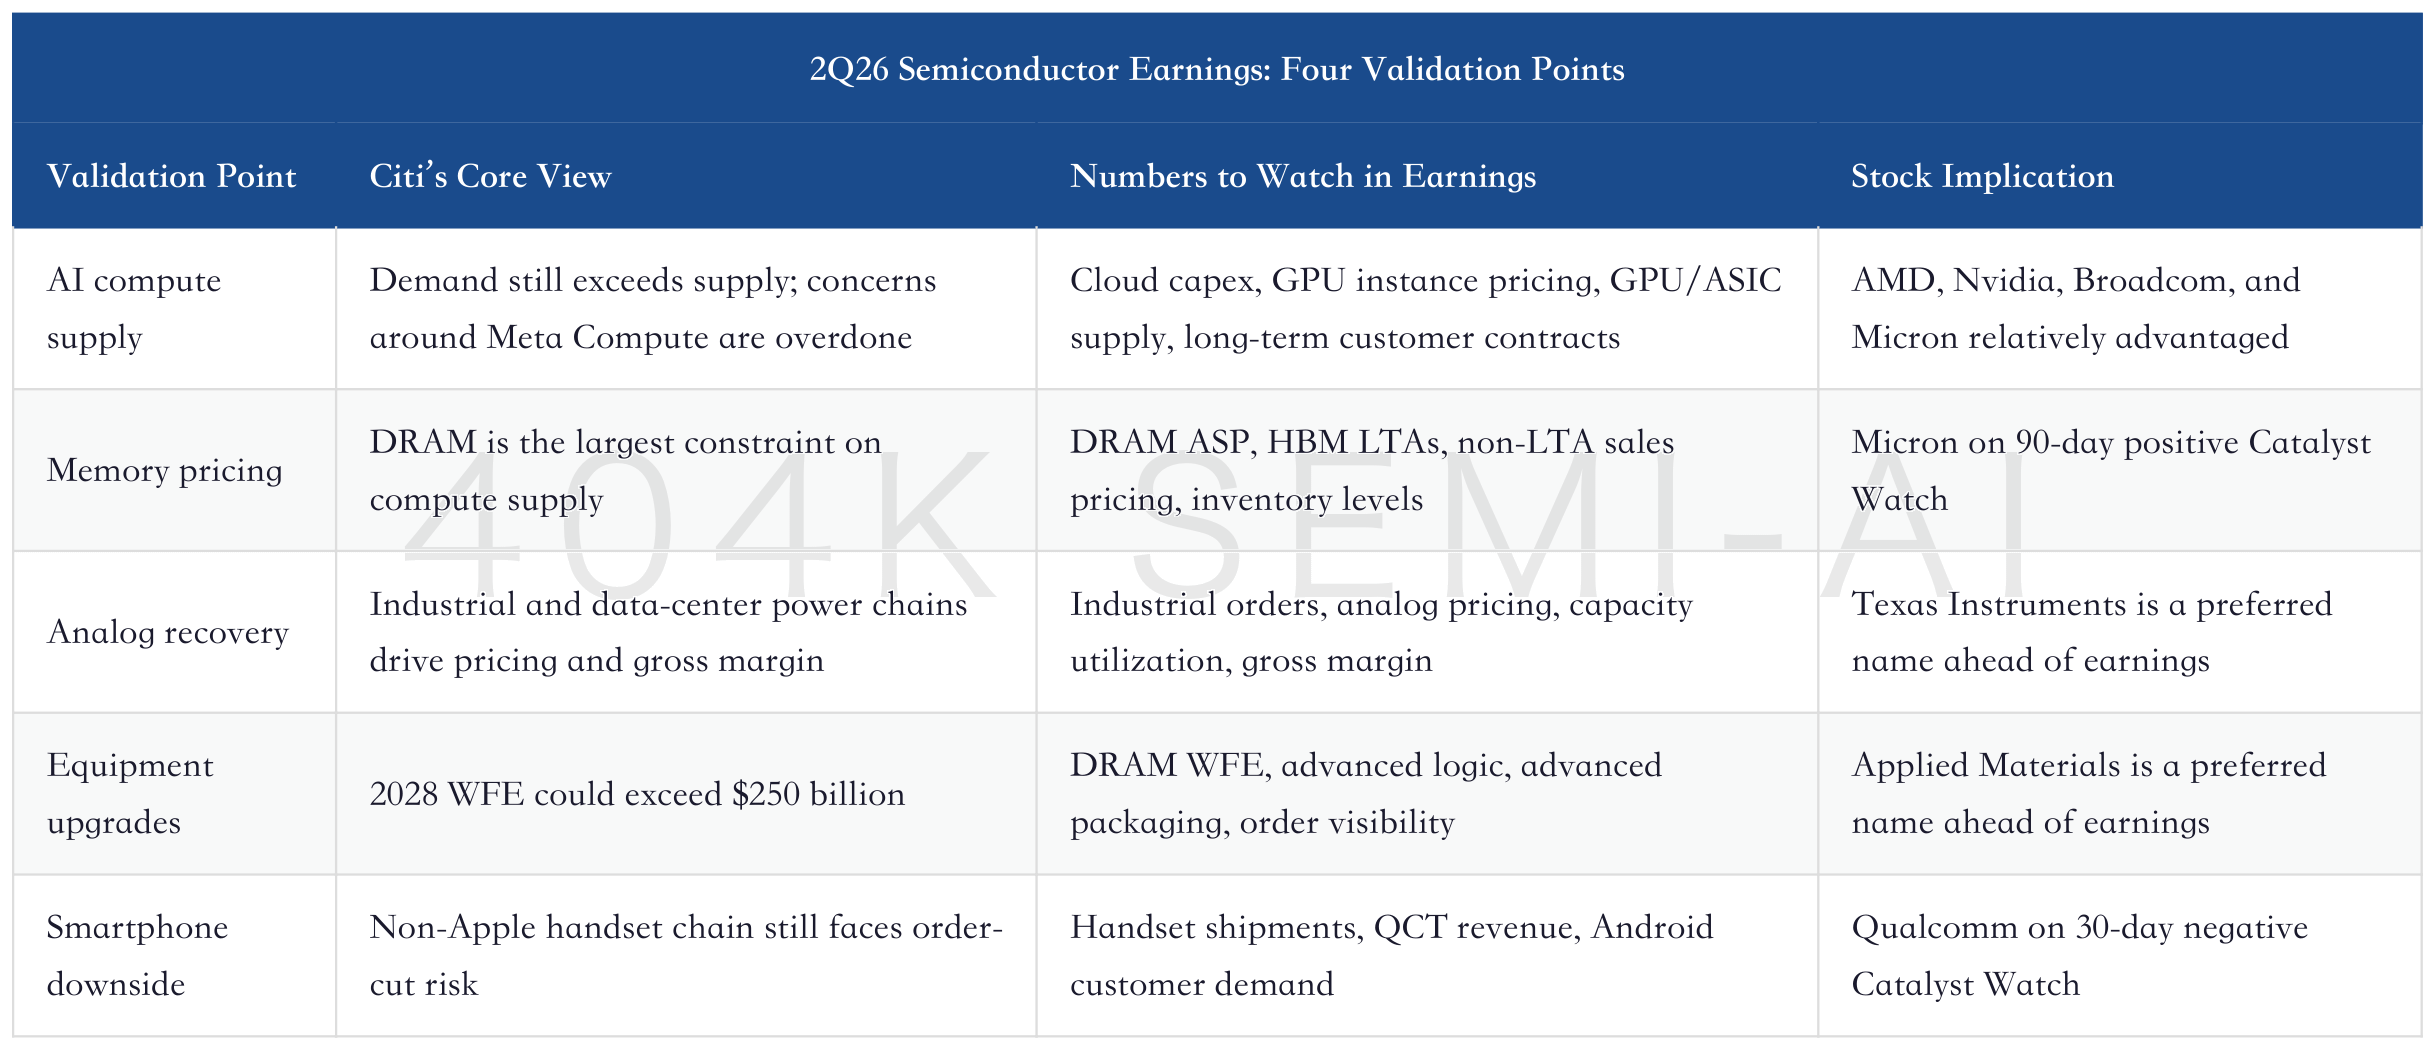
The point of this table is that the semiconductor trade has shifted from an “AI beneficiary list” to “who realizes EPS first.” Over the past few months, the market could tolerate companies talking about long-term TAM and customer qualifications. Earnings season will be more selective. Companies that can translate demand into revenue, pricing, gross margin, and orders can continue to be revised upward. Companies that can only tell a grand narrative may instead see their shares used as an exit for profit-taking capital.
Citi’s preferred names ahead of earnings also illustrate this screening process: AMD, Texas Instruments, and Applied Materials. These three companies are not in the same industry; they represent GPU share, analog price increases, and the equipment cycle, respectively. The combination itself shows that 2Q26 semiconductor earnings are no longer centered only on Nvidia as a single-stock trade, but on how AI demand diffuses into memory, analog, power, CPUs, and front-end equipment.
II. AI Compute Is Not Oversupplied; the Bottleneck Has Expanded From GPUs to DRAM and CPUs
The market has recently worried about oversupply in AI compute, triggered by potential supply releases such as Meta Compute. Citi’s view is more direct: these concerns are amplified in the near term. AWS EC2 GPU instance prices are up 20%, showing that the real market is still willing to pay higher prices for GPU compute. If compute were already oversupplied, cloud GPU prices should not still be rising at this point.
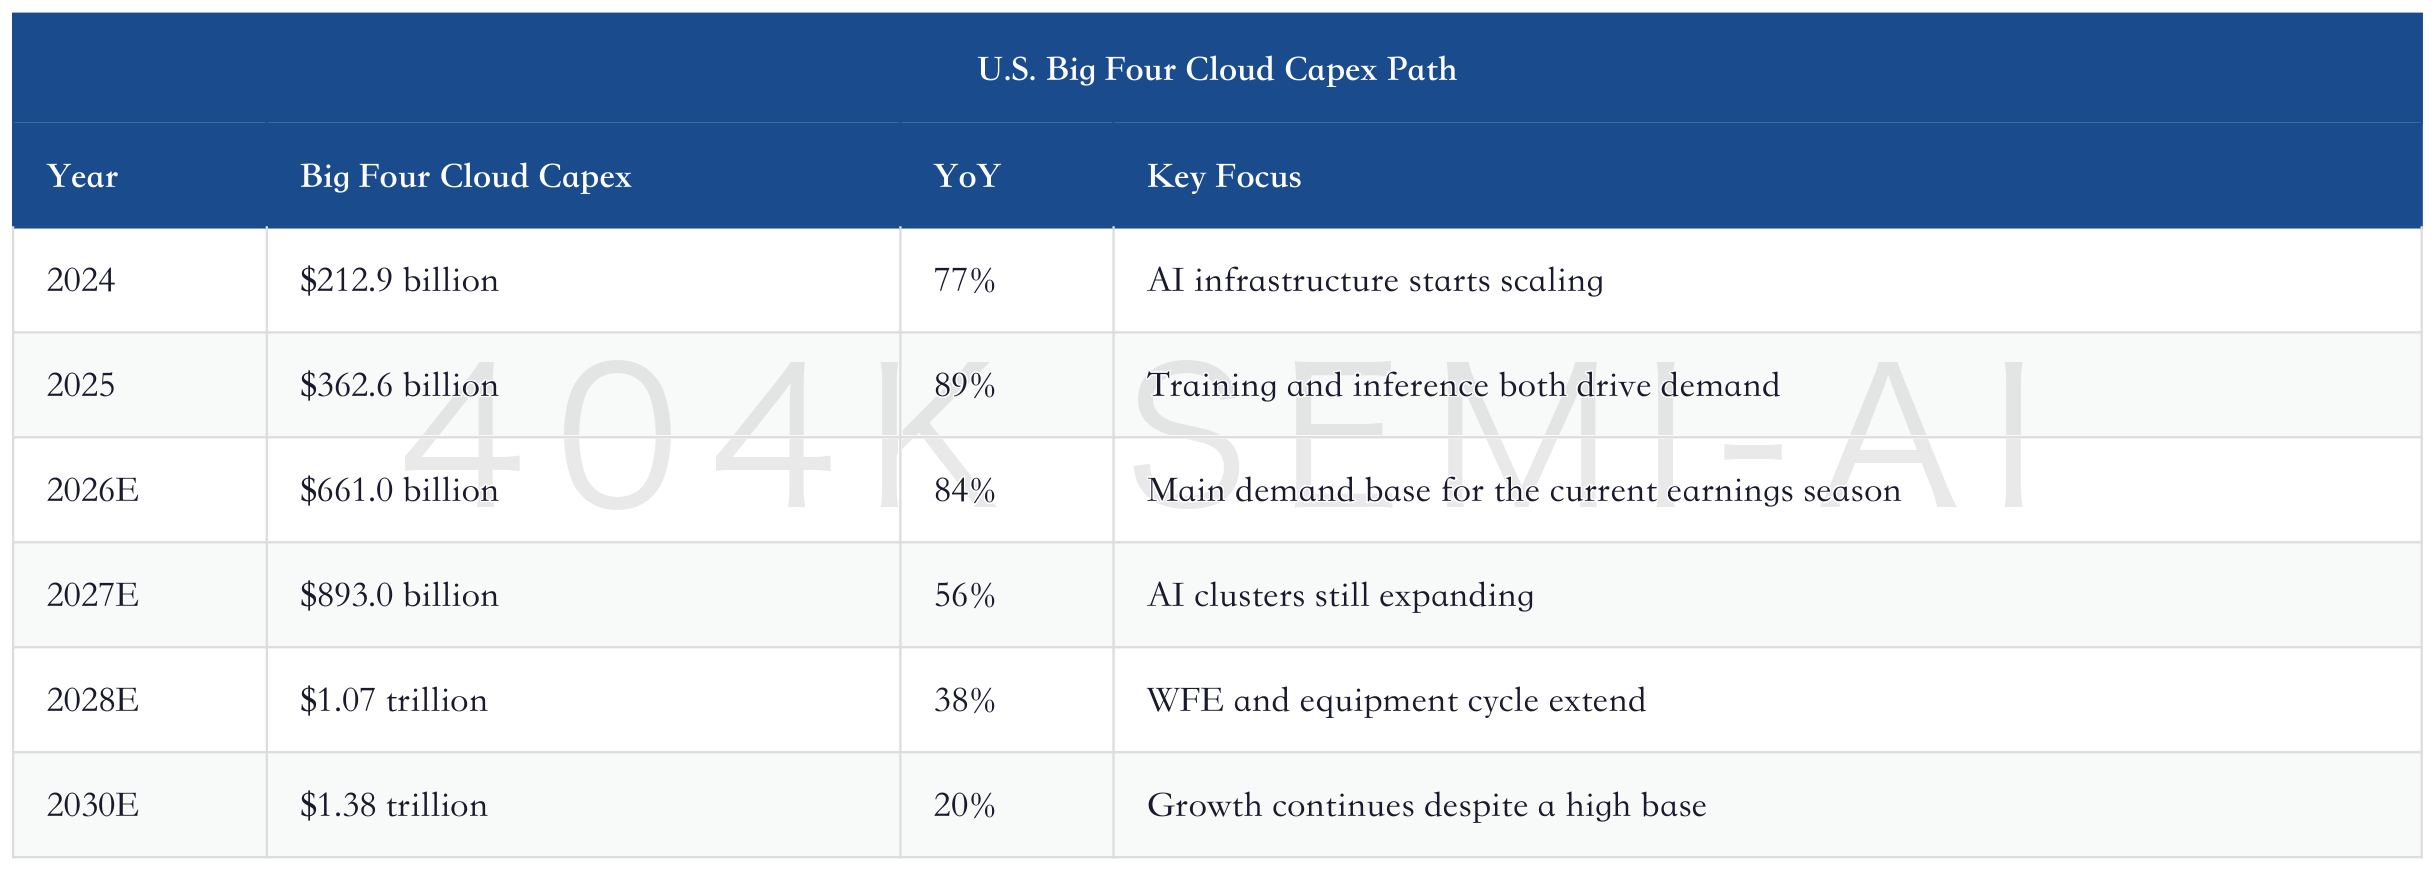
More importantly, the cloud capex model has not reversed. Citi expects capex at the four major U.S. cloud providers to grow 84% in 2026, another 56% in 2027, and still 38% in 2028. This slope indicates AI infrastructure remains in an expansion phase, not a digestion phase.
The real change is the location of the supply constraint. Previously, the market understood the compute bottleneck as GPU shortages. Now the bottleneck looks more like a system function: GPU/ASIC, HBM, commodity DRAM, CPU, networking, power, and wafer equipment all need to keep pace simultaneously. Citi believes DRAM shortage is currently the largest constraint on compute supply. This is very important. It pushes the market from “buy the GPU leader” toward “buy memory, CPUs, analog power, and equipment.”
The AI data-center semiconductor TAM is also expanding. Citi divides the incremental opportunity into three lines: GPU, ASIC, and CPU. Its conclusion is that custom ASIC share will continue to rise, but GPUs will still retain the largest revenue pool.
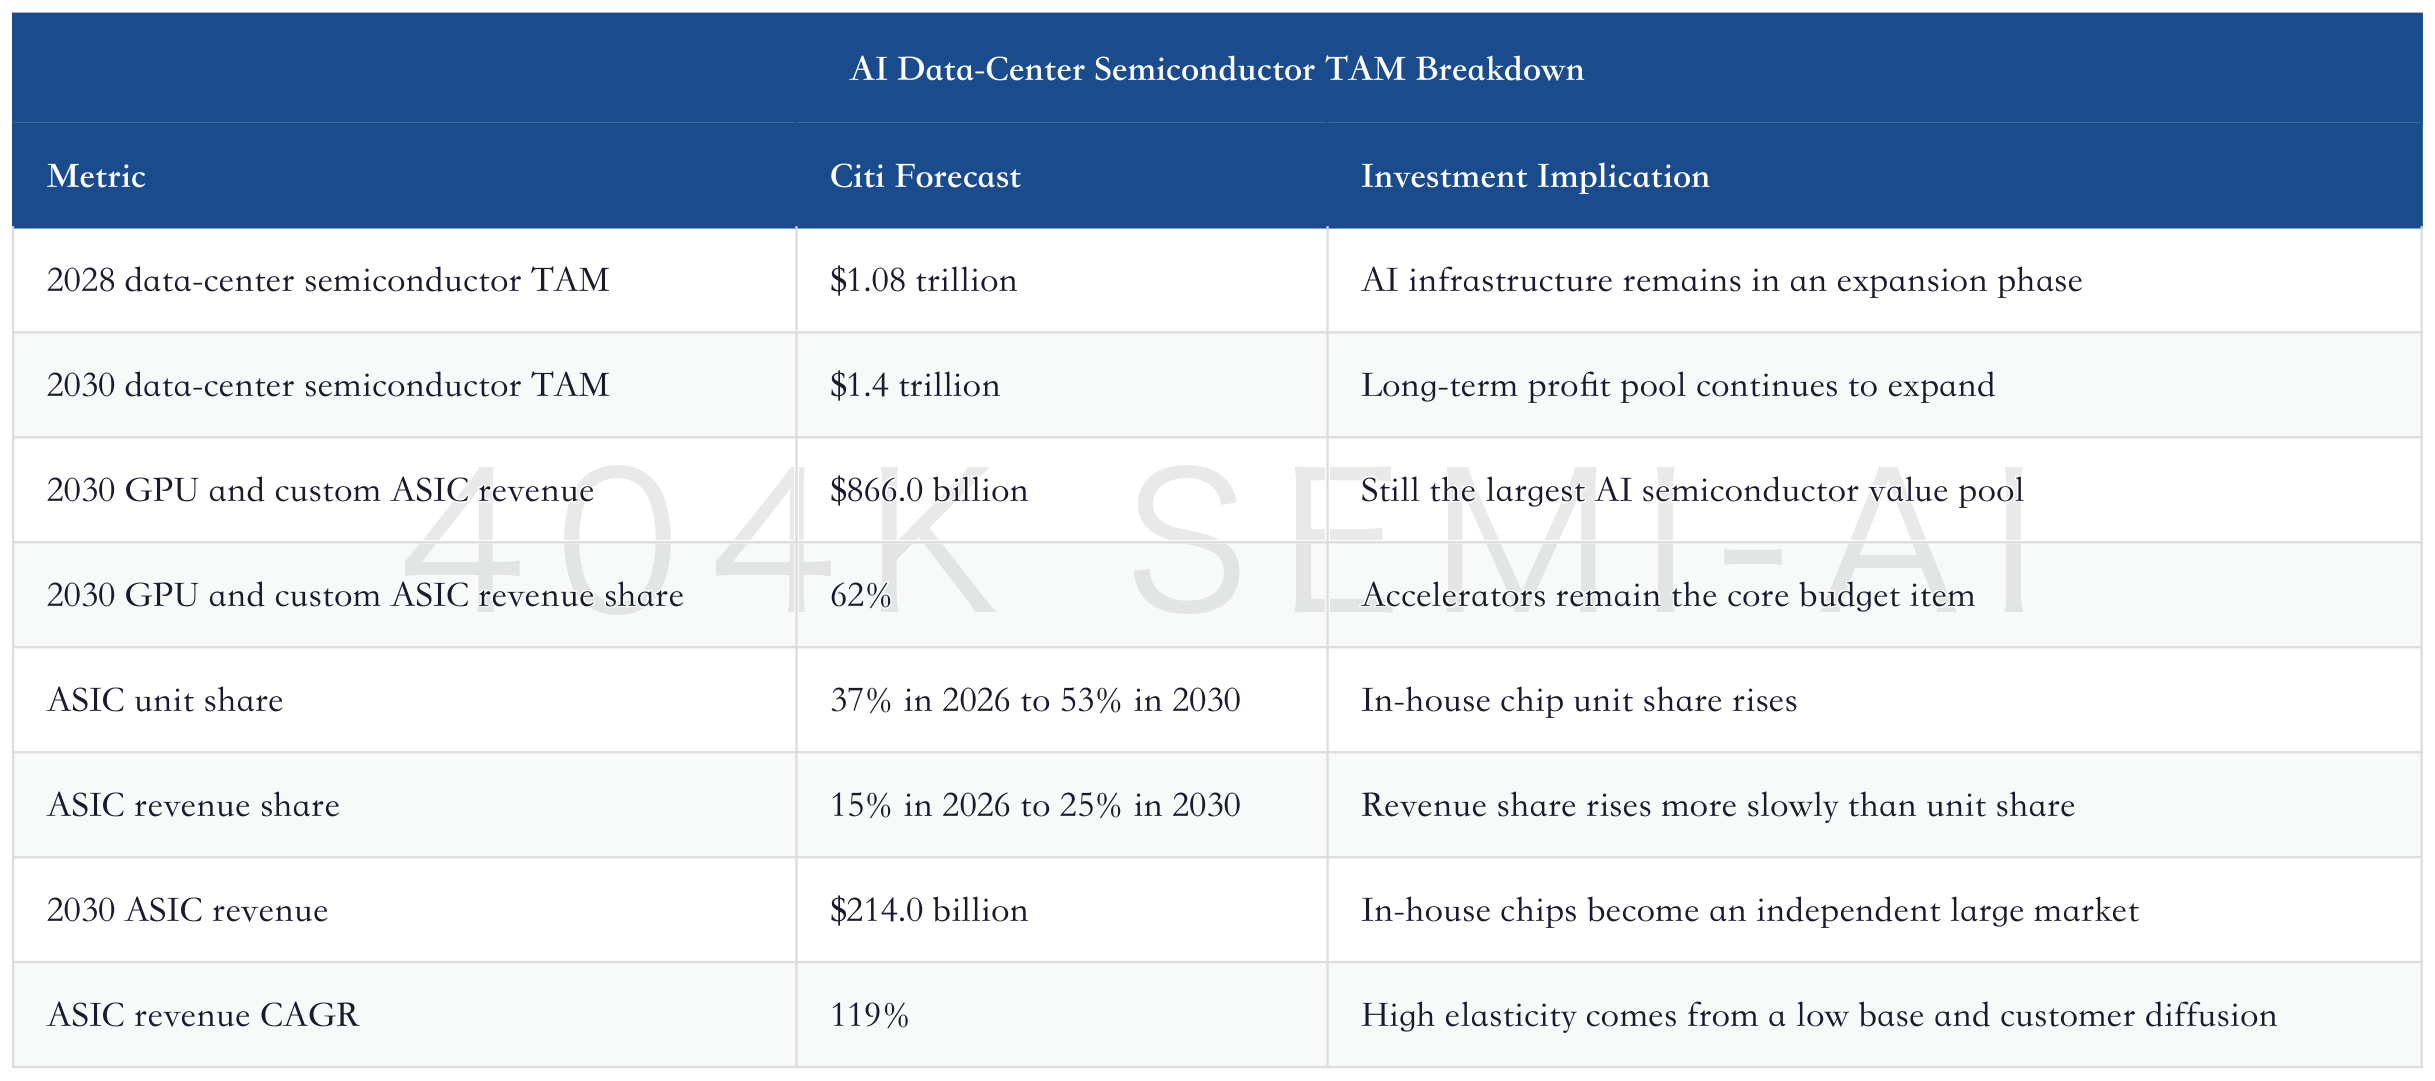
The investment implication of these numbers is not that “GPUs are unimportant,” but that the profit pool of AI clusters is becoming more dispersed. GPUs remain the highest-value segment, but ASICs, CPUs, memory, networking, and equipment are all taking incremental budget. If 2Q26 earnings prove that cloud capex continues to be revised upward, the market will keep pricing multiple chains, rather than focusing only on a single accelerator.
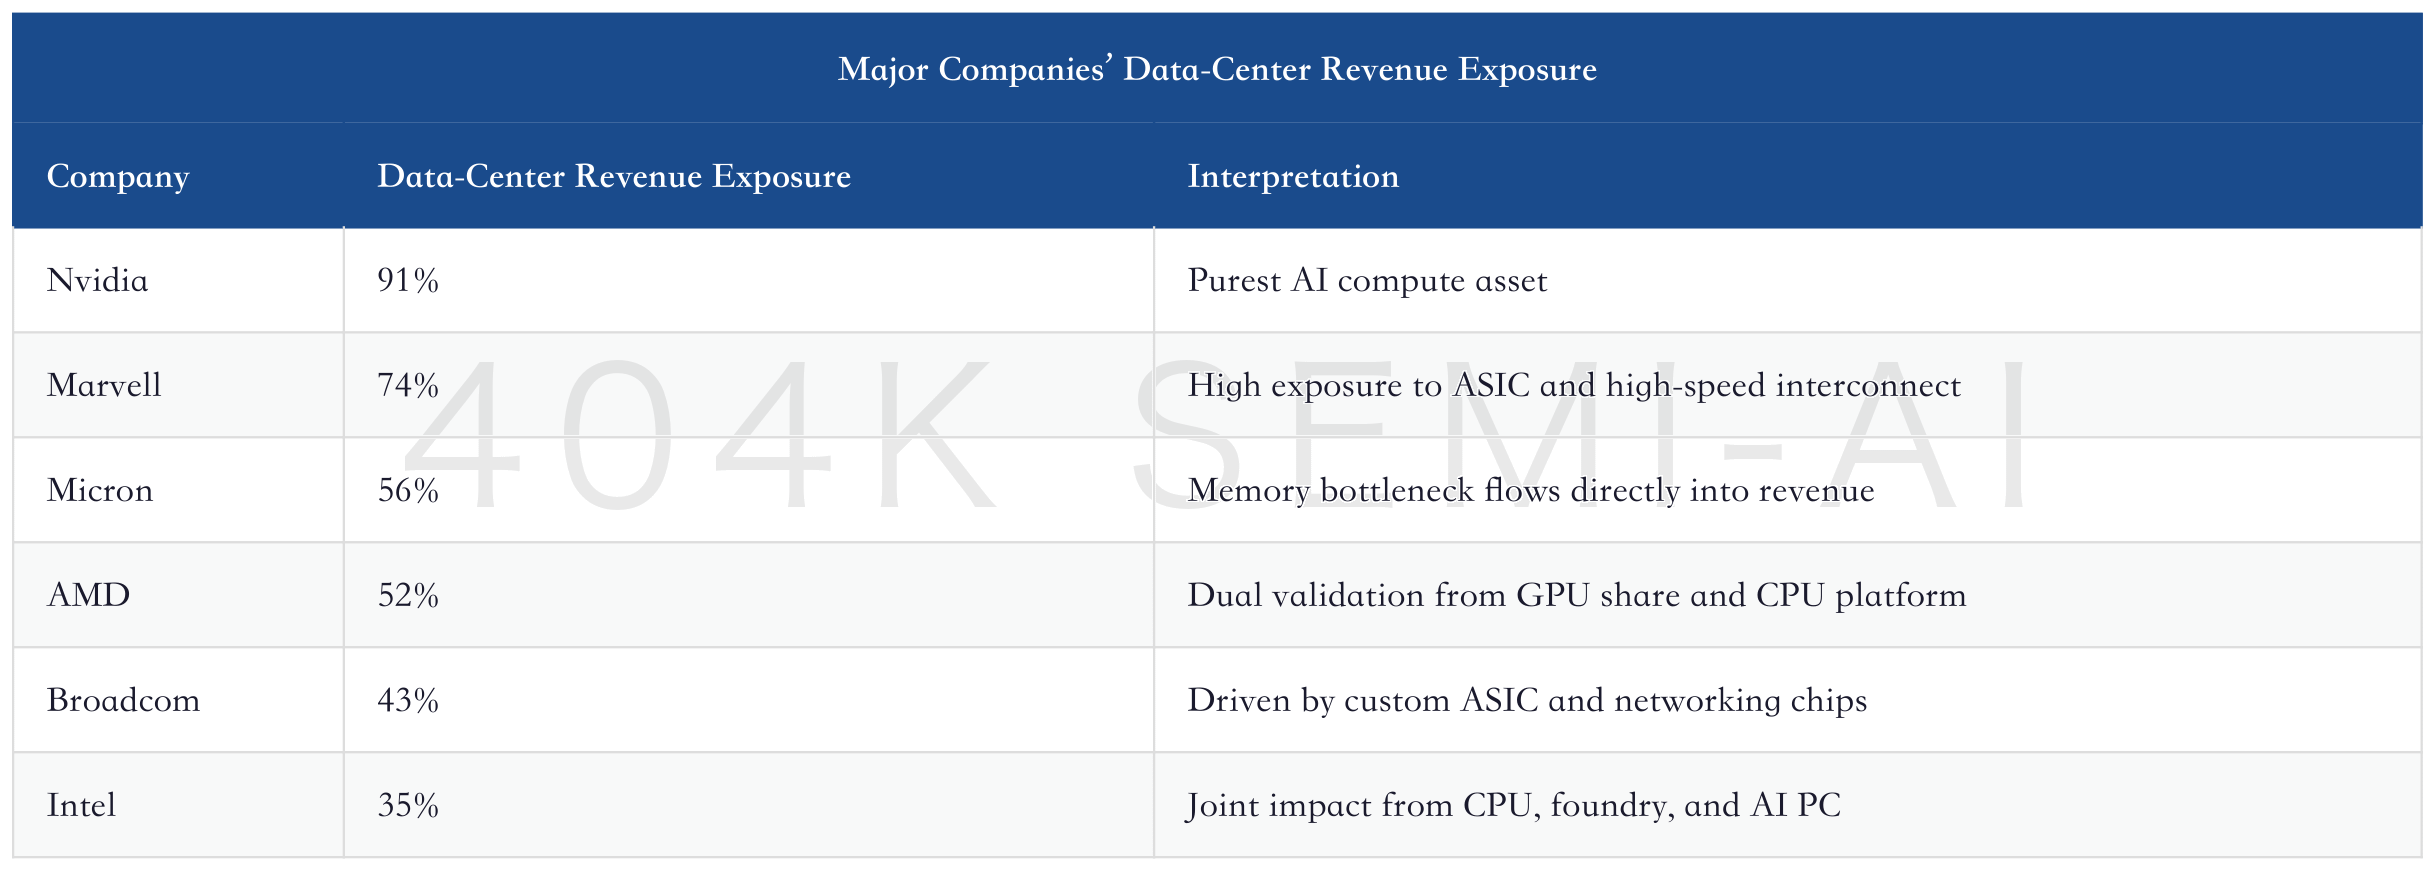
Citi’s ranking of data-center revenue exposure is useful. AMD is not the company with the highest exposure, but it sits at the intersection of GPU share, x86 CPUs, AI head nodes, and customer diversification. If GPU share gains materialize in 2H26, AMD’s earnings elasticity will be more important than a simple PC recovery.
The falsification conditions for the AI compute chain are also clear. First, cloud capex guidance starts to be revised down. Second, GPU instance pricing turns lower, indicating shortage relief. Third, DRAM price upgrades stop, and memory is no longer a constraint. Fourth, ASIC projects are delayed or customers shift orders from in-house chips back to general-purpose GPUs. As long as these four variables do not weaken at the same time, using “compute oversupply” to explain a semiconductor pullback in the near term is too crude.
3. Memory Is the First Tollbooth; Micron’s Leverage Comes from Non-LTA Pricing
Memory is the strongest earnings catalyst in this report. Citi added Micron to its 90-day positive Catalyst Watch, not simply because “HBM is strong,” but because DRAM pricing continues to be revised higher. The change in the price curve is already direct enough; the details are in the table below.
The most important issue for Micron today is not total revenue, but non-LTA revenue. Citi estimates that roughly 60% of Micron’s sales are non-LTA, meaning DRAM price increases can flow through more quickly into revenue and EPS. If all sales were locked under long-term agreements, the pass-through from higher prices to current-quarter profit would be slower; with a higher non-LTA mix, price increases enter the model faster.
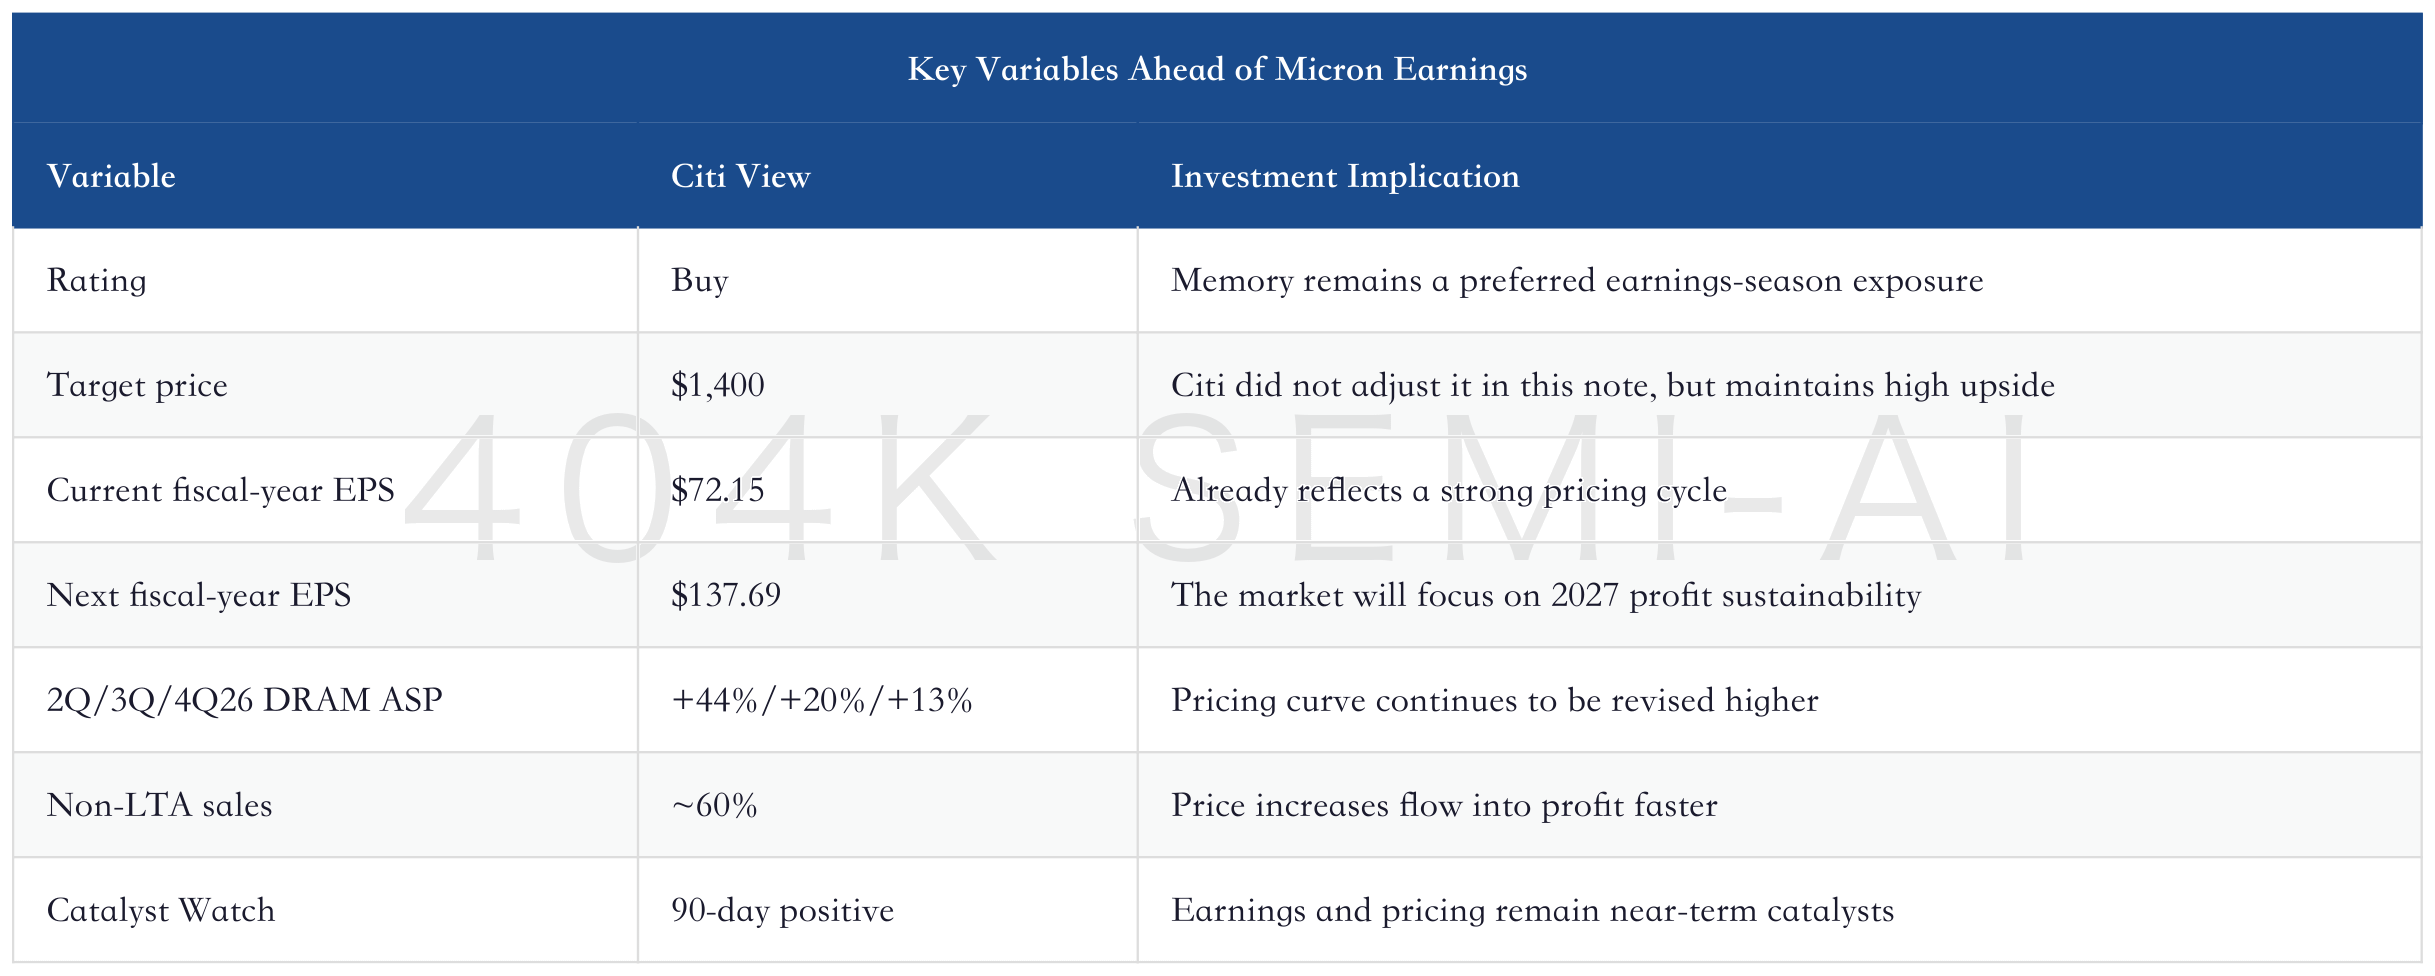
The key point in this thread is that AI demand is not limited to HBM. AI CPUs, inference clusters, long context windows, and high concurrency all consume conventional DRAM. The tighter HBM supply becomes, the more it crowds out advanced DRAM wafers; the tighter ordinary server memory becomes, the more it affects AI system delivery. Citi believes DRAM shortages are the biggest constraint on compute supply. That statement matters more than “HBM is in an upcycle,” because it explains why traditional DRAM can also be re-rated.
Memory Deep Dive Update: 3Q26 DDR Prices +32%, 2027 DRAM Demand +36%; UBS Monthly Report Recalibrates the Memory Supercycle
Micron’s risks also need to be put on the table. Memory remains a cyclical industry, and the biggest risk is a breakdown in supply discipline. If Micron, Samsung, SK Hynix, or other vendors accelerate capacity additions, the price curve will flatten. The second risk is that customers begin pressing down prices in LTAs, suggesting cloud vendors are no longer willing to lock in supply at high prices. The third risk is that higher memory prices backfire on PC and smartphone demand, causing ordinary consumer-end demand to be revised down further.
But in the 2Q26 earnings window, Micron’s trading odds remain high. The reason is that the market is currently focused on continued upward price revisions, not future supply release. As long as DRAM ASP revisions continue to exceed the model, Micron’s EPS revisions will be more direct, and the memory chain will continue to outperform most consumer electronics chains.
4. Analog Chips Enter a Price-Hike Recovery Phase; Texas Instruments Depends on Gross Margin and Nvidia Power
Analog chips have not been the most attractive AI asset over the past few quarters, but two variables start strengthening simultaneously in 2Q26: industrial demand recovery and volume growth in the data-center power chain. Citi lists Texas Instruments as a preferred name ahead of earnings. The core logic is not simply industrial restocking, but gross-margin expansion and share in Nvidia power delivery.
The macro base has already improved. The global manufacturing PMI rose to 52.6 in May, the highest reading since 2023. Industrial semiconductor companies generally guided to roughly 10% QoQ growth in June/July-quarter industrial revenue. This means industrial inventory digestion has shifted from a drag to a recovery driver.
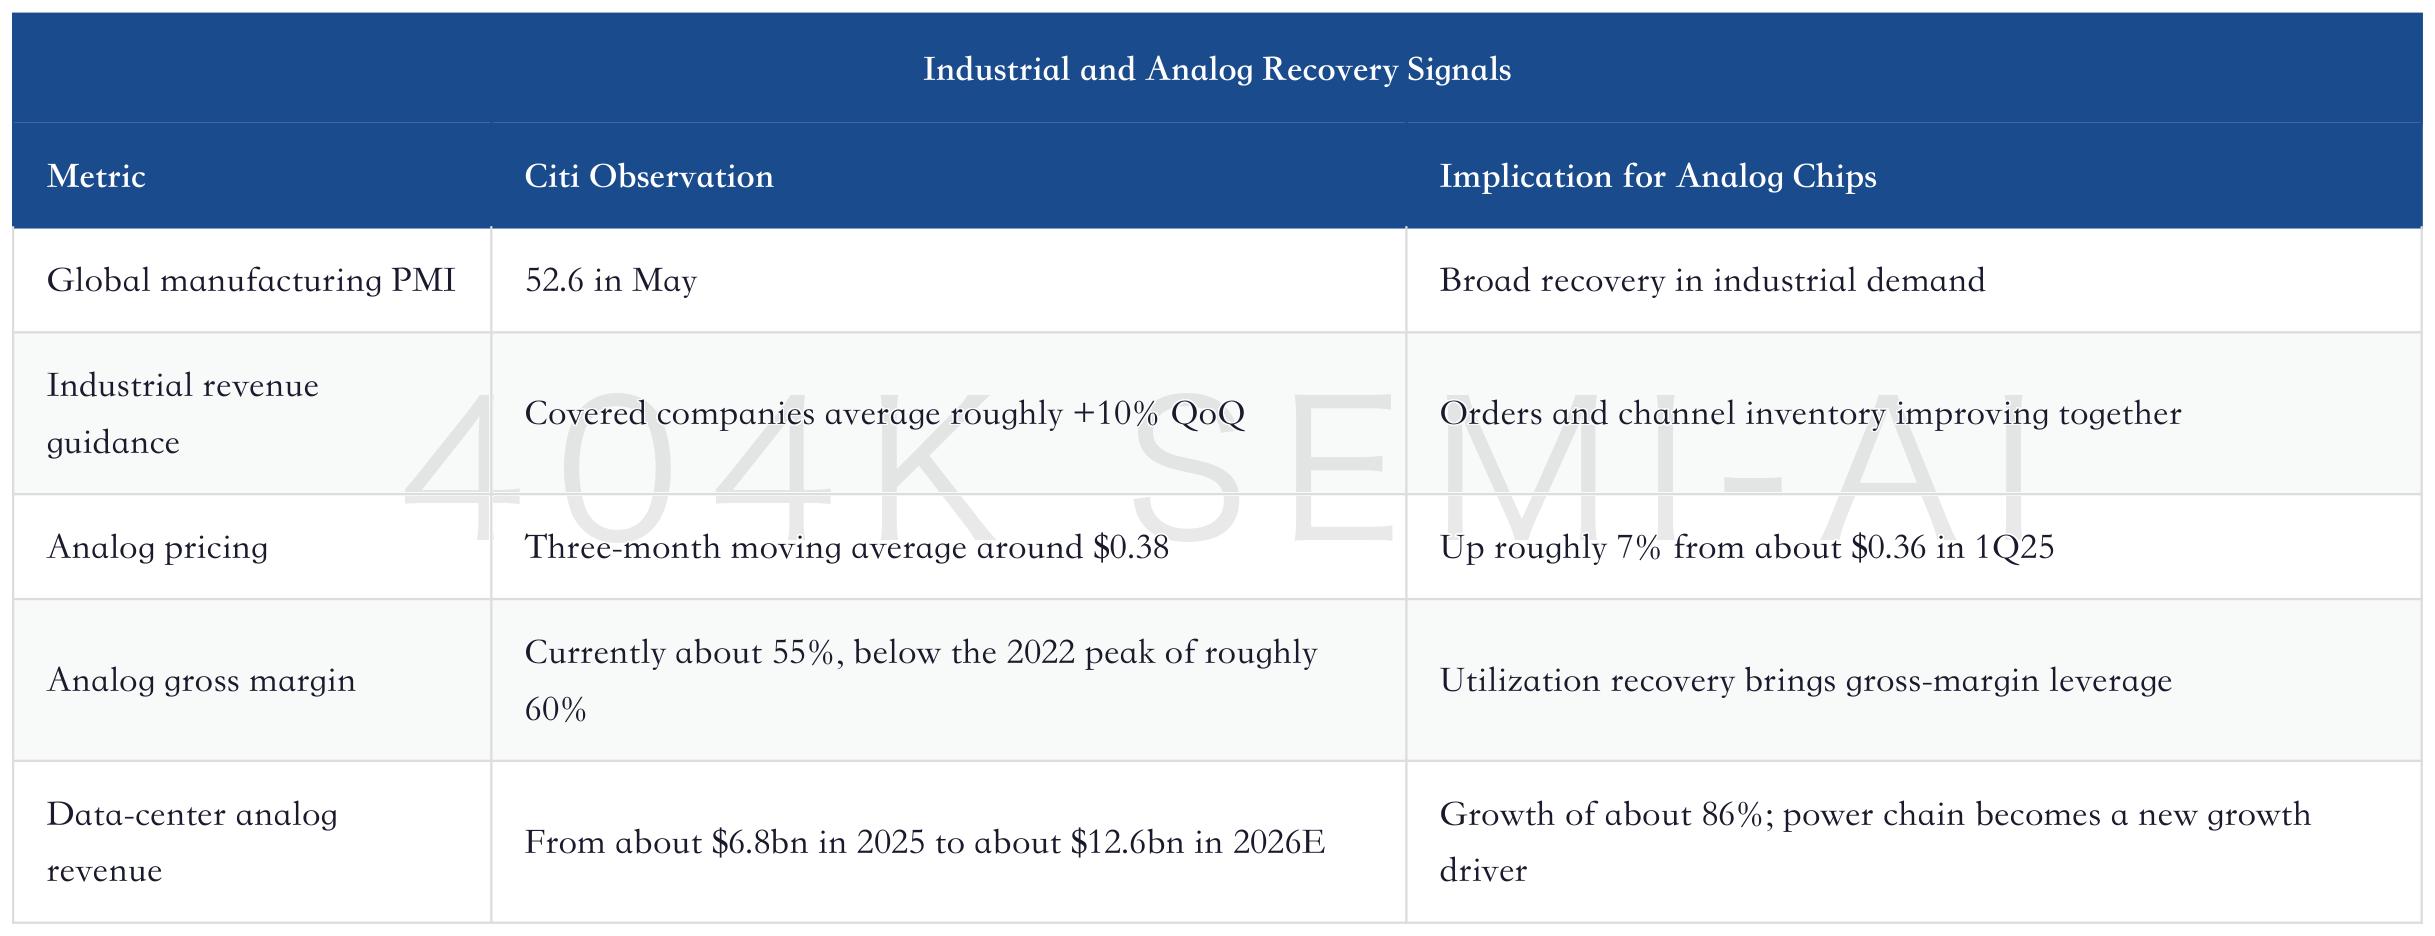
Analog chip price increases are not occurring out of thin air. Infineon, Texas Instruments, NXP, Microchip, ON Semiconductor, and others have all announced or implemented price increases, driven by rising supply-chain costs, demand recovery, and tight supply in specific products. There are also price-increase signals on the foundry side, with UMC, Vanguard International Semiconductor, and Chinese foundries raising prices on some mature nodes.
This is especially important for Texas Instruments. TI manufactures roughly 85% of its wafers internally, so rising utilization creates greater gross-margin leverage. Citi believes TI has share opportunities in the power delivery socket of Nvidia’s power supply chain, which could become a new catalyst in the 2H26 earnings narrative. If both industrial recovery and AI power share materialize, TI is not merely a traditional analog cycle recovery name, but a dual industrial plus AI power asset.
Analog Chip Deep Dive: UBS Raises Texas Instruments Target Price to $350; How an Industrial Upcycle Re-rates the Analog Leader
The debate around the analog chain is valuation. Citi notes that analog semiconductor valuations have already expanded recently because results and guidance have strengthened. The market is willing to pay a higher multiple because data-center exposure is rising, but that also lowers the margin for error during earnings. If TI only proves an industrial recovery, valuation may hold; only if it also proves gross-margin expansion and Nvidia power share will valuation have room to move higher.
5. The Equipment Cycle Points to 2028; $250bn WFE Is the Long Anchor for This Round
Semiconductor equipment is the most easily underestimated part of this AI semiconductor trade. GPUs and HBM get the most discussion, but any wafer capacity, DRAM expansion, advanced logic, advanced packaging, and yield improvement ultimately flow through to equipment orders. Citi expects WFE to reach roughly $145bn/$200bn/$250bn in 2026/2027/2028, with about 25% growth still expected in 2028.
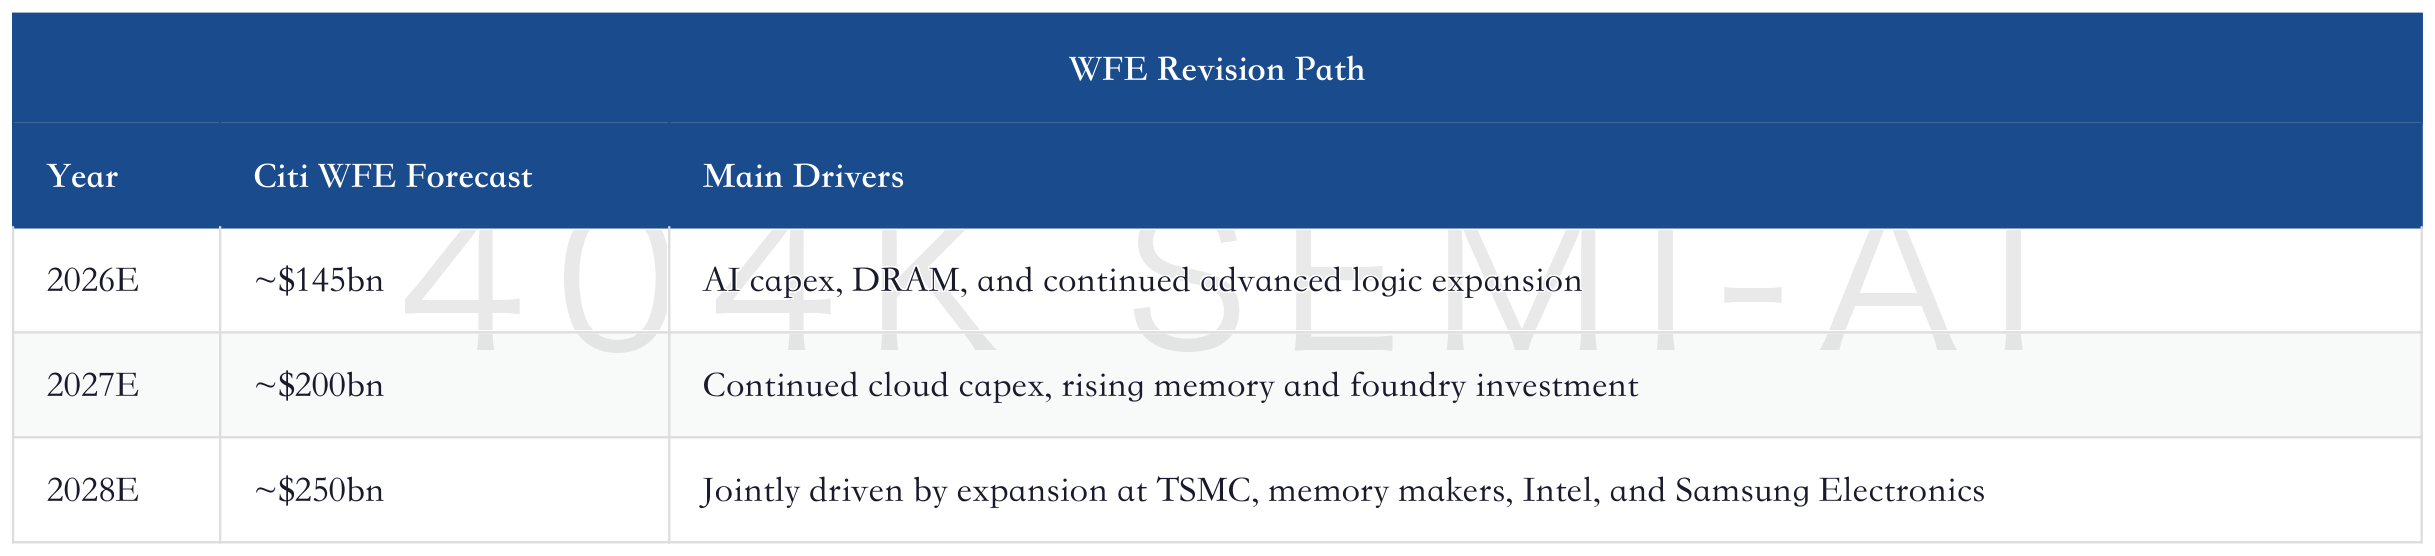
Citi is more constructive on 2028 WFE, and the reason is not a single customer. Advanced semiconductor expansion is coming from several directions at once: TSMC continues to expand advanced processes and CoWoS-related capacity; memory makers expand DRAM and HBM; Intel Foundry makes progress with customers such as Google and Apple; Samsung Electronics accelerates its Taylor fab, with links to Google TPU v10-related memory I/O die and automotive chip projects. As long as these projects keep advancing, equipment companies will not merely be a single-quarter order trade.
Applied Materials is listed as a preferred name ahead of earnings, due to a better DRAM WFE mix, 2028 WFE potential of $250bn, and a valuation discount versus peers. Applied Materials’ advantage is not any single product, but broad coverage across deposition, materials engineering, advanced packaging, and services revenue. If DRAM and advanced logic rise together, Applied Materials should have relatively balanced revenue and profit leverage.
Applied Materials Deep Dive: How the WFE Supercycle, DRAM Expansion, and Advanced Packaging Re-rate the Profit Slope
Investment judgment on the equipment chain should be divided into three layers. The first is total volume: whether WFE truly moves toward $200bn and $250bn. The second is mix: whether incremental growth comes from DRAM, advanced logic, and advanced packaging, or from lower-margin mature nodes. The third is valuation: equipment stocks have already re-rated, but relative to AI compute and memory, they still have not fully reflected the 2028 upside scenario.
The conditions that would disprove the equipment-chain thesis are also clear. If cloud capex is revised down, the market will first discount advanced logic and DRAM expansion. If memory prices rise too quickly and suppress end demand, memory makers may delay expansion. If Intel and Samsung Electronics foundry progress falls short of expectations, the foundry-side increment will also shrink. What equipment stocks fear most is not short-term order volatility, but a rewrite of 2028 visibility.
VI. Handset Supply Chain Is the Weak Spot in Earnings Season; Qualcomm Put on Downside Watch
Citi’s stance on the handset supply chain is clearly conservative. Global smartphone shipments are expected to decline 17% in 2026, then grow 12% in 2027. Rising memory costs will pressure end-demand, with the non-Apple Android chain under particular pressure. Qualcomm expects its QCT business to decline about 19% QoQ in 2Q26, significantly worse than normal seasonality of a 7% QoQ decline.
Qualcomm has been added to Citi’s 30-day downside Catalyst Watch. The core rationale is that its handset business is expected to decline 14% in FY26, while the assumption that Chinese customers recover after bottoming in 3Q26 is at risk. Xiaomi has already cut its 2026 smartphone shipment target by about 30%, while Oppo and vivo have also lowered targets again. These signals will weigh on Qualcomm, Qorvo, Skyworks, and Universal Display.
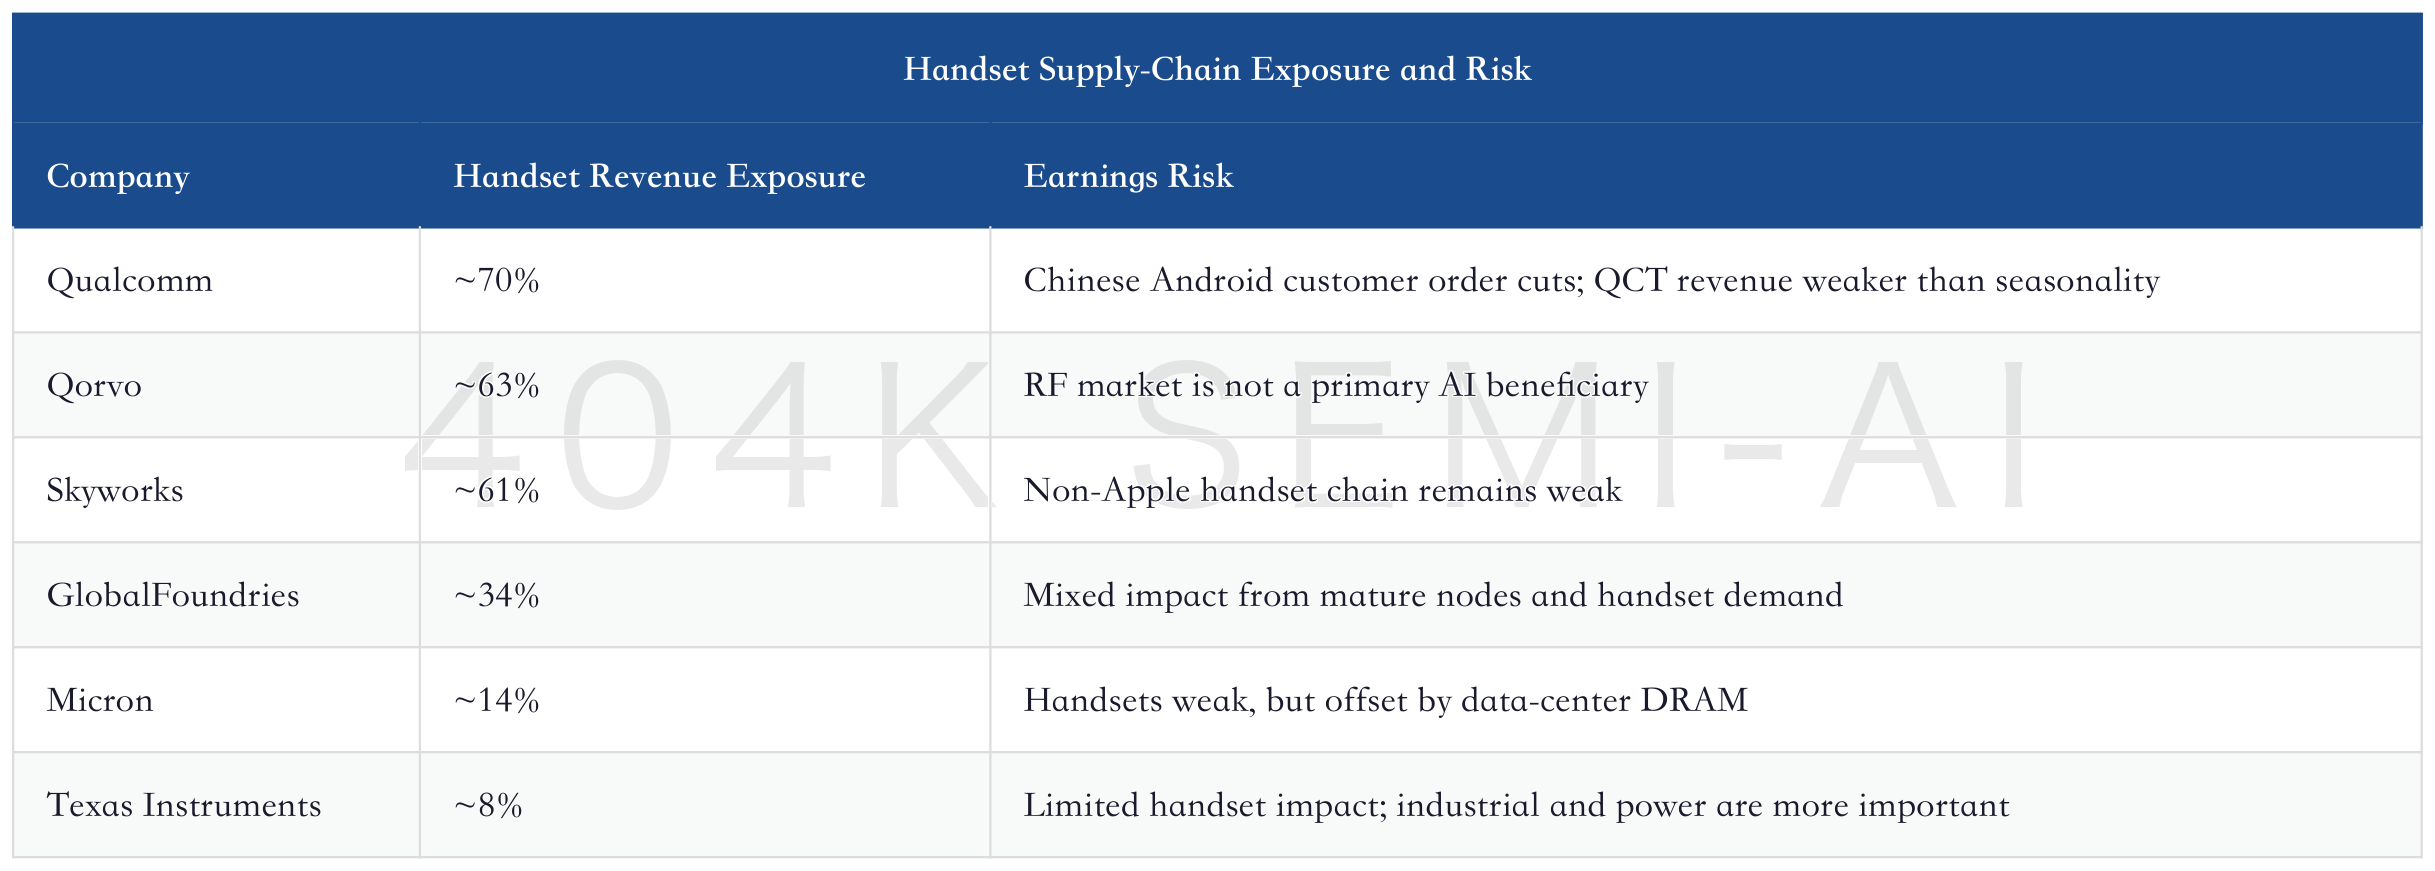
There is an important distinction here: handset weakness does not mean semiconductor weakness. PCs, handsets, and consumer electronics combined still account for about 42% of semiconductor demand in 2026, but those demand pools are declining. Data centers account for 34% and remain strong. The portfolio task is to avoid handset unit downgrades and embrace upside in data centers, memory, analog power, and equipment.
The Apple chain may be relatively better. Citi expects Apple to gain share in the smartphone market in 2026, citing supply-chain resilience, a stronger iPhone 17 cycle, and potential products such as a more advanced Siri and a foldable device. iPhone shipments are expected to be 238 million / 261 million units in 2026/2027, corresponding to -2% / +10% YoY. But the relative resilience of the Apple chain does not change the pressure on the Android handset chain.
VII. Pre-Earnings Stock Ranking: AMD, Texas Instruments, and Applied Materials First
When Citi’s industry view is broken down to the stock level, ranking matters more than direction. Many semiconductor companies can tell an AI story, but earnings season is about whose EPS is more likely to be revised up and whose downside risk is more direct. Citi’s top picks are AMD, Texas Instruments, and Applied Materials; its least preferred names are Qorvo, Skyworks, and Universal Display.
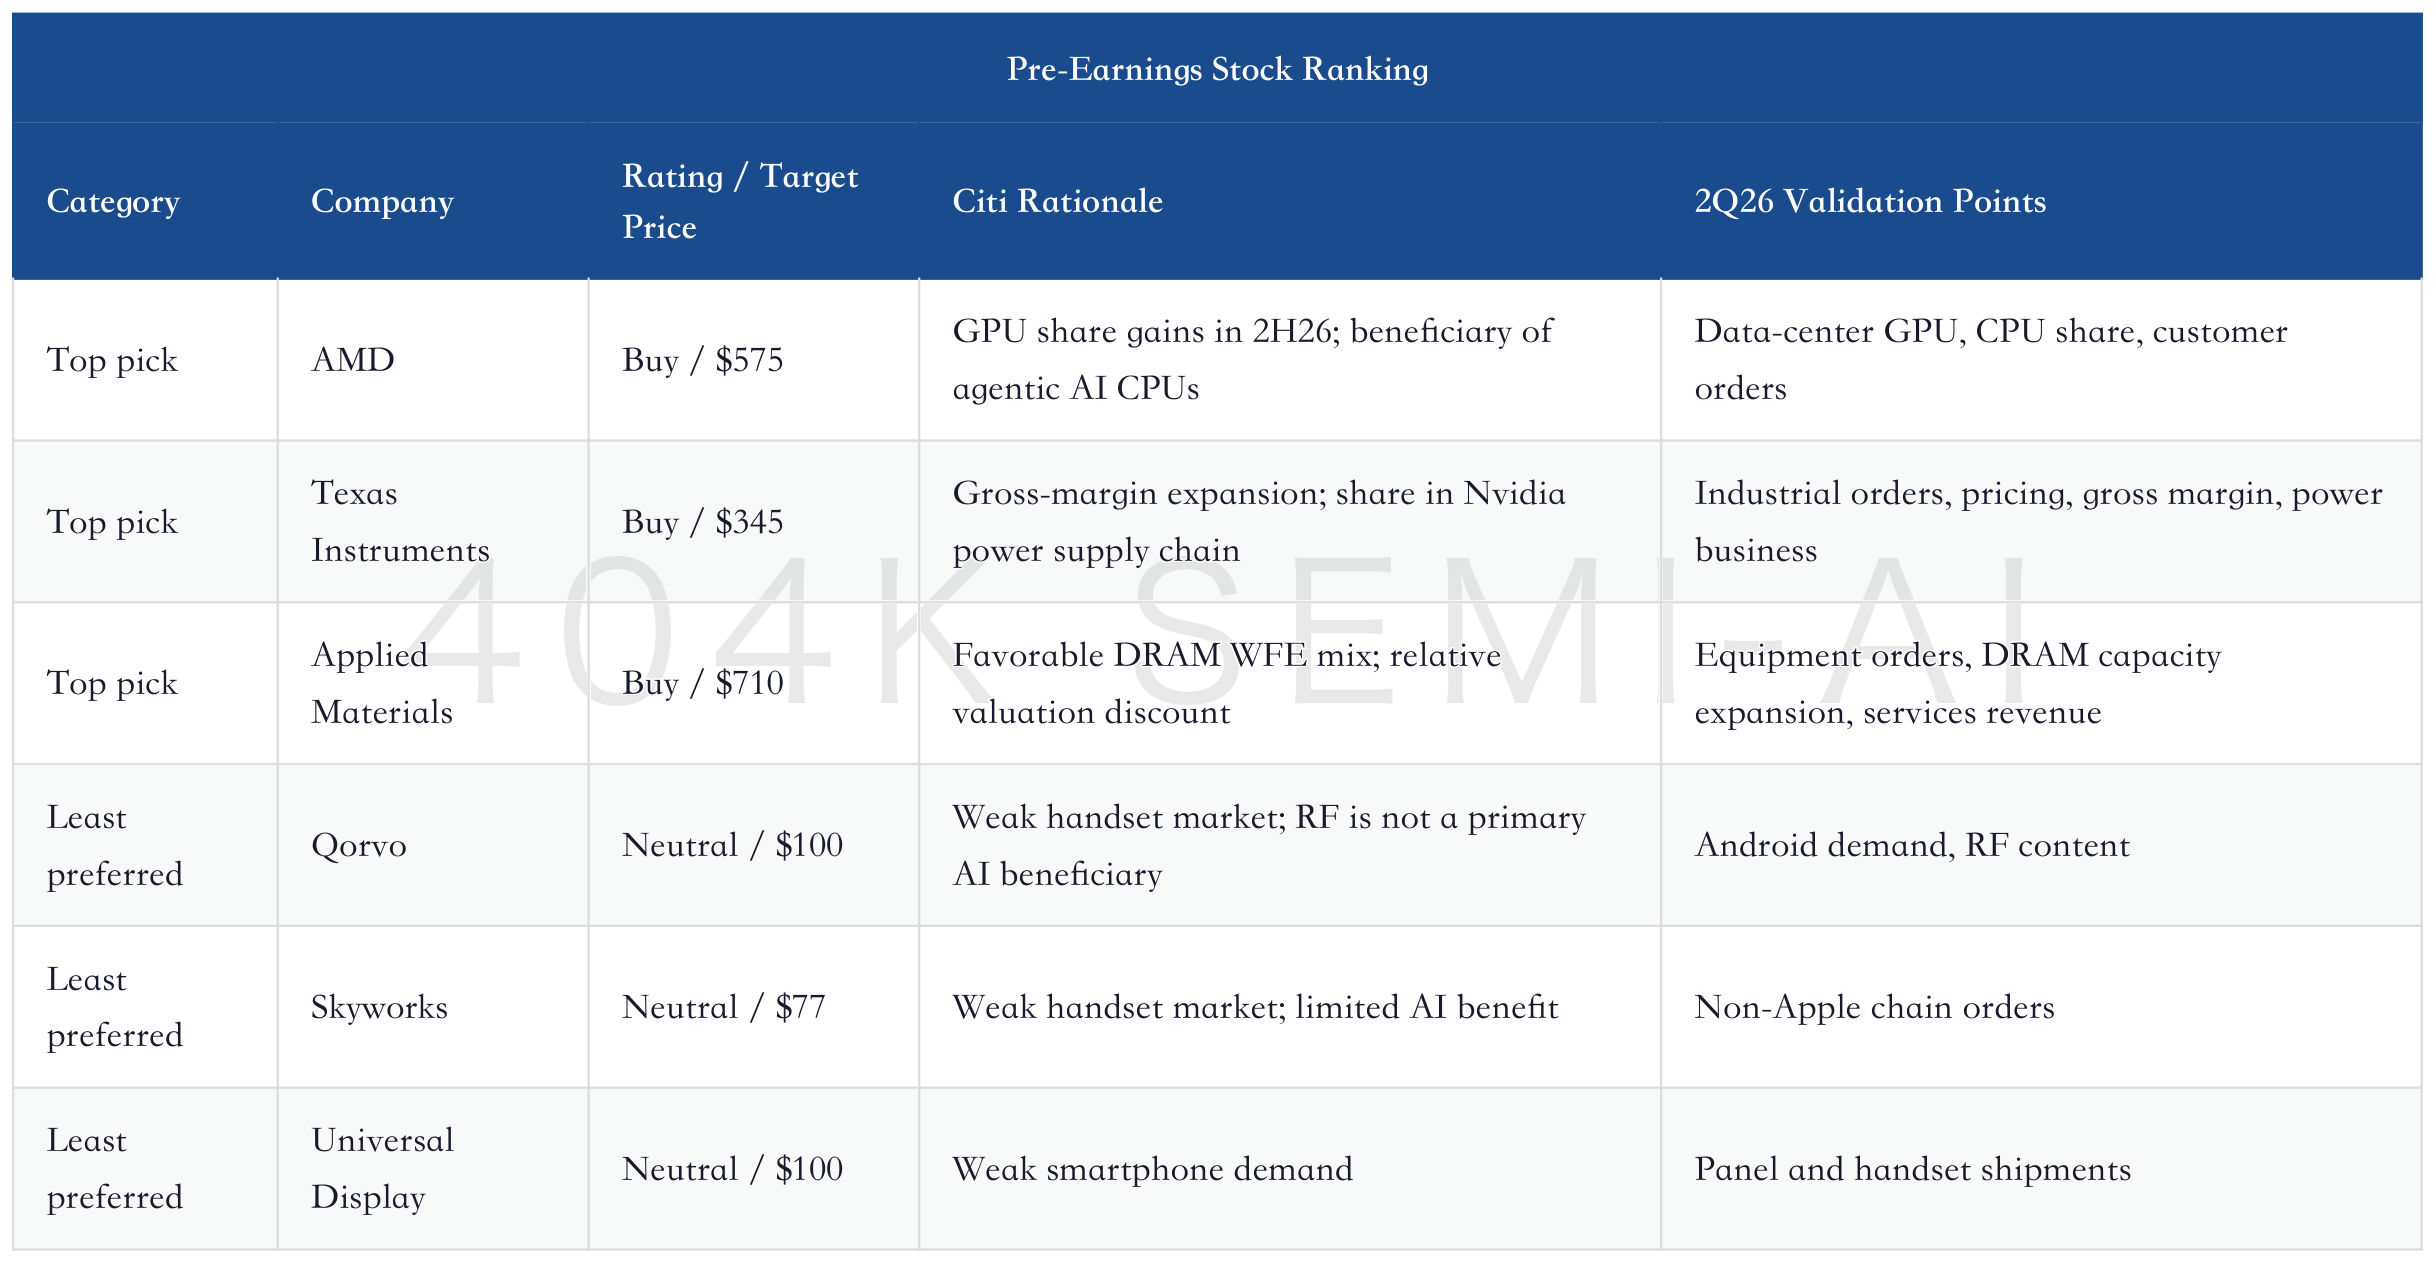
AMD’s earnings focus is data centers. If the market only looks at PCs, it will underestimate AMD, because Citi places more weight on GPU share gains in 2H26 and the CPU’s position in AI head nodes and agentic workloads. AMD’s data-center revenue exposure is about 52%, already high among large-cap semiconductor companies. It is not Nvidia, but precisely because it is not Nvidia, if earnings prove GPU share gains, the stock’s upside beta may be more concentrated.
Texas Instruments’ earnings focus is gross margin. An industrial demand recovery can bring revenue, but pricing and utilization improvements are what drive margin. Texas Instruments has a high share of internal manufacturing and strong fixed-cost leverage, so any move in gross margin toward prior peaks would directly change the EPS curve. If Nvidia’s power supply chain starts to contribute visible revenue, the story would shift from a traditional analog cycle recovery to a re-rating of the AI power chain.
Applied Materials’ earnings focus is orders and mix. The market will look at whether DRAM equipment orders, advanced logic demand, advanced packaging projects, and services revenue can jointly support upward revisions to 2028 WFE. If company guidance only proves near-term order stability, the stock may merely hold ground. If the company can convince the market that the 2027/2028 equipment cycle will be longer, there is room for the valuation discount to narrow.
VIII. Trading View: Semiconductor Pullback Is Healthy, but Positioning Must Shift from Beta to Validation
Citi believes the recent pullback in semiconductors is healthy. That judgment depends on demand and EPS not being revised down at the same time. In other words, the stock-price pullback itself is not the risk; the risk is that the fundamental assumptions are overturned. Current data look more like a cooling of crowded trades than the end of the AI semiconductor theme.
The most reasonable portfolio for 2Q26 earnings season is not to chase the highest beta, but to buy bottlenecks with clear validation. Memory validates pricing; equipment validates orders and 2028 visibility; analog validates price increases and gross margin; AMD validates share; Qualcomm validates handset-chain risk. This framework is more robust than simply ranking stocks by AI exposure.
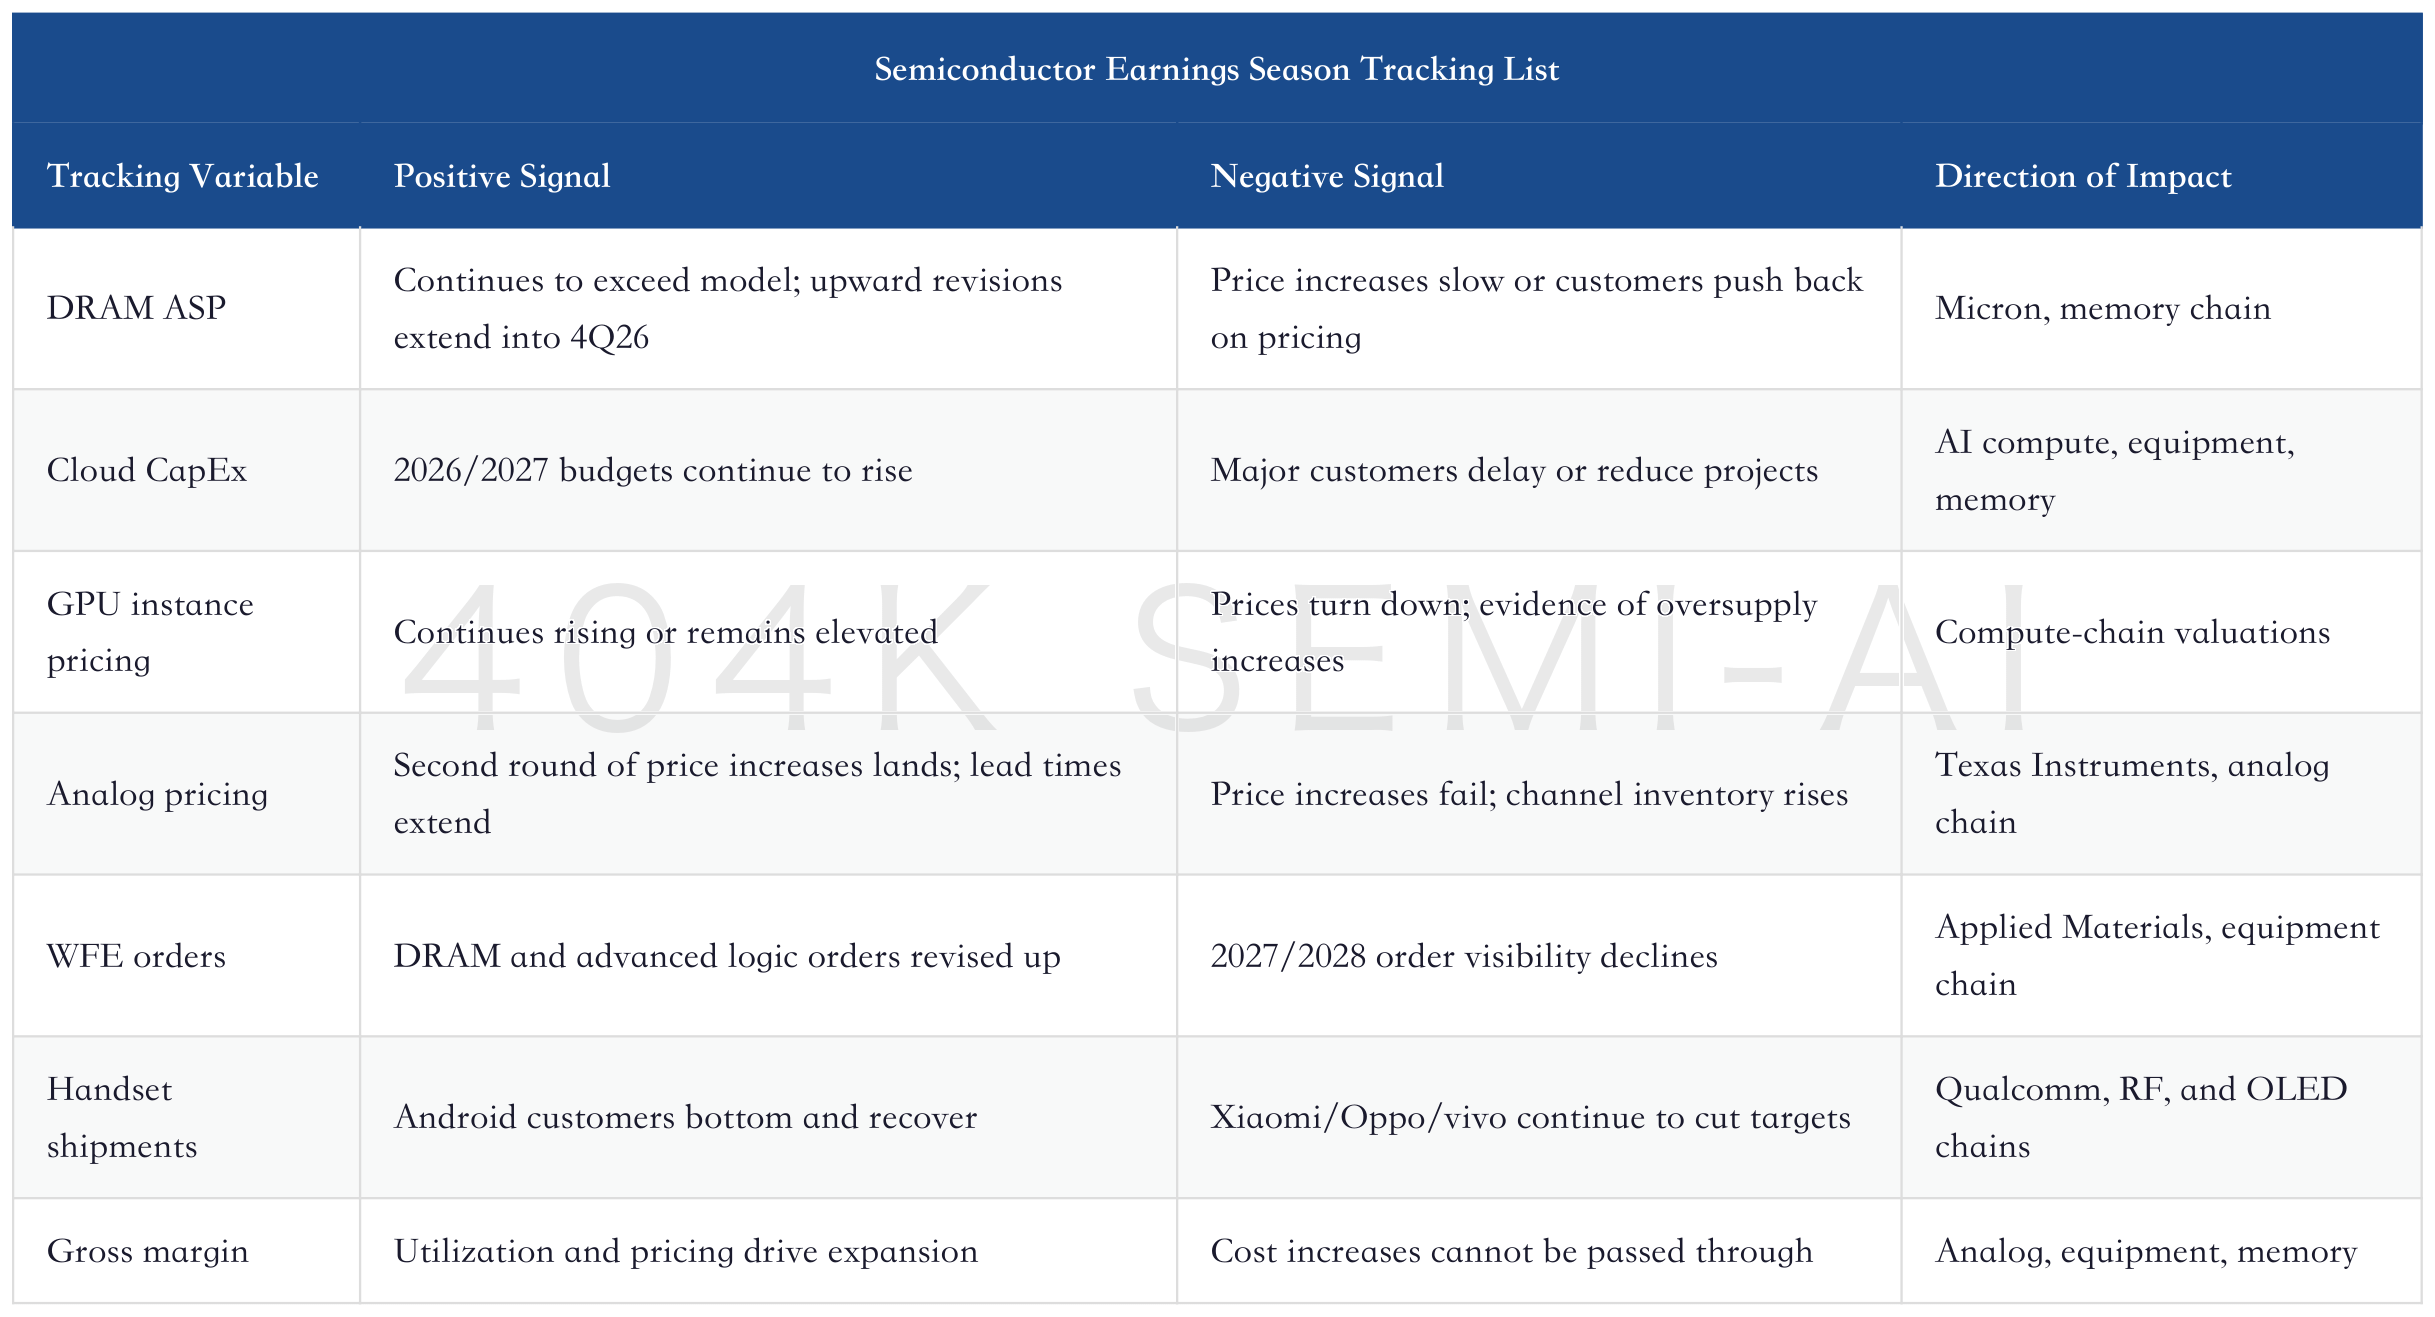
The easiest mistake in this trade is to put all AI-related stocks in the same basket. Citi’s report instead points to differentiation: memory and equipment are seeing strong upward revisions, analog is entering recovery, AMD has share validation, while Qualcomm and the handset RF chain face downside. The semiconductor index can remain strong, but returns within it will become more concentrated.
IX. The Earnings Models for Five Asset Classes Have Already Diverged
The most important change in this U.S. semiconductor earnings season is that different earnings models have emerged under the same AI theme. Memory earns from pricing; compute earns from share; analog earns from gross margin; equipment earns from order visibility; the handset chain must first work through downside revision risk. If these stocks are still grouped into one “AI semiconductor” basket, the post-earnings divergence in strength will be hard to see.
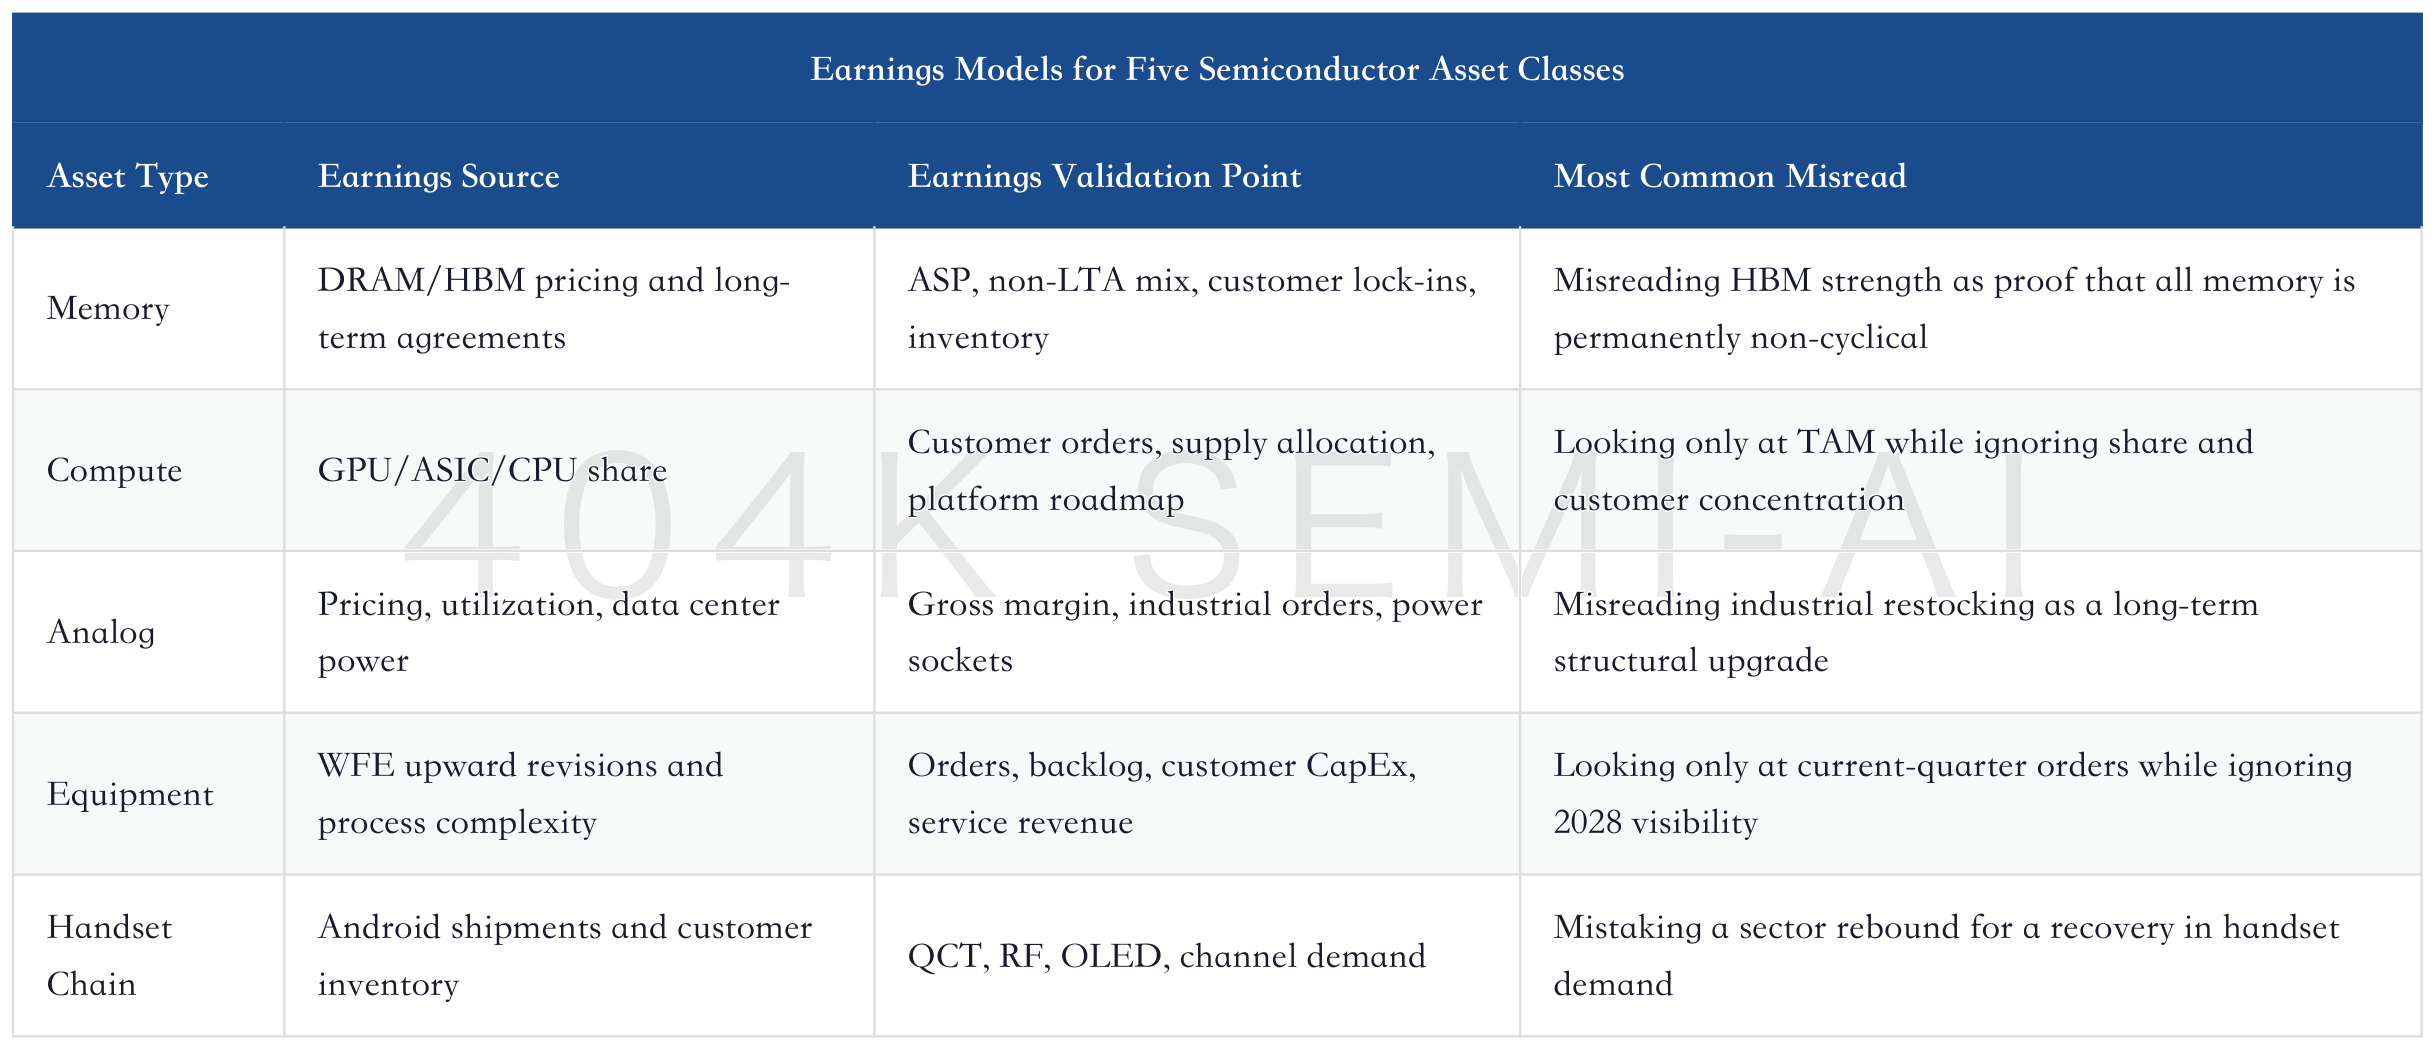
The earnings model for memory is the most direct. Rising DRAM prices first flow into revenue, then into profit through the high fixed-cost structure. Micron is distinctive because it has a relatively high share of non-LTA sales, so upward pricing revisions affect the current-quarter and next-quarter models faster. HBM has lifted the valuation narrative, but ordinary DRAM price increases are the engine of near-term EPS leverage. If earnings only prove that HBM is strong while ordinary DRAM pricing starts to soften, the stock’s upside will be below what the market imagines.
The earnings model for the compute chain is more complex. Nvidia remains the highest-quality asset, but this Citi report focuses more on diffusion: AMD takes GPU share and CPU platform opportunities; Broadcom takes custom ASIC; Marvell takes interconnect and custom silicon; Micron takes the memory constraint. The compute chain is not just about which company has the highest revenue exposure, but whose customer share is changing. AMD’s earnings must answer two questions: whether GPU share is truly increasing, and whether AI server CPUs can capture incremental demand from head nodes and agentic workloads.
The earnings model for the analog chain is the easiest to underestimate. Analog companies do not have explosive TAM like GPUs, but they can raise gross margin through pricing, capacity utilization, and product mix. The key for Texas Instruments is that its internal manufacturing ratio is high, so every step of utilization improvement makes margin leverage clearer. If share in Nvidia’s power supply chain begins to contribute, Texas Instruments will shift from a traditional industrial-cycle recovery into a lower-volatility beneficiary of the AI power chain.
The earnings model for the equipment chain is the most time-dependent. Equipment revenue is not recognized as immediately as cloud software revenue, nor is it reflected in gross margin as quickly as memory pricing. It depends on orders, backlog, customer capital expenditure, and process roadmaps. Applied Materials, Lam Research, and KLA are not benefiting from the same equipment cycle. Applied Materials benefits from broad-based equipment and services; Lam from etch/deposition and memory process migration; KLA from process control and yield complexity. Looking only at total WFE would miss the differences in mix.
The handset chain’s earnings model is negative validation. Qualcomm, Qorvo, Skyworks, and Universal Display are not devoid of long-term value, but the focus this earnings season is whether Android customers continue to cut orders. If target reductions at Xiaomi, Oppo, and vivo feed through to orders, Qualcomm’s QCT business and the RF chain will remain under pressure. Relative resilience in the Apple chain can provide some buffer, but it cannot replace the volume of the entire Android ecosystem.
X. What to Ask on Earnings Calls: Don’t Ask About AI, Ask About Pricing and Supply
The questions in this earnings season cannot stop at “How is AI demand?” Every company will say AI demand is strong. The genuinely informative questions are about pricing, supply, customers, and margins. The value of this Citi report is that it pulls the discussion back from macro narrative to verifiable operating indicators.
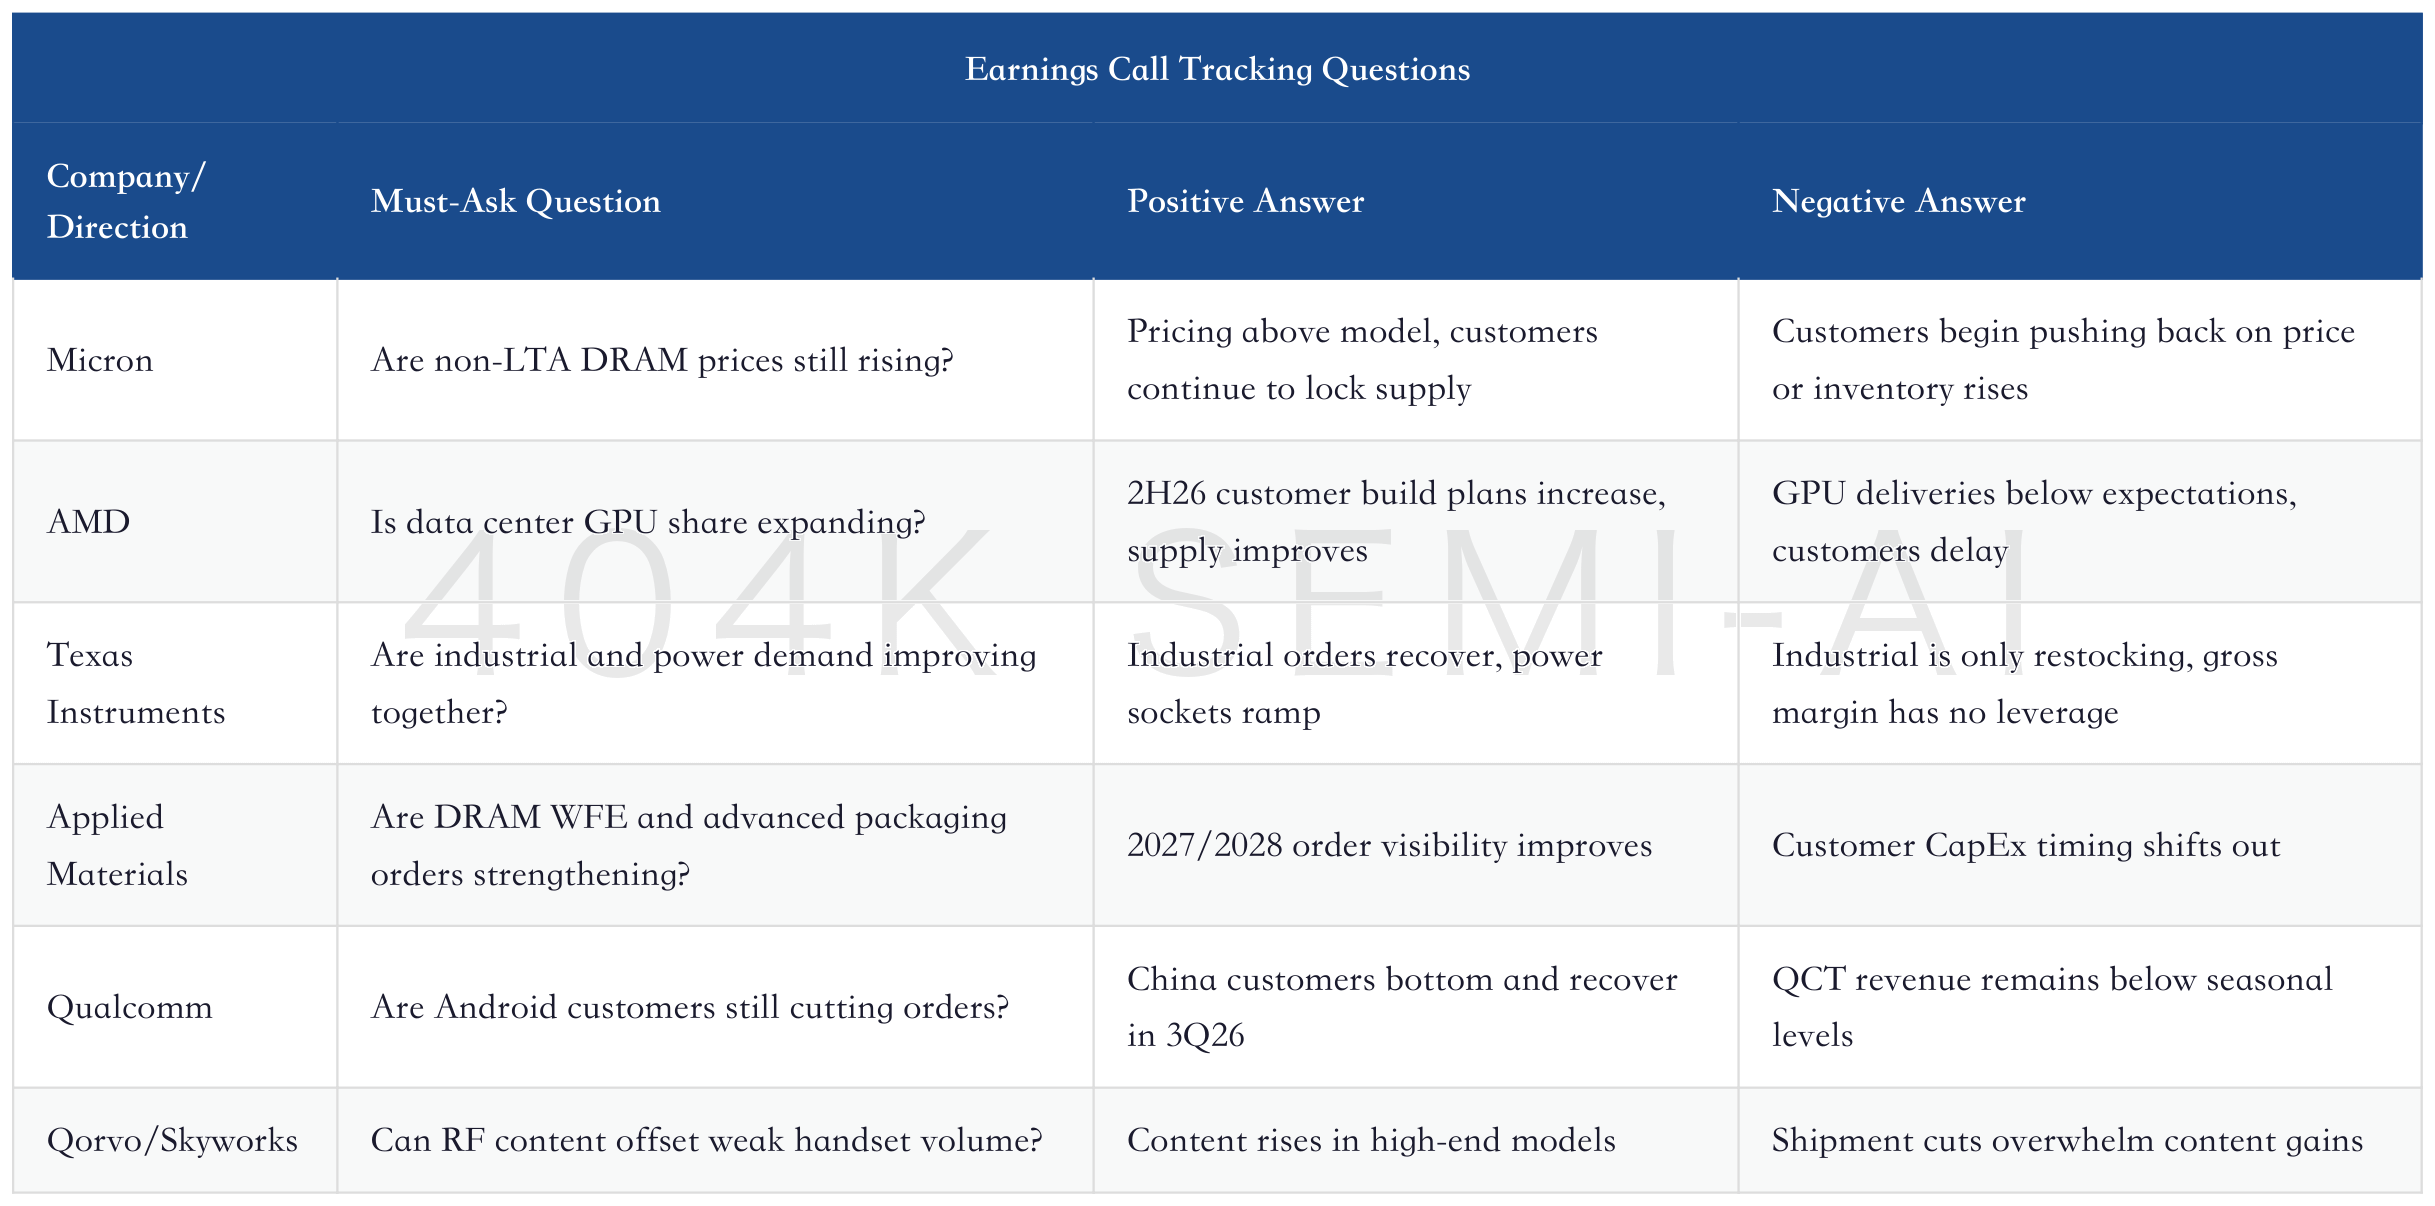
In Micron’s call, the key issue is pricing, not the phrase “AI demand is strong.” If management confirms that DRAM spot and contract prices continue to rise, customers’ willingness to lock supply remains high, and both HBM and ordinary DRAM are tight, the memory chain still has room for EPS upgrades. If management starts emphasizing customer inventory, pricing negotiations, and the pace of capacity expansion, the market will immediately recalculate 2027 profit.
In AMD’s call, the key issue is share. The market already knows AI server demand is strong and that Nvidia remains ahead. AMD needs to prove whether it can gain more GPU share in 2H26 while embedding CPU platform value into AI clusters. If the number of GPU customers increases, supply constraints ease, and the MI-series roadmap is clear, AMD can continue to move beyond the valuation framework of the PC cycle.
In Texas Instruments’ call, the key issue is gross margin. Sequential improvement in industrial is not enough, because many analog companies can benefit from industrial recovery. Texas Instruments must prove two things: first, that pricing and utilization improvement can flow into gross margin; second, that the AI data center power business is not small-scale noise, but an incremental driver that can affect the revenue structure over the next several years.
In Applied Materials’ call, the key issue is 2027 and 2028. Single-quarter order strength will affect near-term trading, but the real valuation anchor for equipment stocks lies in the next two years. If customers remain committed to capital spending on DRAM, advanced logic, advanced packaging, and foundry expansion, the market will continue to assign high visibility to equipment stocks. If customers begin pushing orders out, WFE upward revisions will be discounted first.
In Qualcomm’s call, the key issue is the Android bottom. Citi’s downside watch is not because Qualcomm lacks a long-term AI story, but because its near-term handset business is too heavy. If management cannot provide evidence that Chinese customers are bottoming and recovering, the market will continue to treat Qualcomm as a handset-downcycle asset rather than a data center or edge AI asset.
XI. Scenario Framework: A Strong Market Has More Than One Path
Semiconductor earnings season could produce three scenarios. The strongest scenario is that memory, analog, and equipment all see upward revisions, while handset-chain cuts are treated by the market as a localized issue. The neutral scenario is that the AI chain remains strong, but pricing and orders diverge. The weak scenario is that cloud capital expenditure or memory pricing starts to soften, causing the AI diffusion trade to contract.
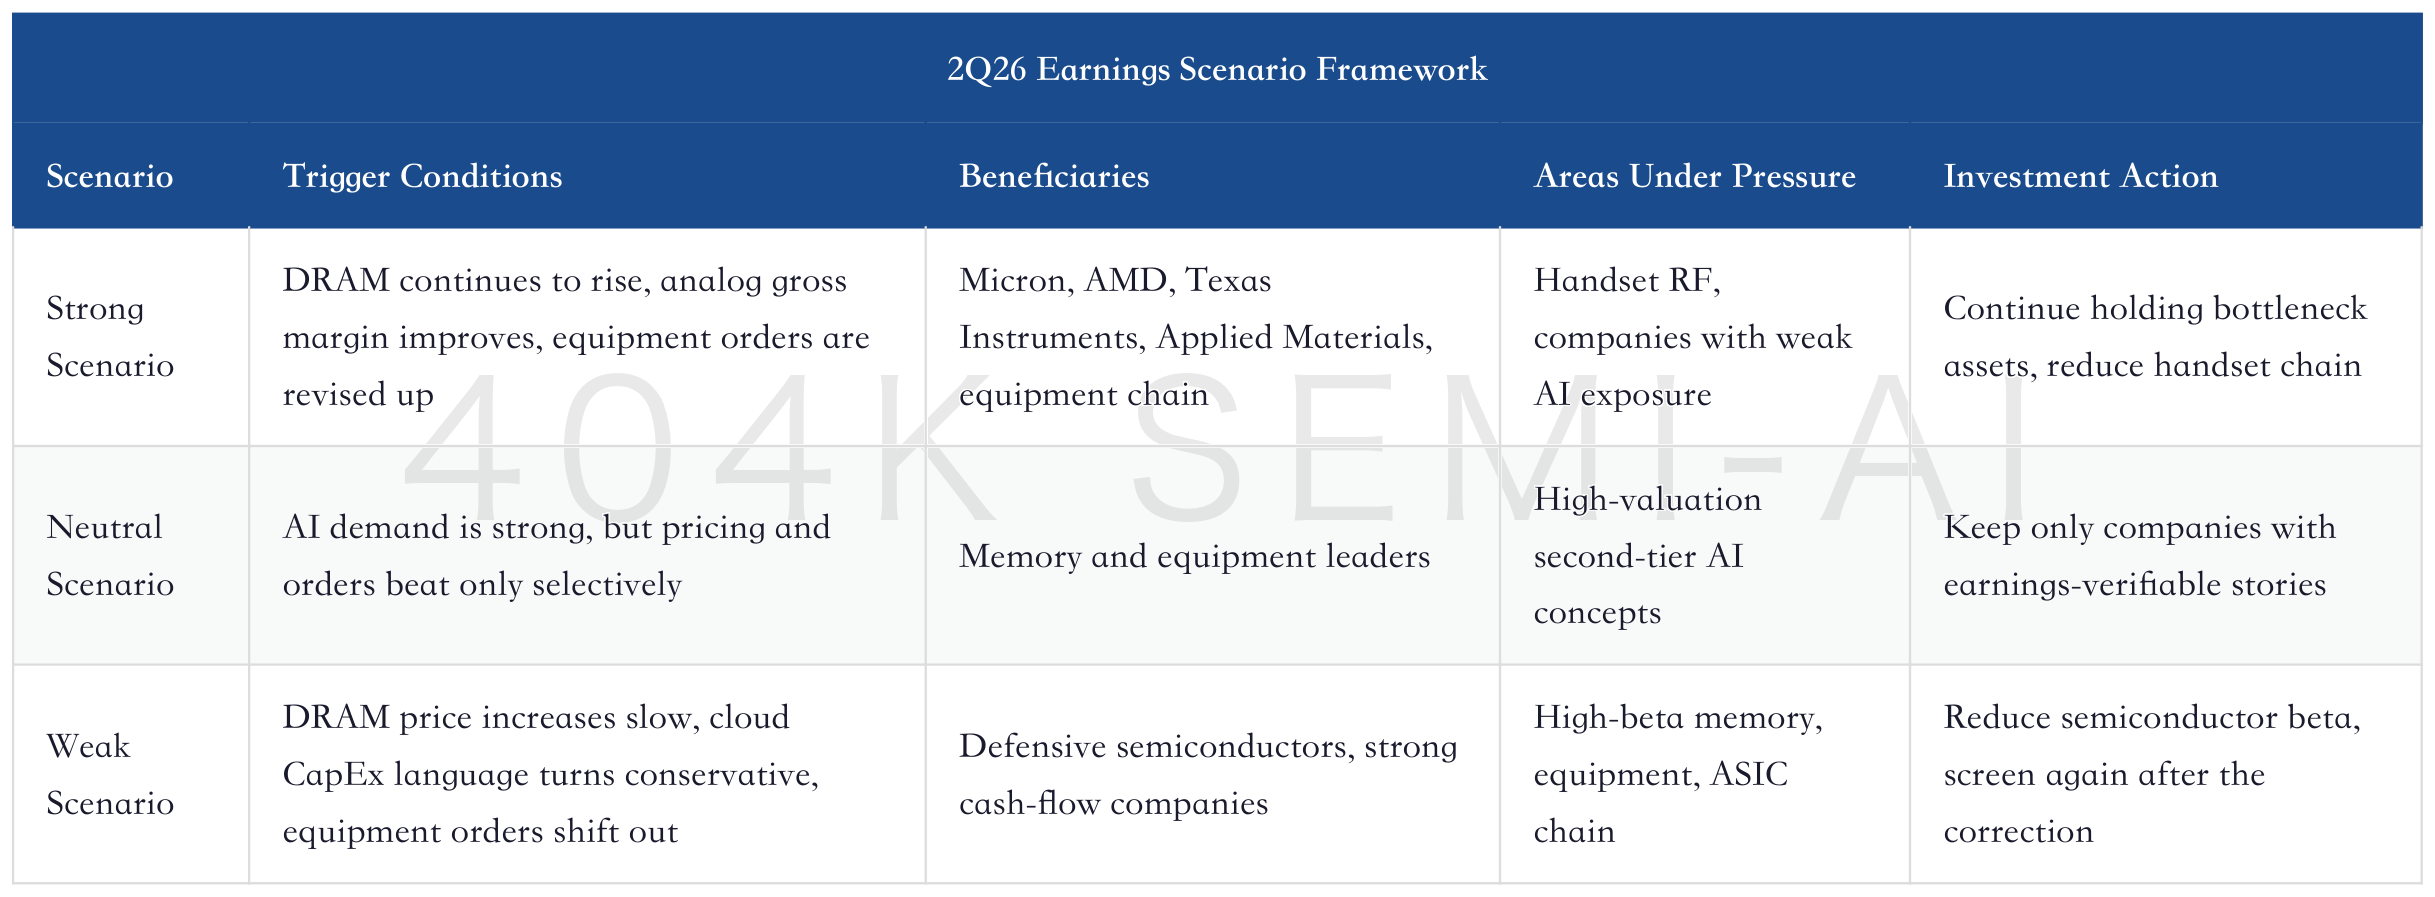
In the strong scenario, the market will not buy only Nvidia. Capital will continue diffusing into Micron, AMD, Applied Materials, Texas Instruments, and the broader equipment/power chain. The reason is that the strong scenario would show AI demand penetrating multiple profit pools, rather than remaining limited to GPU orders. In that environment, the stocks with the most post-earnings leverage are often the bottleneck assets that did not fully rerate in the previous leg.
In the neutral scenario, stock selection will be critical. AI demand remains strong, but not every company can keep rising. The market will ask: who can deliver next-quarter EPS upgrades, and who is merely repeating the industry TAM story? In memory, the focus is pricing leverage; in equipment, order visibility; in analog, gross margin; in compute, customer share. The neutral scenario is the most likely to eliminate second-tier AI concept stocks.
In the weak scenario, semiconductors will not lose their long-term theme because of one earnings season, but valuations will contract first. The most dangerous combination is: cloud-vendor CapEx guidance turns cautious, DRAM price increases slow, equipment orders shift out, and the handset chain continues to be revised down. If all four happen at once, the market will compress the AI semiconductor trade from “diffusion” back into a small number of the strongest companies, putting second-tier stocks under pressure.
The current setup is closer to somewhere between the strong and neutral scenarios. Citi’s data still supports tight AI supply, but share prices have already reflected many optimistic assumptions in advance. The key for the 2Q26 earnings season is not whether semiconductors have AI as a long-term theme, but whether near-term earnings upgrades can catch up with the share-price moves of the past few months.
XII. Valuation Is Not the Biggest Issue; Earnings Revisions Are
The SOX trades at roughly 19x FY2 earnings, broadly in line with the S&P; 500, which makes semiconductors look like they are not in an obvious bubble. But this valuation framework rests on one assumption: FY2 earnings must keep being revised upward. If EPS upgrades stop, 19x is not cheap; if EPS continues to be revised higher, 19x may still look reasonable.
Valuation should not be judged only by the absolute PE multiple. Among companies with AI data center exposure, Nvidia and Broadcom’s FY2 multiples are near two-year lows, while AMD and Marvell trade at higher multiples because the market is still buying share gains and long-term TAM. Analog valuations have already expanded because industrial recovery and the data center power chain have improved visibility. Handset-exposed companies trade at low valuations, but behind those low multiples is the risk of earnings downgrades. Equipment companies have already been re-rated, but if WFE really moves toward $250 billion, valuations still have fundamental support.
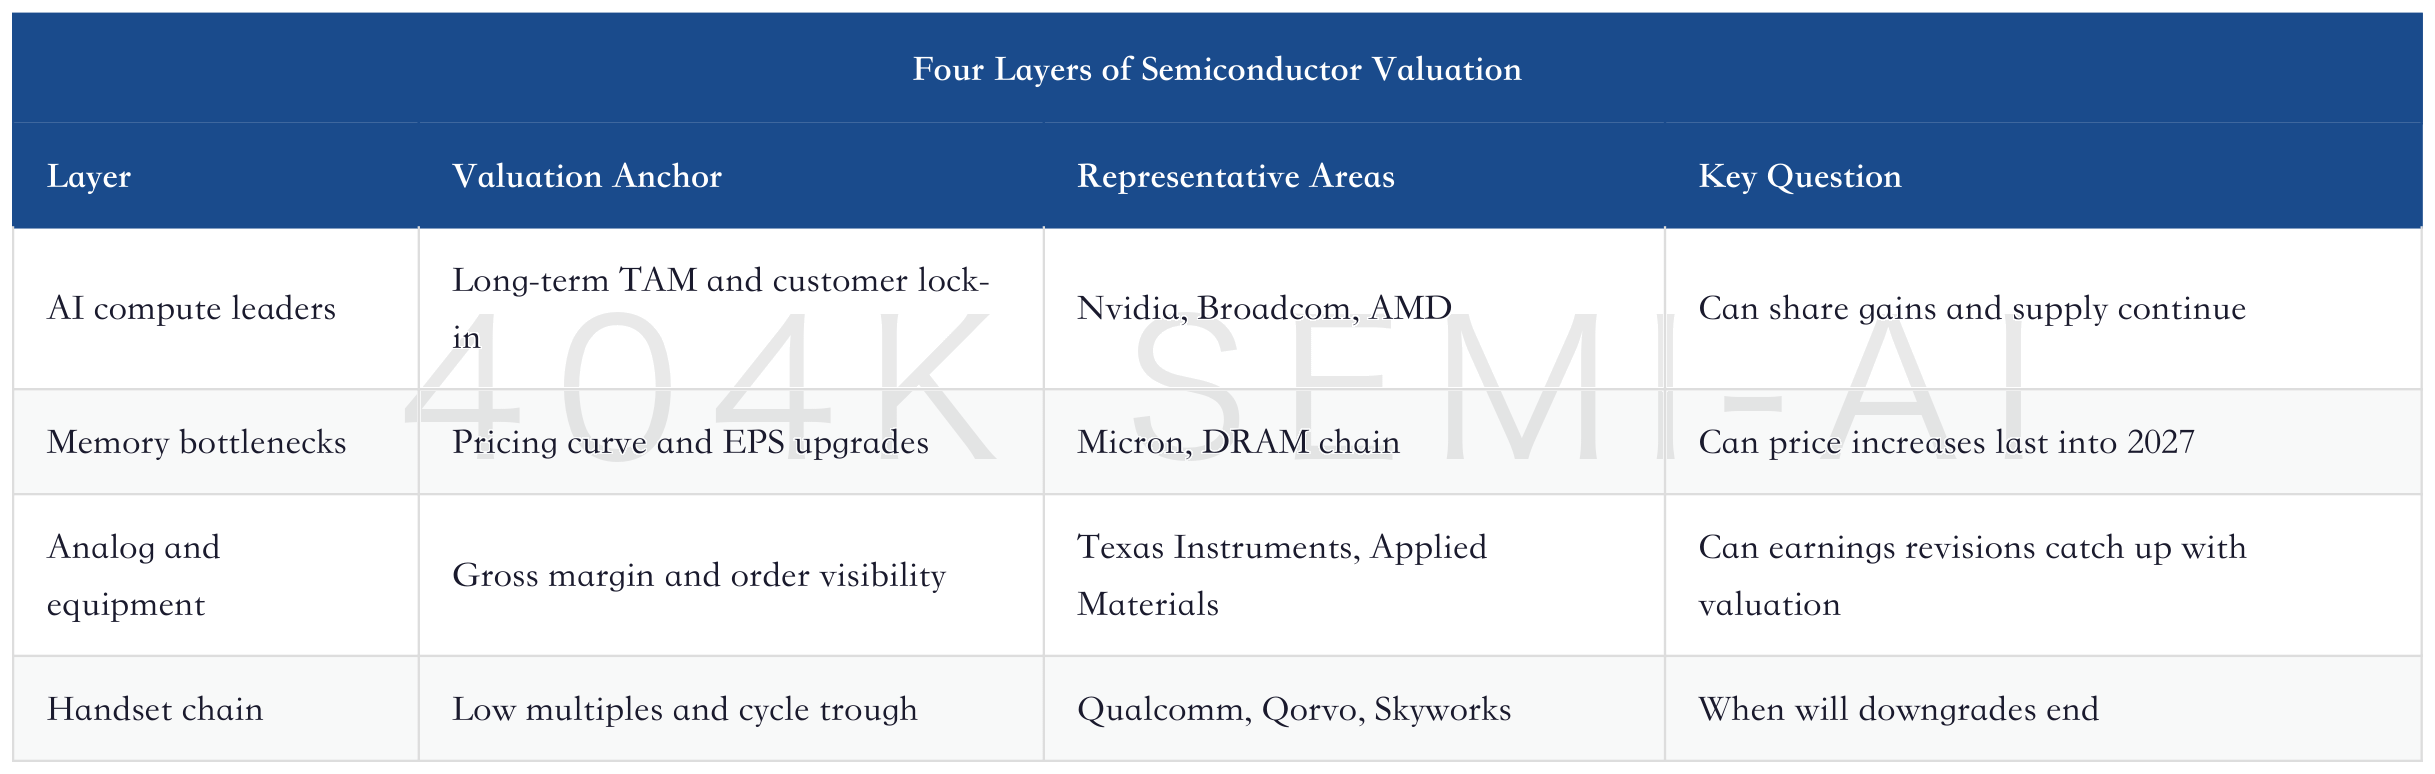
This shows valuation is not simply “expensive” or “cheap.” Micron looks like it has risen a lot, but if DRAM prices continue to be revised higher, EPS will keep lifting the denominator of valuation. Qualcomm looks optically cheap, but if the handset business keeps being revised lower, a low valuation is not a catalyst. The multiples for Applied Materials and Texas Instruments depend on visibility over the next two years, not whether current-quarter revenue slightly beats expectations.
For portfolio management, the most practical approach is to split semiconductor exposure into two parts. The first is long-term AI core exposure, which tolerates valuation volatility and focuses on cloud capex and customer roadmaps. The second is earnings-validation exposure, buying only companies where pricing, gross margin, orders, and share can be verified in the current quarter. 2Q26 is better suited to increasing the weight of the second bucket, because the market is no longer short of long-term stories.
XIII. Falsification Checklist: Signals That Would Show the Main Thesis Is Weakening
What semiconductor bulls fear most is not a share-price pullback, but a simultaneous deterioration in fundamental signals. A pullback can digest positioning; weaker fundamentals compress both valuation and earnings. After 2Q26, the most important things to track are not headlines, but several hard signals.
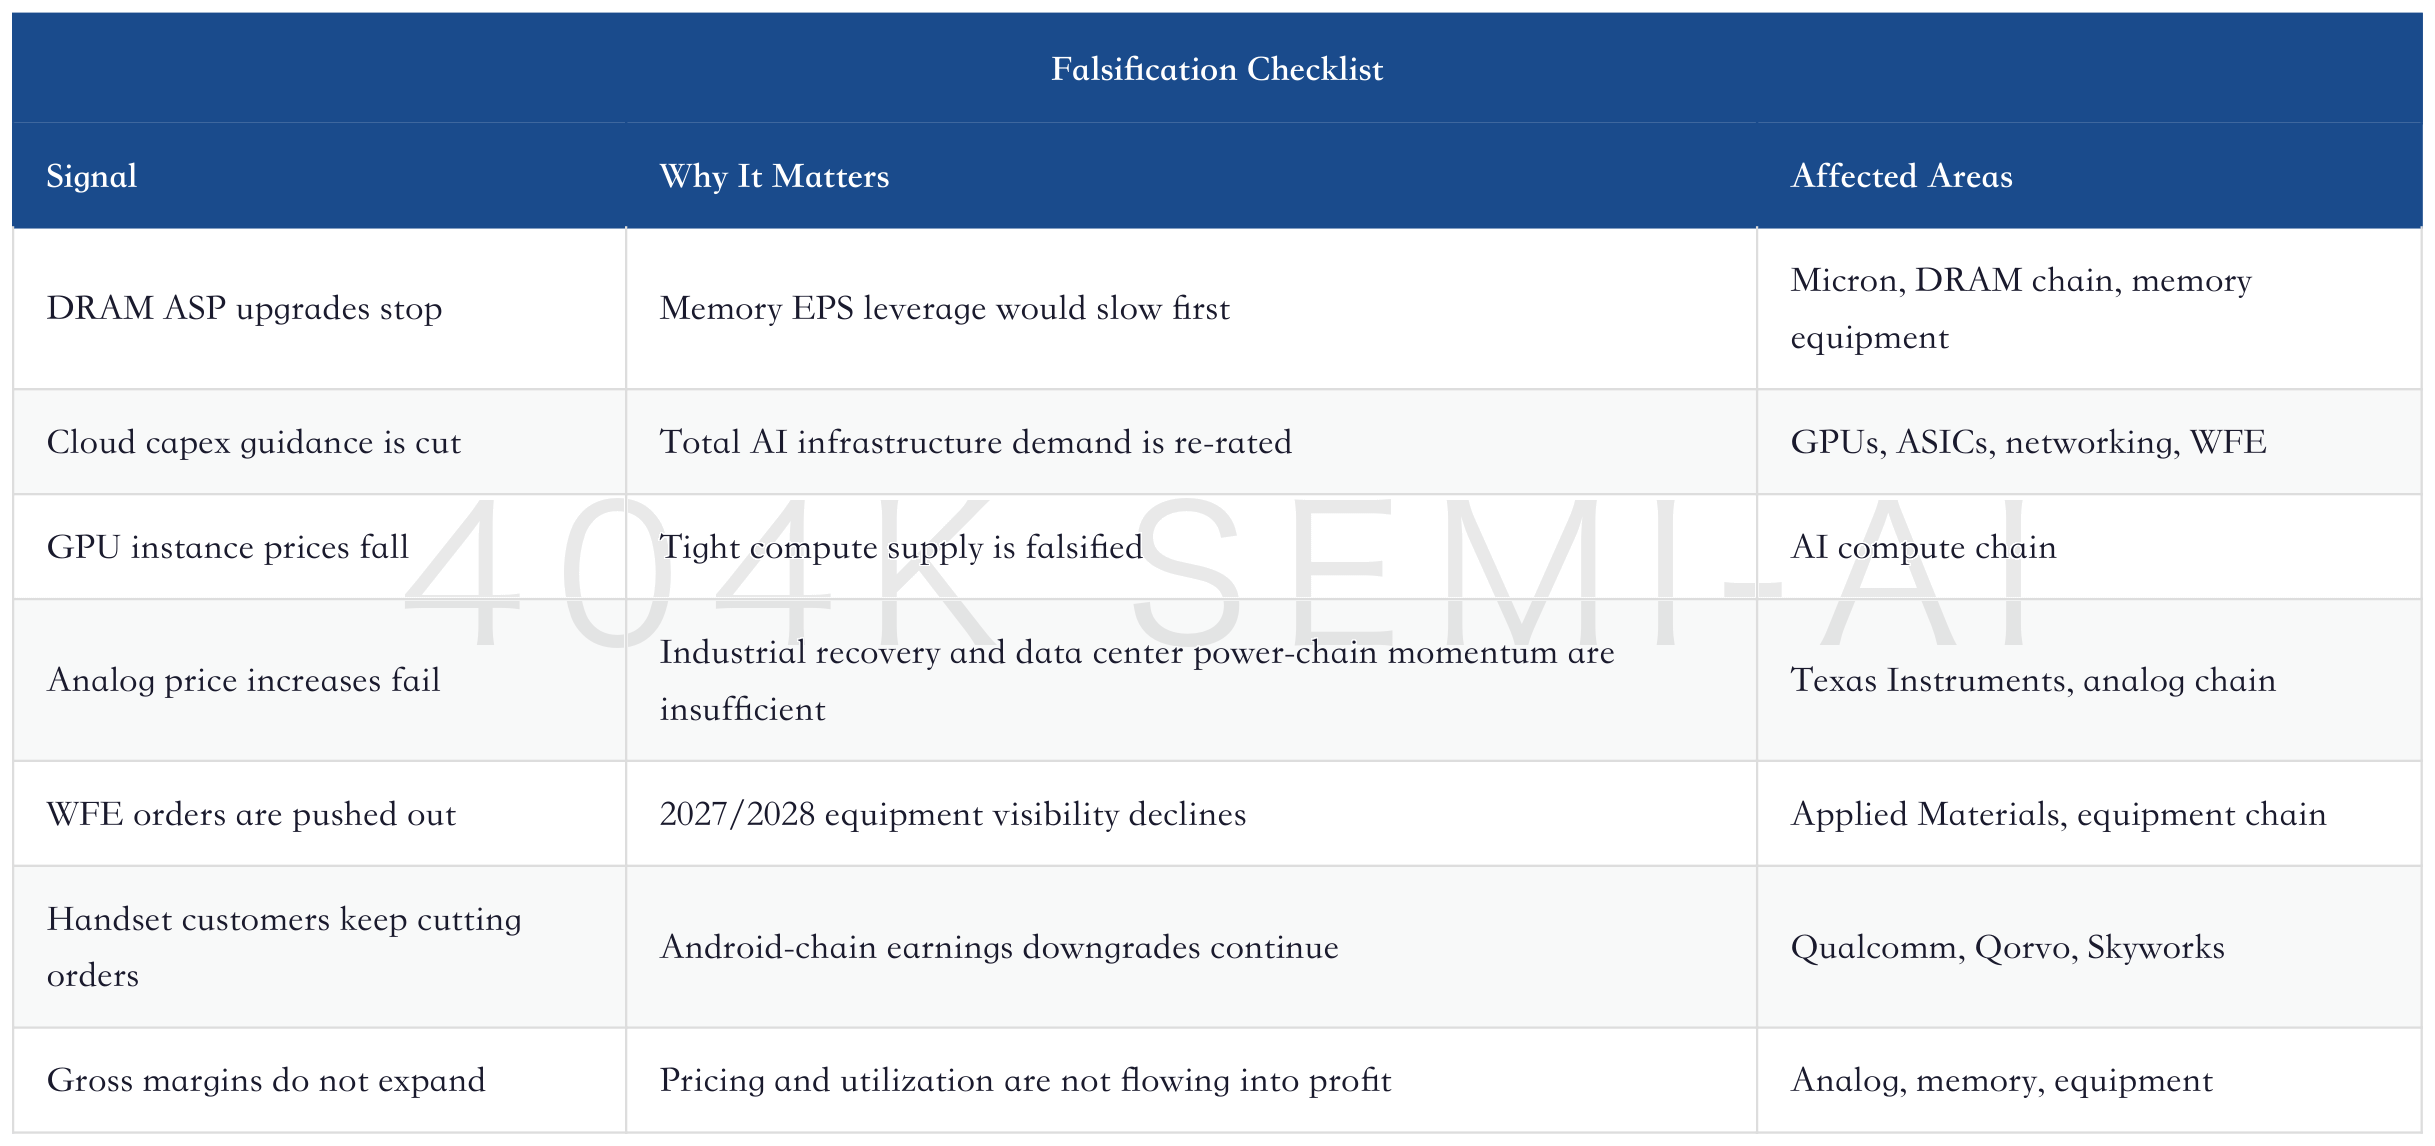
These signals should be assessed together. Weakness in a single variable does not necessarily mean the semiconductor thesis is over. For example, continued weakness in the handset chain would not directly overturn the data center and memory theses; a one-quarter delay in equipment orders may simply reflect changes in customer delivery timing. The real danger is multiple variables weakening at the same time, especially if DRAM pricing, cloud capex, and WFE orders all turn together.
Conversely, if DRAM prices keep rising, cloud capex remains strong, analog gross margins improve, and equipment order visibility extends, then even with handset-chain weakness, the semiconductor index still has a basis for sustained strength. The sector will diverge internally, but the main thesis will not end easily.
XIV. How This Citi Report Relates to the Recent Semiconductor Chain
Over the past month-plus, the semiconductor trade has been spreading from a single GPU story to bottleneck assets. First HBM and DRAM were re-priced, then WFE upgrades, equipment orders, analog power, and AI data center power supply entered the main narrative. Citi’s 2Q26 earnings preview concentrates these threads into one verifiable window: earnings season.
From HBM to WFE: How AI Is Turning the Memory Cycle into an Equipment Supercycle, and How Much Further Semiconductor Equipment Can Rise
The memory thread is already fairly clear. DRAM and HBM pricing upgrades, long-term agreements, supply discipline, and server demand together form Micron’s profit leverage. Citi’s inclusion of Micron on its upside watch is earnings-catalyst confirmation for this thread. The difference is that the market previously focused more on the long-term memory supercycle; this time, the key is whether EPS is revised higher for the current and next quarters.
