
TSMC 2Q26 Earnings Preview: Can NT$1.27tn Revenue, a Nearly 70% Gross Margin, and N2 Capacity Expansion All Deliver?
目录
TL;DR
NT$1.27tn Has Already Provided the Revenue Answer
The Gross-Margin Debate: 67.4% Meets Expectations; 69.5% Marks a New Threshold
Why EPS Cannot Substitute for Gross Margin Analysis
3Q Must Not Only Sustain High Revenue but Also Defend a High-60% Margin
The Real Full-Year Growth Threshold Has Shifted from Above 30% to Around 37%
Whether Capex Is Positive or Negative Depends on Returns on Assets, Not the Total
2027 Pricing Is the Balancing Valve in the Capacity Expansion Model
The 600,000-Wafer N3 Shortfall and 75%–80% N2 Yield Need to Be Translated into a Verifiable Construction Timeline
The CoWoS Question Has Shifted from “Is Capacity Available?” to “Can Qualified Output Be Delivered?”
High-50%, 60%, and 69% AI Growth Do Not Use the Same Denominator
Valuation Is No Longer Just About Whether Results Are Good, but How Much Good News Is Already Priced In
Three Earnings Scenarios: A True Beat Must Include Both Profits and the Outlook
After the Earnings Release, Check These Eight Questions in Order
The Risk Is Not That AI Demand Suddenly Disappears, but That the Positive Factors Cannot All Hold Simultaneously
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
TSMC’s 2Q26 revenue is already locked in by monthly data. The latest July 13 views from BofA and Morgan Stanley point to the same tension: 3Q revenue remains strong, but a nearly 70% gross margin is already above the sell-side baseline. The key question is whether capital expenditure can generate returns from N2, N3, and advanced packaging.
TL;DR
Whether revenue beats expectations is no longer the main issue for this earnings report. TSMC’s April–June revenue totaled NT$1.2704tn, equivalent to approximately US$40.075bn using the company’s original guidance exchange rate of 31.7, already near the top of its US$39.0bn–US$40.2bn range. Morgan Stanley, JPMorgan, and BofA’s 2Q revenue forecasts in New Taiwan dollars differ by only approximately 0.6%. The real variables to trade are margins and forward guidance.
The two latest reports do not validate a 69%–70% gross margin; instead, they turn it into a stress test. BofA forecasts a 2Q gross margin of 67.7%, while Morgan Stanley maintains 67.4%, both close to the high end of company guidance. JPMorgan’s 69.5% remains the most optimistic scenario. BofA also expects N2 volume production to dilute gross margin by 2–3 percentage points in 2H26. On July 13, Morgan Stanley likewise said buy-side expectations of a 69%–70% gross margin in 3Q were too high, versus its own forecast of only 67%–68%.
3Q revenue momentum offers more incremental information than 2Q revenue. JPMorgan forecasts 8%–10% sequential growth in 3Q US-dollar revenue, while the latest estimates from BofA and Morgan Stanley are both 10%–15%. Their respective point estimates for revenue in New Taiwan dollars are NT$1.4188tn and NT$1.4359tn. Yet all three firms cluster around a 67%–68% gross margin for 3Q, showing that the real market debate is whether strong revenue can absorb N2, overseas fabs, and depreciation—not whether demand remains strong.
Consensus on capital expenditure has formed; the difference lies in capacity-expansion efficiency. Morgan Stanley forecasts US$56bn in 2026 and US$75bn in each of 2027 and 2028, totaling US$206bn over three years. BofA forecasts US$58bn, US$78bn, and US$83bn, while JPMorgan expects US$58bn, US$78bn, and US$84bn. Simply “spending more” is not bullish. Capital expenditure represents future revenue rather than future depreciation only if the N3 capacity shortfall, N2 customers, 2027 pricing, and medium- to long-term agreements are all confirmed.
The two new reports add a verifiable volume-and-pricing bridge. BofA forecasts a 31% increase in blended wafer ASP in 2026, 10%–15% price increases for both 5nm and 3nm, 23% shipment growth at advanced nodes, and an 8% decline in mature-node shipments. Morgan Stanley raises its five-year CAGR forecast for AI semiconductors to 70%, while cautioning that expectations for non-AI inventories, foundry competition, and a nearly 70% gross margin may be too optimistic. The post-earnings outcome must still be assessed by connecting five figures: 2Q gross margin, 3Q guidance, full-year US-dollar revenue, capital expenditure, and the company’s AI definition.
NT$1.27tn Has Already Provided the Revenue Answer
TSMC will hold its 2Q26 earnings call at 14:00 on July 16. Unlike most companies, TSMC reports revenue monthly, making quarterly revenue highly transparent before earnings. April revenue was NT$410.726bn, May revenue was NT$416.975bn, and June revenue was NT$442.680bn, totaling NT$1.2704tn. This represents approximately 12.0% sequential growth and approximately 36.0% year-on-year growth.
Using the exchange-rate assumption of 31.7 provided with the company’s 1Q26 guidance, 2Q revenue equates to approximately US$40.075bn, just US$125mn below the top of the US$39.0bn–US$40.2bn guidance range. It is also only approximately 0.4% below JPMorgan’s US$40.248bn forecast and slightly above Morgan Stanley’s NT$1.2666tn estimate. BofA’s latest model forecasts NT$1.2744tn, only 0.3% above the reported monthly total. The actual quarterly average exchange rate may differ from the guidance assumption, so final US-dollar revenue could vary slightly. Nevertheless, the direction is clear: quarterly revenue is at the high end of the company’s range.
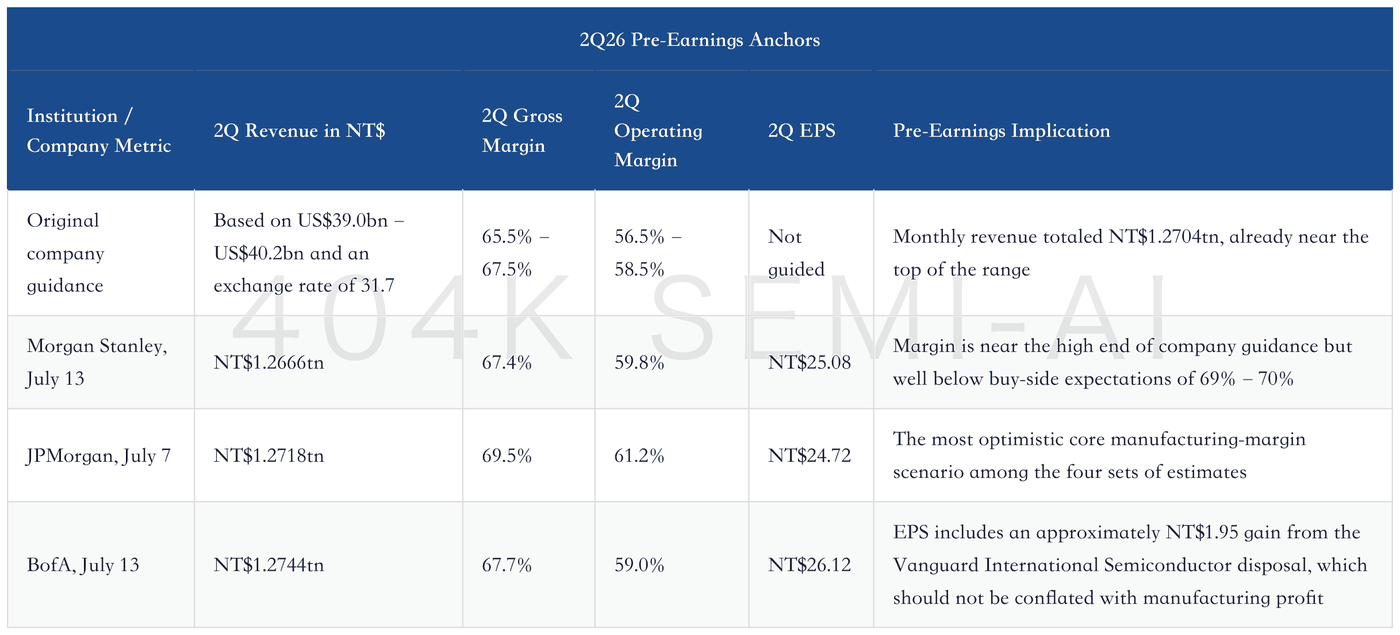
The table also explains why a “revenue beat” should not be interpreted in isolation. Monthly revenue has already shown the market that total wafer shipments and product mix are strong. The earnings report must provide further upside in gross margin, operating margin, and guidance to demonstrate that this revenue is not only “higher,” but also “higher-priced,” “stable,” and “repeatable.”
The Gross-Margin Debate: 67.4% Meets Expectations; 69.5% Marks a New Threshold
Morgan Stanley and JPMorgan have nearly identical revenue forecasts but present two entirely different gross-margin scenarios. Morgan Stanley forecasts 67.4%, essentially at the top of company guidance. JPMorgan forecasts 69.5%, implying that TSMC must improve by another 3.3 percentage points from 1Q26’s 66.2%. With overseas fabs continuing to dilute margins, N2 preparing for volume production, and capital expenditure remaining elevated, this is a very demanding threshold.
BofA’s July 13 forecast of 67.7% further indicates that the latest sell-side baseline remains 67%–68% and has not collectively moved toward 70%. Morgan Stanley’s July 13 feedback from 30–40 US investors showed that the buy side had raised its 3Q gross-margin expectation to 69%–70%, while Morgan Stanley itself still forecasts only 67%–68%. Accordingly, 69.5% is better viewed as an upside stress test than the minimum operating threshold the company must achieve.
BofA quantifies the main 2H26 headwind as 2–3 percentage points of gross-margin dilution from the N2 ramp, with the impact concentrated in the second half. Excluding N2, it believes 2H26 gross margin could reach the low 70% range. This breakdown makes the post-earnings assessment clearer: a gross margin of 67%–68% may simply reflect new-node costs entering the income statement as planned. It would indicate a genuine deterioration in earnings quality only if accompanied by weaker-than-expected 3Q revenue, delayed N2 yield progress, or rising overseas-fab costs.
JPMorgan’s optimistic view rests primarily on four factors. First, leading-edge capacity remains supply-constrained, utilization is high, and fixed costs are spread across greater wafer shipments. Second, expedite premiums paid by customers to secure wafers earlier can directly raise average selling prices. Third, improved N3 yields and efficiency following the ramp could lift its gross margin above the company average in 2H26. Fourth, a rising high-performance-computing share within N3 improves product mix beyond what wafer volumes alone indicate.
However, even an actual result of only 67.4% would not mean that operations have deteriorated. This figure would remain near the top of original guidance, stand 1.2 percentage points above 1Q26, and significantly exceed the company’s long-term through-cycle target of more than 56%. It would merely indicate that JPMorgan has already incorporated most of the anticipated benefits from utilization, expedite premiums, and N3 improvements into its forecast, raising the market’s definition of a “good” result.
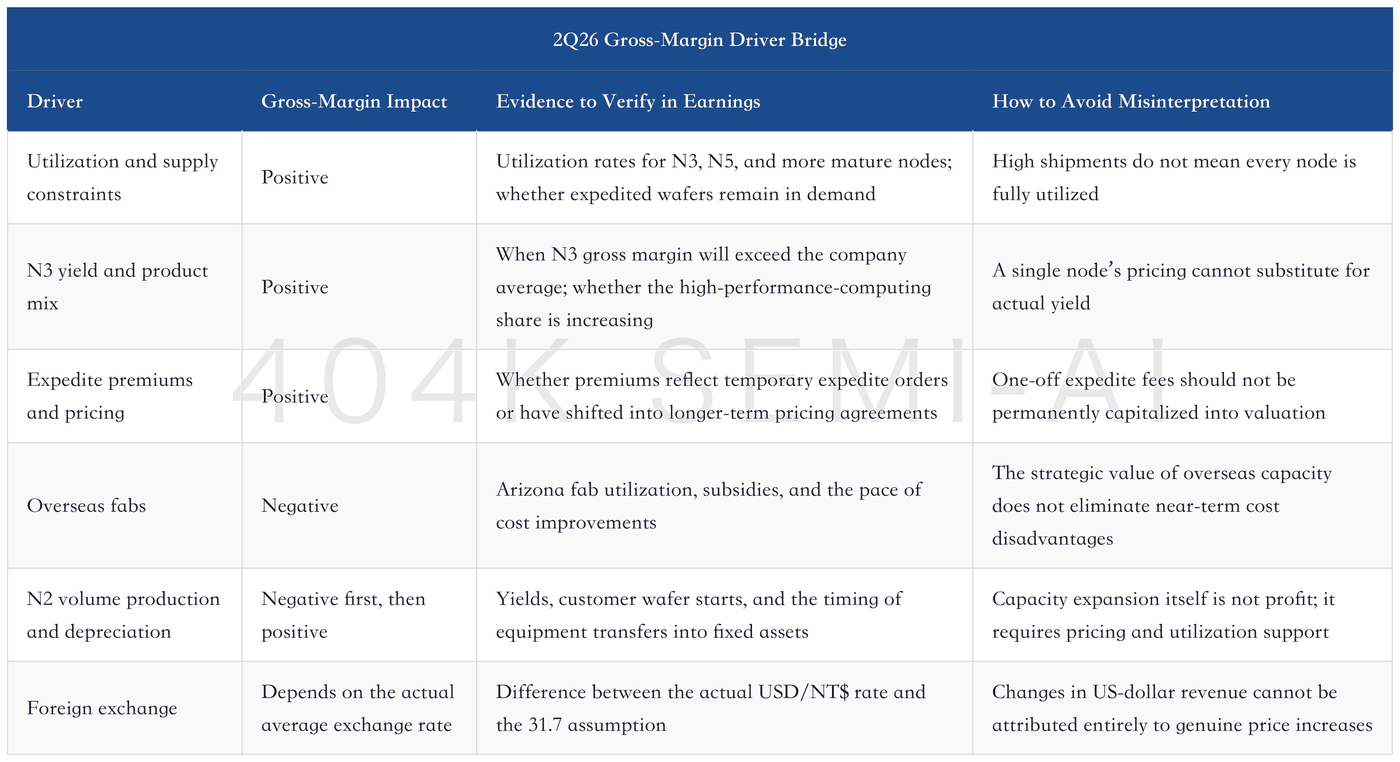
The most important information on earnings day will be whether management can clearly explain the composition of gross margin. If a figure near 70% comes mainly from one-off foreign-exchange effects or expedite fees, its sustainability will be weaker than the headline number suggests. If it is jointly driven by higher N3 margins, stronger long-term pricing, and high utilization, then even some 3Q pullback due to N2 and overseas fabs would not undermine the medium-term margin anchor.
Why EPS Cannot Substitute for Gross Margin Analysis
One phenomenon in the three institutions’ forecasts warrants separate analysis: Morgan Stanley projects a 2Q gross margin of only 67.4%, below JPMorgan’s 69.5%, yet its EPS estimate of NT$25.08 is higher than JPMorgan’s NT$24.72. BofA has the lowest gross-margin estimate at 67.7% but the highest EPS estimate at NT$26.12, because its model includes an approximately NT$1.95 one-off gain from the sale of Vanguard International Semiconductor shares. Mechanically excluding this gain, operating EPS would be approximately NT$24.17, below the other two estimates. This divergence shows that EPS is affected not only by gross margin, but also by operating expenses, non-operating items, tax rates, foreign exchange, and share-count assumptions. Looking only at the bottom line can easily lead investors to mistake non-core gains for improved profitability in the foundry business itself.
The post-earnings review sequence should be standardized. First, determine whether revenue is consistent with monthly data, excluding currency translation and accounting adjustments. Next, examine gross profit and gross margin to assess wafer pricing, product mix, yields, and utilization. Then review operating margin to determine whether R&D;, SG&A;, and overseas expansion costs have absorbed gross profit. Only then should investors examine EPS and explain tax rates, non-operating items, and share count. This sequence separates “improvement in manufacturing operations” from “improvement in the reported bottom line.”
Operating margin is particularly important. The company’s original guidance was 56.5%–58.5%, while Morgan Stanley forecasts 59.8%, JPMorgan 61.2%, and BofA 59.0%. If actual gross margin is close to 69.5% but operating margin does not exceed 60%, this would indicate additional spending on the cost side. If gross margin is around 67.5% but operating margin approaches 60%, cost control and operating leverage would be stronger than expected. These two combinations have entirely different implications for 3Q and full-year earnings.
EPS also needs to be cross-checked against cash flow. The timing of TSMC’s depreciation, equipment payments, and customer prepayments can create short-term divergences between earnings and cash flow. Quarterly EPS above NT$25 would certainly be positive, but if free cash flow is simultaneously squeezed by rapidly rising capital expenditure, the valuation should still incorporate a discount for capital returns. Conversely, if quarterly tax rates or foreign exchange weigh on EPS while gross margin, operating margin, and operating cash flow remain strong, a modest bottom-line miss should not be amplified into an operational inflection point.
3Q Must Not Only Sustain High Revenue but Also Defend a High-60% Margin
The first genuinely new data point from this earnings call will be 3Q26 guidance. JPMorgan expects the company to guide for 8%–10% sequential US-dollar revenue growth and a gross margin of 67%–68%. Its model estimates revenue of US$44.01 billion, a 67.6% gross margin, a 59.3% operating margin, and EPS of NT$27.39. Morgan Stanley’s latest report, dated July 13, forecasts 3Q revenue of NT$1.4359 trillion, up 13.4% sequentially, with a 67.5% gross margin, a 60.3% operating margin, and EPS of NT$29.21. BofA forecasts revenue of NT$1.4188 trillion, up 11.3% sequentially, with a 67.8% gross margin, a 59.4% operating margin, and EPS of NT$28.15.
The three institutions’ 3Q gross-margin forecasts are almost identical, clustering between 67.5% and 67.8%, but they differ on revenue, operating margin, and EPS. This suggests that the sell-side base case does not support the buy side’s expectations for a 69%–70% gross margin. The real disagreement is whether demand will be strong enough for higher revenue to continue absorbing dilution from N2, overseas fabs, and operating expenses. Both Morgan Stanley and BofA place the upper end of sequential revenue growth at 15%, meaning that growth above 10% has moved from an “extreme bull case” into the latest base-case range.
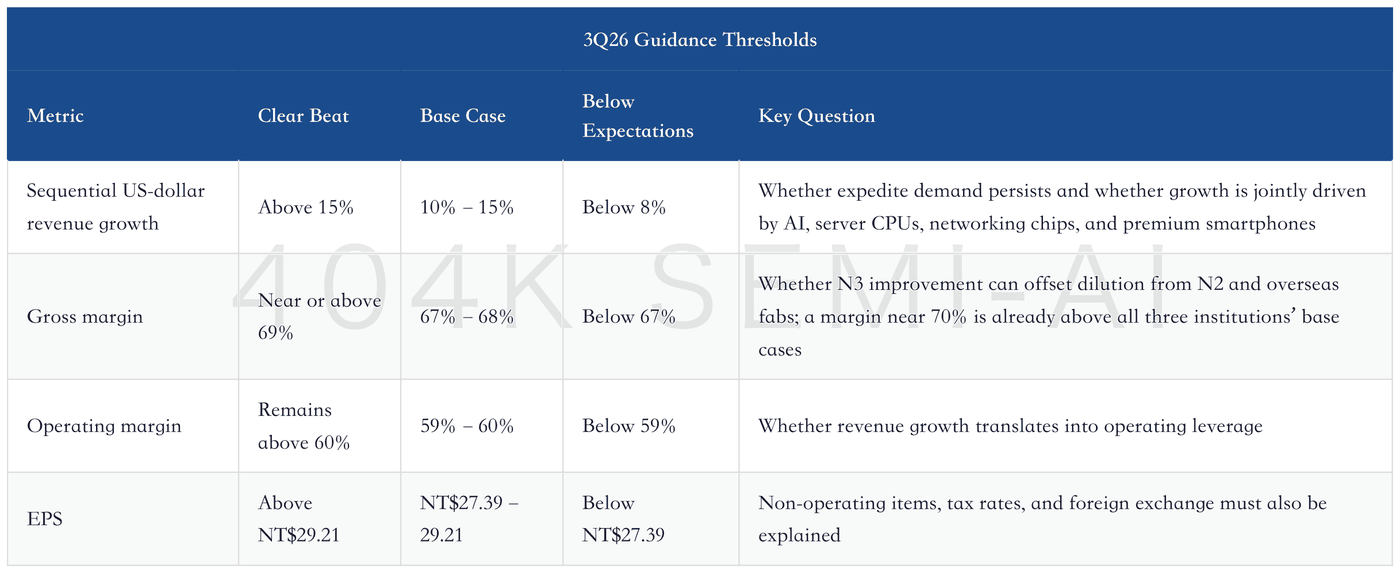
The easiest scenario to misinterpret would be 3Q revenue guidance of 10%–15% growth combined with a gross margin below 67%. This would not constitute a straightforward positive or negative. It would mean that TSMC is deploying greater capacity to meet demand, but the costs and depreciation of new capacity are rising faster than unit-value improvement. If the market is already assigning a premium valuation, this type of “high-revenue, low-quality” growth would be insufficient to support another round of multiple expansion.
The Real Full-Year Growth Threshold Has Shifted from Above 30% to Around 37%
On its 1Q26 earnings call, TSMC raised its 2026 US-dollar revenue-growth outlook to above 30% and explicitly stated that it would provide a more precise figure in July. With first-half revenue and strong June data now available, simply reiterating “above 30%” would no longer constitute an incremental positive.
JPMorgan expects management to raise its US-dollar revenue-growth outlook to the mid-to-high 30% range. Its own model forecasts 2026 revenue of US$168.2 billion, up 37% year over year, equivalent to NT$5.3423 trillion, up 40.3%. The two growth rates differ because they use different currencies and foreign-exchange assumptions; New Taiwan dollar growth cannot be treated directly as US-dollar growth. The company’s official full-year outlook is presented in US dollars, which should therefore be the primary benchmark after earnings.
The two latest reports raise the threshold further. BofA forecasts 39% US-dollar revenue growth in 2026 and New Taiwan dollar revenue of NT$5.3612 trillion, up 40.8%. Morgan Stanley expects full-year US-dollar revenue growth in the high 30% range, approaching 40%, and New Taiwan dollar revenue of NT$5.3609 trillion, up 40.7%. In other words, JPMorgan’s 37% estimate is no longer an isolated extreme bull case but part of a 37%–40% range shared by all three institutions.
A full-year US-dollar revenue-growth outlook of 37%–40% would represent a high-quality upgrade only if management explains that it is driven by genuine demand for N3, AI accelerators, custom silicon, server CPUs, and networking chips, rather than merely by foreign exchange. If the company only reiterates “above 30%” without providing a more precise range, it would fall short of the latest institutional expectations. Guidance of around 35% would represent an upgrade but would still not fully clear current bullish models.
Whether Capex Is Positive or Negative Depends on Returns on Assets, Not the Total
In 1Q26, TSMC raised its annual capital-expenditure outlook to the high end of its US$52 billion–US$56 billion range. As of July 13, Morgan Stanley still forecasts capex of US$56 billion in 2026 and US$75 billion in both 2027 and 2028, totaling US$206 billion over three years. BofA forecasts US$58 billion, US$78 billion, and US$83 billion for 2026–2028, respectively. JPMorgan forecasts US$58 billion, US$78 billion, and US$84 billion, totaling approximately US$220 billion over three years. The gap among the three institutions’ 2026–2027 estimates has narrowed to US$2 billion–US$3 billion. The disagreement is no longer whether to expand, but when fabs, cleanrooms, equipment, and depreciation will translate into revenue.
These figures can easily be interpreted as “the stronger the demand, the greater the spending,” but investors should instead ask whether post-ramp pricing, utilization, yields, and returns on assets can support this level of depreciation. TSMC’s 1Q26 capex was NT$350.76 billion, while free cash flow was NT$348.21 billion—already very close. The company has strong cash-generation capacity, but capex is simultaneously absorbing cash flow, and the valuation cannot ignore this dynamic.
Management needs to provide three types of evidence. The first is demand visibility: whether customers and their customers are providing sufficiently long-term visibility, and whether this has been converted into executable orders through medium- to long-term agreements, prepayments, or equipment plans. The second is pricing evidence: JPMorgan expects 8%–10% price increases for N3 and N2 in 2027, alongside modest price increases for N5, N7, and CoWoS. However, this is an institutional forecast that needs to be validated by customer contracts and company commentary. The third is return evidence: revenue has grown faster than capex over the past several years, and management needs to demonstrate that overseas fabs, supply-chain tightness, and equipment inflation will not undermine this relationship in the years ahead.
BofA provides a more specific explanation of the return profile: it expects capex to grow at an approximately 23% CAGR during 2026–2028, but because fabs and cleanrooms will account for a larger share of incremental investment, depreciation is expected to grow at an approximately 17% CAGR, below the approximately 28% revenue CAGR. Gross margin could therefore remain around 68% in 2028. This is not a management commitment but an institutional assumption that requires validation. If the equipment mix, overseas construction costs, or ramp schedule exceed model assumptions, the expected moderation in depreciation will not materialize on schedule.
2027 Pricing Is the Balancing Valve in the Capacity Expansion Model
Whether high capital expenditure can sustain high gross margins ultimately comes down to pricing. JPMorgan believes that some N5 and more advanced nodes completed price adjustments of approximately 6%–10% in early 2026. It does not expect another broad-based increase in base pricing for leading-edge nodes in 2H26, with subsequent ASP improvement driven mainly by a higher share of high-performance computing at N3. For 2027, the firm expects N3 and N2 prices to rise 8%–10%, with modest increases for N5, N7, and CoWoS, while mature-node pricing remains broadly flat.
Bank of America’s latest report provides a more granular breakdown of the 2026 volume-price mix: blended wafer ASP rises 31% year on year, including 10%–15% price increases for the same products at the 5nm and 3nm nodes, 23% growth in advanced-node shipments, an 8% decline in mature-node shipments, and a potential 5%–10% decrease in mature-node prices. This shows that a sharp increase in ASP does not mean every wafer category is becoming more expensive. Rather, it reflects the combined effects of same-node price increases, a rising advanced-node mix, and the retirement of mature capacity. Morgan Stanley expects TSMC to retain the ability to raise leading-edge process prices by 5%–10% in 2027, consistent with JPMorgan’s direction but more conservative in magnitude.
Three types of price changes must be distinguished. The first is an increase in contract pricing for the same product on the same node, which most directly offsets depreciation and equipment costs. The second is an improvement in process mix as customers migrate from N5 to N3 and N2, raising ASP but also bringing higher depreciation and initial yield costs. The third consists of premiums generated by expedited wafers, special lots, and short-term supply constraints. These carry high incremental margins but may not be sustainable. Only the first category and the second category after the process matures can support long-term gross margins.
JPMorgan expects blended wafer ASP to increase 26% year on year in 2027. This is far above the 8%–10% increase for any individual node, indicating that a significant portion of the model is driven by a product-mix shift toward N3, N2, and high-performance computing. If management merely confirms on the earnings call that “customers are willing to pay more for advanced processes,” without explaining wafer area, node mix, the share of expedited orders, and contract duration, the market will still be unable to determine how much of the 26% is attributable to sustainable pricing.
Pricing is also not determined unilaterally. Customers can reduce unit costs through die shrinks, chiplet architectures, delayed product transitions, greater use of mature nodes, or second-source suppliers. TSMC’s advantages lie in yield, scale, the design ecosystem, and delivery certainty, and customers are willing to pay to reduce the risk of product delays. However, price increases must still leave customers with sufficient profitability on new products to support multi-year partnerships. After the earnings release, investors should focus on whether management continues to emphasize “customer success” and joint investment, and whether price increases can be tied to long-term supply commitments.
This balancing valve determines the nature of capital expenditure. If pricing, utilization, and yields improve in tandem, US$58 billion of capital expenditure represents future revenue and cash flow. If price negotiations stall, utilization falls, or yield ramp-up slows, the same US$58 billion becomes a source of depreciation and free-cash-flow pressure. The higher the capital expenditure figure, the greater the need for management to provide verifiable evidence of pricing and committed customer orders.
Full Transcript of TSMC’s 2026 Shareholders’ Meeting|AI Demand, Capital Expenditure, Advanced Processes, and Global Capacity Deployment
The 600,000-Wafer N3 Shortfall and 75%–80% N2 Yield Need to Be Translated into a Verifiable Construction Timeline
JPMorgan’s optimism on advanced processes is supported by annual models for fabs, equipment, and monthly capacity. The firm expects year-end N3 monthly capacity to reach 167,000, 213,000, and 240,000 wafers in 2026–2028, respectively, corresponding to modeled utilization rates of 115%, 117%, and 108%. Figures above 100% reflect the firm’s modeling assumption that demand exceeds nominal supply and must be met through cross-fab coordination and expedited production; they are not standard financial-reporting measures of capacity utilization. The report estimates that the current N3 supply-demand shortfall is approximately 600,000 wafers and is unlikely to disappear on its own in the near term.
Two recent reports are more constructive on N3 supply. Bank of America expects N3 monthly capacity to reach 190,000 wafers in 4Q26 and 230,000 in 4Q27. Morgan Stanley expects capacity of 180,000–190,000 wafers in 2026, approximately 190,000 in 2027, and 200,000–205,000 in 2028. Compared with JPMorgan’s estimate of 167,000 wafers, Bank of America and Morgan Stanley expect a faster near-term expansion, while JPMorgan is more aggressive on continued growth in 2027–2028. The key issue to verify in the earnings release is whether new capacity comes from permanent expansion, N5-to-N3 conversion, or cross-fab back-end coordination, as the three approaches differ in capital intensity and sustainability.
New supply will not come from a single fab. Phase 9 of Fab 18 is expected to add 25,000–30,000 wafers of monthly capacity in 1Q27; the second Arizona fab is expected to add approximately 20,000 wafers per month by the end of 2027; and the second Japan fab is expected to add 20,000–30,000 wafers per month by mid-2028. Before these new fabs come online, TSMC will also need to use the N7, N12, and even 28nm fab sites to share back-end metal-layer processing for N3 and N5. Such cross-fab coordination can increase effective near-term output but also adds complexity to production scheduling and quality control.
N2 is the larger medium-term test. JPMorgan expects year-end N2 monthly capacity to increase from 60,000 wafers in 2026 to 108,000 in 2027 and 170,000 in 2028, ultimately reaching 240,000–250,000 in 2029–2030. Its industry checks indicate that smartphone-processor yields have reached 75%–80%. Initial products include Apple’s A20 series, AMD’s Venice server processors and MI450 accelerators, and flagship chips from MediaTek and Qualcomm. Subsequent products are expected to include Google custom chips, Nvidia’s Feynman, and Amazon’s Trainium 4. These are institutional supply-chain forecasts. On the earnings date, management will need to validate them through mass-production timing, customer categories, yield ranges, and equipment-installation schedules; they should not be treated directly as company commitments.
Morgan Stanley’s July 13 forecast is more aggressive on N2/A16 capacity construction, projecting nearly 90,000–100,000 wafers by the end of 2026, 150,000–170,000 in 2027, and 210,000 in 2028. Bank of America, meanwhile, emphasizes that N2 defect density reached mass-production targets approximately two quarters earlier than N3, suggesting a potentially better yield and profit curve than N3, although it still expects N2 to dilute gross margin by 2–3 percentage points initially in 2H26. One focuses on the pace of capacity construction, while the other focuses on the progression of yields and profitability. Both require validation through actual tool move-ins, customer wafer starts, and yield ramp-up.
