
TSMC 2Q26 Earnings Deep Dive: US$40.2 Billion Revenue, 67.7% Gross Margin, and AI Capacity Constraints
目录
Executive Summary
1. The Surprise Was Not Revenue, but Margins Raising the Forward Baseline
2. Better-Than-Expected Earnings Quality: Manufacturing Profit Was Strong, but the Bottom Line Was Boosted by a One-Off Gain
3. Revenue Mix: 2-Nanometer Contributed 3% for the First Time, While HPC Rose to 66%
4. 67.7% Gross Margin: Cost Improvements and Utilization Materialize, While Overseas Fabs Remain Dilutive
5. Pre-Call Materials Provide No 3Q Figures; the Next Step Is to Set Thresholds, Not Impersonate Company Guidance
6. N2 and Advanced Nodes: Revenue Has Arrived, While Profitability and Inventory Begin Their Joint Test
7. Cash Flow: Operating Cash Generation Remains Strong, but Capex Is Growing Faster and Free Cash Flow Is Declining
8. Forward-Looking Review: The Core Margin Case Was Validated, but the Near-70% Scenario and Forward Guidance Remain Unresolved
9. Earnings and Valuation: Core Earnings Have Stepped Up, but a 20x Multiple Still Requires Confirmation from Forward Guidance
10. The Eight Numbers That Matter Next
Conclusion: Demand Has Been Confirmed; the Next Test Is the Return on Capacity Expansion and Margin Sustainability
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
2Q26 revenue reached the upper end of company guidance, while both gross margin and operating margin exceeded their respective ceilings. The key issues are manufacturing profitability, the one-off gain from Vanguard International Semiconductor, and the cost of the N2 ramp in terms of cash flow and future margins.
Executive Summary
TSMC’s 2Q26 results were not simply “in line” on revenue; margins provided evidence that operating performance exceeded company guidance. Quarterly revenue was NT$1.2704 trillion, or US$40.201 billion, exactly at the top of the US$39.0–40.2 billion guidance range. Gross margin was 67.7%, 0.2 percentage points above the guidance ceiling, while operating margin was 60.3%, 1.8 percentage points above the ceiling. The actual average exchange rate of 31.60 was also slightly below the company’s 31.7 assumption. The simultaneous strength in revenue and margins therefore cannot be attributed solely to FX.
The NT$27.25 in EPS included a substantial non-operating gain that should not be fully extrapolated. Non-operating income totaled NT$95.827 billion, including a NT$63.2 billion gain from the sale and fair-value remeasurement of TSMC’s stake in Vanguard International Semiconductor. Applying the quarter’s 18.1% effective tax rate mechanically, this gain contributed approximately NT$2.00 per share; adjusted EPS was therefore about NT$25.25. Even so, core EPS was still approximately 14% above 1Q26’s NT$22.08, demonstrating that the one-off item did not obscure strong manufacturing profitability.
The revenue mix shows growth becoming increasingly concentrated in both advanced nodes and high-performance computing. The 2nm node contributed 3% of wafer revenue for the first time, while 3nm rose to 30% and 7nm and below reached 77% in aggregate. High-performance computing accounted for 66% of revenue and grew 20% QoQ, while smartphones represented 22% and declined 4% QoQ. However, HPC is not synonymous with pure AI revenue. Official disclosures do not separately report AI accelerator revenue, so the entire 66% cannot be characterized as AI.
The quality of the 67.7% gross margin exceeded most pre-earnings sell-side base cases, although it fell short of the most bullish 69.5% forecast. The result exceeded Morgan Stanley’s 67.4% estimate, matched Bank of America’s 67.7%, and came below JPMorgan’s bullish 69.5% scenario. The company attributed the improvement to cost optimization and higher utilization, partly offset by dilution from overseas fabs. Combined with the decline in the operating expense ratio from 8.3% to 7.8%, the operating margin’s move above 60% shows that both fixed-cost absorption and operating leverage are materializing.
Capacity expansion has already weighed materially on free cash flow, but it does not currently pose a balance-sheet risk. Operating cash flow was NT$783.365 billion, capital expenditure was NT$496.002 billion, or approximately US$15.7 billion, and free cash flow was NT$287.363 billion, down 17.5% QoQ. First-half capital expenditure totaled US$26.8 billion. At the same time, cash and marketable securities stood at NT$3.518 trillion, with a net cash position of NT$2.486 trillion, providing ample capacity to fund investment. The real issue to monitor is capex continuing to grow faster than operating cash flow, rather than near-term solvency.
N2 has moved from a “future story” into current financial statements, creating new validation pressure. The 2nm node accounted for 3% of revenue, while inventory rose 23.8% QoQ and inventory days increased from 80 to 87, which the company explicitly attributed mainly to the N2 ramp. Accounts receivable also increased 21.5% QoQ, with days sales outstanding rising to 29 days. Strong demand, yield ramping, and advance inventory builds can explain these changes. However, if revenue growth subsequently slows while inventory and depreciation continue to rise, the current high gross margin will face a more stringent cash-return test.
1. The Surprise Was Not Revenue, but Margins Raising the Forward Baseline
TSMC’s monthly sales had already effectively locked in 2Q26 revenue; the genuinely new information in the earnings release came from margins. Aggregate April–June revenue was approximately NT$1.2704 trillion, matching the final reported figure of NT$1.2704 trillion, up 12.0% QoQ and 36.0% YoY. At the quarterly average exchange rate of 31.601, this translated into US$40.201 billion, exactly at the top of the company’s US$39.0–40.2 billion guidance range. Revenue did not deliver a major surprise, but it confirmed the strength of demand for advanced nodes and high-performance computing.
Gross margin of 67.7% was 0.2 percentage points above the upper end of the company’s 65.5–67.5% guidance, while operating margin of 60.3% was 1.8 percentage points above the 56.5–58.5% ceiling. The distinction matters: gross margin only modestly exceeded the upper bound, whereas operating margin surpassed it by a wide margin, indicating that lower expense intensity and operating leverage delivered an additional upside surprise. Quarterly operating expenses were NT$98.982 billion, up only 5.3% QoQ, materially slower than the 12.0% increase in revenue. The operating expense ratio fell from 8.3% to 7.8%.
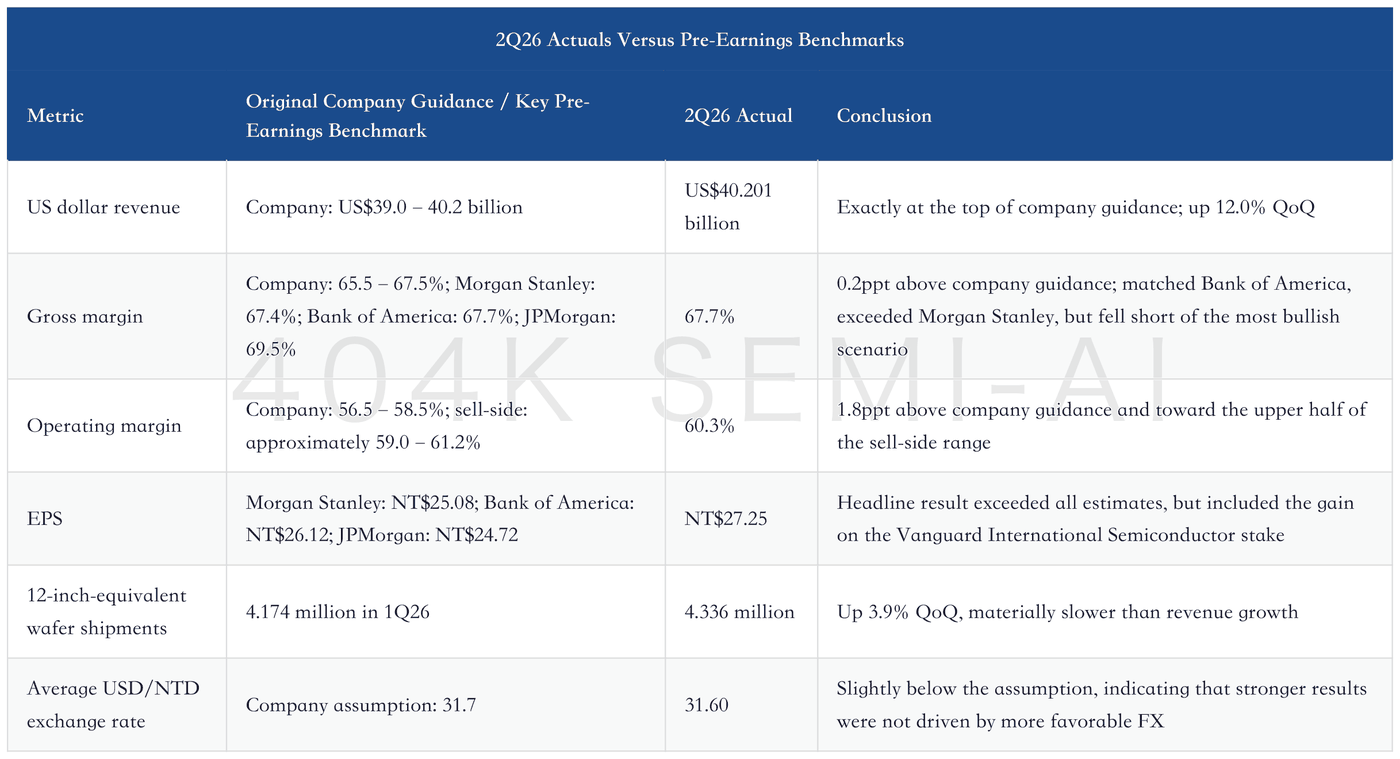
Wafer shipments increased only 3.9% QoQ, while revenue grew 12.0%, implying an approximately 7.8% increase in revenue per 12-inch-equivalent wafer. The gap reflects the process-node and customer mix, wafer area, product value, and potentially pricing factors; it cannot be described directly as a same-node price increase. At a minimum, however, it demonstrates that growth this quarter was not simply driven by shipping more low-value wafers. The rising shares of 2nm and 3nm, together with greater HPC exposure, provide visible explanations for revenue growing faster than wafer volumes.
The YoY comparison leads to the same conclusion, with an even more pronounced structural improvement. Twelve-inch-equivalent wafer shipments increased 16.6% YoY, while NT-dollar revenue grew 36.0%, implying an approximately 16.6% increase in revenue intensity per wafer. Gross margin rose 9.1 percentage points, from 58.6% to 67.7%. This indicates that TSMC not only sold more wafers but also allocated more capacity to leading-edge nodes and HPC products with higher pricing and value content. If the improvement had merely reflected mature-node restocking during an industry recovery, unit revenue and gross margin would not typically have increased this substantially at the same time.
First-half results turn the quarterly movement into a more durable trend. Revenue for 1H26 was NT$2.4045 trillion, up 35.6% YoY. Gross margin was 67.0%, up 8.3 percentage points from 58.7% in the prior-year period, while operating profit rose 63.8% YoY to NT$1.4256 trillion. The strong quarter was not an isolated event. At least during 1H26, advanced nodes, HPC, and high utilization jointly raised TSMC’s revenue and earnings baseline.
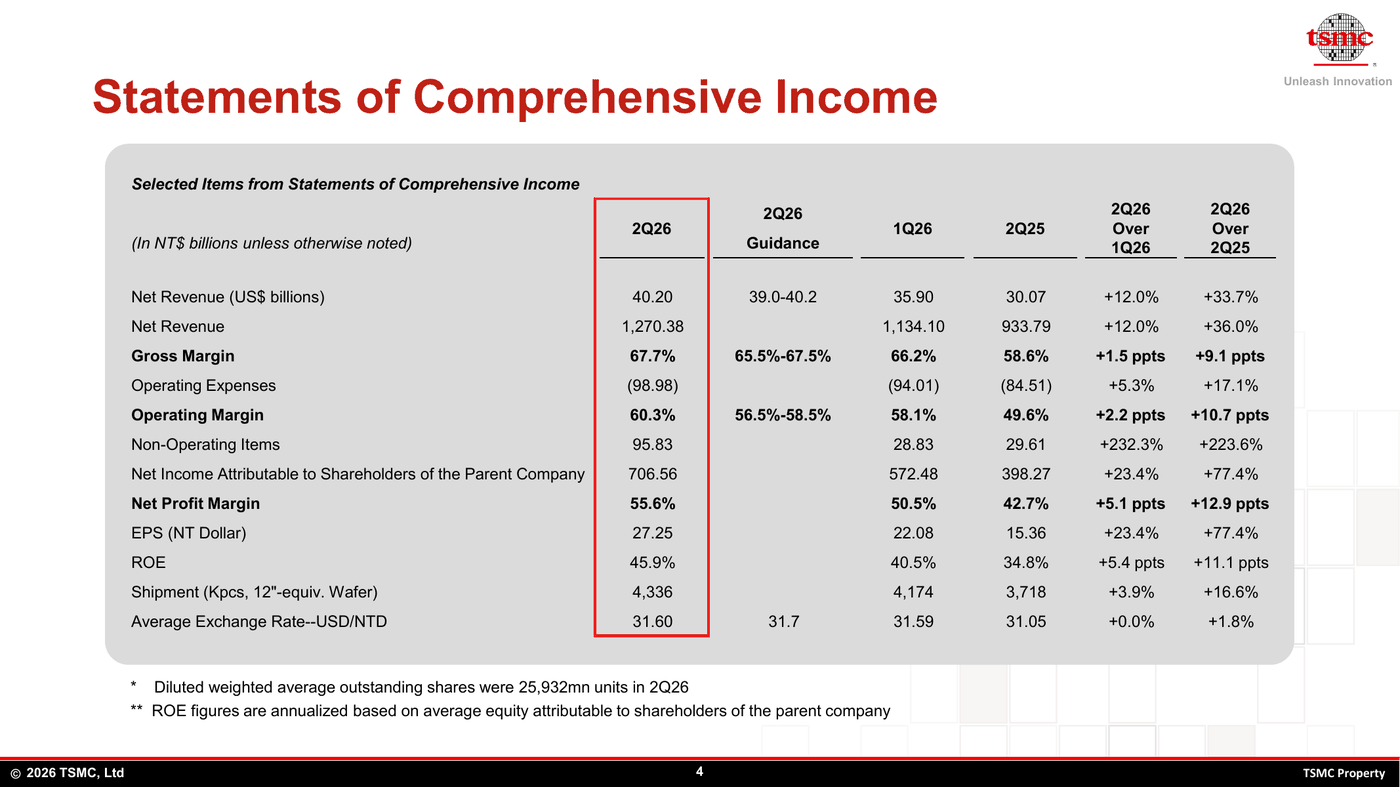
TSMC’s 2Q26 revenue reached US$40.201 billion, with a 67.7% gross margin and 60.3% operating margin, all above the upper end of original guidance. Source: TSMC, “Second Quarter 2026 Results Presentation,” p. 4.
The first conclusion from these results is therefore not that “revenue beat again,” but that the operating-margin baseline has moved higher. Looking only at revenue, the market already knew the answer after June monthly sales were released. Looking at gross and operating margins, the results confirmed that high utilization, cost improvements, and product mix are converting strong demand into higher profits. Whether the valuation can continue to rerate will depend on whether this conversion remains intact as N2 depreciation and dilution from overseas fabs intensify.
2. Better-Than-Expected Earnings Quality: Manufacturing Profit Was Strong, but the Bottom Line Was Boosted by a One-Off Gain
TSMC’s 2Q26 net profit attributable to shareholders was NT$706.562 billion, up 77.4% year over year, significantly outpacing revenue growth of 36.0%; however, net profit included a gain that cannot be replicated quarterly. Non-operating items generated NT$95.827 billion in the quarter, up NT$66.993 billion from 1Q26. Of this, “other gains and losses” amounted to NT$67.43 billion, which management attributed primarily to a NT$63.2 billion gain from the disposal and fair-value remeasurement of its stake in Vanguard International Semiconductor.
Applying the quarter’s 18.1% effective tax rate mechanically, the NT$63.2 billion pre-tax gain contributed approximately NT$2.00 per share. Deducting this from reported EPS of NT$27.25 implies rough core EPS of approximately NT$25.25. This is not a company-reported non-GAAP measure; it is intended solely to avoid extrapolating the equity-disposal gain. Adjusted EPS was still approximately 14.4% above 1Q26 EPS of NT$22.08, indicating that the underlying business improved materially.
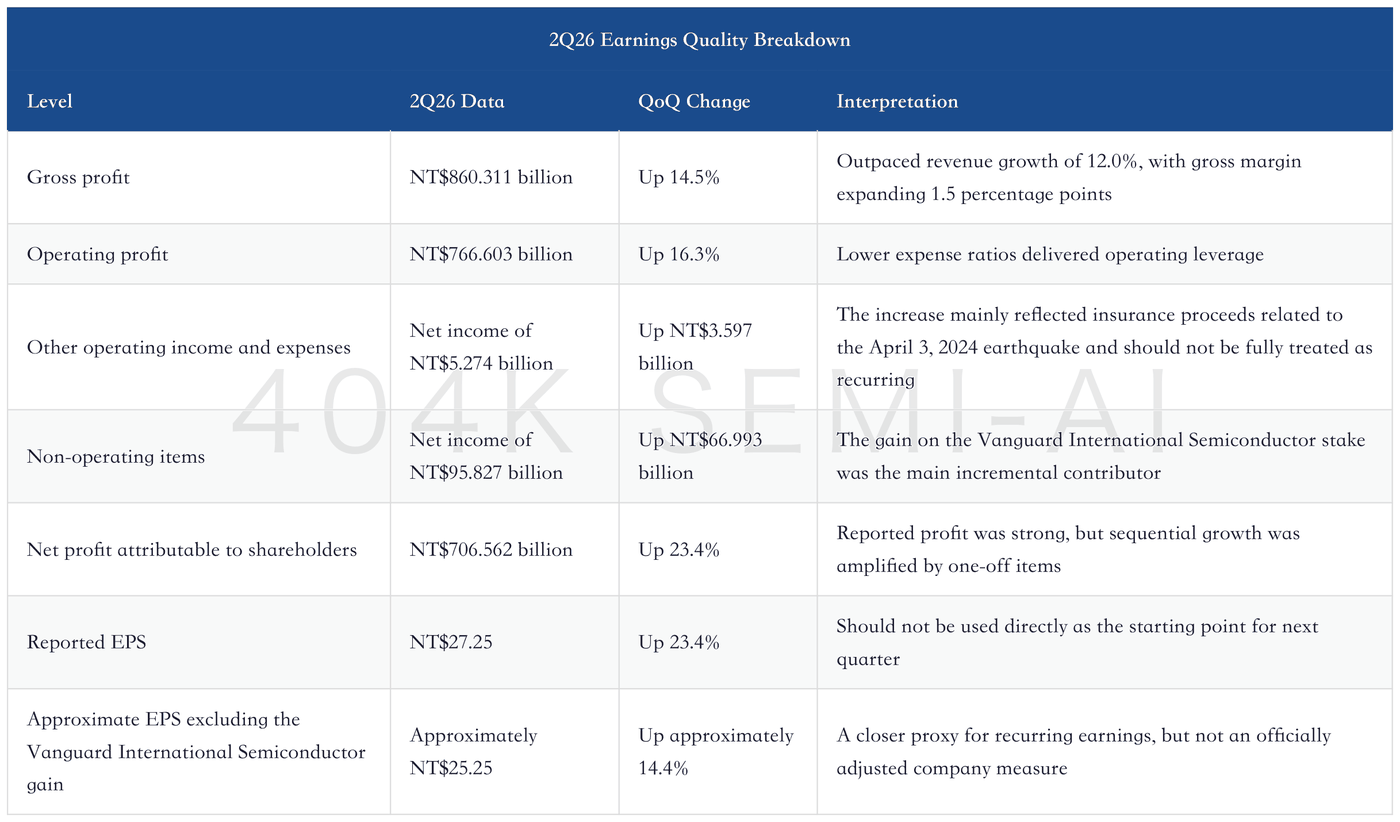
Even if the entire NT$5.274 billion of other operating income were excluded, operating margin would still have been approximately 59.9%, above the similarly adjusted 1Q26 level of approximately 58.0%. This is an extremely conservative upper-bound adjustment because the NT$5.274 billion did not come entirely from insurance proceeds. It still demonstrates that the 60.3% operating margin was not sustained by a single insurance payout. Cost improvements, higher capacity utilization, and operating-expense leverage were more important operating drivers.
R&D; spending was not sacrificed for short-term earnings. Quarterly R&D; expenses were NT$73.146 billion, up 8.0% quarter over quarter and 19.4% year over year; first-half R&D; expenses were NT$140.903 billion, up 19.6% year over year. R&D; grew more slowly than revenue, reducing the R&D; expense ratio, but absolute investment still increased rapidly. This differs from a low-quality earnings beat achieved by cutting R&D; and is more consistent with the operating logic of strong advanced-node revenue growth absorbing R&D; and fixed costs.
A cross-check using net margin also confirms the improvement in the underlying business. Reported net margin was 55.6%. Mechanically deducting the Vanguard International Semiconductor gain at the quarter’s tax rate yields approximate core net profit of NT$654.8 billion and a core net margin of approximately 51.5%, still above the reported 1Q26 net margin of 50.5%. This is not a rigorous accounting adjustment because the actual tax treatment of the equity gain may differ. Even under a conservative calculation, however, core margin did not fall below the prior quarter after removing the one-off item.
Cash flow also showed no divergence between strong accounting profit and weak cash conversion. Quarterly operating cash flow was NT$783.365 billion, equivalent to 110.9% of reported net profit. Despite a substantial increase in capital expenditure, free cash flow remained NT$287.363 billion. The Vanguard International Semiconductor gain affects the bottom line and certain cash-flow classifications, but simultaneous improvements in gross profit, operating profit, core net margin, and operating cash flow are sufficient to confirm that the underlying business strength was not created by one-off items.
The tax rate should be assessed separately. The 2Q26 effective tax rate was 18.1%, up from 16.8% in 1Q26, which the company said mainly reflected the tax on undistributed earnings. The higher tax rate offset part of the non-operating gain, so reported net profit did not retain the full NT$63.2 billion pre-tax gain on a one-for-one basis. Forward earnings models should begin with gross margin and operating margin, then estimate a normalized tax rate, rather than simply annualizing NT$27.25.
3. Revenue Mix: 2-Nanometer Contributed 3% for the First Time, While HPC Rose to 66%
The most important mix shift in 2Q26 was the formal inclusion of 2-nanometer in the revenue breakdown. The 2-nanometer node contributed 3% of wafer revenue, while 3-nanometer contributed 30%, 5-nanometer 33%, and 7-nanometer 11%. Nodes at 7-nanometer and below accounted for 77% in aggregate, up from 74% in 1Q26. The 3-nanometer share rose from 25% to 30%, while 2-nanometer increased from zero to 3%. The declining shares of 5-nanometer and 7-nanometer do not necessarily imply lower absolute revenue; they indicate that more advanced nodes grew faster.
The 3% contribution from 2-nanometer is a starting point, not proof of mature-node profitability. Early-stage nodes typically entail higher depreciation, lower initial yields, more engineering wafers, and inventory build. The fact that 2-nanometer is generating revenue indicates that customer wafer starts and production have moved from validation into the commercial phase. However, only if its revenue share continues rising while inventory days stabilize and gross margin remains elevated can N2 be confirmed as progressing from a revenue growth driver to a profit growth driver.
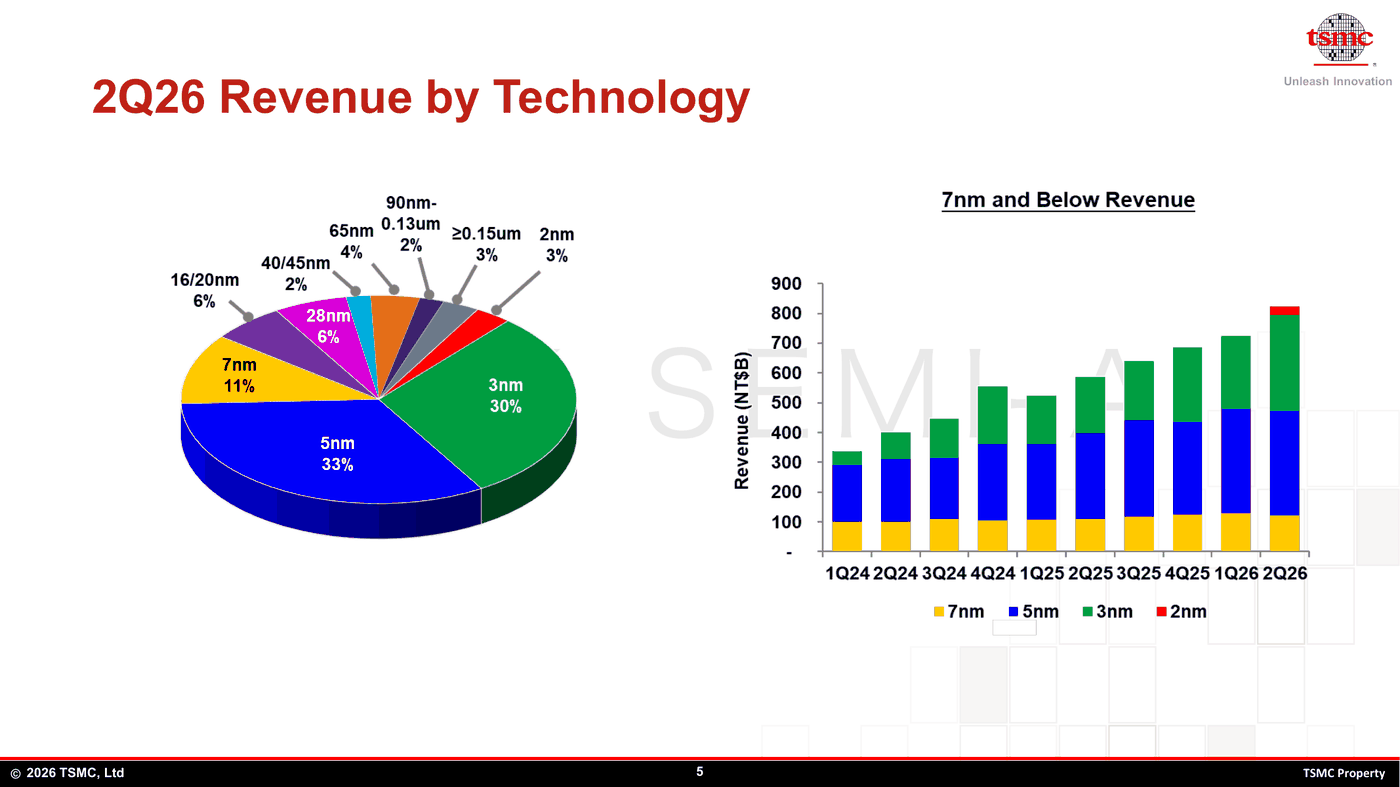
The 2-nanometer node contributed 3% for the first time, 3-nanometer rose to 30%, and nodes at 7-nanometer and below accounted for 77% in aggregate. The bar chart on the right shows that total advanced-node revenue continued to expand. Source: TSMC, “Second Quarter 2026 Earnings Presentation,” p. 5.
The platform mix explains the source of demand this quarter better than the process mix. High-performance computing accounted for 66% of net revenue, up from 61% in 1Q26 and 60% in 2Q25, with revenue increasing 20% sequentially. Smartphones accounted for 22%, down from 26% in 1Q26, with revenue declining 4% sequentially. Internet of Things accounted for 5%, up 4% sequentially; automotive 4%, up 15%; digital consumer electronics 1%, up 5%; and other businesses 2%, up 5%.
The 20% sequential increase in high-performance computing was the primary driver of total revenue growth of 12%. Based roughly on revenue shares, quarterly HPC revenue was approximately NT$838.5 billion, versus approximately NT$279.5 billion for smartphones. HPC is now nearly three times the size of smartphones, and TSMC’s profit mix is increasingly dependent on demand for data-center processors, GPUs, custom chips, networking chips, and related advanced packaging.
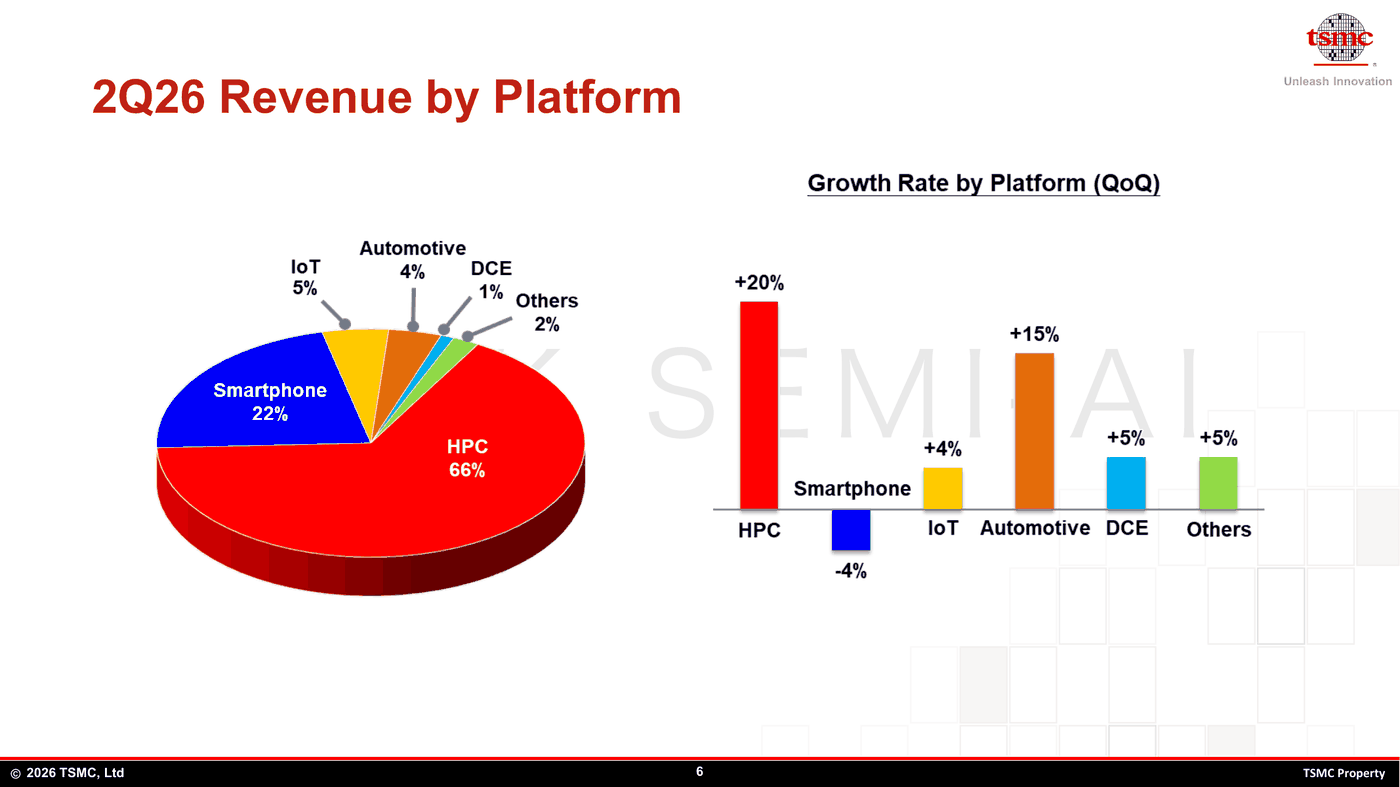
High-performance computing accounted for 66% of revenue and grew 20% sequentially; smartphones accounted for 22% and declined 4%; automotive revenue increased 15%. Source: TSMC, “Second Quarter 2026 Earnings Presentation,” p. 6.
However, “HPC at 66%” should not be equated with “AI revenue at 66%.” TSMC’s platform classification includes server CPUs, GPUs, AI accelerators, custom chips, networking products, and other HPC products. None of the four official materials separately disclosed AI accelerator revenue or updated the previously stated compound growth rate for AI revenue. Treating the entire 66% as AI would include conventional servers, networking, and other computing demand in the AI numerator, overstating pure AI revenue.
The geographic mix also became more concentrated. North American customers accounted for 78% of revenue, up from 76% in 1Q26 and 75% in 2Q25; Asia Pacific accounted for 8%, China 6%, Japan 4%, and Europe, the Middle East, and Africa 4%. This mix reflects strong demand from large U.S. fabless semiconductor and cloud-computing customers, while also increasing revenue sensitivity to customer concentration, export controls, and geopolitical policy. The more demand is concentrated in a small number of high-value platforms, the greater TSMC’s manufacturing scarcity value, but the more pronounced quarterly volatility from individual customer product cycles may become.
In terms of incremental contribution, HPC accounted for nearly all platform growth this quarter. A rough back-calculation based on each platform’s revenue share and sequential growth suggests that HPC revenue increased by approximately NT$140 billion, while smartphone revenue declined sequentially. Although automotive, IoT, and other platforms grew, their absolute scale was still insufficient to explain the company’s entire NT$136.278 billion sequential revenue increase. This calculation is affected by rounding in reported revenue shares and is suitable only for directional analysis, but it is sufficient to show that the quarter did not represent a synchronized recovery across all end markets. Instead, advanced-computing demand clearly offset weakness in other platforms.
This ability to offset weakness is a key distinction between TSMC and a typical cyclical company. When smartphone revenue declines 4% sequentially, HPC can still absorb capacity through larger die sizes, more advanced process technologies, and higher packaging value. When a consumer-electronics product generation is delayed, server CPUs, GPUs, custom chips, and networking chips can provide an alternative demand curve. A multi-platform model does not eliminate cyclicality, but it makes high-value capacity easier to reallocate among customers.
4. 67.7% Gross Margin: Cost Improvements and Utilization Materialize, While Overseas Fabs Remain Dilutive
The company clearly attributed the 1.5-percentage-point sequential gross-margin improvement primarily to cost improvements and higher capacity utilization, partly offset by overseas-fab dilution. This is more meaningful than simply citing a “better product mix,” as it indicates genuine improvement in fixed-cost absorption and manufacturing efficiency. Revenue grew 12.0% while wafer shipments rose 3.9%, with higher revenue per unit providing an additional margin boost.
The 67.7% gross margin was toward the upper end of pre-earnings expectations, but not at the most bullish end. Morgan Stanley forecast 67.4%, Bank of America 67.7%, and JPMorgan 69.5%. The actual result matched Bank of America’s estimate and showed that buy-side expectations approaching 70% were not entirely unfounded. Reaching 69.5%, however, would have required stronger product mix, pricing, yields, or FX support. The result was better characterized as a high-quality outcome broadly in line with and modestly above the base case, rather than a sudden shift to a 70% margin structure.
The 60.3% operating margin deserves more attention than gross margin. Gross margin exceeded the top end of company guidance by only 0.2 percentage points, while operating margin beat by 1.8 percentage points, mainly because the operating-expense ratio declined by 0.5 percentage points and other operating income increased. R&D; spending continued to grow even as its expense ratio declined, indicating that revenue scaled faster than the R&D; and administrative infrastructure. This is the operating leverage created by high utilization and advanced-node scarcity.
Overseas-fab dilution remains, meaning the current 67.7% is not a peak achieved without headwinds. Arizona, Japan, and subsequent overseas expansions provide supply-chain resilience and proximity to customers, but their construction costs, depreciation, initial utilization, and operating expenses are generally higher than those of established Taiwan sites. As overseas capacity continues to increase as a share of the total, TSMC will need higher advanced-node pricing, faster yield ramps, and stronger overall utilization to offset the dilution.
N2 will be the first margin stress test in the second half. The 2nm node already contributed 3% of revenue, while the increase in inventory days was explicitly linked to the N2 ramp. Early-stage revenue growth and cost recognition for a new node often occur simultaneously: customers are willing to pay premium prices, but depreciation, engineering costs, and yield losses are also higher. If the 2nm revenue share continues to rise while gross margin remains in the high-60% range, pricing and yields are sufficient to absorb ramp-up costs. If revenue is strong but gross margin continues to decline, the quality of incremental revenue will need to be reassessed.
Every one-percentage-point change in gross margin has a material impact on earnings. Based on 2Q26 revenue, one percentage point of gross margin equates to approximately NT$12.7 billion in gross profit. Applying the 18.1% tax rate mechanically implies roughly NT$10.4 billion in after-tax profit, or NT$0.40 per share. The 1.8-percentage-point gap between the actual 67.7% and JPMorgan’s bullish 69.5% scenario corresponds to an operating-profit difference of approximately NT$0.72 per share. By comparison, the Vanguard International Semiconductor gain contributed approximately NT$2.00 per share, further illustrating why manufacturing margins must be separated from reported EPS.
Margin drivers must also be divided into recurring and non-recurring factors. Higher utilization, improving N3 yields, long-term pricing agreements, and a higher-value product mix can persist across quarters. Expedited orders, insurance proceeds, asset disposals, and favorable FX are more likely to reverse. The company explicitly cited cost improvements and utilization this quarter but did not quantify same-node price increases or expedite fees in the four materials. It would therefore be inappropriate to characterize the entire increase in unit revenue as permanent pricing power.
Accordingly, the 67.7% margin should neither be extrapolated mechanically nor distorted by one-off gains. The Vanguard International Semiconductor equity gain was recorded below operating profit and did not affect gross margin. Earthquake insurance proceeds were included in other operating income and likewise did not affect gross margin. Gross margin itself is one of the cleanest operating signals in these financial statements and should continue to be analyzed through utilization, N2 yields, overseas-fab dilution, and process mix rather than using EPS as a substitute.
5. Pre-Call Materials Provide No 3Q Figures; the Next Step Is to Set Thresholds, Not Impersonate Company Guidance
The four official materials clearly presented the 2Q26 actual results but did not disclose 3Q26 US-dollar revenue, gross margin, operating margin, or the full-year 2026 capital-expenditure range. The earnings-presentation agenda states that the CFO will discuss the 3Q26 outlook, but the current ten-page presentation contains no numerical guidance page. The management report also covers only the 2Q results, cash flow, actual capital expenditure, and recent developments. Undisclosed figures cannot be presented prematurely as company guidance.
Pre-earnings market benchmarks can still serve as a yardstick after the call, but they must be labeled as expectations. Sell-side expectations for 3Q26 were primarily centered on 10%–15% sequential growth in US-dollar revenue, a 67%–68% gross margin, and a 59%–60% operating margin. A clearly high-quality beat would combine sequential revenue growth above 15% with gross margin above 68%. A low-quality outcome would feature continued strong revenue but gross margin below 67%, indicating that depreciation and costs from new capacity are entering the income statement faster than value creation.
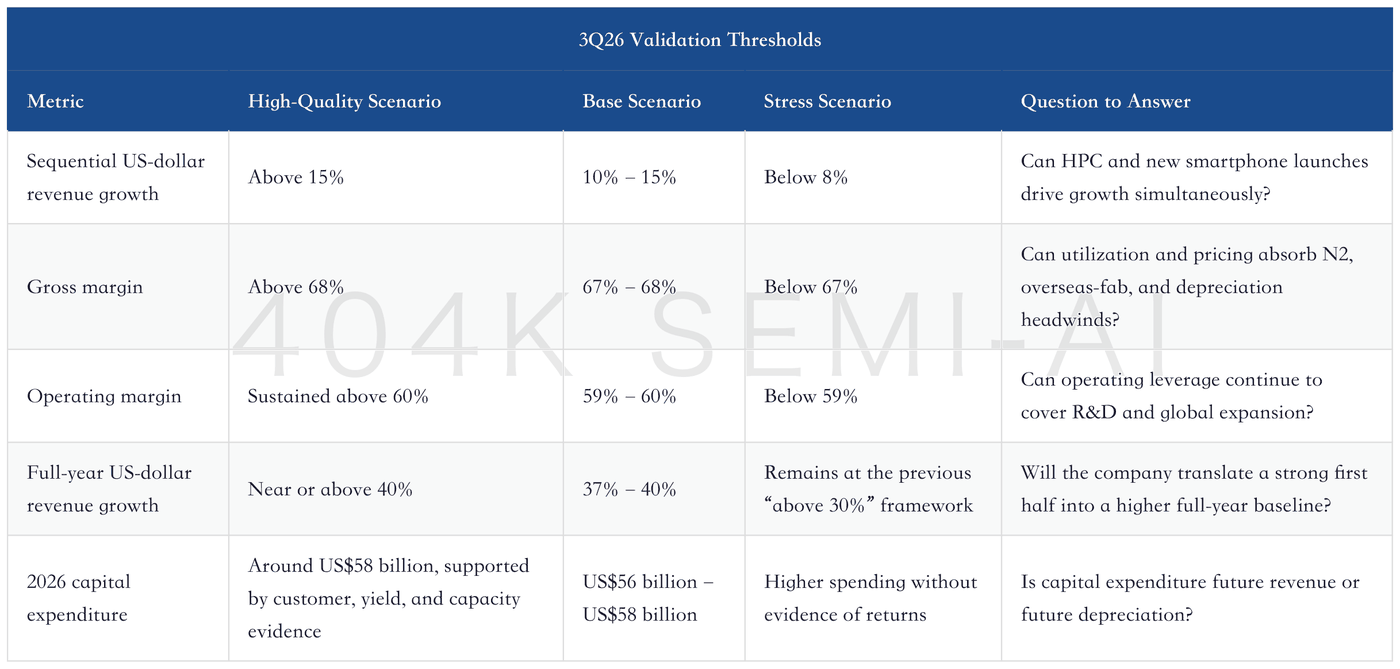
The 2Q results have already raised the bar for 3Q. A 67.7% gross margin and 60.3% operating margin mean that even if revenue continues to grow in 3Q, a retreat in gross margin to 65%–66% would prompt questions about whether N2 and overseas-fab dilution are exceeding expectations. Conversely, if revenue growth slows but gross margin remains above 67%, the cause may simply be product-launch timing rather than simultaneous deterioration in demand and pricing.
Full-year growth likewise requires an updated framework. First-half revenue reached NT$2.4045 trillion, up 35.6% year over year. If the company merely reiterates its prior expectation of “more than 30% growth in US-dollar revenue,” the direction remains positive but provides no new modeling information from the strong first half. What would be genuinely valuable is a narrower full-year growth range, a capital-expenditure range, and the principal demand drivers, together with a breakdown of the respective contributions from FX, wafer volumes, product mix, and pricing.
After the call, the figures should be verified before the explanations. The numerical layer should first assess 3Q revenue, gross margin, operating margin, full-year US-dollar revenue growth, and capital expenditure. The explanatory layer should then assess HPC customer visibility, N2 yields and inventory, overseas-fab dilution, effective CoWoS output, and pricing negotiations. Only when the figures and explanations correspond can the strong 2Q performance be extended into the earnings model. If management offers only “very strong demand” without ranges, the information value will be materially lower than that of restrained but verifiable guidance.
The most important safeguard is to avoid conflating market forecasts with company commitments. Full-year US-dollar revenue growth of 37%–40%, capital expenditure of US$56 billion–US$58 billion, and sequential 3Q revenue growth of 10%–15% currently remain pre-earnings institutional estimates, not new guidance from the four official pre-call materials. Listing them as benchmarks helps gauge the degree of any beat, but valuation upgrades should wait until the company provides formal guidance.
6. N2 and Advanced Nodes: Revenue Has Arrived, While Profitability and Inventory Begin Their Joint Test
A 3% revenue contribution from 2nm means N2 commercialization has entered the financial statements, but the increase in inventory days to 87 shows that the ramp is not costless. Ending inventory was NT$385.525 billion, up NT$74.071 billion sequentially, or 23.8%. Inventory days increased from 80 to 87, which the company explicitly attributed mainly to the N2 ramp. The increase may include work in process, materials, and finished-goods preparations—a common feature around the start of volume production—but it also consumes cash and increases risks related to yields and demand forecasting.
The critical question for N2 is not whether it has customers, but whether revenue, yields, inventory, and gross margin can improve in tandem. The second quarter already demonstrated commercial revenue. The next phase will reveal whether inventory days peak, unit costs decline, and gross-margin dilution narrows as the 2nm revenue share rises. If revenue contribution increases from 3% while inventory continues to grow rapidly, the production line may still be accumulating substantial work in process or building inventory for future demand, causing cash conversion to lag revenue recognition.
The 3nm node remains the principal driver of current profit growth. Its revenue share increased from 25% in 1Q26 to 30%, while 5nm declined from 36% to 33% and 7nm from 13% to 11%. Based on a rough estimate using total wafer revenue, sequential 3nm revenue growth materially exceeded company-wide growth. Mature N3 yields, utilization, and product mix provide a buffer against early-stage N2 dilution.
