
Tianfu Communication Update: 200G EML Supply Eases, 1.6T Optical Engines Accelerate in 2H, 2028 CPO Revised Up
目录
1. What Is New in This Report: Near-Term Cuts, Long-Term Upgrade
2. A Very Steep Revenue Step-Up Is Needed in the Second Half
3. 200G EML Is the Real Constraint; Glass Bridge Is Not Yet the Main Risk
4. CPO Monetization Is Pushed Out; FAU and ELS Competition Cannot Be Ignored
5. How to Read It: Treat This Update as an Execution Test
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Nomura does not reject Tianfu Communication’s 1.6T and CPO thesis, but it makes the delivery timeline more demanding: 2026-2027 earnings forecasts are cut, while 2028 is revised up again. Whether 200G EML supply eases in the second half and whether revenue can step up will determine whether this pullback is merely expectation digestion or the start of a high-valuation stock reverting to a manufacturing framework.
1. What Is New in This Report: Near-Term Cuts, Long-Term Upgrade
Nomura’s new model divides Tianfu Communication into two phases: first acknowledging delivery pressure in 2026-2027, then factoring in volume growth from CPO and higher-value optical engines in 2028. This is more useful than simply raising long-term upside, because it incorporates the market’s current concerns over materials, capacity, and module-business timing into earnings forecasts, while preserving the company’s potential role in next-generation optical interconnect architecture.
Nomura cuts its 2026 and 2027 revenue forecasts by 10.6% and 9.7%, respectively, and cuts net profit forecasts by 5.9% and 6.2%. For 2028, it raises revenue and net profit forecasts by 4.9% and 5.0%, respectively. The cuts mainly reflect a slower ramp in modules and ELS versus prior assumptions, while the upgrades reflect a more optimistic view on the CPO market, 1.6T/3.2T optical engines, and high-end FAU components.
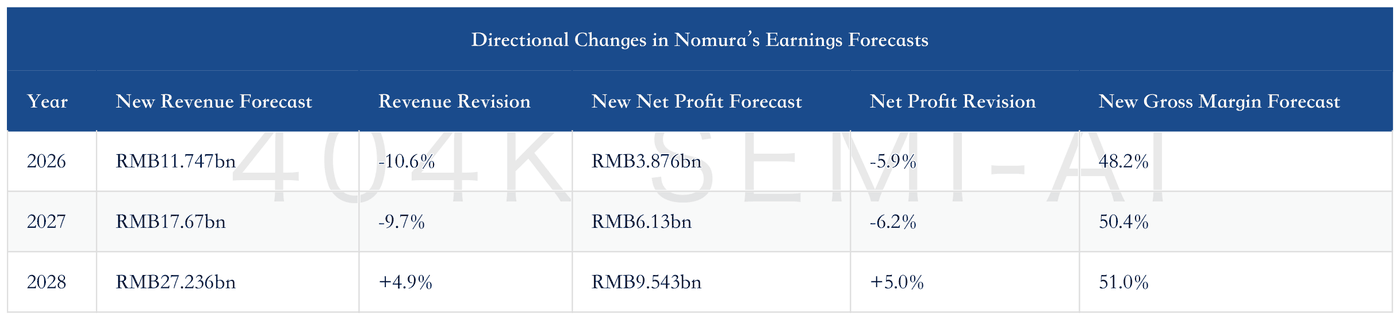
Revenue forecasts are cut more than profit forecasts because the product mix is improving. Nomura raises its 2026 and 2027 gross margin forecasts by 1.9 and 1.5 percentage points, respectively, arguing that the technology upgrade to 1.6T and 3.2T optical engines can offset part of the slowdown in the module business. In other words, the market should not only watch whether revenue grows quickly, but also whether high-value products can support margins.
The target price is cut from RMB300.51 to RMB282, while the rating remains Buy. Nomura values the stock at 50x 2027E EPS of RMB5.63; based on the July 8, 2026 closing price of RMB245.68, this implies around 14.8% upside. That upside is not thick, suggesting the bullish view in the report depends heavily on delivery execution in the second half and cannot be supported by the long-term CPO story alone.
2. A Very Steep Revenue Step-Up Is Needed in the Second Half
Nomura’s assumptions for 2H 2026 are highly aggressive, requiring sequential acceleration in both the third and fourth quarters.
The quarterly model forecasts revenue of RMB1.862bn in 2Q, RMB2.98bn in 3Q, and RMB5.575bn in 4Q; corresponding net profit is RMB610mn, RMB991mn, and RMB1.783bn. Under these figures, second-half revenue would be about RMB8.555bn, 2.7x first-half revenue of roughly RMB3.192bn; second-half net profit would be about RMB2.774bn, 2.5x the first half.
This quarterly forecast turns “1.6T volume ramp in the second half” into measurable numbers. If there is no clear step-up in 3Q, the pressure to meet the full-year forecast in 4Q will rise quickly. Even if revenue comes through, weakening gross margin and cash flow would suggest the incremental revenue may be coming from lower-value assembly, rushed delivery, or working-capital absorption, with insufficient value retained at the profit level.
The previous full-depth report defined 2H 2026 as Tianfu Communication’s first threshold in moving from component supply to an optical-engine platform. Nomura further quantifies that threshold this time: customer demand already exists, and the slope of the financial statements will be determined by 200G EML supply, capacity organization, yield, and delivery capability. The prior directional view has not changed, but the verification window has been compressed into the third and fourth quarters.
Tianfu Communication Deep Dive: From Optical Component Supplier to AI Optical Engine Platform — Revaluing Upstream Value Through 1.6T, NPO, and CPO
3. 200G EML Is the Real Constraint; Glass Bridge Is Not Yet the Main Risk
The hardest short-term constraint remains 200G EML chips, not glass bridge replacing FAU. Nomura believes the 200G EML shortage that weighed on Tianfu Communication over the past few quarters may ease in 2H 2026, driven by a more diversified supplier base and support from a large AI customer in helping the company secure more chip supply. Demand is not weak; the amount of critical chips the company can obtain directly determines how many 1.6T optical engines it can deliver.
Supply easing should not be treated as a certainty. Nomura also emphasizes that the 200G EML market remains tight, and the company’s execution remains critical to delivery. Customer support in securing supply shows Tianfu Communication has entered important projects, but it also exposes supply-chain concentration: if new supplier qualification is slow, yields are unstable, or customer priorities shift, the second-half revenue step-up will be delayed.
Another market concern is that new technologies such as glass bridge may reduce the value of FAU. Nomura believes these concerns are overstated, because such solutions do not yet have a mature mass-production track record in optical modules or CPO, and their commercialization timeline is not sufficient to immediately threaten existing FAU solutions. This view is more suitable for explaining near-term valuation and should not be extrapolated into permanent safety. Once a technology route completes mass-production validation, customers may still reallocate value across optical coupling, connectivity, and packaging.
