
The Over-$700 Billion AI Bet: SK Hynix, Samsung, and the South Korean Government Are Going All-In on Compute Infrastructure
目录
TL;DR
I. This Is Not Ordinary Industrial Policy, but South Korea’s AI Reindustrialization Plan
II. Execution Logic of the Three Major Projects: First Use State Credit to Reduce Uncertainty, Then Accelerate Corporate Capex
III. Semiconductor Main Line: Korea Wants to Use AI Demand to Rewrite the Supply Narrative for Memory
IV. AI Data Centers: What Korea Really Wants to Export Is “Compute Factories,” Not Ordinary Server Rooms
V. Physical AI: Korea Wants to Turn Its Manufacturing Advantage into Export Capabilities in Robotics and Smart Factories
VI. Localization: Whether This Plan Works Depends on Whether Engineers Are Willing to Move There
VII. Where the Money Comes From: Government Provides Certainty, Companies Provide Capex, Financial Tools Add Leverage
VIII. Investment Implications for the Supply Chain: Look at Hard Assets First, Then Software and Model Delivery
IX. Three Possible Paths: From National-Level Success to Heavy-Asset Indigestion
10. Follow-Up Indicators: Whether Projects Move From Slogans to Cash Flow
11. Conclusion: Korea Is Betting the AI Cycle Will Last Long Enough to Absorb a National-Scale Capex Wave
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The real goal of South Korea’s three major projects is to bind memory supply, AI data centers, robotics manufacturing, power, and local infrastructure into a closed-loop reindustrialization system. The investment opportunity is not only in chip capacity expansion, but also in whether compute utilization, power access, domestic NPUs, Physical AI data, and regional carrying capacity can be delivered.
TL;DR
South Korea is treating AI as a reindustrialization project. The three major projects are not standalone semiconductor subsidies; they combine memory, AI data centers, Physical AI, regional cities, and the power system into one industrial balance sheet. In the short term, the story is investment-led growth. In the long term, the question is whether South Korea can upgrade from “producing chips” to “producing intelligent infrastructure.”
Semiconductors remain the foundation of every project. The government’s framing is KRW 30trn over 15 years to support R&D;, design, validation, and manufacturing. Corporate plans are more aggressive: SK has proposed a project pool of roughly KRW 2,100trn around AI data centers and memory capacity expansion, while Samsung is spreading new manufacturing bases, HBM packaging, robotics, batteries, and biomanufacturing across multiple regions.
AI data centers are the largest lever. South Korea plans to build 8.4GW of capacity by 2029, implying roughly KRW 550trn of investment, and add another 10GW by 2035, reaching 18.4GW in total and more than KRW 1,000trn. Project success does not depend on whether server rooms can be built, but on whether power, cloud platforms, NPU/GPU supply, and customer workloads arrive at the same time.
Physical AI addresses manufacturing’s second growth curve. South Korea wants to move from “using robots” to “building robots and smart factories.” Government procurement will first open early demand in education, defense, disaster response, and other areas, then reduce reliance on foreign vendors through data, world models, and a domestic full stack. The real bottlenecks are data standards, mass-production costs, and SME financing.
Localization is the key to policy execution. Gwangju, the southwest region, Gumi, Ulsan, Geoje, Songdo, Yongin, Cheongju, and other areas are being embedded into the industrial division of labor. Supporting measures include regional electricity tariffs, dedicated AIDC power tariffs, enterprise-led advanced cities, 30-minute living circles, and one-hour logistics circles. Only if regions can retain engineers will the projects move beyond investment slogans.
The biggest risk is supply moving too far ahead. If global AI capex declines, memory price increases suppress end demand, or data center utilization falls short, South Korea will simultaneously face pressure from chip capacity expansion, data center depreciation, grid upgrades, and local fiscal support. Four metrics matter for follow-up: grid connection, actual HBM/DRAM capacity, contracted AIDC workloads, and robot orders converting into mass production.
I. This Is Not Ordinary Industrial Policy, but South Korea’s AI Reindustrialization Plan
The three major projects South Korea has announced appear on the surface to be semiconductors, Physical AI, and AI data centers. Underneath is a new growth narrative: connecting South Korea’s strongest legacy capability, memory manufacturing, to AI compute, robotics, data centers, power systems, and regional cities.
This approach rests on a clear premise. South Korea believes AI competition is not only at the model layer, but also at the layer of “intelligent means of production”: whoever can produce more memory, cheaper compute, more stable data centers, and more scalable robots can turn AI into an export industry, rather than merely buying GPUs, cloud services, and software.
That is why the goal is not framed as “supporting AI applications.” The policy language repeatedly uses terms such as AI factory, Token Factory, Physical AI full stack, national strategic industries, regional production bases, and enterprise-led cities. Behind all of these terms are fixed assets, long-term capital expenditure, and a reindustrialization project jointly borne by manufacturing, energy, and local governments.
The most important change is that South Korea is merging the traditional semiconductor cycle with the AI infrastructure cycle. In the past, memory capacity expansion was mainly tied to PC, smartphone, and server inventory cycles. This time, the rationale for expansion has become AI data centers, inference workloads, robots, and smart factories. As long as AI data centers continue to grow, DRAM, HBM, NAND, power equipment, cooling, packaging, and advanced materials will be placed in the same investment basket.
This is also why companies and the government spoke with such consistency at the meeting. The government is responsible for administration, land, power, water, taxes, funds, and initial demand; Samsung and SK are responsible for presenting massive investment projects; local governments are responsible for infrastructure and approvals; universities are responsible for talent; and SMEs are responsible for materials, robots, sensors, controllers, cloud software, and NPUs. What South Korea wants to build is not a policy package, but a national-level project management system.
II. Execution Logic of the Three Major Projects: First Use State Credit to Reduce Uncertainty, Then Accelerate Corporate Capex
The execution sequence of this South Korean plan is clear. The first step is top-level coordination; the second is infrastructure backstopping; the third is regional project deployment by companies; the fourth is using government procurement, tax tools, and financing tools to supplement early demand; and the final step is packaging these capabilities into export industries.
Whether this mechanism can work depends on whether the government can reduce the three uncertainties companies fear most: approval timelines, infrastructure costs, and future demand. The meeting repeatedly mentioned “one-stop administration directly overseen by the president,” “special committees,” and “new organizations within the presidential office.” This suggests South Korea already recognizes that ordinary inter-ministerial coordination is too slow for the capex windows in semiconductors and data centers.
Semiconductor expansion is most vulnerable to delays. For a new fab site, the process from site selection, environmental assessment, water use, power supply, land acquisition, and roads to equipment move-in can drag on for years, potentially missing a technology window. By putting Yongin, Cheongju, the southwest region, and Gwangju onto the same map, South Korea is trying both to preserve existing clusters in the capital region and to divert incremental capacity to areas with more flexible power and land conditions.
AI data centers are most constrained by power. South Korea plans to build 8.4GW of data center investment by 2029 and add another 10GW by 2035. This is a large number even globally, which means it cannot be absorbed only by the existing capital-region grid. The policy simultaneously mentions regional electricity tariffs, dedicated AIDC power tariffs, distributed grids, ESS, pumped hydro storage, SMRs, LNG-to-hydrogen transition, and renewable energy. In essence, it is searching for a long-term power cost curve for data centers.
Physical AI is most constrained by lack of scenarios. Robots and world models do not become industries through lab papers; they must enter factories, education, defense, disaster response, nursing care, and home services. South Korea has chosen government procurement first to provide domestic robot companies, sensor companies, actuator companies, model companies, and system integrators with an early order pool. Without this order pool, domestic robotics companies can easily be squeezed by overseas vendors on price and data scale.
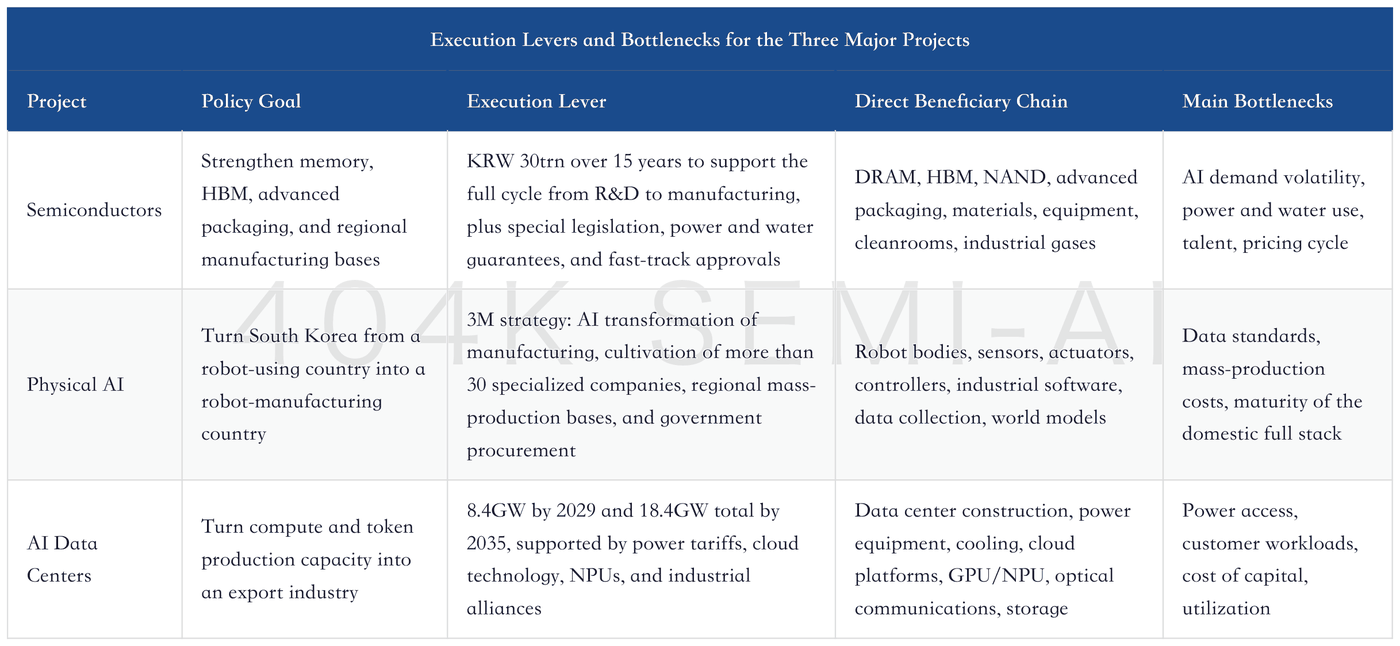
III. Semiconductor Main Line: Korea Wants to Use AI Demand to Rewrite the Supply Narrative for Memory
Semiconductors are the most certain and easiest-to-understand line in this package. Korea already has Samsung Electronics and SK hynix, with strong global memory share, HBM capabilities, and an advanced packaging base. What policy now aims to do is convert future demand from AI data centers and robotics into a rationale for memory capacity expansion.
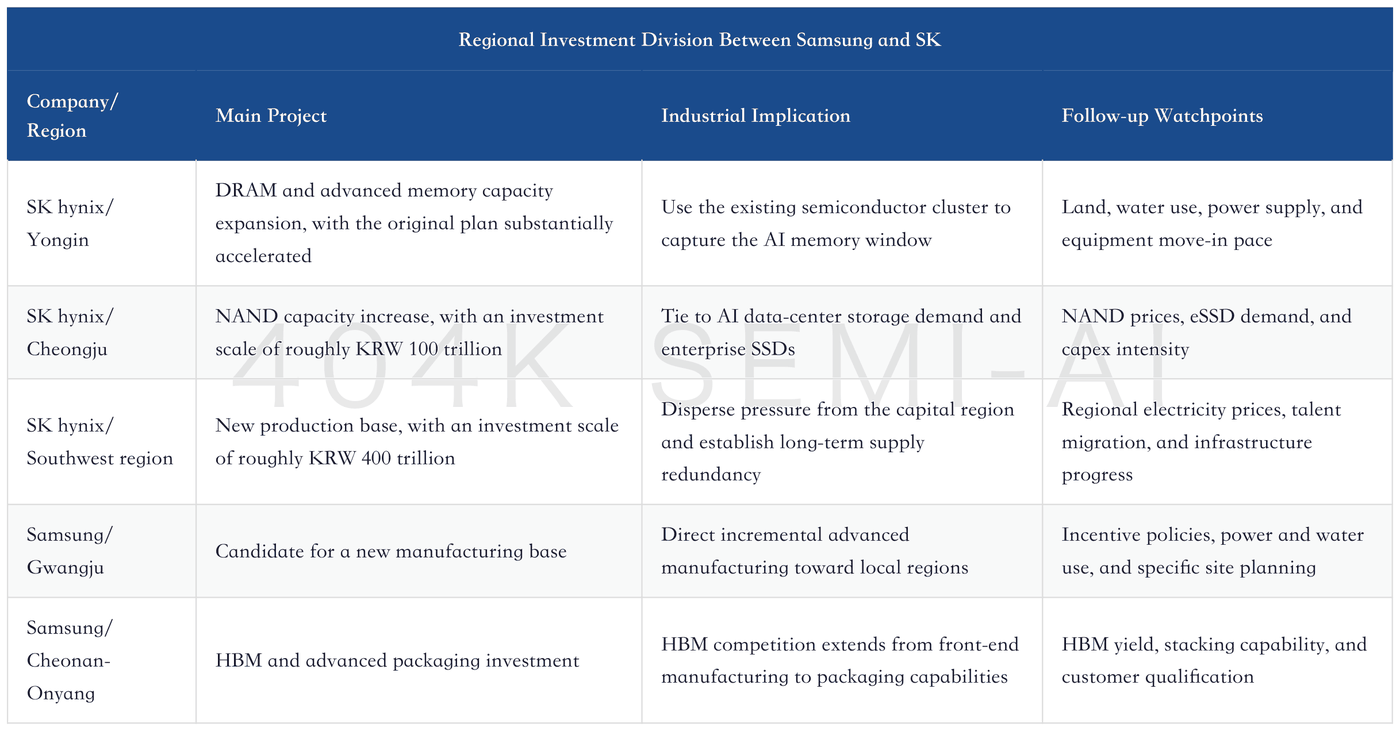
SK’s framing is the most direct: the more AI is used, the greater the demand for memory, and memory supply shortages will intensify. If supply is insufficient, excessively high prices will in turn suppress the AI market. Therefore, SK hynix has proposed accelerating the Yongin cluster, investing roughly KRW 600 trillion around DRAM, adding roughly KRW 100 trillion around NAND in Cheongju, and planning a new production base in the southwest region with roughly KRW 400 trillion of investment.
This logic is important for the memory industry. In the past, the market worried that capacity expansion by memory makers would repeat the pattern of oversupply. Korea now wants to argue that AI inference, training, data centers, and Physical AI will steepen the memory demand curve; capacity expansion is not about pushing prices down, but about preventing high prices from crowding out AI demand. In other words, it wants to replace the traditional memory-cycle narrative of “inventory repair” with “AI infrastructure shortage.”
Samsung’s division of labor looks more like a regional investment map. Gwangju is listed as a candidate for a new manufacturing base; Cheonan and Onyang will take on HBM and advanced packaging; Gumi will take on robotics-related investment; Ulsan will take on all-solid-state batteries and BESS; Geoje will continue shipbuilding; and Songdo will focus on biomanufacturing. Samsung is not talking only about semiconductors. It is telling the government that, as long as infrastructure and incentives keep pace, the group can allocate multiple industrial projects across different regions.
Deep Dive on Korean Technology: How HBM, MLCC, FC-BGA, TCB, and Enterprise AI Are Revalued Under the AI Compute and Memory Supercycle
This also has a direct impact on Korea’s domestic equipment and materials chain. Materials companies mentioned at the meeting that anhydrous hydrofluoric acid is highly dependent on Chinese supply, indicating that Korea remains concerned about critical materials being constrained by external supply chains. Once semiconductor capacity expansion enters actual construction, the beneficiaries will not only be fabs, but also specialty gases, wet electronic chemicals, photoresists, precursors, CMP materials, cleanrooms, vacuum pumps, inspection equipment, and package substrates.
The more practical constraints are water and electricity. At the meeting, the water-resources department specifically responded to water-supply issues in the southwest region, showing that companies already regard water as a hard condition in investment decisions. A semiconductor fab cannot relocate simply because land is cheap. It must also have highly reliable power, stable water sources, chemical supply, environmental treatment, and education and healthcare conditions for engineers’ families. Korea is now putting these issues into the same meeting, which means it is preemptively handling the landing costs that companies are unwilling to publicly assume.
IV. AI Data Centers: What Korea Really Wants to Export Is “Compute Factories,” Not Ordinary Server Rooms
AI data centers are the largest, most leveraged, and most failure-prone projects in this policy package. Korea proposes building 8.4GW of AI data centers by 2029, with investment of roughly KRW 550 trillion, and then adding another 10GW by 2035, bringing the total scale to 18.4GW and more than KRW 1,000 trillion. SK separately proposed building 15GW-scale AI data centers by 2035, with 5GW in the first phase and a sequential expansion to 10GW in the second phase.
AI data centers should not be understood here as traditional IDCs. Traditional data centers mainly sell storage, colocation, and cloud resources. AI data centers sell training and inference capacity, meaning “token production capacity.” At the meeting, they were called AI factories and Token Factories. The point is that as long as models and agents continue consuming tokens, data centers become basic means of production, like power plants and fabs.
How Much Is 1MW of Compute Worth: How Data Centers and Neoclouds Turn Power, GPUs, and Financing into Cash Flow
This logic is highly appealing to Korea. Korea has memory, power engineering, manufacturing customers, telecom operators, and NPU companies that it hopes to localize. As long as it can bind data centers, memory, NPUs, cloud scheduling, and customer applications together, Korea can move from “supplying memory to global AI” toward “supplying compute and intelligent services to global AI.”
The problem is that data-center projects are most vulnerable to being built too quickly while workloads fail to keep pace. A 1GW-scale AI data center requires extremely high capex, with GPUs, server rooms, power, cooling, networking, and operations all funded upfront. If customer demand, cloud software capabilities, and scheduling efficiency do not mature at the same time, the data center becomes a heavy-asset depreciation machine. Some companies at the meeting warned that “supply and demand must be matched simultaneously.” This was not a courtesy statement, but the core risk of such projects.
Korea’s solution to this risk has three layers. The first is regionalization: placing data centers in areas with electricity, land, and water to reduce constraints in the capital region. The second is electricity pricing: designing dedicated power tariffs for AI data centers to reduce long-term operating costs. The third is localization: localizing NPUs, cloud platforms, cluster scheduling, security, networking, and cooling equipment as much as possible, so Korea does not merely act as a landlord for overseas GPU and cloud vendors.
The near-term investment signals are also clear. Once AIDC enters actual construction, power transformers, high-voltage switches, UPS, liquid cooling, pipeline networks, optical modules, servers, storage, networking equipment, construction engineering, and BESS will benefit first. In the medium term, the question is whether cloud platforms, NPUs, inference optimization, and domestic AI chips can win customers. In the long term, the question is whether these data centers can be exported overseas or take on AI workloads from multinational companies.
V. Physical AI: Korea Wants to Turn Its Manufacturing Advantage into Export Capabilities in Robotics and Smart Factories
Physical AI is the least like Korea’s traditional advantages among the three major projects, but it is also the area most capable of opening a second growth curve. Korea’s judgment is that future robots will not merely be automation equipment, but physical agents with perception, decision-making, and action capabilities. Whoever first integrates robots, data, world models, factory scenarios, and mass-production systems will be able to redefine manufacturing efficiency.
The government’s 3M strategy can be broken down into three sentences. Max means accelerating the AI transformation of manufacturing and combining robots with Korea’s strong manufacturing capabilities. Master means cultivating specialized companies in key links, including data, robotics foundation models, core products, and talent, with a target of more than 30 companies. Mass Production means building regional mass-production bases, with the government first procuring in areas such as education, defense, and disaster response to create an early market.
This logic contains a practical judgment: Korea cannot only be a customer of foreign-funded robots. The meeting directly mentioned that if the industry continues to rely on external robots, domestic employment and the supply chain will both come under pressure. If robot development, production, components, and services remain domestic, new employment can be created. This shows that Physical AI is not merely an efficiency tool in Korean policy, but also an employment and local industrial policy.
The real difficulty lies in data. LLMs can obtain massive corpora from web text, but Physical AI requires action, objects, friction, weight, elasticity, environments, and failure cases from the real world. Companies at the meeting proposed having workers, craftspeople, and factories collect raw action data through first-person devices, with the government then purchasing data in the way it purchases agricultural products. This is an imaginative proposal, but it will also bring issues around privacy, standards, annotation quality, and rights allocation.
Korea’s opportunity lies in the breadth of its manufacturing sites. Automobiles, shipbuilding, semiconductors, batteries, electronics, catering, nursing, and logistics all have large numbers of action scenarios that can be collected, verified, and reused. If the government can establish unified data protocols and connect on-site data, synthetic simulation data, and world-model training, domestic robotics companies will gain data assets that overseas companies will find difficult to replicate in the short term.
In investment terms, Physical AI should not be viewed only through robot bodies. What is more worth tracking are actuators, reducers, sensors, controllers, industrial cameras, edge compute, simulation software, factory scheduling systems, data-collection tools, and system integrators. Gross margins for robot bodies may not improve first. The earliest monetization often comes from hardware and software solution providers that can enter factory retrofit budgets.
VI. Localization: Whether This Plan Works Depends on Whether Engineers Are Willing to Move There
This report spent considerable space on regions and cities, not because South Korea has suddenly become interested in urban construction, but because semiconductors, data centers, and robotics all require people to stay in local areas for the long term. Factories can be built with capital expenditure, but if engineers, suppliers, schools, hospitals, housing, and cultural facilities do not follow, local projects can easily become “plants without people.”
The land ministry proposed enterprise-led advanced cities, emphasizing the integration of industry, innovation, and living environments, with the goal of a 30-minute living circle and a one-hour logistics circle. This direction is very pragmatic. Semiconductor and AI data centers are not traditional remote suburban industrial parks. Talent has higher requirements for housing, education, healthcare, and culture. Without livable cities, companies can only rely on high salaries and commuting subsidies to hold the system together, and over time those costs will eat back into project returns.
Education is the area companies worry about most. SK hynix specifically mentioned at the meeting that if young talent works in local areas, their families cannot be forced into a weekend-couple arrangement; local areas must have good primary and secondary schools. This issue runs deeper than tax incentives. Local education quality determines whether engineers’ families can relocate, and whether engineers’ families can relocate determines whether industrial clusters can form.
Electricity pricing is also an important tool for localization. South Korea has proposed regional electricity pricing and dedicated AIDC electricity tariffs. Behind this is an industrial relocation logic: if local areas produce electricity but mainly transmit it to the Seoul metropolitan area, they lack a price advantage to attract advanced industries. Making electricity costs more competitive in power-producing regions can increase the probability that semiconductors and data centers locate in local areas.
This also means opportunities for local equipment and engineering companies. Semiconductor parks, data center parks, robotics mass-production bases, corporate housing, schools and hospitals, transport and logistics, and grid upgrades will create a multi-year order pool. Its investment cadence may come earlier than wafer equipment, because power, water, roads, and housing must start first before factories can truly land.
VII. Where the Money Comes From: Government Provides Certainty, Companies Provide Capex, Financial Tools Add Leverage
The funding scale of this plan is very large and cannot be simply understood as the government budget directly paying the bill. A more accurate structure is: the government uses budgets, taxes, special laws, land, infrastructure, and funds to reduce project uncertainty; companies use capital expenditure to undertake the main construction; and the financial system provides leverage through the National Growth Fund, tax credits, and long-term capital.
For semiconductors, the government explicitly mentioned KRW 30 trillion over 15 years to support the full cycle of R&D;, design, validation, and manufacturing. This figure itself is not shocking. The truly large money comes from Samsung and SK. In SK’s framing, AI data center projects amount to roughly KRW 1,000 trillion, semiconductor supply expansion projects roughly KRW 1,100 trillion, and average annual domestic investment over the next 10 years will exceed KRW 100 trillion. Samsung also placed multiple regional projects into the same investment plan.
For data centers, government targets and corporate targets are nested within each other. The government proposed 8.4GW by 2029 and a total of 18.4GW by 2035, while SK proposed reaching 15GW itself by 2035. This means South Korea will push data centers as quasi-infrastructure, but they still need companies and customer loads to prove returns. Without long-term power contracts, cloud customers, and a closed financing loop, it will be difficult for all projects to land according to the stated scale.
For Physical AI, government procurement and data purchases are more significant. Robotics companies and model companies have weak early cash flow, and capital-market financing alone is unlikely to support R&D;, data collection, and mass-production ramp-up. If the government can truly generate procurement in education, national defense, disaster response, nursing care, and other scenarios, it effectively provides the industrial chain with its first batch of verifiable orders.
SME financing is another key variable. At the meeting, a listed robotics company mentioned that the National Growth Fund tends to invest in unlisted companies and lend to listed companies, which may create financing differences. This issue will affect whether the Physical AI ecosystem can deepen. If only Samsung and SK secure major projects while SMEs cannot access reasonable funding, South Korea’s goal of building “full-stack domestic substitution” will be discounted.
VIII. Investment Implications for the Supply Chain: Look at Hard Assets First, Then Software and Model Delivery
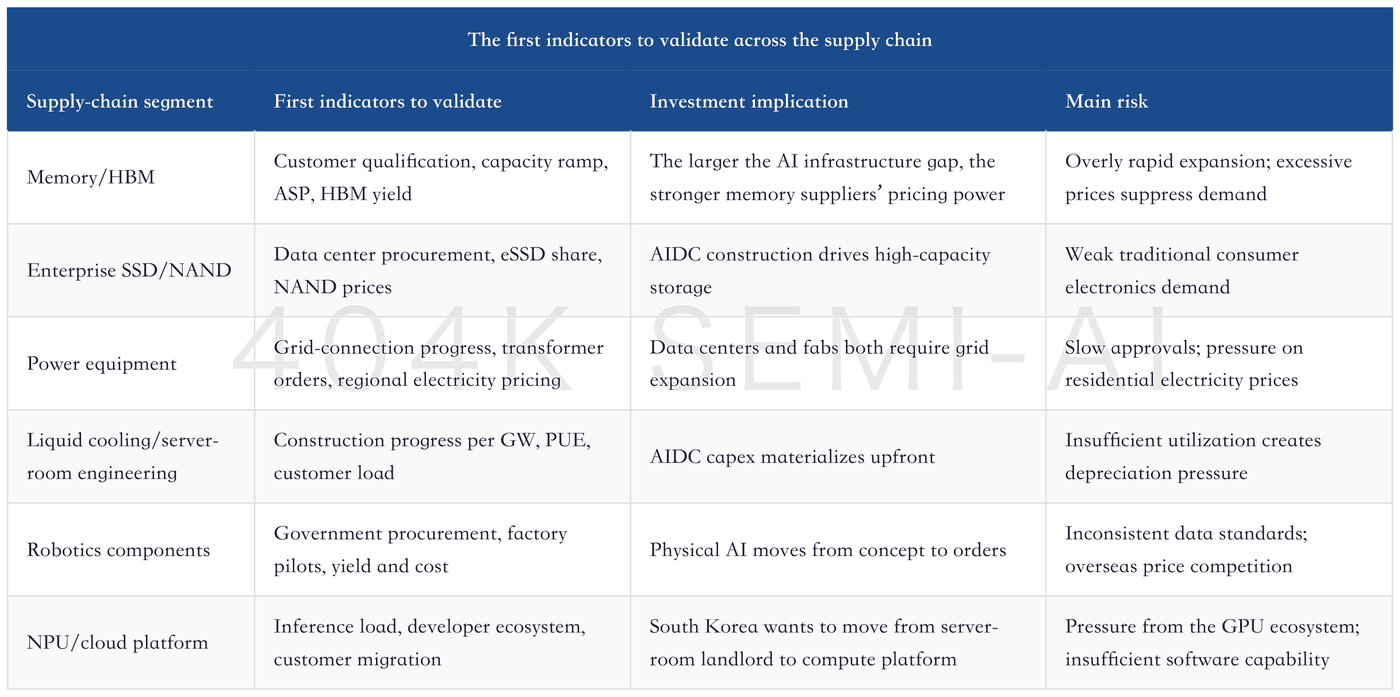
In terms of investment sequence, the first area to materialize is the hard-asset chain. Semiconductor capacity expansion will first pull demand for cleanrooms, facilities, equipment, materials, gases, power, and water treatment; data centers will first pull demand for power equipment, cooling, construction, servers, optical communications, and storage; local cities will first pull demand for engineering, transport, housing, and public services. These orders do not need to wait for robots to reach general intelligence. Demand emerges once projects start construction.
The second stage is equipment and component localization. If South Korea wants to reduce external dependence, it must strengthen anhydrous hydrofluoric acid, specialty gases, wet chemicals, advanced packaging materials, robot actuators, controllers, sensors, NPUs, and cloud orchestration software. This will create a group of companies that “used to be narrow, but are now amplified by national strategy.”
The Memory Tax Arrives: How AI Is Turning HBM, DRAM, and NAND into a Global Macro Bottleneck
Only in the third stage should investors look at models and platforms. Physical AI world models, robotics foundation models, industrial data platforms, AI cloud operating systems, and the token economy sound like they have the greatest upside imagination, but their commercialization validation is the slowest. They require real data, customer scenarios, compute costs, and continuous iteration. In investment, investors cannot look only at slogans; they must look at orders, retention, marginal costs, and whether the model can be replicated across scenarios.
The mapping of South Korean assets can be divided into four groups. The first group is the memory and packaging mainline, directly driven by AI data centers. The second group is power and energy equipment, benefiting from electricity demand from data centers and semiconductor fabs. The third group is robotics and factory automation, benefiting from government procurement and manufacturing upgrades. The fourth group is regional engineering and infrastructure, benefiting from the construction of local industrial cities.
Follow the Power: AI Data Centers Move from GPU Shortages to Revaluation of the Grid, 800V, and Power Semiconductors
IX. Three Possible Paths: From National-Level Success to Heavy-Asset Indigestion
In the optimistic scenario, AI data center demand continues to rise, and South Korea uses its memory and engineering capabilities to capture incremental global compute infrastructure. Semiconductor expansion does not crash prices, while HBM and enterprise storage remain in short supply; regional electricity pricing and infrastructure make local projects work; Physical AI secures its first batch of data and orders through government procurement. In this scenario, South Korea upgrades from a memory powerhouse to an AI infrastructure supplier.
In the neutral scenario, memory expansion and data center construction partially materialize, but Physical AI progresses more slowly. Semiconductors and power equipment benefit first, while robotics and NPUs remain at the pilot stage; local city construction advances, but talent migration is average. This is the most likely scenario: hard assets have orders, software and model delivery lags, and the market must continually distinguish which projects have truly started and which are merely policy slogans.
South Korea’s AI Surplus in Depth: How the Memory Supercycle Revalues Fiscal Policy, Rates, and the Won
In the pessimistic scenario, global AI capital expenditure rolls over from a high base, utilization is insufficient after data centers are completed, memory prices rise too quickly and suppress end demand, and pressure increases on local infrastructure and fiscal support. The government can still push projects, but corporate balance sheets will come under pressure. In this scenario, semiconductor expansion shifts from “removing the supply bottleneck” to “the next risk of oversupply,” and AI data centers shift from “Token Factory” to “depreciation black hole.”
The most important thing to avoid in investing is assuming all numbers fully land. Many figures at the meeting were targets, visions, or project pools, not signed capex orders. South Korea’s advantages are its strong industrial base, high corporate concentration, and strong government coordination capability; its shortcomings are power, local talent, software ecosystem, and heavy-asset financing. Subsequent judgment should rely on project milestones, not press-conference numbers.
JPMorgan Sees the KOSPI at 15,000: Is This South Korean Rally an AI Bubble or a Revaluation of National Wealth?
10. Follow-Up Indicators: Whether Projects Move From Slogans to Cash Flow
First, power. Watch whether dedicated electricity tariffs for AIDCs are introduced, whether the regional grid-connection plan for the 8.4GW project becomes clear, and whether orders for transformers, transmission lines, ESS, and cooling systems materialize. Without electricity, data centers and fabs are just PowerPoint slides.
Second, memory supply. The actual start of construction, equipment move-in, and mass-production timing for SK Hynix’s Yongin and Cheongju projects matter more than the headline investment amount. Samsung’s HBM packaging progress in Cheonan and Onyang also needs tracking, especially yield, customer qualification, and next-generation product cadence.
Third, data-center customers. Whether Korea can secure long-term workload agreements from domestic conglomerates, the government, cloud providers, and overseas customers is central to determining whether AIDCs will generate cash flow. Seeing only GW figures without customers and utilization rates is highly risky.
Fourth, Physical AI orders. Whether government procurement truly covers education, defense, disaster response, and care scenarios; whether robotics companies move from pilots to batch delivery; whether data-collection standards become unified; and whether world models can be reused in factories are all more verifiable than a “20% global share” target.
Fifth, local absorption capacity. Watch whether regions such as Gwangju, the Southwest region, Gumi, Ulsan, Geoje, and Songdo simultaneously introduce policies for housing, schools, hospitals, transportation, and talent. Local projects cannot rely solely on tax incentives; ultimately, they depend on engineers’ families being willing to stay for the long term.
Sixth, financial constraints. Watch whether the National Growth Fund, tax credits, corporate-bond financing, project financing, and local fiscal resources can form a stable funding chain. Heavy-asset projects fear simultaneous headwinds in interest rates, exchange rates, and demand. Korea’s project scale this time is large enough that financing costs will directly affect final returns.
11. Conclusion: Korea Is Betting the AI Cycle Will Last Long Enough to Absorb a National-Scale Capex Wave
The underlying bet behind Korea’s three major projects is clear: AI is not a short software rally, but an infrastructure cycle that requires long-term buildout of computing power, memory, electricity, robotics, and manufacturing bases. As long as that judgment holds, Korea’s memory, engineering, manufacturing, and regional industrial policies have a chance to reinforce one another.
This is also what makes the plan most attractive. Korea is not building AI from scratch; it is entering from its strongest areas: memory, advanced manufacturing, conglomerate capex, supply-chain organization, and engineering execution. It may not defeat U.S. giants in general-purpose large models, but it can try to secure a higher position in AI infrastructure and Physical AI manufacturing systems.
Its biggest risk comes from the same place. The larger the projects, the more they require AI demand to keep rising. The heavier the infrastructure, the more vulnerable it is to insufficient utilization. The more aggressive the regionalization, the more it tests electricity, education, housing, and local public finances. If the AI capex cycle cools earlier than expected, these projects will simultaneously face capacity expansion, depreciation, and financing pressure.
So this plan should not be assessed only by the “trillion-won investment” in the headline. The more important question is whether Korea can deliver four things in sequence: first connect the power and water, then build semiconductor capacity, then fill AI data centers with workloads, and finally generate repeatable orders from Physical AI. If these four steps are delivered in succession, Korea will move from a memory-cycle-stock narrative to an AI-infrastructure national-team narrative. If any one link clearly falls behind, the market will reprice it as an ordinary heavy-asset cycle.The Over-$700 Billion AI Bet: SK Hynix, Samsung, and the South Korean Government Are Going All-In on Compute Infrastructure
目录
TL;DR
I. This Is Not Ordinary Industrial Policy, but South Korea’s AI Reindustrialization Plan
II. Execution Logic of the Three Major Projects: First Use State Credit to Reduce Uncertainty, Then Accelerate Corporate Capex
III. Semiconductor Main Line: Korea Wants to Use AI Demand to Rewrite the Supply Narrative for Memory
IV. AI Data Centers: What Korea Really Wants to Export Is “Compute Factories,” Not Ordinary Server Rooms
V. Physical AI: Korea Wants to Turn Its Manufacturing Advantage into Export Capabilities in Robotics and Smart Factories
VI. Localization: Whether This Plan Works Depends on Whether Engineers Are Willing to Move There
VII. Where the Money Comes From: Government Provides Certainty, Companies Provide Capex, Financial Tools Add Leverage
VIII. Investment Implications for the Supply Chain: Look at Hard Assets First, Then Software and Model Delivery
IX. Three Possible Paths: From National-Level Success to Heavy-Asset Indigestion
10. Follow-Up Indicators: Whether Projects Move From Slogans to Cash Flow
11. Conclusion: Korea Is Betting the AI Cycle Will Last Long Enough to Absorb a National-Scale Capex Wave
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The real goal of South Korea’s three major projects is to bind memory supply, AI data centers, robotics manufacturing, power, and local infrastructure into a closed-loop reindustrialization system. The investment opportunity is not only in chip capacity expansion, but also in whether compute utilization, power access, domestic NPUs, Physical AI data, and regional carrying capacity can be delivered.
TL;DR
South Korea is treating AI as a reindustrialization project. The three major projects are not standalone semiconductor subsidies; they combine memory, AI data centers, Physical AI, regional cities, and the power system into one industrial balance sheet. In the short term, the story is investment-led growth. In the long term, the question is whether South Korea can upgrade from “producing chips” to “producing intelligent infrastructure.”
Semiconductors remain the foundation of every project. The government’s framing is KRW 30trn over 15 years to support R&D;, design, validation, and manufacturing. Corporate plans are more aggressive: SK has proposed a project pool of roughly KRW 2,100trn around AI data centers and memory capacity expansion, while Samsung is spreading new manufacturing bases, HBM packaging, robotics, batteries, and biomanufacturing across multiple regions.
AI data centers are the largest lever. South Korea plans to build 8.4GW of capacity by 2029, implying roughly KRW 550trn of investment, and add another 10GW by 2035, reaching 18.4GW in total and more than KRW 1,000trn. Project success does not depend on whether server rooms can be built, but on whether power, cloud platforms, NPU/GPU supply, and customer workloads arrive at the same time.
Physical AI addresses manufacturing’s second growth curve. South Korea wants to move from “using robots” to “building robots and smart factories.” Government procurement will first open early demand in education, defense, disaster response, and other areas, then reduce reliance on foreign vendors through data, world models, and a domestic full stack. The real bottlenecks are data standards, mass-production costs, and SME financing.
Localization is the key to policy execution. Gwangju, the southwest region, Gumi, Ulsan, Geoje, Songdo, Yongin, Cheongju, and other areas are being embedded into the industrial division of labor. Supporting measures include regional electricity tariffs, dedicated AIDC power tariffs, enterprise-led advanced cities, 30-minute living circles, and one-hour logistics circles. Only if regions can retain engineers will the projects move beyond investment slogans.
The biggest risk is supply moving too far ahead. If global AI capex declines, memory price increases suppress end demand, or data center utilization falls short, South Korea will simultaneously face pressure from chip capacity expansion, data center depreciation, grid upgrades, and local fiscal support. Four metrics matter for follow-up: grid connection, actual HBM/DRAM capacity, contracted AIDC workloads, and robot orders converting into mass production.
I. This Is Not Ordinary Industrial Policy, but South Korea’s AI Reindustrialization Plan
The three major projects South Korea has announced appear on the surface to be semiconductors, Physical AI, and AI data centers. Underneath is a new growth narrative: connecting South Korea’s strongest legacy capability, memory manufacturing, to AI compute, robotics, data centers, power systems, and regional cities.
This approach rests on a clear premise. South Korea believes AI competition is not only at the model layer, but also at the layer of “intelligent means of production”: whoever can produce more memory, cheaper compute, more stable data centers, and more scalable robots can turn AI into an export industry, rather than merely buying GPUs, cloud services, and software.
That is why the goal is not framed as “supporting AI applications.” The policy language repeatedly uses terms such as AI factory, Token Factory, Physical AI full stack, national strategic industries, regional production bases, and enterprise-led cities. Behind all of these terms are fixed assets, long-term capital expenditure, and a reindustrialization project jointly borne by manufacturing, energy, and local governments.
The most important change is that South Korea is merging the traditional semiconductor cycle with the AI infrastructure cycle. In the past, memory capacity expansion was mainly tied to PC, smartphone, and server inventory cycles. This time, the rationale for expansion has become AI data centers, inference workloads, robots, and smart factories. As long as AI data centers continue to grow, DRAM, HBM, NAND, power equipment, cooling, packaging, and advanced materials will be placed in the same investment basket.
This is also why companies and the government spoke with such consistency at the meeting. The government is responsible for administration, land, power, water, taxes, funds, and initial demand; Samsung and SK are responsible for presenting massive investment projects; local governments are responsible for infrastructure and approvals; universities are responsible for talent; and SMEs are responsible for materials, robots, sensors, controllers, cloud software, and NPUs. What South Korea wants to build is not a policy package, but a national-level project management system.
II. Execution Logic of the Three Major Projects: First Use State Credit to Reduce Uncertainty, Then Accelerate Corporate Capex
The execution sequence of this South Korean plan is clear. The first step is top-level coordination; the second is infrastructure backstopping; the third is regional project deployment by companies; the fourth is using government procurement, tax tools, and financing tools to supplement early demand; and the final step is packaging these capabilities into export industries.
Whether this mechanism can work depends on whether the government can reduce the three uncertainties companies fear most: approval timelines, infrastructure costs, and future demand. The meeting repeatedly mentioned “one-stop administration directly overseen by the president,” “special committees,” and “new organizations within the presidential office.” This suggests South Korea already recognizes that ordinary inter-ministerial coordination is too slow for the capex windows in semiconductors and data centers.
Semiconductor expansion is most vulnerable to delays. For a new fab site, the process from site selection, environmental assessment, water use, power supply, land acquisition, and roads to equipment move-in can drag on for years, potentially missing a technology window. By putting Yongin, Cheongju, the southwest region, and Gwangju onto the same map, South Korea is trying both to preserve existing clusters in the capital region and to divert incremental capacity to areas with more flexible power and land conditions.
AI data centers are most constrained by power. South Korea plans to build 8.4GW of data center investment by 2029 and add another 10GW by 2035. This is a large number even globally, which means it cannot be absorbed only by the existing capital-region grid. The policy simultaneously mentions regional electricity tariffs, dedicated AIDC power tariffs, distributed grids, ESS, pumped hydro storage, SMRs, LNG-to-hydrogen transition, and renewable energy. In essence, it is searching for a long-term power cost curve for data centers.
Physical AI is most constrained by lack of scenarios. Robots and world models do not become industries through lab papers; they must enter factories, education, defense, disaster response, nursing care, and home services. South Korea has chosen government procurement first to provide domestic robot companies, sensor companies, actuator companies, model companies, and system integrators with an early order pool. Without this order pool, domestic robotics companies can easily be squeezed by overseas vendors on price and data scale.
III. Semiconductor Main Line: Korea Wants to Use AI Demand to Rewrite the Supply Narrative for Memory
Semiconductors are the most certain and easiest-to-understand line in this package. Korea already has Samsung Electronics and SK hynix, with strong global memory share, HBM capabilities, and an advanced packaging base. What policy now aims to do is convert future demand from AI data centers and robotics into a rationale for memory capacity expansion.
SK’s framing is the most direct: the more AI is used, the greater the demand for memory, and memory supply shortages will intensify. If supply is insufficient, excessively high prices will in turn suppress the AI market. Therefore, SK hynix has proposed accelerating the Yongin cluster, investing roughly KRW 600 trillion around DRAM, adding roughly KRW 100 trillion around NAND in Cheongju, and planning a new production base in the southwest region with roughly KRW 400 trillion of investment.
This logic is important for the memory industry. In the past, the market worried that capacity expansion by memory makers would repeat the pattern of oversupply. Korea now wants to argue that AI inference, training, data centers, and Physical AI will steepen the memory demand curve; capacity expansion is not about pushing prices down, but about preventing high prices from crowding out AI demand. In other words, it wants to replace the traditional memory-cycle narrative of “inventory repair” with “AI infrastructure shortage.”
Samsung’s division of labor looks more like a regional investment map. Gwangju is listed as a candidate for a new manufacturing base; Cheonan and Onyang will take on HBM and advanced packaging; Gumi will take on robotics-related investment; Ulsan will take on all-solid-state batteries and BESS; Geoje will continue shipbuilding; and Songdo will focus on biomanufacturing. Samsung is not talking only about semiconductors. It is telling the government that, as long as infrastructure and incentives keep pace, the group can allocate multiple industrial projects across different regions.
Deep Dive on Korean Technology: How HBM, MLCC, FC-BGA, TCB, and Enterprise AI Are Revalued Under the AI Compute and Memory Supercycle
This also has a direct impact on Korea’s domestic equipment and materials chain. Materials companies mentioned at the meeting that anhydrous hydrofluoric acid is highly dependent on Chinese supply, indicating that Korea remains concerned about critical materials being constrained by external supply chains. Once semiconductor capacity expansion enters actual construction, the beneficiaries will not only be fabs, but also specialty gases, wet electronic chemicals, photoresists, precursors, CMP materials, cleanrooms, vacuum pumps, inspection equipment, and package substrates.
The more practical constraints are water and electricity. At the meeting, the water-resources department specifically responded to water-supply issues in the southwest region, showing that companies already regard water as a hard condition in investment decisions. A semiconductor fab cannot relocate simply because land is cheap. It must also have highly reliable power, stable water sources, chemical supply, environmental treatment, and education and healthcare conditions for engineers’ families. Korea is now putting these issues into the same meeting, which means it is preemptively handling the landing costs that companies are unwilling to publicly assume.
IV. AI Data Centers: What Korea Really Wants to Export Is “Compute Factories,” Not Ordinary Server Rooms
AI data centers are the largest, most leveraged, and most failure-prone projects in this policy package. Korea proposes building 8.4GW of AI data centers by 2029, with investment of roughly KRW 550 trillion, and then adding another 10GW by 2035, bringing the total scale to 18.4GW and more than KRW 1,000 trillion. SK separately proposed building 15GW-scale AI data centers by 2035, with 5GW in the first phase and a sequential expansion to 10GW in the second phase.
AI data centers should not be understood here as traditional IDCs. Traditional data centers mainly sell storage, colocation, and cloud resources. AI data centers sell training and inference capacity, meaning “token production capacity.” At the meeting, they were called AI factories and Token Factories. The point is that as long as models and agents continue consuming tokens, data centers become basic means of production, like power plants and fabs.
How Much Is 1MW of Compute Worth: How Data Centers and Neoclouds Turn Power, GPUs, and Financing into Cash Flow
This logic is highly appealing to Korea. Korea has memory, power engineering, manufacturing customers, telecom operators, and NPU companies that it hopes to localize. As long as it can bind data centers, memory, NPUs, cloud scheduling, and customer applications together, Korea can move from “supplying memory to global AI” toward “supplying compute and intelligent services to global AI.”
The problem is that data-center projects are most vulnerable to being built too quickly while workloads fail to keep pace. A 1GW-scale AI data center requires extremely high capex, with GPUs, server rooms, power, cooling, networking, and operations all funded upfront. If customer demand, cloud software capabilities, and scheduling efficiency do not mature at the same time, the data center becomes a heavy-asset depreciation machine. Some companies at the meeting warned that “supply and demand must be matched simultaneously.” This was not a courtesy statement, but the core risk of such projects.
Korea’s solution to this risk has three layers. The first is regionalization: placing data centers in areas with electricity, land, and water to reduce constraints in the capital region. The second is electricity pricing: designing dedicated power tariffs for AI data centers to reduce long-term operating costs. The third is localization: localizing NPUs, cloud platforms, cluster scheduling, security, networking, and cooling equipment as much as possible, so Korea does not merely act as a landlord for overseas GPU and cloud vendors.
The near-term investment signals are also clear. Once AIDC enters actual construction, power transformers, high-voltage switches, UPS, liquid cooling, pipeline networks, optical modules, servers, storage, networking equipment, construction engineering, and BESS will benefit first. In the medium term, the question is whether cloud platforms, NPUs, inference optimization, and domestic AI chips can win customers. In the long term, the question is whether these data centers can be exported overseas or take on AI workloads from multinational companies.
V. Physical AI: Korea Wants to Turn Its Manufacturing Advantage into Export Capabilities in Robotics and Smart Factories
Physical AI is the least like Korea’s traditional advantages among the three major projects, but it is also the area most capable of opening a second growth curve. Korea’s judgment is that future robots will not merely be automation equipment, but physical agents with perception, decision-making, and action capabilities. Whoever first integrates robots, data, world models, factory scenarios, and mass-production systems will be able to redefine manufacturing efficiency.
The government’s 3M strategy can be broken down into three sentences. Max means accelerating the AI transformation of manufacturing and combining robots with Korea’s strong manufacturing capabilities. Master means cultivating specialized companies in key links, including data, robotics foundation models, core products, and talent, with a target of more than 30 companies. Mass Production means building regional mass-production bases, with the government first procuring in areas such as education, defense, and disaster response to create an early market.
This logic contains a practical judgment: Korea cannot only be a customer of foreign-funded robots. The meeting directly mentioned that if the industry continues to rely on external robots, domestic employment and the supply chain will both come under pressure. If robot development, production, components, and services remain domestic, new employment can be created. This shows that Physical AI is not merely an efficiency tool in Korean policy, but also an employment and local industrial policy.
The real difficulty lies in data. LLMs can obtain massive corpora from web text, but Physical AI requires action, objects, friction, weight, elasticity, environments, and failure cases from the real world. Companies at the meeting proposed having workers, craftspeople, and factories collect raw action data through first-person devices, with the government then purchasing data in the way it purchases agricultural products. This is an imaginative proposal, but it will also bring issues around privacy, standards, annotation quality, and rights allocation.
Korea’s opportunity lies in the breadth of its manufacturing sites. Automobiles, shipbuilding, semiconductors, batteries, electronics, catering, nursing, and logistics all have large numbers of action scenarios that can be collected, verified, and reused. If the government can establish unified data protocols and connect on-site data, synthetic simulation data, and world-model training, domestic robotics companies will gain data assets that overseas companies will find difficult to replicate in the short term.
In investment terms, Physical AI should not be viewed only through robot bodies. What is more worth tracking are actuators, reducers, sensors, controllers, industrial cameras, edge compute, simulation software, factory scheduling systems, data-collection tools, and system integrators. Gross margins for robot bodies may not improve first. The earliest monetization often comes from hardware and software solution providers that can enter factory retrofit budgets.
VI. Localization: Whether This Plan Works Depends on Whether Engineers Are Willing to Move There
This report spent considerable space on regions and cities, not because South Korea has suddenly become interested in urban construction, but because semiconductors, data centers, and robotics all require people to stay in local areas for the long term. Factories can be built with capital expenditure, but if engineers, suppliers, schools, hospitals, housing, and cultural facilities do not follow, local projects can easily become “plants without people.”
The land ministry proposed enterprise-led advanced cities, emphasizing the integration of industry, innovation, and living environments, with the goal of a 30-minute living circle and a one-hour logistics circle. This direction is very pragmatic. Semiconductor and AI data centers are not traditional remote suburban industrial parks. Talent has higher requirements for housing, education, healthcare, and culture. Without livable cities, companies can only rely on high salaries and commuting subsidies to hold the system together, and over time those costs will eat back into project returns.
Education is the area companies worry about most. SK hynix specifically mentioned at the meeting that if young talent works in local areas, their families cannot be forced into a weekend-couple arrangement; local areas must have good primary and secondary schools. This issue runs deeper than tax incentives. Local education quality determines whether engineers’ families can relocate, and whether engineers’ families can relocate determines whether industrial clusters can form.
Electricity pricing is also an important tool for localization. South Korea has proposed regional electricity pricing and dedicated AIDC electricity tariffs. Behind this is an industrial relocation logic: if local areas produce electricity but mainly transmit it to the Seoul metropolitan area, they lack a price advantage to attract advanced industries. Making electricity costs more competitive in power-producing regions can increase the probability that semiconductors and data centers locate in local areas.
This also means opportunities for local equipment and engineering companies. Semiconductor parks, data center parks, robotics mass-production bases, corporate housing, schools and hospitals, transport and logistics, and grid upgrades will create a multi-year order pool. Its investment cadence may come earlier than wafer equipment, because power, water, roads, and housing must start first before factories can truly land.
VII. Where the Money Comes From: Government Provides Certainty, Companies Provide Capex, Financial Tools Add Leverage
The funding scale of this plan is very large and cannot be simply understood as the government budget directly paying the bill. A more accurate structure is: the government uses budgets, taxes, special laws, land, infrastructure, and funds to reduce project uncertainty; companies use capital expenditure to undertake the main construction; and the financial system provides leverage through the National Growth Fund, tax credits, and long-term capital.
For semiconductors, the government explicitly mentioned KRW 30 trillion over 15 years to support the full cycle of R&D;, design, validation, and manufacturing. This figure itself is not shocking. The truly large money comes from Samsung and SK. In SK’s framing, AI data center projects amount to roughly KRW 1,000 trillion, semiconductor supply expansion projects roughly KRW 1,100 trillion, and average annual domestic investment over the next 10 years will exceed KRW 100 trillion. Samsung also placed multiple regional projects into the same investment plan.
For data centers, government targets and corporate targets are nested within each other. The government proposed 8.4GW by 2029 and a total of 18.4GW by 2035, while SK proposed reaching 15GW itself by 2035. This means South Korea will push data centers as quasi-infrastructure, but they still need companies and customer loads to prove returns. Without long-term power contracts, cloud customers, and a closed financing loop, it will be difficult for all projects to land according to the stated scale.
For Physical AI, government procurement and data purchases are more significant. Robotics companies and model companies have weak early cash flow, and capital-market financing alone is unlikely to support R&D;, data collection, and mass-production ramp-up. If the government can truly generate procurement in education, national defense, disaster response, nursing care, and other scenarios, it effectively provides the industrial chain with its first batch of verifiable orders.
SME financing is another key variable. At the meeting, a listed robotics company mentioned that the National Growth Fund tends to invest in unlisted companies and lend to listed companies, which may create financing differences. This issue will affect whether the Physical AI ecosystem can deepen. If only Samsung and SK secure major projects while SMEs cannot access reasonable funding, South Korea’s goal of building “full-stack domestic substitution” will be discounted.
VIII. Investment Implications for the Supply Chain: Look at Hard Assets First, Then Software and Model Delivery
In terms of investment sequence, the first area to materialize is the hard-asset chain. Semiconductor capacity expansion will first pull demand for cleanrooms, facilities, equipment, materials, gases, power, and water treatment; data centers will first pull demand for power equipment, cooling, construction, servers, optical communications, and storage; local cities will first pull demand for engineering, transport, housing, and public services. These orders do not need to wait for robots to reach general intelligence. Demand emerges once projects start construction.
The second stage is equipment and component localization. If South Korea wants to reduce external dependence, it must strengthen anhydrous hydrofluoric acid, specialty gases, wet chemicals, advanced packaging materials, robot actuators, controllers, sensors, NPUs, and cloud orchestration software. This will create a group of companies that “used to be narrow, but are now amplified by national strategy.”
The Memory Tax Arrives: How AI Is Turning HBM, DRAM, and NAND into a Global Macro Bottleneck
Only in the third stage should investors look at models and platforms. Physical AI world models, robotics foundation models, industrial data platforms, AI cloud operating systems, and the token economy sound like they have the greatest upside imagination, but their commercialization validation is the slowest. They require real data, customer scenarios, compute costs, and continuous iteration. In investment, investors cannot look only at slogans; they must look at orders, retention, marginal costs, and whether the model can be replicated across scenarios.
The mapping of South Korean assets can be divided into four groups. The first group is the memory and packaging mainline, directly driven by AI data centers. The second group is power and energy equipment, benefiting from electricity demand from data centers and semiconductor fabs. The third group is robotics and factory automation, benefiting from government procurement and manufacturing upgrades. The fourth group is regional engineering and infrastructure, benefiting from the construction of local industrial cities.
Follow the Power: AI Data Centers Move from GPU Shortages to Revaluation of the Grid, 800V, and Power Semiconductors
IX. Three Possible Paths: From National-Level Success to Heavy-Asset Indigestion
In the optimistic scenario, AI data center demand continues to rise, and South Korea uses its memory and engineering capabilities to capture incremental global compute infrastructure. Semiconductor expansion does not crash prices, while HBM and enterprise storage remain in short supply; regional electricity pricing and infrastructure make local projects work; Physical AI secures its first batch of data and orders through government procurement. In this scenario, South Korea upgrades from a memory powerhouse to an AI infrastructure supplier.
In the neutral scenario, memory expansion and data center construction partially materialize, but Physical AI progresses more slowly. Semiconductors and power equipment benefit first, while robotics and NPUs remain at the pilot stage; local city construction advances, but talent migration is average. This is the most likely scenario: hard assets have orders, software and model delivery lags, and the market must continually distinguish which projects have truly started and which are merely policy slogans.
South Korea’s AI Surplus in Depth: How the Memory Supercycle Revalues Fiscal Policy, Rates, and the Won
In the pessimistic scenario, global AI capital expenditure rolls over from a high base, utilization is insufficient after data centers are completed, memory prices rise too quickly and suppress end demand, and pressure increases on local infrastructure and fiscal support. The government can still push projects, but corporate balance sheets will come under pressure. In this scenario, semiconductor expansion shifts from “removing the supply bottleneck” to “the next risk of oversupply,” and AI data centers shift from “Token Factory” to “depreciation black hole.”
The most important thing to avoid in investing is assuming all numbers fully land. Many figures at the meeting were targets, visions, or project pools, not signed capex orders. South Korea’s advantages are its strong industrial base, high corporate concentration, and strong government coordination capability; its shortcomings are power, local talent, software ecosystem, and heavy-asset financing. Subsequent judgment should rely on project milestones, not press-conference numbers.
JPMorgan Sees the KOSPI at 15,000: Is This South Korean Rally an AI Bubble or a Revaluation of National Wealth?
10. Follow-Up Indicators: Whether Projects Move From Slogans to Cash Flow
First, power. Watch whether dedicated electricity tariffs for AIDCs are introduced, whether the regional grid-connection plan for the 8.4GW project becomes clear, and whether orders for transformers, transmission lines, ESS, and cooling systems materialize. Without electricity, data centers and fabs are just PowerPoint slides.
Second, memory supply. The actual start of construction, equipment move-in, and mass-production timing for SK Hynix’s Yongin and Cheongju projects matter more than the headline investment amount. Samsung’s HBM packaging progress in Cheonan and Onyang also needs tracking, especially yield, customer qualification, and next-generation product cadence.
Third, data-center customers. Whether Korea can secure long-term workload agreements from domestic conglomerates, the government, cloud providers, and overseas customers is central to determining whether AIDCs will generate cash flow. Seeing only GW figures without customers and utilization rates is highly risky.
Fourth, Physical AI orders. Whether government procurement truly covers education, defense, disaster response, and care scenarios; whether robotics companies move from pilots to batch delivery; whether data-collection standards become unified; and whether world models can be reused in factories are all more verifiable than a “20% global share” target.
Fifth, local absorption capacity. Watch whether regions such as Gwangju, the Southwest region, Gumi, Ulsan, Geoje, and Songdo simultaneously introduce policies for housing, schools, hospitals, transportation, and talent. Local projects cannot rely solely on tax incentives; ultimately, they depend on engineers’ families being willing to stay for the long term.
Sixth, financial constraints. Watch whether the National Growth Fund, tax credits, corporate-bond financing, project financing, and local fiscal resources can form a stable funding chain. Heavy-asset projects fear simultaneous headwinds in interest rates, exchange rates, and demand. Korea’s project scale this time is large enough that financing costs will directly affect final returns.
11. Conclusion: Korea Is Betting the AI Cycle Will Last Long Enough to Absorb a National-Scale Capex Wave
The underlying bet behind Korea’s three major projects is clear: AI is not a short software rally, but an infrastructure cycle that requires long-term buildout of computing power, memory, electricity, robotics, and manufacturing bases. As long as that judgment holds, Korea’s memory, engineering, manufacturing, and regional industrial policies have a chance to reinforce one another.
This is also what makes the plan most attractive. Korea is not building AI from scratch; it is entering from its strongest areas: memory, advanced manufacturing, conglomerate capex, supply-chain organization, and engineering execution. It may not defeat U.S. giants in general-purpose large models, but it can try to secure a higher position in AI infrastructure and Physical AI manufacturing systems.
Its biggest risk comes from the same place. The larger the projects, the more they require AI demand to keep rising. The heavier the infrastructure, the more vulnerable it is to insufficient utilization. The more aggressive the regionalization, the more it tests electricity, education, housing, and local public finances. If the AI capex cycle cools earlier than expected, these projects will simultaneously face capacity expansion, depreciation, and financing pressure.
So this plan should not be assessed only by the “trillion-won investment” in the headline. The more important question is whether Korea can deliver four things in sequence: first connect the power and water, then build semiconductor capacity, then fill AI data centers with workloads, and finally generate repeatable orders from Physical AI. If these four steps are delivered in succession, Korea will move from a memory-cycle-stock narrative to an AI-infrastructure national-team narrative. If any one link clearly falls behind, the market will reprice it as an ordinary heavy-asset cycle.