
目录
Executive Summary
I. The Earnings Season’s Central Paradox: Record Profits, Yet Every Stock Fell
II. Seven Earnings Reports Confirm the Same Point: Pricing Matters More Than Shipments, and Profits Are More Leveraged Than Revenue
III. Price Outlook: Slower Increases Do Not Mean an Immediate Decline
DRAM and HBM: Conventional DRAM Sets the Opportunity Cost; HBM Sets the Product Premium
NAND and Enterprise SSDs: The Greatest Pricing Leverage and the Fastest-Improving Demand Mix
Nearline HDDs: Slower Price Adjustments and More Manageable Cost Reduction
IV. What Long-Term Agreements Actually Lock In: Volume, Pricing, Minimum Revenue, and Collateral Must Be Assessed Separately
Micron and SanDisk: The Most Comprehensive Disclosures and the Closest to Genuine Downside Protection
Samsung Electronics and SK hynix: More Contracts, but Lower Transparency
Kioxia, Seagate Technology, and Western Digital: Targets, Capacity Planning, and Binding Contracts Must Not Be Conflated
V. Can Supply Discipline Hold? The Real Test Comes After 2028
VI. Whose Earnings Are Most Durable? Four Moats Matter More Than Gross-Margin Rankings
VII. Buybacks and Dividends: Earnings Must Still Pass Through Capital Expenditure and the Balance Sheet Before Reaching Shareholders
VIII. Why Share Prices Weakened Before Earnings: Four Factors the Market Is Discounting
IX. The Next 4–6 Quarters: Three Scenarios and Eight Tests
X. Conclusion: The Memory Cycle Has Not Disappeared, but the Earnings Trough May Be Redefined
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Profits and guidance continue to rise across all seven companies, yet their shares have retreated in tandem. The key question this memory earnings season has shifted to whether long-term agreements, supply discipline, and cash returns can turn peak profits into a sustainable plateau.
Executive Summary
Fundamentals are still accelerating, but the market has moved on to a different question. Micron, Sandisk, Seagate Technology, Western Digital, Samsung Electronics, SK hynix, and Kioxia all reported strong pricing, margins, or next-quarter guidance. Yet from the close before Micron’s June 24 earnings release through the August 6 research cutoff, all seven stocks declined, with losses ranging from approximately 15% to 47%. The market is no longer paying for “how high profits are this quarter”; it is discounting “how long elevated profits can last.”
Price increases remain the largest driver of profit growth, while volume gains have been modest. Micron’s DRAM and NAND average selling prices rose sequentially by the low-60% range and mid-80% range, respectively; pricing contributed roughly two-thirds of Sandisk’s sequential revenue growth; and NAND ASPs at Samsung Electronics, SK hynix, and Kioxia increased by approximately the high-60% range, 55%, and 70%, respectively, while bit shipments at several companies grew only by single digits. Even if prices continue to rise, slower increases would cause profit growth to peak before absolute profits do.
Long-term agreements have raised the earnings floor, but contract strength varies substantially. Micron’s 16 strategic customer agreements include take-or-pay provisions, non-cancellable commitments, price floors and ceilings, and funding commitments. Sandisk’s new business model agreements with 8 customers disclose $93.9 billion in minimum revenue and $16.5 billion in funding instruments. Samsung Electronics and SK hynix are also expanding multi-year agreements, but disclose fewer details on pricing, coverage, and guarantees; Kioxia’s 50% coverage remains a 2028 target. Seagate Technology’s and Western Digital’s long-term supply agreements primarily secure capacity, product configurations, and pricing frameworks and should not be treated as non-cancellable, fixed-price orders.
Supply discipline—not the AI narrative itself—remains the core driver of “higher prices for longer.” New fabs take years to move from construction to meaningful shipments, while HBM consumes more advanced DRAM wafer capacity. NAND manufacturers are relying primarily on process-node transitions to increase bits, while the 2 HDD vendors are expanding EB through higher areal density rather than greater drive-unit volumes. Visibility into tight supply remains relatively high through 2027; the real risk window begins after 2028, when new capacity, bit growth from technology migrations, and customer inventory releases may arrive simultaneously.
Cash returns have begun, but authorizations should not be mistaken for completed transactions. Sandisk repurchased $4.5 billion of shares in Q4 and increased its remaining authorization to $15.5 billion; Western Digital returned $3.1 billion in FY26; Kioxia authorized repurchases of up to ¥800 billion, equivalent to approximately 5.5% of shares outstanding; and Seagate Technology increased buybacks while reducing debt. Micron plans to increase capital returns after December 9, but FY27 capital expenditure will also exceed the middle of the $40 billion range. SK hynix’s additional buyback remains a UBS estimate, not company guidance.
There is no single winner on profit durability. Micron and Sandisk have the clearest contractual downside protection, but are also the most dependent on the current elevated pricing plateau. Seagate Technology’s and Western Digital’s long-term capacity planning, generational product cost reductions, and low capital intensity improve free-cash-flow quality. Samsung Electronics and SK hynix combine HBM, conventional DRAM, and enterprise SSD exposure, but also have the largest expansion plans. Kioxia offers the greatest pricing and buyback leverage, but its contract coverage has yet to be delivered.
Investors should track 8 variables over the next 4–6 quarters. DRAM and NAND contract pricing, HBM4 pricing, enterprise SSD mix, nearline HDD pricing and cost per TB, actual long-term-agreement coverage, the time required for capital expenditure to become productive capacity, free-cash-flow quality after deducting customer prepayments, and actual buyback execution. Only if pricing, contracts, and cash flow all hold can current profits evolve from a cyclical peak into a higher plateau.
I. The Earnings Season’s Central Paradox: Record Profits, Yet Every Stock Fell
This earnings season spans 3 distinct groups of companies. Micron, Samsung Electronics, and SK hynix operate across DRAM, HBM, and NAND; Sandisk and Kioxia are primarily exposed to NAND and enterprise SSDs; and Seagate Technology and Western Digital supply nearline HDDs. AI infrastructure is simultaneously increasing demand for high-bandwidth memory, caching, and persistent storage within compute nodes, while prompting cloud service providers to secure supply through longer-term contracts. These 3 groups therefore need to be assessed within a common framework.
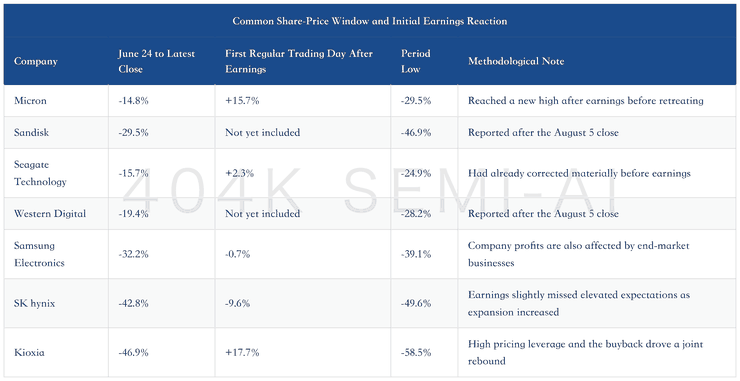
Micron (MU) reported after the U.S. market closed on June 24, so this report sets that day’s close at a common baseline of 100. By the August 5 U.S. close and the latest available regular-session closes in Korea and Japan on August 6, Micron had fallen 14.8%, Seagate Technology 15.7%, Western Digital 19.4%, Sandisk 29.5%, Samsung Electronics 32.2%, SK hynix 42.8%, and Kioxia 46.9%. Sandisk and Western Digital reported their latest results only after the August 5 close, so the period endpoint does not yet capture a full regular-session reaction to those earnings.
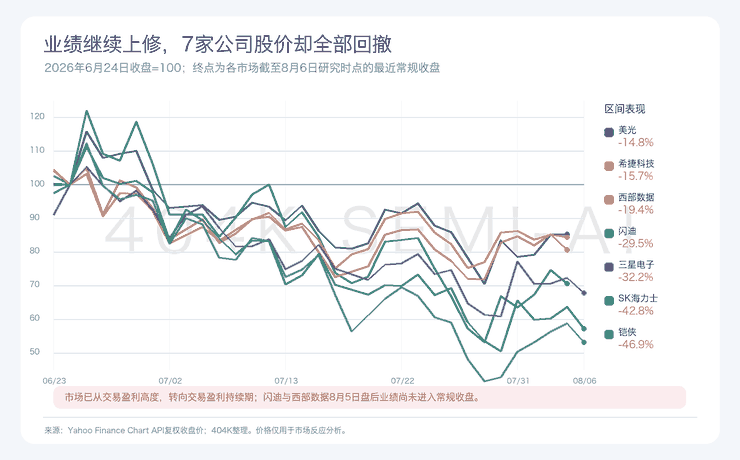
The declines were not continuous. Micron rose 15.7% on the first trading day after earnings, Kioxia gained 17.7% on its reporting day, and Seagate Technology advanced 2.3% on its first post-earnings trading day. By contrast, Samsung Electronics fell 0.7% on its reporting day and SK hynix declined 9.6%. More importantly, Micron reached a new high after earnings but later traded as much as 29.5% below the baseline; Kioxia fell as much as 58.5% below the baseline before its report, with strong results and a buyback driving only a partial recovery.
These moves show that the market is applying two rounds of pricing. The first assesses whether results beat expectations and determines the reporting-day move. The second evaluates profit duration, capital expenditure, and valuation, shaping the trend over subsequent weeks. Fundamentals across the seven companies were generally stronger than in the previous quarter, yet their shares still retreated from their highs—evidence that the second round of pricing has overwhelmed the first.
II. Seven Earnings Reports Confirm the Same Point: Pricing Matters More Than Shipments, and Profits Are More Leveraged Than Revenue
Looking only at revenue growth understates this cycle’s earnings inflection; looking only at margins risks mistaking a pricing tailwind for permanent competitive advantage. The appropriate framework separates revenue into shipment volume, unit pricing, and product mix, then decomposes profit into pricing, costs, utilization, and operating leverage.
Micron reported Q3 revenue of $41.456 billion, a non-GAAP gross margin of 84.9%, and adjusted free cash flow of $18.3 billion. JPMorgan estimates that DRAM ASP rose sequentially by the low-60% range and NAND ASP by the mid-80% range, while bit shipments grew only by the low-to-mid-single-digit range. The company still guides to an approximately 86% gross margin next quarter, but management explicitly warned that the pace of price increases would slow significantly.
Sandisk reported Q4 revenue of $8.965 billion, a non-GAAP gross margin of 84.6%, and adjusted free cash flow of $5.035 billion. Bits contributed approximately one-third of sequential revenue growth and pricing roughly two-thirds; next-quarter gross-margin guidance remains 83%–85%. Kioxia’s profile was even more extreme: Q1 blended ASP rose approximately 70% sequentially, while shipment capacity increased only by the low-single-digit range, lifting its non-GAAP operating margin to 75%. Next-quarter guidance is 79.5%.
The Korean vendors show the same pattern: pricing outweighed volume. Samsung Electronics’ Q2 DRAM ASP increased by approximately the mid-40% range and NAND by approximately the high-60% range. SK hynix’s DRAM and NAND ASPs rose by approximately 30% and 55%, respectively, while its operating margin reached 76%. Both companies still plan to increase bit shipments in the third quarter, but the slope of profit growth will continue to depend primarily on contract pricing, HBM mix, and enterprise SSD exposure.
The volume-price relationship differs for HDDs. Seagate Technology’s Q4 nearline shipments reached 195EB, its non-GAAP gross margin was 52.7%, and price per EB increased approximately 10% year over year. Western Digital shipped 231EB in Q4, recorded a non-GAAP gross margin of 54.4%, and achieved high-teens year-over-year growth in price per TB while reducing cost per TB by approximately 8%. Neither company relies solely on price increases: HAMR, UltraSMR, and higher-areal-density products increase capacity per drive, expanding saleable EB per unit while lowering manufacturing cost per TB.
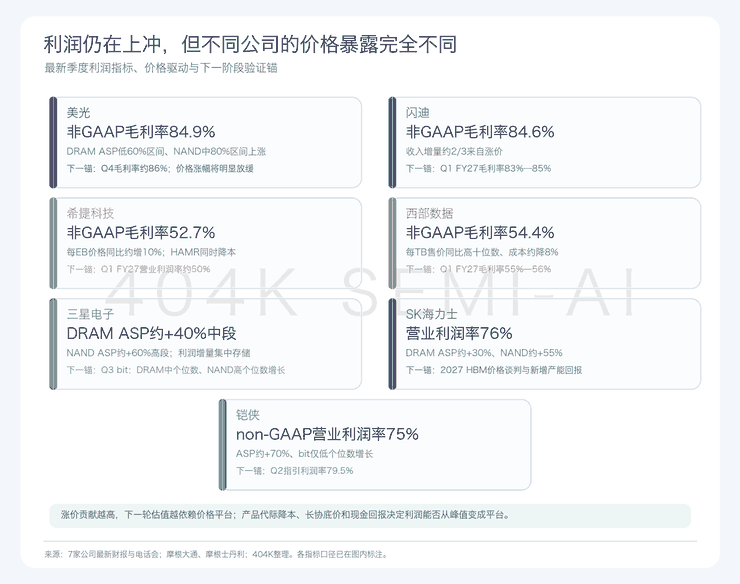
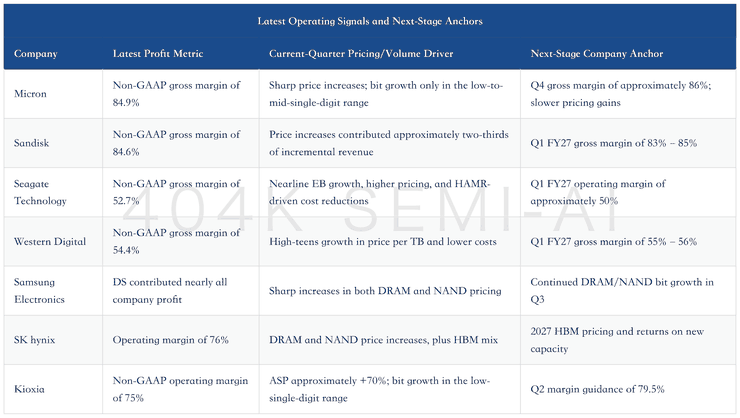
These margins should not be ranked mechanically. Micron, Sandisk, and the HDD vendors report non-GAAP gross margins; the figures shown here for SK hynix and Kioxia are operating margins; and Samsung Electronics includes multiple businesses. The common signal is narrower but clear: higher prices and richer product mix are converting a large share of incremental revenue into profit, while simultaneously increasing earnings dependence on the current pricing plateau.
