
目录
Executive Summary
1. The 5-10x Multiple Resets the Starting Point for CPO Research
2. What the Four Multiples Actually Measure
3. Commercialization Timeline: Scale-Out First in 2026, Scale-Up Volume in 2028
IV. Why the Upstream Supply Chain Entered the Long-Term Contracting Era Early
V. Lumentum: High Share Accelerates Demand Conversion but Concentrates Customer Volatility
VI. Sumitomo Electric: Supplying Both Light and Connectivity
VII. Applied Optoelectronics and Coherent: Customer Readiness Is Improving
VIII. One More Layer of Evidence Is Needed to Bridge Technical Demand and Financial Delivery
IX. Three Scenarios and Key Indicators to Monitor
The next phase of CPO research has moved beyond “when adoption begins” to “how much optical content each GPU requires—and who can deliver it on time.”
Executive Summary
Lumentum (NASDAQ: LITE) estimates that once co-packaged optics (CPO) are deployed in intra-rack scale-up networks, demand for laser products per GPU will be 5-10x that of inter-rack scale-out networks. This multiple measures optical content intensity and should not be directly equated with revenue or profit growth.
Corning provides a separate set of physical metrics: additional network tiers in large clusters can increase fiber demand by approximately 1.5x; an upgrade from 400G to 3.2T implies approximately 2-4x; and if intra-rack copper links transition fully to optics, fiber demand per GPU could rise to approximately 10x current levels. These 4 figures measure different variables and should not be mechanically multiplied.
Commercialization is proceeding in stages. Inter-rack CPO is expected to enter low-volume production or initial sales in the second half of 2026. High-power light sources, external lasers, and intra-rack CPO are concentrated around a second-half 2027 launch, with more comprehensive scale validation not expected until 2028.
The capacity race is already under way, ahead of revenue. Approximately 75% of Lumentum’s business is covered by long-term agreements, while the share of Sumitomo Electric’s optical-device business under long-term agreements is rising from approximately 50% toward 60%-70%. Applied Optoelectronics says high-power lasers require 21-24 months or longer from equipment ordering to mass production.
Supply-chain beneficiaries should not be ranked solely by “CPO purity.” InP substrates, high-power continuous-wave lasers, external lasers, two-dimensional fiber arrays, and high-density connectivity components can all capture incremental demand. However, customer qualification, production yields, market share, and pricing will determine how much of the 5-10x content increase ultimately converts into earnings.
1. The 5-10x Multiple Resets the Starting Point for CPO Research
Over the past six months, the CPO debate has centered on timing: whether volume ramps can begin in 2027, whether near-packaged optics (NPO) will move first, and how long conventional pluggable modules can remain viable. Nomura’s August 20 report does not resolve these disagreements, but it adds quantitative evidence closer to the underlying demand drivers.
During an August 17 investor discussion, Lumentum said that adopting CPO in intra-rack scale-up networks could drive laser-product demand per GPU to 5-10x the level in inter-rack scale-out networks. Scale-out connects separate racks or cluster layers, with traffic fanning outward from switch ports. Scale-up serves a single high-density compute domain, enabling large numbers of GPUs to operate collaboratively at low latency and high bandwidth. As optics migrate from outside the rack into it, the demand function expands from “how many ports does the switch have?” to “how many optical connections does each GPU require?”
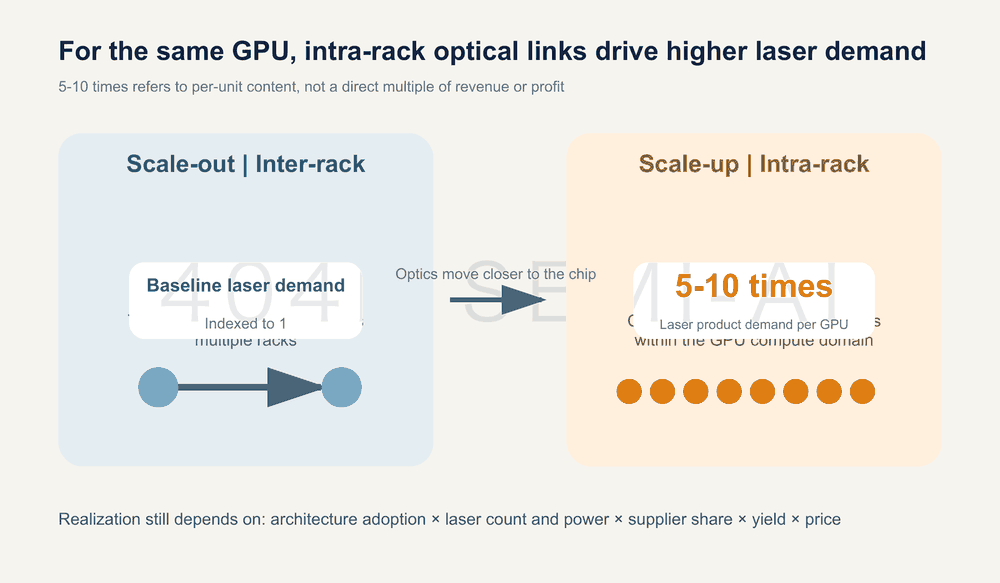
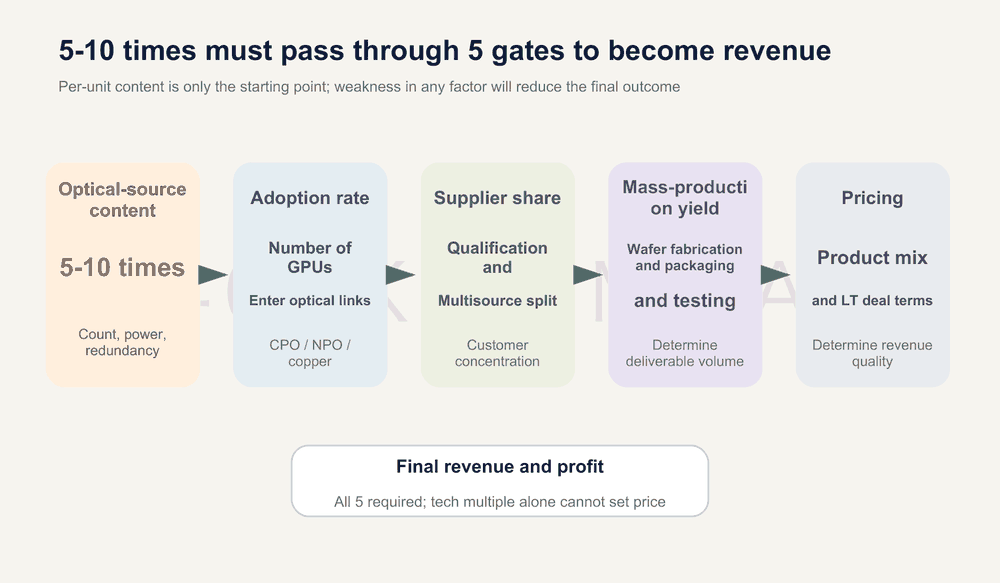
The 5-10x multiple should not be directly translated into revenue growth. Actual revenue depends on five variables: the proportion of GPUs adopting CPO, the number and power of lasers used in each architecture, supplier market share, manufacturing yields, and product pricing. Customers may also split deployment among CPO, NPO, and board-level optics. A single external laser source can serve multiple optical engines, while redundancy requirements can alter actual installed volumes.
Understanding the multiple requires distinguishing laser count from laser power. Scale-out networks are measured primarily by switch ports, with one optical link serving two network nodes. Scale-up networks place large numbers of GPUs within the same low-latency compute domain, requiring each GPU to exchange data with more peers. As topology density increases, high-speed channels also need sufficient optical power to offset coupling, splitting, and transmission losses. Incremental demand may therefore appear simultaneously in laser count, power per laser, and redundancy configurations.
External laser sources separate the light-emitting components from high-thermal-density compute or switch packages, making failed units easier to replace. They can deliver light over fiber to one or more optical engines, while silicon-photonics modulators handle high-speed modulation. The trade-off is the need for additional fiber, connectors, splitters, and coupling components, together with power balancing across channels. CPO shortens electrical connections but introduces new engineering challenges in light-source reliability, connection density, and package testing.
This also explains why laser and fiber demand rise together. Light sources provide the optical power; fibers and two-dimensional arrays deliver it to the correct locations; and optical engines perform modulation, transmission, and reception. A shortfall in any one component can constrain the entire system, so suppliers cannot win high-volume orders with a single high-performance sample. Customers need operating temperature, service life, insertion loss, polarization, yield, and maintainability to meet requirements simultaneously at the full-system level.
The disclosure remains significant because it explains why scale-up could become a larger swing factor for optical content than scale-out. The market previously estimated AI optical-interconnect demand from transceiver port counts. Analysis must now incorporate rack topology, switching tiers, SerDes rates, the reach limits of copper, light-source power, and maintainability. The key question is no longer a single CPO shipment curve, but an integrated set of rack-level physical constraints.
2. What the Four Multiples Actually Measure
Citing Corning’s May 6 materials, Nomura separates incremental demand for data-center fiber and cabling materials into four categories. The first is cluster scale. Once a single cluster exceeds 130,000 GPUs, a two-tier network may no longer be sufficient, requiring a third tier and increasing fiber demand by approximately 50%. This reflects an increase in the number of network nodes and links.
The second category is bandwidth. If both 400G and 800G use 100G per wavelength, upgrading increases the number of fibers. If 1.6T uses 200G per wavelength, fiber count per port may not continue rising. At 3.2T, different choices between 200G and 400G per wavelength produce different outcomes. Fiber volume could therefore increase by 2-4x from 400G to 3.2T, although more of the upgrade may instead be captured through higher component performance.
The third category is the transition from copper to optics within the rack. Copper remains widely used for internal rack connections. If these links become fully optical, Corning estimates that fiber demand per GPU could reach approximately 10x current levels. The fourth category is an emerging requirement for passive photonics: fibers, connectors, and array components are needed to deliver and route light among external laser sources, optical engines, and silicon-photonics chips.
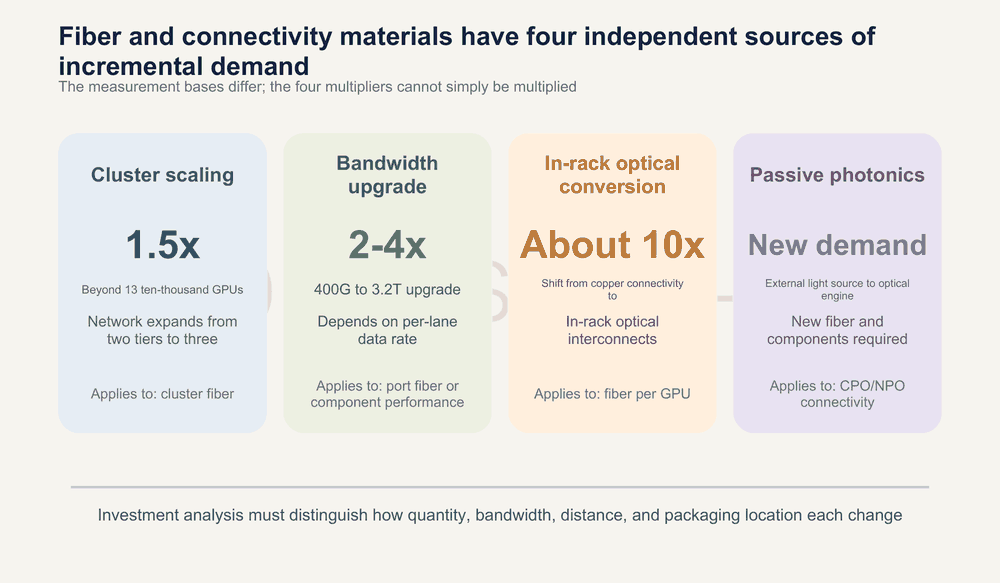
These four changes should not be combined into an exaggerated “1.5×4×10” model. Cluster tiers, port bandwidth, intra-rack connections per GPU, and passive components near the package measure different parts of the system. A more reliable approach is to calculate ports, channels, and connections separately at each layer, then check for double counting.
Compared with May’s Further Upward Revision to AI Optical-Transceiver Demand, this analysis traces the InP and CPO bottlenecks further down to per-unit demand within the rack. The previous framework showed how 1.6T, InP, and CPO could extend supply constraints through 2028. The new disclosure explains why supply can tighten so readily: once scale-up adopts optical connectivity, laser and fiber consumption per GPU could both increase sharply.
