
目录
I. The Most Important Shift: Customer Demand Now Far Exceeds Deliverable Supply
II. Why AI Servers Consume So Much Memory
III. Why the Shortfall Persists Despite Rapid Supply Growth
IV. Prices Will Rise, but Shortages Will Not Translate One-for-One into Profits
V. Both DRAM and NAND Are Tight, but Their Shortage Intensity and Earnings Leverage Differ
VI. Which Companies Can Most Readily Convert Tightness into Cash Flow?
VII. The Three Most Likely Sources of Overestimation
VIII. Six Numbers to Track Next
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
AI servers are pushing memory chips beyond a conventional price-upcycle into a structural shortage lasting through 2027. UBS expects demand to remain well above deliverable supply, although long-term agreements and inventory reductions will limit the pace of price realization.
I. The Most Important Shift: Customer Demand Now Far Exceeds Deliverable Supply
The most valuable insight in this UBS monthly report is its separation of “demand” into two fundamentally different figures. The first is unconstrained demand—what customers request without regard to supply limitations. The second is constrained demand—the volume memory manufacturers can actually deliver given existing capacity and product allocation. The gap between the two is the starting point for understanding the 2027 memory market.
The current overall DRAM demand-fulfillment rate is only about 60%. In other words, for every 100 units customers request, manufacturers can currently supply only around 60 units. Server DDR bit demand is approaching 80% growth in 2027, while unconstrained bit demand for server SSDs and storage SSDs could exceed 100%. UBS estimates that deliverable constrained demand may grow by only about 40%. The gap between customer requests and actual delivery capacity continues to widen.
This gap should not be treated directly as orders or revenue. Customers may submit duplicate requests, secure capacity in advance, or cancel part of their purchases after prices change. Volumes covered by long-term agreements must also be distinguished from incremental customer requests. The report’s unconstrained-demand figures are better viewed as a stress test: they show how much customers want, not how much will necessarily transact.
Even after applying a discount, a DRAM fulfillment rate of about 60% remains extremely low. Memory manufacturers are no longer deciding whether to expand capacity, but which customers should receive their limited wafer and packaging capacity first. AI servers, HBM, server DDR, and enterprise SSDs offer higher margins, and customers are willing to pay for delivery certainty, naturally moving these products to the front of the queue. Memory products for conventional PCs and smartphones must accept slower supply growth and higher procurement costs.
UBS has therefore reduced its confidence in end-demand resilience. It previously expected both PC and smartphone unit sales to grow 2% in 2027, but now sees downside risk to both forecasts. Demand may not disappear, but higher memory costs and insufficient supply could force device manufacturers to delay product launches, reduce configurations, or offer fewer promotional models. As shortages spread from servers to consumer electronics, the industry’s beneficiaries and pressured players will increasingly diverge.
II. Why AI Servers Consume So Much Memory
AI servers drive memory demand through both a rising device count and greater memory content per device. Looking only at GPU or server shipments would materially underestimate demand. UBS multiplies the GPU and ASIC volumes of NVIDIA, AMD, Google, Amazon, Microsoft, Meta, and other vendors by the HBM capacity per accelerator and DDR capacity per server, producing bit-demand estimates by customer and product.
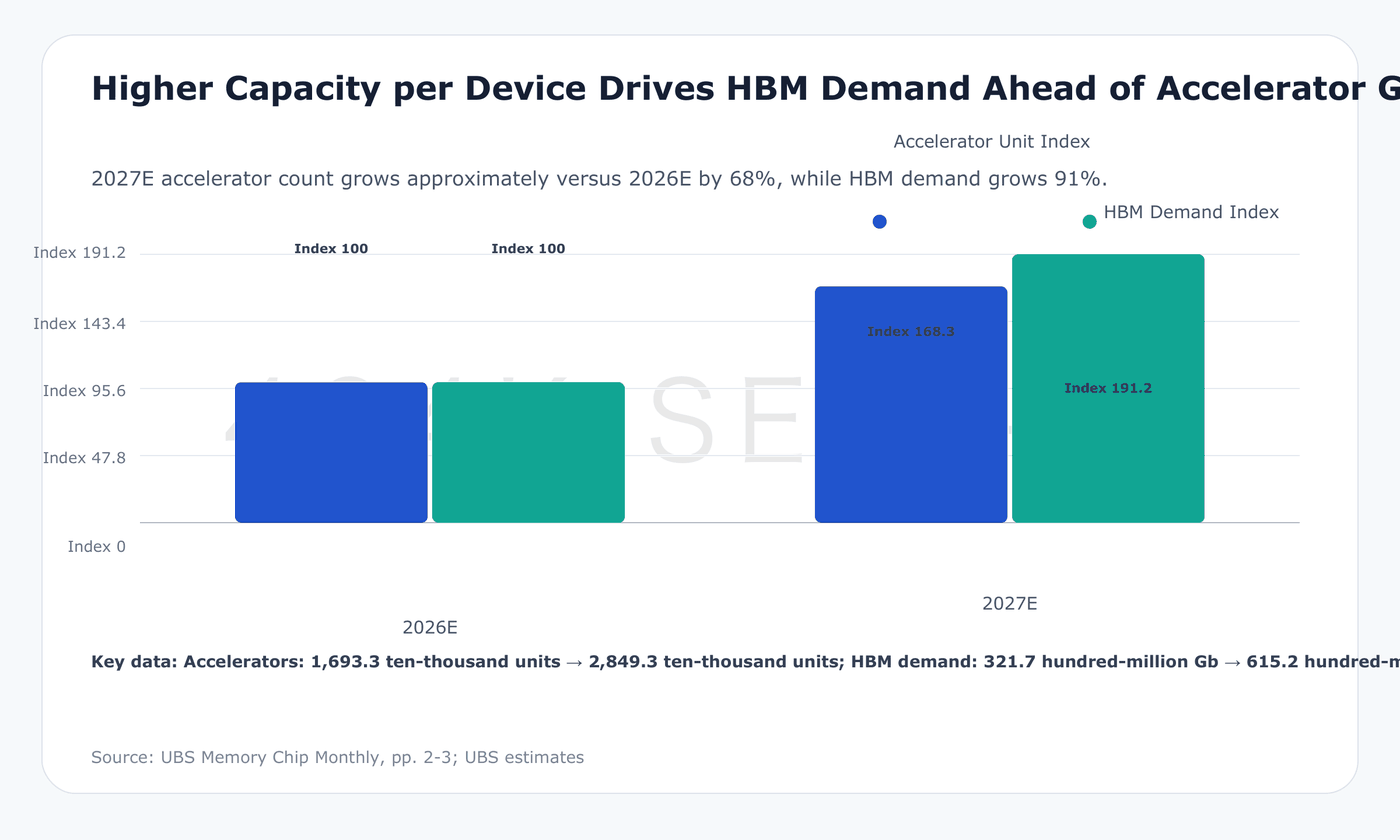
The model projects total GPU and accelerator volumes to increase from 16.933mn units in 2026 to 28.493mn units in 2027, an increase of about 68%. Over the same period, total HBM demand rises from 32.17bn Gb to 61.52bn Gb, up 91%. HBM demand is growing faster than accelerator volumes, indicating that memory capacity per chip continues to increase. As compute chips become more powerful, they must process more model parameters, context, and intermediate results, while the cost of processors waiting for data also rises. Vendors therefore need larger, faster memory configurations to maintain throughput.
The increase in memory content per system is even more pronounced in UBS’s server DRAM model. Average server DRAM capacity is expected to rise 57%, from 927GB in 2026 to 1,455GB in 2027. Average DRAM capacity in AI servers increases from 8,961GB to 14,754GB. With both system volumes and per-system capacity rising sharply, total server DRAM demand reaches 324,124mn Gb in 2027, up 83.1% year over year.
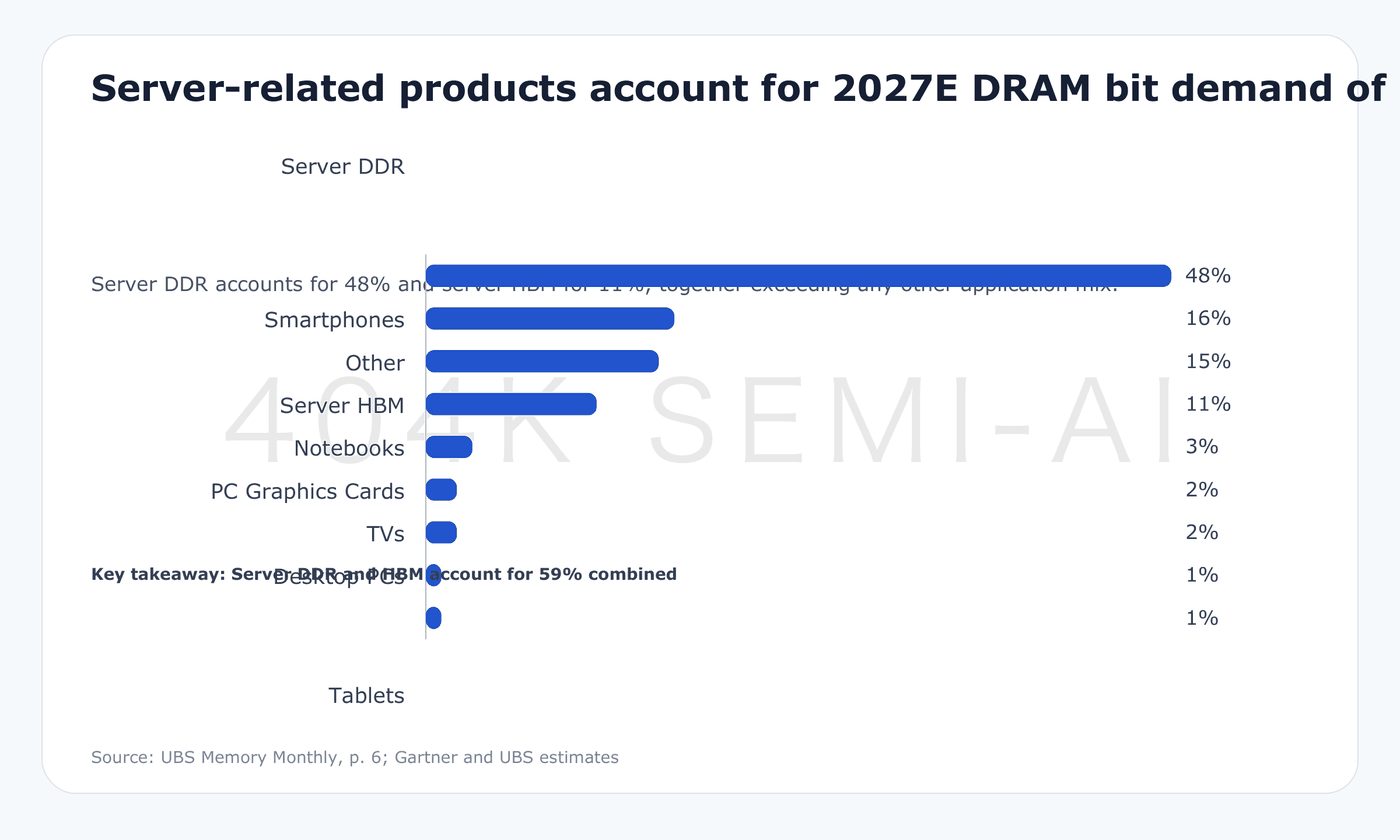
These figures explain why servers are reshaping the entire DRAM market. Server DDR is expected to represent 48% of DRAM bit demand in 2027, with server HBM accounting for another 11%, for a combined 59%. Smartphones, PCs, televisions, and game consoles remain large markets, but they can no longer determine industry pricing on their own. Server-related demand has become both the largest source of incremental growth and the highest-priority category in manufacturers’ capacity-allocation decisions.
HBM’s customer mix is also changing. NVIDIA remains the largest customer, but UBS expects its demand share to decline from 58% in 2026 to 41% in 2027. Google rises to 31% and AMD to 12%. NVIDIA’s lower share does not imply declining demand; it reflects faster investment growth in Google’s internally developed ASICs, AMD accelerators, and other cloud platforms. The HBM market is gradually shifting from dominance by a single major customer toward simultaneous expansion across multiple computing platforms.
Changes in product specifications can also be misinterpreted. The report expects NVIDIA’s VR300 initially to use HBM4 8-Hi rather than HBM4E 12-Hi, while a previously considered 4-Hi configuration is constrained by the development timeline. A specification reduction for one product changes that model’s capacity but does not automatically reduce total demand. Higher accelerator shipments, richer configurations among other customers, and transitions to next-generation products can offset lower capacity in a single model. UBS maintains its forecast for 91% HBM demand growth in 2027.
III. Why the Shortfall Persists Despite Rapid Supply Growth
Suppliers have not stopped expanding capacity. UBS expects total HBM supply to increase from 36.616bn 1Gb units in 2026 to 53.728bn 1Gb units in 2027, growth of about 47%. Total DRAM bit supply is also expected to grow 23.3% in 2027. The problem is that demand is growing faster, while products also compete for the same wafers, equipment, engineering resources, and advanced-packaging capacity.
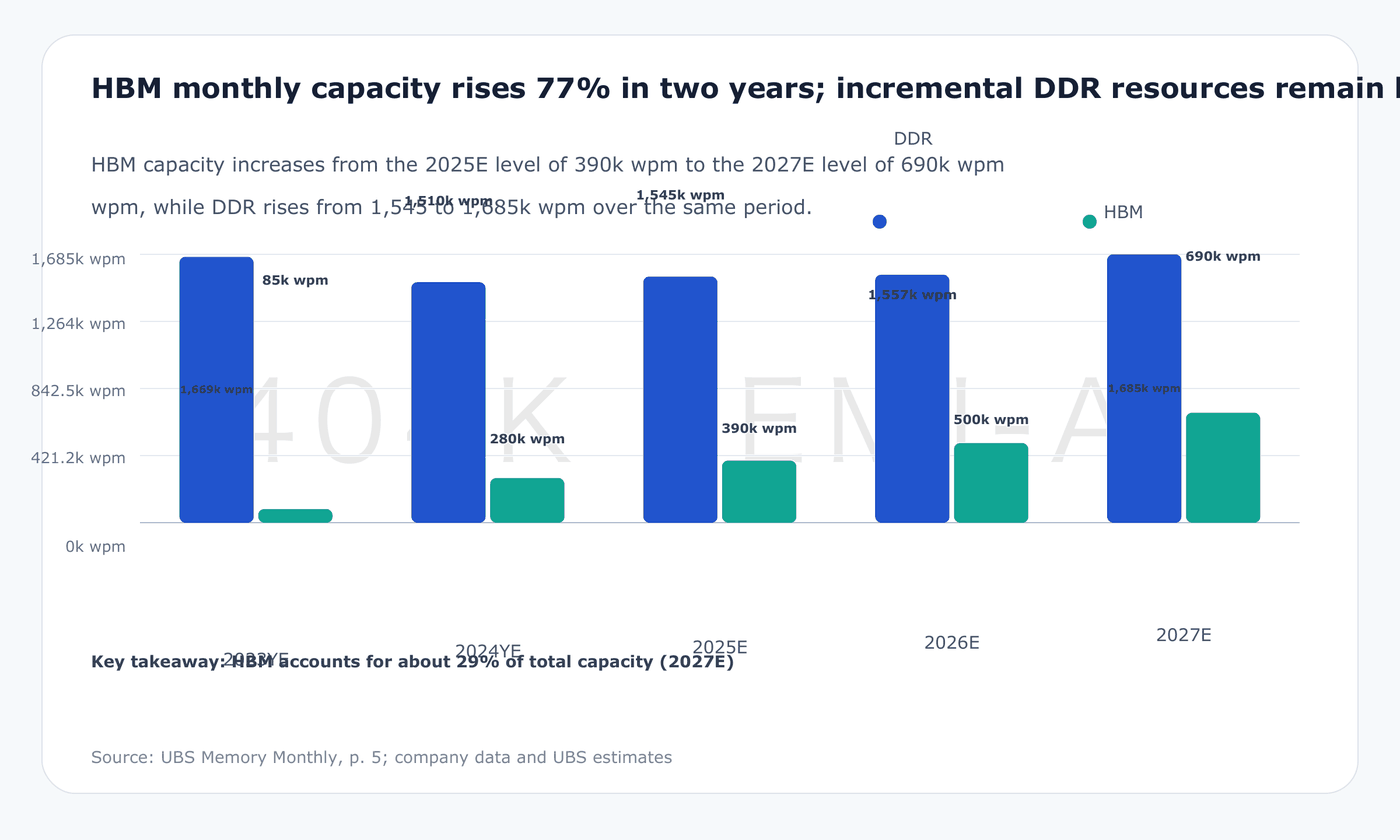
Expanding HBM capacity crowds out conventional DDR. The report expects monthly HBM wafer capacity to rise from 390k wpm in 2025 to 690k wpm in 2027. Memory manufacturers cannot expand total wafer input without limit at the same pace, and process transitions take time. Allocating more wafers to HBM leaves less incremental capacity for conventional DDR. With server DDR demand also approaching 80% growth, supply pressure is emerging simultaneously in both high-bandwidth memory and conventional server memory.
Technology upgrades cannot resolve the shortage immediately. DRAM and NAND can increase output per wafer through more advanced process nodes, additional layers, and higher bit density, but yield ramp-ups delay the release of effective supply. HBM also requires stacking, testing, and advanced packaging; a shortfall at any stage constrains final deliveries. Financially, capital expenditure first appears as equipment and depreciation, while qualified products convert into revenue and cash flow only after volume production ramps. Higher prices strengthen the incentive to expand, but they cannot bring next quarter’s wafers into the present.
