
Tesla Q2 2026 Deep Dive: How a 1.4% Operating Margin and $25 Billion in Capex Reshape Valuation After Record Deliveries
目录
TL;DR
Demand Has Recovered, but Profit Conversion Continues to Deteriorate
Automotive Gross Margin at 16.3%: Sequential Performance Was Not as Weak as It Appeared, but the Mix Was Not as Favorable Either
Energy Gross Margin Fell from 39.5% to 20.4%; One-Time Charges Explain Only Part of the Decline
Services Are Improving, but Cannot Yet Offset the Profit Shortfall in Automotive and Energy
R&D Expense Rose to $2.371 Billion, While Net Income Was Again Lifted by $1.005 Billion in Investment Gains
The Improvement in Operating Cash Flow Is Real, but Negative Free Cash Flow Was Not a One-Off
Robotaxi: 2.5 Million Paid Miles Mark Progress, but 380,000 Unsupervised Miles Remain an Early Sample
FSD Attach Rate Above 55% Is This Quarter’s Clearest Evidence of a Software Flywheel
The Most Candid Optimus Disclosure Is Not the Production Target, but That “the Initial Ramp Will Be Long and Flat”
Why Morgan Stanley Cut Its Price Target from $417 to $400
Goldman Sachs’ $390 Target Is Close to Morgan Stanley’s $400, but the Underlying Logic Differs
The Next Eight Data Points Matter More Than Launching in a Few More Cities
The Risk Is Not the Number of Narratives, but That Every Narrative Requires Capital at the Same Time
Conclusion: Tesla Has Proven It Can Do Many Things, but Not Yet That It Can Deliver High Returns While Doing Them Simultaneously
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Record Q2 deliveries confirm that demand for Tesla remains intact; a 1.4% operating margin and negative free cash flow show that the scarcest capability in the next phase will be converting physical AI investment into verifiable returns.
TL;DR
Tesla generated $28.236 billion in revenue in Q2 2026, up 26% year over year, while posting record Q2 deliveries. Revenue was 1% below Goldman Sachs' forecast but 7% above the FactSet consensus. The headline revenue beat was primarily driven by 480,100 deliveries, growth in services, and a recovery in energy storage deployments; demand was not the quarter's biggest surprise.
The real shortfall was margins. Total gross margin was 16.8%, automotive gross margin excluding regulatory credits was 16.3%, and energy gross margin was 20.4%, all well below investment-bank expectations. Operating income was only $398 million, with operating margin falling to 1.4%. Goldman Sachs had forecast operating income of $1.805 billion, while Morgan Stanley had estimated automotive and energy gross margins of 18.1% and 28.0%, respectively. Revenue scale returned, but unit economics did not recover with it.
GAAP net income of $1.114 billion also overstated underlying earnings for the period. Tesla recognized a $1.005 billion unrealized gain on its SpaceX equity investment, while R&D; expenses rose 49% year over year to $2.371 billion and stock-based compensation increased to $1.151 billion. Operating quality is better assessed through the $398 million in operating income and $3.273 billion in adjusted EBITDA than through net income alone.
Operating cash flow rose 85% year over year to $4.697 billion, but capex increased to $5.789 billion, resulting in negative free cash flow of $1.092 billion. On the earnings call, management explicitly guided to more than $25 billion in 2026 capex and said spending would continue to grow over the next two to three years. The company is also preparing up to $30 billion in debt financing capacity. Its $43.524 billion in cash and short-term investments provides a buffer, but does not establish that returns on capital have been proven.
Robotaxi and FSD delivered the strongest operational progress, but also highlighted the evidence required to support the valuation. Paid Robotaxi miles are approaching 2.5 million, including more than 380,000 unsupervised miles. FSD take rate on new North American deliveries exceeded 55%, and global active paid users reached 1.48 million. Yet 380,000 miles remains insufficient to validate very-low-probability safety events, while Cybercab still needs to accumulate data specific to its new platform. Expanding the number of cities does not mean density, utilization, and unit economics have been proven within each city.
Goldman Sachs maintained its Neutral rating and $390 price target. Following the earnings call, Morgan Stanley maintained its Equal-weight rating and cut its price target from $417 to $400. Of Morgan Stanley's $400 valuation, the core automotive business accounts for only $45, while network services, Robotaxi, and humanoid robots collectively account for $320. In other words, 80% of the valuation depends on future businesses that have yet to contribute meaningfully to earnings and cash flow. Q2 did not invalidate the long-term physical AI thesis, but it materially raised the cost of validation and the required waiting period.
Demand Has Recovered, but Profit Conversion Continues to Deteriorate
Tesla produced 451,800 vehicles and delivered 480,100 in Q2, up 10% and 25% year over year, respectively. Global days of inventory fell from 24 in the prior-year period to 15, indicating that delivery growth did not rely on a larger buildup of quarter-end inventory. Automotive revenue rose 23% year over year to $20.516 billion; energy revenue increased 13% to $3.139 billion; and services and other revenue grew 50% to $4.581 billion. Growth across all three business lines lifted total revenue to $28.236 billion.
These figures are sufficient to reject the extreme view that the core business has lost demand. Management also said the company exited Q2 with its largest order backlog since 2023, with sequential delivery growth of 60% in North America, 27% in Asia-Pacific, and 12% in Europe, the Middle East, and Africa. These claims still require confirmation in subsequent delivery data, but they are at least directionally consistent with lower days of inventory and record quarterly deliveries.
The problem is that the revenue recovery did not translate into a profit recovery.
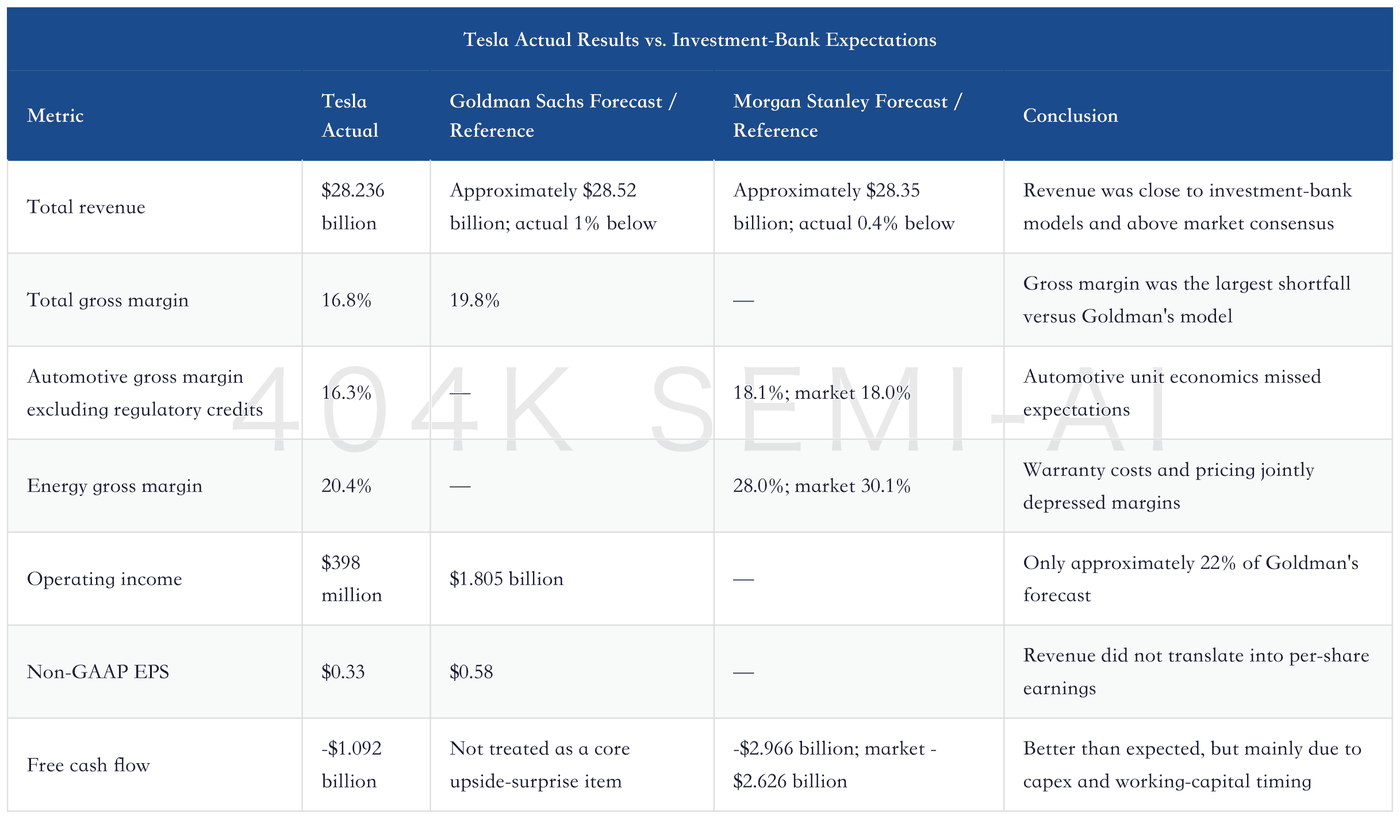
Goldman Sachs noted that revenue was 7% above the FactSet consensus and 2% above the sell-side estimates compiled by Tesla, but total gross margin was 3 percentage points below Goldman's forecast and operating income missed by $1.407 billion. Morgan Stanley reached a similar conclusion: revenue was only 0.4% below its model, while automotive and energy gross margins missed by 1.8 and 7.6 percentage points, respectively. The results therefore cannot simply be characterized as “revenue beat, earnings miss.” More precisely, Tesla delivered scale, but its conversion rate deteriorated.
Automotive Gross Margin at 16.3%: Sequential Performance Was Not as Weak as It Appeared, but the Mix Was Not as Favorable Either
The automotive segment's GAAP gross margin was 16.9%, or 16.3% excluding $146 million in regulatory-credit revenue, down from 19.2% in Q1. On the surface, the 2.9-percentage-point sequential decline appears to signal another sharp deterioration in price competition.
Management offered a more moderate explanation. Q1 automotive results included approximately $230 million in warranty adjustments and tariff-mitigation benefits that did not recur in Q2. Excluding this favorable Q1 comparison base, management said automotive gross margin was approximately flat sequentially. In other words, the 16.3% figure does not entirely reflect incremental deterioration in Q2; part of the decline came from the absence of one-time Q1 benefits.
However, “flat sequentially on an adjusted basis” does not mean margins are healthy. Average vehicle selling prices continued to decline, product mix was unfavorable, and higher interest rates increased the cost of subsidized vehicle financing, which is recognized as a direct reduction in revenue upon delivery. Meanwhile, regulatory-credit revenue fell year over year from $439 million to $146 million. Higher deliveries helped absorb manufacturing costs but were not yet sufficient to offset pressure from pricing, financing subsidies, and revenue mix.
This explains why automotive revenue grew 23% year over year while operating income fell 57%. The problem in Q2 was not a lack of vehicle sales, but thinner per-vehicle profits available to fund R&D;, SG&A;, and investment in new businesses. As long as core automotive gross margin remains around 16%, FSD subscriptions and services revenue will need to grow faster to support simultaneous expansion in Robotaxi, Optimus, and compute infrastructure.
Energy Gross Margin Fell from 39.5% to 20.4%; One-Time Charges Explain Only Part of the Decline
Tesla deployed 13.5 GWh of energy storage in Q2, up 41% year over year and 53% sequentially, representing the company's second-highest quarterly deployment volume. Neither demand nor shipments were problematic, and energy revenue recovered to $3.139 billion.
Gross margin, however, fell from 39.5% in Q1 to 20.4%. Management attributed the change to three factors: approximately $240 million in Q2 warranty provisions related to supplier cell issues in legacy projects; the non-recurrence of more than $200 million in tariff benefits recognized in Q1; and intensifying competition in utility-scale storage, which continued to pressure average selling prices.
Excluding the $240 million Q2 warranty charge, energy gross margin would have been approximately 28%. Excluding the roughly $200 million in Q1 tariff benefits, comparable Q1 gross margin would have been approximately 31%. This means unusual items explain most of the headline volatility, but still leave an approximately 3-percentage-point comparable sequential decline, consistent with management's comments on average selling-price pressure. Morgan Stanley consequently lowered its post-2030 energy gross-margin assumption by 1.5 percentage points to 23.5%.
The long-term demand thesis for the energy business remains strong. Management believes AI training workloads will fluctuate sharply over very short periods, and that batteries and power-electronics systems can smooth data-center loads while helping grids improve utilization of existing generation capacity. The question is not the size of the addressable market, but whether Tesla can use software, power electronics, and manufacturing efficiency to sustain gross margins in the mid-20% range as competition intensifies. Record deployments alongside declining margins demonstrate precisely why “power scarcity” does not automatically equate to “high-return energy storage.”
Services Are Improving, but Cannot Yet Offset the Profit Shortfall in Automotive and Energy
Services and Other was an easily overlooked bright spot this quarter. Revenue reached $4.581 billion, up 50% year over year; gross profit was $648 million, with gross margin rising from 9.2% in Q1 to a record 14.1%. Scale benefits are beginning to emerge across used vehicles, Supercharging, after-sales services, and insurance, while early investment in Robotaxi infrastructure is also recorded in this segment.
However, $648 million in gross profit remains small relative to company-wide operating expenses of $4.353 billion. Services can improve full-lifecycle fleet economics and may eventually become a vehicle for software and operating revenue, but for now it cannot offset declining automotive and energy margins. Investors should avoid inferring that “record services gross margin” means “Robotaxi profits have arrived”; under current disclosures, these remain two different things.
R&D; Expense Rose to $2.371 Billion, While Net Income Was Again Lifted by $1.005 Billion in Investment Gains
Tesla’s Q2 operating expenses were $4.353 billion, up 47% year over year. R&D; expense reached $2.371 billion, up 49%, while selling, general and administrative expenses were $1.982 billion, up 45%. Management attributed the increase to preparations for production of Semi, Optimus, Cybercab, and other AI programs, higher depreciation on computing infrastructure, stock-based compensation, and litigation expenses.
Operating expenses consumed nearly all gross profit. Company-wide gross profit was $4.751 billion, leaving only $398 million in operating income after deducting $4.353 billion in operating expenses, for an operating margin of 1.4%. Adjusted EBITDA was $3.273 billion, with an 11.6% margin, down 4% and 3.53 percentage points year over year, respectively.
Yet GAAP net income reached $1.114 billion, significantly above operating income. This was because Tesla recognized a $1.005 billion unrealized gain on its equity investment in SpaceX, partly offset by approximately $300 million in foreign-exchange losses and approximately $100 million in digital-asset losses. In calculating non-GAAP net income, the company excluded $763 million in after-tax SpaceX gains, along with $989 million in after-tax stock-based compensation and other items, resulting in non-GAAP net income of $1.153 billion and EPS of $0.33.
Accordingly, the figure investors should least consider annualizing this quarter is the $1.114 billion in net income. A more reliable analytical sequence is to examine automotive, energy, and services gross profit first; then R&D; and SG&A; expenses; and finally operating income and free cash flow. Investment revaluations can improve reported net income, but they cannot fund Cybercab production lines or AI chip purchases.
The Improvement in Operating Cash Flow Is Real, but Negative Free Cash Flow Was Not a One-Off
Tesla generated $4.697 billion in operating cash flow in Q2, up 85% year over year. Capital expenditures reached $5.789 billion, up 142% year over year and $3.296 billion sequentially, resulting in negative free cash flow of $1.092 billion. Over the past 12 months, operating cash flow was $18.685 billion and capital expenditures were $12.923 billion, leaving free cash flow positive at $5.762 billion; one negative quarter does not mean the company has lost its ability to generate cash.
However, operating cash flow also benefited from working-capital timing. Increases in accounts payable, accrued expenses, and other liabilities contributed $1.94 billion; lower inventory contributed $592 million; while increases in prepaid expenses and other assets consumed $1.259 billion. The cash benefit from supplier credit and delivery timing may not recur every quarter.
More importantly, the $5.789 billion represents only the beginning of the investment cycle. Management explicitly stated on the earnings call that it expects 2026 capital expenditures to exceed $25 billion, increase further in the second half, and continue growing over the next two to three years. Investment areas include the company-owned Robotaxi fleet, Optimus capacity, semiconductor fabs, solar manufacturing, AI compute, battery materials, and conventional automotive capacity.
The company holds $43.524 billion in cash, cash equivalents, and short-term investments, so the balance sheet remains strong. Management also said it is opportunistically arranging up to $30 billion of debt financing capacity. This does not signal “funding stress”; rather, it suggests the company wants to lock in longer-duration capital ahead of its expansion. For common-equity valuation, the question therefore shifts from “Can Tesla invest?” to “When will each additional dollar of investment generate verifiable cash returns?”
Robotaxi: 2.5 Million Paid Miles Mark Progress, but 380,000 Unsupervised Miles Remain an Early Sample
Tesla’s official update disclosed that Robotaxi has accumulated nearly 2.5 million paid miles. Management added on the earnings call that unsupervised Robotaxis have driven more than 380,000 miles across six cities in two states. The company said these miles involved no major accidents and that unsupervised mileage continues to grow at a double-digit rate each week.
These figures must be clearly distinguished. The 2.5 million miles are paid operating miles, not all of which were unsupervised; the 380,000 miles are the sample management cited to demonstrate unsupervised safety performance. Given the statistical characteristics of low-probability safety events, 380,000 miles are insufficient to prove that the system has achieved the extremely high reliability required for large-scale commercial deployment. Management itself described the constraint as achieving “multiple nines” of reliability and emphasized that any single accident could trigger tighter regulation.
Rather than rapidly concentrating vehicles solely in Austin, the company has expanded into more cities to test whether its software can generalize across locations and to address differing local operating and regulatory requirements one by one. This strategy makes technical sense, but it reduces the value of “number of cities covered” as a standalone measure of commercial progress. Investors need metrics such as vehicles per city, paid miles per vehicle per day, deadhead ratio, human-intervention frequency, accident rate, revenue per mile, and operating cost per mile.
Cybercab production has begun, but commercial deployment remains constrained by the lack of data for its new platform. Management explained that Model 3 and Model Y already have road data from millions of vehicles, while Cybercab lacks the same foundation. Test vehicles equipped with steering wheels and pedals must first accumulate mileage to calibrate FSD v15 on the new platform. Therefore, “production has begun” cannot be equated directly with “ready for large-scale deployment into a driverless fleet.” The manufacturing milestone has been reached, but the software and safety milestones remain outstanding.
FSD Attach Rate Above 55% Is This Quarter’s Clearest Evidence of a Software Flywheel
Tesla’s global active paid FSD user base reached 1.48 million, up 56% year over year. More than 55% of new vehicles delivered in North America during Q2 included an FSD subscription at delivery. Management said approximately 55% of existing paid users purchased FSD outright and 45% subscribe, while the company has discontinued new one-time purchase options in most markets; future growth will primarily come from subscriptions.
These figures carry greater financial significance than the number of Robotaxi cities. Vehicle sales bring customers into the fleet, FSD subscriptions increase lifetime revenue per vehicle, and a larger paid user base generates additional usage data and cash flow. If the 55% attach rate is sustained in North America and replicated in more markets following regulatory approval, software revenue could gradually offset pressure on automotive gross margin.
However, Tesla does not disclose quarterly FSD revenue recognized, subscription churn, average monthly fees, free-trial conversion rates, or attach rates by region. The above-55% attach rate also applies only to new North American deliveries, not 55% of the global fleet. It therefore demonstrates that the software flywheel is accelerating, but not yet that software profits are sufficient to fund investment in physical AI.
The Most Candid Optimus Disclosure Is Not the Production Target, but That “the Initial Ramp Will Be Long and Flat”
The first-generation Optimus production line is replacing the former Model S and Model X lines at the Fremont factory, and Tesla expects production to begin soon. The first robots will enter the “Optimus Academy,” accumulating training data through human observation, dedicated demonstrations, and the robots’ own trial and error.
Management’s description of manufacturing difficulty deserves more attention than the timeline. Automotive production can still draw on mature supply chains for wheels, glass, and body components, but many Optimus components must be designed from scratch, sourced from new suppliers, or manufactured in-house. Dexterous hands, actuators, flexible circuits, power electronics, reliability, and general-purpose task capability must all work simultaneously. Management explicitly stated that the initial phase of the manufacturing S-curve will be “very flat and very long.”
This means investors should not linearly extrapolate from “production-line installation” using the experience of automotive factories. Early Optimus validation should proceed in the following order: whether robots can reliably complete non-preprogrammed tasks; whether mean time between failures improves; whether unit material and manufacturing costs decline; whether deployment in Tesla’s own factories produces genuine savings; and only then, external sales volumes. The production vision may determine the upper bound of valuation, but reliability and unit economics will determine when that valuation can enter the base case.
Why Morgan Stanley Cut Its Price Target from $417 to $400
In its initial earnings review on July 22, Morgan Stanley noted that automotive and energy gross margins fell short of expectations, but awaited the earnings call for clarity on the capital expenditure implications. Its full update on July 23 provided the answer: the long-term physical AI thesis remains intact, but the timing and cash cost of the returns need to be reassessed.
Morgan Stanley cut its adjusted EBITDA forecasts for 2026 and 2027 by approximately 7% and 12%, respectively, raised its 2027 capital expenditure assumption from roughly $20 billion to nearly $30 billion, and increased its projected 2027 free cash flow burn from approximately $5 billion to $14 billion. It lowered its price target from $417 to $400 while maintaining an Equal-weight rating.
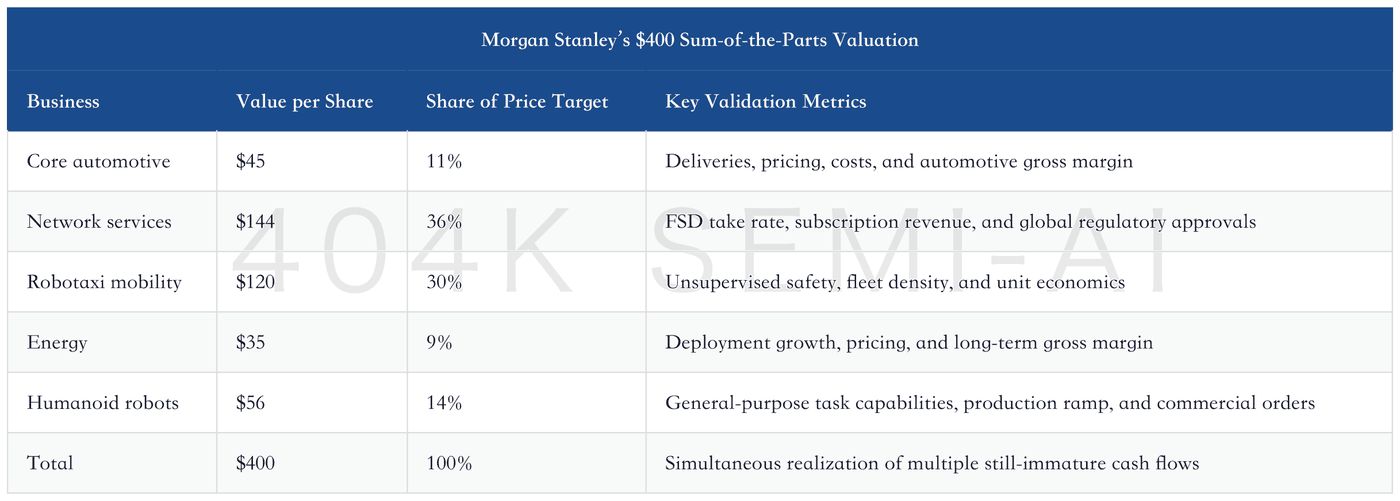
This table reveals the true structure of Tesla’s valuation. Core automotive accounts for only 11%, while network services, Robotaxi, and humanoid robots together represent 80%. Consequently, even if quarterly automotive EPS falls short of expectations, the price target will not decline proportionately. Conversely, any delay in the realization of autonomous driving, Robotaxi, or Optimus would materially amplify the valuation discount.
Morgan Stanley’s bull-, base-, and bear-case price targets are $821, $400, and $130, respectively—a range of more than sixfold. This wide distribution does not reflect an imprecise model. Rather, it reflects an underlying valuation that spans mature automotive earnings and multiple options that have yet to generate stable cash flows. Investors are not dealing with ordinary quarterly earnings volatility, but with the multiplicative effects of technological success probabilities, regulatory timing, capital intensity, and terminal margins.
Goldman Sachs’ $390 Target Is Close to Morgan Stanley’s $400, but the Underlying Logic Differs
On July 22, Goldman Sachs maintained its Neutral rating and $390 price target, based on approximately 150 times expected EPS over quarters five through eight. Morgan Stanley uses a sum-of-the-parts and discounted cash flow approach, valuing automotive, network services, mobility, energy, and humanoid robots separately.
The two price targets differ by only $10, but that does not mean the firms share the same view of Tesla. Goldman Sachs’ framework concentrates forward earnings and a premium valuation multiple within a single earnings metric. Morgan Stanley explicitly assigns most of the value to FSD, Robotaxi, and Optimus. The former is highly sensitive to forward EPS and the valuation multiple; the latter is highly sensitive to the probability of business success, commercialization timing, and capital expenditure.
They genuinely agree on only two points. First, current automotive and energy margins were materially below expectations. Second, the long-term optionality remains, but there is insufficient margin of safety around the current share price. Both $390 and $400 are better understood as “awaiting validation” prices than as values readily derived from current automotive earnings.
The Next Eight Data Points Matter More Than Launching in a Few More Cities
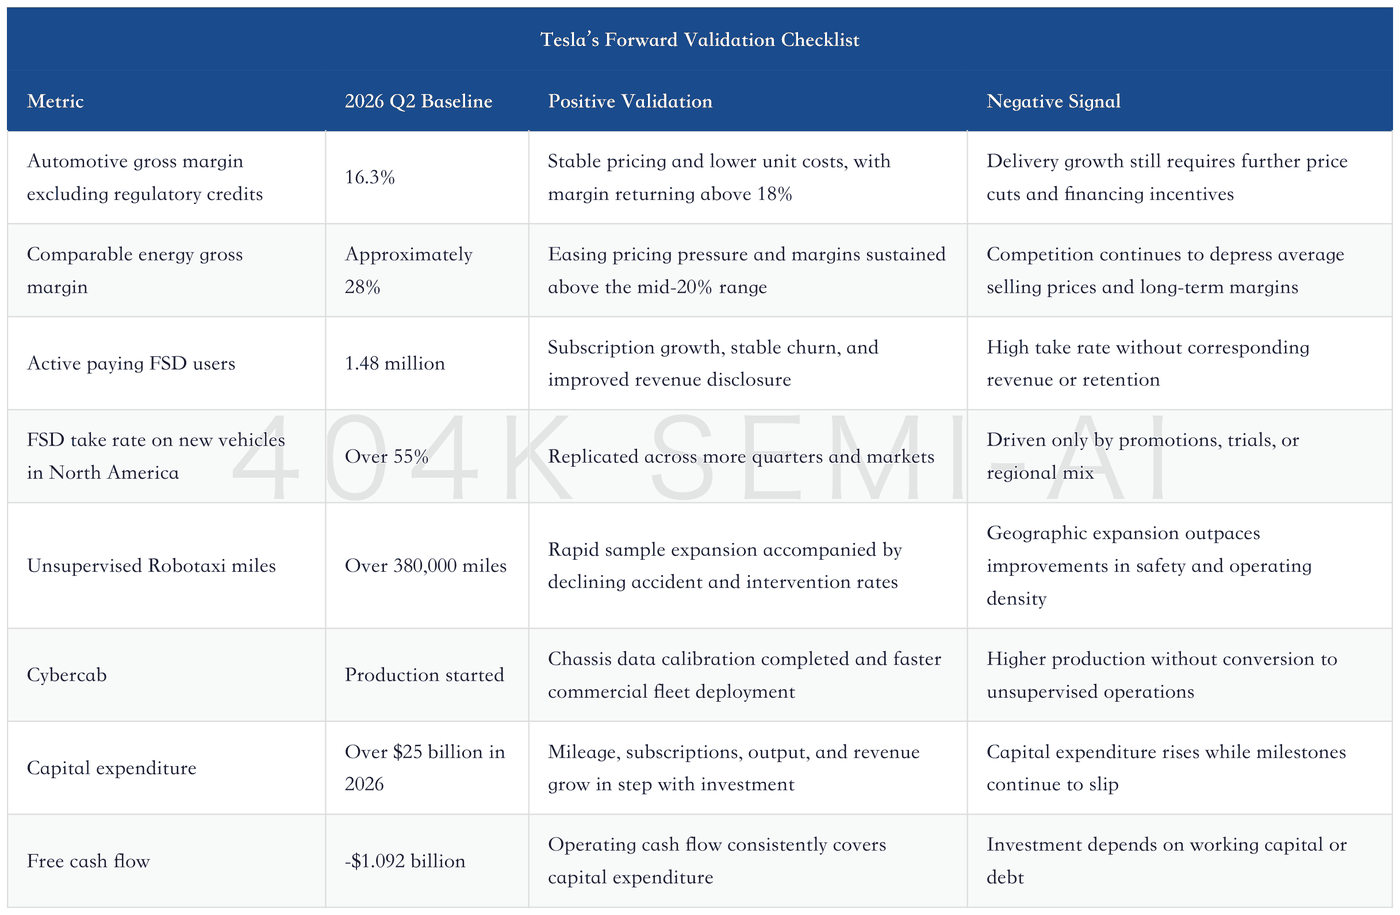
These eight data points follow a clear sequence. Automotive and energy must first stabilize margins; FSD and Robotaxi must then demonstrate software and operating revenue; finally, operating cash flow must cover capital expenditure. Tesla can evolve from a high-valuation option into a verifiable compounding asset only if all three steps—technological progress, commercial revenue, and free cash flow—are achieved.
The Risk Is Not the Number of Narratives, but That Every Narrative Requires Capital at the Same Time
The first risk is core automotive margins. Record deliveries demonstrate demand but do not guarantee pricing or unit costs. If volume growth continues to depend on price cuts, interest-rate subsidies, and a low-margin product mix, the automotive business will provide less internal funding for new initiatives.
The second risk is safety and regulation. Robotaxi’s 380,000 unsupervised miles remain an early-stage sample, and any major accident could alter the pace of expansion. Differing rules across cities and states could also make the commercialization trajectory nonlinear.
The third risk is manufacturing ramp-up. Cybercab requires data for a new chassis, Optimus lacks a mature supply chain, and Semi, Megapack 3, battery materials, and semiconductor manufacturing are all advancing simultaneously. Ramping multiple new production lines at once amplifies risks related to equipment utilization, yields, and supply chains.
The fourth risk is energy pricing competition. Strong data-center power demand does not mean every energy-storage supplier can maintain high gross margins. Gross margin excluding warranty expenses still declined sequentially in the second quarter, demonstrating that average selling-price pressure is real.
The fifth risk is capital structure. Liquidity of $43.524 billion is sufficient to support current investment, but rising capital expenditure over the next two to three years, free cash flow burn, and potential debt capacity of $30 billion will bring financing costs and the return horizon into the valuation equation.
The sixth risk is valuation dependence. In Morgan Stanley’s $400 price target, 80% of the value comes from network services, Robotaxi, and humanoid robots. Any adjustment to the probability of success, commercialization timing, or terminal margins for any of these businesses would have a far greater impact on the price target than a change in one quarter’s automotive earnings.
Conclusion: Tesla Has Proven It Can Do Many Things, but Not Yet That It Can Deliver High Returns While Doing Them Simultaneously
The strongest evidence from Tesla’s second quarter of 2026 was 480,100 vehicle deliveries, 13.5 GWh of energy-storage deployments, 1.48 million active paying FSD users, and nearly 2.5 million paid Robotaxi miles. Automotive, energy, services, and autonomous driving are all advancing. A collapse in demand is not the central issue in these results.
The weakest evidence was a 16.8% total gross margin, a 1.4% operating margin, and negative free cash flow of $1.092 billion. Automotive and energy gross margins fell short of investment-bank expectations, R&D; expenses grew faster than revenue, and net income was boosted by unrealized gains on the company’s SpaceX equity investment. Tesla is using thinner current earnings to fund more businesses that have yet to mature.
The earnings call further confirmed that this was not a one-quarter spending anomaly. Capital expenditure will exceed $25 billion in 2026 and continue rising over the next two to three years, with the Robotaxi fleet, Optimus, semiconductors, solar, AI compute, batteries, and automotive capacity all competing for the same balance sheet. Tesla has the capacity to invest; investors are waiting for evidence of returns.
The most important valuation change this quarter, therefore, is not the invalidation of the long-term narrative but the extension of the discounting period. Goldman Sachs’ $390 target and Morgan Stanley’s $400 target both preserve the physical AI optionality without overlooking margin and cash flow constraints. What will truly determine the valuation is not how many more factories and products management announces, but whether FSD subscriptions can generate visible software profits, Robotaxi can progress from city coverage to density within individual cities, Optimus can move through the long manufacturing S-curve, and operating cash flow can once again cover capital expenditure.
If these four questions are answered affirmatively in sequence, the 1.4% operating margin can be understood as a temporary trough during the buildout of future platforms. If mileage, factories, and capital expenditure continue to grow without corresponding gains in profits and free cash flow, the same investment will be repriced from a long-term moat into a return-on-capital risk. That is the central issue Tesla’s second-quarter results leave the market to resolve.
Information boundary: This article uses Tesla’s unaudited second-quarter 2026 results update, the official earnings-call replay and full transcript, Goldman Sachs’ initial earnings review dated July 22, 2026, and Morgan Stanley’s July 22 flash report and July 23 post-call update. As of publication, Tesla’s investor relations website had not yet provided the Form 10-Q for the quarter. Safety performance and growth rates discussed on the earnings call are presented as stated by management and should not be regarded as independently audited conclusions.
Related Reading
Alphabet Q2 2026 Deep Dive: Cloud Revenue Surges 82%, While AI Capex Pushes Free Cash Flow Negative