
TDK Deep-Dive Update: Citi's JPY4,500 Target Price and How AI Servers Revalue Batteries, HDDs and Passive Components
目录
Too Long; Didn't Read
1. Conclusion First: This Upgrade Buys a "Multi-Engine AI Physical Layer"
2. What Citi Changed: Target Price, Earnings Forecasts and Discount Rate Moved Together
3. Earnings Forecasts: Operating Profit from JPY338.0bn to JPY460.0bn, with Margin Expansion as the Key
4. Segment Structure: TDK's Revaluation Comes from "Profit-Mix Rebalancing"
5. Four AI-Server Lines: Passive Components, HDD, BBU and Higher Battery Value
6. Passive Components: TDK Is Less Pure than Murata, but Broader in Power Components
7. HDD Heads and Suspensions: The Hidden Beneficiary of AI Data-Storage Expansion
8. BBU and Medium-Sized Batteries: A New Entry Point into AI Data-Center Power Reliability
9. Smartphone Batteries: Near-Term Pressure and Long-Term Base Coexist
10. RoIC-WACC Valuation: JPY4,500 Requires Margin and Cash Flow to Materialize Together
11. Financial Quality: Profit Upgrades Must Pass Through Cash Flow, Inventory and Capex
12. Peer Comparison: Murata Is Purity, TDK Is Multi-Engine, Taiyo Yuden Is Torque
13. Three Scenarios: Base Case at JPY4,500, Bull Case on Multi-Engine Resonance, Downside from Handsets and HDD
14. How to Track the Next Four Quarters: First 1Q Progress, Then AI-Related Weight
15. Risk Breakdown: TDK's Biggest Risk Is "Insufficient Multi-Engine Strength"
16. Why Citi Is at JPY4,500: It Should Not Be Mixed with the Earlier JPY5,500 Framework
17. Looking at TDK as a System Problem: It Solves "Stable Operation" for AI Servers
18. The Real Threshold for Multi-Engine Growth: At Least Two to Three Lines Must Deliver Together
19. Data Validation Rhythm: Repair Expectations First, Then Confirm Platform Character
20. Why the Risk Premium Can Fall: The Market Is Buying Higher Verifiability
21. Change in Asset Character: From Smartphone Battery Leader to AI-Server Physical-Layer Portfolio Asset
22. Difference from the Earlier TDK Framework: Citi Focuses More on Near-Term Earnings and Valuation Parameters
23. How to Read Management Commentary: Separate the "Battery Base" from the "AI Increment" First
24. Conclusion: TDK Enters a Multi-Engine Validation Period, and JPY4,500 Must Be Earned Through Segment Profit
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Citi maintains its Buy rating on TDK and raises its target price from JPY2,800 to JPY4,500. The core drivers are simultaneous changes in earnings forecasts, the risk premium and the valuation base year. TDK's AI-server exposure is not built on a single MLCC product. Instead, profit quality is being lifted by passive components, HDD heads, medium-sized BBU batteries and higher smartphone battery content.
Too Long; Didn't Read
Citi has materially raised TDK's valuation anchor. The rating remains Buy, while the target price has been lifted sharply from the prior framework. The move reflects higher operating-profit forecasts, a lower risk premium and a later valuation base year. This reframes TDK from a handset-battery-led electronic components company into a multi-node supplier to AI servers.
AI exposure comes from four lines. Citi expects AI-server-related profit weight to rise gradually, driven by initial shipments of power MLCCs, share in large aluminum electrolytic capacitors, higher value in nearline HDD heads and suspensions, and medium-sized battery revenue growth from the BBU market. Together, these businesses determine whether TDK can move beyond a single battery label.
Earnings upgrades have multiple sources. Citi has moved operating-profit forecasts for the next three fiscal years to a higher level; the specific numbers are in the model tables below. The upgrades include FX, AI-server passive components, aluminum electrolytic capacitors and higher smartphone battery value. Investors need to separate FX sensitivity from operating quality.
Smartphone batteries remain the base. Smartphone batteries still account for a high share of TDK's profit, and Citi assumes the contribution is above 40%. Smartphone-demand downside risk in FY3/27 will therefore continue to weigh on relative performance. The key point is that if 1Q profit grows YoY and progress against guidance is solid, the market may revalue the combination of the battery base and new AI-server variables.
Valuation turns on RoIC-WACC. Citi uses a RoIC-WACC method, rolls the valuation base to a later year and lowers the risk premium. To support a JPY4,500 target price, TDK must prove that operating margin can keep rising while cash flow, inventory and capex all remain healthy.
The next validation rests on six signals. Focus on AI-server-related profit weight, passive-component margins, magnetic applications profit, energy applications cash flow, smartphone-demand revisions and the yen exchange rate. If several lines improve together, TDK looks more like an AI physical-layer platform. If the improvement is only FX or a one-quarter battery rebound, the valuation will fall back toward a normal electronic-components cycle.
1. Conclusion First: This Upgrade Buys a "Multi-Engine AI Physical Layer"
Citi's TDK update is, on the surface, a target-price increase from JPY2,800 to JPY4,500 with the Buy rating maintained. The more important change is that Citi is taking TDK out of its old label of "too much handset-battery profit, insufficient AI-server purity" and redefining it as a multi-node AI-server supplier. These nodes map to four business lines: passive components, HDD heads and suspensions, medium-sized batteries, and higher smartphone battery value.
TDK is very different from the Murata Manufacturing case discussed earlier. Murata's revaluation is concentrated: high-capacitance AI-server MLCCs lift ASP, margins and RoIC together. TDK's revaluation is more diversified. It does not have Murata's clear, single high-capacitance MLCC profit gate, but it has entry points in AI-server power, storage and backup power systems. Diversification reduces near-term torque, but it also improves the stability of profit sources.
Citi's core view is that TDK is still not viewed by the market as an AI-server-related stock because smartphone batteries account for a very high share of total company profit. However, the weight of AI-server-related profit should expand gradually. In FY3/27, these businesses could contribute close to 10% of company profit; in FY3/28, the contribution could reach about 12%. That ratio does not look large yet, but it changes profit quality: smartphone batteries are the old base, while AI-server-related businesses become the new valuation anchor.
Japan Electronic Components Deep-Dive Update: Expansion of High-Value-Added Components for AI Data Centers and Valuation Discipline for Murata, TDK and Ibiden
This report should be read on two levels. The first is financial: Citi raises its FY3/27 and FY3/28 operating-profit forecasts and adds a FY3/29 operating-profit forecast of JPY460.0bn. The second is asset character: TDK is no longer valued only through smartphone batteries and the ordinary electronic-components cycle. It is beginning to be valued through AI-server power, data storage, backup batteries and a broader components portfolio that can explain mid-term margins.
The JPY4,500 target price therefore should not be read simply as "TDK also has an AI theme." A more accurate reading is that Citi believes TDK's multi-business portfolio is entering a new growth phase, while the company still has to deal with traditional constraints such as smartphone battery demand, FX, inventory and segment margins. The investment challenge for TDK is to prove that AI exposure is sufficient to change the profit structure.
2. What Citi Changed: Target Price, Earnings Forecasts and Discount Rate Moved Together
Citi maintains its Buy rating on TDK and raises the target price materially. Based on the reference share price at the report date, Citi still sees meaningful total-return upside. The specific target price, reference price and return split are shown below. The more important point is that this adjustment is driven simultaneously by earnings, the risk premium and the valuation base year.
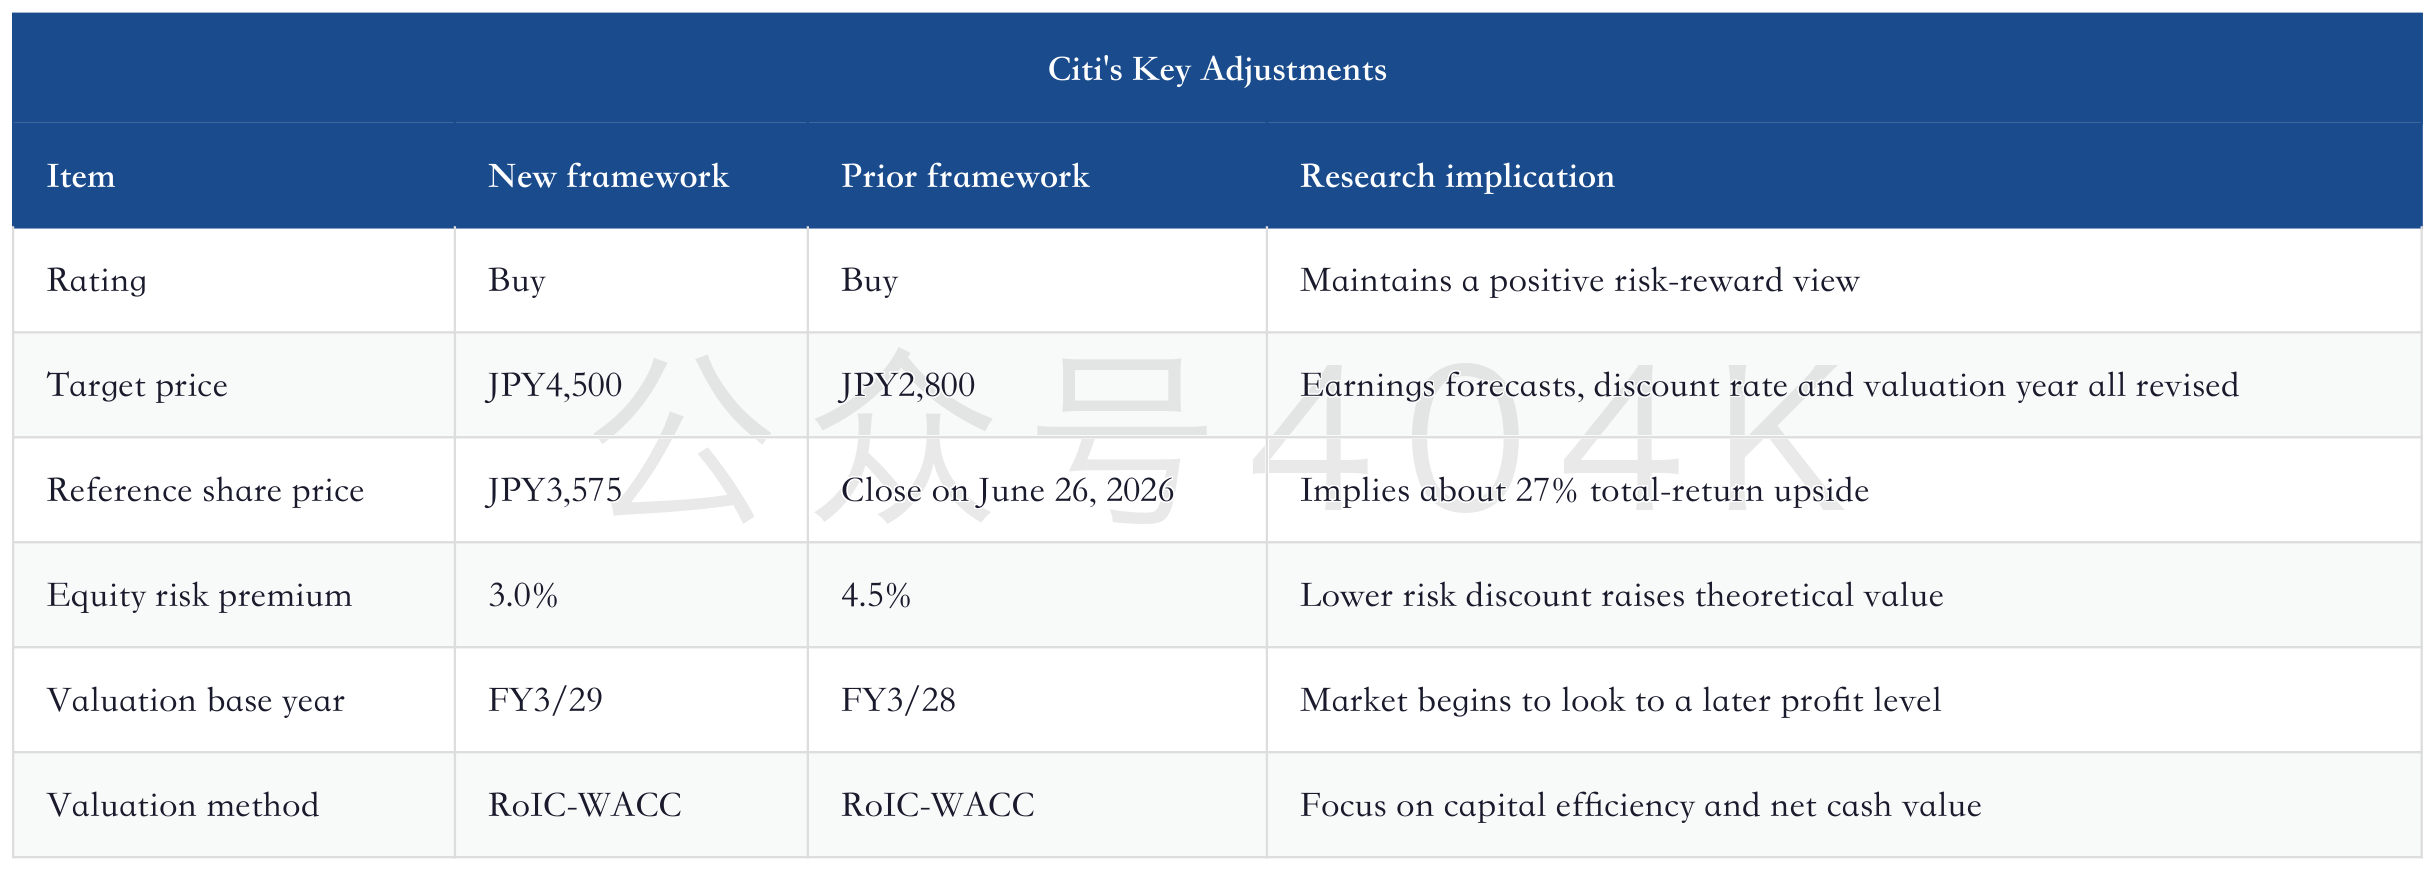
Two items matter most in this table. First, Citi lowers the equity risk premium from 4.5% to 3.0%, which materially lifts long-term value. Second, the valuation base rolls from FY3/28 to FY3/29, implying Citi expects TDK's earnings improvement to continue into the profit-structure changes of the next three fiscal years.
There are constraints to this upgrade. Citi does not frame TDK as a pure AI-server name. The report explicitly notes that smartphone batteries account for a high share of TDK's profit, with Citi assuming the share is above 40%. That means TDK's near-term share price will still be affected by smartphone demand. AI-server-related businesses are increasing their profit weight, but not yet enough to fully offset the handset cycle.
3. Earnings Forecasts: Operating Profit from JPY338.0bn to JPY460.0bn, with Margin Expansion as the Key
Citi raises its FY3/27 operating-profit forecast from JPY314.7bn to JPY338.0bn, up 24.1% YoY; raises its FY3/28 operating-profit forecast from JPY360.6bn to JPY395.0bn, up 16.9% YoY; and adds an FY3/29 operating-profit forecast of JPY460.0bn, up 16.5% YoY. This profit path shows that what Citi is really buying is a year-by-year climb in operating margin.
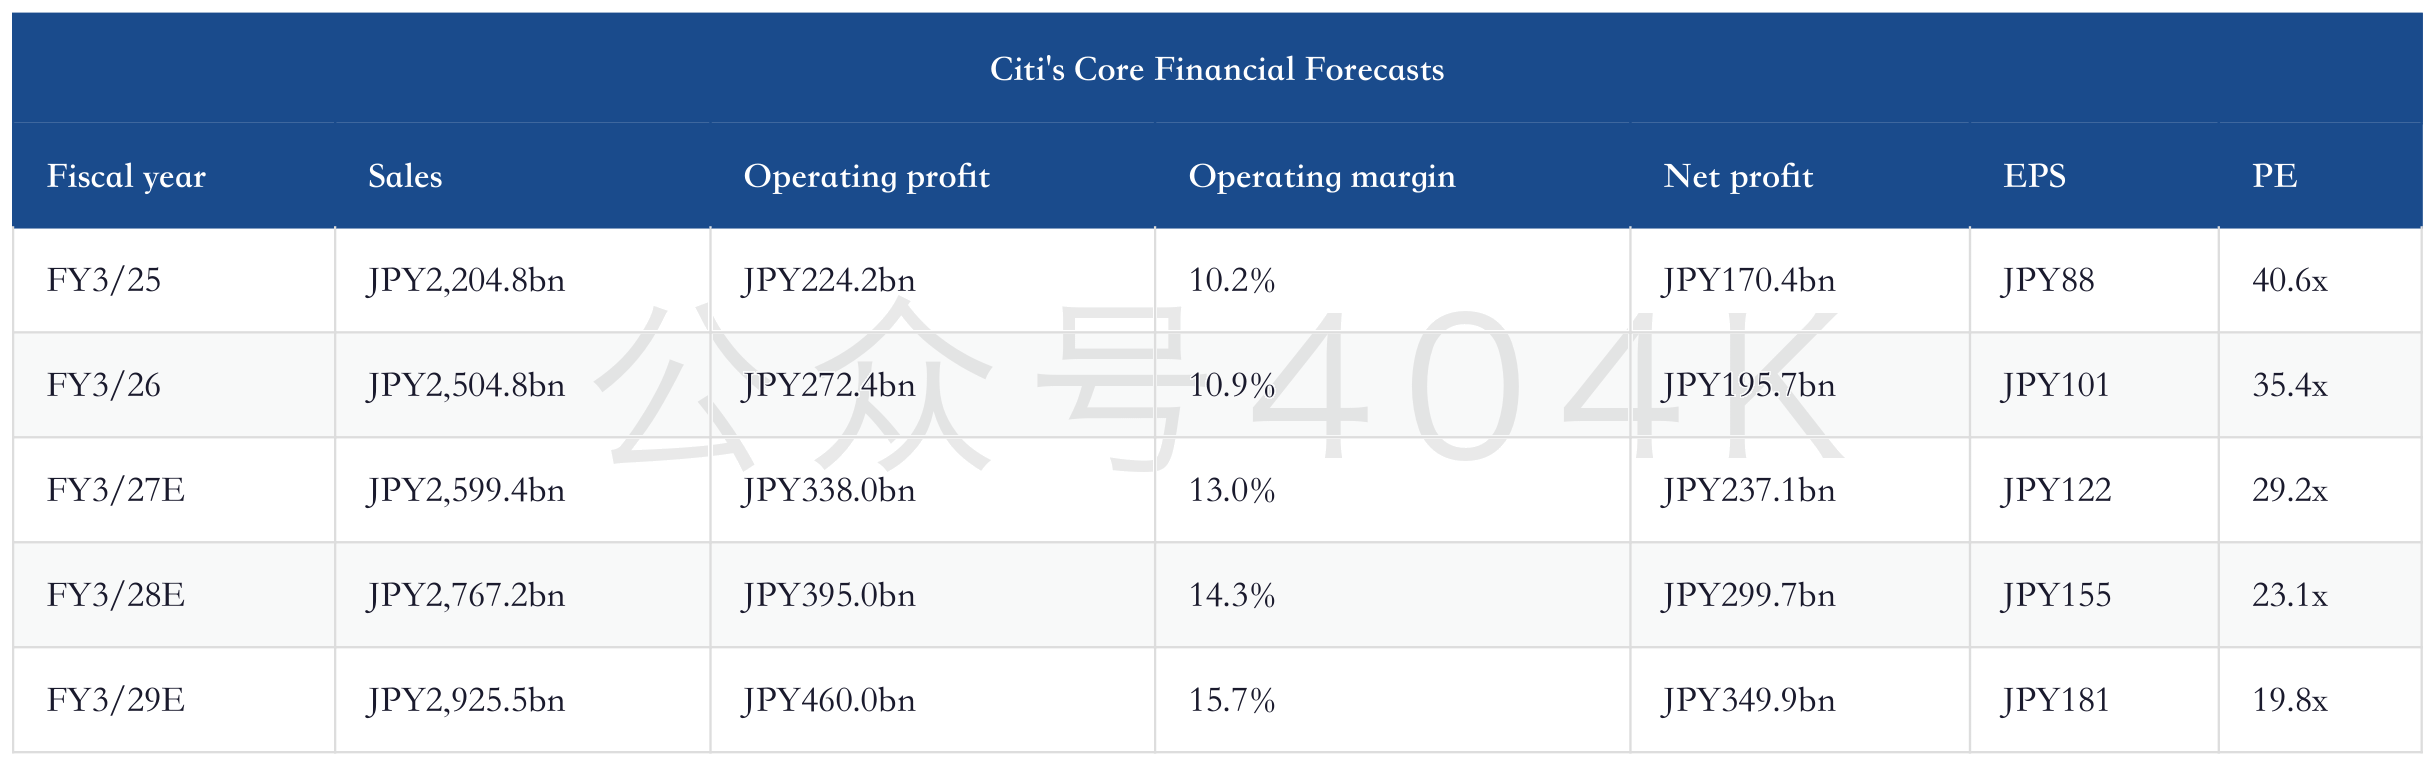
The core of these numbers is margin. Sales rise from JPY2,504.8bn in FY3/26 to JPY2,925.5bn in FY3/29, which is not an extreme increase. The real support for the target price is the operating-margin expansion from 10.9% to 15.7%. If TDK delivers revenue growth but margins do not follow, the JPY4,500 target price will lack support.
Citi's earnings upgrade is mainly composed of three factors: FX, AI-server-related passive components, and higher smartphone battery value. For FY3/27, FX and the 1Q battery outlook are more visible contributors. For FY3/28, the contribution from AI-server aluminum electrolytic capacitors and higher smartphone battery value is clearer. The specific amounts are in the table below. The main point is that upgrade quality gradually shifts from FX toward operating variables.
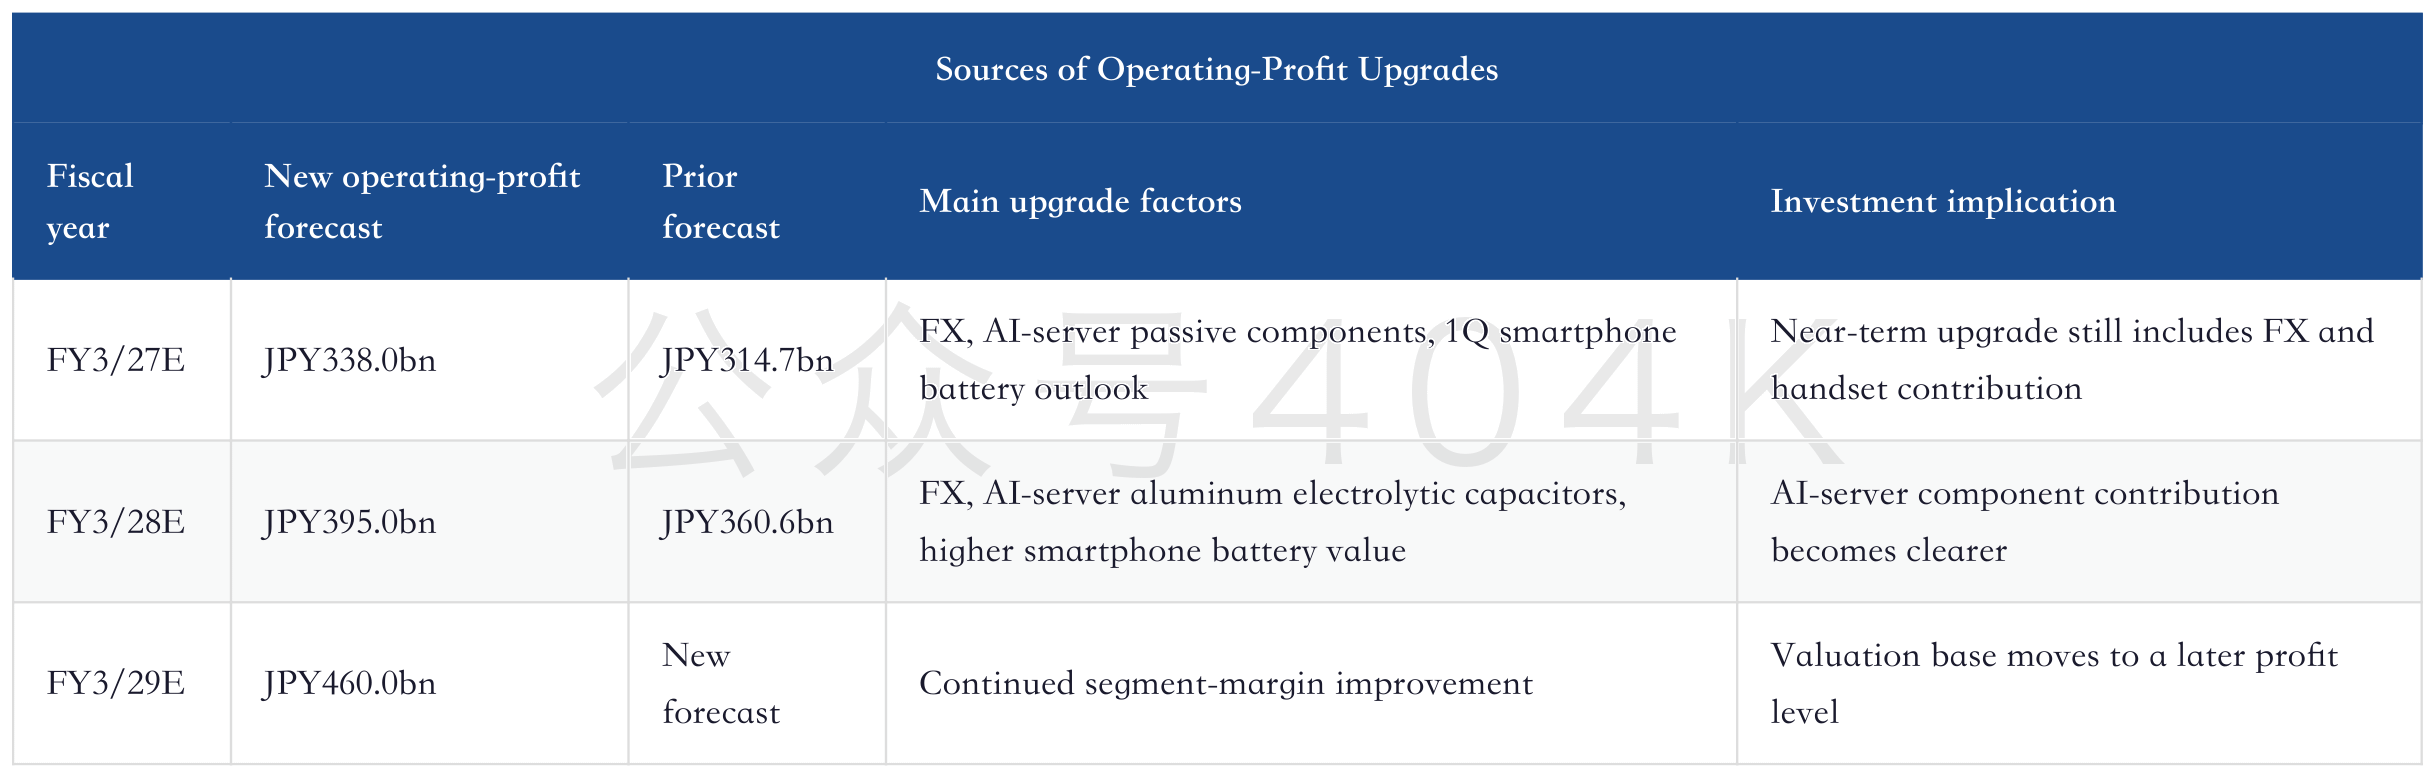
FX and product strength need to be separated. FX helps earnings upgrades, but it does not create a long-term moat. What can be capitalized in valuation is higher AI-server-related business contribution, better passive-component margins, improved profitability in magnetic applications, and higher battery-business value. The quality of Citi's target price depends on whether these operating variables can offset FX volatility.
4. Segment Structure: TDK's Revaluation Comes from "Profit-Mix Rebalancing"
The most important change at TDK is that the profit mix is becoming more balanced. Energy application products remain the profit base, passive components and magnetic applications are improving, and sensors provide a mid-term option. This structure means TDK has less torque than Murata, but better stability.
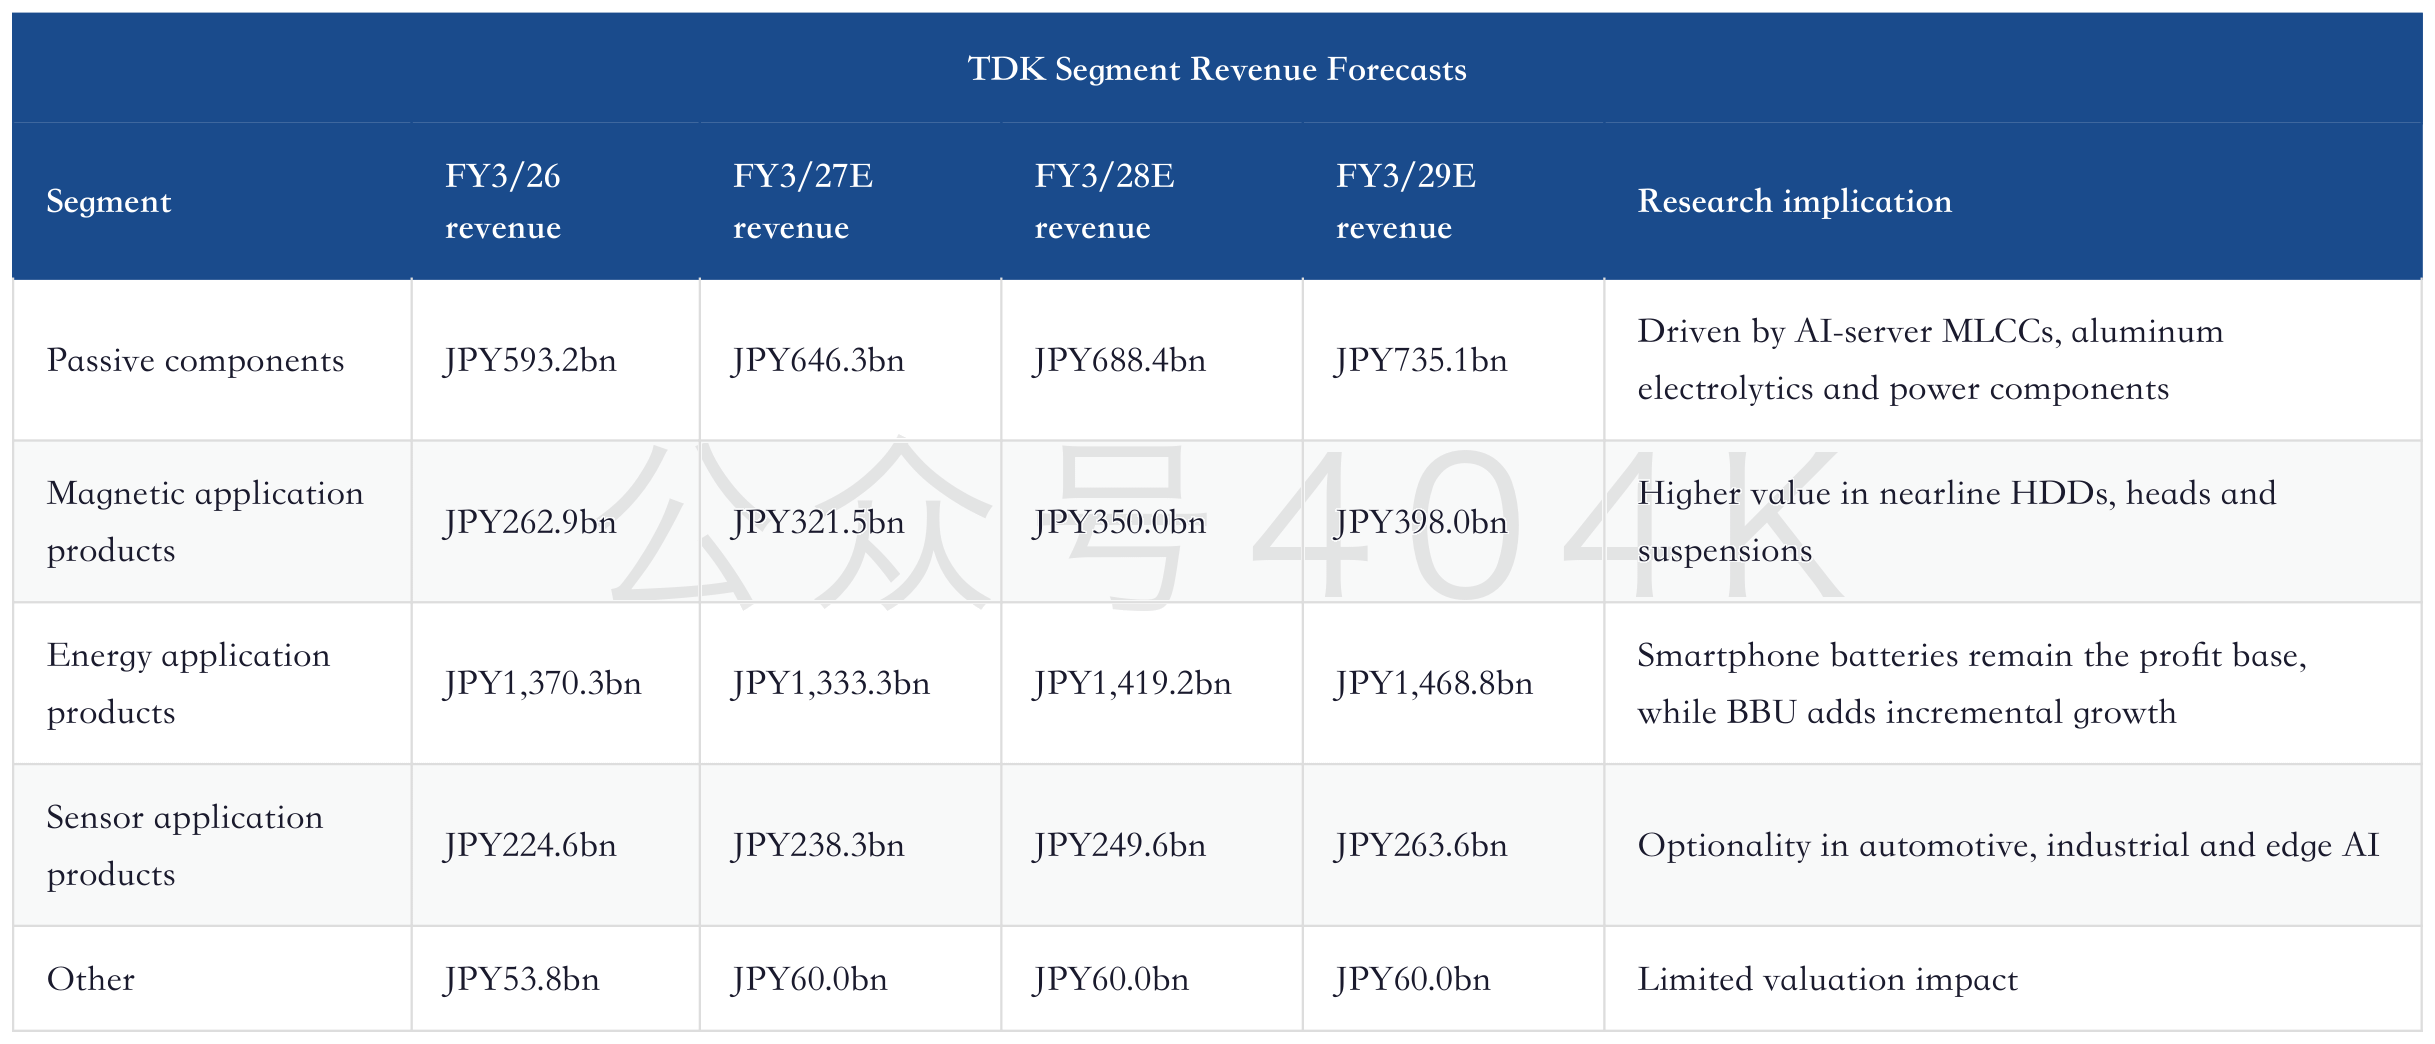
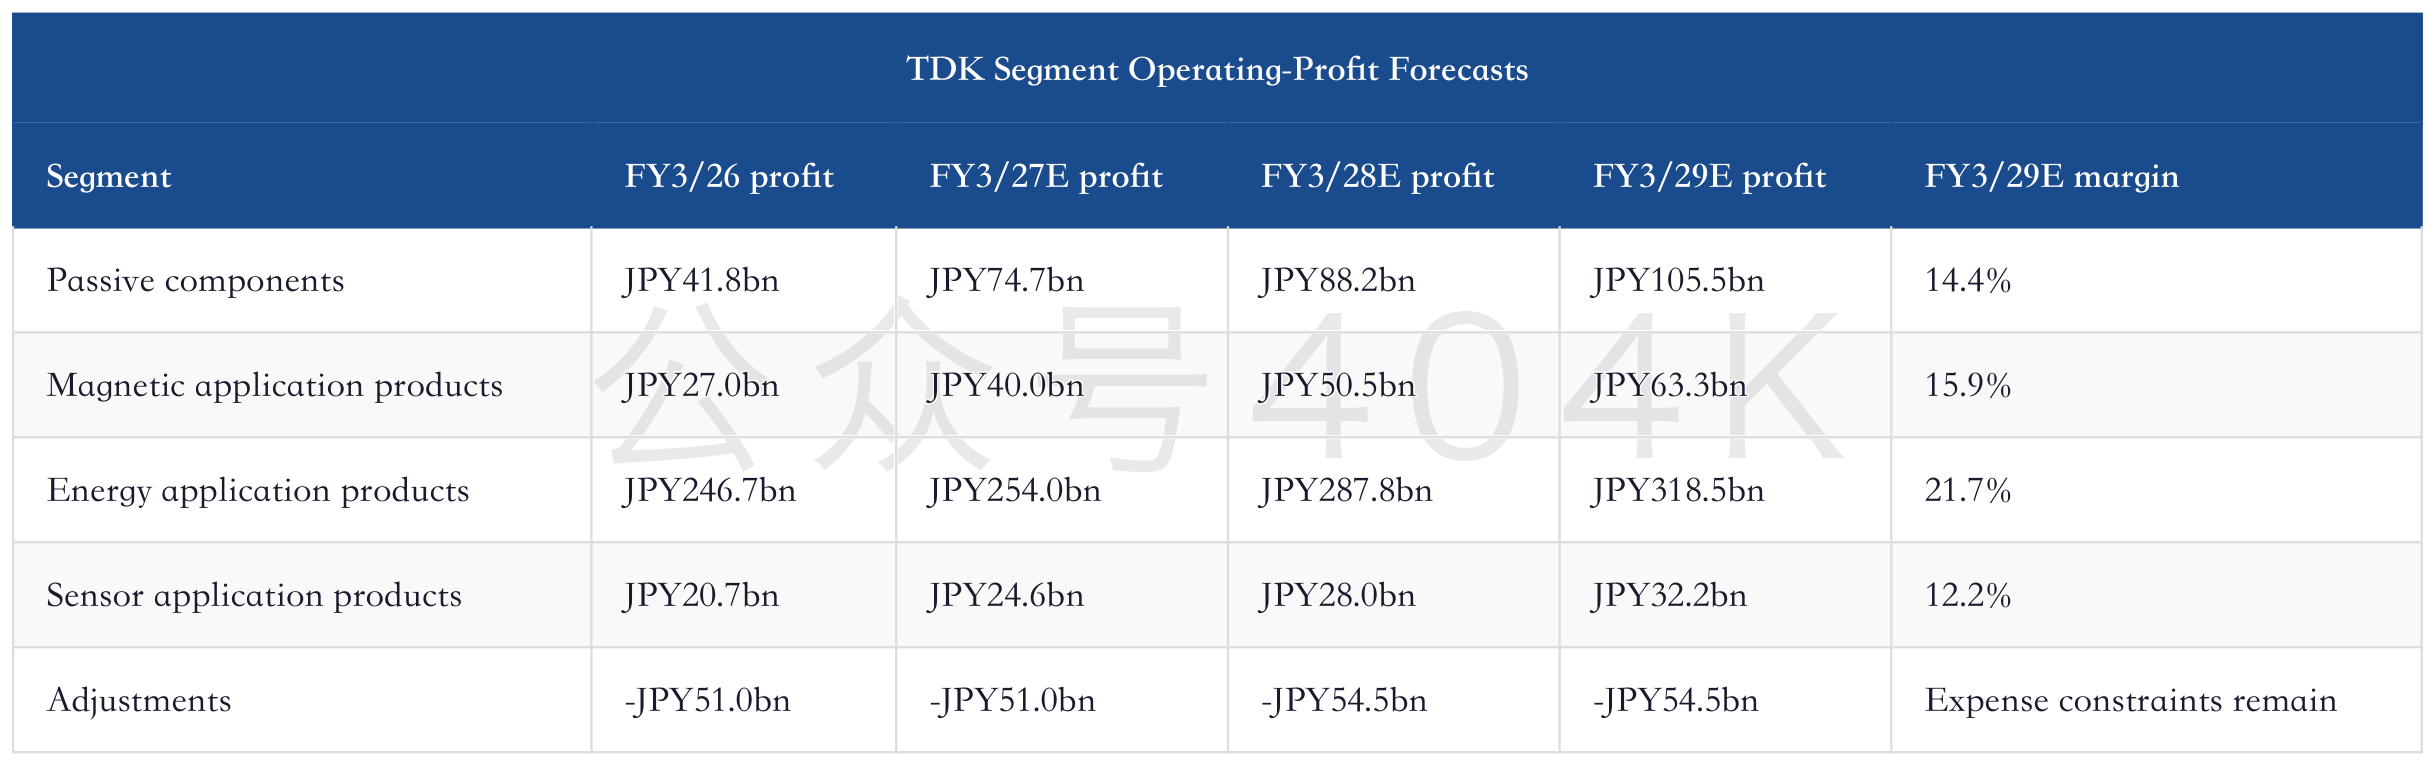
The segment data show that TDK has not moved away from the battery base. Energy application products still contribute the most profit. The real change is that passive components and magnetic applications are no longer just auxiliary segments. In Citi's model, profit in both continues to rise. Together, they lift AI-server-related profit weight meaningfully and broaden TDK's profit sources from smartphone batteries to power components and data storage.
This is the difference between TDK and Murata. Murata's high-end MLCCs are the profit gate, while TDK is hardening across multiple business lines. The market used to explain TDK through smartphone batteries. It now needs to view the company through AI-server power stability, nearline HDD capacity expansion and BBU backup batteries.
Murata Manufacturing Deep-Dive Update: The Profit Gate and Valuation Discipline of AI-Server MLCCs
5. Four AI-Server Lines: Passive Components, HDD, BBU and Higher Battery Value
Citi's AI-server logic for TDK is already mapped to concrete businesses. It divides AI-server-related profit sources into four lines: MLCCs for power applications have started shipping; TDK has a high share in large aluminum electrolytic capacitors and demand is expected to grow; nearline HDD heads and suspensions are gaining value; and medium-sized batteries grow as the BBU market expands. These four lines jointly determine whether TDK can move beyond the single label of "smartphone battery company."
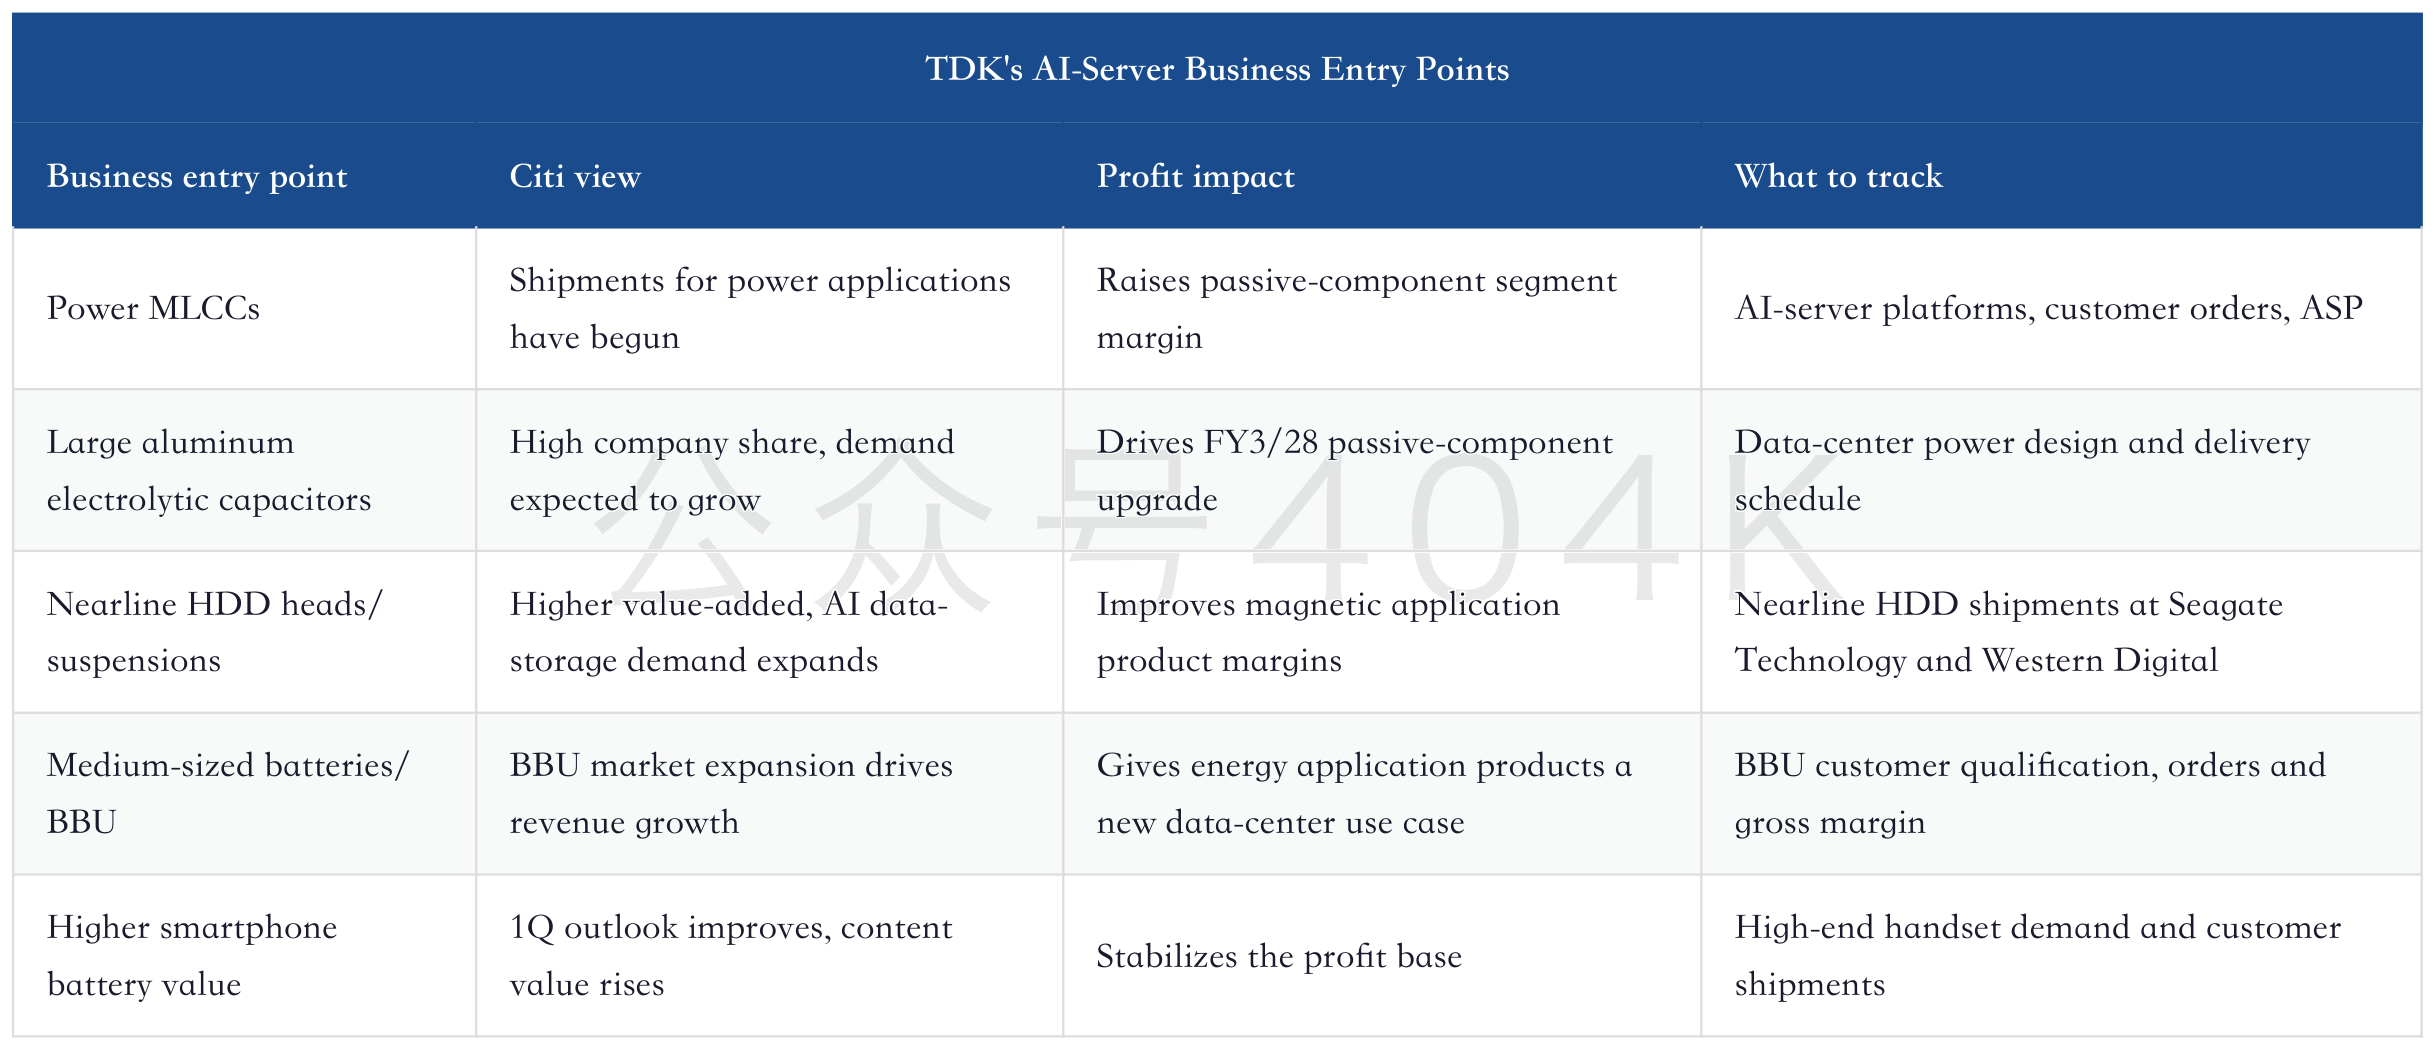
These four lines have one thing in common: they do not sell GPUs directly, but they all support stable AI-server operation. MLCCs and aluminum electrolytic capacitors solve power stability; HDD heads and suspensions serve data storage; BBUs provide backup power; and higher smartphone battery value provides the cash-flow base. TDK's AI exposure is therefore more like a "system reliability asset" than a single compute asset.
This structure also explains why Citi says TDK is still not a typical AI-server-related stock. The market likes pure exposure, and TDK is not pure. But as AI servers move from chip shortages to system delivery, the importance of power, storage, backup power and component reliability will rise. TDK's multi-line layout is well suited to this stage.
The Second Revaluation of the AI-Server Materials Chain: From Passive Components to PCB/CCL, ABF Substrates and Test Equipment
6. Passive Components: TDK Is Less Pure than Murata, but Broader in Power Components
TDK's passive-component business lacks Murata's single-point purity in high-capacitance MLCCs, but its portfolio is broader along the AI-server power chain. As AI-server power rises, board-level power delivery and system power both require more high-reliability passive components: MLCCs, aluminum electrolytics, inductors and magnetic components all benefit. Citi attributes JPY10.0bn of its FY3/28 upgrade to higher AI-server aluminum electrolytic capacitor sales, showing that it values power components beyond MLCCs.
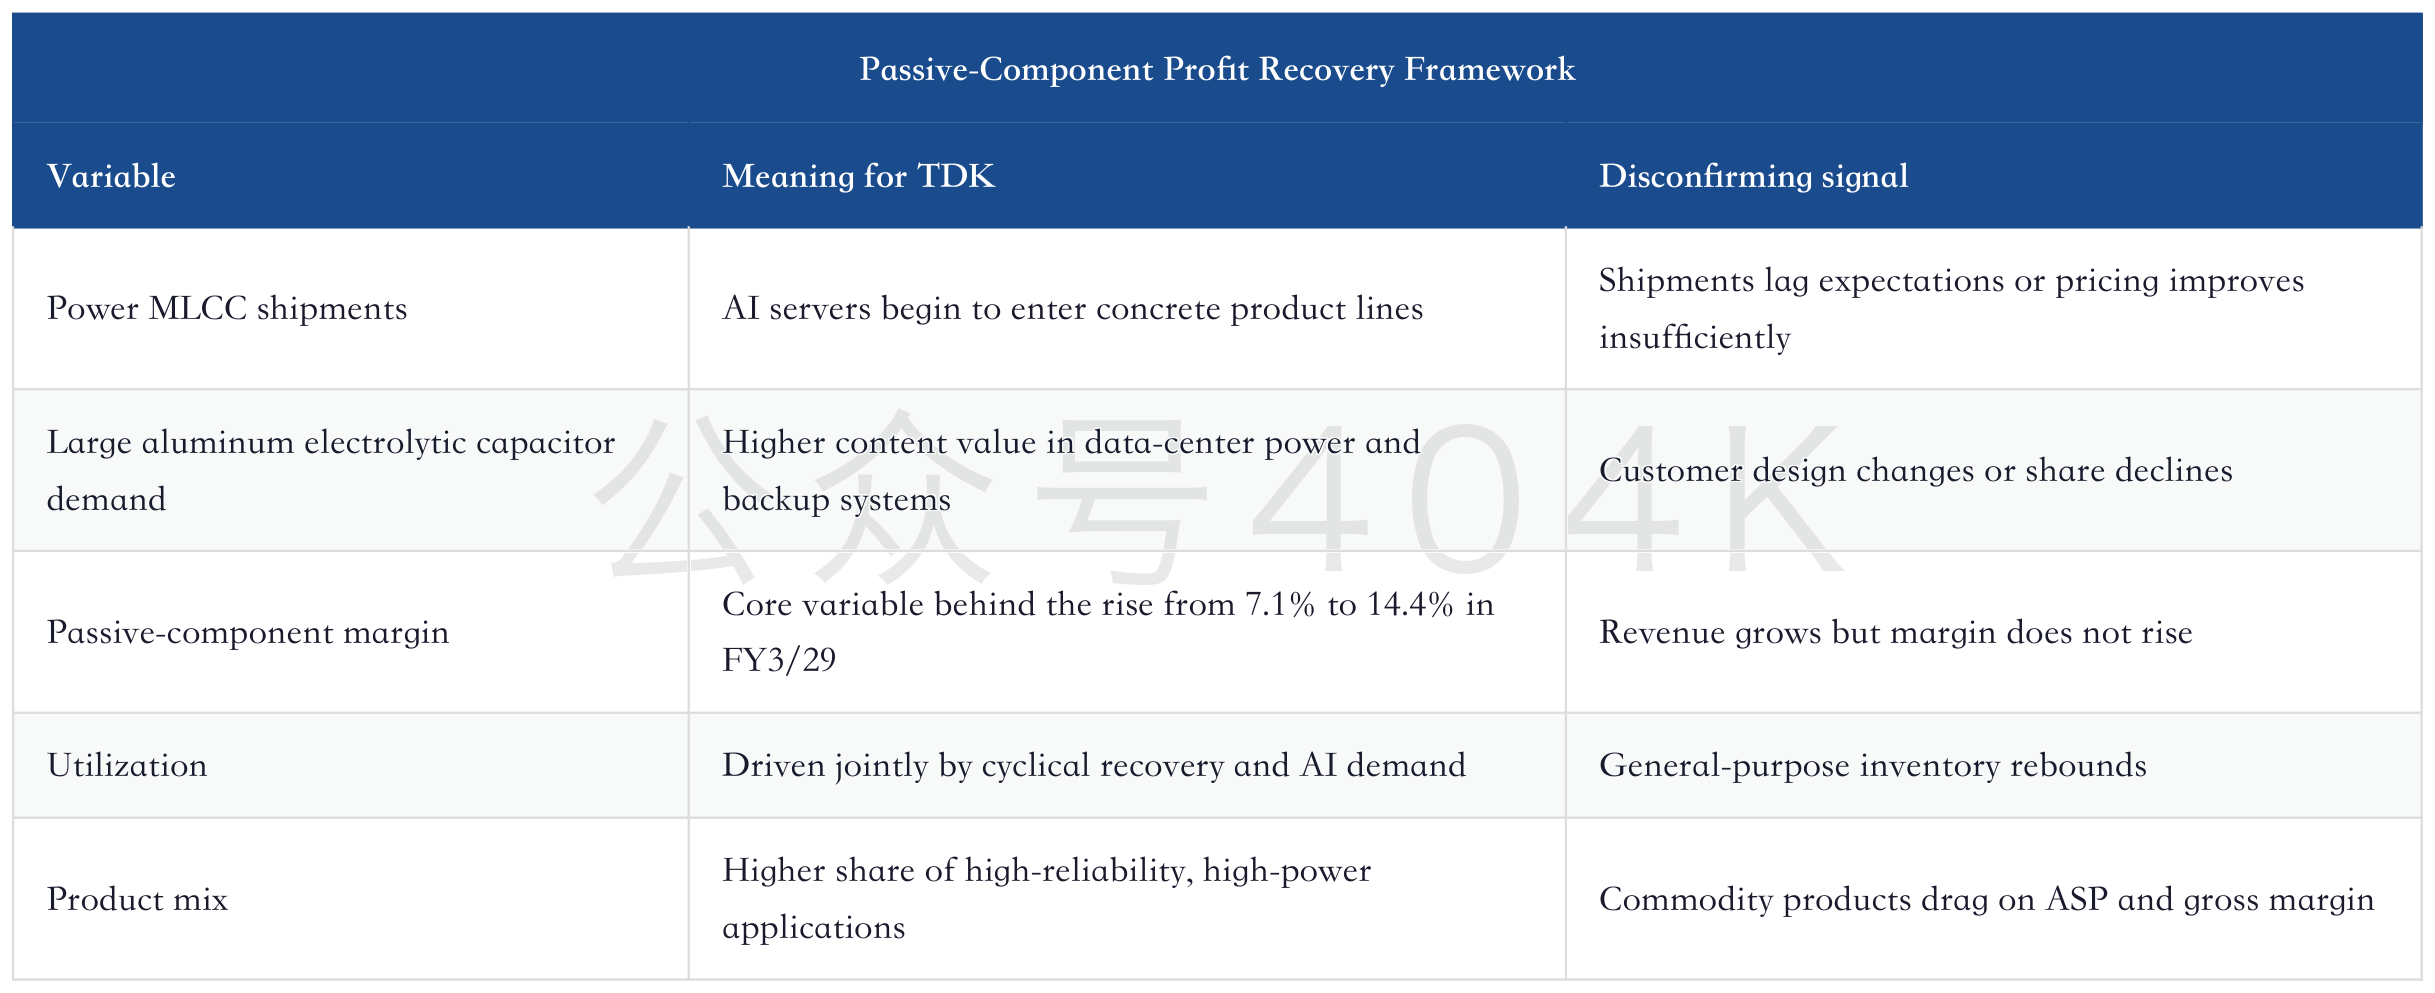
The key to researching TDK's passive components is not to frame the business as a "Murata substitute." TDK is not as pure as Murata in high-end MLCCs, but it can benefit from diversified component demand in AI-server power architecture. AI servers do not need only high-capacitance board-level MLCCs; they also need large capacitors, power inductors and magnetic components to keep power systems stable.
Financially, passive-component segment margin rising from 7.1% in FY3/26 to 14.4% in FY3/29 is one of the clearest segment improvements in Citi's model. If this improvement is delivered, TDK's valuation can move beyond the label of a low-margin components company. If revenue grows but margin does not follow, the market will conclude that AI servers are bringing volume but not profit quality.
7. HDD Heads and Suspensions: The Hidden Beneficiary of AI Data-Storage Expansion
Another spillover from AI servers is nearline HDDs. Data generated by GPU training and inference needs to be stored. Hot data may use more SSDs, but cold data and large-scale long-term retention still rely on the capacity economics of nearline HDDs. TDK does not make complete HDDs, but it makes heads, suspensions and magnetic application products, placing it further upstream in the value chain.
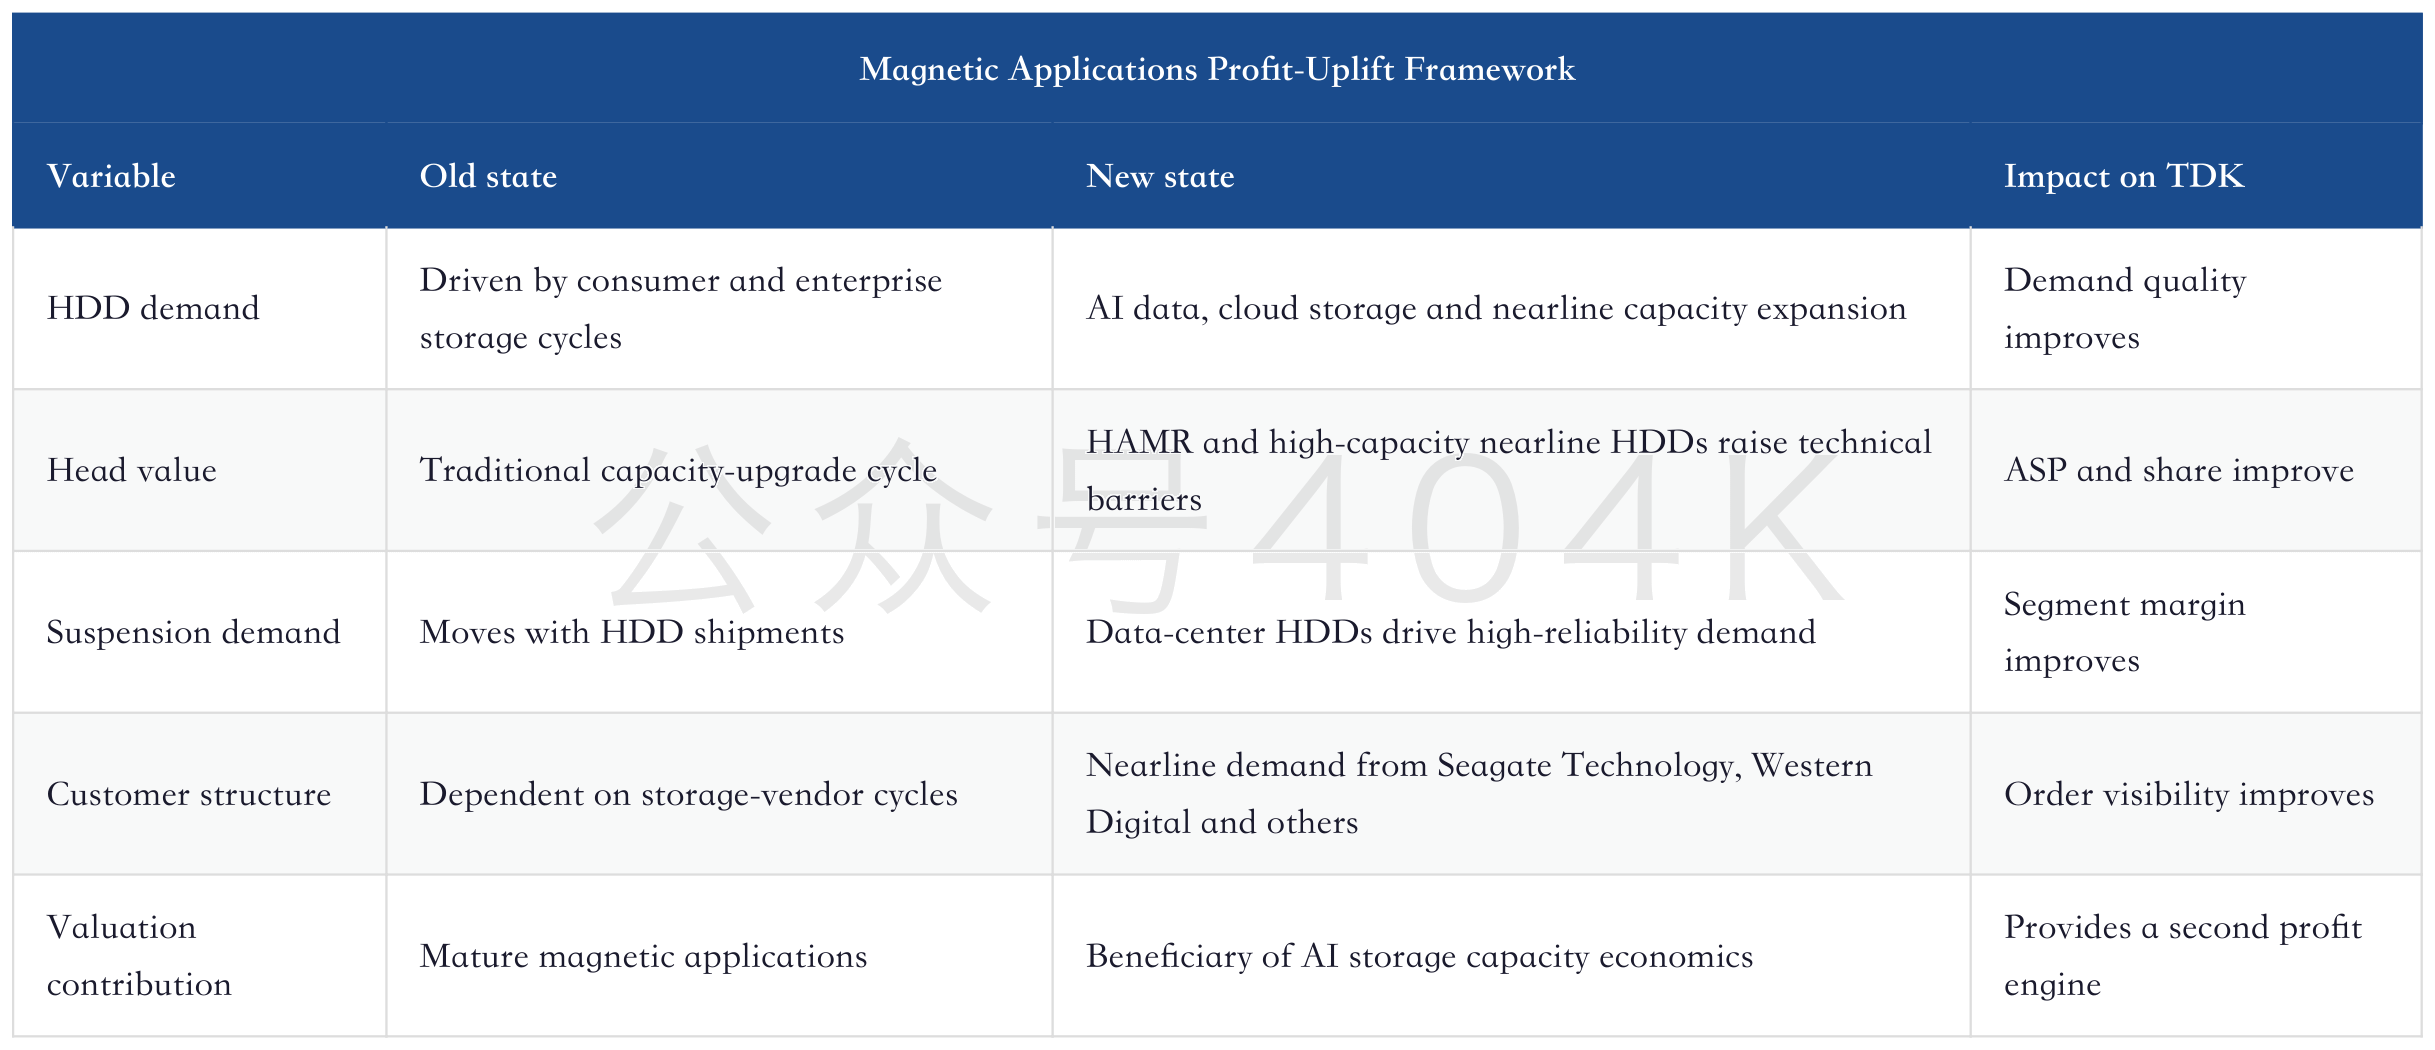
Citi emphasizes the rising value-added of nearline HDD heads and suspensions. This is an underappreciated line for TDK. Revenue, profit and margin in magnetic application products all improve continuously in the model, as shown in the segment table above. This change means magnetic applications are no longer just a mature business; they are starting to share in the profit torque from AI data-storage expansion.
Storage Deep Dive: AI Servers, LTA Contracts and the Margin Revaluation of DRAM/NAND/HBM
The value of this line is that it sits in a different cycle from passive components. Passive components track AI-server power systems and general electronic-component demand. Magnetic applications track data storage and HDD capacity upgrades. If both cycles move up together, TDK's multi-engine structure will materially improve profit stability.
The risks are also clear. If nearline HDD demand falls short of expectations, or if cloud vendors use SSDs more in certain scenarios, growth in heads and suspensions will be lower than the model assumes. If storage vendors change internal capacity or supply strategies, TDK's share could also fluctuate. Investors should therefore track nearline HDD orders at Seagate Technology and Western Digital, HAMR mass-production progress, and TDK's magnetic application margins.
8. BBU and Medium-Sized Batteries: A New Entry Point into AI Data-Center Power Reliability
The old label for TDK's energy application products is smartphone batteries. Citi's update still acknowledges the high share of smartphone batteries, but it also includes medium-sized batteries and BBU market expansion in AI-server-related profit weight. BBU has moved beyond a simple backup battery. It is part of high-power-density and power-reliability architecture in AI data centers.
As AI-server rack power rises, power systems need stronger redundancy, faster response and higher reliability. Traditional UPS, rack-level BBUs, centralized backup power and battery safety management all become part of data-center power architecture. If TDK's medium-sized batteries can enter this market, energy application products can extend from a consumer-electronics base into AI infrastructure.
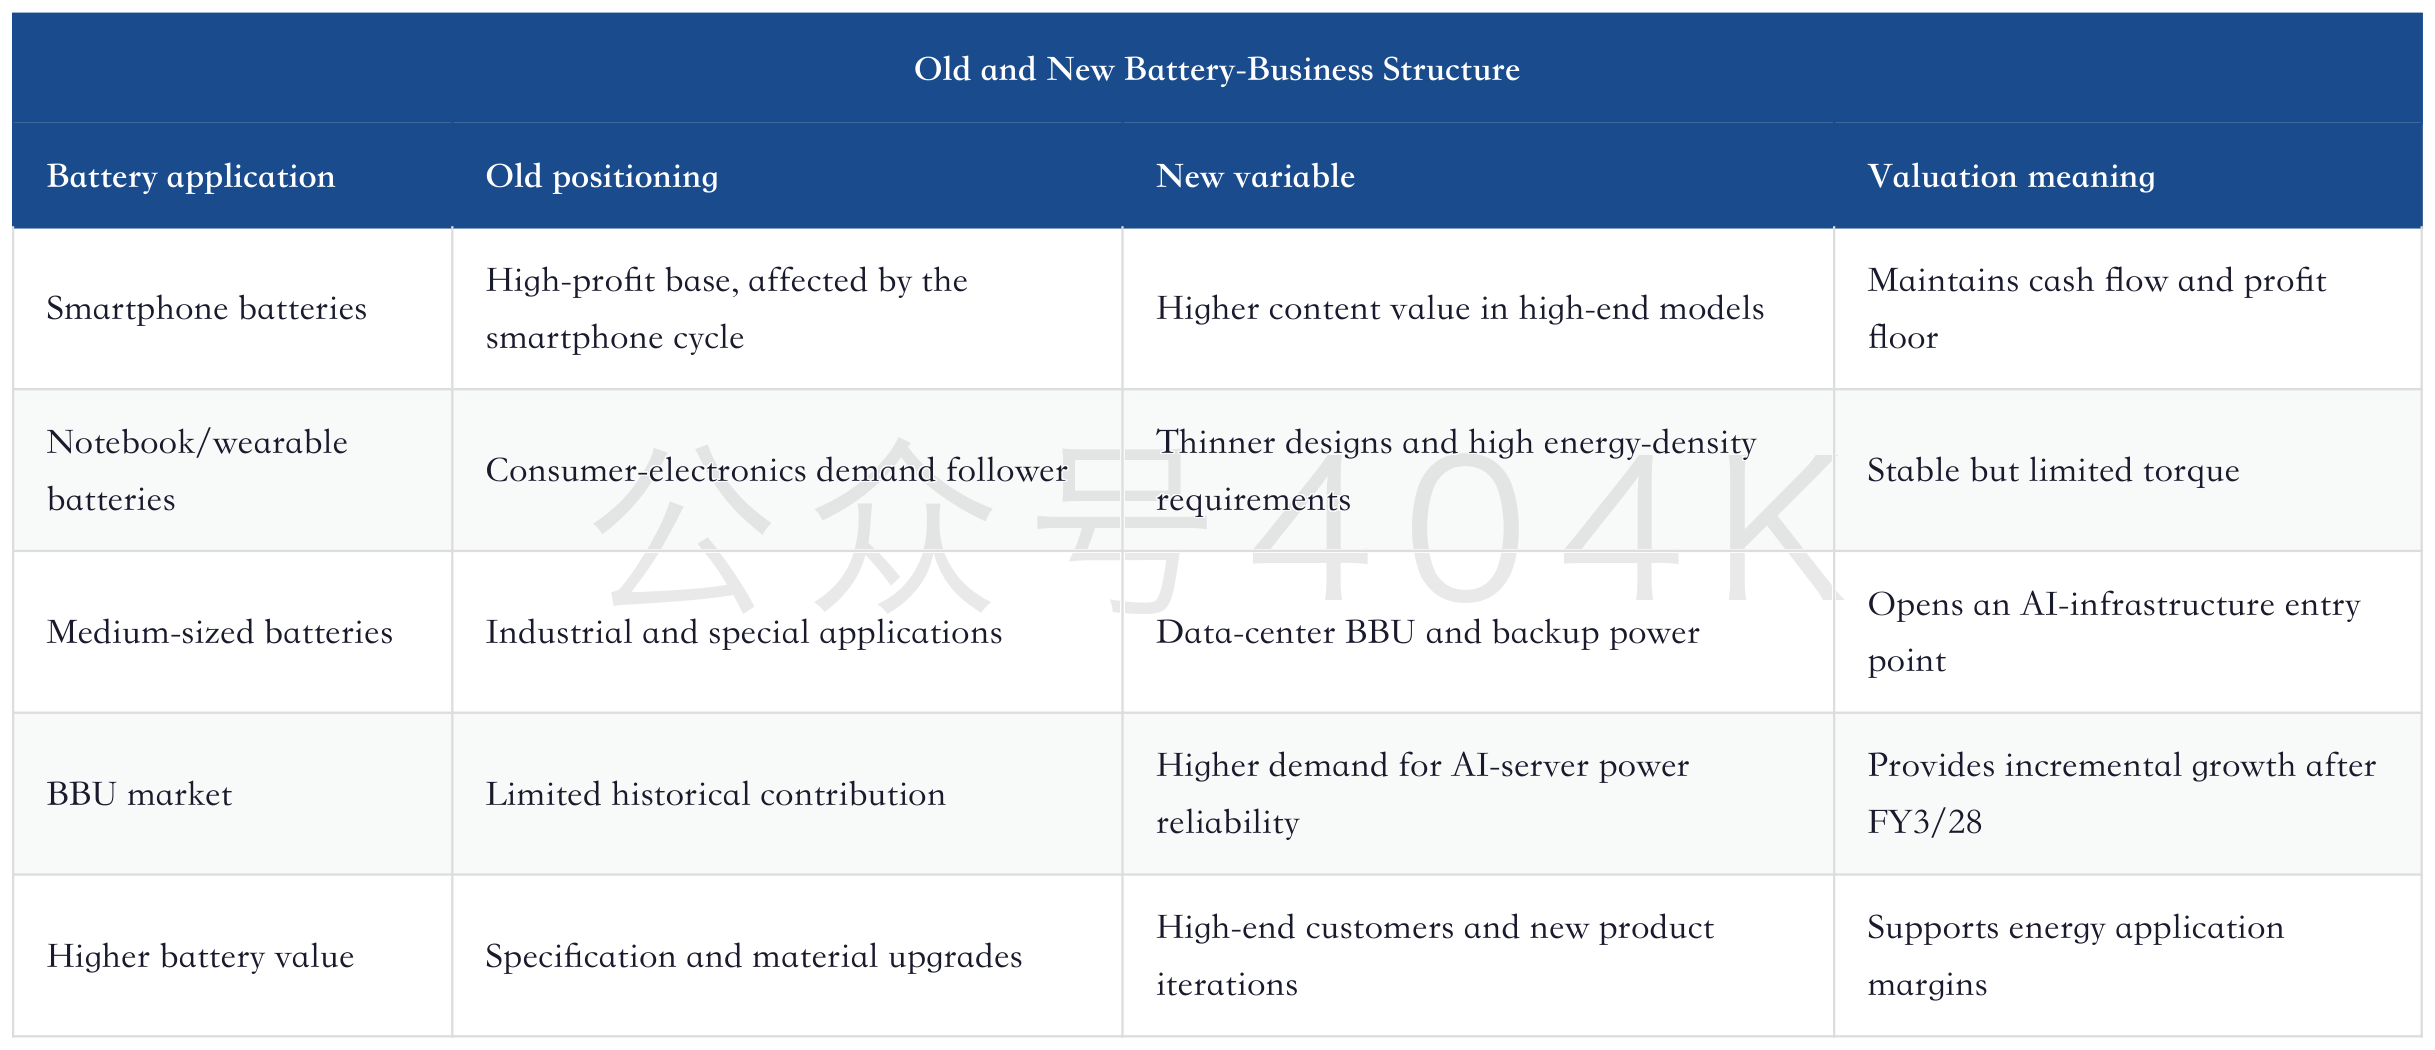
This line matters to TDK because it determines whether the company can reduce dependence on the smartphone cycle. Citi notes that smartphone batteries account for more than 40% of TDK's profit, which will keep the market cautious when smartphone demand weakens. But if BBU, medium-sized batteries and higher value in premium smartphone batteries all materialize, the market will reinterpret energy application products: not just consumer-electronics batteries, but also a supplier to AI data-center backup power systems.
9. Smartphone Batteries: Near-Term Pressure and Long-Term Base Coexist
Citi remains restrained on TDK's near-term risk because of smartphone batteries. TDK assumes total smartphone demand declines by about 10% in FY3/27, a risk that will weigh on the share price's relative performance. At the same time, Citi believes recent China smartphone shipments have still maintained positive YoY growth, and the negative 1Q impact may be more limited than the company originally feared.
This point is critical. TDK is still not a pure AI-server stock, so if 1Q smartphone battery profit grows YoY and progress against the company's initial guidance is solid, the market may revise overly pessimistic expectations. In other words, the near-term catalyst can come from outside AI servers: it may come from handset-battery downside risk being less severe than feared.
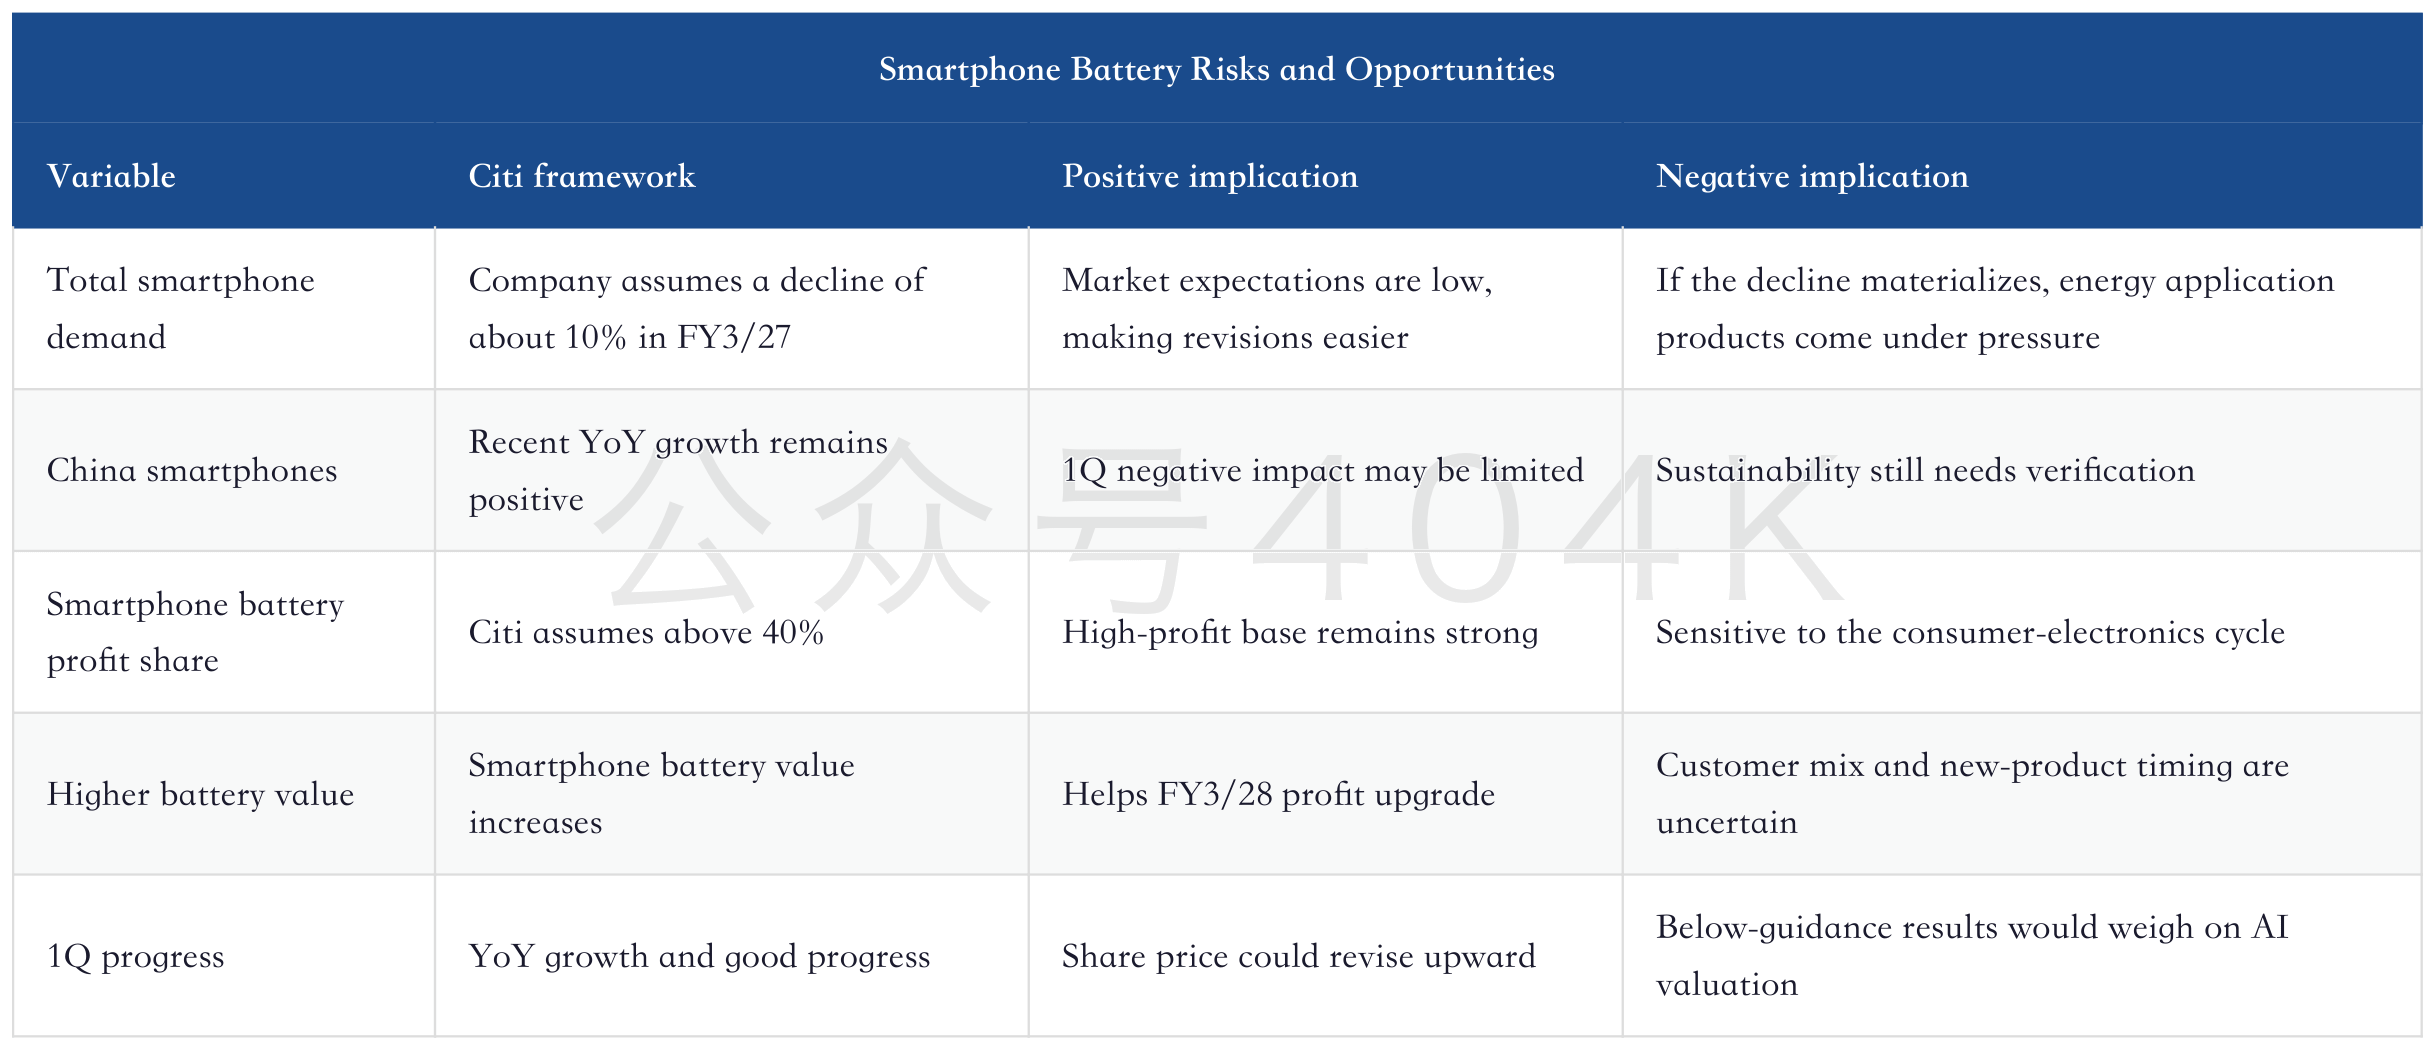
Investors need to accept TDK's dual character. The new valuation anchor is in AI-server-related businesses, while the old profit base remains smartphone batteries. In the near term, 1Q smartphone battery performance will affect market sentiment. In the medium term, whether AI-server-related profit weight can move from close to 10% toward 12% or even higher will determine whether the valuation can keep rising.
10. RoIC-WACC Valuation: JPY4,500 Requires Margin and Cash Flow to Materialize Together
Citi values TDK using a RoIC-WACC method and includes net cash. Key assumptions include FY3/29 as the base year, an expected growth rate of 0%, a risk-free rate of 2.0%, and an equity risk premium of 3.0%. Theoretical shareholder value comes from FY3/29 adjusted NOPAT, the future business-value multiple, terminal net cash and minority interests, then discounted at WACC.
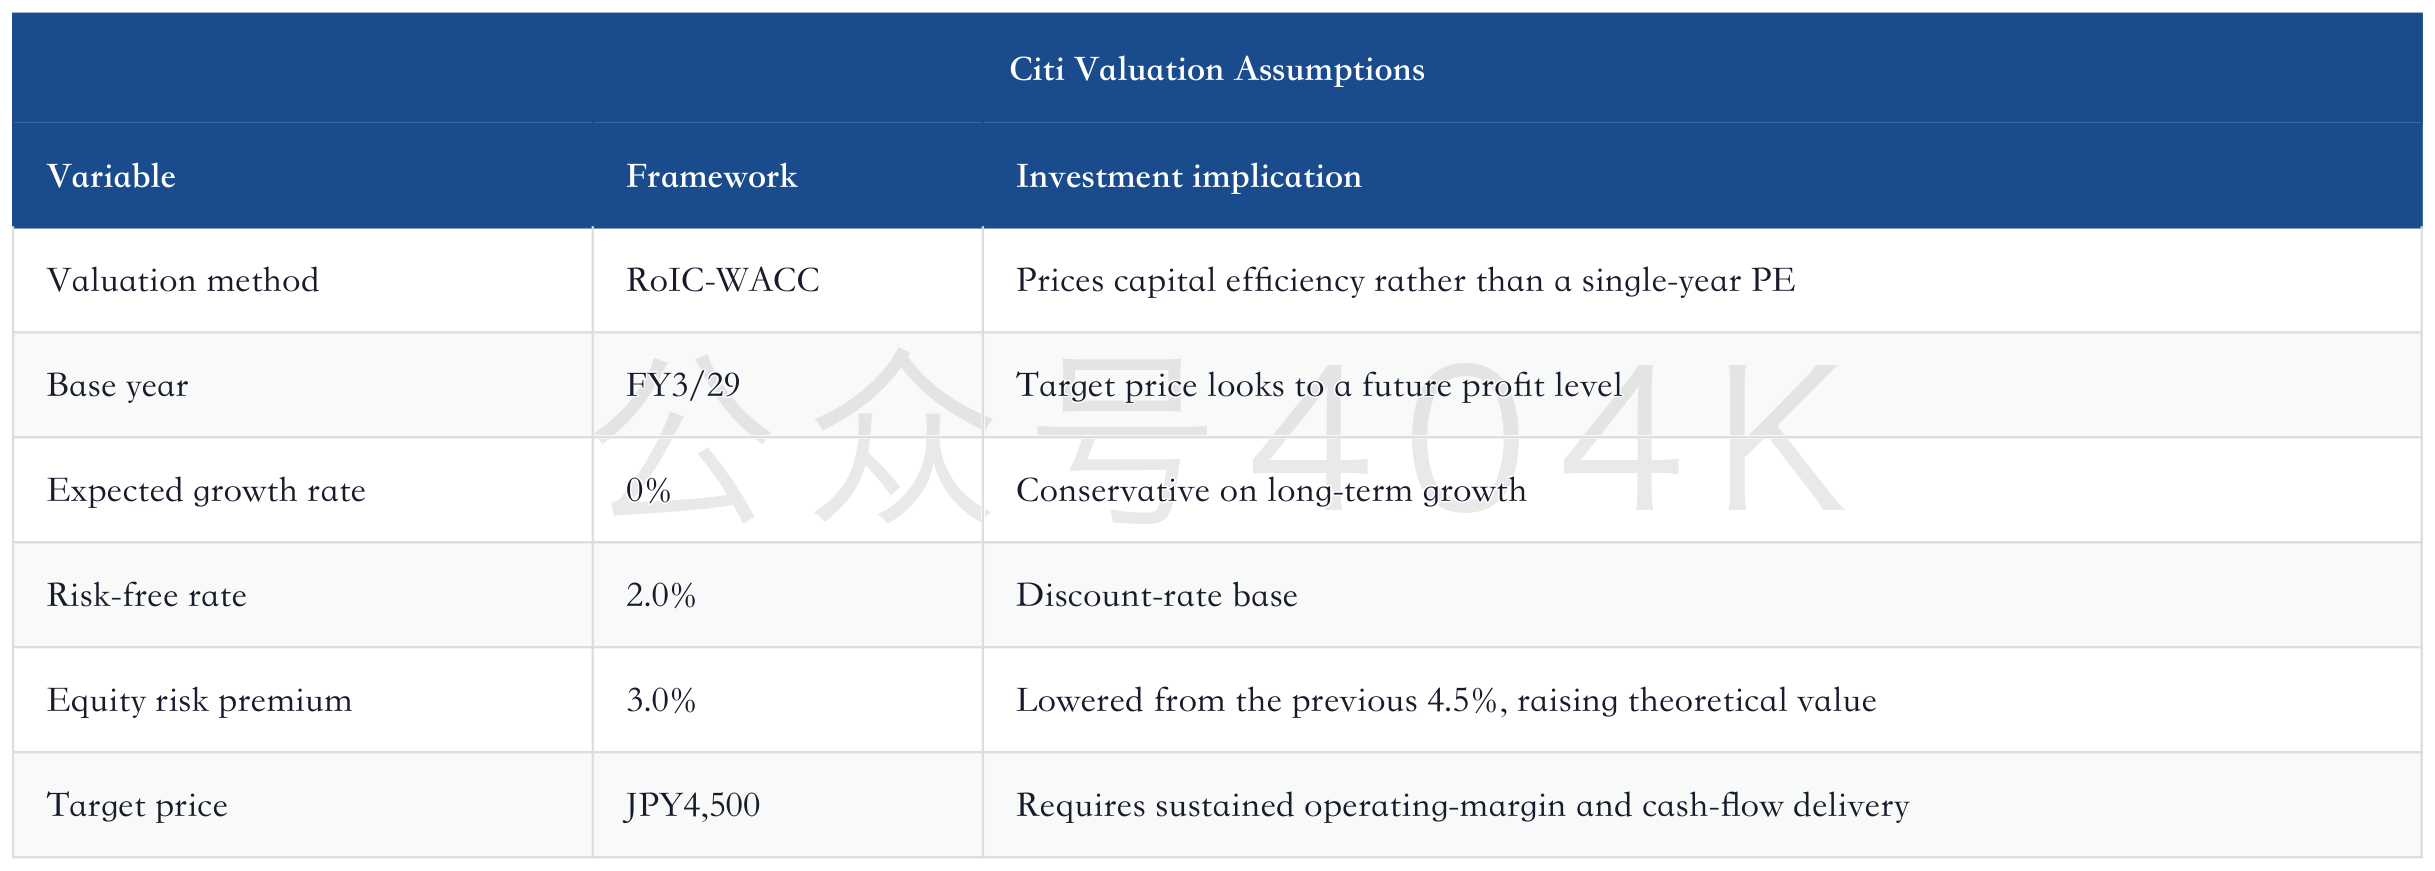
This valuation framework suits TDK. TDK is a multi-business compounder, and its value comes from several business lines improving capital returns together. RoIC-WACC can place passive components, magnetic applications, batteries and cash flow into one framework, avoiding excessive focus on short-term torque in any single segment.
But the valuation is also sensitive. Lowering the risk premium from 4.5% to 3.0% materially raises the target price. If handset demand, HDD demand or AI-server component growth falls short, the market may raise the risk premium again. Rolling the valuation year to FY3/29 also means investors are paying in advance for distant profit. The further out the profit, the more important quarterly validation becomes.
11. Financial Quality: Profit Upgrades Must Pass Through Cash Flow, Inventory and Capex
TDK's financial quality should be viewed through three filters: cash flow, inventory and capex. Citi expects FY3/27 capex of JPY370.0bn, materially above JPY190.0bn in FY3/28 and FY3/29. At the same time, free cash flow is forecast at JPY301.6bn in FY3/27, JPY337.9bn in FY3/28 and JPY338.1bn in FY3/29. In other words, FY3/27 is the key year in which investment and profit rise together.
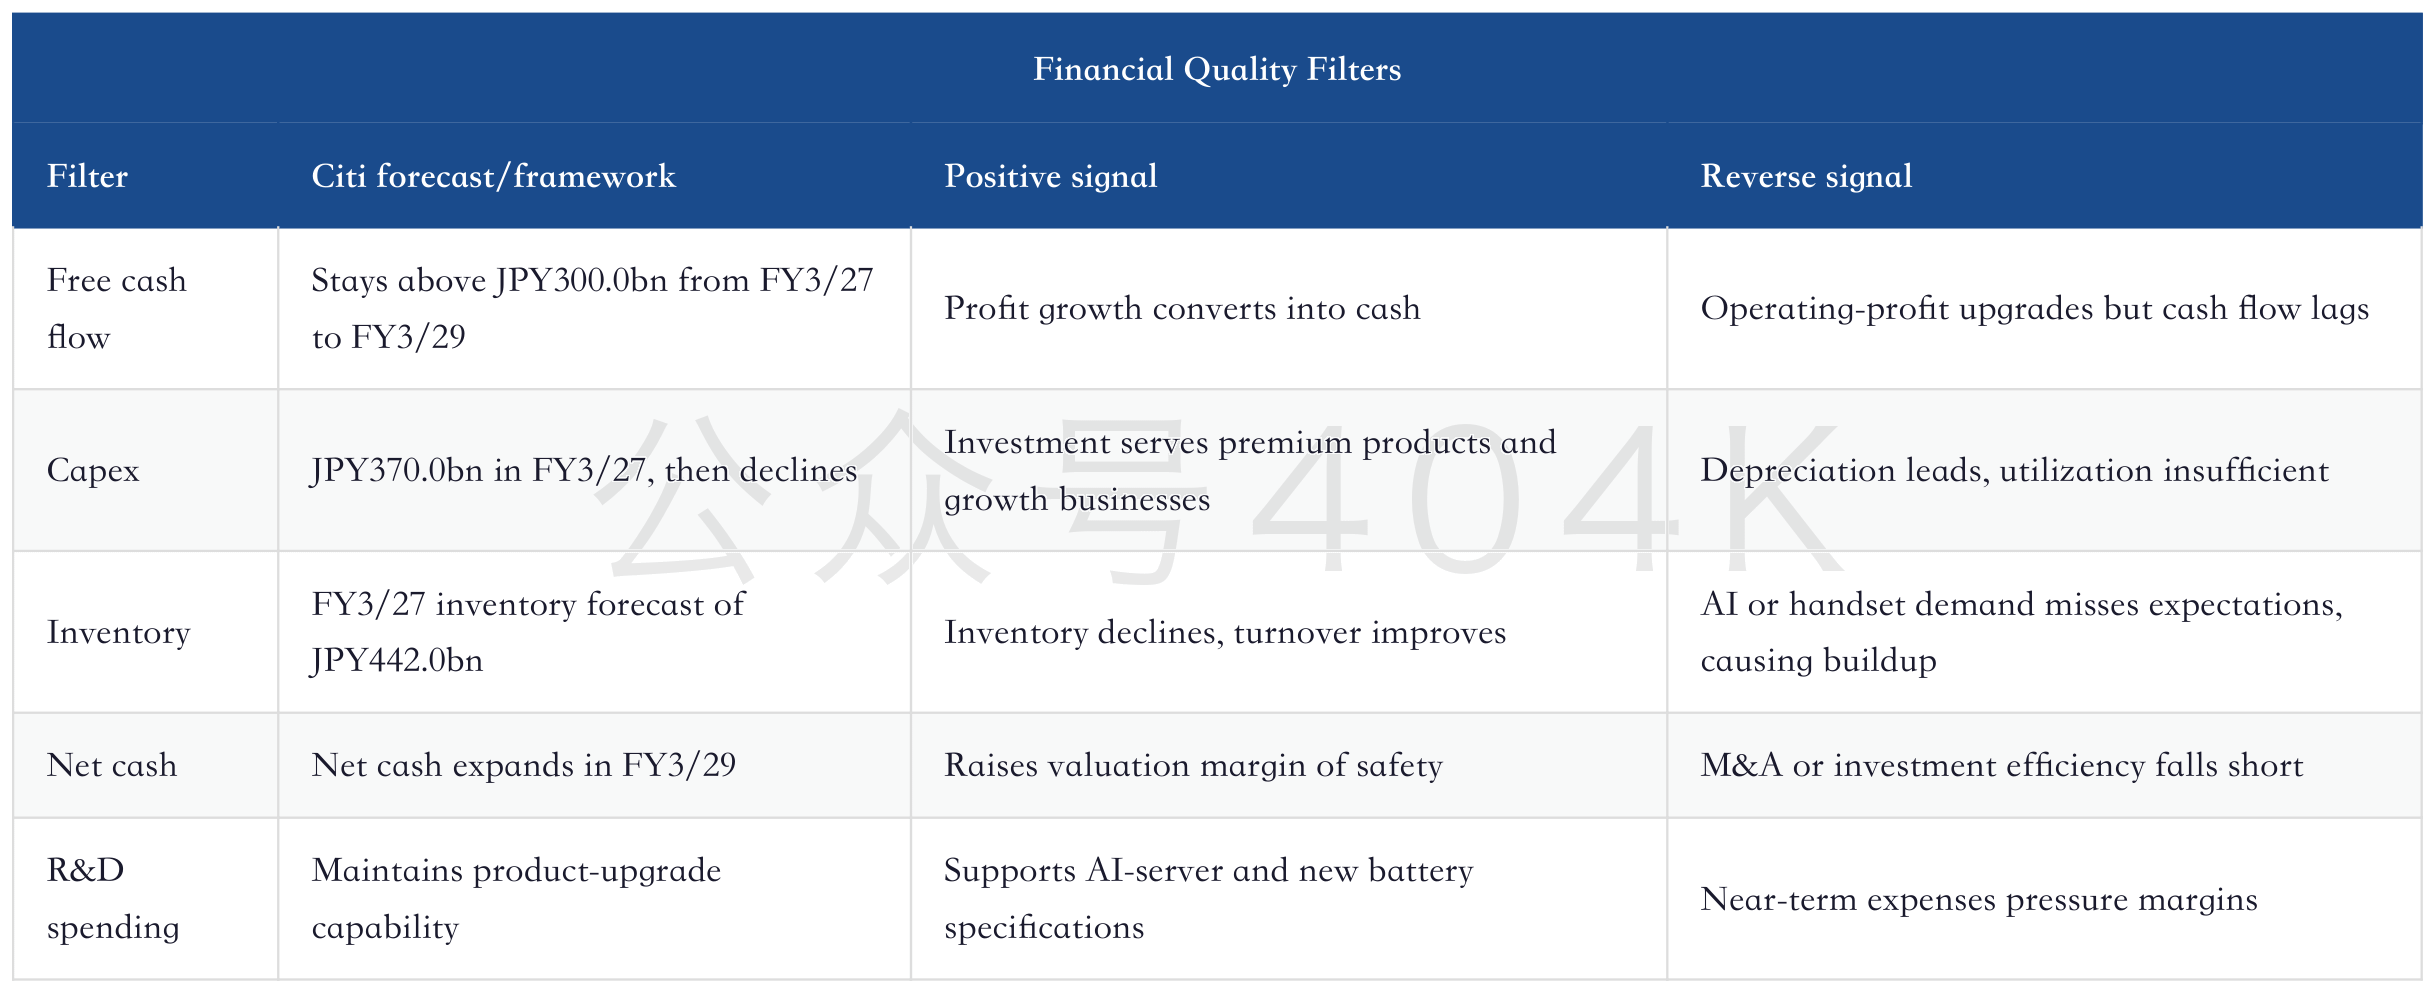
TDK's advantage is that cash flow is not weak. Its risk is that it has many business lines, and any one of them could create a mismatch between inventory and capex. Weak handset-battery demand would affect energy application cash flow; higher commodity passive-component inventory would compress margins; HDD-demand volatility would affect utilization in magnetic applications. Citi's JPY4,500 target price requires these variables to remain healthy overall.
12. Peer Comparison: Murata Is Purity, TDK Is Multi-Engine, Taiyo Yuden Is Torque
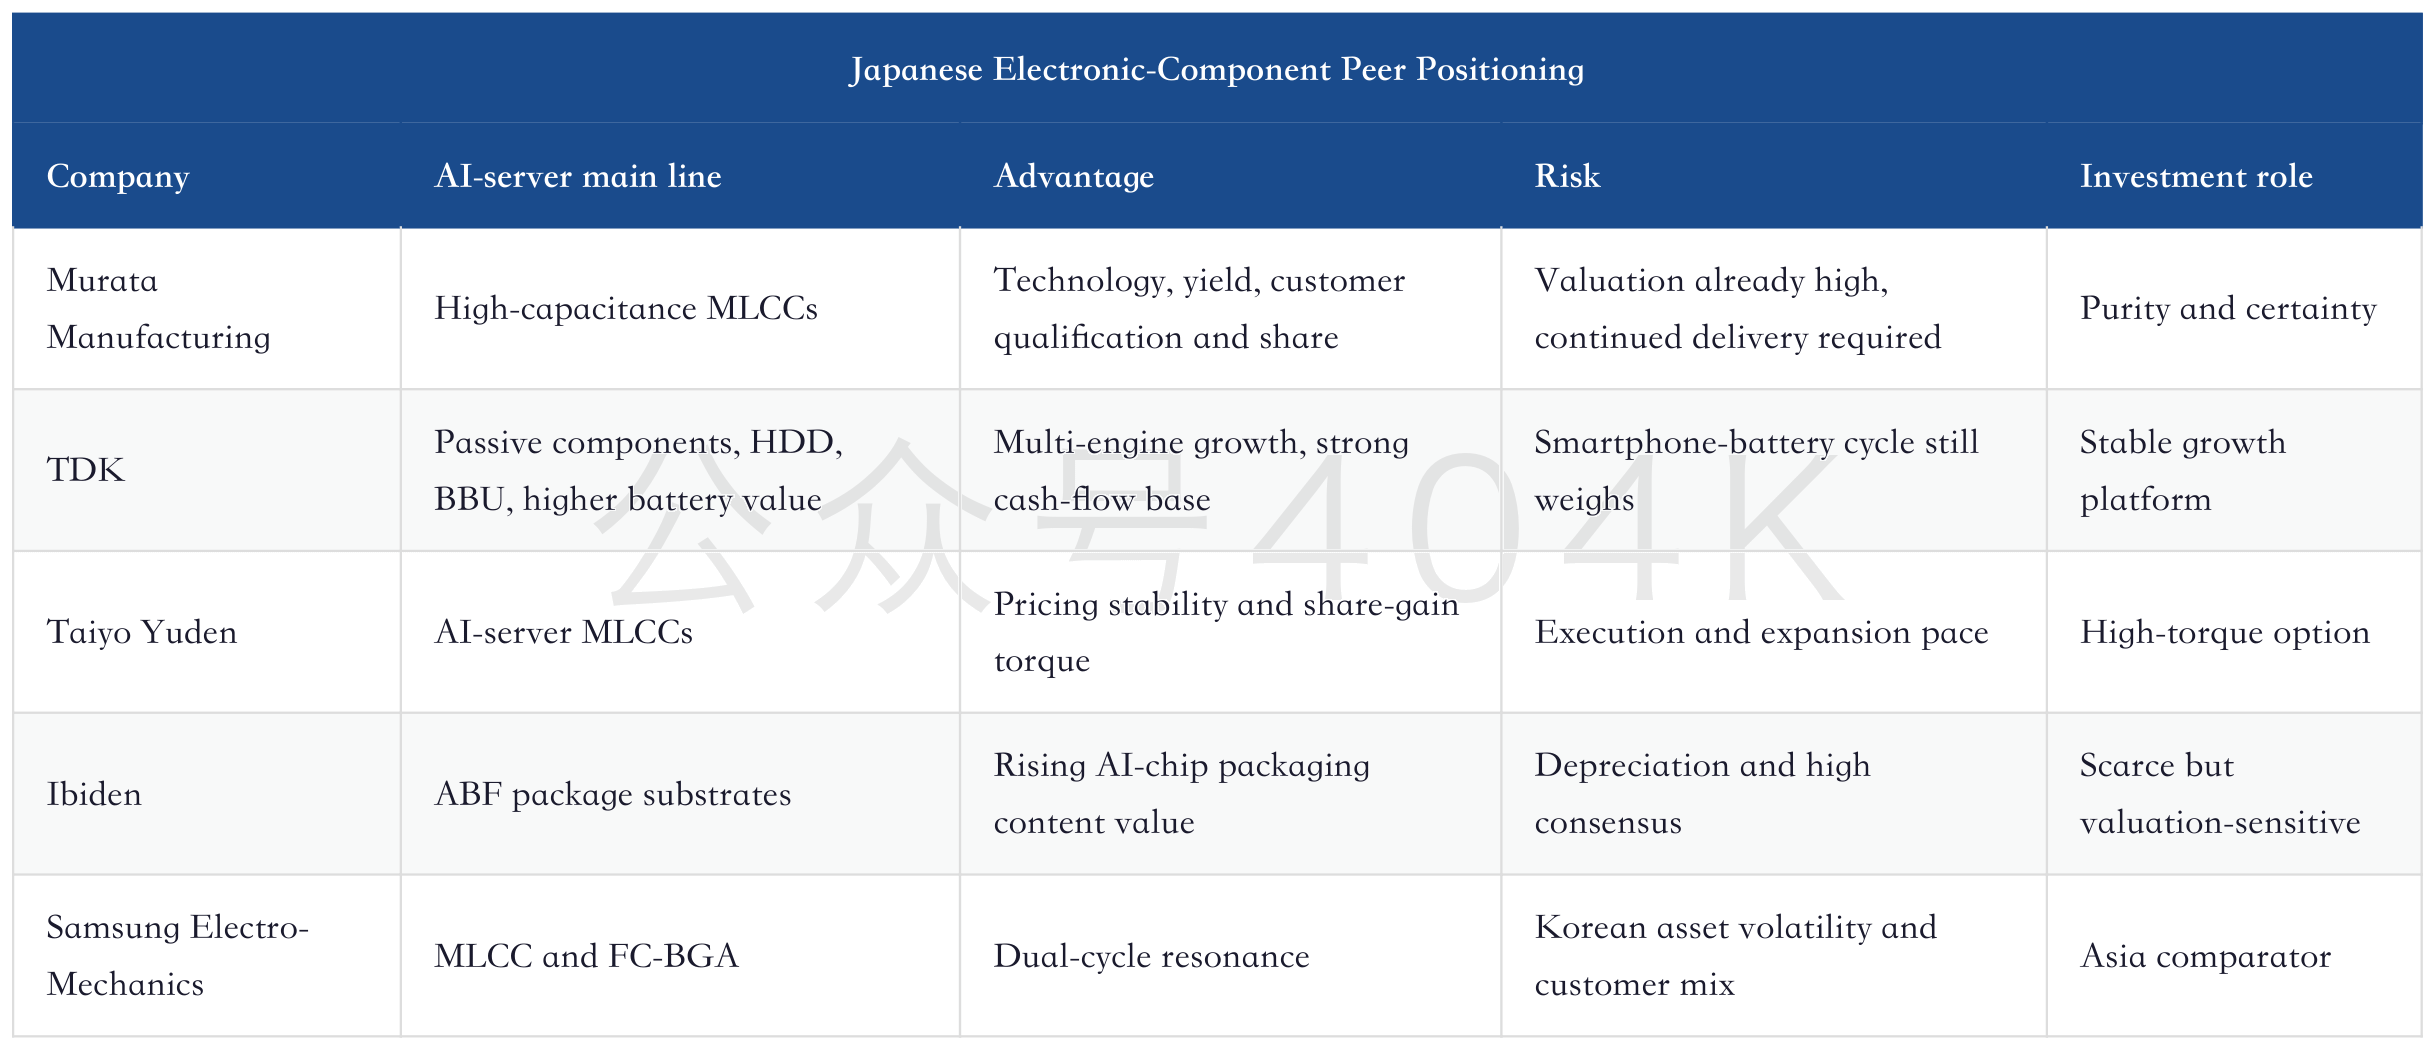
TDK has to be viewed within the stratification of Japanese electronic components. Murata Manufacturing's advantage is high-capacitance MLCC purity, Taiyo Yuden's advantage is MLCC torque, Ibiden's advantage is scarcity in ABF package substrates, and TDK's advantage is broader AI-server-related exposure. It may not be the sharpest name, but the portfolio is steadier.
Japan Electronic Components Deep Dive: Morgan Stanley Asia Investor Survey and How AI Servers Widen the Valuation Gap between MLCC and ABF
This ranking shows that TDK should not be viewed simply as a "lower-end Murata." Murata's question is whether high-end MLCCs can continue lifting RoIC. TDK's question is whether multiple business lines can raise margins together. The validation method is different. TDK is better assessed through segment margins, cash flow and AI-related profit weight, rather than focusing only on MLCC prices.
13. Three Scenarios: Base Case at JPY4,500, Bull Case on Multi-Engine Resonance, Downside from Handsets and HDD
TDK's scenario framework should be built around its multi-engine businesses. The base case is that AI-server-related profit weight rises gradually, smartphone-battery downside risk is manageable, and operating margin moves above 15%. The bull case is that passive components, HDD heads/suspensions, BBU and higher smartphone battery value all exceed expectations together. The downside case comes from smartphone demand, HDD demand, the yen and inventory.
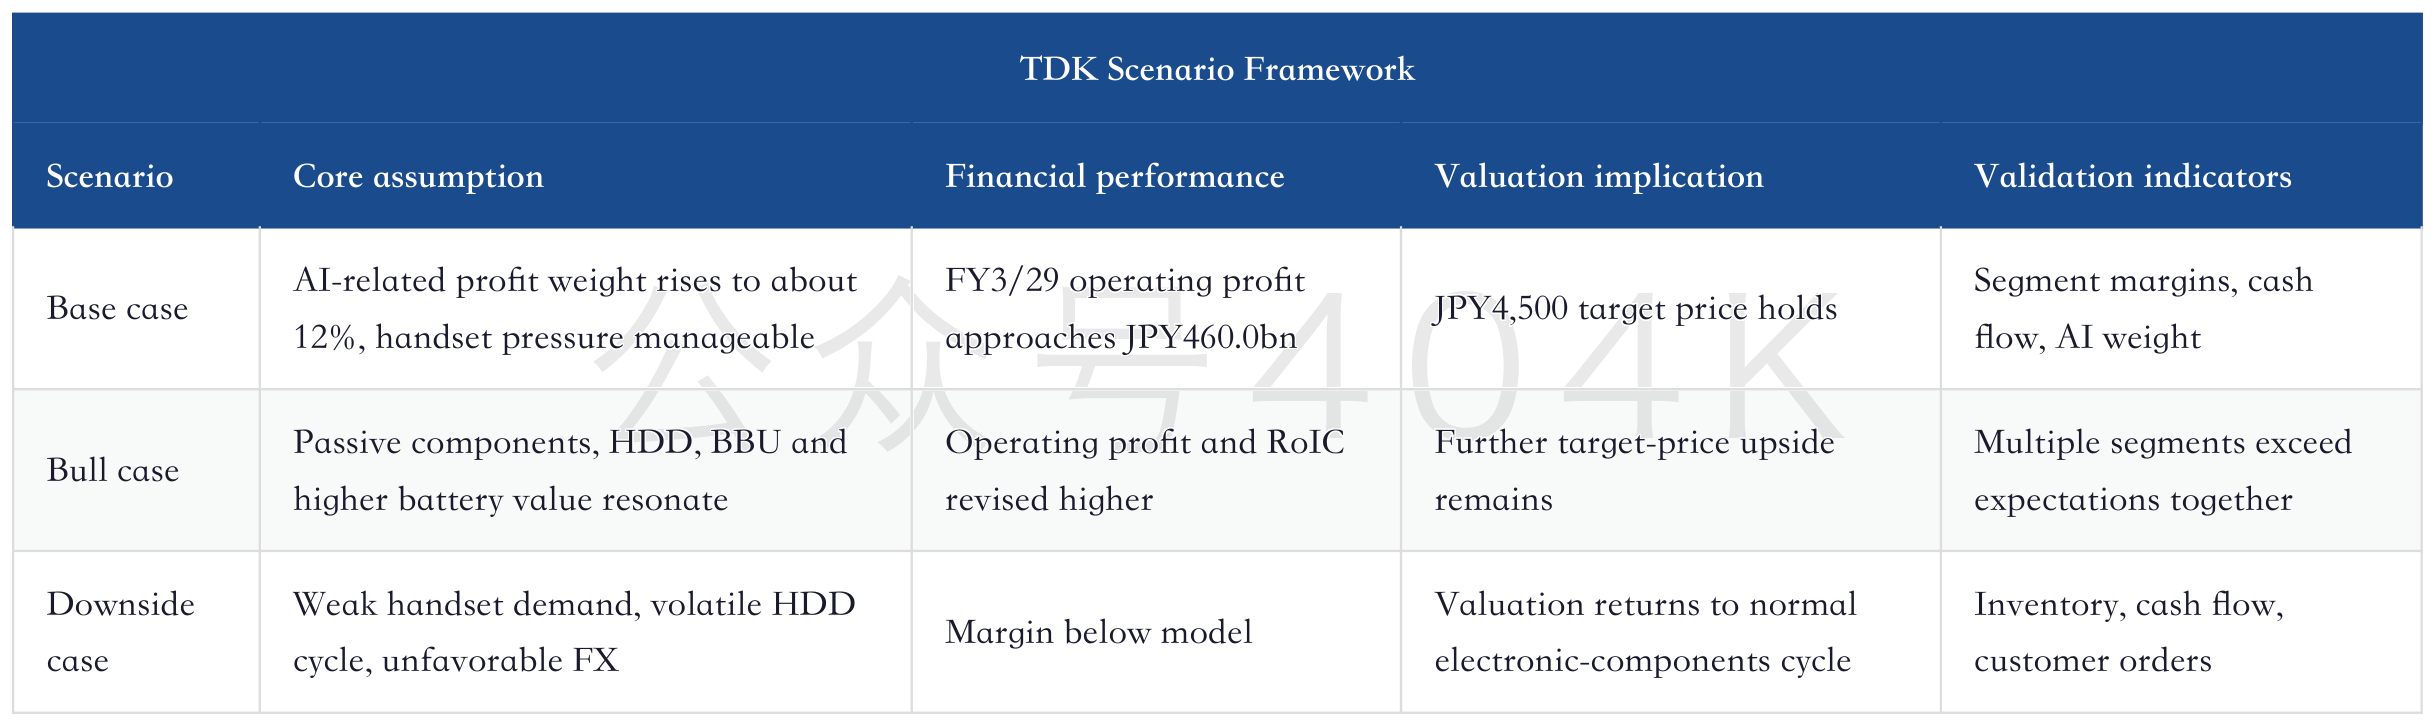
The base case depends on rising AI-related profit weight. If the view of close to 10% in FY3/27 and about 12% in FY3/28 materializes, the market will reclassify TDK from a consumer-battery-led asset into a multi-node supplier to the AI-server physical layer. If that weight stalls, the JPY4,500 target price will depend more on FX and smartphone batteries, reducing its quality.
14. How to Track the Next Four Quarters: First 1Q Progress, Then AI-Related Weight
Citi specifically notes that if 1Q results show YoY profit growth and good progress versus initial company guidance, the share price could revise upward. This gives a clear near-term validation point. TDK's first task is to see whether FY3/27 1Q can break the pessimism created by declining smartphone demand.
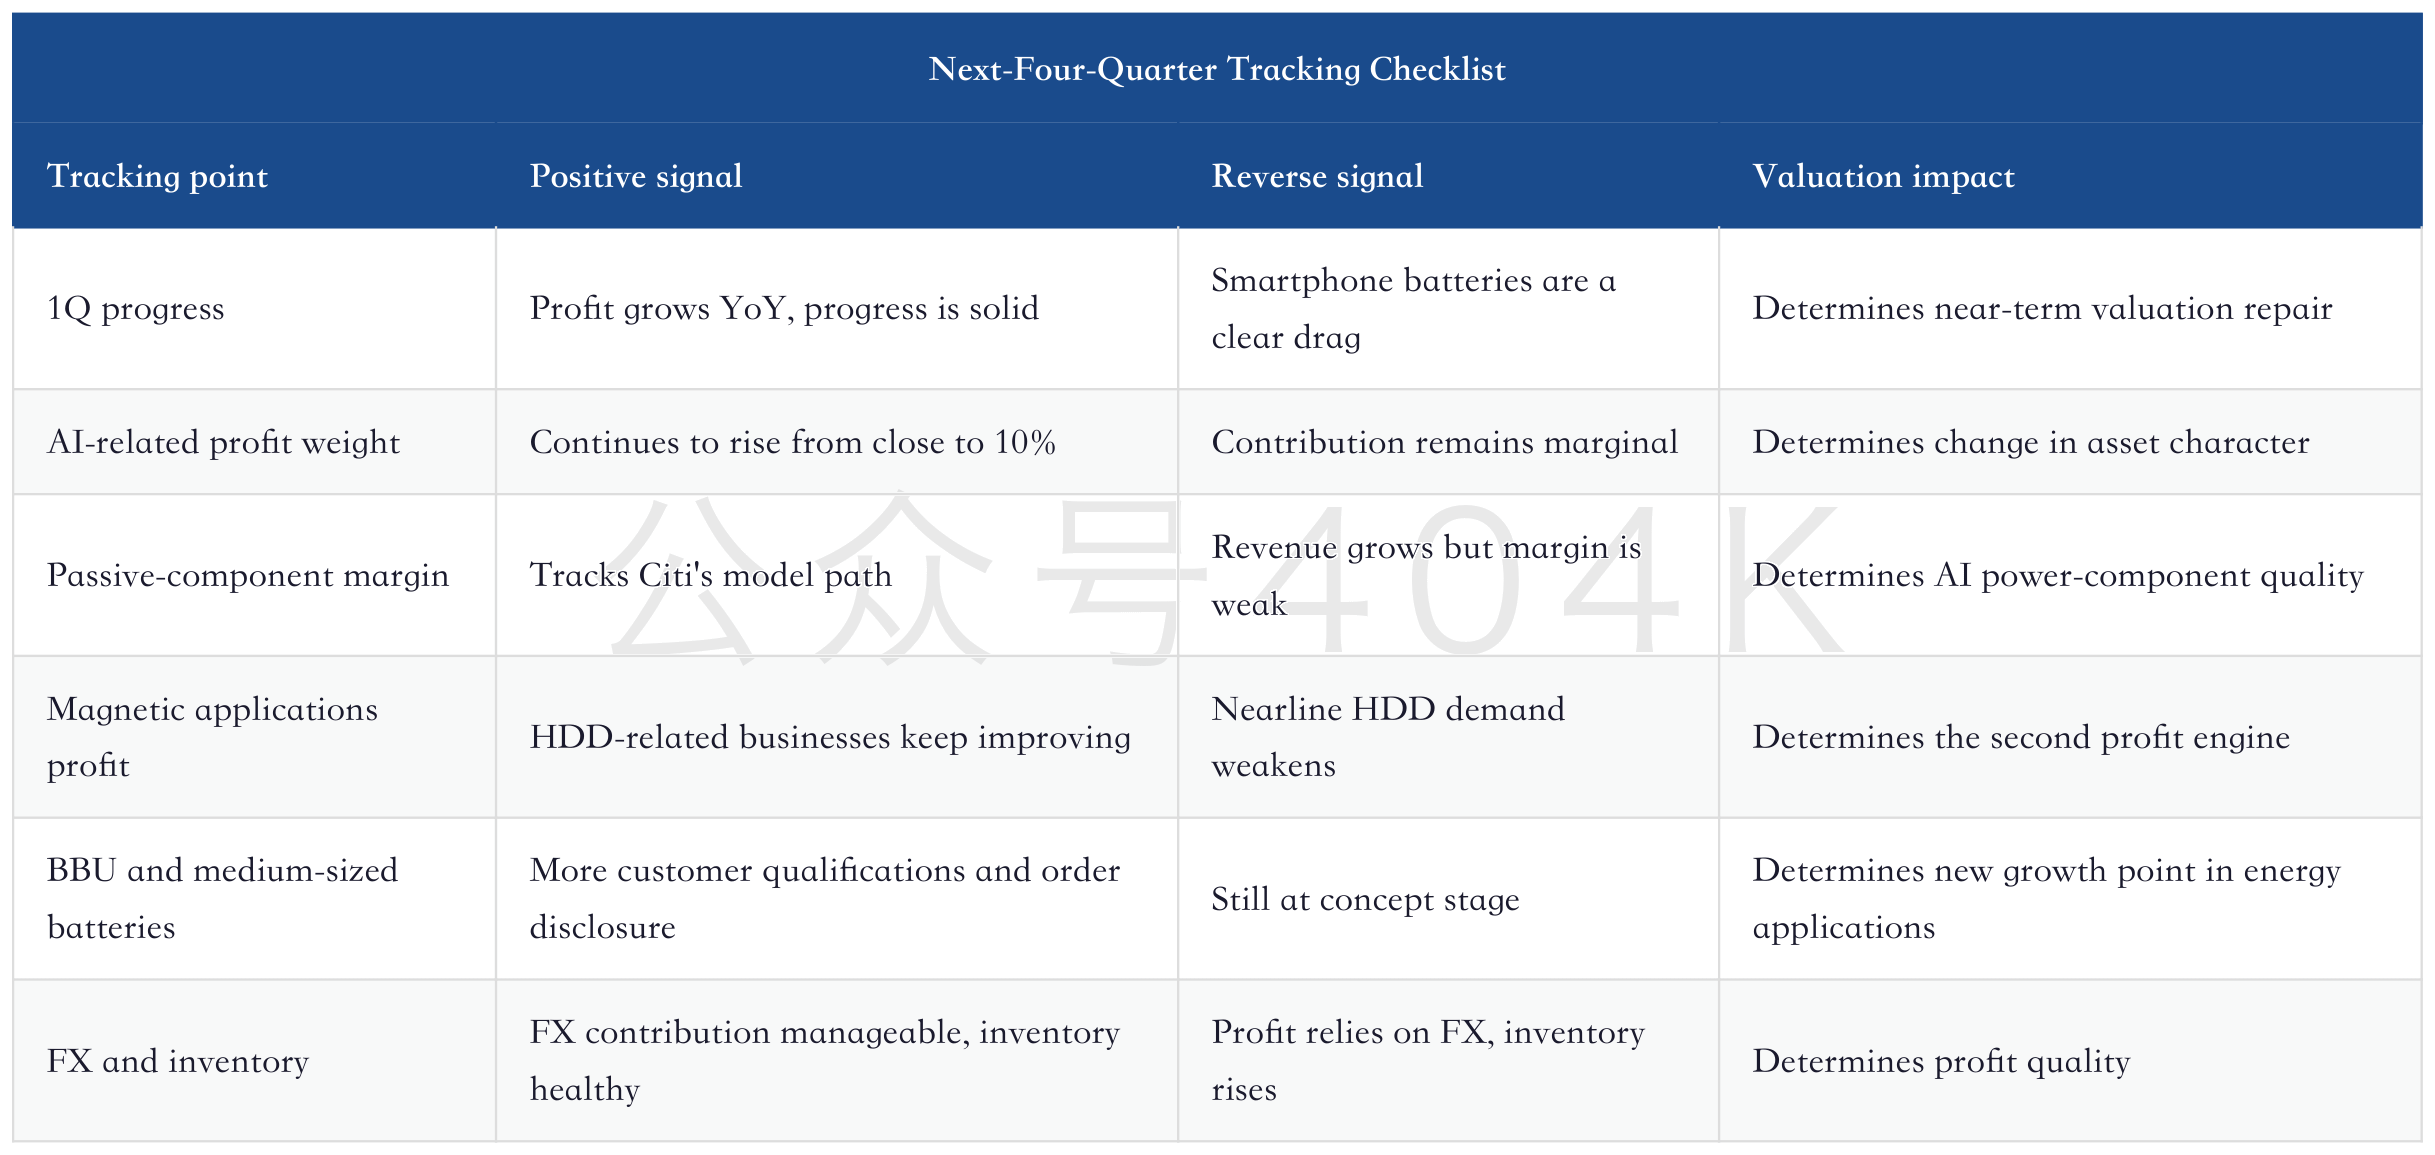
The order of this table also matters. Near term, watch 1Q progress. Medium term, watch segment margins. Long term, watch AI-related profit weight. If all three levels improve together, TDK's JPY4,500 target price is more robust. If only 1Q handset batteries improve and AI-related profit weight does not rise, the market will treat it as a consumer-electronics recovery.
Japan Electronic Components Deep Dive: AI Servers Push MLCCs from Cyclical Products toward Compute Infrastructure
15. Risk Breakdown: TDK's Biggest Risk Is "Insufficient Multi-Engine Strength"
TDK's advantage is multi-engine growth; its risk is also multi-engine growth. Each line can improve, but no single line yet forms an overwhelming main driver. Passive components need to prove that AI-server power products truly lift margins. Magnetic applications need to prove sustained nearline HDD demand. Energy applications need to prove that smartphone batteries are not a major drag and that BBU can become incremental growth. Sensors need to prove recovery torque.
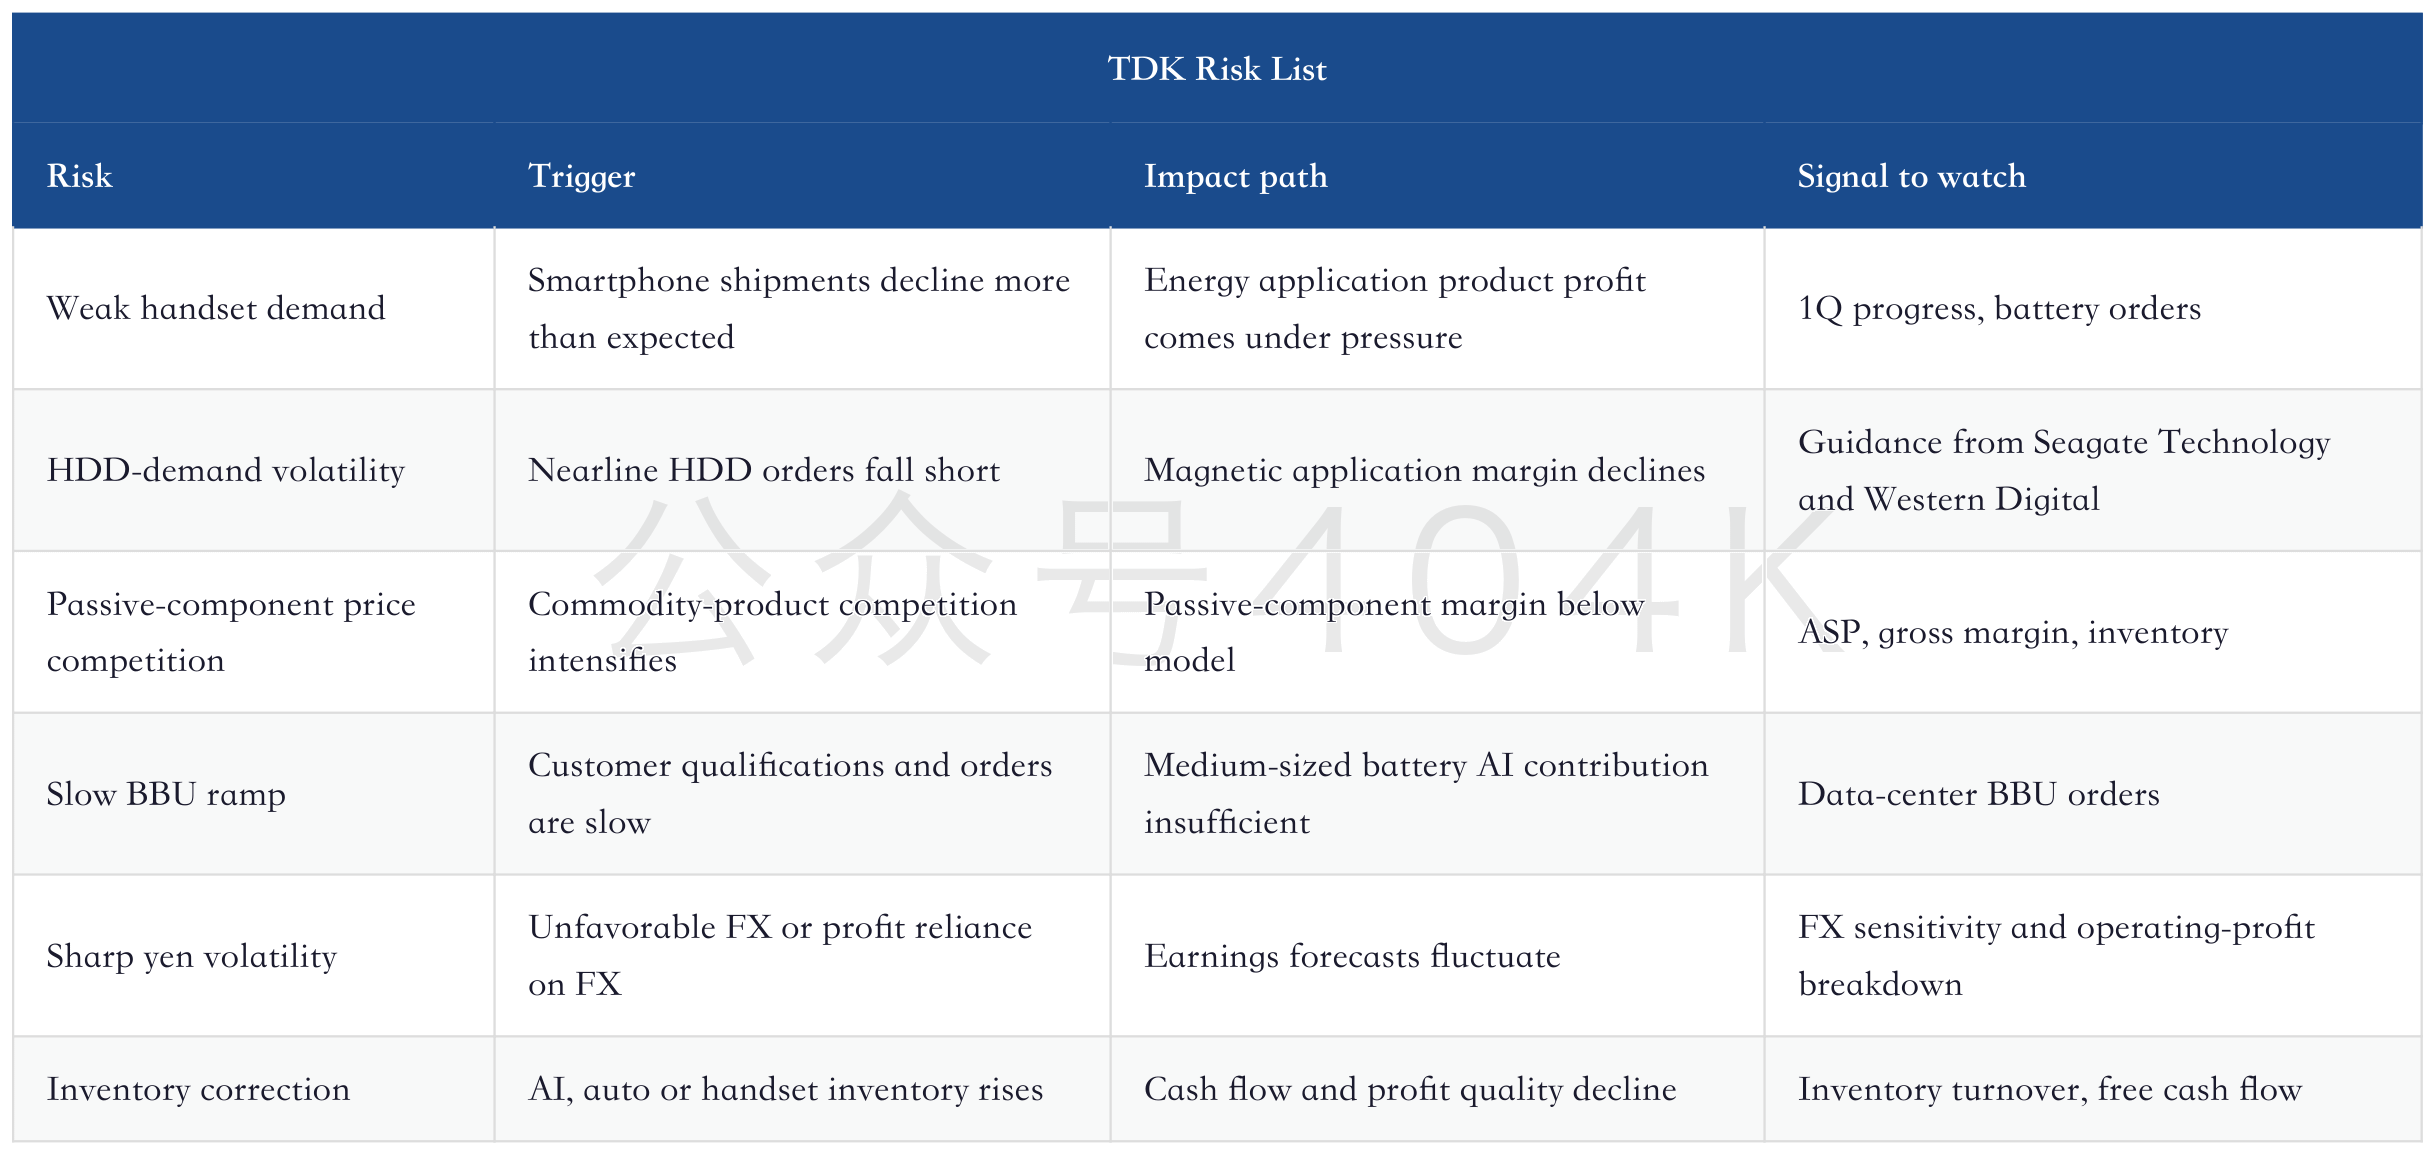
The common thread in these risks is that they would make the market question whether TDK's multi-engine growth is strong enough. Citi's target price already includes distant profit and a lower risk premium. If every business improves only slightly, but no line is strong enough to change the profit structure, the valuation will lack upside torque. TDK needs at least two to three lines to deliver together for the market to keep raising the target price.
16. Why Citi Is at JPY4,500: It Should Not Be Mixed with the Earlier JPY5,500 Framework
TDK has already had a more aggressive target-price narrative. Earlier, JPMorgan raised its TDK target price to JPY5,500, with the core view focused on the post-FY2028 profit level and TDK's asset character as a multi-node AI physical-layer asset. Citi's JPY4,500 target is more restrained and more closely tied to near-term financial validation. Both recognize TDK's multi-business improvement, but their emphases differ.
JPMorgan is closer to buying distant asset character: TDK enters the AI physical layer through batteries, MLCCs, HDD heads, sensing, BBU, liquid cooling and AR. If multiple lines deliver together in the future, valuation can be understood against a higher peak for the electronic-components cycle. Citi is closer to buying verifiable earnings upgrades: FY3/27 and FY3/28 operating-profit forecasts are raised, FY3/29 operating profit is set at JPY460.0bn, and the risk premium is lowered while the valuation year rolls to FY3/29.
The difference between these two frameworks needs to be clear. JPY4,500 is Citi's current base-case target price. It depends on operating-profit upgrades, a lower risk premium and higher AI-server-related profit weight. JPY5,500 belongs to the earlier, more optimistic distant revaluation framework. It requires more business lines to deliver, including HDD head share, BBU orders, passive-component margins, sensor recovery and distant optionality. Mixing the two numbers would lead readers to think all sell-side firms assign the same strength to the revaluation.
From a research perspective, Citi's JPY4,500 is better used as the "current verifiable base case." It does not place liquid cooling, AR or Edge AI sensors at the center of the thesis. Instead, it clarifies the segments visible in the income statement. Passive components, magnetic applications, energy applications and sensors all have segment revenue and profit forecasts; AI-server-related profit weight is also given as a staged ratio. This framework is easier to test quarter by quarter.
The earlier JPY5,500 target is better used as a "reference for the upper bound of asset revaluation." If three things happen together, the JPY5,500 framework will become more persuasive again: first, AI-server-related profit weight continues moving above 12%; second, BBU and medium-sized batteries move from optionality to clear orders; third, sensing, AR, liquid cooling or other edge physical-layer businesses produce quantifiable revenue. Without this evidence, JPY4,500 remains the steadier base anchor.
This is also why the title of this report only mentions Citi's JPY4,500. The target-price framework must match the report source. TDK can have multiple sell-side valuation anchors at the same time, but the body needs to separate them into base case, bull case and distant optionality. Citi provides a base revaluation after current earnings upgrades. JPMorgan leans more toward the upper-bound imagination of a distant AI physical-layer platform. Together, the two lines form TDK's valuation map.
