
Taiwan High-End CCL Update: Second-Round Price Hikes and AI Material Upgrades Reignite Margin Expansion at EMC and TUC
目录
TL;DR
What Has Changed: Price Increases Are Starting to Flow Through From Revenue to Margins
Material Value per System Matters More Than Server Volume Growth
Both High-End and Low-End Prices Are Rising, but the Earnings Implications Are Entirely Different
Elite Material and TUC: One Leads Through Market Share, the Other Through Mix Catch-Up
Price-Target Increases Reflect Both Earnings Revisions and a Roll-Forward of the Valuation Clock
Watch Four Milestones, Not One Long-Term Narrative
View: The CCL Rally Is Entering the Margin-Validation Phase
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The key question for high-end copper-clad laminates has shifted from whether suppliers can raise prices to whether those increases can sustainably translate into gross margin. Second-round price hikes, new-platform ramp-ups, and exits from low-end products are putting Elite Material and Taiwan Union Technology on a steeper earnings trajectory.
TL;DR
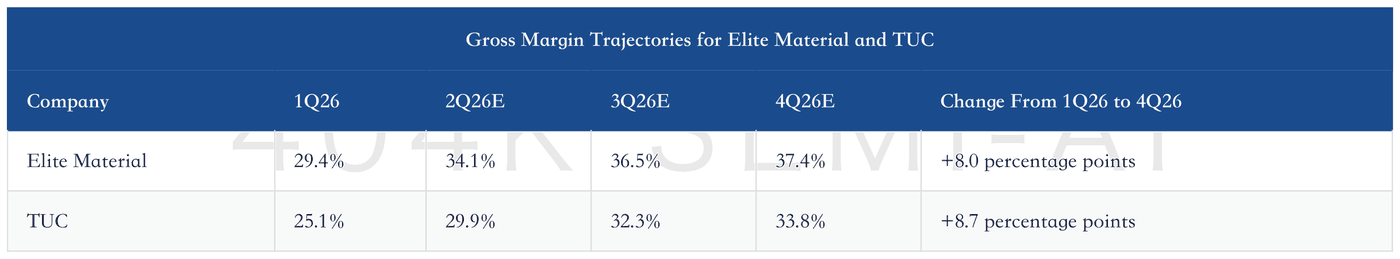
Goldman Sachs’ latest view as of July 17 is that Elite Material and Taiwan Union Technology will resume margin expansion from the second quarter of 2026. Elite Material’s gross margin is expected to rise from 29.4% in the first quarter to 34.1% in the second quarter and 37.4% in the fourth quarter. TUC’s gross margin is projected to increase from 25.1% to 29.9% and 33.8%, respectively. The improvement is being driven by price increases, product mix, and ramping artificial intelligence (AI) projects, making it higher quality than a simple pass-through of raw-material costs.
A second round of high-end price increases could begin in late third quarter or early fourth quarter 2026. Prices for M7-and-above CCL are expected to rise another 10%–15%, while customers have shown little resistance to the first round of increases since April. High-end CCL remains a delivery bottleneck for AI printed circuit boards (PCBs), and most PCB manufacturers can continue passing the additional costs on to end customers.
Incremental demand is increasingly being driven by higher material value per system, rather than merely growth in server volumes. Goldman Sachs estimates that CCL content value per VR200 system will be more than 3.5 times that of GB300, reflecting both an average selling price increase of more than 50% from the upgrade from M7+ to M8+ and greater material usage from the addition of a midplane. Google TPU, Amazon Web Services’ Trainium 3, switches, and general-purpose servers are also moving to higher material grades.
Elite Material and TUC offer different forms of operating leverage. Elite Material already supplies major AI programs at Nvidia, Google, and Amazon Web Services and has a stronger product mix. Goldman Sachs raised its 2026–2028 EPS forecasts by 27%/13%/27%. TUC’s margin catch-up is faster, but its 2026 growth remains constrained by capacity. Goldman Sachs cut its 2026 revenue forecast by 2% while raising its 2026–2028 net profit forecasts by 4%/9%/12%.
The NT$9,500 and NT$2,860 price targets are driven by both earnings upgrades and a valuation-period roll-forward. Goldman Sachs continues to apply 27x and 22x P/E multiples to Elite Material and TUC, respectively, but has rolled the valuation period forward from 2027 to the second half of 2027 through the first half of 2028. Whether these targets hold will depend on second- and third-quarter gross margins, the second round of price increases, project shipments, and continued delivery against 2027 earnings forecasts.
What Has Changed: Price Increases Are Starting to Flow Through From Revenue to Margins
Previous research on high-end CCL focused on whether M7, M8, and M9 materials were in short supply and whether PCB manufacturers would accept higher prices. There is now a more concrete performance metric: Elite Material and TUC’s quarterly gross margins are expected to rise consecutively from the second quarter of 2026 and remain above market expectations in the third quarter.
Goldman Sachs forecasts a second-quarter gross margin of 34.1% for Elite Material, up 4.7 percentage points quarter on quarter, and 29.9% for TUC, up 4.8 percentage points. In the third quarter, gross margins are expected to rise by another 2.4 percentage points for both companies, reaching 36.5% and 32.3%, respectively. Fourth-quarter forecasts rise further to 37.4% and 33.8%. This trajectory matters more than revenue growth because it shows whether price increases are merely offsetting costs or beginning to generate incremental profit.
Why can margins continue to rise? The first driver is the repricing of low-end products. Goldman Sachs estimates that both companies raised prices for M6-and-below products by more than 40% in the second quarter. These increases both cover higher E-glass cloth and copper foil costs and deliberately reduce exposure to low-return orders. TUC has already indicated that it stopped supplying certain low-end products from the second quarter. Price-sensitive customers are naturally exiting, allowing capacity to be reallocated to higher-grade materials.
The second driver is higher prices for high-end products. Elite Material and TUC raised prices for M7-and-above products by 10%–15% from April, with no meaningful resistance from PCB customers. Goldman Sachs further expects another 10%–15% increase in late third quarter or early fourth quarter. As long as customers care more about securing qualified materials than about the incremental cost per panel, price increases will not be a one-off event.
The third driver is the ramp-up of new projects. CCL shipments for Amazon Web Services’ Trainium 3 are expected to grow by more than 50% quarter on quarter in the third quarter. Mass production of CCL for Nvidia Vera Rubin is scheduled to begin in August, while shipments for Google TPU are expected to start in September. These new projects will further shift the product mix toward M7+ and AI materials, enabling pricing and mix improvements to occur simultaneously.
A Complete Guide to the AI PCB Material Revaluation — From CCL Price Increases and Fiberglass Looms to the ABF Shortfall and Rack Upgrades
The previous thesis was that material bottlenecks would ultimately appear in the income statement. The new evidence in this report is that Elite Material and TUC have already entered this phase. If actual gross margins come close to forecasts, the CCL thesis will evolve from a pricing theme into an earnings-delivery story. If revenue grows rapidly but gross margins remain at first-quarter levels, raw-material costs, low-end orders, or customer bargaining power are still absorbing the price spread.
Material Value per System Matters More Than Server Volume Growth
Goldman Sachs estimates that the global CCL market will reach US$57 billion in 2028, representing a 53% CAGR from 2025 to 2028. The market is expected to reach US$20 billion in 2026 and US$34.1 billion in 2027. More importantly, the mix is changing: demand for high-end CCL is expected to grow at a 96% CAGR over the same period, far above the approximately 1% growth rate for mid- and low-end products. High-end materials are projected to rise from 52% of total market value in 2026 to 71% in 2027 and 82% in 2028.
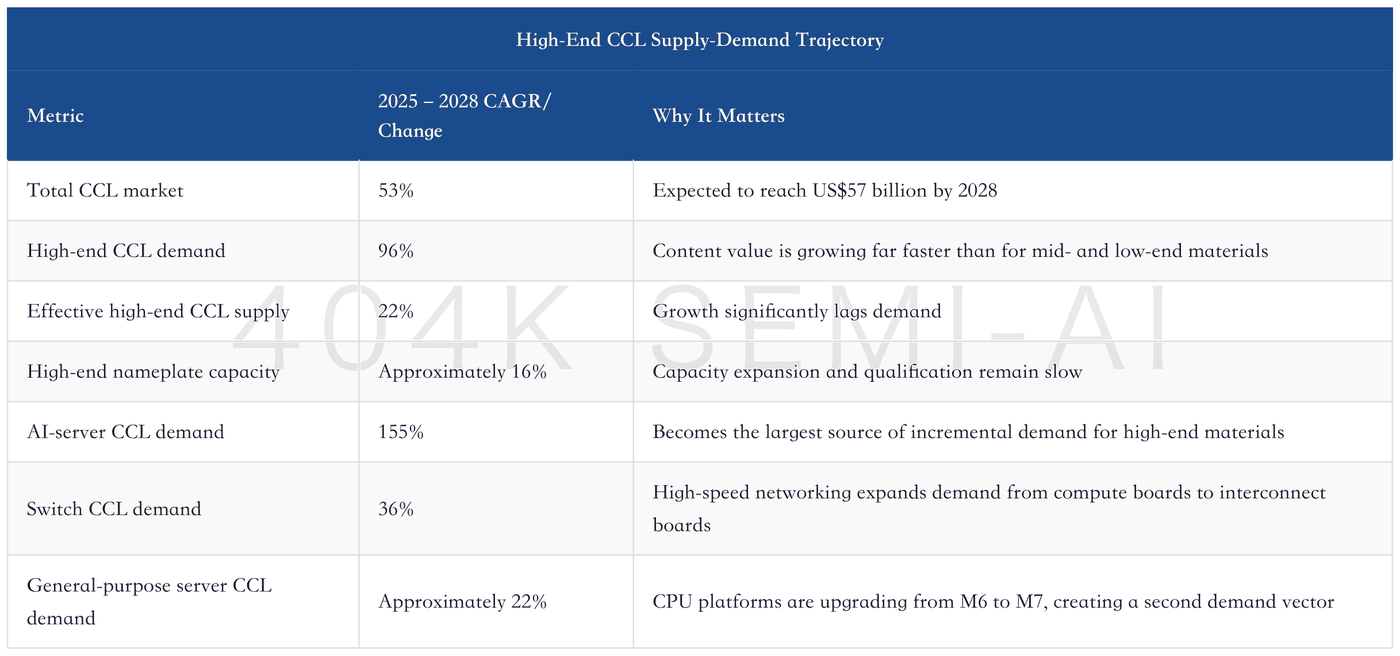
These figures should not be interpreted simplistically as implying that the market will grow by 96% every year. The further sell-side models extend into the future, the greater the forecasting error. What they actually illustrate is the divergence in growth trajectories: demand is being lifted simultaneously by multiple platforms, while high-end capacity requires formulations, equipment, customer qualification, and stable mass production and cannot be replaced by conventional capacity in the near term. Even if the long-term market estimate is discounted, continued high-end demand growth well above effective supply growth would still support price increases and margin expansion.
Content value per system is the more robust driver. Goldman Sachs expects Nvidia-related CCL demand to grow at a 192% CAGR from 2025 to 2028, while GPU shipments increase at only a 14% CAGR over the same period. The gap is mainly driven by material upgrades: VR200 migrates from M7+ to M8+, lifting average selling prices by more than 50%, while the addition of a midplane takes CCL content value per system to more than 3.5 times that of GB300.
ASICs and general-purpose servers are also contributing. Goldman Sachs expects ASIC CCL demand to grow at a 96% CAGR over the same period, supported by shipment growth of more than 40% and material upgrades that trail Nvidia’s timing slightly. Next-generation general-purpose server CPUs will move from M6 to M7, potentially increasing material average selling prices by more than 80%, while higher layer counts will add approximately 10% to material usage. GPU, ASIC, switch, and CPU platforms are competing for higher-grade materials simultaneously, giving high-end CCL demand a broader foundation than the Nvidia supply chain alone.
CCL/PCB Update: High-End CCL Shortage Extends Into 2027 as M9 Materials and HDI Capacity Continue to Reprice
Both High-End and Low-End Prices Are Rising, but the Earnings Implications Are Entirely Different
Low-end CCL prices rose more rapidly in the first half of 2026, mainly because of E-glass cloth shortages, displacement of conventional capacity by high-end products, and the reallocation of some production lines toward higher-value, low-dielectric materials. Goldman Sachs states that E-glass cloth prices increased by more than 80% in the first half, driving substantial price increases for M6-and-below products.
The weakness of this pricing cycle is also evident. As suppliers shift some capacity back to E-glass cloth, the shortage could gradually ease in the fourth quarter. At the same time, consumer electronics are entering a seasonal downturn, leaving low-end demand without strong support. Goldman Sachs forecasts year-on-year smartphone shipment growth of -10%/3%/1% in 2026–2028 and PC shipment growth of -14%/-5%/0%. Once low-end price increases lose the support of raw-material shortages, they could readily decelerate.
The foundation for high-end price increases is more durable. Customers are purchasing qualified materials that can be delivered reliably and meet high-speed signal-integrity requirements. CCL represents a limited share of total system cost but can determine whether an entire high-value PCB can be manufactured. PCB producers are generally willing to accept 10%–15% price increases for high-end materials, provided they can secure sufficient qualified supply and continue passing the costs on to cloud service providers and system customers.
This also explains why AI revenue will rapidly increase as a share of total revenue for Elite Material and TUC. Goldman Sachs expects Elite Material’s AI revenue mix to rise from 38% in 2025 to 50% in 2026 and 89% in 2028. TUC’s is projected to rise from 12% to 26% and 64%, respectively. The M7+ mix is increasing even faster: Elite Material’s is expected to rise from 55% to 70% and 99%, while TUC’s rises from 36% to 50% and 75%. High-end materials and AI projects are not synonymous, but together they are displacing low-end products from the capacity mix.
Three factors require close monitoring: whether high-end price increases can continue, whether the AI and M7+ mix can rise, and whether raw-material costs can be covered. Only when all three move in the same direction will gross margins establish a sustained trend. If higher low-end prices merely reflect E-glass cloth inflation, the profit improvement is more likely to represent a temporary cost pass-through.
Elite Material and TUC: One Leads Through Market Share, the Other Through Mix Catch-Up
Elite Material’s advantage lies in its high-end customer base and project coverage. Goldman Sachs states that the company holds more than 70% and 90% shares in high-end HDI and substrate-like PCB materials, respectively, and supplies major AI-server projects at Nvidia, Google, and Amazon Web Services. Its share of AI-server CCL is expected to remain at 46%–53% in 2026–2028, close to half the market for a single supplier. This scale makes it easier for Elite Material to receive priority allocations of high-end fiberglass cloth, copper foil, and customer capacity, while also enabling it to defend price increases.
