
目录
Executive Summary
I. Why Does the Same Revenue Table Show Two Opposing Cycles?
II. The New-Product Cycle Is a Two-Quarter Relay, Not a Single Date
III. The Semiconductor Upstream Has Delivered the First Round of Physical Evidence
IV. YoY Growth Is Not Enough: MoM Determines the Near-Term Trajectory
V. The Key Question for the Materials Chain: Where Does Pricing Power Stop?
VI. Rising Power Consumption Shifts Value from Chips to Power, Cooling, and BBU
VII. Server Revenue Is Surging—Why Are Notebook PCs Still Contracting?
VIII. Memory Revenue Growth of 375% Is More a Function of Pricing and Base Effects
IX. From Monthly Momentum to Earnings Delivery: Five Gates Must Be Cleared
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Taiwan’s technology cycle is splitting into two tracks: AI infrastructure continues to accelerate, while traditional PCs remain constrained by costs, pricing, and end-market demand.
Executive Summary
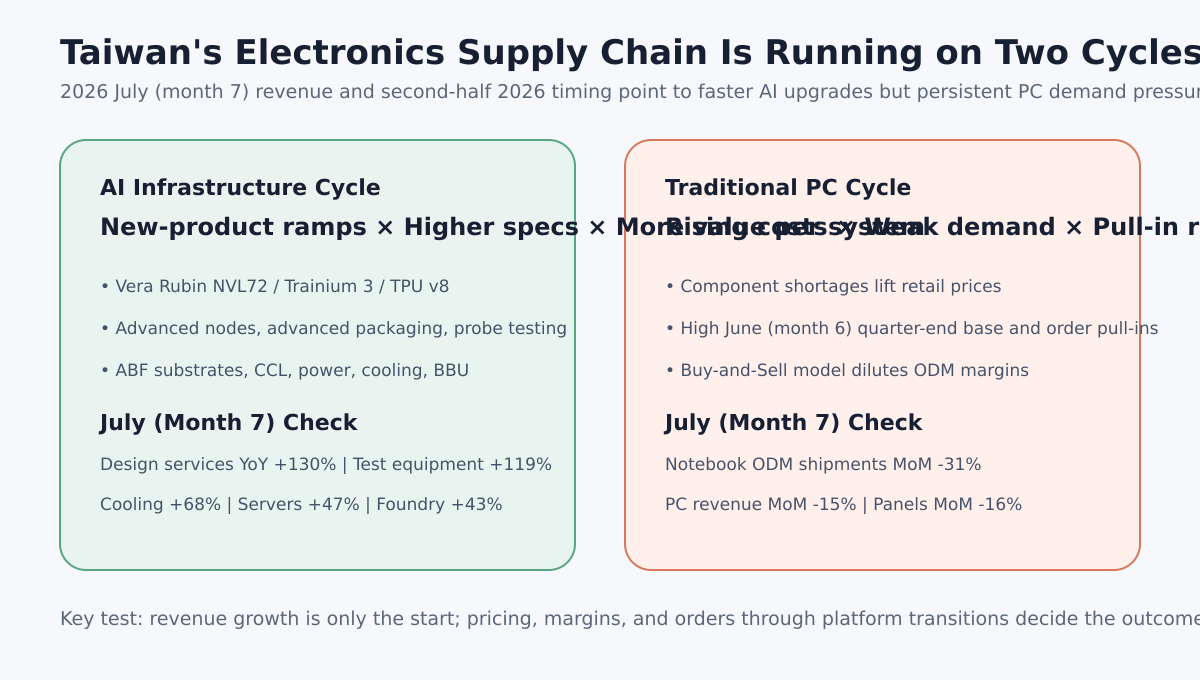
Citi’s July 2026 tracking of Taiwan’s electronics supply chain points to a highly uneven recovery. Revenue from design services, probe cards and testing equipment, thermal solutions, PCBs, servers, foundries, and assembly and testing grew 130%, 119%, 68%, 64%, 47%, 43%, and 41% year over year, respectively. By contrast, PC and panel revenue fell 15% and 16% month over month. The upstream AI supply chain accelerated during the month, while traditional end markets continued to cool.
Four product ramps overlap in the second half of 2026: Nvidia’s GB300 continues to ship; Vera Rubin NVL72 begins contributing from late in the third quarter; Amazon Trainium 3 enters volume production; and TPU v8 and AMD Helio racks add to demand for cloud providers’ proprietary ASICs. These products increase not only chip volumes but also package area, board-layer counts, power consumption, and cooling requirements. The profit pool should therefore extend beyond GPUs into advanced processes, packaging, ABF substrates, copper-clad laminates, power supplies, thermal solutions, and battery backup units.
The strongest upstream signals come from Alchip Technologies and MPI. Alchip’s July revenue reached NT$7.433 billion, up 108% month over month and 182% year over year, directly reflecting the start of Trainium 3 design-service deliveries. MPI generated NT$1.6 billion in revenue, up 10% month over month and 156% year over year, indicating that testing and probe-card demand is ramping concurrently. TSMC and ASE Technology Holding grew 45% and 43% year over year, respectively, confirming that advanced processes and advanced packaging remain relatively reliable volume indicators.
The critical question for the materials supply chain is which suppliers can retain price increases. ABF substrates are supported by larger unit area, higher layer counts, and greater yield complexity, with July revenue at Unimicron, Nan Ya PCB, and peers rising 8%—16% month over month. Copper-clad laminate supply remains tight, and further price increases are expected from Elite Material and Taiwan Union Technology. PCB manufacturers such as Gold Circuit Electronics and Tripod Technology, however, absorb higher material costs first. If customer price adjustments lag, revenue growth may not translate into higher gross margins.
The notebook supply chain faces pressure from both rising costs and weak demand. Notebook ODM shipments fell 31% month over month in July, and Citi expects third-quarter shipments to decline 8% quarter over quarter and 18% year over year. Component price increases are pushing up retail prices, while June’s high quarter-end base and advance ordering pulled demand forward. Buy-and-resell models can also inflate revenue while diluting gross margin, and higher system prices can only partially offset lower volumes.
The analysis cannot stop at monthly revenue. The proper validation sequence is: new products enter mass production on schedule; orders convert into shipments; upstream price increases are successfully passed through; gross margins improve faster than revenue; and inventory and receivables do not consume the resulting cash. A prolonged mismatch at any stage could reframe “structural growth” as advance ordering, margin pressure from price increases, or inventory accumulation.
I. Why Does the Same Revenue Table Show Two Opposing Cycles?
The core value of Citi’s report lies in placing more than 20 Taiwanese technology subsectors within a single cross-sectional framework, rather than labeling individual companies as strong or weak based on one month’s revenue. Year-over-year comparisons reveal the 12-month trend, while month-over-month changes capture the latest momentum. Together, they expose the central tension in the electronics supply chain during the second half of 2026: AI infrastructure demand is spreading from a small group of GPU vendors across the entire rack, while traditional PCs are not participating in the recovery.
Growth in the AI supply chain is being driven by both volume and specification upgrades. New GPUs and cloud providers’ proprietary ASICs require more advanced processes, more complex packaging, larger ABF substrates, higher-speed copper-clad laminates and PCBs, as well as higher-power supplies, cooling systems, and battery backup units. Even if rack volumes rise only modestly, content value per system can still increase. By contrast, PC performance upgrades are unlikely to offset the near-term pressure that higher retail prices place on unit demand. The more expensive the components, the longer consumers may defer replacement purchases.
“Growth in Taiwan technology revenue” is therefore insufficient on its own. Investors must answer three additional questions: Is growth coming from AI or traditional products? Is it volume- or price-driven? And are gross margins and cash flow improving alongside revenue? Only when all three are addressed can monthly data be upgraded from a cyclical signal to an earnings conclusion.
II. The New-Product Cycle Is a Two-Quarter Relay, Not a Single Date
The second-half 2026 AI hardware cycle comprises several overlapping product ramps. GB300 resumed shipments following the second-quarter platform transition and continues to support server original design manufacturers (ODMs) and thermal suppliers. Trainium 3 has already appeared in Alchip’s July revenue and should subsequently extend into networking, PCB, and copper-clad laminate suppliers. Vera Rubin NVL72 is expected to begin contributing in late third quarter, with a more meaningful revenue mix only in the fourth quarter. TPU v8 and AMD Helio racks further diversify demand beyond a single GPU platform.
These timing differences explain why monthly supply-chain performance is uneven. Design services generally precede mass production; testing equipment benefits as new chips enter validation and capacity ramps; foundry and assembly-and-testing revenue more closely tracks actual shipments; and ODM performance depends on customer acceptance, product mix, and component availability. A company’s month-over-month decline in July does not necessarily indicate weakening AI demand. Concern over project share or production progress becomes warranted only if it trails peers for several consecutive months.
