
目录
Executive Summary
Storage Holdings Nearly Triple in Value, Yet Share Counts Fall Across All 4 Stocks
Why Faster Market-Value Growth Can Coincide With Falling Institutional Share Counts
Why Did Situational Awareness Raise Its Semiconductor Allocation to 64.8% Against the Broader Trend?
AI Chip Share Counts Are Still Rising: This Is Not a Broad Semiconductor Exit
Foundries and Equipment: Market Value Doubled, but Share Counts Rose Only Modestly
Analog Chips, EDA, and Optical Communications: Broader Coverage Does Not Mean Capital Concentration
Calls and Puts Expanded Together: Risk Appetite With Insurance
Have Semiconductors Peaked? 13F Data Show Rotation, Not a Broad Exit
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
As of June 30, 2026, storage-stock prices and institutional share counts had diverged sharply. The 13F data do not support the view that the semiconductor sector as a whole has peaked. However, falling storage-stock share counts, greater use of protective instruments, and high portfolio concentration collectively indicate that the broad-based rally has given way to greater dispersion.
Executive Summary
Among 737 large institutions with strictly comparable filings, the reported value of core semiconductor common-stock holdings rose 55.1%, from $4.45 trillion to $6.91 trillion. The estimated net increase attributable to share-count changes was only $47.095 billion, equivalent to 1.06% of opening positions. Most of the increase in market value came from price appreciation, not synchronized institutional accumulation.
The combined market value of institutional holdings in Micron, SanDisk, Western Digital, and Seagate Technology rose 199.5%, from $368.302 billion to $1.1 trillion, even though quarter-end share counts fell for all 4 stocks. Valued at Q2 prices, these share-count changes represented an estimated reduction of $61.56 billion; this was neither a decline in holdings’ market value nor actual sale proceeds.
AI compute and connectivity chips recorded the strongest increase in share counts, with an estimated net addition of $36.78 billion. Nvidia, Advanced Micro Devices, and Broadcom added $19.48 billion, $14.77 billion, and $12.66 billion, respectively. Capital remained within semiconductors but rotated away from storage and certain high-beta exposures toward compute platforms offering greater earnings visibility.
Situational Awareness LP moved against the broader sample. Semiconductor and storage common stocks rose from 5.7% to 64.8% of its portfolio, with SanDisk and Micron together accounting for 55.6%. SEC filings confirm the reporting manager’s positions as of June 30; they do not establish that those positions were still held in August or that the fund’s legal entity had completed liquidation.
The reported value of semiconductor-related call options increased 134.6%, while put options rose 169.5%, lifting the put-to-call ratio from 1.20 to 1.38. Common stocks still recorded a net increase, but protective instruments grew faster. The 13F data point to internal rotation and increased downside protection, not a wholesale retreat from semiconductors.
Storage Holdings Nearly Triple in Value, Yet Share Counts Fall Across All 4 Stocks
In Q2, the reported value of memory and controller-chip holdings rose from $197.4 billion to $667.0 billion, while storage-device holdings increased from $172.3 billion to $440.4 billion. Combined, the 2 categories nearly tripled from $369.7 billion to $1.11 trillion. Micron, SanDisk, Western Digital, and Seagate Technology accounted for most of this increase, rising by $734.762 billion from $368.302 billion to $1.1 trillion.
The sample is drawn from official SEC filings. There were 787 Q2 13F filings with reported values above $5 billion, of which 783 had corresponding Q1 filings. After excluding 9 confidential-treatment filings and 37 filings affected by changes in the reporting manager’s scope, the strictly comparable sample comprised 737 institutions. This methodology removes spurious changes caused by shifts in consolidated-reporting boundaries, changes in delegated managers, and missing data.
A holding’s market value reflects both its share price and its share count. Calculated as “Q2 shares minus Q1 shares, multiplied by the aggregated Q2 reference price,” Micron declined by $11.99 billion, SanDisk by $16.61 billion, Western Digital by $28.75 billion, and Seagate Technology by $4.21 billion. Across the 4 stocks, the share-count changes represented a combined reduction of $61.56 billion.
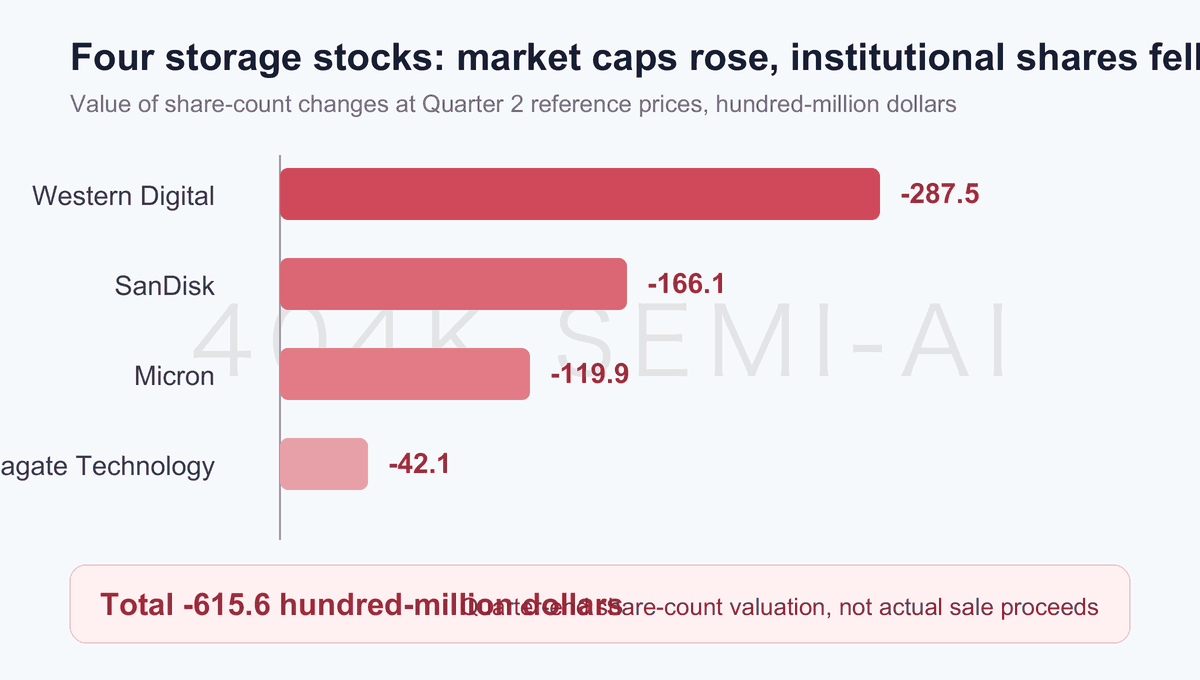
The $61.56 billion figure is the value of the share-count changes at reference prices. It does not represent a decline in holdings’ market value or actual sale proceeds. Because 13F filings provide only March 31 and June 30 snapshots and disclose neither transaction dates nor prices nor intraperiod round trips, they can indicate only the direction and approximate magnitude of quarter-end share-count changes.
In percentage terms, Western Digital’s share count fell by approximately 16.0%, SanDisk’s by approximately 9.0%, Seagate Technology’s by approximately 3.4%, and Micron’s by approximately 1.8%. Western Digital accounted for the largest reduction because it had the steepest decline in quarter-end shares. Although Micron’s reduction was also substantial in dollar terms, it had the smallest percentage change in shares.
Institutional coverage expanded across all 4 stocks: SanDisk gained 59 holders, Seagate Technology 41, Western Digital 39, and Micron 22. The number of holders in memory stocks rose from 526 to 552, while storage-device holders increased from 489 to 528. More institutions appeared on the holder lists, but the reductions by sellers exceeded the additions by buyers, producing the combination of “more holders, fewer aggregate shares.”
Gross two-way activity was far larger than the final net change. Micron’s share-count increases represented an estimated nearly $65 billion, while decreases represented approximately $77 billion, resulting in a net reduction of $11.99 billion. Institutions clearly diverged in their views on the cycle, investment horizons, and risk budgets.
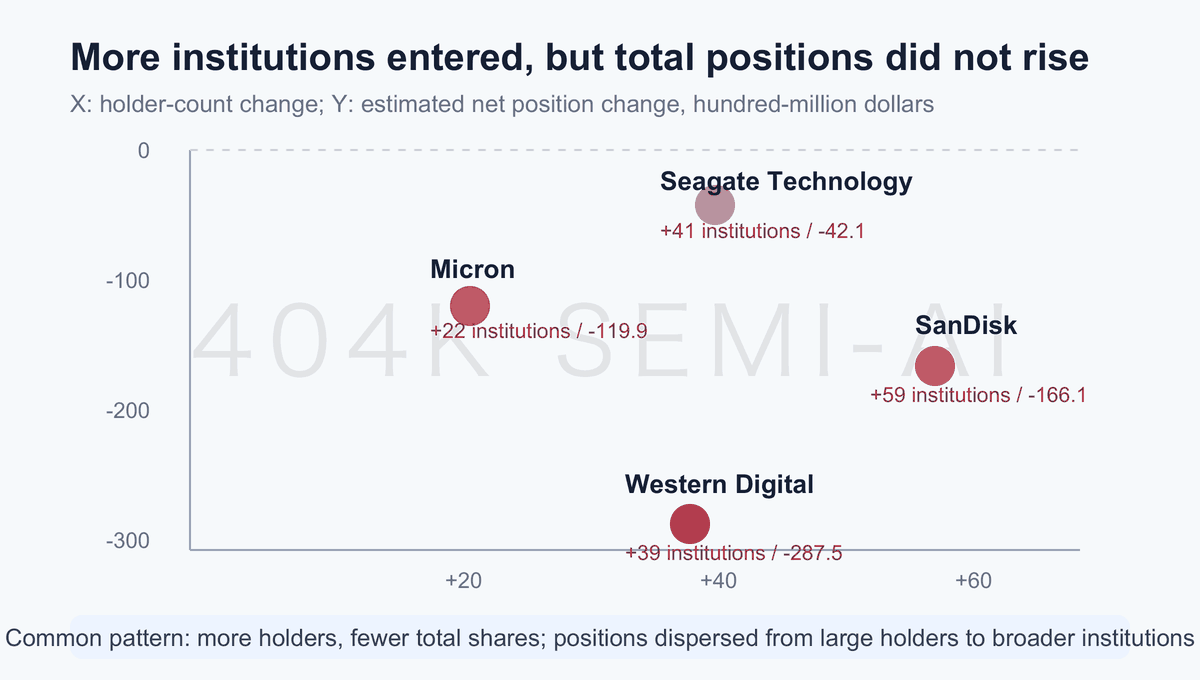
Storage holdings spread from a small group of large holders to a broader institutional base. The increase in holder counts reduced concentration, but the decline in aggregate shares left current valuations more dependent on subsequent earnings delivery.
Why Faster Market-Value Growth Can Coincide With Falling Institutional Share Counts
Memory and storage devices shared a common pattern: reported values rose far more than share counts. The market value of memory holdings increased 237.9%, even as estimated net holdings fell by $11.85 billion. Storage-device holdings rose 155.6% in market value, while estimated net holdings declined by $49.57 billion. Once price appreciation mechanically increases a position’s portfolio weight, institutions can reduce shares while still reporting a substantially higher quarter-end market value than in the prior quarter.
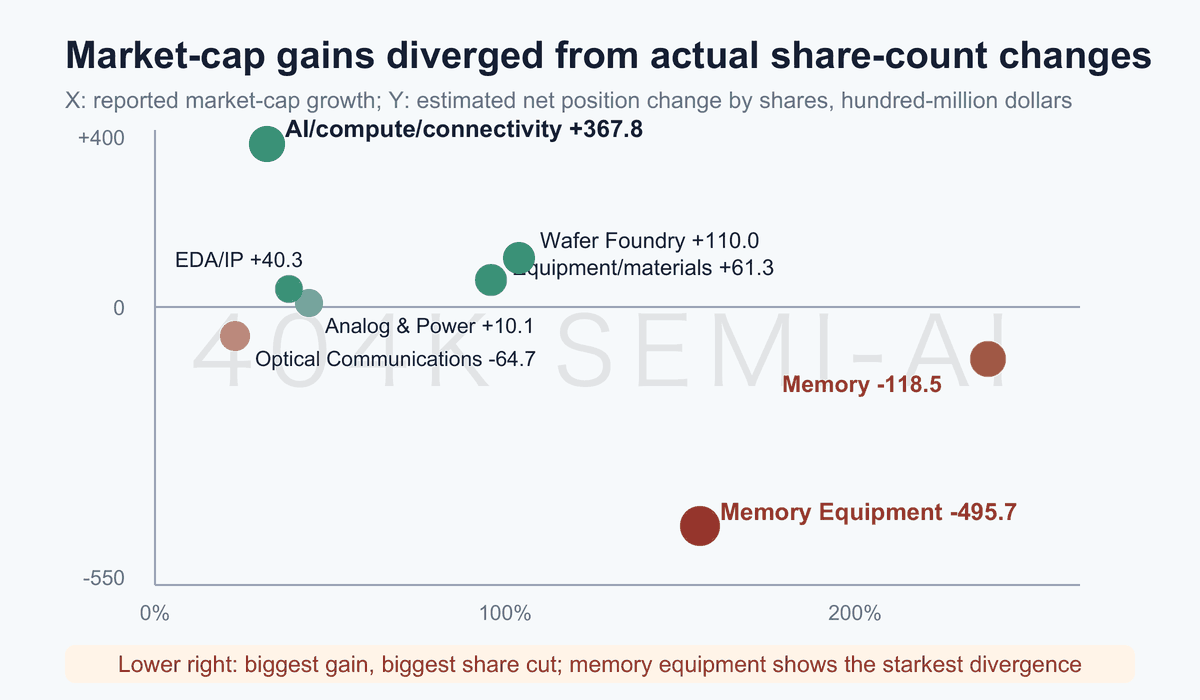
Limited to chip design, manufacturing, equipment, materials, analog, and EDA, core semiconductor common stocks still recorded a net increase of $47.095 billion. After expanding the universe to include storage devices and optical communications, however, the broader portfolio posted a net reduction of $8.95 billion. New industry-level risk budgets were absorbed by compute chips, while reductions in storage devices and optical communications almost entirely offset the increase in core semiconductors.
