
目录
Growth of 68.7% Year on Year: Three Distinct Questions
Semiconductors Generated the Entire Monthly Increase—and Exposed Growth’s Concentration
China and the U.S. Drove the Entire Increase: Demand Composition Matters More Than the Headline
Falling Imports and a Wider Surplus Do Not Necessarily Signal Weaker Domestic Demand
How the Export Rebound Translates into Korean Corporate Revenue and Profits
Four Common Misreadings of Strong Export Data
Seven Indicators to Assess Whether the Rebound Can Continue
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
South Korea’s exports rebounded strongly in August, but growth was concentrated almost entirely in semiconductors and the Chinese and U.S. markets. A wider trade surplus improved the headline balance, yet divergence across industries and destinations suggests this is not a broad-based recovery.
Growth of 68.7% Year on Year: Three Distinct Questions
August’s clearest signal was a decisive recovery in monthly export momentum. Goldman Sachs estimates that exports rose 2.8% month on month on a seasonally adjusted, non-annualized basis, reversing July’s 2.5% decline. Year-on-year growth accelerated from 63.0% in July to 68.7%, beating both the pb consensus of 63.0% and Goldman Sachs’ forecast of 64.6%. The result exceeded expectations, the previous reading, and the firm’s forecast, showing that the market had materially underestimated export strength.
These comparisons answer different questions. The return to positive monthly growth means August’s export value exceeded July’s, making it useful for assessing the latest direction. Growth of 68.7% year on year puts exports far above their year-earlier level, but may reflect a combination of base effects, prices, volumes, exchange rates, and product mix. Beating consensus means the market underestimated that month’s trade strength before the release. Together, these measures support the conclusion that the near-term rebound was stronger than expected.
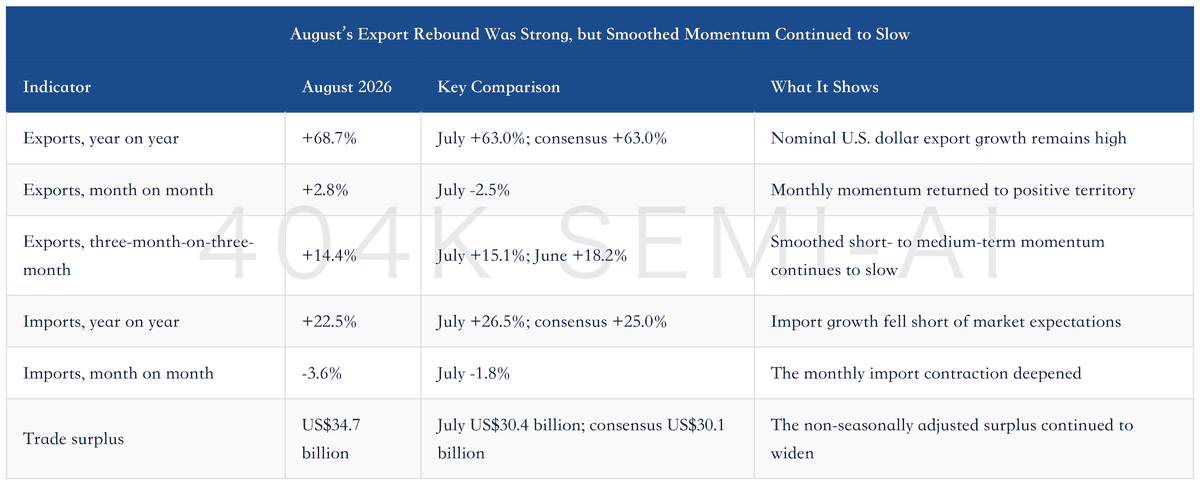
Strong year-on-year growth does not mean real export volumes rose 68.7%. The report measures exports in U.S. dollars without separating the contributions from export prices, physical volumes, and exchange rates. Rising semiconductor prices can lift nominal export values substantially even if shipment volumes change little. Differences in working days, customs-clearance timing, and the year-earlier comparison base are also not separately disclosed. The 68.7% figure is first and foremost nominal value growth; volume, price, and product-mix data are needed to explain its drivers.
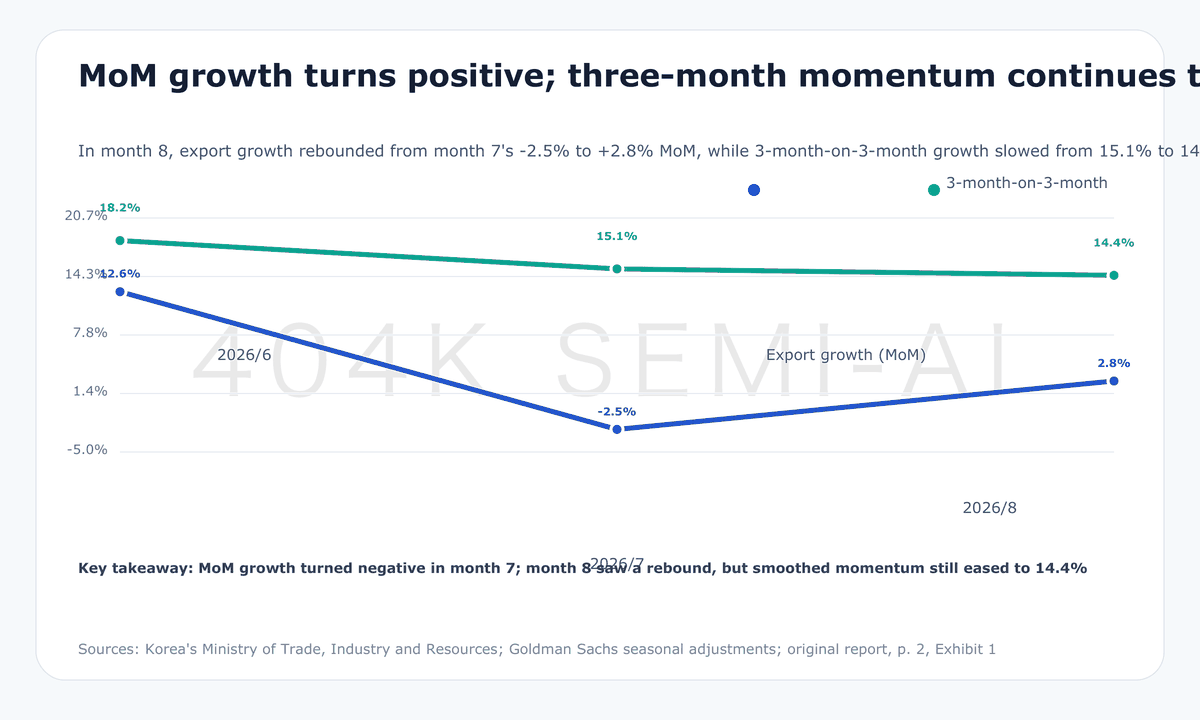
A monthly rebound can coexist with slowing three-month momentum. Monthly growth recovered from -2.5% in July to +2.8% in August, indicating a clear improvement in the latest month. Yet seasonally adjusted three-month-on-three-month growth slowed from 18.2% in June to 15.1% in July and then 14.4% in August. The monthly reading is a snapshot; the three-month measure is closer to a short video. The latest picture has improved, but the broader upward trajectory is becoming less steep.
This difference in time horizons shapes the assessment. August’s data challenge a simple narrative of rapidly weakening exports, but do not yet establish a new acceleration cycle. Sustained positive monthly growth over the next two to three months could lift three-month momentum again. If monthly growth turns negative, August is more likely to prove a strong rebound within a volatile series.
Semiconductors Generated the Entire Monthly Increase—and Exposed Growth’s Concentration
The main driver of August’s exports was clear: technology exports rose 6.5%, led by 7.2% growth in semiconductors. Semiconductor exports maintained roughly this pace for a third consecutive month and alone accounted for the entire month-on-month increase in total exports. Other technology products also improved, rising 4.6% month on month, led by computers. Gains within technology extended beyond a single category, but chips remained the decisive driver of the aggregate trend.
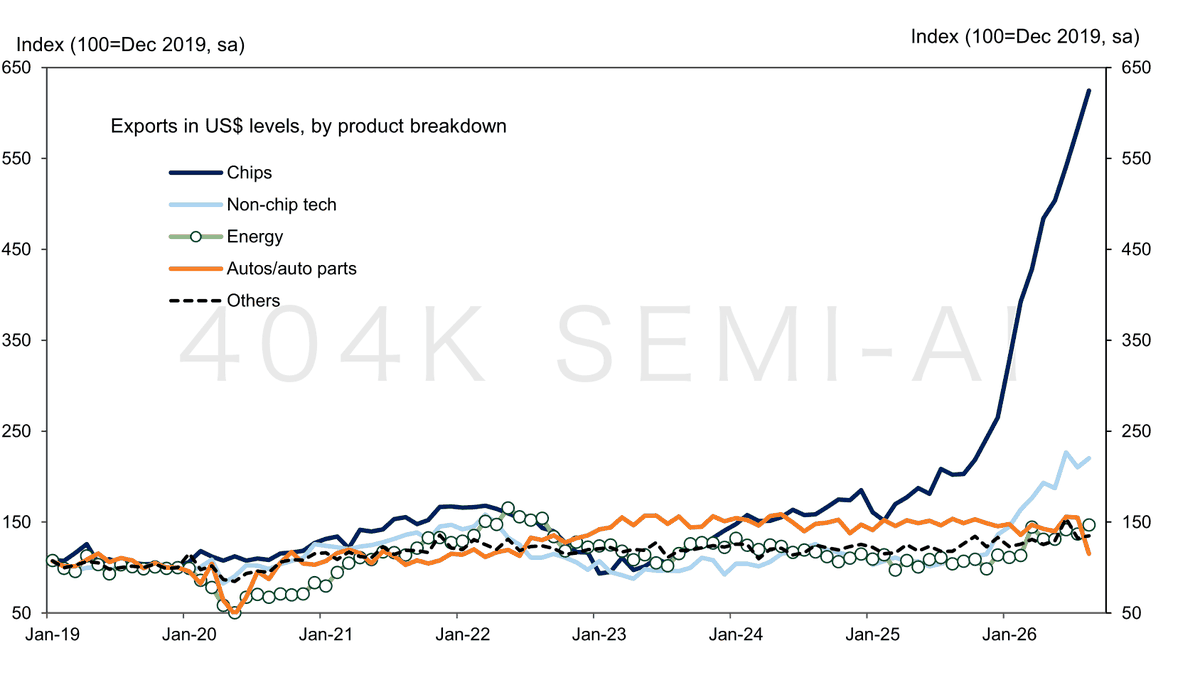
“Accounting for the entire increase” matters more than “growing fastest.” An industry can post rapid growth yet have little influence on the aggregate if its starting base is small. Semiconductors have sufficient weight in South Korean exports for their 7.2% monthly gain to offset the net drag from other sectors. With chips alone accounting for the entire 2.8% increase in total exports, all other categories combined contributed no net growth.
This structure highlights South Korean manufacturing’s high sensitivity to the global technology cycle. When demand for memory, logic chips, and related electronics rises, export values improve rapidly. Corporate revenue growth may also accelerate through higher volumes, higher prices, or both. South Korean macroeconomic data therefore often register shifts in the global electronics cycle earlier, and with greater amplitude, than end-consumption data.
That sensitivity also works in reverse. Overall exports could cool markedly if chip prices stop rising, customers finish restocking, or orders shift between months. The report provides no data on memory prices, chip shipment volumes, customer inventories, or order visibility, so it is impossible to determine whether prices or volumes drove the 7.2% increase. Earnings sensitivity cannot be inferred directly from export values either, because gross margins also depend on product mix, unit costs, yields, and exchange rates.
