
目录
Executive Summary
What the Announcement Has Already Decided
Shareholder Returns Were Discussed Before, but the Earlier Commitments Were Different
How Firm Is the “More Than 50%” Target?
Sandisk’s Buyback Is More Aggressive, but the Check Is More Flexible
Whose Capital Return Is Stronger Depends on the Question
How KRW 40 Trillion Could Change Per-Share Value
The Next Public Disclosures Will Determine the Buyback’s True Value
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
SK hynix has turned its previous policy on the maximum potential shareholder return into a board-approved resolution specifying when shares will be purchased and how they will be treated afterward. The program is smaller than Sandisk’s relative to market capitalization, but its execution path is firmer.
Executive Summary
SK hynix’s KRW40 trillion buyback has been approved by the board but has not yet been completed. The program will begin on August 20, 2026 and run for approximately 3 months. Based on the KRW1.662 million closing price on the day before the resolution, the company would purchase an estimated 24.07 million shares, equivalent to 3.3% of total issued shares. All repurchased shares will be cancelled once the purchases are completed.
This is not SK hynix’s first shareholder-return commitment, but it represents a material policy upgrade. In 2024, the company established a principle of allocating 50% of cumulative 2025–2027 free cash flow to shareholder returns, centered on a fixed dividend of KRW1,500 per share and balance-sheet resilience. In January 2026, it announced total 2025 dividends of KRW2.1 trillion and plans to cancel 15.30 million treasury shares already held. The latest program commits new capital to open-market purchases followed by full cancellation within a defined timeframe.
The new target of “more than 50% of cumulative free cash flow” does not mean every distribution detail has been approved. The KRW40 trillion buyback and full cancellation are covered by a board resolution. A higher fixed dividend, special dividends, and other incremental returns remain under consideration; their size and structure will be disclosed with the Q3 2026 results following board approval.
Sandisk’s buyback is larger proportionally but subject to looser execution constraints. Sandisk added a $14 billion authorization on August 5. Based on its August 18 share price and August 7 share count, this represents approximately 5.9% of market capitalization. Including the $1.5 billion remaining under the previous program, total unused authorization is $15.5 billion, or approximately 6.5% of market capitalization. However, the program has no expiration date, may be suspended or terminated, and does not formally commit to cancelling all repurchased shares.
The direct impact on SK hynix’s per-share value is approximately 3%; the longer-term effect depends on whether the action is repeated. Assuming unchanged net income and an actual 3.3% reduction in share count, the purely mathematical uplift to earnings per share would be approximately 3.4%. A larger valuation impact would require evidence from the Q3 2026 incremental-dividend plan, the actual number of shares cancelled, and the company’s ability to sustain recurring shareholder returns from free cash flow despite high capital expenditure.
What the Announcement Has Already Decided
SK hynix’s August 19 announcement establishes a clear evidence chain: the board has approved a KRW40 trillion program; repurchases will begin on August 20 and run for approximately 3 months; and every share purchased will be cancelled once the program is completed. This is therefore a formal program capable of commencing the next day, not merely a management proposal under review.
“Approved,” however, should not be confused with “completed.” The share price will fluctuate over the 3-month period, and the estimated 24.07 million shares are based on the KRW1.662 million closing price rather than a fixed final quantity. The figures that will ultimately appear in the financial statements are the actual amount spent, weighted-average purchase price, cancellation date, and final total share count.
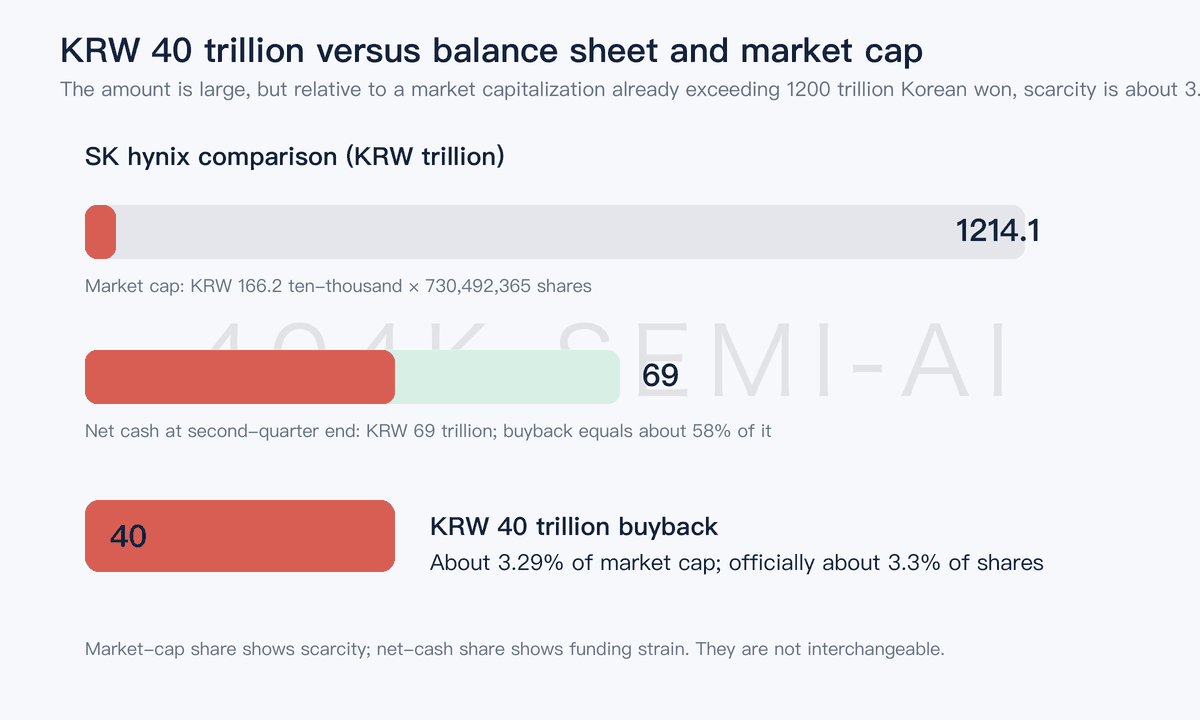
The resolution also carries weight because the company has sufficient cash to support it. At the end of Q2, SK hynix reported approximately KRW69 trillion of net cash; the KRW40 trillion program is equivalent to roughly 58% of that amount. Based on the closing price and total issued shares cited in the announcement, the company’s equity market capitalization was approximately KRW1,214.1 trillion, making the buyback equivalent to about 3.29%. The first ratio measures pressure on cash resources, while the second measures the reduction in equity supply; they should not be conflated.
Shareholder Returns Were Discussed Before, but the Earlier Commitments Were Different
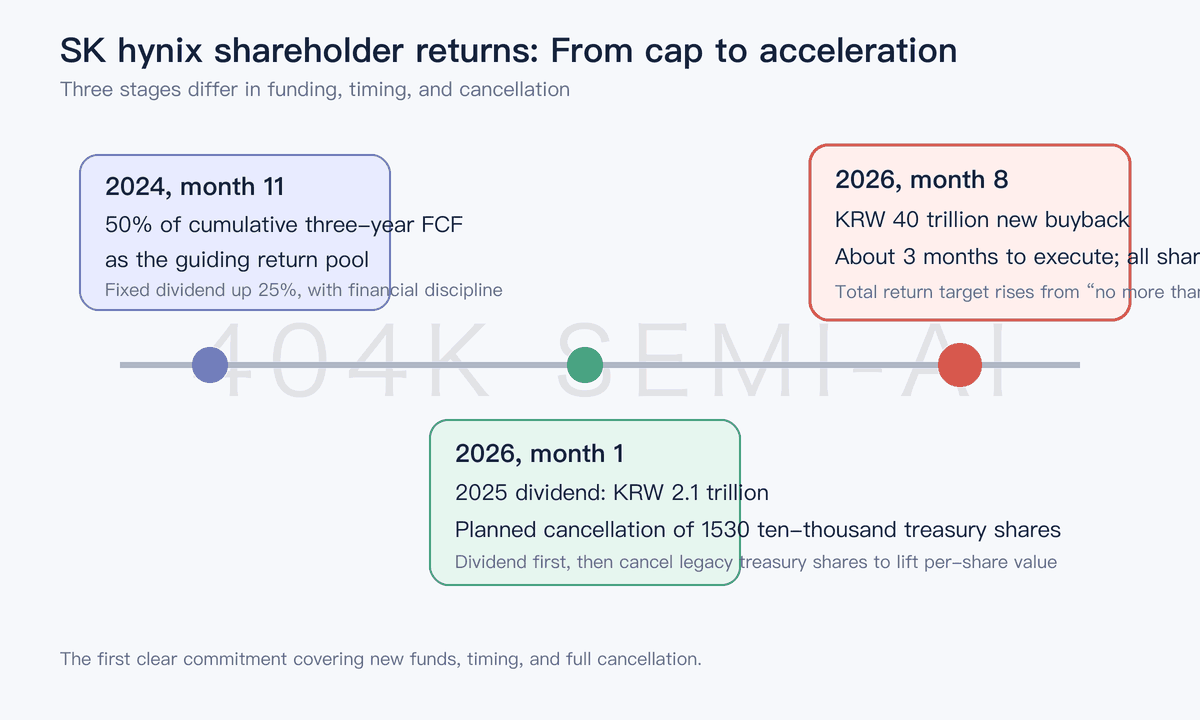
In November 2024, SK hynix announced its 2025–2027 shareholder-return plan. The framework retained the principle of allocating 50% of cumulative free cash flow to shareholder returns, raised the annual fixed dividend from KRW1,200 to KRW1,500 per share, and reserved 5% of free cash flow for strengthening the financial structure. The company also said it could provide additional returns before the end of the 3-year cycle if free cash flow materially exceeded expectations.
The policy was effectively sequenced as follows: pay the base dividend, repair the balance sheet, and increase returns if cash generation outperformed. It allowed for incremental distributions but did not specify the size or start date of a new buyback or commit to cancelling the shares purchased.
The second step came in January 2026. SK hynix raised its 2025 dividend to KRW3,000 per share, totaling KRW2.1 trillion, and announced plans to cancel 15.30 million treasury shares, then worth approximately KRW12.2 trillion and representing about 2.1% of total shares. This removed concerns that those treasury shares could later be reissued. However, because treasury shares were already excluded from shares outstanding, cancelling existing treasury stock is not equivalent to spending a fresh KRW12.2 trillion on open-market repurchases during the period.
The new KRW40 trillion program changes precisely that: SK hynix will deploy new capital to purchase shares currently trading in the market and then cancel all of them. Relative to the previous policy, the commitment now includes a cash outlay, an execution timetable, and an irreversible reduction in share capital.
How Firm Is the “More Than 50%” Target?
The announcement raises SK hynix’s shareholder-return target from “no more than 50% of cumulative 2025–2027 free cash flow” to “more than 50%.” This is a formal policy upgrade: the company no longer treats 50% as the upper limit for shareholder returns. Buybacks and cancellations will proceed alongside cash dividends rather than being mutually exclusive alternatives.
It is not yet a complete formula that can be entered directly into a financial model. The company said future returns will also depend on cash flow, market conditions, and distributable profit. A higher fixed dividend and special dividends are only options under consideration. SK hynix will disclose the specific scale and execution method with its Q3 2026 results after obtaining a new board approval.
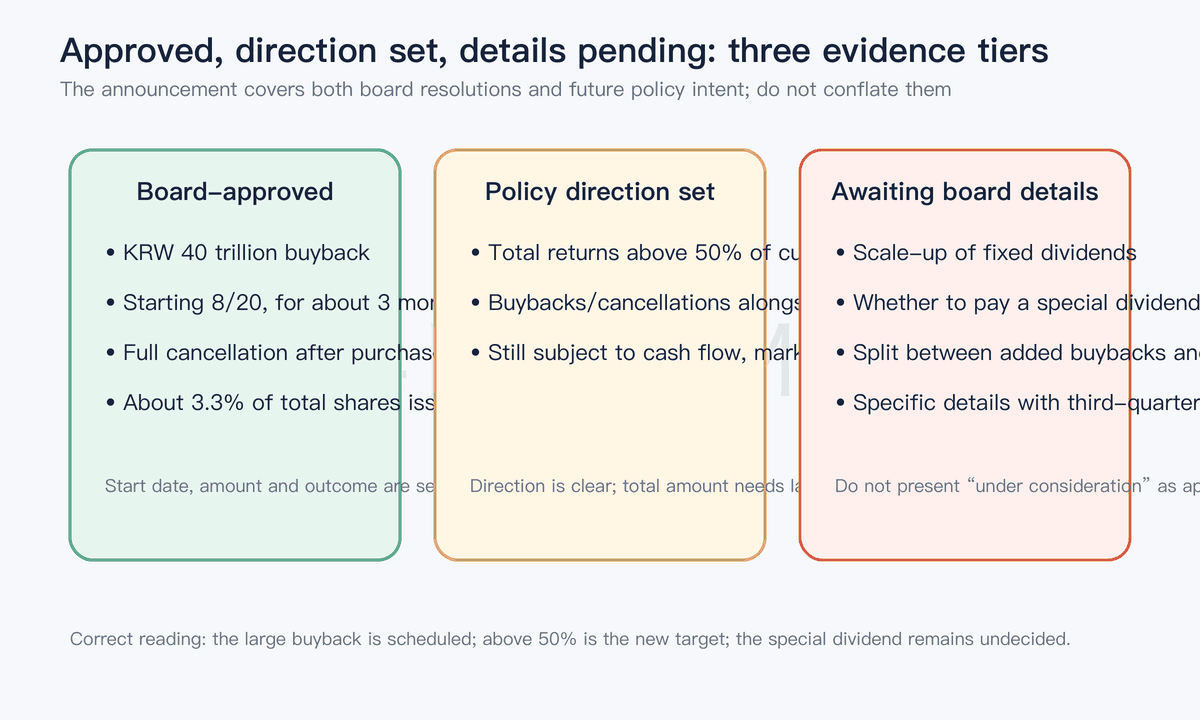
The most accurate formulation is therefore: the KRW40 trillion program has been approved and is executable; a payout above 50% is now the aggregate shareholder-return target; and the size of additional cash dividends remains undecided. Separating these three levels of evidence avoids both understating the buyback and prematurely treating a special dividend as a settled fact.
Sandisk’s Buyback Is More Aggressive, but the Check Is More Flexible
Sandisk’s timeline is short but compelling. On April 30, its board approved a $6 billion repurchase program. By July 3, the company had spent $4.5 billion to repurchase 2.836275 million shares, equivalent to approximately 1.94% of the common shares outstanding on August 7. On Sandisk’s FY2026 basis, the $4.5 billion represented approximately 39.2% of its $11.494 billion in free cash flow, or 51.5% of its $8.743 billion in adjusted free cash flow after excluding effects including long-term agreement prepayments. This demonstrates that the initial authorization was substantive, not rhetorical.
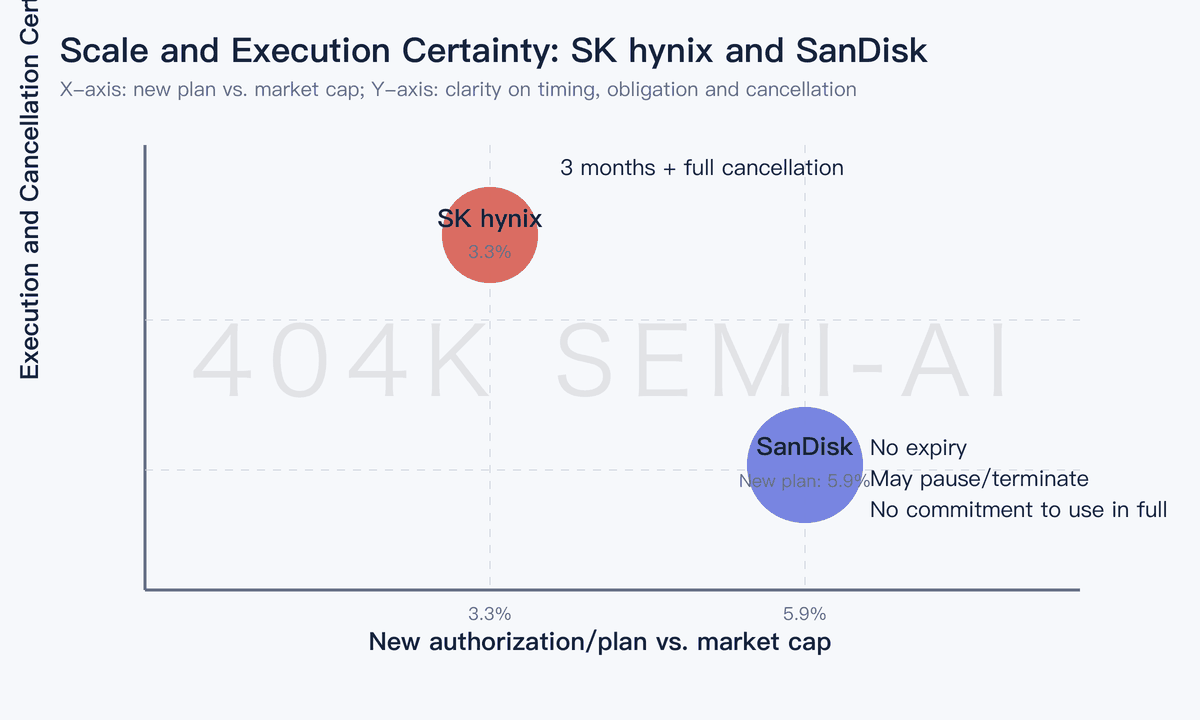
On August 5, Sandisk added another $14 billion authorization, taking its total remaining capacity to $15.5 billion. Based on the August 18 closing price of $1,625.78 and 146,419,001 common shares outstanding, Sandisk’s market capitalization was approximately $238.05 billion. The new authorization represented approximately 5.88% of market capitalization, while total remaining authorization represented approximately 6.51%. Relative to market capitalization, the program is clearly more aggressive than SK hynix’s 3.3%.
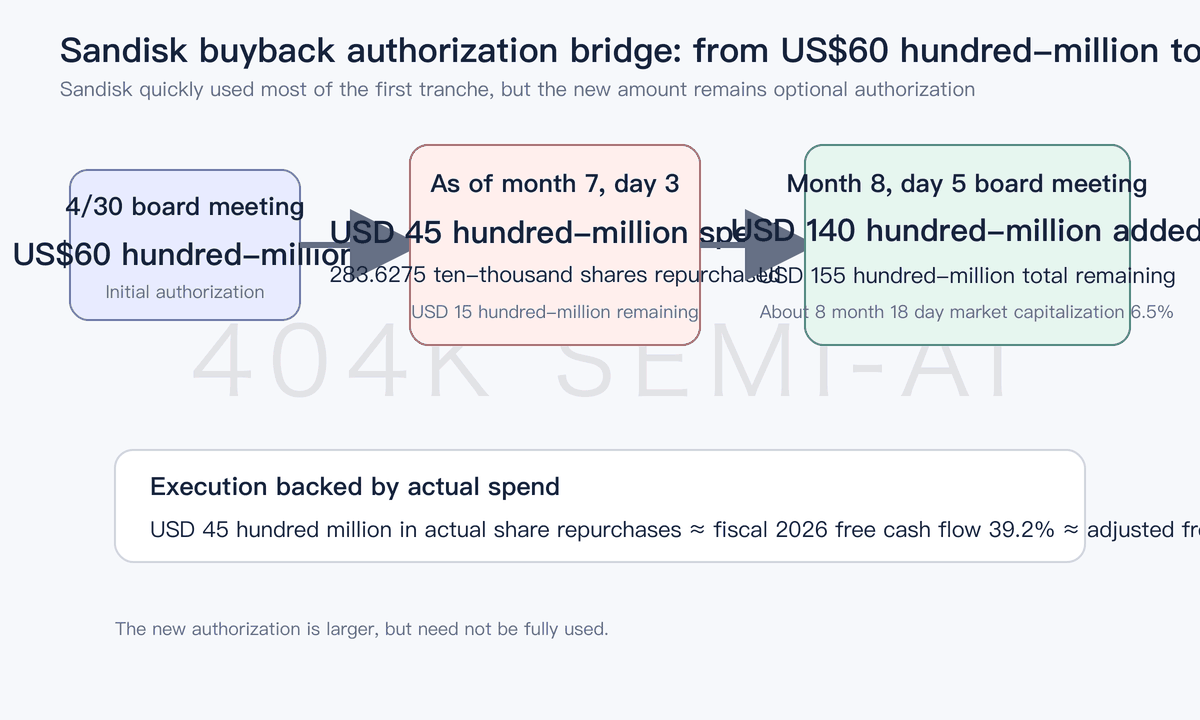
The difference lies in the terms of the authorization. Sandisk’s 10-K explicitly states that the program has no expiration date; the amount and timing of repurchases depend on market conditions and other factors; and the company may suspend or terminate the program at any time. The board authorization also does not obligate the company to repurchase any specified amount. This gives management greater discretion over price but leaves the ultimate reduction in dilution uncertain.
Sandisk’s filings also do not commit to cancelling every repurchased share. Treasury shares still reduce current shares outstanding and can increase earnings per share if they are not reissued, but cancellation further eliminates the option to reissue them. SK hynix is therefore offering a smaller but more certain reduction in share capital, while Sandisk is offering greater buyback capacity while preserving management discretion.
Whose Capital Return Is Stronger Depends on the Question
If the question is whose new program is larger relative to market capitalization, the answer is Sandisk. Its new $14 billion authorization represents approximately 5.9% of market capitalization, about 2.6 percentage points above SK hynix’s 3.3%. If the question is how much the share count will definitively shrink within three months, SK hynix has the stronger evidence because it has specified both a deadline and full cancellation.
If the question is which company has already demonstrated a willingness to repurchase shares aggressively during an industry upcycle, Sandisk has the more complete track record. It spent $4.5 billion in approximately 2 months, clearly demonstrating its speed from authorization to execution. SK hynix’s new program will not begin until August 20, so evidence of execution must come from subsequent repurchase data and the cancellation announcement.
There is also an easily overlooked funding constraint. Sandisk’s remaining $15.5 billion authorization is more than 3 times its period-end cash balance of $4.762 billion and equals 177% of adjusted fiscal 2026 free cash flow. Execution must therefore rely on future cash flow; existing cash alone cannot fund the authorization in one payment. SK hynix’s KRW 40 trillion represents approximately 58% of its current net cash, providing stronger funding coverage, although substantial investment in HBM, front-end DRAM capacity, and advanced packaging will continue to drive capital expenditure higher.
How KRW 40 Trillion Could Change Per-Share Value
Assuming total profit remains unchanged and the actual share cancellation matches the company’s official estimate of 3.3%, earnings per share would increase by approximately 3.4% as the denominator contracts. This is a direct and quantifiable benefit, but it cannot alone explain a larger market repricing. For a highly cyclical, capital-intensive memory company, investors care more about whether management will maintain discipline when cash is abundant than whether it will immediately convert all available cash into new capacity at the top of the cycle.
The central question for SK hynix has been whether high profits would genuinely accrue to common shareholders once pricing momentum slowed and capital expenditure increased. The announcement provides part of the answer: a new cash-funded repurchase covering approximately 3.3% of outstanding shares will be executed on an accelerated schedule, and the shares will be cancelled rather than held in treasury for potential reissuance.
The remaining question is cash-flow durability. If net cash is rapidly rebuilt after the repurchase while ordinary or special dividends increase, “more than 50%” would become a multi-year capital-allocation principle. If this is a one-off action and capital expenditure subsequently consumes free cash flow, the long-term impact will look more like a one-time 3.4% mathematical uplift to per-share value.
The Next Public Disclosures Will Determine the Buyback’s True Value
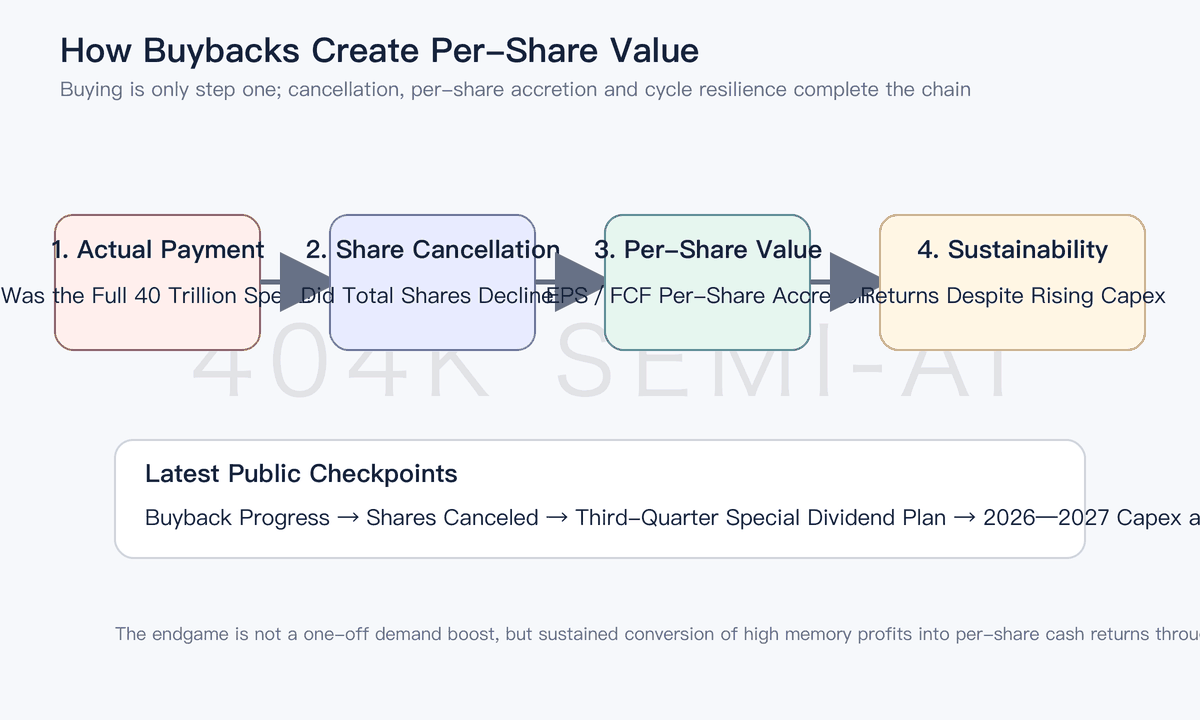
The first number to watch is actual repurchase progress. KRW 40 trillion is the target amount; the final number of shares acquired will depend on the purchase price. If the share price rises sharply, the cancellation ratio will be below 3.3%; if it falls, the same amount will retire more shares. Regardless of price movements, investors must see both procedural milestones: completion of the purchases and effectiveness of the cancellation.
The second number is the amount of additional shareholder returns disclosed with the third-quarter 2026 results. If both ordinary and special dividends increase, confidence in the “more than 50%” commitment will strengthen. If the company merely reiterates the direction without specifying an amount, annual cadence, or board resolution, the market will continue to discount the portion above 50%.
The third number is free cash flow after capital expenditure. SK hynix continues to expand HBM, advanced DRAM, M15X, and packaging capacity. Buybacks should not come at the expense of capacity investments that generate attractive returns, but capacity investment should not become a permanent justification for withholding cash from shareholders. Both conditions must hold for the company to evolve from a beneficiary of the cyclical upturn into a memory leader capable of generating sustainable per-share cash returns.
This announcement has cleared the most important threshold: the new cash-funded repurchase is no longer hypothetical but a board-approved resolution with a timetable, a defined amount, and mandatory cancellation. Compared with Sandisk, SK hynix will not deliver the larger reduction in share count, but its outcome is more predictable. The next signal capable of raising long-term value will be continued dividends and repurchases despite high capital expenditure after these shares have been fully cancelled.
Related Reading
Arm FY2027 Q1 Deep Dive: Data Center Royalties More Than Double, AGI CPU Demand Exceeds $2 Billion