
SK hynix Deep-Dive Update: Is It Still Expensive? DDR5 Takes Over Price Increases, Korean Exports Break Out, and Samsung Catch-Up Risk
目录
TL;DR
1. New Evidence from the Past Week: Prices, Exports, and Valuation Are All Sending Signals
II. SK Hynix’s Asset Attributes Have Changed: It Is Not Just Selling Memory, But AI Bandwidth and Supply Certainty
III. Why the Sharp DDR5 Rally Matters More Than NAND Divergence
IV. HBM: 2027 Pricing Expectations Are Improving, but Leadership Should Not Be Treated as Permanent Monopoly
V. Korean Exports and KOSPI Pullback: Fundamentals Revised Up, Trading Layer Cools
VI. Peer Ranking: Buy SK hynix for Certainty, Samsung for Catch-Up, Micron for U.S. Exposure, Kioxia for High NAND Beta
VII. Valuation Framework: Further Target-Price Revisions Depend on Three Layers of Profit
VIII. Falsification Checklist: What to Watch Over the Next Four Quarters
IX. Old Framework vs. This Week’s Incremental Evidence: What Has Been Reinforced, and What Needs to Cool Down
10. Conclusion: Quality Remains in the Top Tier, but Entry Points Must Follow the Evidence
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The key point in this SK hynix update is not just another target-price increase, but the simultaneous emergence of a sharp DDR5 rally, high growth in Korean memory exports, and improving HBM pricing expectations. The market is repricing SK hynix from an HBM leader into an asset with AI memory supply rights, but Samsung’s catch-up, capex, and crowded positioning will determine how far this re-rating can go.
TL;DR
The main thread for SK hynix has changed. Materials from the past week show price increases spreading from HBM to DRAM and SSD, while exports remain elevated. The investment implication is shifting from an HBM premium toward AI memory supply rights. The next things to watch are whether server contract prices, HBM4 share, and Korean exports can continue moving in the same direction.
DDR5 is the strongest incremental evidence this week. Server DDR5 modules continued to rise in June, and the premium over DDR4 is also expanding. 3Q26 server DRAM is still being pointed toward further upside. HBM determines the valuation ceiling; DDR5 determines the slope of EPS delivery in 2026-2027.
The essence of the target-price increase is multiple expansion. In May, BofA raised its SK hynix target price to KRW 3,000,000, using 9x 2027-2028 P/E, citing upward revisions to DRAM/NAND ASPs, sustained AI demand, and constrained wafer-capacity growth. Materials from the past week continue to show memory valuation multiples expanding, with target prices for Samsung and SK hynix raised again. The market is not just chasing one quarter of profit; it is debating how much of peak earnings can be capitalized.
Samsung’s catch-up is both a risk and industry validation. Samsung’s higher server DRAM ASPs, improving HBM proxy indicators, and rising price expectations for 64GB DDR5 RDIMMs prove that industry demand is very strong. But the same evidence also reminds SK hynix that HBM4 and 2027 HBM pricing are not risk-free monopolies. SK hynix remains the higher-quality certainty asset, while Samsung looks more like a catch-up elasticity asset.
A short-term pullback does not mean fundamentals have deteriorated. The KOSPI has pulled back by about 4% over the past week, with foreign investors continuing to sell technology stocks, and 12-month forward P/E falling to around 6.65x. But KOSPI 12-month EPS was revised up 4.8% over the same period, and technology-sector EPS was revised up 5.5%. This looks more like a stress test of crowded positioning than a rejection of AI memory fundamentals.
1. New Evidence from the Past Week: Prices, Exports, and Valuation Are All Sending Signals
The most important change this week is that pricing evidence has spread from “HBM is very tight” to commodity DRAM, server DDR5, and Korean exports. If only HBM prices are strong, SK hynix’s valuation still mainly depends on share in a single product. If server DRAM, PC DRAM, mobile DRAM, NAND, and eSSD all rise together, the market will start viewing the company as a broad supply-rights asset at the AI memory layer.
Memory Is No Longer Just a Cyclical Sector: JPM LTA Breakdown, Agentic AI Memory Multipliers, and the Rewriting of Samsung and hynix Valuations
Several data points in the past week’s materials are especially solid.
The first is memory pricing. TrendForce’s judgments on 3Q26 conventional DRAM, PC DRAM, server DRAM, and mobile DRAM all point to continued price increases, indicating this is not a shortage in “one small category,” but an upward shift in the overall DRAM price curve. More importantly, server DDR5 modules continued to surge in June, with the premium versus DDR4 expanding. For SK hynix, DDR5 is not a supporting role to HBM. It is the profit base jointly driven by AI CPUs, inference servers, system-memory expansion, and restocking of ordinary cloud servers.
The second is exports. Korea’s memory exports rose 280% YoY in June, marking the fifth consecutive month of more than 200% YoY growth. DRAM exports rose 385% YoY, an extremely strong level in the tracking framework since 2008. NAND chip exports rose 301% YoY, and SSD exports rose 355% YoY. This data set matters because it bypasses single-company reporting frameworks and directly shows that external demand and pricing are jointly pushing up export value across the Korean memory chain.
The third is valuation. Report titles and summaries from the past week indicate that the memory upcycle may be “longer and higher,” with DRAM, NAND, and HBM improving in sync and driving upward revisions to memory valuation multiples. Target prices for Samsung and SK hynix were raised with Buy ratings reiterated, and Kioxia was also upgraded to Buy. The focus here is not any single target price, but “valuation multiple expansion.” The market is starting to use earnings in more distant years and higher P/E or P/B multiples to value memory companies, instead of only focusing on 2026 peak EPS.
The fourth is a market stress test. The KOSPI has pulled back by about 4% over the past week, with foreign investors continuing to sell technology stocks. The 12-month forward P/E has fallen to around 6.65x, a very low level. But earnings expectations are still being revised upward, with KOSPI 12-month EPS up 4.8% and the technology sector up 5.5%. This indicates that share-price volatility includes factors such as crowded positioning and risk appetite, and is not entirely due to deteriorating fundamentals.
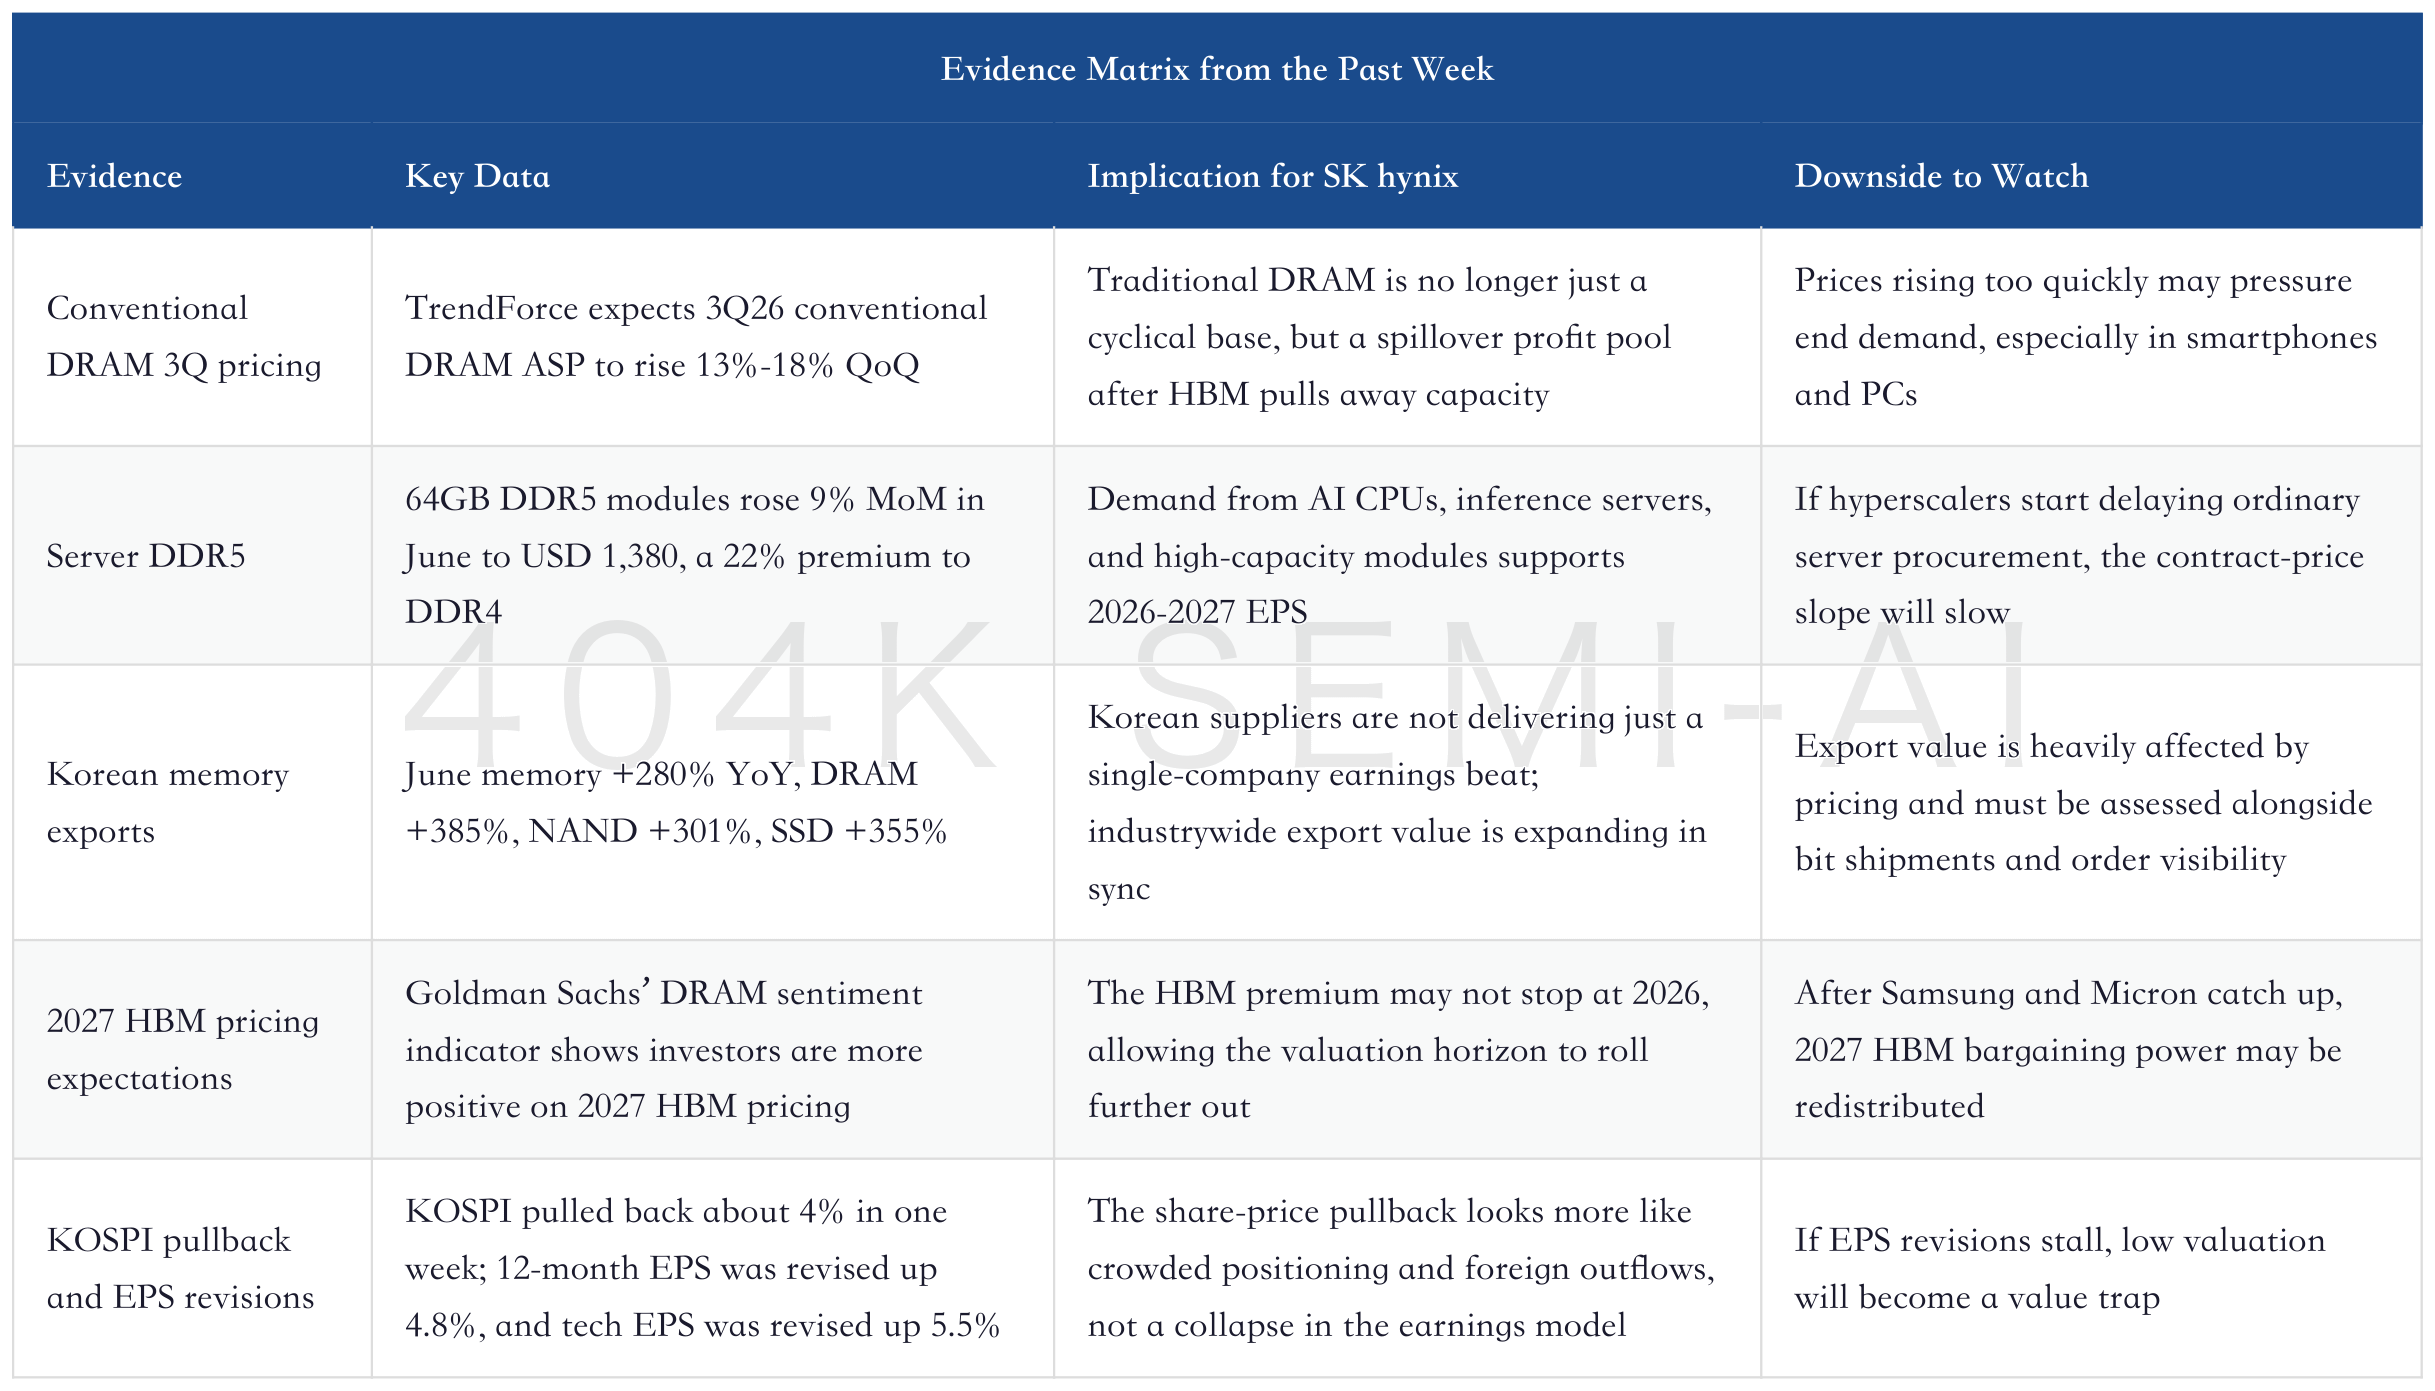
The conclusion from this table is straightforward: SK hynix’s short-term trading can be disrupted by the KOSPI pullback and foreign outflows, but the fundamental evidence is still strengthening. When prices, exports, and valuation multiples all move in the same direction, “it has gone up too much” cannot be the only explanation for the share price. The real question is: among these new pieces of evidence, which are merely 2026 peak earnings, and which can become high ROE that remains discountable beyond 2027?
Goldman Sachs DRAM Deep-Dive Update: DDR5 Price Increases, 2027 HBM Repricing, and Samsung’s KRW 2,450 Trillion Investment
II. SK Hynix’s Asset Attributes Have Changed: It Is Not Just Selling Memory, But AI Bandwidth and Supply Certainty
Historically, the core lens for SK Hynix was the DRAM cycle; today, the core lens is control over AI memory supply. This is a major shift. Cyclical companies expand capacity when they make money, and prices fall after capacity comes online, so the market assigns low multiples. Supply-right assets work differently: customers are willing to lock in supply early for certainty, yield, roadmap coordination, and delivery cadence, allowing profits to be discounted over more distant years.
SK Hynix’s greatest strength is HBM purity. Samsung carries a blended valuation across smartphones, memory, foundry, display, and system semiconductors; Micron has U.S. capital-market mapping and a three-line resonance across DRAM, NAND, and HBM; SK Hynix is closer to a “pure-play AI memory asset.” Its share price is more sensitive to HBM share, server DRAM, LTAs, AI capex, and Korean exports, giving it greater upside elasticity, but also sharper drawdowns.
In this update, the change in asset attributes is mainly reflected in four areas.
First, HBM has pushed SK Hynix next to GPUs and AI ASICs. HBM is not ordinary memory; it is the bandwidth layer attached to accelerators. The larger AI models become, the longer context windows get, and the higher inference concurrency rises, the more data movement between GPU and memory becomes the bottleneck. Over the past few years, SK Hynix has built a first-mover advantage in HBM3E, HBM4, TSV, MR-MUF, yield, and customer collaboration. Customers are not buying an ordinary DRAM chip; they are buying supply security within a platform roadmap.
Second, HBM pulls away advanced DRAM capacity, making DDR5 even tighter. HBM production consumes advanced DRAM wafers, packaging, testing, and engineering resources. The more customers compete for HBM, the more supply of ordinary server DDR5 and high-capacity RDIMMs is squeezed. The sharp rally in server DDR5 prices over the past week is a real-world validation of this mechanism.
Third, NAND and eSSD are starting to shift from a drag into a supplementary profit pool. NAND is not the highest layer of SK Hynix’s valuation, but AI inference, RAG, KV cache, model checkpoints, and enterprise SSD expansion mean NAND is no longer just a consumer-electronics cycle. In June, NAND chip exports rose 301% YoY and SSD exports rose 355% YoY, showing that data-center capacity demand is not absent.
Fourth, the latest target-price increases are ultimately about “profit sustainability.” In May, BofA raised its target price for SK Hynix to KRW 3.0 million, using 9x 2027-2028 P/E, and raised its 2026/2027 EPS forecasts by 12%/17%. The rationale was around 10% upward revisions to DRAM and NAND ASPs, strong AI demand, and limited wafer-capacity growth. The discussion over the past week about “valuation multiple expansion” is an extension of this framework: if 2027-2028 EPS can still hold, the market will not assign only a low multiple to 2026 peak earnings.
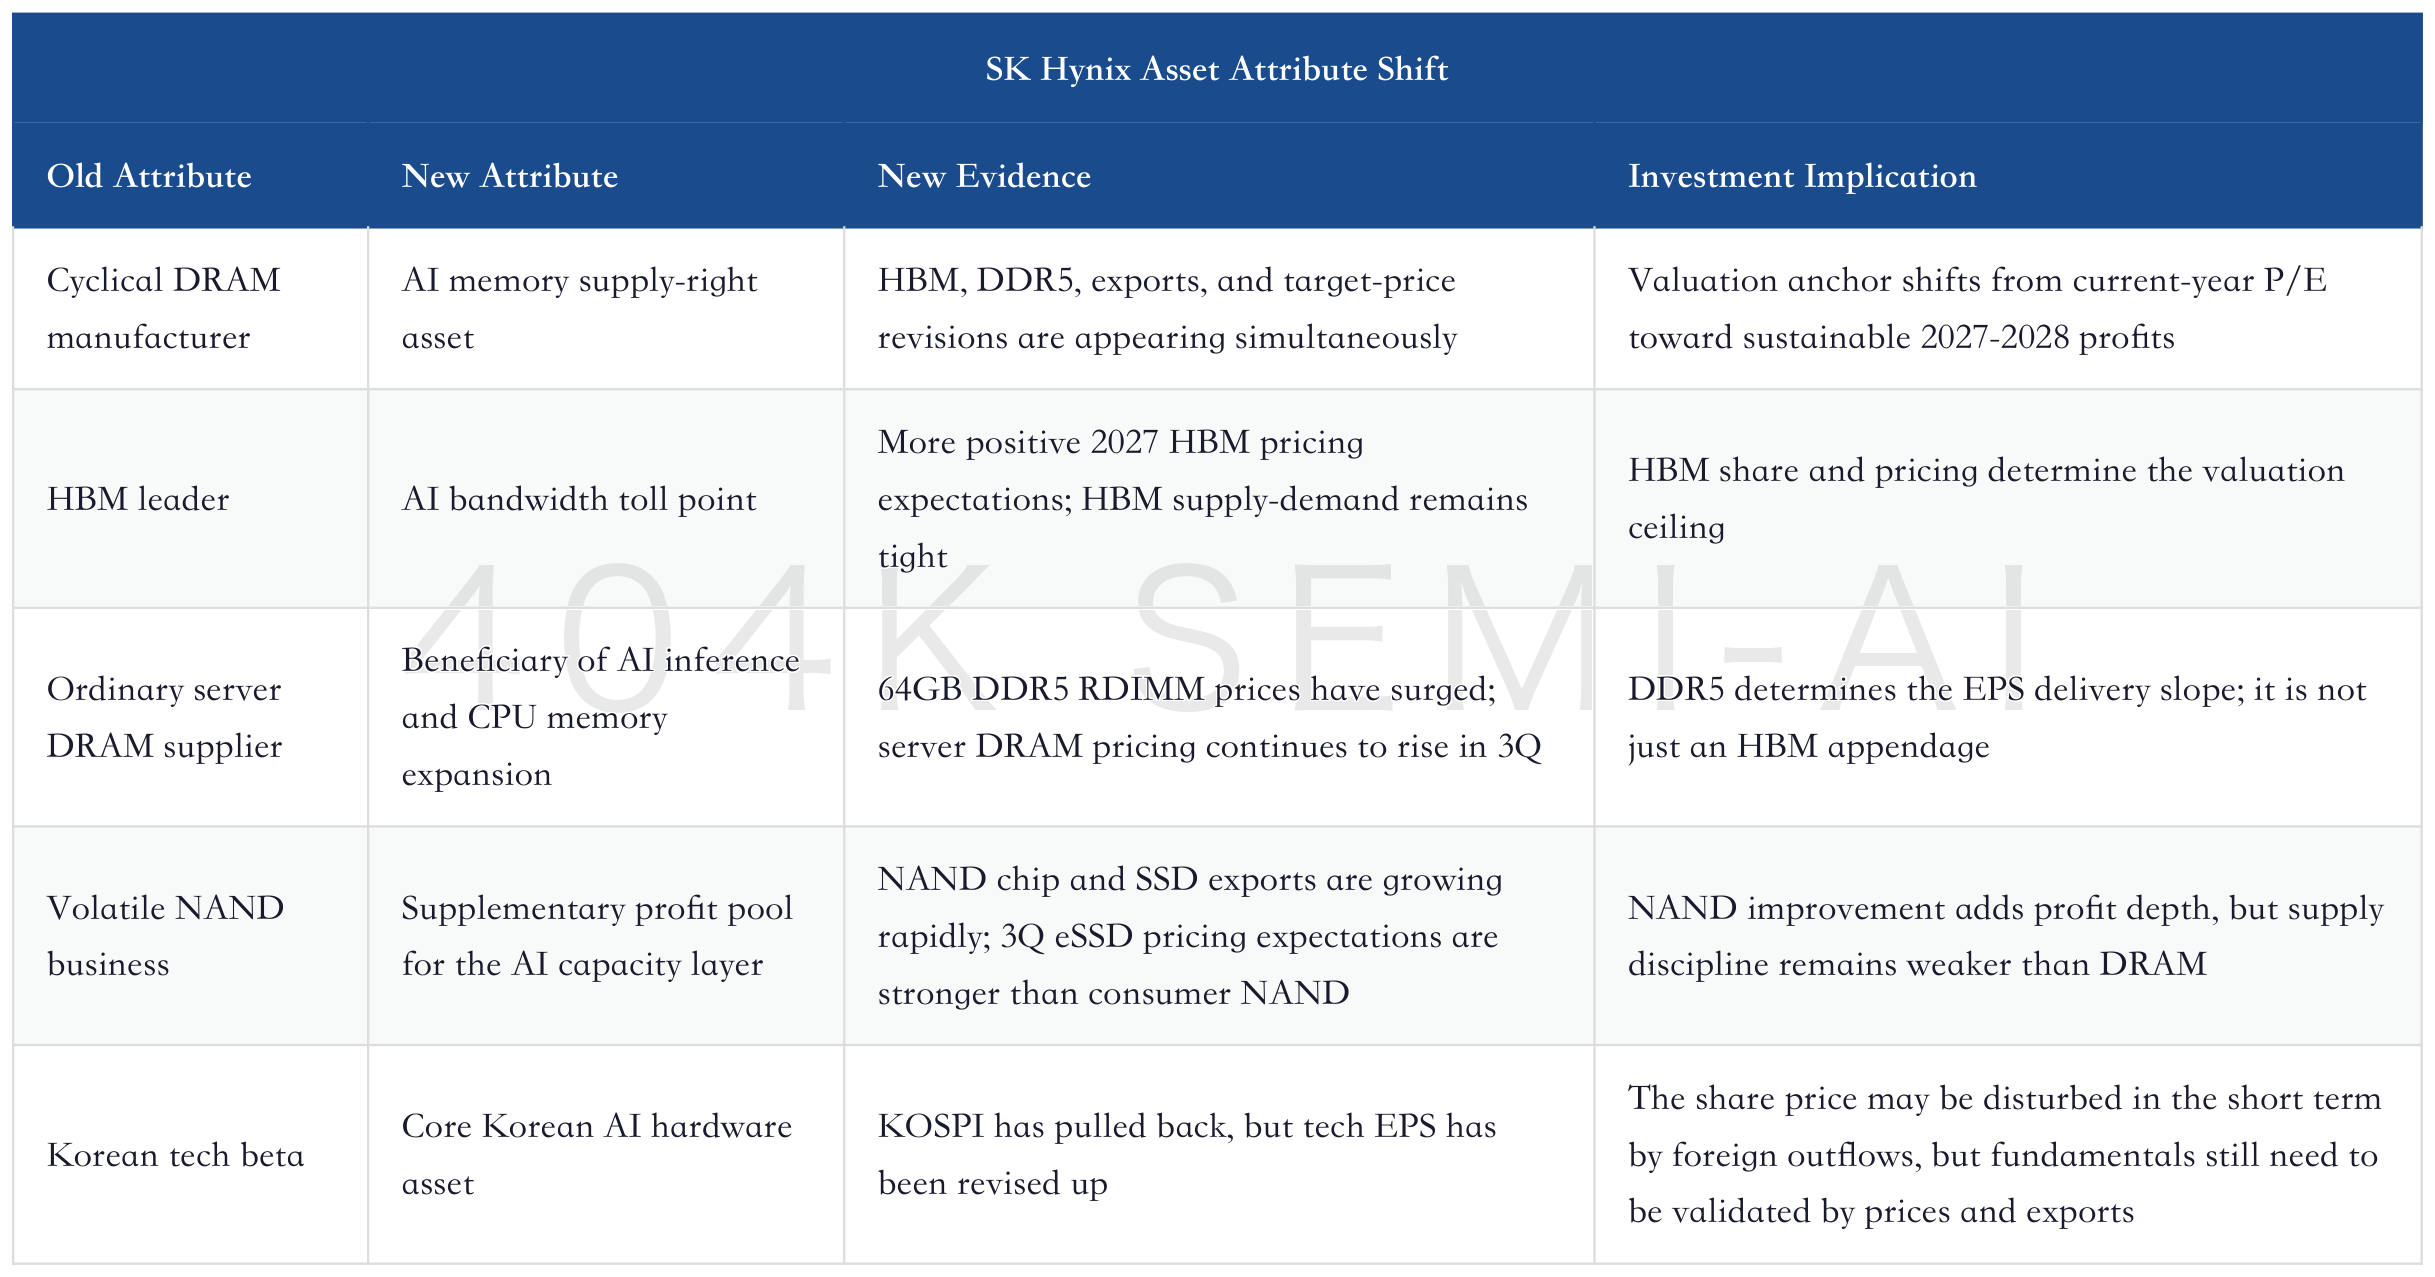
Therefore, this SK Hynix update should not be written as “prices are up again.” Price increases are only the surface layer. The deeper question is whether AI memory shortages have lifted SK Hynix’s normalized ROE to a higher level. If this is only an extreme 2026 shortage, target-price increases are just late-cycle optimism; if HBM, DDR5, LTAs, and customer roadmap coordination can carry profits into 2027-2028, then valuation multiple expansion has a foundation.
AI Is Driving a Sector-Wide Revaluation of Memory: Who Has the Most Pricing Power Across DRAM, NAND, SSDs, and HDDs, as Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Earnings Cross-Validate One Another
III. Why the Sharp DDR5 Rally Matters More Than NAND Divergence
DDR5 is the most important marginal variable to watch in this update. HBM is already heavily watched by the market, and NAND recovery is also underway, but the sharp rally in server DDR5 prices shows that AI demand is spreading from HBM next to accelerators into the entire server memory layer.
June price tracking shows that DDR5 in PC DRAM is also catching up, with the price gap versus DDR4 narrowing meaningfully. This data shows that DDR5 price recovery is not only happening on the server side; PCs and general-purpose computing are also following, although the valuation quality of PC-side demand is lower than that of servers.
Server DRAM is more important. In June, high-capacity DDR4 modules were broadly flat, but high-capacity DDR5 modules continued to rise and their premium widened further; server DRAM prices already rose sharply in 2Q26, and 3Q26 is still expected to maintain double-digit growth. For SK Hynix, this set of data is more important than a single HBM headline, because server DDR5 is a category that can enter revenue and EPS at scale.
The NAND signal is more complex. TrendForce expects NAND prices to continue rising in 3Q26, but enterprise SSDs are clearly stronger than consumer-side eMMC/UFS. This suggests strong NAND demand from AI data centers, but weaker acceptance in consumer NAND. For SK Hynix, NAND is an incremental positive, not the core pricing-power asset; valuation quality is still determined by HBM and DDR5.
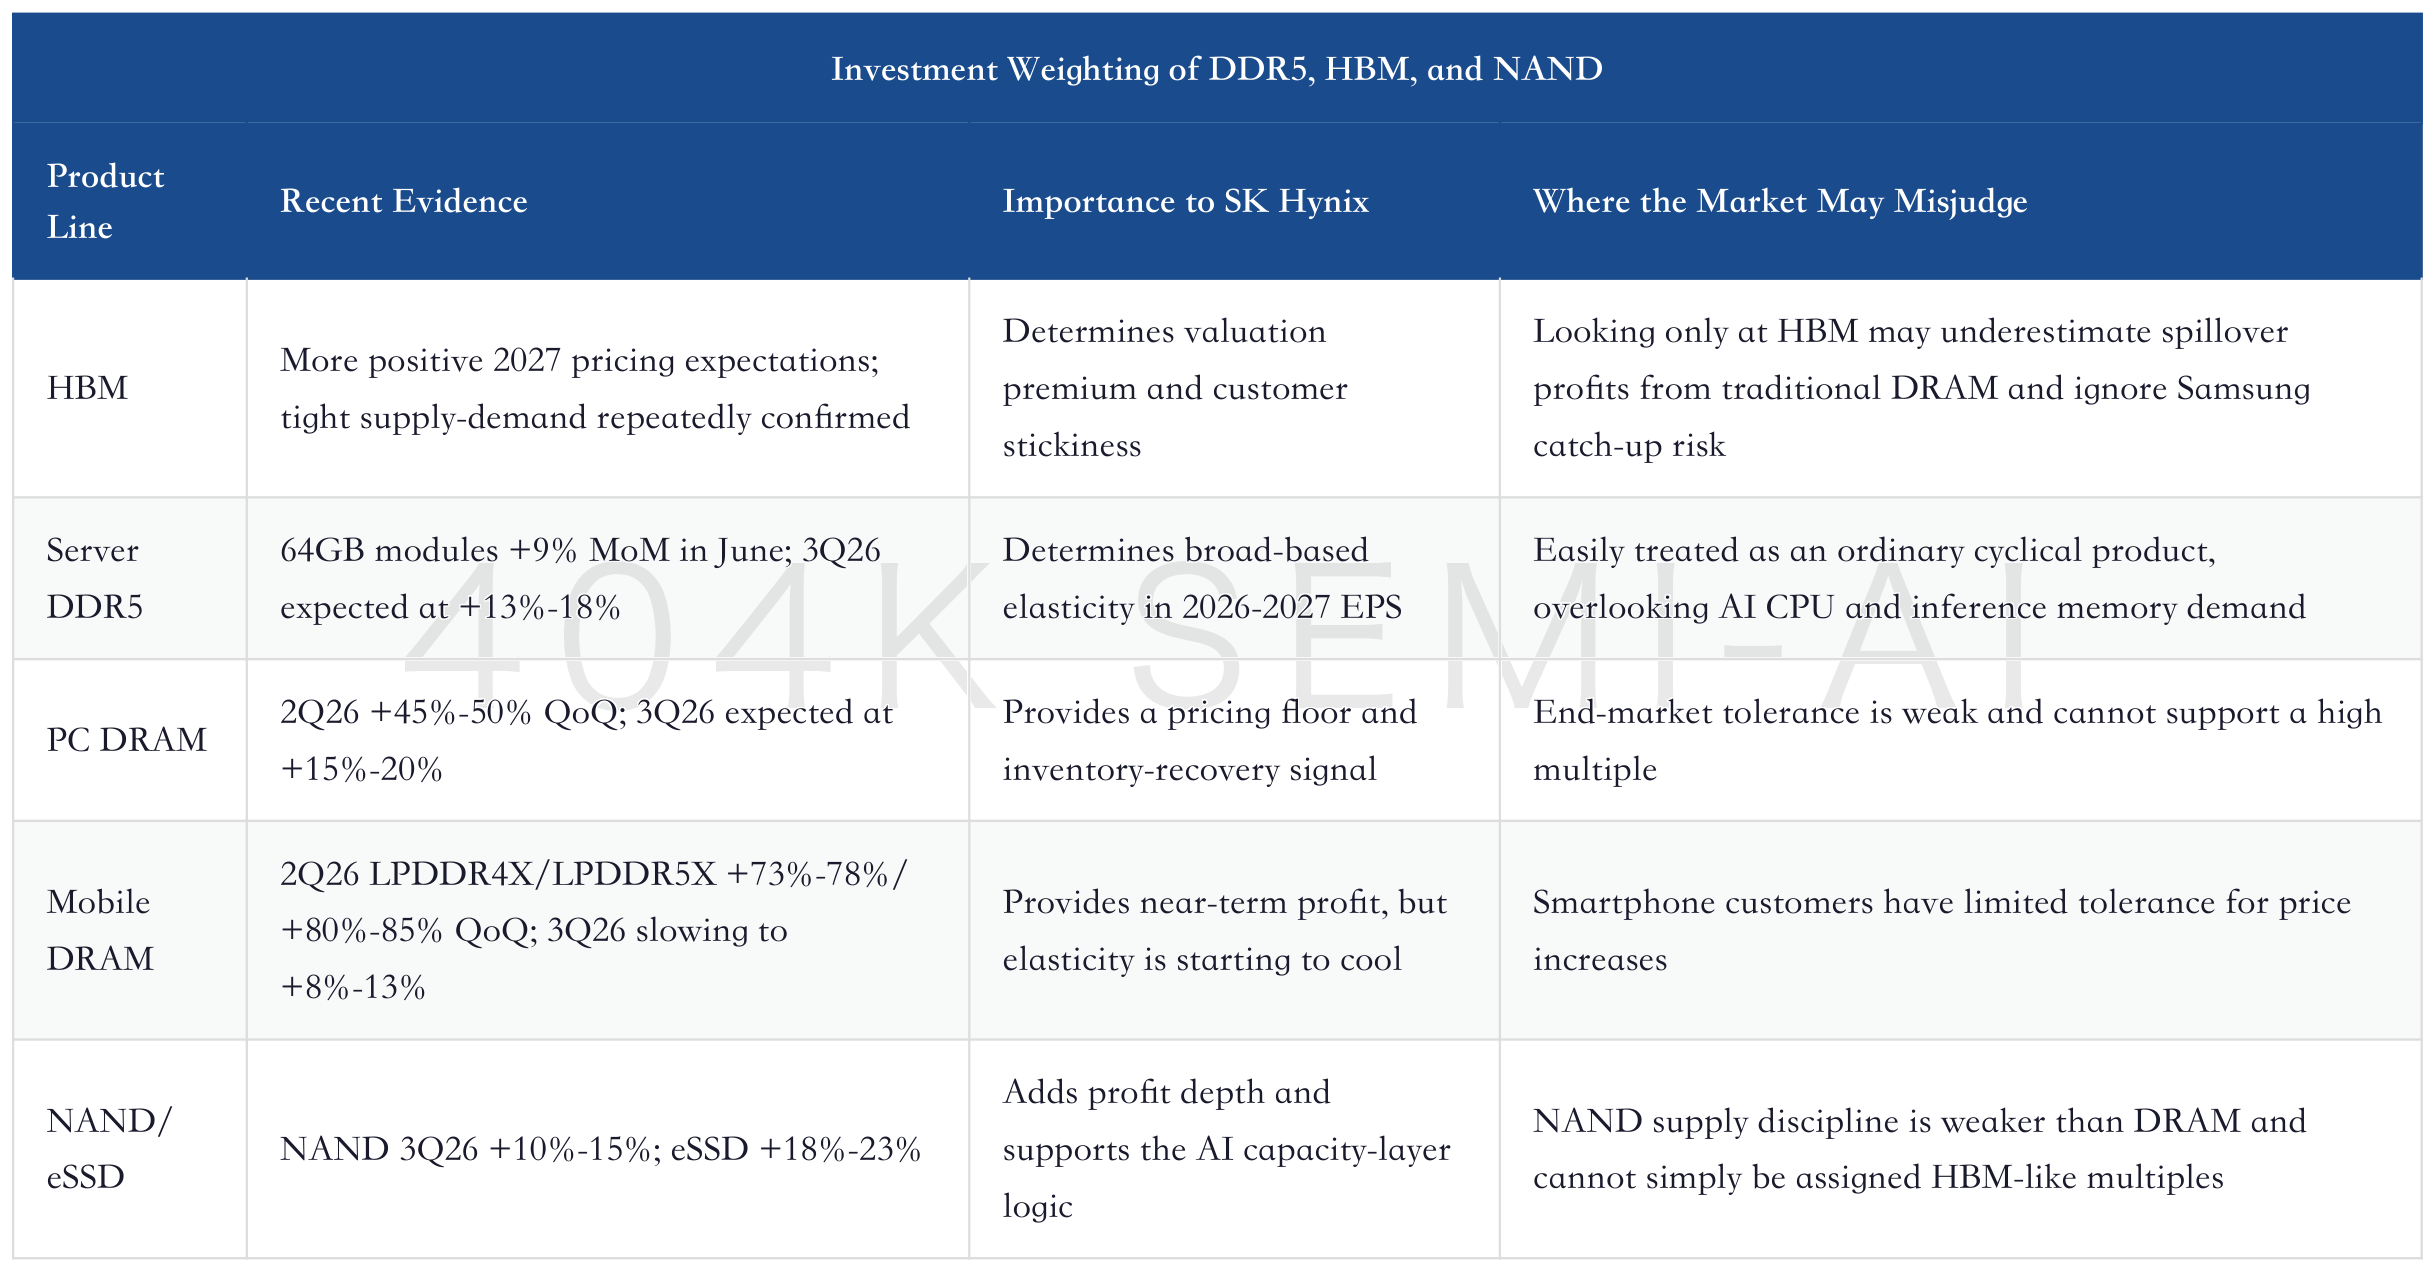
The significance of DDR5 is that it turns SK Hynix from an “HBM leader” into the holder of total AI server memory supply rights. If only HBM rises in 2026, the market will worry about single-customer, single-product, and single-technology-generation risk. If DDR5, high-capacity RDIMMs, server DRAM, and eSSD all rise together, SK Hynix’s profit sources become broader and its valuation logic becomes more stable.
This is also why this week’s upward revision to Samsung’s DRAM ASP is not bad news for SK Hynix. In its Samsung report, Citi raised its 4Q26 ASP forecast for 64GB DDR5 RDIMM from USD 1,586 to USD 1,805, and lifted its 2026 global DRAM/NAND ASP growth forecasts to 234%/236%. Samsung is SK Hynix’s competitor, but this kind of peer price revision proves the industry price level. SK Hynix enjoys higher quality through its HBM share, while Samsung benefits from catch-up and scale-driven elasticity. Together, they confirm that the AI memory price curve is still moving upward.
The Memory Tax Keeps Rising: Storage Prices May Surge Sequentially for Two Consecutive Quarters in the Second Half of This Year
IV. HBM: 2027 Pricing Expectations Are Improving, but Leadership Should Not Be Treated as Permanent Monopoly
HBM remains the highest-multiple layer of SK hynix’s valuation. DDR5 determines EPS; HBM determines the multiple. Among DRAM sentiment indicators over the past week, the most valuable signal is that investors have become more positive on 2027 HBM pricing: the price gap between commodity DRAM and HBM is widening, while HBM supply-demand remains tight, significantly improving 2027 HBM pricing expectations.
This matters because strong HBM in 2026 is no longer new information. What really affects the target price is 2027. If the market believes that after HBM3E, SK hynix can still remain the leading supplier in HBM4/HBM4E, and that 2027 pricing will not decline materially, valuation can roll from peak 2026 EPS toward 2027-2028 earnings. If the market believes Samsung and Micron will catch up and HBM premiums will compress rapidly, SK hynix will be treated as a cyclical stock again.
SK hynix’s advantages remain intact. It has been the most consistent HBM execution story over the past two years, with stronger customer relationships, yield, packaging, and delivery cadence. As discussed in prior deep-dive reports, HBM4 competition is not only about the DRAM die, but also the base die, packaging, power consumption, testing, customer roadmap coordination, and yield. Customers want stable suppliers that can deliver in line with Rubin, ASIC, and subsequent platform schedules.
But the risks are also clearer. Samsung is using stronger capex, DDR5 pricing flexibility, and improving HBM proxy indicators to prove it is catching up. Micron has U.S. supply-chain attributes and capital-market relevance. HBM4 competition will not be as one-sided as HBM3E, and customers will also actively diversify suppliers. SK hynix remains the highest-quality asset, but HBM leadership cannot be written as permanent monopoly.
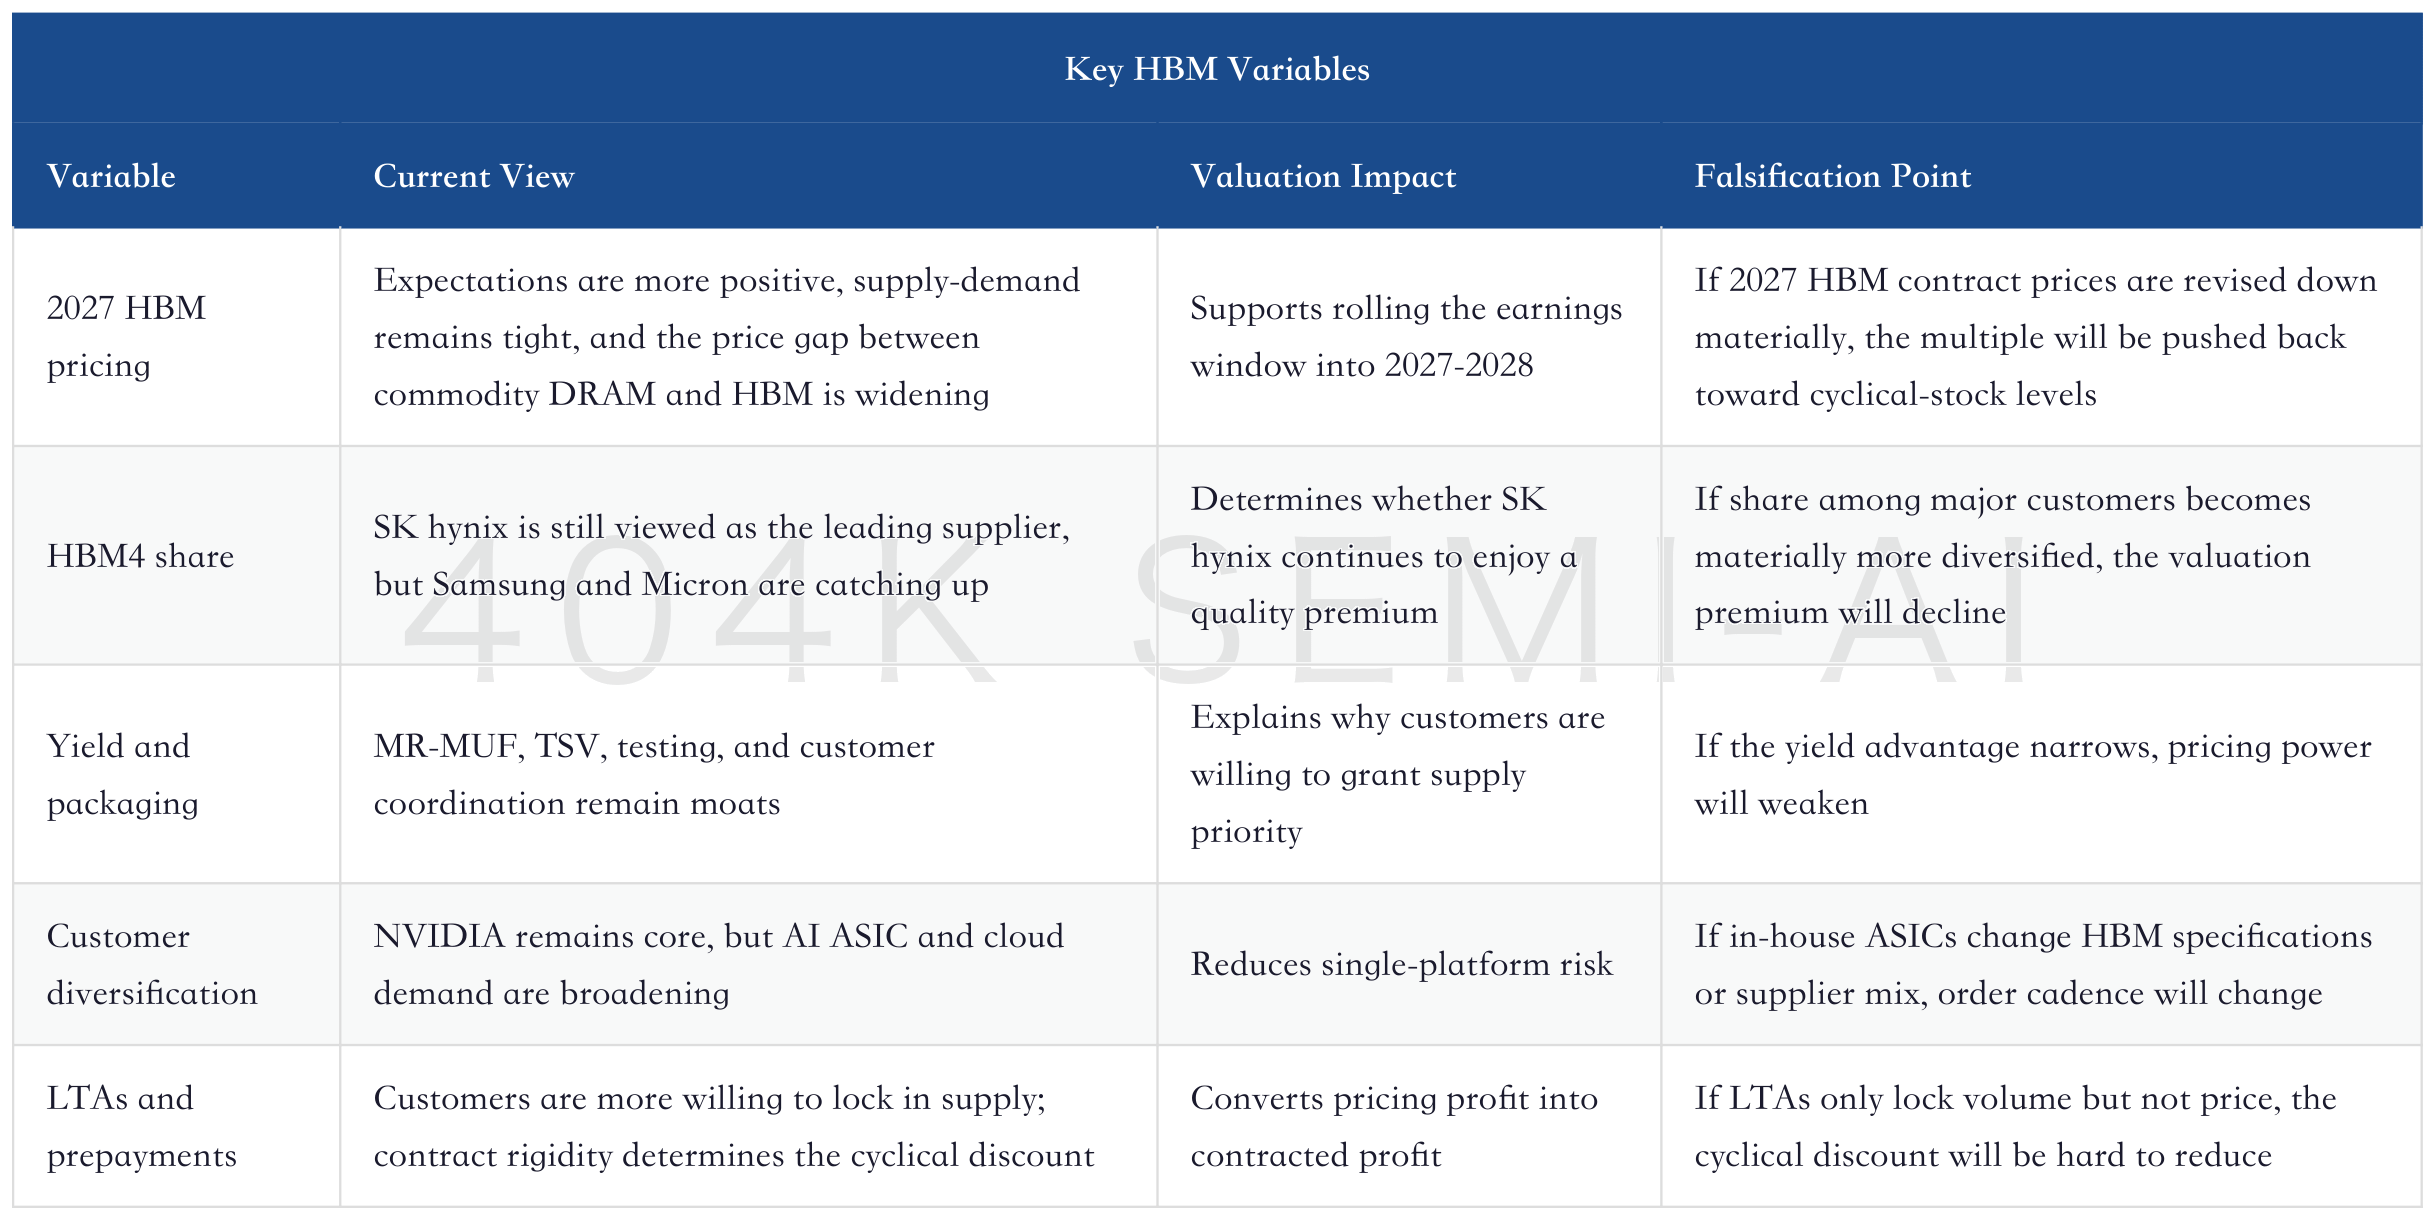
The HBM investment view can be simplified: SK hynix is a certainty trade, Samsung is a catch-up optionality trade, and Micron is a U.S. mapping and late-cycle growth trade. All three companies will benefit from AI memory shortages, but the market assigns SK hynix a higher quality premium because it has the best HBM purity and execution history. This premium can persist, but it needs HBM4 and 2027 pricing to keep extending the story.
AI Packaging Deep Dive: HBM4E Moves Toward 2.5TB/s, and How Bridge Interconnects, Vertical Power Delivery, and Thermal Paths Are Rewriting Hardware Competition
V. Korean Exports and KOSPI Pullback: Fundamentals Revised Up, Trading Layer Cools
Korean data show a very interesting combination: exports are strong, while share prices have pulled back. This explains SK hynix’s current trading setup. Fundamental evidence is strengthening, but positioning and valuation expectations are already crowded, so foreign outflows, the KOSPI pullback, and tech-stock volatility will amplify share-price beta.
In Korea’s June technology exports, memory was the brightest segment. Memory exports rose 280% YoY, DRAM rose 385% YoY, NAND chips rose 301% YoY, and SSDs rose 355% YoY. This is not a minor data point. It is macro export evidence validating earnings upgrades for SK hynix and Samsung. If price increases were only inventory speculation, export value would struggle to sustain this kind of strength for several consecutive months. If exports and prices are both strong, it means real procurement by overseas customers is also following through.
But KOSPI price action has not been smooth. Weekly reports show the KOSPI fell about 4% amid market volatility and foreign outflows, with forward P/E dropping to around 6.65x. Technology stocks were one of the main areas of foreign selling. More interestingly, earnings expectations did not weaken at the same time: KOSPI 12-month EPS was revised up 4.8%, while the technology sector was revised up 5.5%. This is a classic case of “fundamentals revised up, trading layer cooling.”
For SK hynix, this environment has two implications.
First, a pullback is not necessarily negative. As long as evidence from DDR5, HBM, exports, and LTAs remains intact, valuation compression improves risk-reward. When the market sells Korean technology stocks broadly, the highest-quality asset does not necessarily have the weakest fundamentals. It may simply be the most liquid and most profitable position to sell.
Second, crowding cannot be ignored. SK hynix is already one of the clearest and most direct AI memory trades. Once the market shifts from “prices continue to be revised up” to “expectations are too full,” it will be used first for profit-taking. High quality does not mean low volatility, especially after target prices have been revised up continuously and earnings expectations have risen sharply.
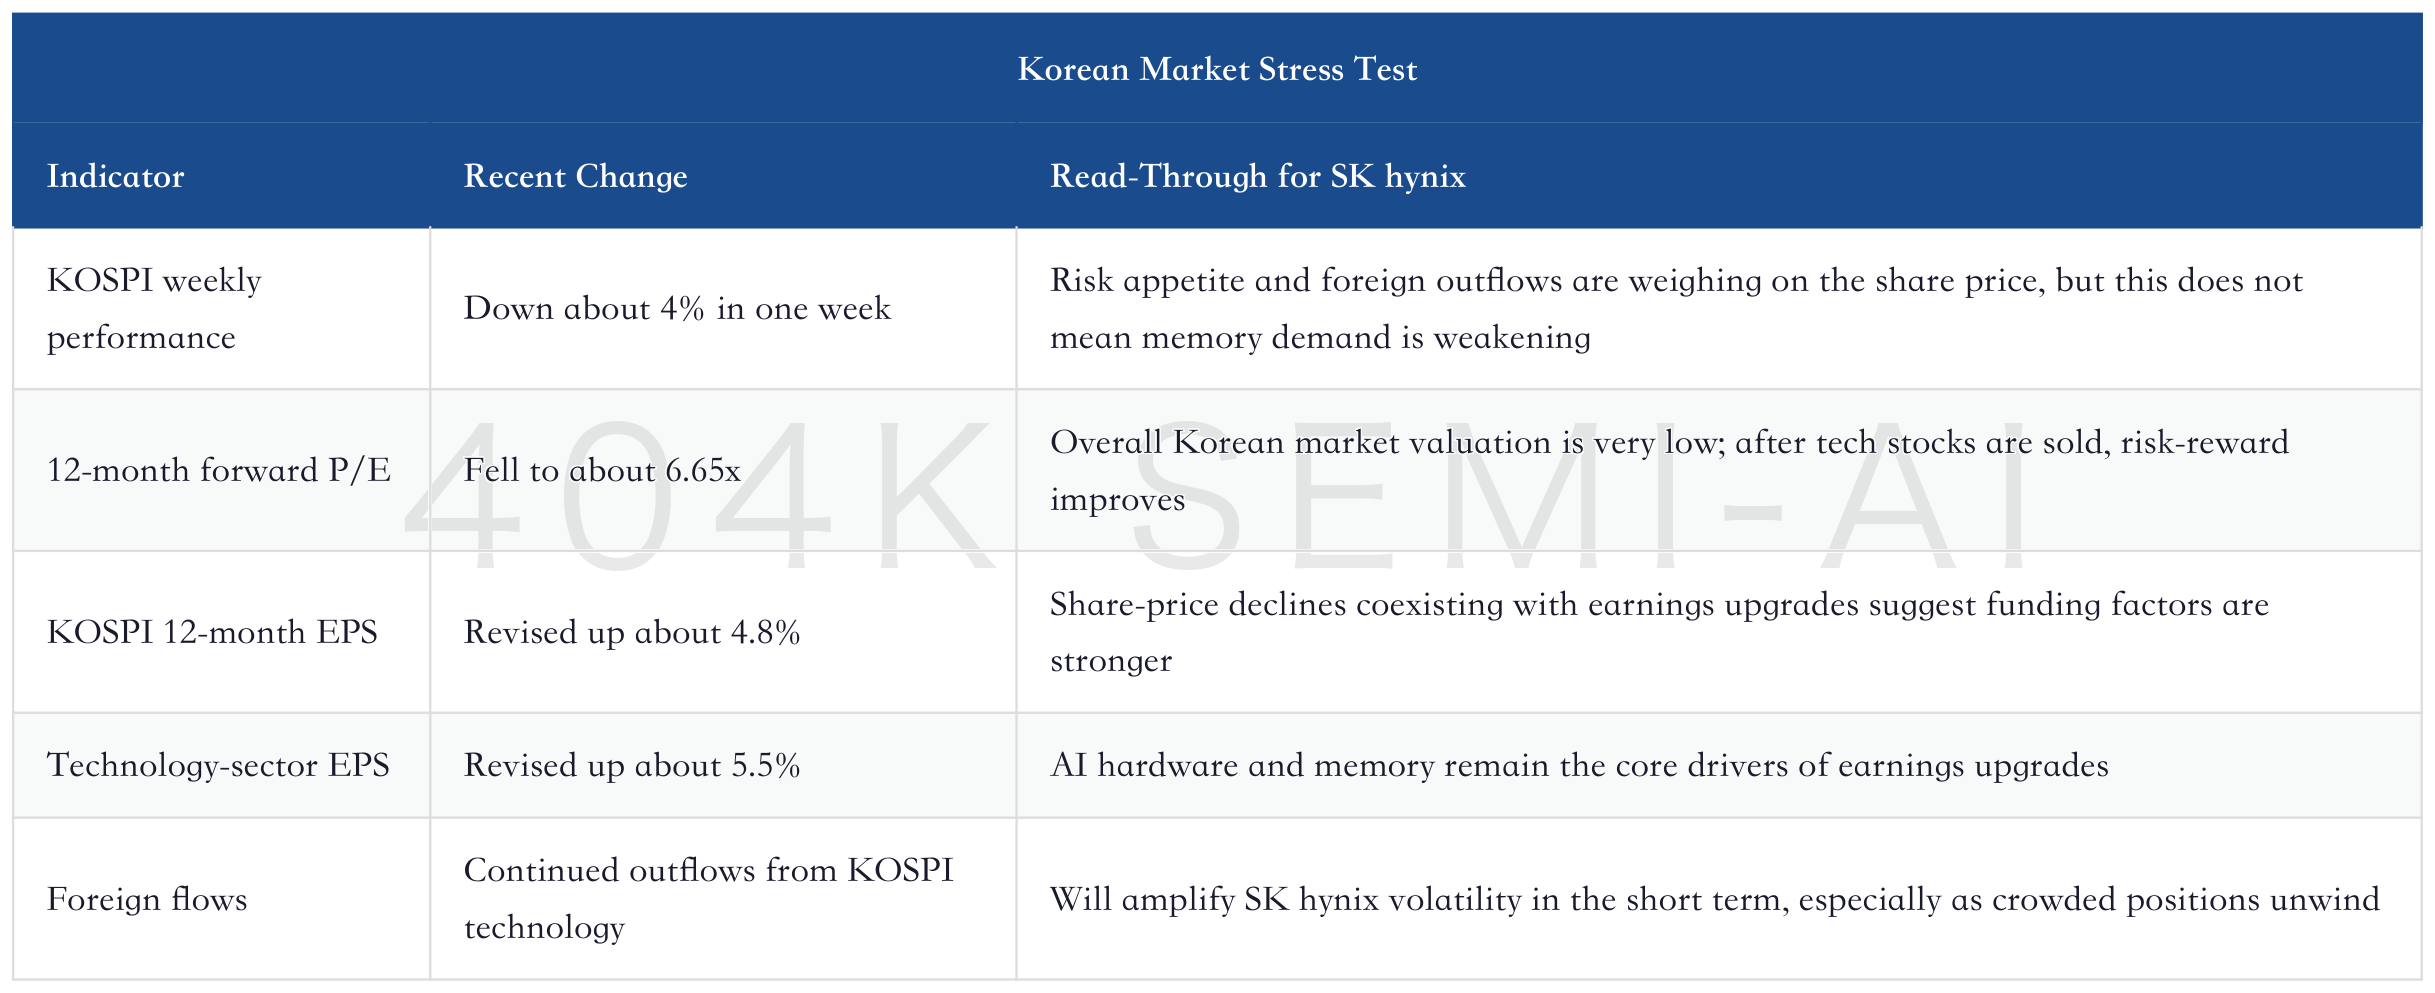
The conclusion from this stress test is: SK hynix can fall, but the logic should not be rejected simply because the stock has fallen. What really needs to be tracked is whether exports and contract prices are turning, whether HBM4 share is changing, and whether 2027 HBM pricing expectations are being revised down. If these have not deteriorated, the pullback is more trading-layer noise. If they start to deteriorate, low valuation will not save a cyclical stock.
Memory Deep-Dive Update: How Korea’s $3.1 Trillion AI Investment Plan Revalues DRAM, NAND, and the Equipment Chain
VI. Peer Ranking: Buy SK hynix for Certainty, Samsung for Catch-Up, Micron for U.S. Exposure, Kioxia for High NAND Beta
This memory upcycle should not be expressed through only one name, but SK hynix still has the clearest position. It is not the largest or the cheapest; it is the asset with the highest AI memory purity, the most stable HBM execution, and the most direct profit spillover from conventional DRAM.
Samsung’s appeal lies in catch-up beta. Upward revisions to server DRAM pricing, improving HBM proxy indicators, and stronger capex all show that Samsung is not a bystander. If Samsung gains more share in HBM4 and major customer qualifications, it could outperform SK hynix for a period, as the market shifts from a “laggard discount” to a “catch-up option.” But Samsung’s valuation is blended, with smartphones, foundry, display, and general consumer electronics diluting HBM purity.
Micron’s logic is U.S. mapping and broad-based price increases. It does not have SK hynix’s HBM purity, nor Samsung’s full industrial-group scale, but U.S. equity investors can express the AI memory cycle more easily through Micron. If U.S. AI capex continues to be revised upward, Micron will benefit from its role as a capital-access vehicle.
Kioxia and the NAND line are more like high-beta supplements. NAND chips and SSD exports have been very strong over the past week, and eSSD pricing expectations are also strong, but NAND’s supply discipline and competitive structure are weaker than DRAM/HBM. Kioxia has high upside beta and high risk. It is suitable for expressing extreme NAND supply-demand tightness, but not as a substitute for HBM certainty.
