
SK Hynix ADR Listing: 2.5% Quota, 5-10% Premium, and Index-Flow Timing
目录
1. This Listing Mainly Changes the Trading Gateway
2. The 5-10% Premium Comes from Quota, Time Zone, and Trading Tools
3. The Conversion Mechanism Determines Whether the Premium Can Hold
4. Index Flows Are More Realistic Than Nasdaq-100 Inclusion
5. This Event Amplifies Fundamentals, but Earnings Still Depend on HBM and DRAM
6. The Main Risks Are Premium Compression and Cooling Memory Sentiment
7. Three Scenarios for the ADR Premium
8. How to Understand This Event
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
SK Hynix’s decision to list its ADRs on Nasdaq mainly affects trading access and fund structure in the near term: the 2.5% initial quota limits supply, while U.S. investors, ETFs, and the options ecosystem increase premium elasticity and may also amplify early trading volatility. The earnings view still comes back to HBM deliveries, DRAM pricing, and capital-expenditure discipline.
1. This Listing Mainly Changes the Trading Gateway
SK Hynix plans to list ADRs on Nasdaq under the proposed ticker SKHY. The timetable in the materials is clear: roadshow begins on July 6, pricing is expected on July 9, trading is expected to start on July 10, settlement is expected around July 14, and newly issued common shares are expected to list on the Korea Exchange on July 29.
This is more of a trading-structure event than a standard exchange-transfer listing. SK Hynix already has London GDRs and Korea-listed common shares. The new element is the U.S. ADR channel. The problem it solves is straightforward: some U.S. institutions cannot easily buy Korea-listed shares, or do not want to deal with KRW, time zones, Korean brokers, and local settlement. After the ADR listing, these investors can trade SK Hynix in U.S. hours in U.S. dollars.
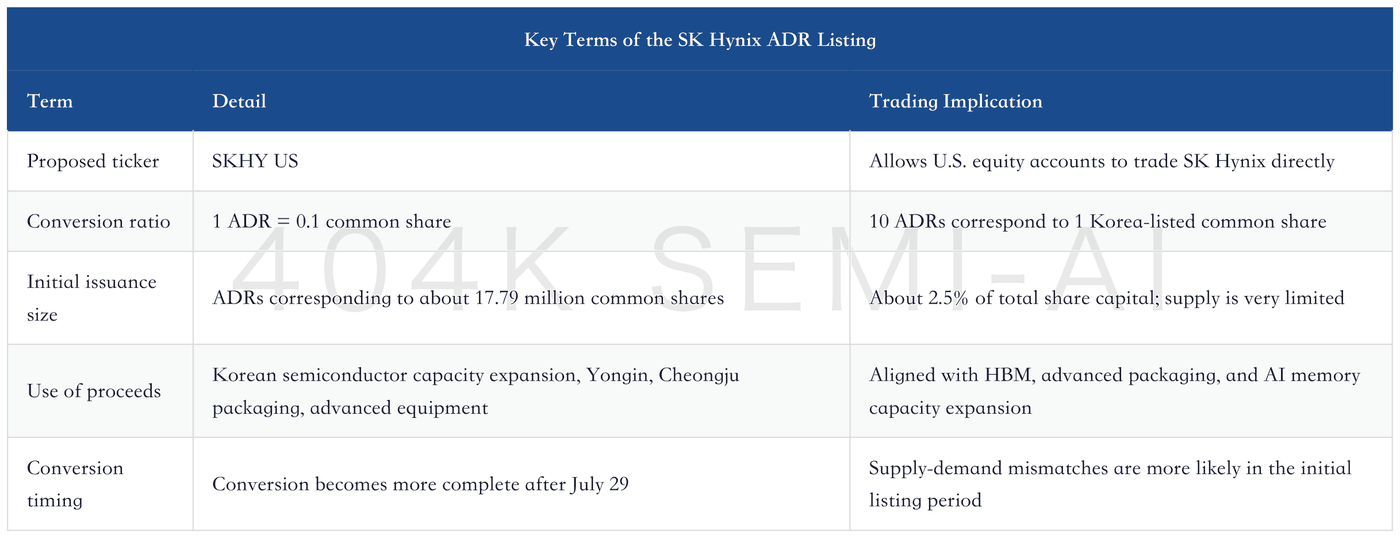
The most important number here is 2.5%. If the ADR were merely another fully fungible trading line, its price would be unlikely to deviate from the Korean common share price for long. But the underlying shares corresponding to the initial ADRs account for only about 2.5% of total share capital, meaning tradable float on the U.S. side starts out limited. If U.S. investors buy aggressively, the price will reflect not only fundamentals but also whether there is enough supply in the U.S. trading line.
2. The 5-10% Premium Comes from Quota, Time Zone, and Trading Tools
The judgment in the materials most likely to attract market attention is that SK Hynix ADRs may trade at a 5-10% premium to the Korea-listed common shares. This is based on market microstructure and has little to do with upward earnings revisions.
First, ADR supply is limited. The initial ADR quota is about 2.5% of total share capital and is likely to be fully used at listing. Later, if investors want to convert Korea-listed common shares into ADRs, the process will be constrained by issuance quota, depositary mechanics, and Korean local rules. It cannot be understood simply as “as long as there are common shares, ADRs can be created freely.” The more rigid the supply side, the easier it is for U.S.-side demand to push prices higher.
Second, U.S.-side demand is more concentrated. Many global technology funds, semiconductor ETFs, quant funds, and options traders are more accustomed to operating in the U.S. market. SK Hynix has been one of the clearest HBM beneficiaries in the AI memory chain, but its main trading gateway has been Korea. This ADR listing puts the stock inside the U.S. trading system, lowering the cost of holding, hedging, and portfolio management.
Third, there will be more trading tools. The materials note that 2x long and 2x short leveraged ETFs linked to SK Hynix ADRs are expected to launch around July 13. If options are also listed smoothly later, long, short, hedge, and volatility trades will all become easier. The more tools there are, the more active short-term turnover may become, and the easier it is for single-day fund flows to be amplified.
This is also why MS estimates that the ADR channel could account for 10-20% of combined SK Hynix local and ADR trading volume in the coming months. That share is not exaggerated. Foreign investors already contribute about 29.7% of Korea-listed trading volume. If part of that U.S. capital migrates to ADRs, a 10-20% trading-volume share has a realistic basis.
3. The Conversion Mechanism Determines Whether the Premium Can Hold
Whether the ADR premium can hold depends on whether conversion is sufficiently smooth. The materials’ judgment is that converting ADRs back into Korean common shares is relatively smooth, while converting Korean common shares into ADRs is constrained by the 2.5% quota. This structure slows arbitrage.
Normally, if ADRs become too expensive, arbitrage capital can buy Korean common shares, convert them into ADRs, and sell the ADRs, compressing the spread. The difficulty for SK Hynix this time is that common-share-to-ADR conversion has a clear quota limit. Once the initial quota is fully used, new ADRs require existing ADR holders to cancel and convert back into local common shares before quota is freed up. This mechanism turns arbitrage from a mechanical trade into a question of whether quota is available.
The materials also caution that the theoretical ADS capacity in the SEC Form F-6 registration statement should not be treated directly as the actual convertible quota. A more practical metric is the quota shown by KSD and other depositary and local registration systems. Investors who look only at the registration ceiling may overestimate the elasticity of future ADR supply.
This constraint also explains why TSMC ADRs can trade at a premium for years. TSMC’s U.S. ADR liquidity is strong, ADR trading volume consistently accounts for roughly 50-60%, and the premium has often stayed in the double digits in recent years. SK Hynix has not yet reached TSMC’s level of global liquidity, but it has one similar feature: strong U.S.-side demand and an institutional cap on ADR supply.
The differences also need to be clear. TSMC is a long-term global core asset, and its ADRs have accumulated years of liquidity and index-allocation habits. SK Hynix ADRs are newly listed, so the initial premium may be more affected by event trades, tight float, and semiconductor sentiment. If U.S. demand is strong, the premium can spike; if the memory trade cools, the premium can also fall quickly.
4. Index Flows Are More Realistic Than Nasdaq-100 Inclusion
This ADR listing also has a fund-flow implication: it affects both the Korean local line and the U.S. ADR line. The materials break potential index changes into relatively fine detail. The actual impact can be grouped into three categories.
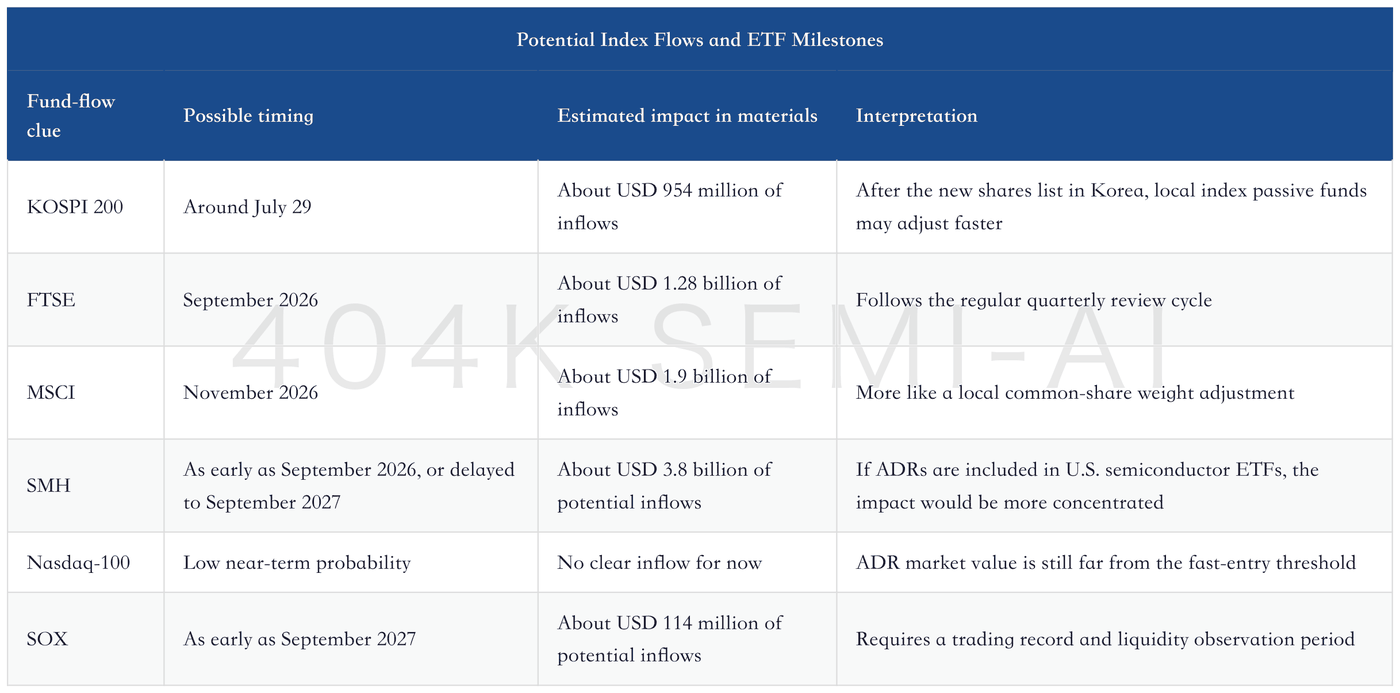
The most important node to watch is SMH. Nasdaq-100 has market-cap and listing-duration requirements. The materials estimate SK Hynix ADR value at about USD 30 billion, still well below the fast-entry threshold. A semiconductor ETF such as SMH is closer to actual trading demand. If the ADR is later included, it could directly make SK Hynix a regular holding in U.S. semiconductor portfolios.
The local line also cannot be ignored. Fund flows from KOSPI 200, FTSE, and MSCI adjustments are more passive-allocation oriented, with the impact mainly landing in the Korea-listed common shares. They may not necessarily lift the ADR premium, but they support liquidity and the valuation anchor for the underlying common shares. However high the ADR premium becomes, it ultimately has to return to the fundamental price of the local common shares.
The time window can be divided into three stages. The first is from the July 10 open to July 14 settlement, when the focus is the initial ADR pricing, trading-volume share, and immediate premium to the local common shares. The second is after the July 29 Korean new-share listing, when the focus is conversion, KOSPI 200 adjustment, and whether arbitrage capital starts compressing the spread. The third is September to November, when the focus is whether expectations related to FTSE, MSCI, and SMH materialize. The three windows correspond respectively to first-day supply-demand, the conversion mechanism, and passive flows. Combining them too loosely can lead to misjudgment. This is also the clearest trading calendar for tracking SKHY going forward; the timeline itself is the tracking framework.
5. This Event Amplifies Fundamentals, but Earnings Still Depend on HBM and DRAM
The ADR listing will not directly increase SK Hynix’s HBM shipments, nor will it directly change DRAM prices. But it will change how capital prices SK Hynix.
SK Hynix’s largest fundamental variable remains HBM. AI GPUs and ASICs continue to drive demand for high-bandwidth memory, and the company is in a strong position in HBM supply, customer relationships, and delivery cadence. The ADR listing puts this fundamental story into the U.S. semiconductor capital pool, allowing U.S. investors to express their view on the HBM cycle in a more familiar way.
The use of proceeds also has fundamental meaning. The materials note that proceeds will be used for Korean semiconductor expansion, including the Yongin project, Cheongju packaging, and advanced equipment. These directions align with the AI memory supply chain. They are more like long-term capacity and technology investments and will not immediately become profits in the short term, but they can reinforce market attention on the company’s capacity-expansion capability and high-end memory roadmap.
