
SK hynix 2Q26 Earnings Deep Dive: Revenue and Profit Miss Market Expectations, Driving a Further Sharp After-Hours Selloff in Memory Stocks — KRW60.5 Trillion Profit, Early HBM4 Shipments and LTA Contractualization
目录
TL;DR
I. Strip the Numbers Down First: Operating Results Were Very Strong, but Net Income Is Not the Focus
II. Did These Results Actually Beat Expectations? Earnings Broadly Delivered, While Product Progress Was Better
III. DRAM and NAND Revenue Bridge: Pricing Drove Most of This Cycle’s Profit Growth
IV. HBM4 Is the Most Tangible Incremental Positive in This Earnings Report: From Qualification Narrative to Actual Shipments
V. Why Approximately 10 LTAs Matter: The Cyclical-Stock Discount Has Its First Verifiable Contractual Anchor
VI. Cash Flow and Balance Sheet: Strong Expansion Capacity, but Profit-to-Cash Conversion Still Requires Segmentation
VII. Capital Expenditure: The High End of the KRW 40 Trillion Range Reflects Both Order Confidence and the Next Supply Risk
VIII. What Valuation Should Focus On: Separate One-Off Gains, Shortage-Driven Profits, and Structural Profits
IX. Five Key Questions for the Next Two Quarters
X. Conclusion: Not a “Net-Income Myth,” but a New Earnings Baseline Entering the Contract and Product Validation Phase
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This is not an earnings report that delivers a surprise through the net-income figure. What truly deserves a re-rating is that SK hynix has simultaneously embedded pricing power, HBM4 execution and customer supply-lock mechanisms into its operating results.
TL;DR
SK hynix reported 2Q26 revenue of KRW79.319 trillion and operating profit of KRW60.543 trillion, up 51% and 61% QoQ, respectively, with the operating margin rising to 76%. Actual operating profit was close to the cautious pre-earnings forecast of KRW60.4 trillion and did not meaningfully exceed the consensus reference of approximately KRW65 trillion. Core operating execution was very strong, but this was not an unequivocal major beat.
Net income of KRW93.923 trillion and a net margin of 118% cannot be annualized. The company disclosed KRW62.166 trillion in non-operating income, including KRW63.27 trillion in investment-asset-related gains. Earnings quality should be assessed based on KRW60.543 trillion in operating profit and KRW65.71 trillion in operating cash flow, rather than net income inflated by one-off gains.
The largest positive increment is that HBM4 shipments already began in 2Q, with a full ramp planned for 2H. The previous cautious model had assumed that formal sales contributions would begin in 3Q. HBM4E samples were already delivered to one major customer in 1H, while 1cnm SOCAMM2 is now in full supply. Product execution is ahead of the market’s most conservative expectations.
The company completed negotiations for approximately 10 long-term agreements (LTAs) and, for the first time, explicitly mentioned pricing structures designed to address price volatility and financial mechanisms such as deposits to support contract performance. LTAs have advanced from a “volume-lock story” toward contracts with financial constraints, but the duration, price floors and deposit amounts were not disclosed, leaving the company far from proving that the cycle has disappeared.
2026 capital expenditure will reach the upper end of the KRW40 trillion range, M15X mass production has been brought forward, and capacity expansion at Yongin FAB1 will accelerate in early 2027. Net cash of KRW69.371 trillion provides a buffer for expansion, but 3Q bit-shipment growth is already normalizing. Further earnings upgrades will therefore need to rely more on pricing, product mix and contract quality than on indefinitely accelerating shipments.
I. Strip the Numbers Down First: Operating Results Were Very Strong, but Net Income Is Not the Focus
SK hynix’s headline 2Q26 figures are extraordinary: revenue was KRW79.319 trillion, up 51% QoQ and 257% YoY; operating profit was KRW60.543 trillion, up 61% QoQ and 557% YoY; and net income was KRW93.923 trillion, up 133% QoQ and 1,242% YoY. Looking only at the bottom line, the net margin reached 118%, seemingly implying that the company earned KRW118 for every KRW100 of products sold.
Clearly, this cannot be explained through the normal economics of manufacturing.
The company clearly explained the reason in its official materials. Non-operating income for the period was KRW62.166 trillion, including KRW60.889 trillion in other non-operating income, which contained KRW63.27 trillion in investment-asset-related gains. There was also KRW1.147 trillion in foreign-exchange-related gains. After deducting KRW28.786 trillion in income-tax expense, net income was KRW93.923 trillion.
This earnings report must therefore be viewed in two layers.
The first layer is core operations: KRW79.319 trillion in revenue, KRW65.991 trillion in gross profit and KRW60.543 trillion in operating profit, representing a 76% operating margin. These results were jointly driven by higher memory pricing, a higher-value product mix and cost improvements.
The second layer comprises asset-related and accounting gains: KRW63.27 trillion in investment-asset-related gains lifted pre-tax profit to KRW122.708 trillion and pushed net income above operating profit. The company has not disclosed the specific assets or complete accounting notes in these preliminary materials. It therefore would be inappropriate to attribute the gain to any particular equity holding or treat it as profit that will recur next quarter.
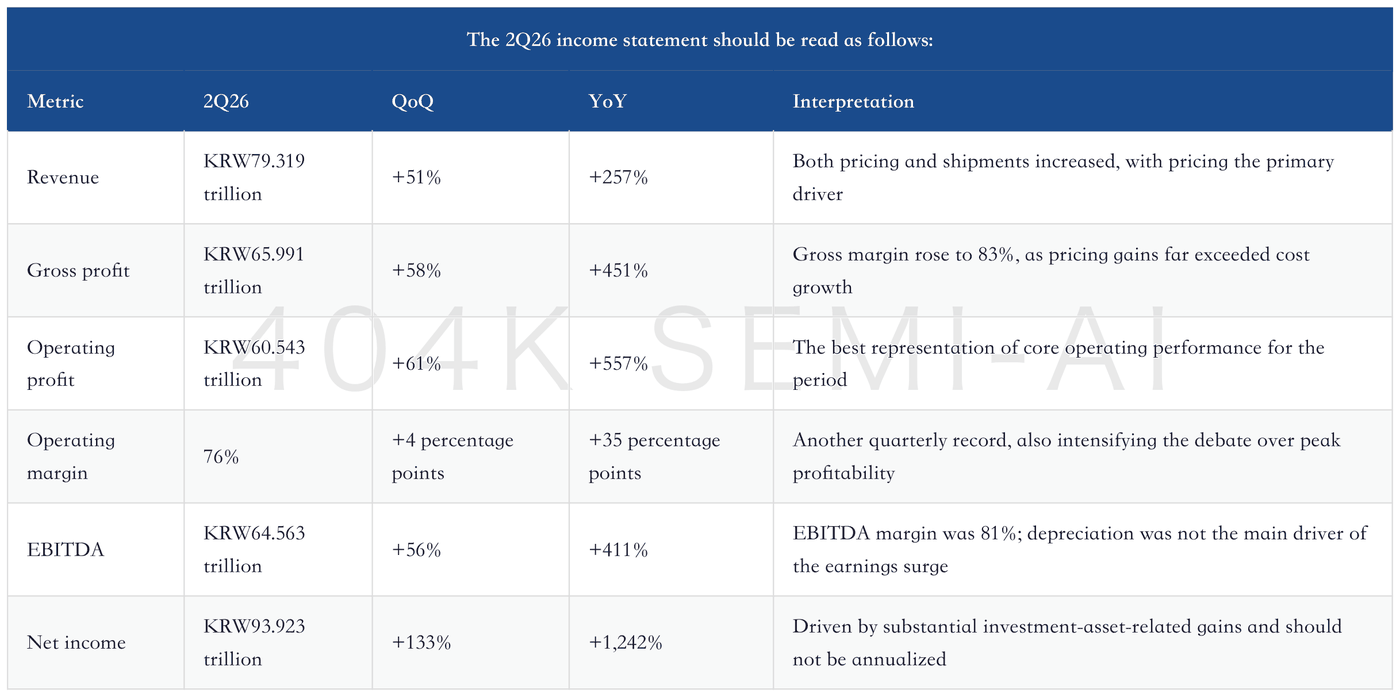
Revenue increased 51%, while cost of sales rose only 22% and selling and administrative expenses increased 34%. This relationship matters more than net income: the company did not manufacture profits by cutting R&D;, marketing or maintenance spending. Instead, gains from revenue pricing and product mix flowed through the cost structure. Gross margin increased from 79% in 1Q26 to 83%, while operating margin rose from 72% to 76%, indicating that the incremental margin in 2Q remained above the average margin.
However, a 76% operating margin is also a risk signal. The memory industry has rarely sustained such high profitability for long. The market will no longer ask only whether growth can continue in 3Q; it will ask how much of the profit comes from temporary shortages and how much can be retained through HBM4, LTAs and high-end products.
II. Did These Results Actually Beat Expectations? Earnings Broadly Delivered, While Product Progress Was Better
The market was already clearly divided ahead of the earnings release. A more cautious institutional model forecast 2Q26 revenue of KRW80.9 trillion and operating profit of KRW60.4 trillion, while the consensus reference at the time was approximately KRW65 trillion in operating profit. Actual revenue of KRW79.319 trillion was slightly below the cautious model, while actual operating profit of KRW60.543 trillion landed almost exactly in line with the KRW60.4 trillion forecast.
Accordingly, judged by operating profit, this was not a “major earnings beat” in the traditional sense. It was closer to a high-quality delivery: the market already knew that memory pricing was strong and margins were high, and the company delivered results close to cautious expectations but below the most optimistic consensus reference.
However, comparing only the profit figures would still understate the significance of this report. A key concern in the previous conservative model was that HBM4 would not begin making a formal sales contribution until 3Q. The company’s latest disclosure instead indicates that HBM4 shipments already began in 2Q, with a full ramp planned for 2H. The pace at which the product met customer requirements, including power efficiency and cost competitiveness, also met the company’s targets.
This means that 2Q contained an important “structural beat”: profit did not materially exceed elevated expectations, but HBM4 execution was faster than assumed in the cautious model.
Earnings Delivery Fell Short of Elevated Expectations, but Product and Contract Progress Was Faster
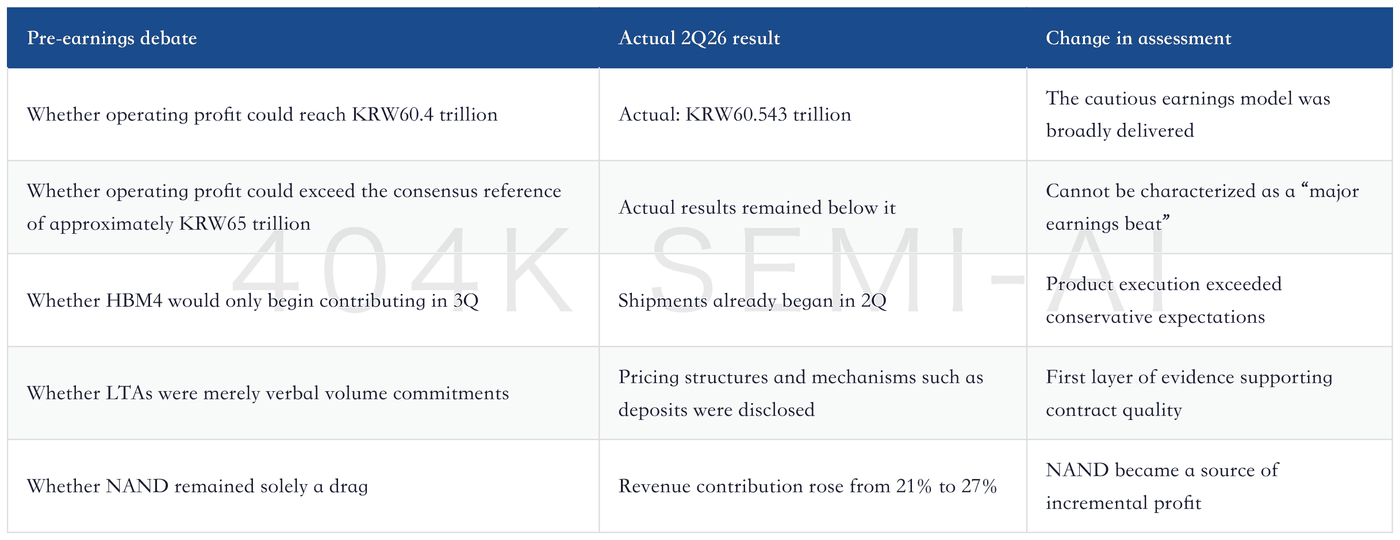
This is why the most accurate characterization of the earnings report is not “explosive profit,” but “operating delivery, accelerated product execution and firmer contracts.”
Whether profit exceeds a particular quarterly forecast affects only short-term trading. Early HBM4 shipments and the introduction of financial constraints into LTAs affect the appropriate cyclical discount on earnings from 2027 onward. The former is a numerical variance; the latter changes the language of valuation.
III. DRAM and NAND Revenue Bridge: Pricing Drove Most of This Cycle’s Profit Growth
The key driver of 2Q26 revenue growth was not a sudden, uncontrolled expansion in bit shipments, but another sharp increase in average selling prices.
DRAM bit shipments grew by a high-single-digit percentage QoQ, while average selling prices rose by approximately 30%; NAND bit shipments grew by a mid-teens percentage QoQ, while average selling prices increased by a mid-50% percentage. Together, these factors lifted revenue from KRW52.576 trillion in 1Q26 to KRW79.319 trillion.
