
Semiconductor Momentum Trade Fades: Morgan Stanley Sees Not the End of AI, but CapEx Return Pressure Coming to the Table
目录
Too Long; Didn’t Read
I. What This Weekly Report Is Really About: A Shift in the AI Trade
II. Why Semiconductors Lagged First: Customers Are Strong, Suppliers Were Stronger, and the Divergence Needed Repair
III. Why Meta Became the Trigger: Compute Leasing Brings CapEx Back Onto the Operating Ledger
IV. Why This Is “Not the End of the Cycle”: AI Hardware Will Go Through Multiple Resets
V. Why Memory Looks Most Like Silver Stocks: Strong Fundamentals, but the Most Violent Share-Price Volatility
VI. Why Hyperscalers Are Preferred in the Short Term: They Have Already Paid for CapEx Pressure
VII. Why Market Broadening Is Happening at the Same Time: Oil Prices, Rates, and Semiconductor Weightings Are All Loosening
VIII. What This Report Means for the Investment Framework: Semiconductors Are No Longer Just About Demand, but Customer Returns
IX. Translating “Momentum Deceleration” Into Trading Language: Growth Has Not Disappeared, but the Second Derivative Has Deteriorated
X. The Core Tension in AI CapEx: Orders Are Supply-Chain Revenue, Depreciation Is Customer Cost
XI. Memory Is the Most Sensitive Branch: It Has Both AI Logic and a Commodity Cycle
XII. Why Hyperscalers Have a Relative Advantage: From Cost Bearers to Return Provers
XIII. Market Broadening Is Not a Side Issue: It Determines the Damage from a Semiconductor Pullback
XIV. Three Worldviews: Where the AI Trade Goes Next
XV. Segment Ranking: From “Who Gets Orders” to “Who Can Survive the Return-Validation Period”
XVI. How Valuation Changes: From “Order Multiples” Back to “Discounted Cash Flow”
XVII. When to Buy Semiconductors Again: Not When the Drawdown Is Large Enough, but When the Evidence Lines Up Again
XVIII. The Easiest Mistake: Mixing Up Industry Direction, Earnings Direction, and Share-Price Direction
XIX. Risks and Falsification: What Changes Would Overturn This View
20. Portfolio Action: Shift from Pure AI Beta to “Customer Returns Plus Supply Bottlenecks”
21. Investment Conclusion: The AI Theme Has Entered Stage Two; Semiconductors Need to Shift from Beta Back to Stock and Segment Selection
22. Follow-Up Indicators
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The core of this semiconductor pullback is that the market has started to discount “continued acceleration in capital spending.” Morgan Stanley’s weekly report lays out the tension clearly: the AI cycle is still intact, but the semiconductor trade has moved from order upgrades to a peak in the second derivative. The next phase depends on hyperscaler cash flow, compute utilization, and whether broadening sectors can take over.
Too Long; Didn’t Read
Semiconductors are trading the second derivative. AI capital spending remains high, and hyperscalers have not stopped building, but semiconductor stocks had been pricing in “upgrades on top of upgrades.” When EPS revision breadth is near historical highs, the market will trade a slowdown in the pace of upgrades before waiting for actual earnings downgrades.
The AI cycle is still expanding. Morgan Stanley defines the current pullback as the fourth reset within the AI cycle; the prior three did not interrupt infrastructure build-out either. What has changed is that the market no longer rewards supply chains only for winning orders. It is also asking hyperscalers to prove that every $1 of CapEx can translate into revenue, gross profit, and free cash flow.
Meta was the trigger. Meta said it may sell excess compute capacity to external customers. This forced the market to revisit an old question: is AI compute a scarce asset, or have some hyperscalers built too quickly and are now looking for outlets? This does not mean demand has peaked, but it shifts semiconductor valuation from “customers keep spending” to “can customers make money after spending?”
Memory is the most vulnerable to adjusting first. Morgan Stanley compares semiconductor stocks to silver stocks because both have gone through parabolic rallies and both have commodity attributes. Memory is the most commoditized segment in semiconductors. Price increases and long-term contracts can support fundamentals, but share prices are most exposed to volatility amplified by a peak in the price-increase slope and crowded positioning.
Hyperscalers look better than semiconductors in the near term. Morgan Stanley prefers hyperscalers because they have already fallen over the past several months, CapEx pressure is partly priced in, and they still have optionality from the application layer, cost reductions, and compute leasing. Semiconductors need customers to keep accelerating spending; hyperscalers have a chance to prove those investments can be recovered.
Broadening is the second main trade. Lower oil prices, cooler rate expectations, and weaker employment data have led the market to buy laggards such as consumer goods, transportation, regional banks, and biotech. Semiconductor weakness itself is also relieving index-weight pressure, with capital rotating from leading AI hardware names into a broader set of earnings-recovery assets.
Watch five signals from here. First, hyperscaler 2027 CapEx guidance; second, compute leasing prices; third, DRAM/NAND contract prices and long-term agreements; fourth, whether semiconductor EPS revision breadth rolls over; fifth, whether equal-weight indexes, transportation, biotech, and consumer goods can keep outperforming.
I. What This Weekly Report Is Really About: A Shift in the AI Trade
The two most important words in Morgan Stanley’s weekly report title are “broadening” and “momentum.” The former refers to market gains starting to broaden; the latter refers to fading momentum in the semiconductor trade. Put together, they capture the core of the report: the AI story is still alive, but the semiconductor trade has become overly concentrated, and the market needs a new leadership structure.
Over the past few months, the cleanest narrative in the AI hardware chain was “hyperscaler capital spending continues to be revised up, and semiconductor supply chains continue to win orders.” That narrative has not failed, but its marginal payoff is declining. Share prices care not only about direction, but also speed. Semiconductors are strongest when CapEx is being revised up from a low base to a high level. Once the market starts asking whether spending can keep accelerating, the trade enters a more selective phase.
Morgan Stanley explains this shift through EPS revisions breadth. Think of it as the breadth of analysts raising earnings forecasts. When more and more companies in a sector see upward revisions, share prices usually reflect good news in advance. When revision breadth approaches elevated levels, it becomes harder to keep beating expectations. That is the problem semiconductors face now: fundamentals are still strong, but the market has already priced in “very strong.”
The AI Trade Has Moved Ahead of Macro: Recalibrating Compute CapEx, Earnings Expectations, and Market Pricing
This is consistent with the structure of the AI trade since 2026. The first phase was buying Nvidia, memory, advanced packaging, PCBs, equipment, and power because supply bottlenecks were clear and order visibility was high. The second phase depends on customer returns, meaning whether hyperscalers, model companies, and enterprise customers can turn compute into cash flow. Morgan Stanley’s weekly report brings that second-phase question to the foreground.
II. Why Semiconductors Lagged First: Customers Are Strong, Suppliers Were Stronger, and the Divergence Needed Repair
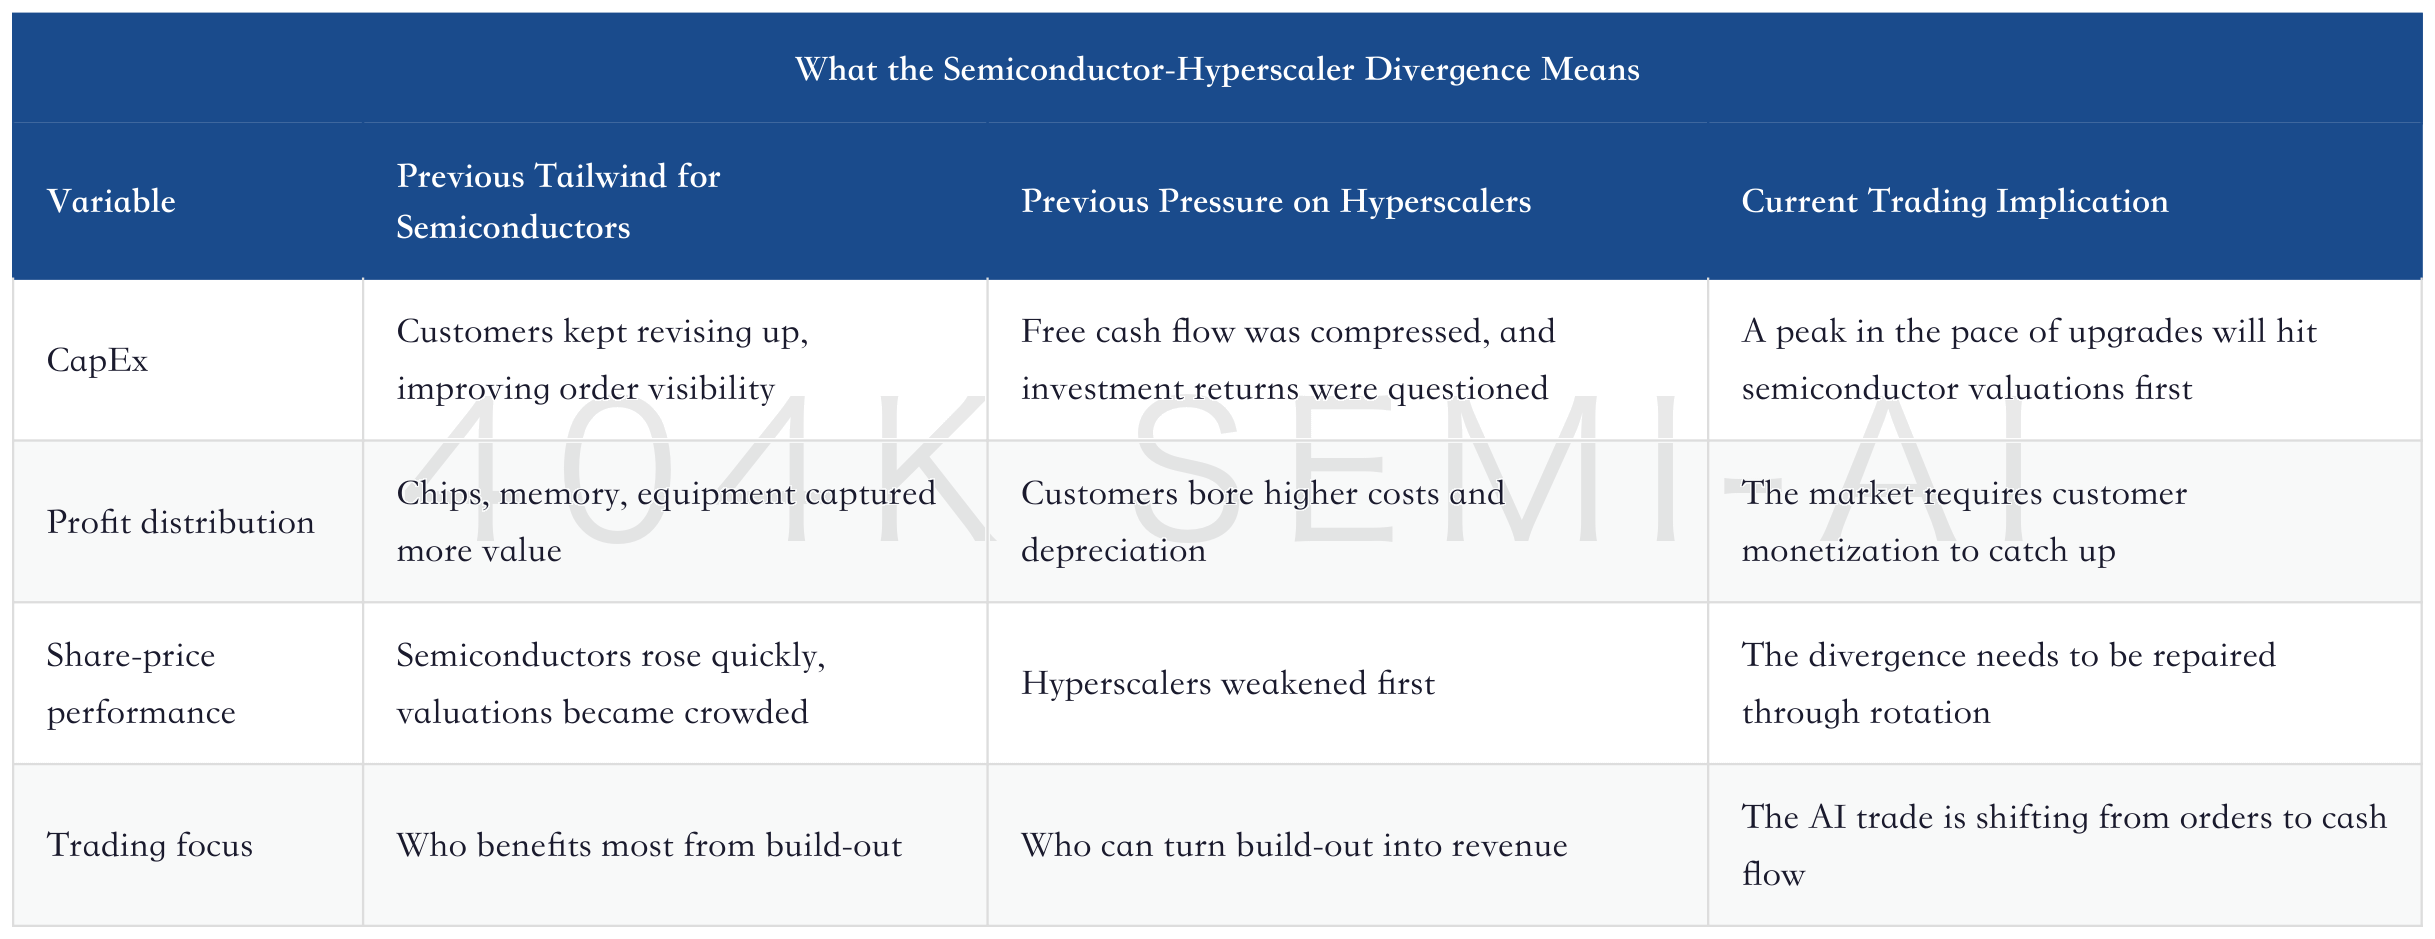
Semiconductors depend on hyperscalers, but recently semiconductors outperformed while hyperscalers underperformed. This divergence cannot last indefinitely. The profits of GPUs, HBM, memory, equipment, packaging, and PCBs ultimately come from hyperscalers and model companies being willing to keep raising capital spending. If customer share prices, cash flow, and capital costs come under pressure, supply-chain valuations will eventually be reassessed.
Morgan Stanley’s logic is that hyperscaler weakness may have led the market in reflecting concerns about returns on AI CapEx, while the subsequent semiconductor pullback represents those concerns moving upstream. Semiconductors had previously rallied harder because supply-chain orders materialized first. Hyperscalers fell first because investors saw free-cash-flow pressure first. Now the two sides are beginning to converge.
This convergence does not necessarily have to happen through further declines in hyperscalers. It can also happen through a semiconductor correction. Morgan Stanley leans toward the latter: after a historic rally, semiconductors are starting to lose momentum, while hyperscalers have already digested one round of pressure. The short-term allocation shift from semis to hyperscalers reflects a change in relative risk-reward, not a reversal in the direction of the industry cycle.
Microsoft, Google, Meta, and Amazon Q1 Together: AI Demand Has Not Collapsed, CapEx Has Exploded First, Cloud and Advertising Keep Accelerating, and Cash Flow Is Starting to Come Under Pressure
The easiest mistake here is to interpret the semiconductor pullback as “demand being disproven.” A more accurate framing is that customers have not stopped spending, but the market is starting to demand proof after they spend. Supply-chain valuations cannot depend forever only on customers raising budgets. In the end, the question is how much revenue, gross profit, and cash recovery those budgets generate.
III. Why Meta Became the Trigger: Compute Leasing Brings CapEx Back Onto the Operating Ledger
Meta’s sale of part of its excess compute capacity is the key trigger in this weekly report. It made the market suddenly realize that AI infrastructure does not automatically become valuable just because it is built. After it is built, it still needs utilization, pricing, and customers. The semiconductor trade previously focused more on “how much hyperscalers buy.” The Meta event changed the question to “how do hyperscalers make money after they buy?”
If Meta is leasing compute externally to improve asset turnover, the event is positive. It shows that AI compute remains scarce, and that Meta can sell capacity it is not yet fully using internally to external customers, cushioning free-cash-flow pressure. In that case, AI CapEx is not only a cost, but also an operable asset.
If Meta is leasing compute because internal demand is ramping slowly, the event is negative. The market will ask: if even Meta, with advertising cash flow, social distribution, and AI product ambitions, needs to sell compute to others, does that mean some hyperscalers built too fast? This will not directly overturn the AI cycle, but it will reduce the valuation multiple the market assigns to semiconductor orders.
Meta Selling Compute: The Last Straw for the Semiconductor Euphoria?
This is why Morgan Stanley says the “AI capex cycle is far from over” while “semis could enter a correction.” The cycle is far from over, and construction continues. But the trade needs to pull back because the market’s validation standard has changed. Previously, the question was whether hyperscalers were willing to build. Now the question is whether what they build can be sold, who it can be sold to, at what price, and whether it can cover depreciation and financing costs.
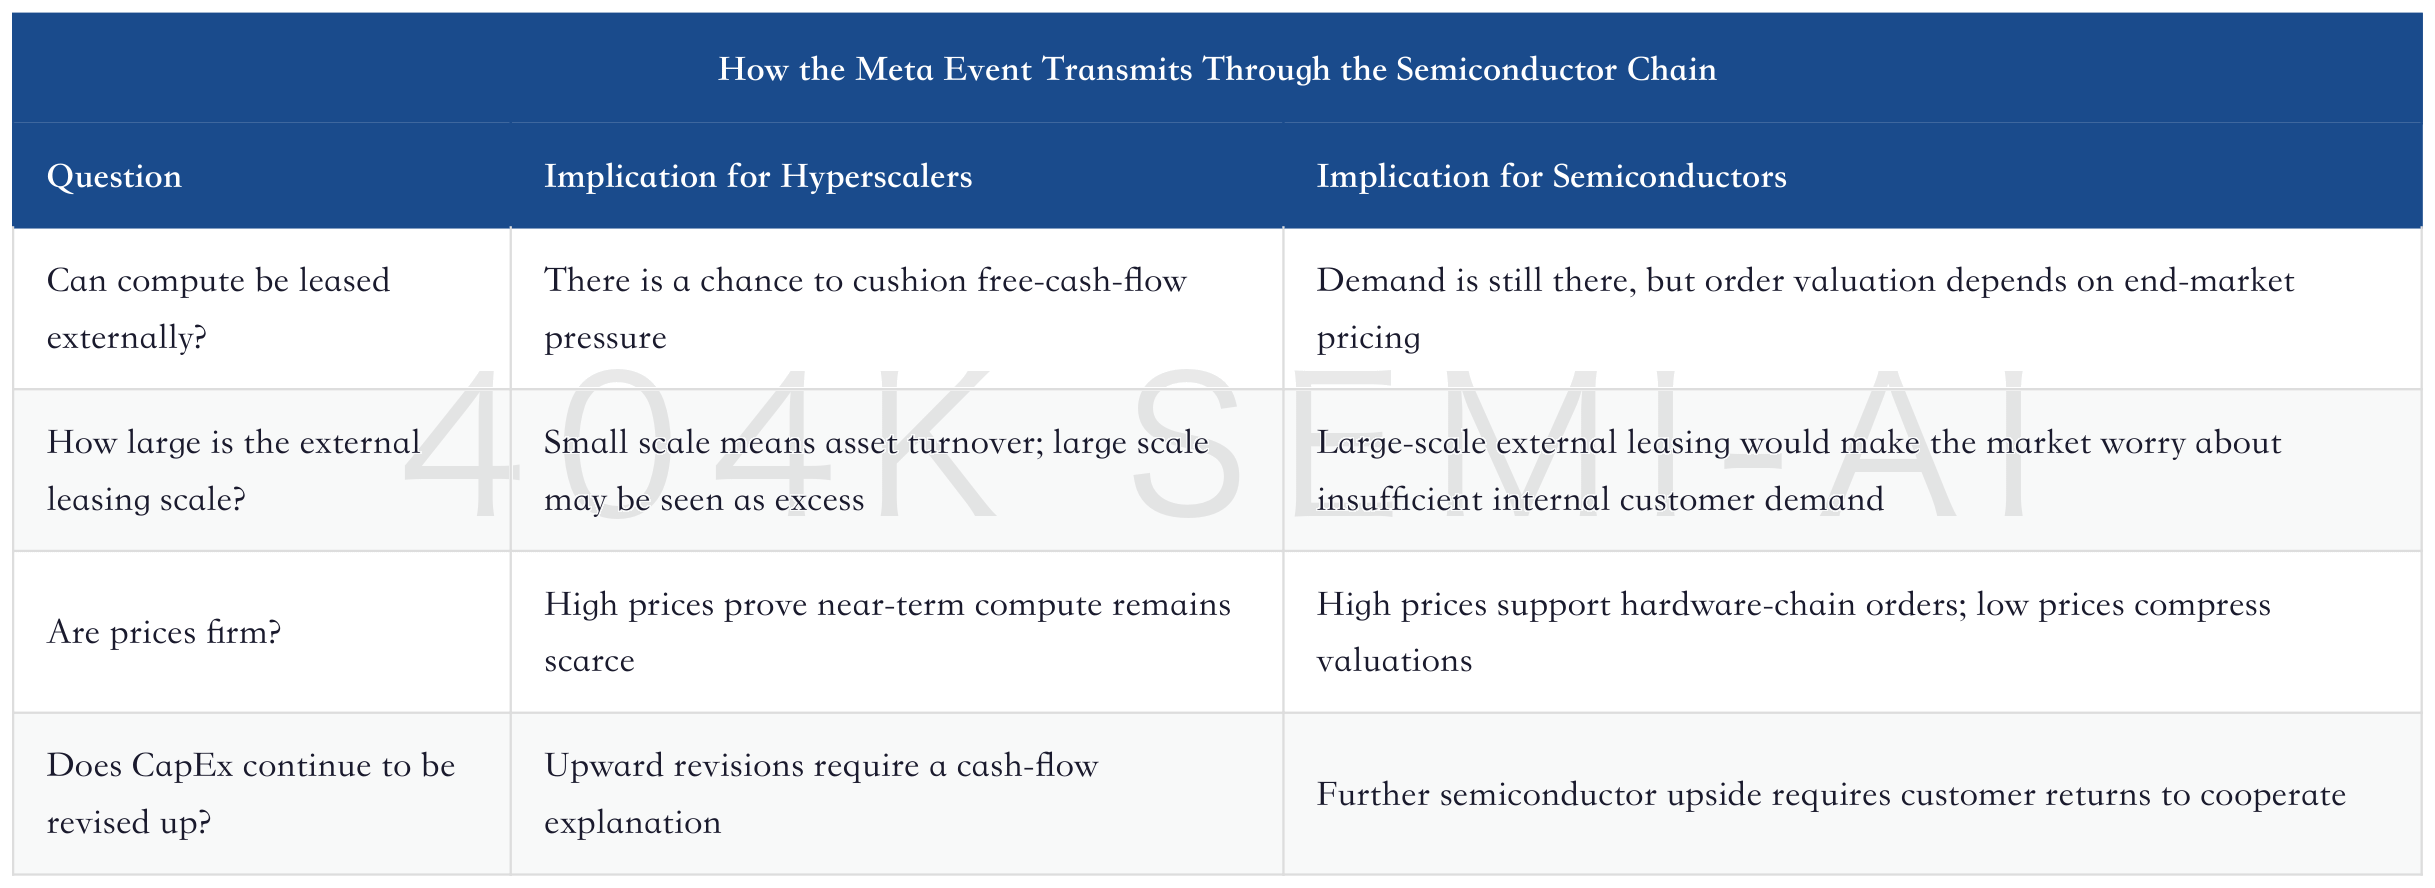
Morgan Stanley does not frame the Meta event as a single bearish catalyst. It frames it as a rationale, meaning a reason why semiconductor momentum may now start to loosen. That wording is restrained and important: it points to the market changing its yardstick, not a death certificate for fundamentals.
IV. Why This Is “Not the End of the Cycle”: AI Hardware Will Go Through Multiple Resets
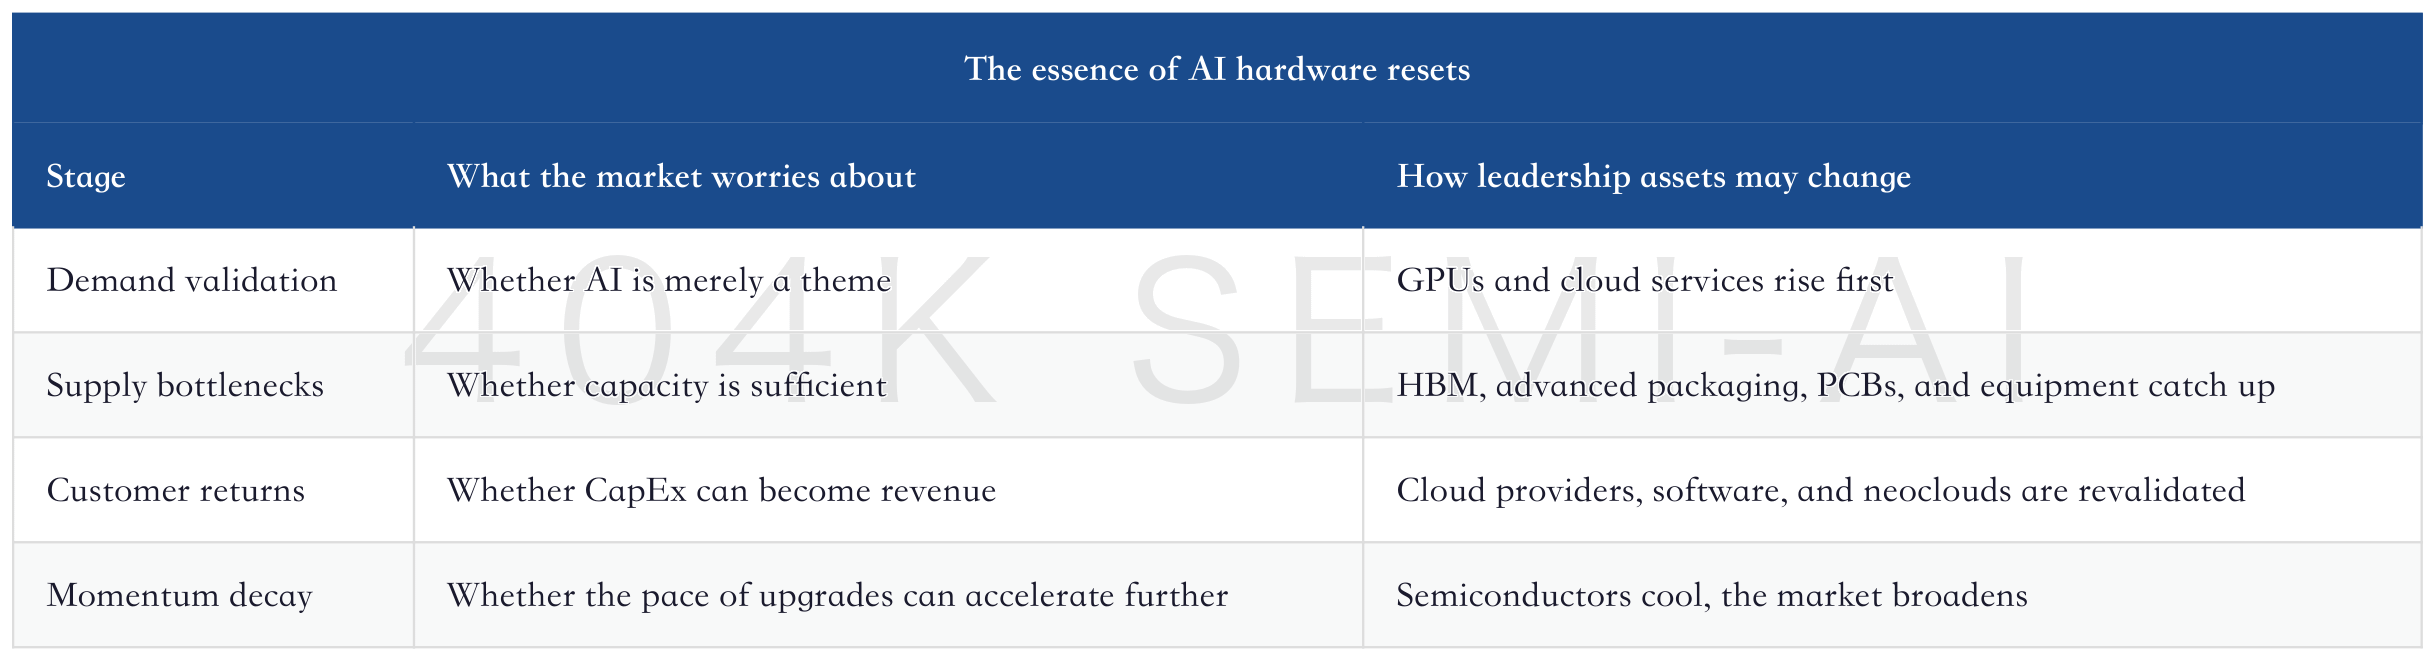
Morgan Stanley emphasizes that since the release of ChatGPT, the AI trade has already seen three similar corrections, and this may now be the fourth. The value of that observation is that it places the current pullback inside a still-expanding cycle, rather than treating it as the end of the cycle.
Each AI hardware correction has corresponded to a different question. Early on, the market worried whether training demand was one-off; later, whether model revenue could cover compute costs; later still, whether power, memory, packaging, and networking bottlenecks would constrain delivery. The question now is: capital expenditure is already large enough, but can cloud providers convert it into cash flow?
These resets do not eliminate demand, but they do change the leadership segment. The first round may shift from GPUs to cloud providers, the second from GPUs to HBM, the third from HBM to PCBs and power, and the fourth may shift from semiconductors to hyperscalers, consumer goods, transportation, biotech, and equal-weight indices. The cycle continues; capital is rotating seats.
AI Semiconductors Enter a Broad Diffusion Phase: From Order Visibility and Supply Bottlenecks to Compute-Chain Profit Revaluation
This main thread should be understood within a trading framework. A semiconductor pullback does not mean shifting from bullish to bearish; it means the trade is moving from “who gets the orders” to “who can turn orders into cash flow.” That step is harder, but also healthier. As long as revenue from cloud providers, model companies, and enterprise customers can keep up, the AI chain will continue to diffuse; if it cannot, the high valuations in semiconductors and memory will be compressed first.
V. Why Memory Looks Most Like Silver Stocks: Strong Fundamentals, but the Most Violent Share-Price Volatility
Morgan Stanley’s comparison between semiconductors and silver stocks is mainly a reminder to the market: after an asset has risen parabolically, if it still has strong commodity attributes, price volatility will be extremely high. Within semiconductors, memory best fits that description.
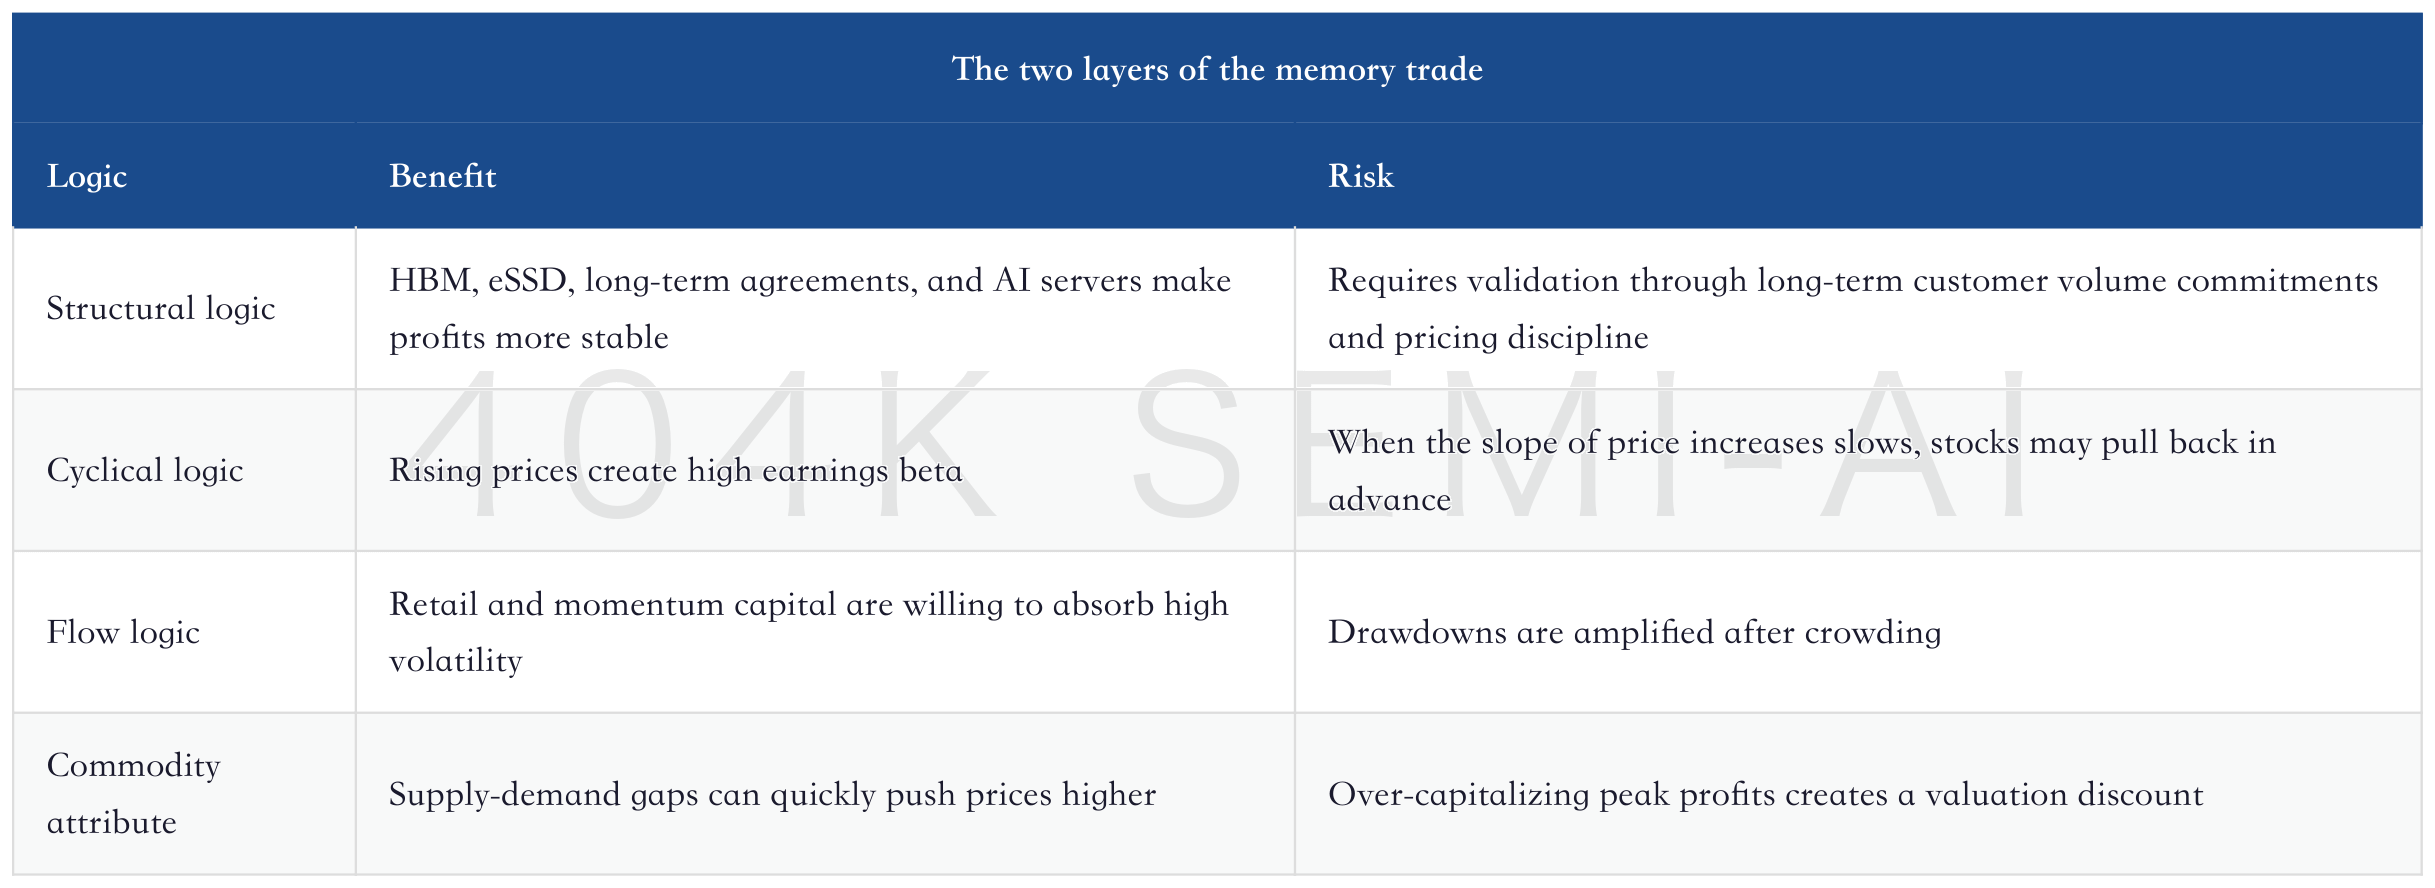
Memory fundamentals can remain strong. DRAM, NAND, HBM, eSSD, and nearline HDD all benefit from AI data centers, while price increases and long-term agreements are also improving earnings visibility. The issue is that share prices have already priced in price hikes, long-term agreements, supply discipline, and 2027 demand. As soon as the slope of price increases or the breadth of earnings upgrades starts to slow, the market will sell high-beta assets first.
Memory Pullback: Buy the Dip or Clear the Position? Watch These Five Signals First
Memory is most likely to become the leading edge of a semiconductor correction for another reason: capital most easily treats it as a “cyclical beta” trade. HBM and enterprise SSDs have given memory a structural narrative, but many investors still manage exposure based on pricing cycles and inventory cycles. The faster prices rise, the more excited capital becomes; once the price-increase slope or share-price momentum cools, selling pressure can also arrive faster.
Deep Memory Update: 3Q26 DDR Prices +32%, 2027 DRAM Demand +36%; UBS Monthly Report Recalibrates the Memory Supercycle
So the key reason memory is being singled out is that it most readily combines “strong fundamentals, high expectations, high volatility, and commodity attributes.” When Morgan Stanley says a semiconductor correction may be led by memory, this is the judgment behind it.
VI. Why Hyperscalers Are Preferred in the Short Term: They Have Already Paid for CapEx Pressure
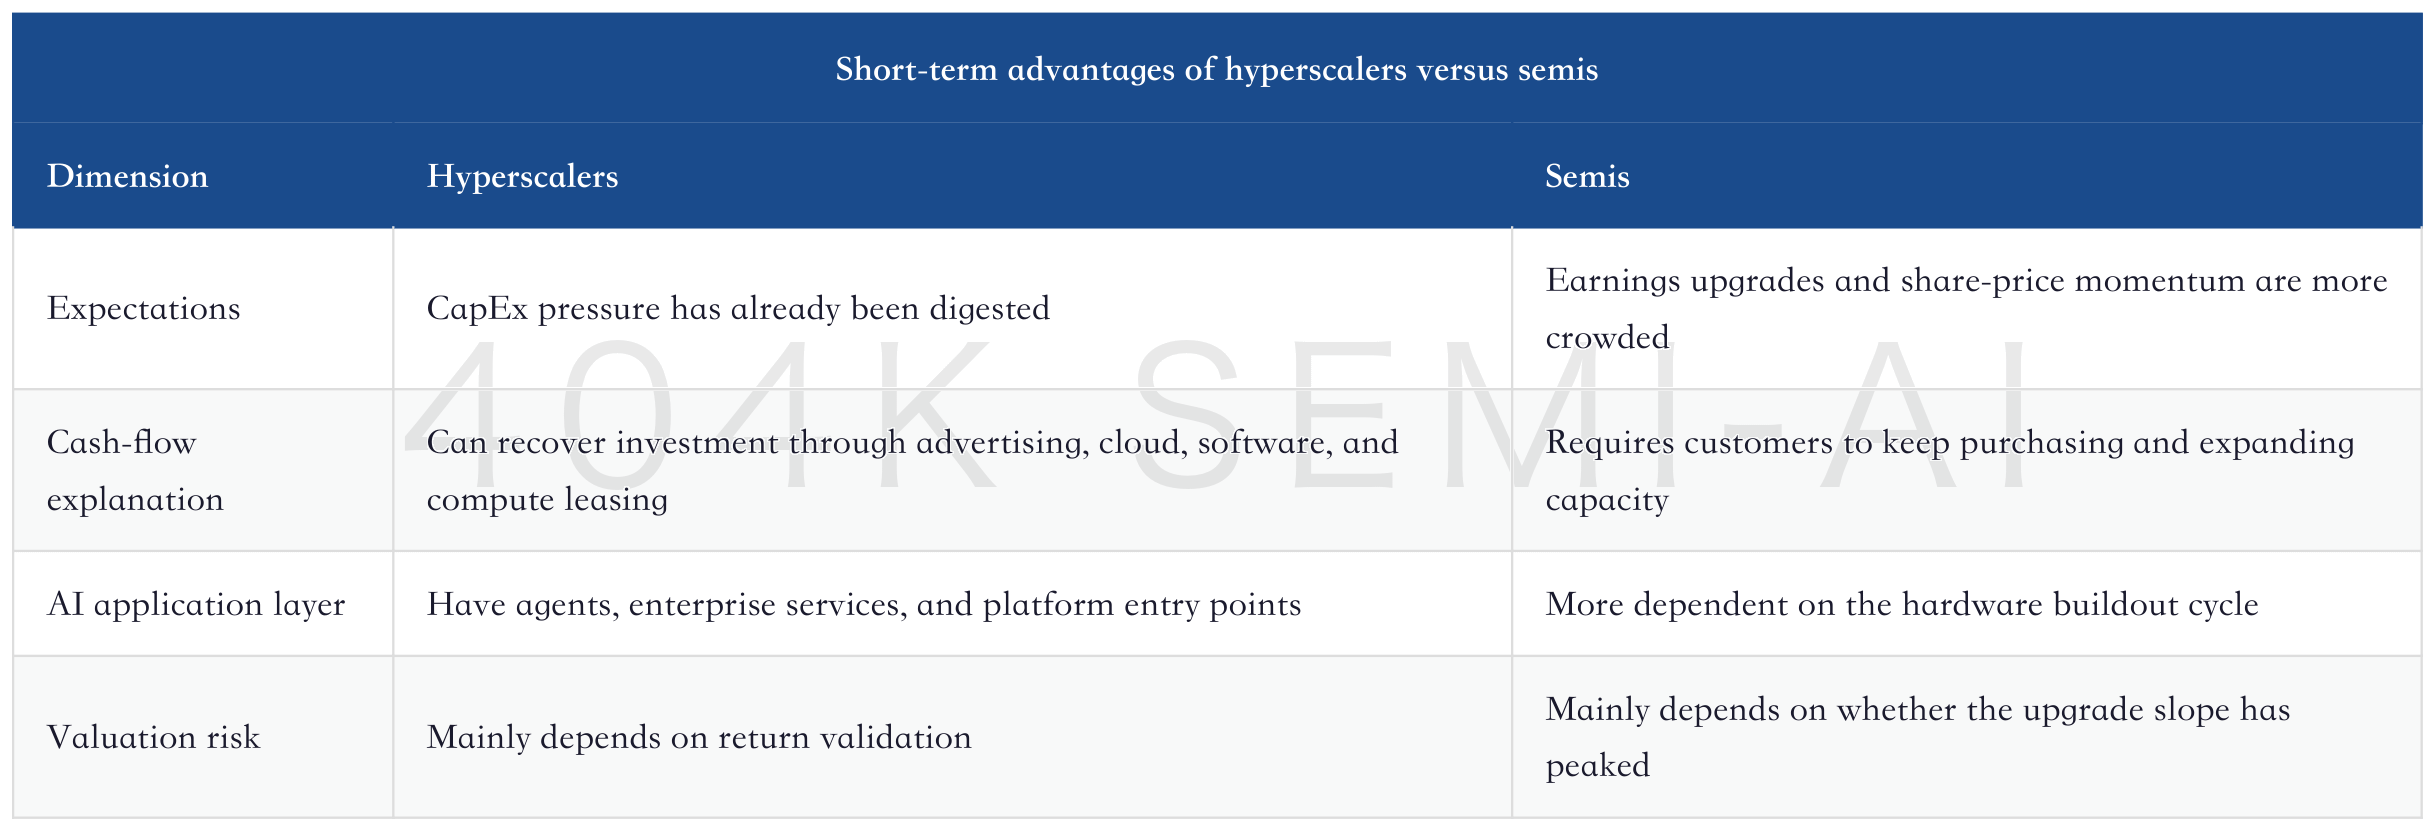
Morgan Stanley’s short-term preference for hyperscalers comes down to the order in which risk is priced. Cloud providers have underperformed over the past few months, and the market has already reflected CapEx growth, free-cash-flow pressure, and doubts over AI returns; semiconductors, by contrast, have just gone through a strong rally, with fuller expectations.
Cloud providers also have three options that semiconductors do not. First, they control end demand and can convert compute into revenue through advertising, cloud services, enterprise AI, agents, and model services. Second, they can offset part of the CapEx pressure through cost reduction and efficiency gains. Third, like Meta, they can turn part of their compute capacity into externally leased assets, cushioning free cash flow.
Semiconductor optionality is more supply-side. GPUs, HBM, equipment, PCBs, optical modules, and power devices all depend on customers continuing to spend; the stronger the customers, the stronger the supply chain. But when the market starts to question customer returns, supply-chain valuations are constrained first by customer cash flow.
Behind the 138GW Data Center Expansion Plan: AI CapEx Keeps Being Revised Up; How Cloud Providers, Bond Markets, ABS, and Power Infrastructure Absorb This Construction Cycle
This does not mean semiconductors will lose to cloud providers over the long term. A more reasonable judgment is that relative performance in the AI trade will swing among different beneficiary segments. When semiconductors have risen too much, the market buys return validation from cloud providers; once cloud providers prove returns, that in turn supports supply-chain orders. Morgan Stanley’s point that leadership oscillates among AI winners is about exactly this rhythm.
VII. Why Market Broadening Is Happening at the Same Time: Oil Prices, Rates, and Semiconductor Weightings Are All Loosening
This weekly report is not only about semiconductors. Its larger framework is market broadening, meaning gains are spreading from a small number of large-cap AI assets to more sectors. Semiconductor cooling is only one driver; the other two are lower oil prices and cooling rate expectations.
Lower oil prices reduce inflation pressure and also ease the drag on consumer goods, transportation, and economically sensitive sectors. Morgan Stanley believes that if core inflation remains controlled, the market’s hawkish pricing of the Federal Reserve will ease, giving rate-sensitive sectors room to recover. Weaker-than-expected employment data would also reduce market concerns about rate hikes.
This macro backdrop is critical for semiconductors. Because large-cap AI hardware has a high weighting in indices, if semiconductor momentum decays, headline indices may not look attractive in the short term; but capital can rotate within indices toward equal weight, consumer goods, transportation, regional banks, biotech, and other previously lagging areas. This is what Morgan Stanley means when it says major averages may be choppy in the short term.
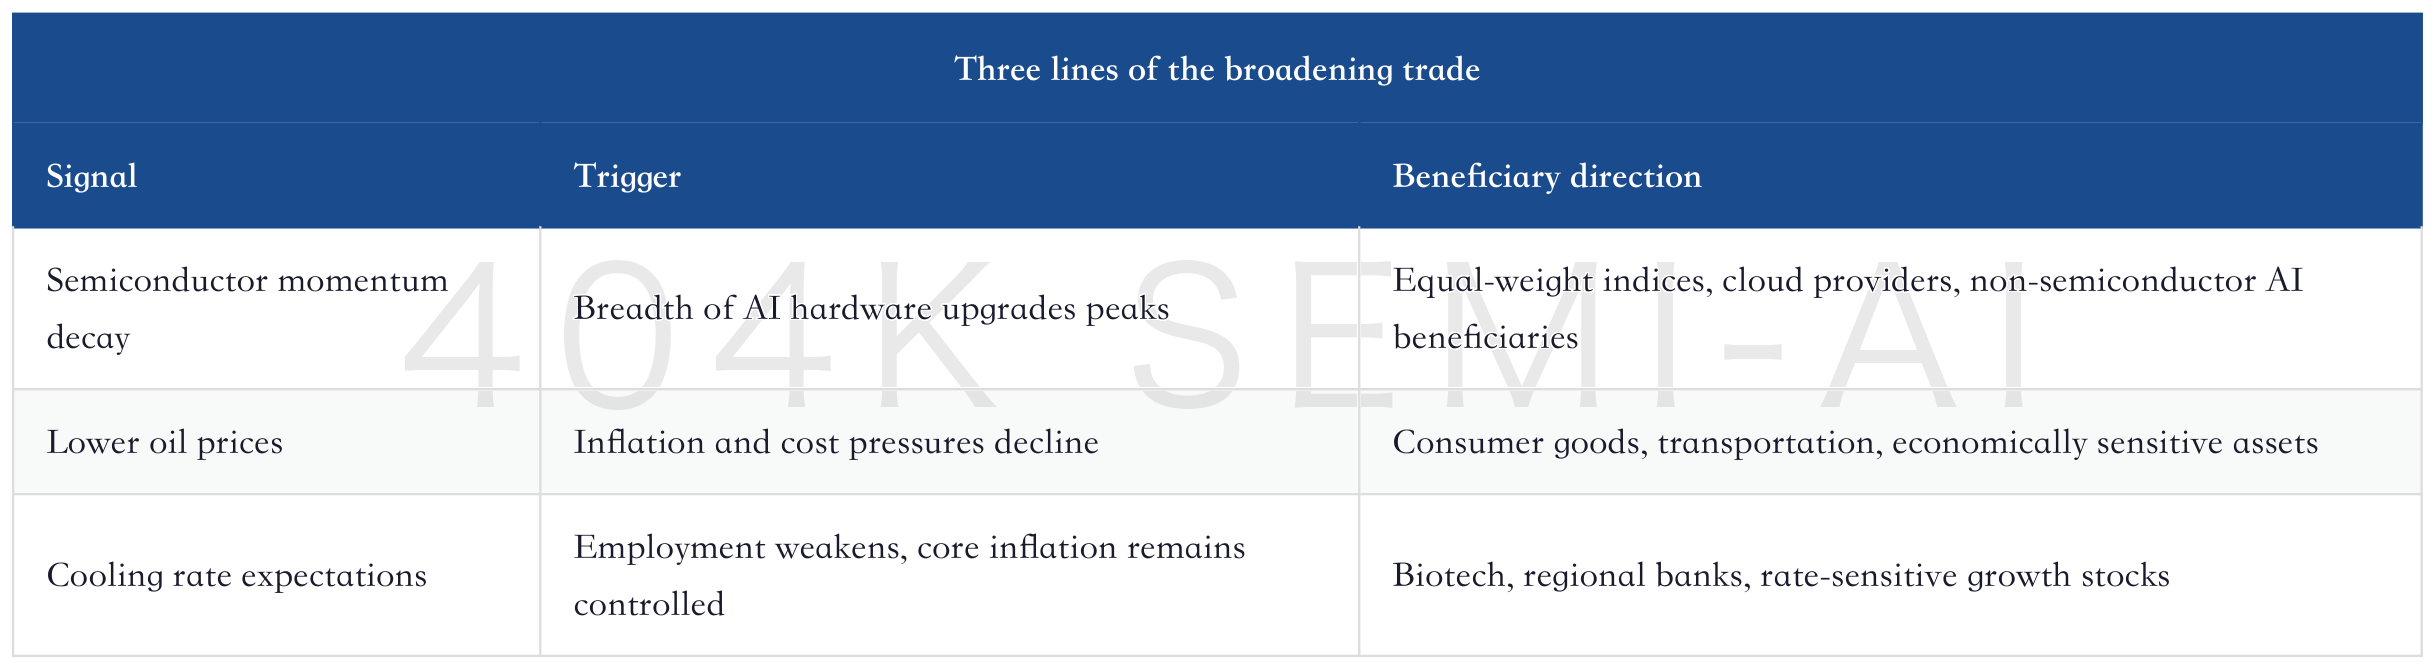
This is also why the weekly report is not simply “sell semiconductors, buy defensives.” It is “AI trade concentration is declining, and the market is looking for the second group of assets with improving profits.” If the semiconductor pullback is moderate, the broadening trade can continue; if semiconductors fall sharply and drag down indices, the broadening trade will also become volatile.
VIII. What This Report Means for the Investment Framework: Semiconductors Are No Longer Just About Demand, but Customer Returns
The most important question for the next stage of semiconductor trading is customer returns. In the past, looking at semiconductors mainly meant judging AI demand, capacity bottlenecks, and order visibility. Now investors also need to look at the revenue, profit, and cash flow behind customer capital expenditure. The more aggressively upstream prices rise, the more downstream customers need to prove they can make money.
This will change the screening order. The first layer is still supply bottlenecks: HBM, advanced packaging, high-end PCBs, power, and memory remain important. The second layer is customer quality: whether cloud vendors can sustain high CapEx, whether compute-leasing prices are stable, and whether AI application revenue is scaling. The third layer is valuation and crowded positioning: for segments that have risen too quickly, investors need to watch the slope of upward revisions, not just absolute fundamentals.
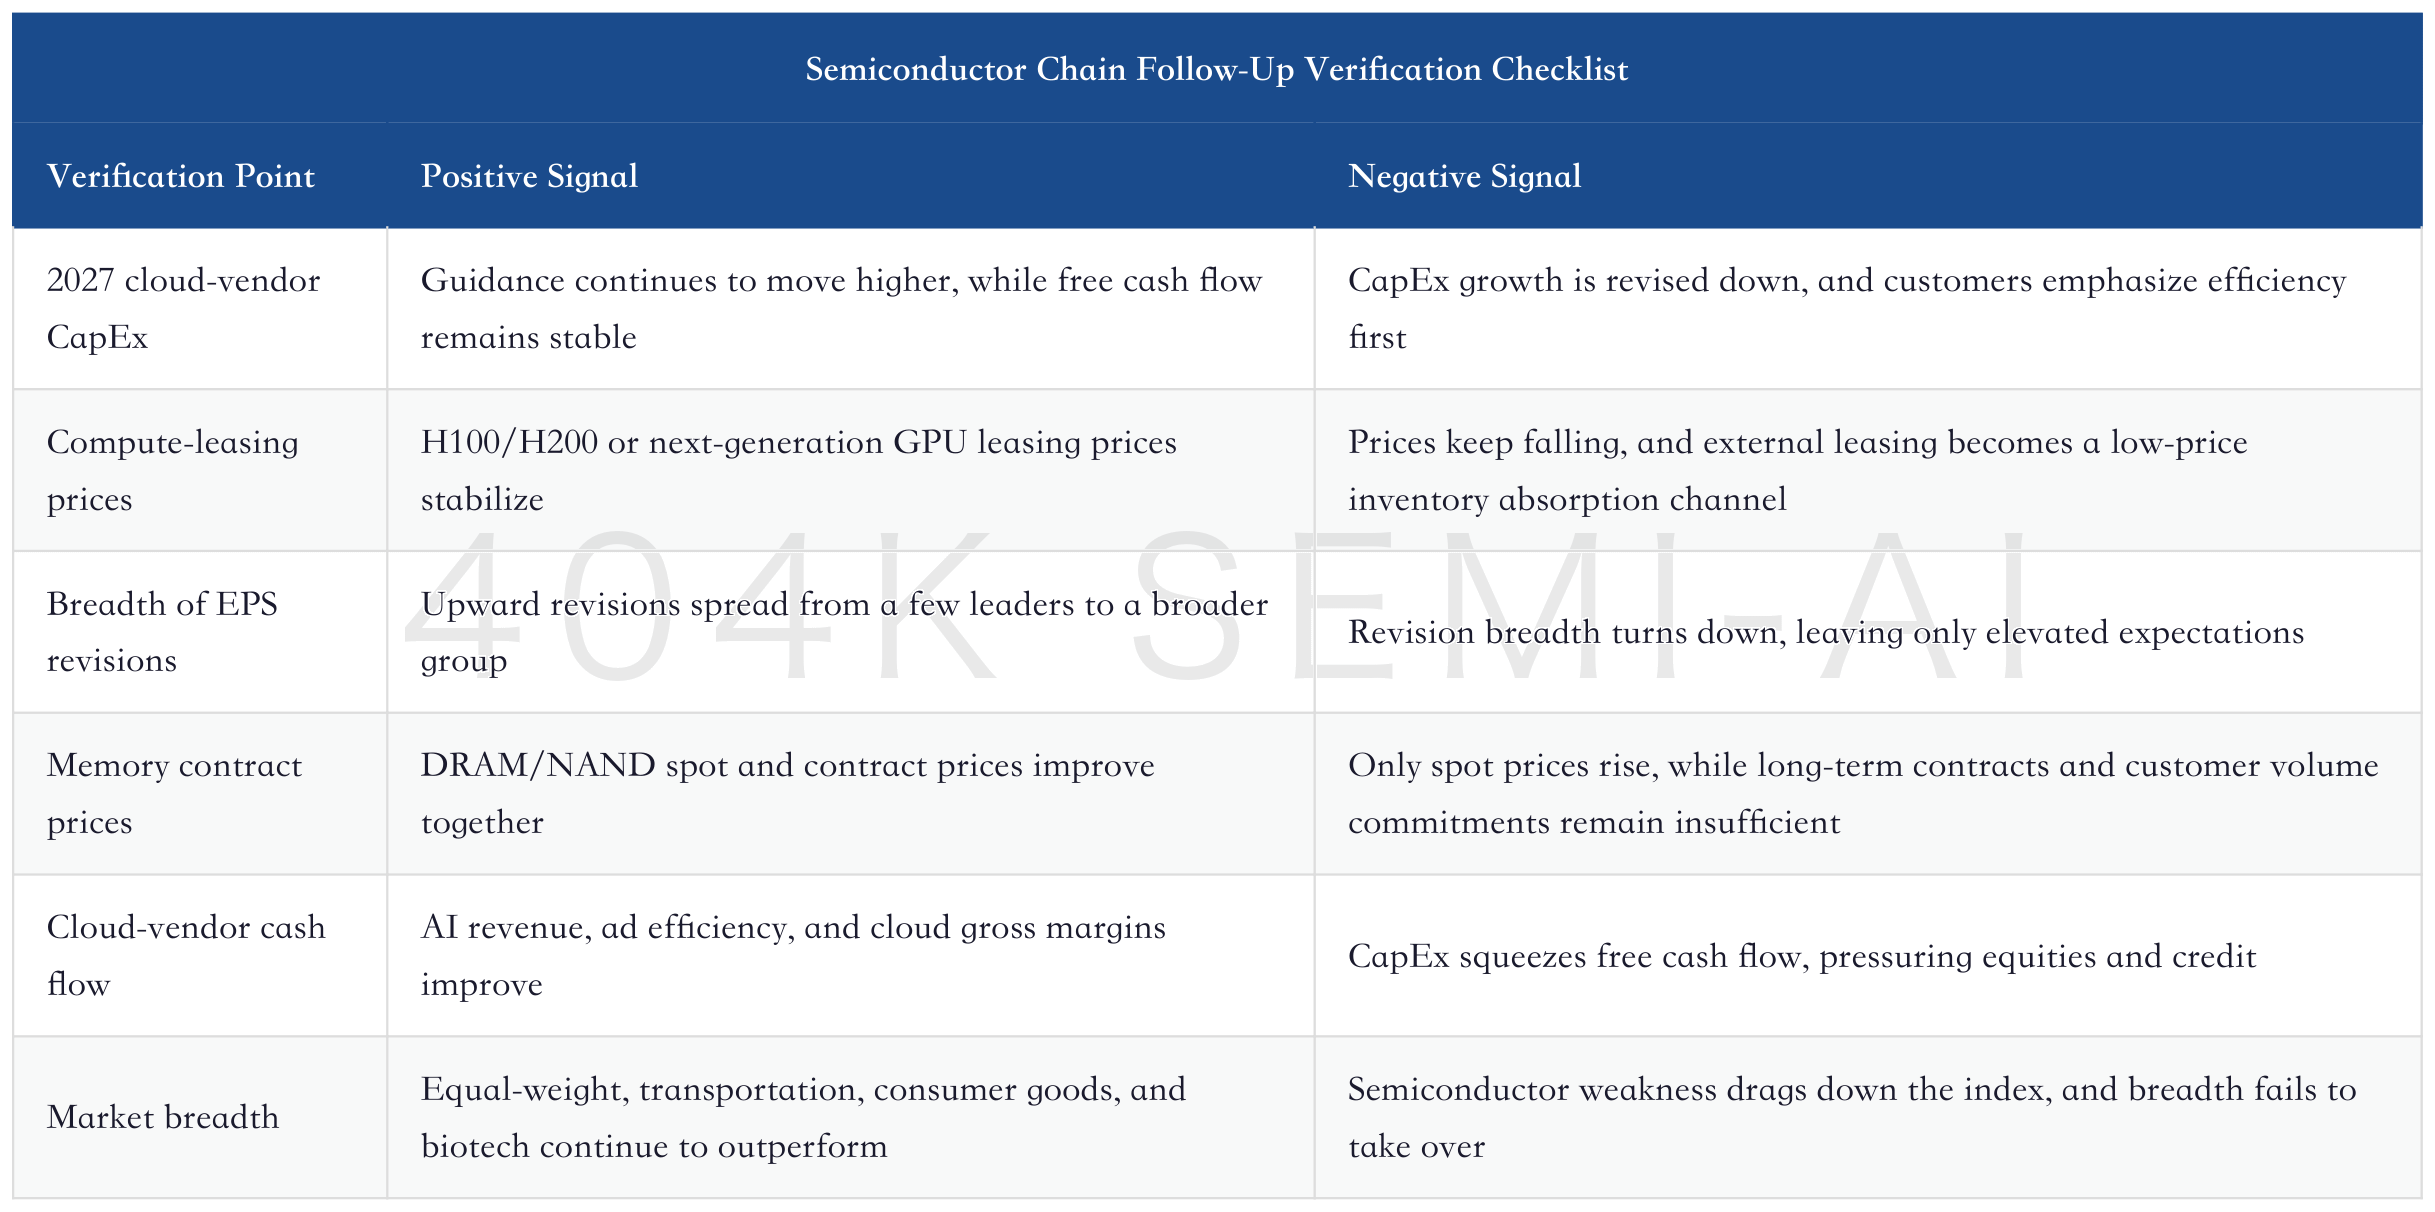
This checklist is more useful than simply asking whether semiconductors can keep rising. Semiconductors can pull back when fundamentals are strong, and they can resume rising when market concerns are most intense. The key is whether the verification variables are aligned.
IX. Translating “Momentum Deceleration” Into Trading Language: Growth Has Not Disappeared, but the Second Derivative Has Deteriorated
The easiest mistake in semiconductor trading is to interpret fading stock-price momentum as a peak in industry demand. Morgan Stanley’s weekly report is talking about the former, not the latter. AI infrastructure is still expanding, and cloud vendors are still spending. But the equity market is not trading the static question of “whether there is growth.” It is trading whether the acceleration of growth can continue to increase. Once the market already believes AI CapEx will grow rapidly, further gains in semiconductor stocks require a higher level of evidence: another round of upward guidance revisions, supply-chain orders continuing to beat expectations, margins still expanding, and customer cash flow not deteriorating.
This is a second-derivative trade. The first derivative is that revenue, profit, and capital expenditure are still growing. The second derivative is whether the growth rate is still increasing. During the strongest phase for semiconductors over the past few months, the market was trading continuous improvement in the second derivative: cloud vendors raised CapEx, the HBM gap widened, advanced-packaging capacity tightened, PCB and power-related suppliers rose in sympathy, and memory prices moved up from the cyclical bottom. What Morgan Stanley is flagging now is not that all these variables have reversed, but that the steepest slope of upward revisions is becoming harder to sustain.
It is normal for stock prices to react first at this point. Stocks do not wait for orders to decline before falling, nor do they wait for earnings downgrades before correcting. Once it becomes harder for conditions to get “even better,” crowded assets will loosen first. This semiconductor rally has been fast, and the narrative has been the easiest to explain, so capital has treated it as a high-beta expression of the AI trade. When the AI trade needs to cool down, it will also be among the first areas to be reduced.
This becomes clearer when viewed alongside the “broadening” in Morgan Stanley’s title. The market is not suddenly shifting from risk appetite to broad risk aversion. It is reducing reliance on a single dominant theme. Semiconductors are moving from “the engine of index upside” to “a highly crowded asset that needs verification,” while lagging sectors such as consumer, transportation, regional banks, and biotech are starting to take over. If this broadening can continue, semiconductor cooling is a healthy rotation. If breadth cannot carry the handoff, then it could evolve into index-level risk.
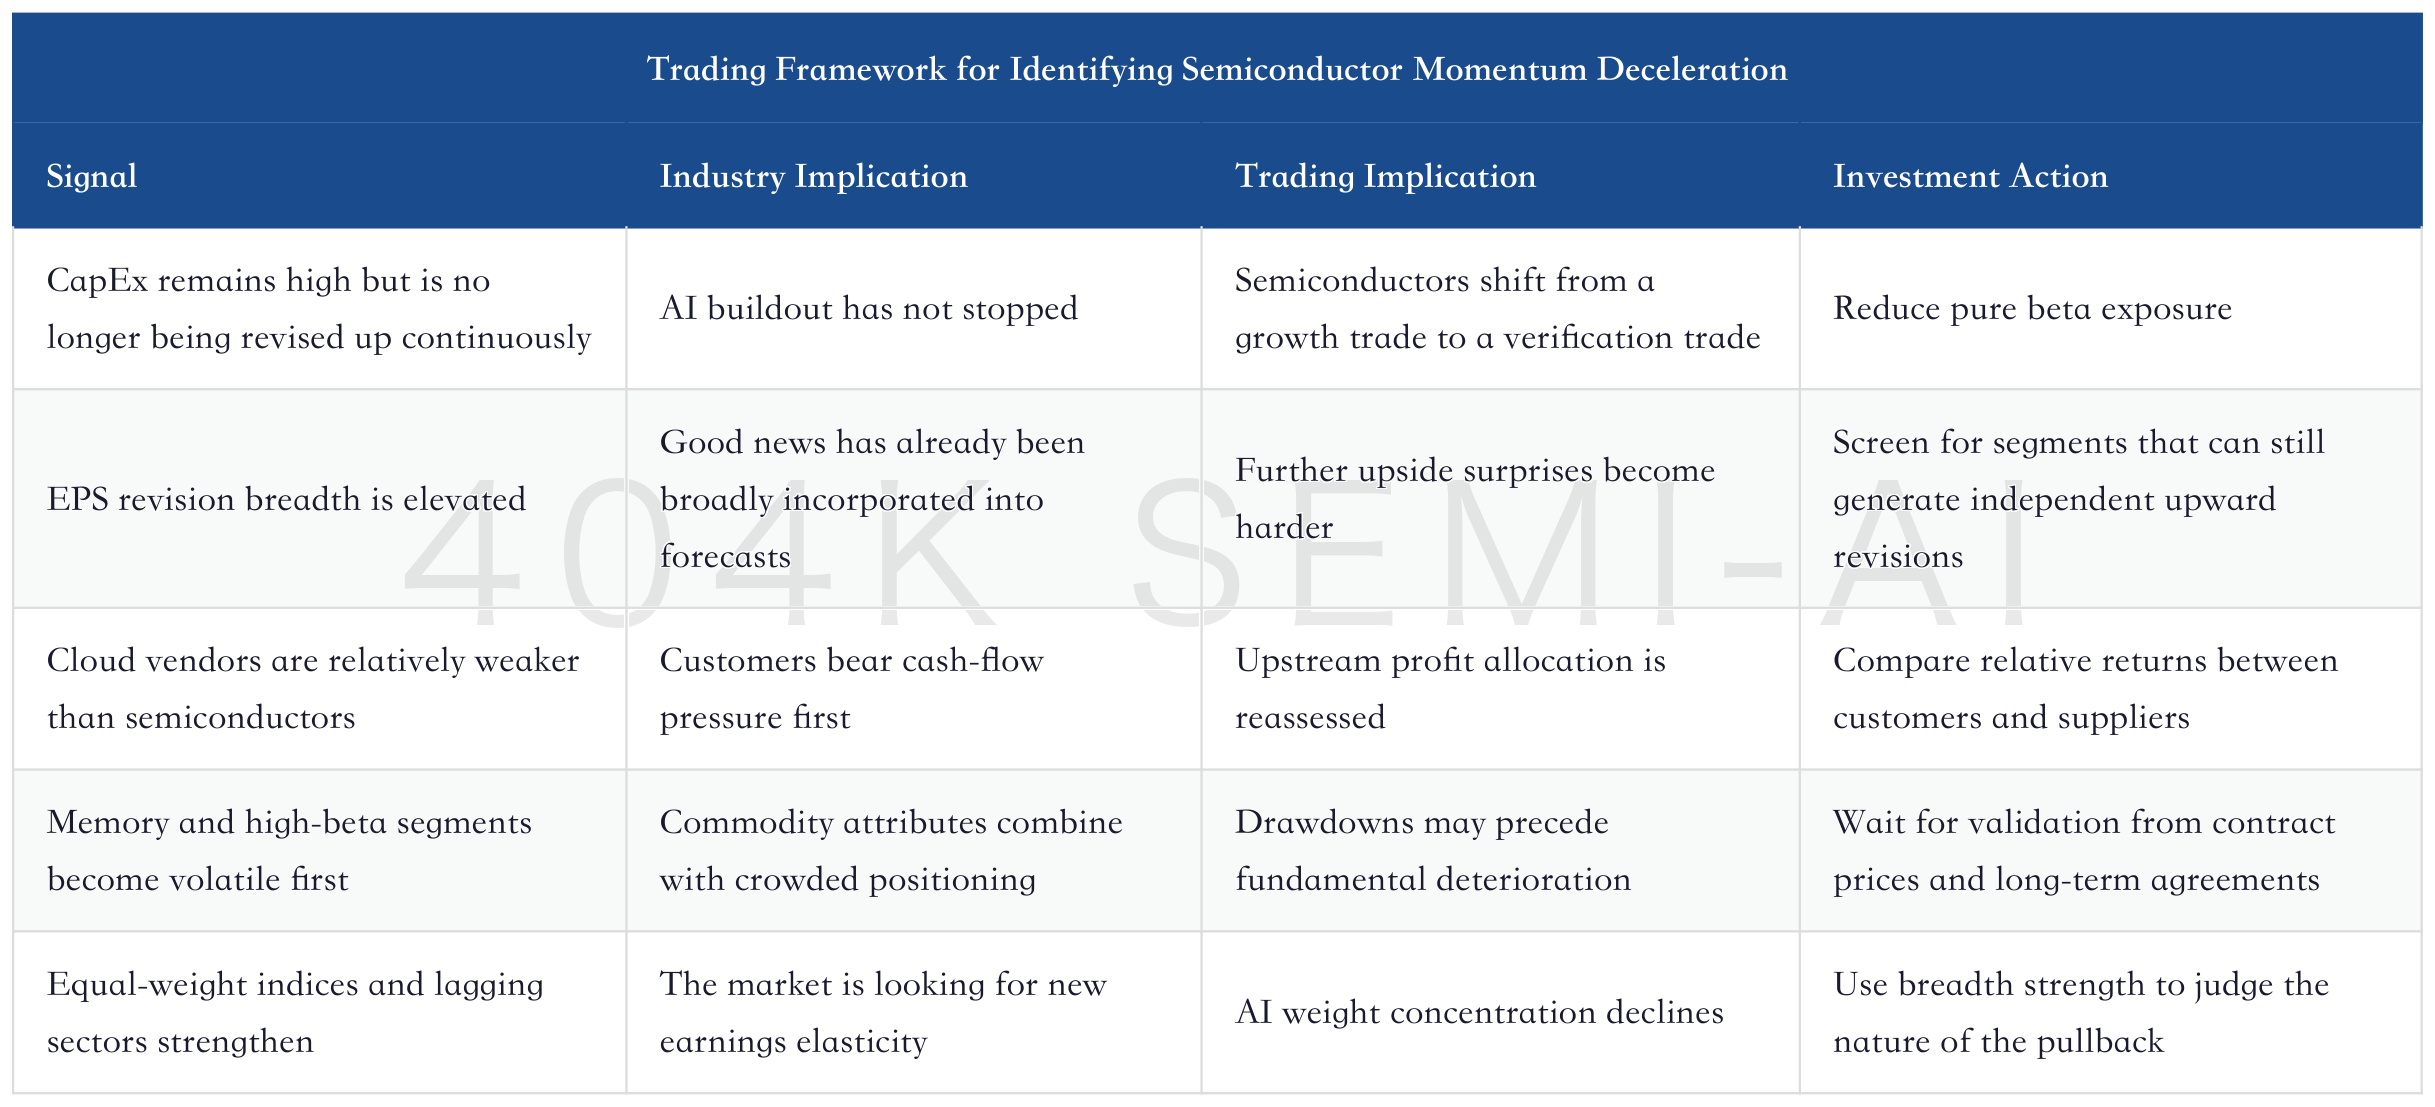
The core of this framework is not to attach a “bearish” label to semiconductors, but to separate variables across different levels. Industry variables can remain strong, earnings variables can still be revised up, while trading variables can cool first. The stronger the trend asset, the more likely this kind of mismatch becomes. For investors, the real risk is treating the industry’s long-term logic as a short-term trading shield.
Put more directly, Morgan Stanley is saying that “growth remains strong, but further upward revisions to growth expectations are becoming harder.” That is not the same as “growth is slowing.” Growth slowing means revenue, profit, or capital expenditure itself is starting to cool. Momentum deceleration means those data points are still solid, but the market is no longer willing to keep paying for a more optimistic slope. The former is a fundamental problem; the latter is an expectations-gap and valuation problem.
This semiconductor rally has layered these two issues together, which makes it easy to misread. For example, cloud-vendor 2027 CapEx may still be very high, HBM demand may still be tight, and AI server shipments may continue to grow. But if these variables have already been priced in ahead of time, further upside requires stronger evidence. Without stronger evidence, stocks can pull back first, even if fundamentals have not deteriorated.
That is also why Morgan Stanley puts semiconductors and broadening in the same title. It is not saying the market has no growth assets left to buy. It is saying the most crowded growth assets need a break, and capital is starting to look for marginal improvement elsewhere. Momentum deceleration is not “growth disappearing”; it is “fewer tradable growth surprises.” This is especially important for semiconductors, because many supply-chain companies may experience valuation compression before earnings revisions stop moving higher.
In investment terms, “growth rate” needs to be broken into three layers. The first is absolute growth: whether AI CapEx, semiconductor revenue, memory prices, and equipment orders are still growing. The second is the slope of growth: whether these variables are still accelerating. The third is the expectations gap: whether the market had already priced in an even higher slope. Morgan Stanley is concerned about the second and third layers, not a complete collapse in the first.
If investors only look at the first layer, it is easy to conclude that “AI is still here, so semiconductors are fine.” If they only look at stock prices, it is easy to conclude that “semiconductors are falling, so AI is over.” Both judgments are too crude. A more accurate view is: AI is still here, semiconductors are still strong, but the market has shifted from buying the direction of growth to buying the quality of growth. The future outperformers will not be every supply-chain company with an AI label, but the segments that can continue to prove order quality, profit quality, and cash-flow quality during the customer verification phase.
So the semiconductor view in this weekly report can be compressed into one sentence: it is not that “growth is gone,” but that “the slope of growth and valuation tolerance have deteriorated at the same time.” This judgment is more actionable than simply being bearish. It allows investors to continue tracking the AI theme, while also requiring them to reduce crowded high-beta exposure and shift attention to customer returns, supply bottlenecks, long-term contract prices, EPS revision breadth, and the quality of market broadening.
This also explains why the report does not separate semiconductors from the AI cycle. Morgan Stanley calls this adjustment a reset within the AI cycle, which essentially acknowledges that infrastructure buildout will continue. It is just that every reset reprices the most crowded and most linear narrative from the previous round. The first reset may come from valuations being too expensive, the second from macro rates, the third from customer cash flow, and the fourth from the divergence between semiconductor momentum and cloud-vendor returns. After each reset, the market leaves behind a tougher verification standard.
Therefore, the key to judging this reset is not to find a single-point conclusion, but to see whether it pushes the AI trade into a more mature phase. If, after the pullback, the market is only willing to buy cloud vendors that can prove cash flow, memory companies that can prove long-term contracts and committed volumes, and advanced packaging and networking names that can prove physical bottlenecks, then the quality of the AI trade has improved. If, after the pullback, the market continues chasing marginal themes without orders or profits, then momentum risk has not been fully released. What Morgan Stanley’s weekly report is really flagging is the former migration.
X. The Core Tension in AI CapEx: Orders Are Supply-Chain Revenue, Depreciation Is Customer Cost
AI infrastructure spending is split into two sets of books across the industry chain. For semiconductor companies, every additional dollar spent by cloud providers is a revenue opportunity in GPUs, HBM, networking, PCBs, power, liquid cooling, racks, and equipment. For cloud providers, that same dollar becomes depreciation, energy consumption, operations and maintenance, and opportunity cost to be amortized over the next several years. The supply chain sees orders; customers see the capital recovery cycle.
The most comfortable phase of a semiconductor bull market is when these two ledgers are not in conflict. Cloud providers have strong cash flow, advertising and cloud businesses are growing quickly, rate pressure is manageable, and investors are willing to believe AI is a long-term strategic expenditure. Under those conditions, the more supply-chain orders, the better. That conflict is now becoming explicit. Orders are still there, but customer returns are being questioned; supply-chain profits are still there, but customer free cash flow is being compressed. Morgan Stanley’s preference for hyperscalers is essentially saying that the customer ledger has already gone through one round of scrutiny, while the upstream ledger is only now entering the same scrutiny.
That is also the significance of the Meta event. Meta saying it may sell excess compute to external customers does not mean there is no demand for AI compute. On the contrary, it may indicate that compute can still be monetized and that cloud providers are seeking more flexible ways to turn over assets. But the market will ask a different question: if internal demand is strong enough, why lease it externally? If external leasing prices are not high enough, what exactly is the return on investment for these servers and chips? If external leasing is a short-term cash-flow buffer, how long can it continue to support supply-chain orders?
So Meta is not evidence that semiconductor demand has peaked. It is a trigger that pulls AI CapEx back from a “strategic narrative” to an “operating ledger.” Previously, the market was willing to price the hardware chain on long-dated imagination. Now the market wants to see recoverable cash flow. For semiconductor suppliers, this means the quality of customer CapEx is more important than its size. CapEx without returns can support one round of orders; CapEx with returns can support multiple rounds of procurement.
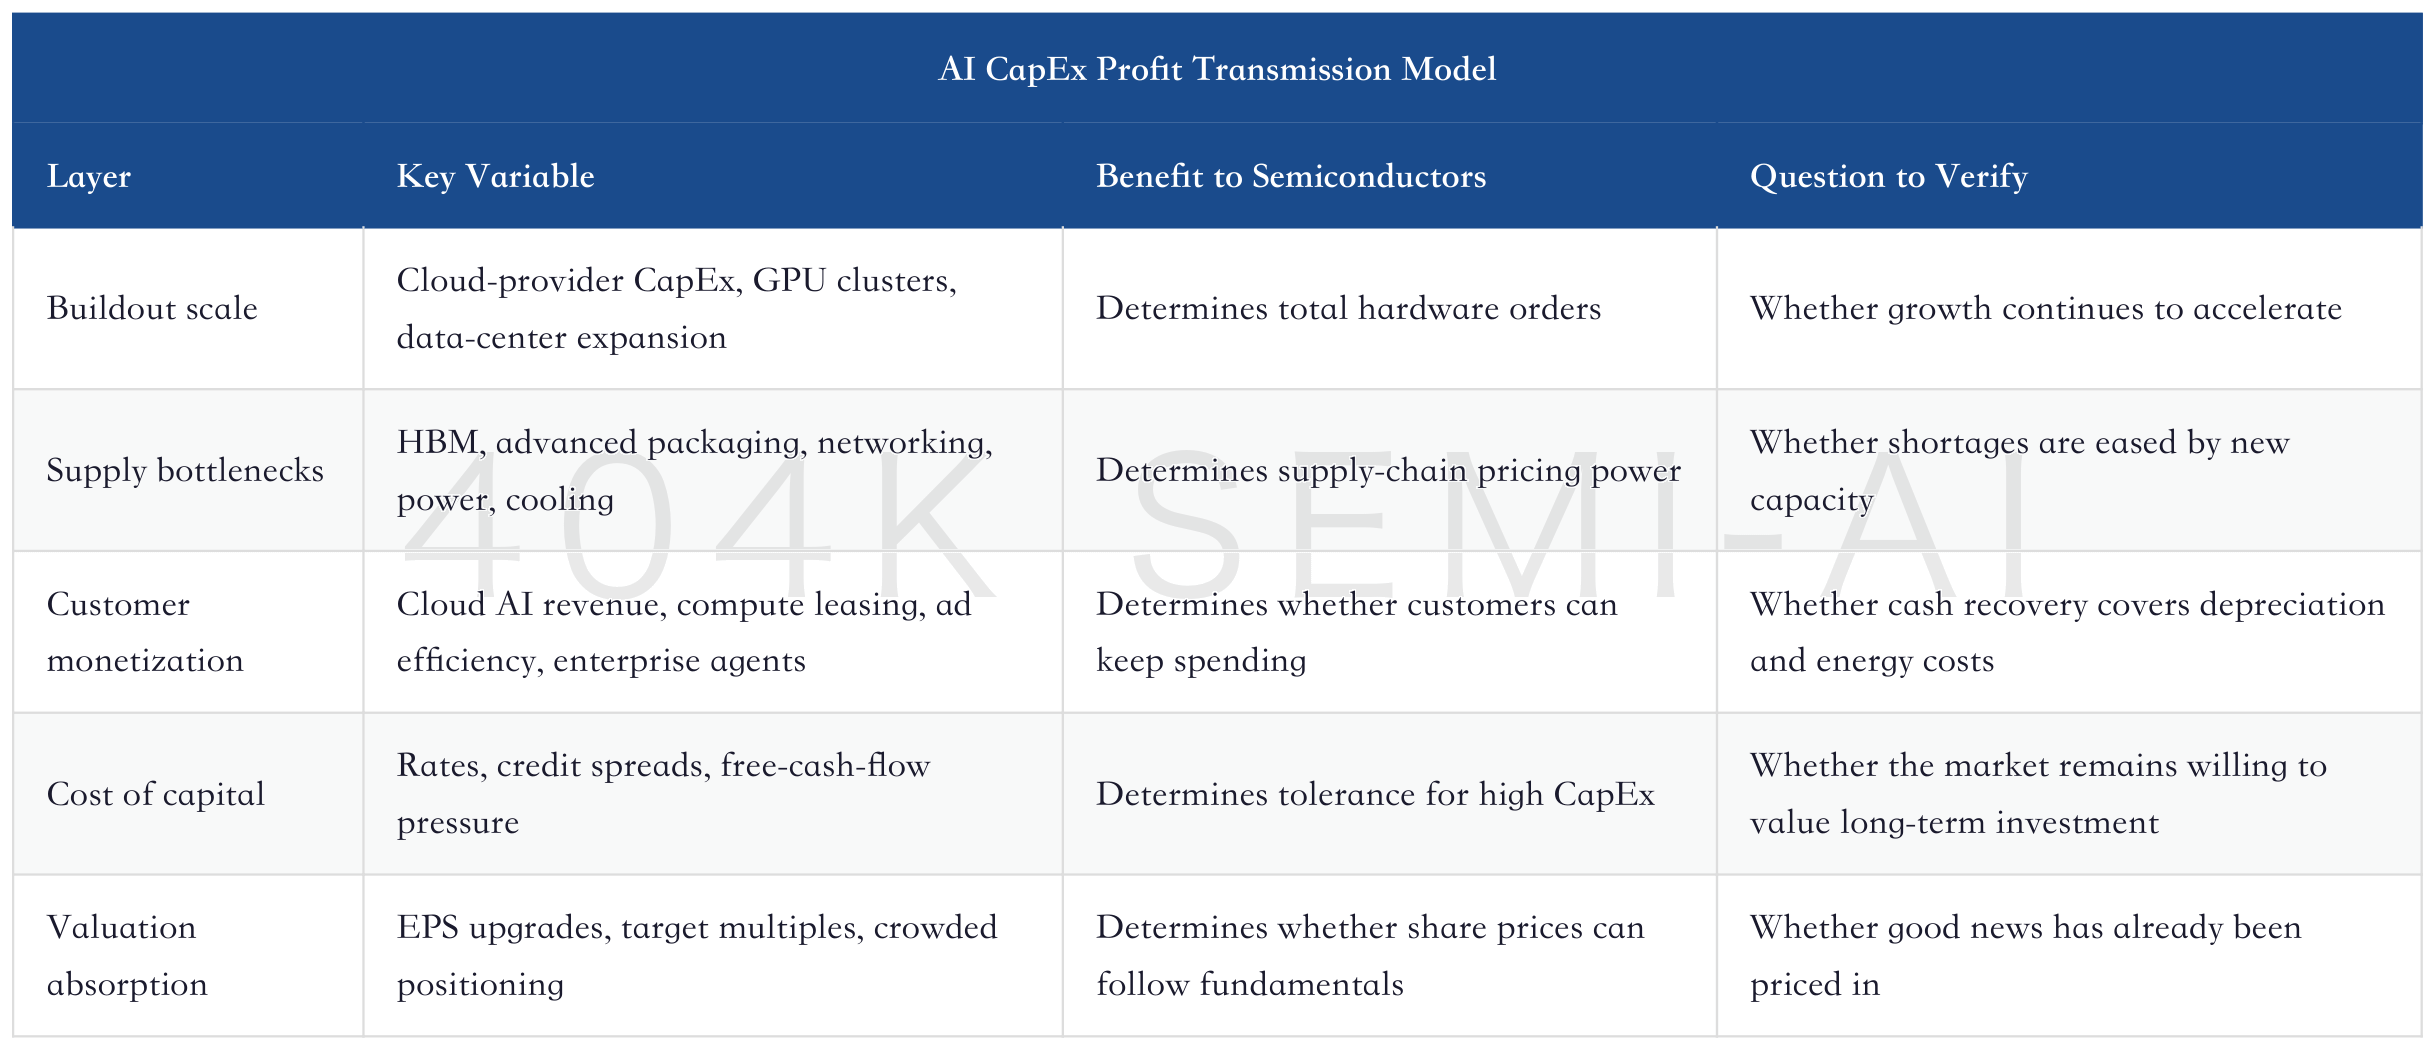
This model explains why semiconductors can correct even when the industry is strong. Looking only at the first layer, AI buildout is still expanding. Looking at the second layer, supply bottlenecks have not been fully resolved. But once the third, fourth, and fifth layers are included, it becomes clear that share prices now require higher-quality evidence. Whether semiconductors can strengthen again in the next phase depends on whether these five variables can realign in the same direction.
For cloud providers, the best outcome is that CapEx remains elevated while AI revenue, ad-delivery efficiency, cloud-service gross margins, and external compute-leasing prices all improve. In that case, the market will view them as investing early and recovering cash in the future. For semiconductors, the best outcome is that customers continue procuring after proving returns, turning upstream orders from one-off buildout into sustained capacity expansion. Conversely, if customers begin emphasizing efficiency, delaying data centers, or leasing compute externally at low prices, the supply chain will enter a valuation pressure zone.
XI. Memory Is the Most Sensitive Branch: It Has Both AI Logic and a Commodity Cycle
Morgan Stanley’s analogy between semiconductor stocks and silver miners is most useful when applied to memory. GPUs and advanced packaging look more like scarce capacity; memory has a more obvious commodity nature. DRAM, NAND, HBM, and eSSDs all benefit from AI server expansion, but their prices, inventories, long-term agreements, capital expenditure, and customer pull-in cadence amplify earnings cyclicality and also amplify share-price volatility.
The bull-market logic for memory is not weak. AI servers require higher bandwidth, larger capacity, and faster access. HBM has become a key constraint for GPU clusters; eSSDs benefit from data throughput and storage-tier restructuring; traditional DRAM/NAND also benefit from supply discipline and demand recovery. If long-term contract prices continue rising, customer volume-locking ratios increase, and capacity does not expand disorderly, memory profits may be more stable than in previous cycles.
But that is also where memory’s problem lies. The more the market prices it as an AI scarcity asset, the more it needs to prove that it is not just a normal commodity cycle. Once price increases slow, spot and contract prices diverge, or inventories begin to rise, the stock will shift from a “structural asset” valuation framework back to a “cyclical asset” framework. That shift may not necessarily change the company’s profit direction, but it will change the multiple the market is willing to assign.
Memory trades are also easily amplified by flows. Because the logic is simple, beta is high, and short-term pricing data is frequent, retail and momentum capital can participate easily. On the way up, price-hike data, AI demand, and supply discipline reinforce each other. On the way down, slowing price momentum, crowded positioning, and index-weight adjustments can also reinforce each other. When Morgan Stanley says semiconductors have lost momentum, memory is often the first segment the market uses as a test case.
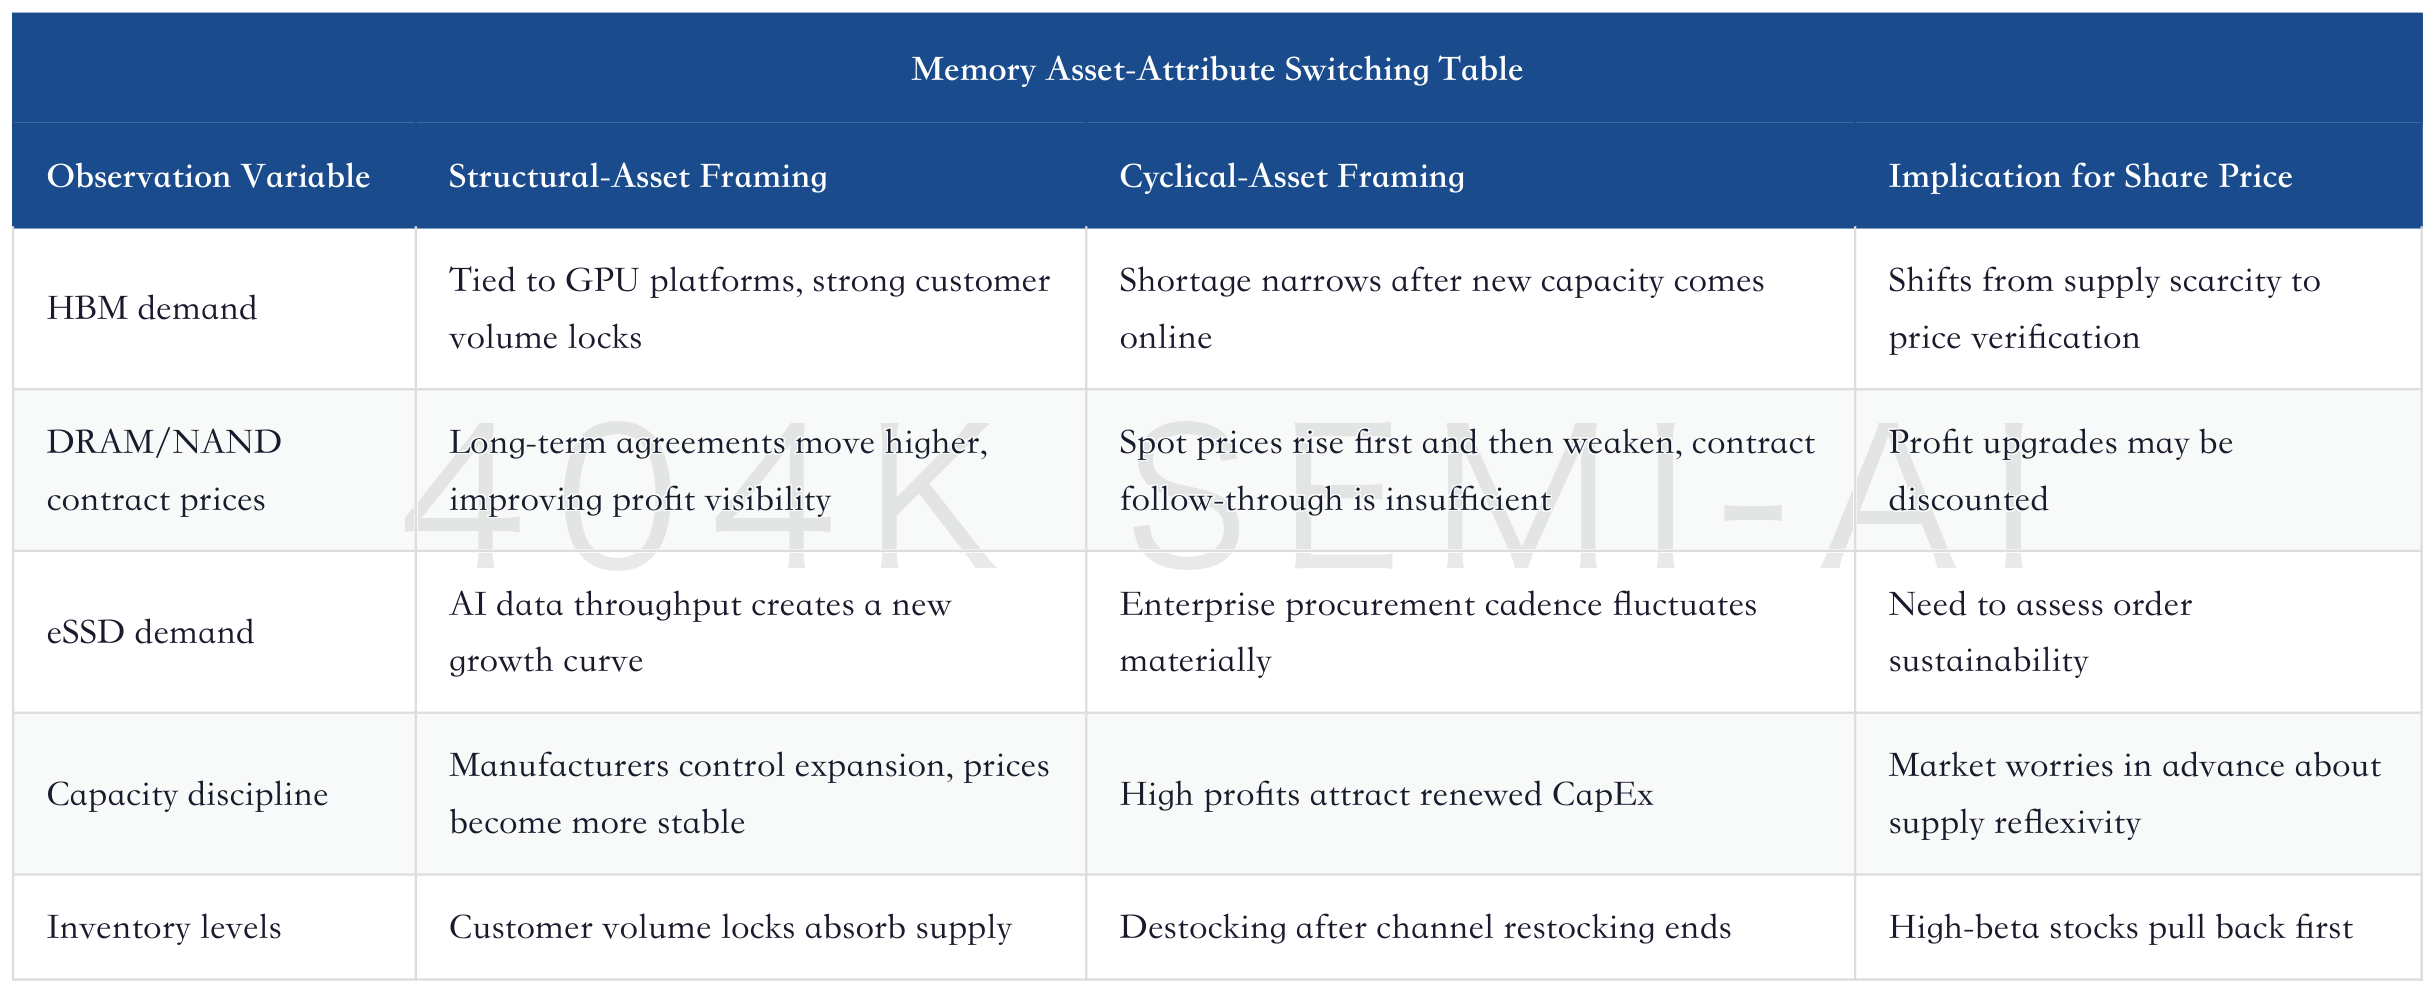
So memory is not simply a matter of “sell because it has risen too much.” A more reasonable approach is to split memory into two lines: one focused on real AI incremental demand, and the other on the traditional commodity cycle. As long as long-term agreements for HBM, eSSDs, and high-end DRAM remain strong, the medium-term logic for memory is not broken. But once the price slope for ordinary DRAM/NAND begins to slow, short-term trading can no longer extrapolate using the most optimistic multiples.
This has direct implications for investment ranking. HBM and high-end server storage are more structural; ordinary NAND and consumer-electronics-related memory are more cyclical. The former depends on customer volume locks, yield, and supply bottlenecks; the latter depends on prices, inventory, and restocking cadence. If the market uses only the four words “memory price increases” to explain all stocks, it can easily lose its anchor when momentum reverses.
XII. Why Hyperscalers Have a Relative Advantage: From Cost Bearers to Return Provers
Morgan Stanley’s short-term preference for hyperscalers is not because their AI spending pressure has disappeared, but because they have already been punished by the market first. Previously, cloud-provider stocks underperformed semiconductors, reflecting investor concerns over free cash flow, depreciation, and investment returns. Now that semiconductors are starting to catch down, the relative valuations of customers and suppliers are returning to a more balanced position.
The advantage of cloud providers is that they can explain AI investment through multiple revenue lines. Advertising platforms can use AI to improve delivery efficiency; cloud services can package GPU clusters as enterprise compute and model services; office software can use agents to lift average revenue per user; consumer internet platforms can use recommendations and content generation to increase engagement. Semiconductor suppliers’ revenue comes from customer procurement, while cloud providers’ revenue comes from end-user payments. The former relies on buildout spending; the latter relies on operating returns.
This does not mean cloud providers have no risk. The biggest risk remains an overly steep depreciation curve. If AI servers refresh too quickly, GPU generation transitions are too abrupt, energy consumption and data-center leasing costs are too high, and customer payments have not yet caught up, free-cash-flow pressure will persist. A rebound in cloud-provider stocks needs to prove one thing: AI CapEx is not “spending to avoid falling behind,” but can be converted into revenue growth, margin improvement, and platform moats.
But at this point, the semiconductor supply chain also needs the same proof, and the proof path is longer. They must first wait for customers to keep placing orders, then wait for orders to become revenue, then wait for revenue to become profit, while also facing the question of whether valuation has already absorbed the upside. If cloud providers can directly prove returns on investment, their share prices may recover first. Semiconductors need customers to confirm the next round of procurement budgets before they can regain upgrade momentum.
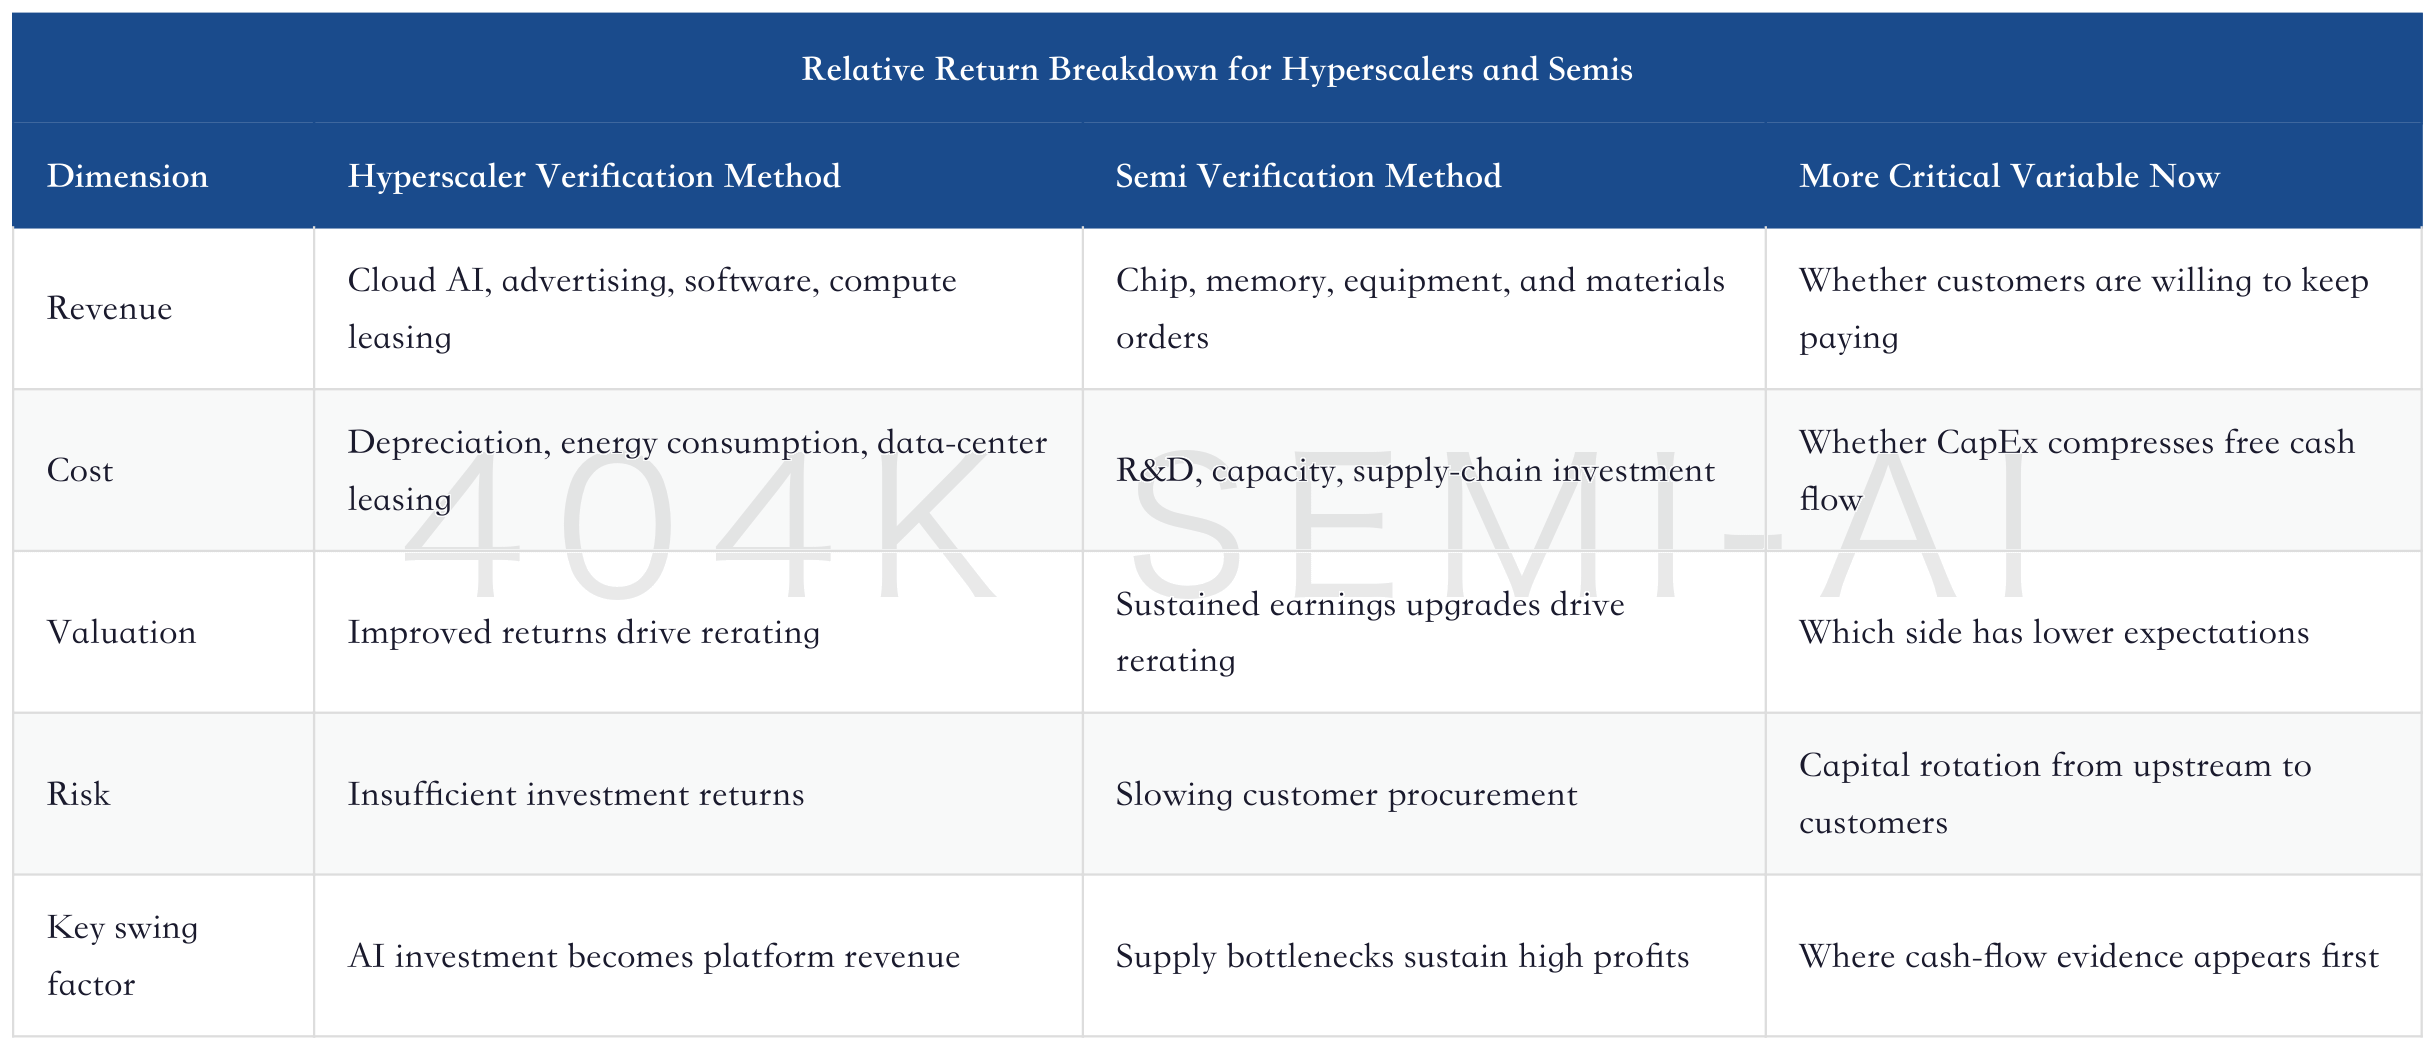
In the short term, hyperscaler risks have been discussed more fully, while semiconductor risks are only beginning to be repriced. In the medium term, the two are not in opposition. If cloud providers prove that AI investment can make money, the semiconductor chain will ultimately continue to benefit. If semiconductors keep rising on short-term customer pull-ins, but customer cash flow does not improve, the rally is more likely to be short-lived.
The real allocation question is timing. In the first stage, buy the supply chain because supply constraints are clearest. In the second stage, buy the customers because customer returns need to be proven. In the third stage, return to the supply-chain companies best able to convert orders into profits. Morgan Stanley’s weekly report stands at the entrance to the second stage. It does not reject the first stage; it simply warns that the first-stage trade has become too crowded.
XIII. Market Broadening Is Not a Side Issue: It Determines the Damage from a Semiconductor Pullback
Whether fading semiconductor momentum is dangerous depends on whether the market has a second source of upside. Another key point in Morgan Stanley’s weekly report is that broadening gains are gaining steam, meaning the market rally is starting to spread. This judgment is critical. If capital flows out of semiconductors and simply hides in cash or defensive assets, it means risk appetite is falling. If capital flows into consumer goods, transportation, regional banks, biotech, and equal-weight indices, it means the market is still looking for earnings recovery, but with less concentrated dependence on AI hardware.
The broadening trade has several macro conditions. Lower oil prices can ease pressure on consumer and transportation costs. Cooler rate expectations can help long-duration growth and rate-sensitive assets. Softer employment data can push the market back toward policy-easing bets. Semiconductor weakness itself can also relieve index-concentration pressure, giving sectors previously suppressed by AI weights more room to perform.
But the broadening trade is not a free lunch. It requires lagging sectors to deliver their own earnings improvement, not just rally on “low valuation.” Consumer goods need to show real demand and margin recovery. Transportation needs lower costs and better volumes. Regional banks need stable net interest margins and contained credit risk. Biotech needs a better funding environment and pipeline catalysts. If these sectors are only staging a short-term catch-up rally, a semiconductor pullback could still drag down the index.
This is why Morgan Stanley’s view cannot be simplified as “sell semis, buy cyclicals.” A more accurate reading is: AI weights are coming down, and the market is starting to test broader sources of earnings. Semiconductors are no longer carrying the index rally alone; other sectors must provide enough earnings evidence. If broadening can persist, a semiconductor correction is a healthy shift in gears. If broadening cannot persist, a semiconductor correction will expose the index’s dependence on a small number of leaders.
