
Semiconductor Equipment Deep Dive: Each Additional 1GW Requires 50,000 Wafers per Month—How AI Could Push WFE Toward $300 Billion
目录
TL;DR
The Real Tension in Equipment Stocks: Deep Pullbacks, but Valuations Remain Expensive
From 1GW to 46,000 Wafers per Month: How the Model Works
50GW Is Not Cumulative Capacity Buildout, and $300 Billion Is Not a Three-Year Average
Why Memory, Not Advanced Logic, Is the Primary Source of Incremental Equipment Demand
Recalculating Applied Materials, Lam Research, and KLA Under the 50, 75, and 100GW Scenarios
Baseline Financial Forecast Reminder: EPS Upgrades Are Not Entirely Driven by Equipment Revenue
Where This Model Is Most Likely to Be Wrong
Six Sets of Validation Indicators to Watch Over the Next Four Quarters
Conclusion: $300 Billion Is a Path That Can Be Validated Quarter by Quarter
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Bernstein translates the expansion of AI data-center power capacity into wafer and equipment demand: the real determinant of upside for semiconductor equipment stocks is whether gigawatt-scale projects convert into monthly wafer capacity, orders, and cash flow.
TL;DR
Bernstein provides a quantitative bridge from power capacity to earnings. Each additional 1GW of annual data-center build capacity requires approximately 46,000 wafers per month of incremental 300mm-equivalent capacity, rounded to roughly 50,000 wafers per month in the summary. Based on equipment capital intensity across process technologies, each 1GW translates into approximately $7.5–8.0 billion of incremental wafer fabrication equipment spending (WFE).
The 50GW scenario assumes that annual capacity additions in 2030 are 50GW above the 2026 baseline. The 2026 baseline is approximately 20GW, implying around 70GW of new capacity in 2030 alone. Cumulative incremental data-center capacity from 2027 to 2029 could reach 130–140GW, far above 50GW. Fab equipment must be ordered, installed, and qualified in advance.
The $300 billion figure reflects “incremental AI demand plus the non-AI base,” not merely a headline claim. The 50GW scenario implies $376 billion of incremental AI-related WFE from 2027 to 2029. Adding a three-year non-AI baseline of $360 billion produces a total of approximately $736 billion, with annual spending of around $200 billion, $245 billion, and $291 billion. More precisely, WFE approaches $300 billion in 2029 rather than averaging $300 billion over the three years.
Memory accounts for 89% of incremental wafer demand, making Applied Materials Bernstein’s top pick. For each 1GW of demand, dynamic random-access memory (DRAM) accounts for 53%, NAND flash for 20%, high-bandwidth memory (HBM) for 16%, and advanced logic for only 11%. The AI equipment cycle is not solely a graphics-processing-unit and advanced-logic story. Off-rack central processing units and their associated DRAM represent the largest source of incremental wafer demand in the model.
Further share-price upside depends on earnings catching up with valuations, not just the absolute level of WFE. Under the 50GW scenario, Applied Materials, Lam Research, and KLA’s 2029 earnings per share exceed consensus estimates by 59.5%, 54.4%, and 37.1%, respectively, implying P/E multiples of 14.9x, 18.4x, and 21.2x. The 75GW and 100GW cases are more bullish stress tests. Any weakness in project power access, facility power definitions, chip energy efficiency, memory content, equipment deliveries, or inventory-related cash flow could warrant a scenario discount.
The Real Tension in Equipment Stocks: Deep Pullbacks, but Valuations Remain Expensive
Semiconductor equipment stocks currently exhibit two seemingly contradictory features: substantial drawdowns and strong gains. Based on data through July 17, 2026 used in Bernstein’s report, ASML, Tokyo Electron, Applied Materials, Lam Research, and KLA were down an average of approximately 23.9% from their respective 52-week highs, with the three US companies down around 28%–31%. Yet the five stocks were still up an average of 84.1% year to date, with individual gains ranging from approximately 67% to 106%.
The pullback has not fully reversed the valuation expansion. The report shows that KLA and Lam Research’s next-12-month P/E multiples rose from approximately 28x and 27x at the beginning of the year to 42.2x and 36.8x, respectively. Valuations for Applied Materials, Tokyo Electron, and ASML also increased significantly. Investors therefore need to answer two more demanding questions: how much additional effective power capacity will AI data centers require, and can the resulting chip demand drive earnings growth fast enough to outpace valuation compression?
Demand indicators have not weakened in parallel. Operating US data-center capacity reached 50.7GW at the end of June 2026, up 11.4GW year over year, or 29%. Pipeline capacity reached approximately 338GW, an increase of 216.6GW, or 179%, year over year. However, 338GW represents a pool of planned projects, not operating capacity that has already secured power, financing, land, grid connections, and customer orders. Bernstein’s contribution is that it does not convert the entire pipeline directly into revenue. Instead, it asks: if annual construction capacity genuinely increases by 50GW, 75GW, or 100GW by 2030, how much manufacturing capacity must the semiconductor industry prepare in advance?
The market previously viewed $250 billion as the long-term ceiling for a WFE supercycle. Bernstein’s new framework turns that ceiling into a set of decomposable intermediate variables: first actual gigawatts, then monthly wafer capacity, and finally equipment orders and earnings.
The WFE Supercycle Is Just Beginning: How AI Capex Could Push Semiconductor Equipment Spending to $250 Billion
From 1GW to 46,000 Wafers per Month: How the Model Works
The first step is to convert 1GW into racks and chips. Bernstein uses the Vera Rubin rack as a proxy for the 2030 compute architecture. At approximately 220kW per rack, 1GW of compute power corresponds to around 4,545 racks. Each rack consumes the equivalent of approximately 64.6 300mm wafers across advanced logic, HBM, conventional DRAM, and NAND. For the racks alone, 1GW therefore represents one-time demand for approximately 294,000 wafers.
That is not the entire requirement. In addition to in-rack graphics processing units, head-node central processing units, and HBM, AI systems require off-rack central processing units for agent orchestration, tool calls, data access, and system services. Bernstein assumes that the 70GW scenario in 2030 requires approximately 95.2 million central processing units, equivalent to around 1.36 million per GW. After excluding rack head nodes, each 1GW still requires approximately 9,027 advanced-logic wafers. Each peripheral central processing unit is paired with another 0.5TB of DRAM, translating into approximately 195,000 DRAM wafers per GW at an assumed 80% yield. The model also assumes a 30% compound annual growth rate for off-rack data-center NAND from 2028 to 2030.
The second step is to convert annual chip demand into steady-state monthly capacity. Combining in-rack and off-rack demand, each additional 1GW of annual build capacity requires approximately 46,000 wafers per month of incremental capacity: 24,400 DRAM wafers, 9,200 NAND wafers, 7,300 HBM wafers, and 5,300 advanced-logic wafers. The most easily overlooked conclusion is that memory accounts for 89% of total wafer volume, while advanced logic represents only 11%.
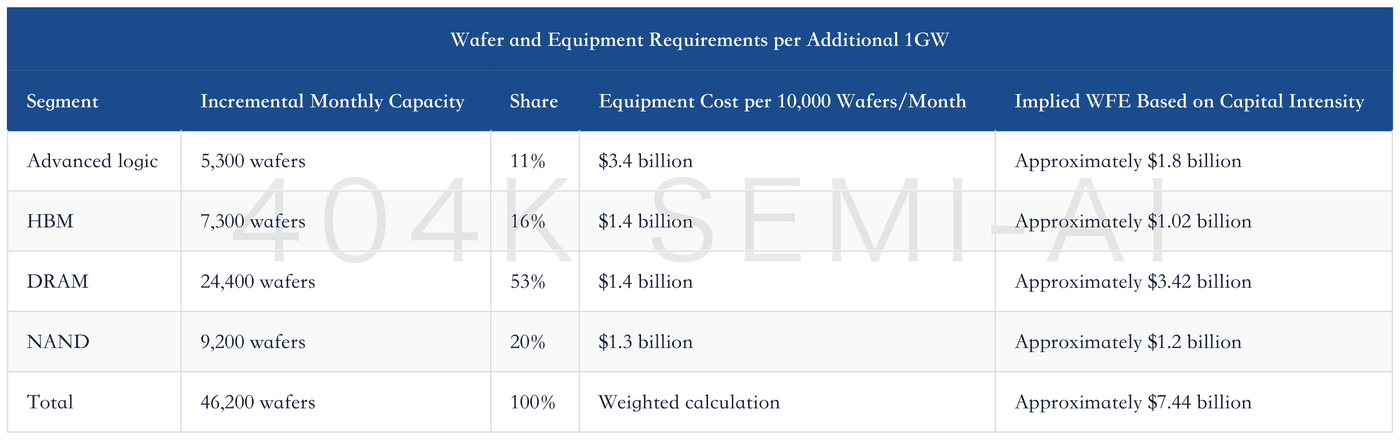
The third step is to convert monthly capacity into equipment capital expenditure. Bernstein estimates that each 10,000 wafers per month of advanced-logic capacity requires approximately $3.4 billion of equipment, while HBM and DRAM require around $1.4 billion and NAND approximately $1.3 billion. On the weighted basis shown above, each 1GW corresponds to approximately $7.44 billion, rounded in the report to $7.5–8.0 billion. Advanced logic has the highest capital intensity per unit of capacity, but memory wafer volumes are substantially larger. Memory therefore still contributes approximately three-quarters of incremental AI-related WFE.
This methodology is more useful than assuming equipment spending rises in direct proportion to cloud-provider capex because each layer can be tested against real-world data. Any change in rack power consumption, chip die size, yields, server configuration, DRAM capacity, or NAND growth will alter the resulting WFE estimate.
