
目录
TL;DR
I. One Earnings Week, Four Distinct Earnings Models Under Review
II. AMD: Server Demand Continues to Rise, but the Real Test Is Product Transition and Profit Conversion
III. Astera Labs: Scorpio Drives the Near Term, While UALink and Optical Interconnects Extend Valuation Duration
IV. SanDisk: Fundamental Confidence at 9.5, but Earnings-Trade Confidence at Only 7.5
V. GlobalFoundries and Microchip Technology: Channel Destocking Is Progressing, but Industrywide Inventory Has Not Yet Normalized
VI. Aeva, IonQ, and NXP/Ambarella: Valuable Technology Assets, but Commercialization Timelines Cannot Be Ignored
VII. After Earnings, Do Not Focus Only on “Beats”; Identify Which Evidence Changes the Valuation Thesis
Conclusion: Growth That Can Clear High Expectations Is Scarce
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Morgan Stanley maps seven companies onto a single earnings framework this week. The real dividing line is whether revenue growth can overcome product transitions, inventory, and valuation hurdles and ultimately translate into profits and cash flow.
TL;DR
AI demand remains strong at AMD and Astera Labs, but the market’s focus has shifted to whether growth can exceed expectations. AMD’s server TAM and 2027 GPU revenue estimates were raised, although the MI455 ramp is heavily weighted toward the fourth quarter; Astera Labs’ Scorpio switch chips are entering their main ramp, and its price target was raised to $335, but the base case offers only approximately 7.6% upside.
SanDisk has the strongest fundamental conviction in this report, yet its near-term outcome is the hardest to trade. Morgan Stanley believes NAND has strengthened significantly again over the past 30 days, while long-term agreements are securing more 2027 supply and even extending into 2028–2029; however, near-term earnings expectations are already very high, and the author assigns 9.5/10 confidence to the cycle’s continuation but only 7.5/10 confidence that the share price will rise the day after earnings.
GlobalFoundries and Microchip Technology confirm that mature-node and analog semiconductors are recovering, but they do not prove that industry-wide inventories have normalized. Distributor inventory declined sequentially, while semiconductor-company and end-customer inventories remain materially above historical medians. Microchip Technology’s orders are closer to real demand, while GlobalFoundries must offset weakness in mobile RF with automotive, industrial, and data-center demand.
Aeva, IonQ, and NXP/Ambarella are milestone-driven assets that should not be valued directly on a single quarter’s revenue growth. Aeva is still expected to remain loss-making through 2028; IonQ’s acquisition of SkyWater materially changed its revenue profile and capital structure; the industrial logic behind NXP’s potential acquisition of Ambarella is sound, but the transaction remains an unconfirmed market rumor.
I. One Earnings Week, Four Distinct Earnings Models Under Review
This report covers Advanced Micro Devices (AMD), Astera Labs, GlobalFoundries, SanDisk, Aeva (AEVA), IonQ, and Microchip Technology, while also discussing market rumors that NXP Semiconductors (NXPI) may acquire Ambarella (AMBA). Simply grouping them under “semiconductor earnings week” would obscure the most important differences among these companies.
The first is structural growth in AI compute and interconnects. AMD must validate server CPUs, GPUs, and the transition to the new MI455; Astera Labs must validate the ramp in Scorpio switch chips driven by Trainium 3 and demonstrate that UALink, optical interconnects, and CPO can support the next phase of growth.
The second is NAND pricing and cycle duration. SanDisk’s near-term pricing, bit shipments, and gross margin are all strong. The real debate is whether long-term agreements will extend the cycle or exchange some upside optionality for greater certainty.
The third is inventory recovery in mature nodes, MCUs, and analog semiconductors. Both GlobalFoundries and Microchip Technology are seeing demand improve, but the former continues to face a mobile drag, while the latter’s next-quarter guidance did not exceed consensus despite low channel inventory.
The fourth is long-duration technology and M&A; optionality. Aeva, IonQ, and Ambarella all have technology assets worth examining, but they remain far from stable profitability. Research should focus on mass production, customer validation, and cash consumption rather than revenue surprises in one or two quarters.
II. AMD: Server Demand Continues to Rise, but the Real Test Is Product Transition and Profit Conversion
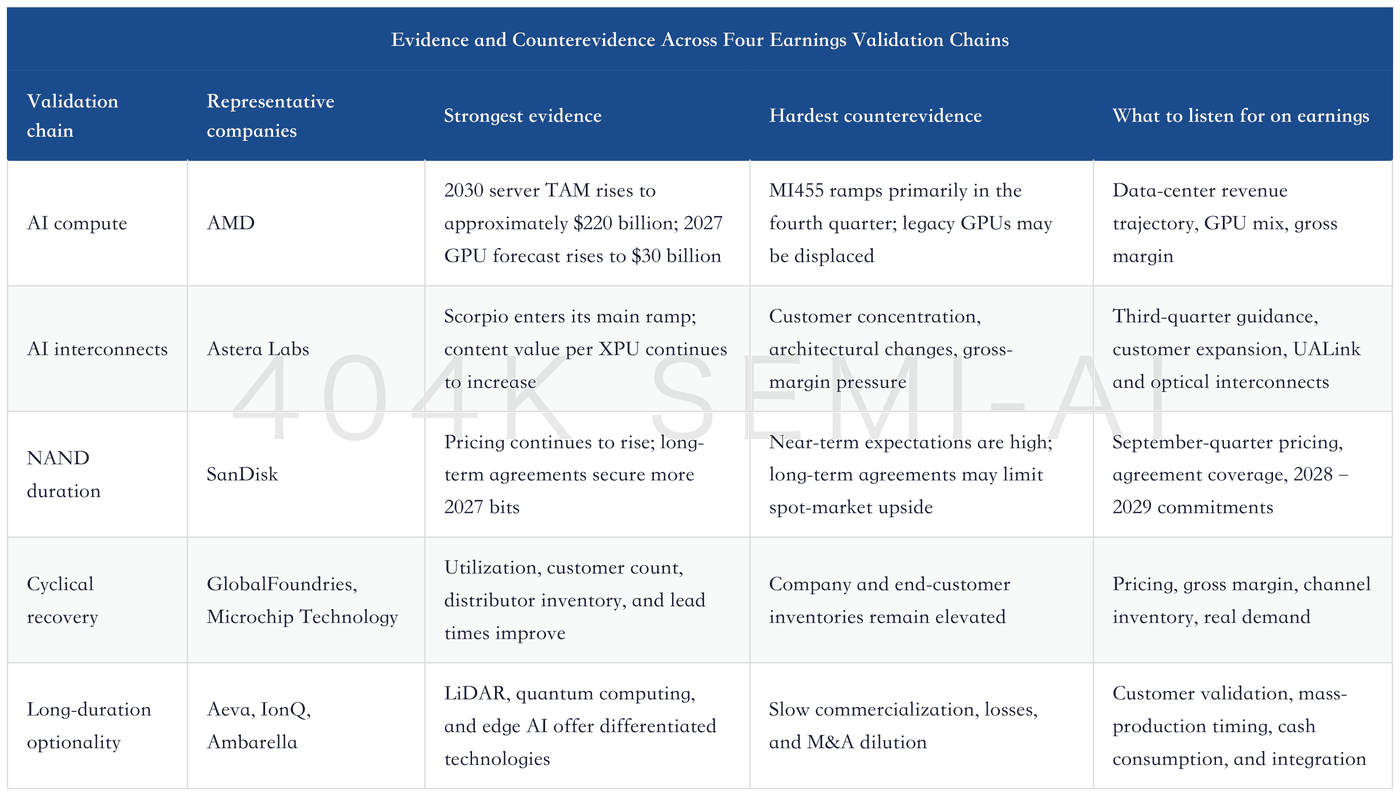
AMD’s demand outlook is one of the clearest upward revisions in this report. The company recently raised its 2030 server TAM from $120 billion to approximately $220 billion, implying an approximately 50% CAGR. On that basis, Morgan Stanley raised its server revenue growth forecasts for 2026 and 2027 to 79% and 49%, respectively, while raising its 2027 GPU revenue estimate from $23 billion to $30 billion; its 2026 GPU revenue estimate remains approximately $13 billion.
Growth will not flow smoothly into every quarter. The MI455 contribution is more heavily weighted toward the fourth quarter. Morgan Stanley expects third-quarter GPU revenue to increase by approximately $700 million from the second quarter, followed by another approximately $2.2 billion increase in the fourth quarter. Meanwhile, legacy Instinct products still represent a quarterly revenue base of approximately $2.5 billion, and the ramp of new products may coincide with declining legacy-product revenue. Therefore, “MI455 shipments have begun” does not mean all incremental new-product revenue can simply be added directly to total GPU revenue.
Revenue and profit also do not lead in tandem in the model. Morgan Stanley expects second-quarter revenue of $11.297 billion, up 10.2% sequentially, and third-quarter revenue of $12.607 billion, up 11.6% sequentially, including 20.8% sequential growth in data centers. However, its third-quarter gross-margin forecast of 54.8% and EPS forecast of $1.85 show no stronger operating leverage than consensus. Its 2027 revenue forecast of $76.102 billion is below consensus of $79.63 billion, while its EPS forecast of $14.19 is above consensus of $13.83. Morgan Stanley’s real bet is on product mix and margins, not on unconditionally pushing total revenue to the highest possible level.
Valuation raises the verification threshold further. The $410 base-case price target is based on approximately 31 times 2027 earnings and is below the share price of approximately $476 at the time of the report. The $570 bull-case target requires the company to solidify its position as the No. 2 data-center GPU vendor, while the $210 bear-case target assumes weaker AI momentum, intensified server competition, and GPU revenue falling short of expectations. Inventory days are also forecast to rise to 212.4 days in 2026. Elevated inventory can support a new-product ramp, but it may also indicate mismatches in demand, product transitions, or supply preparation; management must explain it alongside the delivery cadence on the earnings call.
The earlier AMD First-Quarter 2026 Earnings Review already showed that CPUs, GPUs, and systems are jointly expanding data-center revenue. The new conclusion here is that demand continues to strengthen, but further share-price appreciation requires MI455 execution, server-share gains, and gross-margin delivery simultaneously; a standalone revenue beat is no longer sufficient.
III. Astera Labs: Scorpio Drives the Near Term, While UALink and Optical Interconnects Extend Valuation Duration
Astera Labs’ near-term catalyst is the ramp of Scorpio switch chips in Trainium 3. Morgan Stanley expects second-quarter revenue of $362.2 million, up 17.4% sequentially and 88.7% year over year; third-quarter revenue is expected to reach $405.7 million, up 12.0% sequentially. Scorpio is expected to become the company’s largest product line in December, and the upcoming earnings report still has the potential to deliver a “beat and raise.”
However, the third-quarter revenue forecast is below the consensus estimate of $412.2 million, while EPS of $0.73 is also below the $0.79 consensus. Despite rapid revenue growth, non-GAAP gross margin is expected to decline from 75.8% in 2025 to 70.4% in 2028. R&D; investment, product mix, and non-cash expenses related to customer warrants will all create a gap between revenue growth and EPS growth.
The longer-term thesis rests on platform expansion. The combined addressable market for UALink and PCIe is approximately $10 billion, with UALink and optical-interconnect revenue expected to begin scaling in 2027, while CPO provides a longer-dated upside option. Management aims to increase content value per XPU from more than $1,000 today to $10,000 over the next 3—5 years. Achieving this goal will require retimers, switch chips, optical connectivity, and custom solutions to add increasing value within the same rack.
The price target was raised from $240 to $335, based on 2027 sales and approximately 40% revenue CAGR from 2025—2028. With the shares trading at approximately $311 at the time of the report, base-case upside is only 7.6%, while the $181 bear-case target implies approximately 41.8% downside. The valuation already requires the company to demonstrate that it has more customers beyond Amazon, that another product cycle will follow Scorpio, and that changes in connectivity protocols will not shift value back to customers’ in-house solutions.
This aligns with the earlier conclusion in Triple Validation of AI Networking: Astera Labs’ value derives from the complexity of AI rack connectivity, rather than a one-off volume ramp in any single generation of retimers. The most important questions on the earnings call concern new customers and new protocols, rather than simply how much Trainium 3 has sold.
IV. SanDisk: Fundamental Confidence at 9.5, but Earnings-Trade Confidence at Only 7.5
SanDisk presents the report’s clearest combination of bullish fundamentals and cautious trading expectations. Morgan Stanley believes the NAND market has strengthened materially again over the past 30 days, with cloud customers concerned that they may be unable to secure sufficient supply this year, next year, or even the year after. The authors assign 9.5/10 confidence to sustained fundamental strength, but only 7.5/10 confidence that the shares will rise on the first day after earnings, because buy-side expectations for the current and following quarters are already high.
The near-term model remains strong. Morgan Stanley expects June-quarter revenue of $8.197 billion, bit shipments up 12% sequentially, average selling prices up 23% sequentially, gross margin of 80.4%, and EPS of $33.27; September-quarter revenue is expected to reach $10.841 billion, with both bit shipments and average selling prices up 15% sequentially, gross margin rising further to 85.7%, and EPS of $46.42. Kioxia’s prices rose by approximately 70% over the same period, but the two companies have different business mixes, and the report does not mechanically apply that increase to SanDisk—a reasonable degree of caution.
The annual forecasts reveal the more important divergence. Morgan Stanley expects 2026 revenue of $38.078 billion, materially above the $34.454 billion consensus; EPS of $161.07 is also above the $137.07 consensus. By 2027, however, its revenue forecast of $48.278 billion is below the $52.733 billion consensus, while EPS of $208.11 is likewise below the $226.67 consensus. Sell-side estimates are more optimistic about near-term pricing and margins, but less aggressive than the market regarding longer-term sustainability.
Long-term agreements are the central valuation variable. Approximately one-third of fiscal 2027 bits had already been locked in under agreements last quarter, and coverage is now expected to have increased materially. These agreements sacrifice some spot-price upside in exchange for duration, prepayments, or demand commitments; if the largest cloud customers are willing to commit capital in advance to secure supply for 2028—2029, that itself validates the duration of the cycle. Importantly, agreement pricing is not permanently fixed and can still be adjusted based on timing and market conditions; it should not be simplistically interpreted as “signing a contract locks in profits.”
The $1,750 price target is based on 28 times through-cycle EPS of $62.50. It deliberately avoids valuing the company directly on peak-cycle annual EPS of more than $200, indicating that Morgan Stanley is also guarding against a cyclical downturn. SanDisk has risen substantially year to date but has experienced a significant pullback over the past month; after earnings, investors should assess long-term agreements and supply commitments first, near-term pricing second, and only then whether the shares continue to respond amid elevated expectations. The earlier In-Depth SanDisk Update discussed the durability of NAND profits; the new evidence this time is that agreement coverage continues to expand and cloud customers’ supply concerns now extend into more distant years.
V. GlobalFoundries and Microchip Technology: Channel Destocking Is Progressing, but Industrywide Inventory Has Not Yet Normalized
GlobalFoundries and Microchip Technology are both improving, but the sources and quality of that improvement differ.
GlobalFoundries is being weighed down by the handset RF supply chain. Qualcomm accounted for approximately 15% of its revenue last year, and Qualcomm’s cautious view on its iPhone 18 share may affect GlobalFoundries’ content value in Apple-related RF components. On the positive side, demand from automotive, industrial IoT, communications infrastructure, and data centers continues to improve, while mature-node utilization is approaching full capacity; UMC’s utilization rate has already reached approximately 90%, providing an industry benchmark for price increases in comparable products during the second half.
Morgan Stanley expects GlobalFoundries’ second-quarter revenue to reach $1.761 billion, with gross margin of 28.5% and EPS of $0.42; third-quarter revenue is expected to reach $1.817 billion, below the $1.876 billion consensus, with gross margin of 29.5% and EPS of $0.48. The price target was cut from $65 to $57 because the 2027 valuation multiple was compressed from approximately 27 times to 24 times, while the EPS assumption remains $2.39. Improving fundamentals can increase the earnings numerator, but cannot guarantee that the market will continue to assign a higher multiple.
Microchip Technology’s channel signals are more constructive. Management believes the inventory correction has been prolonged but is largely complete, customer counts are recovering rapidly, distributor inventory is below the normal range, and customers are placing orders primarily to satisfy real demand rather than replenish inventory. Data-center solutions revenue is guided to increase from $303 million in 2025 to approximately $500 million in 2026; sixth-generation PCIe uses a 3nm process, but the main volume ramp is still expected in 2027.
Morgan Stanley expects Microchip Technology’s June-quarter revenue to reach $1.446 billion, up 10.3% sequentially, with gross margin of 62.6% and EPS of $0.70; September-quarter revenue is expected to reach $1.5143 billion, below the $1.5543 billion consensus, while EPS of $0.74 is also below the $0.80 consensus. The $94 price target corresponds to approximately 28 times 2027 earnings, and the rating remains Neutral. Operating readings from peers Texas Instruments, STMicroelectronics, and Renesas support a demand recovery, but analog semiconductor stocks generally declined after this earnings season, indicating that the market had already priced in the inventory inflection point.
Industry inventory data explain this contradiction: distributor inventory stands at 61 days, down 2 days sequentially but still 7 days above the historical median; semiconductor-company inventory stands at 114 days, up 2 days sequentially and 23 days above the historical median; end-customer inventory stands at 60 days, up 9 days sequentially. Channel destocking is progressing, but that does not mean manufacturer and customer inventories have both normalized.
Channel Improvement Is Outpacing Inventory Improvement at Companies and End Customers
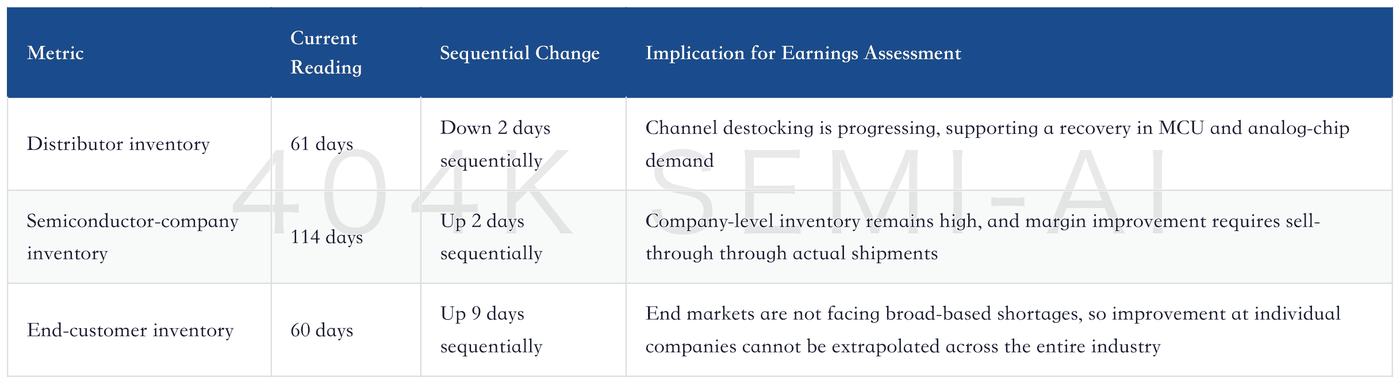
Therefore, Microchip Technology is closer to a “recovery driven by real demand,” while GlobalFoundries reflects an “offset between handset weakness and improving mature-node conditions.” Both companies need to demonstrate the quality of the recovery through gross margin and cash flow; revenue growth alone is not yet sufficient.
VI. Aeva, IonQ, and NXP/Ambarella: Valuable Technology Assets, but Commercialization Timelines Cannot Be Ignored
Aeva’s FMCW lidar is applicable to automotive, industrial sensing, and physical AI use cases, with Daimler, Torc, a leading European automaker, Bendix, NVIDIA Hyperion, and Omni 360-degree lidar all representing potential milestones. Morgan Stanley expects second-quarter revenue of $6.262 million and third-quarter revenue of $7.828 million. The original report body used the unit mn, but the table clearly labels the figures in thousands of dollars; the formal assessment must therefore treat them as being on the order of $1 million and must not overstate revenue by 1,000 times.
Even by 2028, Aeva’s projected revenue is approximately $181.7 million, while EPS remains negative at $1.09. The $18.50 price target is based on a 2028 revenue multiple and discounting; the true determinants of value are mass production, customer share, gross margin, and cash burn. CPO offers substantial potential, but it remains a longer-term opportunity and cannot yet be incorporated into earnings with certainty.
IonQ’s situation is more complex. The company’s revenue exceeded guidance by 20%—50% in each of the past 4 quarters, and second-quarter revenue is projected at $66 million; however, following the SkyWater acquisition, 2027 pro forma revenue is approximately $952 million, with a gross margin of only 25% and an operating loss of approximately $517 million. Most of the revenue and physical assets come from SkyWater, and IonQ has shifted from a relatively pure-play quantum computing company into a capital-intensive company spanning quantum computing, wafer foundry services, and space platforms.
The $48.50 price target applies approximately 45 times 2027 sales. For the valuation to hold, the 256-qubit system must be demonstrated by the end of 2026 and delivered in the first half of 2027, while the company must also prove that its quantum technology advantages can generate sustained commercial revenue. If investors focus only on the post-acquisition revenue increase while ignoring gross margin and operating losses, the conclusion will be fundamentally distorted.
A potential combination of NXP and Ambarella has a clear industrial rationale. Ambarella specializes in low-power machine vision and edge AI, while NXP is stronger in software-defined-vehicle central processors and automaker relationships but explicitly lacks camera-based ADAS and LiDAR capabilities. NXP has already acquired Kinara, TTTech Auto, and Aviva Links, and Ambarella could add the vision and autonomous-driving layer.
A sound transaction rationale does not mean that a transaction has already occurred. The report remains unconfirmed by either party, and Morgan Stanley has not verified its authenticity. Ambarella previously lost the competition for Volkswagen’s Level 3 program, highlighting the difficulty smaller suppliers face in entering critical automotive platforms; NVIDIA, Mobileye, and Qualcomm also have greater resources. Even if the transaction proceeds, Ambarella’s equity compensation and limited GAAP earnings may cause near-term dilution, while meaningful revenue contributions may not emerge until after 2028. The correct research sequence should be customer validation, transaction terms, integration pathway, and only then synergy revenue.
VII. After Earnings, Do Not Focus Only on “Beats”; Identify Which Evidence Changes the Valuation Thesis
Industry share-price performance has already shown that strong fundamentals and trading outcomes can diverge. SanDisk’s year-to-date gain is among the highest across the covered companies, yet the shares have pulled back sharply over the past month; Advanced Micro Devices has also risen significantly this year, even though its base-case price target was below the share price at the time of the report. Astera Labs received an Overweight rating, but its base-case price-target upside is limited. The market is shifting from “the direction is right” to “the pace of delivery must be fast enough.”
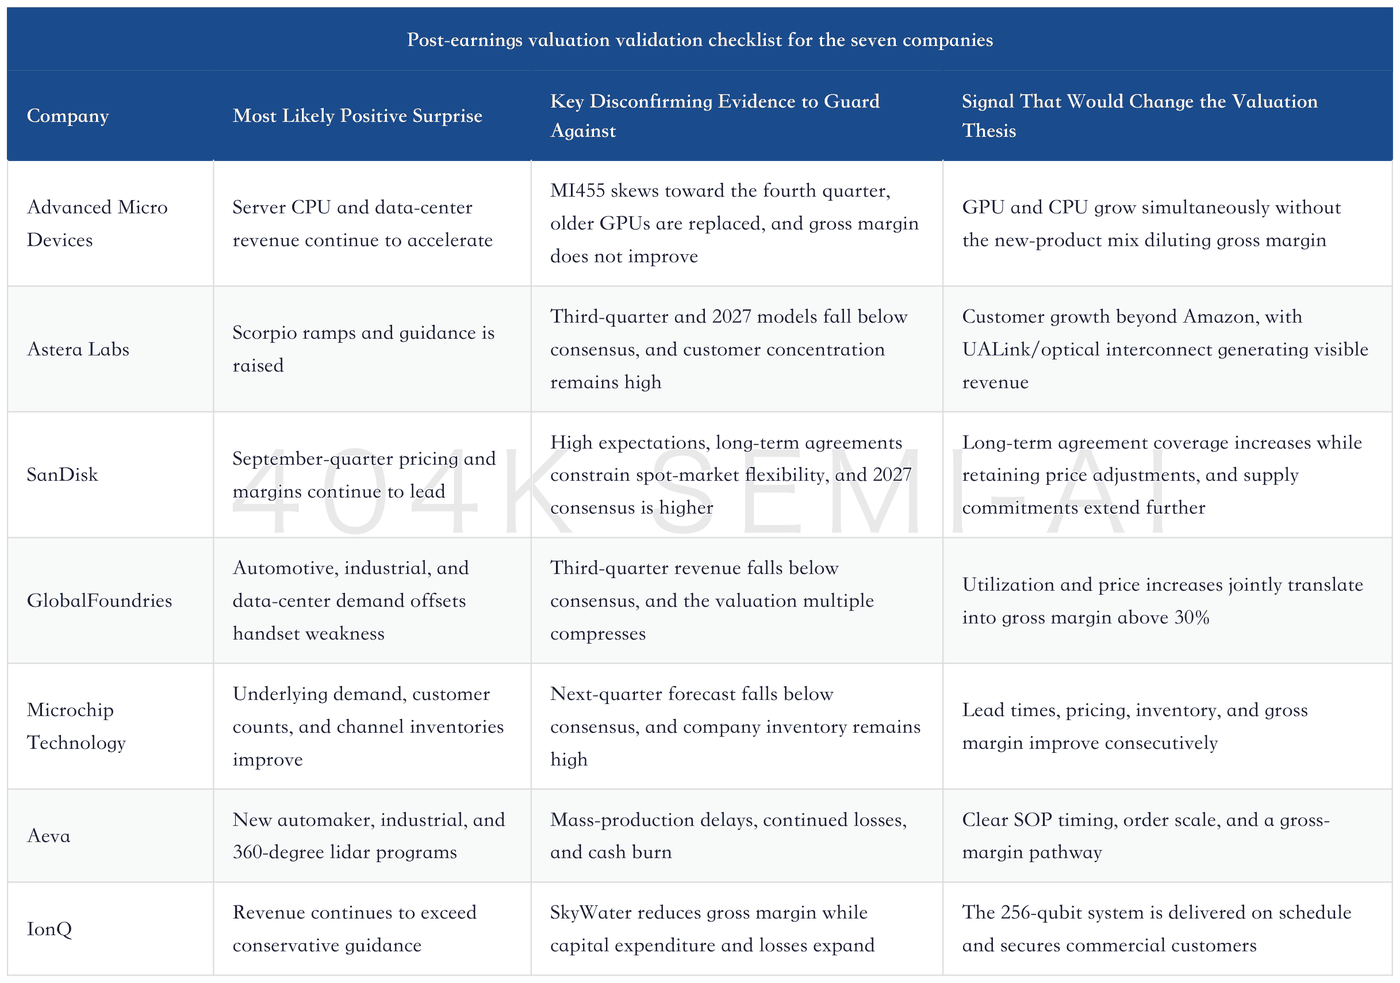
Sequencing also matters. On August 4, first assess Advanced Micro Devices and Astera Labs to validate AI compute and interconnect demand; on August 5, focus on GlobalFoundries, SanDisk, Aeva, and IonQ to validate mature-node semiconductors, NAND, lidar, and the post-quantum-acquisition financial structure, respectively; on August 6, use Microchip Technology to validate the inventory cycle in analog chips and MCUs. For each company, investors should first check next-quarter guidance, then gross margin and inventory, and finally assess whether the price target and valuation multiple still have room for adjustment.
Conclusion: Growth That Can Clear High Expectations Is Scarce
The most valuable aspect of this Morgan Stanley weekly report is that it separates several seemingly similar forms of “high growth” across the industry.
Advanced Micro Devices and Astera Labs operate in the strongest AI demand segment, with revenue trajectories still rising, but their valuations require simultaneous execution on new products, customers, and gross margins. SanDisk has the strongest near-term earnings upgrades, while long-term agreements add duration to the cycle, but near-term expectations are already so high that “good results” may not be enough to drive the share price. GlobalFoundries and Microchip Technology demonstrate that mature-node semiconductors and analog chips are recovering, yet improvements in distribution inventory have not yet broadened into industry-wide inventory normalization. Aeva, IonQ, and NXP/Ambarella offer technology and M&A; optionality, but value realization still depends on customers, mass production, and capital discipline.
Therefore, the most effective framework this week is not to rank the 7 companies by “who will beat expectations,” but to verify each point individually: whether revenue comes from genuine demand or inventory transfers, whether product transitions erode gross margin, whether long-term agreements preserve pricing flexibility, whether longer-term technologies have achieved customer validation, and whether earnings growth is outpacing the valuation the market has already paid. Only companies that can clear all these thresholds have room for sustained post-earnings re-rating.
Quarterly results, next-quarter guidance, price targets, and medium- to long-term models that had not yet been released in the report are based on Morgan Stanley’s forecasts as of August 3, 2026, and are presented as estimates rather than realized results.