
Semiconductor Deep Dive: The Memory Tax Spills Over, and How SanDisk, Applied Materials, and onsemi’s Synaptics Deal Reprice AI Hardware
目录
Too Long; Didn’t Read
1. Bottom Line First: This Report Is About Phase 2 of the AI Hardware Trade
2. Memory Tax Spillover: Why Microsoft and Apple Price Hikes Matter
3. SanDisk: NAND Upside Is Moving From Price Increases to eSSD Share Recovery
4. Micron’s Long-Term Contracts Provide Corroboration: Storage Profits Are Becoming Contracted
5. Applied Materials: Buying WFE Volume Is Not Enough; Investors Also Need to Buy Process Intensity
6. China WFE Decline: Short-Term Noise or a Cycle Inflection?
7. Advanced Packaging: CoPoS and Panel-Level Packaging Extend the Equipment Logic
8. onsemi Acquires Synaptics: Physical AI Ambition and Valuation Dilution
9. MCU Price Increases: Mature Nodes Are Also Being Squeezed by AI
10. Cerebras, Qualcomm, and Power: Alternative Architectures Show Bottlenecks Are Spreading
11. Three Worldviews: Memory Cycle, Equipment Intensity, Physical AI Platform
12. Company and Segment Ranking: Who Looks Most Like a Bottleneck Asset
13. Why AI Hardware Will Diverge
14. New Information in This Report Relative to Our Prior View
15. Investment Framework: From Price-Increase Trades to Bottleneck-Asset Trades
16. Profit Bridge: From Memory Tax to EPS, There Are Six Gates in Between
17. Scenario Framework: Base Case Is Diffusion, Bull Case Is Contracting, Stress Case Is Demand Destruction
18. What Numbers to Watch Over the Next Four Quarters
19. Disconfirmation Checklist: When to Reduce Exposure
20. Allocation Tempo: Price and Share First, Then Orders and Platformization
21. Conclusion: In Phase Two of AI Hardware, the Market Buys Whoever Controls the Bottleneck
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
What really matters in this Jefferies semiconductor update is that it pushes memory price inflation from AI servers into consumer electronics, equipment intensity, and edge AI. This piece breaks down the earnings transmission behind SanDisk, Applied Materials, and onsemi’s Synaptics transaction, and assesses which bottleneck assets matter in Phase 2 of AI hardware.
Too Long; Didn’t Read
The memory tax is starting to spill over. Microsoft and Apple raised prices on some consumer electronics, showing that memory inflation has moved from AI data centers into endpoint hardware costs; upstream earnings power is strengthening, while downstream demand elasticity is also being compressed.
SanDisk is a high-beta NAND name. Jefferies raised its SanDisk target price to $3,000, driven by eSSD share recovery, progress in TLC and QLC enterprise SSDs, and stronger preference for SLC NAND.
Applied Materials benefits from equipment intensity. DRAM, HBM, 3D DRAM, and advanced packaging lift equipment value per unit of capacity; Applied Materials spans front-end, interconnect, hybrid bonding, CoPoS, and panel-level packaging.
onsemi is betting on edge AI. The Synaptics acquisition expands the company from power, sensing, and control into edge compute, connectivity, and human-machine interface, increasing the physical AI optionality while also making the valuation framework more complex.
Corroborating evidence comes from multiple chains. Micron long-term agreements, MCU price hikes, China WFE cadence, panel-level packaging, Cerebras, and Qualcomm’s data-center moves all point to bottlenecks spreading from GPUs into memory, power, packaging, and equipment.
The key is watching for falsification. If price hikes come with demand destruction, inventory build, or delayed capex, the beta will cool first; if long-term agreements, eSSD share, HBM4, CoPoS, and edge AI orders all materialize together, the rerating can continue to spread.
1. Bottom Line First: This Report Is About Phase 2 of the AI Hardware Trade
Jefferies’ June 26 semiconductor update appears to cover many topics at once: memory, SanDisk, Applied Materials, onsemi’s acquisition of Synaptics, China WFE, Micron, MCUs, Cerebras, power, panel-level packaging, and Qualcomm’s data-center business. The content looks scattered, but the main thread is not: the AI hardware trade is moving from “who sells GPUs” to “who controls bottleneck resources.”
In Phase 1 of the AI hardware trade, the market mainly bought GPUs, HBM, advanced packaging, and cloud capex. Phase 2 is more complicated, but also offers more opportunities: memory prices are moving from data centers into consumer electronics, DRAM and NAND companies are rewriting margin structures; equipment companies benefit not only from aggregate WFE, but also from higher process intensity in DRAM, HBM, 3D DRAM, hybrid bonding, and panel-level packaging; power, sensing, edge compute, and connectivity chips are starting to be placed inside the “physical AI” framework.
The Memory Tax Has Arrived: How AI Is Turning HBM, DRAM, and NAND into Global Macro Bottlenecks
This is also why the term “memory tax” is becoming increasingly important. In the past, memory price hikes were mainly seen as earnings beta for memory companies. Now, those price hikes are entering end-product pricing, server BOMs, MCU costs, automotive electronics, and industrial control. Rising prices support SanDisk, Micron, Samsung, SK hynix, legacy memory, and niche memory on one side, while also consuming non-AI endpoint demand on the other. The market has to buy upstream earnings beta while also watching for downstream demand destruction.
The most important part of the report is how five evidence chains interlock: Microsoft and Apple price hikes prove cost pass-through; SanDisk’s eSSD share recovery proves high-end NAND demand; Micron’s long-term agreements show the memory cycle becoming contractualized; Applied Materials’ Masterclass proves equipment intensity is rising; and onsemi’s Synaptics acquisition shows the AI hardware narrative spreading toward the edge and the physical world.
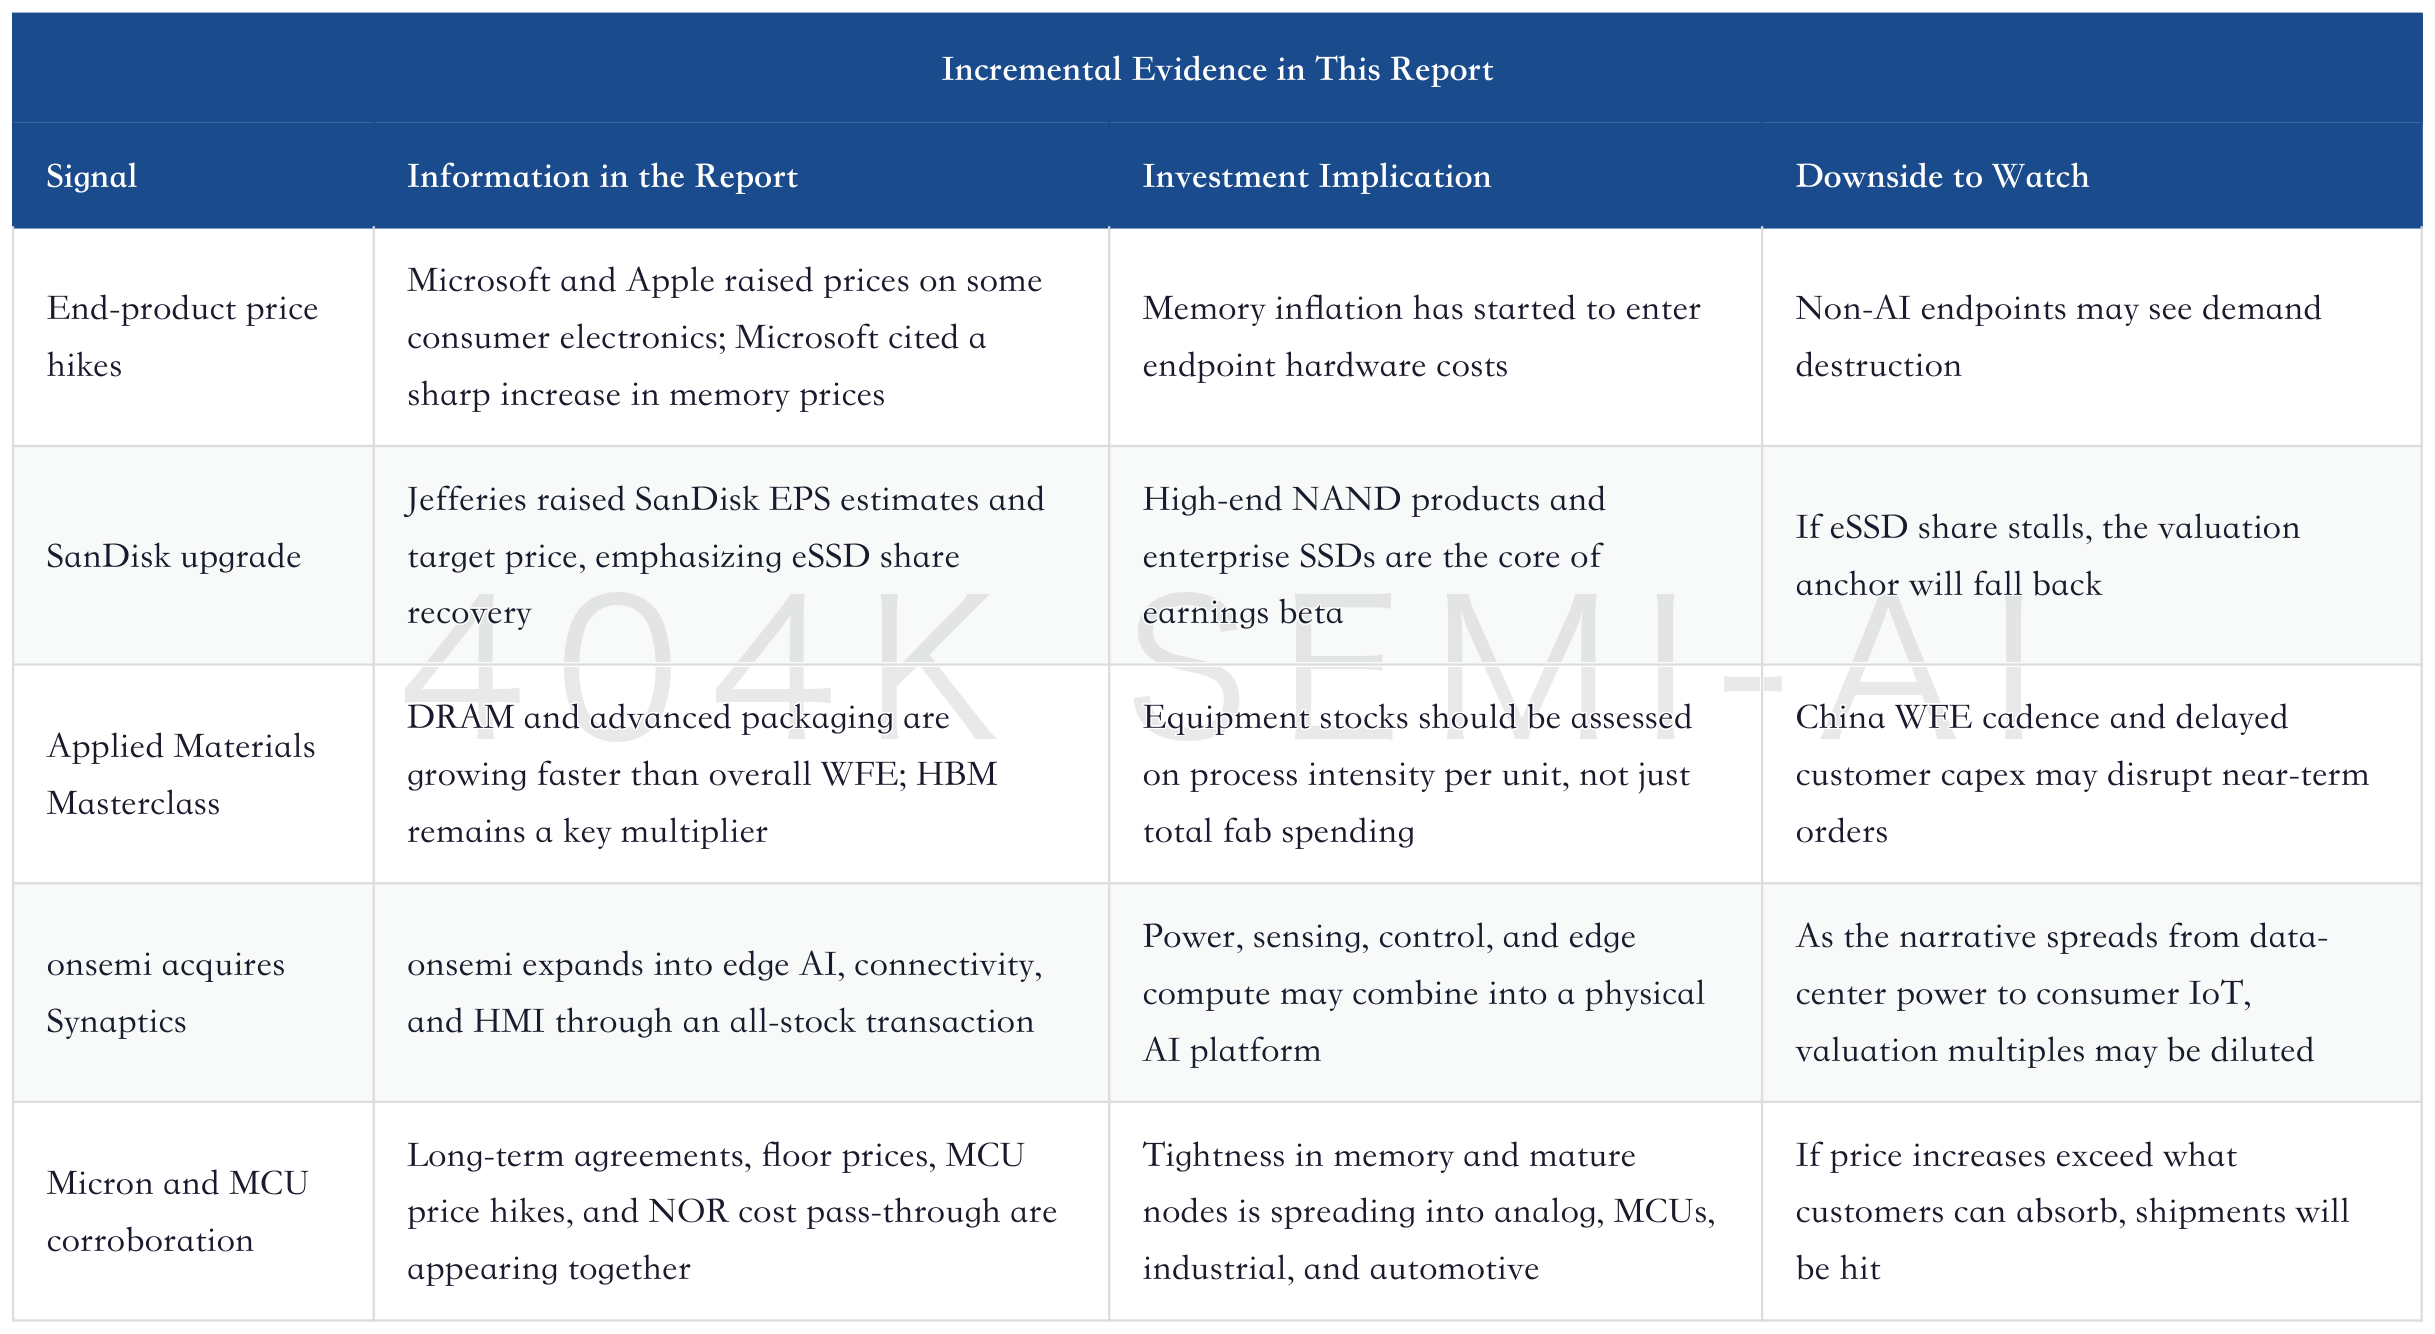
The judgment from this table is straightforward: AI hardware bottlenecks are moving from isolated points into a system. GPUs remain the core, but memory, power, equipment, packaging, interconnect, edge control, and long-term agreements will all affect profit distribution. For investors, simply asking “who is closest to Nvidia” is no longer enough. The better question is: “whose products become harder to replace in the next round of bottlenecks?”
2. Memory Tax Spillover: Why Microsoft and Apple Price Hikes Matter
The significance of Microsoft and Apple raising prices is not how much a specific model rose, but that the object of price hikes has spread from the cloud and AI servers into consumer electronics. Jefferies noted that Microsoft and Apple raised prices on products including Xbox, iPad, and MacBook Pro on June 25, and expects further adjustments may follow with the new iPhone cycle. Microsoft also attributed the move to a sharp increase in memory prices and expects continued upward pressure on memory prices.
This changes how the market reads the memory cycle. Rising memory prices had already been explained by data-center procurement, HBM shortages, and enterprise SSD pull-in for NAND. But when consumer electronics giants start raising prices, it means upstream costs have become large enough that they can no longer be absorbed solely through brands, channels, or internal component offsets. End-product price hikes are a watershed: they prove stronger pricing power for upstream memory suppliers, while also reminding the market that non-AI demand will be squeezed by prices.
The implications differ completely by company. For SanDisk, Micron, Samsung, SK hynix, Kioxia, and some niche memory companies, price increases mean higher gross margins and cash flow. For PCs, smartphones, consumer electronics, traditional server CPUs, and some industrial and automotive endpoints, price increases mean higher BOM pressure. Endpoint companies can raise prices once, but not indefinitely; customers can pull in inventory once, but not forever.
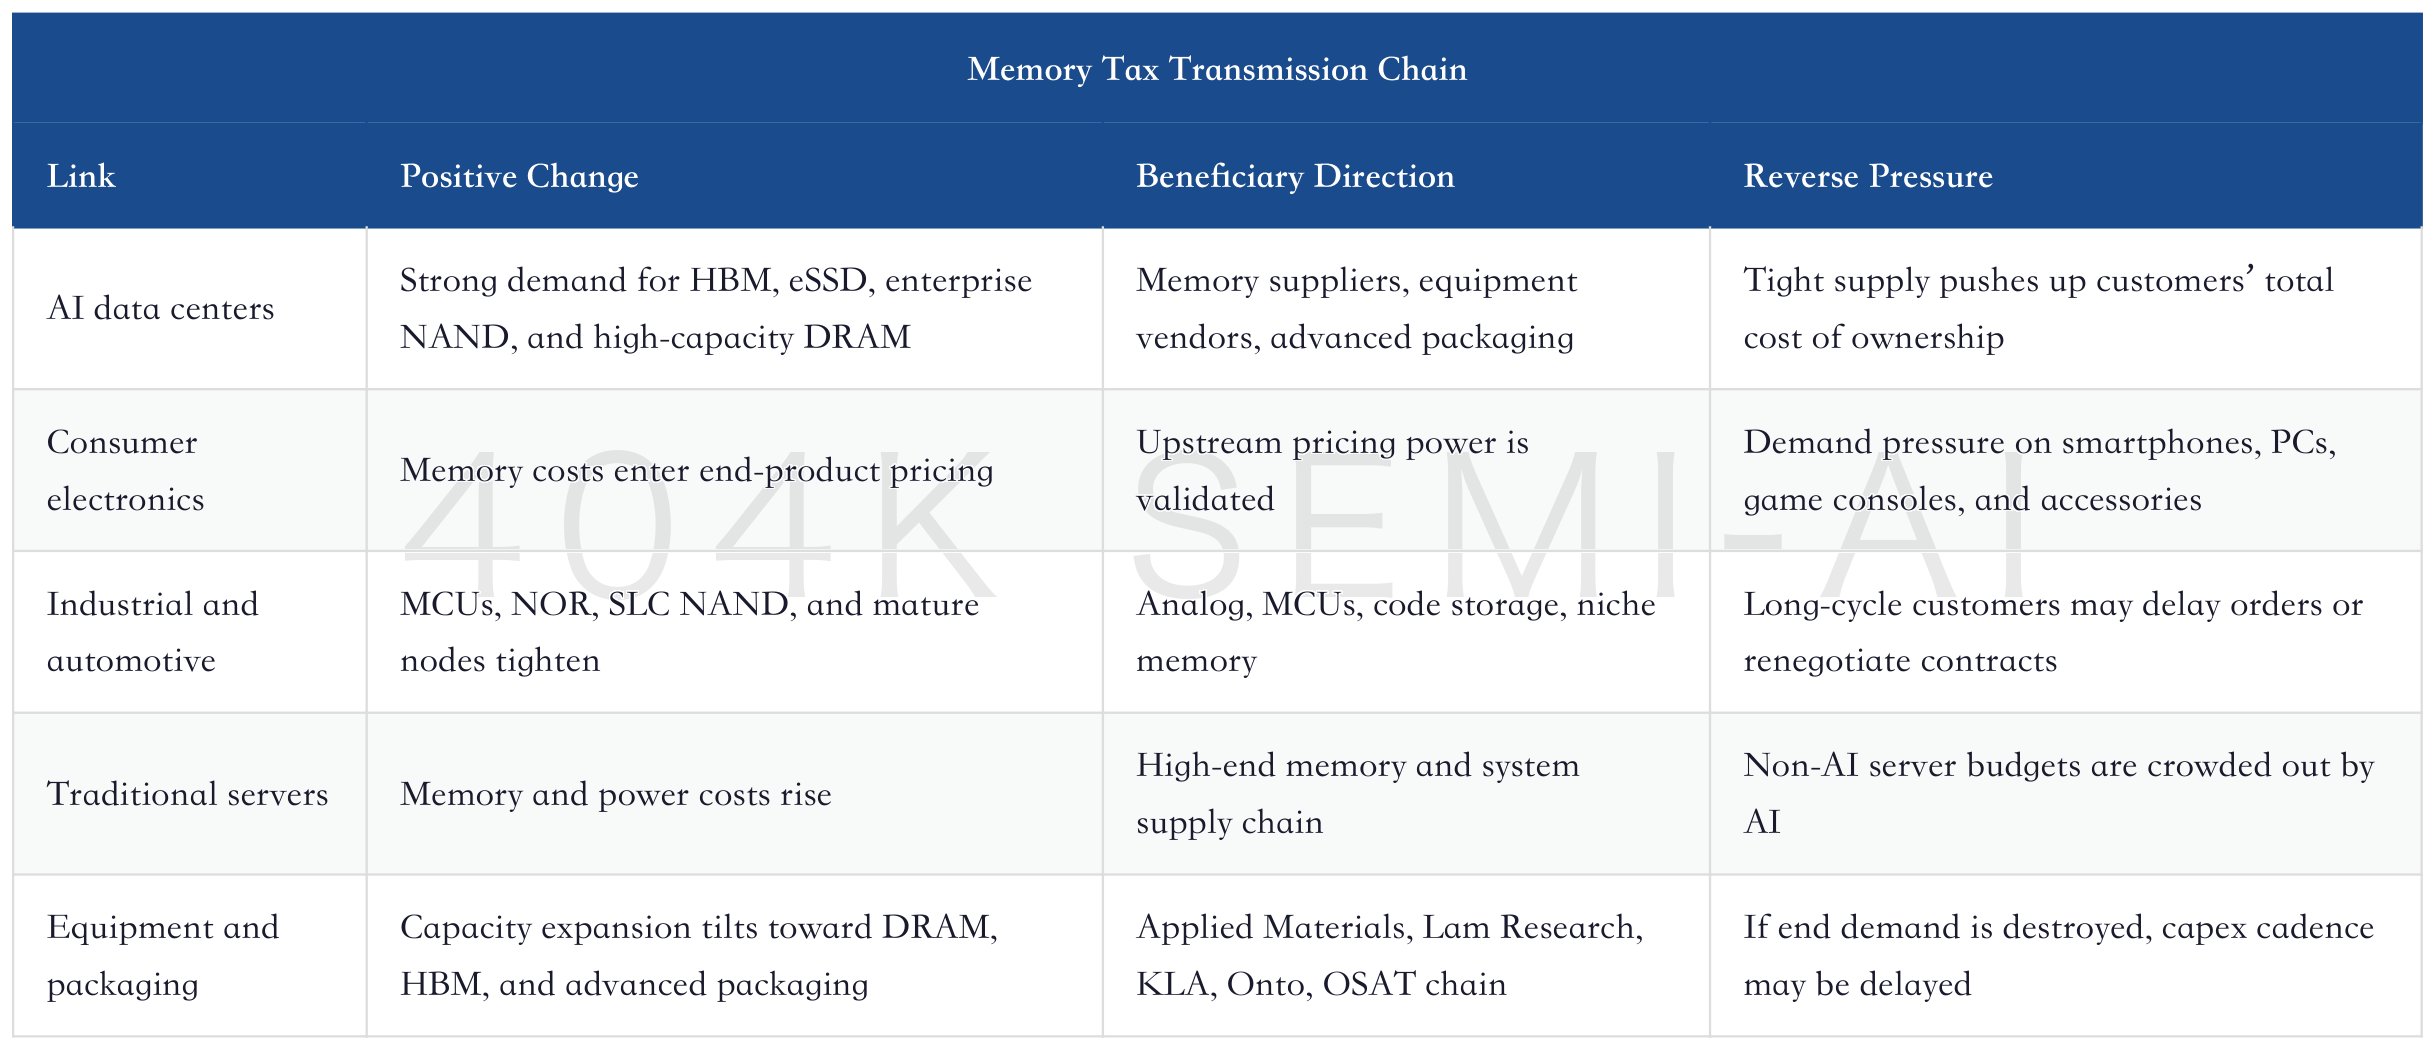
The ideal state for memory companies is rising prices, stable shipments, customers willing to sign long-term agreements, and equipment makers continuing to expand capacity. The most dangerous state is prices continuing to rise while end shipments start to fall, customer inventories build, and cash flow fails to keep up with accounting profits. This is why the next step is not only watching spot memory prices, but also revenue mix, long-term agreement coverage, customer inventory, server and PC shipments, and operating cash flow at memory companies.
3. SanDisk: NAND Upside Is Moving From Price Increases to eSSD Share Recovery
SanDisk is the most direct upside stock in this report. Jefferies raised its SanDisk price target from US$1,400 to US$3,000 and significantly lifted its C27 and C28 EPS forecasts. The upgrade is not just about “NAND price increases”; it also reflects enterprise SSD share, product mix, preference for SLC NAND, and long-term contracts jointly improving earnings durability.
SanDisk has historically been easy for the market to treat as a cyclical stock: NAND prices rise, profits surge; prices fall, and the valuation resets. Jefferies is now emphasizing a different logic: TrendForce data show SanDisk’s eSSD revenue share rose from 4% to 8% in the latest quarter, while historically SanDisk once reached a mid-teens share. As long as share continues to recover, SanDisk benefits not only from pricing but also from changes in the data-center customer mix.
SanDisk Deep-Dive Update: AI Demand, NBM Long-Term Contracts, and NAND Profit Durability
eSSD is the key dividing line in NAND investing. Consumer NAND price increases can drive profits, but data-center eSSD is more valuation-changing because it is tied to AI training, inference, data lakes, caching, and storage-tier restructuring. Customers are willing to pay for capacity, reliability, endurance, and supply stability, while storage companies are also more likely to secure long-term contracts, floor prices, and structurally higher gross margins.
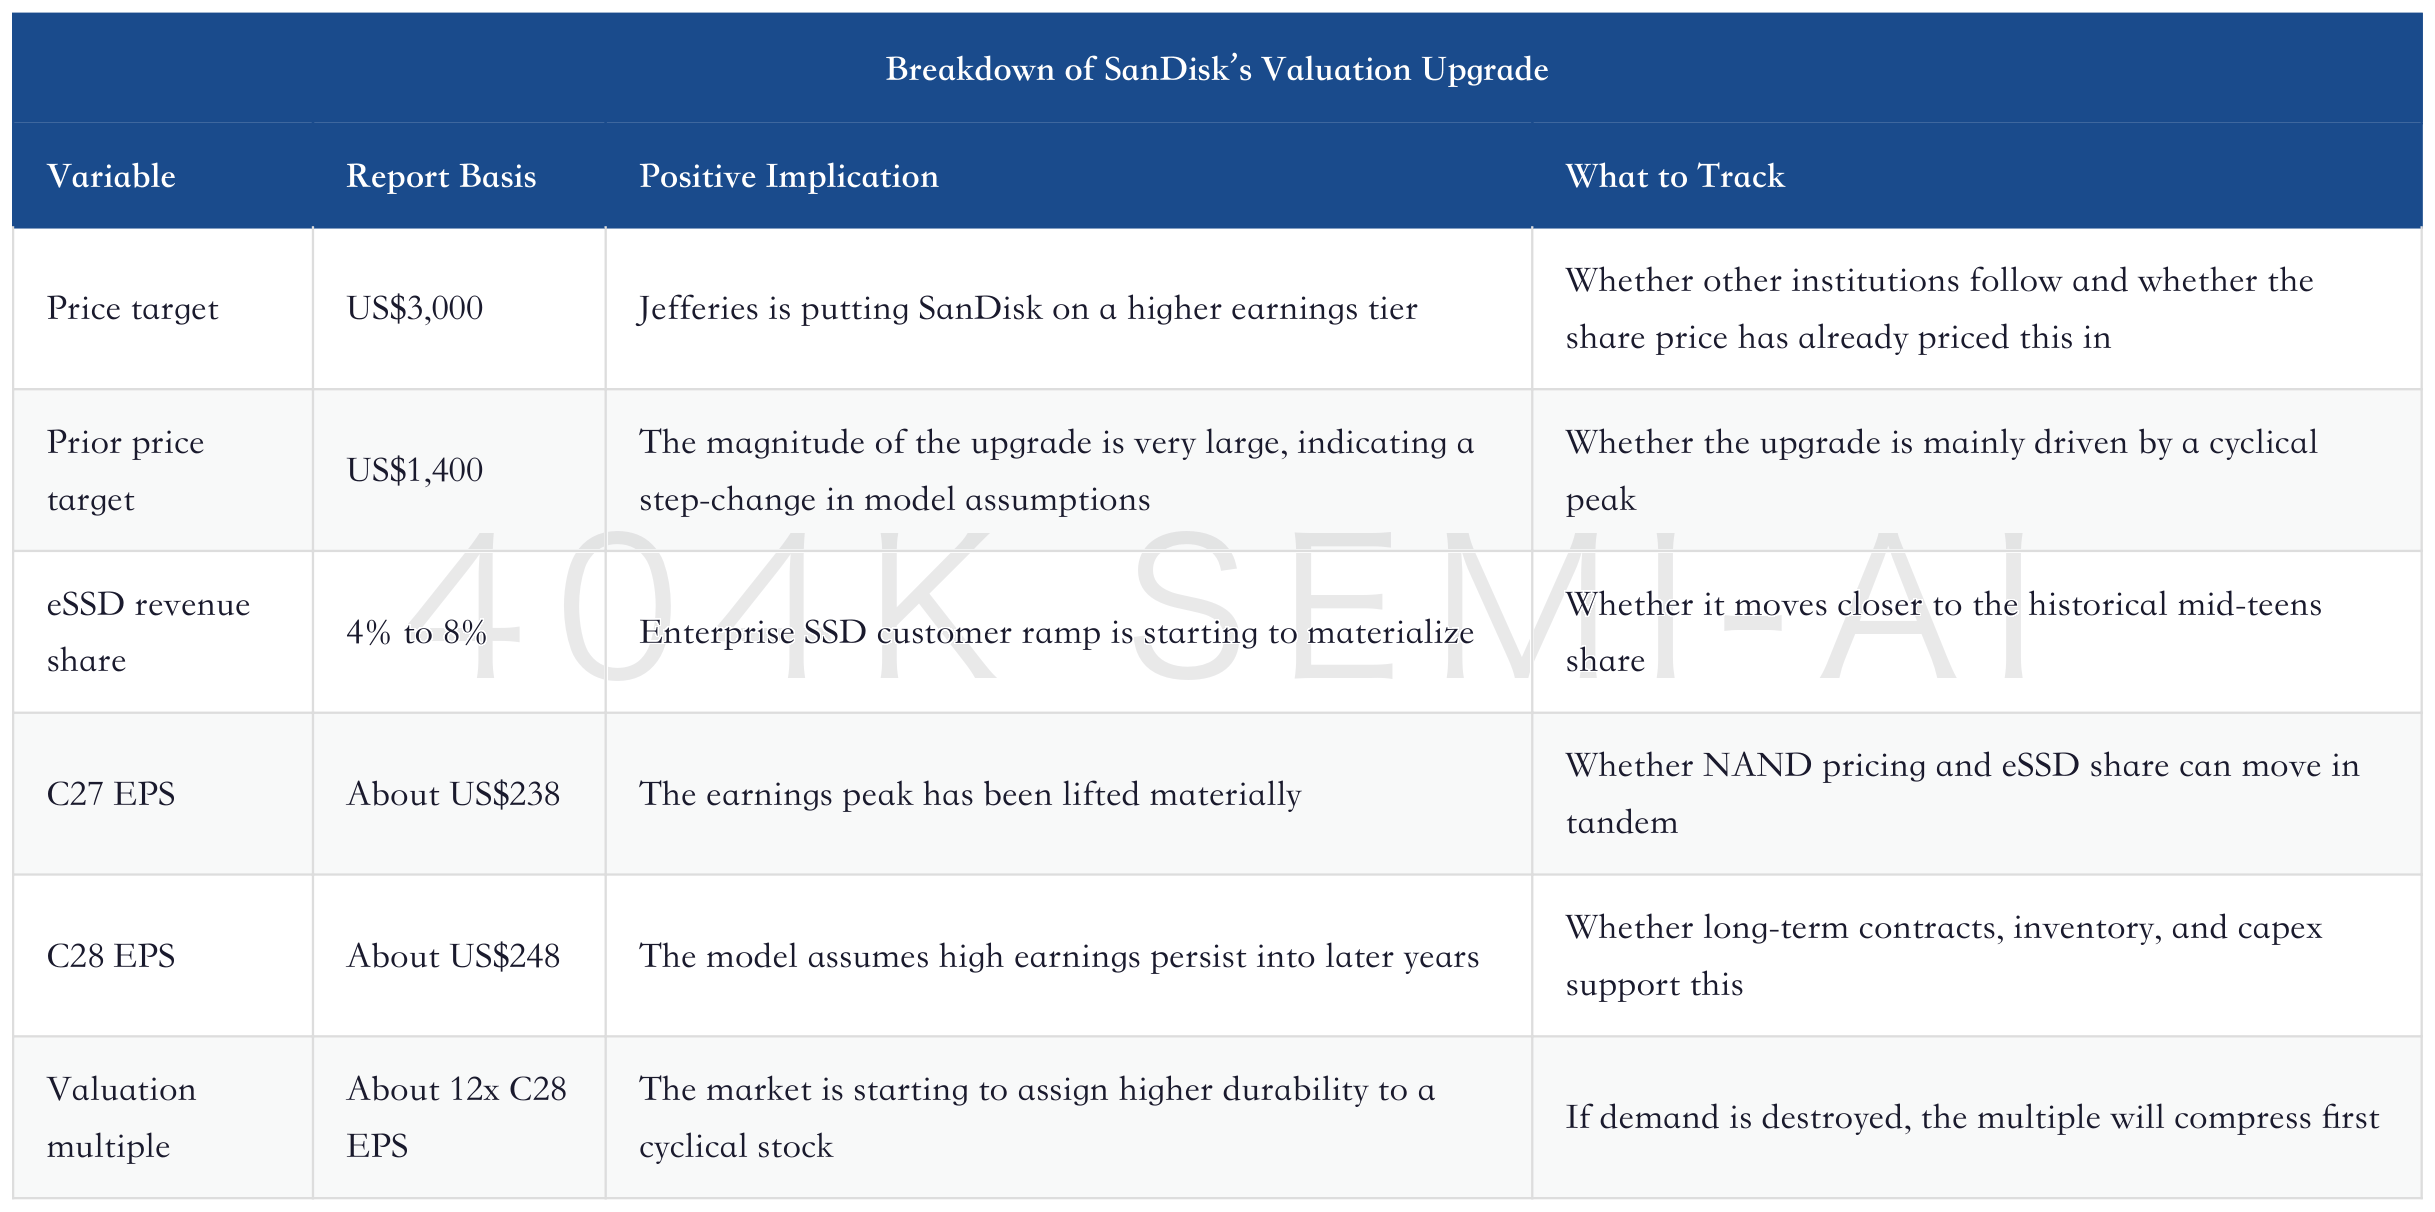
The two most important numbers in the table are eSSD share and C28 EPS. eSSD share determines whether SanDisk can move from being a consumer NAND cyclical stock to an AI data-center storage supplier; C28 EPS determines whether the earnings peak can be capitalized. If this is only about price increases, SanDisk remains a high-beta cyclical stock. If eSSD share, long-term contracts, and preference for SLC NAND improve together, the market will re-rate SanDisk as an asset with “AI storage capacity optionality.”
SLC NAND also deserves attention here. SLC NAND may sound less exciting than HBM, but it is critical in enterprise HDDs, firmware, hot data, defect mapping, and high-endurance scenarios. The report notes that supply-chain preference for SLC NAND is rising because it offers higher endurance than TLC and QLC. This shift could allow NAND price increases to spread from high-end eSSD into more granular industrial and enterprise applications.
SanDisk’s risks are equally clear. First, if eSSD share is only rebounding from a low base, the price-target upgrade will look too fast. Second, if NAND price increases cause customers to delay procurement, near-term profits may be strong, but later orders could face an air pocket. Third, SanDisk’s independent valuation after the separation from the Western Digital system still needs to be digested by the market, and single-product NAND exposure will amplify volatility when prices fall.
4. Micron’s Long-Term Contracts Provide Corroboration: Storage Profits Are Becoming Contracted
Micron’s latest results and guidance are important corroborating evidence for the SanDisk thesis. Jefferies notes in the report that Micron management emphasized multiple strategic customer agreements covering data center, consumer, and automotive, with contract terms primarily spanning multiple years and covering part of DRAM and NAND shipments. It also noted that these agreements include price floors, with gross margins expected to exceed prior cyclical peaks.
This matters more than a single quarter of price increases. Historically, the storage industry has struggled to receive high valuations because profits are easily consumed by the pricing cycle. EPS surges in the upcycle; in the downcycle, inventory write-downs, price declines, and utilization drops arrive together. Long-term contracts and floor prices change the profit distribution: they do not eliminate the cycle, but they can pull part of profits out of spot-price volatility, allowing customers and suppliers to jointly bear the cost of supply security.
Micron Earnings Deep Dive: Q3 Results Beat Sharply, the AI Storage Supercycle Enters the Monetization Phase, and How Much Profit Can Long-Term Contracts Lock In?
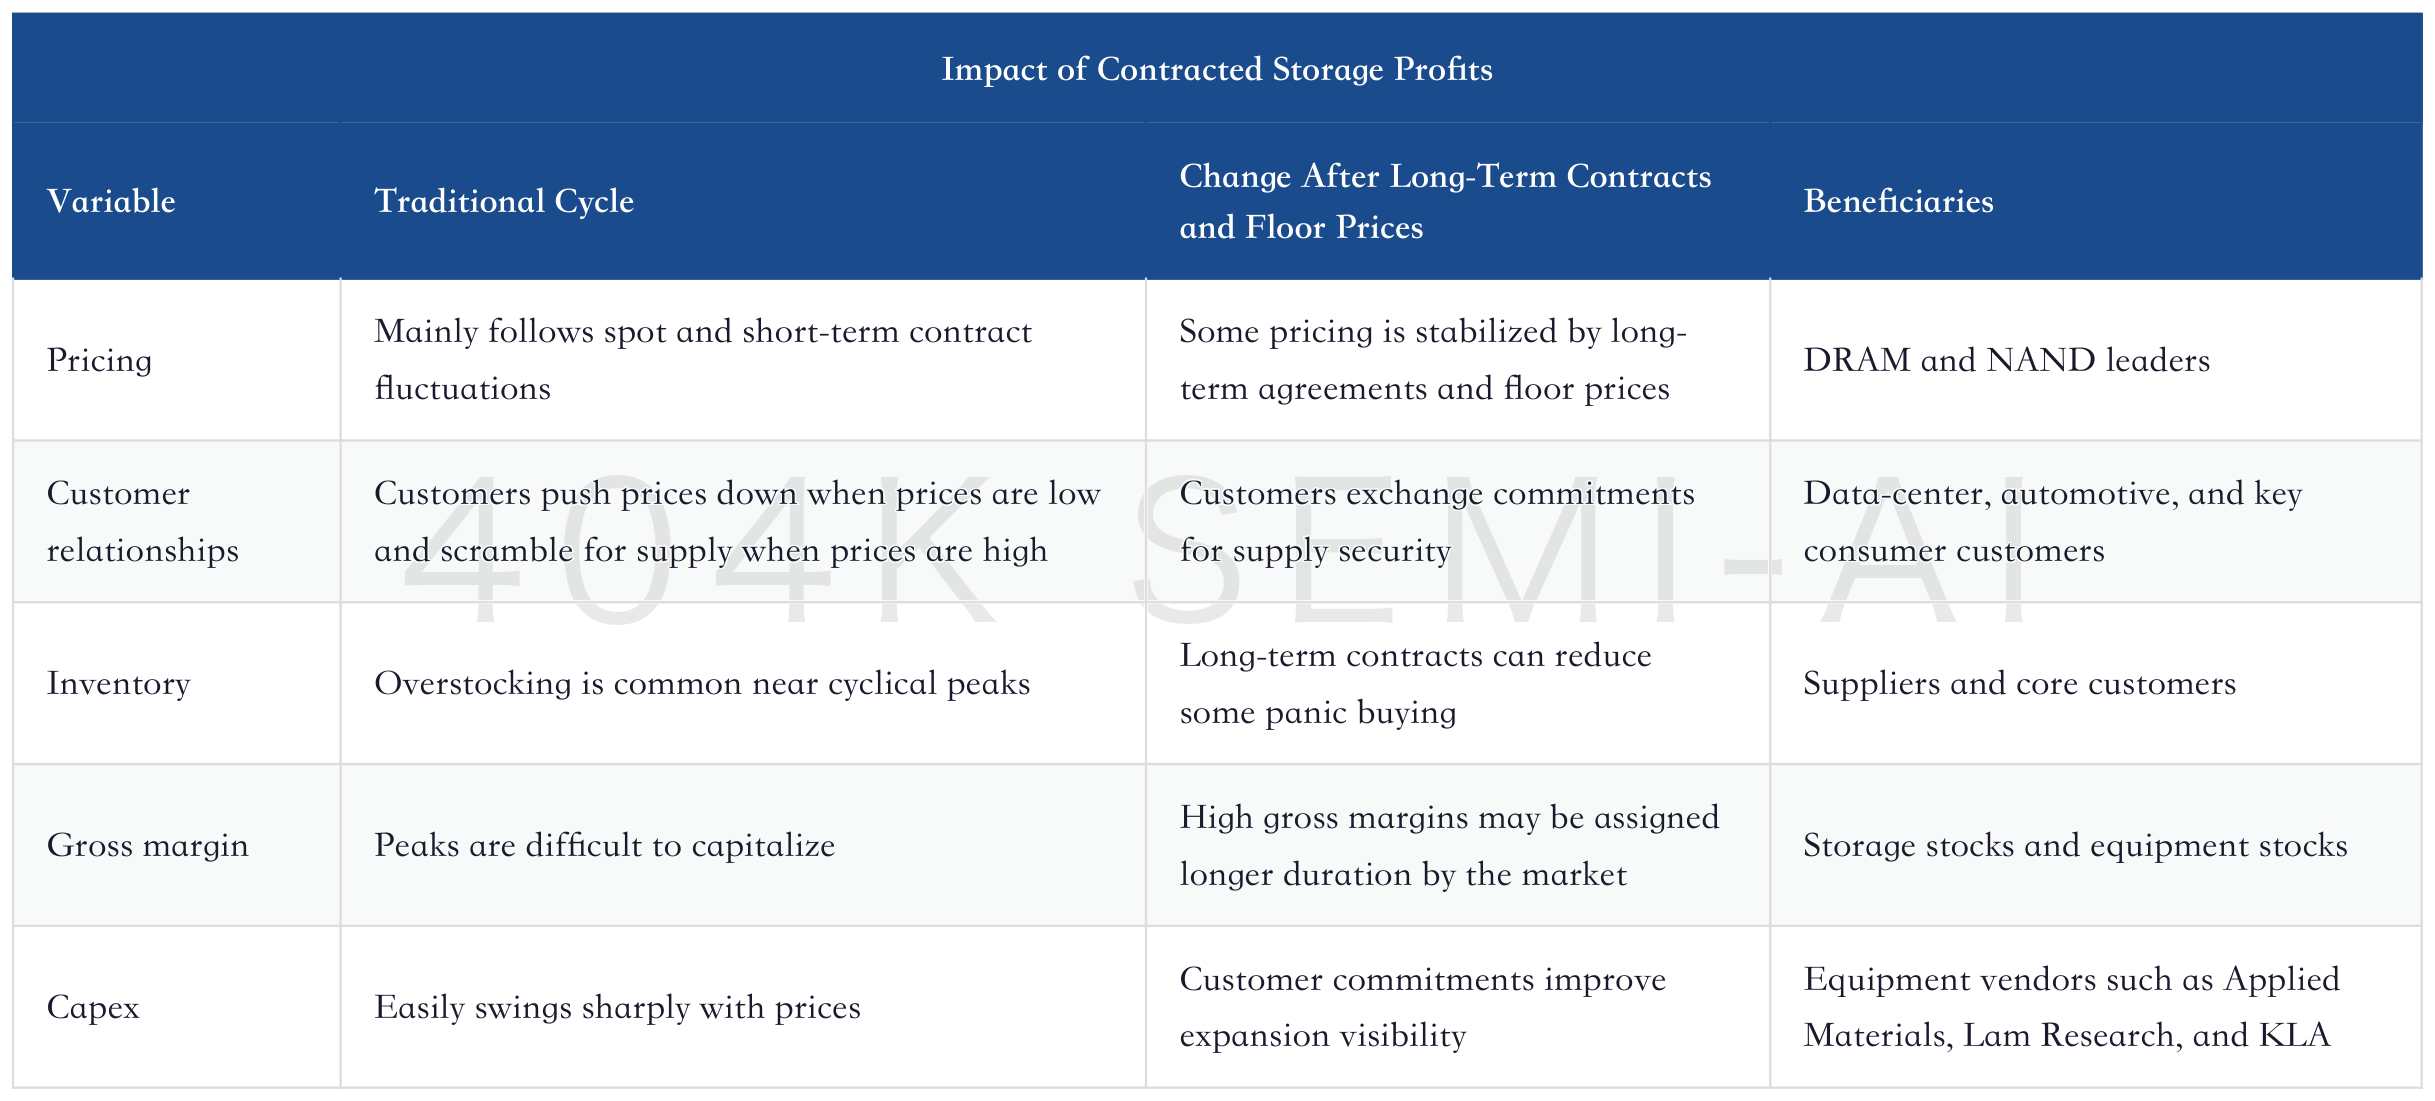
This table explains why SanDisk’s price target can be upgraded so sharply. If investors look only at NAND prices, they will worry about a cyclical peak. When they also see eSSD share, long-term contracts, SLC preference, and Micron’s price floors, they begin to assess whether peak profits can last longer. Valuation shifts from “a few times next year’s EPS” to “how many years high-gross-margin cash flow can persist,” and the stock’s upside naturally changes.
But long-term contracts also have limits. Customers sign them for supply security; they will not accept price increases unconditionally. If storage costs continue to squeeze end demand, customers will hedge through product design, procurement cadence, inventory management, and alternative architectures. For storage stocks, long-term contracts are a tool to improve profit quality; they cannot guarantee that prices rise forever.
5. Applied Materials: Buying WFE Volume Is Not Enough; Investors Also Need to Buy Process Intensity
Applied Materials is the equipment signal most worth amplifying in this report. In Jefferies’ summary of Applied Materials’ DRAM/AP Masterclass, the core point is that DRAM and advanced packaging are growing faster than overall WFE. In other words, AI hardware capacity expansion requires not only more fabs, but also more process steps, more materials, more interconnects, and more packaging equipment per unit of capacity.
From HBM to WFE: How AI Is Turning the Storage Cycle Into an Equipment Supercycle, and How Much Longer Can Semiconductor Equipment Rise?
DRAM itself is becoming heavier. The report notes that SAM per 100,000 wafer starts per month of DRAM capacity will rise from US$6 billion in the 6F² era to US$6.5 billion in the 4F² era, and then to US$7.5 billion in the 3D DRAM era. The reason is that FinFET, CMOS, bonded array, more capacitor patterning, peripheral interconnects, and more complex processes are entering DRAM. For equipment companies, the best industry environment is simultaneous growth in capacity and process complexity.
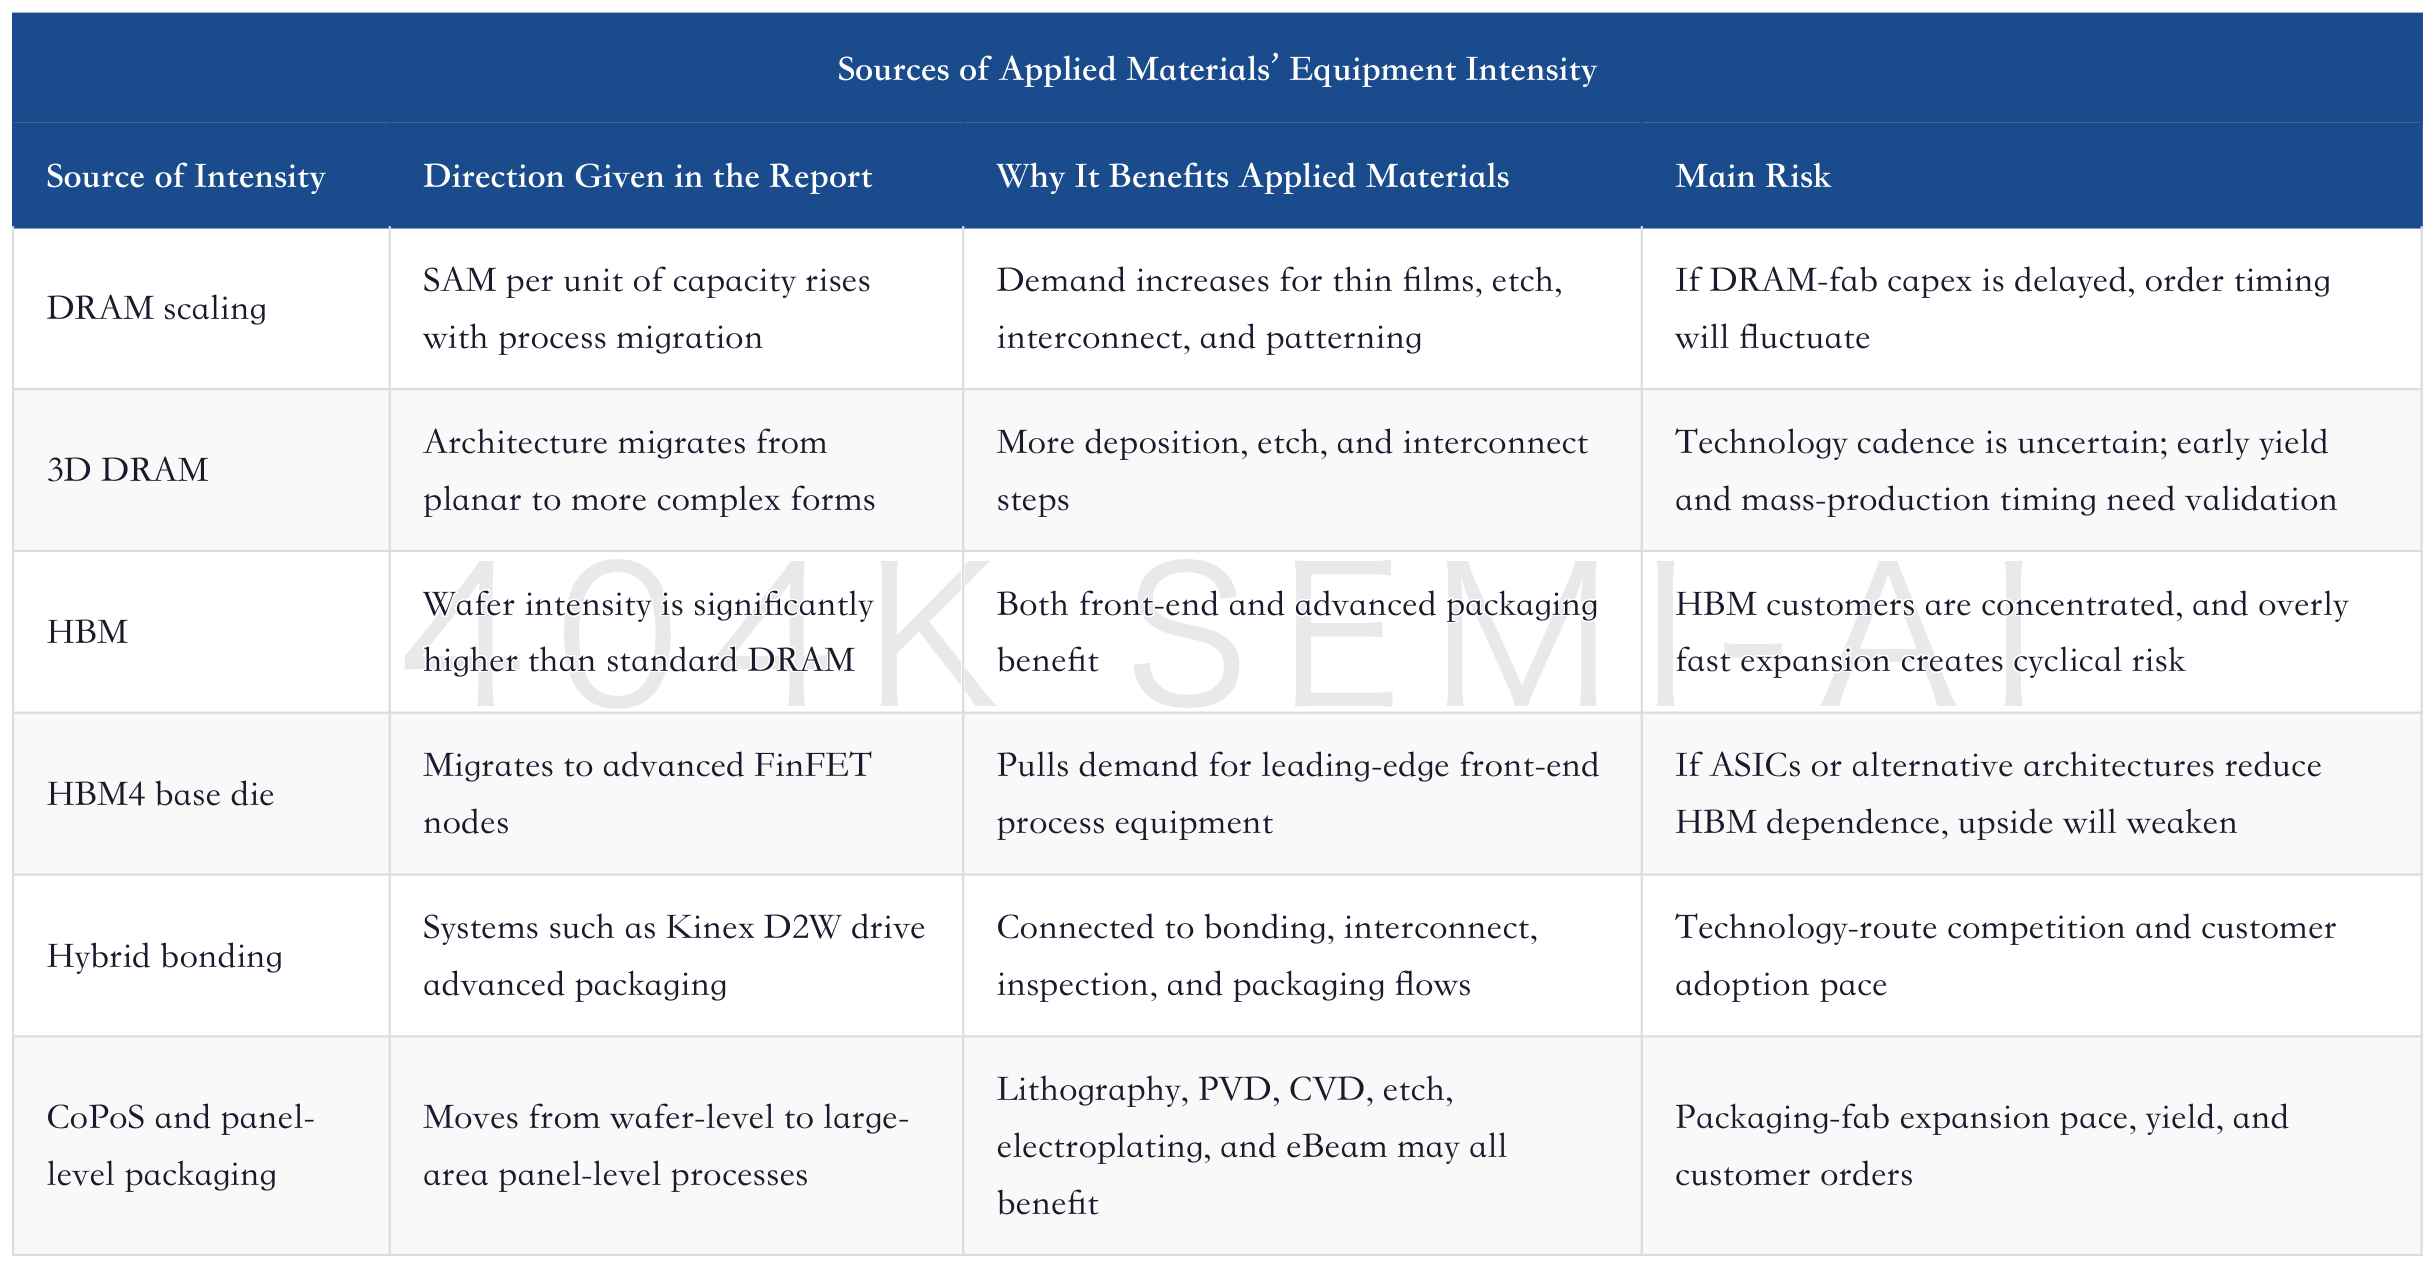
This table shows that the Applied Materials investment thesis cannot be assessed only through overall WFE dollars. The real incremental driver is process intensity: for the same wafer, if it enters HBM, 3D DRAM, hybrid bonding, CoPoS, and panel-level packaging, the equipment value content is higher. As AI hardware progresses, the trade is increasingly likely to shift from “chip count” to “manufacturing complexity behind each chip.”
Applied Materials’ advantage over pure storage stocks is that it does not need to bet on a single storage price. Storage price increases drive customer expansion; HBM and DRAM complexity increase equipment intensity; advanced packaging diffusion brings new equipment demand. These logic chains provide some diversification. Its advantage over pure logic-equipment stocks is that DRAM, HBM, and advanced packaging all directly benefit from AI capex.
Risks should not be ignored. The short-term decline in China WFE imports shows that equipment orders face regional and quarterly disruptions. If storage price increases destroy demand, customers may also defer capex. The best investment environment for Applied Materials is one in which storage prices are high enough, customer long-term contracts improve expansion visibility, HBM4 and 3D DRAM continue to advance, and advanced packaging expands from CoWoS to CoPoS and panel-level packaging.
6. China WFE Decline: Short-Term Noise or a Cycle Inflection?
The report notes that China WFE imports declined sequentially in May and were weaker than the five-year seasonal pattern. Viewed in isolation, this data point could easily be interpreted as cooling in the equipment cycle. But Jefferies’ framing is more measured: similar month-on-month declines have occurred in prior years, some equipment companies still expect full-year China WFE to be flat to slightly up, and Micron plus memory capex provide clues for a second-half recovery.
The real role of China WFE imports is to remind the market that equipment stocks do not re-rate in a straight line. AI and memory can create long-term demand, but equipment orders are still affected by region, customer, node, export controls, installation cadence, and acceptance cycles. When equipment-stock valuations are high, any monthly import data point gets amplified; when valuations are low, the market can easily overlook the strength in DRAM and advanced packaging.
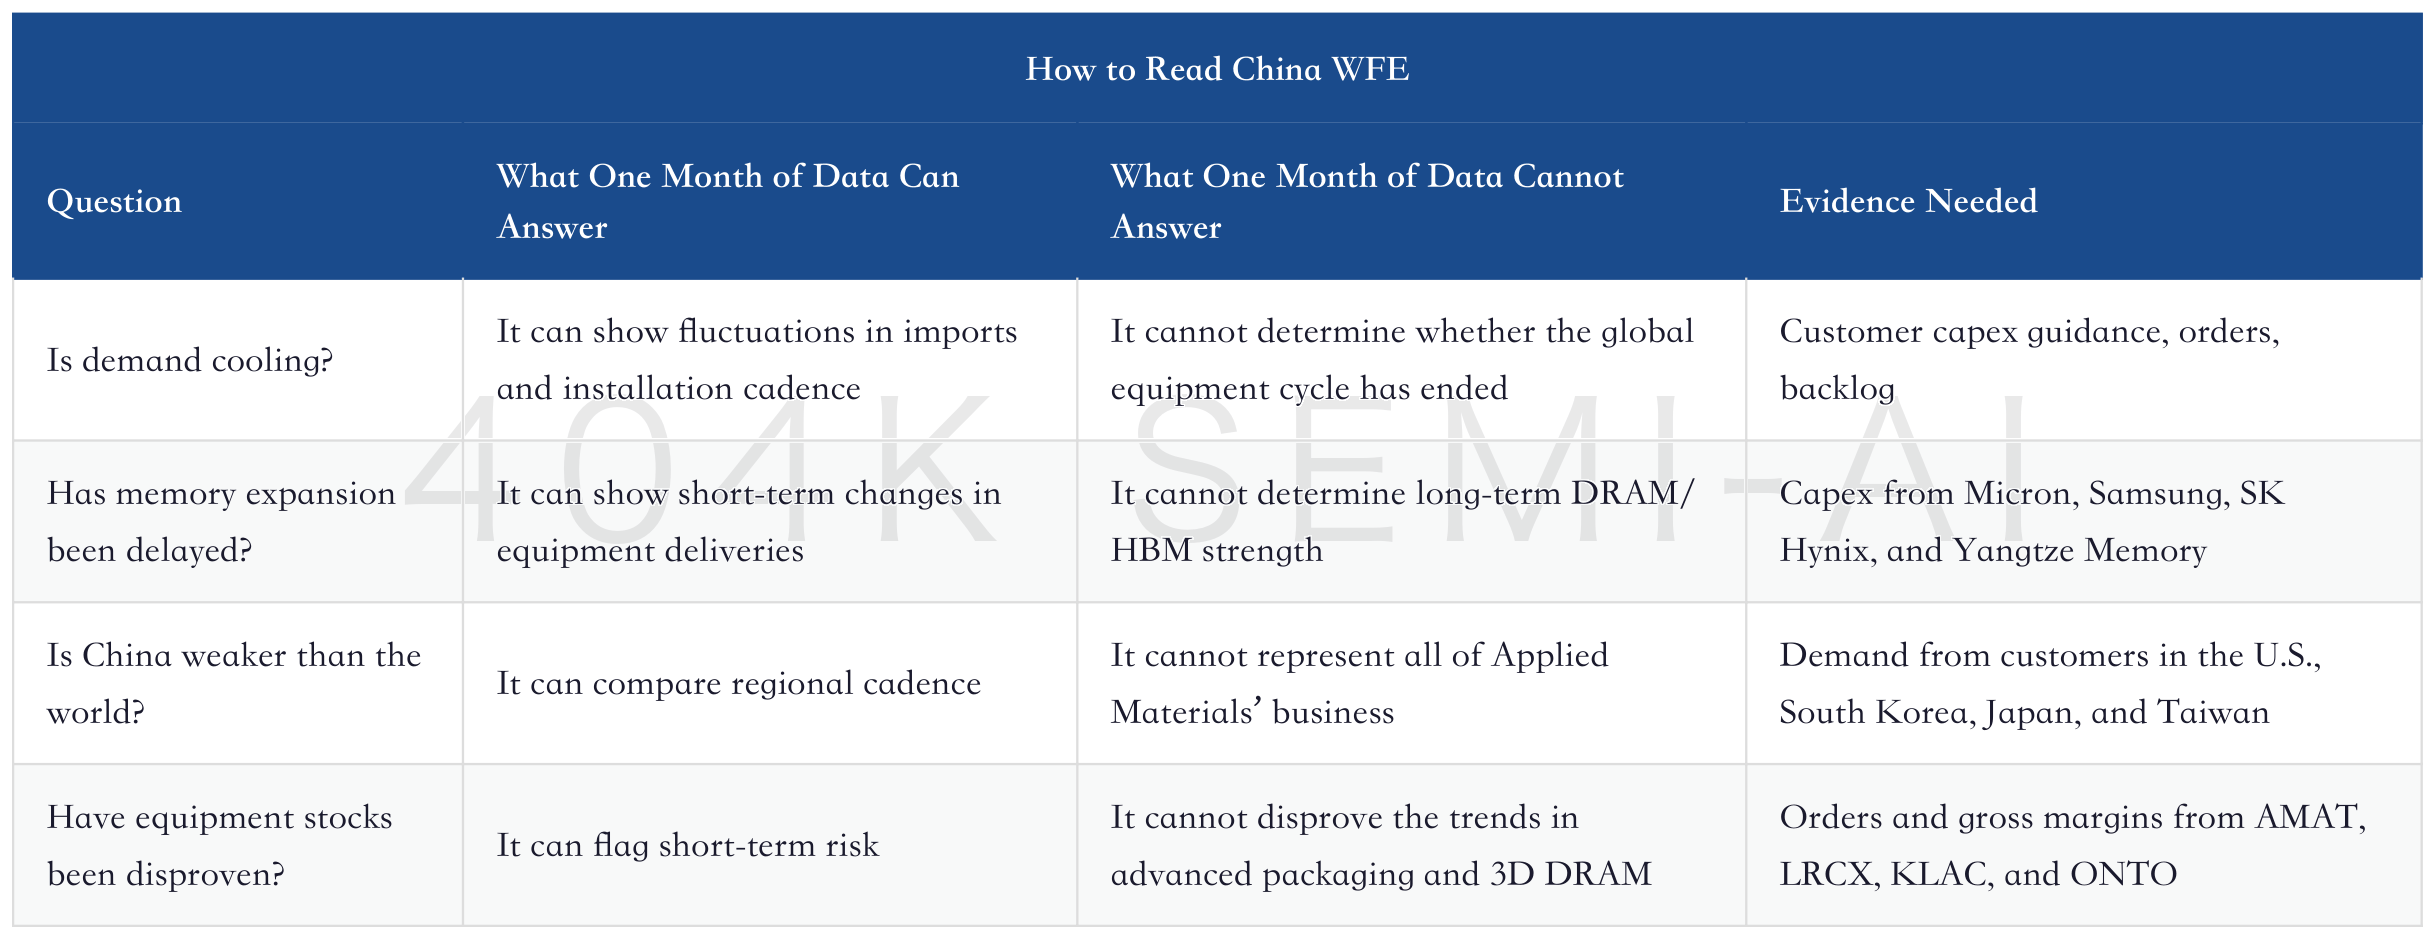
For Applied Materials, the risk in the May data lies in short-term order cadence and market sentiment; the opportunity is that if the market focuses only on monthly imports, it may underestimate the medium- to long-term process intensity brought by DRAM, HBM, and advanced packaging. The most important items to watch next are equipment-company management teams’ segmented guidance on China, DRAM, advanced packaging, and ICAPS. Monthly import/export fluctuations can only provide interim validation.
7. Advanced Packaging: CoPoS and Panel-Level Packaging Extend the Equipment Logic
It is valuable that this report places panel-level packaging within the same core thesis. ASE is pushing FOPLP mass production, while TSMC is advancing CoPoS. The common denominator is that AI chips are getting larger and multi-die systems are becoming more complex, making the traditional 300mm wafer format increasingly stretched in packaging area and yield. A panel format can improve effective area utilization, while also creating new lithography, deposition, inspection, electroplating, and interconnect steps.
Equipment Capex Ledger Update: AI Financing, $250 Billion WFE, and Semiconductor Equipment Repricing
In the past, the market mainly treated advanced packaging as a theme around TSMC CoWoS, ABF substrates, and the HBM supply chain. Now it is expanding into a broader equipment theme: CoPoS pushes CoWoS-like 2.5D integration into a panel-level format, while FOPLP serves a wider range of applications. For equipment stocks, the key is that multiple routes will increase process steps.
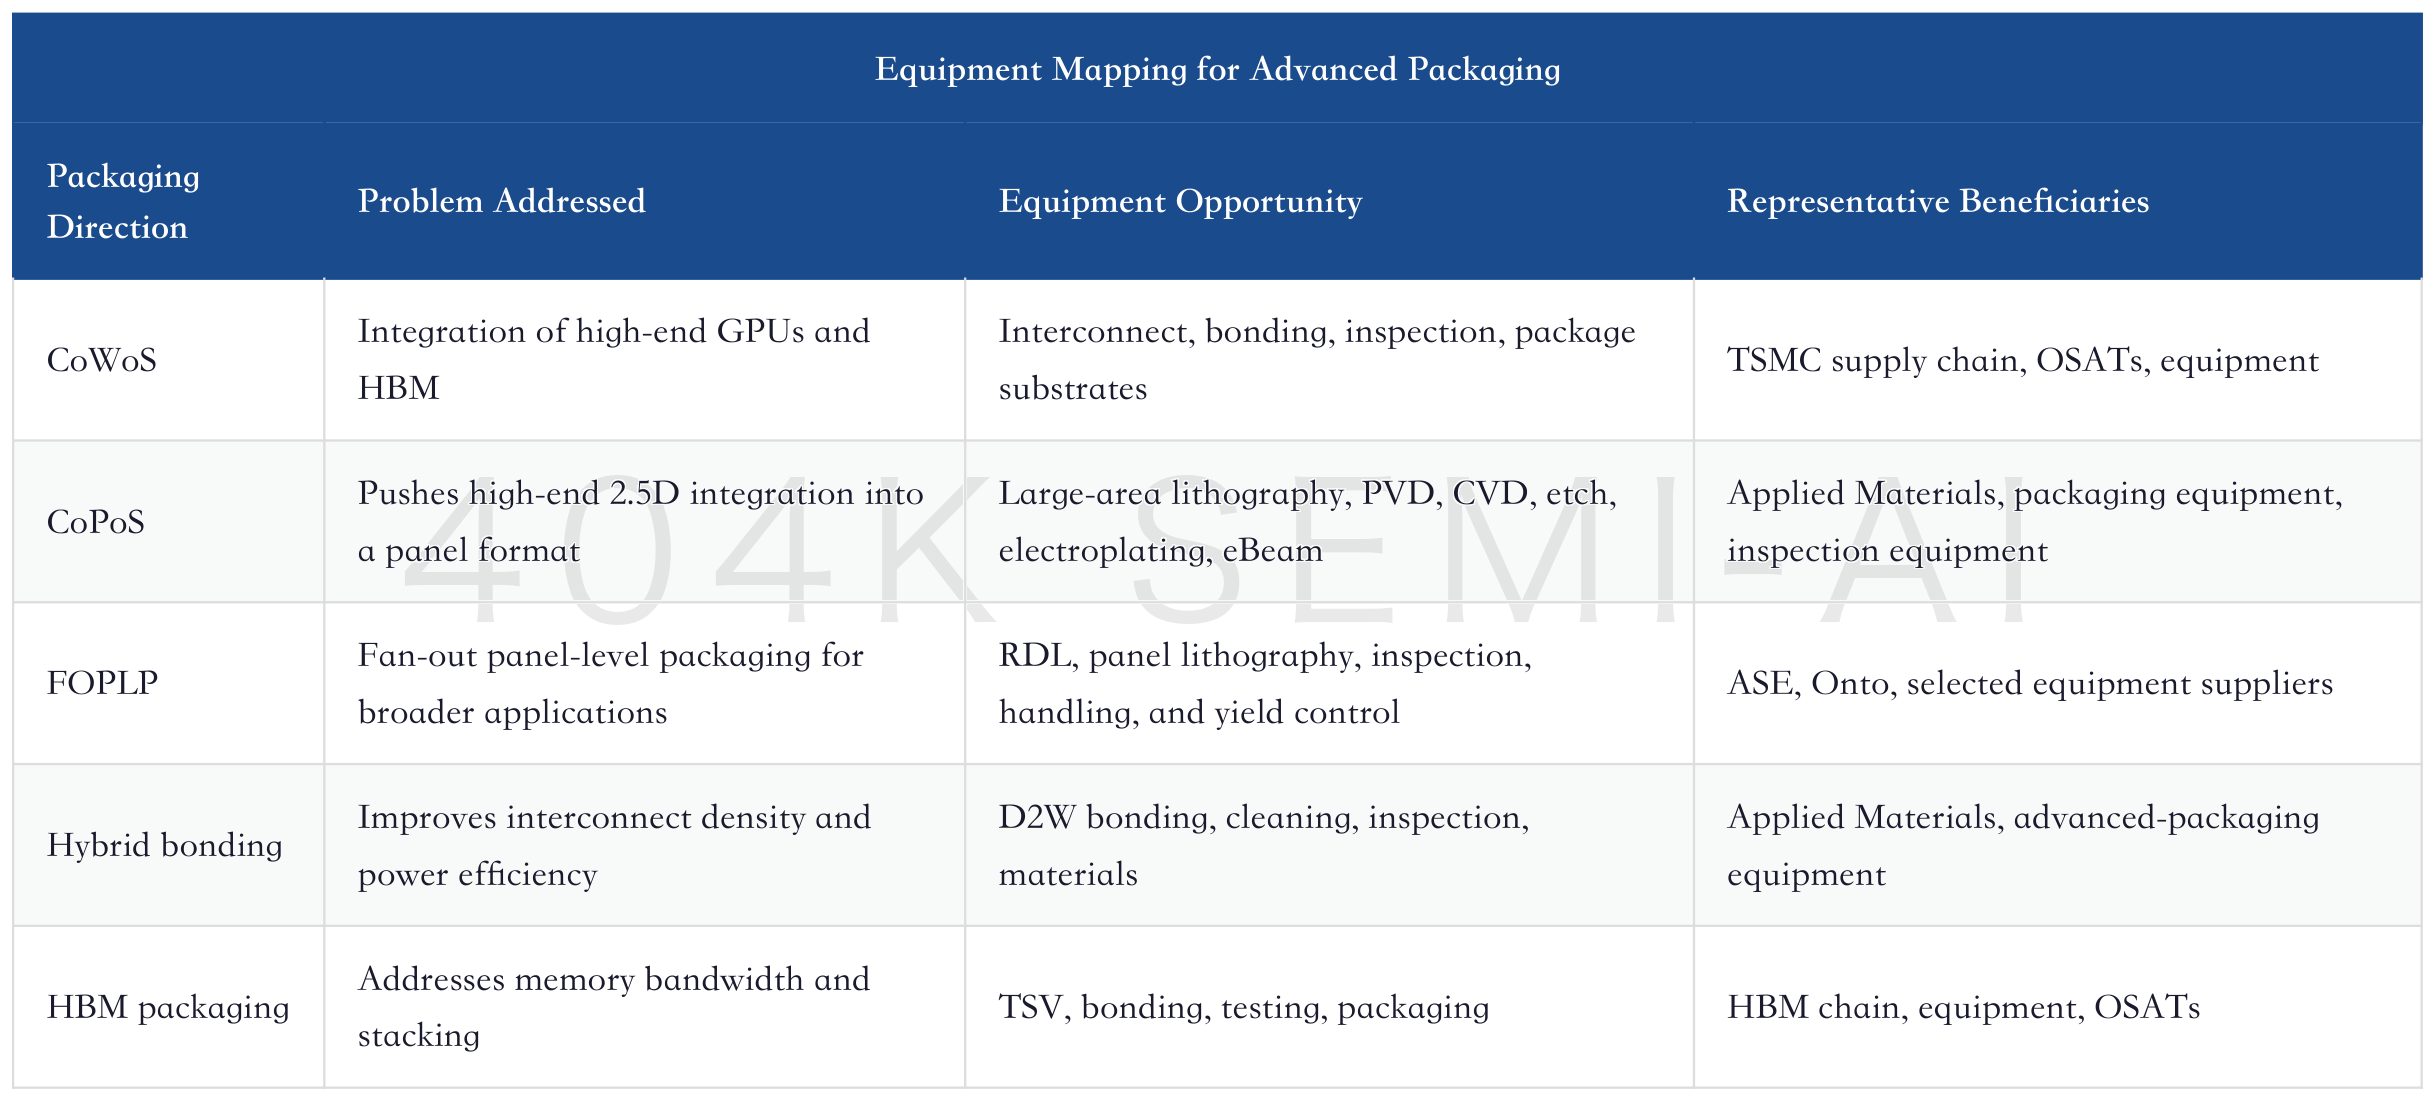
This table explains why Applied Materials and Onto appear together in the report. Applied Materials benefits from a broad process portfolio, while Onto is more skewed toward inspection, metrology, and specific packaging equipment. The larger AI chips become and the more complex packaging gets, the more valuable yield control becomes. The second layer of the equipment-investment logic is the shift from “who can supply equipment” to “who can improve large-area, multi-die, high-yield manufacturing.”
Advanced packaging also carries cadence risk. CoPoS, FOPLP, and hybrid bonding all require customer adoption, capacity ramp-up, and yield validation. The market can easily price long-term upside into valuations ahead of time, but near-term revenue recognition will not rise linearly. The right way to track this is through customer projects, equipment orders, mass-production milestones, yield, and OSAT capex. Roadmaps are only the starting point.
8. onsemi Acquires Synaptics: Physical AI Ambition and Valuation Dilution
onsemi’s acquisition of Synaptics is the section of this report most likely to be misread. On the surface, the transaction is an all-stock acquisition, with an enterprise value of about $7 billion, a premium of about 19%, and expected annual synergies plus EPS accretion. The deeper logic is that onsemi wants to extend from power, sensing, and control into edge computing, connectivity, human-machine interaction, and physical AI.
onsemi’s original AI narrative was clearer: 800V DC, power conversion, SiC, industrial and automotive electrification, and data-center power. This line is directly connected to AI compute centers, and the valuation logic is closer to an “AI power tree.” Synaptics brings another line: edge AI, the Astra platform, connectivity chips, HMI, and industrial and consumer IoT. It pushes onsemi from power hardware toward intelligent endpoints and the physical world.
800V DC Reshapes Data-Center Power: Who Monetizes First, Texas Instruments or onsemi, and How GaN, SiC, and the AI Power Tree Re-Rate
The benefit of this deal is a more complete portfolio. Robotics, industrial automation, smart edge, automotive cockpit, and humanoid robots all need power, sensing, control, connectivity, edge computing, and HMI. If onsemi can sell these products to the same customer base, its cross-selling and solution-selling capabilities will improve. Synaptics’ edge AI platform can also extend onsemi’s narrative from “power supply” to “sensing and control.”
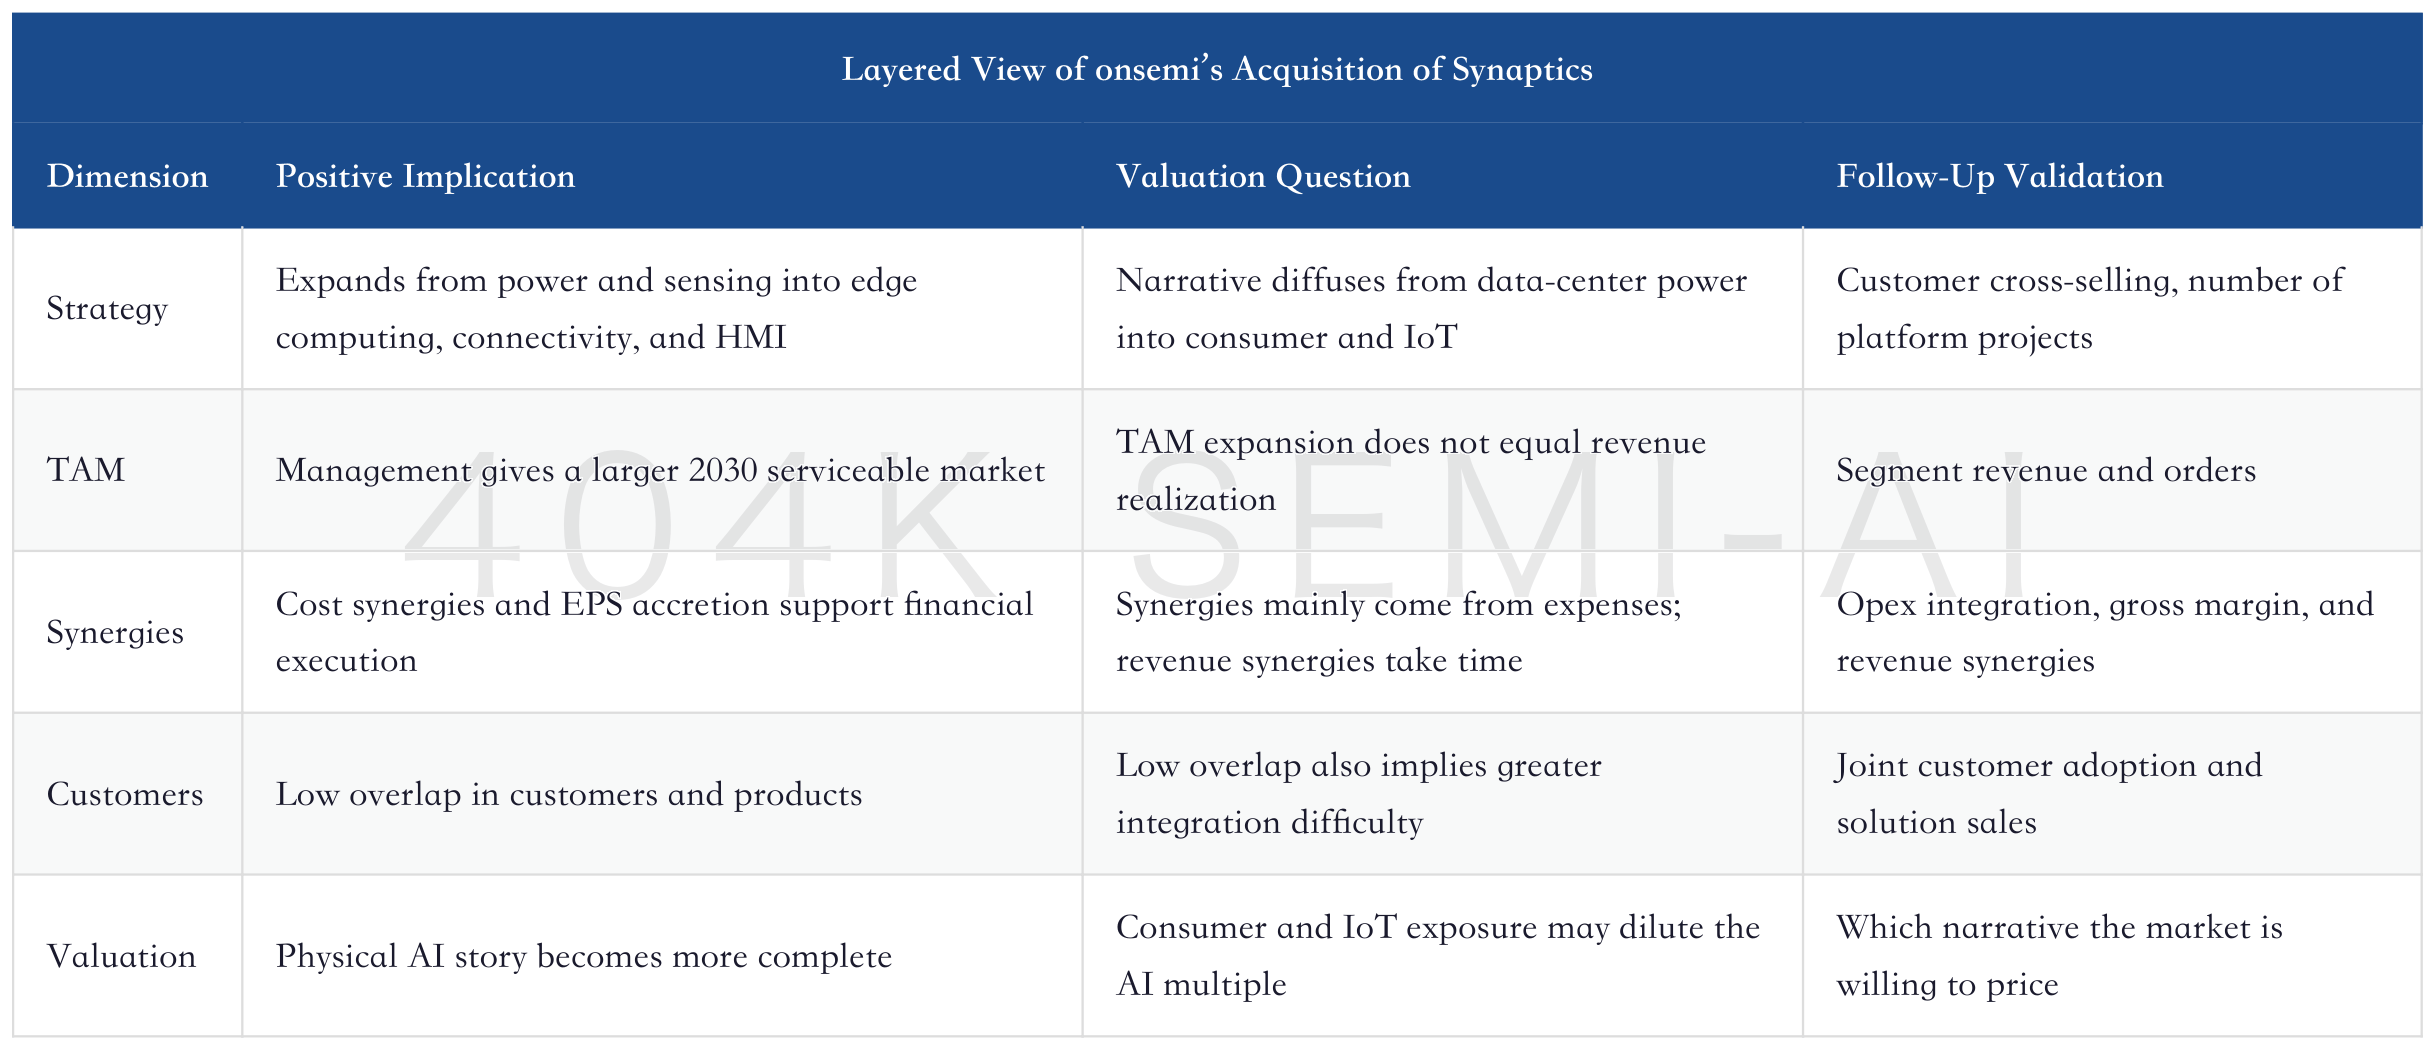
Jefferies’ stance on the deal is neutral-positive, for the same reason. It recognizes the strategic significance of the physical AI portfolio, but believes the transaction may pull onsemi away from a purer data-center power narrative. For the stock, the biggest risk in this type of deal is “strategically larger, but valuation-wise more ambiguous.” If the market was previously assigning onsemi an 800V DC and AI-power multiple, then after adding consumer IoT and edge connectivity, investors need to reassess what valuation a mixed business deserves.
This does not mean the deal is bad. It means the market needs to distinguish between two time horizons: in the short term, transaction integration, synergies, and EPS accretion; in the medium term, edge AI and physical AI customer adoption; and in the long term, whether onsemi can sell power, sensing, control, connectivity, and edge computing as one platform. If there are only cost synergies, the transaction value is limited; if it can create bundled sales across robotics, industrial, and automotive endpoints, the valuation upside will be greater.
9. MCU Price Increases: Mature Nodes Are Also Being Squeezed by AI
The report notes that STMicroelectronics has notified customers of price increases for MCU products, and that MCU vendors including Infineon, NXP, Microchip, and Texas Instruments are also expected to raise prices in June or July. This may seem distant from AI servers, but it shows that supply tightness has already spread across mature nodes and code storage.
There are three layers of transmission behind MCU price increases. First, foundries are shifting resources toward higher-value products, tightening mature-node supply. Second, AI data centers and high-end hardware are absorbing more supply and capex, reducing other products' bargaining power for capacity. Third, rising NOR Flash prices are entering MCU BOMs because code and firmware storage depend on NOR. This chain will ultimately affect industrial, automotive, consumer electronics, and edge devices.
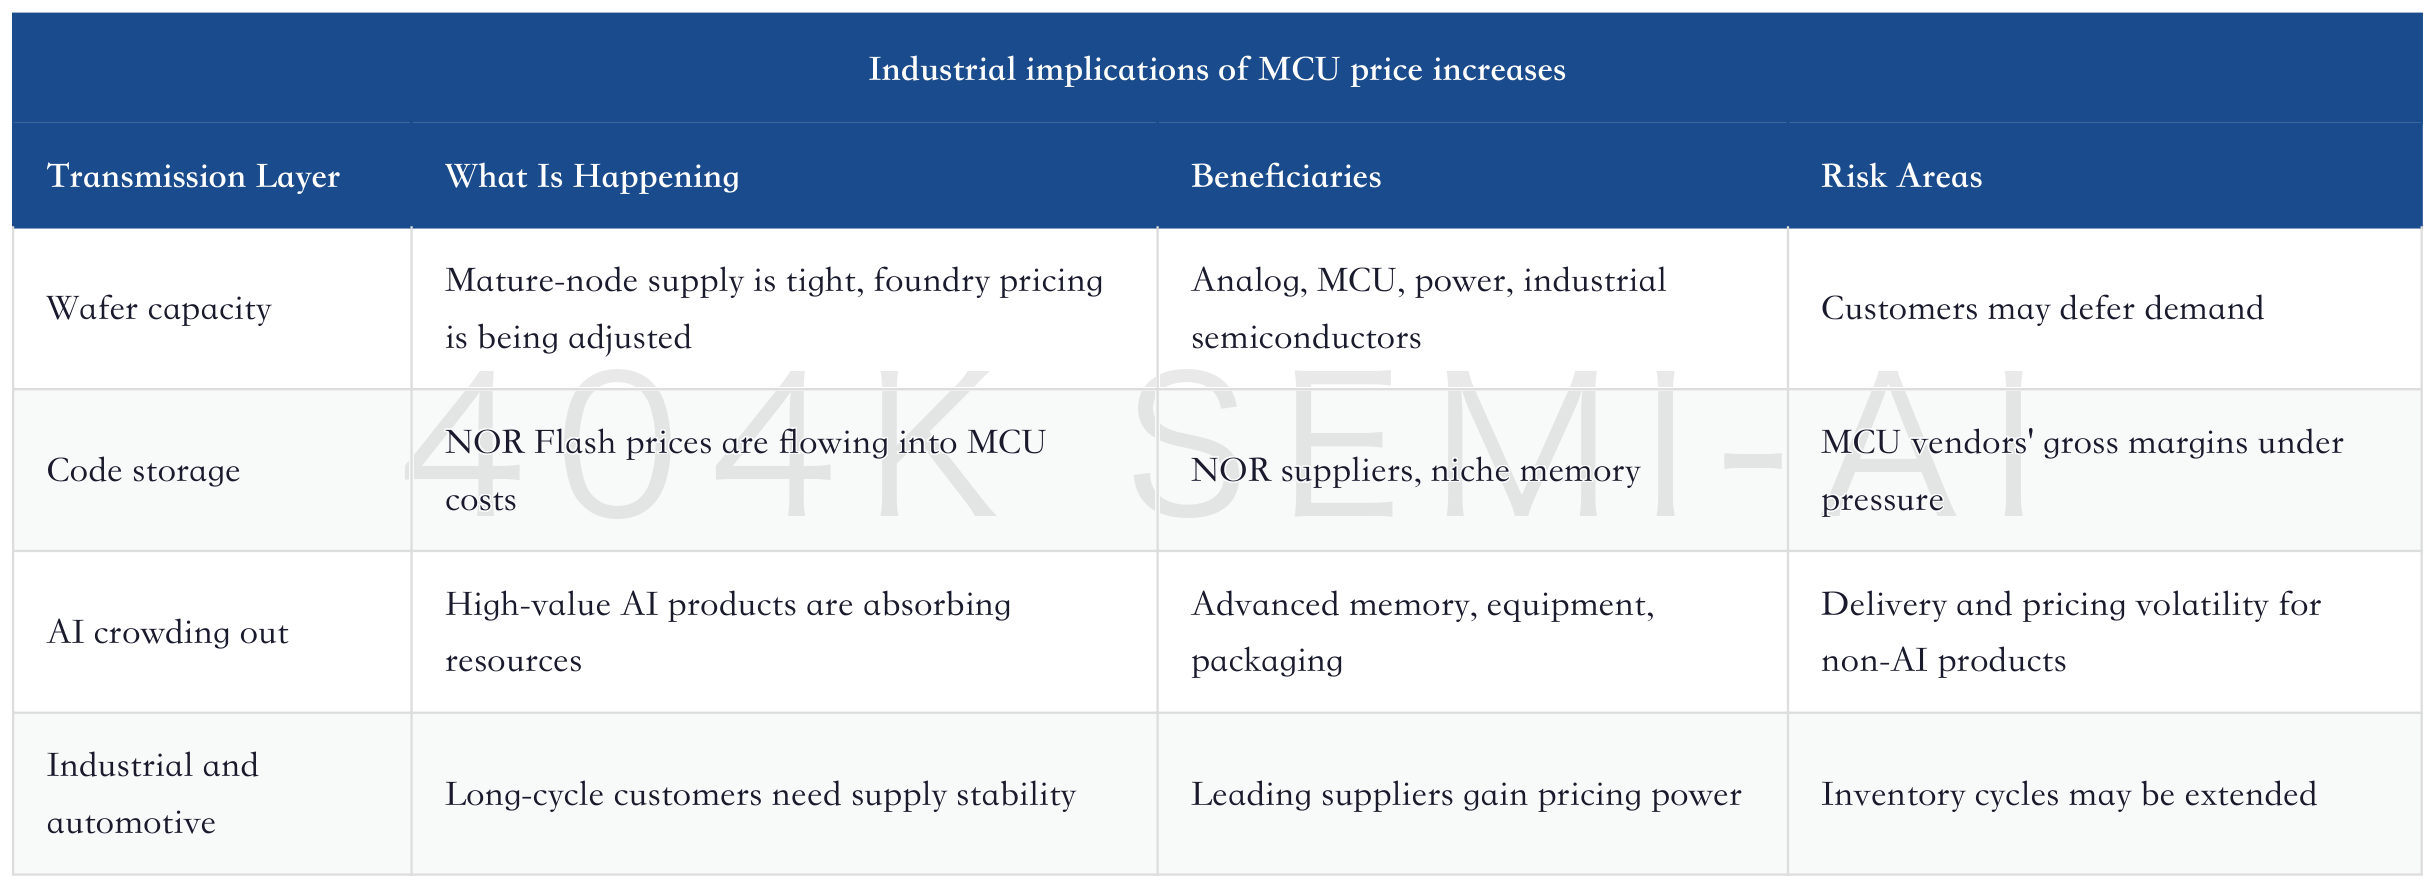
This signal also helps the onsemi trade. Physical AI needs to land in factories, robots, vehicles, energy systems, and edge terminals. The closer AI moves into the physical world, the more important MCUs, sensing, power, connectivity, code storage, and analog chips become. Price increases on mature nodes will lift revenue sensitivity for these companies, while also testing customers' ability to absorb higher costs.
10. Cerebras, Qualcomm, and Power: Alternative Architectures Show Bottlenecks Are Spreading
Jefferies also includes Cerebras, Qualcomm, and the Microsoft/Chevron power agreement in the report, showing that AI infrastructure bottlenecks have spread from chips to data center capacity, power, packaging, and alternative architectures. Cerebras emphasizes inference demand and data center capacity constraints, Qualcomm is advancing its Dragonfly roadmap and HBC architecture, and Microsoft has locked in a 20-year power agreement. Together, these developments point to one issue: AI compute demand is growing too quickly for any single solution to be enough.
Deep Dive on AI Compute Warning Signals: Cerebras, Memory, and Re-screening Opportunities in the Post-GPU Diffusion Phase
The emergence of alternative architectures should not be read directly as Nvidia share declining immediately. A steadier interpretation is that customers are willing to pay to route around bottlenecks: HBM price pressure, CoWoS tightness, advanced-node capacity, power interconnection constraints, and single-supplier limits. As long as AI demand keeps rising, alternative architectures, ASICs, inference chips, fan-out packaging, power PPAs, and data center capacity will all have commercial value.
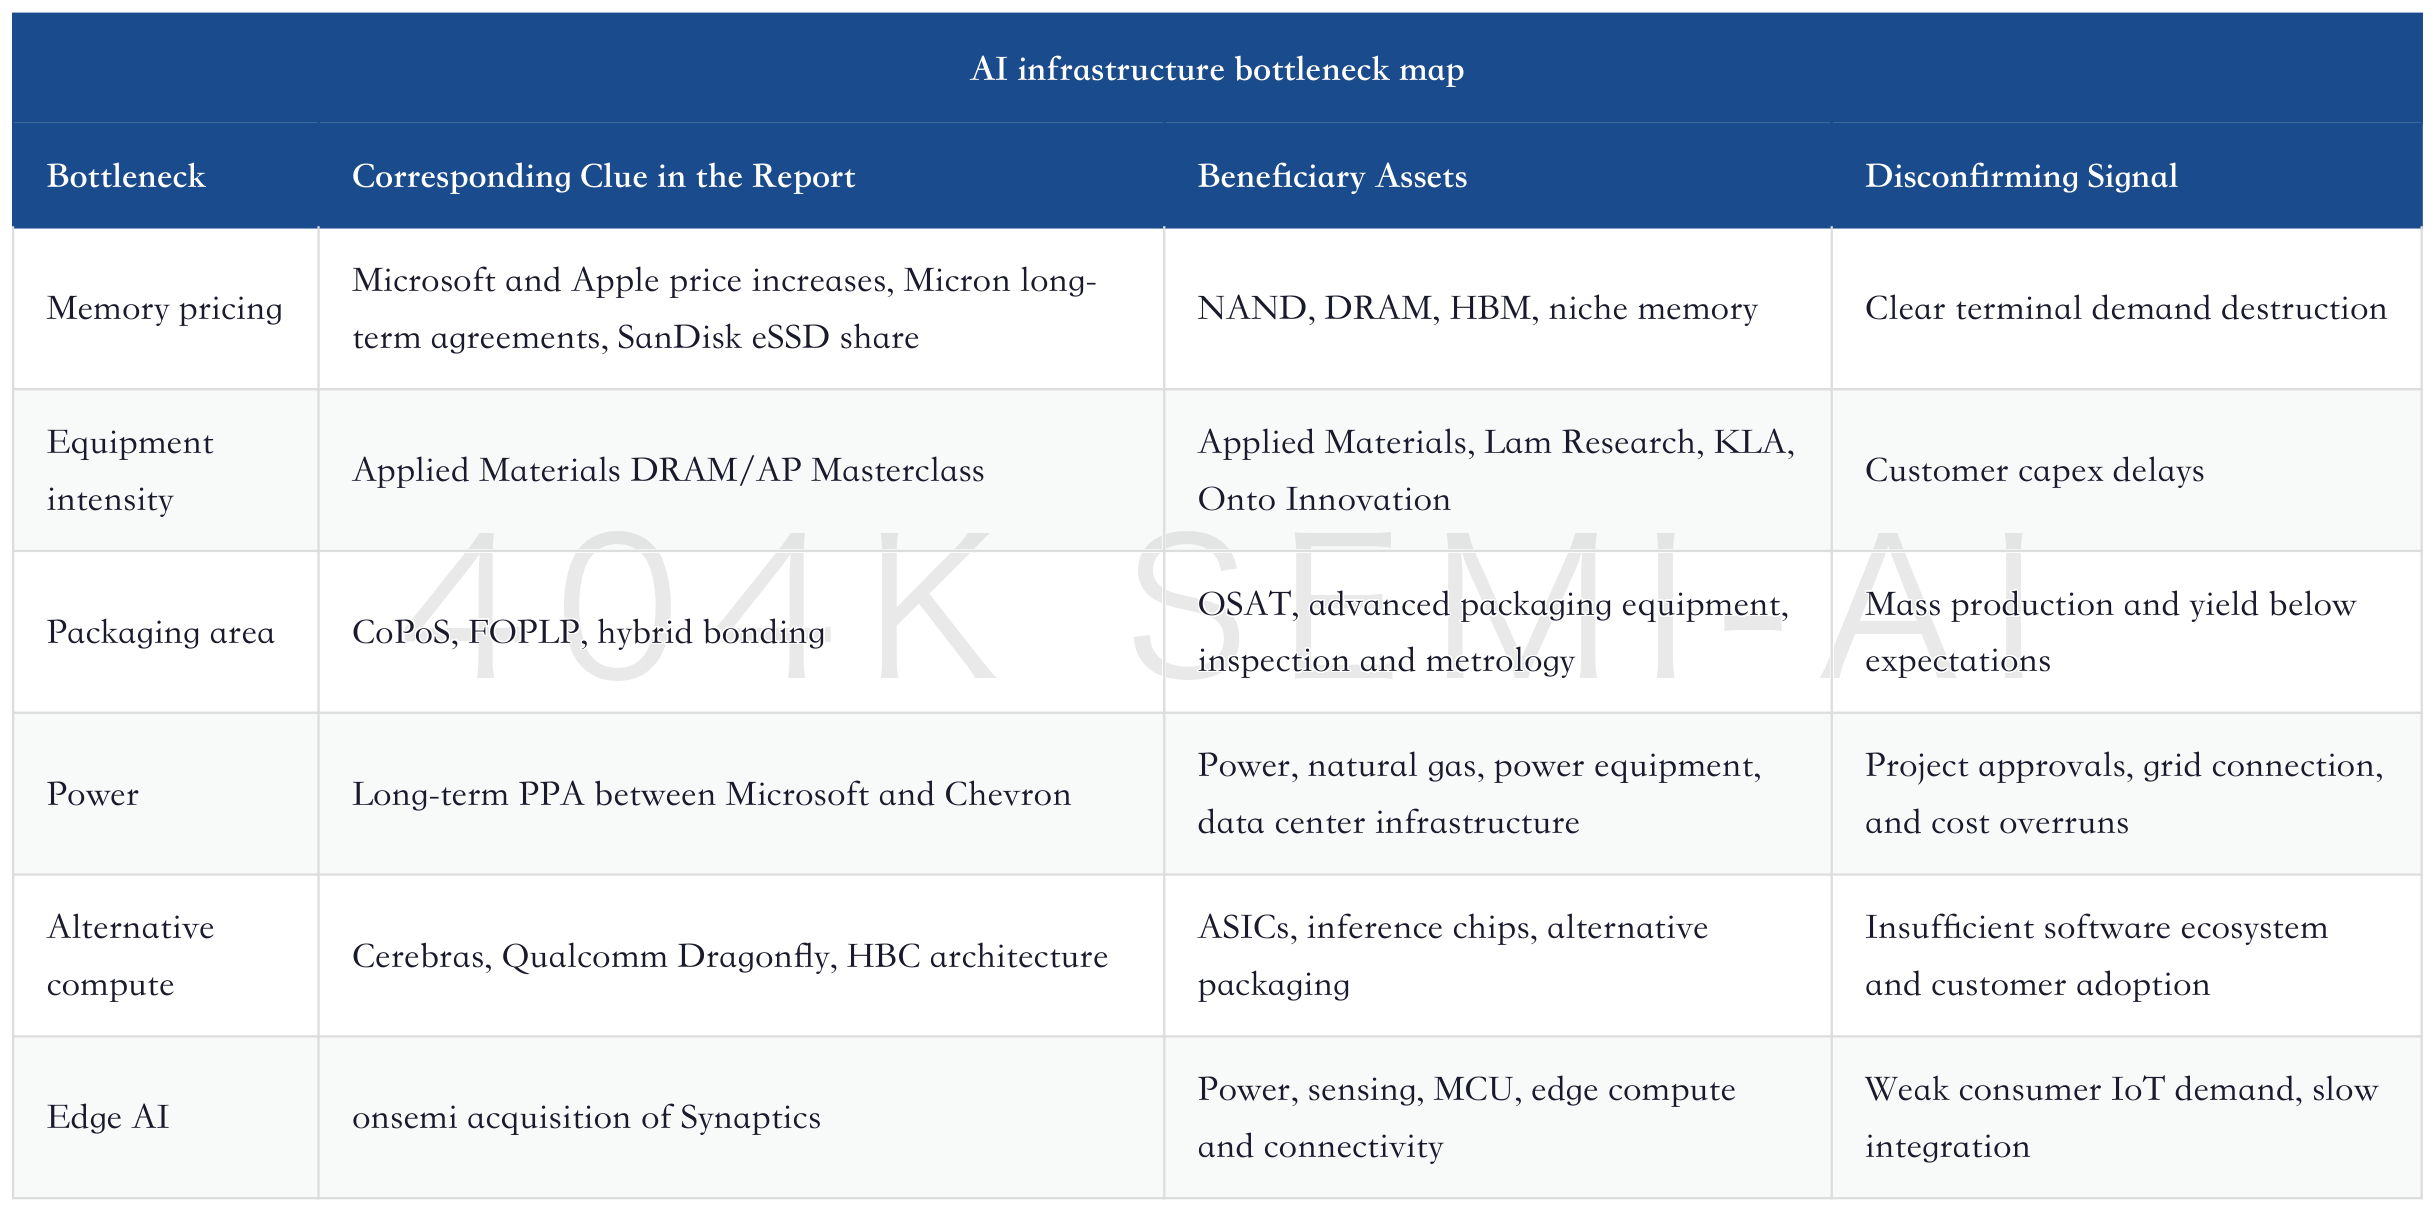
The value of this map is that it helps investors avoid focusing on only one link in the chain. The second stage of AI hardware may not be driven by a single leader rising alone. It is more likely to appear as rotation among bottleneck assets: memory may be strongest in one phase, equipment and packaging may catch up in the next, and power and edge control may gain pricing in the following phase. The closer an asset is to an unavoidable physical constraint, the easier it is to earn high-quality profit.
11. Three Worldviews: Memory Cycle, Equipment Intensity, Physical AI Platform
This report can be split into three worldviews. The first is the memory-cycle worldview: AI servers absorb DRAM and NAND, price increases pass through to end markets, and earnings for memory stocks such as SanDisk and Micron continue to be revised upward. The second is the equipment-intensity worldview: DRAM, HBM, 3D DRAM, and advanced packaging increase equipment value per unit of capacity, giving equipment companies such as Applied Materials a longer cycle. The third is the physical-AI-platform worldview: AI moves from the cloud to robotics, industrial, automotive, and edge devices, with power, sensing, MCUs, connectivity, and edge computing forming a new platform.
The three worldviews can reinforce one another. Memory price increases provide cash flow and order justification for equipment expansion. Equipment intensity supports supply expansion in memory and advanced packaging. Edge AI expands the application boundary of AI hardware. Their common risks are also similar: terminal demand destruction, inventory mismatch, customer capex delays, technology roadmap shifts, and valuation pull-forward.
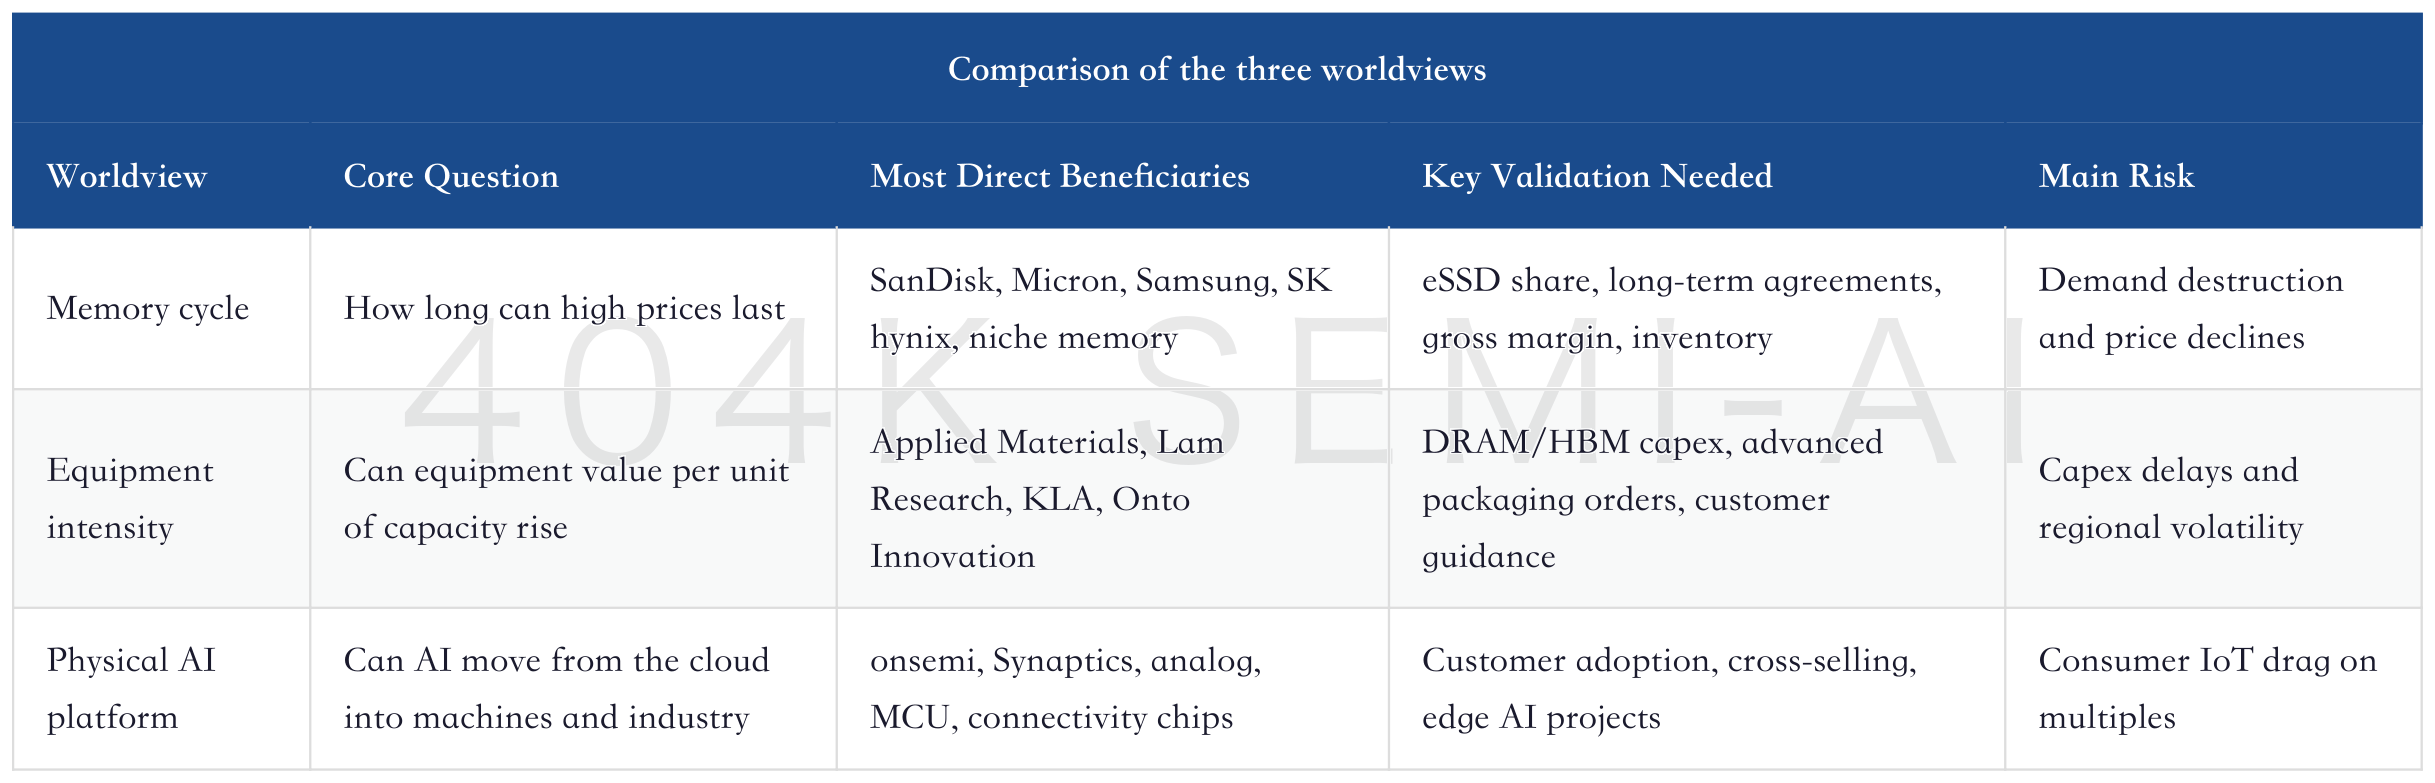
In investment terms, the three worldviews correspond to three position profiles. Memory stocks have the highest beta and the fastest returns during price-up cycles, but also the sharpest drawdowns. Equipment stocks have slightly lower beta, but are closer to the long-term increase in manufacturing complexity. Physical AI platforms move slowest and require order and integration validation, but once solution selling takes hold, durability may be better. The incremental value of the report is that it puts these three lines of evidence into the same-day evidence chain, showing the market that the AI hardware trade is broadening.
12. Company and Segment Ranking: Who Looks Most Like a Bottleneck Asset
Ranked by the strength of evidence in this report, SanDisk and Applied Materials are at the top. SanDisk directly benefits from NAND pricing, eSSD share, and SLC preference, giving it the highest earnings beta. Applied Materials directly benefits from DRAM, HBM, 3D DRAM, and advanced packaging equipment intensity, giving it better cycle durability. The upside for the onsemi and Synaptics combination depends on whether the physical AI platform can materialize, while near-term work remains around integration and mixed narratives.
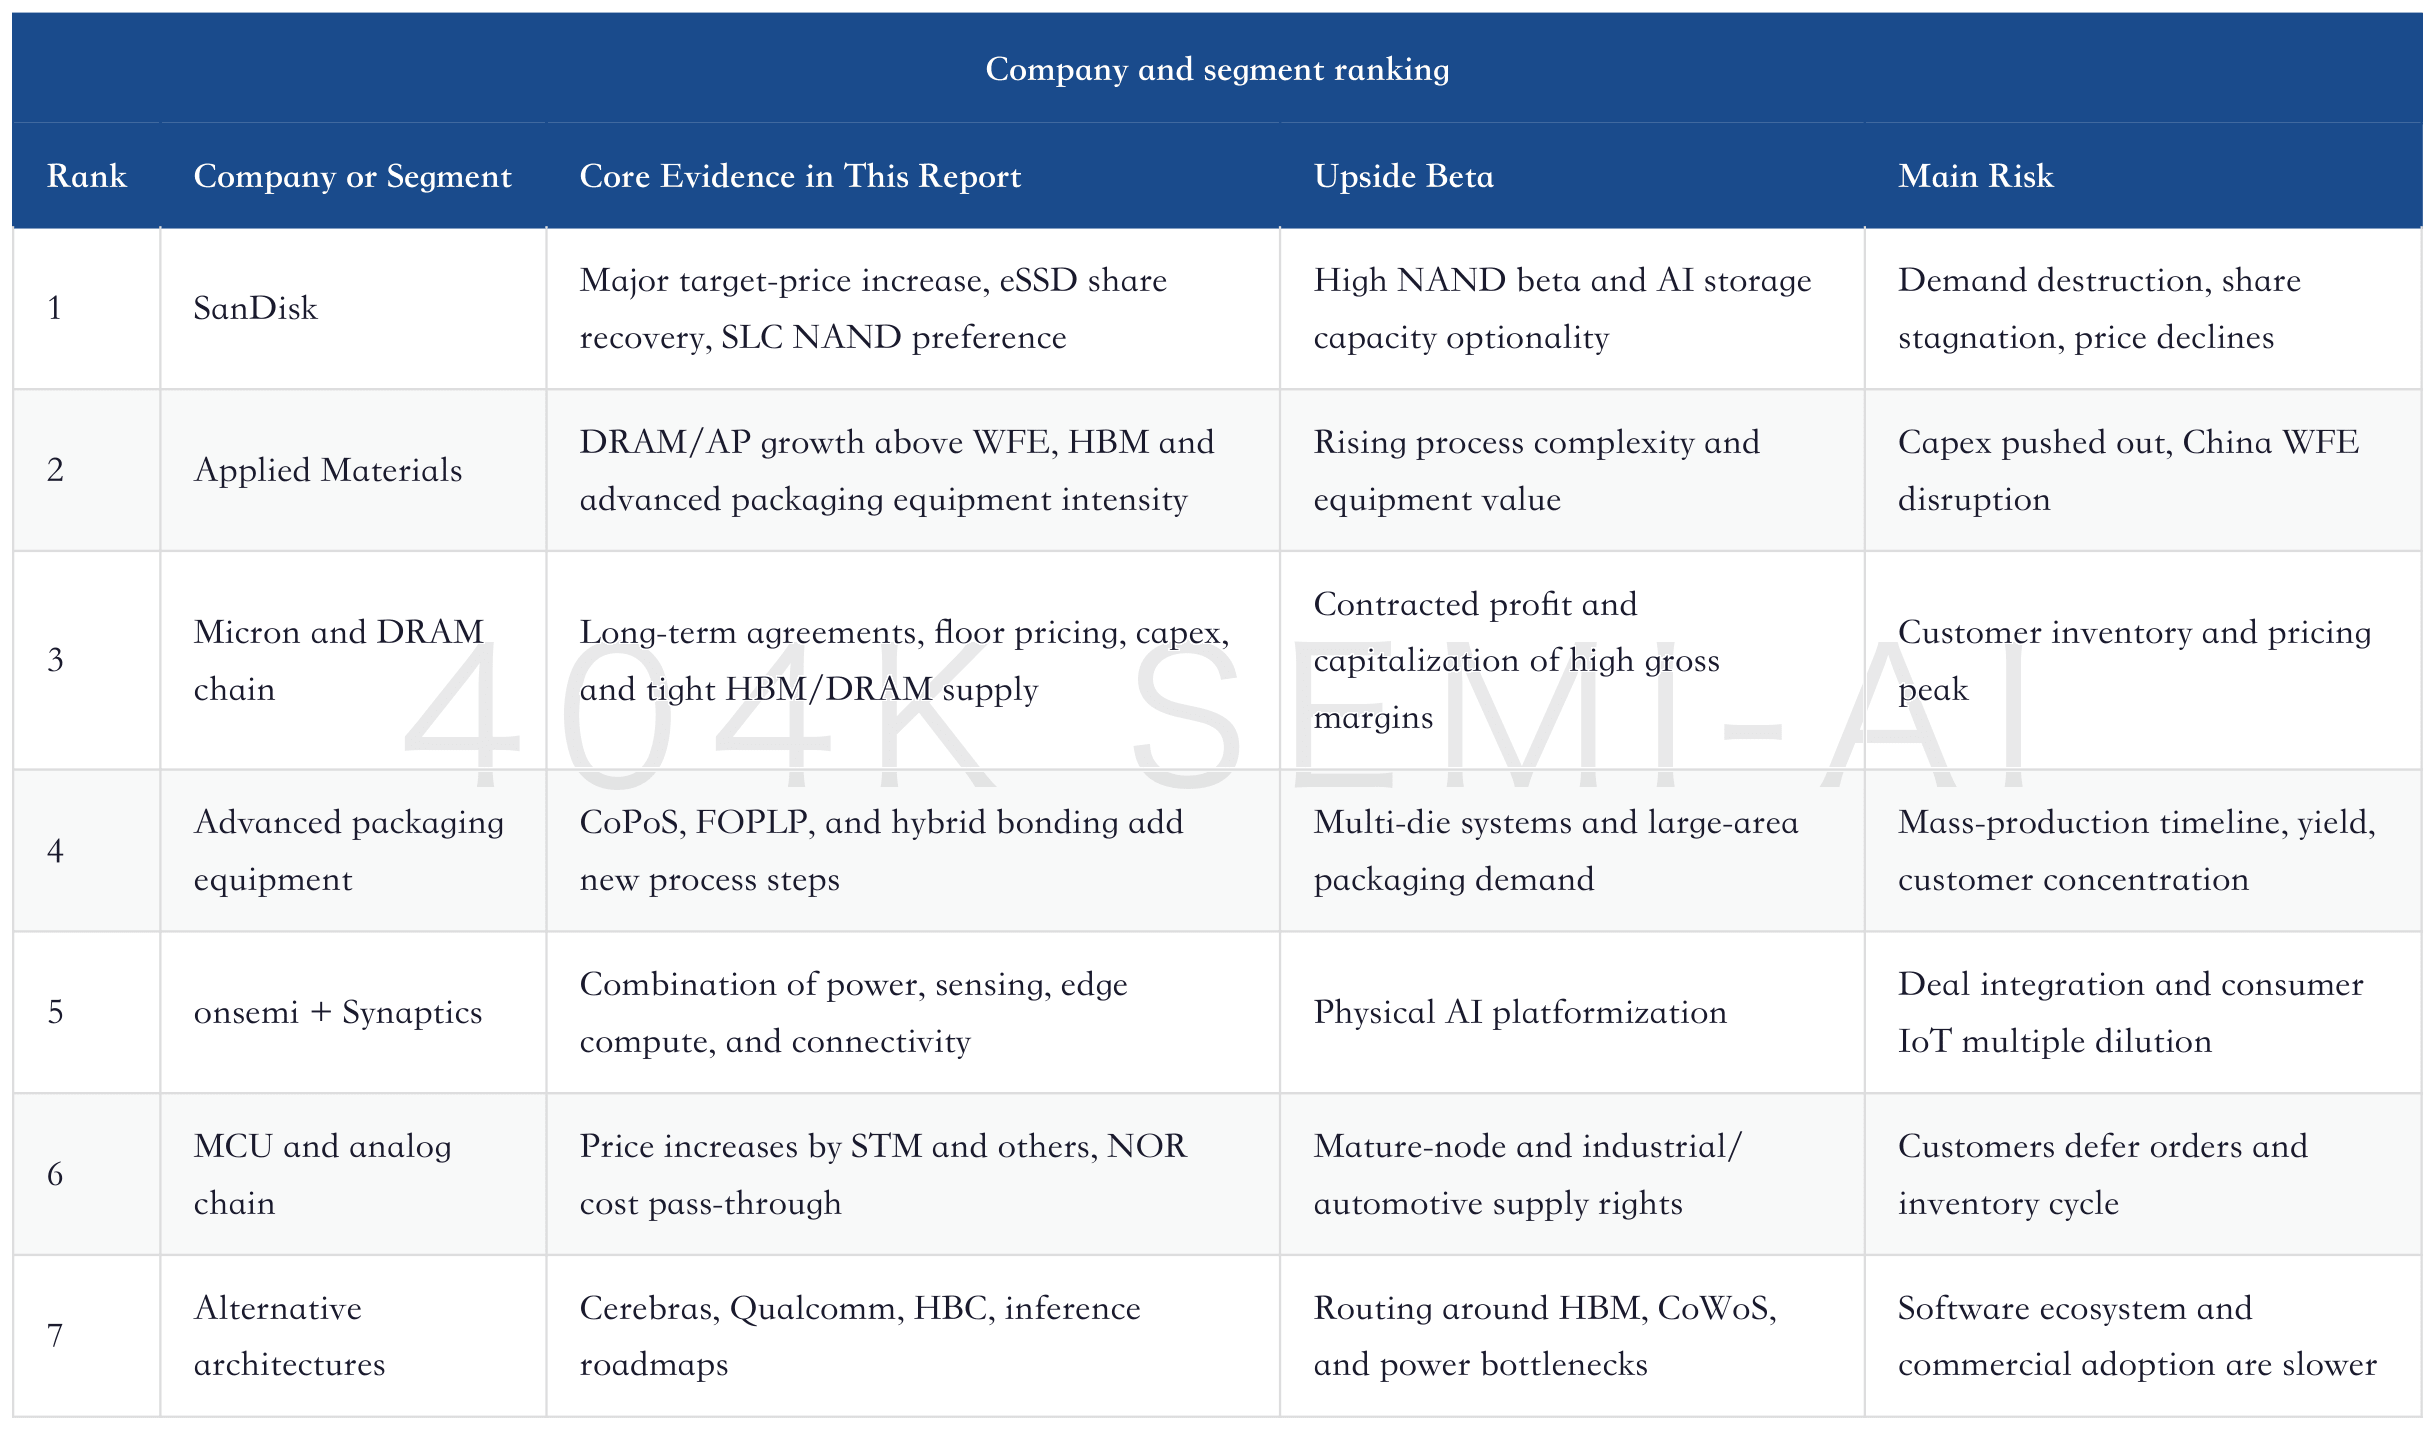
This ranking is not a stock-price conclusion. It simply ranks evidence strength and speed of profit transmission. SanDisk has the most direct earnings beta, Applied Materials has stronger cycle durability, and onsemi has a longer-dated story that requires more validation. For portfolio management, SanDisk is suitable for expressing NAND and eSSD beta, Applied Materials for AI manufacturing complexity, and onsemi for long-term optionality in edge and physical AI.
13. Why AI Hardware Will Diverge
The biggest issue in Phase 2 of AI hardware is that price increases and demand destruction will appear at the same time. The stronger memory pricing becomes, the better upstream profits look; the stronger pricing becomes, the greater the cost pressure downstream. The higher equipment intensity becomes, the more companies such as Applied Materials benefit; the higher equipment intensity becomes, the heavier customers’ capital expenditure burden becomes. The bigger the physical AI narrative becomes, the more optionality ON Semiconductor’s acquisition of Synaptics appears to have; the bigger the narrative becomes, the harder integration, customer adoption, and valuation tiering become.
This means the stocks in the report cannot be valued using one single logic. SanDisk should be assessed on NAND pricing and eSSD share; Applied Materials on DRAM/HBM/advanced packaging equipment intensity; ON Semiconductor on synergies and physical AI customers; the MCU and analog chain on mature-node supply and demand; and alternative architectures on customer adoption and ecosystem development. Simply grouping all of them as “AI beneficiaries” would miss the most important divergences.
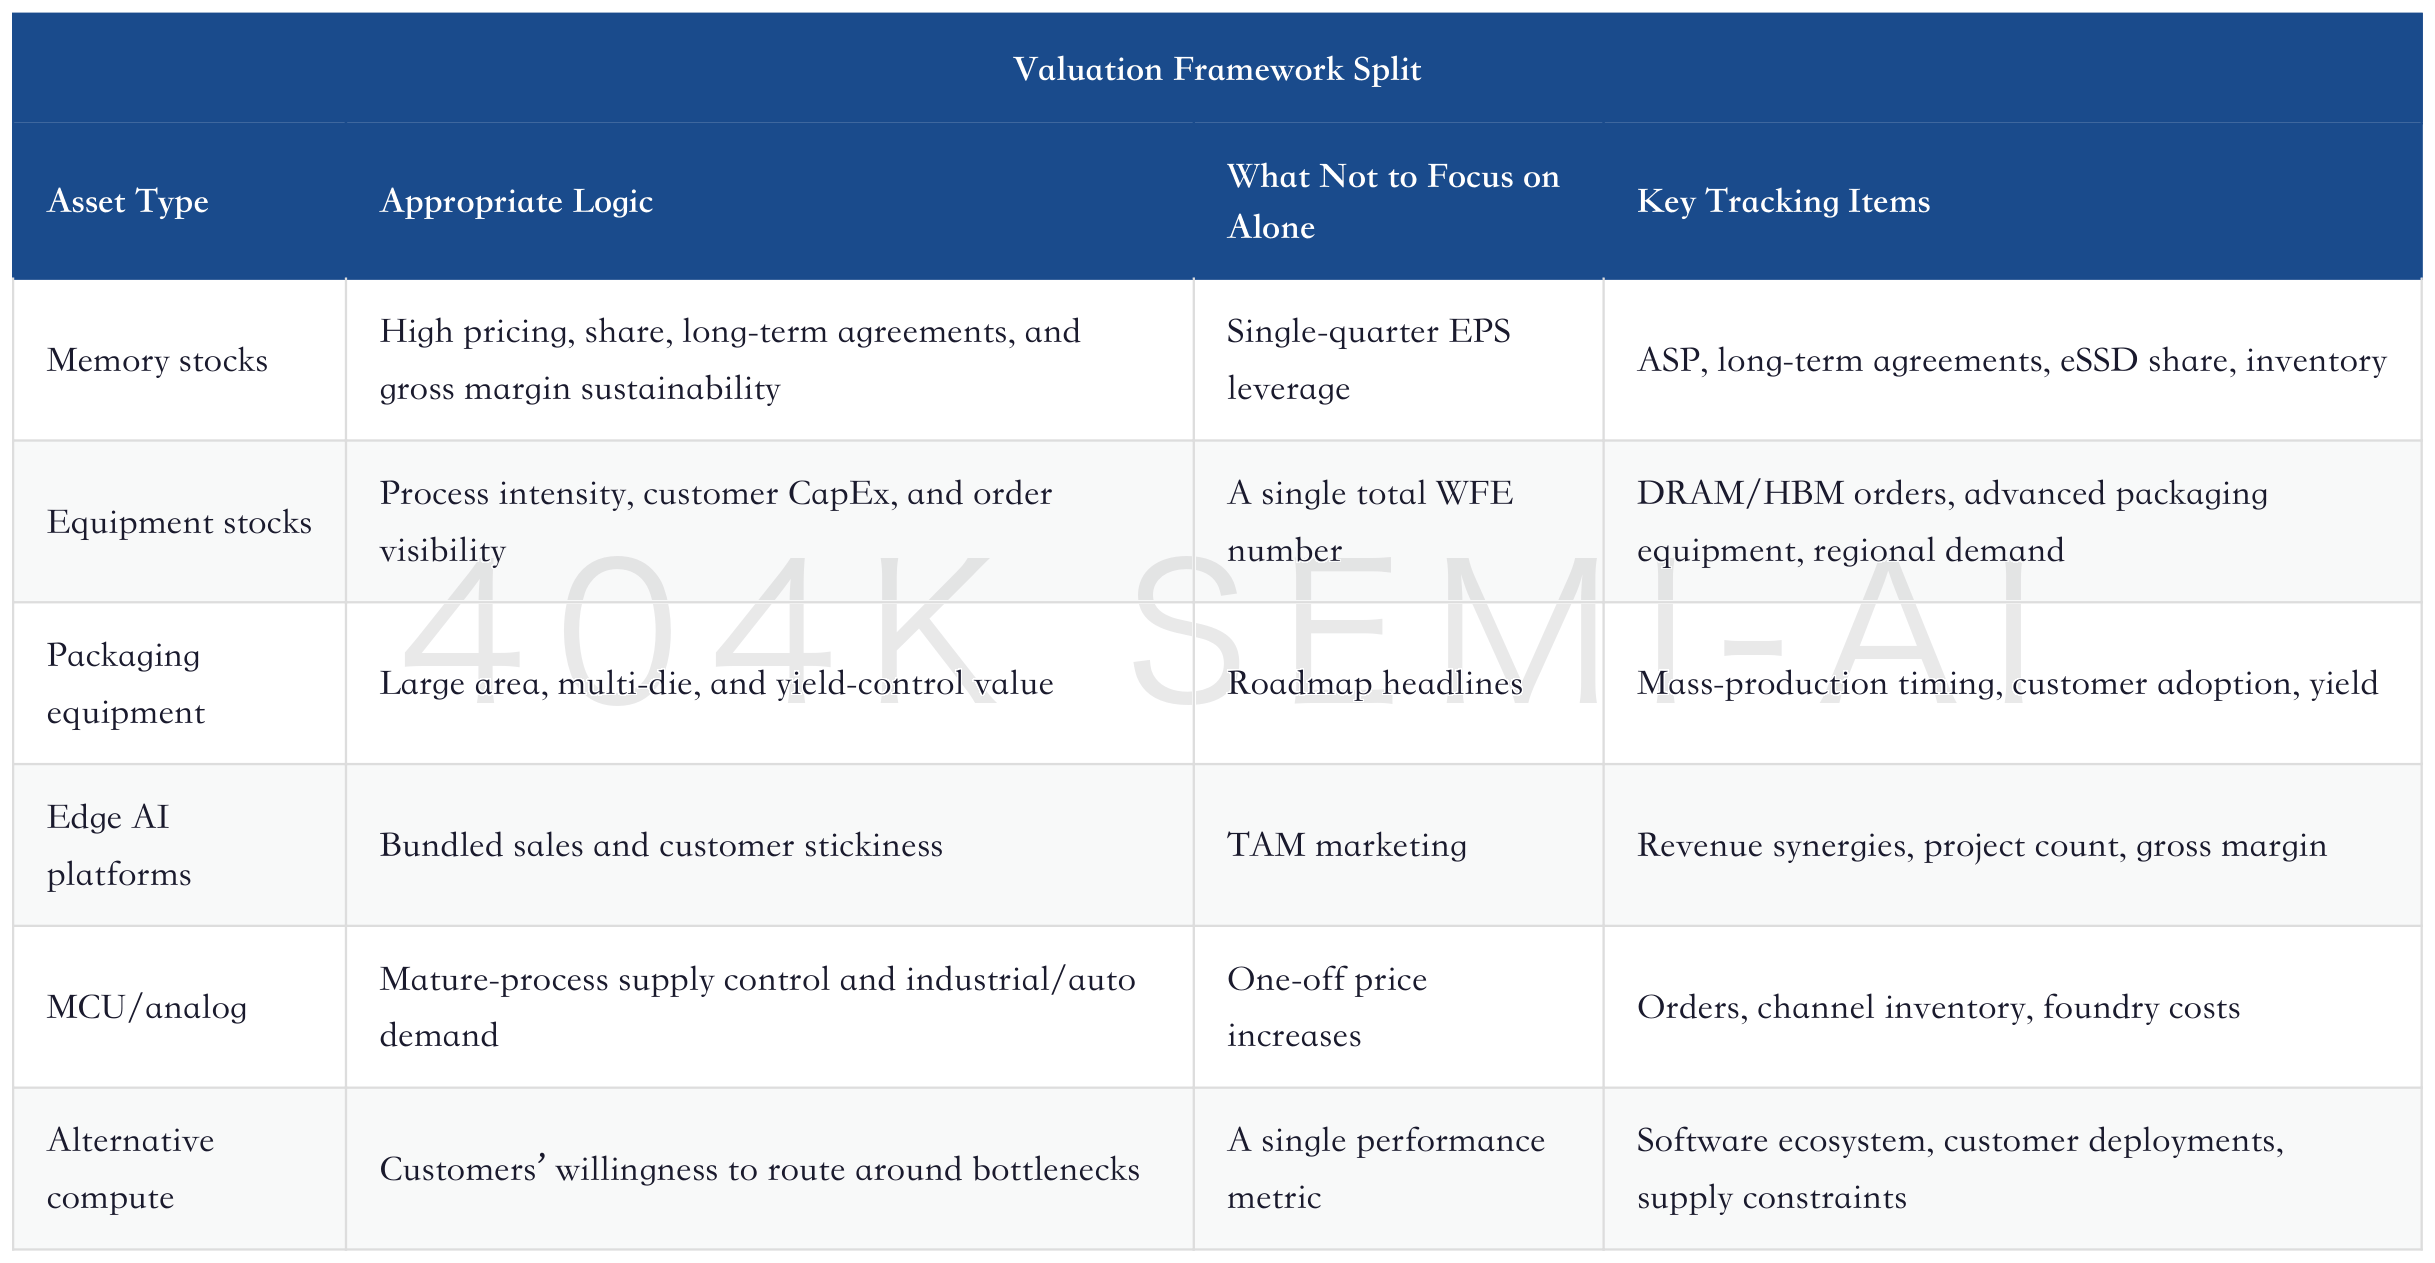
This table is also the baseline for subsequent tracking. The biggest risk for memory stocks is a pricing rollback; for equipment stocks, order pushouts; for edge AI platforms, slow integration; for MCUs and analog, channel inventory; and for alternative compute, insufficient ecosystem depth. Only by separating these risks can investors judge which line is undergoing a real re-rating and which is merely following the AI theme for a period.
14. New Information in This Report Relative to Our Prior View
Previously, the memory and equipment lines had repeatedly shown that AI demand is squeezing DRAM, NAND, HBM, eSSD, WFE, and advanced packaging. The incremental contribution of this Jefferies update is that it more clearly pushes “upstream price increases” into “downstream device price increases” and “non-AI demand destruction” for the first time. It tells us that the memory tax has moved beyond an upstream investment slogan and is beginning to enter consumer electronics, MCU, industrial, and automotive BOMs.
AI Drives a Sector-Wide Memory Re-Rating: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, as Earnings from Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Cross-Validate Each Other
The second new point is that SanDisk’s recovering eSSD share gives the NAND re-rating a more specific lever. In the past, when discussing NAND price increases, the market could easily view it as just industry beta. Now, with eSSD share recovering from low levels, stronger preference for SLC NAND, and more long-term agreements and floor prices, SanDisk has an explanation that looks more like company-specific alpha. Price increases are industry resonance; share gains are company differentiation.
The third new point is that Applied Materials’ Masterclass shifts the equipment-stock logic from aggregate volume to intensity. Total WFE is important, but in the AI era, what matters more is how much complexity each dollar of CapEx buys. DRAM, HBM, 3D DRAM, advanced packaging, and panel-level packaging are all increasing equipment value content, making equipment-stock earnings durability stronger than in traditional fab expansion cycles.
