
Seagate Technology F4Q26 Deep Dive: Nearline Capacity Locked Through 2028—Can Price Increases and HAMR Support a $1,187 Price Target?
目录
TL;DR
Versus Initiation: Three Points Confirmed, Two Still Unresolved
This Is More Than an Ordinary “Beat”: Margin Upside Matters More Than Revenue
Earnings Quality: Cash Flow Is Not Merely a Product of Accounting Adjustments
Three Keys: Shipments, Pricing, and Unit Costs Are All Moving Favorably
What Exactly Is “Locked In Through 2028”?
HAMR Has Evolved From a Narrative Into a Profit Tool, but It Is Not Yet a Risk-Free Straight Line
The Most Easily Misread Figures: Gross Margins of 63.5% and 74.8%
$1,187 Price Target: Earnings Drive the Upside, While the Multiple Drives the Risk
Free Cash Flow Is Beginning to Shift From “Repairing the Balance Sheet” to “Reducing the Share Count”
What to Watch Next
Conclusion: Seagate Technology Has Moved from Cyclical Recovery to Expectations Management
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The key to Seagate Technology’s valuation has become the simultaneous delivery of four factors: longer visibility into capacity, pricing, unit costs, and capital allocation.
TL;DR
Seagate Technology’s F4Q26 revenue was $3.629 billion, up 48.5% year over year; non-GAAP gross margin was 52.7%, up 14.8 percentage points year over year; and diluted EPS was $5.71, up approximately 121%. Revenue was strong, but profit growing far faster than revenue was the quarter’s most important change.
Data center revenue was $2.933 billion, up 57% year over year; nearline HDD shipments were 195EB, up 43%. The company said most nearline supply has already been allocated through 2028, while customers are planning beyond 2029. However, “capacity allocation” does not mean multiyear fixed pricing, much less that margins are locked in.
Morgan Stanley believes revenue per EB increased 10.3% year over year in the June quarter and that the September quarter’s price increase may approach 25%; meanwhile, cost per EB fell 15.9% year over year. Volume, price, and cost all moved in the same favorable direction, while quarterly operating expenses were almost unchanged, creating exceptional operating leverage.
The $1,187 price target comes from Morgan Stanley applying a 20x P/E multiple to its calendar-year 2027 EPS estimate of $59.33. The issue is not the calculation but the inputs: its FY2027 and FY2028 gross-margin forecasts are as high as 63.5% and 74.8%, respectively, clearly more aggressive than the company’s formal guidance, which covers only the next quarter.
Seagate Technology has reduced net leverage to 0.4x. Following the July repayment of $1 billion in high-yield notes, capital allocation is expected to shift from “repairing the balance sheet first” toward “more buybacks.” However, if pricing normalizes, HAMR qualification slows, or supply expands again, both earnings and the valuation multiple may decline.
Versus Initiation: Three Points Confirmed, Two Still Unresolved
The previous full deep dive framed Seagate Technology’s rerating around three themes: whether high-capacity nearline HDDs could secure longer order visibility, whether Mozaic 4+ could convert its HAMR lead into a unit-cost advantage, and whether free cash flow could first complete deleveraging and then transition to buybacks. F4Q26 provided stronger quarterly evidence for all three themes, and any new investment conclusions should also center on these changes.
The first confirmed point is that demand visibility continues to extend. The market had previously focused more on capacity arrangements for 2027; this quarter, the company described “most nearline supply” as allocated through 2028, while customer planning now extends beyond 2029. Each additional year of visibility further reduces the near-term risks of idle capacity and a sharp loss of pricing momentum.
The second confirmed point is that HAMR has entered commercial ramp-up rather than remaining only on qualification lists. Mozaic 3+ has already reached the production environments of all major cloud customers, while Mozaic 4+ has begun ramping at two of the world’s largest cloud service providers. The third confirmed point is the concurrent improvement in cash flow and the balance sheet: FY26 free cash flow reached $3.105 billion, net leverage declined to 0.4x, and the cleanup of high-cost debt entered its final stage.
The first unresolved issue is how long elevated pricing can persist. Allocated capacity does not mean prices can continue rising every quarter, nor does it guarantee that customers will not use procurement mix, contract renegotiations, or tiered solid-state storage to reduce costs. The second issue is whether HAMR cost reductions can maintain yields across more customers and at greater scale. The current ramp at two major customers is only the starting point; stable manufacturing performance after broader adoption will ultimately determine long-term gross margins. These two unresolved issues also represent the largest gap between Morgan Stanley’s long-term model and the company’s near-term guidance.
This Is More Than an Ordinary “Beat”: Margin Upside Matters More Than Revenue
Seagate Technology’s F4Q26 revenue increased 48.5%, from $2.444 billion a year earlier to $3.629 billion. Viewed solely through revenue, this could still be interpreted as a strong cyclical upswing jointly driven by inventory replenishment among cloud customers, rising nearline capacity, and tight industry supply. However, the income statement sent a stronger signal. Non-GAAP gross margin increased from 37.9% to 52.7%, operating margin from 26.2% to 44.6%, diluted EPS from $2.59 to $5.71, and free cash flow from $425 million to $1.118 billion.
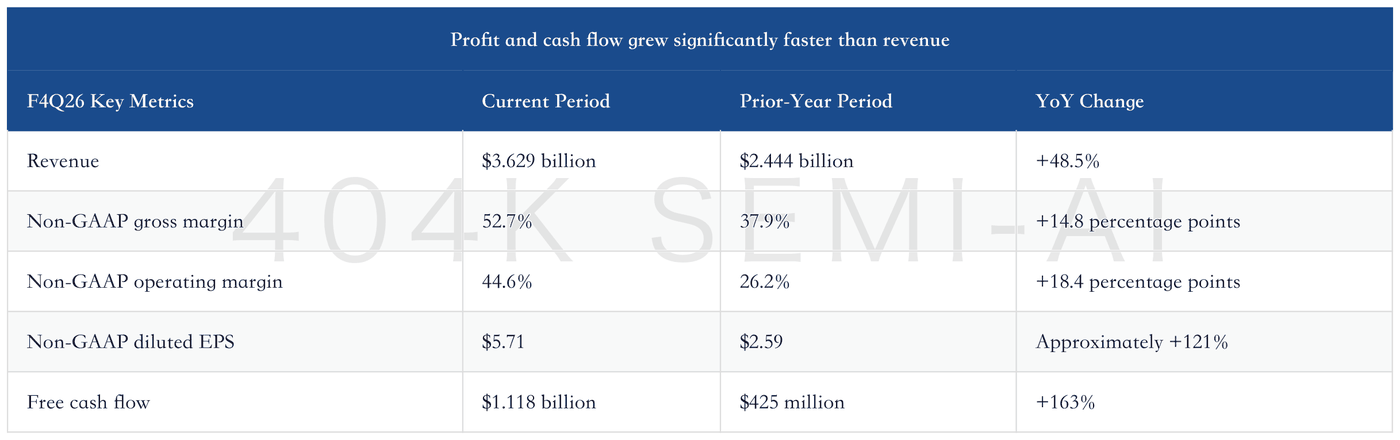
The incremental gross profit is particularly worth unpacking. Quarterly revenue increased by $1.185 billion year over year, while non-GAAP gross profit rose by $986 million, from $926 million to $1.912 billion. Based on these two sets of reported figures, the implied incremental gross margin on the additional revenue was approximately 83.2%. Meanwhile, non-GAAP operating expenses increased only from $286 million to $293 million. In other words, almost none of the additional revenue was absorbed by expense growth; instead, it passed directly through both the gross-margin and expense gates into operating profit and cash flow.
This is also why next quarter’s guidance carries more weight than the revenue figure itself. The company guided to an F1Q27 revenue midpoint of $4.1 billion, a non-GAAP operating margin of approximately 50%, and an EPS midpoint of $7.30. Multiplying $4.1 billion by 50% yields approximately $2.05 billion in operating profit; adding approximately $300 million in operating expenses implies gross profit of approximately $2.35 billion, corresponding to a gross margin of approximately 57.3%. This is an arithmetic derivation based on the company’s guidance, not separate gross-margin guidance issued by the company. However, it is close to Morgan Stanley’s estimate of approximately 57.5%, indicating that margin expansion has not yet peaked in the September quarter.
Earnings Quality: Cash Flow Is Not Merely a Product of Accounting Adjustments
Whether high margins convert into cash is the second test of the quality of an upcycle in manufacturing. This quarter, GAAP net income was $1.294 billion and operating cash flow was $1.305 billion, broadly matching each other. After $187 million in capital expenditures, free cash flow remained $1.118 billion, equivalent to 30.8% of revenue. Full-year operating cash flow was $3.674 billion, exceeding GAAP net income of $3.184 billion; after $569 million in capital expenditures, free cash flow was $3.105 billion. At least in the current period, profit growth was not entirely absorbed by inventory, accounts receivable, or capital-intensive investment.
