
目录
Executive Summary
Q4 Was Not an Ordinary Beat; It Was a Stress Test of the Existing Thesis
Data Centers Are Now a Core Business, but Revenue Alone Is Not Enough
What the $93.9 Billion of NBMs Actually Secure
How Long Can an 84.6% Gross Margin Last?
Cash Flow Is Strong, but Its Quality Has Two Layers
Valuation Should Shift From “How High Are Profits?” to “How Long Can They Last?”
The Next 6 Validation Points
Conclusion: Contracts Raise the Floor, but Pricing Still Sets the Ceiling
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
SanDisk posted record Q4 revenue, gross margin, and cash flow at the same time. Whether $93.9 billion of non-binding memoranda, or NBMs, can turn the data center upcycle into durable profits will determine what this growth is worth.
Executive Summary
SanDisk's fourth-quarter revenue reached $8.965 billion, up 51% sequentially, while non-GAAP gross margin reached 84.6%; both exceeded the high end of the company's prior guidance. The composition matters even more: about 33% of the sequential increase came from bit shipments and about 67% came from pricing. Profitability has moved beyond a conventional recovery into scarcity-driven supply pricing, but that also makes it more dependent on NAND prices and supply discipline.
Data center revenue reached $2.977 billion, doubling sequentially and accounting for 33% of quarterly revenue; the related share of total bits rose from 12% one year ago to 38%. This proves that enterprise SSDs have become a material destination for capacity. Data center revenue, however, is still being driven by both product-share gains and higher NAND prices. The next test is whether revenue, bit mix, and customer expansion can keep rising together.
For the first time, NBMs have moved from vague “long-term agreements” to a measurable contract portfolio: 8 customers, $93.9 billion of minimum contract revenue, $59.8 billion of remaining performance obligations at quarter-end, and $16.5 billion of financial guarantees. About 50% of fiscal 2027 bits and about 67% of fiscal 2028 bits are committed, materially improving revenue visibility. Yet the guarantees cover only about 18% of minimum contract revenue, so the contracts do not eliminate counterparty, price-cap, or product-delivery risk.
Fourth-quarter operating cash flow was $7.126 billion and reported free cash flow was $7.083 billion, but adjusted free cash flow was $5.035 billion after excluding NBM prepayments and deposits and including Flash Ventures activity. Cash generation is exceptionally strong, while roughly $2 billion of the total reflects contract-payment effects. Adjusted free cash flow is the better measure of cash quality, alongside receivables, inventory, refund liabilities, and contract liabilities.
The midpoint of SanDisk's fiscal 2027 first-quarter guidance is $10.55 billion of revenue, $45 of non-GAAP EPS, and a gross margin of about 84%. That suggests elevated profitability will persist for at least 1 more quarter. A higher valuation multiple will require the gross margin to hold as supply expands, inventory rises, and customer contracts enter fulfillment; mechanically annualizing 1 quarter of EPS is not enough.
Q4 Was Not an Ordinary Beat; It Was a Stress Test of the Existing Thesis
The most important feature of SanDisk's report is that nearly every optimistic assumption from the prior quarter received a strong simultaneous validation. Fourth-quarter revenue was $8.965 billion, an increase of $3.015 billion from the third quarter and about 12% above the $8 billion midpoint of prior guidance. The company said explicitly that roughly one-third of the sequential increase came from higher shipments and two-thirds from pricing. As a rough bridge, pricing contributed about $2 billion of incremental revenue, while volume and mix contributed about $1 billion.
That split is more important than the headline 51% growth rate. If most of the increase had come from bits, the market could have treated it mainly as an enterprise SSD share-gain story. Because two-thirds came from pricing, the 84.6% gross margin still carries a substantial cyclical windfall. GAAP gross margin increased 6.2 percentage points sequentially, and GAAP operating income reached $7.037 billion, equal to a 78.5% operating margin. Non-GAAP operating income was $7.104 billion against only $484 million of operating expenses, showing that incremental pricing and product mix flowed almost directly to profit.
The previous full model estimated fourth-quarter revenue of $8 billion and data center revenue of $2.4 billion; actual results were 12% and 24% higher, respectively. Fiscal 2026 revenue of $20.248 billion was also about 5% above the old model's $19.283 billion, while full-year non-GAAP EPS of $70.88 exceeded the old $61.75 estimate by about 15%. The thesis that data centers, pricing, and BiCS8 would lift earnings together was validated, but the constraint that peak gross margins must eventually normalize was not disproved.
SanDisk and Western Digital Fiscal Q3 2026 Earnings: NAND Windfall, HDD Cash Flow, and Validation of the AI Storage Cycle
Data Centers Are Now a Core Business, but Revenue Alone Is Not Enough
Data center revenue reached $2.977 billion, up 103% sequentially and 1,298% year over year, and rose to 33.2% of quarterly revenue. Edge remained the largest end market at $5.432 billion, or 60.6% of revenue. Consumer revenue fell to just $556 million, or 6.2%. Compared with one year ago, SanDisk's profit center has clearly shifted away from consumer and client products toward higher-value enterprise SSDs.
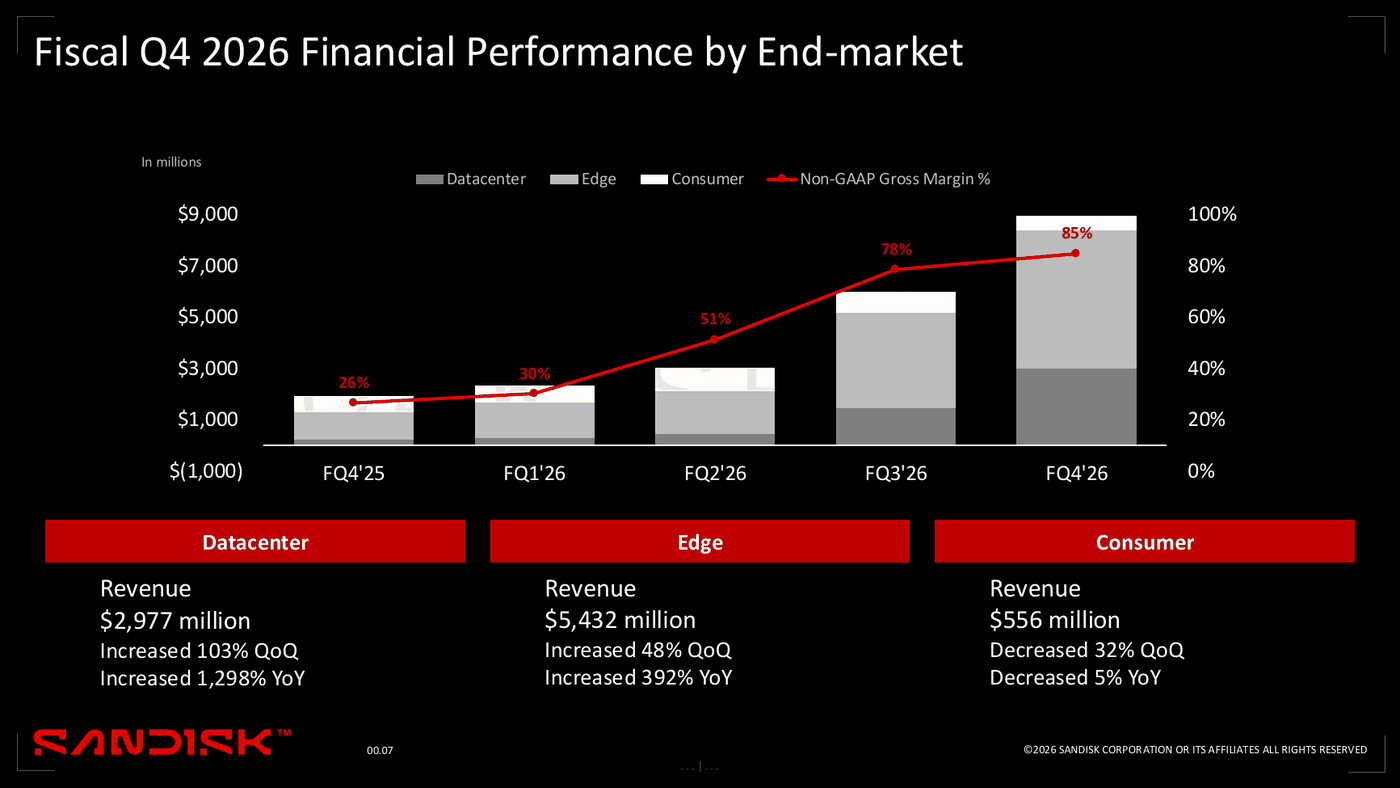
Page 7 of SanDisk's Fiscal 2026 Fourth Quarter Earnings Presentation shows data center revenue ramping alongside the rise in non-GAAP gross margin, supporting the view that a higher-value product mix is improving profitability.
Management supplied another, more discriminating data point: data centers rose from 12% of company bits in fiscal Q4 2025 to 38% in fiscal Q4 2026. A 33% revenue share and a 38% bit share show that data centers are now a material destination for capacity rather than an accounting fluctuation caused by a handful of premium products. Compute TLC enterprise SSDs have entered more hyperscale and AI infrastructure customers, while the QLC Stargate platform began generating revenue this quarter.
The real tracking test is whether data center revenue, data center bit share, and the number of enterprise SSD customers continue to rise together. If revenue increases while bit share stalls, the gain may be mostly NAND pricing. If bit share rises while gross margin falls quickly, SanDisk may be buying share through price. Only when all three move in the same direction can the company prove that it is converting roughly half of its joint-venture wafer supply into higher-value products.
Management expects data centers to increase from about 30% of global NAND industry revenue in 2025 to about 50% in 2026. Its internal model effectively gives the segment an Outperform rating versus the market in 2027. This is a company forecast, not a realized outcome. The presentation even cites an industry scenario in which NAND revenue rises from more than $300 billion in 2026 to $500 billion in 2027, an increase of about 67%. That scenario helps explain why customers are competing for long-term supply, but it should not be used directly as a valuation baseline. A change in end demand, competitor yields, or new supply could sharply reduce the forecast.
What the $93.9 Billion of NBMs Actually Secure
The biggest incremental disclosure this quarter was not a tenth contract, but the decision to put contract value, guarantees, and bit coverage on the same page. SanDisk disclosed that 8 data center and Edge customers have signed NBMs. Minimum contract revenue, calculated at price floors, totals $93.9 billion. Remaining performance obligations, or RPO, were $59.8 billion at quarter-end and would have been $91.1 billion including 2 agreements signed after the quarter. Cash deposits and guarantees from financial instruments total $16.5 billion. The weighted-average contract term exceeds 4 years, with a maximum of 5 years.
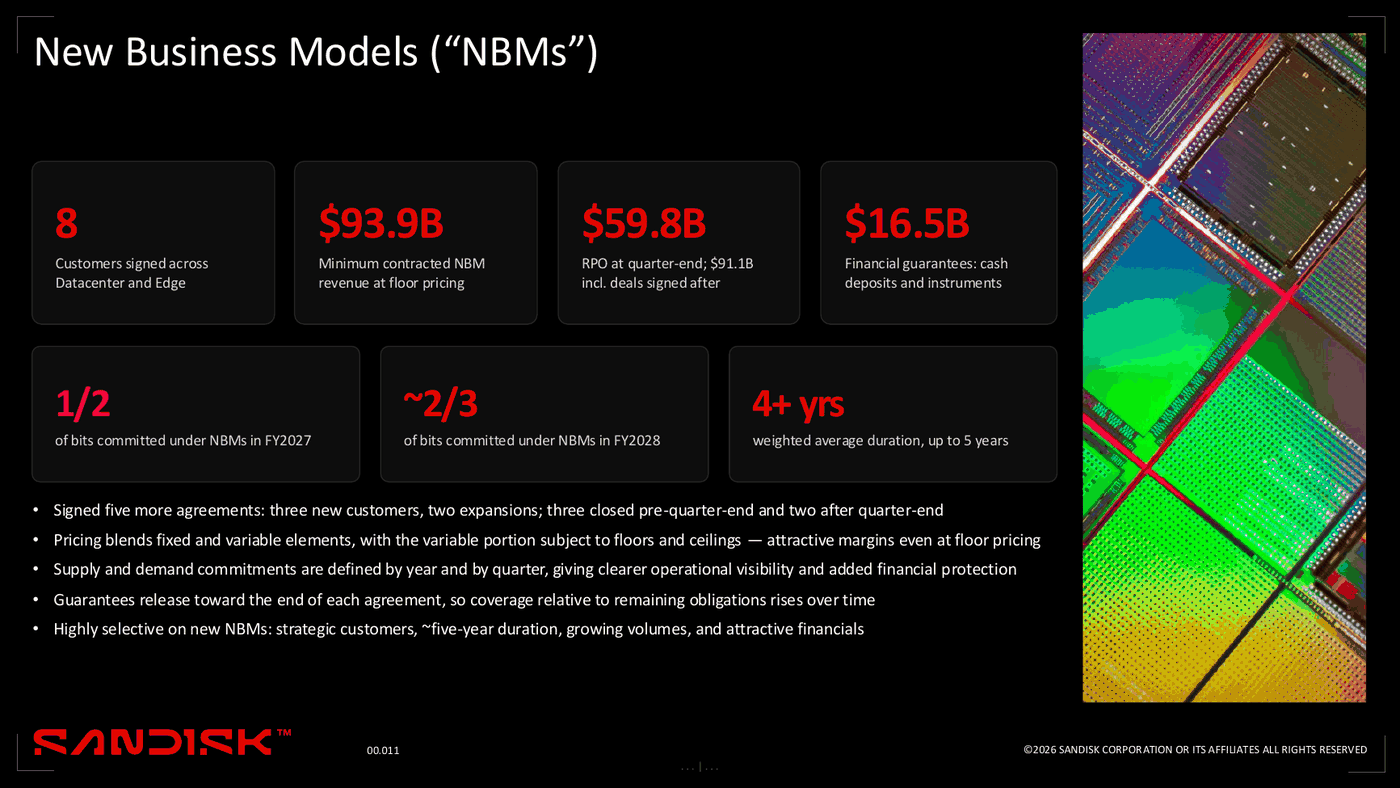
Page 11 of SanDisk's Fiscal 2026 Fourth Quarter Earnings Presentation places NBM value, guarantees, duration, and bit commitments on a consistent basis, proving that the contract story has entered a measurable phase.
The quality of disclosure has changed fundamentally from the prior quarter. Previously, official materials disclosed only $41.6 billion of RPO across 3 agreements and referred to firm financial commitments; more than $11 billion of guarantees came mainly from sell-side materials. This quarter, SanDisk directly disclosed $16.5 billion of guarantees and $93.9 billion of minimum contract revenue, closing the main information gap around guarantee size and showing that later agreement expansions were much larger than the earlier disclosure.
Long-Term Memory Contracts: How Strong Are SanDisk's and Micron's AI Memory Agreements Backed by $11 Billion of Guarantees and $22 Billion of Cash Letters of Credit?
NBMs secure supply-and-demand responsibility first and profits second. About half of fiscal 2027 bits and two-thirds of fiscal 2028 bits are covered by agreements. Supply and demand commitments are defined by year and quarter, while pricing combines fixed and variable components with floors and ceilings. SanDisk can therefore plan wafers, process nodes, and inventory earlier, while customers gain multiyear supply certainty. The $93.9 billion of minimum contract revenue equals about 4.6 times fiscal 2026 revenue. Even when spread over more than 4 years, it is large enough to change how capacity is planned.
But $93.9 billion cannot be added directly to valuation. First, it is multiyear revenue calculated at price floors, not profit, cash, or a current order book. Second, the $16.5 billion of guarantees equals only about 17.6% of minimum contract revenue. The company says guarantee coverage should rise relative to remaining obligations later in the contracts, but coverage is not complete upfront. Third, price ceilings can limit the profit upside of committed bits if open-market prices continue to climb. Fourth, specifications, quantities, delivery timing, and customer credit can still lead to reductions, refunds, or disputes.
NBMs raise the bottom of the cycle; they do not abolish the cycle. Greater contract coverage should make SanDisk less vulnerable to simultaneous collapses in volume and price during a downturn. Open-market bits, noncontract customers, Flash Ventures fixed costs, and new-node yields will still preserve cyclical volatility. Whether the valuation multiple can expand will ultimately depend on the conversion of contract liabilities into revenue, realization of guarantees, and adjusted free cash flow—not merely on continued RPO growth.
How Long Can an 84.6% Gross Margin Last?
First-quarter guidance offers a clear short-term answer: conditions remain strong, but management has not promised that the level is permanent. Fiscal 2027 first-quarter revenue guidance is $10.3 billion to $10.8 billion, with a midpoint of $10.55 billion, implying about 17.7% sequential growth. Non-GAAP gross-margin guidance is 83% to 85%, with a midpoint of 84%, nearly unchanged from the fourth quarter. Non-GAAP EPS guidance is $44 to $46, with a midpoint of $45, up about 14.6% sequentially.
Three factors support elevated near-term margins. First, customer demand is growing faster than SanDisk supply, and the company expects bit-allocation conditions to persist into 2027 and beyond. Second, BiCS8 now represents the majority of bit output, while the TLC and QLC mix is shifting toward higher-value data center products. Third, NBM price floors and quarterly commitments reduce the probability that volume and price fall at the same time.
The counterevidence is equally clear: SanDisk expects fiscal 2027 supply bits to grow in the high teens, while saleable bits increase only in the mid-teens; most of the difference will build inventory. Inventory can support NBMs and absorb higher component costs, but it also leaves future supply pressure on the balance sheet. If competitors expand capacity, improve yields, or face weaker-than-expected demand in traditional end markets, inventory could shift from supply assurance to pricing pressure.
Gross margin also cannot be separated from the volume-price bridge. Roughly two-thirds of the fourth-quarter revenue increase came from pricing, making price the single largest contributor to the elevated margin. Data center mix and BiCS8 can raise the structural floor, but SanDisk will have proved a structural upgrade only if gross margin remains well above the historical cycle midpoint after average selling prices normalize. Over the next 2 quarters, the key question is not whether gross margin reaches another record, but whether data center bits, cost reductions, and contract pricing fill the gap as the contribution from price declines.
Cash Flow Is Strong, but Its Quality Has Two Layers
Fourth-quarter operating cash flow was $7.126 billion and company-defined free cash flow was $7.083 billion, making it appear that almost all operating profit converted into cash. The official reconciliation, however, shows adjusted free cash flow of $5.035 billion after excluding the $1.938 billion impact of NBM prepayments and deposits and including net Flash Ventures activity. Reported free-cash-flow margin was about 79%, while adjusted free-cash-flow margin was about 56%. Both are strong, but the latter is closer to sustainable operating cash generation.
Working-capital movements explain why headline operating cash flow is insufficient. Receivables increased by $1.982 billion and inventory rose by $460 million in the fourth quarter, consuming a combined $2.442 billion of cash. Refund liabilities increased by $1.36 billion, contract liabilities by $731 million, and tax payables by $730 million, providing substantial cash. Contract expansion naturally moves these accounts, but operating cash flow can fall sharply when the timing of prepayments, refunds, and tax payments changes.
The balance sheet is much stronger than it was one year ago, but it is not unconstrained. Quarter-end cash was $4.762 billion, marketable equity securities were $1.777 billion, and long-term debt had fallen to zero. SanDisk repurchased $4.524 billion of stock in the fourth quarter and has $15.5 billion remaining under its authorization. The remaining authorization equals about 2.4 times the combined cash and equity-securities balance, which means future repurchases must rely on continuing free cash flow rather than the current cash stockpile alone.
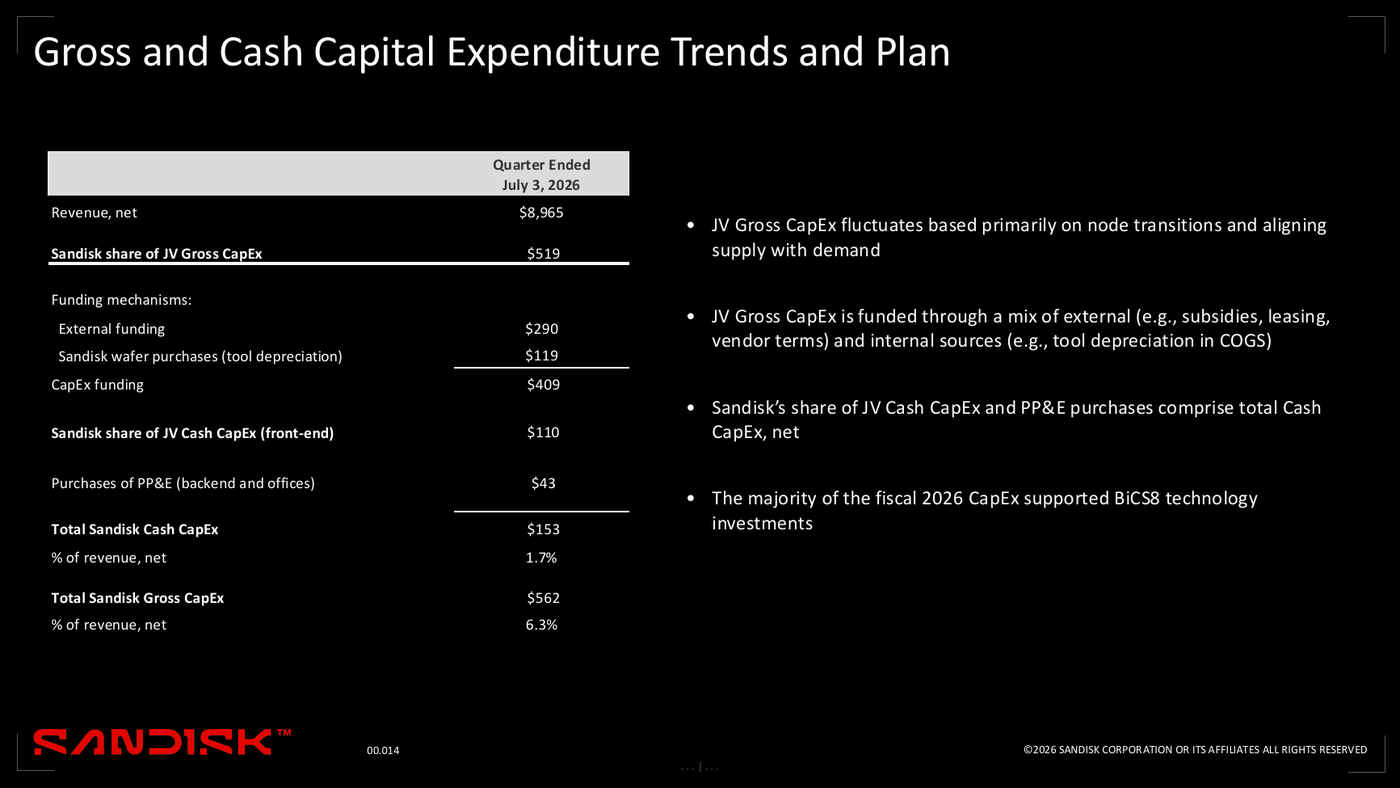
Page 14 of SanDisk's Fiscal 2026 Fourth Quarter Earnings Presentation shows that SanDisk's share of gross joint-venture capital expenditure was $519 million, while joint-venture cash capex plus back-end property, plant, and equipment totaled only $153 million for the quarter. The 2 figures answer different questions and should not be deducted twice.
Flash Ventures remains the easiest place to make a cash-flow analytical error. SanDisk's share of gross joint-venture capital expenditure was $519 million in the fourth quarter. External financing was $290 million and equipment depreciation embedded in wafer purchases was $119 million, leaving SanDisk's share of joint-venture cash capital expenditure at $110 million. Adding $43 million of back-end and office PP&E; purchases brings total cash capex to $153 million. Cash capex was only 1.7% of revenue, while total gross capex was 6.3%. The joint-venture structure lowers current cash intensity; it does not eliminate manufacturing equipment, depreciation, financing, or supply commitments.
Valuation Should Shift From “How High Are Profits?” to “How Long Can They Last?”
The midpoint of first-quarter EPS guidance is $45, or $180 when mechanically annualized, but that is a sensitivity rather than a full-year forecast. At a traditional cyclical-stock multiple of 8 times earnings, the implied value would be about $1,440 per share. If NBMs, data center share, and cash-flow quality justify 10 times earnings, the implied value would be about $1,800. For the higher multiple to hold, subsequent quarterly EPS would need to remain at or above the first-quarter level while gross margin becomes less dependent on ever-higher prices.
The prior $1,900 base-case price target did not assume that an 84.6% gross margin would last forever. It instead assumed roughly $190 to $200 of normalized EPS and a multiple near 10 times. Fourth-quarter results make that earnings step more credible: full-year non-GAAP EPS was $70.88, and the first-quarter guidance midpoint alone is another $45. The $93.9 billion of NBMs also improves visibility into the long-term floor for volume and price. Visibility is not realization, however. A formal increase in long-term valuation still requires at least 2 pieces of evidence: adjusted free cash flow remains high as NBM revenue begins to be recognized, and gross margin does not quickly fall back into the traditional cyclical range after new supply arrives.
In the most optimistic scenario, data center bits continue to expand, NBMs are renewed, BiCS8 and BiCS10 lower unit costs, and gross margin remains elevated after pricing normalizes. In the neutral scenario, contracts raise the earnings floor, but new supply gradually brings gross margin down and the stock retains a cyclical multiple. In the downside scenario, slower customer deployments, inventory releases, and competitor expansion occur together; NBM price ceilings limit upside while guarantees fail to cover all default losses. The dividing lines among the 3 scenarios are not industry slogans but measurable gross margin, adjusted free cash flow, inventory, and contract-liability conversion.
The Next 6 Validation Points
First, can data center revenue keep growing faster than total revenue? If next-quarter revenue reaches the $10.55 billion guidance midpoint, data center revenue should at least maintain a roughly one-third share to prove that enterprise SSDs remain the main growth engine.
Second, can data center bit share rise beyond 38%? Revenue growth without a higher bit share would show that pricing still contributes more than product share. Simultaneous growth in bit share and revenue would demonstrate structural improvement.
Third, if gross margin stays near 84%, what does the volume-price bridge look like? When pricing's contribution falls from roughly two-thirds in the fourth quarter, BiCS cost reductions, QLC mix, and contract pricing must take over.
Fourth, can NBM RPO, guarantees, and contract liabilities convert into revenue together? The $93.9 billion of minimum contract revenue has little meaning by itself. RPO recognition, guarantee coverage, declining contract liabilities, and cash collections must appear together to prove fulfillment.
Fifth, does the gap between adjusted and reported free cash flow narrow? The fourth-quarter gap was $2.048 billion, driven mainly by NBM payments and joint-venture activity. A widening gap would mean that cash generation is becoming more dependent on customer prepayments.
Sixth, do inventory and repurchases squeeze the balance sheet? Building inventory to support long-term agreements is rational, but the cash cushion will decline if inventory days, repurchase activity, and supply expansion rise at the same time.
Conclusion: Contracts Raise the Floor, but Pricing Still Sets the Ceiling
SanDisk's fourth quarter proves that the company is no longer merely a passive beneficiary of higher consumer NAND prices. Data center bit share has risen to 38%, QLC Stargate has begun shipping, NBMs cover about half of fiscal 2027 bits, and contract values and guarantees are measurable for the first time. The company now has better visibility into capacity planning, customer responsibility, and cash flow.
The report does not yet prove that an 84.6% gross margin is durable. About two-thirds of incremental revenue came from pricing, inventory is rising, the industry's market-size assumptions are aggressive, and the economic cost of joint-venture manufacturing has not disappeared. NBMs can soften a downturn, but they cannot replace customer performance, product competitiveness, or supply discipline.
The investment view is therefore more positive and more specific than it was one quarter ago: SanDisk's earnings floor has genuinely risen because of data centers and long-term agreements, but the valuation cannot escape a traditional cyclical discount until contracts convert into revenue, the pricing contribution declines, and adjusted free cash flow remains strong. There is no need to guess how large the NAND story might become. The next proof point is whether data center bits, an 84% gross margin, NBM performance, inventory, and roughly $5 billion of adjusted free cash flow can keep appearing in the same quarter.