
SanDisk Deep-Dive Update: Jefferies’ $3,000 Target, eSSD Share Recovery, and How NAND LTAs Reprice Earnings Durability
目录
Too Long; Didn’t Read
1. First, Clarify the $3,000: It Has Moved From Blue-Sky Scenario Into the Base-Case Model
2. SanDisk’s Core Product Is Now Entering the AI Data-Center Capacity Layer
3. eSSD Share Recovery Is the Strongest New Evidence Behind Jefferies’ Upgrade to $3,000
4. NBMs Are the Second Main Thread: They Determine Whether Earnings Can Carry Through the Cycle
5. Official FQ3 Data Has Already Validated “Pricing Elasticity”
6. Divergence Across Firms: Everyone Is Bullish on NAND Tightness, but the Multiples Differ
7. NAND Industry Supply Discipline Is SanDisk’s External Moat for High Gross Margins
8. Consumer Electronics Price Increases Are a Double-Edged Sword: They Prove Cost Pressure and Expose Demand Destruction
9. SanDisk’s Asset Profile Is Changing: From NAND Price Leverage to Supply Rights and Contracted Cash Flow
10. Three Worldviews: Cycle Peak, Profit Step-Up, and AI Storage Platform
11. Valuation Bridge: From $1,700 to $3,000, the Gap Is Four Variables
12. Versus Micron, Kioxia, and Western Digital, SanDisk Offers “NAND Purity + LTA Leverage”
13. The Next Four Quarters Require Watching a Set of Matching Relationships
14. Earnings Bridge: From NAND Price Increases to C28 EPS, There Are Six Gates
15. NBM Stress Test: How Much Profit Drawdown Can Contracts Absorb When Prices Fall?
16. Technology Roadmap: TLC, QLC, SLC, and HBF Correspond to Different Profit Quality
17. Cash Flow and Capital Returns: High Profit Must Become Distributable Cash
18. Risk Breakdown: The Three Things SanDisk Should Fear Most
19. Why This Requires a Separate Update: The Variables Behind $3,000 Have Changed
20. Data Framework: Price-Target Revisions Should Be Split Into Earnings, Multiple, and Forward Credibility
21. Scenario Model: What Evidence Is Needed for $3,000, $4,000, and $1,250
22. Falsification Cadence: Price Moves First, Contracts Are Verified Later, Share Takes the Longest
23. Event Calendar: August Investor Day Will Decide Which Track the Market Focuses On
24. Conclusion: SanDisk Enters the “$3,000 Validation Period”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Jefferies raised its SanDisk target price to $3,000, indicating that the NAND trade has shifted from price elasticity to earnings durability. This report breaks down eSSD share recovery, NBM long-term agreements, AI inference storage demand, and peer supply discipline, assesses which data points can further validate this rerating, and lays out the next tracking framework.
Too Long; Didn’t Read
The target-price upgrade has entered a new phase. Jefferies raised its SanDisk target price from $1,400 to $3,000. The key change is that eSSD share recovery and higher C28 earnings are now embedded in the base-case model.
eSSD is the central axis of this rerating. TrendForce data show SanDisk’s enterprise SSD revenue share rose from 4% to 8% in the most recent quarter. Jefferies believes the company still has room to return to its historical mid-to-high-teens share.
NBM LTAs are changing the cycle discount. The company has already locked more than one-third of FY27 bits into the new business model. Some agreements include price floors, prepayments, and default compensation, and the market is beginning to price earnings durability.
Valuation dispersion comes from the earnings mid-cycle level. Citi is at $2,500, BofA at $2,100, Morgan Stanley at $1,750, and Bernstein at $1,700. The differences center on whether CY27/CY28 EPS and gross margin can hold up.
Supply discipline determines the upside ceiling. Kioxia, Samsung, SK hynix, and Micron are all directing advanced resources toward DRAM/HBM. NAND incremental supply is slower than AI SSD demand, which is critical to whether SanDisk can sustain high gross margins.
Watch five numbers for follow-through. Focus on eSSD share, NBM coverage, RPO and financial guarantees, FQ4 gross-margin guidance, and data-center revenue mix. These numbers will determine whether $3,000 becomes the new base case or a near-term peak.
1. First, Clarify the $3,000: It Has Moved From Blue-Sky Scenario Into the Base-Case Model
The most important new change in this SanDisk cycle is the status of the $3,000 target price. In early April, the market still treated $3,000 as an extreme blue-sky scenario. On June 26, Jefferies made it the official target price in Blayne’s Bytes and maintained its BUY rating on SNDK. This change matters more than the number itself.
Jefferies’ core line was brief:
"Raising estimates and PT for SNDK"
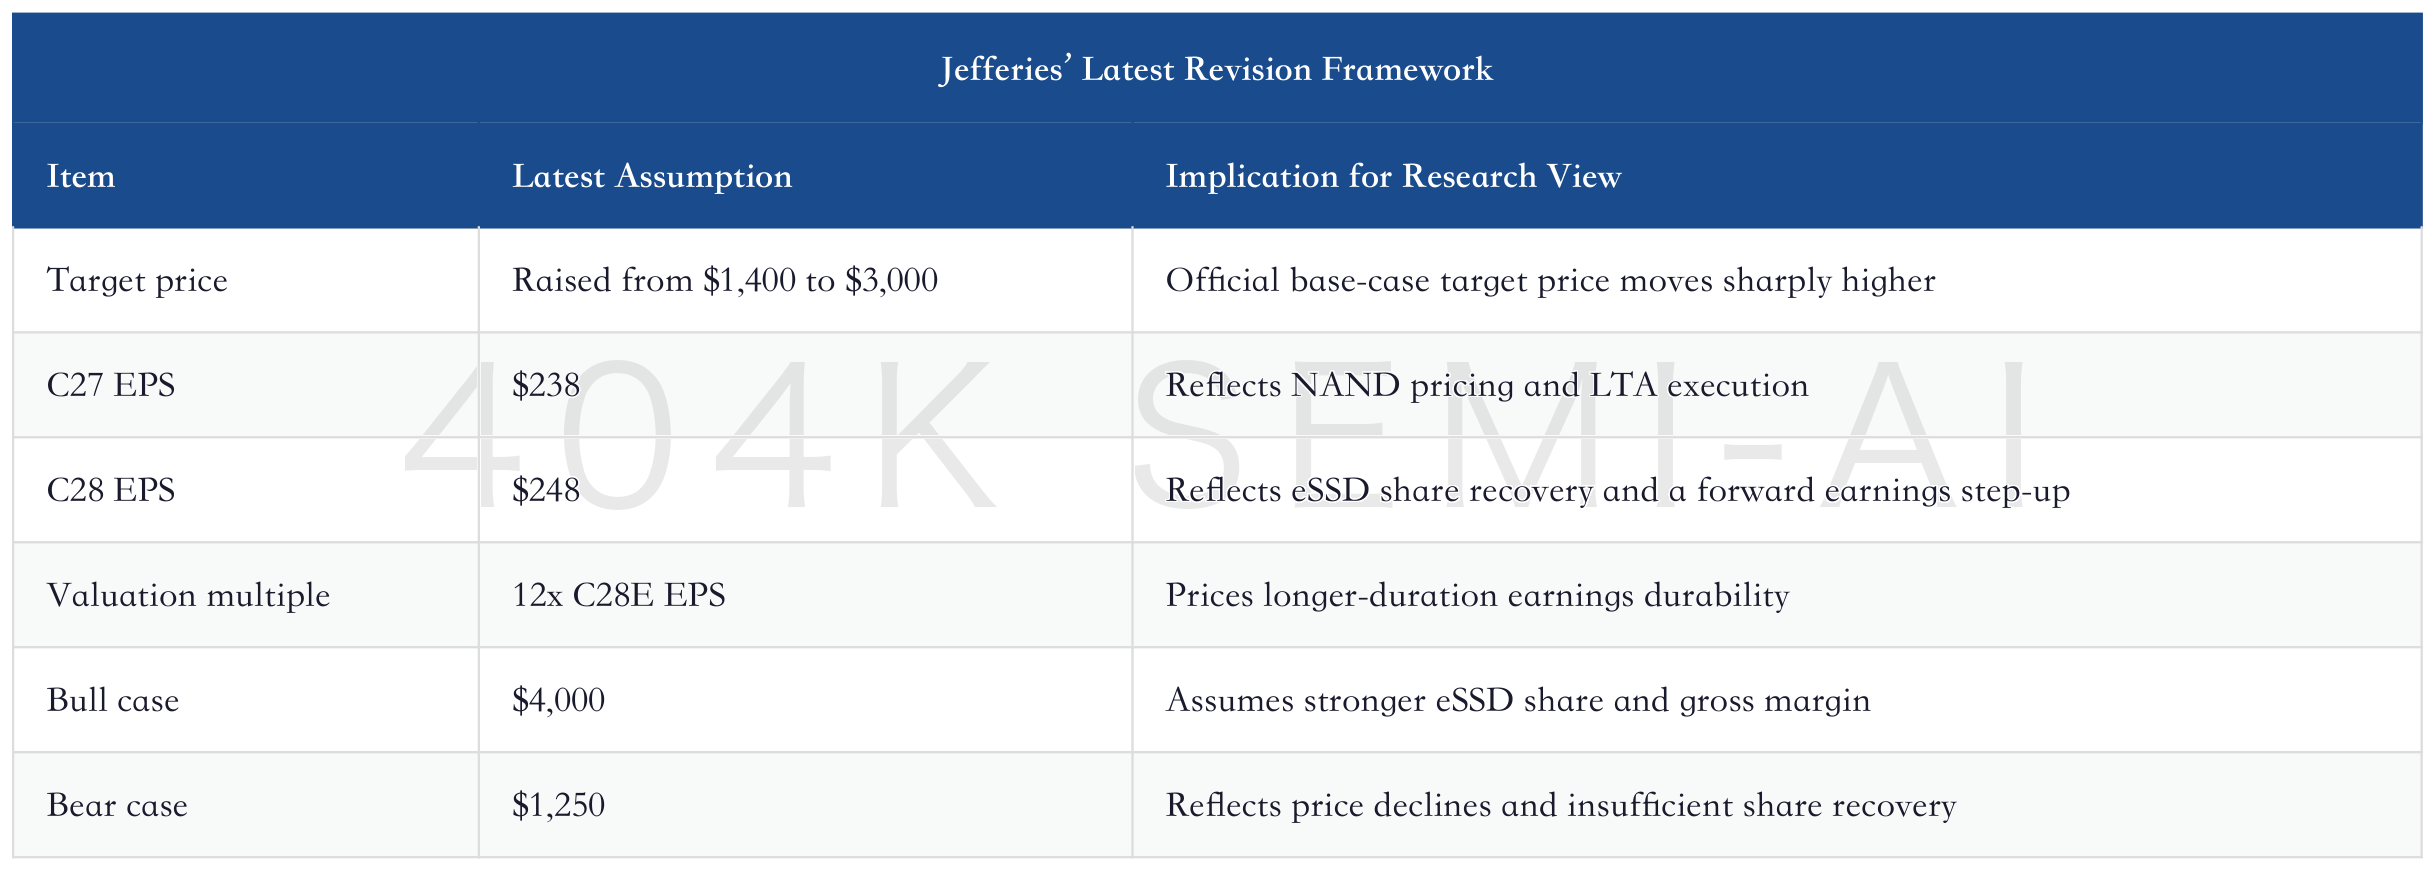
This target price comes from a set of synchronized upward revisions. Jefferies raised EPS, the target price, the valuation multiple, and scenario values at the same time. The core assumptions are shown below. In other words, $3,000 has moved from an imagined upside case of “if NAND stays euphoric” into Jefferies’ current base-case capitalization of 2028 earnings.
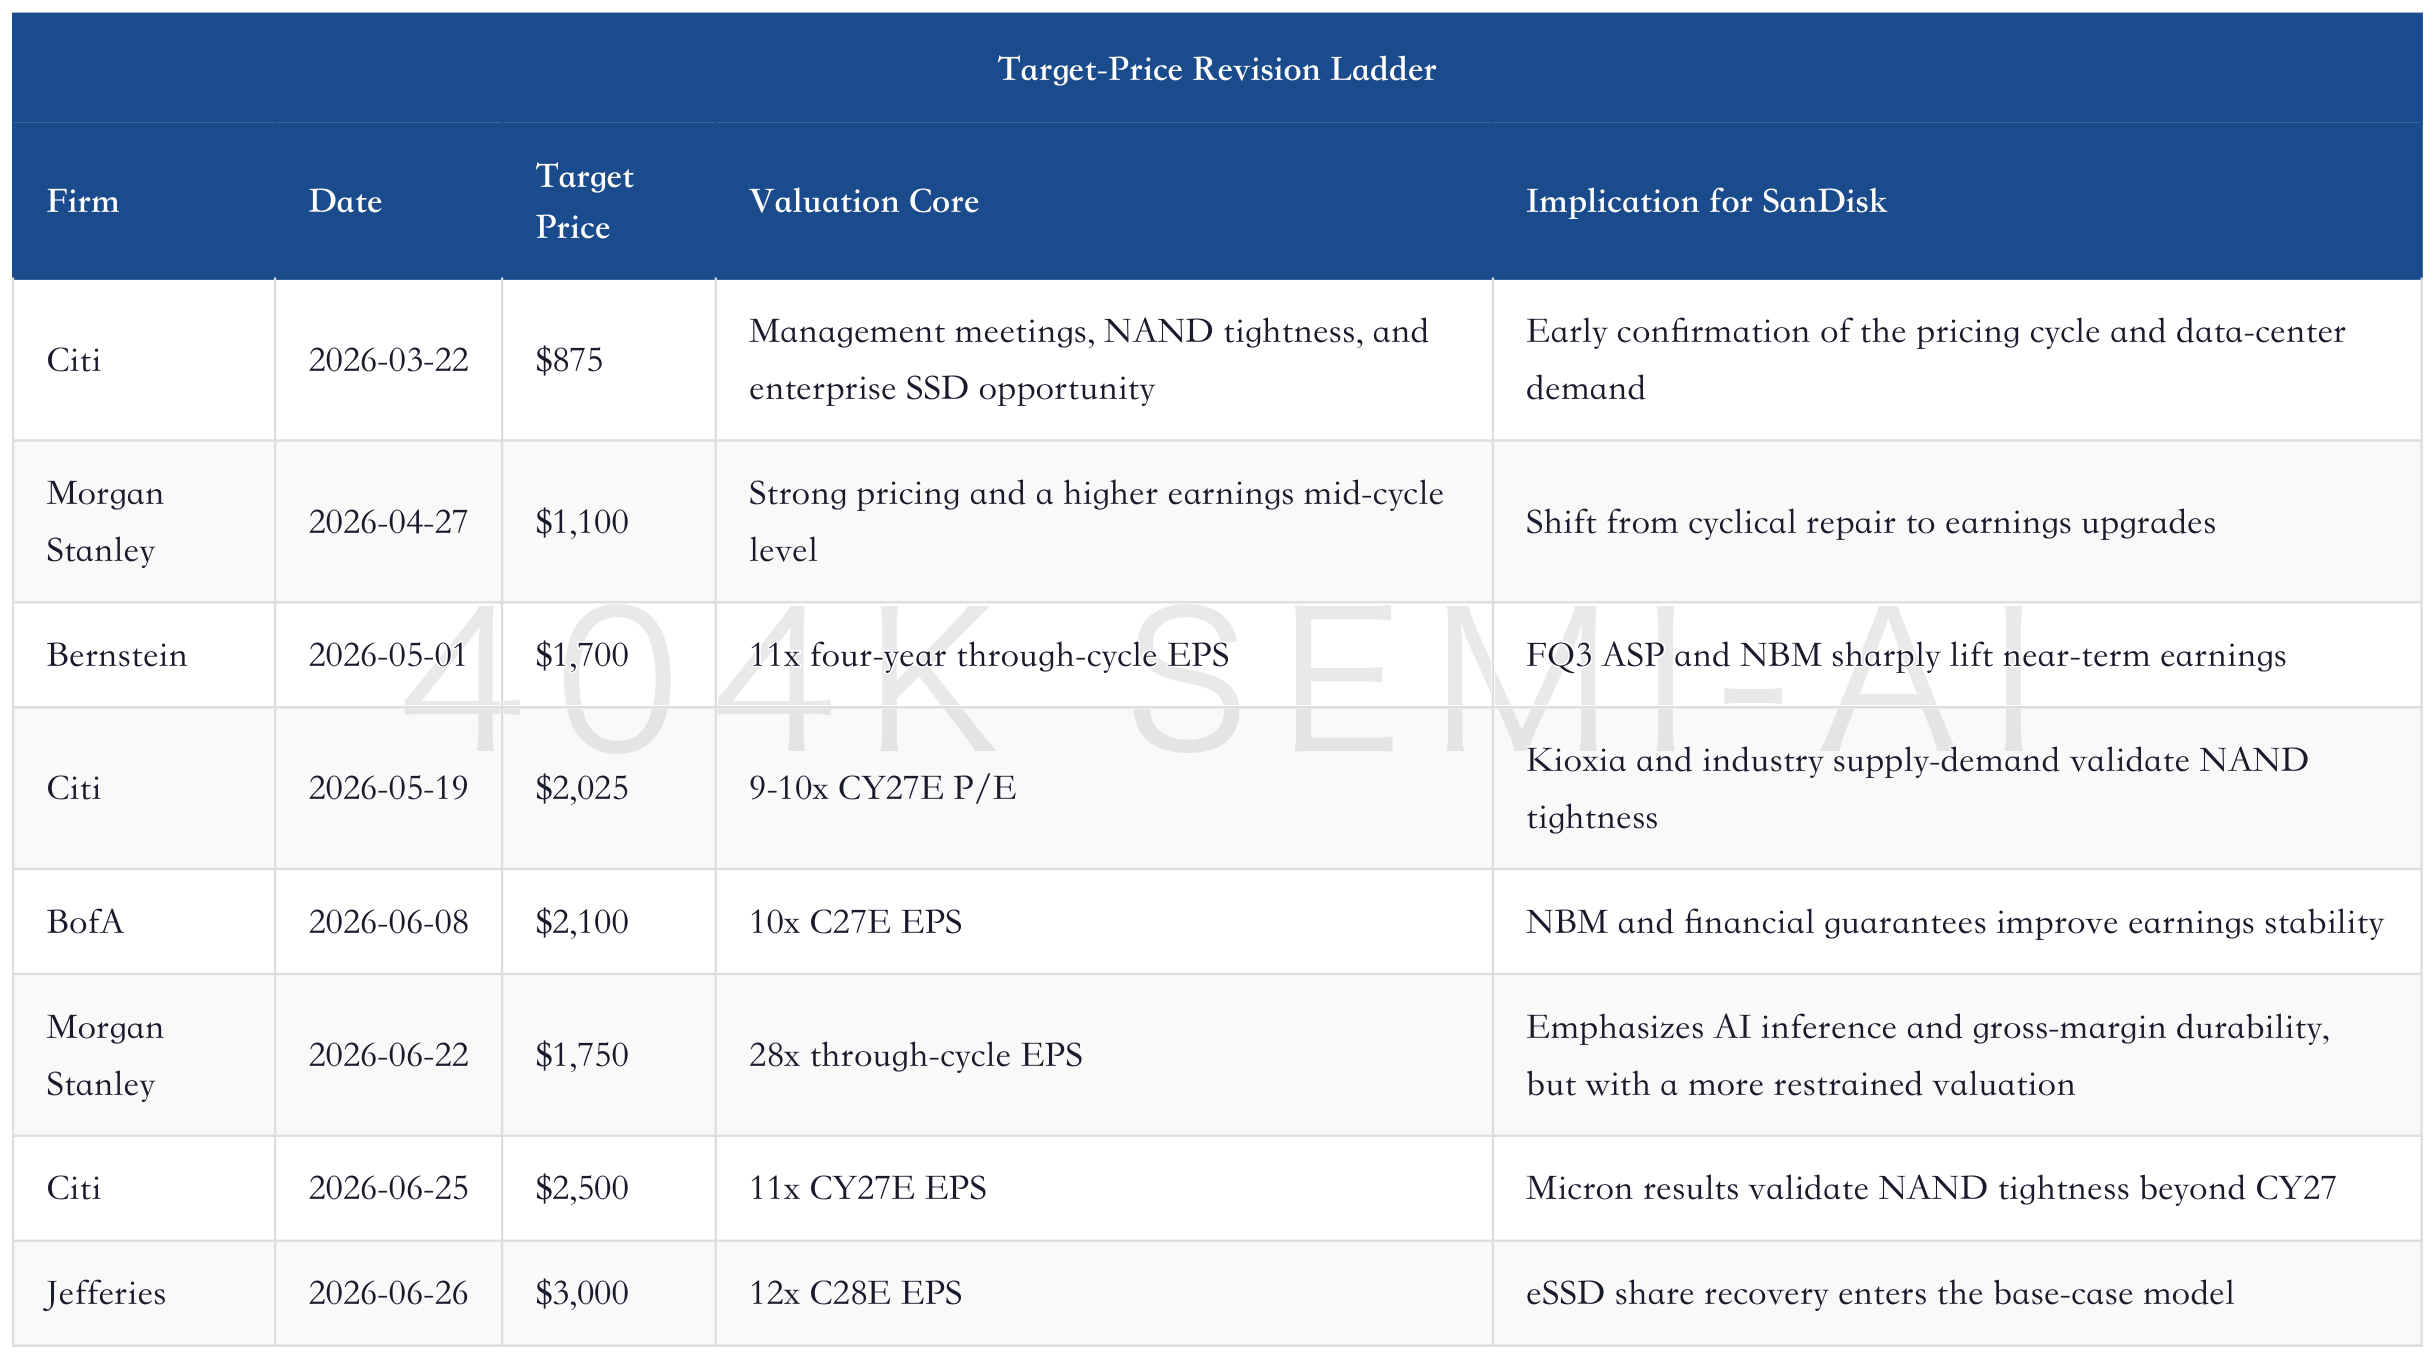
This table shows two things. First, multiple firms have continuously raised SanDisk target prices over the past three months. Second, the rationale is changing: the early phase was about NAND price increases, the middle phase about LTAs and gross margin, and the latest phase about eSSD share recovery and the 2028 earnings step-up.
This point is critical. Price increases can explain $1,700 and can also explain $2,025. To support $3,000, two harder questions must be proven: can SanDisk regain enterprise SSD share, and can NBM LTAs prevent this earnings cycle from being fully discounted as a traditional cycle?
2. SanDisk’s Core Product Is Now Entering the AI Data-Center Capacity Layer
SanDisk used to be viewed as a NAND cyclical stock: it made money when prices rose and pulled back after capacity expanded. That framework is still useful, but it is no longer enough to explain this round of target-price upgrades. AI inference is pushing NAND from a low-cost storage medium into the data-center capacity layer, with enterprise SSDs beginning to handle part of the intermediate workload where “HBM cannot fit it, DRAM is too expensive, and HDD is too slow.”
Citi’s June 25 report used a straightforward technical logic: RAG, KV cache, and long-context inference will push large volumes of intermediate results, cached results, and external-knowledge access toward high-performance SSDs. GPU HBM is the most expensive, DRAM capacity is limited, and HDD latency is too high, making eSSD the new extension layer. This gives NAND a higher-value position.
For SanDisk, the business issue is simple: the same NAND sold into low-end smartphones or PCs faces extremely price-sensitive customers; NAND sold into the AI storage layer of cloud providers is evaluated more on throughput, latency, endurance, and supply certainty. The former receives a cyclical valuation. The latter can justify a higher multiple.
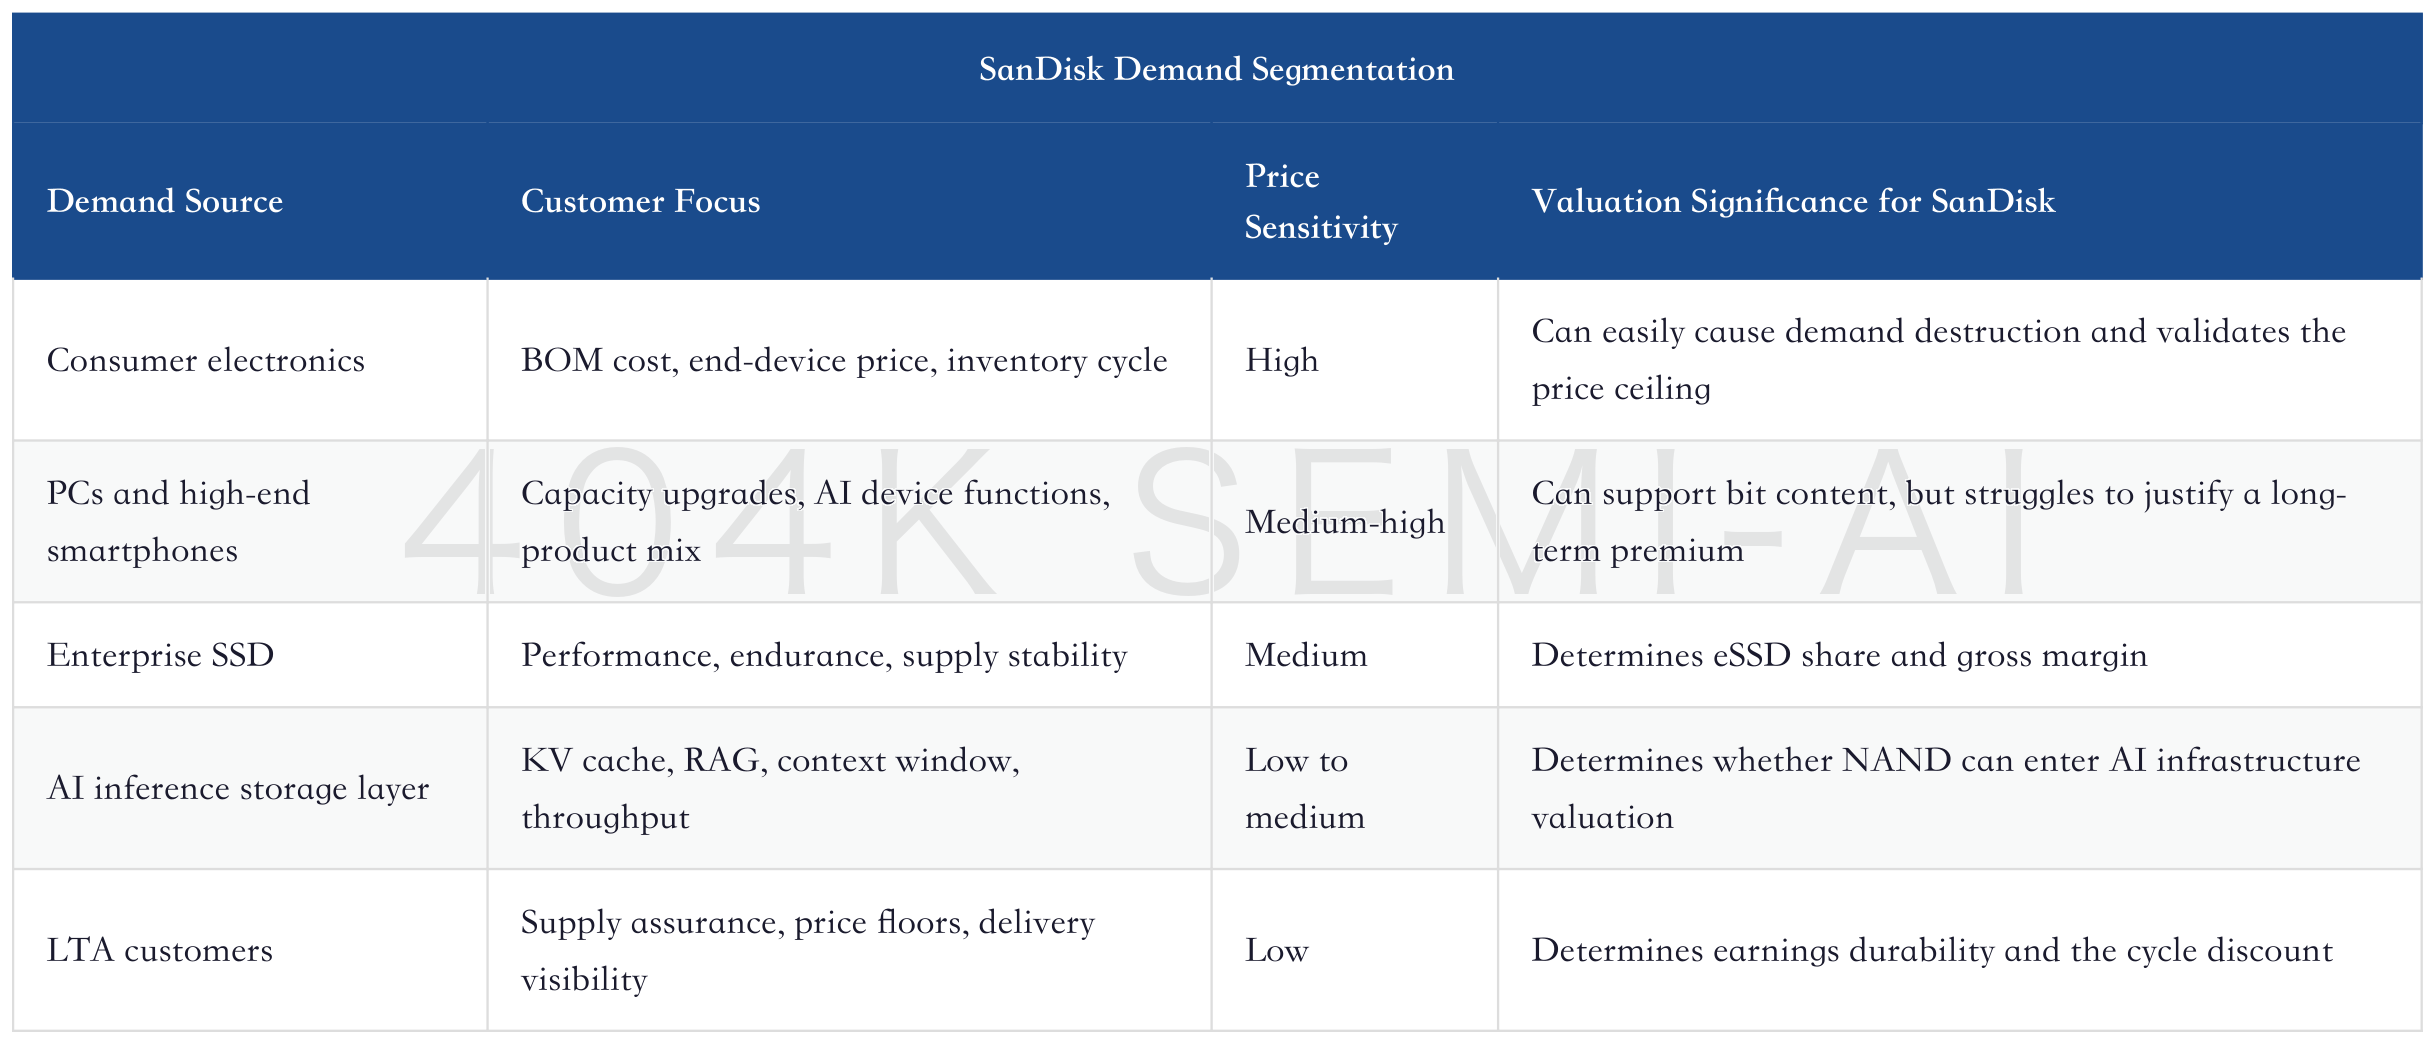
Morgan Stanley described this shift directly: AI demand is changing the nature of the NAND market, and cloud customers are less sensitive to NAND pricing than PC and smartphone customers. This explains why SanDisk’s target-price upgrades have moved faster than traditional cyclical stocks: the mix of high-value customers and high-value applications is rising.
The risk is also here. If the AI inference storage layer is merely a concept, NAND price increases will quickly run into demand destruction. If KV cache, RAG, and long-context inference truly make eSSD part of the system bottleneck, SanDisk is no longer just a “price-hike beneficiary,” but a supplier-rights asset in the AI data layer.
3. eSSD Share Recovery Is the Strongest New Evidence Behind Jefferies’ Upgrade to $3,000
The most valuable detail in Jefferies’ upgrade is TrendForce data showing SanDisk’s eSSD revenue share rising from 4% to 8% in the latest quarter. The number does not look large, but it changes how the market judges the company’s competitive position.
Historically, SanDisk’s weakness was that its enterprise SSD market share had fallen below prior levels. Jefferies notes in the report that SanDisk once held a mid- to high-teens share of the enterprise SSD market. If share has moved from 4% back to 8%, and then continues toward its historical midpoint, the income statement can be amplified by both price and share.
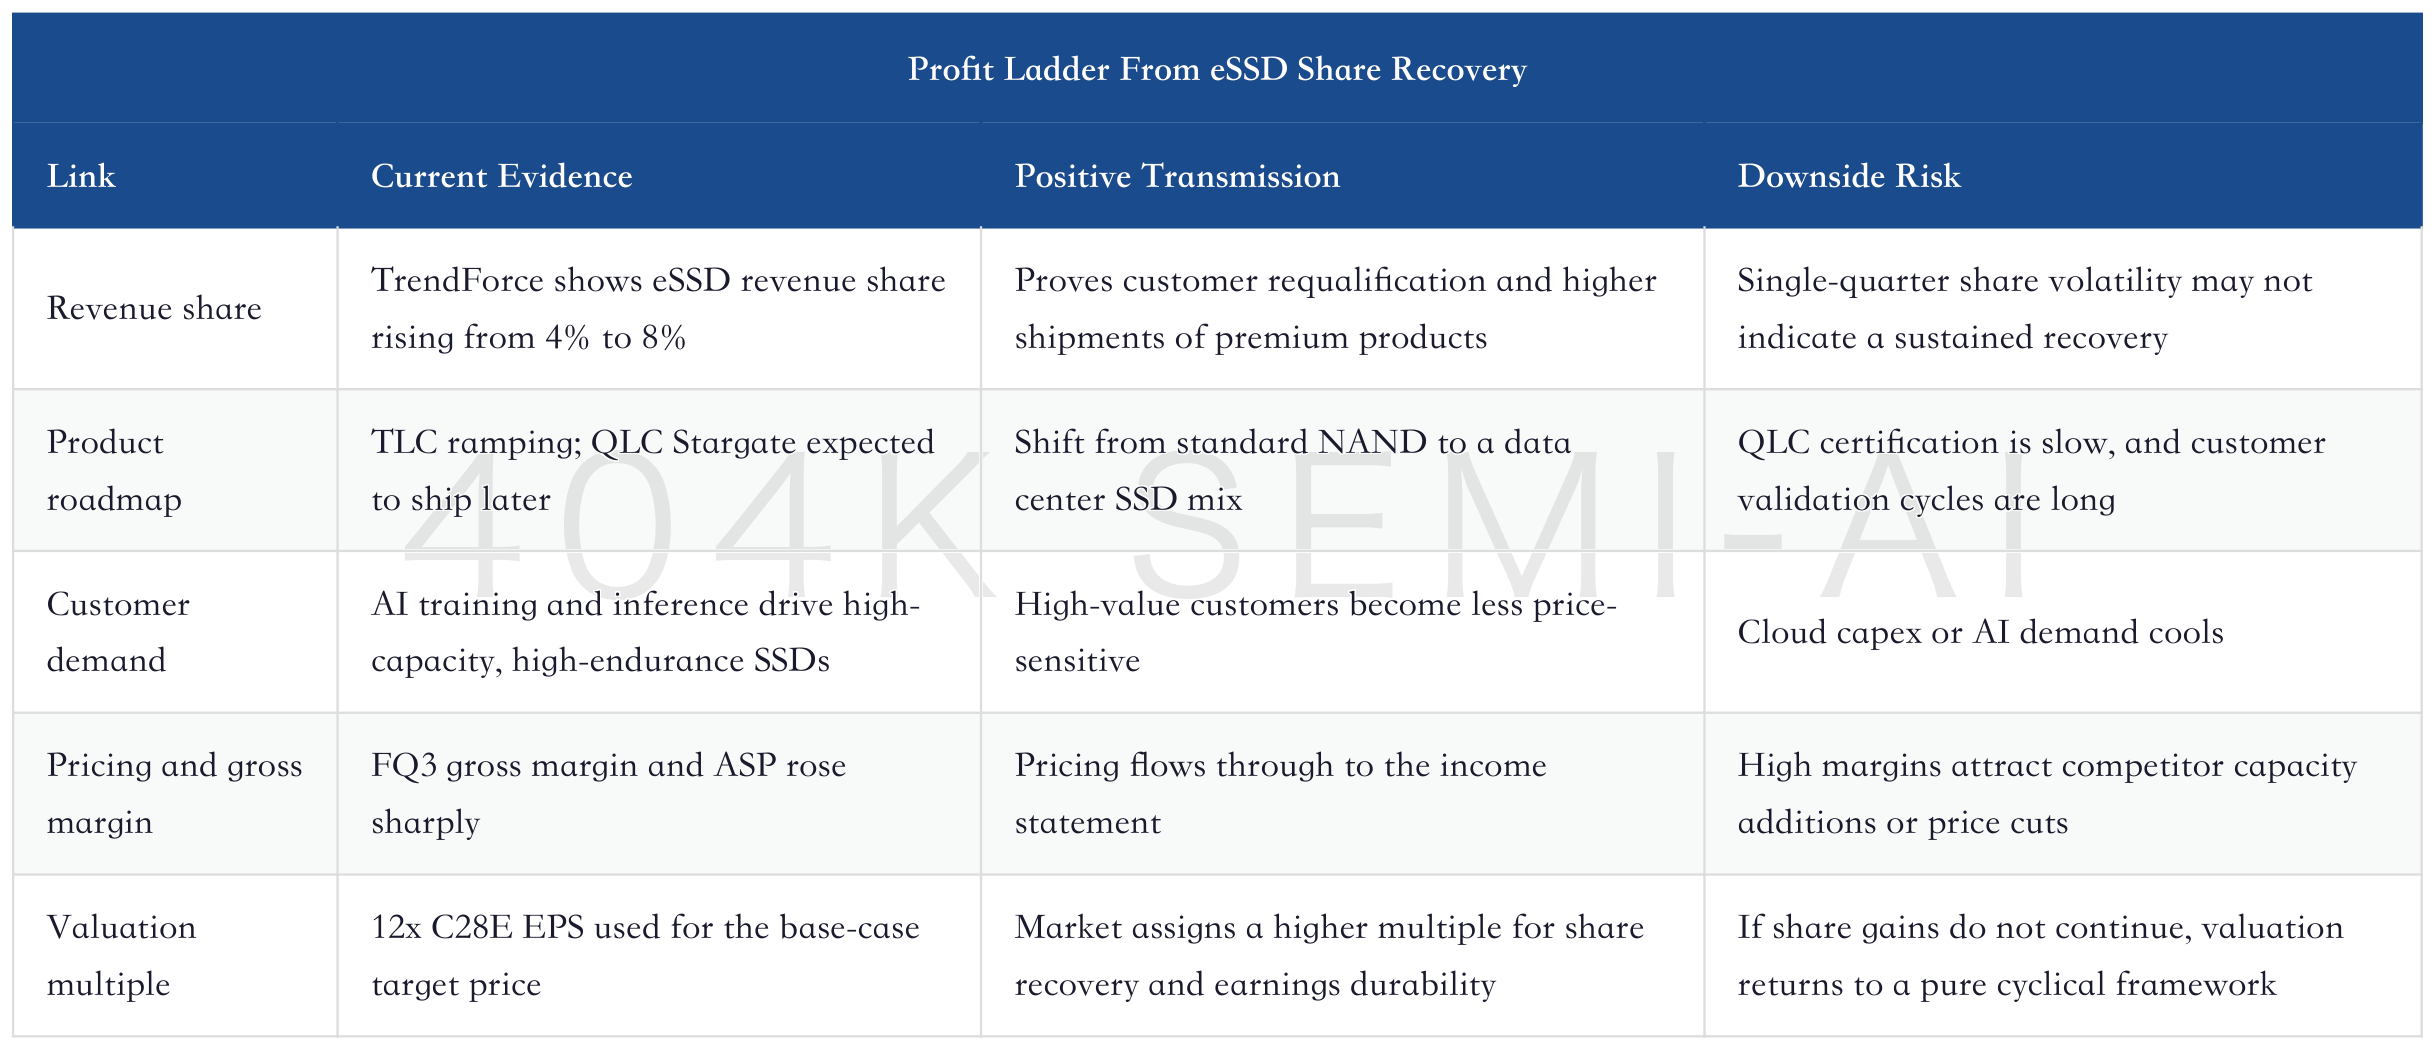
Jefferies’ model does not stop at extrapolating NAND prices. It combines eSSD business growth, share recovery, and 2028 EPS. In the report’s risk-reward page, Jefferies writes that the eSSD business has a chance to contribute more than 7% of revenue share by 2027, bringing about $2.5 billion of revenue and more than $2 of EPS contribution. That number is not large relative to total company EPS, but it amplifies the valuation narrative: it tells the market that SanDisk is entering higher-value customers, and that price and share can jointly expand the income statement.
This is the key to the $3,000 target price. Looking only at NAND prices, the target price can easily be interpreted as a cyclical peak. Adding eSSD share recovery turns it into a combination of “cyclical pricing + customer mix + long-term agreement visibility.”
4. NBMs Are the Second Main Thread: They Determine Whether Earnings Can Carry Through the Cycle
NBMs are one of the core variables in SanDisk’s current re-rating. They are stronger than ordinary long-term agreements, using fixed prices, price floors and ceilings, prepayments, financial guarantees, and default compensation to bind customer demand and SanDisk supply more deeply.
Bernstein noted in its May 1 report that SanDisk has signed five NBMs, covering more than one-third of FY27 bit demand, with the longest contract term extending to five years. BofA further noted in its June 8 report that some agreements include more than $11 billion of financial guarantees and prepayment arrangements. Morgan Stanley’s NDR report also emphasized that management believes the price floors under NBMs still correspond to gross margins close to current high levels.
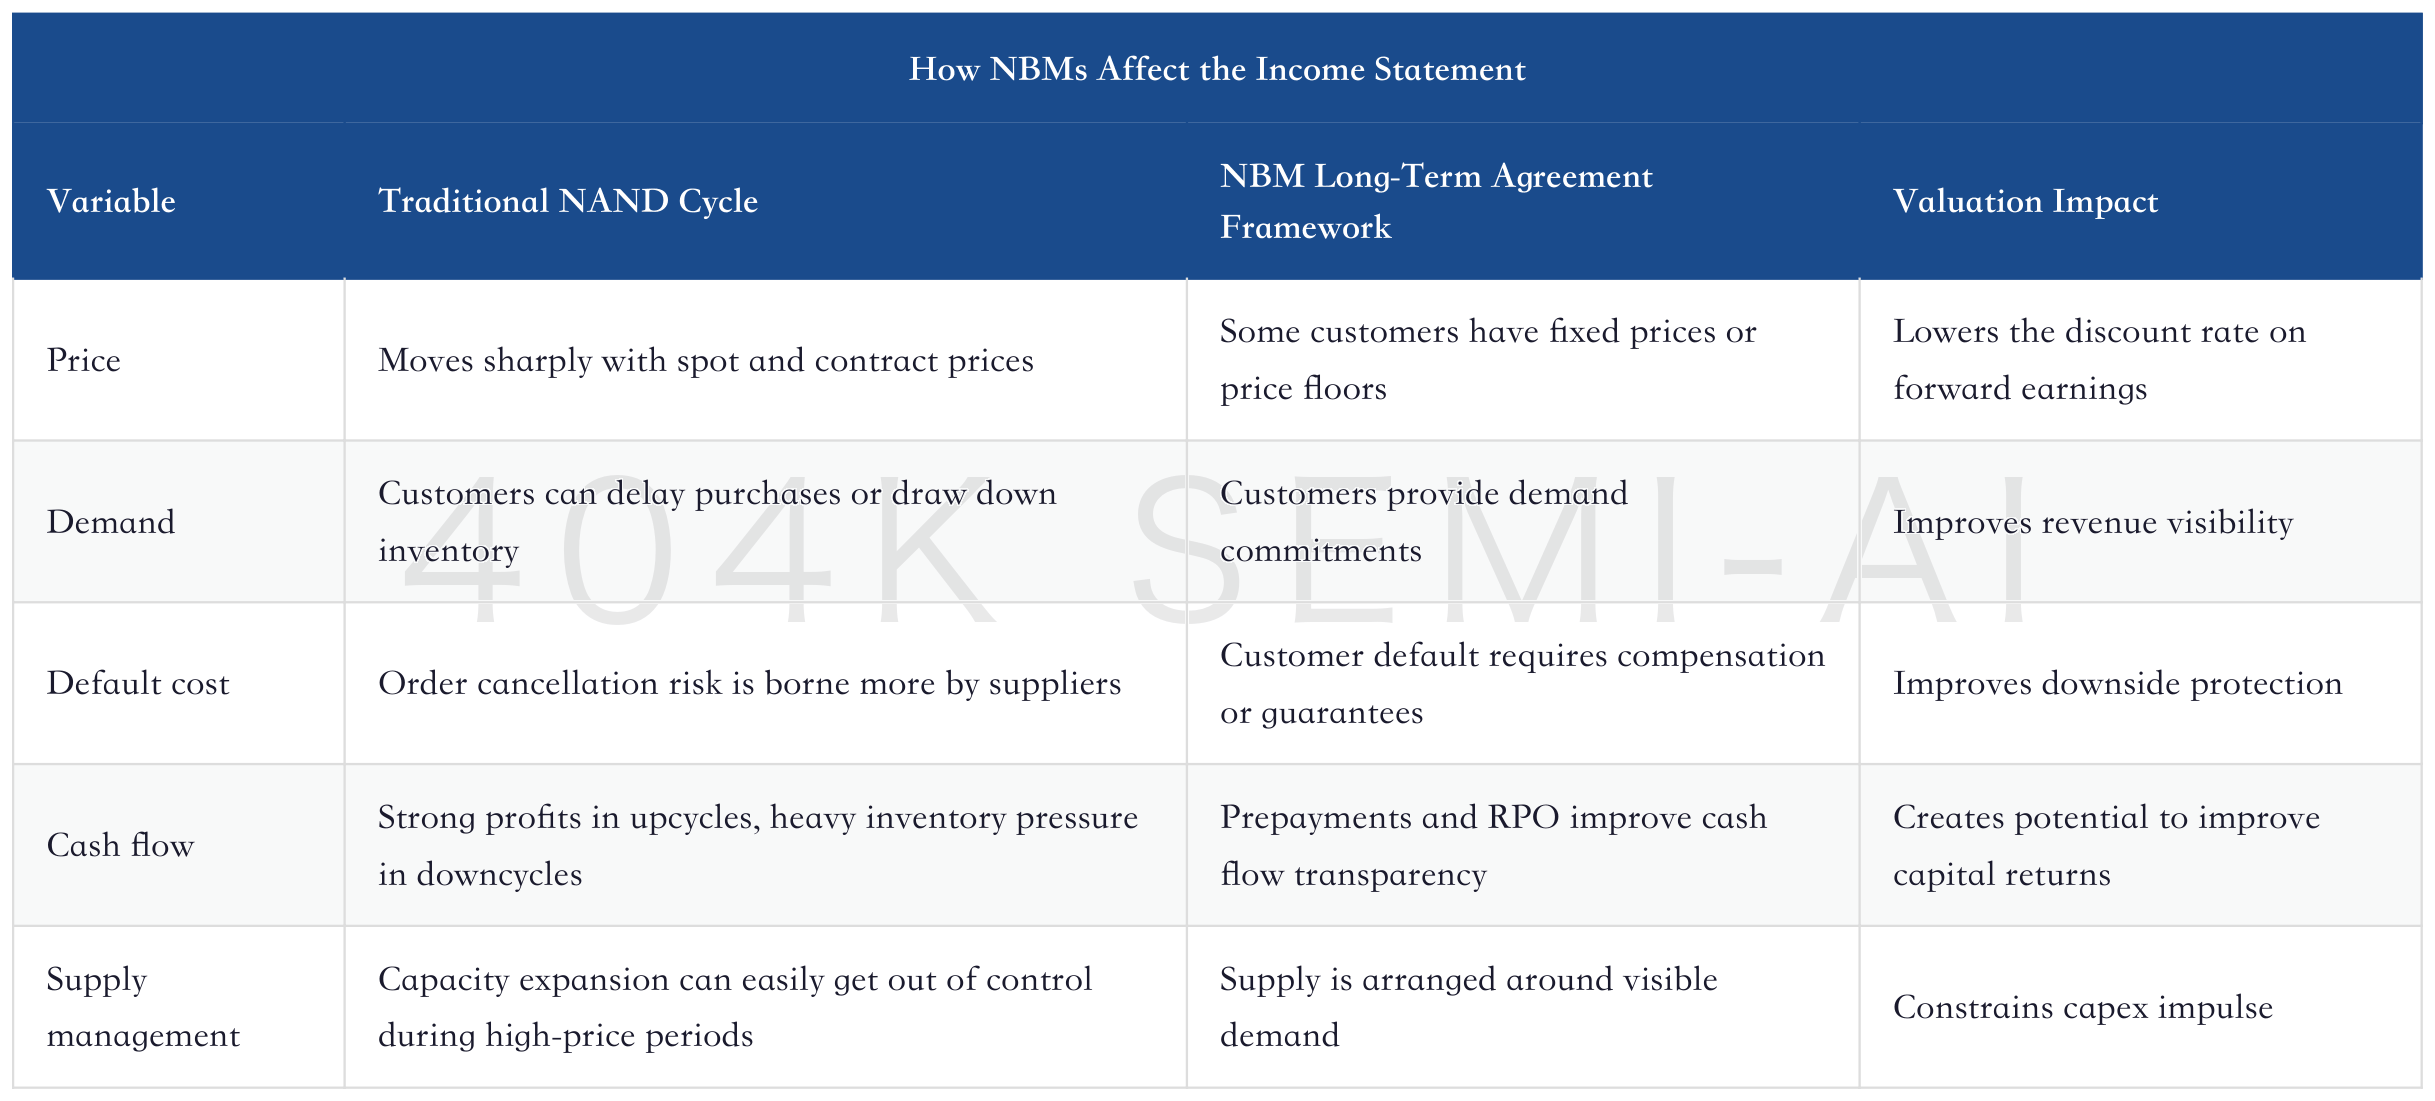
Why does this mechanism matter? Because the long-standing valuation discount on memory stocks comes from an old problem: peak earnings look very high, but investors do not believe they can last. NBMs try to answer that question. They do not guarantee NAND prices will stay high forever, but they can lock part of future profits into contracts and turn the cycle trough from “industry-wide dumping” into a combination of “customer default, supplier production cuts, and cash compensation.”
BofA therefore raised its SanDisk target price from $1,550 to $2,100, based on significant upward revisions to 2027 revenue and EPS, while NBMs make earnings more stable. BofA uses roughly 10x C27E EPS, below Jefferies’ 12x C28E EPS, but the direction is consistent: multiple firms are starting to assign a higher valuation to NBM visibility.
5. Official FQ3 Data Has Already Validated “Pricing Elasticity”
SanDisk’s FQ3 results gave the market a hard validation. Pricing, gross margin, EPS, and data center revenue all beat expectations, with the specific figures summarized in the table below. More importantly, data center has moved from a conceptual variable to an income-statement variable.
These numbers show two facts. First, price increases have genuinely flowed through to the income statement. Second, data center is becoming the core driver of revenue and gross margin. The company also guided FQ4 revenue, gross margin, and EPS to remain elevated, implying high gross margins are not set to immediately fall back in the near term.
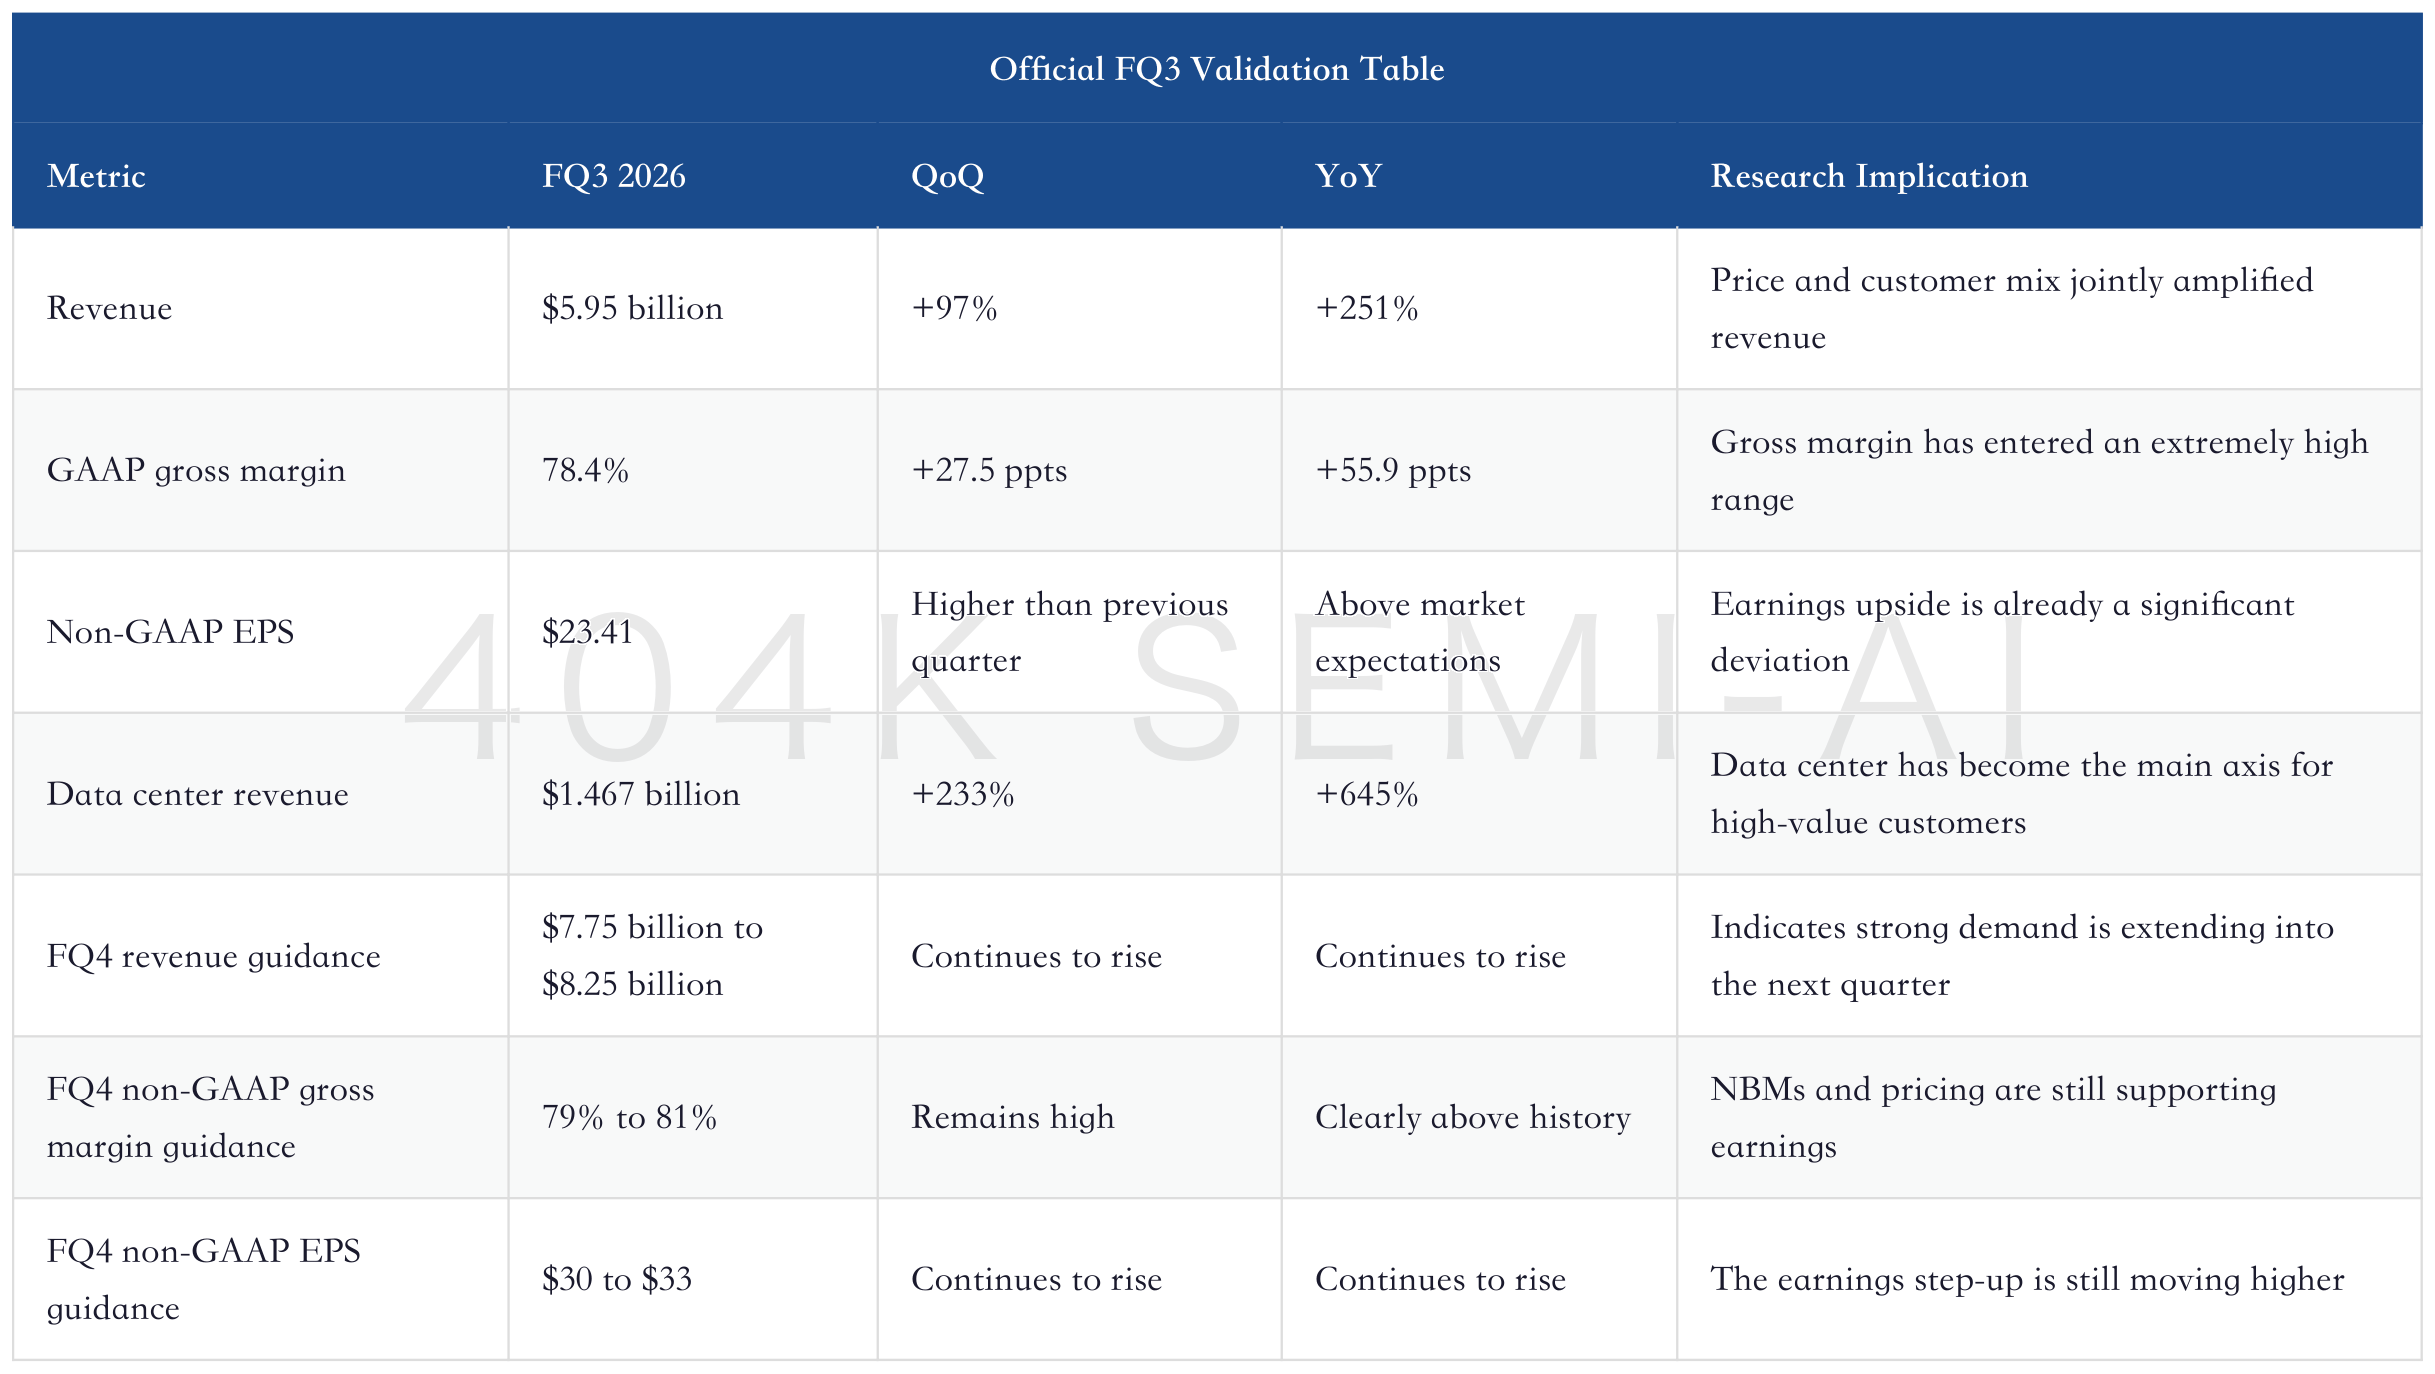
Bernstein’s interpretation of this data set is direct: FQ3 ASP rose 140% QoQ, far above its prior blue-sky scenario; the slower ASP growth in FQ4 guidance may instead reflect NBM prices being locked in ahead of time and conservative management assumptions. This explanation matters because it converts the risk of “a single quarter rising too fast” into the possibility of “long-term agreements locking in profits.”
Of course, a 78% to 80% gross margin is hard to treat lightly as a permanent midpoint. Morgan Stanley remains more restrained. It recognizes that AI inference and NBMs improve earnings durability, but still sets its target price at $1,750, because current gross margins are closer to shortage-driven highs and have not yet been proven as a permanent norm for the NAND industry.
This is also the biggest debate around SanDisk: the short-term data is already very strong, and the dispute has shifted to “how many years of these earnings can be capitalized.”
6. Divergence Across Firms: Everyone Is Bullish on NAND Tightness, but the Multiples Differ
The sell-side debate on SanDisk is now less about direction and more about valuation methodology. Citi, BofA, Morgan Stanley, Bernstein, and Jefferies all acknowledge tight NAND supply and demand, AI demand, and improving enterprise SSD momentum, but they handle the earnings midpoint, peak duration, and valuation multiple differently.
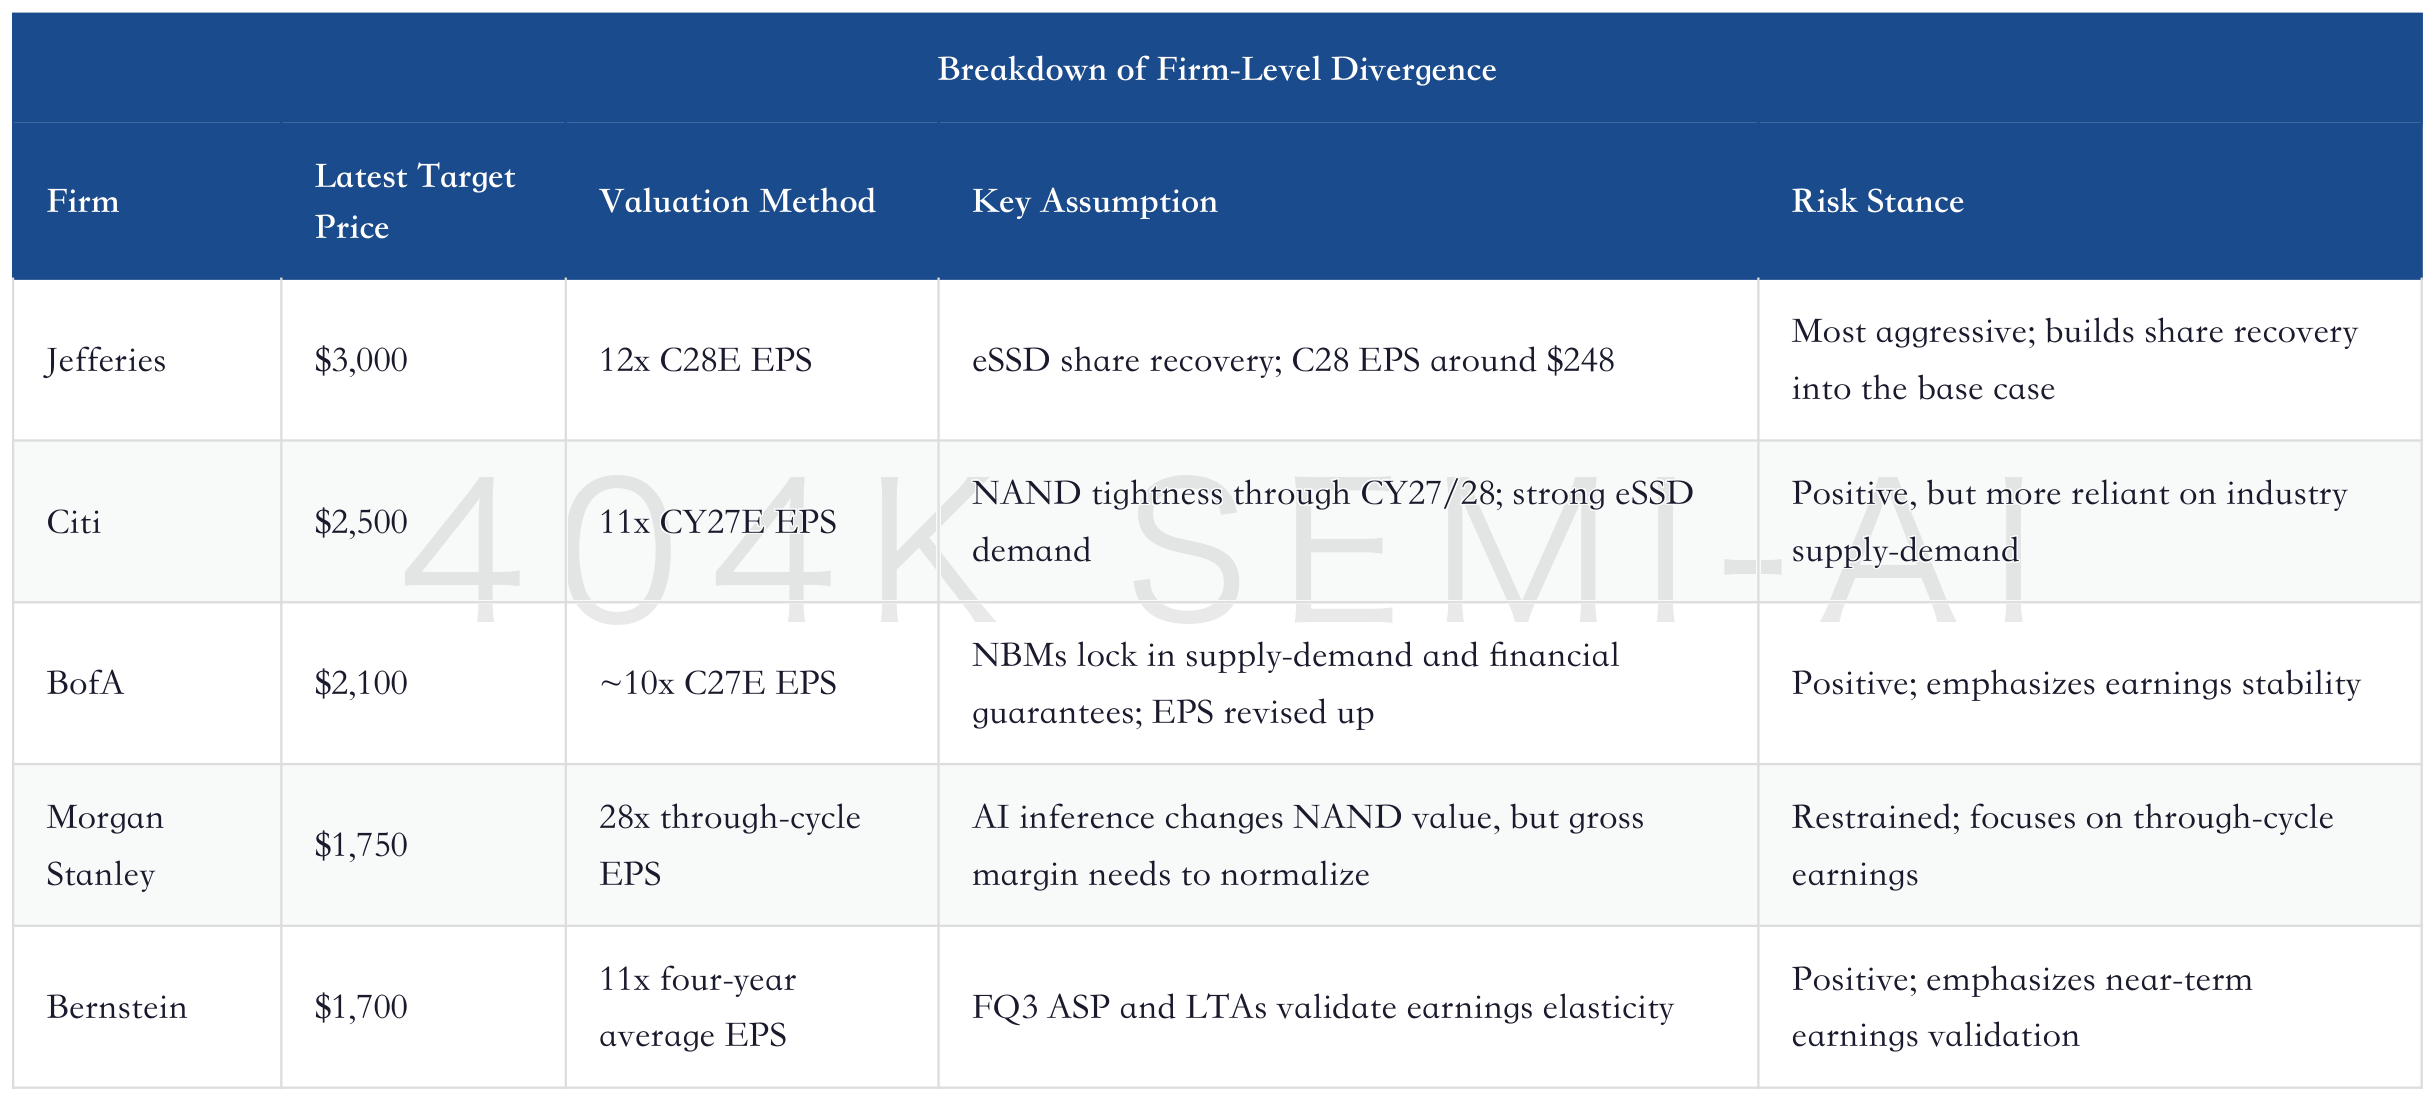
Jefferies’ difference is that it is more willing to use 2028 EPS. Citi uses CY27 EPS, BofA uses C27 EPS, Morgan Stanley uses through-cycle EPS, and Bernstein uses four-year average EPS. The further out the year, the more one needs to believe this earnings cycle can last for years; the stronger the through-cycle framework, the more one needs to haircut high gross margins. The target-price spread is essentially a trade-off between these two issues.
This has practical meaning for readers. $3,000 represents the outcome after the most aggressive firm capitalizes eSSD share recovery, AI inference demand, and NBM long-term agreements all at once. If subsequent data only validates price increases, the $1,700 to $2,500 framework is steadier; if share and long-term agreements are validated together, $3,000 gains stronger explanatory power.
7. NAND Industry Supply Discipline Is SanDisk’s External Moat for High Gross Margins
SanDisk cannot determine the entire NAND cycle by itself. The company can lock in customers, raise prices, and build eSSDs, but what really determines how long high gross margins can last is industry supply discipline. This requires watching Kioxia, Samsung, SK Hynix, Micron, and Chinese vendors.
Goldman Sachs made a key point in its Kioxia IR Day report: on a capacity basis, the NAND market is expected to grow at a CAGR of roughly 22% from CY25 to CY28, while data-center-related NAND demand is expected to grow at a CAGR of roughly 46%; supply-demand tightness should persist at least until 2H27. Kioxia management also emphasized that capex will be centered on BiCS 8, BiCS 10, and existing fabs, with disciplined investment based on demand visibility.
This matters a lot for SanDisk. SanDisk and Kioxia have a long-term manufacturing partnership. If Kioxia maintains capex discipline, SanDisk’s supply and pricing environment will be more stable. If Kioxia or other NAND vendors resume aggressive capacity expansion, SanDisk’s profit leverage outside NBM would come under pressure first.
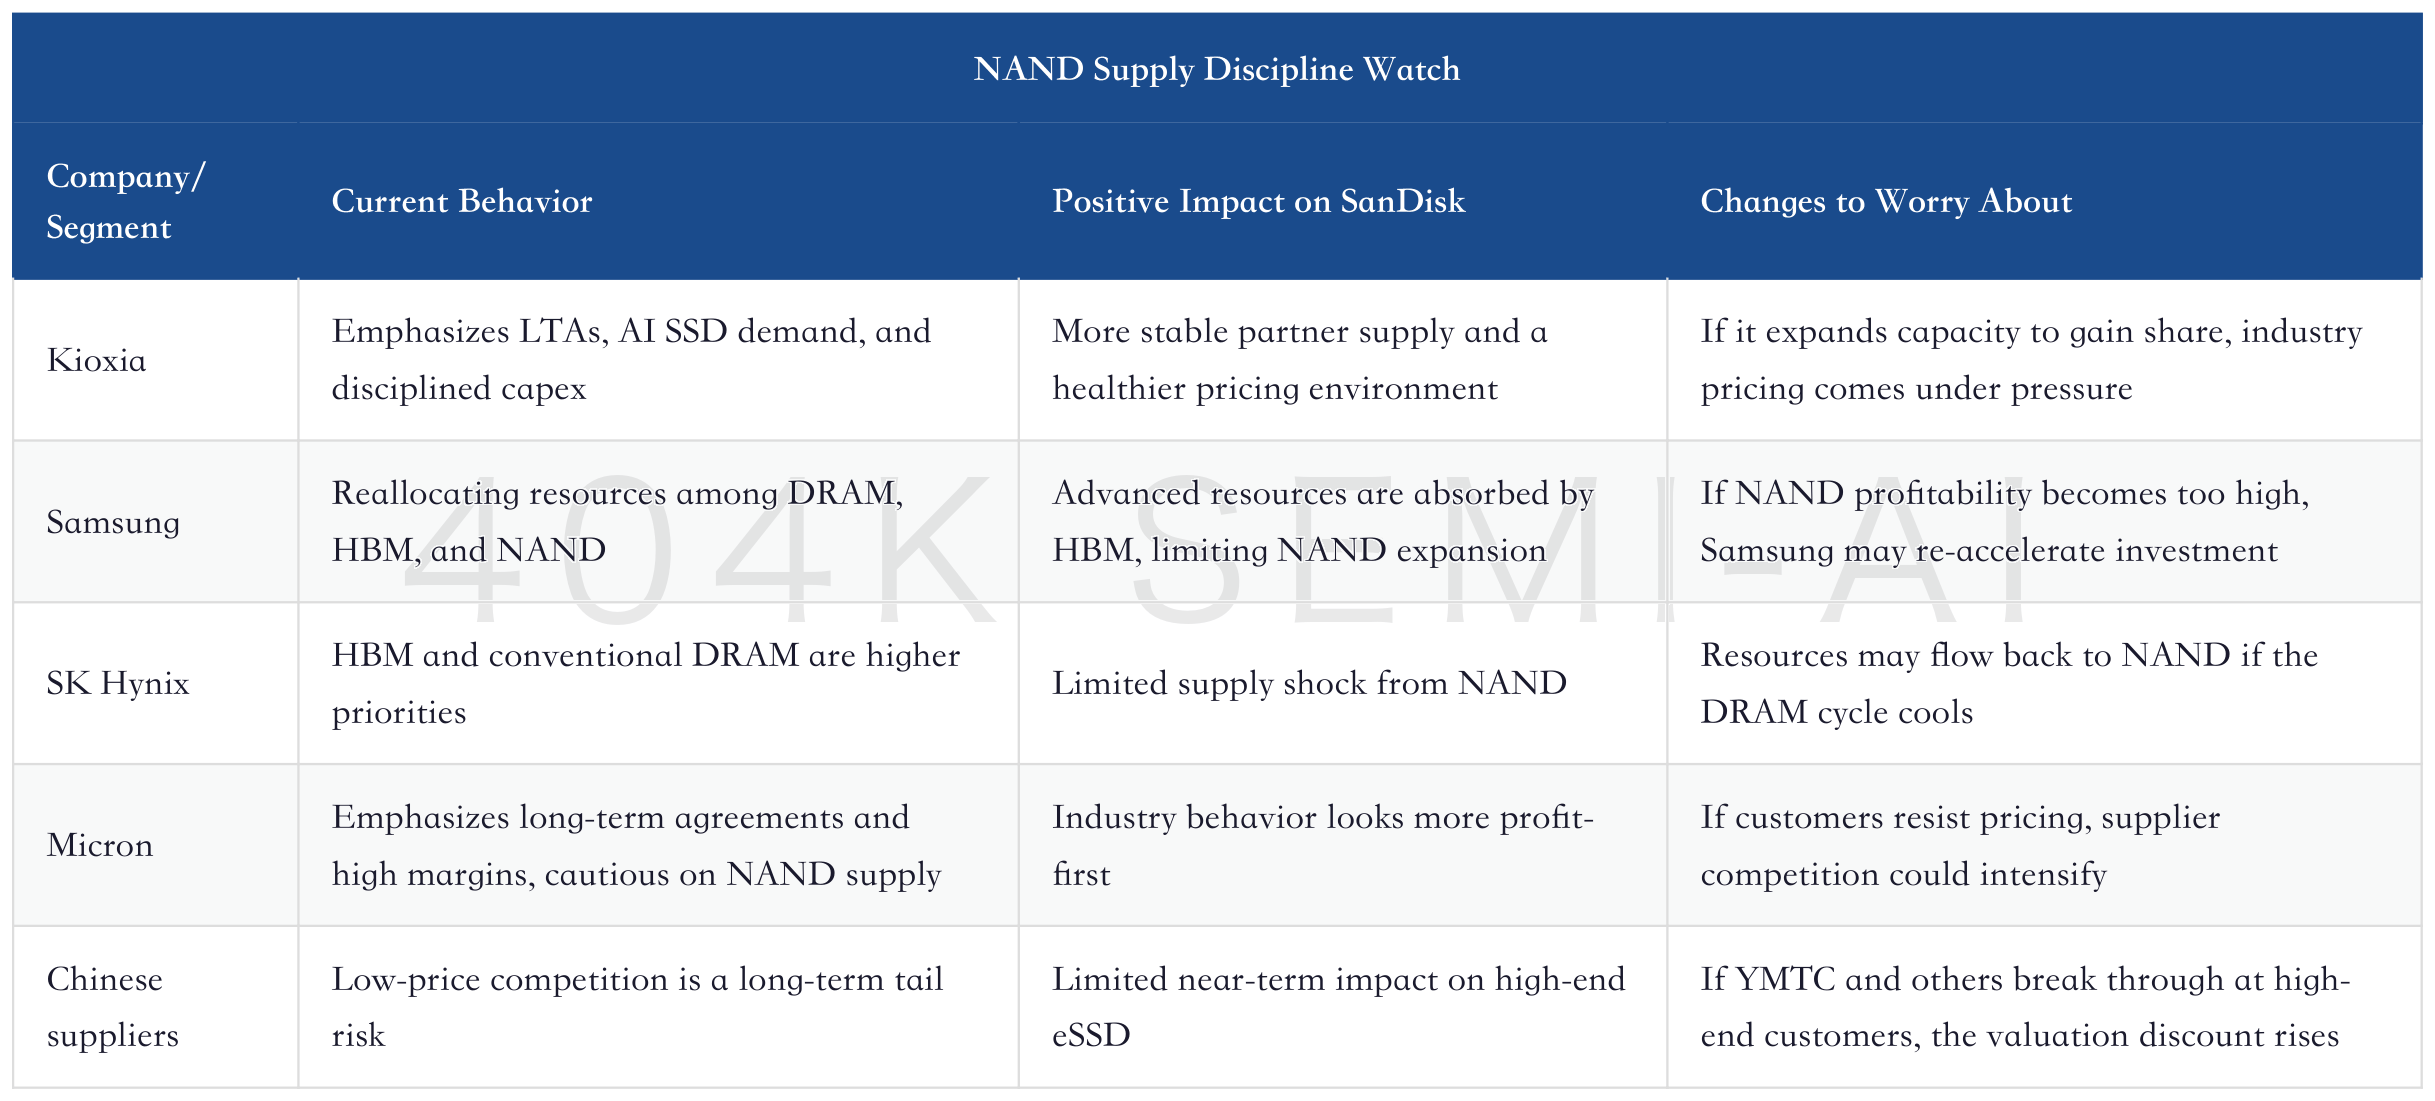
Supply discipline determines the valuation ceiling. If the industry treats this round of high gross margins as a signal to expand capacity, SanDisk will revert to a typical NAND cycle. If the industry treats AI SSDs and LTAs as a new demand layer, and ties capex to customer commitments, SanDisk’s profit center has a chance to sit above history.
8. Consumer Electronics Price Increases Are a Double-Edged Sword: They Prove Cost Pressure and Expose Demand Destruction
There is another easily overlooked clue in the Jefferies report: both Apple and Microsoft are raising prices on some consumer electronics products. Microsoft also noted that memory prices have risen by more than 2.5x and are expected to double again by fall 2027. This shows that storage pricing has moved from an internal supply-chain issue to an end-product pricing issue.
This has two implications for SanDisk. First, the price increases are real and already large enough to push end brands to raise prices. Second, price increases are also starting to test the tolerance of non-AI end demand. PCs, smartphones, game consoles, and traditional servers have limited ability to absorb NAND price increases. Once customers cut capacity, delay procurement, or reduce configurations, SanDisk will need to redirect more supply to data center customers.
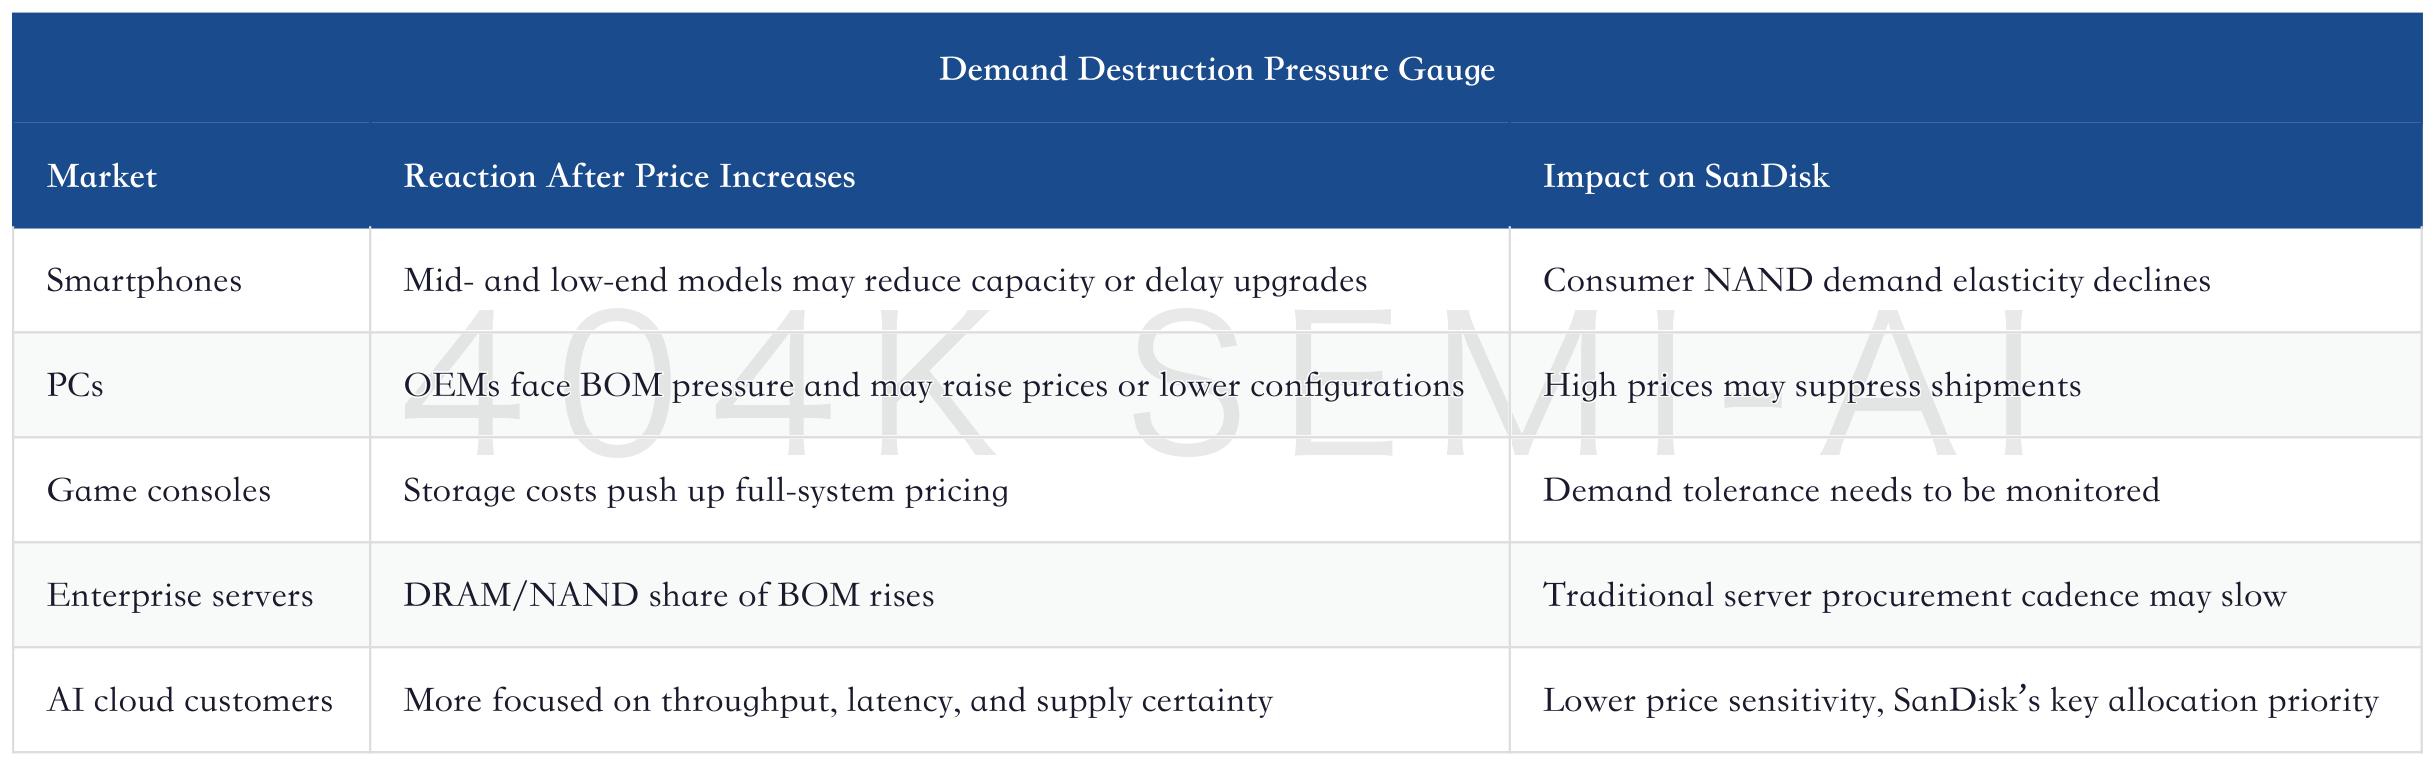
This is why eSSD share and data center revenue matter more than total revenue. Total revenue can be lifted by price increases; data center mix and enterprise SSD share are what prove SanDisk is selling high-priced supply to customers that can better absorb it.
If consumer electronics demand clearly cools over the next two quarters while data center revenue continues to grow rapidly, SanDisk can still defend high gross margins. If consumer weakness is compounded by data center customers also cutting orders, the $3,000 target price would first lose the expansion assumptions beyond eSSD and NBM.
9. SanDisk’s Asset Profile Is Changing: From NAND Price Leverage to Supply Rights and Contracted Cash Flow
The most important thing to write about SanDisk today is the change in its asset profile. In the past, it looked like a high-beta play on NAND price increases. Now the market is starting to debate whether it can become a combined asset of “AI data center NAND supply rights + NBM contracted cash flow.”
This change has three layers. The first is product attributes: NAND is moving from a consumer electronics capacity component into the AI inference storage layer. The second is customer attributes: cloud providers and data center customers are rising as a share of the mix, reducing price sensitivity. The third is contract attributes: NBM writes part of future demand, price floors, and default compensation into agreements, improving profit visibility.
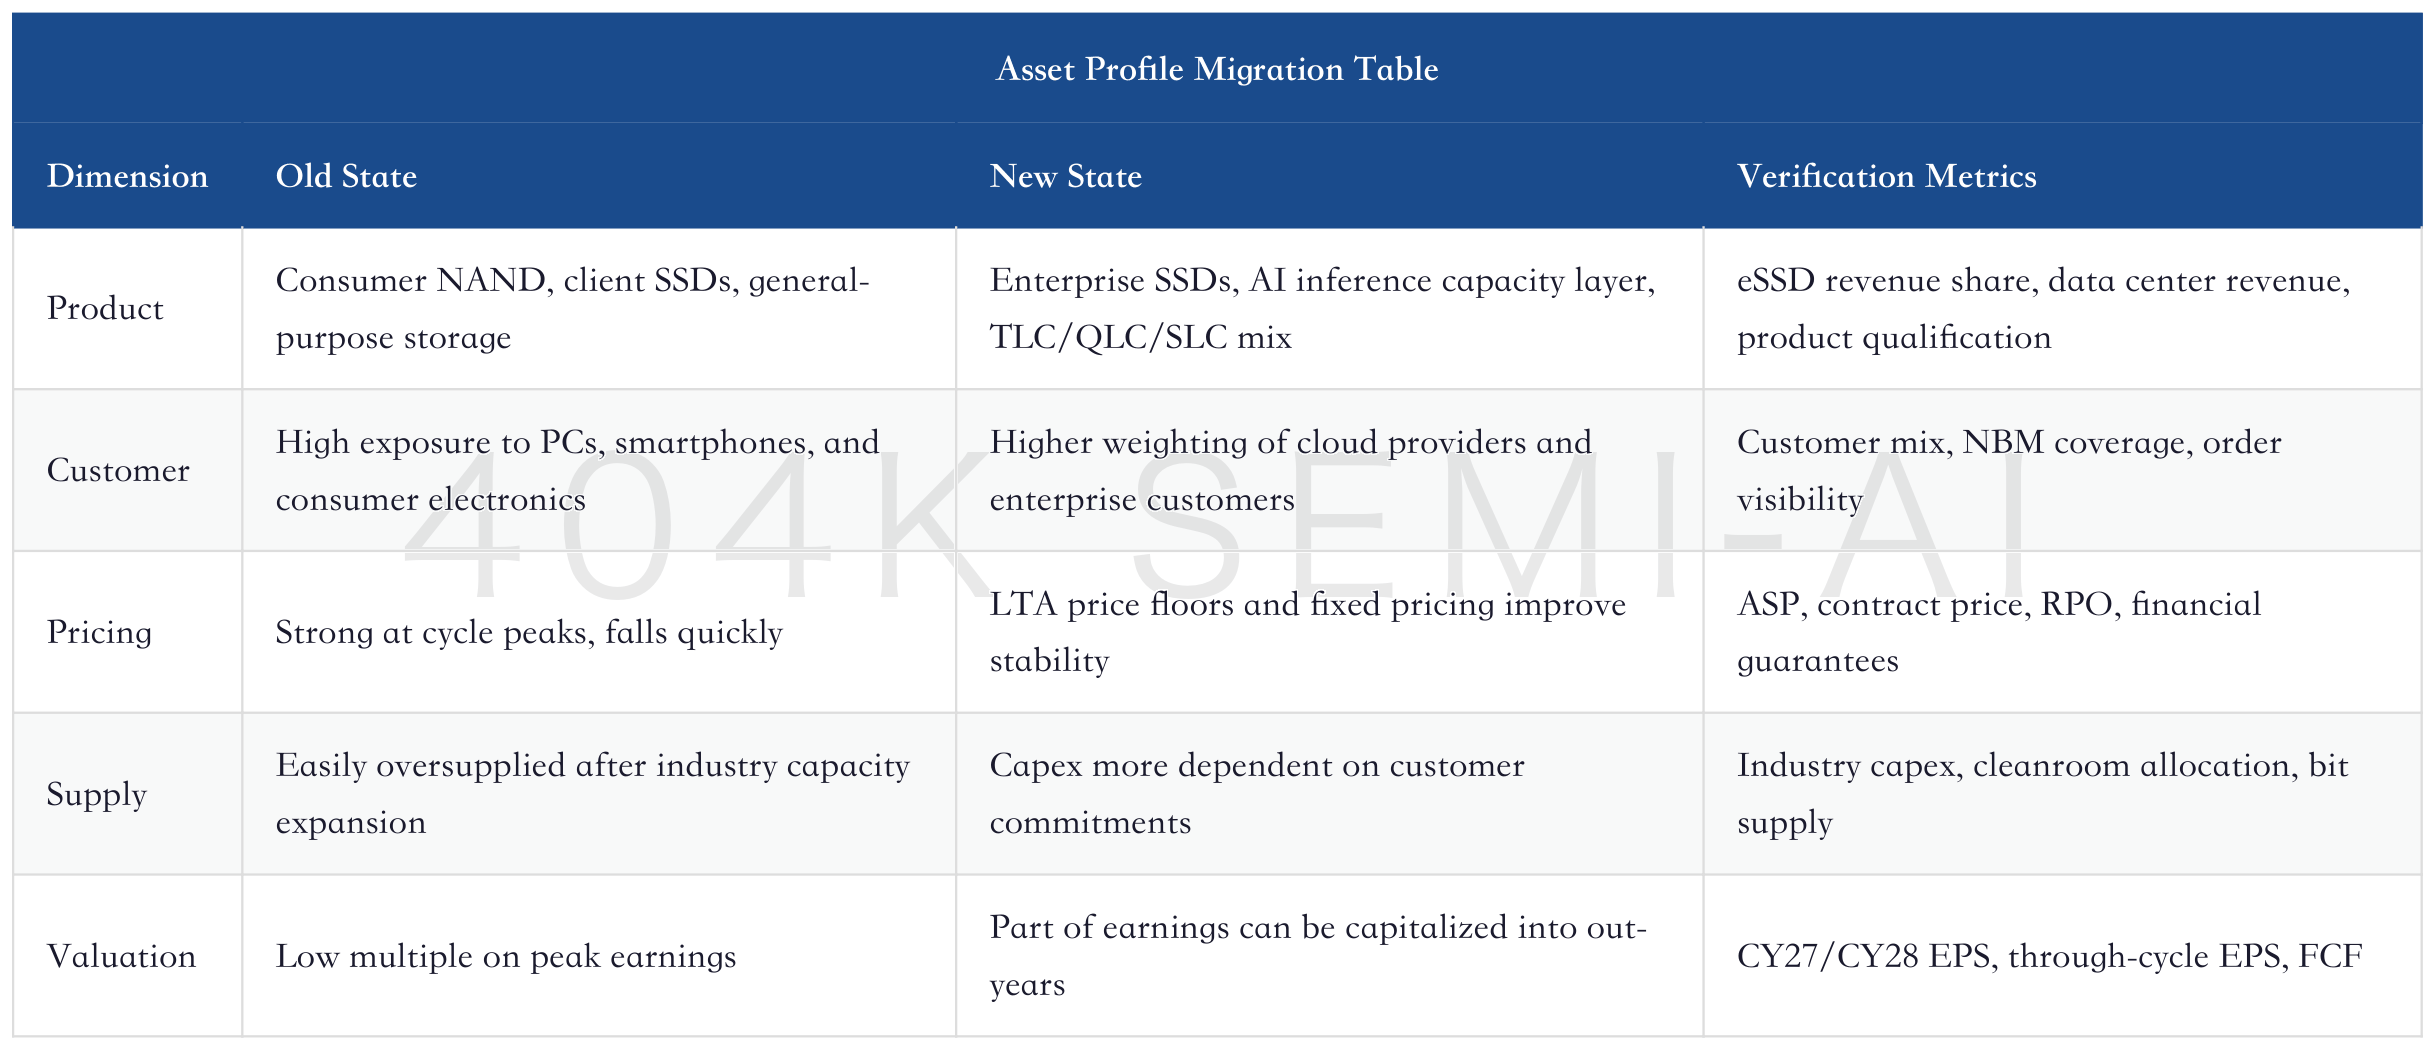
This table also explains why target prices differ so much across institutions. A traditional cycle framework applies a large discount to high profitability. A supply-rights and contracted-cash-flow framework assigns higher credibility to out-year EPS. Jefferies is in the latter camp, Morgan Stanley is closer to the middle, while Citi and BofA are looking for balance between pricing and LTAs.
10. Three Worldviews: Cycle Peak, Profit Step-Up, and AI Storage Platform
SanDisk’s future trajectory can be viewed through three worldviews. The first is cycle peak, which argues that the surge in NAND pricing has already pulled forward future upside and that target price increases are merely following peak EPS. The second is profit step-up, which argues that NBM and data center customers have lifted the profit trough; the cycle still exists, but the discount declines. The third is AI storage platform, which argues that eSSD and the AI inference storage layer give SanDisk new platform-like value.
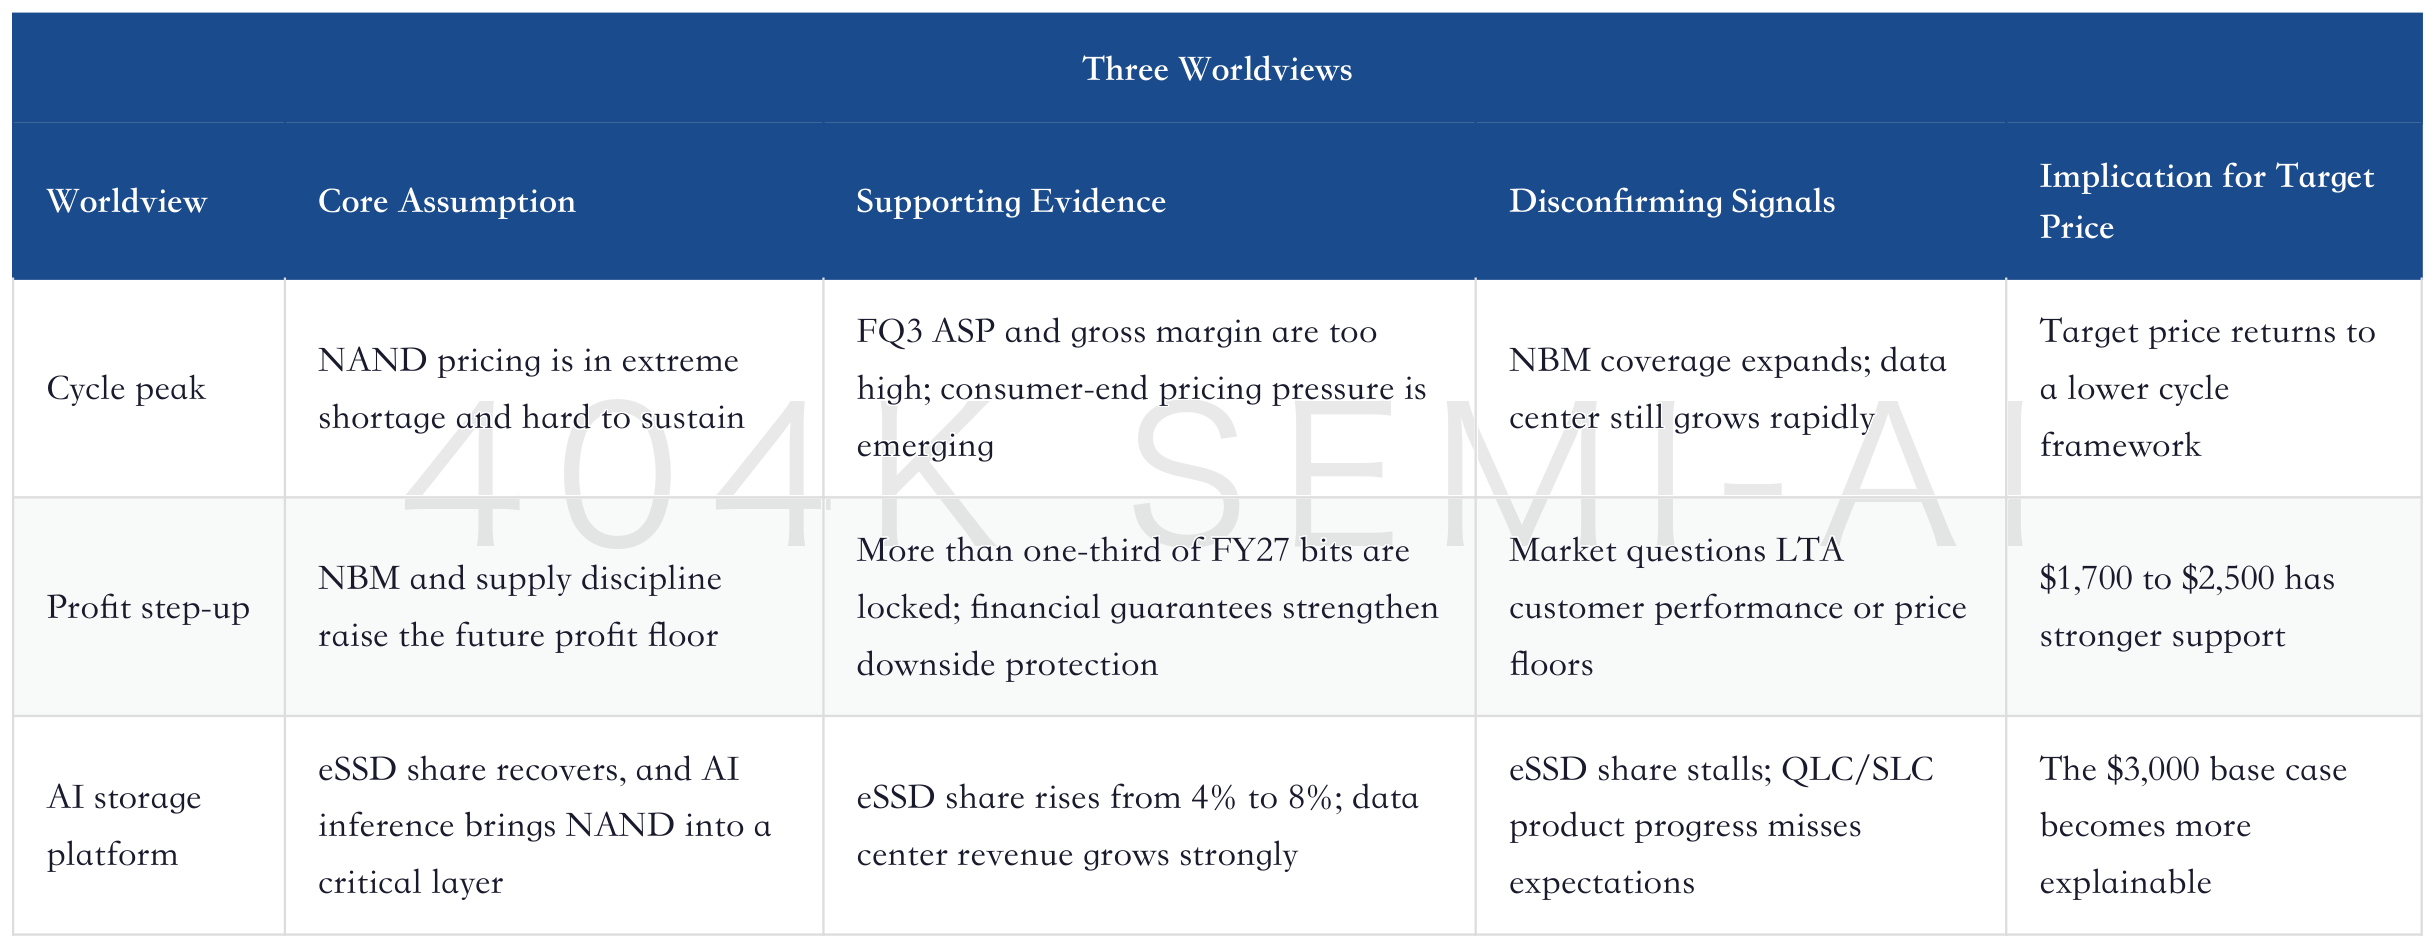
Current evidence better supports a position between the second and third worldviews. FQ3 proved that a profit step-up has already appeared, while Jefferies’ new target price is betting that the eSSD share recovery continues. What the market needs to verify next is whether SanDisk can move from the second worldview to the third.
This is also the key research judgment. As long as NBM coverage, RPO, financial guarantees, data center revenue, and eSSD share continue to rise, $3,000 will not be merely a sentiment-driven number. If these indicators stall, the market will again see $3,000 as an extrapolation of a cyclical peak.
11. Valuation Bridge: From $1,700 to $3,000, the Gap Is Four Variables
The gap between $1,700 and $3,000 is not just a difference in price targets. It reflects different assumptions for four variables: the EPS base, valuation multiple, earnings year, and cycle discount.
Bernstein’s $1,700 is based on four-year through-cycle EPS and an 11x multiple. Citi’s $2,500 is based on 11x CY27E EPS. Jefferies’ $3,000 is based on 12x C28E EPS. The earnings year moves from 2027 to 2028, EPS shifts from near-term pricing to longer-term share and mix, and the valuation multiple gradually moves from “discounted cycle peak” toward “pricing for earnings durability.”
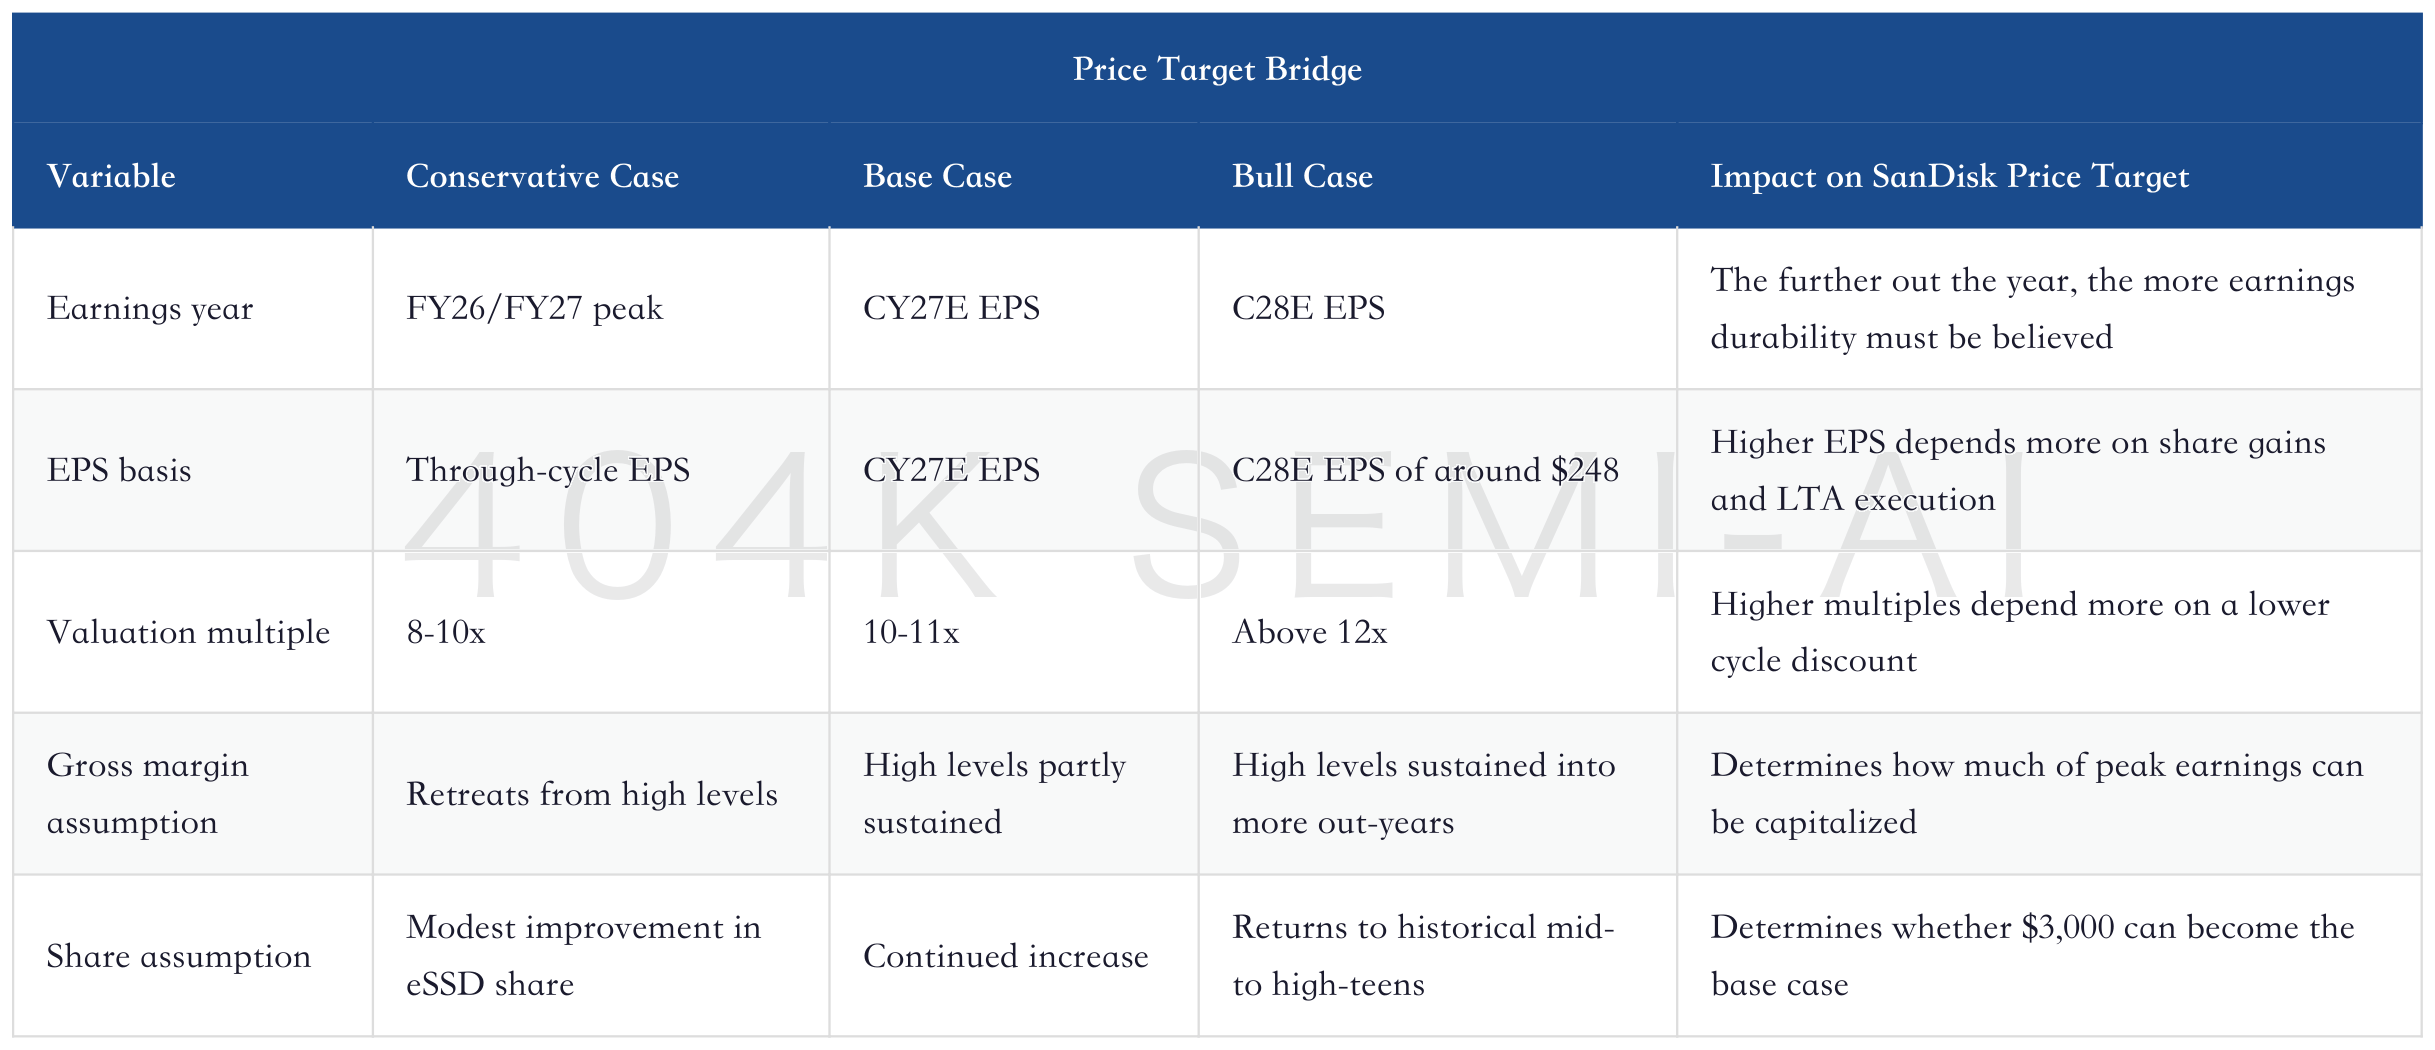
The most fragile parts of the $3,000 case are longer-term share and gross margin; price increases have already happened. Pricing can be tested through next-quarter guidance, while share and gross-margin durability require multiple quarters of validation. By anchoring on C28 EPS, Jefferies effectively puts the market’s focus on orders, contracts, and customer mix beyond 2027.
12. Versus Micron, Kioxia, and Western Digital, SanDisk Offers “NAND Purity + LTA Leverage”
SanDisk is only one beneficiary. Micron offers combined DRAM/HBM/NAND leverage; Kioxia offers NAND purity and Japan equity re-rating; Western Digital offers HDD scarcity and long-term visibility. SanDisk is distinctive because it is both a NAND-pure asset and has already pulled forward some profit visibility through NBM.
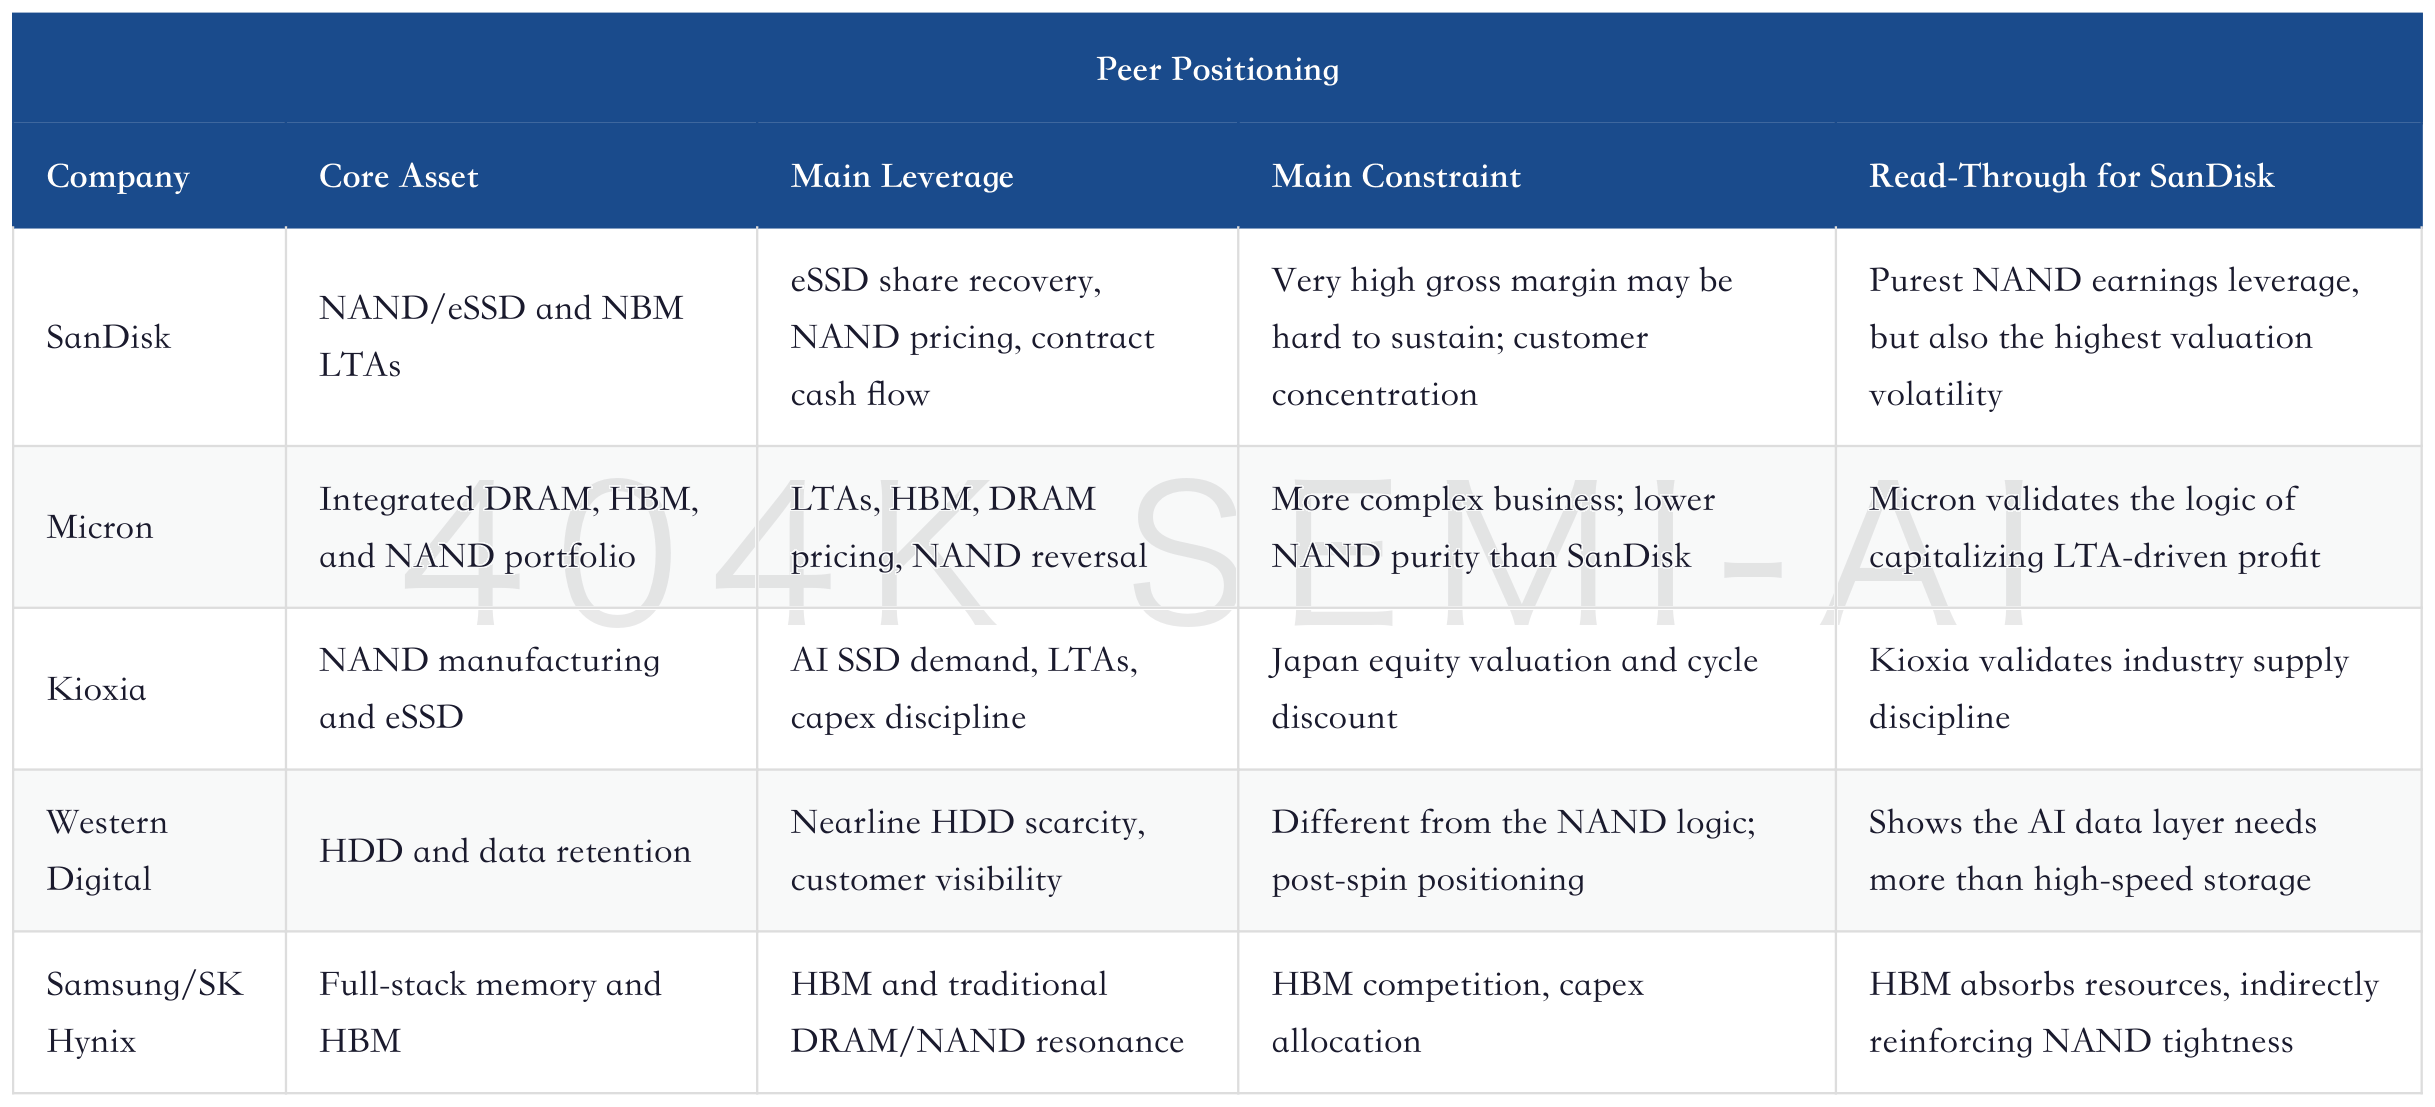
This comparison shows that SanDisk is less stable than some diversified peers, but may be the most concentrated exposure to NAND pricing, eSSD share, and NBM contracts. Its upside comes from purity, and so does its risk. If NAND prices fall, SanDisk will be more sensitive than diversified memory companies. If NAND tightness continues to extend, SanDisk’s earnings leverage will also be more direct.
13. The Next Four Quarters Require Watching a Set of Matching Relationships
The easiest mistake in interpreting SanDisk from here is to look only at the price target or only at EPS. The price target is the output of the model, and EPS is the result of pricing and mix. What really matters is a set of matching relationships: whether pricing, share, contracts, inventory, cash flow, and capex are moving in the same direction.
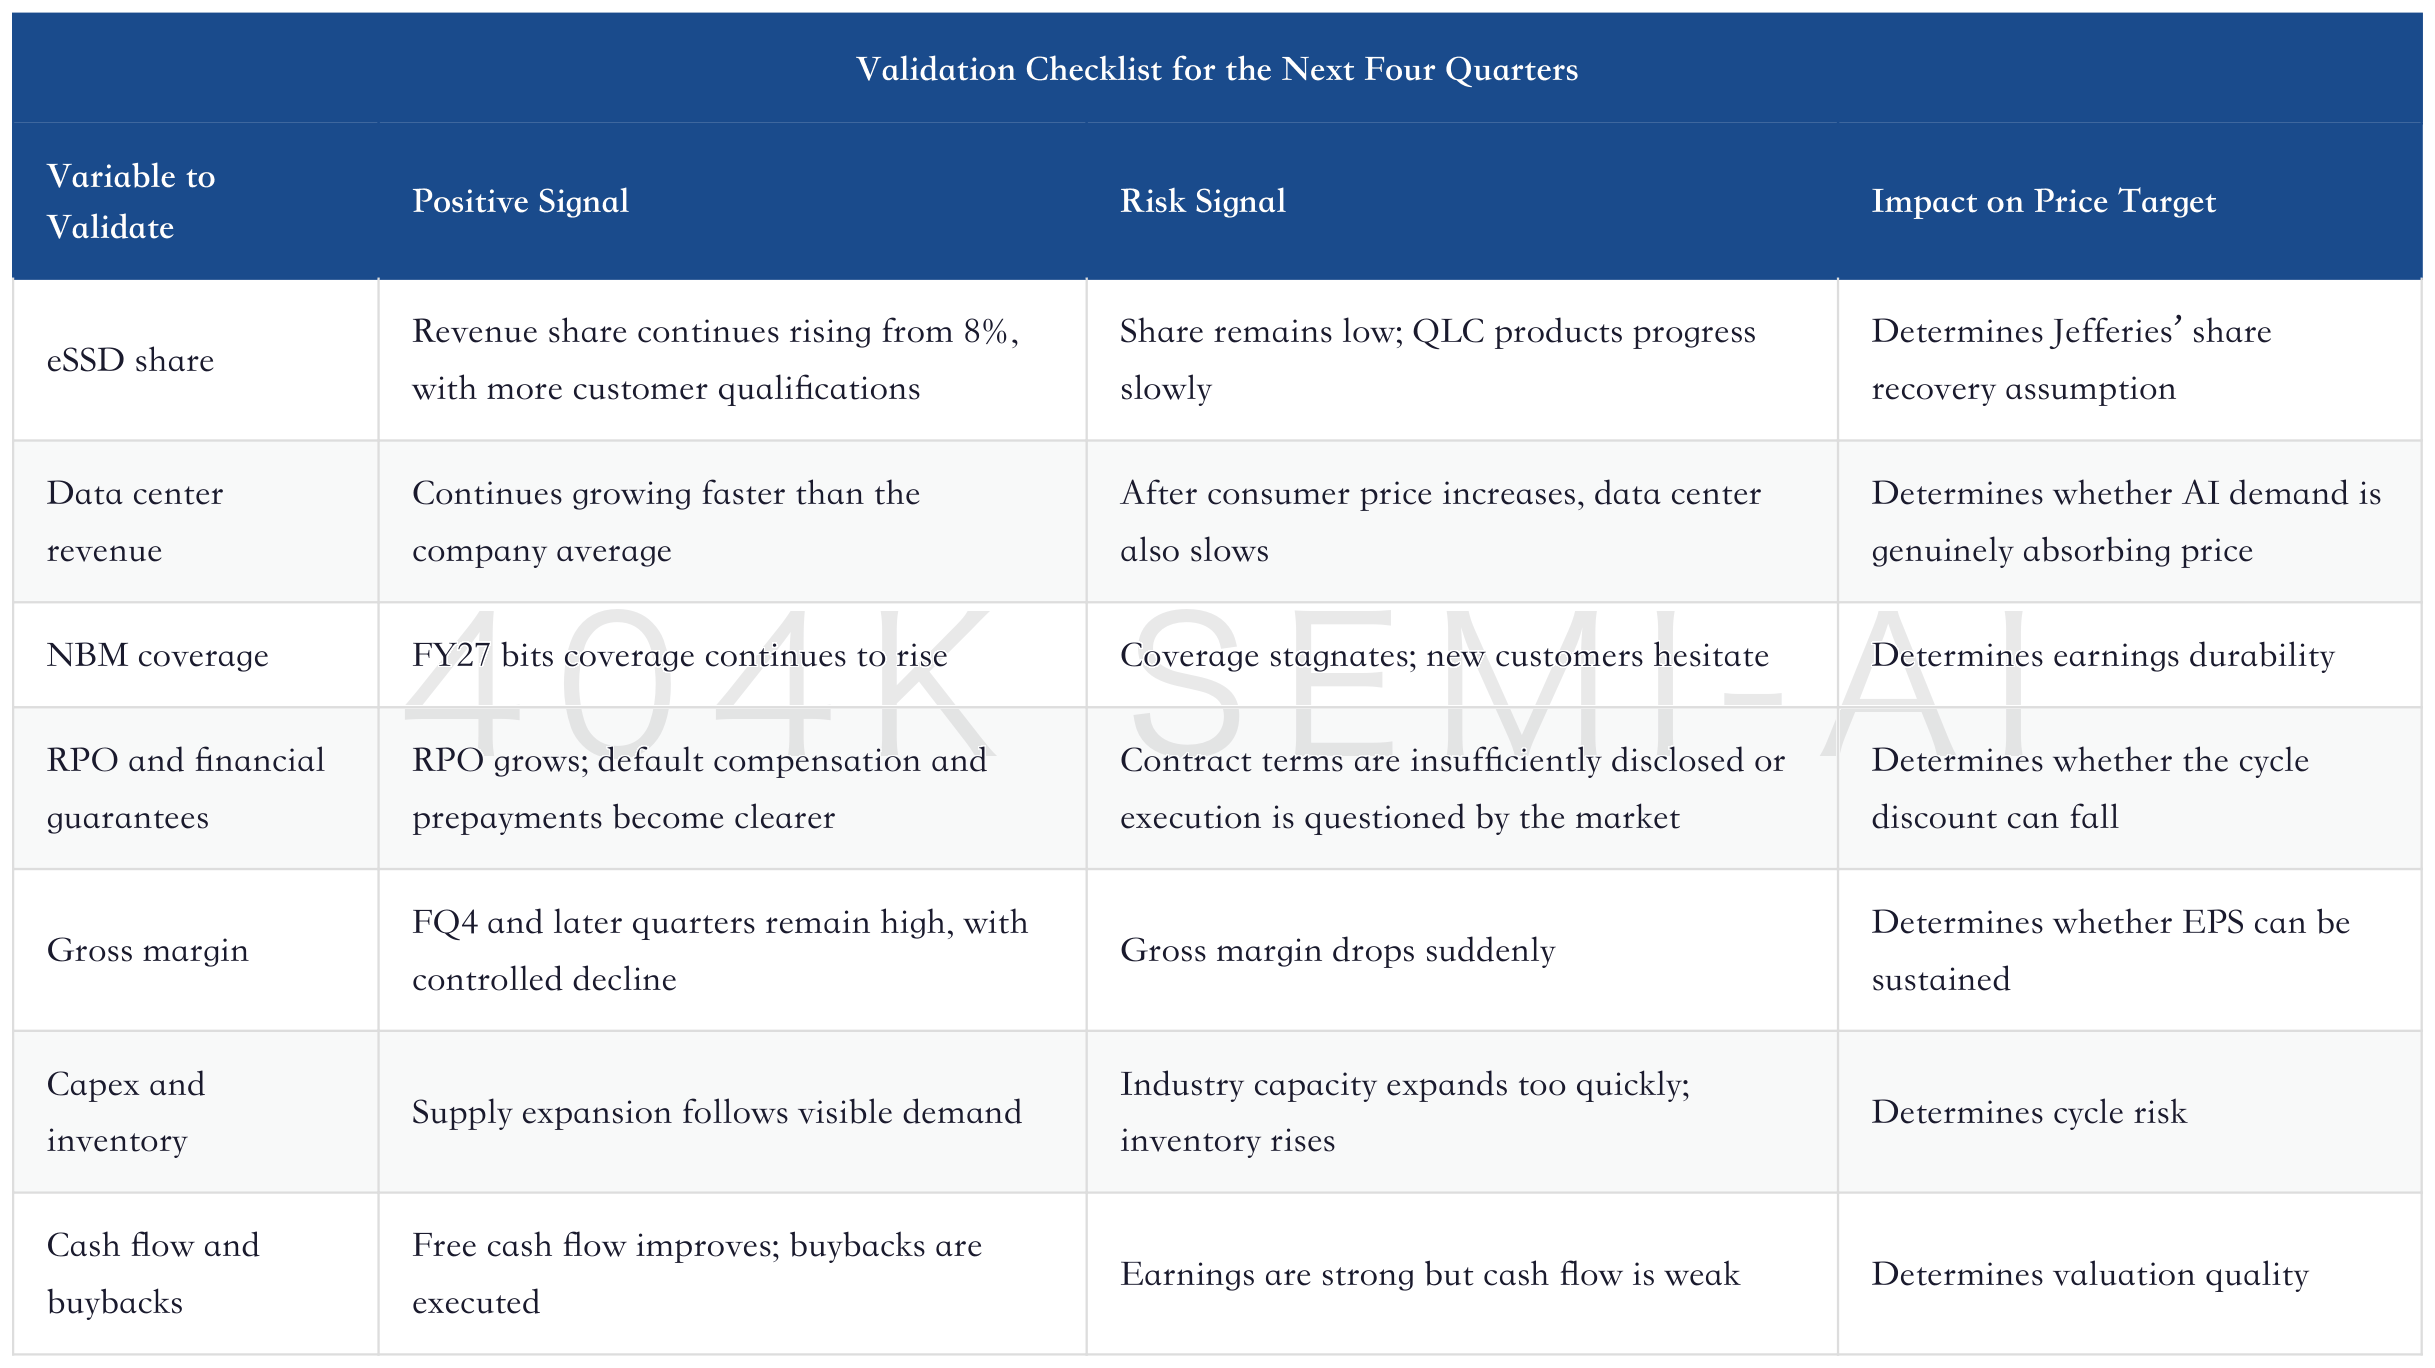
These numbers need to be read together. If eSSD share rises but gross margin falls, the company may be exchanging price for share. If gross margin is high but RPO does not grow, profits are still likely short-term. If RPO rises but cash flow is poor, contracts may not be converting smoothly. Only if share, contracts, gross margin, and cash flow all improve at the same time will the $3,000 price target become more robust.
14. Earnings Bridge: From NAND Price Increases to C28 EPS, There Are Six Gates
SanDisk’s price target upgrades look like a valuation change, but underneath them is an earnings transmission chain. NAND price increases are only the starting point. They must first flow into ASP, then revenue, then gross margin, then through NBM and customer mix into longer-term EPS, before finally being capitalized by the valuation multiple.
The first gate is price. FQ3 ASP rose sharply quarter over quarter, showing that the supply-demand gap is already strong enough for customers to accept higher prices. The second gate is shipments and product mix. If price increases come with lower bit shipments, revenue leverage will be offset. If higher-priced products are primarily sold to data center and enterprise SSD customers, revenue and gross margin will rise together.
The third gate is customer mix. Consumer electronics customers have limited ability to absorb price increases, while data center customers care more about supply and performance. SanDisk’s FQ3 data center revenue rose 233% quarter over quarter, showing that higher-value customers have already begun to change the income statement. The fourth gate is NBM. Without NBM, high gross margin is easily viewed as a shortage-period outcome. With NBM, part of the high profit pool can be embedded into forward contracts.
The fifth gate is cash flow. Strong earnings do not equal strong cash flow, especially in memory, where inventory, prepayments, customer collections, and capex timing often diverge. The sixth gate is the valuation multiple. Only when the first five gates are all open will the market be willing to apply a higher multiple to high EPS.
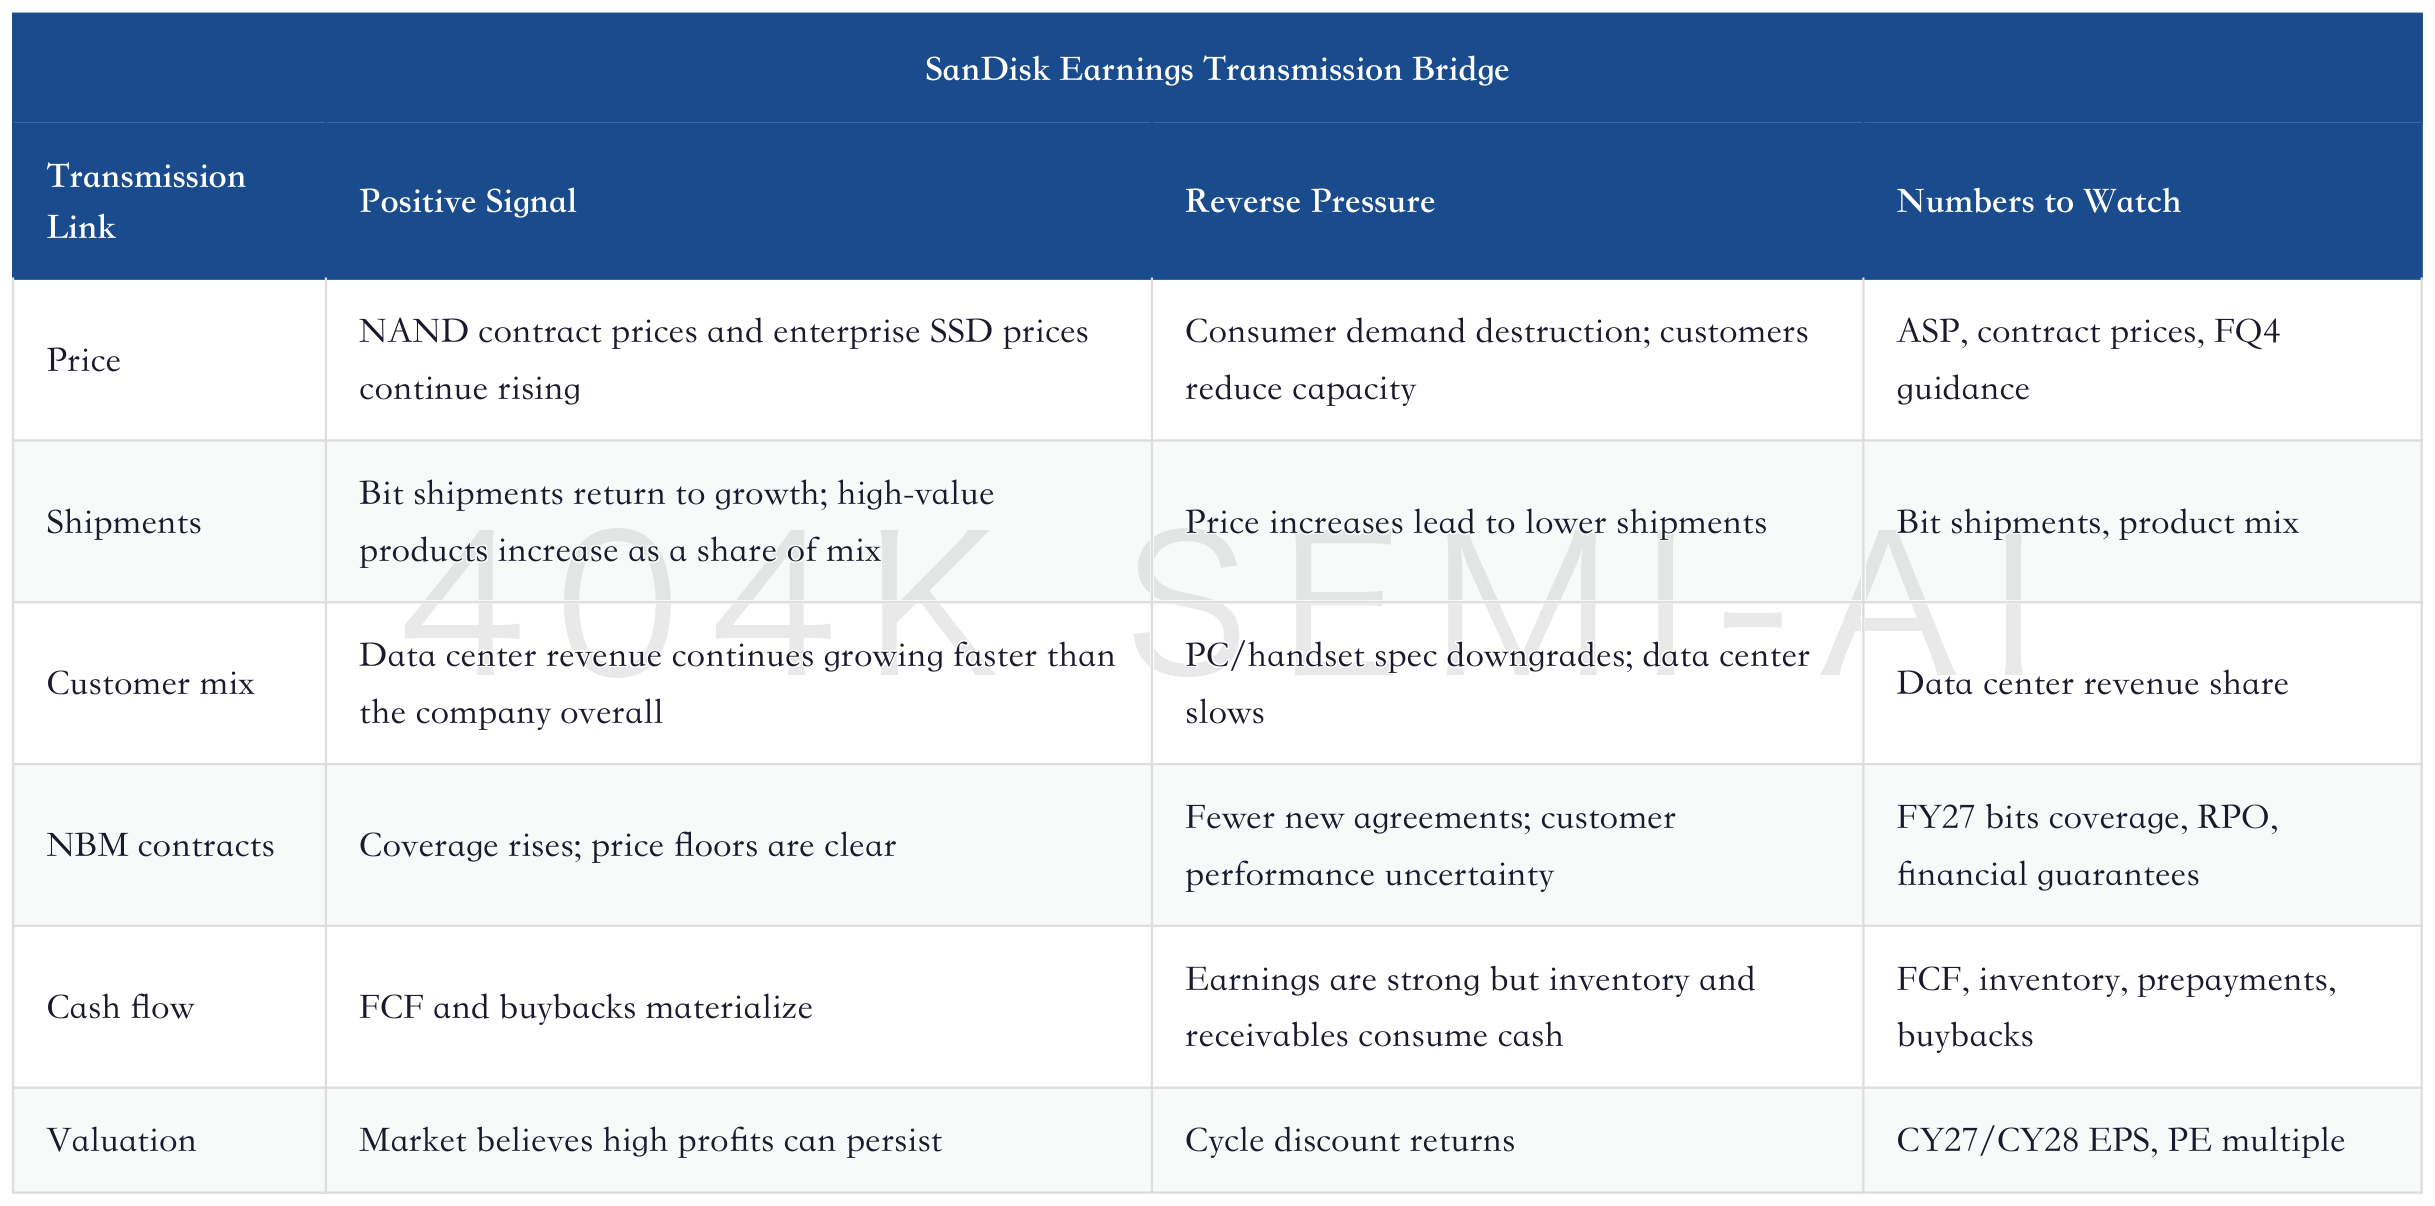
This bridge explains the differences among institutions. Bernstein and Citi place more emphasis on the first four gates. Jefferies incorporates the fifth and sixth gates into more aggressive assumptions. Morgan Stanley recognizes the first four gates, but keeps a cycle discount on the sixth. BofA views NBM and financial guarantees as key evidence between the fourth and fifth gates.
15. NBM Stress Test: How Much Profit Drawdown Can Contracts Absorb When Prices Fall?
The most important validation point for NBM is a period of price decline. When prices rise, every contract looks attractive; when prices fall, price floors, prepayments, financial guarantees, and default compensation reveal their real value.
If NAND prices remain strong in 2027, NBM’s role is to lock in supply and customer relationships. SanDisk can allocate high-value supply to customers willing to commit demand; customers receive assured supply, while the company gains higher forward visibility. In this scenario, NBM would lift the valuation multiple.
If NAND prices decline moderately, NBM’s role shifts to protecting gross margin. Contractual price floors can slow ASP erosion, customer demand commitments can reduce inventory pressure, and prepayments and RPO can improve cash-flow transparency. In this scenario, NBM may not keep EPS rising, but it can make EPS decline more slowly than in a traditional cycle.
If NAND prices fall sharply, NBM enters a stress test. Customers may compare the cost of performance with the cost of default; suppliers may proactively cut production; financial guarantees and default compensation begin to provide protection. In this scenario, whether NBM can cushion profit drawdown depends on whether contract terms are truly enforceable, as well as customers’ own cash flow and business needs.
