
SanDisk Deep-Dive Update: Goldman’s $2,200 Price Target, NAND LTAs, eSSD, and 80% Gross-Margin Upside
目录
TL;DR
1. The Key Point in Goldman’s Update: The Target Is Not the Highest, but the Earnings Bridge Is the Cleanest
2. The Heaviest Numbers in Goldman’s Model: CY26 and CY27 Are Both Meaningfully Above Street
3. NAND Supply-Demand: Tightness May Last Longer Than DRAM, but the Near-Term Bar Is Already High
4. LTA/NBM: From a Price-Hike Trade to a Profit-Floor Trade
5. eSSD: Can SanDisk Move from NAND Beta to an AI Storage Asset?
6. Benchmarking Against Seagate and Western Digital: Storage Tightness Is Shared, but Profit Characteristics Differ
7. Risk Breakdown: Elevated Expectations, YMTC, Supply Additions, and eSSD Execution
8. Follow-Up Monitoring: Use Four Tables to Judge Whether $2,200 Is the New Base
9. Conclusion: Goldman’s $2,200 Is Not the Endpoint, but a Repricing of Normalized Earnings
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Goldman raised its SanDisk price target from $1,200 to $2,200. It is not the highest target on the Street, but it offers the clearest earnings bridge: 20x normalized EPS, CY26 EPS about 33% above Street, and whether NAND LTAs and eSSD can turn a pricing cycle into a cash-flow cycle.
TL;DR
The target price rests on the earnings base. Goldman’s target is not the most aggressive current version, but the valuation bridge is cleaner: the multiple was not pushed higher, while normalized earnings assumptions were systematically revised up. This shows the update is less about momentum-chasing and more about reconfirming the profit center of gravity.
Estimate revisions matter more. Goldman’s revenue and EPS forecasts for SanDisk over the next two years are meaningfully above Street, especially in 2026 and 2027. That explains better than a single target price whether the stock can keep absorbing expectations, because what the market ultimately trades is whether earnings can be delivered.
LTAs remain the swing factor. Goldman put the conference-call focus on the number, scope, and pricing framework of new LTAs. The reason is direct: if NAND price increases rely only on spot tightness, SanDisk remains a high-beta cyclical stock; if customer agreements can lock in supply, price floors, and financial commitments, peak earnings have room to be capitalized.
eSSD determines profit durability. Goldman explicitly noted that eSSD design wins at key hyperscale customers are improving SanDisk’s product mix. The investment implication is that NAND is no longer just about industry-wide ASPs; it is about whether AI inference, KV cache, enterprise SSD mix, and customer concentration can support gross margins above 80%.
The risk is not a lack of narrative. Goldman also cautioned that investor expectations are already high. Near-term earnings must deliver a quarterly beat, strong guidance, and LTA details at the same time. If YMTC’s roadmap advances, supply increases, or eSSD share gains fall short of expectations, SanDisk will first revert from a contract cash-flow asset back into a conventional cyclical-stock framework.
Watch four sets of evidence next. First, whether 2Q26 and 3Q26 guidance continues to exceed Street; second, the number, coverage, and guarantee structure of new LTAs/NBMs; third, whether eSSD customers and gross margins are delivered together; fourth, whether supply additions after 2027 interrupt the NAND price upcycle.
1. The Key Point in Goldman’s Update: The Target Is Not the Highest, but the Earnings Bridge Is the Cleanest
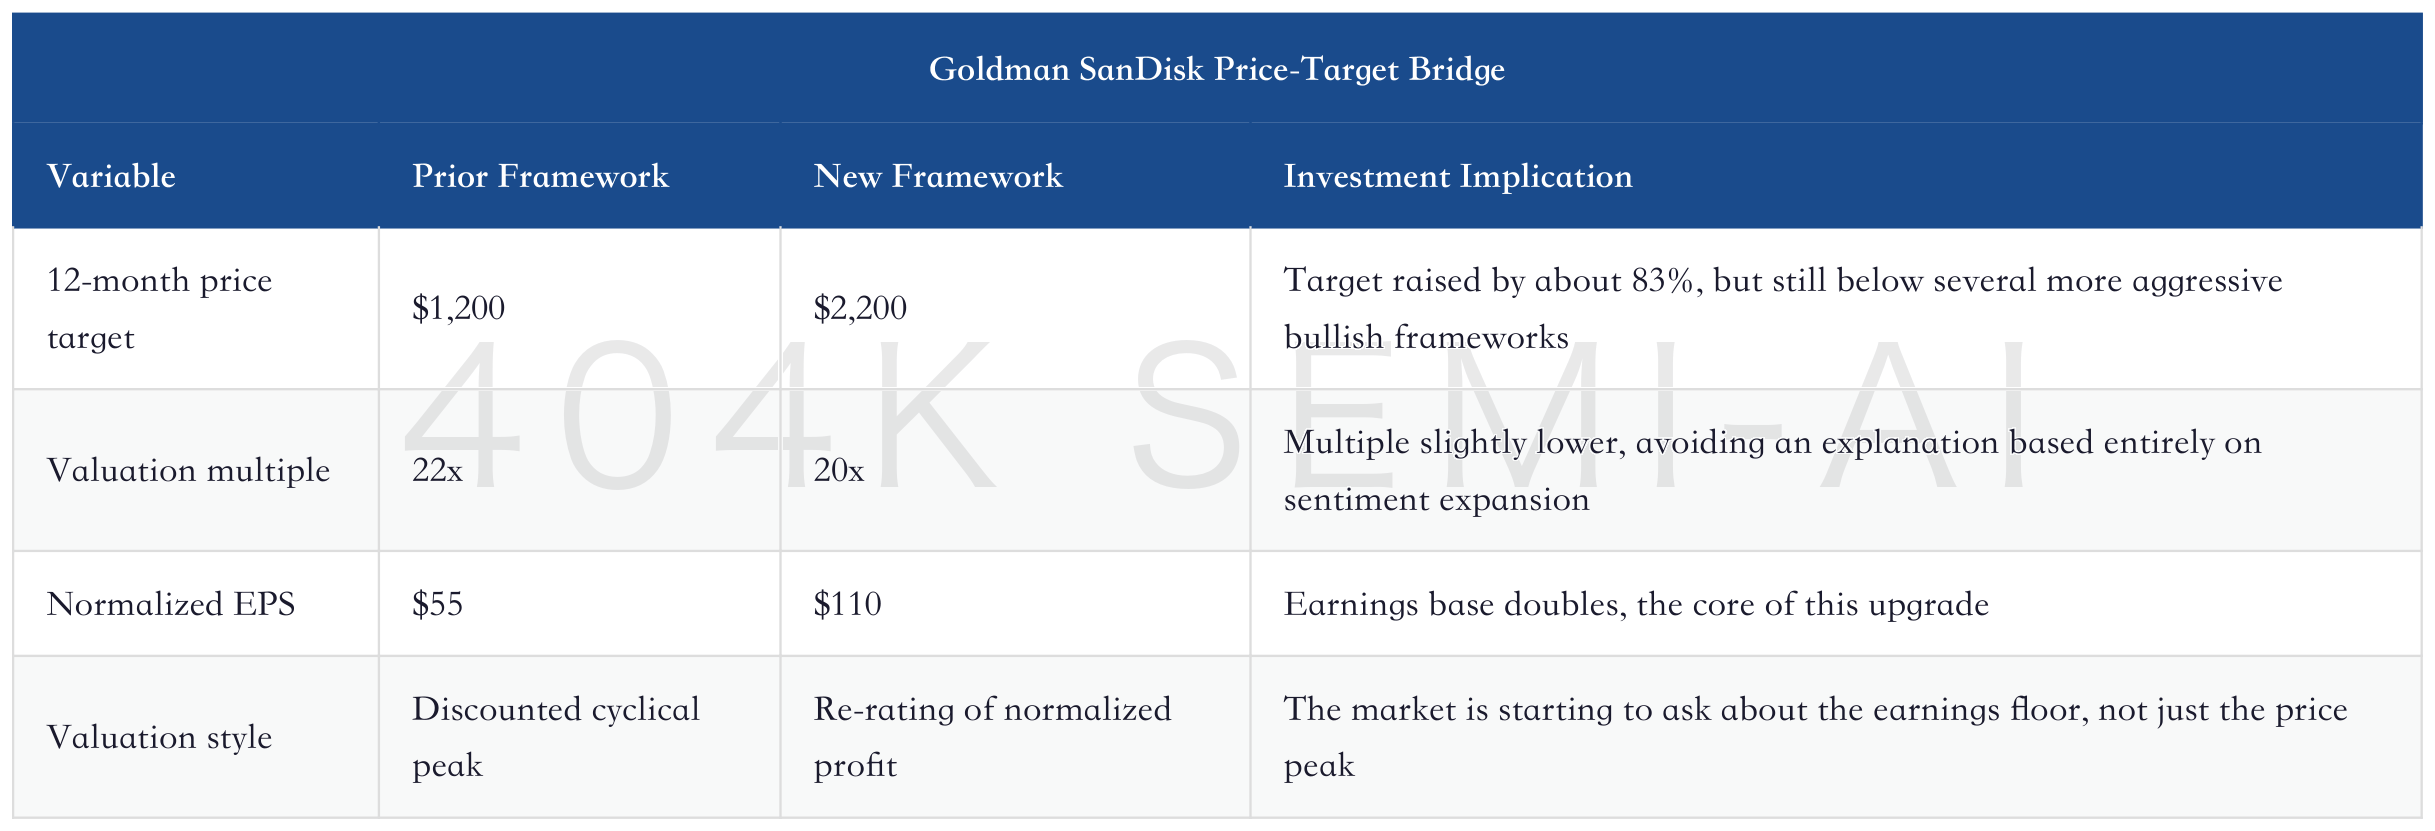
SanDisk has already become very crowded after multiple rounds of target-price increases. Citi, Jefferies, and Bernstein have each offered higher targets or more aggressive scenarios, and the market is already familiar with the narratives around NAND tightness, NBM LTAs, and enterprise SSDs. Goldman’s update looks less aggressive by comparison, but its significance lies in breaking down the valuation more clearly: the earnings base is being revised up, rather than relying on further multiple expansion.
This means Goldman is not explaining the upgrade with a higher multiple, but with a higher earnings base. In other words, the market debate shifts from “can SanDisk keep going up” to “has future normalized EPS really moved from tens of dollars to above $100.” If $110 of normalized EPS holds, 20x is not excessive; if $110 is merely an extrapolation of a one-time pricing peak, 20x instead becomes overcapitalization.
SanDisk Deep-Dive Update: Citi Raises Price Target to $2,500, NAND Tightness Extends Beyond CY27
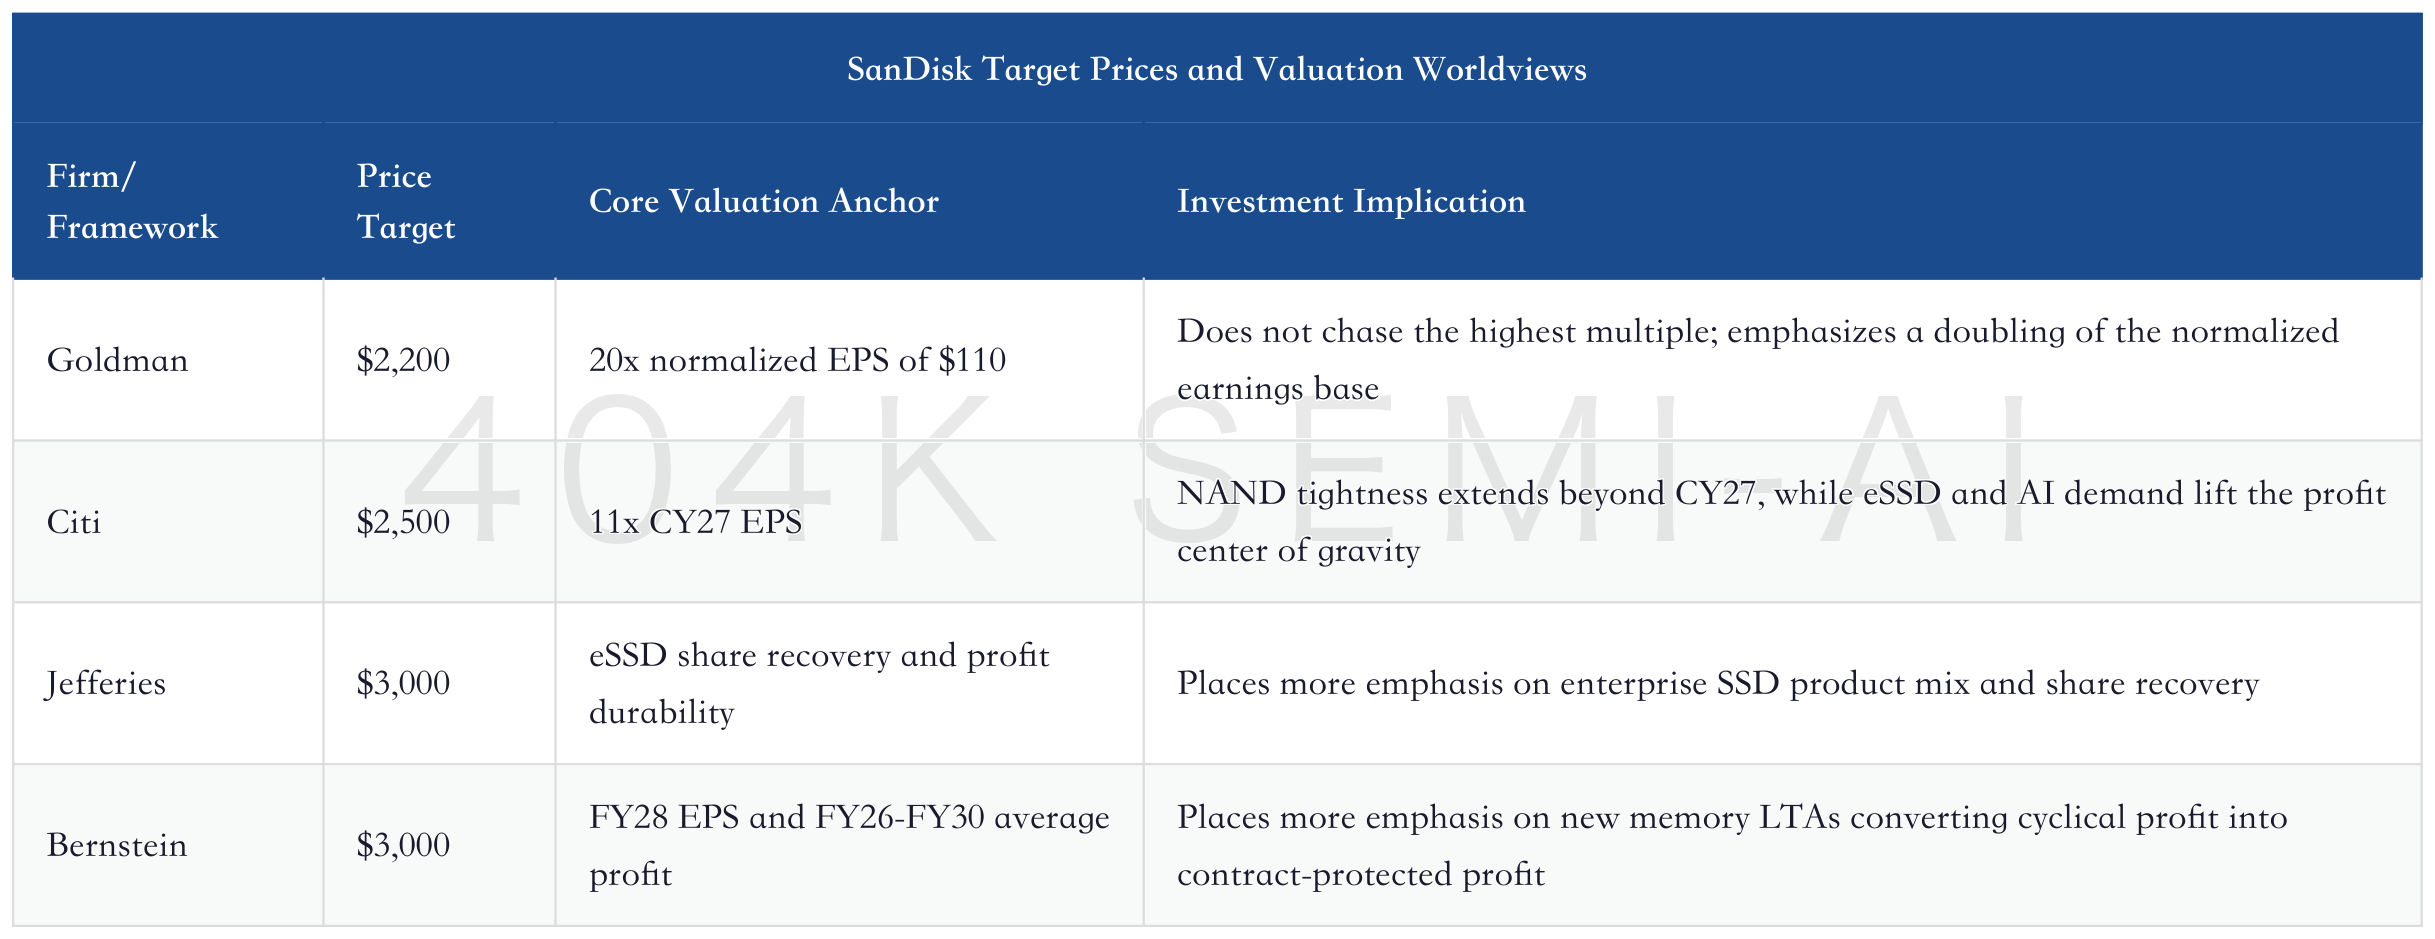
This update differs from the prior Citi, Jefferies, and Bernstein frameworks in this respect. Citi emphasized that Micron’s results validated tight NAND supply-demand through beyond CY27; Jefferies emphasized the recovery of eSSD share; Bernstein emphasized floor pricing and guarantee structures in new memory LTAs. Goldman folds these three points into a more standard valuation bridge: sustained NAND supply tightness, improved eSSD product mix, and higher visibility from LTAs/NBMs, ultimately landing on normalized EPS and the target multiple.
The divergence in sell-side targets is no longer a linear ranking of “who is more bullish,” but three different worldviews.
SanDisk Deep-Dive Update: Jefferies’ $3,000 Price Target, eSSD Share Recovery, and How NAND LTAs Re-rate Profit Durability
The research judgment is straightforward: Goldman’s target price does not fully price in the upside imagination, but it makes clear whether the thesis can still be written into models. If SanDisk continues to re-rate, the driver will not be another investment bank raising its target price, but more models starting to acknowledge that CY26-CY27 earnings are not a temporary spike.
2. The Heaviest Numbers in Goldman’s Model: CY26 and CY27 Are Both Meaningfully Above Street
Goldman’s estimate revisions for SanDisk are large, especially for 2026 and 2027. The specific figures are shown in the two tables below. The more important implication is that Goldman is not only betting on a next-quarter beat; it has already made high 2027 earnings the backbone of the model.
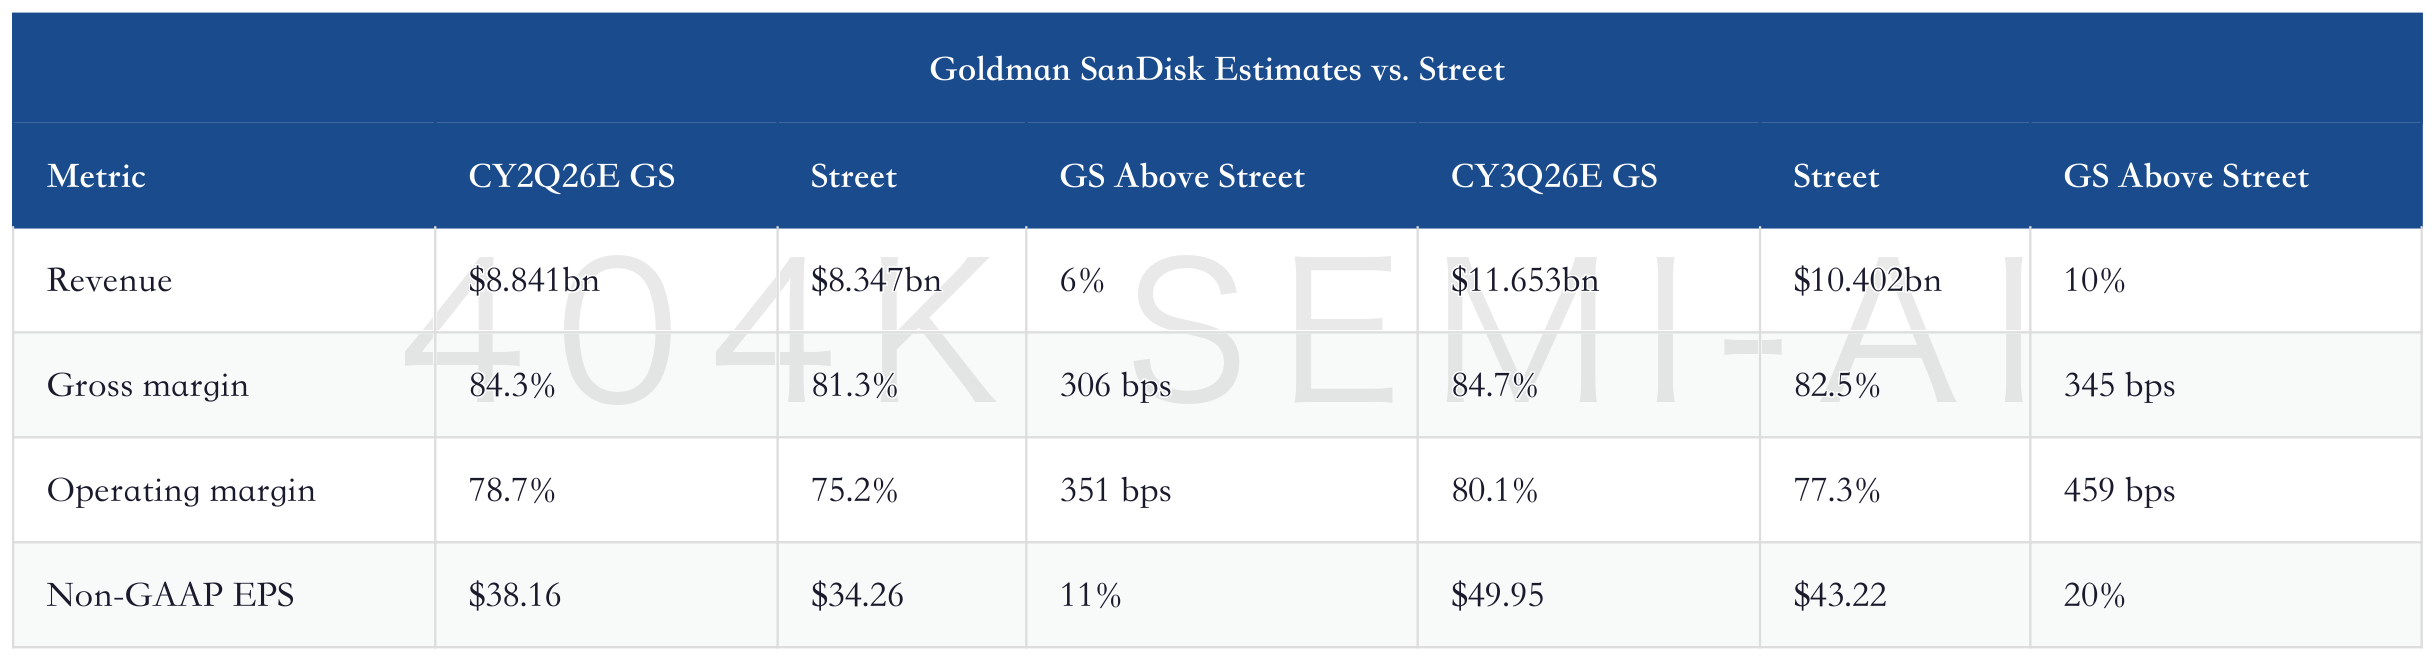
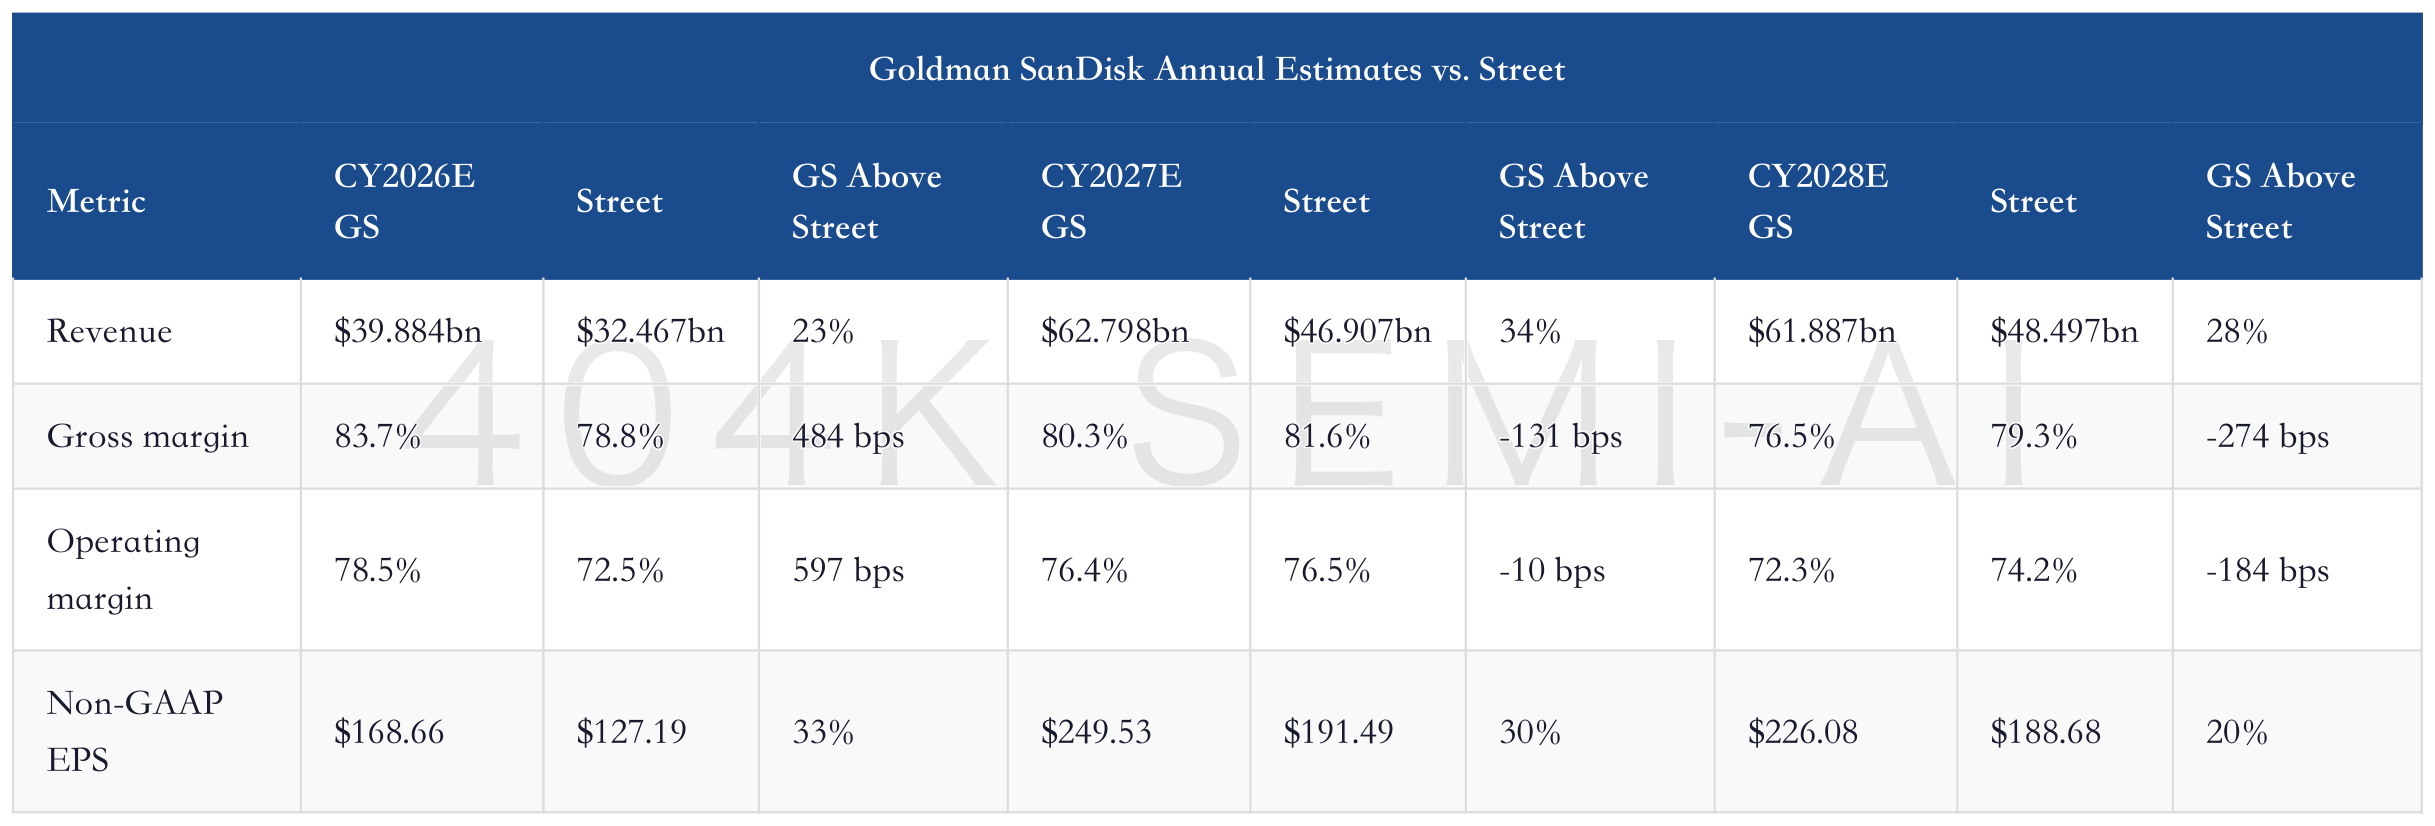
There is one easily overlooked detail in these two tables: Goldman’s CY27 and CY28 gross-margin and operating-margin forecasts are not uniformly higher than Street. CY27 gross margin is 80.3%, below Street at 81.6%; CY28 gross margin is 76.5%, also below Street at 79.3%. Yet Goldman’s revenue and EPS remain meaningfully above Street, which shows that its real bet is on revenue scale, NAND price levels, shipment mix, and operating leverage, rather than simply assuming gross margins stay at the most extreme levels forever.
That actually makes the model more credible. The models most easily discounted by the market are those that push NAND prices, gross margins, and multiples all to high levels. Goldman’s update is more like an acknowledgment that margins will be extremely high in 2026, then gradually decline in 2027-2028; even so, revenue scale and eSSD mix still keep EPS far above traditional cyclical levels.
SanDisk Deep-Dive Update: Bernstein’s $3,000 Price Target, and How New Memory LTAs Rewrite the NAND Cycle Discount
So the focus in Goldman’s model should not only be the price target, but two specific numbers: whether normalized EPS of $110 can be accepted by more sell-side analysts, and whether CY27 EPS of $249.53 becomes the new bullish consensus. If these two numbers keep moving higher, $2,200 is only an interim anchor; if they begin to move lower, the trade will start to fade even if the target price does not change immediately.
3. NAND Supply-Demand: Tightness May Last Longer Than DRAM, but the Near-Term Bar Is Already High
Goldman Sachs maintains a Buy rating on SanDisk. The core rationale is that NAND supply-demand tightness will persist, and may last longer than DRAM tightness. The reason is limited incremental NAND supply. Suppliers remain cautious on new capacity, and the industry has been disciplined by several years of losses and balance-sheet pressure. In the near term, there is not enough incentive to flood the market with supply again.
This is essentially the same line as the early-July memory monthly report, Citi’s read-through from Micron earnings, and Bernstein’s decomposition of long-term agreements: the memory cycle is not ordinary restocking. AI is pulling the memory hierarchy back into compute infrastructure. HBM addresses the highest-performance memory layer, DRAM carries active data, and NAND plus enterprise SSDs are beginning to carry a cheaper, larger-capacity context and data layer closer to inference systems. As long as AI inference continues to expand, NAND demand will no longer be determined only by smartphones, PCs, and consumer electronics.
Deep Update on the NAND Industry: Triple Validation from AI eSSD Shortages, Supply Discipline, and 2028 New Capacity
At the same time, Goldman Sachs warns that the near-term earnings bar is already very high. SanDisk’s 2Q guide was already strong, and management has recently made positive comments. The market has already priced a substantial amount of good news into the stock. That means simply delivering “strong results” on earnings day may not be enough. The company likely needs to provide strong guidance, pricing commentary, incremental LTA/NBM updates, and a clear supply-discipline message.
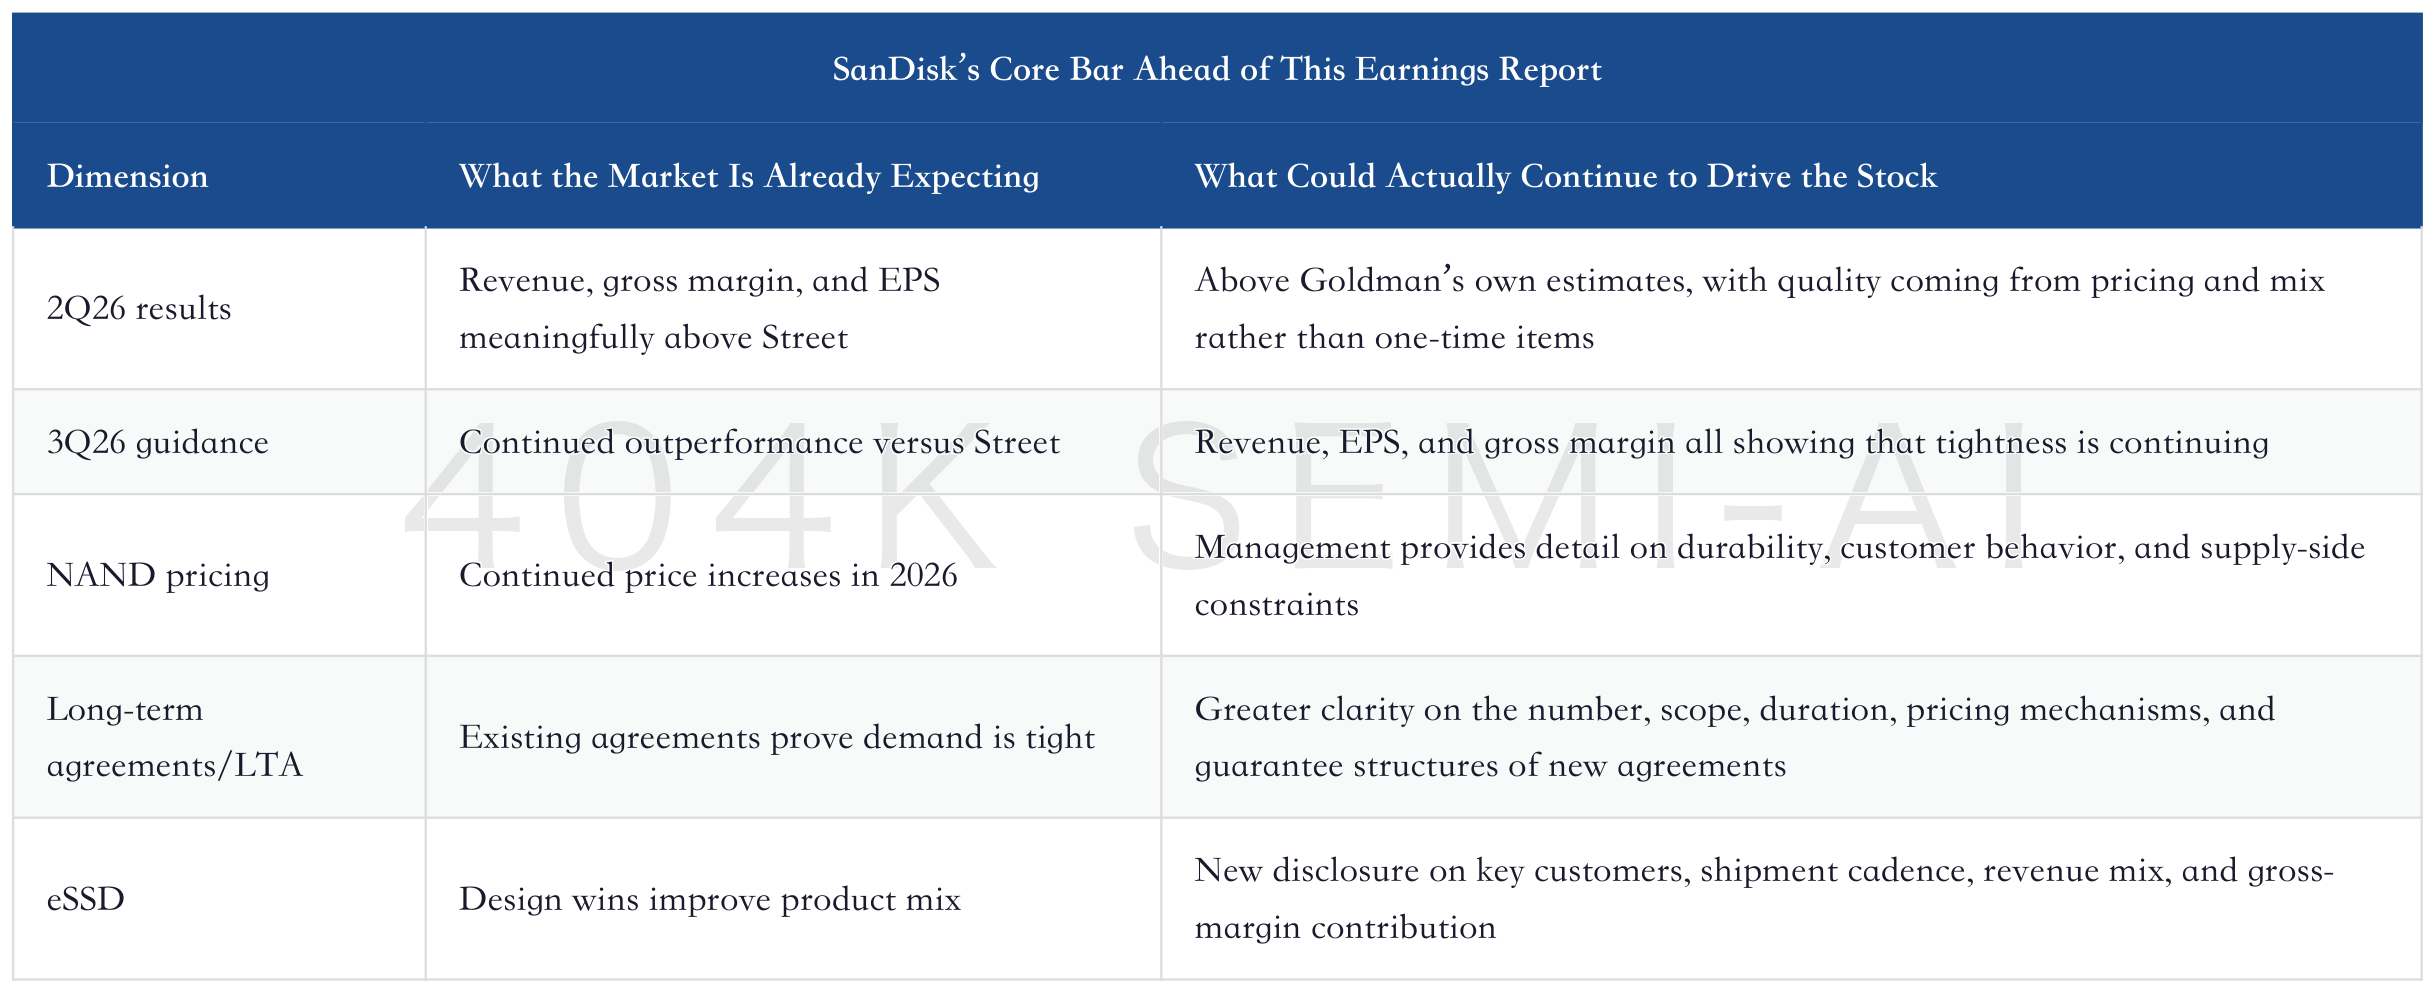
This is SanDisk’s current “high-expectations paradox”: the stronger the fundamentals, the higher the earnings bar; the higher the expectations, the less sufficient an ordinary beat becomes. For bulls to win, they do not need to prove that NAND is still tight. They need to prove that the tightness can last long enough to support the 2027 and 2028 earnings models.
4. LTA/NBM: From a Price-Hike Trade to a Profit-Floor Trade
Goldman Sachs places LTA among the most important issues for the earnings call. Especially after Micron recently announced multiple customer agreements, investors will directly ask SanDisk: how many new agreements are there, how large is the scope, how do the pricing and guarantee mechanisms work, and can SanDisk lock in future demand and a profit floor the way Micron has?
This directly extends SanDisk’s main storyline over the past month. Prior notes have already discussed that SanDisk’s new business model is not a normal long-term supply contract, but a structure that combines customer supply assurance, price ranges, minimum revenue, and financial commitments. BofA’s June management meeting notes mentioned that SanDisk had already contracted more than one-third of F27 revenue through NBM, with five agreements containing more than $11 billion in financial guarantees. The first three agreements provided about $42 billion of minimum contracted revenue, along with $400 million of prepayments and arrangements with third-party financial institutions.
Deep Update on SanDisk: AI Demand, NBM Long-Term Agreements, and NAND Profit Durability
Goldman Sachs does not rehash all of that prior information in detail, but by placing LTA as the top focus for the earnings call, it shows that what the market is really buying now is the “profit floor.” If SanDisk only sells spot NAND, investors will discount peak profits as they would for a cyclical stock. If SanDisk can lock one-third, one-half, or even more of future supply into agreements with price floors and guarantees, the market will begin to value it on visible cash flow.
Long-term agreements do not change upside elasticity. They change the company’s ability to explain the downside.
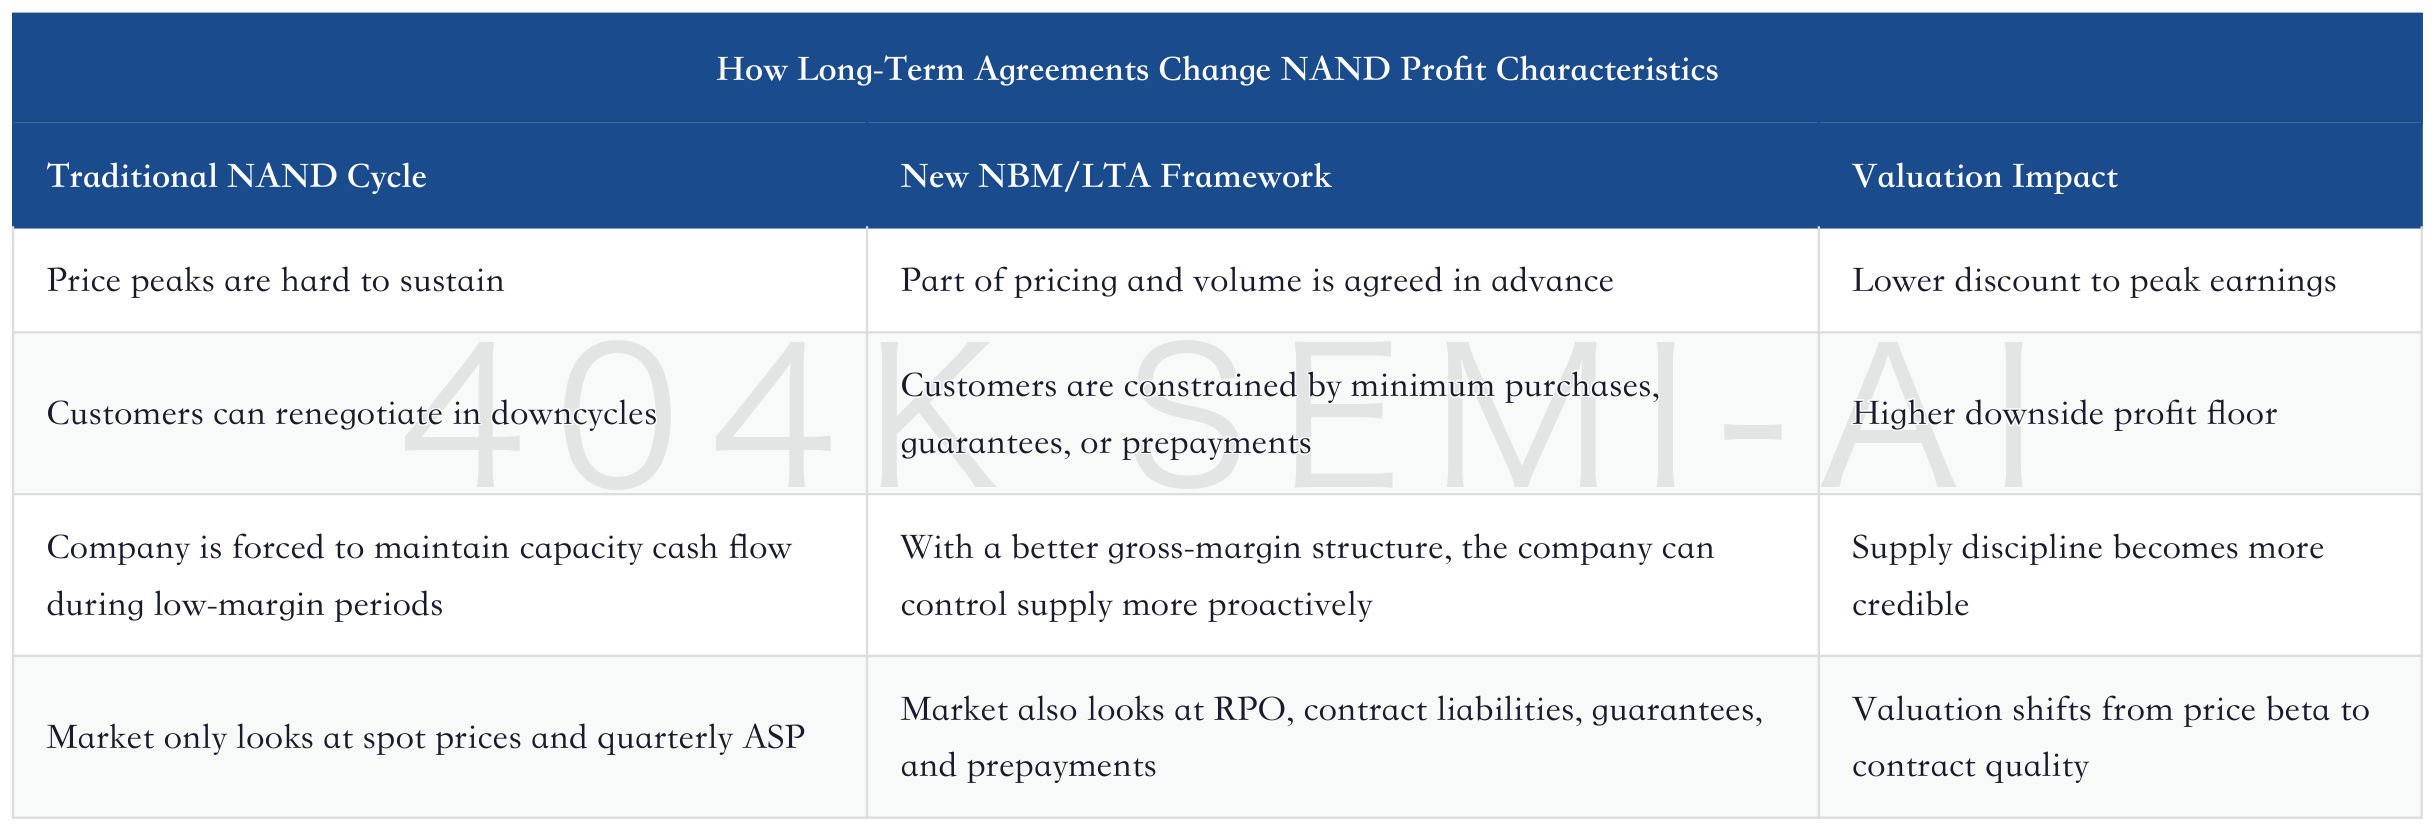
This is also why Goldman Sachs can nearly double its price target even while lowering the target multiple from 22x to 20x. The multiple is not more aggressive, but the earnings base has moved sharply higher. Whether that earnings base can be accepted depends on whether LTA/NBM can prevent profits from floating quarter by quarter on spot prices.
5. eSSD: Can SanDisk Move from NAND Beta to an AI Storage Asset?
Goldman Sachs explicitly notes that SanDisk’s product-mix improvement comes from eSSD design wins at key hyperscale customers. This point is very important because it determines whether SanDisk is merely a high-beta vehicle for NAND price increases, or a storage asset within AI inference infrastructure.
If one looks only at NAND pricing, SanDisk, Kioxia, Micron, Samsung, and SK hynix are all in the same cycle. All benefit when prices rise, and all come under pressure when supply opens up. But eSSD is different. It directly connects to cloud providers, AI inference, KV cache, RAG, cold/warm data tiering, and unit token cost. The larger AI inference becomes, the less feasible it is for systems to place all context inside GPU HBM. Whether high-performance SSDs can become a cheaper expansion layer will determine the price elasticity and customer stickiness of enterprise NAND.
