
SanDisk Deep Dive Update: Bernstein's $3,000 Price Target, and How New Memory LTAs Rewrite the NAND Cycle Discount
目录
Too Long; Didn't Read
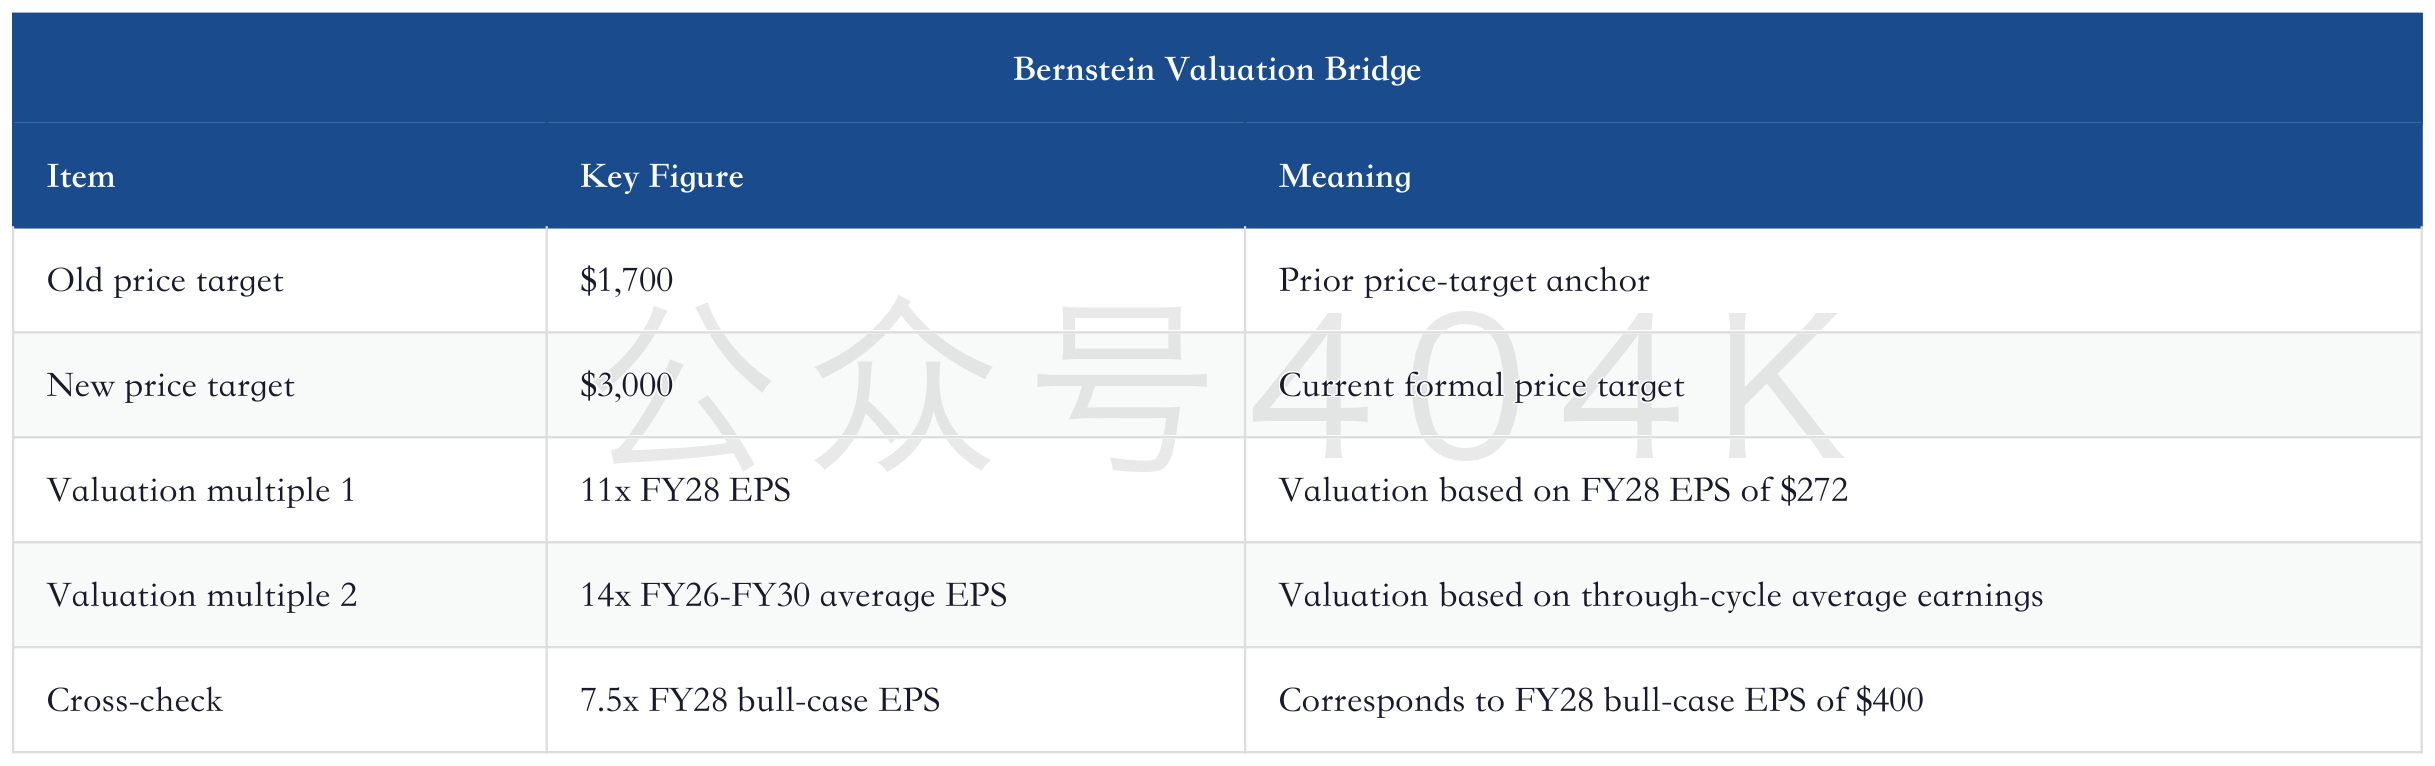
1. Conclusion: The Key to the $3,000 Price Target Is a Higher Earnings Floor
2. New Memory LTAs: From a Price Cycle to a Contract Cycle
3. Why It Differs from Micron: SanDisk Has a Higher Floor Price, Micron Has Longer Contracts
4. Stress Test: LTAs Prevent Extreme Downside from Flowing Directly Through the Income Statement
5. Model Revisions: FY27 and FY28 Are the Valuation Core
6. Follow-Up Validation: Watch Four Numbers, Not Just NAND Spot Prices
7. Conclusion: SanDisk's Valuation Anchor Shifts from Price Peaks to Contract Protection
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Bernstein raised its SanDisk price target from $1,700 to $3,000. The core change extends from NAND price increases to earnings protection under new memory LTAs. This article breaks down the $0.29/GB floor price, more than $11 billion of guarantees, the 60% coverage case, and valuation multiples to assess whether SanDisk can move from a cyclical stock to a storage asset with steadier cash flow.
Too Long; Didn't Read
$3,000 is the formal price target. Bernstein raised its SanDisk price target from $1,700 to $3,000, and the valuation anchor moved from FY27 earnings to FY28 earnings and FY26-FY30 average earnings. This means the market needs to reprice earnings durability; the next test is whether high profits can hold through a price downturn.
New memory LTAs are the main driver of this upgrade. These contracts have price floors, customer guarantees, and 3-5 year terms. Customers face a higher cost to walk away when prices fall, so SanDisk's downside earnings are steadier than in a traditional NAND cycle. The validation points are the number of newly signed contracts and coverage.
$0.29/GB is the key floor price. Bernstein estimates that the floor price in SanDisk's newly signed LTAs is close to CQ2'26 ASP, materially stronger than Micron's lower floor price, but SanDisk's average contract term is slightly shorter. This implies strong earnings leverage, while renewal pressure also deserves attention.
60% coverage changes the stress test. If 60% of shipments move into LTAs, FY30 EPS could still reach roughly $184-214 even under an extreme ASP downside scenario, far above the earnings floor without LTAs. The higher the coverage, the easier it is for the market to accept the target multiple.
Model revisions come from price and visibility. Bernstein raised FY27/FY28 EPS to $243 and $272, both well above consensus. The items that need validation are gross margin, RPO recognition, cash flow, and contract renewals. NAND spot prices alone are not enough.
Risks are concentrated in disclosure and the cycle inflection. SanDisk's near-term numbers are very strong, but the structure of RPO, guarantees, cash prepayments, and contingent commitments is complex. If NAND demand weakens, customer renewals slow, or disclosure remains opaque, valuation will first revert to a standard cyclical-stock framework.
1. Conclusion: The Key to the $3,000 Price Target Is a Higher Earnings Floor
Bernstein's upgrade of SanDisk shifts the focus from extrapolating NAND prices to the earnings floor. The core call in the report is more aggressive: new memory LTAs are changing the way SanDisk's earnings fluctuate. Historically, NAND companies have had difficulty earning high valuation multiples because price peaks and profit peaks are hard to sustain. Now customers lock in volume and price bands in advance and provide financial guarantees, lifting SanDisk's EPS and gross-margin floor in downcycles.
SanDisk Deep Dive Update: Jefferies' $3,000 Price Target, eSSD Share Recovery, and How NAND LTAs Revalue Earnings Durability
This is aligned with Jefferies' prior $3,000 target for SanDisk, but Bernstein puts more weight on contract structure. Jefferies focuses on eSSD share recovery, NAND supply-demand, and margin expansion; Bernstein focuses on LTAs locking in future downside risk. Combined, the two frameworks show that the market's focus has shifted from "how high can NAND rise this cycle" to "can SanDisk turn high profits into capitalizable long-term cash flow."
2. New Memory LTAs: From a Price Cycle to a Contract Cycle
The NBM/LTA contracts signed by SanDisk are meaningfully different from traditional storage LTAs. Older LTAs often looked more like supply assurance for customers: pricing still fell with the market, and suppliers did not receive enough protection in downturns. The new LTAs add three layers of protection: price floors, customer financial commitments, and longer contract terms. Customers provide guarantees or prepayments in advance, suppliers deliver under the contracts, and both sides lock part of future price volatility into the contract.
The known facts disclosed by Bernstein are important. SanDisk has already signed five agreements. The first three agreements carry RPO of $41.6 billion, financial guarantees across all five agreements exceed $11 billion, and more than one-third of FY2027 bit supply is already under explicit commitments. The report also infers from disclosed RPO that the total value of the five agreements is about $69.3 billion.
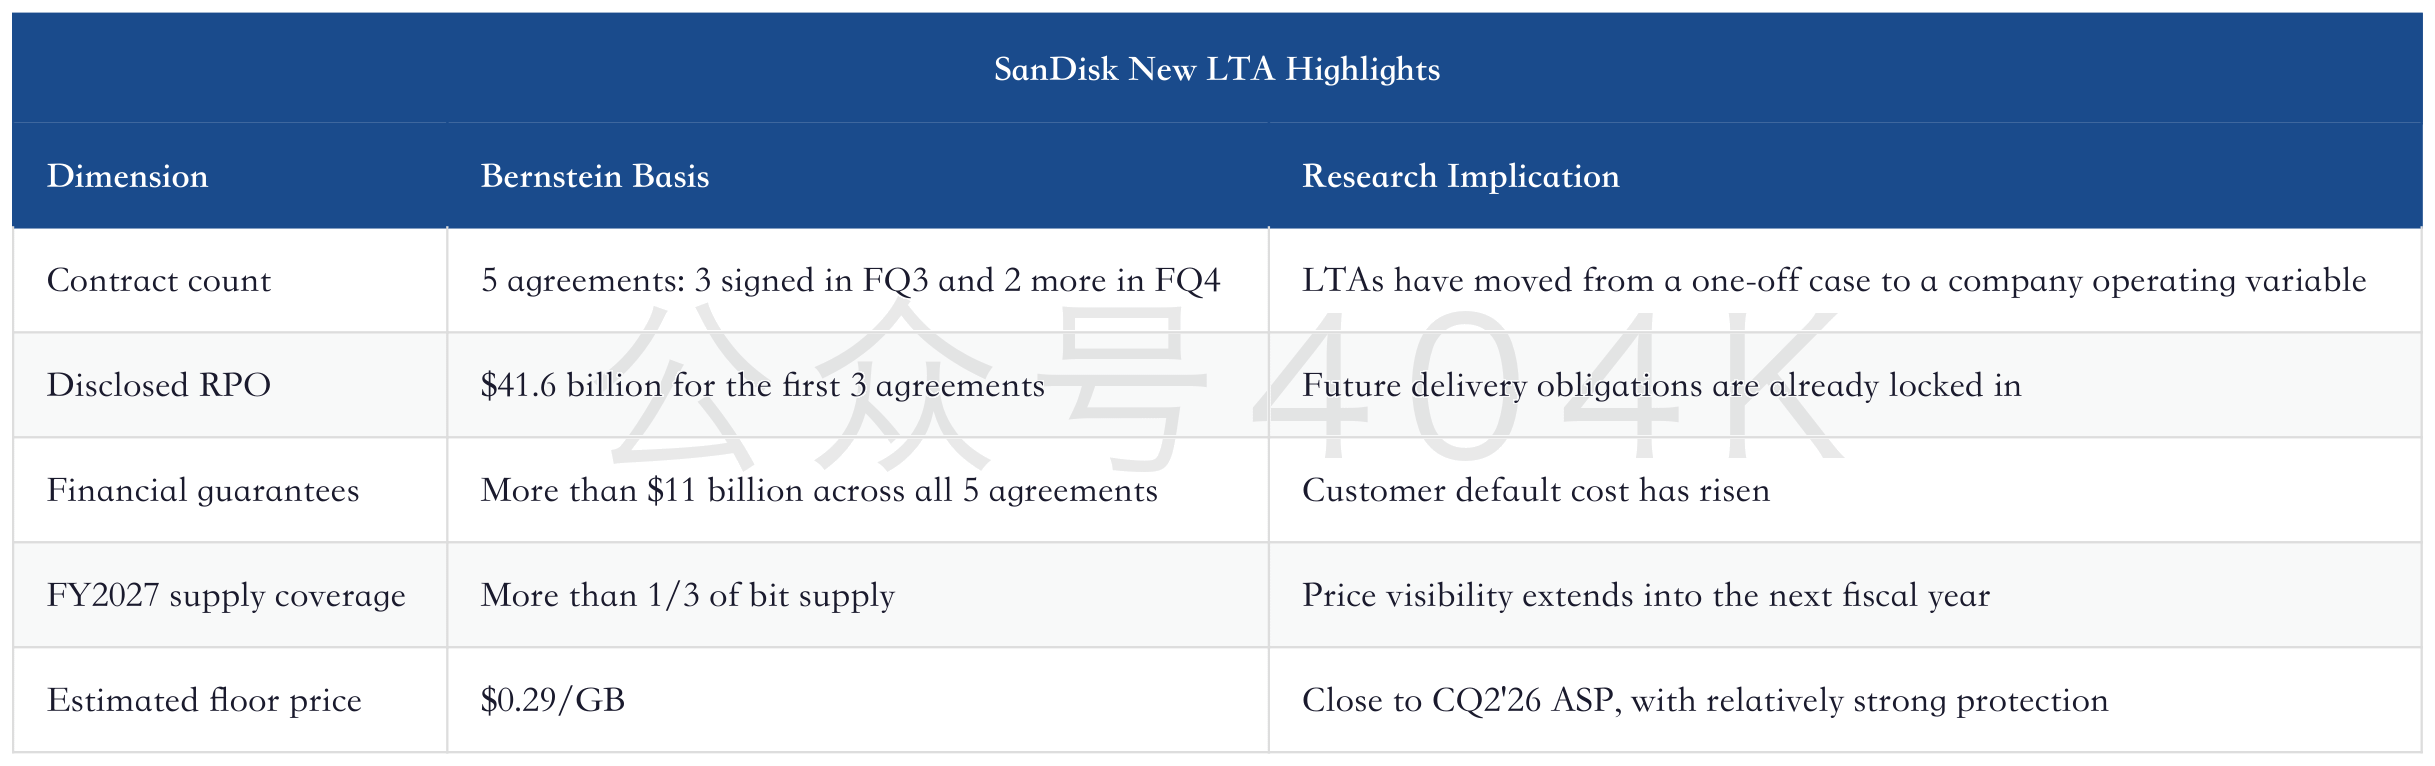
The investment implication of this structure is direct: SanDisk is converting part of spot-market risk into contract-performance risk. As long as customer demand remains, prices do not need to set new highs every quarter for the earnings model to maintain a higher floor.
SanDisk Deep Dive Update: Citi Raises Price Target to $2,500, NAND Shortage Cycle Extended Beyond CY27
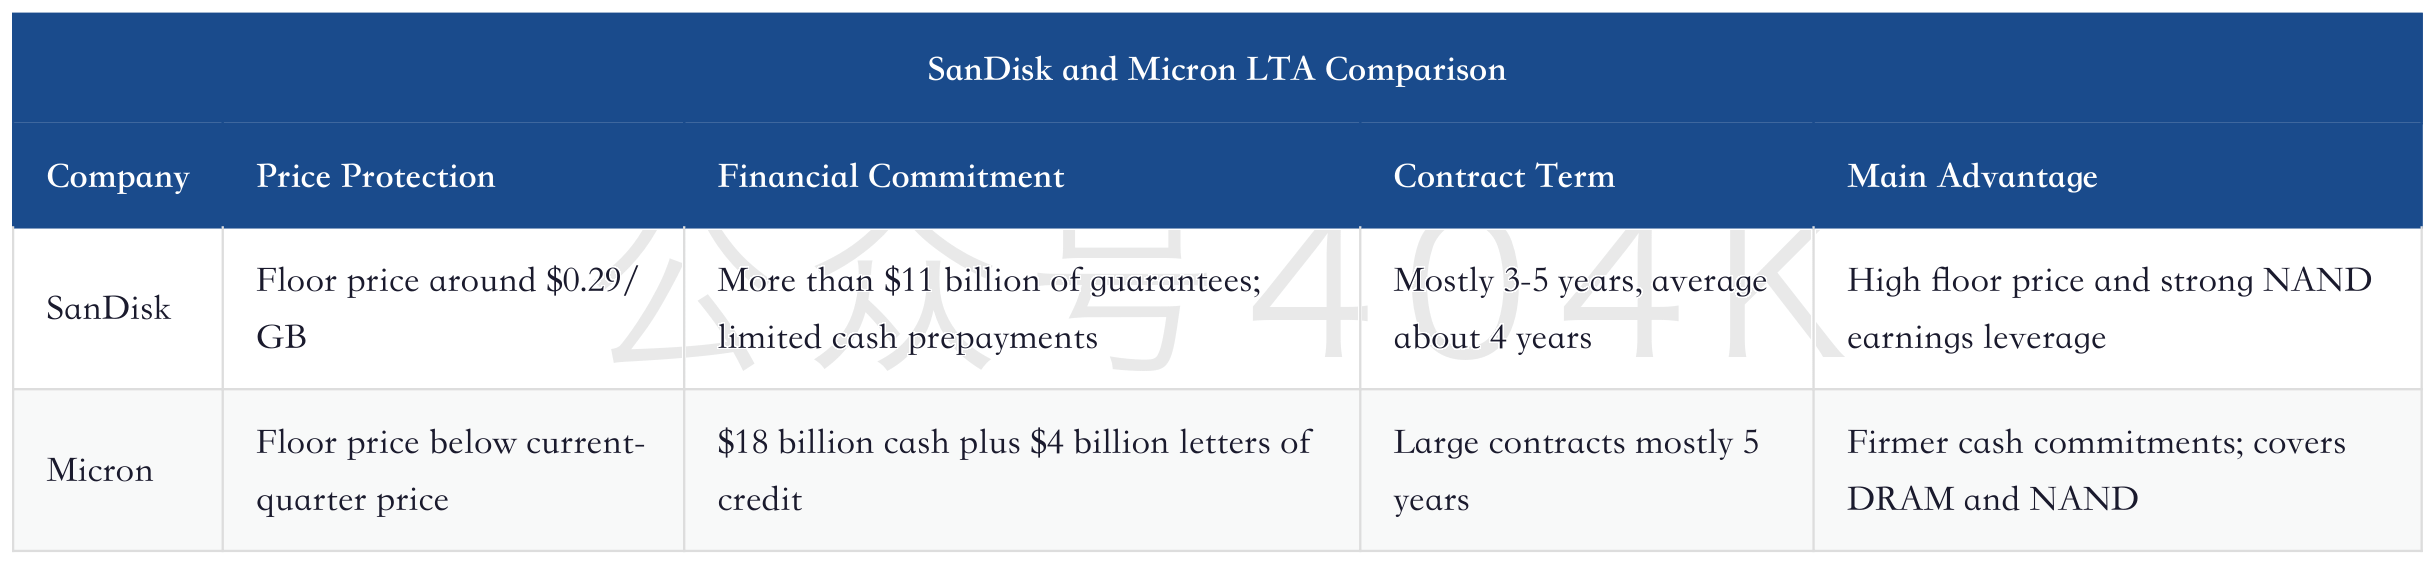
3. Why It Differs from Micron: SanDisk Has a Higher Floor Price, Micron Has Longer Contracts
Bernstein compares SanDisk with Micron. SanDisk's strength is a high floor price, estimated at about $0.29/GB and close to the current-quarter market price. Micron's floor price is lower; the report estimates it is about 50% below CQ2'26. But Micron's contracts have longer terms and firmer cash guarantees, with 16 SCAs covering DRAM and NAND and roughly $22 billion in combined cash deposits and letters of credit.
This difference drives different rerating paths. SanDisk looks more like a high-floor-price, high-NAND-beta earnings lever. Micron looks more like a storage cash-flow asset with broader product coverage and longer contract duration. SanDisk's advantage is earnings leverage in 2027-2028; the risk is contract renewal and disclosure complexity. Micron's advantage is customer cash commitments and category coverage; the risk is a relatively low floor price.
Micron Deep Dive: Can Peak Earnings Be Capitalized, and How AI Memory LTAs Rewrite the Cycle Discount
4. Stress Test: LTAs Prevent Extreme Downside from Flowing Directly Through the Income Statement
The most valuable part of Bernstein's report is the stress test. It does not assume NAND prices stay high forever. Instead, it sets four market ASP downside scenarios and then observes how much EPS is retained under different LTA coverage rates. This is a severe test; the most extreme scenario is harsher than most past NAND cyclical downturns.
