
目录
Executive Summary
1. The $2,250 Price Target Is a Bet on a New Earnings Regime
2. What the Roughly $94 Billion in Long-Term Agreements Actually Locks In
3. AI Inference Is Turning NAND from a Storage Layer into Compute Infrastructure
4. BICS10 Makes Growth Less Dependent on Capacity Expansion; HBF Remains Future Optionality
5. Four Conditions Must Hold for an 80% Gross Margin
6. How JPMorgan Gets to $2,250
7. The Five Numbers to Watch Next
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
JPMorgan has reinstated coverage of SanDisk at “Overweight” with a $2,250 price target. The key question is whether long-term agreements can convert peak NAND profitability into sustainable cash flow.
Executive Summary
JPMorgan’s $2,250 price target is not merely an optimistic extrapolation of NAND spot prices. It assumes that 8 long-term agreements will transform SanDisk’s earnings model from pure price sensitivity to committed volumes, floor pricing, and floating upside.
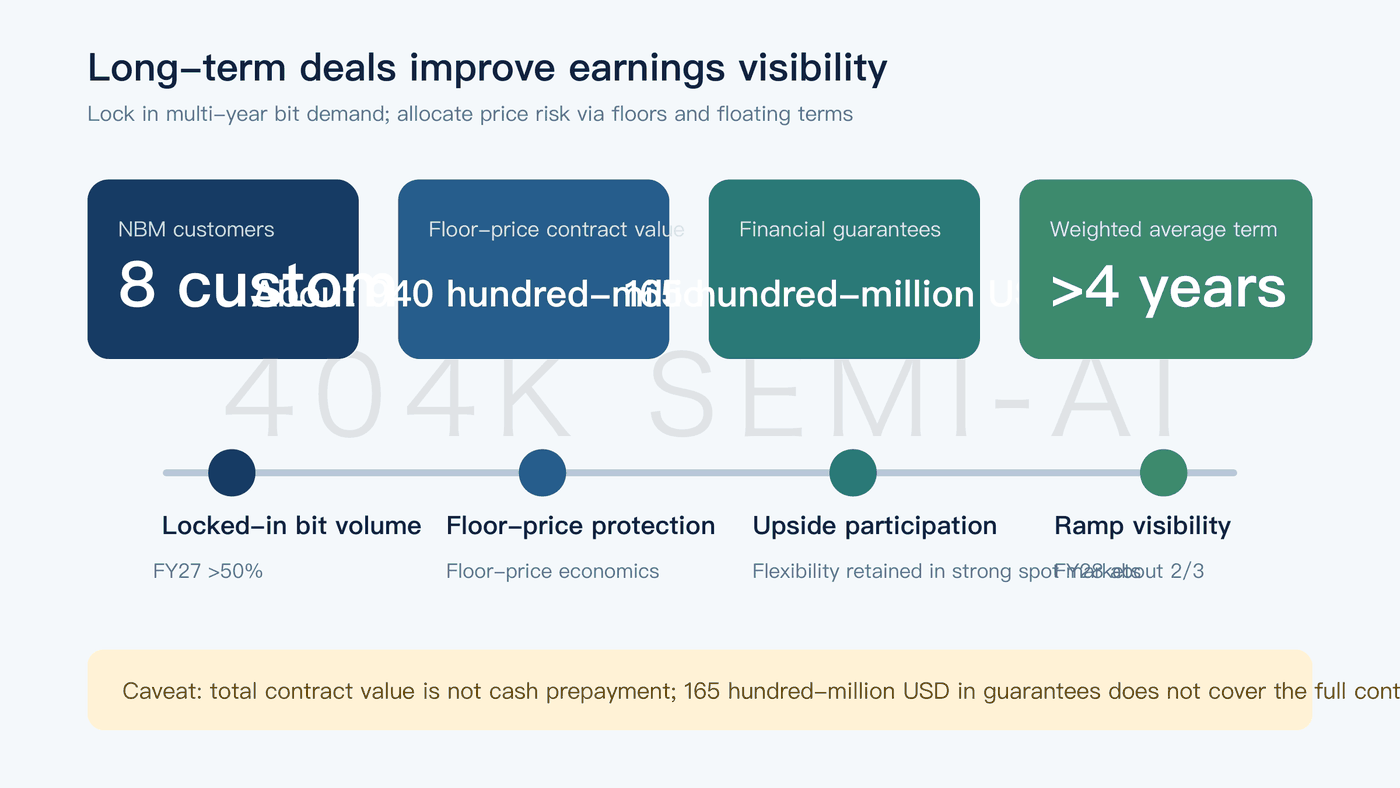
Roughly $94 billion in floor-value contracts, $16.5 billion in financial guarantees, and a weighted-average term exceeding 4 years materially improve visibility into shipments and production planning. However, they are not equivalent to full cash prepayment and do not eliminate performance, customer-concentration, or cost-inflation risks.
JPMorgan forecasts an 84.3% gross margin, $217.67 in adjusted EPS, and $27.866 billion in free cash flow for SanDisk in fiscal 2027. This model requires demand, supply discipline, technology-driven productivity, and share repurchases all to deliver simultaneously, leaving less room for error than the $2,250 target might suggest.
BICS10 represents tangible, trackable product progress. HBF’s 8-fold capital efficiency and 2-fold GPU efficiency remain simulation results. Until samples and customer adoption emerge in 2027, HBF should be treated as future optionality rather than current-period revenue.
1. The $2,250 Price Target Is a Bet on a New Earnings Regime
The report’s most important takeaway is not that JPMorgan raised its price target from SanDisk’s August 13 closing price of $1,528.11 to $2,250, but that its definition of “cyclicality” has changed. JPMorgan initiated coverage with a “Neutral” rating and a $235 price target; following the investor day, it reinstated coverage at “Overweight.” The two targets should not be read mechanically as a nearly 10-fold increase under the same model, because the timing, share price, earnings base, and company disclosures have all changed. Still, the shift in stance shows that sell-side analysts are beginning to treat long-term agreements as a structural variable rather than simply customers chasing supply at the top of the cycle.
In the traditional NAND model, rising prices drive high gross margins, high margins encourage capacity expansion, and new capacity ultimately pushes prices back down. JPMorgan now argues that long-term agreements give SanDisk visibility into a portion of its shipment volumes, floor prices, and customer capital commitments before the next bout of volatility arrives. If that thesis holds, investors will no longer need to wait for quarterly spot prices to assess profitability. That is the core rationale for shifting the valuation anchor from “peak EPS” to “predictable free cash flow.”
2. What the Roughly $94 Billion in Long-Term Agreements Actually Locks In
SanDisk has signed agreements with 8 customers representing roughly $94 billion in total contract value at floor prices, with a weighted-average term exceeding 4 years and approximately $16.5 billion in financial guarantees. Management also expects these agreements to cover more than 50% of bit shipments in fiscal 2027 and nearly two-thirds in fiscal 2028. Official presentation materials disclosed $59.8 billion in remaining performance obligations at quarter-end and $91.1 billion including post-quarter agreements. The latter broadly aligns with JPMorgan’s roughly $94 billion total-contract figure, although the two are not the same accounting metric.
These figures primarily lock in capacity planning and only secondarily revenue. With customers providing multiyear demand commitments and floor prices, SanDisk can plan wafers, assembly and testing, and product transitions more accurately, reducing the temptation to overexpand in anticipation of spot demand. Contract prices can float above the floor, preserving upside during strong pricing environments, while guarantees and performance provisions provide some protection during weaker periods.
