
Samsung Electronics Deep Update: 2Q26 Core Profit Beats, HBM4 Surpasses US$1 Billion, and Valuation Re-Rating After the First Smartphone Loss
目录
TL;DR
1. What This Update Really Changed: Headline KRW89.4 Trillion, Core Profit Above KRW100 Trillion
2. DRAM and NAND Margins Have Changed Shape: 80% and 64% Are Not Ordinary Cycle Numbers
III. HBM4 Breaks US$1 Billion: Samsung’s Catch-Up Validation Moves from “Qualification” to “Revenue”
IV. The First Smartphone Loss Is Bad News, but Also Hard Evidence of Memory Price Increases
V. Foundry and LSI Provide a Marginal Buffer, but Are Not Yet the Main Re-Rating Driver
VI. LTA Is the Valuation Core of the Next Stage: Can High Profit Become Visible Cash Flow?
VII. The KRW 480,000 Target Price Is Not Paying for One Beat, but for 2027 Earnings Visibility
VIII. Conclusion: Samsung Electronics Has Entered the Stage of “Profits Delivered, Contracts Awaiting Verification”
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
This Samsung Electronics update brings the contradiction to the surface: 2Q26 headline profit looks ordinary, but core profit after stripping out semiconductor bonus provisions has already exceeded KRW100 trillion; HBM4 is beginning to convert into revenue, while the smartphone business has been pushed into a loss for the first time by memory costs. The July 30 earnings call will determine how far the valuation re-rating can go.
TL;DR
Core profit is underestimated. Samsung Electronics’ headline operating profit this quarter was above consensus, but the semiconductor special bonus provision significantly depressed the reported figure. Goldman Sachs estimates that core operating profit excluding this expense was meaningfully higher than the headline number. The share-price pullback that day reflected a market still trading on “headline profit did not continue to see a large upward revision.” But the real focus should not be the surface-level difference; it should be that the memory business, under high pricing and high utilization, has already pushed margins to a new level.
DRAM and NAND have entered a high-margin phase. Goldman Sachs’ updated 2Q26 pricing assumptions show conventional DRAM ASP up 46% QoQ and NAND ASP up 66% QoQ; corresponding operating margins reached 80% for DRAM and 64% for NAND. This shows Samsung Electronics is not simply a single HBM catch-up story. DRAM, NAND, and HBM are simultaneously moving the memory business from cyclical recovery into a high-profit state.
HBM4 is starting to contribute real revenue. Goldman Sachs believes Samsung Electronics’ HBM business is better than expected. The key evidence is a smooth HBM4 ramp, with the company recently becoming the first to generate more than US$1 billion in HBM4 revenue. Goldman Sachs also sharply raised its 2027 HBM price assumptions and expects HBM prices next year to rise nearly 90% YoY. Under the old framework, the market worried Samsung was merely a “weaker version of SK Hynix.” The change in the new data is that Samsung is at least beginning to prove its catch-up progress with revenue and pricing.
The first smartphone loss is an important counter-proof. Goldman Sachs estimates that Samsung Electronics’ smartphone business posted an operating loss for the first time in 2Q26, as rising memory costs significantly compressed terminal-device margins. This bad news actually provides strong validation for memory price increases: pricing has become powerful enough to pressure the group’s internal downstream businesses. But it also defines the boundary condition: if memory price increases continue to raise costs for smartphone, PC, and server customers, demand destruction will become the largest valuation pressure in the next stage.
The valuation debate has shifted to contracts and cash flow. Goldman Sachs maintains a 12-month target price of KRW480,000 for the common shares, implying 62.2% upside versus the July 7 closing price of KRW296,000. It estimates Samsung Electronics trades at 5.3x 12-month forward P/E and 2.1x P/B. The market’s real debate is not a one-off earnings beat, but whether long-term agreements can turn high prices into visible cash flow, and whether free cash flow can further translate into shareholder returns.
Watch seven variables on the earnings call. The key for the July 30 2Q26 call is not whether management repeats that “memory demand is strong,” but the number of LTAs, contract duration, pricing structure, prepayment ratio, long-term capex, HBM4 guidance, supply-demand assessment, smartphone demand destruction, advanced foundry utilization, and capital allocation. As long as the two lines of contracts and cash returns are confirmed, Samsung Electronics’ valuation re-rating remains underway. If management provides only direction without constraints, near-term pullbacks will continue to recur.
1. What This Update Really Changed: Headline KRW89.4 Trillion, Core Profit Above KRW100 Trillion
The part of Samsung Electronics’ 2Q26 preliminary results most prone to misinterpretation is that headline operating profit was not meaningfully above Goldman Sachs’ prior forecast. The company reported 2Q26 operating profit of KRW89.4 trillion, versus Goldman Sachs’ prior forecast of KRW90.8 trillion and Bloomberg consensus of KRW85.9 trillion. If one looks only at this line, the market can say there was “no surprise,” which was also the direct reason for the 7% share-price pullback that day.
The real incremental information lies in the bonus provision. Goldman Sachs estimates that Samsung Electronics’ semiconductor division booked more than KRW15 trillion in special bonus provisions during the quarter. Excluding this item, core operating profit exceeded KRW100 trillion. In other words, what the market saw that day was a headline figure depressed by a one-off expense, while the memory business delivered a different level of profit intensity.
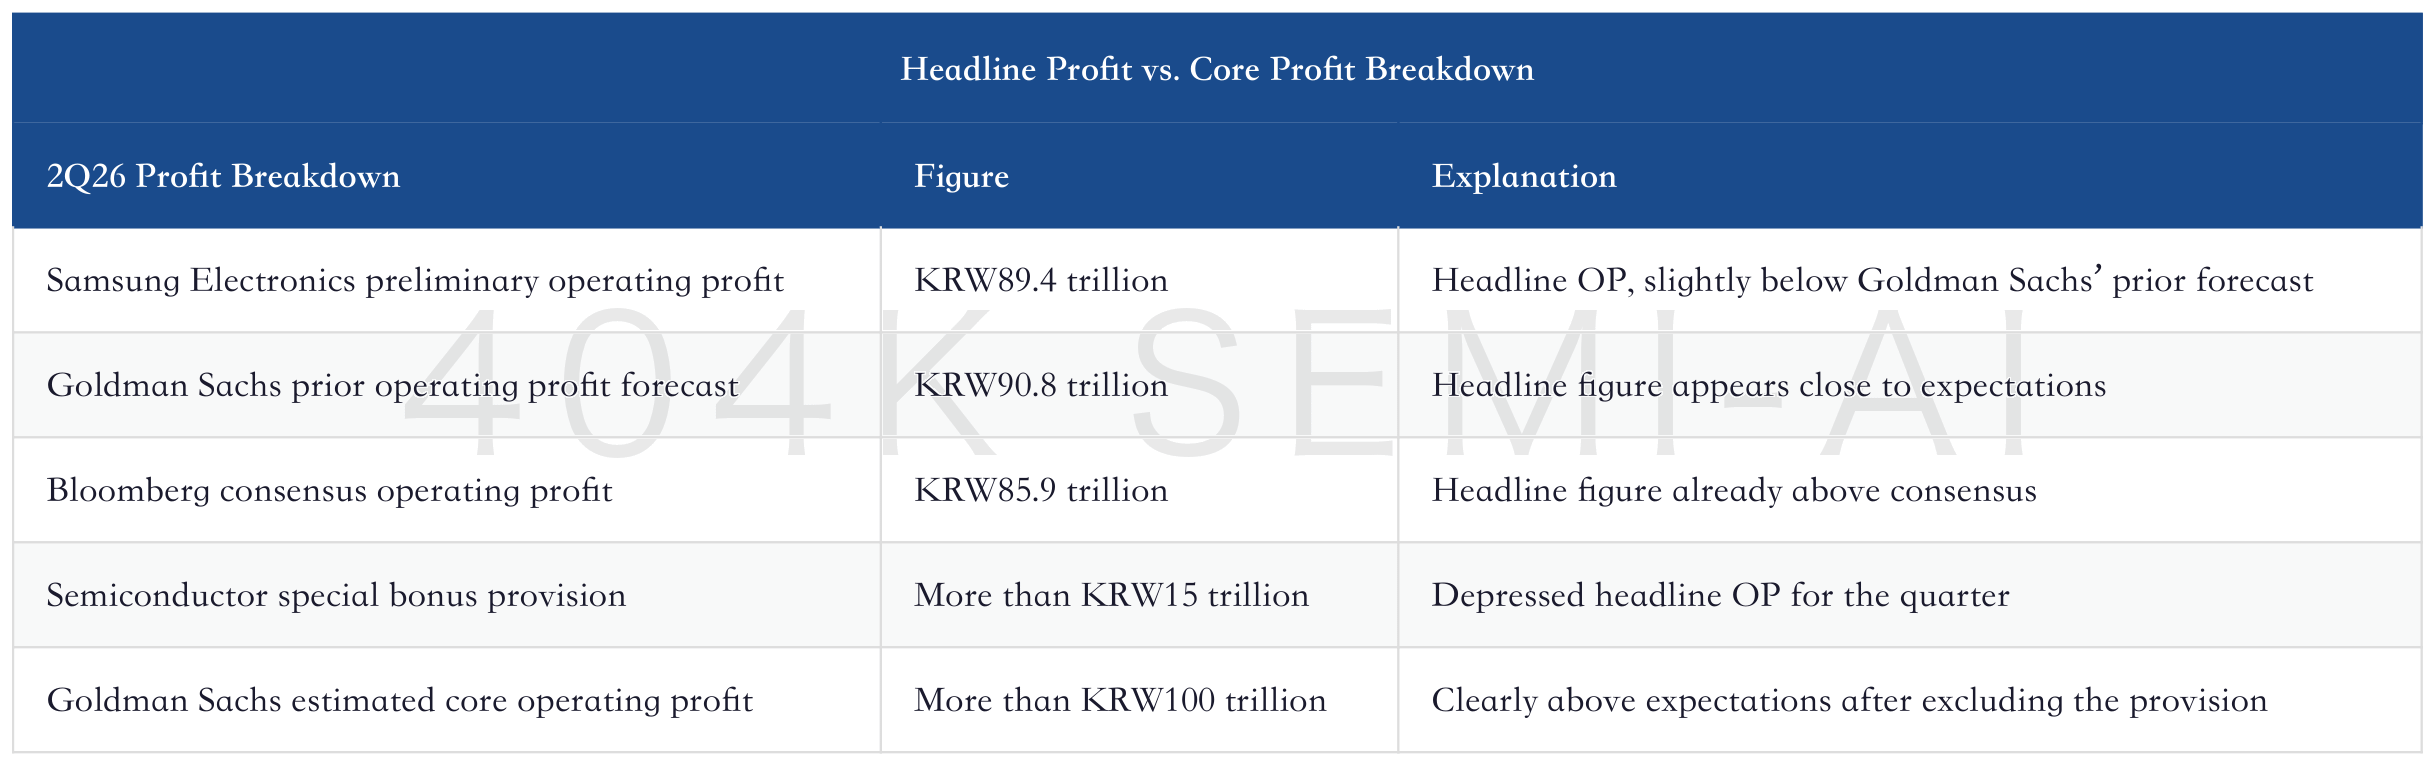
This breakdown pulls Samsung Electronics’ valuation issue back to memory pricing power. If the profit beat is merely a one-time expense reclassification, the valuation should not change. If core profit has already moved above KRW100 trillion and is jointly driven by DRAM and NAND pricing, HBM4 revenue, and LTA contracts, then the market needs to reassess Samsung Electronics’ cyclical position.
In the previous Samsung update, the core conclusion was that Samsung should not be treated only as a “laggard catching up in HBM”; its value comes from the breadth of DRAM, NAND, and HBM. The new report pushes that framework one step further: the three lines are not merely recovering; they have already begun to deliver profit simultaneously.
2. DRAM and NAND Margins Have Changed Shape: 80% and 64% Are Not Ordinary Cycle Numbers
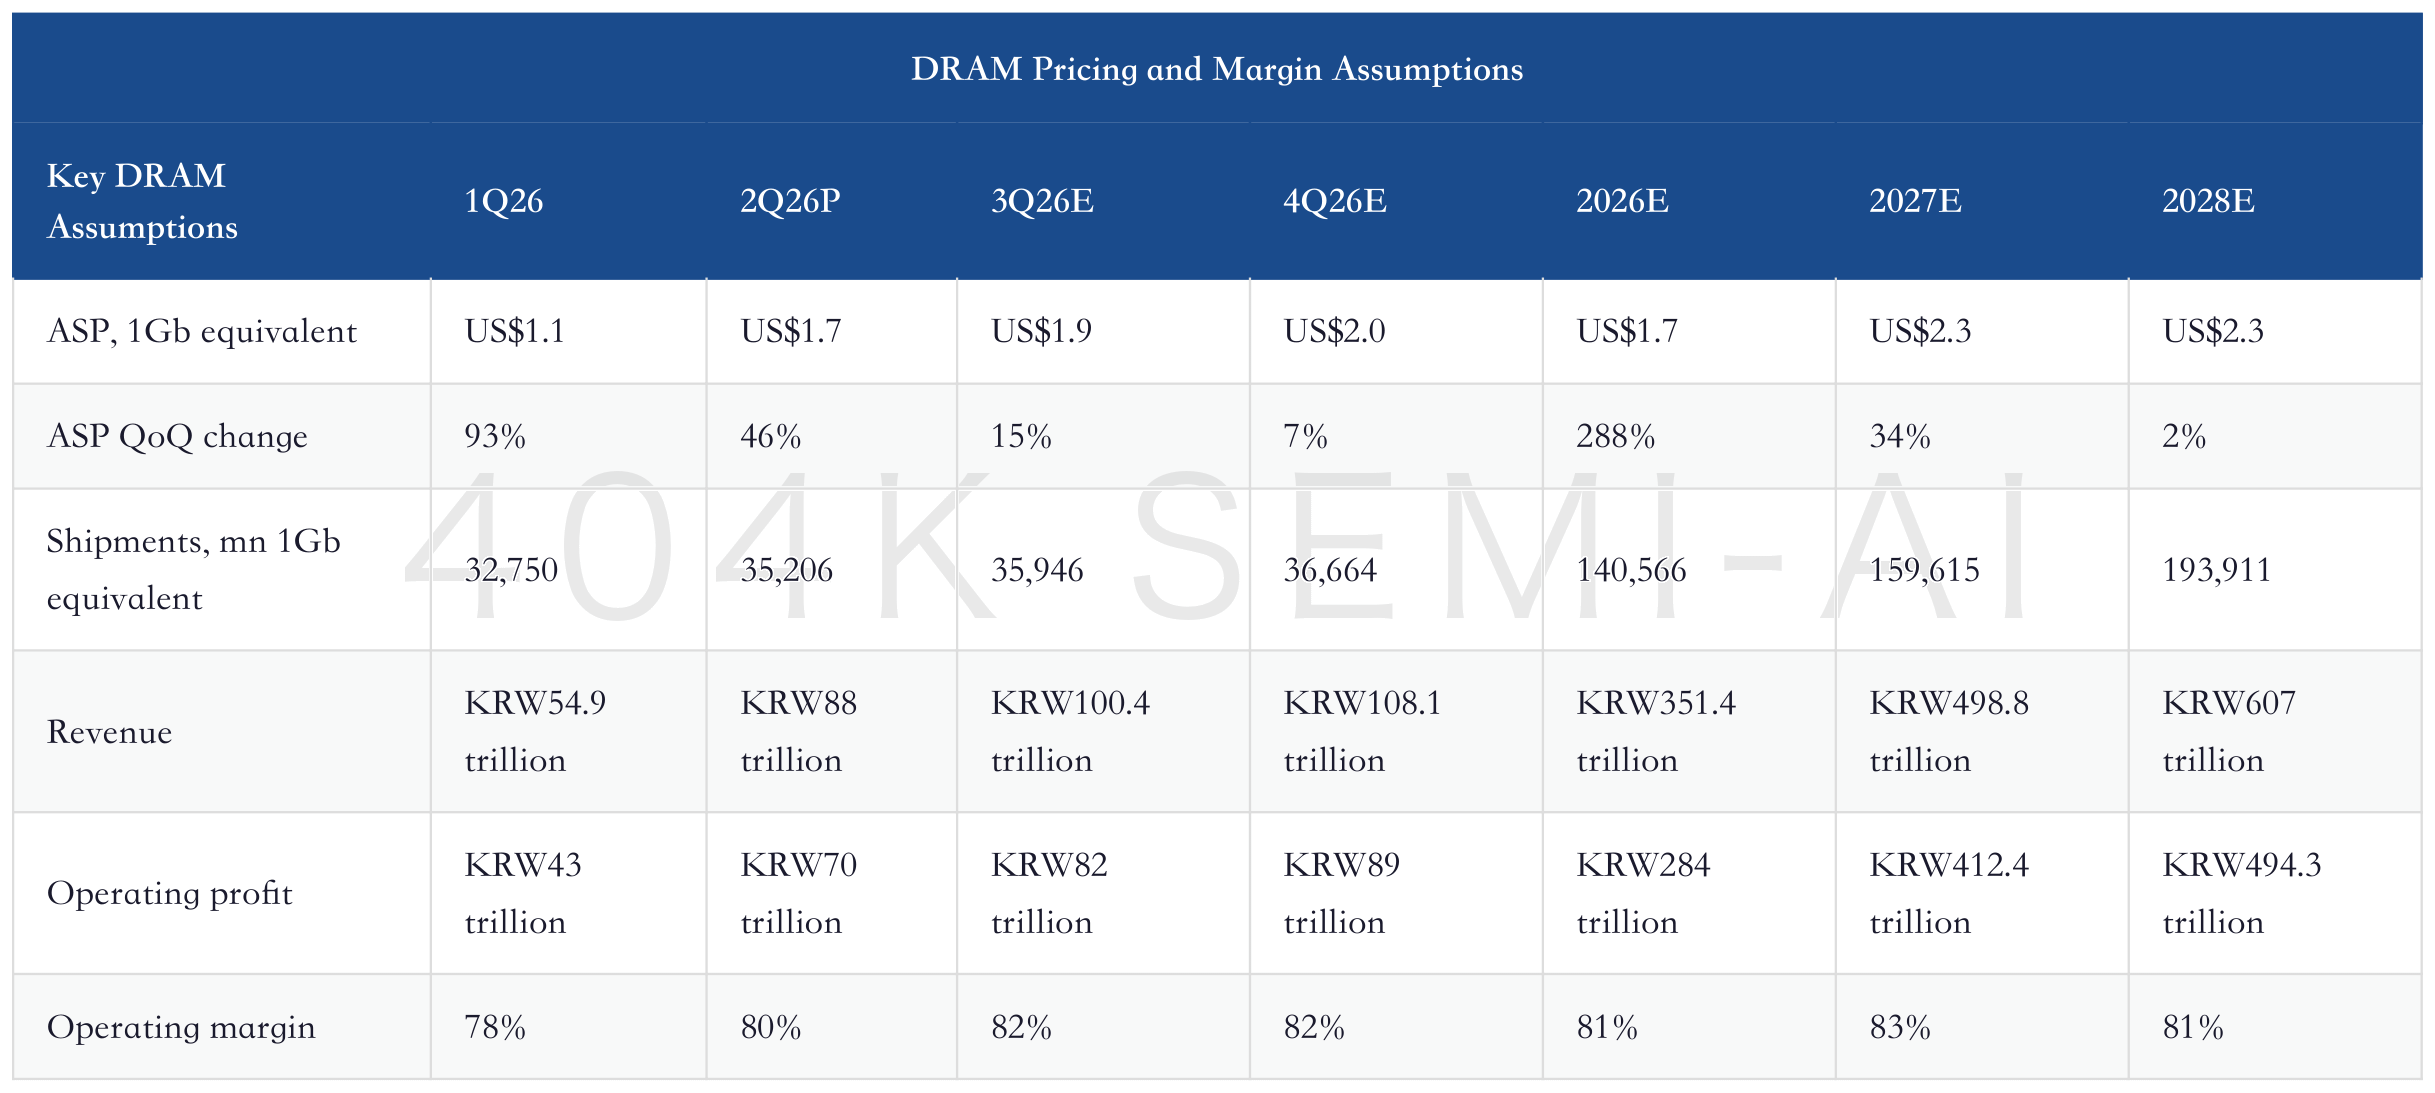
DRAM is the first driver of this core profit beat. Goldman Sachs raised both conventional DRAM pricing and margin assumptions. The key numbers are shown in the table below: price slope, revenue, operating profit, and margin all move higher at the same time, indicating this is not simply a shipment improvement.
The significance of this margin is substantial. In the past, Samsung Electronics was often assigned a lower multiple by the market because it had drags from foundry, display, and smartphones, while its HBM share lagged SK Hynix. But once the DRAM segment’s margin reaches 80%, Samsung Electronics is no longer gaining valuation elasticity only from HBM optionality. Conventional server DRAM itself is already generating margins close to those of a monopolistic segment.
The NAND change is even easier to underestimate. The market usually sees NAND as a category that is more fragmented, more cyclical, and less sustainably profitable than DRAM. But in Goldman Sachs’ 2Q26 update, NAND ASP rose 66% QoQ and operating margin reached 64%; 2026E and 2027E operating margins are 66% and 68%, respectively. This means Samsung Electronics’ NAND is not merely recovering from a trough, but re-entering a high-profit range under AI data-center SSD demand, enterprise SSD restocking, and supply constraints.
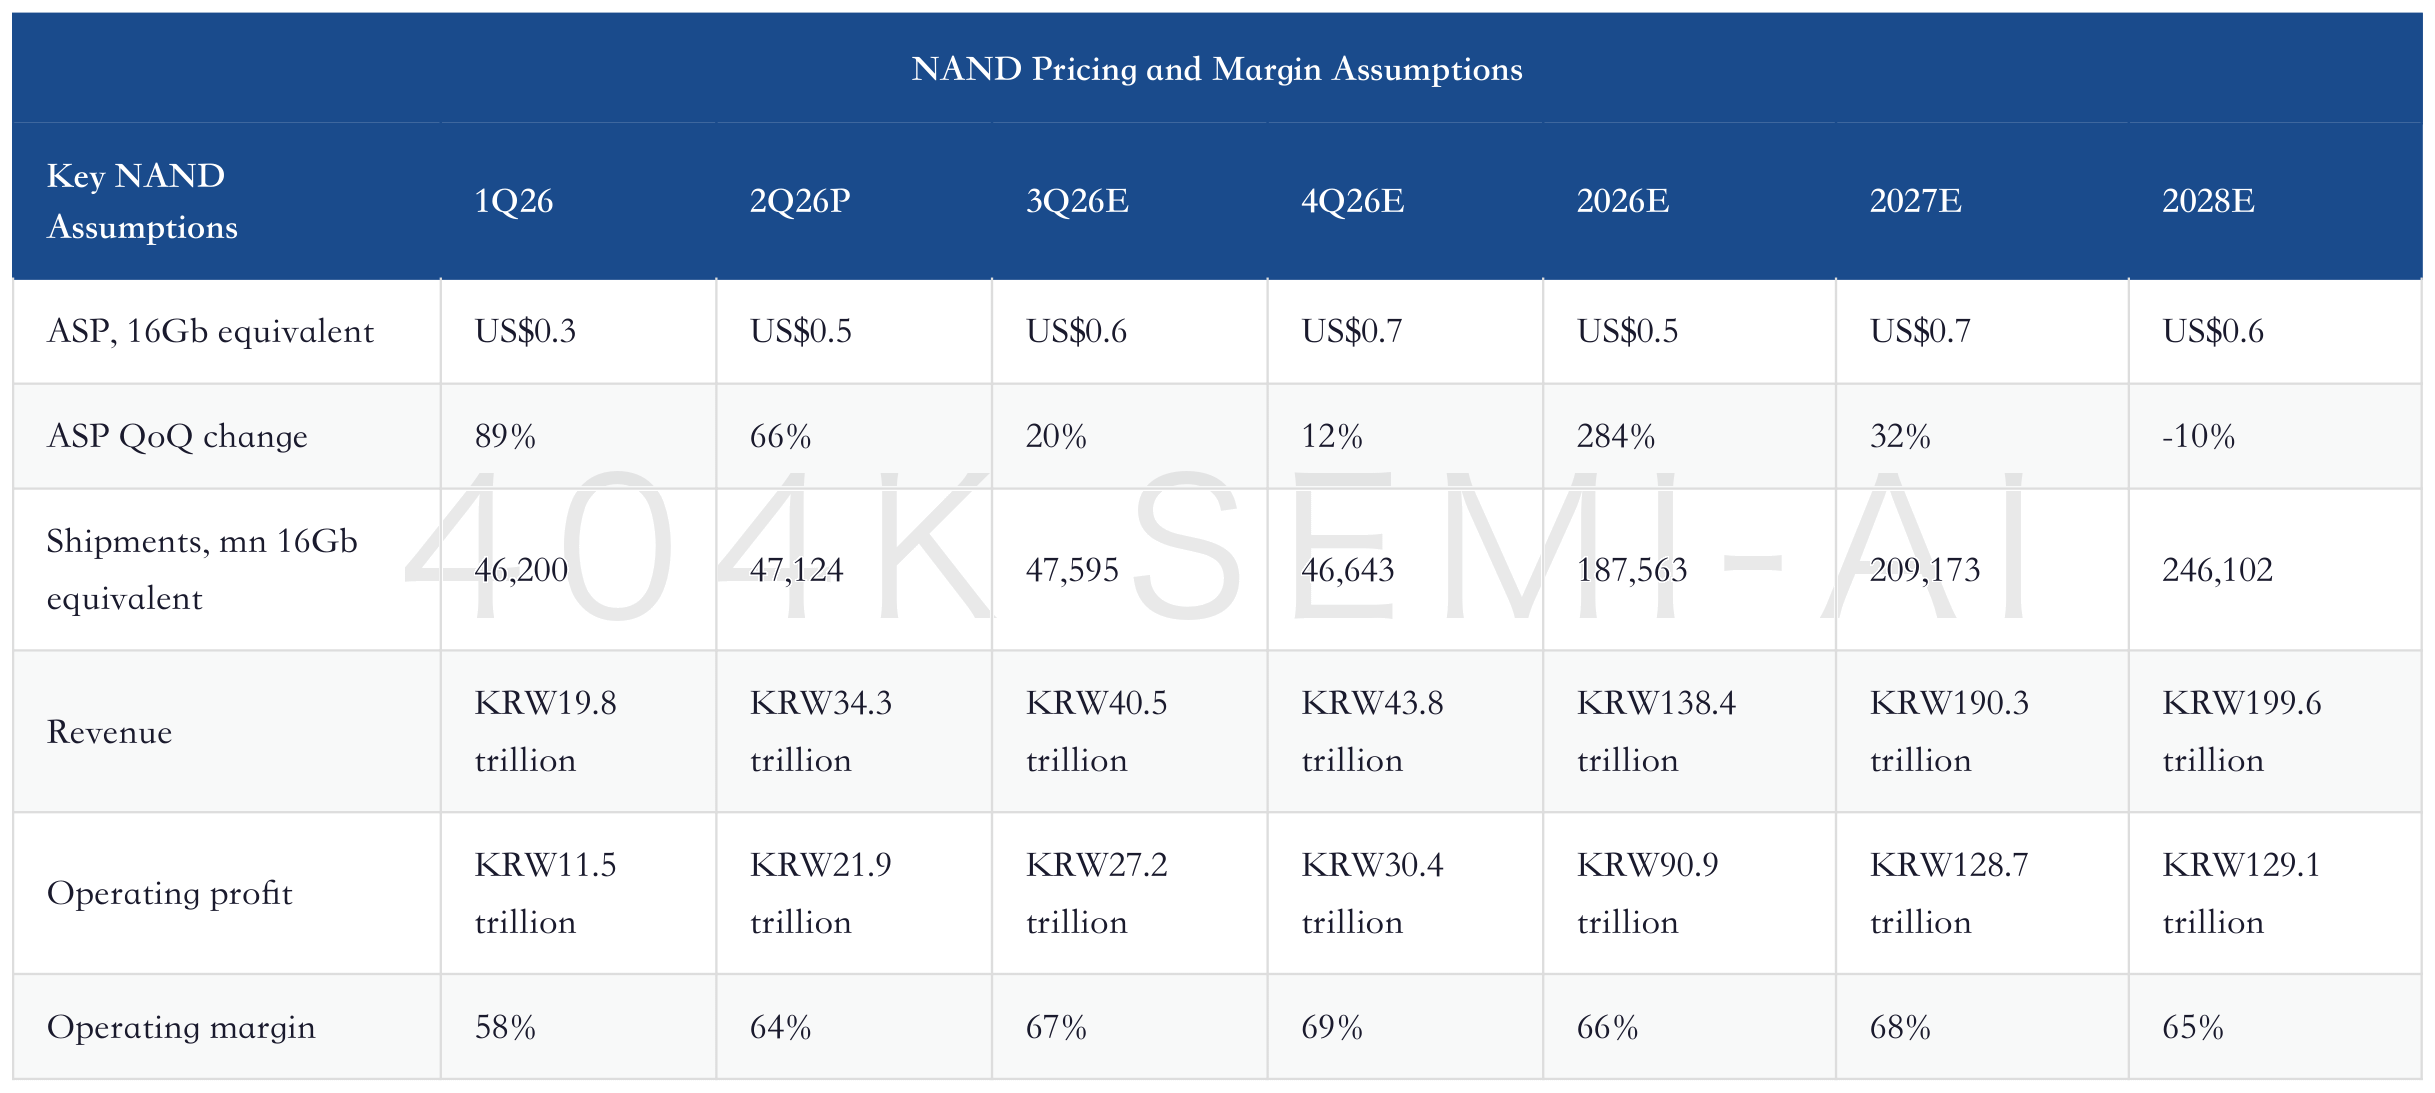
The conclusion from these two tables is direct: Samsung Electronics’ core asset today is not HBM alone, but a full memory balance sheet. DRAM provides profit elasticity, NAND provides cyclical breadth, and HBM provides multiple migration. When all three strengthen at the same time, using an old-cycle stock multiple to compress Samsung Electronics will run into margins that are difficult to explain away.
This is also the difference between this round of memory re-rating and past cyclical rebounds. In past memory price upcycles, investors mainly worried about supply coming back, prices falling, and profits reversing. This time, behind high prices are AI servers, HBM, enterprise SSDs, long-term agreements, and customer prepayments. If these mechanisms hold, Samsung Electronics’ high-margin duration will be longer than in a traditional cycle.
III. HBM4 Breaks US$1 Billion: Samsung’s Catch-Up Validation Moves from “Qualification” to “Revenue”
Samsung Electronics’ HBM has long been where the market applies a discount. SK hynix’s first-mover advantage in high-end HBM has been too obvious, while Samsung Electronics’ story in the past was mostly about “qualification progress,” “customer adoption,” and “capacity catch-up.” The change highlighted in this Goldman Sachs report is that Samsung Electronics’ HBM4 business is better than expected, HBM4 ramp is proceeding smoothly, and the company recently became the first to generate more than US$1 billion in HBM4 revenue.
US$1 billion is not the end point, but it has three implications.
First, it pulls HBM4 out of the technology narrative and into the revenue statement. Once revenue begins to appear, shipments, pricing, customers, yields, and orders can be continuously verified. Investors no longer have to rely only on management language.
Second, it explains why Goldman Sachs materially raised its 2027 HBM pricing assumptions. Goldman Sachs now expects Samsung Electronics’ HBM price to rise by nearly 90% YoY in 2027. This is not ordinary DRAM inflation, but an expansion of the structural premium for high-end AI memory.
Third, it turns the gap between Samsung Electronics and SK hynix into a dynamic question. The market can still continue to assign hynix a higher purity premium, but if Samsung Electronics delivers on both HBM4 revenue and pricing, Samsung’s discount will be compressed.
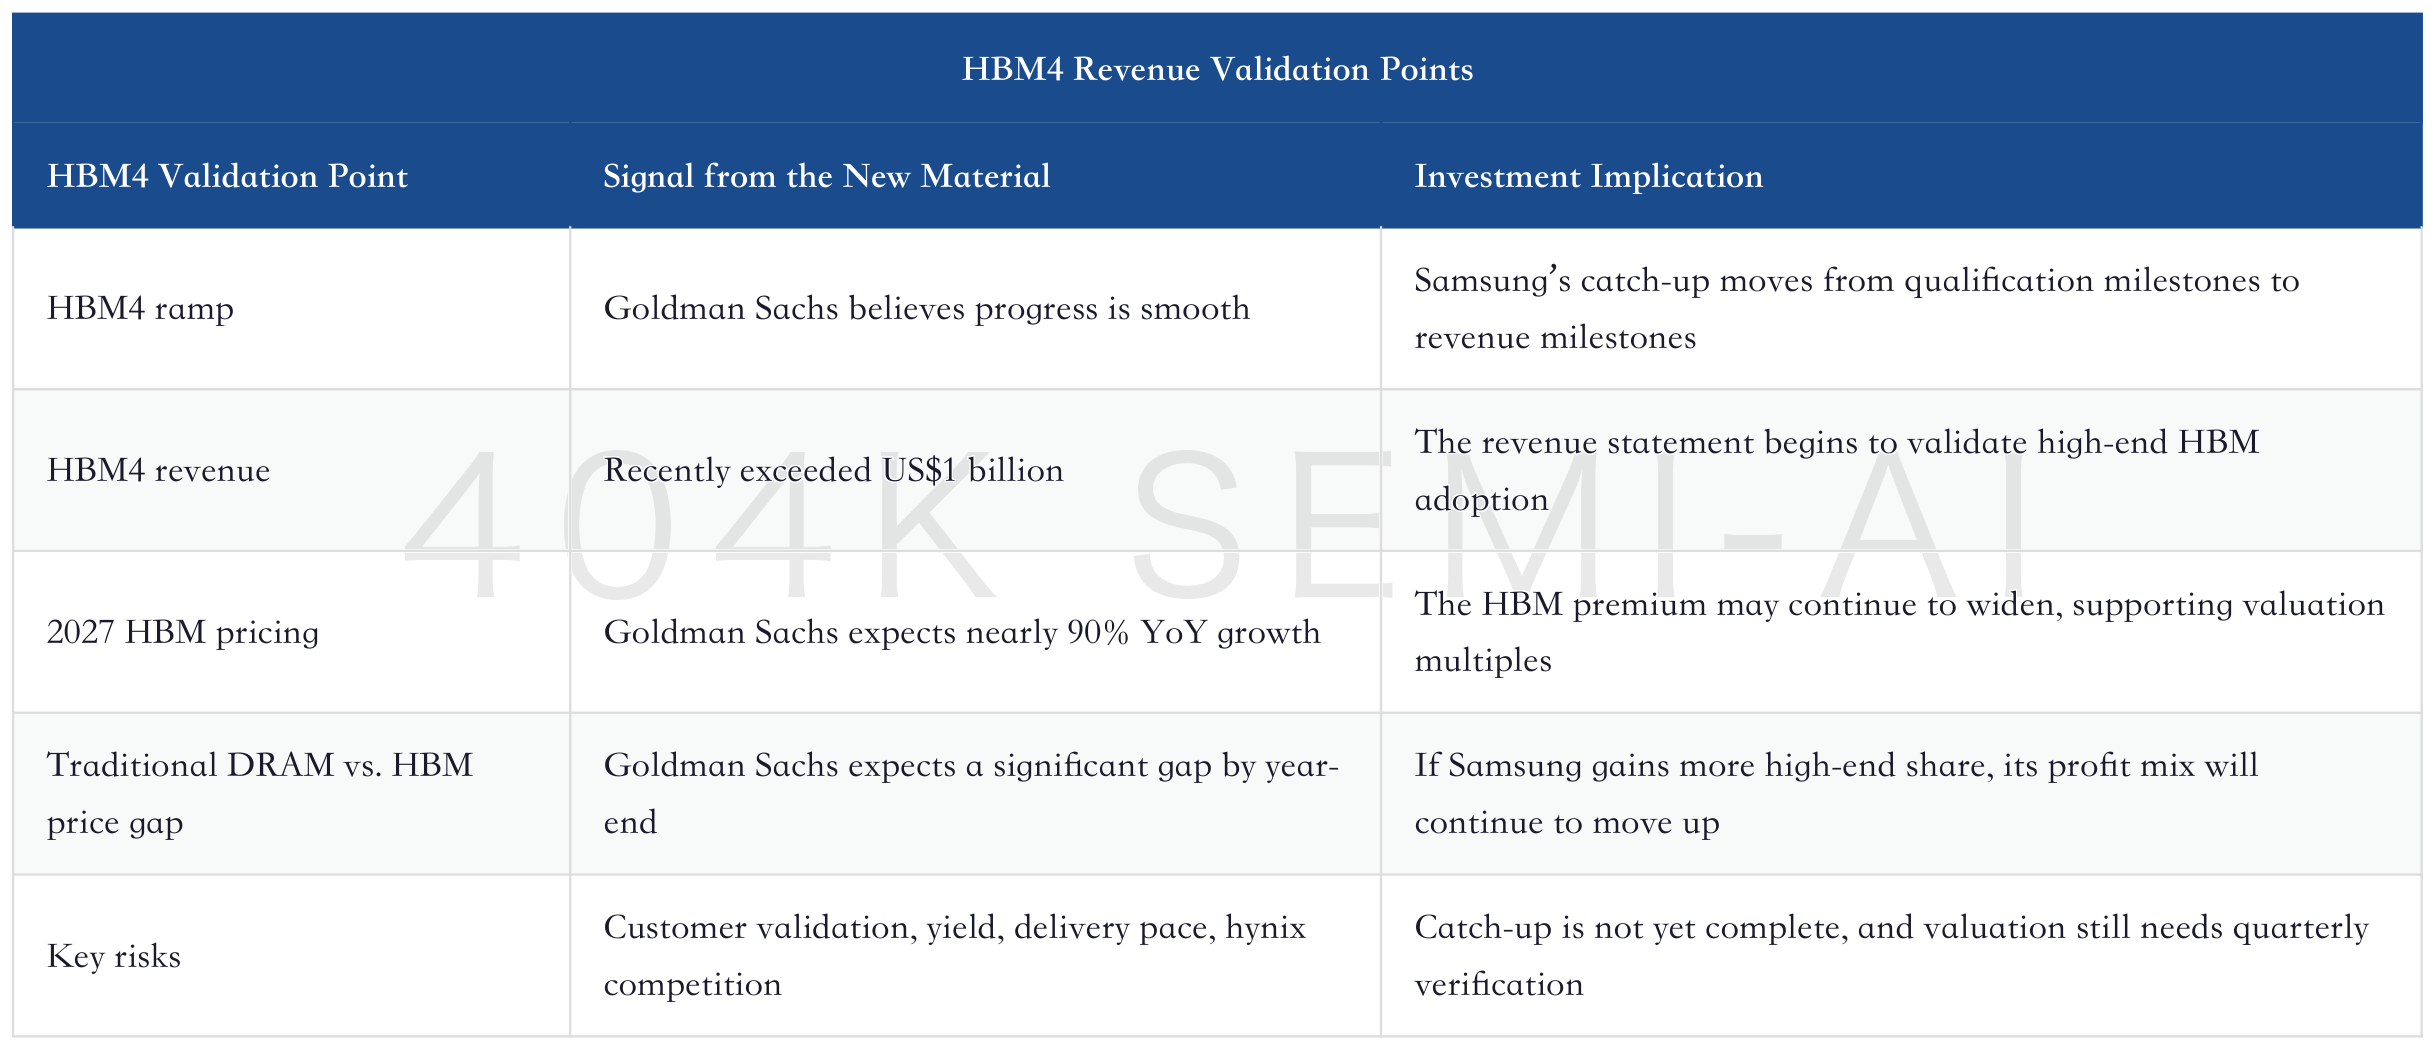
This is also the part of Samsung Electronics that most resembles an “asset re-rating.” High profits in DRAM and NAND can explain current-year EPS, while HBM4 revenue and pricing slope explain the future multiple. Whether the market is willing to view Samsung as an AI memory platform rather than a cyclical stock depends on whether HBM4 can continue moving from US$1 billion in revenue toward higher customer share.
IV. The First Smartphone Loss Is Bad News, but Also Hard Evidence of Memory Price Increases
Goldman Sachs estimates that Samsung Electronics’ smartphone business posted its first operating loss in 2Q26, with the DX division generating an operating loss of KRW 450bn, MX/NW losing KRW 320bn, Mobile losing KRW 380bn, and Handset losing KRW 480bn. The reason is direct: rising memory costs materially squeezed end-device margins.
This information is important because it sends two opposing signals at the same time.
First, memory price increases are genuinely strong. Samsung Electronics is one of the few global companies with both memory and smartphone businesses. If even its internal smartphone business has been pushed into losses by memory costs, it shows that price increases have already moved from supplier quotes into end-device manufacturers’ income statements, rather than remaining only in spot prices or sell-side models.
Second, demand destruction is coming into view. Continued increases in memory prices will strengthen Samsung Electronics’ memory profits, but they will also squeeze BOM costs for smartphone, PC, and server customers. Once customers’ income statements come under enough pressure, delayed demand, lower configurations, procurement negotiations, and alternatives will reappear.
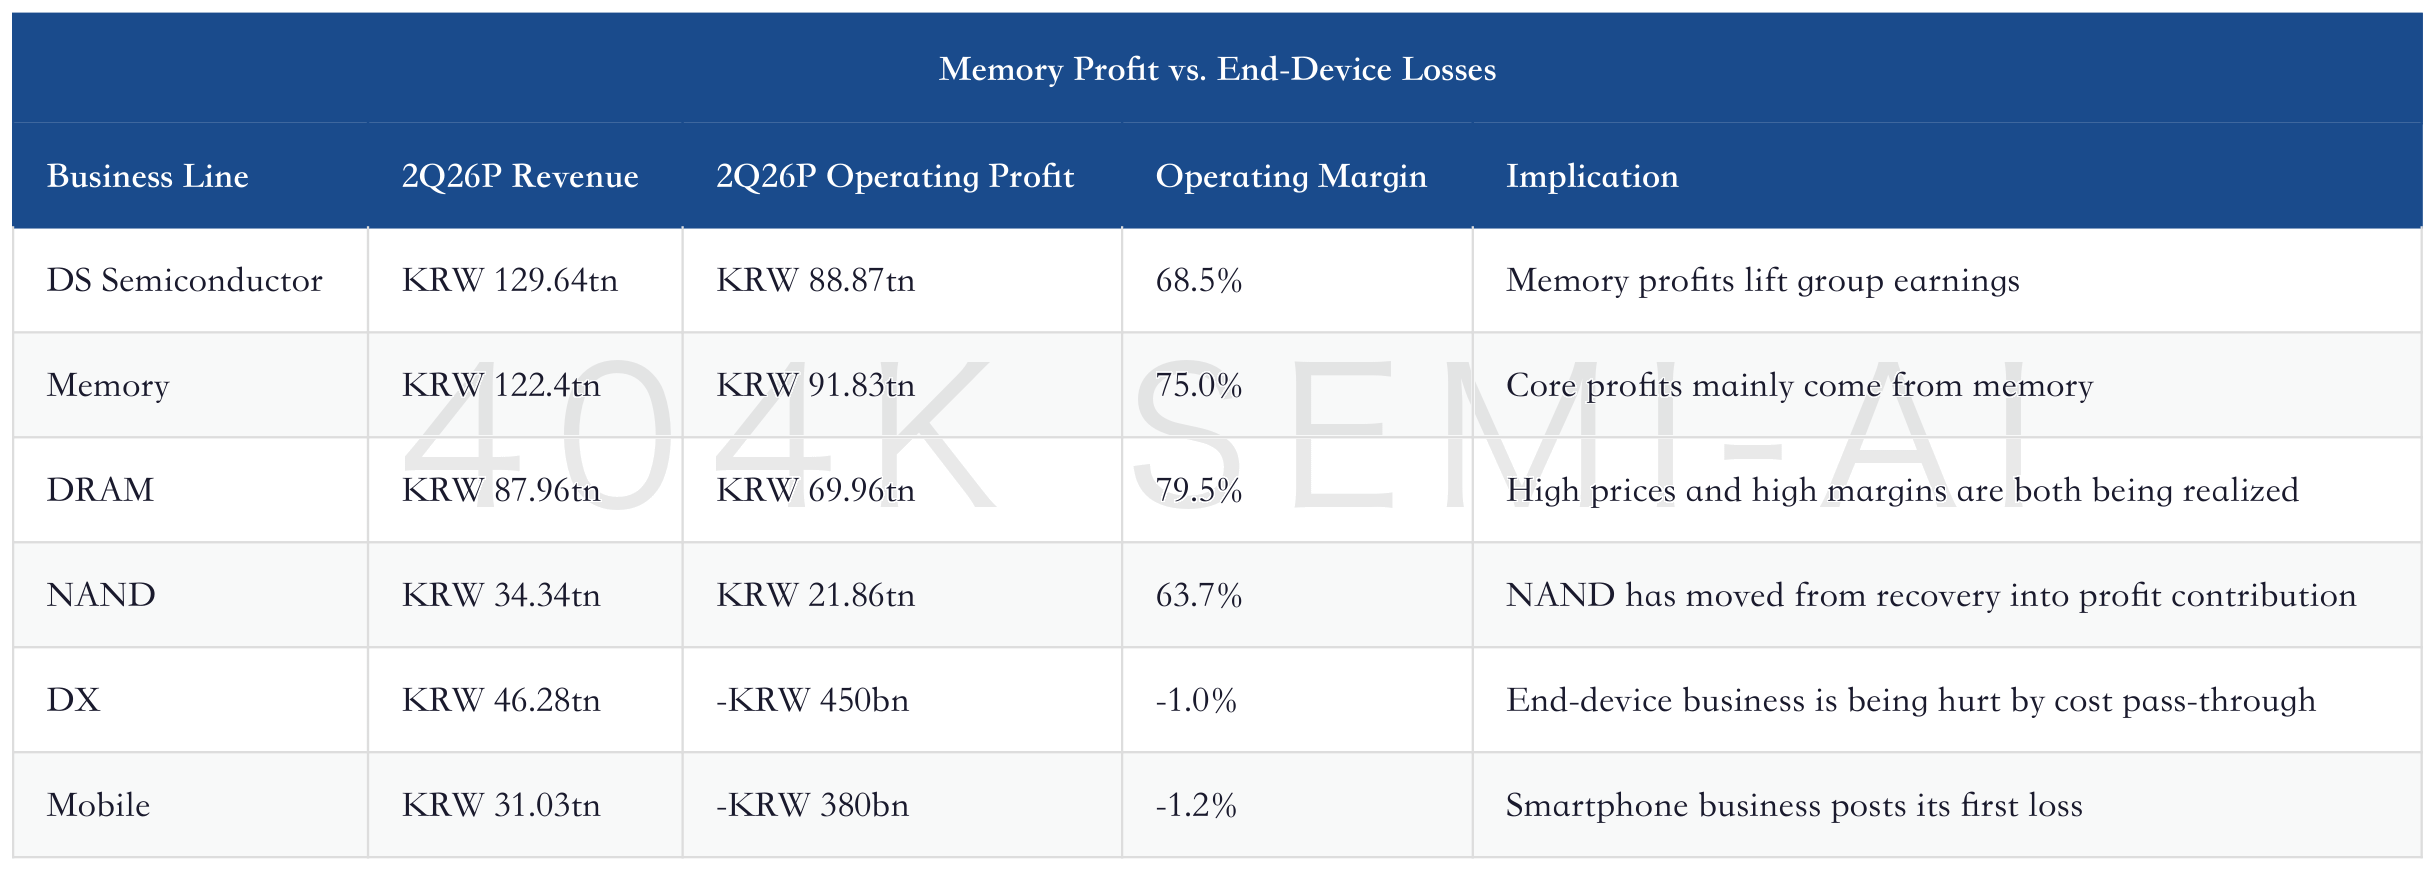
Therefore, this Samsung Electronics update should not simply be written as “memory is too strong.” A more accurate investment judgment is that memory is strong enough to start hurting downstream customers. Supplier profits have entered a high-margin phase, but downstream tolerance will become the ceiling for the next leg of the trade.
