Samsung Electronics Deep-Dive Update: 60%–70% of Memory Capacity Locked into Long-Term Agreements—Why Higher Earnings Forecasts Still Led to a Price-Target Cut to KRW400,000
目录
TL;DR
I. Higher Earnings Forecasts and a Lower Price Target Are Not Contradictory
II. With 60%–70% of Capacity Locked into Long-Term Agreements, the Cycle Is First Being Rewritten at the Order Level
III. In 2Q26, Focus on Pricing Rather Than Shipments; NAND Is the Most Easily Misread Thesis
IV. Catching Up in HBM4 Is Genuine Progress, but Not Yet Proof of a Technology Moat
V. DX Losses Are the Pressure Gauge for How Far Memory Price Increases Can Run
VI. Capital Returns Could Become a Catalyst, but Broadly Defined Cash Flow Should Not Be Treated as a Commitment
VII. What Could Undermine the KRW 400,000 Price Target: Six Indicators to Watch
VIII. Conclusion: LTAs Extend the Cycle; Valuation Rewards Delivery Alone
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
JPMorgan raised its 2026–2028 earnings forecasts while cutting the valuation multiple from 8x to 6x; whether long-term agreements can turn cyclical profits into multi-year cash flow is the real pillar supporting the KRW400,000 price target.
TL;DR
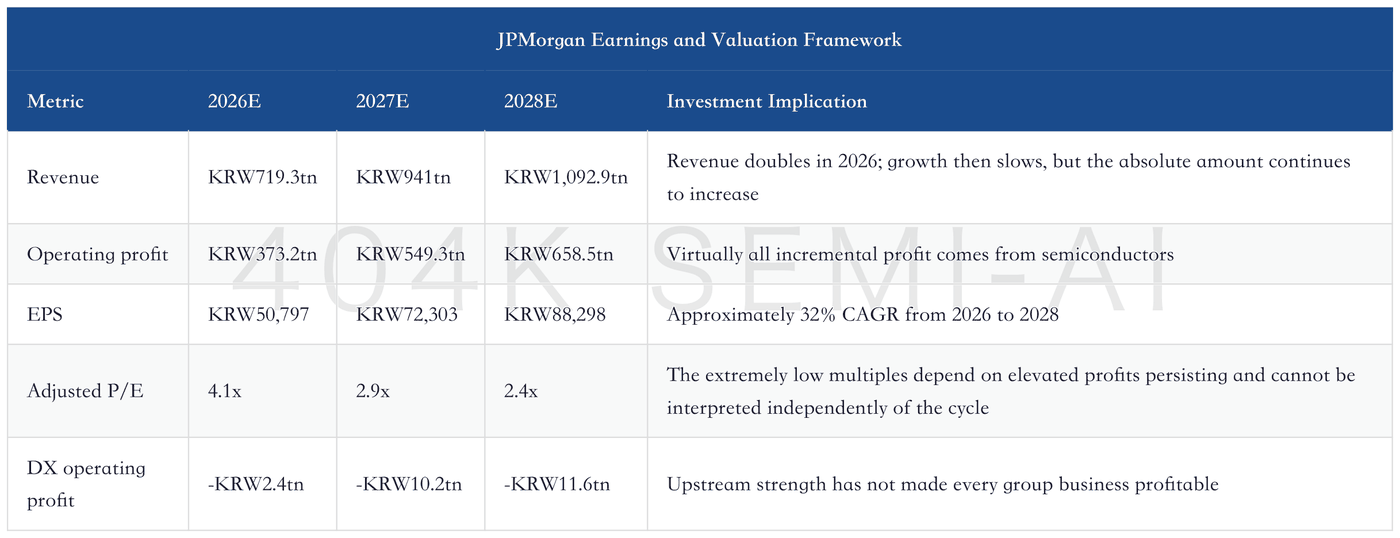
JPMorgan has not turned negative, but it cut its Samsung Electronics price target from KRW480,000 to KRW400,000. The new price target still carries an Overweight rating and implies approximately 90.9% upside from the July 30 share price of KRW209,500. The cut reflects a reduction in the next-12-month P/E multiple from 8x to 6x, rather than weaker earnings forecasts; JPMorgan instead raised its 2026–2028 EPS estimates to KRW50,797, KRW72,303, and KRW88,298.
Long-term agreements—not merely the current price increases—are what truly change the shape of the memory cycle. Samsung Electronics said that once all contracts are completed, 60%–70% of its total future DRAM and NAND capacity will be covered by long-term agreements, with a base term of 5 years, an annual 1-year extension option, and price floors. 5 major data-center customers have already signed contracts, while another 5 large AI customers are in final negotiations; prepayments received already exceed one-quarter of total contractual prepayments.
The 2Q26 profit surge was driven mainly by pricing; whether demand can absorb it must be validated next. DRAM bit shipments increased by low double digits QoQ, while average selling prices rose in the mid-40% range; NAND bit shipments grew only by low single digits, but average selling prices rose 60%. This explains DS’s operating margin of approximately 70%, while also identifying end demand as the most important risk for the next phase: smartphones, PCs, and other end products may reduce specifications, postpone procurement, or cut volumes because costs are too high.
NAND is shifting from a “potential surplus” into a capacity bottleneck for AI inference. JPMorgan believes KV cache is driving enterprise SSD demand, while Samsung Electronics expects enterprise SSDs to account for more than 60% of NAND sales in 2026, up from 40% in the prior year, with 2H26 QLC bit shipments doubling versus 1H. If long-term agreements and high-capacity products both deliver, NAND will no longer merely follow the DRAM upcycle; if B2C weakness spreads, the 60% quarterly price increase will also amplify the risk of a price correction.
Execution in HBM and foundry has indeed improved, but a “restored technology moat” has not yet been proven. Management said HBM4 accounts for well over 60% of 2H26 HBM revenue, while JPMorgan expects monthly HBM capacity to increase from approximately 220,000 wafers at end-2026 to approximately 280,000 wafers at end-2027; 2nm projects and advanced-node utilization are also improving. However, JPMorgan continues to question the company’s technology leadership at 1c nm and expects System LSI and Foundry to remain loss-making through 2027.
The biggest internal counterevidence for Samsung Electronics is the losses at DX and MX. JPMorgan revised its DX operating-profit forecasts for 2026–2028 from positive figures to losses of KRW2.4tn, KRW10.2tn, and KRW11.6tn, respectively. Memory price increases are pushing profits toward DS while eroding margins in smartphones, televisions, and home appliances; if the end-product businesses cannot raise prices, cut costs, or increase the share of premium products, the stronger the high-profit cycle becomes, the more visible the internal cost backlash across the group will be.
I. Higher Earnings Forecasts and a Lower Price Target Are Not Contradictory
Samsung Electronics’ 2Q26 results have already demonstrated that memory profits can reach extreme levels. The company reported group revenue of KRW171.5tn and operating profit of KRW89.5tn, with DS contributing approximately 99.7% of group operating profit, while DX recorded an operating loss of KRW800bn. The market debate has shifted to how long these elevated profits can last and what valuation multiple they deserve.
JPMorgan’s answer is measured: earnings will continue to grow, but valuation recovery will take time. The report maintained its Overweight rating and set a June 2027 price target of KRW400,000, equivalent to 6x next-12-month EPS from 3Q26E through 2Q27E. Under the report’s model, aggregate EPS for the four quarters is approximately KRW66,268; multiplied by 6x, this yields KRW397,608, broadly consistent with the KRW400,000 price target.
The 16.7% price-target cut from KRW480,000 primarily reflects a reduction in the target multiple from 8x to 6x. A 6x multiple is already at the upper end of the 4x–6x forward-P/E range historically observed at cyclical peaks for memory stocks. In other words, JPMorgan is willing to recognize that Samsung Electronics’ EPS could compound at more than 30% over the next two years, but is unwilling to assume that the market will immediately treat these profits as those of a stable growth stock.
This combination of “higher earnings and a lower multiple” encapsulates the valuation challenge for memory companies. When profits are elevated, forward P/E mechanically declines; if investors are concerned that pricing is peaking, a 2.9x or 2.4x forward P/E is not necessarily cheap. Only when long-term agreements, price floors, prepayments, and the customer mix demonstrate that earnings no longer fluctuate sharply with quarterly orders will a low multiple shift from a “cyclical-peak trap” into a genuine valuation floor.