
Samsung Electronics Deep-Dive Update: DRAM/NAND/HBM Three-Line Repair, Moving from Cyclical Rebound to Asset Re-Rating
目录
Too Long; Didn’t Read
1. What Recent Materials Have Really Changed
2. KRW 2,450tn of Investment: Moat or Next-Round Supply Risk
III. DDR5 64GB Server Modules: The Short-Term Price Anchor to Watch Most Closely
IV. HBM Material Imports: Physical Proxy Indicators Begin to Appear in the Catch-Up Story
V. NAND/eSSD: From Restocking Business to Inference Data Layer
VI. Korea Export Data: The Macro Surplus Is Underwriting Corporate Profit
VII. Valuation: The KRW 530,000 Target Price Buys Earnings Upgrades; Next Comes Multiple Migration
8. How Samsung Compares With SK Hynix, Micron, SanDisk, and Kioxia
9. Balance Sheet: High Profits Must Be Retained
10. Three Worldviews: Is KRW 530,000 a Peak Target or an Interim Stop?
XI. Core Model: Four Variables Determine Whether Samsung Can Be Re-rated
XII. How to Validate 2Q26 Results
XIII. Bear Case: The Biggest Risk Is Not Disappearing AI Demand
XIV. Tracking Checklist for the Next Four Quarters
XV. Conclusion: Samsung’s Re-rating Needs to Proceed in Three Steps
References
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Samsung Electronics’ core debate is not simply whether HBM can catch up with SK hynix. It is whether, after KRW 2,450tn of long-term investment, DDR5 server memory premiums, and HBM material imports all strengthen at the same time, the market can reprice Samsung from a memory-cycle stock into an AI-memory breadth asset, and assign a higher multiple for that breadth.
Too Long; Didn’t Read
Samsung’s trading anchor has broadened. Recent materials provide three new pieces of evidence at the same time: Goldman Sachs disclosed that Samsung will invest KRW 2,450tn domestically through 2040, of which about KRW 2,100tn will go into semiconductors; Citi raised its 4Q26E price forecast for 64GB DDR5 RDIMM to US$1,805; and Korea export data show Samsung’s HBM-related material imports rose 76% YoY. This means Samsung is no longer relying only on HBM qualification to repair its discount. Server DRAM, NAND/eSSD, and long-term capex are also entering the valuation framework together.
Server DRAM is the near-term profit key. Citi raised its 2026 global DRAM and NAND ASP growth forecasts to 234% and 236%, and raised Samsung’s 2026/2027 operating-profit forecasts to KRW 401tn/KRW 517tn. What truly matters is not the target price increase from KRW 460k to KRW 530k, but that 64GB DDR5 RDIMM is moving from US$1,310 in 2Q26E toward US$1,805 in 4Q26E, providing the most direct validation line for the next two quarters’ income statements.
KRW 2,450tn of investment is not simply negative capacity expansion. Goldman estimates that if R&D; is included, Samsung’s domestic capex and R&D; over the next 15 years would equal about KRW 163tn per year, implying a long-term growth rate of about 5-6% for 2029-2040, which is not aggressive. The risk is not the size of investment, but whether the money goes into HBM, advanced DRAM, SOCAMM2, eSSD, and customer-locked supply capacity. If commodity capacity is released first, the re-rating will again be capped by a cyclical discount.
HBM material imports add physical evidence to the catch-up story. Korea tech export tracking shows imports of plastic films from Japan to Hwaseong/Pyeongtaek rose 76% YoY in May and 61% YoY from the start of the year through May. Goldman views this as a proxy for Samsung’s HBM shipment scale. This data cannot replace key customer qualification, but it reduces the bear-case pressure that “HBM remains only a story,” and also explains why 2027 HBM price expectations have been raised to 44% YoY growth.
NAND/eSSD can no longer be treated under the old cycle framework. TrendForce expects enterprise SSD prices to rise 18-23% QoQ in 3Q26, while Citi expects SSD prices to rise 330% YoY in 2026 and NAND ASPs to rise 236% YoY. If AI inference demand for KV cache, retrieval, and data caching continues to expand, Samsung’s NAND is no longer merely a weak-cycle business dragging on group valuation, but a second profit curve tied to server storage and the inference data layer.
Samsung is a breadth trade, not a purity trade. SK hynix is more like an HBM quality premium, Micron more like the US-listed AI memory entry point, and SanDisk and Kioxia more like NAND beta. Samsung’s difference is that DRAM, HBM, NAND/eSSD, SOCAMM2, display, and foundry synergies all sit on the same balance sheet. This breadth can improve fault tolerance, but it also brings capex and execution complexity. Going forward, investors need to track server DRAM pricing, HBM customer feedback, eSSD orders, and cash returns at the same time.
1. What Recent Materials Have Really Changed
The core of the recent incremental information on Samsung Electronics is not that there is yet another bullish memory report. It is that Samsung’s three validation lines have all become firmer at the same time: long-term investment, server DRAM pricing, and physical proxy indicators for HBM capacity ramp. These three lines correspond respectively to long-term supply, margin of safety, and AI product multiples in valuation.
In the past, the most common question on Samsung was whether HBM could catch up with SK hynix. This question remains important, but it makes the Samsung story too narrow. Samsung is not a pure HBM company. It is a heavy-asset platform spanning server DRAM, HBM, NAND/eSSD, smartphones, display, and some foundry synergy. Valuing it only on HBM share would underestimate its breadth in AI server system memory and the inference data layer, and also underestimate the impact of capex discipline on the valuation discount.
The changes in recent materials can first be condensed into one table.
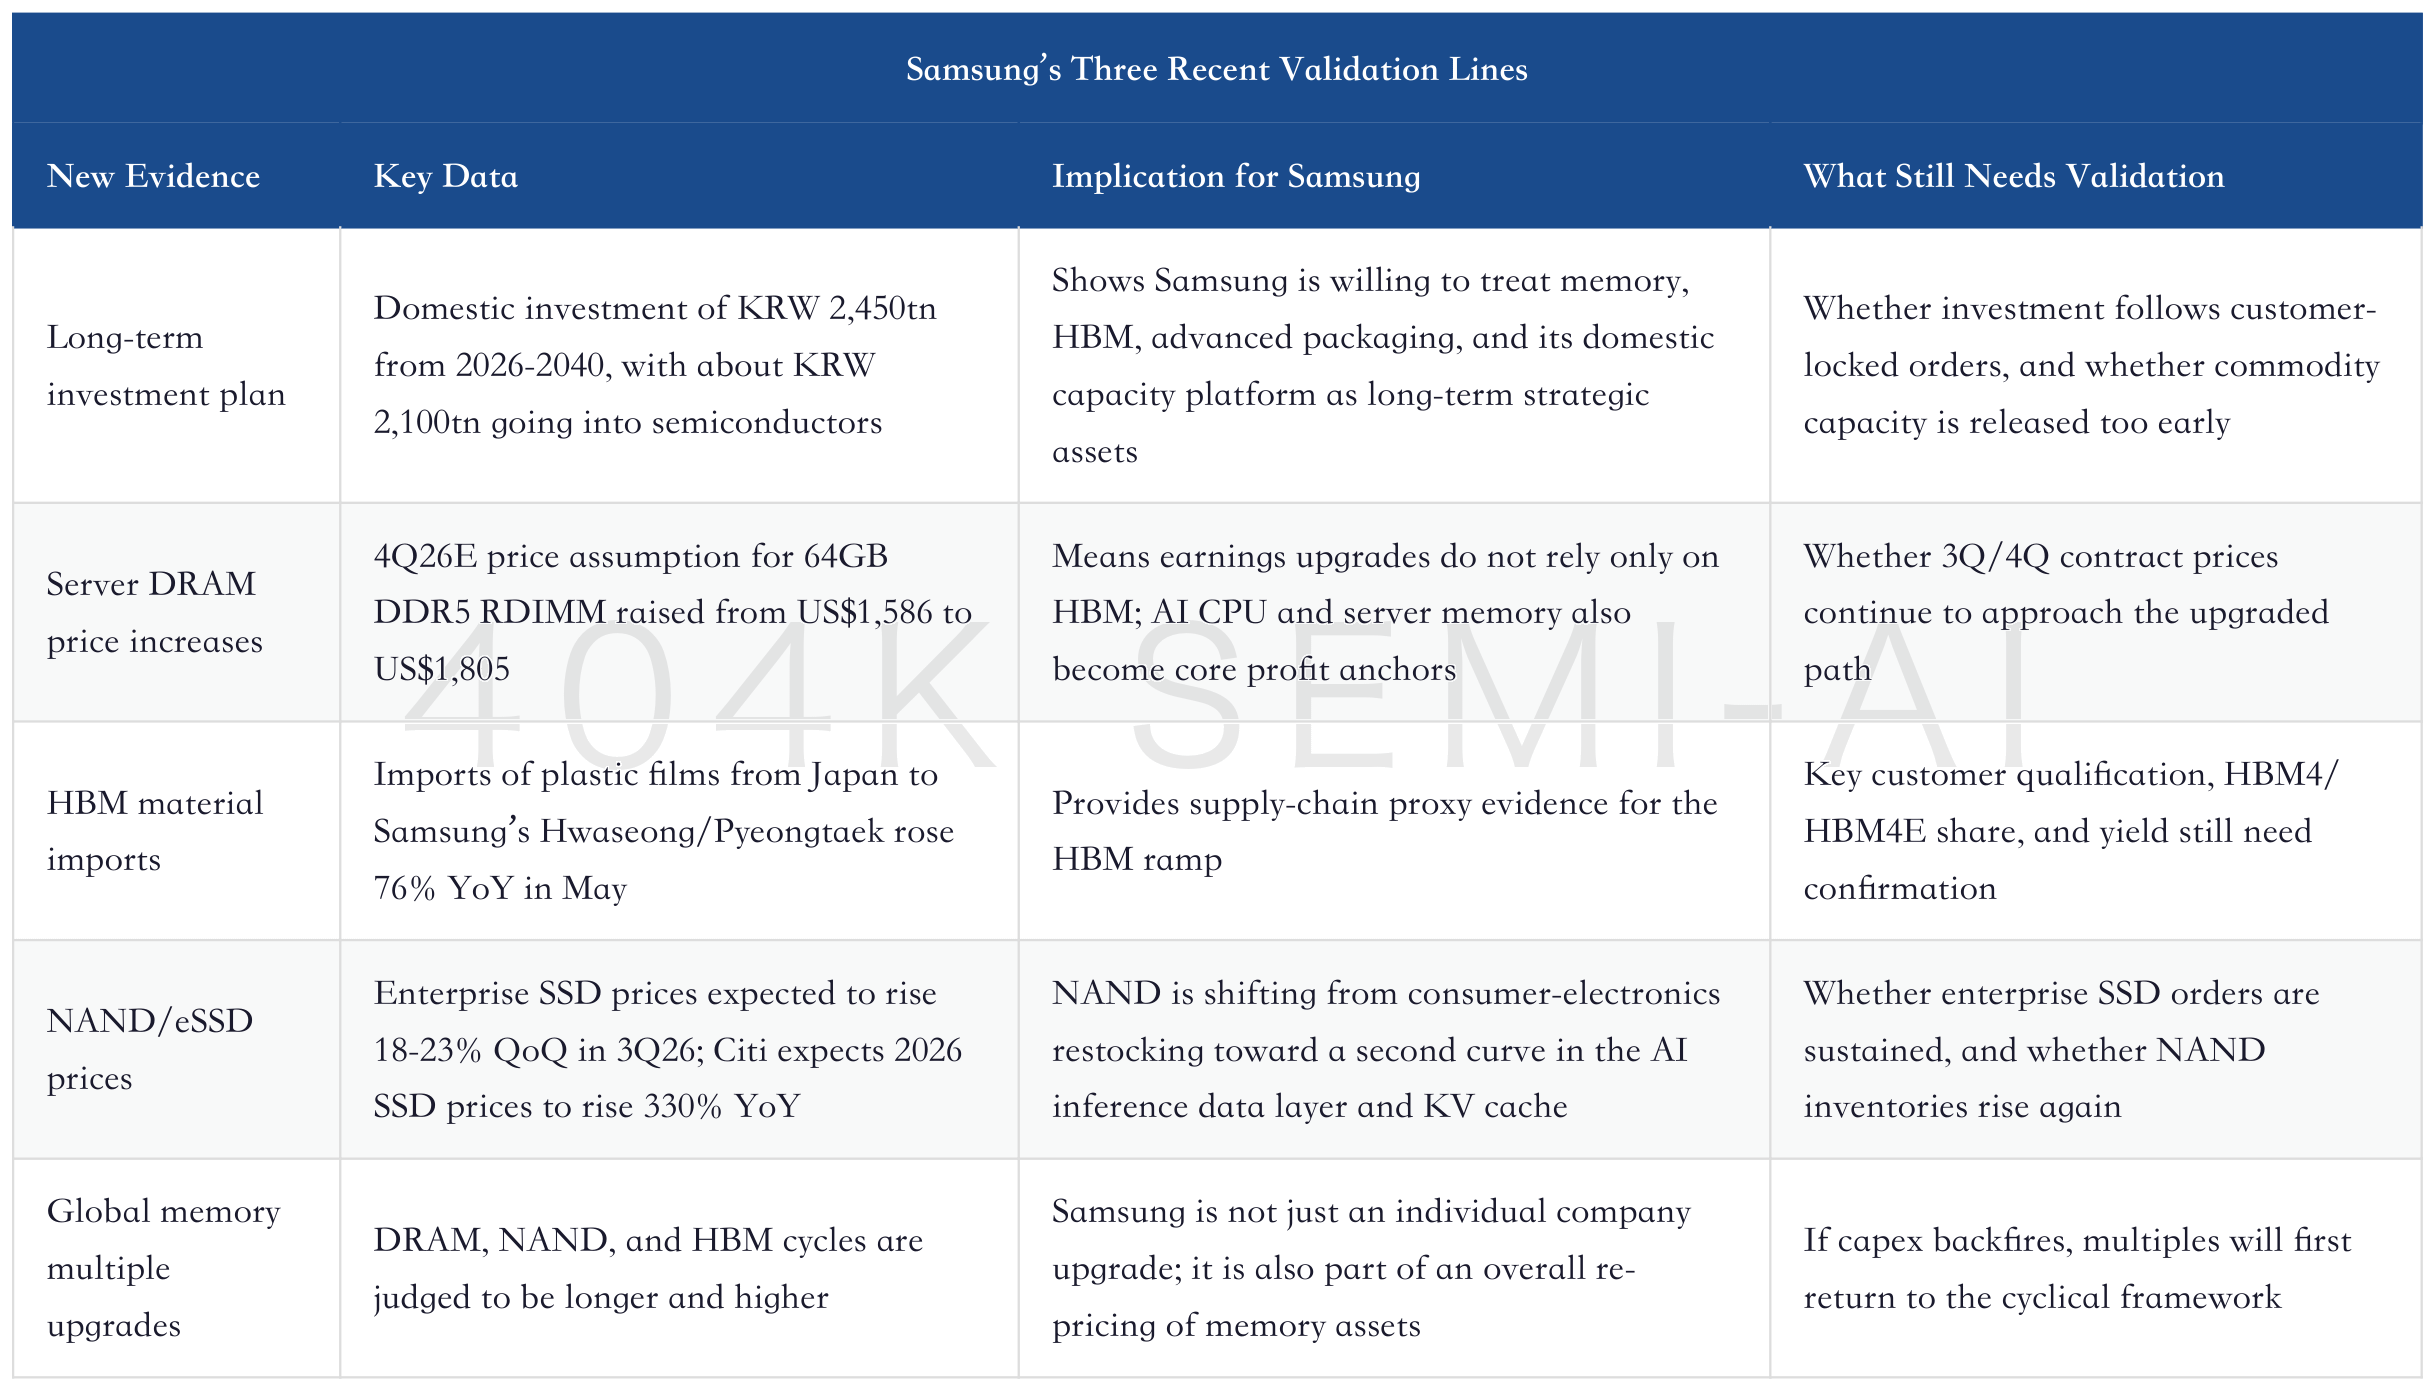
The key point of this table is that Samsung’s valuation variables have multiplied. Single-variable companies look clearer, but risk is also more concentrated. Samsung’s breadth makes analysis more complex, but also gives it more fault tolerance when AI storage demand diffuses. As long as server DRAM and NAND/eSSD first push up the income statement, and HBM then proves customer share and product-generation progress, the market will reassess whether Samsung should receive a cyclical-stock multiple or an AI-memory-platform multiple.
Memory Is No Longer Just a Cyclical Stock: JPM LTA Breakdown, Agentic AI Memory Multipliers, and the Rewriting of Samsung and SK hynix Valuations
This logic is consistent with the previous memory framework: the AI memory trade has already spread from buying only the HBM leader to system memory, enterprise SSDs, long-term agreements, and customer supply security. Samsung’s value lies in the fact that it covers almost all these lines, though each line still needs to be validated.
2. KRW 2,450tn of Investment: Moat or Next-Round Supply Risk
Samsung announced that it will invest KRW 2,450tn domestically in Korea through 2040. This is the variable most easily misread recently. When investors see a large investment figure, the first reaction is usually to worry that capacity expansion will break pricing. That concern is reasonable, but not all capex should be treated as negative. The key question for the memory industry has never been “whether to invest,” but “where the investment goes, who locks in the orders, and how firm the pricing terms are.”
Goldman’s breakdown is clear: this is not a budget spread evenly across all businesses, but a long-term investment plan centered on semiconductors while also covering existing fabs, new clusters, HBM capacity, and the display business. Putting the details into a table makes it easier to judge which parts may form a moat and which parts require caution around supply backfire.
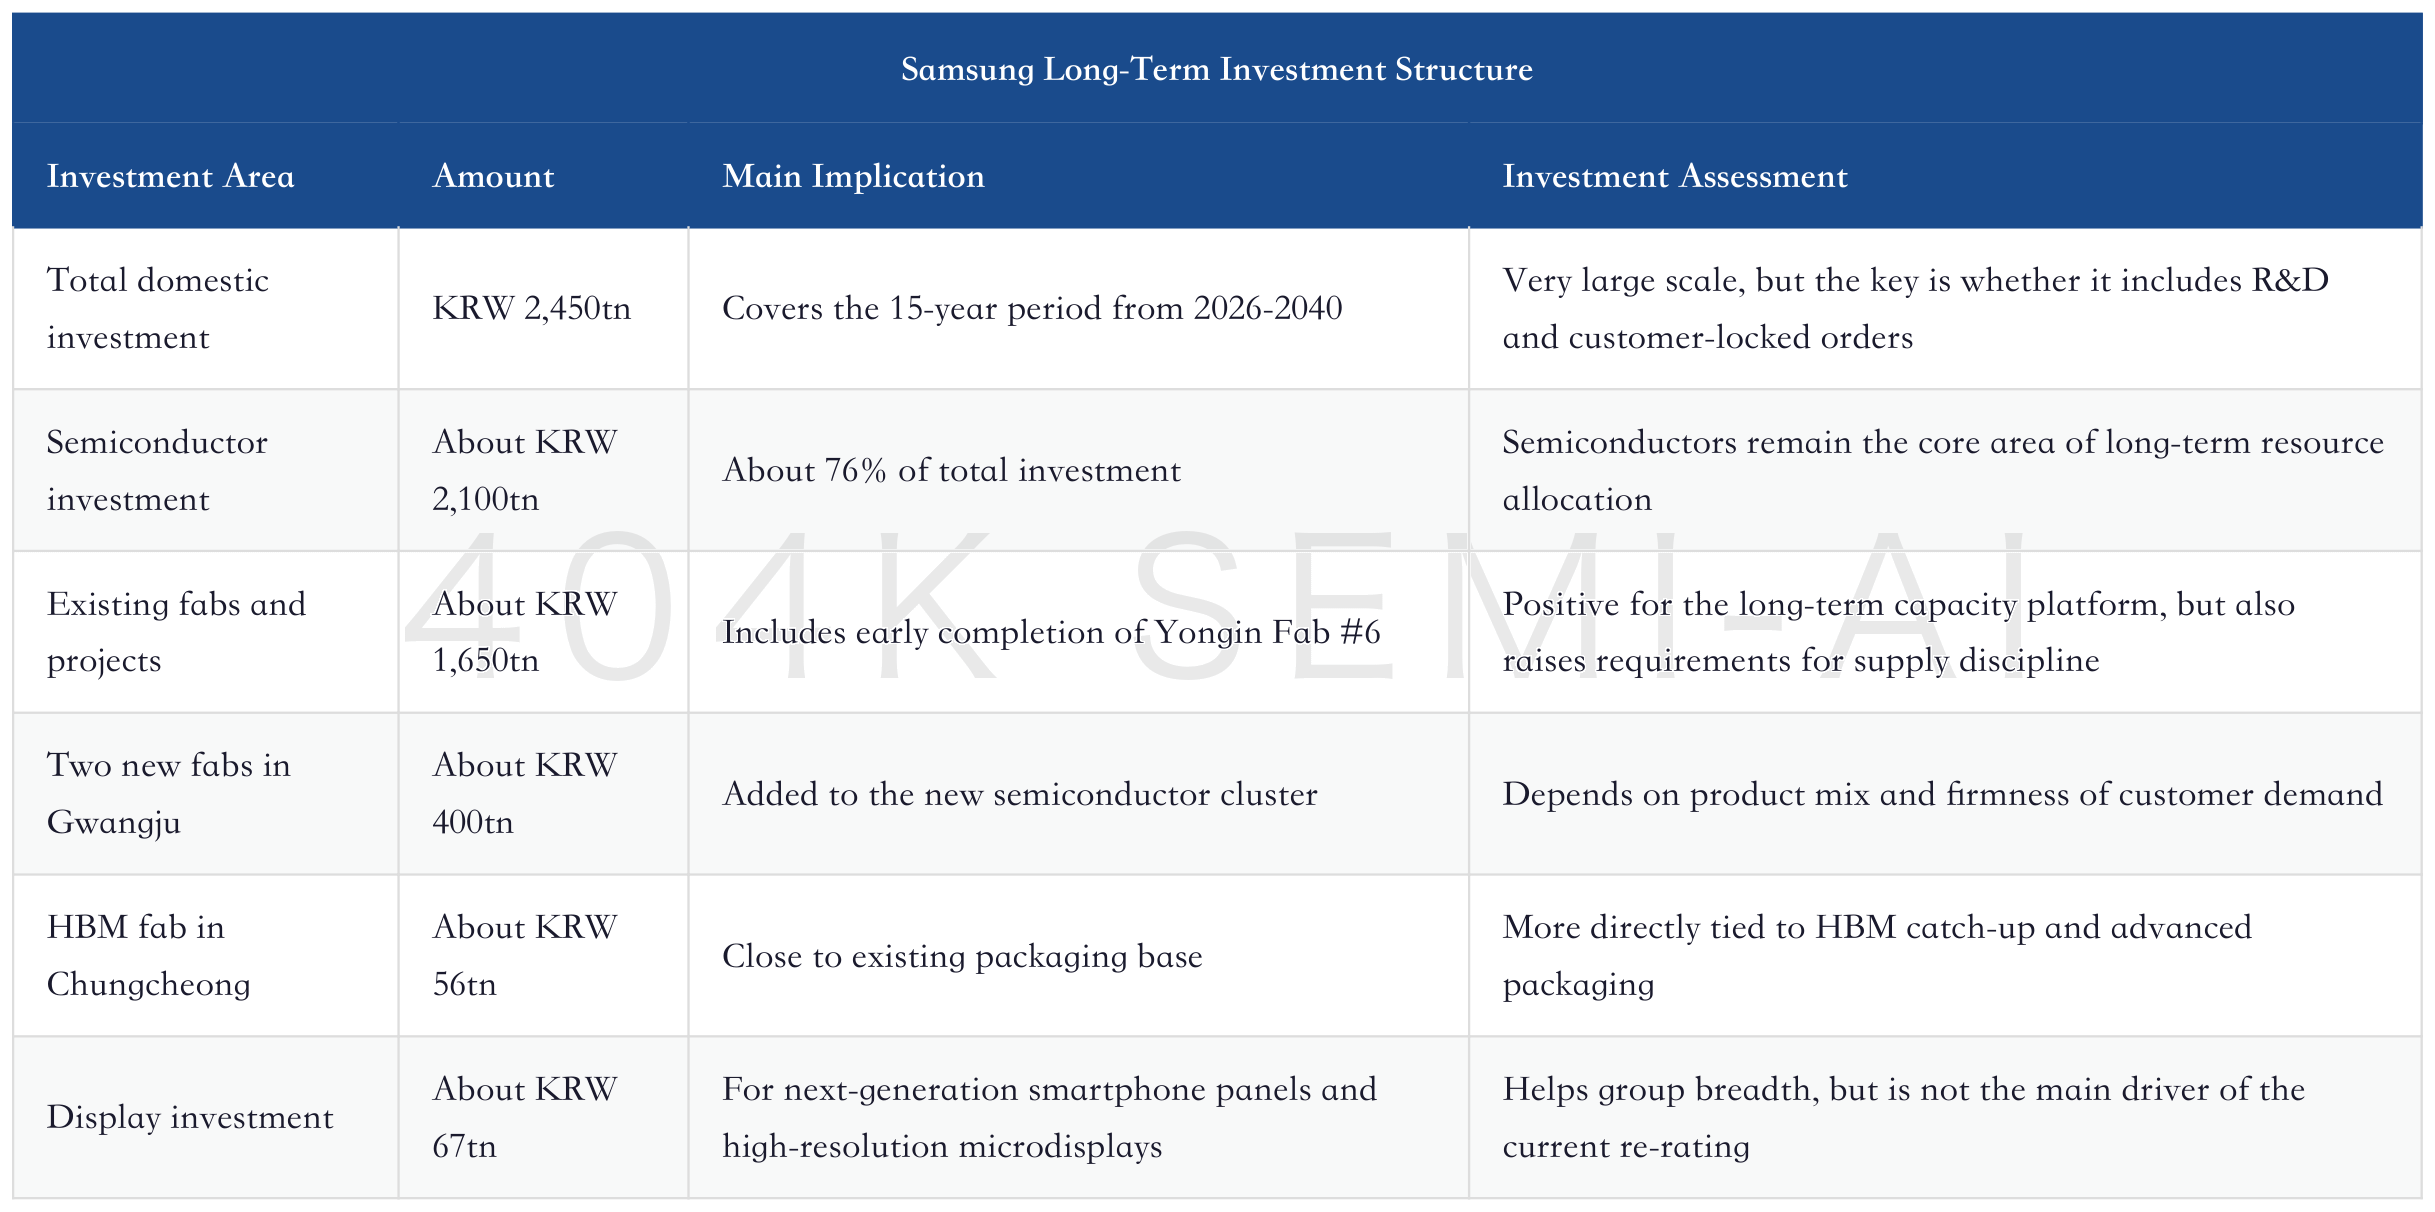
Goldman’s assessment of this plan is measured: if R&D; is included, the long-term plan implies annual average spending above the baseline forecast for the next three years, but under reasonable assumptions for domestic share and medium- to long-term growth, the cumulative scale is broadly close to the announced figure. In other words, the announcement looks more like a long-term platform commitment than immediate undisciplined capacity expansion.
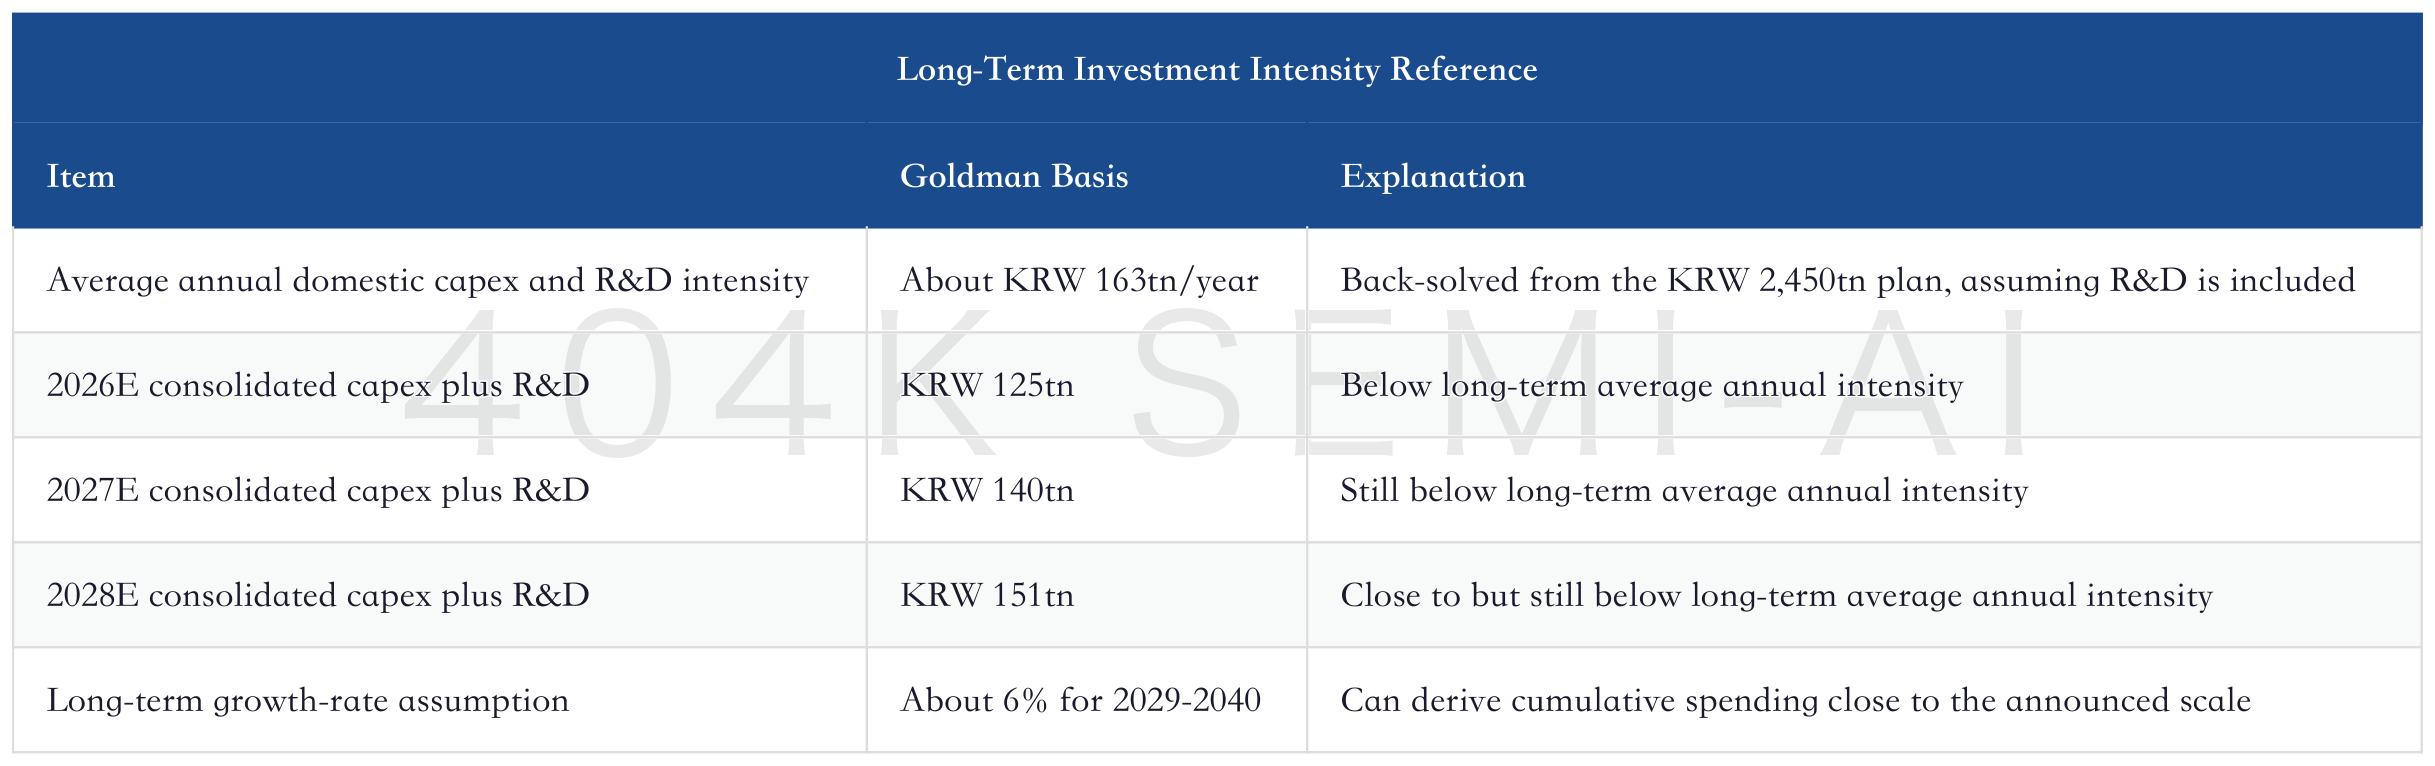
This means KRW 2,450tn cannot be simply interpreted as blind capacity expansion. It implies a long-term growth rate, not that Samsung will start dumping commodity DRAM and NAND into the market from tomorrow. The real debate is whether this money serves high-end capacity that customers already need.
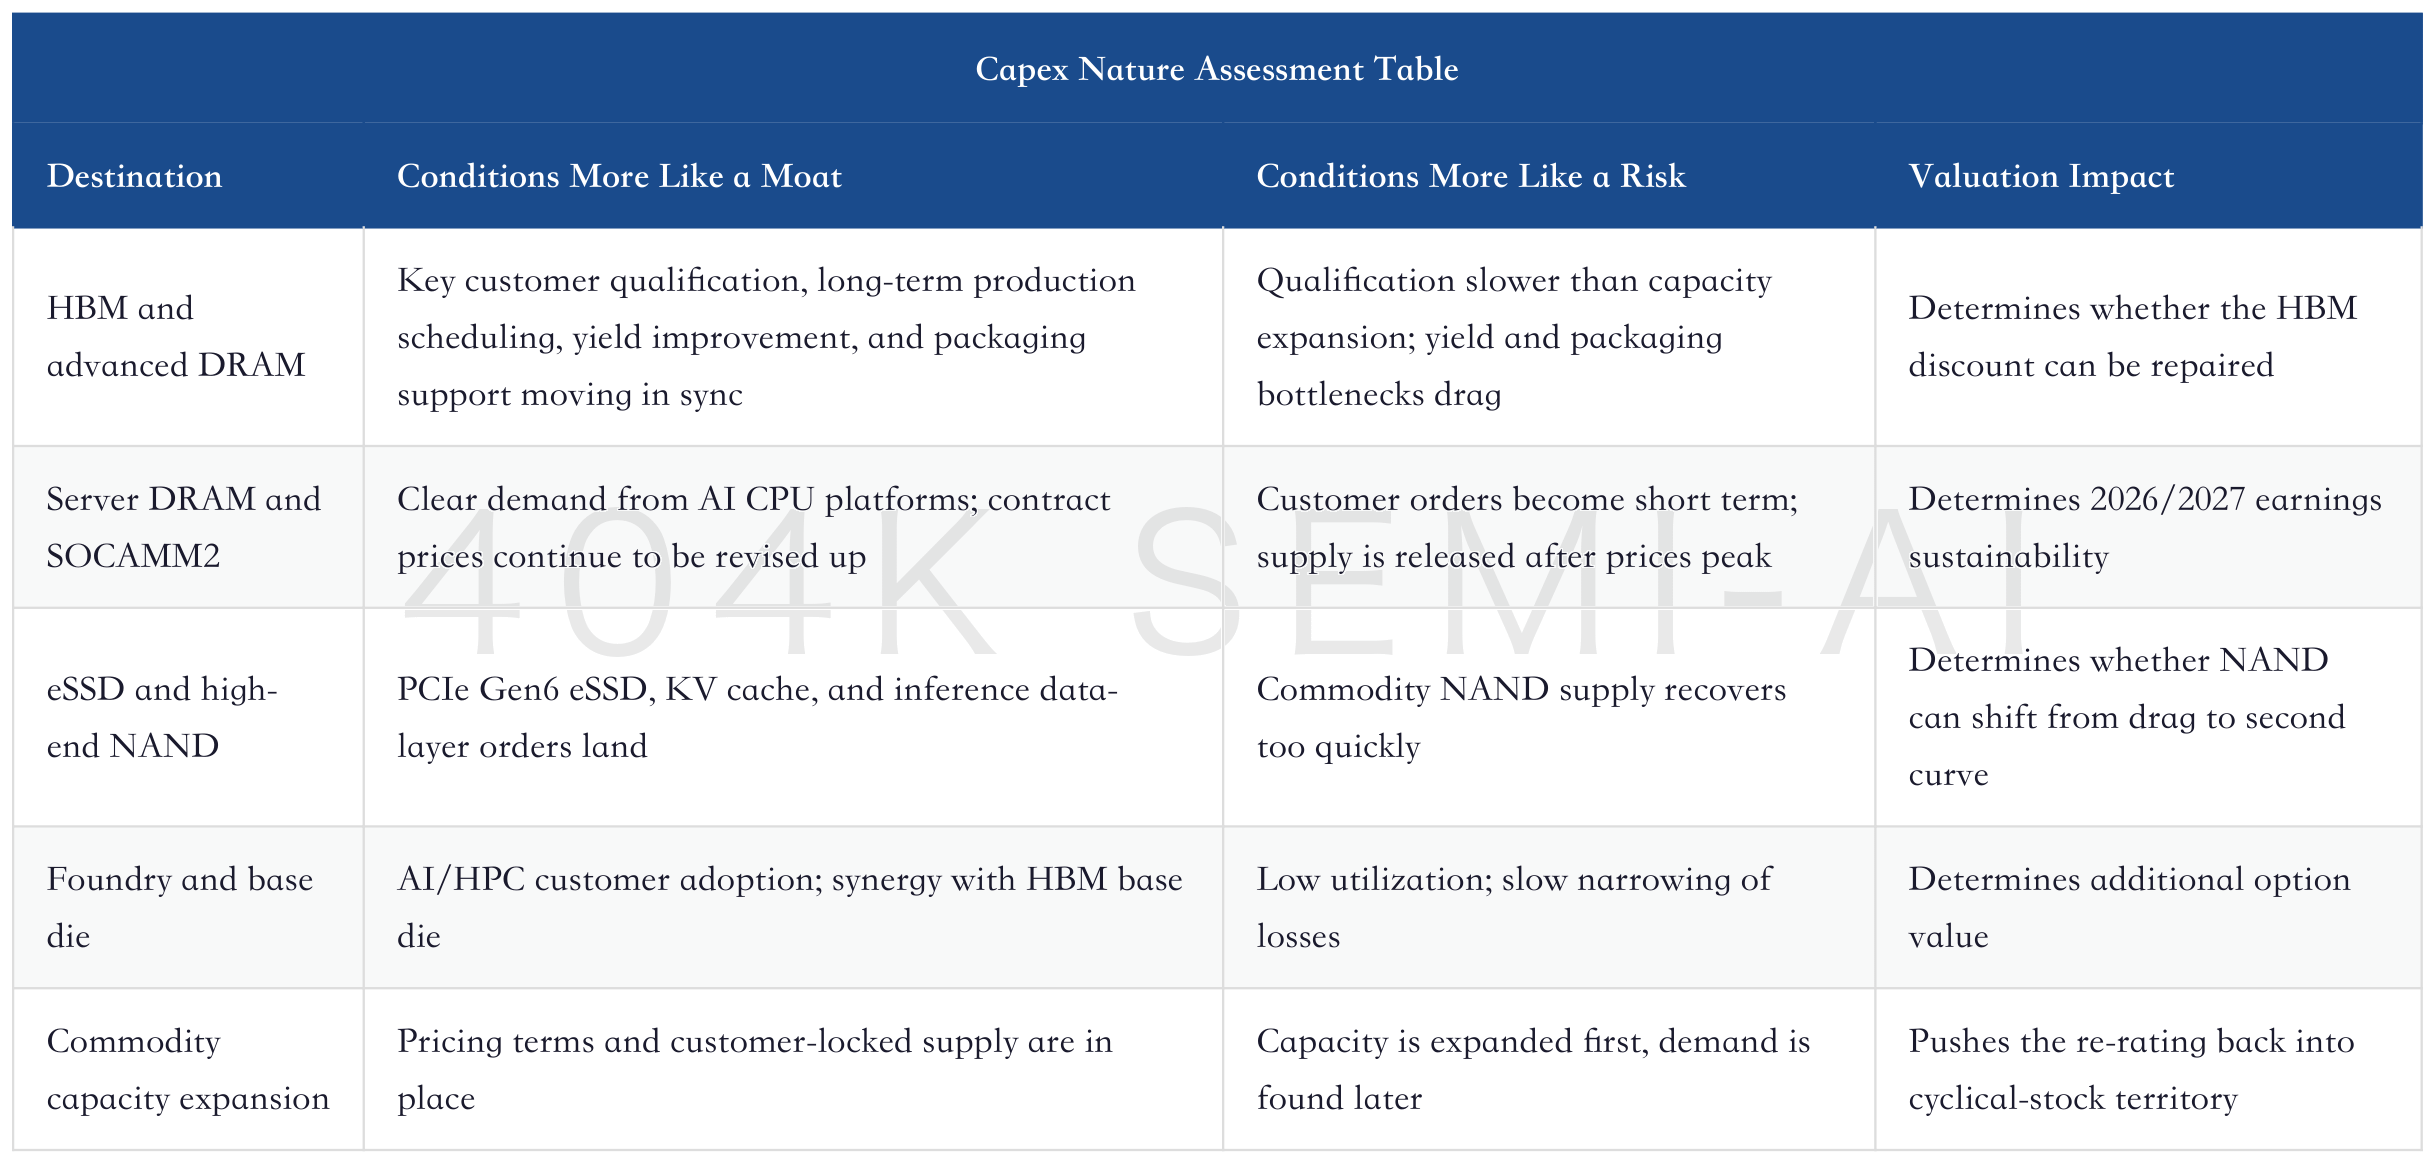
The larger the investment scale, the more Samsung needs to prove “customers first, capacity second.” This differs from past memory cycles. In previous upcycles, all vendors could easily expand supply under high prices, and inventories and depreciation would eventually compress earnings together. Now, if customers are willing to lock volume, price, and production schedules in advance for AI server supply security, capex is not purely a supply risk, but part of the value of supply security.
The best-case scenario is that Samsung uses the KRW 2,450tn plan to tell customers that it is not merely selling expensive memory in a given quarter, but can provide high-end DRAM, HBM, NAND/eSSD, and packaging platforms for the next decade-plus. The worst-case scenario is that the market reads the long-term plan as commodity capacity release, in which case investors will immediately discount 2026/2027 earnings as peak-cycle profits.
III. DDR5 64GB Server Modules: The Short-Term Price Anchor to Watch Most Closely
Server DRAM is the most direct earnings variable in the near term. Citi raised its 4Q26E price assumption for 64GB DDR5 RDIMM from US$1,586 to US$1,805, with a quarterly path of US$1,310, US$1,612, and US$1,805 for 2Q/3Q/4Q26E, respectively. This price anchor is more useful than the abstract statement that “AI memory demand is strong,” because it can feed directly into Samsung’s 2H26 income statement.
64GB DDR5 RDIMM may look less compelling than HBM, but it is likely the most important price indicator over the next two quarters. In the AI training phase, the market naturally focuses on GPUs and HBM. In the AI inference and enterprise LLM diffusion phase, CPUs, system memory, cache layers, and enterprise SSDs become more important. Servers are not only adding more GPUs; they also need more CPU memory to support longer context windows, more concurrent inference, more agent tasks, and more data caching.
Citi’s view on server DRAM rests on three layers of logic.
First, AI CPU demand is lifting system memory configurations. Inference workloads do not only consume GPU memory. CPU-side memory, data preprocessing, retrieval, caching, and service orchestration all require higher-capacity and more stable server DRAM. 64GB DDR5 RDIMM has become the mainstream server-memory price anchor, matching this shift.
Second, HBM is crowding out advanced DRAM resources. The stronger HBM demand is, the tighter advanced DRAM wafer and packaging resources become, making it harder for ordinary server DRAM supply to ramp quickly. Investors have historically viewed HBM and conventional DRAM separately, but on the supply side they affect each other. HBM absorbs high-end resources, while AI CPUs increase system memory demand. As a result, server DRAM pricing has gained resilience rarely seen in prior cycles.
Third, server DRAM pricing flows into reported earnings faster than many long-term narratives. HBM customer qualification and annual price negotiations affect valuation multiples, but server DRAM contract prices change quarterly, so profit transmission is faster. Citi raised its 2026 global DRAM ASP growth forecast to 234% YoY and expects DRAM ASPs to rise 44%, 20%, and 13% QoQ in 2Q/3Q/4Q26E. This is the direct source of near-term earnings upgrades.
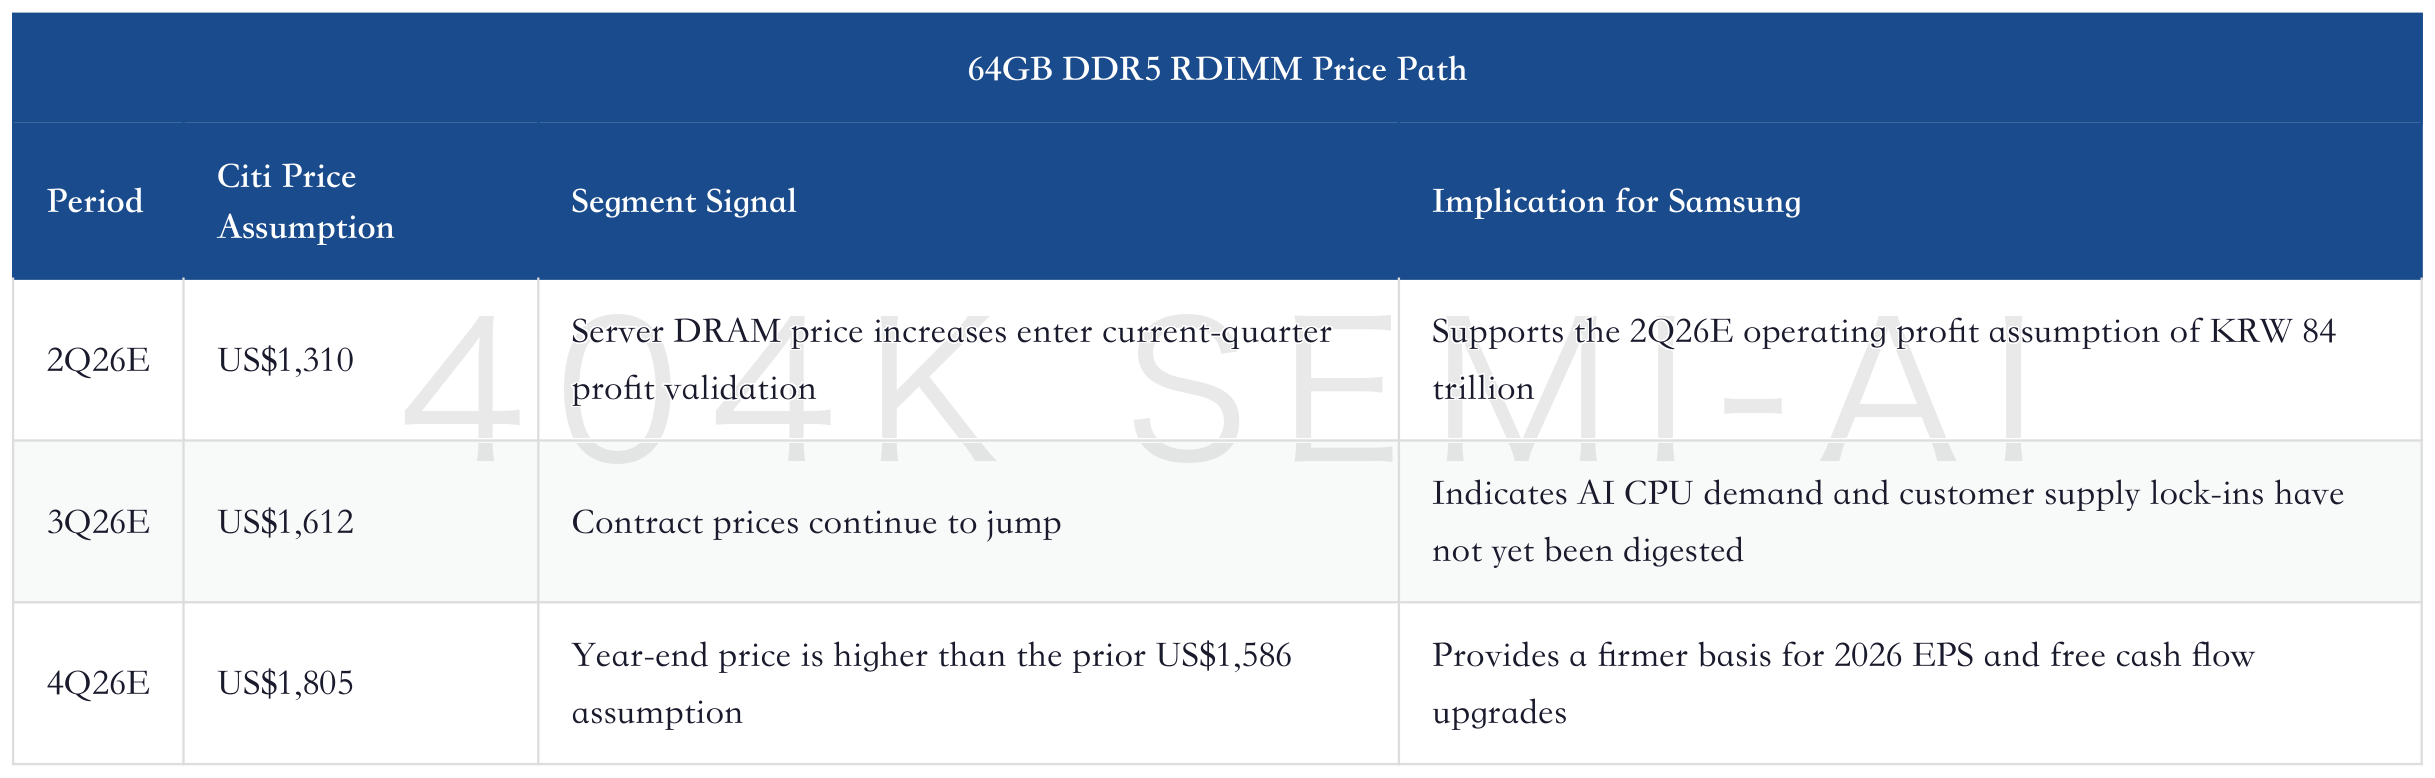
Memory price tracking also provides cross-validation. TrendForce’s 3Q price outlook, monthly pricing for DDR5 64GB server modules, and the DDR5 premium over DDR4 all point to the same conclusion: DDR5 server modules are not simply an optimistic assumption in a single broker model; the premium is widening simultaneously in industry pricing.
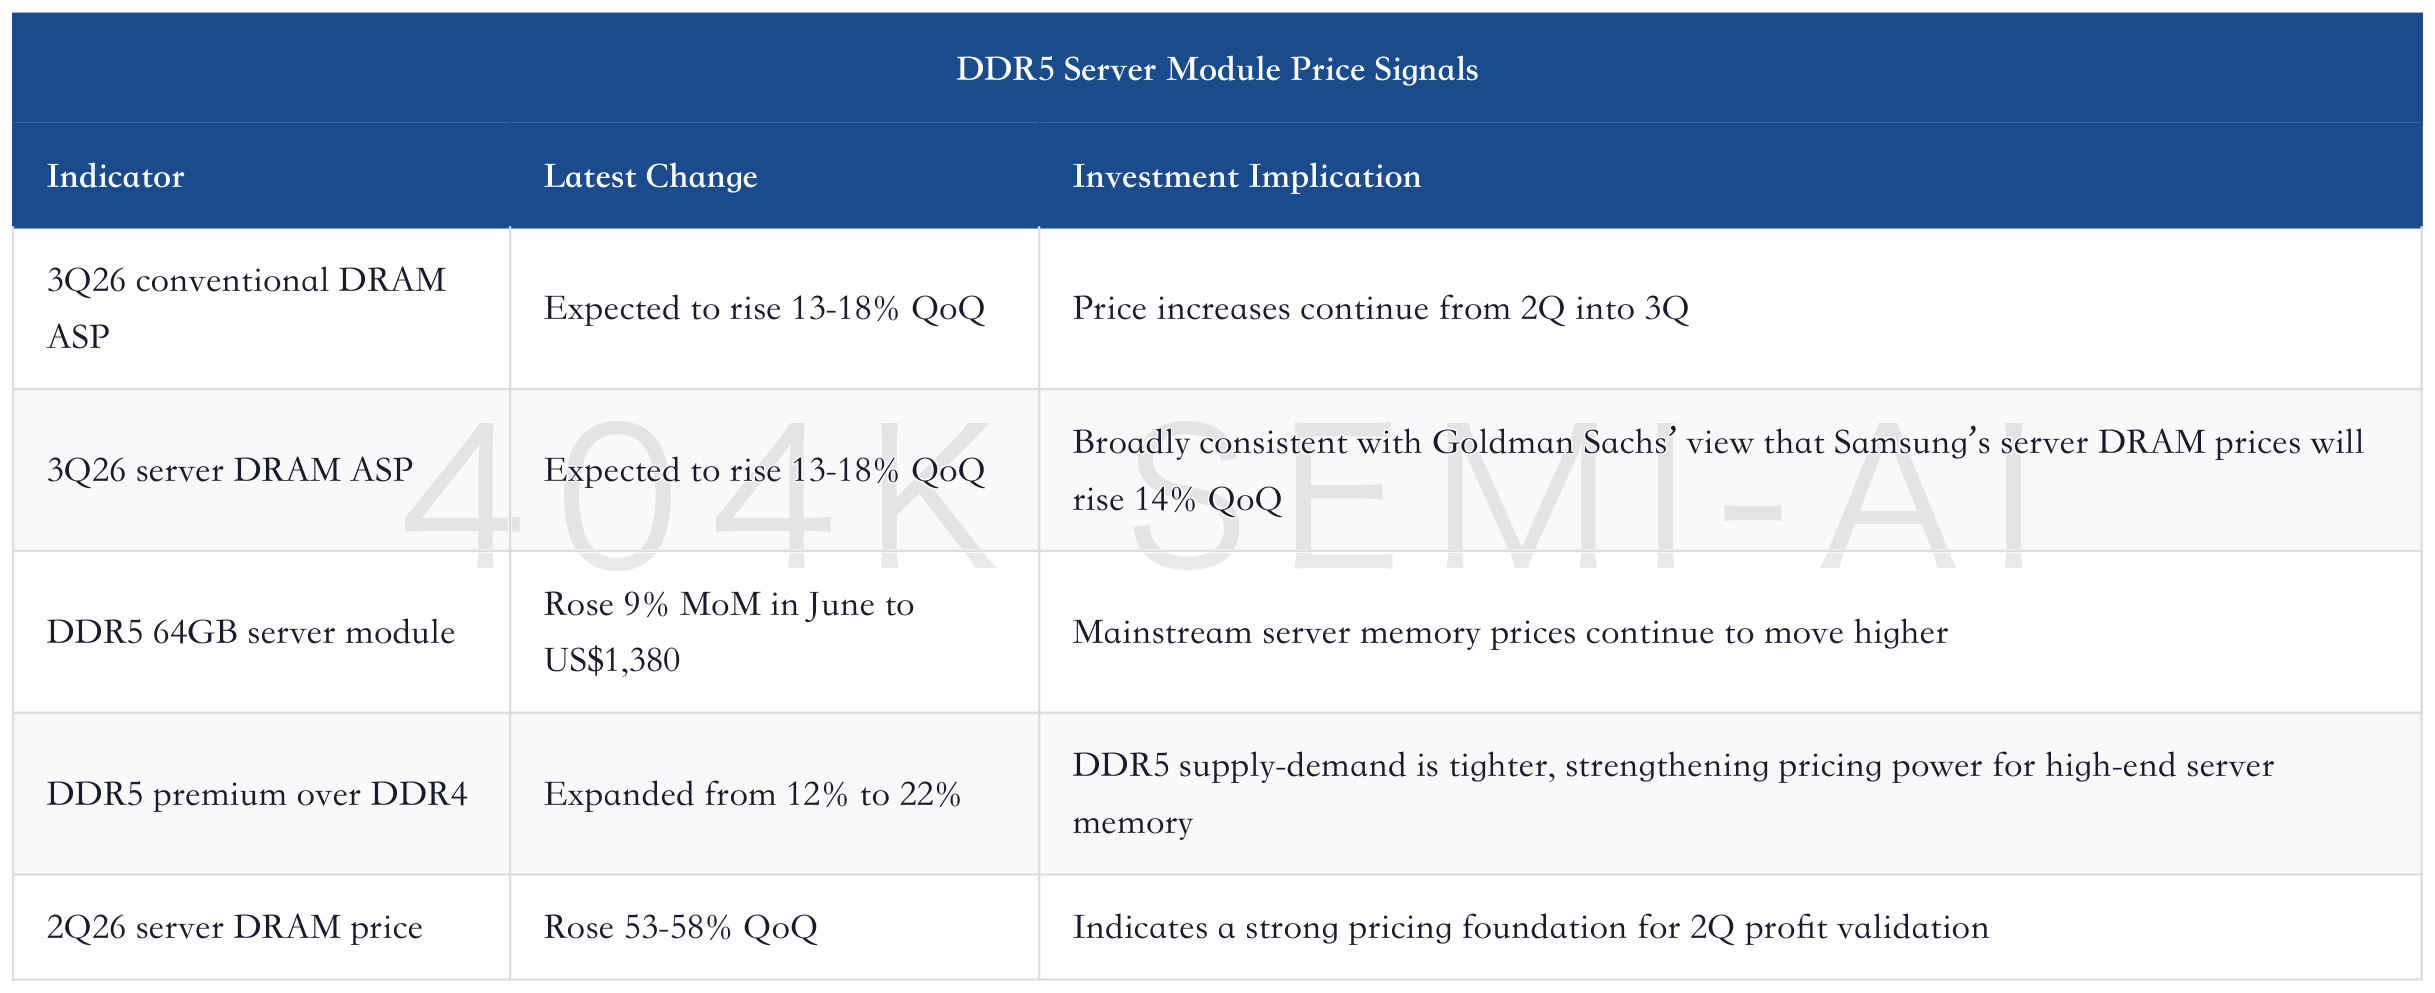
This is one of the most important tables in the recent Samsung investment debate. As long as DDR5 64GB server modules remain strong, Samsung’s near-term earnings can be driven first by server DRAM and NAND/eSSD, without waiting for all HBM qualification information to land at once. Conversely, if 3Q/4Q contract prices suddenly fall below the US$1,310, US$1,612, and US$1,805 path, the market will first cut earnings estimates, then reassess whether long-term investment will turn into supply pressure.
Rubin’s memory crowding-out effect is on the same line as the current widening premium for DDR5 server modules. Advanced DRAM resources are being absorbed by HBM, SOCAMM, and server RDIMM together, and consumer electronics memory no longer naturally gets priority access to capacity. If Samsung can supply HBM, SOCAMM2, and server RDIMM at the same time, it can turn product breadth into an income-statement stabilizer.
IV. HBM Material Imports: Physical Proxy Indicators Begin to Appear in the Catch-Up Story
Samsung’s HBM story has always had two layers. The first is direction: the company must prove that it is qualified to become a reliable source of supply for key customers in HBM4, HBM4E, and next-generation AI platforms. The second is evidence: the market cannot rely only on company statements; it also needs physical signals from orders, qualification, materials, yields, and shipments.
Recent Korean technology export tracking provides a useful proxy indicator. Goldman Sachs tracks imports of plastic film from Japan to Samsung’s Hwaseong/Pyeongtaek facilities, because Samsung’s HBM production bases are located in these areas and its TC-NCF materials mainly come from Japanese suppliers. The report shows that the relevant import value rose 76% YoY in May and 61% YoY from the beginning of the year through May. Goldman Sachs’ view is that this may indicate a relatively solid ramp in Samsung’s HBM production.
This indicator should not be overstated. Material imports are not end shipments, do not mean key customer qualification has been completed, and do not mean share has already been determined. But it has two important implications. First, it indicates that Samsung’s HBM ramp is not just a verbal plan; there is already incremental activity in the supply chain. Second, before observing HBM qualification, it gives the market an intermediate piece of evidence between company statements and final revenue.
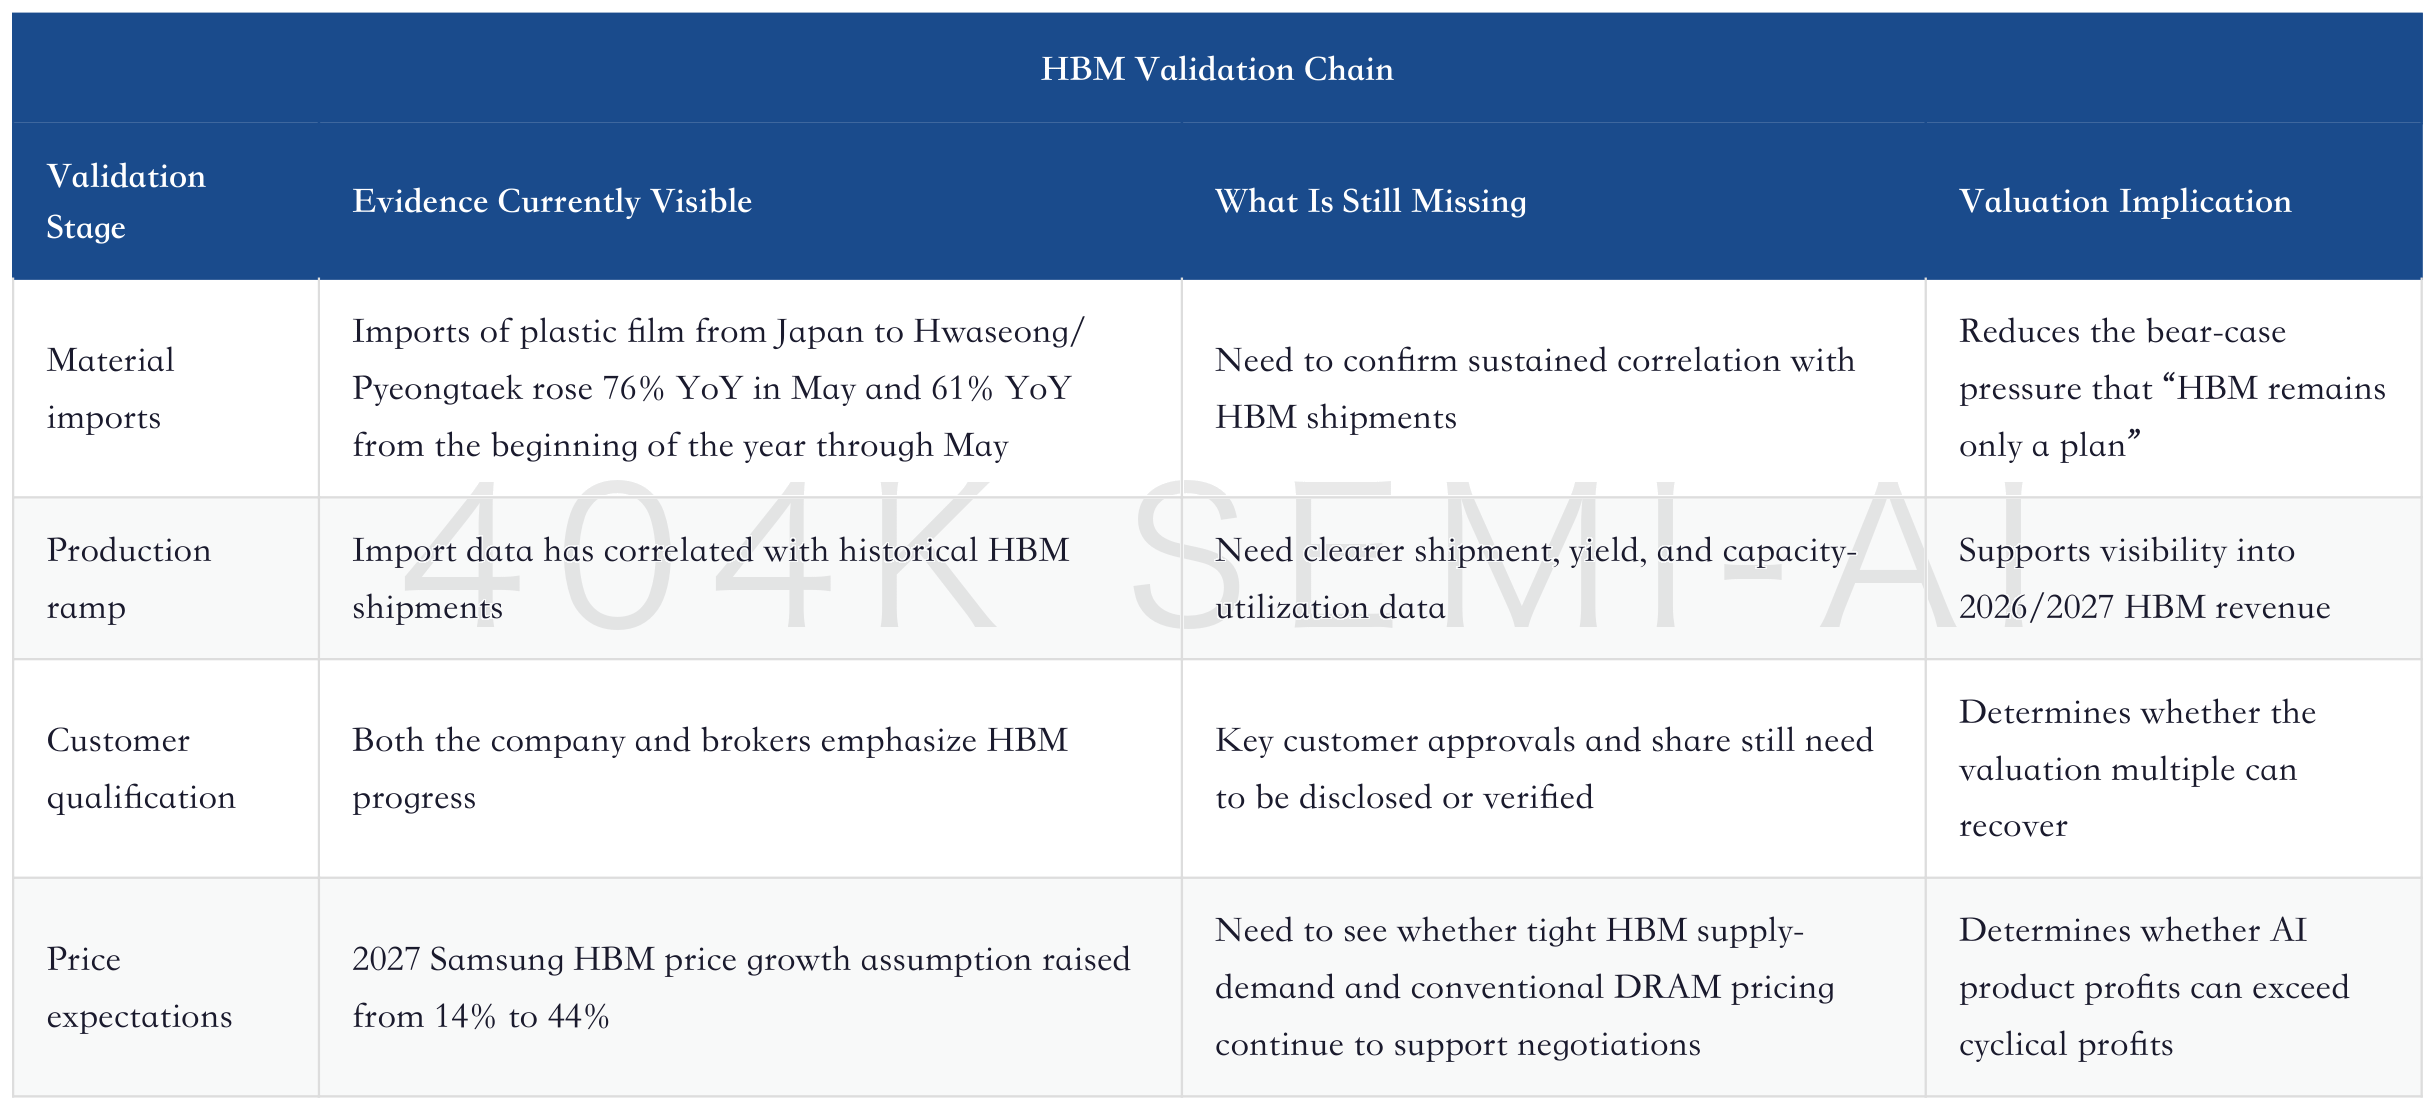
Goldman Sachs also raised its 2027 Samsung HBM price assumption from 14% YoY growth to 44%. This adjustment is critical because it links HBM pricing with conventional DRAM pricing: when conventional DRAM prices are strong, the floor for HBM price negotiations is also lifted. In other words, HBM price increases are not isolated; high prices for conventional server DRAM will affect next year’s HBM negotiations.
This is especially important for Samsung. SK Hynix’s HBM quality premium is already easier for the market to accept. For Samsung to repair its discount, it must prove not only that it can sell HBM, but also that it can obtain reasonable pricing in next-generation products and a multi-customer structure. The 76% increase in material imports is only the first step; the 44% increase in price expectations is the higher-level signal of asset quality.
In the near term, HBM gives Samsung a valuation multiple, but it may not be the entire source of current-quarter profit. Server DRAM and NAND/eSSD can first deliver the income statement, while HBM determines whether the market is willing to view part of those profits as AI product profits rather than peak-cycle profits. As long as HBM validation continues to improve, Samsung can migrate from a “low-P/E memory stock” to an “AI memory breadth asset.”
V. NAND/eSSD: From Restocking Business to Inference Data Layer
NAND is the Samsung business line most easily underestimated. In the past, NAND was often viewed as a drag on group valuation: painful price wars, large inventory swings, strong consumer-electronics correlation, and investors unwilling to assign a high multiple. The recent change is that NAND/eSSD is becoming more tightly connected to the AI inference data layer.
Citi raised its 2026 global NAND ASP growth forecast to 236% YoY and expects SSD prices to rise 330% YoY. In memory price tracking, TrendForce expects 3Q26 NAND ASP to rise 10-15% QoQ, with enterprise SSD prices up 18-23% QoQ, clearly stronger than mobile NAND at 5-10%. This shows that NAND is also becoming segmented internally: consumer price recovery and enterprise SSD re-rating are not the same thing.
AI inference will magnify the importance of enterprise SSDs. Large-model inference is not a one-off computation. Systems need to store context, schedule retrieval, process vector databases, write intermediate states, and frequently move data between memory and storage. As KV cache, retrieval-augmented generation, and multi-agent workflows become more widespread, the data layer is no longer just ordinary storage; it becomes part of AI service latency, cost, and throughput.
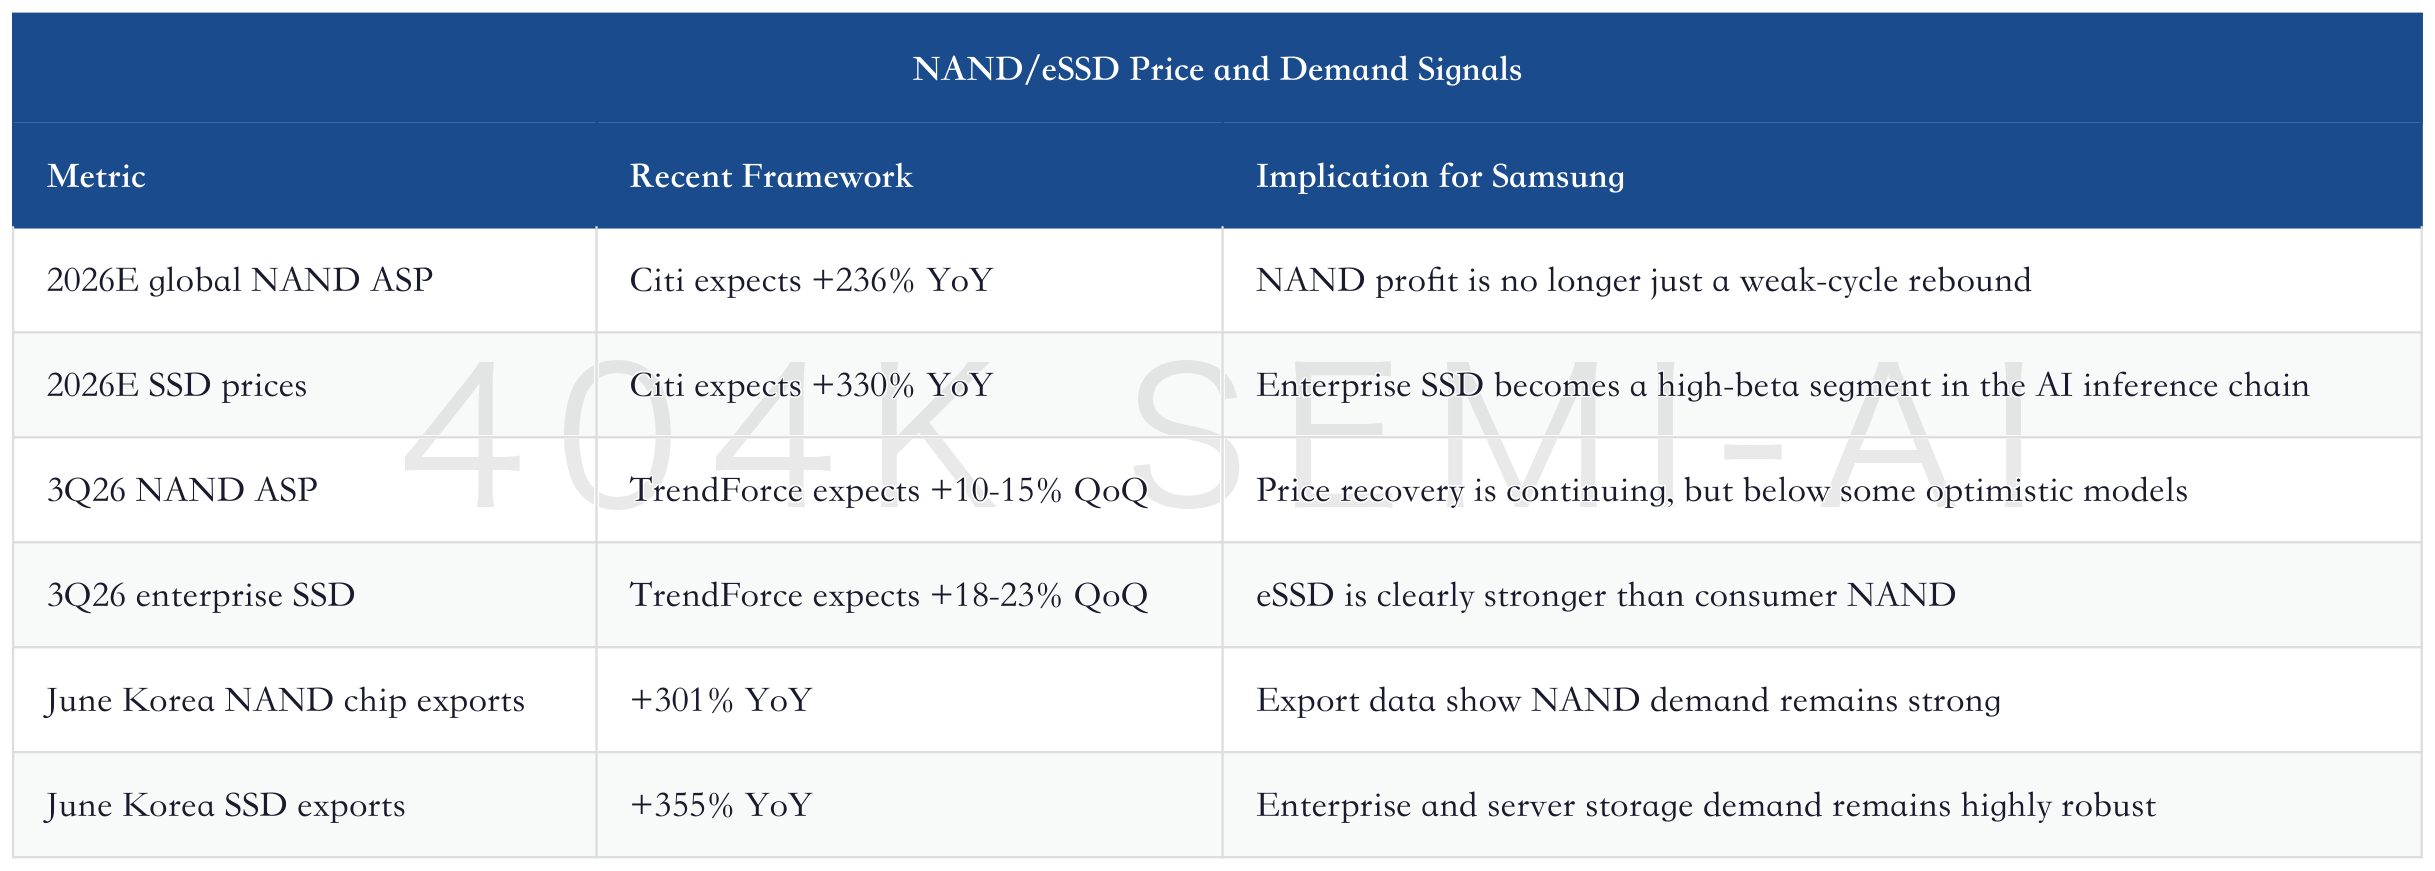
This table matters for Samsung because it explains why Samsung cannot be valued only on HBM share. If NAND/eSSD is merely a cyclical rebound, its valuation contribution is limited; if it becomes the AI inference data layer, Samsung’s breadth value rises meaningfully. Especially when DRAM profit is very strong, NAND only needs to stop dragging on group valuation to improve visibility for overall earnings and cash flow.
The core validation point for NAND/eSSD is not how much prices rise in one quarter, but order quality. We need to see sustained demand from PCIe Gen6 eSSD, high-capacity enterprise SSDs, AI server customers, and KV cache-related use cases. If this is only short-term restocking, prices will quickly return to a cyclical framework; if it is a restructuring of the inference data layer, the NAND discount still has room to repair.
VI. Korea Export Data: The Macro Surplus Is Underwriting Corporate Profit
A company deep dive cannot only write about the company’s own model; it also needs to assess whether external data are aligned. Korea’s June technology export tracking provides a very strong backdrop: memory exports rose 280% YoY, marking five consecutive months of more than 200% YoY growth; DRAM exports rose 385% YoY, again setting a new growth-rate high since tracking began in 2008; NAND chip and SSD exports rose 301% and 355% YoY, respectively.
The value of this dataset is that it validates the revenue expectations for Samsung, SK hynix, and others at the national export level. A single company report can be affected by model assumptions, but export data show that pricing and demand are already visible in macro trade data. Goldman Sachs also expects Korea’s memory companies to have a high probability of reporting positive 2Q26 results, and expects Samsung’s 2Q26 memory revenue to grow 452% YoY, with DRAM and NAND up 502% and 355%, respectively.
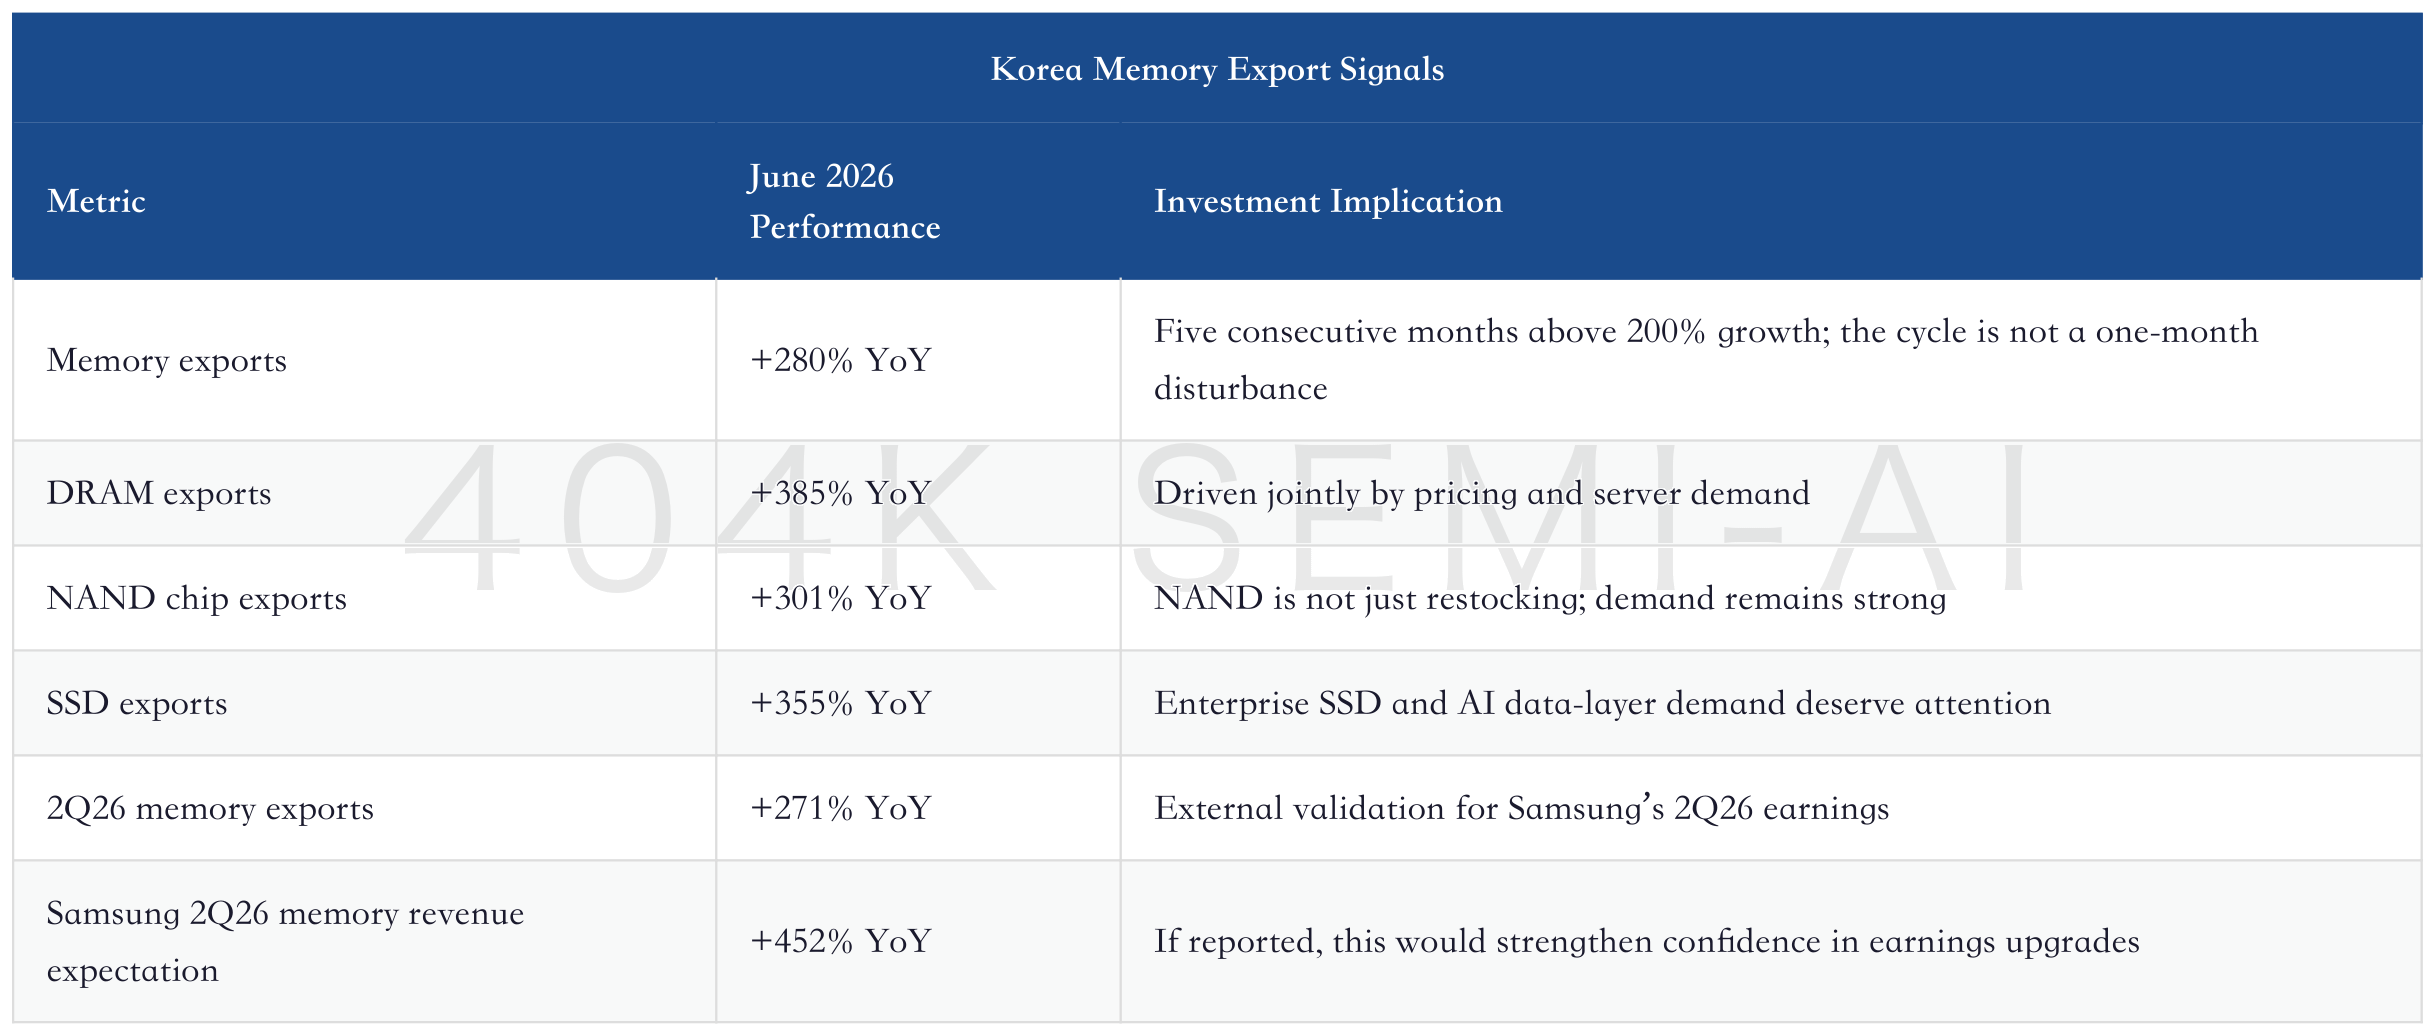
Export data also support a broader judgment: memory is already affecting Korea’s technology surplus and industrial cycle. For Samsung, this is both an opportunity and a pressure point. The opportunity is that macro data will attract more capital to reallocate toward Korean AI hardware and memory assets; the pressure is that when the data are too strong, the market will worry earlier about the cycle peak and supply backlash.
This is also why Samsung’s long-term investment plan must be assessed together with export data. Strong exports show that demand and pricing are being realized; strong investment means supply will also increase. What truly makes the market willing to assign a higher multiple is not “strong demand plus strong investment” itself, but customers’ willingness to lock in future supply in advance through long-term agreements, production-allocation priority, and pricing terms.
VII. Valuation: The KRW 530,000 Target Price Buys Earnings Upgrades; Next Comes Multiple Migration
Citi raised its Samsung Electronics target price from KRW 460,000 to KRW 530,000 and maintained its Buy rating. On the surface, this is a target-price revision; in substance, it incorporates upgrades to server DRAM, NAND/eSSD, and SSD pricing into the 2026/2027 profit model.
The focus of Citi’s upgrade is to concentrate the server DRAM, NAND/eSSD, and SSD price increases into operating profit, EPS, and cash flow over the next two years. A low P/E looks attractive, but low P/Es for memory stocks often appear at earnings peaks. It cannot be treated directly as a margin of safety; the nature of the profit must continue to be disaggregated.
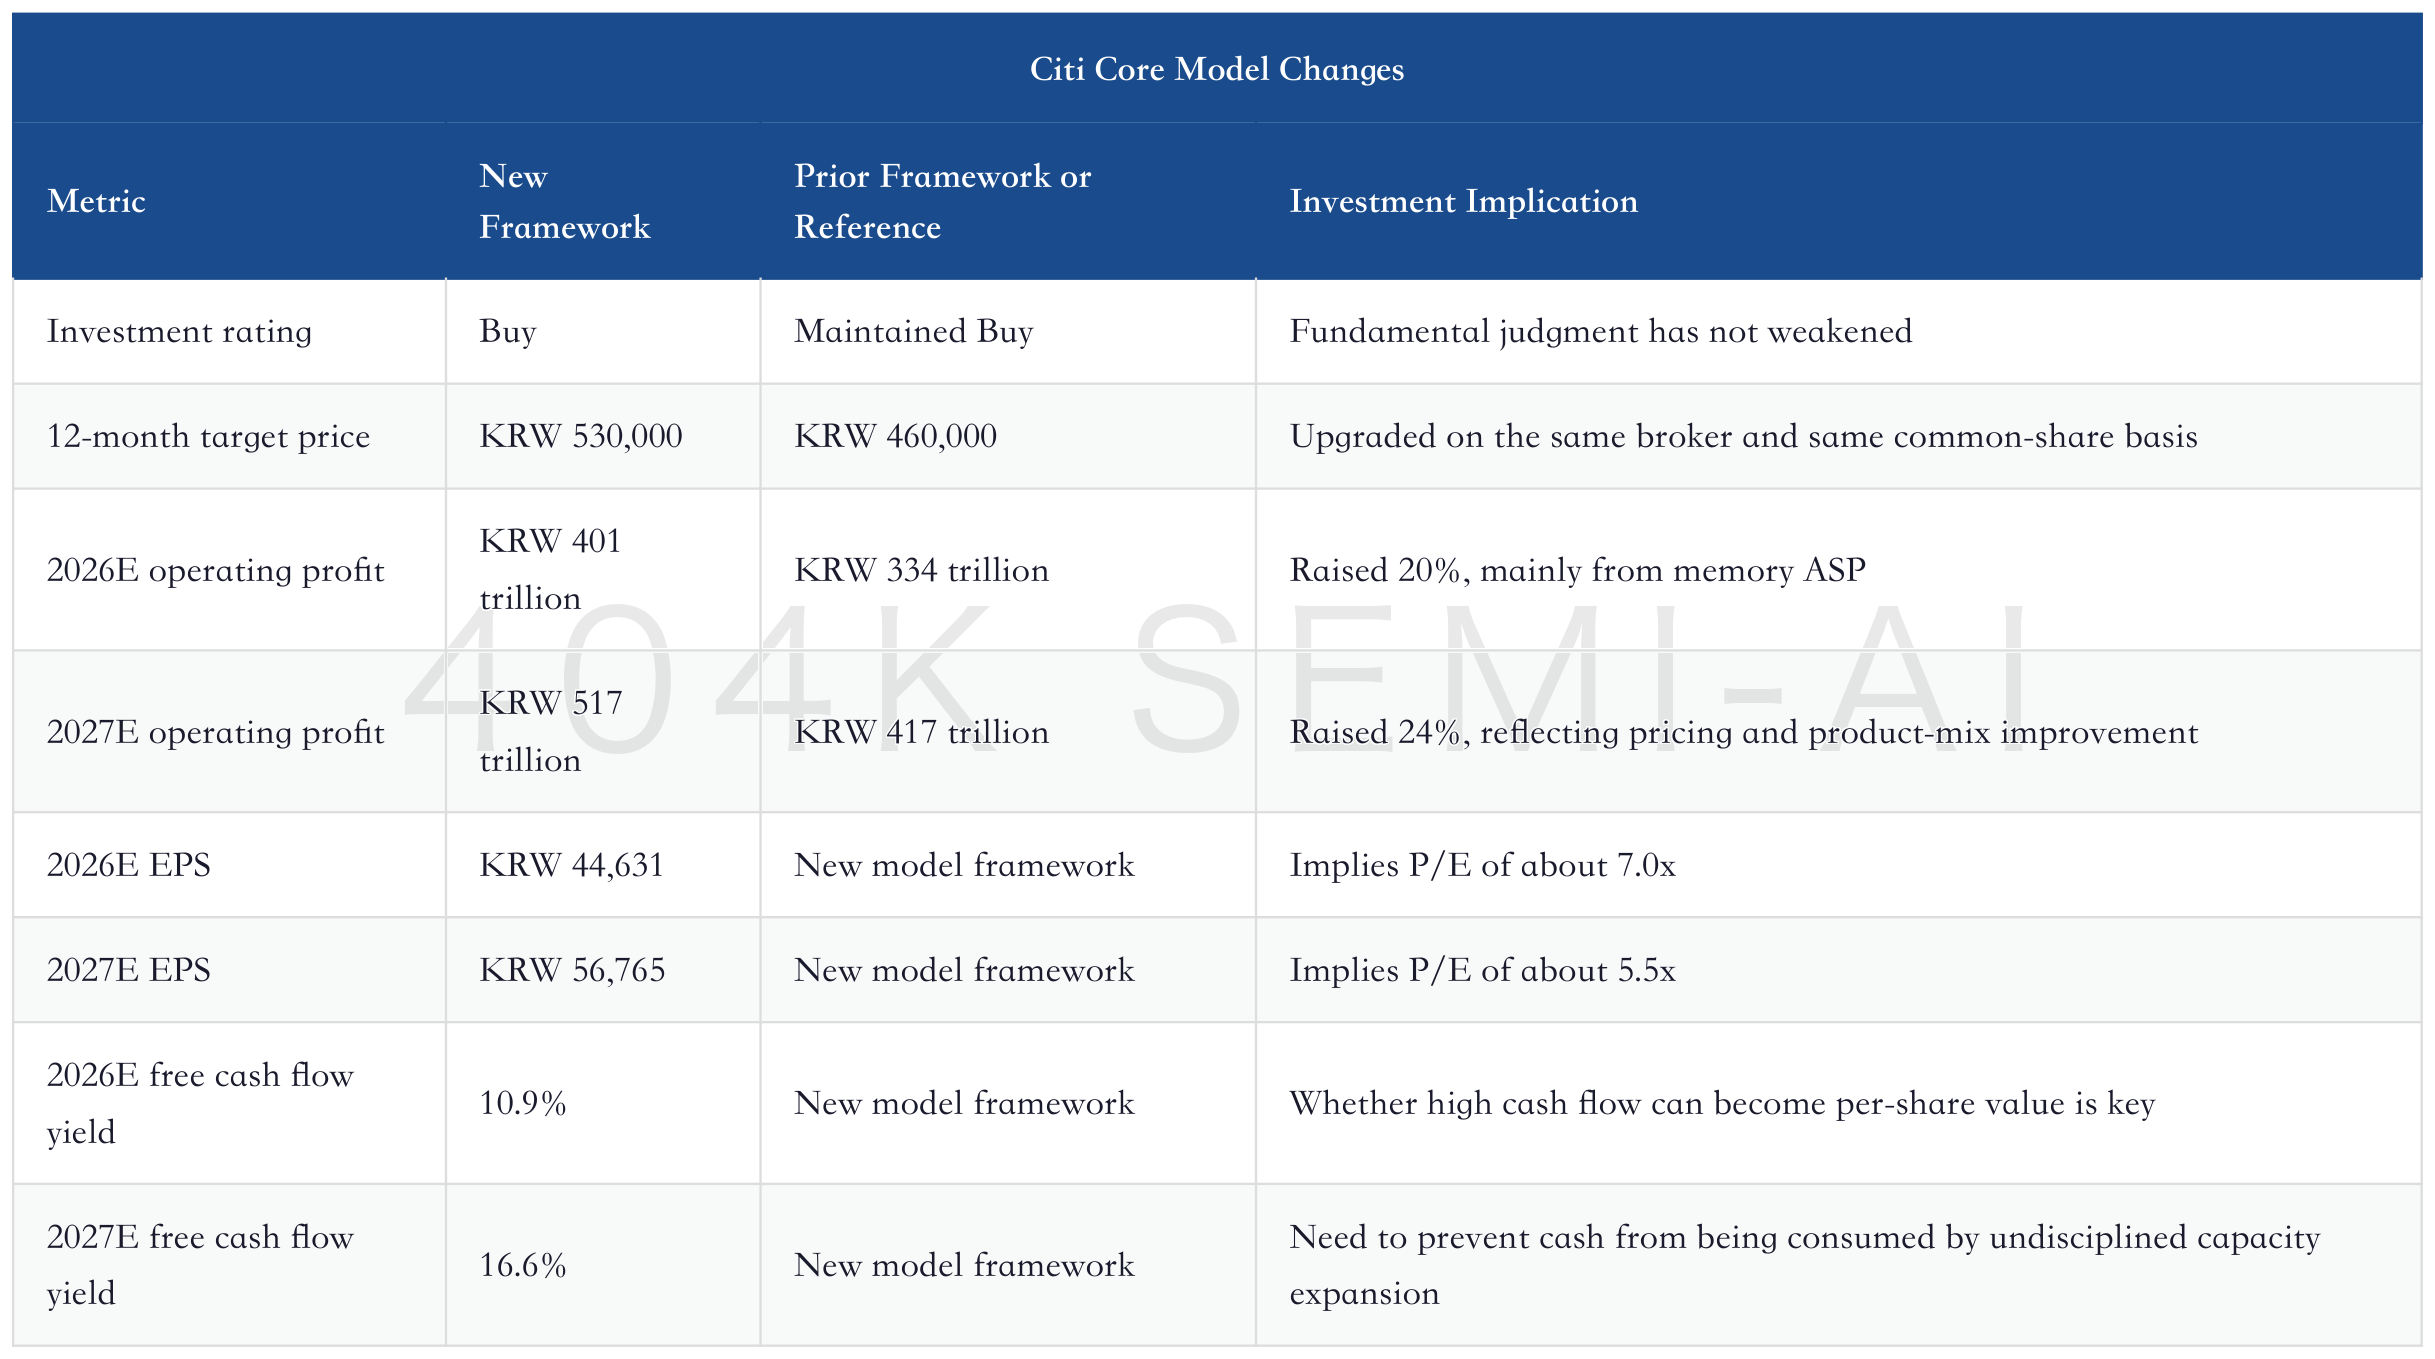
The most important valuation issue is not KRW 530,000 itself, but how much multiple the market is willing to assign to each type of profit. Samsung’s profit can be divided into four layers.
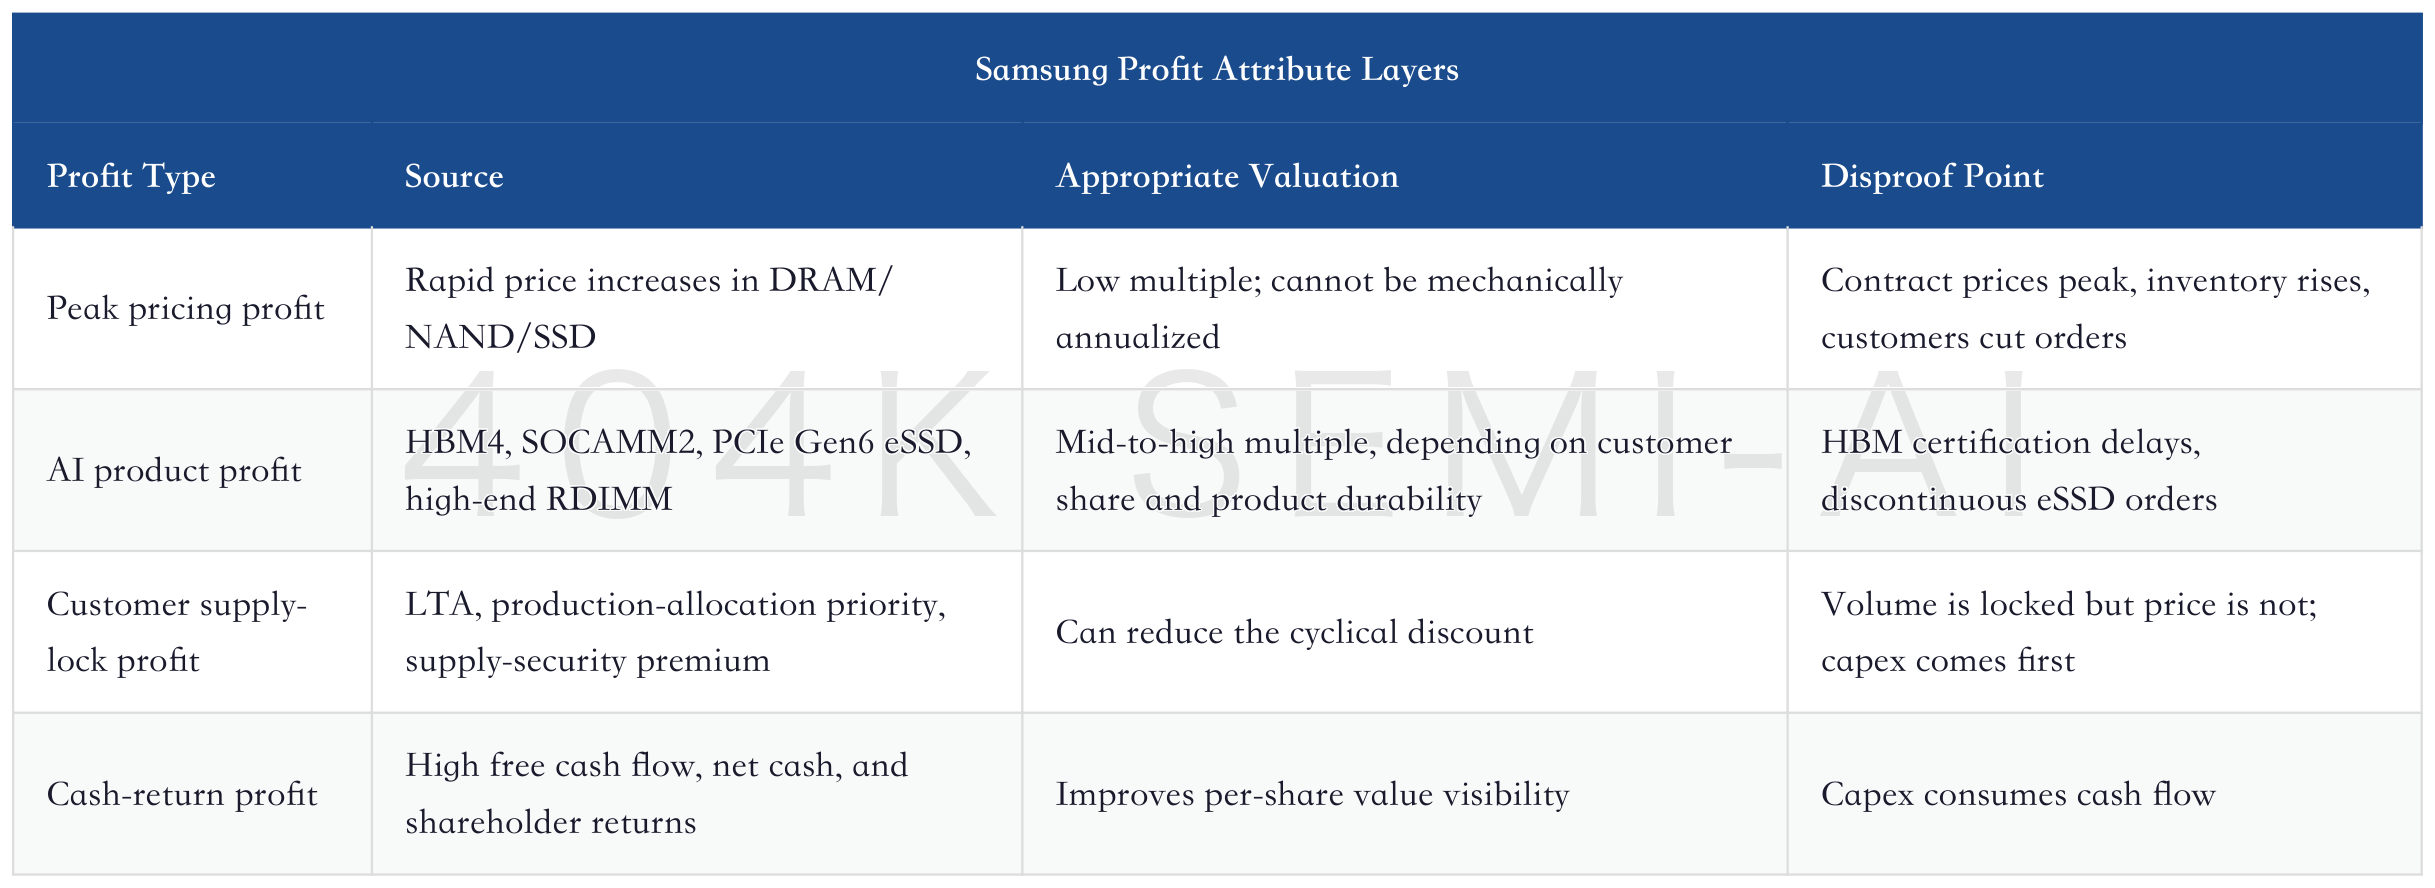
This table is more important than a single target price. Citi’s KRW 530,000 target price first reflects near-term earnings upgrades in valuation; whether the share price can continue to rise depends on whether the second and third types of profit can be proven. If only the first type remains, a low P/E will not protect the stock price; if the second and third types are delivered consistently, Samsung will move from a strong cyclical trade into an asset-attribute re-rating.
8. How Samsung Compares With SK Hynix, Micron, SanDisk, and Kioxia
This memory cycle has moved beyond isolated price increases toward a re-stratification of company attributes. Samsung’s position cannot be ranked only by HBM share, nor only by NAND beta. Its investment value comes from breadth, but that breadth only matters if multiple lines deliver at the same time.
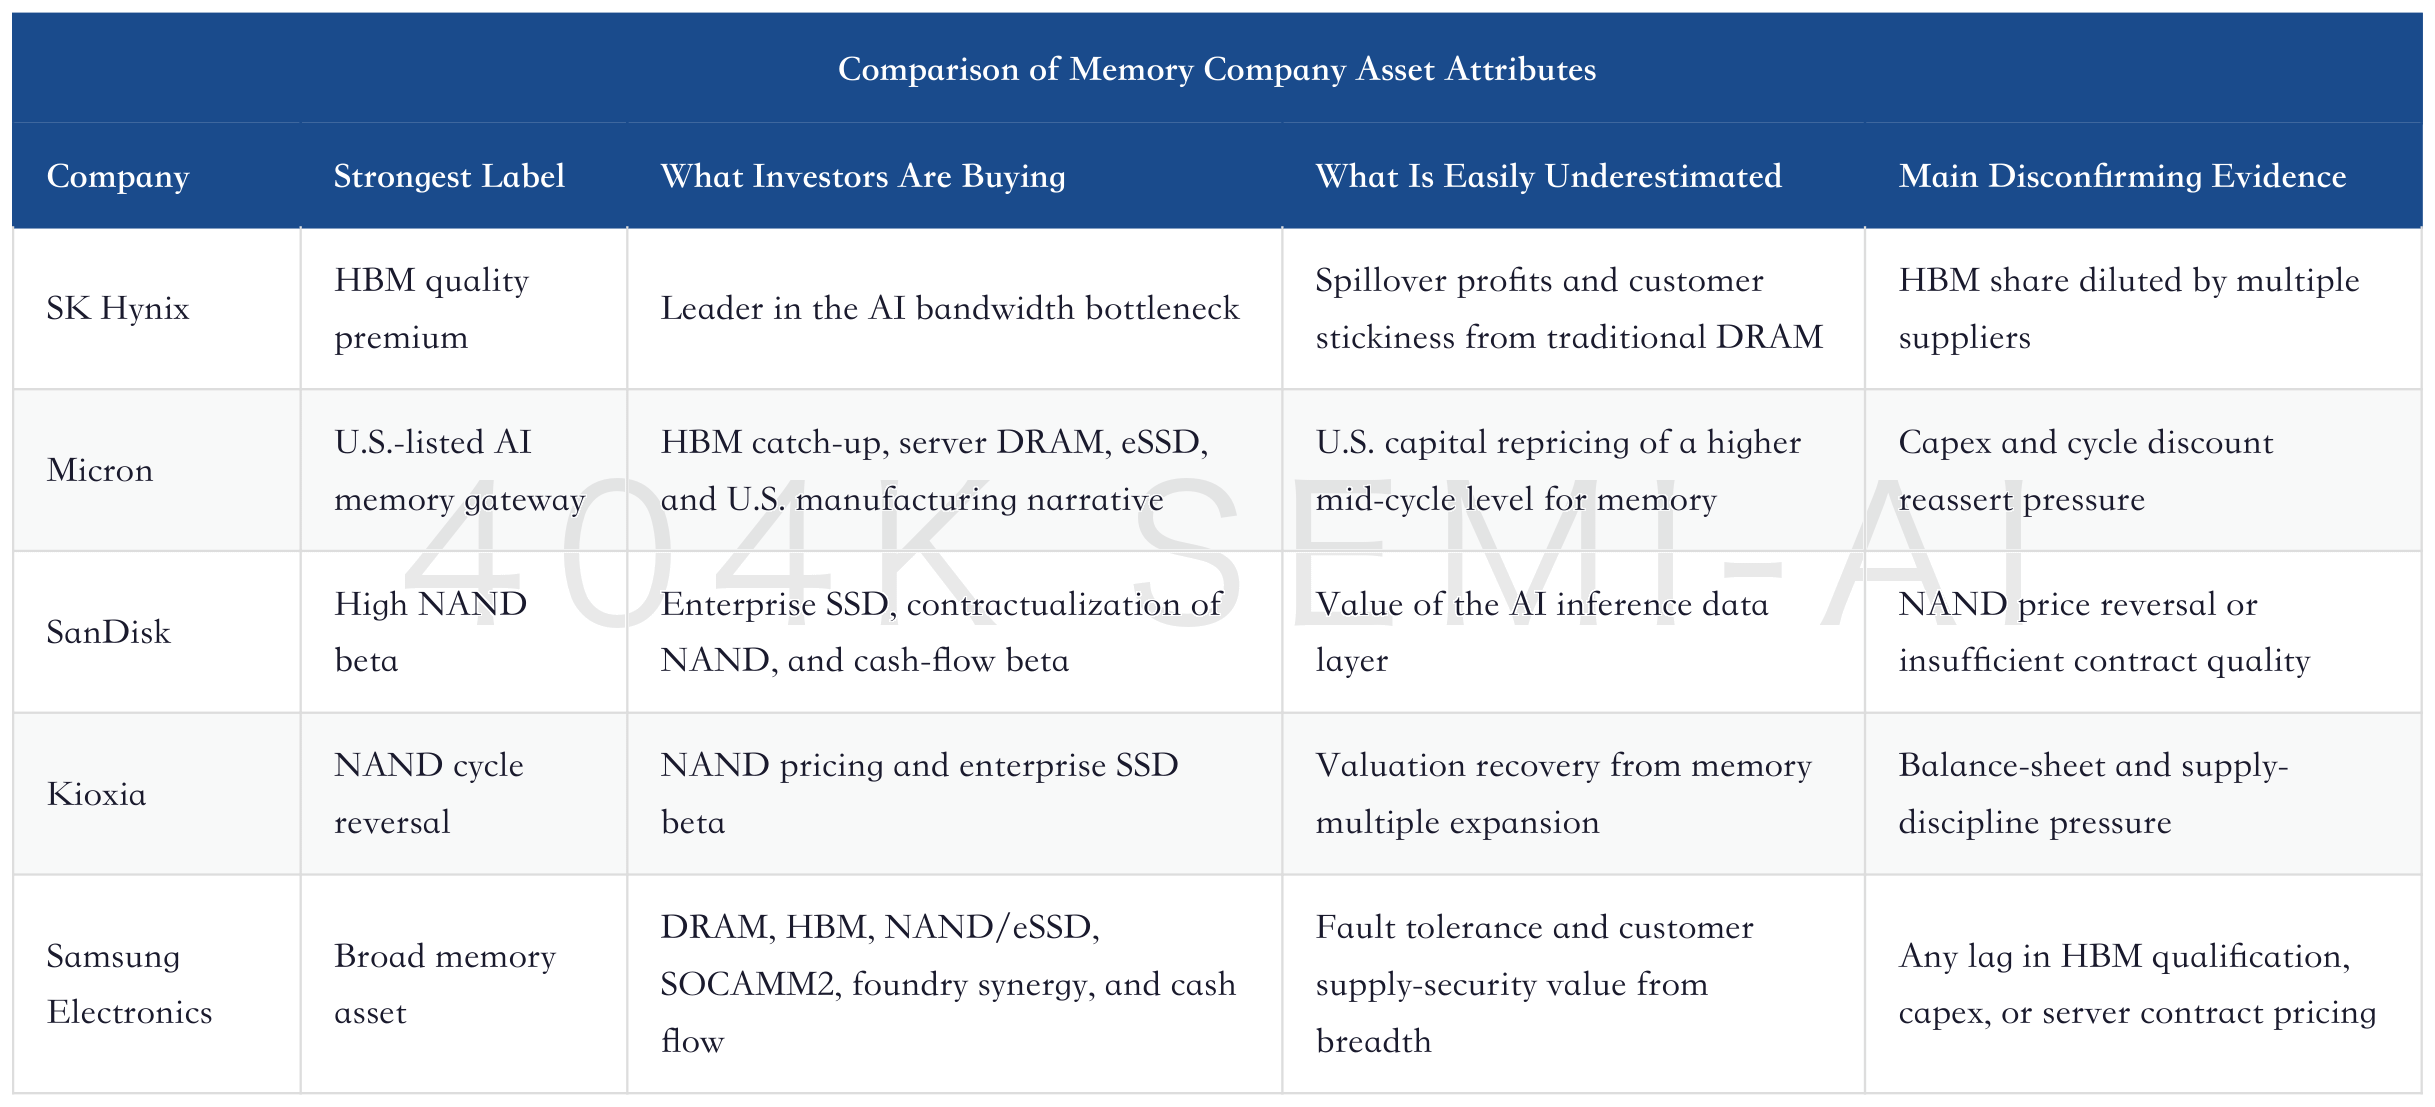
This table shows that Samsung cannot simply be classified as “a slightly weaker Hynix.” Hynix is sharper; Samsung is broader. Micron is easier for U.S. equity capital to reprice, while Samsung’s discount recovery must come through customer qualification, Korean market liquidity, and a reduction in the conglomerate-complexity discount. SanDisk and Kioxia have purer NAND beta. Samsung’s NAND is only the second curve within the portfolio, but it also has server DRAM and HBM.
AI Is Driving a Sector-Wide Revaluation of Memory: Who Has the Most Pricing Power Across DRAM, NAND, SSD, and HDD, as Samsung, SK Hynix, SanDisk, Western Digital, and Seagate Earnings Cross-Validate One Another
