
Samsung Electronics Deep Dive: KRW 89.4 Trillion Quarterly Profit, HBM4 Catch-Up, and Narrowing Foundry Losses
目录
TL;DR
I. Company Profile: Selling Memory, End Devices, and the Combined Value of a Manufacturing Ecosystem
II. How Quickly Profits Were Rewritten: One Quarter Exceeded the Previous Full Year
III. What KRW89.4 Trillion Means: Higher Memory Earnings, but Greater Pressure on End Products
IV. Conventional DRAM and NAND: The Variables That Truly Overturned the Earnings Model
V. HBM4: Mass-Production Sales Are Established, but the Recovery in Leadership Still Hinges on Four Questions
VI. Foundry and System LSI: Loss-Making Today, Potential Synergies Tomorrow
VII. MX and DX: Flagship Smartphones as Both a Cash-Flow Foundation and a Gauge of Memory-Price Pressure
VIII. Samsung Display and Harman: Providing a Buffer, but No Substitute for the Memory Cycle
IX. Capital Expenditure, Net Cash, and Shareholder Returns: Ample Funds, but Every Won Must Earn a Return
10. What Is Vertical Integration Really Worth? Trace Profit Transmission Before Assigning a Synergy Premium
11. How Does It Compare with SK Hynix? Purity Versus Breadth
12. Valuation: KRW530,000–550,000 Depends on Earnings Delivery, Not Multiple Expansion
13. Three Scenarios: Define What Would Change the Thesis Before Forecasting a Precise Price
XIV. What to Watch Over the Next Four Quarters: Distilling the Grand Narrative into 12 Numbers
XV. Conclusion: View Samsung Electronics as a Company First, and a Memory Stock Second
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The market often views Samsung Electronics as a memory stock chasing SK hynix, but KRW 89.4 trillion in quarterly operating profit reveals a more complex business: DRAM and NAND generate cash, HBM4 determines the valuation recovery, smartphones absorb cost pressures, and foundry determines whether synergies can be realized. The key question is whether high profits can translate into sustainable free cash flow.
TL;DR
Samsung Electronics combines a memory profit engine, an end-device revenue base, display and automotive-electronics buffers, and an option on narrowing foundry losses—a business mix distinct from the higher-purity exposure of SK hynix. DS contributed 93.8% of group operating profit in 1Q26, yet represents only part of the company’s value. Treating every other business as a drag would undervalue net cash, internal synergies, and downside protection during cyclical downturns; treating them all as synergistic would overlook how rising memory prices are squeezing smartphones and televisions.
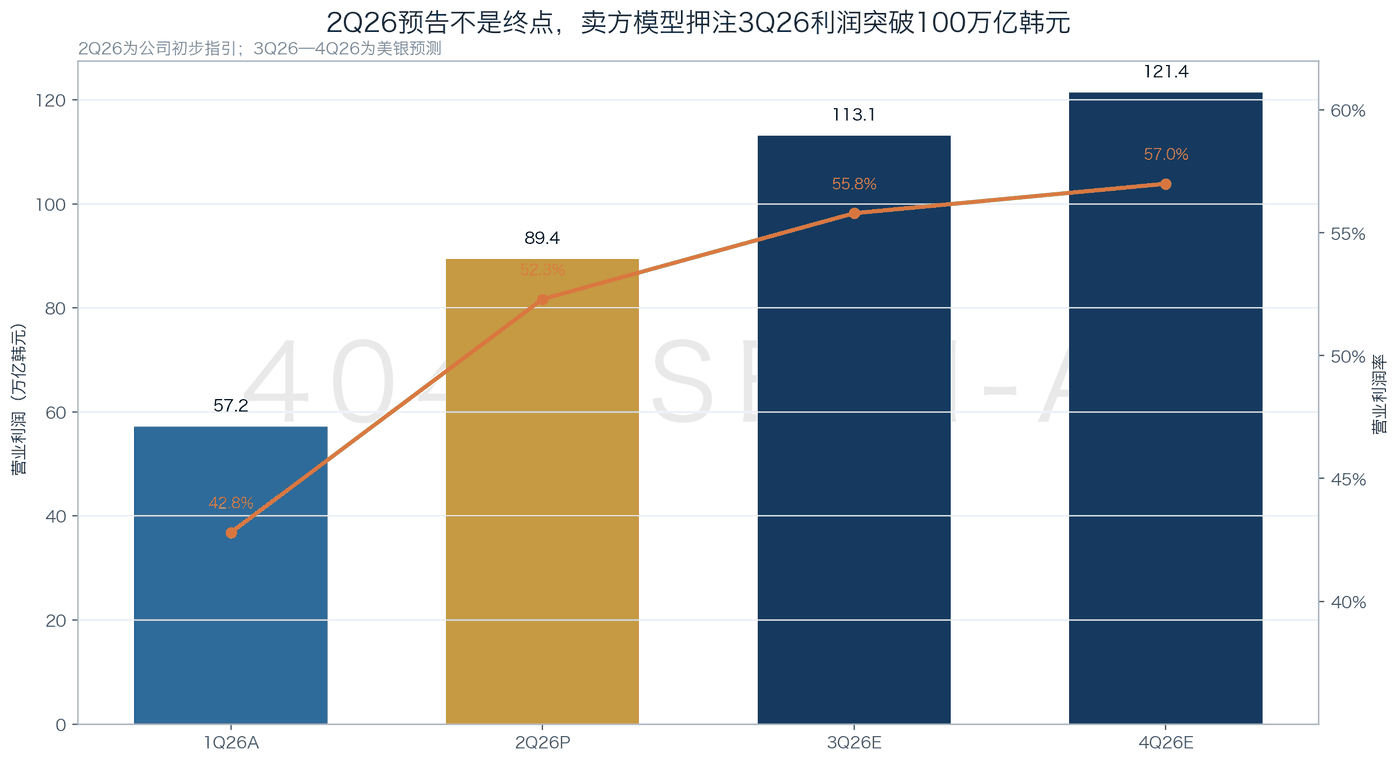
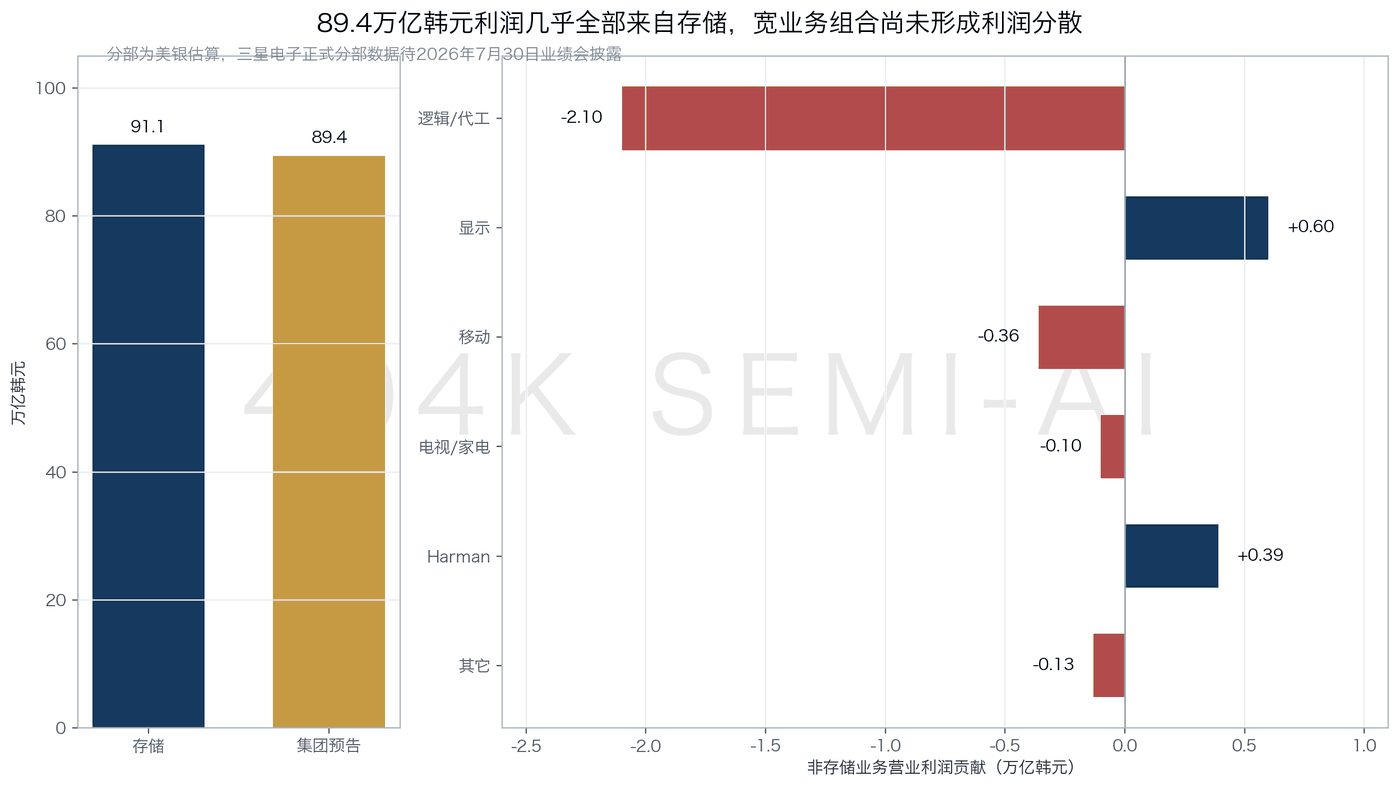
KRW 89.4 trillion in quarterly operating profit primarily demonstrates the strength of conventional memory pricing; it does not by itself prove that HBM leadership has been restored. Preliminary guidance indicates 2Q26 revenue of approximately KRW 171 trillion and operating profit of approximately KRW 89.4 trillion. Bank of America estimates memory operating profit at approximately KRW 91.1 trillion, while foundry, smartphones, televisions, and home appliances remained loss-making in aggregate. Samsung Electronics has confirmed mass-production sales of HBM4 for Nvidia’s Vera Rubin platform, but has not disclosed customer qualification, market share, or product-level profitability.
Profit expectations have undergone a step-change upgrade within six months, while valuation multiples have become more restrained. In January, HSBC and JPMorgan forecast 2026 operating profit of approximately KRW 169–173 trillion; by July, Citi and Bank of America had raised their estimates to KRW 381–401 trillion. Over the same period, Citi lowered its memory valuation multiple from 7.9x to 7.6x, while Bank of America reduced its P/E multiple from 11x to 10x. This indicates that target prices of KRW 530,000–550,000 rely mainly on earnings delivery rather than further multiple expansion.
The investment value of the HBM4 catch-up lies in its ability to drive high-bandwidth memory, 4nm base dies, and advanced packaging simultaneously, but “internal orders” do not necessarily imply “external competitiveness.” Going forward, HBM revenue, customer coverage, yields, 1c process capabilities, and external foundry customers should be assessed separately. If any link falls behind, vertical integration could shift from a source of synergy into a cycle of high capital expenditure and internal costs.
The real stress test begins after 2027. Bank of America forecasts 2027 operating profit of KRW 506.4 trillion and free cash flow of KRW 335.5 trillion, but these figures are neither net income nor company guidance. Its 2028 scenario already assumes 10%–12% declines in both DRAM and NAND average selling prices. If profits decline only modestly at that point, it would suggest that long-term agreements, product mix, and cost improvements have increased earnings durability. If cash flow falls rapidly with prices, the current cycle remains an amplified peak.
I. Company Profile: Selling Memory, End Devices, and the Combined Value of a Manufacturing Ecosystem
Samsung Electronics (005930.KS) is distinctive because the same group operates at both the component and end-device levels. Device Solutions (DS) comprises memory, foundry, and System LSI; Device eXperience (DX) covers smartphones, network equipment, televisions, and home appliances; Samsung Display supplies premium OLED panels; and Harman extends the portfolio into automotive electronics and audio. In 2025, DX generated revenue of KRW 187.97 trillion, exceeding DS revenue of KRW 130.13 trillion, but DS operating profit of KRW 24.86 trillion was nearly twice DX’s. By 1Q26, DS generated quarterly operating profit of KRW 53.66 trillion, accounting for 93.8% of the group’s KRW 57.23 trillion. The revenue base and profit engine have clearly diverged.
Samsung Electronics’ Principal Businesses and Their Role in the Investment Thesis
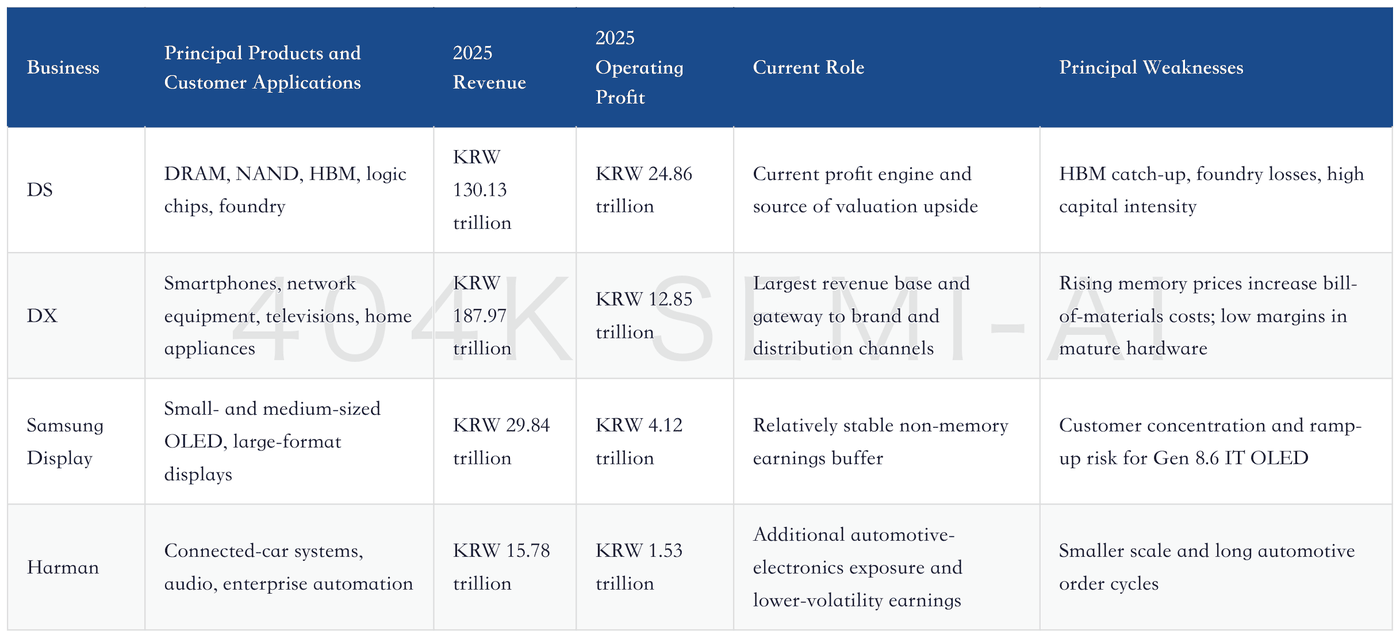
Note: Segment revenue includes intersegment transactions and therefore cannot simply be added together and compared with group revenue. Figures are from Samsung Electronics’ audited 2025 consolidated financial statements.
The market’s most common misreading of Samsung Electronics is to equate business breadth with a conglomerate discount. Breadth does dilute upside leverage to a memory upcycle: smartphones, displays, and automotive products all purchase memory, so rising component prices transfer profit internally from downstream businesses to upstream operations; foundry and System LSI may still absorb several trillion won of profit. Yet this breadth also provides three options unavailable to pure-play memory companies: flagship end devices can provide initial scale for internally developed chips and display products; 4nm logic base dies can create internal synergies for HBM4; and substantial net cash can fund advanced memory, foundry investment, and shareholder returns simultaneously. The investment assessment should not stop at “conglomerates deserve a discount.” It should determine, business by business, which operations generate cash, which merely consume capital, and which are approaching breakeven inflection points.
II. How Quickly Profits Were Rewritten: One Quarter Exceeded the Previous Full Year
Samsung Electronics had already emerged from the previous trough between 2024 and 2025; 1Q26 pushed the earnings trajectory beyond prior models. Group revenue increased from KRW 300.87 trillion in 2024 to KRW 333.61 trillion in 2025, while operating profit rose from KRW 32.73 trillion to KRW 43.6 trillion. In 1Q26 alone, revenue reached KRW 133.87 trillion and operating profit KRW 57.23 trillion, already exceeding full-year 2025 operating profit. Quarterly results cannot be directly annualized against full-year figures, but this demonstrates that the combined impact of memory pricing, product mix, and supply constraints is far greater than in a normal recovery.
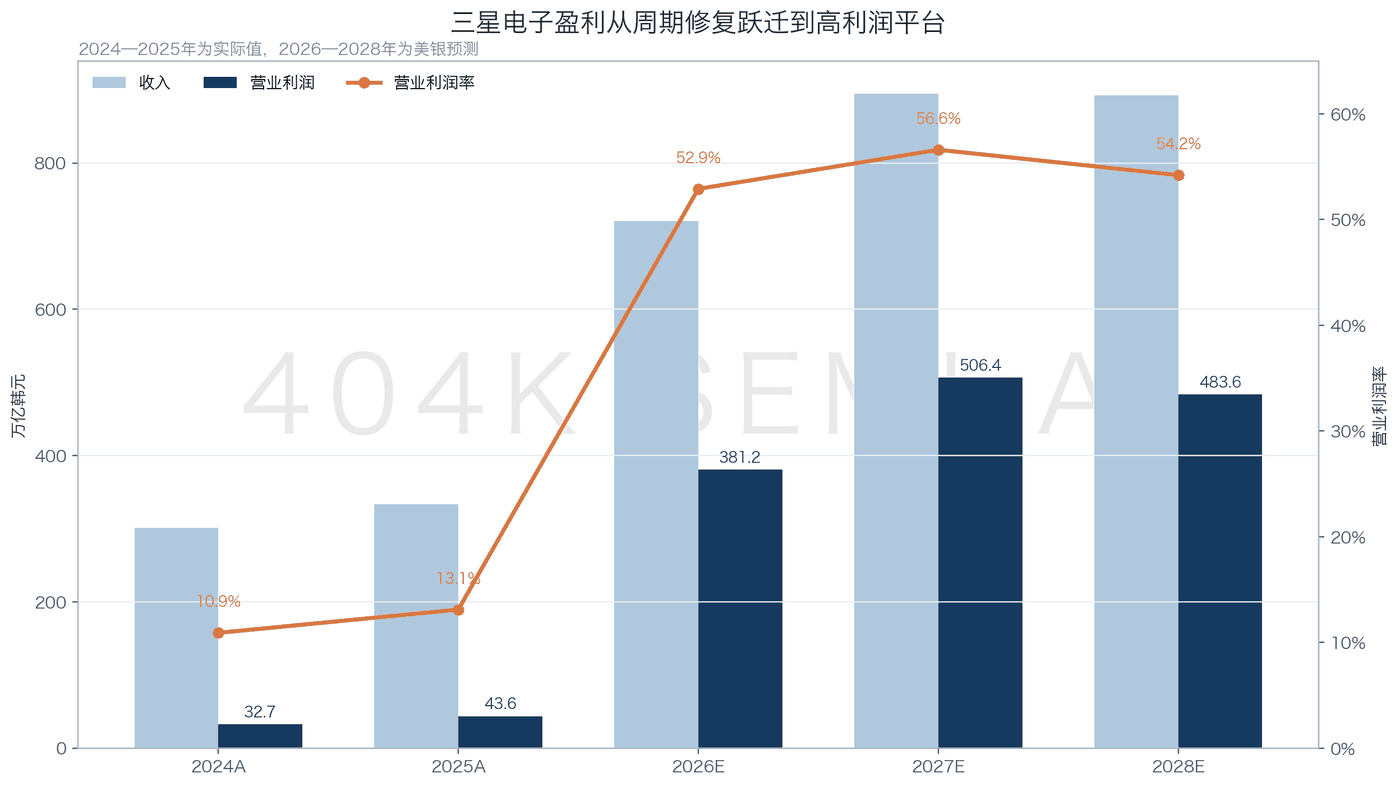
Almost all profit growth came from DS; the other segments did not enter a synchronized boom. In 1Q26, DX generated revenue of KRW 52.65 trillion and operating profit of KRW 2.97 trillion; Samsung Display recorded revenue of KRW 6.69 trillion and operating profit of KRW 360 billion; and Harman posted revenue of KRW 3.83 trillion and operating profit of KRW 220 billion. Profits at DX, Samsung Display, and Harman were all below year-earlier levels. The current earnings structure resembles “single-engine acceleration”: memory has suddenly added thrust, while some other businesses are coasting and others continue to absorb profits.
Cash conversion also requires looking beyond reported profit. Net cash flow from operating activities was KRW 40.27 trillion in 1Q26, below net income of KRW 47.23 trillion. Changes in operating assets and liabilities produced a net outflow of KRW 32.01 trillion, mainly due to increases in accounts receivable and related items. The company retains strong cash-generating capacity, but quarterly profit cannot be treated entirely as freely distributable cash. The most important financial discipline in fundamental research is to distinguish operating profit, net income, operating cash flow, and free cash flow rather than using an exceptionally strong profit figure as a substitute for the entire cash-conversion chain.
III. What KRW89.4 Trillion Means: Higher Memory Earnings, but Greater Pressure on End Products
Samsung Electronics’ preliminary second-quarter guidance, released on July 7, 2026, is the most important new benchmark. The company expects quarterly revenue of approximately KRW171 trillion and operating profit of approximately KRW89.4 trillion. Full segment results will be disclosed with formal earnings on July 30. Accordingly, KRW89.4 trillion can be treated as actual group guidance, but any current breakdown of DRAM, NAND, foundry, smartphone, or display profits remains an institutional estimate and should not be presented as company disclosure.
Bank of America’s second-quarter breakdown highlights the extremity of the profit mix. It estimates memory operating profit at approximately KRW91.1 trillion, foundry and logic-chip losses at approximately KRW2.1 trillion, a DX loss of approximately KRW360 billion, and TV and home-appliance losses of approximately KRW100 billion, while Samsung Display and Harman contributed approximately KRW600 billion and KRW390 billion, respectively. The segment total differs from group guidance because of model eliminations and rounding, but the direction is clear: memory profit exceeded group profit, with loss-making businesses absorbing part of the gains.
The broad business portfolio is amplifying internal cost transmission. Higher memory prices benefit DS revenue and gross margin but create component-cost pressure for MX, TVs, displays, and Harman. Goldman Sachs estimates a KRW320 billion operating loss for MX/NW in the second quarter, potentially marking the mobile business’s first quarterly loss. This reflects special bonuses, seasonality, and the product-launch cycle, but also suggests that higher flagship average selling prices may not be sufficient to offset memory costs. Whether Samsung Electronics can restore end-product profitability in the third and fourth quarters will be the first test of whether KRW89.4 trillion represents a structural uplift in group earnings or the peak of internal profit redistribution.
