
Samsung Electronics 2Q26 Deep Dive: DS Contributes 99.7% of Operating Profit as Memory Booms While End-Product Businesses Swing to Losses
目录
TL;DR
I. Final Figures Were Almost Exactly in Line With Guidance; All the New Information Was in the Profit Mix
II. DS Accounted for Almost All Profits
III. DX’s Swing to a Loss Reveals the Group’s Most Critical Internal Price Transmission
IV. HBM4, HBM4E, and Foundry Are Forming a Second Validation Chain
V. KRW 105.08 Trillion in Operating Cash Flow Is Strong, but Working Capital Cannot Be Ignored
VI. Three Supply-Demand Feedback Loops to Watch in the Second Half
VII. Cross-Check Against the Early-July Preview: Three Confirmations, Two Areas to Temper Expectations
VIII. Five Indicators to Watch Next Quarter to Determine Whether the Record Is a Platform or a Peak
IX. Conclusion: Record Profit Has Been Delivered; What Is Truly Scarce Is Sustainability
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
Operating profit reached another record high of KRW 89.5 trillion, but DX’s swing to a loss shows that rising memory prices are shifting profits upstream; the real tests in 2H26 are HBM4 volume ramp-up, cost pass-through in end products, and 2nm utilization.
TL;DR
The final results did not materially raise the headline figures further; the new information was concentrated in the profit mix. Samsung Electronics reported 2Q26 revenue of KRW 171.5 trillion and operating profit of KRW 89.5 trillion, only KRW 500 billion and KRW 100 billion above the respective midpoints of its July 7 guidance. DS contributed approximately 99.7% of group operating profit, meaning record earnings were driven almost entirely by semiconductors.
Memory has entered an exceptionally profitable phase. DS generated revenue of KRW 127.5 trillion and operating profit of KRW 89.2 trillion, implying an operating margin of approximately 70%; memory revenue reached KRW 120.8 trillion, up 62% QoQ and 471% YoY. A record-high server revenue mix, record-high DRAM and NAND bit shipments, and expanding HBM4 sales collectively show that earnings were lifted by server-memory pricing, volume, and product mix—not by reliance on a single high-end product.
The group-wide boom is uneven. DX recorded revenue of KRW 48 trillion and an operating loss of KRW 800 billion, including a loss of KRW 700 billion at MX/NW; the company explicitly attributed the earnings decline to rising industry component costs. While Samsung Electronics earns enormous profits from memory shortages, its smartphone, television, and home-appliance businesses are bearing higher costs. This both validates upstream pricing power and exposes, ahead of time, the limits of downstream demand’s capacity to absorb those costs.
The HBM story is moving from qualification to product iteration. The company confirmed that HBM4 sales are expanding and that it has delivered the industry’s first HBM4E samples to major customers; Foundry is also benefiting from demand for HBM base dies, advanced-node orders, and improving utilization. The validation bar for the next phase has risen: HBM4 must continue ramping in volume, HBM4E must move from samples to orders, and 2nm and 4nm must convert design wins into revenue.
Earnings have strong cash backing, but the balance sheet still has pressure points. Second-quarter cash flow from operating activities was KRW 105.08 trillion, equivalent to 146.7% of net income; after deducting KRW 14.11 trillion of fixed-asset purchases, simplified residual cash was KRW 90.97 trillion. Meanwhile, accounts receivable increased 17.2% QoQ, inventories rose 22.5%, and investments grew 91.9%, indicating that rapid growth is also consuming more capital; the increase in reported cash cannot be viewed in isolation.
The underlying 2H26 outlook remains strong, but the evaluation criteria must change. Management expects demand for server DRAM, enterprise SSDs, and HBM to remain robust, and the industry may remain undersupplied even if production increases; however, smartphone and PC demand has already shown localized softness. Samsung Electronics’ next leg no longer depends solely on how high memory prices can rise, but on how long elevated prices can be sustained, whether DX can absorb the costs, whether Foundry can reduce its drag, and whether cash can continue to be returned to shareholders.
I. Final Figures Were Almost Exactly in Line With Guidance; All the New Information Was in the Profit Mix
Samsung Electronics’ July 7 guidance range for 2Q26 was revenue of KRW 170 trillion–KRW 172 trillion and operating profit of KRW 89.3 trillion–KRW 89.5 trillion; the final figures released on July 30 were KRW 171.5 trillion and KRW 89.5 trillion, respectively. In other words, revenue was KRW 500 billion above the midpoint of the range, while operating profit was KRW 100 billion above the midpoint and at the top end of the range. It would be inaccurate to characterize the change from preliminary guidance to final results as another major upside surprise.
The value of the final materials lies in completing the consolidated income statement, segment results, financial position, and cash-flow picture. Revenue increased 28% QoQ and 130% YoY, while operating profit rose 56% QoQ and 1,814% YoY; the operating margin increased from 42.8% in 1Q26 to 52.2%. Gross margin rose from 61.2% to 69.6%, while cost of sales edged up only slightly from KRW 52 trillion to KRW 52.2 trillion. The combination of sharply higher revenue and virtually unchanged costs indicates that pricing and product mix were the key drivers of the margin expansion.
One important qualification must be retained: Samsung Electronics’ official 2Q26 consolidated financial information explicitly states that the figures are consolidated under K-IFRS, but the external review has not yet been completed, and the review results may still lead to adjustments to certain items. As of publication, Samsung Electronics IR’s financial-statements page had also not yet separately posted the reviewed 2Q26 version. Accordingly, this report treats pages 5 and 12–15 of the official materials as the current actual figures, while not presenting them as the final reviewed results.
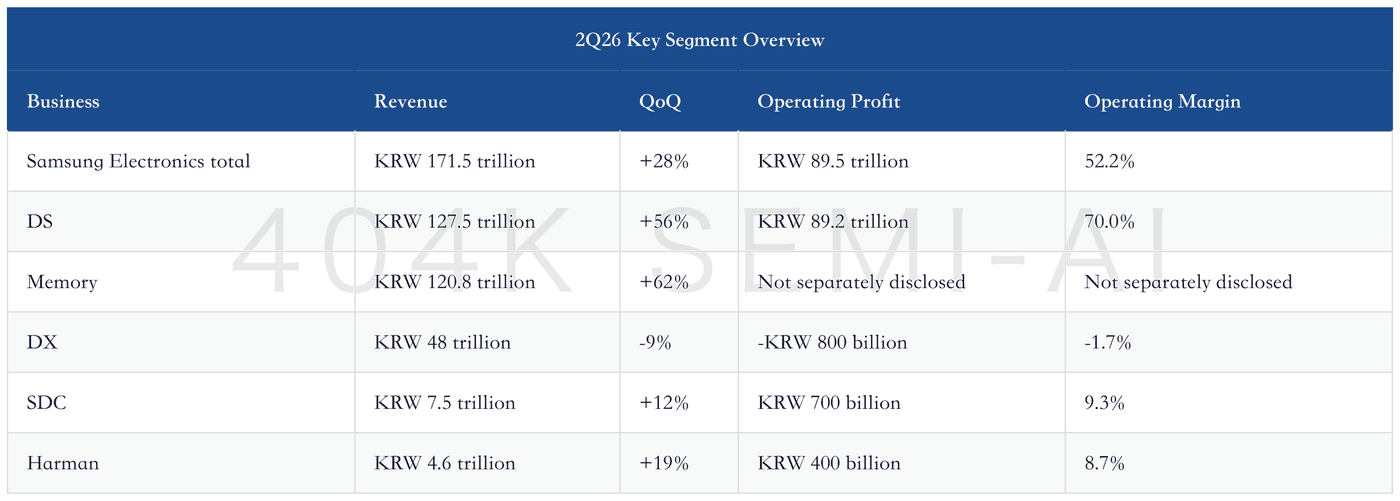
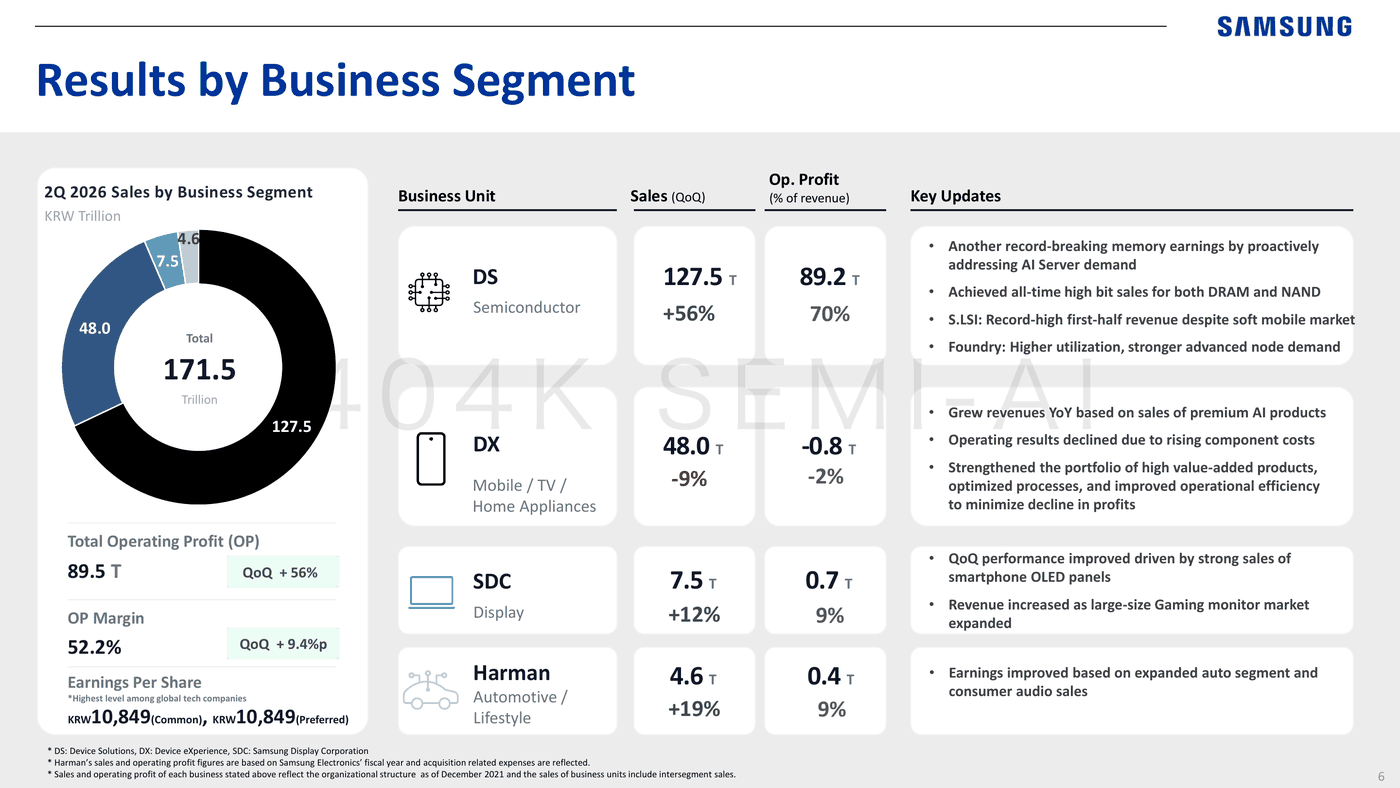
Chart: Samsung Electronics’ official 2Q26 segment results. Segment sales include intercompany transactions and therefore cannot be added directly to consolidated revenue without adjustments.
II. DS Accounted for Almost All Profits
DS generated operating profit of KRW 89.2 trillion this quarter, versus group operating profit of KRW 89.5 trillion. Based on the official figures, DS contributed 99.7%. This goes beyond semiconductors merely being the largest business: Samsung Electronics is currently, in effect, a diversified group whose earnings are supported by semiconductor profits while its other businesses collectively consume revenue and capital.
DS operating profit increased 66.1% QoQ, with an operating margin of approximately 70%. Memory revenue of KRW 120.8 trillion was equivalent to 70.4% of consolidated group revenue based on segment disclosures. However, because segment revenue includes intercompany transactions, this ratio is useful only for assessing the business’s scale and cannot be treated as the precise post-elimination revenue mix. More importantly, the company did not separately disclose memory operating profit, so external models’ breakdowns of DRAM, NAND, and HBM margins remain estimates and cannot substitute for the official segment results.
The operating evidence provided by management is internally consistent: DRAM and NAND bit shipments both reached record highs, the server revenue mix hit a record high, the company prioritized AI-server demand amid limited capacity, and industry pricing continued to rise. This quarter’s incremental profit was jointly driven by server DRAM, enterprise SSDs, HBM, and conventional memory, with pricing, volume, and product mix all contributing.
The central reason the market previously applied a discount to Samsung Electronics was its lag in high-end HBM and the excessive cyclicality of conventional DRAM and NAND. 2Q26 changed half of that thesis: conventional memory not only ceased to be a drag but instead became the foundation of the earnings surge. The other half has not yet been fully resolved—whether sustained HBM4 shipments can narrow the gap with industry leaders. High profits have already materialized, but the company’s competitive position must still be validated quarter by quarter.
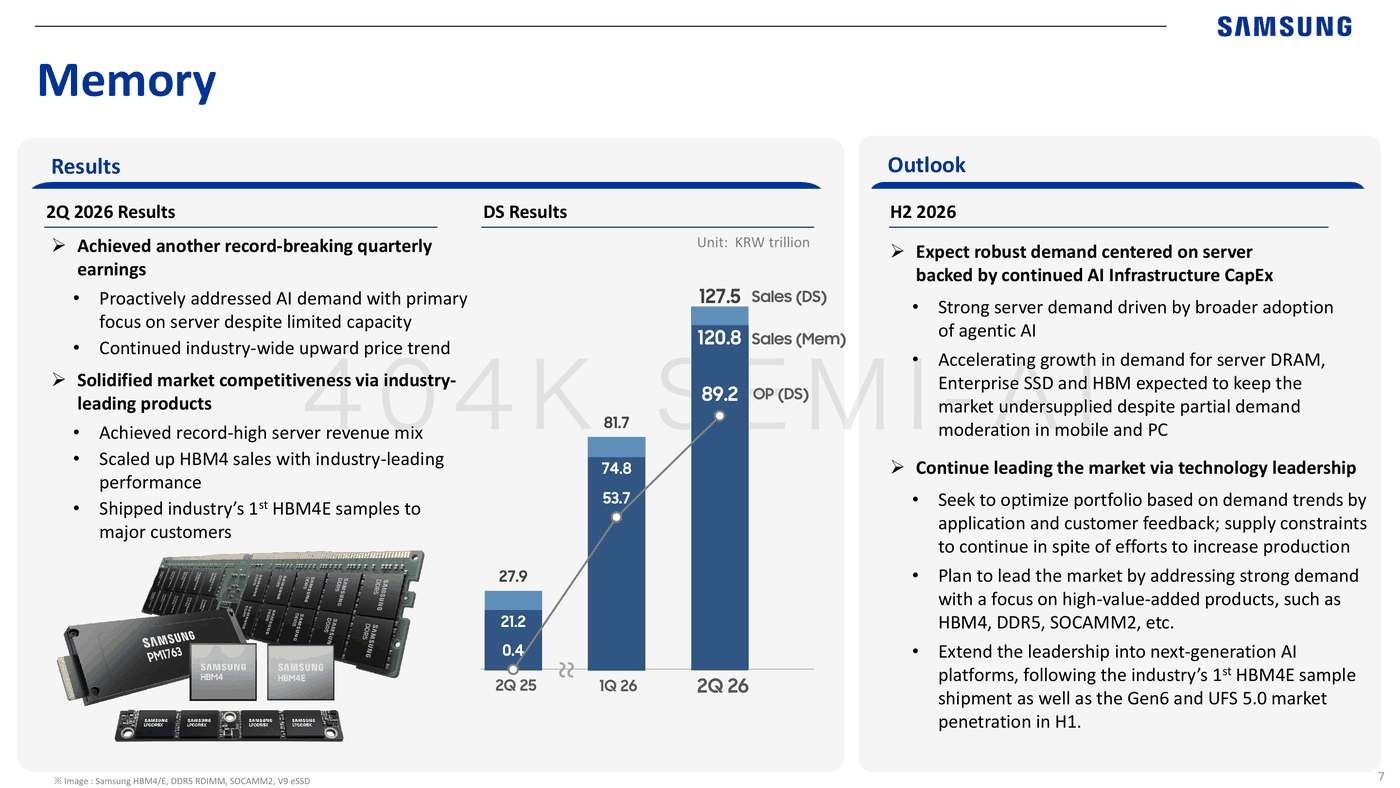
Chart: Samsung Electronics confirmed expanding HBM4 sales and expects demand for server DRAM, enterprise SSDs, and HBM to remain strong in 2H26.
III. DX’s Swing to a Loss Reveals the Group’s Most Critical Internal Price Transmission
DX revenue still grew 10% YoY this quarter but declined 9% QoQ, while operating profit swung from KRW 3 trillion in 1Q26 to a loss of KRW 800 billion, representing a quarterly profit swing of KRW 3.8 trillion. MX/NW revenue was KRW 33.2 trillion, up 14% YoY and down 13% QoQ, while operating profit swung from KRW 2.8 trillion to a loss of KRW 700 billion. The divergence between revenue growth and the reversal into a loss points directly to cost and product-mix pressure.
Management’s explanation for MX was straightforward: flagship models and the A series supported YoY revenue growth, but elevated industry-wide component costs weighed on profitability. VD/DA also approached breakeven due to rising costs. Because Samsung Electronics operates both upstream memory and downstream devices, it reveals the two-sided impact of price increases earlier than a pure-play memory vendor: stronger upstream pricing lifts DS profit, but if downstream businesses cannot raise prices or optimize configurations in time, DX profit will be compressed.
This cannot simply be interpreted as an accounting transfer of profit within the group, because segment pricing, procurement sources, and the external sales mix have not been fully disclosed. However, in economic terms, tight memory supply and demand have already become sufficient to alter the profitability of the device businesses. DX’s loss is therefore both bad news and compelling industry evidence: memory pricing power has moved from quotation sheets into customers’ income statements.
It also provides a leading indicator for the upper end of the cycle. If smartphone and PC manufacturers absorb costs through price increases, specification reductions, or scaled-back promotions, memory demand will eventually face a negative feedback effect. If new products can still sustain unit sales and customers accept long-term orders and higher configurations, elevated prices will persist for longer. To assess whether demand is being destroyed, investors need not wait for memory prices to reverse; they can first monitor whether Samsung Electronics’ MX/NW margin recovers.
IV. HBM4, HBM4E, and Foundry Are Forming a Second Validation Chain
The formal materials contained two key statements on HBM: first, HBM4 sales have already expanded; second, the company has delivered the industry’s first HBM4E samples to major customers. The former means HBM4 is no longer merely progressing through qualification and has begun contributing revenue. The latter means next-generation competition has started early, but “sample delivery” still cannot be equated with completed customer qualification or the award of volume orders.
This also corrects the wording used at the preliminary-results stage. In early July, sell-side materials cited “HBM4 revenue exceeding USD 1 billion” as an important anchor, but the final official materials did not disclose this figure. This report therefore no longer treats USD 1 billion as an actual figure confirmed by the company. What the official materials confirm is expanded sales, product performance, and HBM4E samples; what they do not confirm is the customer mix, specific revenue, yield, or market share. Drawing this boundary clearly makes it easier to track the actual incremental contribution next quarter.
Foundry provides another avenue of synergy for HBM. The company said quarterly revenue was driven by demand for HBM base dies and orders from overseas customers, advanced-node utilization increased, and it continued to win 2nm HPC design orders. In the second half, it plans to promote sales of its second-generation 2nm mobile process, 4nm LPU, and base dies, targeting double-digit revenue growth. If Samsung Electronics can simultaneously provide memory stacks, base dies, and advanced-node manufacturing, it could theoretically channel spillover HBM demand into Foundry.
However, the official materials did not separately disclose S.LSI/Foundry operating profit, making it impossible to prove that the business is already profitable. At this stage, the more reasonable assessment is that “utilization is improving and loss pressure may be narrowing,” rather than declaring that the foundry business has completed a turnaround. The evidence truly required is 2nm mass-production yield, external-customer revenue, conversion of HPC orders into mass production, and Foundry’s standalone contribution to DS profit.
V. KRW 105.08 Trillion in Operating Cash Flow Is Strong, but Working Capital Cannot Be Ignored
Second-quarter net profit was KRW 71.62 trillion, cash flow from operating activities was KRW 105.08 trillion, and cash conversion reached 146.7%. Purchases of fixed assets were KRW 14.11 trillion; subtracting this amount from operating cash flow produces a simplified cash surplus of KRW 90.97 trillion. This is not the company’s definition of free cash flow, but it is sufficient to show that quarterly profit was not confined to accrual items.
Cash flow also supported proactive deleveraging and shareholder returns: net cash outflow from financing activities was KRW 17.89 trillion, including KRW 6.06 trillion in net debt repayments, KRW 5.63 trillion in treasury-share repurchases, and KRW 6.21 trillion in dividends paid. Period-end cash was KRW 190 trillion, while net cash was KRW 167.59 trillion, up 40.5% from the end of March. For a capital-intensive semiconductor company, this balance sheet provides simultaneous buffers for technology investment, cyclical volatility, share repurchases, and dividends.
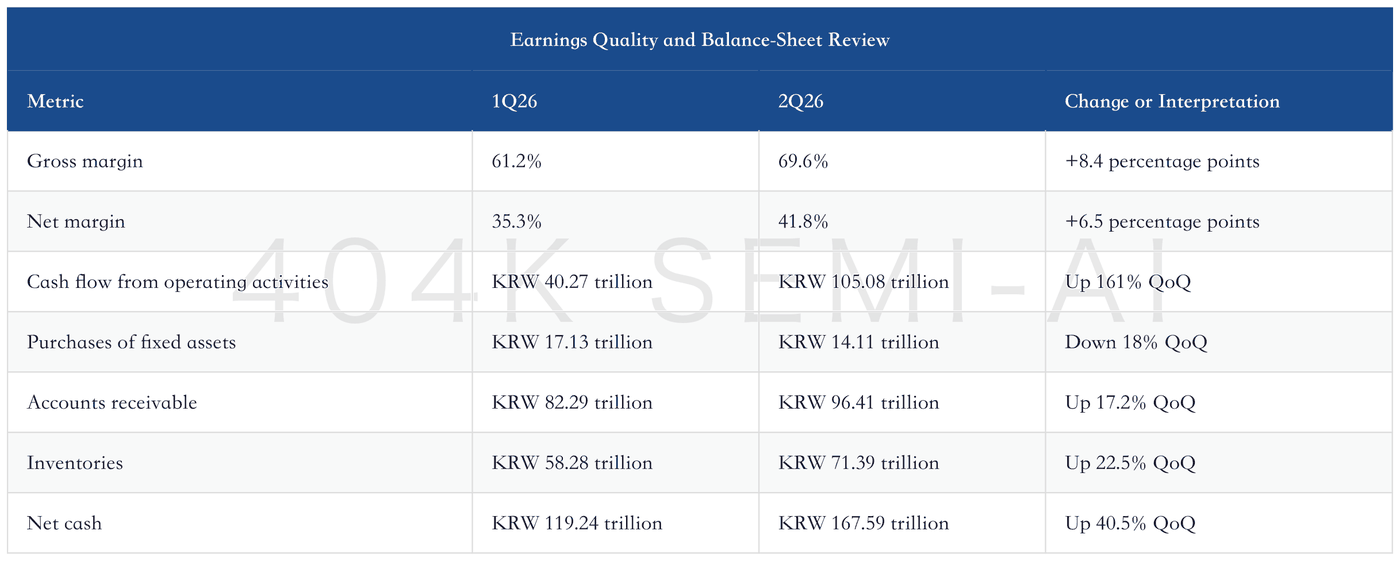
The caveat is that cash growth does not mean every change in assets is free of pressure. Accounts receivable increased by KRW 14.12 trillion QoQ, inventories increased by KRW 13.11 trillion, and investments on the balance sheet rose from KRW 54.62 trillion to KRW 104.82 trillion. The company did not further break down the composition of the increase in investments in these materials, nor did it disclose changes in raw materials, work in progress, and finished goods within inventories. It would therefore be premature to attribute these movements categorically to capacity expansion or weakening demand.
Two combinations should be monitored going forward. If operating cash flow continues to cover the increase in working capital and inventory growth corresponds to the ramp-up of high-value products, the balance sheet will remain healthy. If receivables and inventories continue to grow faster than revenue while DX demand simultaneously weakens, high profit may be accompanied by longer collection cycles and rising inventory risk.
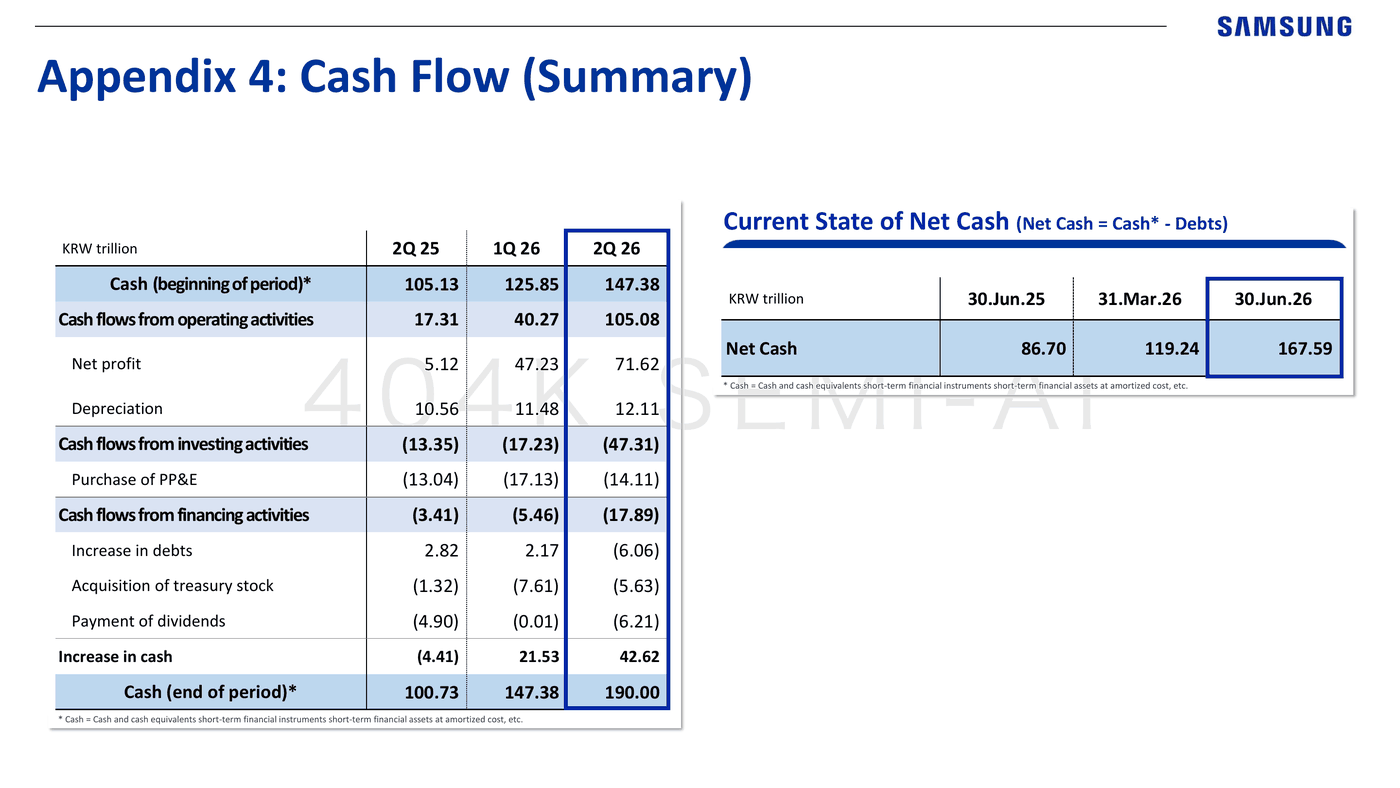
Figure: Samsung Electronics generated KRW 105.08 trillion in cash flow from operating activities in 2Q26 and ended the period with net cash of KRW 167.59 trillion.
VI. Three Supply-Demand Feedback Loops to Watch in the Second Half
Management remains positive on second-half memory demand: broader adoption of Agentic AI will support server demand, while demand for server DRAM, enterprise SSDs, and HBM will continue to grow. Even as the company works to increase output, industry supply may still fall short of demand. The company will continue shifting its product mix toward HBM4, DDR5, and SOCAMM2, while advancing GEN6 and UFS 5.0.
The first feedback loop comes from supply. Purchases of fixed assets did not surge in tandem with profit this quarter, while the company continued to emphasize capacity constraints. This indicates that near-term bottlenecks may not be resolved simply by “building more fabs”; they may also involve advanced-node yields, packaging capacity, product transitions, and customer qualification. If HBM4 and server products consume more resources, supplies of conventional mobile and PC memory may remain tight. Conversely, rapid yield improvements may release more effective supply.
The second feedback loop comes from end markets. The company has already acknowledged localized slowdowns in mobile and PC demand, while DX swung to a loss due to component costs. In the second half, the Galaxy Z FOLD8, S26 series, and smart glasses will be tasked with improving the premium product mix. If the new products can raise prices while sustaining unit sales, DX margins are expected to recover. If consumers lengthen replacement cycles and channels step up promotions, high memory prices will feed back through end demand and constrain upstream suppliers.
The third feedback loop comes from non-memory businesses. SDC needs to expand through premium smartphone panels, gaming monitors, and mass production of 8.6G IT OLED; Harman needs growth from automotive central computing and audio; and Foundry needs 2nm, 4nm, and HBM base dies to raise utilization. These businesses do not need to replicate DS margins in the near term. As long as they shift from being a drag to making stable contributions, group profit will become less sensitive to a single memory cycle.
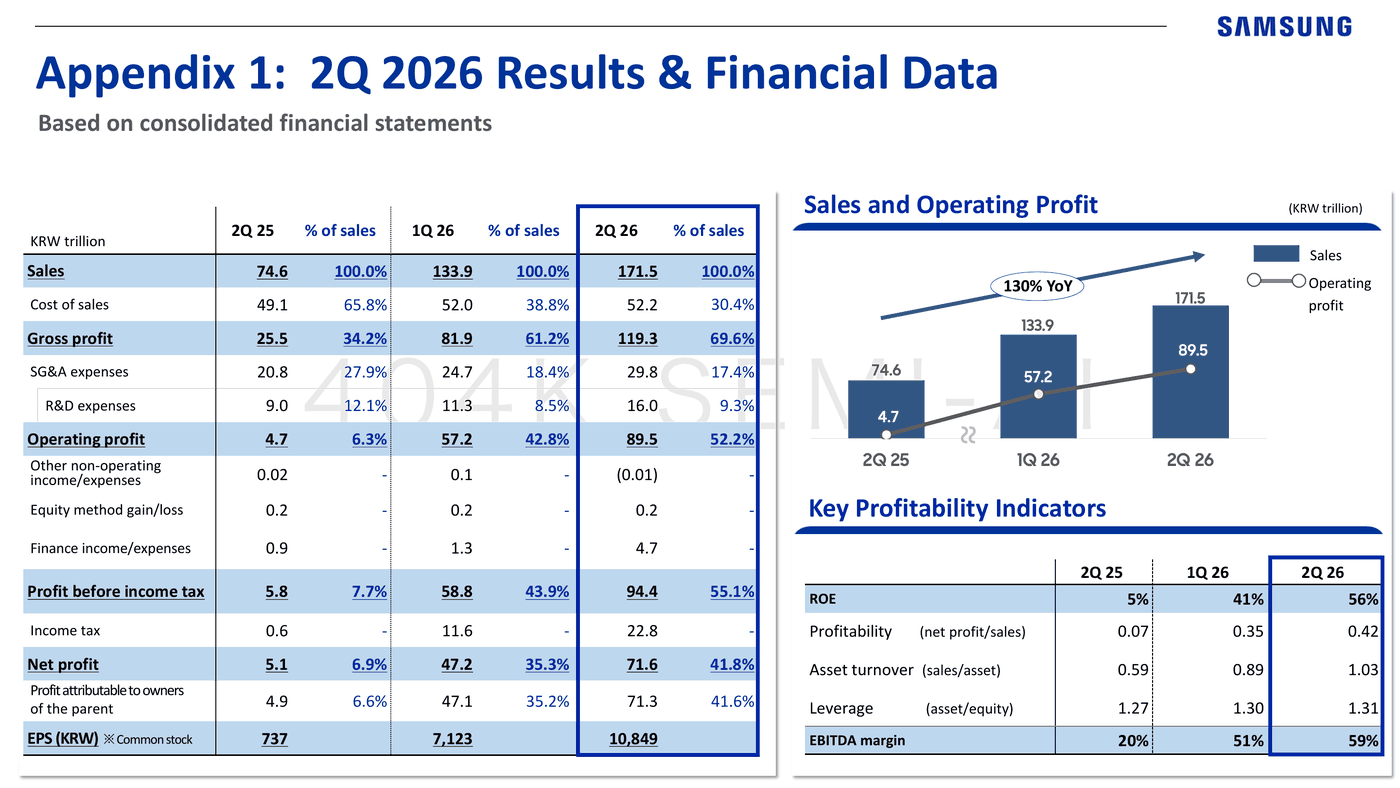
Figure: Samsung Electronics’ 2Q26 gross margin was 69.6%, operating margin was 52.2%, and net margin was 41.8%, all continuing to rise from 1Q26.
VII. Cross-Check Against the Early-July Preview: Three Confirmations, Two Areas to Temper Expectations
The early-July analysis of Samsung Electronics’ 2Q26 preview proposed three hypotheses to be tested: memory had entered a high-profit phase, the mobile business might swing to a loss, and HBM4 was moving from qualification to revenue. The full earnings report provided directional confirmation of all three—memory revenue and the DS margin rose sharply, MX/NW officially posted a loss, and HBM4 sales expanded.
The first area requiring tempered expectations is “core operating profit exceeding KRW 100 trillion.” That was an adjusted figure calculated by sell-side analysts based on bonus provisions. Samsung Electronics’ official materials confirmed only KRW 89.5 trillion in operating profit and did not provide adjusted core profit. Analyzing one-off expenses is valuable, but once the full earnings report is released, the report’s primary anchor should revert to the company-disclosed figure; model-adjusted metrics should not override the consolidated financial statements.
The second area requiring tempered expectations is using a single HBM figure as a proxy for the entire memory chain. The strongest evidence in the official materials is not an unconfirmed revenue figure, but the simultaneous occurrence of memory revenue reaching KRW 120.8 trillion, record-high DRAM and NAND bit shipments, a record-high server revenue mix, and expanding HBM4 sales. Samsung Electronics’ advantage this quarter remains breadth: HBM determines its technological catch-up and valuation upside, server DRAM and enterprise SSDs underpin the profit base, and demand from traditional end markets determines the cycle’s upper bound.
This also means that the analytical framework after 2Q26 should shift from “did earnings beat expectations?” to “can profits be replicated quarter after quarter?” The preview had already disclosed total profit to the market. The full earnings report’s real task was to identify which businesses generated that profit, whether it translated into cash, and whether high prices might impair downstream demand.
VIII. Five Indicators to Watch Next Quarter to Determine Whether the Record Is a Platform or a Peak
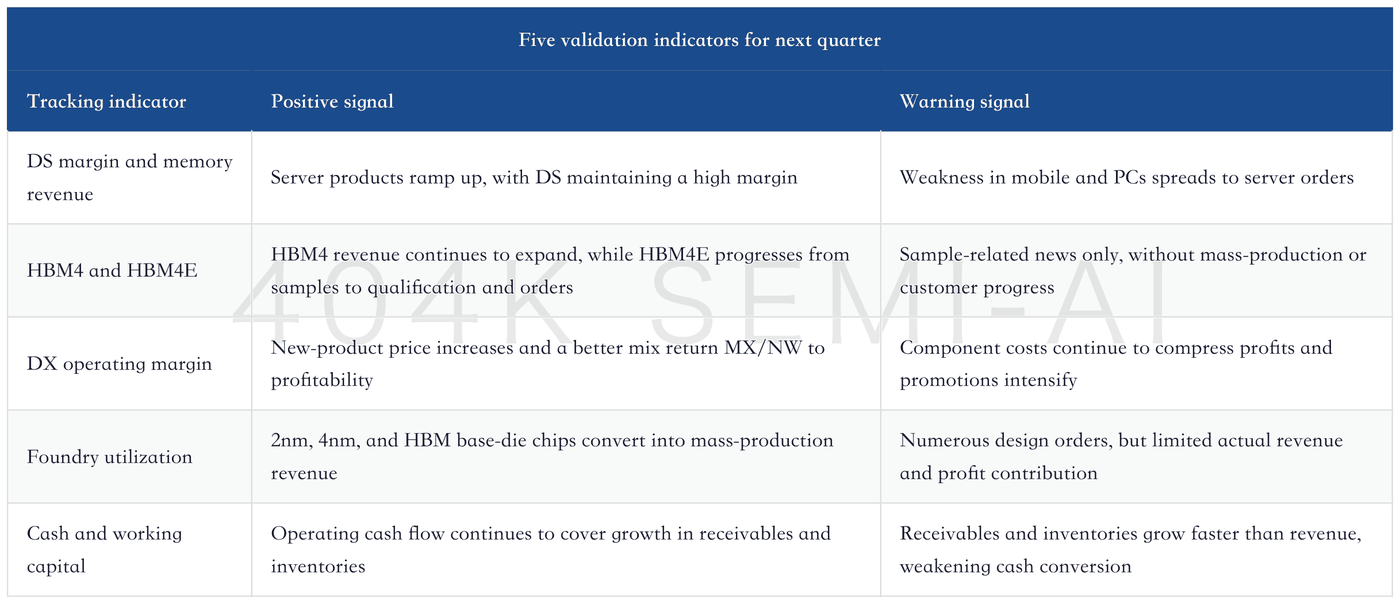
Under the base case, server demand remains strong, tight memory supply persists, and DS continues to contribute the vast majority of profit, but a recovery in DX profit will take time. A more bullish scenario would involve a large-scale HBM4 ramp, accelerated HBM4E qualification, and higher Foundry utilization, while DX absorbs component costs through new products and price increases. Samsung Electronics would then move beyond being a “beneficiary of the memory cycle” and closer to becoming an “integrated AI infrastructure platform.”
The downside scenario is equally clear: weakness in mobile and PCs spreads to servers, while customers reduce specifications or defer purchases because of high prices; HBM4E remains at the sample stage, and Foundry orders fail to translate into utilization; receivables and inventories continue to grow faster than revenue. If any two of these occur simultaneously, the current 70% DS operating margin is more likely to be viewed by the market as a cyclical peak rather than a new earnings platform.
IX. Conclusion: Record Profit Has Been Delivered; What Is Truly Scarce Is Sustainability
Samsung Electronics’ 2Q26 results no longer need to be framed as “above expectations.” Final revenue and profit were almost exactly in line with the preview. What truly warrants reassessment is the full segment and cash-flow disclosure: DS contributed 99.7% of operating profit, memory revenue reached KRW 120.8 trillion, DX swung to a loss, and cash flow from operating activities reached KRW 105.08 trillion. Together, these 4 figures present a more accurate picture than the group-level record—upstream memory is exceptionally strong, downstream end markets are under pressure, profit conversion into cash is excellent, but concentration is also extremely high.
In the short term, server DRAM, enterprise SSDs, HBM4, and industry supply constraints continue to support high profits. Over the medium term, HBM4E, 2nm, 4nm, and 8.6G IT OLED provide new validation points. The counterweights are DX cost pressure, slowing mobile and PC demand, and rising receivables and inventories. Samsung Electronics has sufficient net cash and R&D; investment to navigate volatility, but a strong balance sheet does not automatically mean margins can remain elevated permanently.
Therefore, the most accurate summary of these results is not that “all businesses are prospering together,” but that “the memory boom pushed group profit to a record while bringing end-market cost pressure to the forefront.” If DS maintains high profitability next quarter, DX returns to profit, HBM4E progresses to orders, and Foundry utilization continues to improve, KRW 89.5 trillion will look more like the starting point of an earnings platform. If end-market demand destruction and working-capital pressure rise simultaneously, it will look more like an impressive number at the top of the cycle.