
Samsung Electro-Mechanics Deep-Dive Update: Goldman Sharply Raises Estimates as AI Servers Push MLCCs, Silicon Capacitors, and ABF onto the Same Income Statement
目录
Too Long; Didn’t Read
1. What Goldman’s New Report Adds: From Materials Story to Income-Statement Rewrite
2. Samsung Electro-Mechanics: Three AI Profit Lines Are Put into the Same Table for the First Time
III. MLCC: AI Servers Are Not Buying Tiny Capacitors, but High-End Effective Capacity
IV. Silicon Capacitors: Samsung Electro-Mechanics’ Key Step from Board-Level Components Toward the Package Vicinity
V. ABF: Samsung Electro-Mechanics Is the Profit Mainline; LG Innotek Is a Low-Base Option
VI. LG Innotek: Target Price Raised, but Valuation Is Still Pulled Back to Reality by Camera Modules
VII. Mapping to Asian and Chinese Assets: Find the Gates First, Then the Companies
8. Three Scenarios: Can Samsung Electro-Mechanics Move from Cyclical Stock to AI Hardware Compound Asset?
9. What to Watch Over the Next Four Quarters: Orders, ASP, Margins, and Customer Proliferation
10. Samsung Electro-Mechanics' Identity Shift: From Consumer Electronics Components to an AI Hardware Bottleneck Portfolio
XI. Margin Matters More Than Revenue: What Goldman’s Model Is Really Betting On Is Structural Upgrade
XII. The Right Way to Read LG Innotek: The Camera Business Sets the Base, ABF Determines the Upside
XIII. Discipline in Mapping the China Supply Chain: Do Not Substitute Concepts for Orders
14. Disconfirmation Checklist: What Could Break Goldman’s Model
15. Valuation Discipline: Replace One-Off Target-Price Worship with a Verification Sequence
Conclusion: Samsung Electro-Mechanics Looks Like a Core Asset; LG Innotek Looks Like an Option Asset
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The value of Goldman’s Korea electronic components update is not another claim that AI servers drive MLCC demand. It is that Goldman puts Samsung Electro-Mechanics’ MLCCs, silicon capacitors, and ABF substrates into the same income statement: three lines jointly steepening the earnings slope, while also reminding investors that LG Innotek’s ABF upside remains constrained by its core Apple camera business.
Too Long; Didn’t Read
Samsung Electro-Mechanics is the main line. Goldman raised its target price for Samsung Electro-Mechanics from KRW 1,000,000 to KRW 2,600,000, and lifted 2026-2028 EPS forecasts by roughly 10%, 41%, and 96%, respectively. The core reason is not a single MLCC price hike, but the simultaneous entry of three AI server chains, MLCCs, silicon capacitors, and ABF substrates, into the income statement. This model reprices Samsung Electro-Mechanics from a consumer-electronics cyclical into the most direct Korean electronic-components compound asset exposed to AI server power density, package area, and power-delivery stability.
MLCCs become a power-delivery gatekeeper. Goldman expects Samsung Electro-Mechanics’ AI server MLCC revenue in 2028 to be about 6.4x its 2025 level, accounting for 28% of MLCC revenue and pushing operating margin toward 35%. What really matters is not how many more capacitors AI servers use, but that high-capacitance, high-voltage, miniaturized, and high-reliability specifications are starting to absorb premium capacity. MLCCs are shifting from an annual price-down logic to stable pricing, long-term agreements, and selective price increases.
Silicon capacitors are a new option. Samsung Electro-Mechanics has already disclosed one silicon capacitor supply contract worth a combined KRW 1.6trn for 2027-2028. On that basis, Goldman anchors 2028 silicon capacitor revenue at about KRW 1.5trn. Silicon capacitors are not a simple substitute for MLCCs. They are high-frequency decoupling components placed closer to AI chips, interposers, or substrates, moving Samsung Electro-Mechanics from a “board-level MLCC supplier” toward a “power-delivery stability supplier near the package.”
The ABF shortage is more rigid. Goldman believes ABF substrates will remain in tight balance for at least another 18-24 months: AI accelerators and server CPUs are larger in area and require more layers, while new capacity comes online slowly. Samsung Electro-Mechanics’ ABF revenue is expected to rise from KRW 1.2trn in 2025 to KRW 3.9trn in 2028, with operating margin increasing from 9% to 35%. LG Innotek has a lower base and greater elasticity, but still needs to clear three gates: yield, customer qualification, and capex allocation.
LG Innotek still requires restraint. Goldman also raised LG Innotek’s target price from KRW 550,000 to KRW 1,000,000, but kept the rating at Neutral. Even if 2028 ABF revenue reaches KRW 700bn, it would account for only about 2.5% of total revenue. The company’s best incremental story is ABF, but the factor that still determines the profit base is Apple camera modules. As long as camera-module margins and smartphone demand do not improve materially, the ABF option alone is unlikely to support a valuation rerating.
Mapping to China requires segmentation. This report can reinforce the demand view for high-end MLCCs, ceramic powders, ABF/BT substrates, PCB/CCL, and testing in AI servers, but it cannot equate every passive-component company with Samsung Electro-Mechanics. For A-share and Hong Kong mappings, three things matter: whether the company has high-end AI server specification orders, whether it can pass customer qualification, and whether gross margin improves with product mix, not simply whether the company name contains MLCC, ceramics, or PCB.
1. What Goldman’s New Report Adds: From Materials Story to Income-Statement Rewrite
The most valuable part of Goldman’s Korea electronic components update is that it does not stop at the generalized narrative of “AI servers driving component demand.” Instead, it directly writes three specific variables into the earnings forecasts for Samsung Electro-Mechanics and LG Innotek: MLCCs, silicon capacitors, and ABF substrates. In our previous MLCC work, the focus was on AI servers turning small components into power-delivery bottlenecks. In ABF, the focus was on insufficient near-term substrate supply after GPU and ASIC package areas expanded. Goldman goes one step further this time by putting these two chains and a new variable, silicon capacitors, into the same income statement.
This step matters. Materials-chain research can easily stop at phrases such as “demand is strong,” “capacity is tight,” and “price hikes are likely.” But stock rerating ultimately has to come back to revenue, ASP, margins, and target prices. In Goldman’s model for Samsung Electro-Mechanics, MLCCs are not an independent price-hike line, ABF is not a standalone packaging line, and silicon capacitors are not merely a conceptual new product. Together, the three point to a more specific judgment: AI server power density and packaging complexity are pushing Samsung Electro-Mechanics from a consumer-electronics cyclical into a compound supplier of AI hardware infrastructure.
MLCC Deep Dive: Samsung Electro-Mechanics Rerating Under the AI Power-Delivery Bottleneck
Previously, Samsung Electro-Mechanics’ investment framework could be split into two layers: consumer-electronics recovery driving MLCCs and smartphone components, and AI servers driving FC-BGA and high-end MLCCs. Goldman’s report changes the framework into three layers. The first is MLCC, with both revenue and ASP moving up. The second is silicon capacitors, entering power-delivery stability near AI chips. The third is ABF substrates, where AI accelerators and server CPUs raise the bar for package area, layer count, and yield. Only when all three layers materialize at the same time can we explain why Goldman’s 2028 EPS upgrade for Samsung Electro-Mechanics is close to a doubling.
Goldman’s core upward revisions for the two Korean electronic-component companies
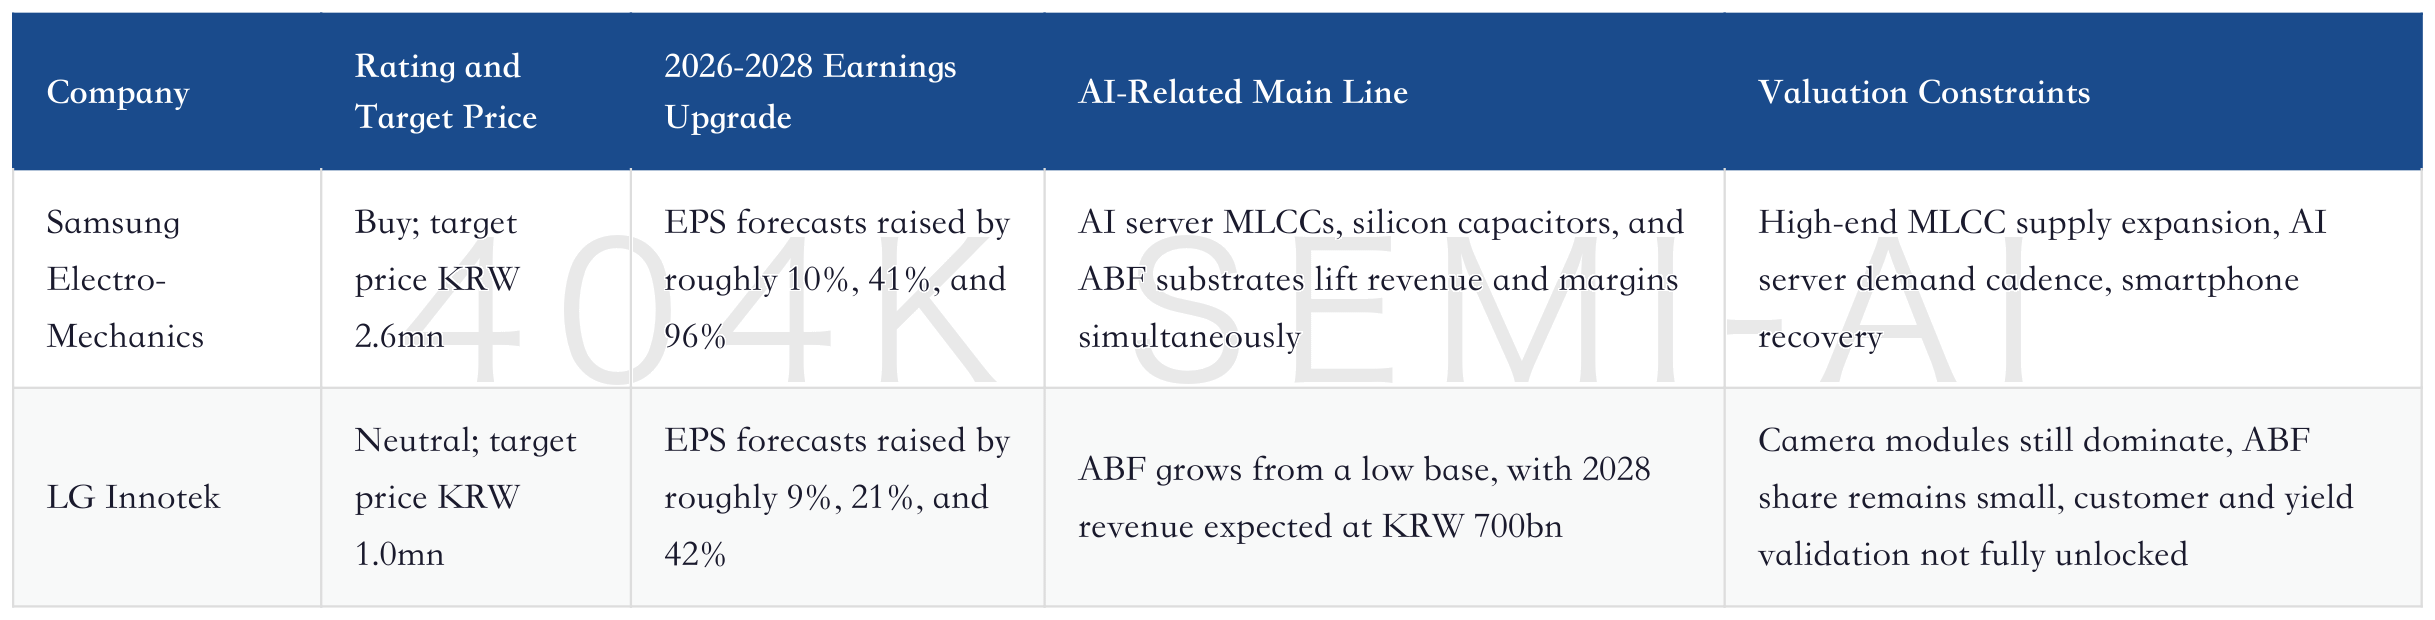
The conclusion of this report is not that “all Korean electronic components need to be rerated.” A more accurate reading is that Samsung Electro-Mechanics’ income statement is already close enough to the AI server bottleneck, while LG Innotek remains in the position of “has optionality, but the core business drags on valuation.” Both companies benefit from ABF, but the weight is completely different. Both can tell an AI hardware story, but Samsung Electro-Mechanics holds MLCCs, silicon capacitors, and ABF at the same time, while LG Innotek is more about low-base incremental growth outside its core camera business.
This is also how this piece differs from our previous MLCC or ABF foundation notes. Earlier articles already explained why AI servers drive MLCCs and why ABF substrate supply is tight. The question this time is: after Goldman writes these variables into the earnings models for Samsung Electro-Mechanics and LG Innotek, which part represents a truly priceable earnings slope, and which part is still only an option?
2. Samsung Electro-Mechanics: Three AI Profit Lines Are Put into the Same Table for the First Time
The most attractive aspect of Samsung Electro-Mechanics this time is that its AI exposure no longer depends on a single business line. MLCCs, silicon capacitors, and ABF correspond to three hard constraints in AI servers: board-level power-delivery stability, high-frequency decoupling near the chip, and advanced-package carrier area. The common feature across the three is that their share of system BOM may not be the largest, but the cost of failure is high, qualification cycles are long, and customers are more willing to pay for certainty.
Start with Goldman’s model. Sales, operating profit, and operating margin all show clear non-linear improvement. This is not an ordinary revenue-growth model, but a margin step-up driven by product-mix upgrade. The real drivers of margin are the simultaneous expansion of the Component Solution and Substrate Solution divisions.
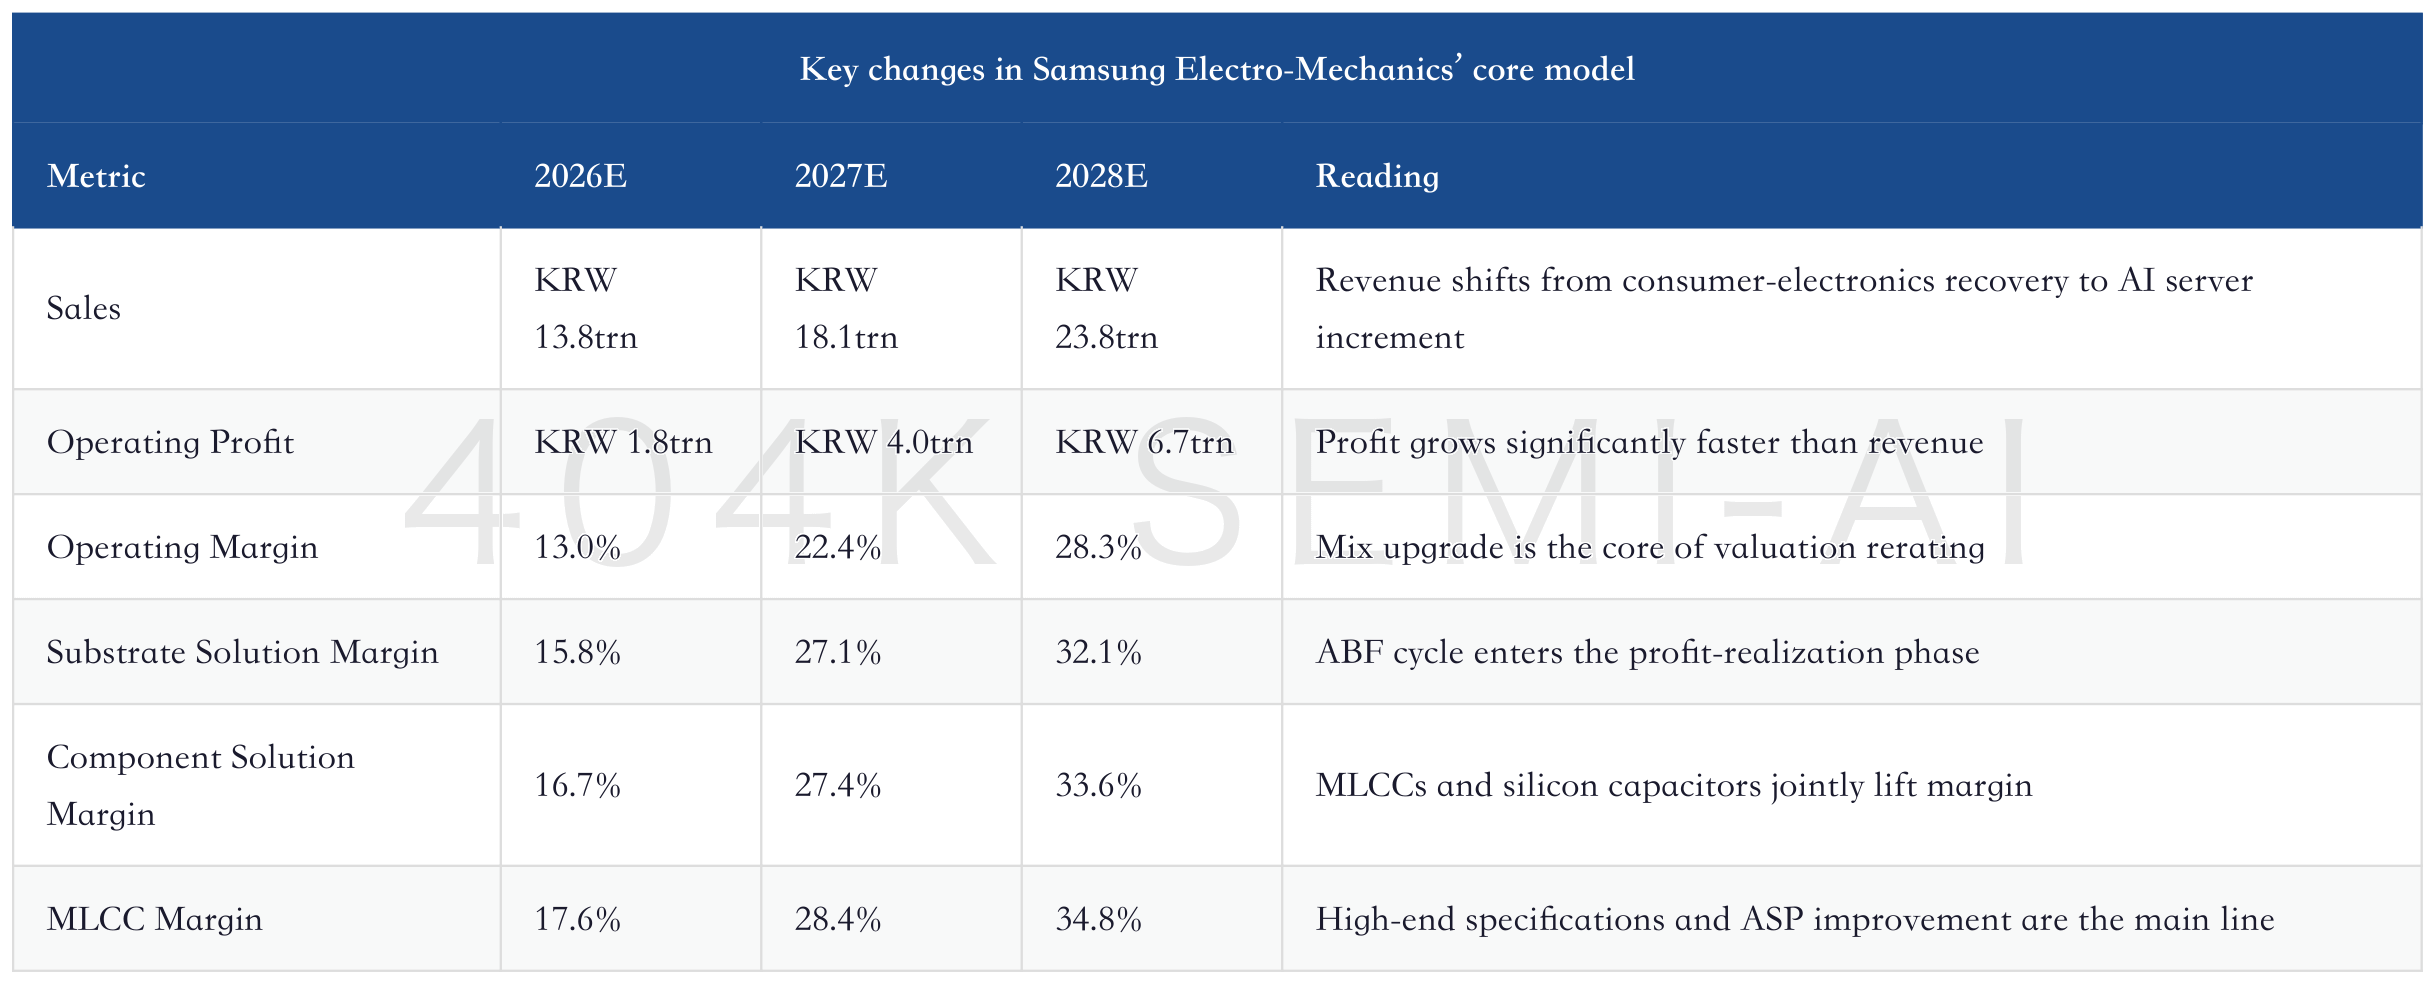
The key point in this table is not the number for any single year, but the margin slope. If Samsung Electro-Mechanics were only benefiting from recovery in smartphones, PCs, and traditional autos, it would be difficult for margin to move from the teens to nearly 30%. Goldman is willing to assign this slope because it assumes AI server-related MLCCs, silicon capacitors, and ABF all enter high-value-added territory at the same time.
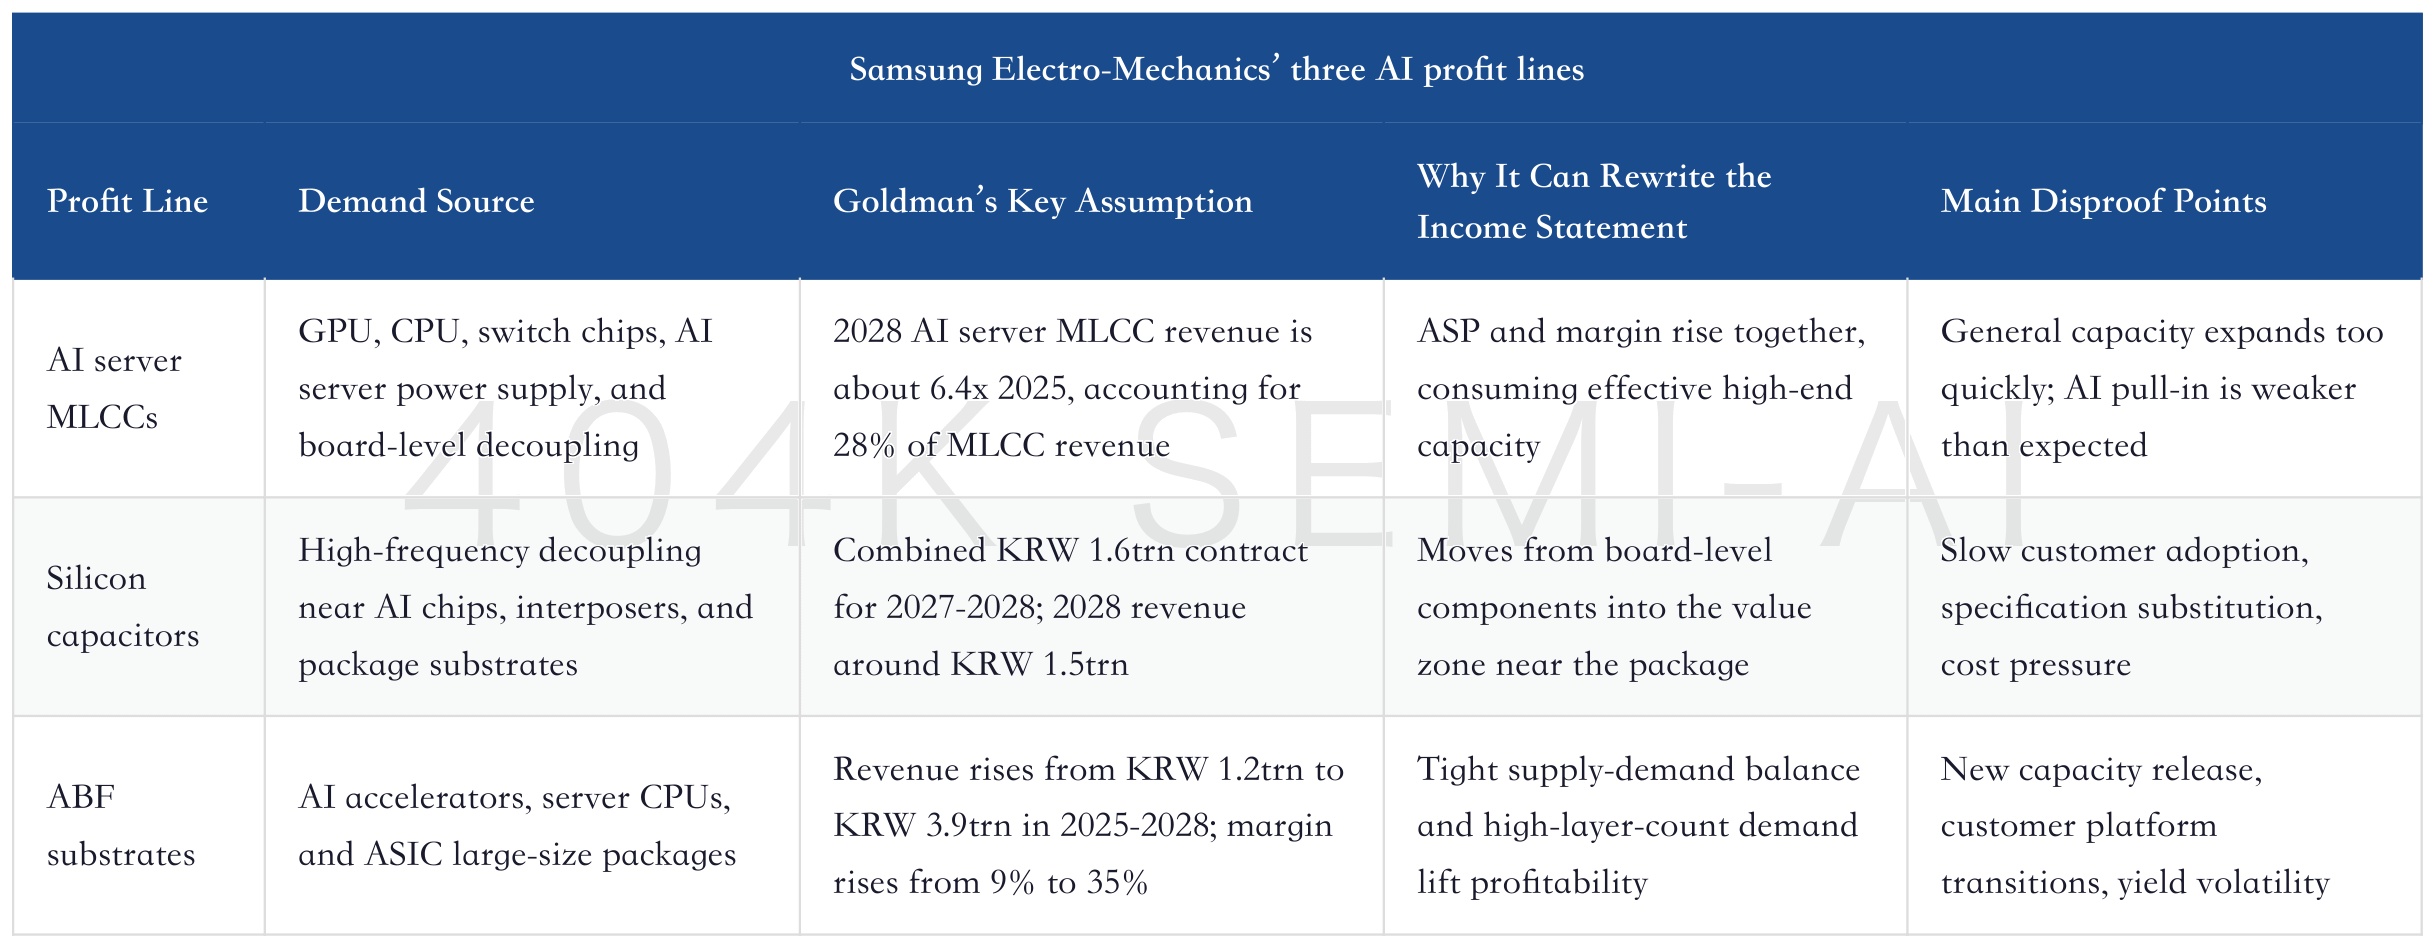
The simultaneous emergence of these three lines is what differentiates Samsung Electro-Mechanics from an ordinary MLCC company. Murata is the global pricing anchor for high-end MLCCs; Taiyo Yuden is operating-leverage elasticity; Yageo is more exposed to MLCC supply spillover and price elasticity. Samsung Electro-Mechanics is distinctive because in AI servers it has MLCCs, ABF, and is also starting to push silicon capacitors closer to AI chips. It is not a single passive-component rerating, but a combined asset of “power-delivery stability plus package substrates.”
MLCC Deep-Dive Update: Agentic AI, Rubin Racks, and the High-End Capacitor Supply Gap
The valuation implication of this combination is also different. A single MLCC company needs to prove high-end specification shortages and pricing discipline. A single ABF company needs to prove large-size package orders and capacity utilization. Samsung Electro-Mechanics needs to prove that three things can hit revenue and margins at the same time: AI server MLCC shipments expanding, silicon capacitors moving from contracts into mass-production revenue, and ABF maintaining full utilization and high margins. If two of the three materialize, the income statement is already materially different; if all three materialize simultaneously, the target-price upgrade becomes explainable.
III. MLCC: AI Servers Are Not Buying Tiny Capacitors, but High-End Effective Capacity
The MLCC line is easy to underestimate because its absolute dollar content in AI servers is not large. System customers looking at the BOM see MLCCs as only a very small share; suppliers looking at profit, however, may find MLCCs one of the areas most prone to nonlinear earnings elasticity. The reason is simple: customers will not sacrifice power stability for a small cost saving, while suppliers are not selling ordinary unit volume, but premium capacity occupied by high-capacitance, high-voltage, miniaturized, and high-reliability specifications.
Goldman Sachs’ assumptions for Samsung Electro-Mechanics’ MLCC business are very direct: AI server revenue share, ASP per 1,000 units, and operating margin all rise together. This set of numbers turns AI server MLCCs from an “incremental demand” story into a “margin variable.” Looking only at unit volume makes it easy to underestimate; looking at ASP and margin shows how it is changing the income statement.
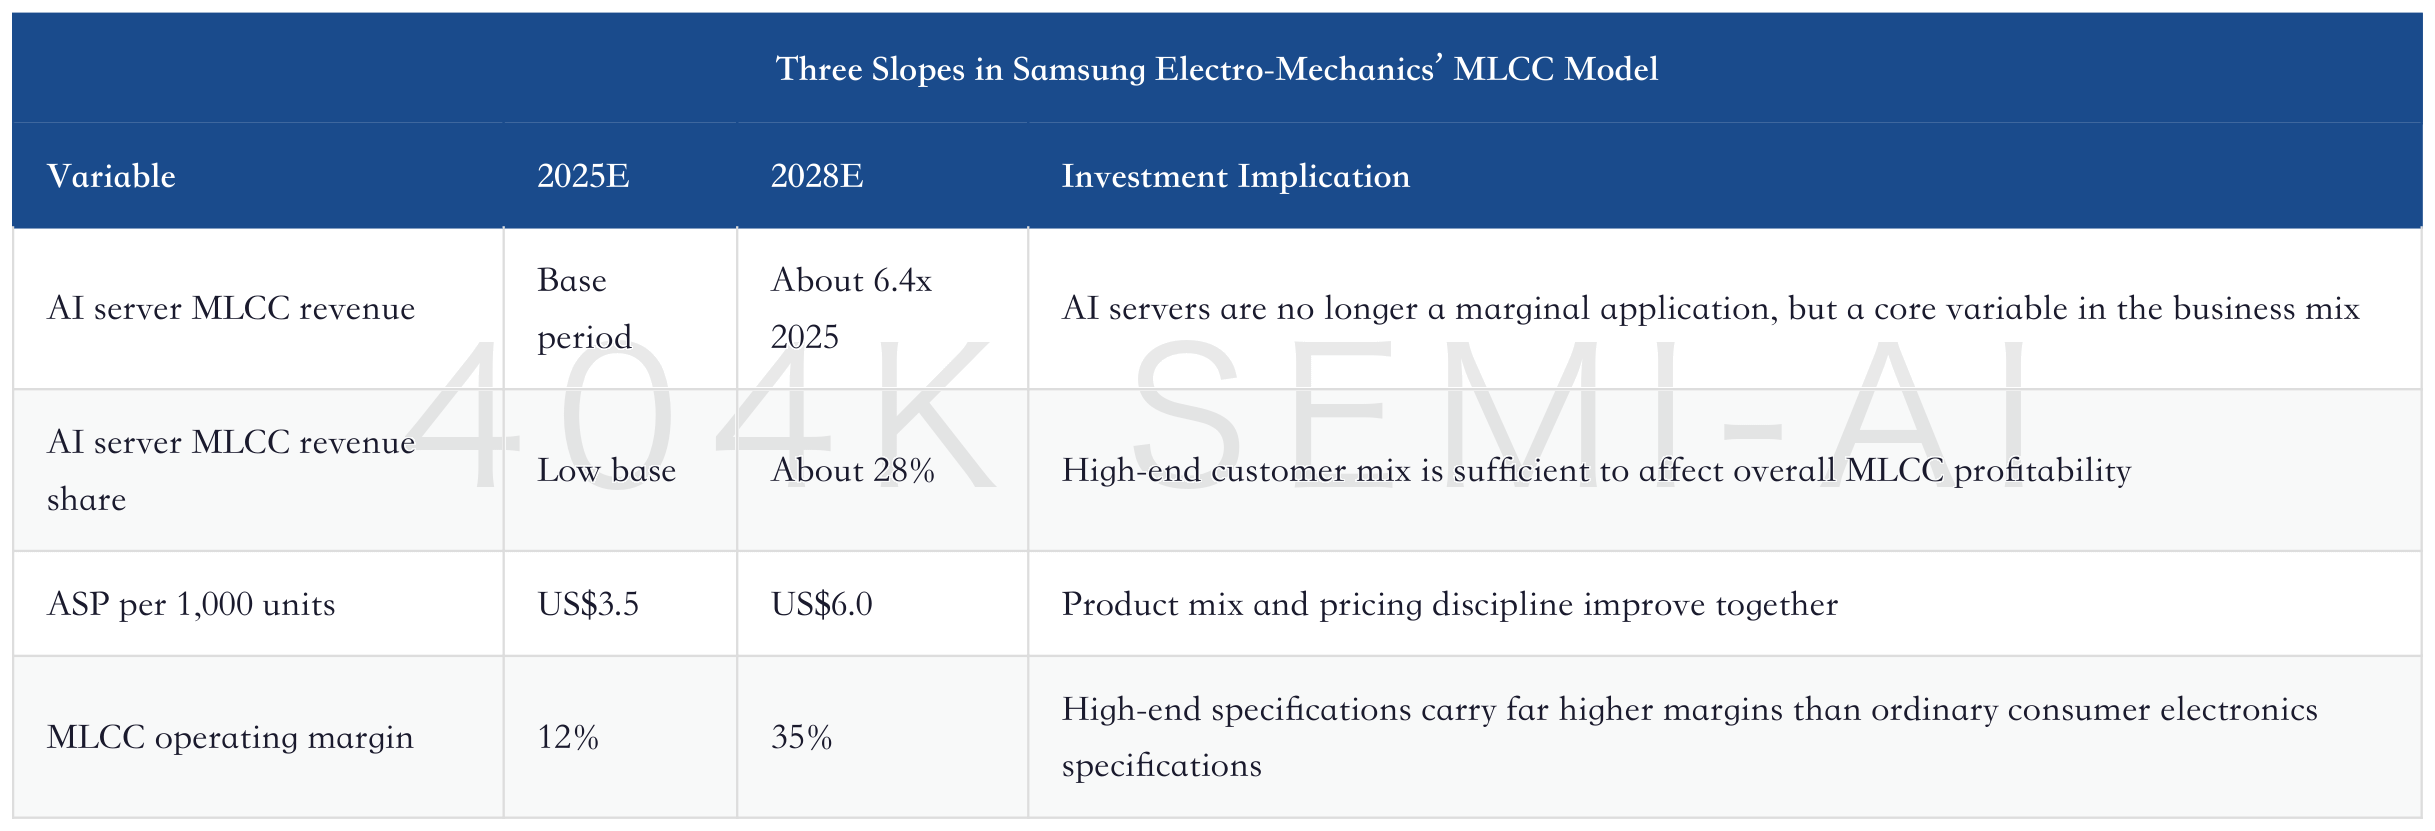
The key here is not simply “MLCC price increases,” but why prices can rise, or at least no longer decline at the old pace. AI servers require different MLCC characteristics from smartphones. Smartphones pursue miniaturization and space utilization; AI servers pursue long-term stable operation under high power density. GPUs, CPUs, switch chips, retimers, VRMs, power modules, and high-speed networking cards are all increasing requirements for decoupling, filtering, and transient response. Once an AI server fails, downtime and maintenance costs far exceed the price of a single capacitor, so customers are naturally more willing to pay for specification quality and supply certainty.
MLCC Deep Dive: JPMorgan Sharply Raises Estimates, from Cyclical Recovery to Structural Re-rating as AI Servers Rewrite the Supply-Demand Gap
This is also the dividing line between high-end MLCCs and ordinary MLCCs. Large nominal capacity does not mean sufficient high-end effective capacity. Ordinary consumer electronics MLCCs, high-reliability automotive MLCCs, and high-capacitance, high-voltage AI server MLCCs cannot be switched freely among one another. Materials, thin-layering, stacking, sintering, sorting, reliability validation, and customer qualification all take time. Customers also will not casually switch suppliers for critical hardware such as AI servers.
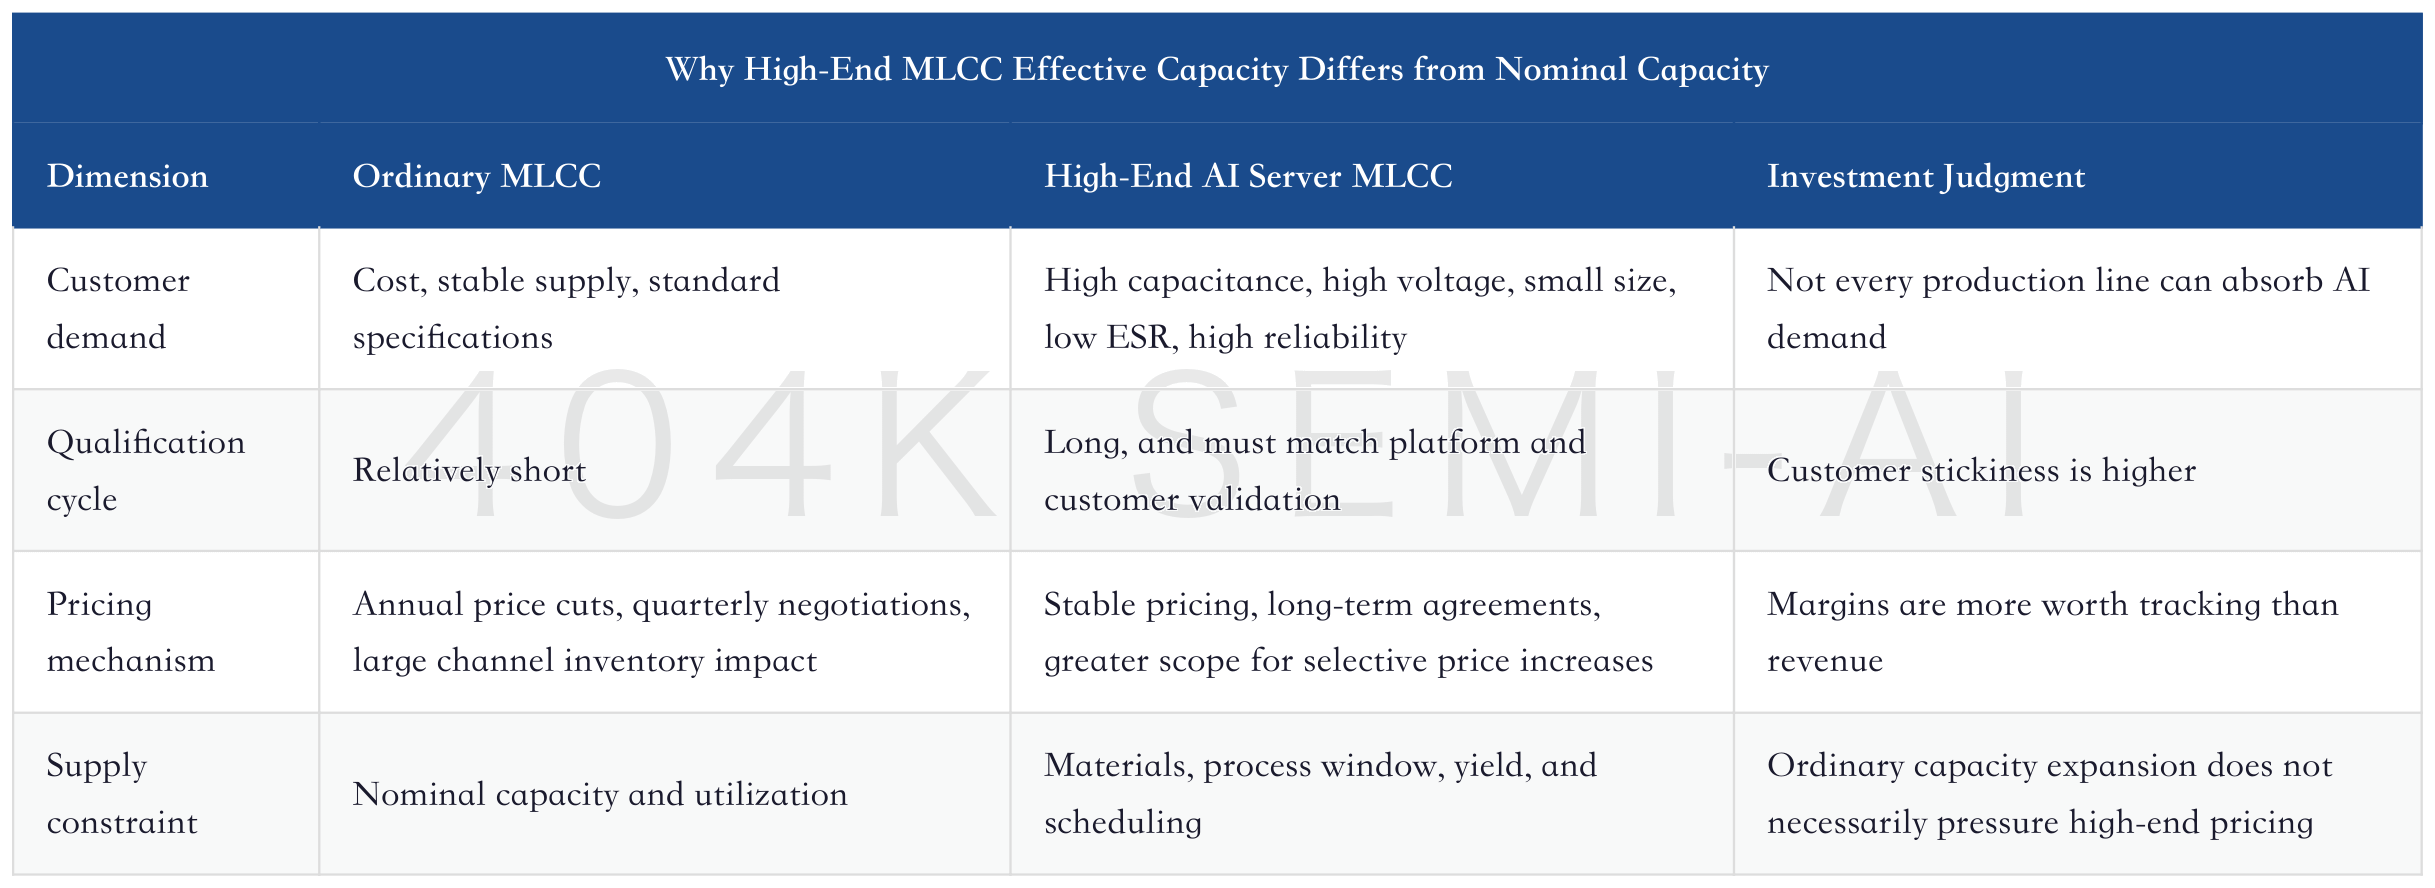
Samsung Electro-Mechanics’ advantage in MLCCs is that it is not relying purely on a high-end smartphone recovery. AI servers, automotive, and high-end industrial demand are jointly lifting the product mix, giving the company an opportunity to reprice its MLCC business from a consumer electronics cycle into a high-end manufacturing asset. Goldman Sachs’ assumption of a 35% MLCC operating margin in 2028 is essentially pricing in this mix upgrade.
The risks must also be stated clearly. MLCCs are not without supply response. Leading Japanese, Korean, and Taiwanese players will all expand high-end capacity, while Chinese manufacturers are also upgrading toward high-reliability and automotive-grade products. If new capacity is released too quickly after 2027, or if AI server pull-in falls short of expectations, pricing discipline in high-end specifications will weaken. The biggest risk to Samsung Electro-Mechanics’ model is not slightly weaker ordinary smartphone demand, but AI server MLCC revenue share and ASP failing to ramp as Goldman Sachs assumes.
IV. Silicon Capacitors: Samsung Electro-Mechanics’ Key Step from Board-Level Components Toward the Package Vicinity
Silicon capacitors are the new information content in this report. MLCCs and ABF have already been discussed repeatedly by the market, while silicon capacitors have not yet been fully incorporated into most electronic component companies’ valuation frameworks. Samsung Electro-Mechanics disclosed a contract totaling KRW 1.6 trillion for 2027-2028, with a major technology company as the customer; based on this, Goldman Sachs expects silicon capacitor revenue of about KRW 1.5 trillion in 2028. This is not a small trial order, but a new revenue stream large enough to change the structure of the Component Solution division.
The value of silicon capacitors does not lie in “replacing MLCCs.” A more reasonable interpretation is that they and MLCCs jointly serve AI chip power stability, but differ in location, form factor, and application scenario. MLCCs are used more for board-level and module-level decoupling; silicon capacitors can sit closer to chips, interposers, or package substrates, serving high-frequency, short-path, space-constrained power delivery scenarios. The higher AI chip power density becomes, the more difficult power integrity near the package becomes, and the easier it is for customers to see the value of silicon capacitors.
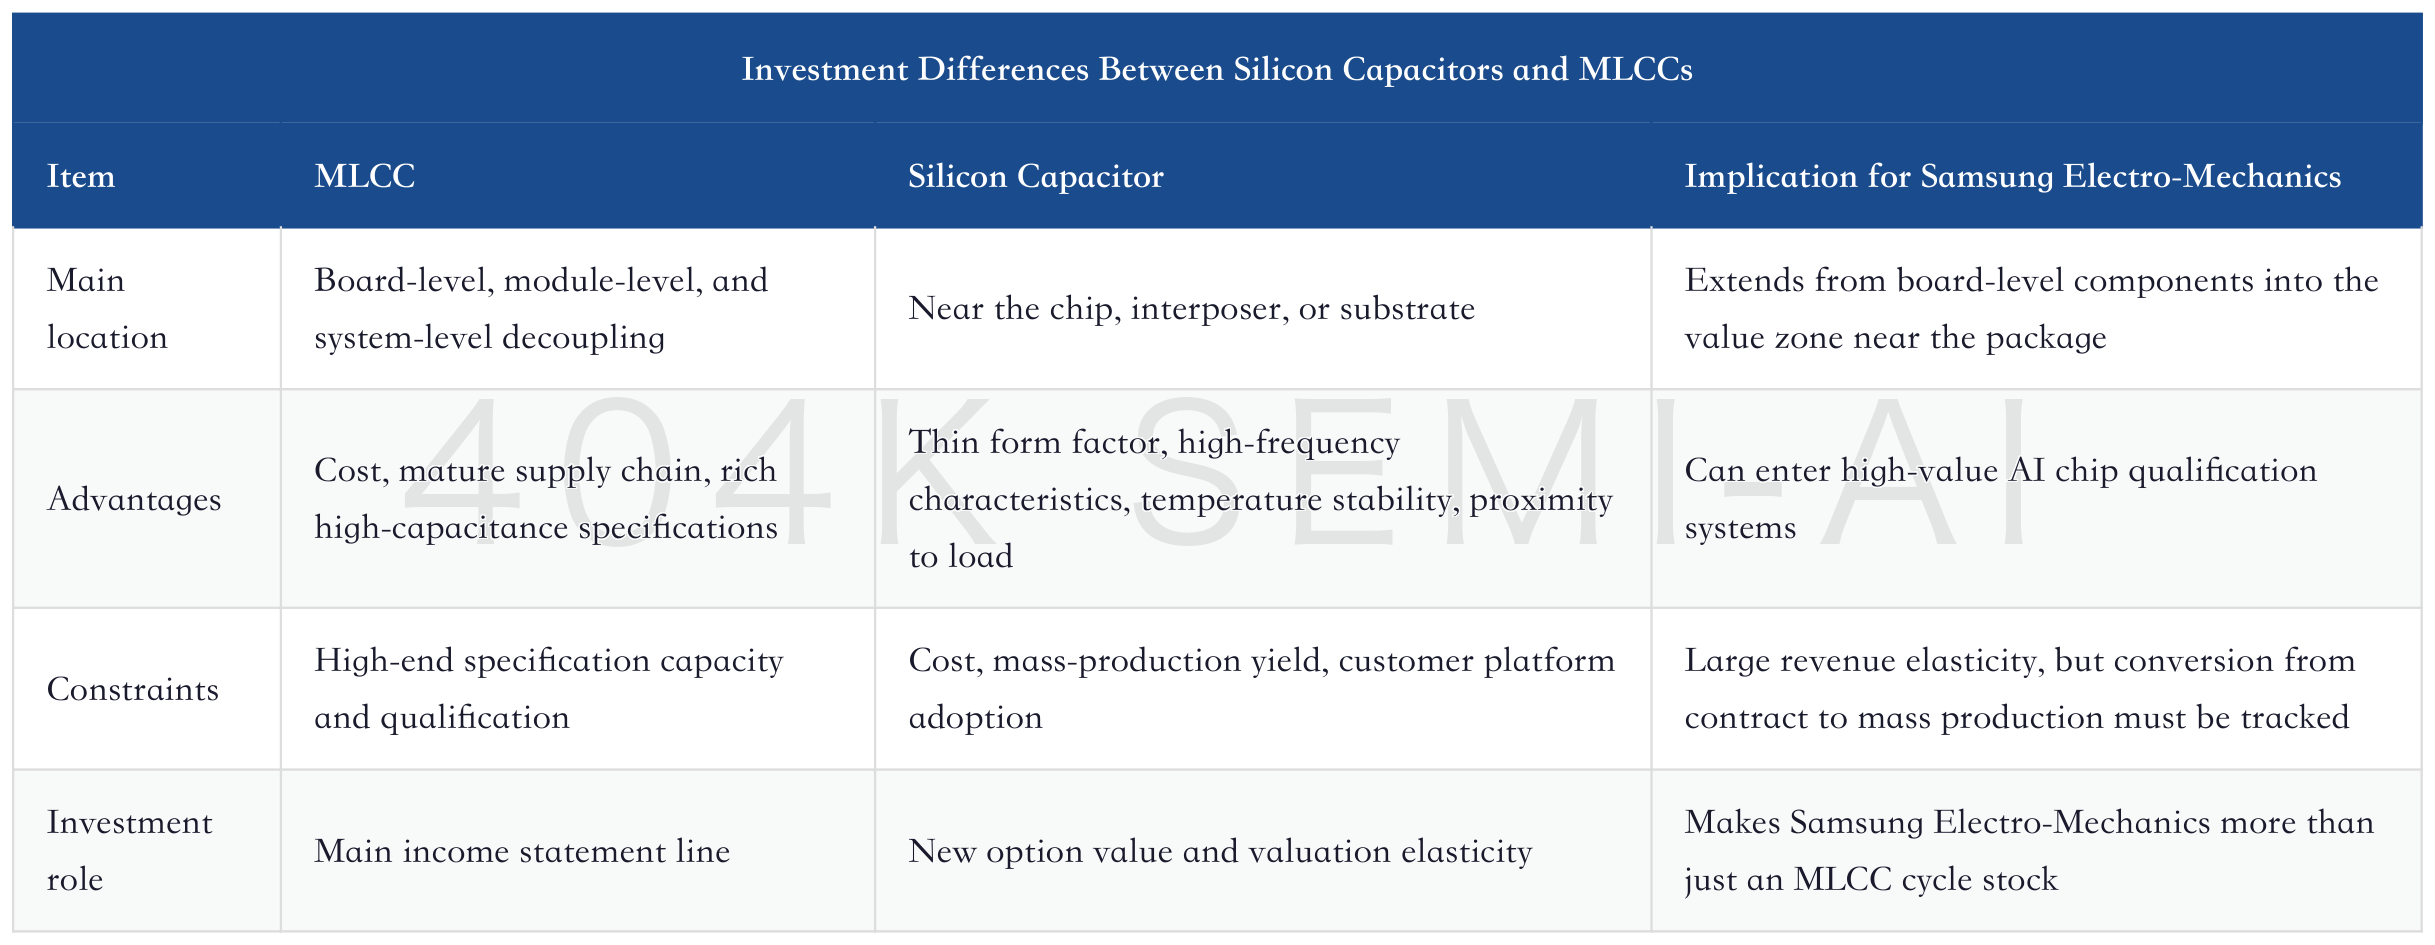
This line has significant strategic importance for Samsung Electro-Mechanics. AI hardware value is spreading from “the chip itself” to “the surrounding systems that allow the chip to operate stably.” HBM, CoWoS, ABF, thermal, power delivery, PCB, connectors, and MLCCs are all tied to the same major trend: as compute density rises, system-level bottlenecks become increasingly expensive. Silicon capacitors bring Samsung Electro-Mechanics closer to the chip and package, meaning it has an opportunity to participate in higher-value AI hardware orders.
Of course, silicon capacitors also carry uncertainty. First, contract value does not equal steady annual revenue; the 2027-2028 delivery pace, yield, and customer platform validation still need to be observed. Second, silicon capacitors and MLCCs are complementary, but there may also be substitution and cost trade-offs in certain local applications. Third, if customer platforms are revised, packaging schemes are adjusted, or power architecture changes, order cadence may fluctuate. Goldman Sachs anchoring 2028 revenue at about KRW 1.5 trillion is a strong modeling assumption; subsequent validation will depend on mass production, yield, and broader adoption by more customers.
For investors, the best way to track silicon capacitors is not to ask “whether they will replace MLCCs,” but to ask three more specific questions: whether Samsung Electro-Mechanics can deliver existing major customer contracts on schedule; whether silicon capacitors can expand from a single customer to multiple AI platforms; and whether silicon capacitor revenue can bring higher gross margin or customer stickiness than traditional MLCCs. As long as these questions are progressively validated, Samsung Electro-Mechanics’ valuation framework will look more like an AI packaging and power stability asset than a traditional passive component cycle stock.
V. ABF: Samsung Electro-Mechanics Is the Profit Mainline; LG Innotek Is a Low-Base Option
The ABF substrate logic is more robust. AI accelerators, server CPUs, and ASIC packages are becoming larger, layer counts are rising, and yield requirements are higher, while new capacity is slow to come online. Goldman Sachs believes ABF supply-demand conditions will remain favorable for at least another 18-24 months. The core reason is not short-term restocking, but larger AI server designs, long customer qualification cycles, and slow capacity ramp-up. This view is consistent with the prior foundation of the ABF industry, but Goldman Sachs has now mapped it specifically to Samsung Electro-Mechanics and LG Innotek.
ABF Substrate Deep Dive: The Packaging Foundation of AI Compute, from Introductory Framework to Supply-Demand Structure and Company Ranking
Samsung Electro-Mechanics’ ABF revenue is expected to grow from KRW 1.2 trillion in 2025 to KRW 3.9 trillion in 2028, with operating margin rising from 9% to 35%. The implication is straightforward: Samsung Electro-Mechanics’ ABF business is not “winning orders without making money,” but entering a phase of high utilization and high profitability. Goldman Sachs also noted that current AI server-related demand already exceeds existing capacity by more than 50%, with full utilization expected in 2H26, while the new Vietnam plant will not provide a larger release until 2028. Limited near-term supply elasticity is the basis for margin upside.
LG Innotek’s ABF business is more like an option. Goldman Sachs expects its ABF revenue to rise from KRW 50 billion in 2025 to KRW 700 billion in 2028, with operating margin turning from -18% to 18%. That sounds highly elastic, but the base is too low. Even by 2028, ABF would account for only about 2.5% of total company revenue. Therefore, LG Innotek can tell an ABF growth story, but ABF is still not enough to fully rewrite the company’s valuation.
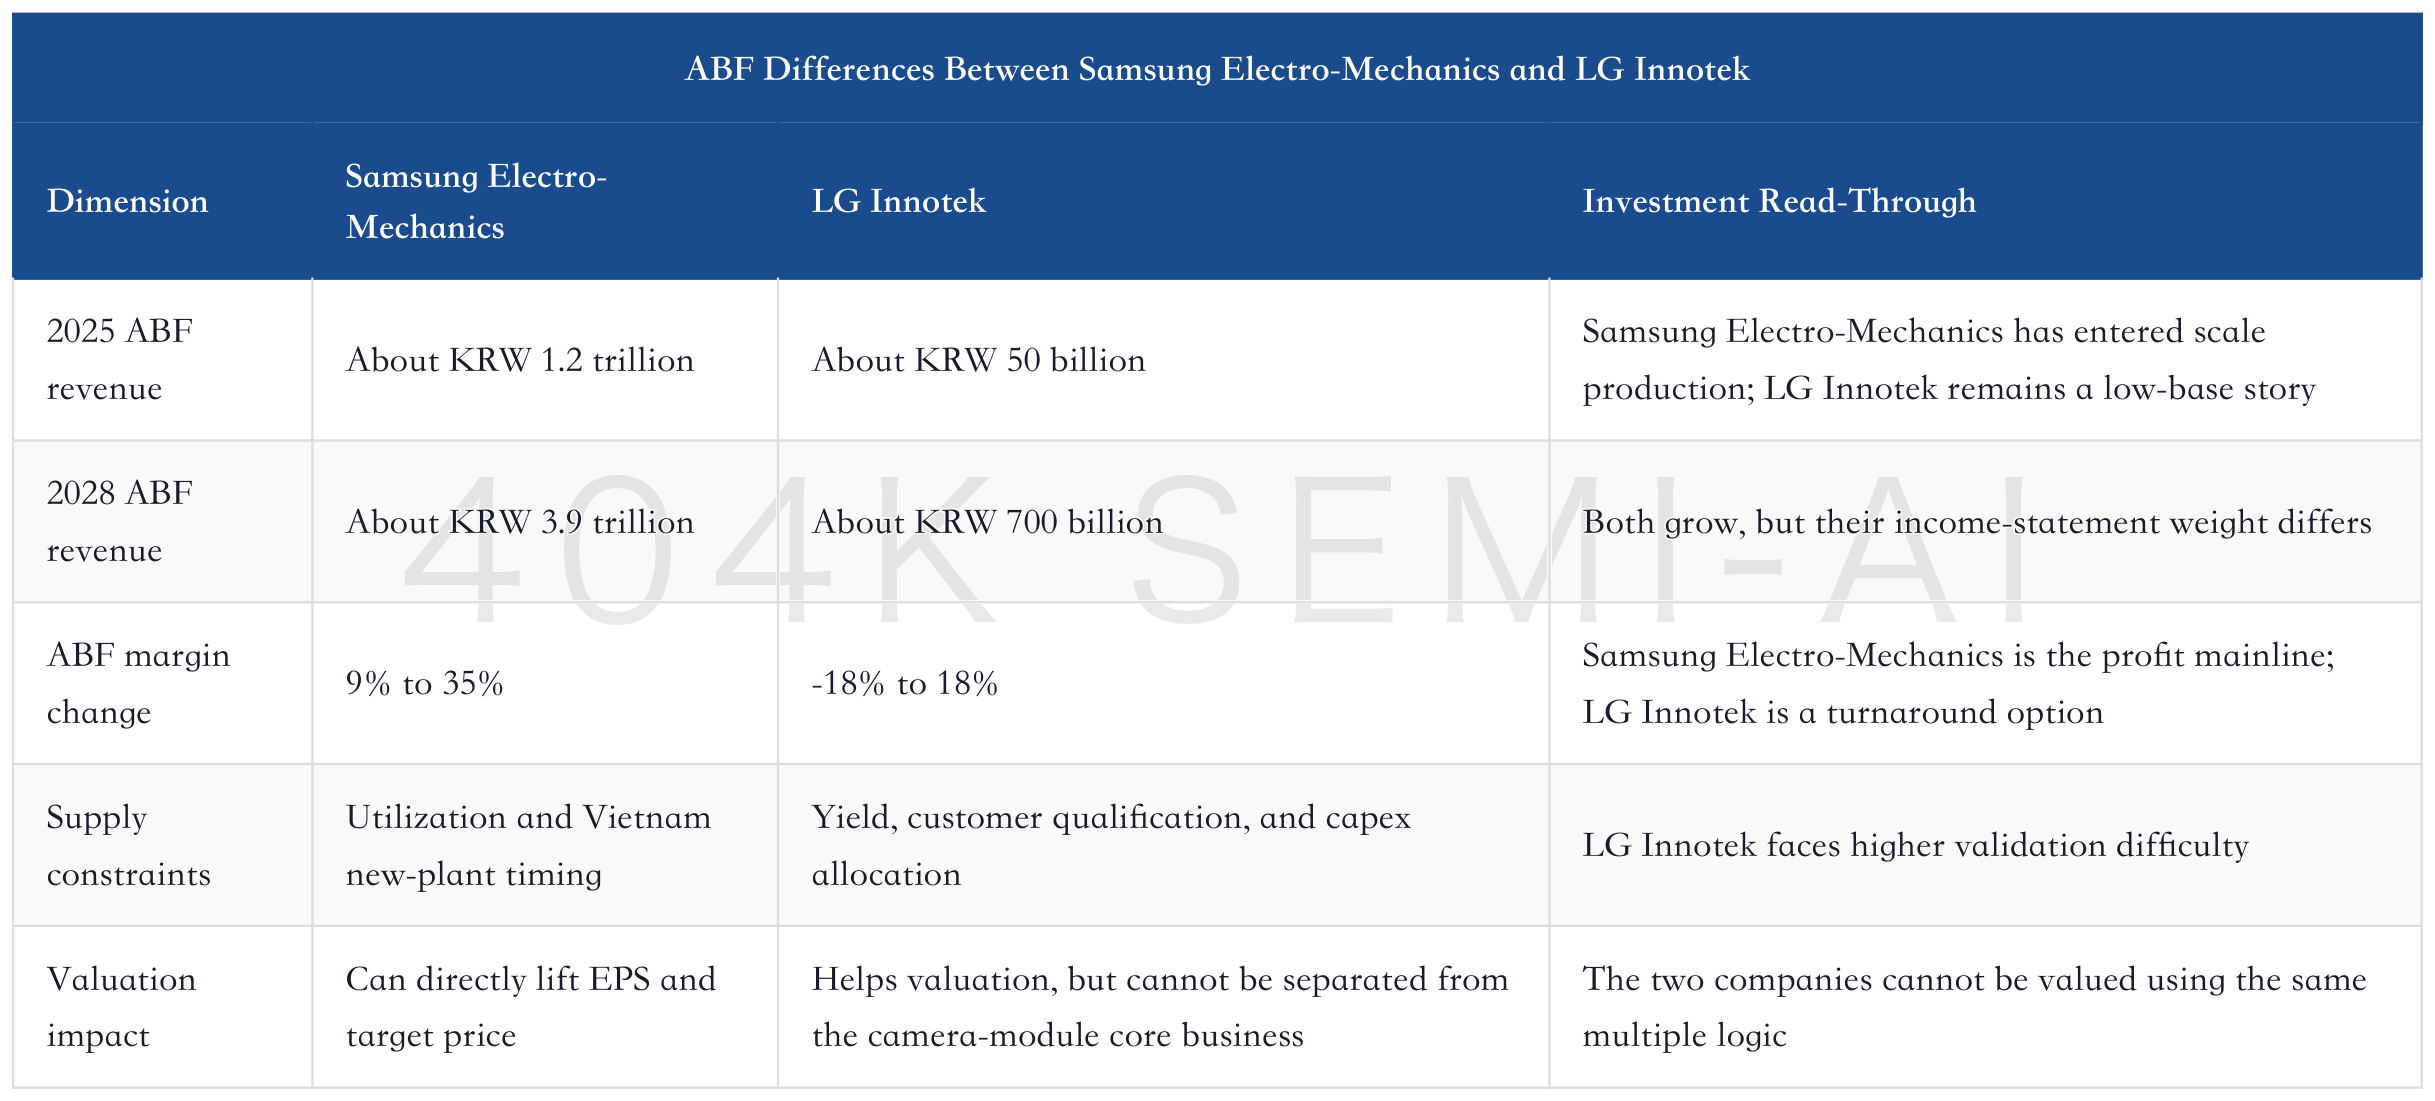
ABF is easily misread as “whoever has capacity benefits.” That is not the case. The difficulty of AI server ABF lies in large area, high layer count, low warpage, signal integrity, and customer qualification. Capacity expansion alone does not equal effective capacity; yield ramp-up and customer adoption determine the pace of profit release. Samsung Electro-Mechanics already has a relatively mature ABF mass-production base, which is why Goldman Sachs is willing to push its margin to 35%. LG Innotek still needs to prove it can steadily enter high-end server ABF, rather than merely growing revenue from a low base.
ABF and BT Substrate Price Hikes Raised Again: From T-glass Constraints to BT Spillover, Why the AI Substrate Pricing Cycle Is Not Over
ABF also has another spillover variable that needs to be added: BT substrates. Goldman Sachs also noted that smartphone demand is weak, but AI server memory-related demand, including GDDR, LPDDR, SSD controllers, and others, can support BT-related demand. In other words, AI servers not only drive large-size ABF for GPUs and CPUs, but also drive some BT applications through storage and controller links. Samsung Electro-Mechanics’ substrate-business elasticity is not just one ABF line, but a multi-layer transmission from AI server accelerators to storage controllers.
VI. LG Innotek: Target Price Raised, but Valuation Is Still Pulled Back to Reality by Camera Modules
LG Innotek’s story needs to be written with restraint. Goldman Sachs raised its target price from KRW 550,000 to KRW 1,000,000 and also significantly lifted earnings forecasts, but maintained a Neutral rating. This is not because ABF is unimportant, but because ABF is not yet large enough. ABF revenue reaching KRW 700 billion in 2028 sounds like substantial growth versus 2025, but for a company whose 2028 revenue is expected to approach KRW 28.4 trillion, it would still account for only about 2.5%.
What truly determines LG Innotek’s income statement remains Apple camera modules. Goldman Sachs raised its forecasts for company revenue and operating profit over the next few years, but the slope is gentler than for Samsung Electro-Mechanics. The reason is that although camera modules have ASP support from the Vietnam plant, variable aperture, and feature upgrades, smartphone demand, rising storage costs, and customer bargaining power still limit margin expansion.
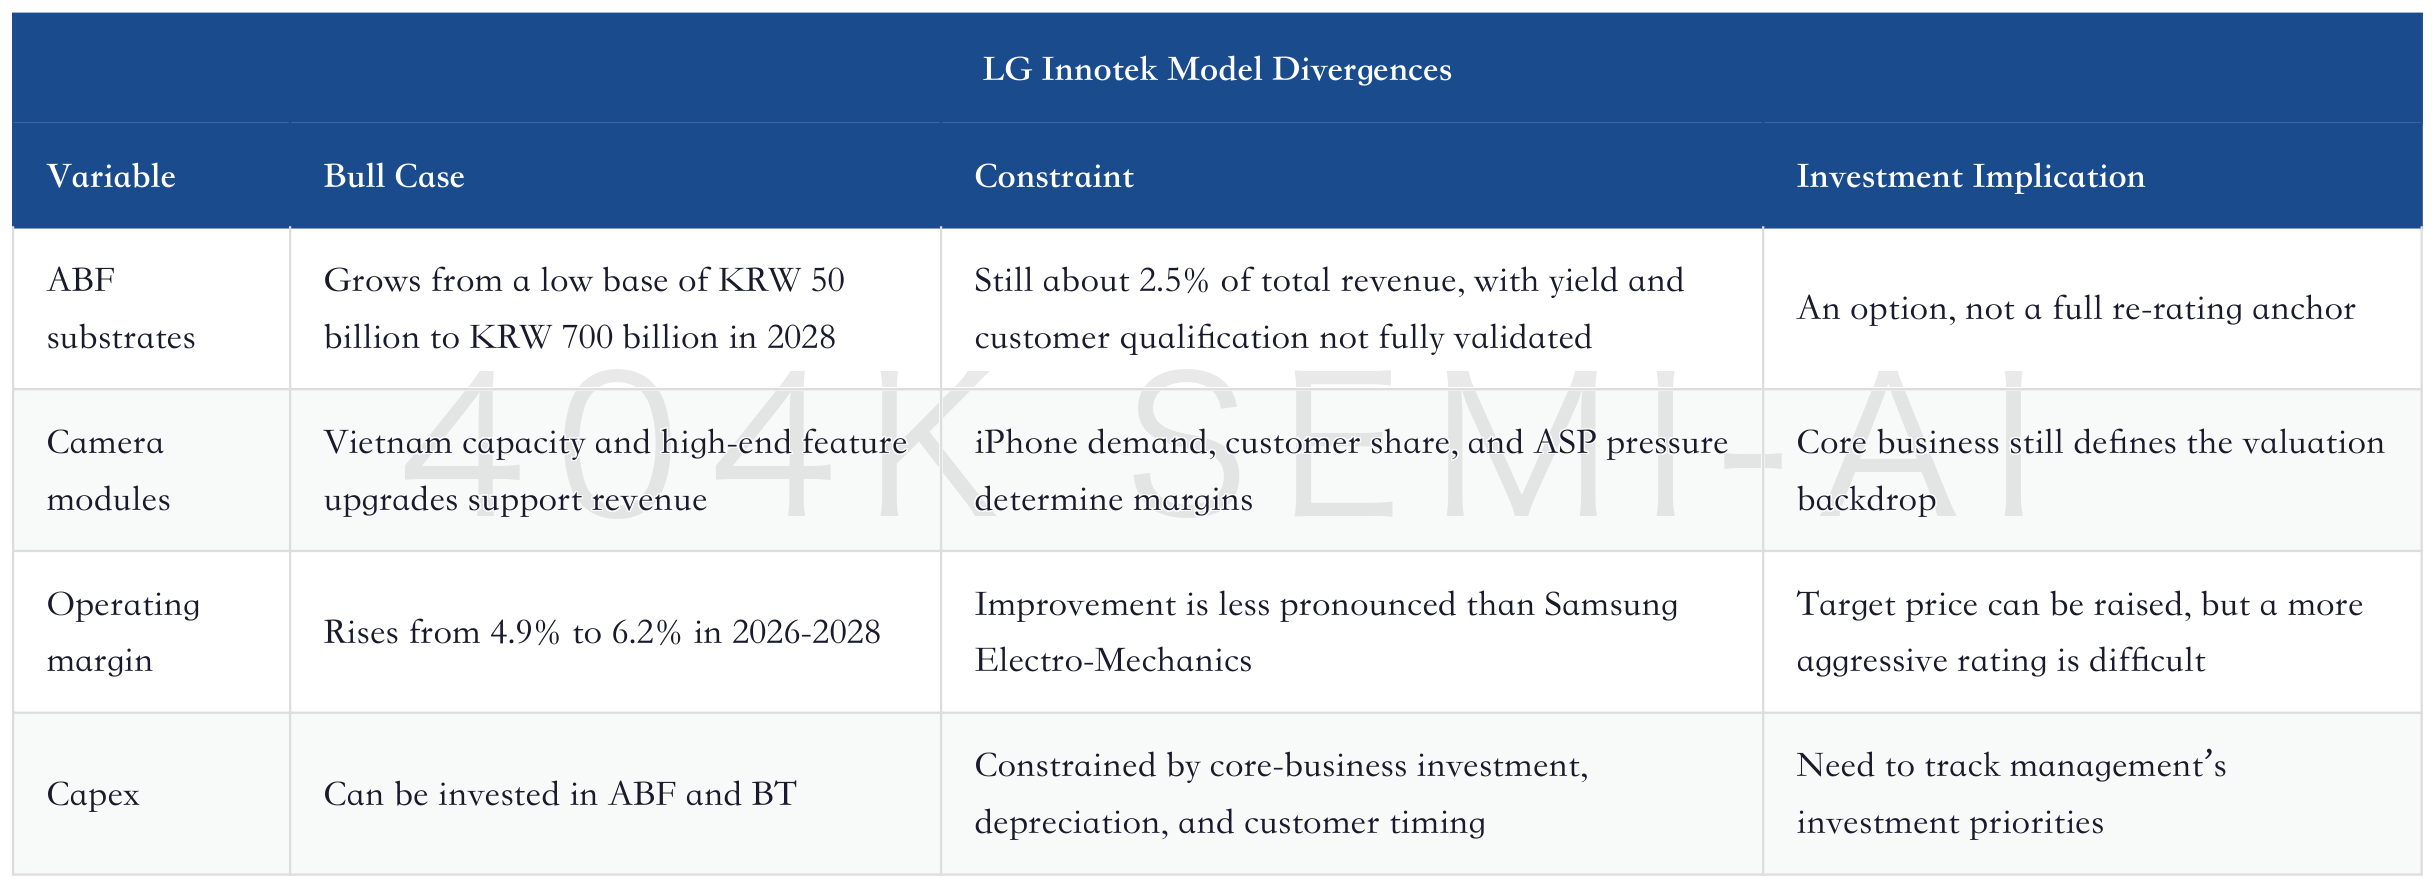
The biggest question for this company is whether it can move from being an “Apple camera-chain company” to a combination of “camera cash flow plus ABF growth option.” If ABF yield ramp-up goes smoothly, customer qualification expands, margins turn positive and continue rising, then LG Innotek will gain a second growth curve. But while ABF still accounts for a small share, the market will continue to price the camera-module core business first.
Therefore, LG Innotek’s tracking indicators are completely different from Samsung Electro-Mechanics’. For Samsung Electro-Mechanics, the question is whether AI server MLCC, silicon capacitors, and ABF can jointly drive margins higher. For LG Innotek, the question is whether ABF can move from option to mainline, while camera-module margins do not become a drag. Looking only at ABF revenue growth can easily overestimate LG Innotek’s valuation elasticity; looking only at the camera business can underestimate the ABF option.
VII. Mapping to Asian and Chinese Assets: Find the Gates First, Then the Companies
The implication of this Goldman Sachs report for A-shares, Hong Kong equities, and the Korea/Japan/Taiwan supply chain is not to directly map Samsung Electro-Mechanics to a specific domestic company, but to reconfirm the three gates in the AI server materials chain: high-end MLCC and ceramic materials, ABF/BT substrates and PCB/CCL, and power stability near packaging. Each gate has different company-screening criteria and cannot be bundled under a single “AI electronic components” label.
The Second Re-rating of the AI Server Materials Chain: From Passive Components to PCB/CCL, ABF Substrates, and Test Equipment
The first layer is high-end MLCC and ceramic materials. Samsung Electro-Mechanics’ model reinforces one view: what AI servers truly drive is high-end effective capacity, not nominal ordinary MLCC capacity. For Chinese companies, Fenghua Advanced Technology, Chaozhou Three-Circle Group, Sinocera, Torch Electron, and others should all be placed within a tiered research framework, but the ranking criteria need to be strict. The key is whether they can produce high-end AI server specifications, enter core customer qualification, and convert powder, ceramic dielectric, paste, sintering, or high-reliability packaging into margin improvement. Simply saying they “have MLCC capacity” is not enough.
The second layer is ABF, BT, PCB, and CCL. AI servers do not drive ABF alone. GPU/ASIC packaging, switches, backplanes, line cards, and storage controllers will all transmit demand to board-level materials. PCB, CCL, glass-fiber cloth, copper foil, and high-end package substrate companies in Hong Kong and A-shares should all be screened along four indicators: customer qualification, material grade, utilization, and whether price hikes can flow into the income statement. The most common mistake here is to treat ordinary PCB capacity as AI high-end board capacity, ordinary CCL as high-end low-loss materials, and nominal expansion as effective supply.
AI Hardware Deep Update: How PCB, CPO, and MLCC Become the Three Physical Gates of the Rubin Rack
The third layer is power stability near packaging. Silicon capacitors currently do not have a particularly clear direct mapping among Chinese assets, but they point to one direction: the closer AI chips get to system limits, the closer power integrity moves to the packaging core. In the future, this will include not only MLCC, but also silicon capacitors, film capacitors, polymer capacitors, advanced packaging materials, power modules, and test validation. Opportunities here are more medium to long term; for now, it is important to prevent concepts from replacing orders.
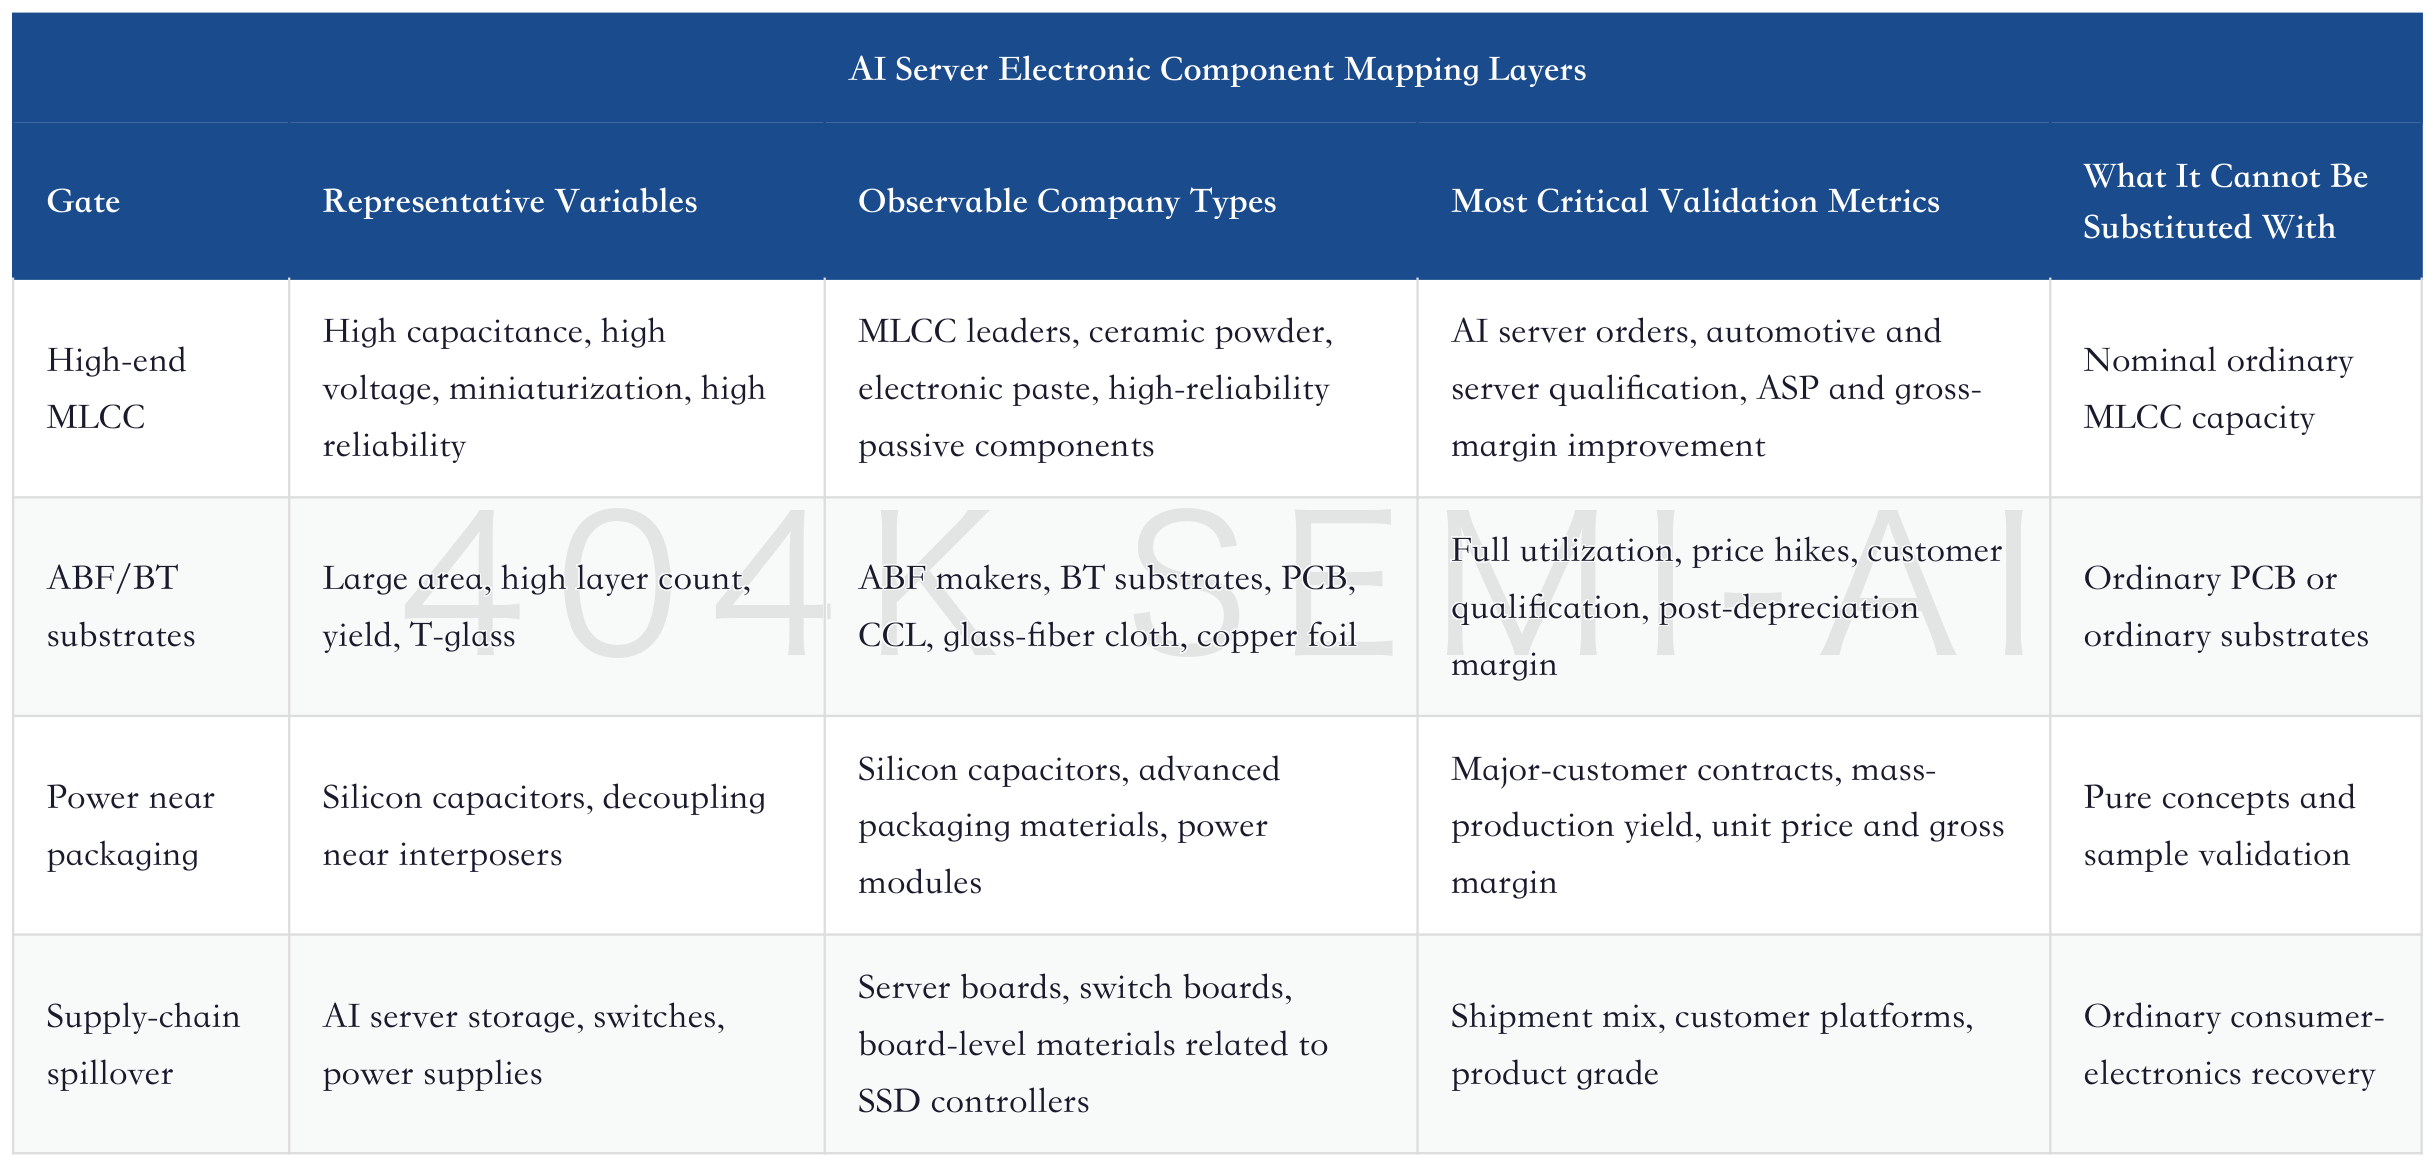
This is also why companies such as Fenghua Advanced Technology, Chaozhou Three-Circle Group, and Sinocera need to be analyzed separately. Fenghua Advanced Technology is more oriented toward MLCC and automotive-grade/high-reliability passive component platforms; Chaozhou Three-Circle Group is more oriented toward electronic ceramics and high-end ceramic component capabilities; Sinocera is more oriented toward MLCC powder and electronic paste materials. All can benefit from the high-end MLCC industry trend, but their direct comparability with Samsung Electro-Mechanics differs. Samsung Electro-Mechanics has global AI customers, silicon capacitor contracts, and scaled ABF revenue; domestic companies need to be validated item by item through orders, qualifications, gross margins, and capacity structure.
Chaozhou Three-Circle Group Deep Dive: From Electronic Ceramics Platform to High-end MLCC, How AI Servers Re-rate Domestic Ceramic Component Capabilities
This Goldman Sachs report also reminds us not to focus only on “who looks most like Samsung Electro-Mechanics.” The better question is: as AI server power density, package area, and power integrity continue to rise, which companies control high-end effective capacity, and which can only share in an ordinary cyclical recovery? The former should be judged by customer qualification and margins; the latter by inventory and utilization. Both asset types can rise together, but their valuation multiples should not be the same.
8. Three Scenarios: Can Samsung Electro-Mechanics Move from Cyclical Stock to AI Hardware Compound Asset?
The most important issue for Samsung Electro-Mechanics is not whether revenue beats expectations in a given quarter, but what asset identity the market ultimately assigns to it. The old framework treated it as a consumer electronics cyclical. The new framework treats it as an AI hardware materials and packaging supplier. Whether that asset-identity shift holds depends on whether three profit lines are delivered together under Goldman Sachs' model.
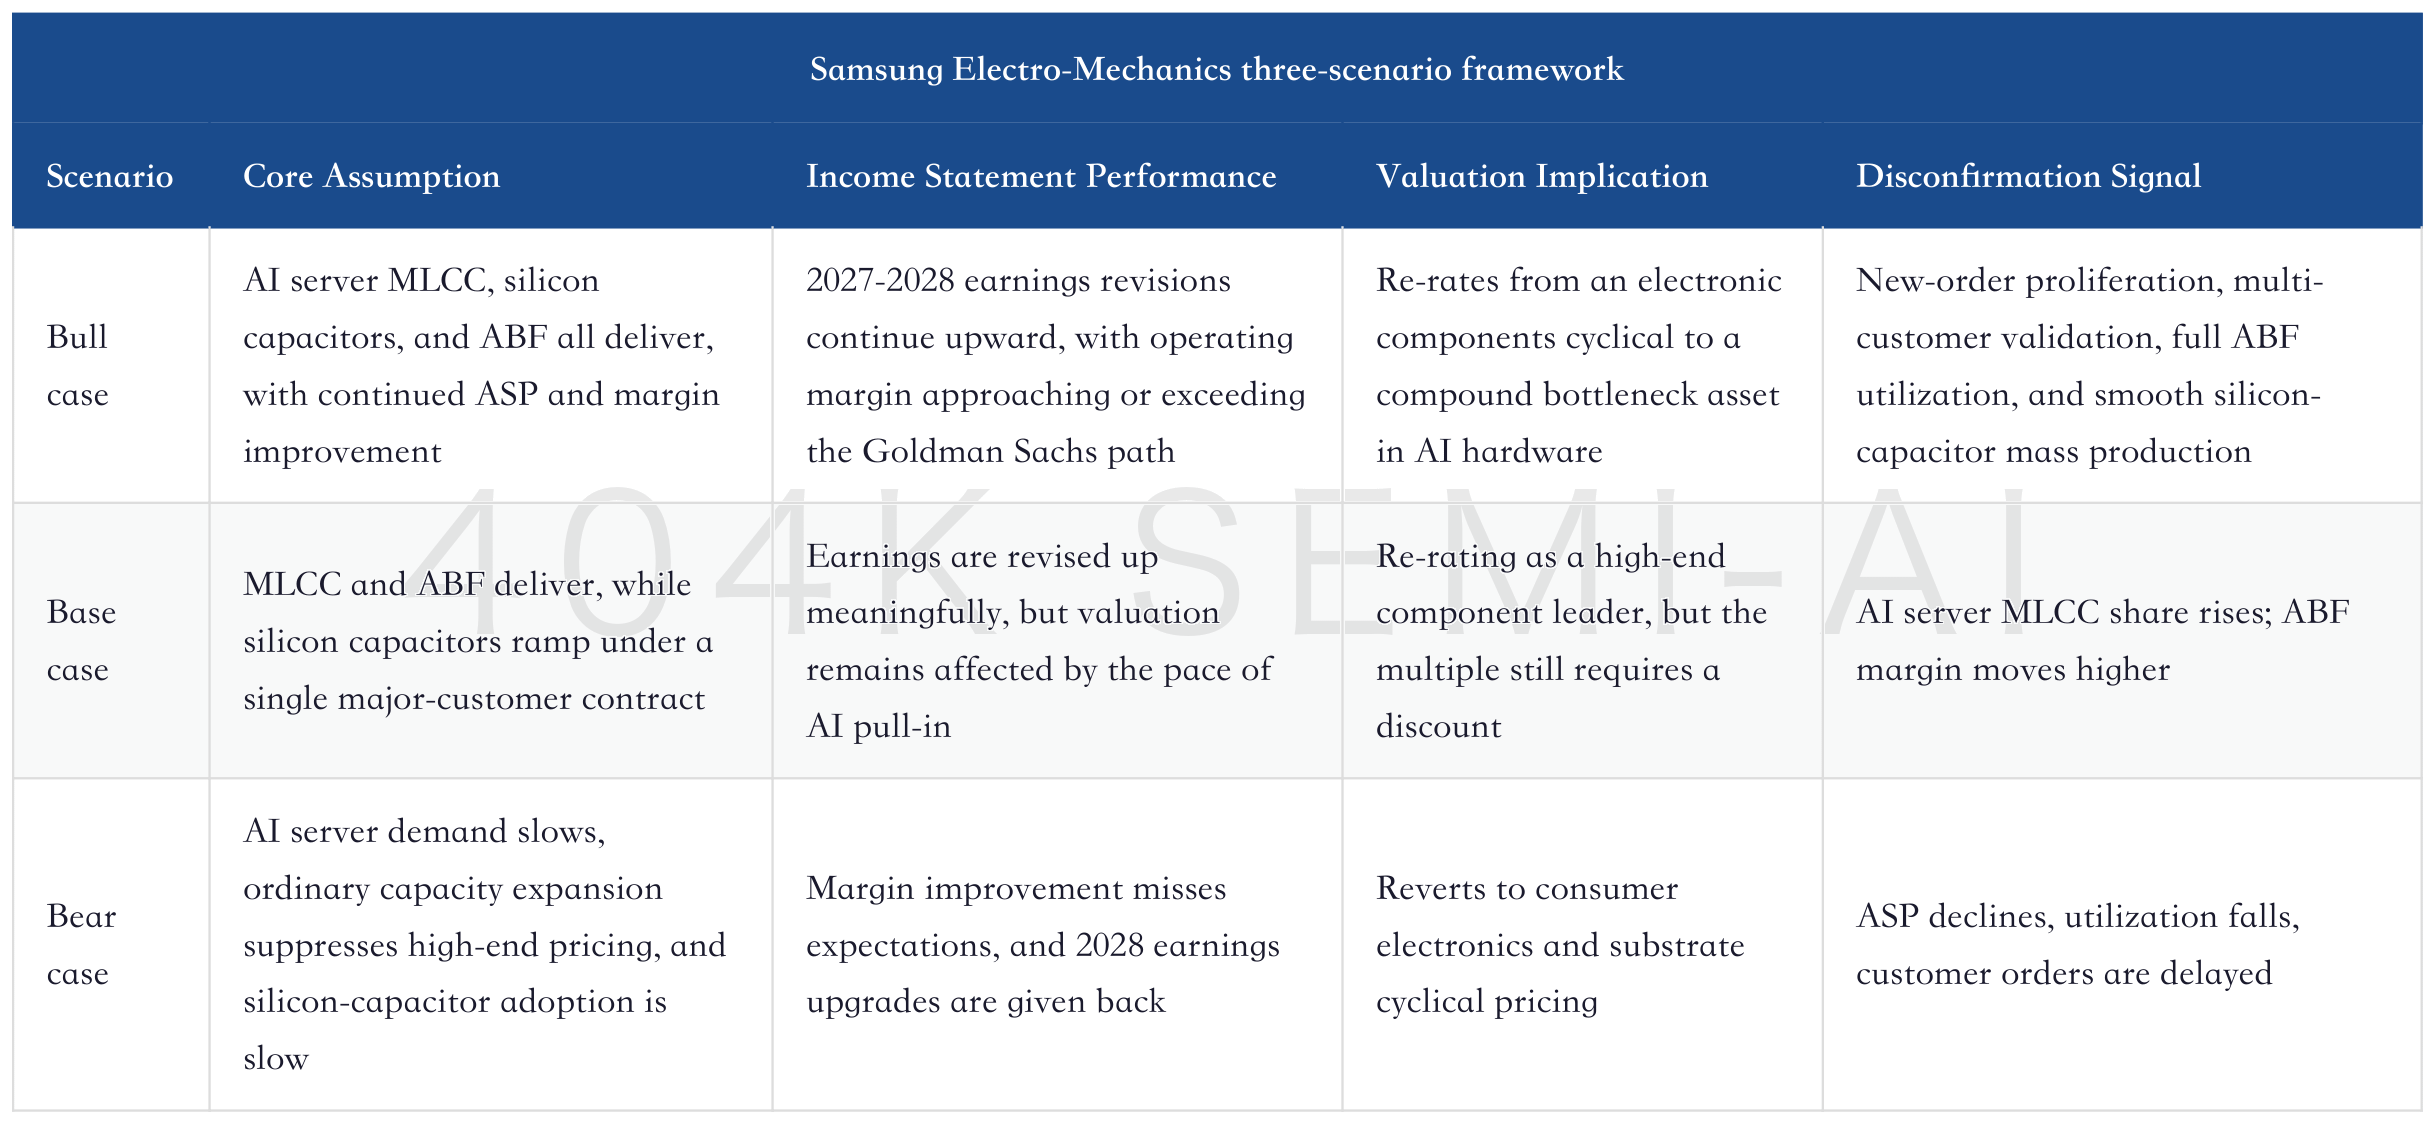
Among these three scenarios, the key question is whether the base case can hold. The market does not necessarily require silicon capacitors to immediately become a second MLCC, but it at least requires MLCC and ABF to deliver margin first. If MLCC ASP climbs from US$3.5 to US$6.0 and ABF margins move from single digits toward around 30%, Samsung Electro-Mechanics' asset identity has already changed. If silicon capacitors then deliver, that becomes an additional valuation option.
LG Innotek's scenario needs to be assessed separately. Its bull case is not simply "ABF revenue growth"; it requires ABF growth while camera-module margins stop being a drag. If iPhone demand, camera ASP, and share remain stable, and ABF then scales from a low base, LG Innotek can gain a second growth curve. If the core camera business comes under pressure, ABF growth can easily be offset by volatility in the main business.
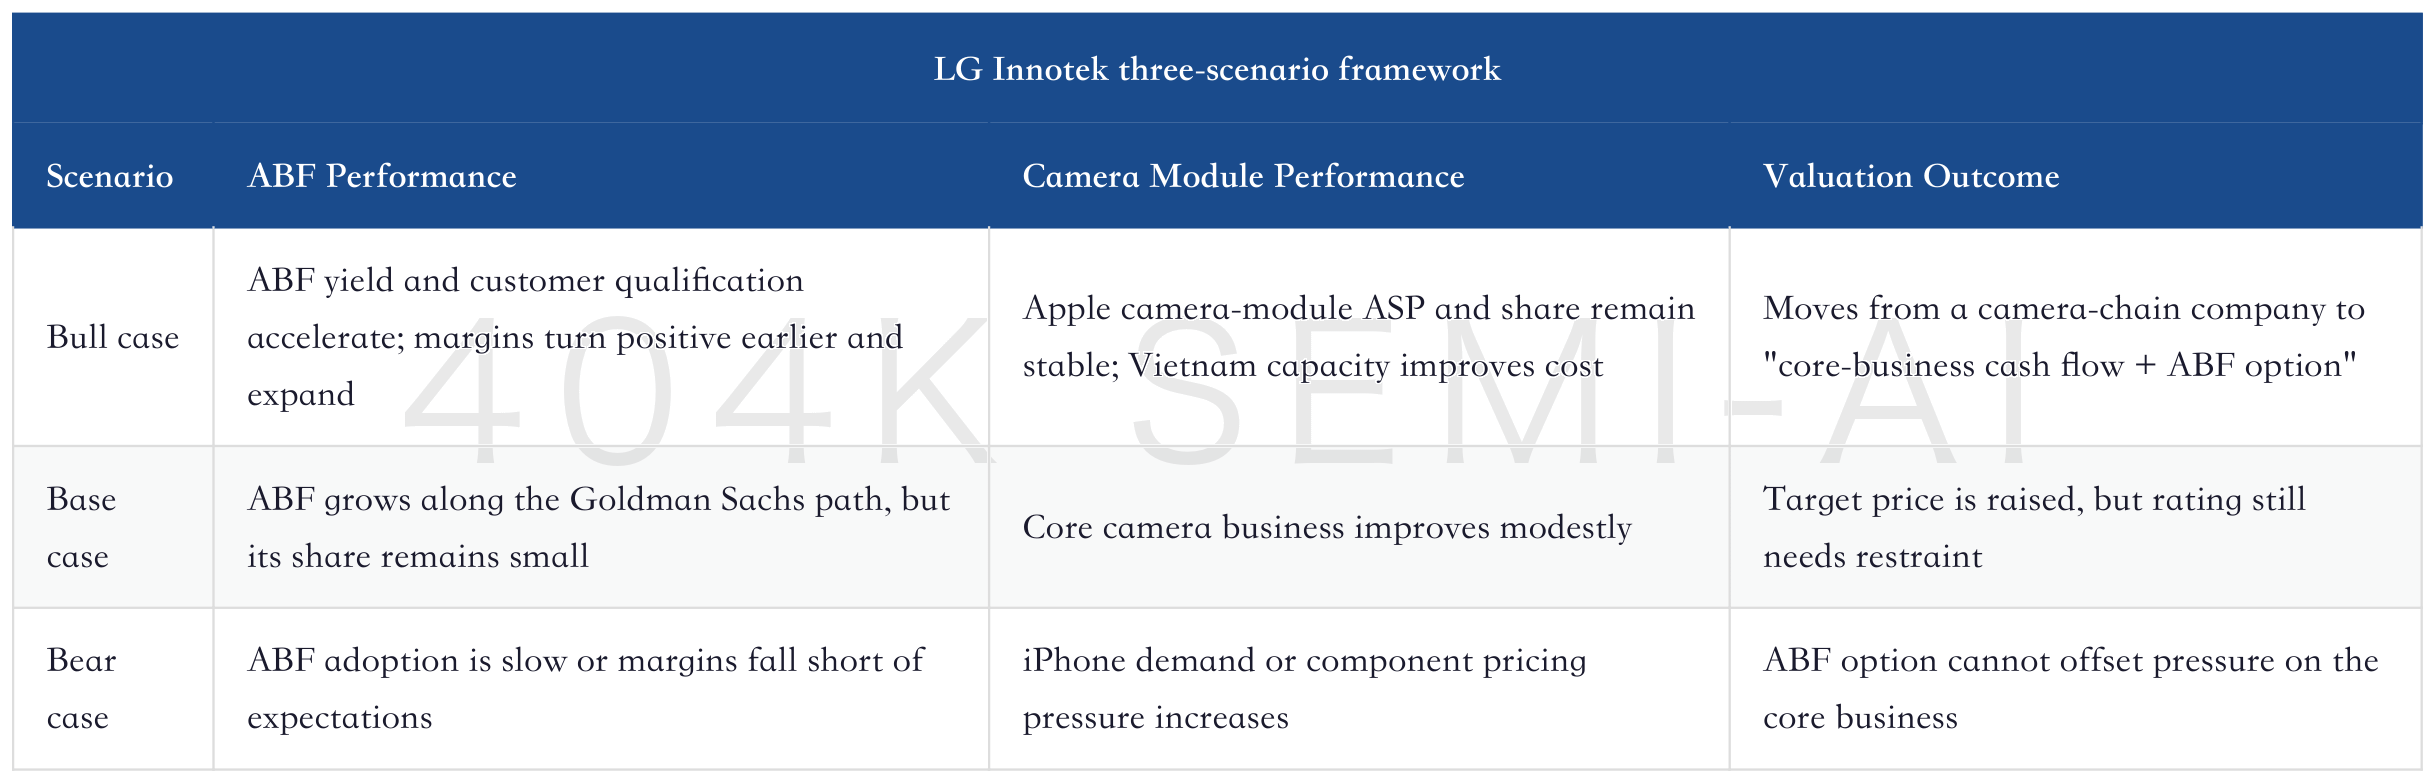
Putting the two scenario tables together, the conclusion is clear: Samsung Electro-Mechanics' AI variable is already large enough to be written into the main income statement, while LG Innotek's AI variable still looks more like an option alongside the income statement. Both companies benefit from the AI server materials chain, but their asset identities are different.
9. What to Watch Over the Next Four Quarters: Orders, ASP, Margins, and Customer Proliferation
The model in this Goldman Sachs report is strong, and the verification will also be very specific. Going forward, it is not enough to watch whether the company says "AI demand is strong." Orders, ASP, margins, and customer proliferation need to be separated. The more specific the indicators, the better they distinguish genuine profit re-rating from thematic trading.
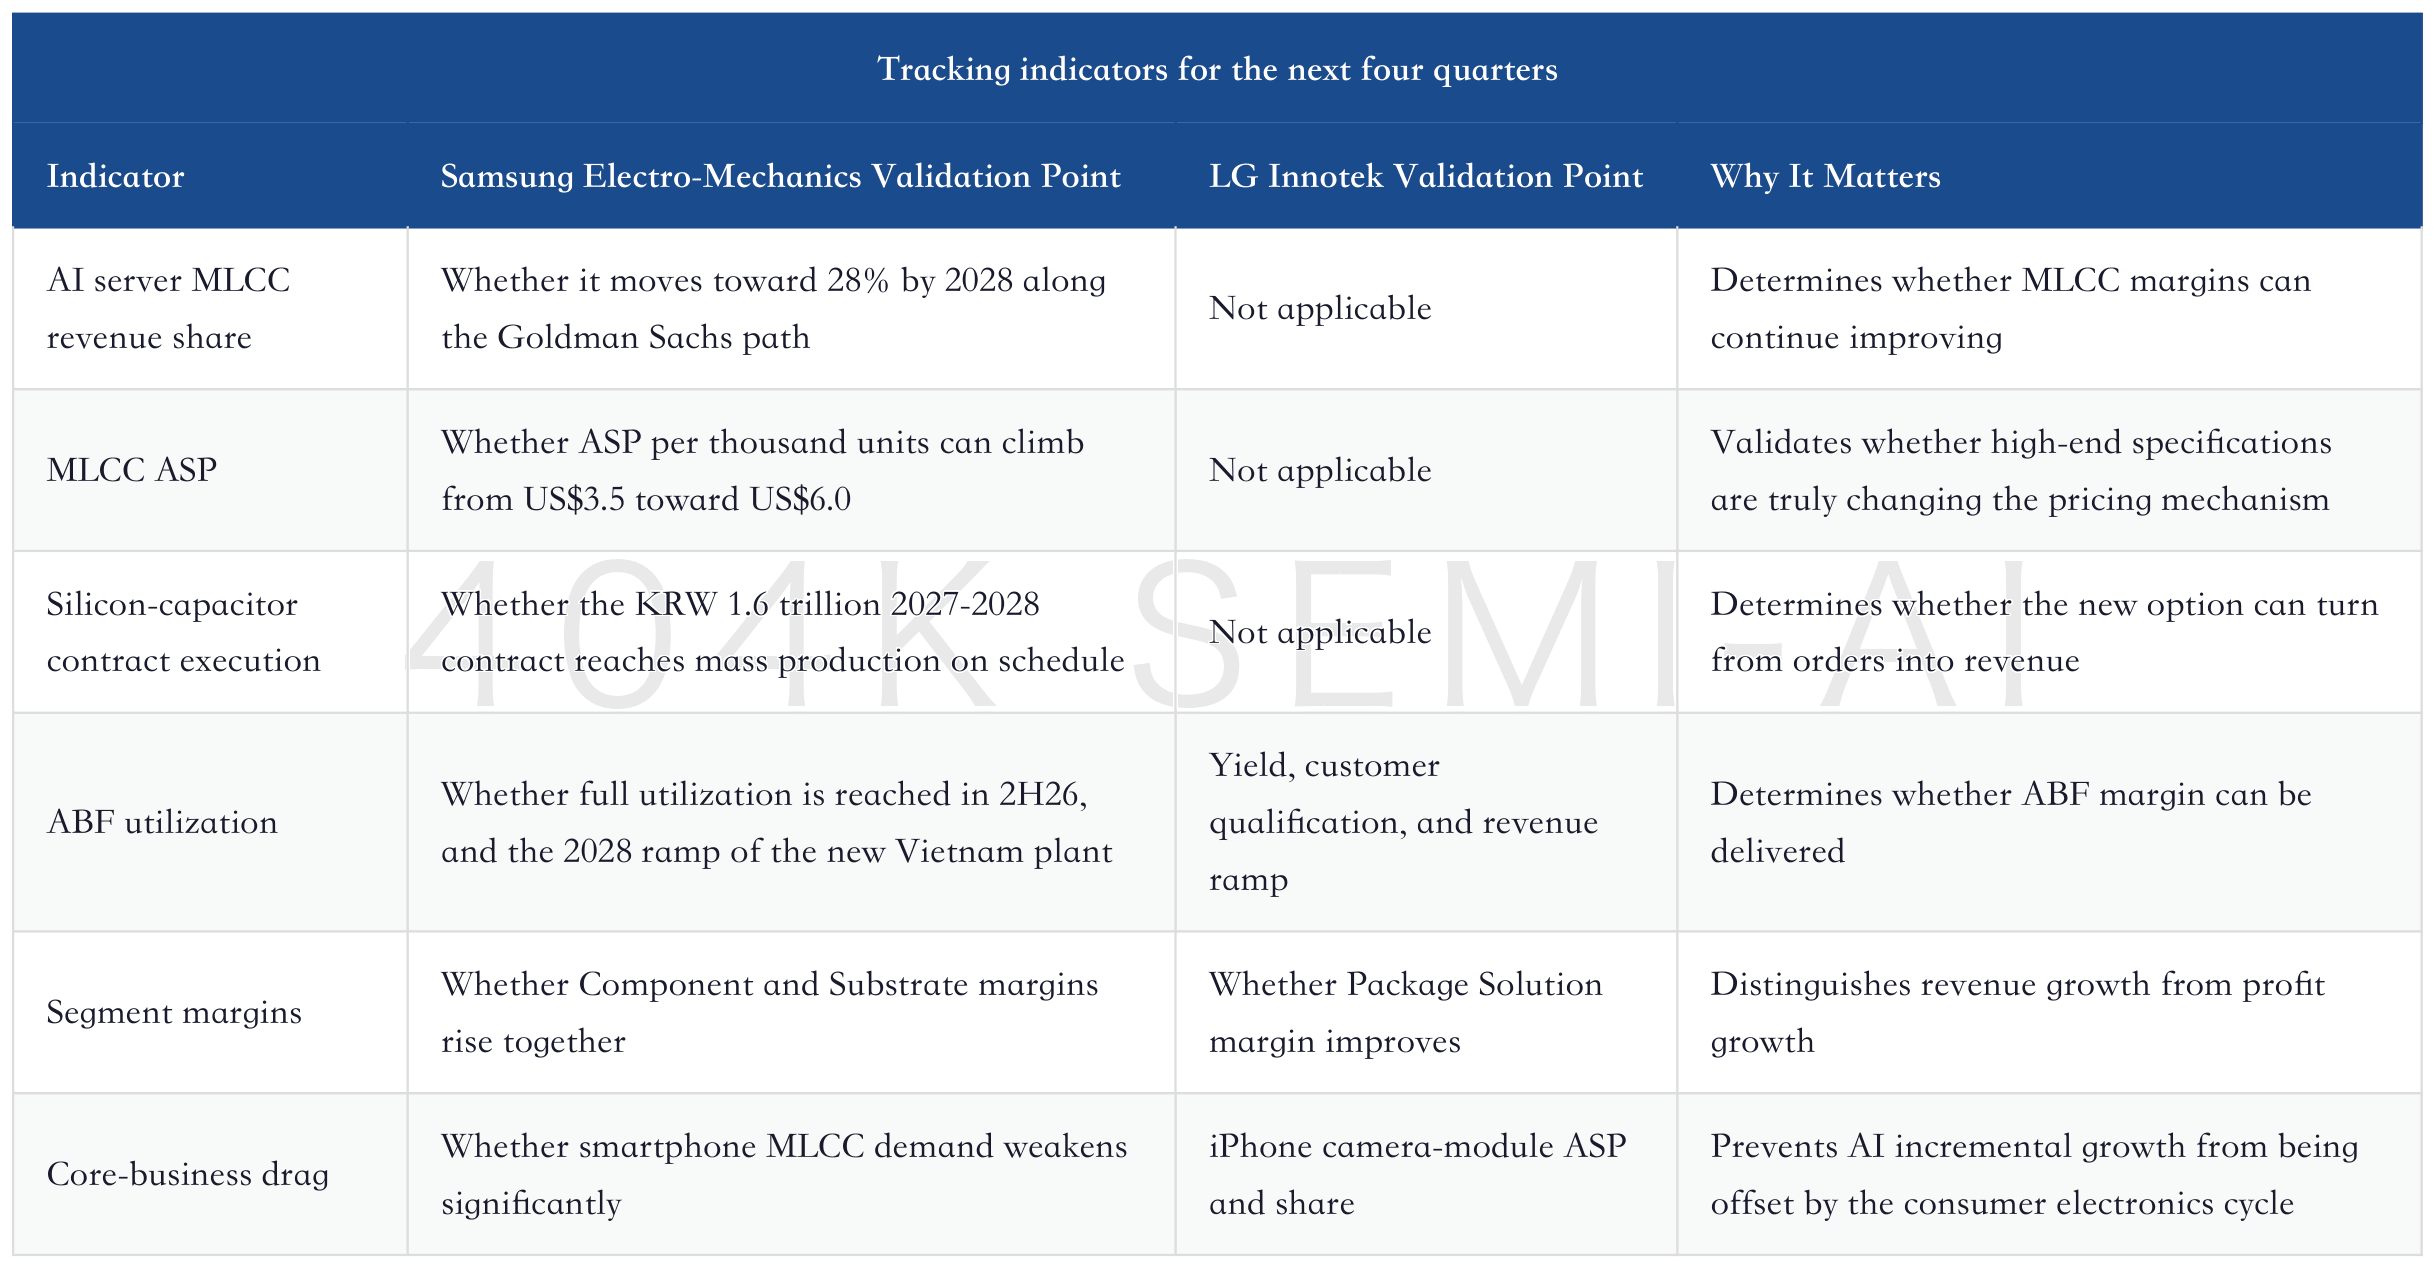
The strongest validation signal would be three things appearing simultaneously in Samsung Electro-Mechanics' quarterly results: the high-end MLCC revenue share continues to rise, ABF utilization and margin continue to improve, and silicon capacitors move from contract disclosure into a clearer mass-production path. As long as two of these three continue to deliver, Goldman Sachs' target-price upgrade logic has support.
The weakest validation signal would be discussion of strong AI demand without visible improvement in ASP, margins, or order mix. Electronic components companies often go through phases of "revenue growth but no profit movement," especially after capacity expansion and depreciation pressure rise. The reason Samsung Electro-Mechanics deserves deeper coverage this time is that Goldman Sachs has written the margin uplift very clearly. Future validation must therefore center on margins, not just revenue.
One reverse risk also needs to be watched: supply response. High-end MLCC and ABF are not impossible to expand. As long as price improvement is visible enough, leaders will increase capital expenditure, and later entrants will also try to enter high-end customers. A tight balance over the next 18-24 months cannot necessarily be extrapolated linearly beyond 2029. Investors should benefit from the upcycle, but cannot treat shortage as permanent.
10. Samsung Electro-Mechanics' Identity Shift: From Consumer Electronics Components to an AI Hardware Bottleneck Portfolio
The most important re-rating point for Samsung Electro-Mechanics this time is that the company's identity is changing. In the past, when looking at Samsung Electro-Mechanics, the market usually first asked about smartphone and PC recovery, then automotive electronics, and only then placed server-related businesses in the incremental category. That framework treated Samsung Electro-Mechanics as a consumer electronics cyclical: when downstream shipments were good, utilization rose and MLCC and camera-related components recovered; when downstream shipments were weak, pricing and margins came under pressure together.
The model Goldman Sachs presents this time effectively reverses the order of the questions. The first question now is whether AI server-related demand can determine the margins of high-end MLCC, silicon capacitors, and ABF; only after that comes the question of whether consumer electronics recovery can support base revenue. Once that order changes, the valuation framework also changes. Consumer electronics cyclicals are evaluated on inventory, utilization, and annual price-downs; AI hardware bottleneck assets are evaluated on customer qualification, long-term contracts, product mix, and margin ceiling.
Samsung Electro-Mechanics occupies a special position. It is not the purest global MLCC asset; Murata Manufacturing is more like the pricing anchor for high-end MLCC. It is also not the purest ABF asset; companies such as Ibiden, Unimicron, and Kinsus are easier to discuss separately in ABF supply-demand. Samsung Electro-Mechanics' value lies in the portfolio: MLCC explains board-level power-supply stability, silicon capacitors explain power-supply stability near the package, and ABF explains the carrying capacity for large-size packages. The more AI servers move toward high power density, the more easily these three lines can be pulled by the same customer budget and the same platform-upgrade cycle.
This portfolio makes Samsung Electro-Mechanics' income statement look more like a checklist of physical constraints in AI servers. GPU performance improvement brings higher power consumption and greater packaging complexity. Higher power consumption creates stricter requirements for decoupling, filtering, and transient response. Greater packaging complexity creates demand for ABF substrates with more layers and larger area. AI servers are not procuring multiple independent components in a scattered way; they are paying a premium for system-level reliability. Whether Samsung Electro-Mechanics can re-rate depends on whether it can concentrate these premiums into its own revenue mix.
The key point here is not the phrase "AI demand is strong." Many hardware companies can say AI demand is strong, but whether strong demand can become margin improvement depends on whether they are selling high-end specifications that customers cannot easily replace. If MLCC is only ordinary specification, customers can push down pricing. If ABF yield is unstable, customers will not assign it to critical platforms. If silicon capacitors remain only at sample and small-batch validation, contract value will not naturally become profit. Samsung Electro-Mechanics' advantage is that all three lines are close to customers' high-reliability requirements. The difficulty is that all three lines must pass strict validation.
Samsung Electro-Mechanics' valuation re-rating also needs a time dimension. 2026 looks more like the starting point for validation: AI server MLCC share rises, ABF enters high utilization, and silicon-capacitor orders await a clearer mass-production schedule. 2027 is the key delivery year: if silicon capacitors begin to generate material revenue, ABF pricing and margins remain stable, and high-end MLCC ASP is not suppressed by ordinary capacity expansion, the market will be more willing to believe that Samsung Electro-Mechanics' margin center has risen. 2028 is the stress test for the Goldman Sachs model: all three lines need to support a companywide operating margin approaching 30%.
Under the old cyclical framework, Samsung Electro-Mechanics' biggest fear was a decline in smartphone demand, because smartphones affect the cycle for MLCC, cameras, and general components. Under the new framework, smartphone demand remains important, but its weight declines. The more important questions become: whether AI server customers are willing to keep locking in high-end MLCC and ABF capacity; whether silicon capacitors can expand from a single major customer to more platforms; and whether Samsung Electro-Mechanics can maintain pricing discipline when high-end supply is tight. As long as these questions receive positive answers, smartphone-cycle volatility will not fully determine the company's valuation.
This is also the difference between Samsung Electro-Mechanics and most domestic passive-component companies. A-share passive-component companies can participate in domestic substitution and high-reliability demand, and can also follow the materials and specification upgrades brought by AI servers, but most still need to prove they have truly entered the high-end global AI server specification supply chain. Samsung Electro-Mechanics' question is not whether it has a ticket, but whether that ticket can bring enough profit. For most domestic companies, the task is first to prove they have obtained the ticket, and then to prove the ticket can turn into profit.
XI. Margin Matters More Than Revenue: What Goldman’s Model Is Really Betting On Is Structural Upgrade
In this report, Goldman’s revenue upgrade is clearly important, but margin is the more central signal. In electronic components, revenue often grows while profit does not, due to higher depreciation, customer price pressure, yield ramp-up, production-line transitions, and inventory cycles. If Samsung Electro-Mechanics were only seeing revenue growth this time, the scope for valuation upside would be limited. Goldman’s large target-price increase is fundamentally based on its belief that product-mix upgrade can lift margins meaningfully.
