
目录
Table of Contents
What the Q2 Turnaround Truly Signals
How Optical Module Equipment Replaced Photovoltaics as the Primary Growth Engine
Can the 43.6% Quarterly Gross Margin Be Sustained?
Multiple Balance Sheet Constraints Remain Even After Cash Flow Turns Positive
What Does BofA's RMB 630 Price Target Imply for 2027–2028?
Key Metrics to Watch Ahead
Robotechnik saw a simultaneous surge in revenue and profit in Q2, with optical transceiver equipment officially taking over as its core business. The next critical milestone is converting order backlog into recognized revenue, operating cash flow, and sustainable, high gross margins.
Table of Contents
What the Q2 Turnaround Truly Signals
How Optical Module Equipment Replaced Photovoltaics as the Primary Growth Engine
Can the 43.6% Quarterly Gross Margin Be Sustained?
Post-Cash-Flow Inflection: Ongoing Balance Sheet Constraints
What BofA's RMB 630 Price Target Implies for 2027–2028
Key Metrics to Monitor Next
What the Q2 Turnaround Truly Signals
Robotechnik’s 1H 2026 interim report presents headline numbers that appear unremarkable at first glance, but are striking upon closer inspection. First-half revenue reached RMB 608 million, up 145.03% YoY, while net profit attributable to parent company shareholders fell 80.51% YoY to RMB 6.56 million. The YoY profit decline was largely due to a Q1 net loss of RMB 38.82 million. Backing out Q1 from 1H results reveals standalone Q2 revenue of approximately RMB 445 million, net profit of approximately RMB 45.37 million, and net operating cash flow of approximately RMB 241 million.
In other words, Q2 contributed roughly 73% of 1H revenue and fully erased Q1 losses. Quarterly revenue grew approximately 193% YoY and 172% QoQ. Gross profit reached approximately RMB 194 million, translating into an implied gross margin of roughly 43.6%—a 7.3 percentage point expansion over Q1. The simultaneous convergence of revenue scaling, gross margin expansion, and positive operating cash flow demonstrates a much higher quality of earnings recovery than one driven merely by cost-cutting or non-recurring items.
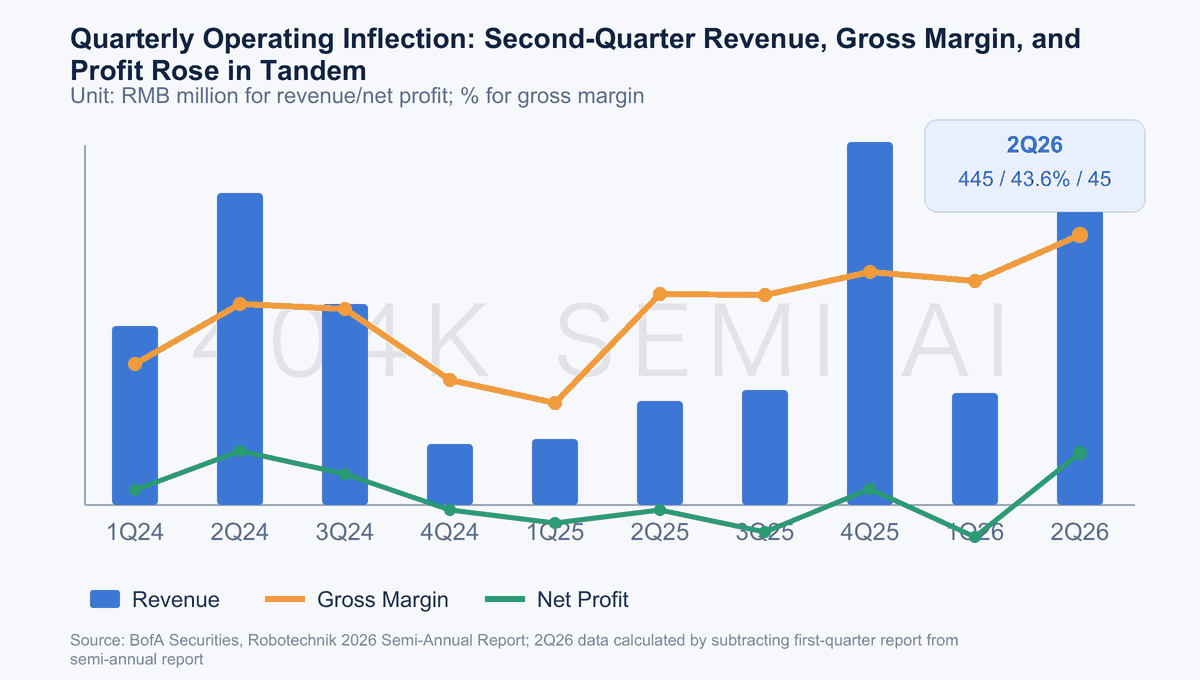
The quarterly financial progression compiled in BofA's report underscores the magnitude of this turnaround. From Q4 2024 through Q1 2026, Robotechnik saw quarterly revenue linger below RMB 200 million for multiple consecutive quarters, logging net losses of approximately RMB 26 million in Q1 2025 and RMB 39 million in Q1 2026. In Q2 2026, revenue rebounded above RMB 400 million, gross margin climbed to a 10-quarter high, and net profit reached approximately RMB 45 million.
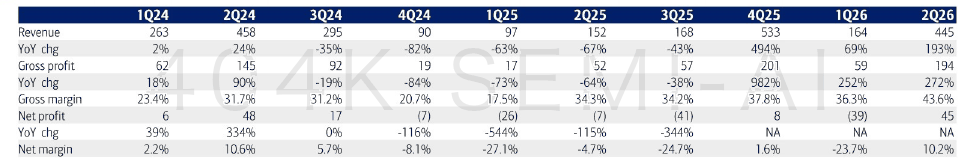
However, the Q2 jump should not be conflated with guaranteed, steady full-year hypergrowth. Equipment vendors are inherently subject to revenue recognition timing driven by customer acceptance test schedules; shifting a few major projects across quarter boundaries can dramatically swing quarterly top and bottom lines. This volatility was already evident when revenue reached RMB 533 million in Q4 2025 before pulling back to RMB 164 million in Q1 2026. As such, Q2 primarily validates the revenue- and earnings-generating capacity of the new business lines; sustained performance will hinge on subsequent delivery and acceptance cadences.
Structurally, Q2's P&L; improvement stemmed from a decisive shift in business mix rather than a sudden recovery in the legacy photovoltaic (PV) business. In 1H 2026, revenue from optical module and semiconductor equipment reached RMB 488 million, surging 952.17% YoY and accounting for roughly 80% of total revenue, whereas PV equipment revenue fell 53.93% YoY to RMB 83 million. Generating more optical module equipment revenue in just six months than the RMB 485 million recorded in all of 2025 confirms that the company has completed a substantive transition of its strategic focus.
This pivot fundamentally enhances operating leverage and profit elasticity. PV equipment caters to mature production lines characterized by cyclical capex downcycles and fierce price competition. In contrast, optical module equipment spans high-precision active optical alignment, die bonding, testing, and automation integration—demanding stringent precision, high yields, and custom engineering capabilities. As high-value equipment expands as a share of total revenue, each incremental unit of revenue generates substantially higher gross profit than legacy PV orders ever did.
How Optical Module Equipment Replaced Photovoltaics as the Primary Growth Engine
Robotechnik’s new growth curve is primarily powered by the consolidation of ficonTEC, a specialist in micro-assembly and testing equipment for optoelectronic devices catering to silicon photonics, optical transceivers, and co-packaged optics (CPO). As AI data centers drive surging demand for high-speed optical interconnects, optical transceiver manufacturers have accelerated capacity expansions, transitioning tool procurement from R&D; prototyping and pilot validation to high-volume commercial deployment. This has unlocked a significantly faster-growing demand window for Robotechnik than legacy PV automation could provide.
The company’s position in the supply chain dictates its revenue recognition cadence. Equipment vendors secure purchase orders, proceed through engineering design, procurement, assembly, commissioning, and on-site customer acceptance before booking revenue. Order intake leads reported financial growth, with production throughput and customer acceptance efficiency determining the lag between the two. Robotechnik’s ultimate valuation depends not only on broader optical transceiver industry tailwinds, but also on its ability to standardize bespoke engineering into modular platforms that can be replicated across diverse customer fabs and manufacturing sites.
At year-end 2024, the company’s total order backlog stood at approximately RMB 570 million. By year-end 2025, backlog had surged to RMB 2.187 billion, including RMB 1.105 billion in optical module and semiconductor equipment. By August 25, 2026, total backlog expanded further to RMB 3.386 billion, with optical module and semiconductor equipment reaching RMB 2.452 billion, or approximately 72% of the total. In less than eight months, optical module and semiconductor equipment backlog surged by RMB 1.347 billion, representing a 122% increase.
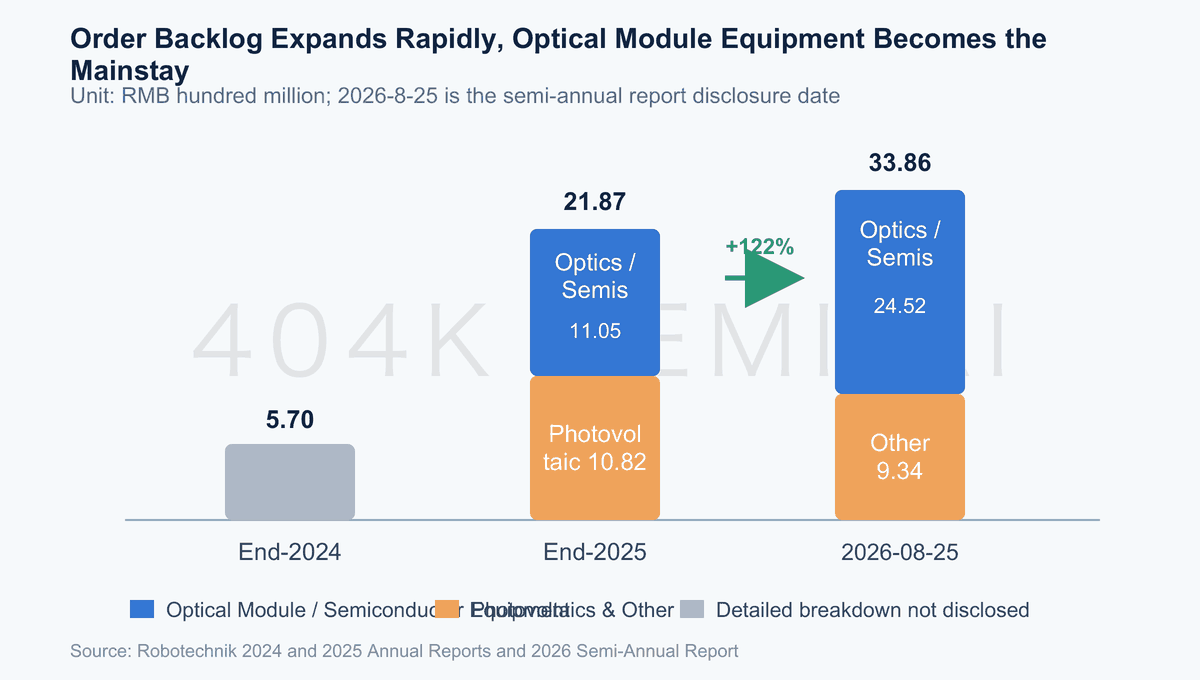
The expanding backlog provides strong visibility into future revenue. Based on 1H 2026 optical module and semiconductor equipment revenue of RMB 488 million, the RMB 2.452 billion segment backlog represents roughly 2.5 semiannual revenue periods. While this ratio cannot simply be extrapolated into the next twelve months of revenue due to varying delivery cycles and potential customer acceptance delays, it confirms that the primary operational bottleneck has shifted from "order acquisition" to "execution and on-time delivery."
