
Robinhood Deep Dive: Prediction-Market Revenue Could Grow More Than 10-Fold, $21.7 Billion in Net Deposits, and Crypto Revenue Declines
目录
TL;DR
I. The Numbers Are Strong, but Not All in the Same Way
II. A Two-Year Baseline: From a Crypto Rebound to a Multi-Product Financial Platform
III. $21.7 Billion in Net Deposits Is Impressive, but the Scope Changes Are Also Material
IV. The Interest-Earning Business Appears Stable, but Its Underlying Asset Mix Has Shifted Toward Higher Credit Risk
V. Profit Should Be Adjusted for RVI, While Expense Guidance Must Be Read Together With Its Exclusions
VI. Cash Flow and Capital Allocation: $2.2 Billion of Zero-Coupon Convertible Notes Expand Optionality
VII. The Five Points Most Likely to Be Misread by the Market
VIII. Disconfirming Evidence and Forward Validation Metrics
本内容基于公开资料和研报数据整理,不构成任何投资建议,不代表任何个人观点,仅供学习参考,请理性阅读
The central takeaway from this earnings report is a rapid rotation in Robinhood’s growth engines: prediction markets, equities, and options have taken the lead, while crypto weakness has not yet prevented revenue and profit from reaching record highs.
TL;DR
Second-quarter 2026 total net revenue was $1.308 billion, up 32% year over year and 23% quarter over quarter. Transaction-based revenue increased 44%, primarily driven by prediction markets, equities, and options, while cryptocurrency revenue declined 38%.
Quarterly net deposits reached $21.7 billion, platform assets reached $369.0 billion, and Gold subscribers reached 4.8 million, all records; however, TradePMR and WonderFi are now included in the reported scope, so the headline figures should not be treated as entirely organic growth.
GAAP net income was $573 million and diluted EPS was $0.62, both up 48% year over year. Gains including the RVI deconsolidation contributed $129 million and $0.14 per share.
The company lowered and narrowed its 2026 guidance for adjusted operating expenses and share-based compensation from $2.700 billion–$2.825 billion to $2.675 billion–$2.775 billion, stating that efficiency gains would be sufficient to absorb the additional costs of Rothera and WonderFi.
The balance sheet is expanding: margin balances reached $21.6 billion, up 127% year over year, while credit-card net interest revenue increased 208%. Accordingly, the doubling of credit-loss provisions, working-capital volatility, and regulatory-capital requirements must be monitored together.
Key items to validate going forward include net deposits excluding acquired businesses, prediction-market revenue per contract, stabilization in crypto, credit losses, and whether earnings growth can offset convertible-note dilution.
I. The Numbers Are Strong, but Not All in the Same Way
Robinhood generated total net revenue of $1.308 billion this quarter, up 32% year over year and 23% from the first quarter. All three revenue pillars grew, but their underlying trajectories diverged significantly.
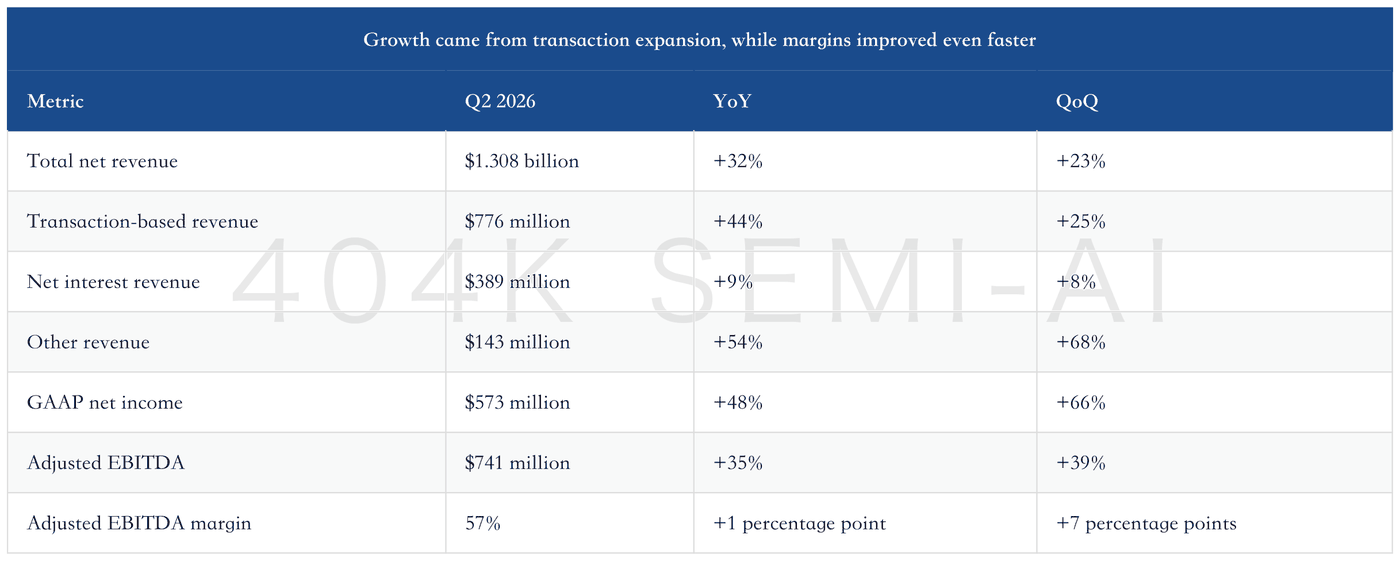
Within transaction-based revenue, prediction-market contract revenue was $156 million, up more than 10-fold year over year; options revenue was $342 million, up 29%; and equities revenue was $129 million, up 95%. Cryptocurrency revenue was only $100 million, down 38% year over year. These figures suggest that Robinhood continues to benefit from active trading, but it no longer relies solely on the crypto cycle.
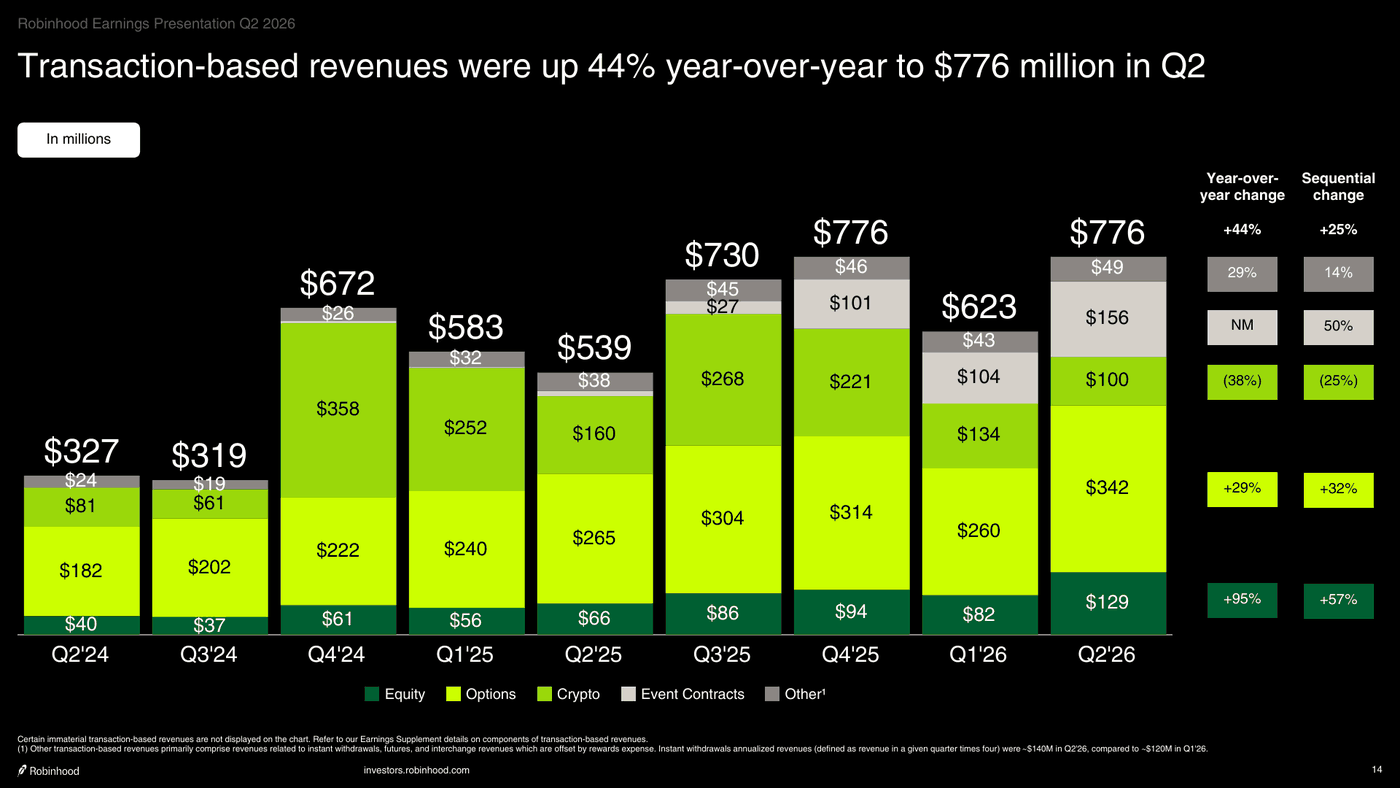
Page 14 of Robinhood’s Q2 2026 Earnings Presentation: The chart retains the complete revenue units, business legends, and year-over-year and quarter-over-quarter changes, supporting the assessment that growth was driven by equities, options, and event contracts while crypto revenue contracted.
Volume data were consistent with revenue: equity notional trading volume reached $956.0 billion, up 85% year over year; options volume reached 774 million contracts, up 50%; and event-contract volume reached 13.6 billion contracts, up more than 10-fold. By contrast, crypto trading volume in the Robinhood App was $18.3 billion, down 35% year over year and 23% quarter over quarter; Bitstamp trading volume was $22.1 billion, down 47% quarter over quarter. Combined crypto trading volume was $40.4 billion, down 39% from the first quarter.
The most easily overlooked detail is Rothera. Rothera contributed $17 million of this quarter’s event-contract revenue; in addition to the 13.6 billion event contracts traded, the materials separately reported 2.1 billion contracts matched by Rothera. The prediction-market surge came both from Robinhood’s existing distribution channel and from the new exchange and clearing infrastructure launched in June. This expanded the revenue pool but also introduced regulatory and execution risks associated with a joint-venture platform that Robinhood may not fully own or operationally control.
II. A Two-Year Baseline: From a Crypto Rebound to a Multi-Product Financial Platform
In a first comprehensive assessment of Robinhood, the company’s structure cannot be explained through a single quarter alone. The official annual reports show that from 2024 to 2025, total net revenue increased 52%, from $2.951 billion to $4.473 billion, while net income increased 33%, from $1.411 billion to $1.883 billion.
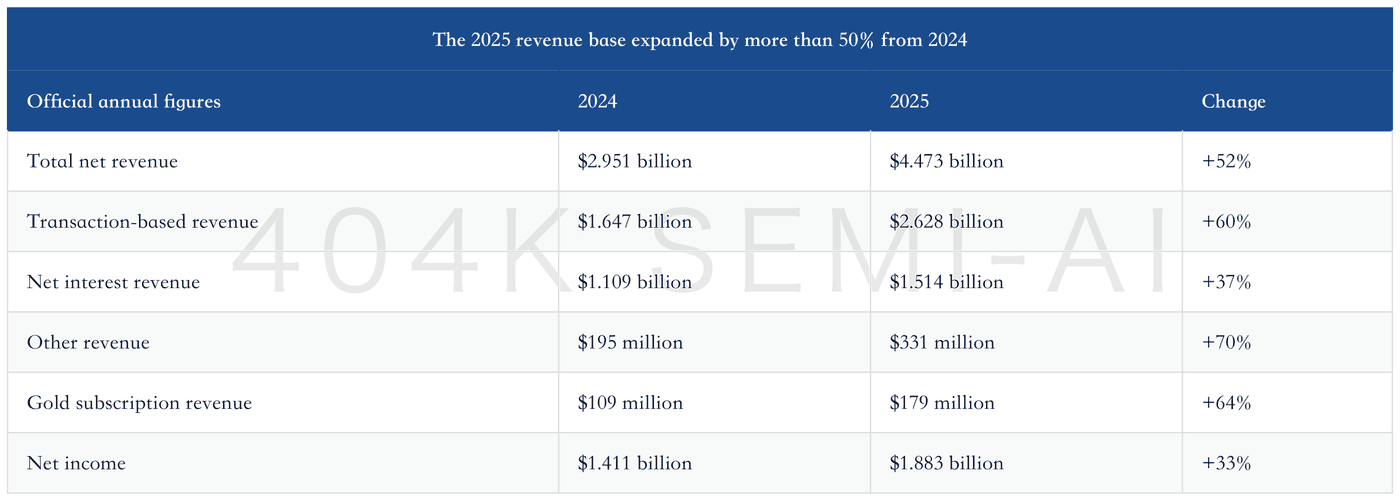
Crypto revenue remained an important growth driver in 2025, still increasing from $626 million to $901 million. By the second quarter of 2026, however, it had shifted to a 38% year-over-year decline, while companywide revenue still grew 32%. This is the period’s most valuable structural signal: options, equities, prediction markets, margin lending, credit cards, and subscriptions can now offset cooling in a single asset class.
The company stated that 13 business lines have reached at least $100 million in annualized revenue, with Robinhood Legend and the credit-card business newly joining the list this quarter. Importantly, “reaching $100 million in annualized revenue” is based on the simple convention of multiplying a single quarter’s revenue by four. It does not mean these businesses have necessarily generated $100 million in revenue over a full consecutive year, nor does it imply equal profit contributions. The metric demonstrates broader product coverage, but it cannot replace validation of durability and unit economics.
III. $21.7 Billion in Net Deposits Is Impressive, but the Scope Changes Are Also Material
This quarter, funded customers reached 28.4 million, up 7% year over year; investment accounts reached 29.9 million, up 9%; platform assets reached $369.0 billion, up 32%; and quarterly net deposits reached $21.7 billion, equivalent to a 28% annualized growth rate based on platform assets at the end of the prior quarter. Net deposits over the past twelve months totaled $75.7 billion, corresponding to a 27% growth rate. Gold subscribers reached 4.8 million, up 39% year over year and representing approximately 17% of funded customers; ARPU increased to $187, up 24%.
However, at least three changes in reporting scope inflate the apparent growth rate:
This quarter’s funded-customer count includes approximately 300,000 customers added through the June 1 acquisition of WonderFi, representing approximately 16% of the 1.9 million year-over-year net increase.
Platform assets have included WonderFi customers’ crypto assets since June.
Net deposits have included TradePMR since March and WonderFi since June, while the historical comparison period did not fully include either component.
Accordingly, the $21.7 billion primarily demonstrates that the Robinhood platform is absorbing substantial assets, but it does not directly prove that organic deposits from existing retail customers accelerated by the same magnitude. The most important incremental disclosures going forward are how much TradePMR and WonderFi each contributed to net deposits, how many net new customers were added excluding acquisitions, and whether recurring deposits from existing customer cohorts continue to increase.
The positive aspect is that Robinhood is clearly gaining wallet share. Retirement assets reached $34.5 billion, up 82% year over year; Gold Card customers exceeded 1 million, with annualized spending above $17.0 billion; Robinhood Banking balances reached $3.1 billion; and Robinhood Strategies had $1.9 billion in assets under management. The average Gold subscriber holds more assets and generates stronger net deposits than the average non-Gold customer, indicating that the subscription ecosystem is evolving from a source of membership-fee revenue into a cross-product distribution channel.
IV. The Interest-Earning Business Appears Stable, but Its Underlying Asset Mix Has Shifted Toward Higher Credit Risk
Net interest revenue was $389 million, up 9% year over year. While the headline growth was modest, interest-related assets at period-end had increased to approximately $71.492 billion, up 26% year over year. Margin loans totaled $21.641 billion, up 127%; Cash and Deposits were $18.687 billion, up 34%; Cash Sweep was $29.707 billion, down 9%; and credit card-related balances were $1.457 billion.
There was also a significant classification change. In February, Robinhood revised its high-yield cash program, converting more than $6 billion of Cash Sweep balances into customer free credit balances and classifying them under Cash and Deposits to support growth in margin lending. Therefore, the decline in Cash Sweep and increase in Cash and Deposits did not reflect a sudden shift in customer cash, but rather a change in how the funds were deployed.
Revenue quality changed accordingly. Margin interest revenue was $215 million, up 89% year over year; credit card net interest revenue was $40 million, up 208%. Meanwhile, interest on corporate cash declined 33%, Cash Sweep revenue declined 32%, and net securities lending revenue declined 81%. The average yield on interest-earning assets fell 3 basis points sequentially to 2.33%, with the company relying on asset growth and higher-yielding margin and credit card assets to sustain growth.
The cost is already visible in the income statement: provision for credit losses was $56 million, doubling year over year and increasing 56% sequentially. As margin balances and credit card receivables grow rapidly, net interest revenue cannot be assessed in isolation from provisions. If markets retreat, customer leverage rises, or credit card delinquencies deteriorate, the higher yields on the revenue side will translate into losses more quickly.
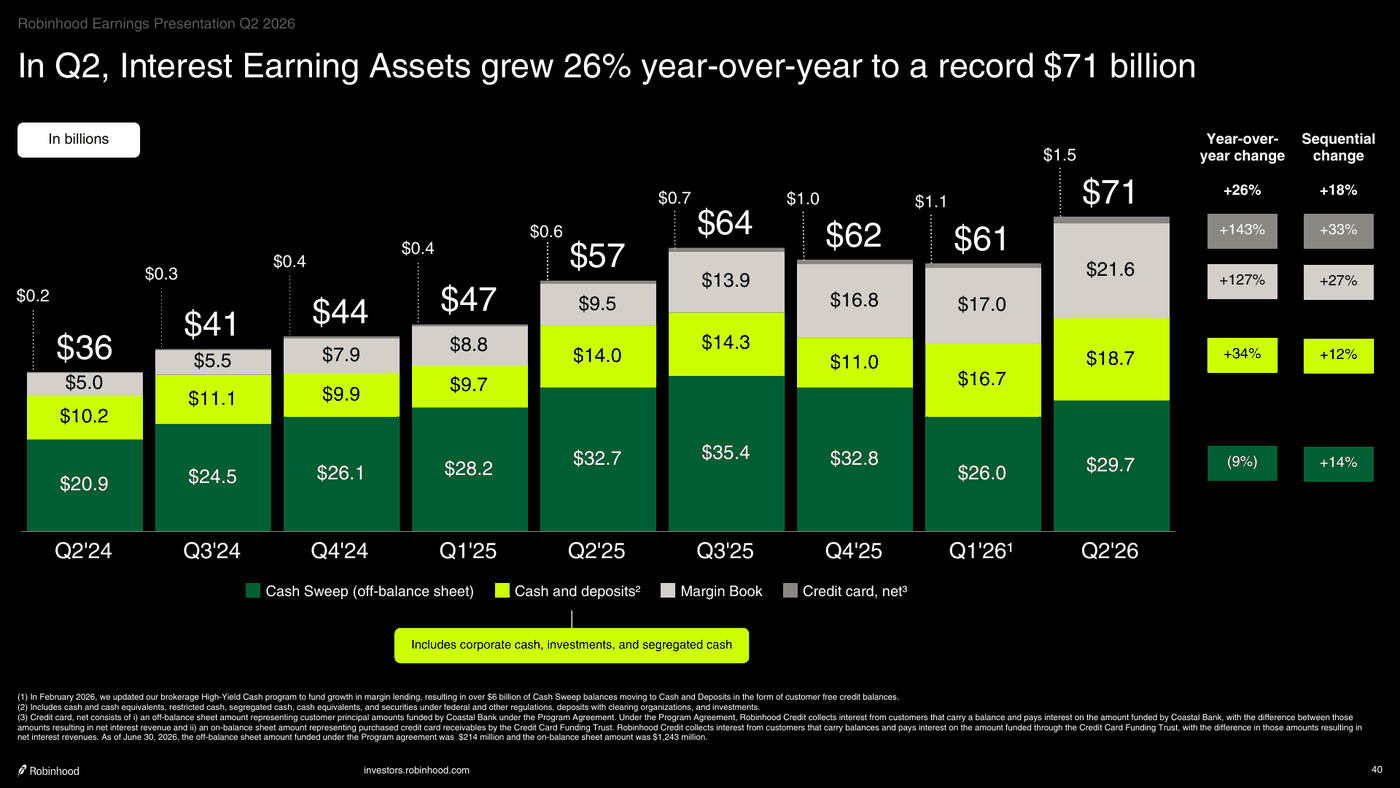
Page 40 of Robinhood’s Second Quarter 2026 Earnings Presentation: The chart retains the classifications for Cash Sweep, Cash and Deposits, margin loans, and net credit card balances, showing that interest-earning assets increased 26% year over year to $71 billion. It also highlights the asset-mix shift toward margin and credit card assets, which offer higher yields but also carry greater credit risk.
V. Profit Should Be Adjusted for RVI, While Expense Guidance Must Be Read Together With Its Exclusions
GAAP net income was $573 million, up 48% year over year; diluted earnings per share were $0.62. Both figures included $129 million of RVI-related gains, equivalent to $0.14 per share, comprising a $106 million deconsolidation gain and $23 million of equity gains primarily related to the RVI investment. On the most direct mechanical adjustment, net income would have been approximately $444 million and earnings per share approximately $0.48—still above the prior-year period, but with growth far below the headline 48%.
Adjusted EBITDA was $741 million, up 35% year over year, with a margin of 57%. The reconciliation excludes the $106 million RVI deconsolidation gain and $23 million of equity gains, while adding back $105 million of share-based compensation and $23 million of restructuring expenses. This measure is more useful for assessing operating leverage, but it is not cash earnings: share-based compensation and restructuring do affect shareholder equity or cash outlays.
Total operating expenses were $734 million, up 33% year over year. General and administrative expenses increased 51% to $199 million, technology and development increased 20% to $256 million, and operations expenses increased 97% to $57 million. Adjusted operating expenses plus share-based compensation totaled $641 million, up 23%, below revenue growth.
Management lowered and narrowed its 2026 guidance for this expense measure from $2.700 billion–$2.825 billion to $2.675 billion–$2.775 billion. The first-half actual was $1.248 billion. Management expects Rothera and WonderFi to add approximately $70 million of costs in the second half, which it intends to absorb through efficiency gains. This guidance is a positive signal, but it excludes credit losses, costs related to acquisitions that have yet to close, certain restructuring and executive-transition share-based adjustments, significant regulatory matters, and other unpredictable expenses. In other words, it constrains “adjusted controllable costs,” not total GAAP expenses.
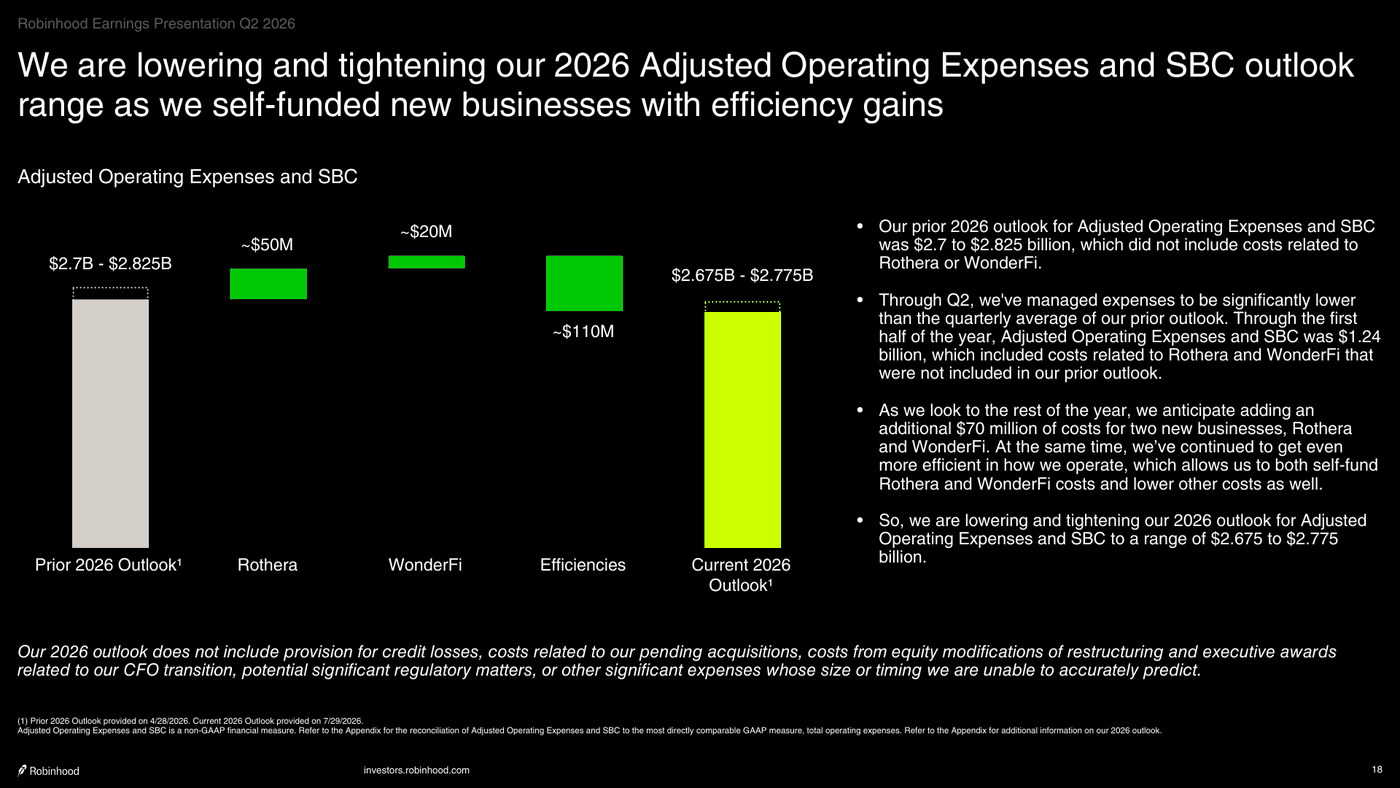
Page 18 of Robinhood’s Second Quarter 2026 Earnings Presentation: Management lowered and narrowed its 2026 guidance for adjusted operating expenses plus share-based compensation to $2.675 billion–$2.775 billion and explicitly stated that approximately $70 million of incremental acquisition-related operating costs would be absorbed through efficiency gains. The exclusions listed on the page also make clear that this is not a ceiling on total GAAP expenses.
VI. Cash Flow and Capital Allocation: $2.2 Billion of Zero-Coupon Convertible Notes Expand Optionality
As of the end of June, cash and cash equivalents were $5.362 billion, up from $4.261 billion at the beginning of the year. On the company’s definition, corporate cash, investments, and stablecoins totaled $5.6 billion, with an additional $4.9 billion of available credit facilities. In June, the company issued $2.2 billion of zero-coupon convertible notes due in 2029, generating approximately $1.8 billion of net proceeds; part of this capital was offset by working-capital requirements arising from record trading activity.
Operating cash flow for the first half was $2.758 billion, but it should not be treated directly as free cash flow in the same way as for a conventional industrial company. Payables for securities lending increased by $8.91 billion and payables to users increased by $5.196 billion, boosting operating cash flow. Conversely, receivables from users increased by $4.476 billion, borrowed securities increased by $3.628 billion, and segregated cash increased by $3.573 billion, consuming substantial cash. As a brokerage and clearing platform, Robinhood experiences significant operating cash-flow volatility from customer assets and securities-financing activities. Its capital capacity should therefore be assessed using corporate cash, regulatory capital, credit facilities, and customer-related assets and liabilities together.
The company repurchased $414 million of stock during the quarter, representing approximately 4.4 million shares at an average price of approximately $94. Of this amount, $290 million, or approximately 2.7 million shares, was executed in connection with the convertible-note issuance and outside the existing repurchase authorization. Approximately $130 million has been used under the original $1.5 billion repurchase program, leaving approximately $1.37 billion. The concurrent repurchase reduces near-term pressure on the share count, but the presentation explicitly states that its diluted share-count table does not yet reflect potential shares from the convertible notes or certain executive performance awards. The ultimate outcome of this capital allocation will depend on the relative pace of future conversion dilution, ongoing repurchase prices, and per-share earnings growth.
VII. The Five Points Most Likely to Be Misread by the Market
First, “net income increased 48%” does not mean core profit increased 48%. RVI-related gains contributed approximately 23% of quarterly net income.
Second, “$21.7 billion of net deposits” does not mean all of it came from existing retail customers. The timing of the inclusion of TradePMR and WonderFi changed the year-over-year comparison basis.
Third, “Cash Sweep declined 9%” does not indicate customer cash outflows. More than $6 billion of balances were transferred to Cash and Deposits following the program adjustment.
Fourth, “transaction-based revenue increased 44%” does not indicate a recovery in the crypto market. Both crypto revenue and trading volume declined materially; growth came from equities, options, and prediction markets.
Fifth, “expense guidance was lowered” does not mean total GAAP expense risk declined. Credit losses, regulatory matters, acquisitions, and certain restructuring expenses are not included in the guidance.
VIII. Disconfirming Evidence and Forward Validation Metrics
The current positive assessment would be weakened by the following disconfirming evidence: a rapid decline in prediction-market trading volume or regulatory restrictions on event contracts; a material slowdown in net deposits after excluding TradePMR and WonderFi; margin and credit card expansion causing credit losses to grow persistently faster than net interest revenue; continued declines in crypto trading volume without new products filling the gap; adjusted expenses remaining controlled while substantial costs enter GAAP expenses through excluded items; and convertible notes and share-based compensation increasing the diluted share count.
Six sets of metrics should be monitored going forward:
Event-contract trading volume, revenue, and revenue per contract; Rothera’s contribution and regulatory status;
Crypto trading volume, trader counts, and unit monetization across the Robinhood App and Bitstamp;
Net customer additions, net deposits, and platform asset growth excluding acquisition impacts;
Gold penetration, Gold Card balances, Banking deposits, and Strategies assets under management;
Margin loans, credit card balances, net interest yield, and provision for credit losses;
Total GAAP expenses, guidance exclusions, shares repurchased, and fully diluted share count including the convertible notes.
This quarter demonstrated that Robinhood can continue expanding revenue and profit even as its crypto business weakens. However, it has also entered a more complex phase: prediction markets introduce regulatory risk, acquisitions alter the growth comparison basis, margin and credit cards increase credit risk, and convertible notes create potential dilution. After normalizing the reporting basis and incorporating risk costs, whether these new growth engines remain sustainable will determine the long-term quality of these results.
As of this report’s completion, Robinhood had not yet filed its second-quarter 2026 Form 10-Q. The current-period data are sourced from Exhibit 99.1 to the company’s July 29, 2026 Form 8-K and its official Earnings Presentation, while historical baselines are sourced from official SEC filings over the past two years.
Related Reading
Qualcomm Q3 Earnings: Autos Grow 61%, but a 20% Handset Decline Creates Transition Pressure